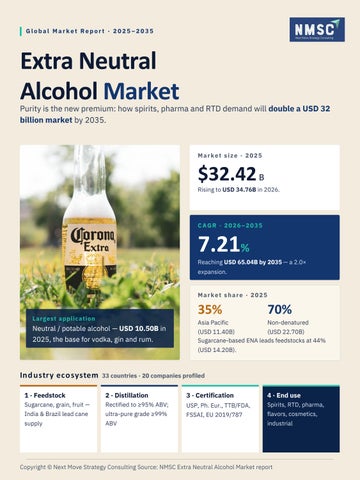
Global Market Report · 2025–2035
Extra Neutral Alcohol Market
Purity is the new premium: how spirits, pharma and RTD demand will double a USD 32 billion market by 2035.
Market size · 2025
$32.42 B
Rising to USD 34.76B in 2026.
CAGR · 2026–2035
7.21% Reaching USD 65.04B by 2035 — a 2.0× expansion.
Market share · 2025
Largest application
Neutral / potable alcohol — USD 10.50B in 2025, the base for vodka, gin and rum.
35%
70%
Asia Pacific
Non-denatured
(USD 11.40B) (USD 22.70B) Sugarcane-based ENA leads feedstocks at 44% (USD 14.20B).
Ind ustry eco system 33 countries · 20 companies profiled 1 · Feedstock
2 · Distillation
3 · Certification
4 · End use
Sugarcane, grain, fruit —
Rectified to ≥95% ABV;
USP, Ph. Eur., TTB/FDA,
Spirits, RTD, pharma,
India & Brazil lead cane
ultra-pure grade ≥99%
FSSAI, EU 2019/787
flavors, cosmetics,
supply
ABV
industrial
Copyright © Next Move Strategy Consulting Source: NMSC Extra Neutral Alcohol Market report
Growth Drivers & Opportunities
Purity, RTD and pharma are rewriting rewriting the demand curve Eight structural drivers add up to +7.6 pts of CAGR impact, offset by –1.8 pts from feedstock volatility and compliance costs.
High-growth segments
Demand drivers · impact on CAGR
CAGR 2025–2035
Emerging-market ultra-pure ENA
+1.5%
Spirits premiumization
+1.4%
RTD & hard seltzer expansion
+1.2%
Pharma-grade ethanol demand
+0.9%
Fruit-based feedstock
Ethanol blending mandates
+0.8%
8.5%
Cosmetics & personal care
+0.7%
Raw-material price volatility
–1.0%
Compliance cost escalation
–0.8%
Also: craft spirits +0.6%, sustainability certification +0.5%
8.8%
≥99.0% ABV ultra-pure tier
8.8%
Compound / RTD beverages
8.5%
Cosmetics & personal care
8.3%
Pharmaceuticals
Reg io nal o p p o rtunity m ap 2025 value · CAGR 2025–2035 · darker = faster growth North America
Europe
Asia Pacific · largest
$7.80B
$8.20B
6.5% CAGR · US is the largest country at $4.80B
6.4% CAGR · beet & grain purity hubs
$11.40B
Latin America · fastest
Middle East & Africa
$2.22B
$2.80B
8.1% CAGR · Brazil RenovaBio exports
7.6% CAGR · industrial & denatured demand
8.0% CAGR India's sugarcane ENA base and China's grain spirits (baijiu, vodka) anchor demand. Vietnam: 9.3% CAGR — fastestgrowing national market
Copyright © Next Move Strategy Consulting Source: NMSC Extra Neutral Alcohol Market report
Competitive Scenario
Scale meets purity in a concentrated concentrated field 20 companies profiled; top-10 share analysis. Agri-conglomerates win on cost, specialists win on purity — and the premium sits where the two converge.
Competitive positioning matrix
Market positioning North America & Europe ADM, Tereos and MGP Ingredients hold leading positions. Asia India's fragmented but collectively large industry dominates production volumes. Specialist niches Manildra leads Australia (wheatbased); Pannonia Bio is a major grain-ENA exporter from Hungary. Barrier to entry GMP and pharmacopoeial compliance progressively exclude smaller producers.
Key strategies in play M&A
Consolidation
Greenfield Global — multi-country acquisitions
Tereos — consolidated international capacity across
across Canada, the US and the UK.
Brazil and Europe.
Capacity expansion
Tech & certification
BCL Industries — 150 KLPD Bathinda plant (May
ADM, Tereos, Greenfield — IoT fermentation
2026), total 900 KLPD.
monitoring plus USP / Ph. Eur. grades.
Copyright © Next Move Strategy Consulting Matrix: qualitative, based on NMSC report
Strategic Outlook
Where the next USD 32 billion will will come from Beverages remain the volume core, but pharma, RTD and cosmetics compound fastest — and pay more for certified purity.
Application value, USD B 2025 2035 · CAGR at right Neutral / potable alcohol 10.50 19.80
6.6%
Distilled alcoholic beverages 8.20 15.40
6.5%
Compound / RTD beverages 3.80 8.60
8.5%
Flavors & fragrances 3.20 6.50
7.4%
Pharmaceuticals 2.80 6.20
8.3%
Cosmetics & personal care 2.40 5.40
8.5%
8–15% price premium for WHO-GMP, USP & Ph. Eur.-certified ENA
What it means for you Investors •
•
Back certified ≥99% ABV capacity — the fastest tier at 8.8% CAGR. Latin America (8.1%) and Vietnam (9.3%) offer abovemarket growth.
Strategy teams •
•
Diversify grain + cane feedstock to hedge the –1.0 pt volatility drag. Pair digital production monitoring with pharmacopoeial certification.
B2B buyers •
•
Lock long-term RTD and pharma contracts with GCverified neutrality. Require ISCC / Bonsucro sustainability credentials for EU supply.
Copyright © Next Move Strategy Consulting Source: NMSC Extra Neutral Alcohol Market report
Let's Connect
Thank You Connect with our analysts for in-depth ENA insights, custom segment cuts and strategic guidance tailored to your investment or sourcing decisions.
Official website
www.nextmsc.com Contact number
+1 857 758 5017 Email
info@nextmsc.com
gen-dedup-346ccdb965062f1ceb2c9afb257b1e82.png
Call to action
Click here for the complete report
Follow us LinkedIn
Twitter / X
Twitter / X Instagram
YouTube
YouTube
@nextmsc
Inside the full report
20
33
4
2035
companies profiled
countries covered
segment lenses
forecast horizon
Copyright © Next Move Strategy Consulting