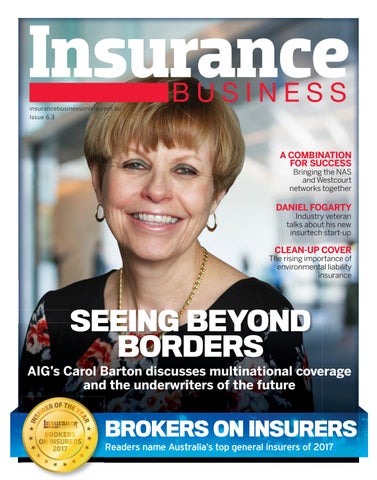
insurancebusinessonline.com.au Issue 6.3
A COMBINATION FOR SUCCESS
Bringing the NAS and Westcourt networks together
DANIEL FOGARTY Industry veteran talks about his new insurtech start-up
CLEAN-UP COVER
SEEING BEYOND BORDERS
F ER O THE YE R U
AR
INS
The rising importance of environmental liability insurance
AIG’s Carol Barton discusses multinational coverage and the underwriters of the future
BROKERS ON INSURERS Readers name Australia’s top general insurers of 2017
OFC and spine Subbed.indd 1
23/05/2017 11:44:37 AM
IFC-01_Contents subbed.indd 2
23/05/2017 12:00:20 PM
INS
AR
R OF THE Y E E UR
ISSUE 6.3
CONNECT WITH US Got a story, suggestion or just want to find out some more information?
CONTENTS
twitter.com/InsuranceBiz_au www.facebook.com/pages/ Insurance-Business-Australia
UPFRONT 02 Editorial
Remaining on the radar
04 Statistics
What Gen Y customers want
FEATURES
34
THE CLEAN-UP COVER
22
FEATURES
The increasing relevance of environmental liability insurance
SEEING BEYOND BORDERS
Succeeding in the cyber-risk market
10 News analysis
The latest risks posed by technology
12 Intelligence
AUB Group announces its latest acquisition and AJG CEO heads for BMS
16 Underwriting agencies update Lloyd’s 2017 Dive In festival?
FEATURES
FEATURES
46
A COMBINATION FOR SUCCESS Bringing together the NAS and Westcourt authorised broker networks
36 Business insight
Former Zurich CEO Daniel Fogarty talks Evari – his insurtech start-up
38 Securities class actions causing distress
Increasing securities class action activity and the D&O market
42 Break from the pack
Gratex International’s insights into using technology to stand out
50 Avoiding burnout
How to chill out, not burn out
Carol Barton, the president of AIG’s multinational division, opines on what’s ahead for underwriters
18
08 Opinion
The industry reacts to the federal budget
Brokers vote to determine Australia’s best general insurers
PEOPLE
Do businesses need terrorism cover?
14 Insurer update
BROKERS ONBROKERS INSURERS 2017
ON INSURERS 2017
06 Head to head
52 Going for the win
Collingwood Football Club CEO Gary Pert on successful partnerships
FEATURES
48
A GENERATION SET UP FOR FAILURE?
Making millennials good leaders
PEOPLE 56 Other life
Broker Peter Peirano on his passion for competitive drag racing
INSURANCEBUSINESSONLINE.COM.AU
CHECK IT OUT ONLINE www.insurancebusinessonline.com.au
IFC-01_Contents subbed.indd 1
1
23/05/2017 12:00:43 PM
UPFRONT
EDITORIAL
www.insurancebusinessonline.com.au EDITORIAL
REMAINING ON THE RADAR
A
nalytics and actuarial consulting firm Taylor Fry recently released its 2017 Radar: Insights for Insurance Leaders report. While indicating a more positive overall outlook for Australian insurers than in recent years, the report identified five prominent issues confronting those insurers. Firstly, it cited the need for insurers to be prepared to adapt to a changing regulatory environment, evolving to address issues that include the increasingly pressing matter of climate change, as well as considerable concerns ASIC flagged last year around car dealerships’ sale of add-on products. Secondly, cyber risk is as great an issue as it has ever been for the industry, and while underwriters continue to have access to only limited insured-loss data, appropriate pricing of cyber products is a challenge with which they must grapple. The third issue the report identified recognised that the benefits of big data have been widely publicised, but alongside those advantages stand questions for insurers around the responsible management of personalised information. Next, according to Taylor Fry, fraud is now estimated to be a more than $2bn per year issue for the
It’s imperative that insurers and brokers effectively partner with a view to delivering world-class customer service experiences to insured clients industry in Australia, and solutions to address that challenge should occupy a prominent place on insurers’ agendas. And, finally, as the world continues to change at an unprecedented pace, innovation to keep up with changing consumer needs and expectations also warrants substantial attention from insurers. Whether individual insurers remain successful in an increasingly competitive environment will also be influenced by how they’re perceived by brokers. It’s imperative that insurers and brokers effectively partner with a view to delivering world-class customer service experiences to insured clients. Where choice is greater, where disruptors are beginning to make their own play in the space, and where customer service expectations are driven by experience across industries, insurers must work to ensure they’re part of a client’s decision-making process. In this issue, we bring you the results of our fifth annual Brokers on Insurers survey, in which readers share their own experiences with Australia’s major insurers over the past 12 months and cast their vote for those at the top of the pack. We know that you’ll find the insights they’ve shared interesting and important reading.
Tim Garratt, editor
Editor Tim Garratt News Editor Jordan Lynn Writers Libby MacDonald, Lucy Hook Production Editors Bruce Pitchers, Roslyn Meredith
CONTRIBUTORS Alan Thorn, Hiam Sakakini, Karen Gately, Raisa Conchin, Tom King
ART & PRODUCTION Design Manager Daniel Williams Designer Joenel Salvador Traffic Coordinator Freya Demegelio
SALES & MARKETING General Manager Peter Smith Commercial Development Manager Sophie Knight Marketing & Communications Manager Lisa Narroway
CORPORATE Chief Executive Officer Mike Shipley Chief Operating Officer George Walmsley Managing Director Justin Kennedy Chief Information Officer Colin Chan Human Resources Manager Julia Bookallil
EDITORIAL ENQUIRIES tim.garratt@keymedia.com.au
SUBSCRIPTION ENQUIRIES
subscriptions@keymedia.com.au
ADVERTISING ENQUIRIES
sophie.knight@keymedia.com.au peter.smith@keymedia.com.au
Key Media Regional head office, Level 10, 1–9 Chandos St, St Leonards, NSW 2065, Australia tel: +61 2 8437 4700 • fax: +61 2 9439 4599 www.keymedia.com Offices in Sydney, Auckland, Denver, London, Singapore, Toronto, Manila, Bengaluru
Insurance Business is part of an international family of B2B publications and websites for the insurance industry INSURANCE BUSINESS AMERICA cathy.masek@keymedia.com T +1 720 316 0151
INSURANCE BUSINESS CANADA john.mackenzie@kmimedia.ca T +1 416 644 874O
INSURANCE BUSINESS NZ peter.smith@keymedia.com.au T +61 2 8437 47OO
INSURANCE BUSINESS UK jonathan.connelly@keymedia.com T +44 20 7193 0935
INSURANCE BUSINESS ASIA peter.smith@keymedia.com.au T +61 2 8437 4700
2
www.insurancebusinessonline.com.au
02-03_Eds letter Subbed Final.indd 2
Copyright is reserved throughout. No part of this publication can be reproduced in whole or part without the express permission of the editor. Contributions are invited, but copies of work should be kept, as Insurance Business magazine can accept no responsibility for loss.
23/05/2017 11:45:55 AM
02-03_Eds letter Subbed Final.indd 3
23/05/2017 11:46:03 AM
UPFRONT
STATISTICS
CHANGING CHANNELS
A WORLD OF USER EXPERIENCE Globally, members of Generation Y are likely to have fewer positive experiences with insurance companies across the board. That’s primarily due to high expectations and a pronounced preference for digital channels, pointing to gaps in service.
Gen Yers are on the rise, and they’re not satisfied with the insurance status quo YOUNG, MOBILE and attuned to a world of constant digital interaction, Generation Y is emerging as a new kind of customer. According to the latest World Insurance Report from Capgemini and Efma, fewer Gen Y customers reported a positive experience with their insurance carriers than their elders. Perhaps most important is the marked gulf between what Gen Y customers expect and what
traditional insurers provide. This generation is characterised by a desire to engage more frequently, with a preference for twice as much contact as other demographic segments, particularly in newer channels, such as social media. That opens the field to new competitors, especially as Gen Yers say they’d be more likely to consider purchasing insurance from a tech brand like Apple or Google, if offered.
NORTH AMERICA
100% 80% 60% 64.7% 40% 40.3% 20% 0% Positive experience in traditional channels
25+%
40.5%
of the global population is part of Gen Y
30.9%
of Gen Y customers consider themselves to be strong technology users
of non-Gen Y customers consider themselves strong technology users
36.2%
51.6%
Positive experience in digital channels
23.4%
of customers worldwide are likely to purchase insurance from a tech company, if offered
Gen Y
Others
Source: World Insurance Report 2016, Capgemini and Efma
REACHING OUT
THE DIGITAL GENERATION
Gen Y consumers communicate with their insurers more often across all channels, though they do reach out more frequently online.
Gen Y customers have a clear preference for digital channels – they turn to social media to access insurance services up to two and a half times more often than other customers and use mobile more than twice as often as other customers.
Gen Y
Others
Gen Y
CUSTOMERS USING DIGITAL CHANNELS AT LEAST ONCE A MONTH
CUSTOMERS USING THE CHANNEL AT LEAST ONCE A MONTH Agent
27.8%
Phone
35.6%
North America
31.9%
15.5%
Internet (PC)
43%
Internet (Mobile) Social media 0%
10%
20%
30%
4
17.3%
Developing Asia-Pacific 40%
50%
Source: World Insurance Report 2016, Capgemini and Efma
56.7%
34.6%
Developed Asia-Pacific
32.1%
13%
32.1%
15.3%
Latin America
36.2%
16.2%
39.5%
20.4%
Europe
27.5%
Others
30.2% 53.2%
33.9% 0%
20%
40%
60%
80%
Source: World Insurance Report 2016, Capgemini and Efma
www.insurancebusinessonline.com.au
04-05_Stats Subbed.indd 4
23/05/2017 11:46:30 AM
EUROPE
DEVELOPED ASIA-PACIFIC
100% 80% 60% 56.6% 40% 20% 34.6% 0%
100% 80% 60% 40% 20% 0%
49.9% 29%
Positive experience in traditional channels
44.7% 29%
Positive experience in traditional channels
Positive experience in digital channels
LATIN AMERICA
DEVELOPING ASIA-PACIFIC
100% 80% 60% 59.3% 40% 20% 35.4% 0%
100% 80% 60% 48.8% 40% 20% 33.9% 0%
Positive experience in traditional channels
51.6% 36%
32.3%
47.3%
33.3%
Positive experience in traditional channels
Positive experience in digital channels
Positive experience in digital channels
40.7%
Positive experience in digital channels
Source: World Insurance Report 2016, Capgemini and Efma
THE LURE OF BUYING ONLINE
TECH TAKEOVER?
Digital migration is hardly the sole province of the younger generation – across all age groups, online and mobile channels were most likely to see increased usage for the purchase of primary insurance policies.
Almost a fifth of Gen Yers in the developed Asia-Pacific area were willing to purchase insurance through a tech company, but that number was even higher elsewhere.
0.6%
1.5%
50%
16.5%
25.3%
14.2%
11.9%
11.8% 20.7% 8.8%
18.5%
9.9%
15.3%
37.5%
43.5% 13.2% 9%
30% 20%
13.1% 8.8%
10% 0%
Agent
Phone
Bank
Broker
Internet (PC)
Internet (mobile)
Social media Source: World Insurance Report 2016, Capgemini and Efma
25.2%
32.2%
12.5% 14.1% 8.8%
22.5%
37.1%
38.6%
40%
17.3%
Others
47.2%
0.7%
0.8%
Gen Y
Would you purchase insurance policies from a top technology brand such as Google, if offered?
North America
Europe
36.2%
1.6%
3.5%
Channel likely to be used to purchase or renew insurance policy in next 12 months (Others)
19.6%
2.1%
Channel used to purchase insurance policy (Others)
11%
2.1%
Channel likely to be used to purchase or renew insurance policy in next 12 months (Gen Y)
49%
Channel used to purchase insurance policy (Gen Y)
Latin Developed Developing America Asia-Pacific Asia-Pacific
Source: World Insurance Report 2016, Capgemini and Efma
www.insurancebusinessonline.com.au
04-05_Stats Subbed.indd 5
5
23/05/2017 11:46:34 AM
UPFRONT
HEAD TO HEAD
Is terrorism coverage now necessary for all businesses? Terrorism insurance is essential for business clients in high-risk industries and locations – but what about everyone else?
Julian Enoizi
Reggie Gibbs
Geoff Stilwell
CEO Pool Re
Managing underwriter, security risks Starr Companies
CEO and managing director Beech Underwriting Agencies
Recent attacks have emphasised the terrorism threat we now face; the insurance industry needs to increase the uptake of cover and its scope. In many of these events, small businesses have borne the brunt of the costs – from street closures to loss of attraction – damaging the wider economy as a result. These attacks have not been restricted to major cities or high-risk industries and locations. As high-profile sites become better defended, terrorists might turn their attention to less obvious and more exposed targets. Ensuring that businesses have access to terrorism insurance cover is key to mitigating this threat.
The need for terrorism insurance, particularly that of the non-certified variety – i.e. not subject to TRIA – has become increasingly important in recent years, as threats have shifted from highprofile locations to targets that would not traditionally be considered high-risk. Recent examples include attacks at the Pulse nightclub in Orlando and at the Inland Regional Centre in San Bernardino. Low-level, lone wolf attacks have become even more prevalent in Europe. Hence, regardless of the location, profile or industry class of business, the chance of becoming a target of, or suffering collateral damage from, an act of terror has increased.
Unfortunately, any act of terrorism, as we know, is totally random. Therefore, it doesn’t matter where a client is based or the type of business they are in – I would recommend terrorism insurance. Quite simply, any client must think of the following: should an incident take place, who is going to pay back the mortgage or loans to the lender, or can I continue to trade? All the lender is interested in is getting their money back – whether you can trade or not trade – and having the right cover will enable a business to continue to trade.
A CONSTANT THREAT Fifteen years after the September 11 attacks, the threat of global terrorism lingers, albeit in an altered form. The April incident in Stockholm, which resulted in the deaths of four people and injuries to 15 when a truck was driven into a pedestrian shopping street and department store, is the type of lone wolf attack that typifies the changing face of terrorism. According to a 2016 report from Marsh, this change in the nature of terror attacks has seen a growing awareness of the need for organisations to assess their coverage for indirect losses stemming from business interruption risks. In the US, the passage of the Terrorism Risk Insurance Program Reauthorisation Act in 2015, which extended the legislation until 2020, has increased the take-up rate for terrorism coverage embedded in property programs.
6
www.insurancebusinessonline.com.au
06-07_Head to head Subbed.indd 6
23/05/2017 11:46:58 AM
06-07_Head to head Subbed.indd 7
23/05/2017 11:47:01 AM
UPFRONT
OPINION
GOT AN OPINION THAT COUNTS? ibo@keymedia.com.au
SUCCEEDING IN THE EVOLVING CYBER RISK MARKET What are the key considerations for insurers seeking to take advantage of opportunities in cyber? 2016 WAS another year of large data breaches for both Australian business and government, with the most memorable being the distributed denial of service attack that shut down the nation’s census website. As the number of data breaches continues to grow year-on-year, so does the cyber risk insurance market. There is tremendous opportunity for cyber risk insurance within the market today; it’s a line of business poised for significant growth. The nature of different risks within the market is still evolving (including factors such as the internet of things, for example), which means insurers will need to evolve their products quickly and respond to the market as it changes. There are three key factors that insurers should consider to successfully take advantage of future growth within the cyber risk market:
Risk management Leaders in the cyber risk market will be the insurers that provide an evolving risk management program that gives demonstrable value to the client. These insurers will benefit tremendously from the insight provided by their own risk management services to inform underwriting, adjust pricing and determine how to proactively respond to the market. Risk management, how it’s implemented, the value it brings to clients, and how it interplays with coverage will weigh heavily in the marketplace. Successful insurers will be able to tailor and scale services to the size, scope and need of each market segment. To make this successful and economical, insurers need to analyse and apply risk management options at the right level of activity
8
and at the right time. Throughout the life cycle of the insured, insurers need to leverage the data available about the insured, including their cyber activities and maturity, to determine which risk management activities the insured should be self-administering and what can be offered/ sponsored by the insurer. Artificial intelligence can go a long way to helping insurers determine how risk management models should be applied during the insured’s life cycle. Insurers that manage this well will have a leg up on the competition and will be on their way to creating a profitable book of business.
actionable insight to management and underwriting in real time, will enable insurers to change their pricing, underwriting, claims process, products and go-to-market strategy before the portfolio turns unprofitable.
Flexible systems Today, insurers’ ability to leverage the benefits of the first two points are tightly tied to how easy it is to update and change the underlying systems that support their business. Insurers need to be able to update rules, decisioning and processes to reflect an insurer’s emerging go-to-market strategy. Without this, insurers will be at risk of not being able to respond to the market quickly and effectively. One thing that is clear is most insurance environments are not up to the task of providing a flexible environment that can be responsive to both the market and the need to support underwriters. Often, the response to the needs of product innovation is to buy a new policy administration system, which is generally a huge investment that never results in the return insurers expect and does not give underwriters the tools they need to be effective.
“There is tremendous opportunity for cyber risk insurance within the market today; it’s a line of business poised for significant growth” Actionable analytics Cyber risk is similar to the growth and development of professional liability in the late 1970s and early ’80s. When professional liability took off, a lot of insurers jumped into the new, largely unknown market but were caught unaware as results developed horribly, horribly wrong. Insurers need actionable analytics (preferably with scenario-based planning) that help them monitor book and market performance to avoid making the same mistakes made by their professional liability predecessors. An insurer can’t think of all of the permutations, but what they can do is monitor results. This includes market penetration, risk assumed, claims trends, incident reports and risk management findings. Leveraging all of this data, and providing
Instead, insurers should be looking at core underwriting solutions that can sit on top of existing policy administration solutions and bring together the risk management, analytics, information, workflow, rules and product information underwriters need to act. Cyber risk is still a new market that is not yet fully defined. Investing in AI and underwriting systems that enable the points above will provide the most return for the dollar and help insurers write business profitably. Tom King is the senior director and industry principal of insurance at Pegasystems. Tom has more than 25 years of experience in the insurance industry. Tom.king@pega.com Twitter: @tomkingNJ
www.insurancebusinessonline.com.au
08-09_Opinion Subbed.indd 8
23/05/2017 11:47:31 AM
08-09_Opinion Subbed.indd 9
23/05/2017 11:47:36 AM
UPFRONT
NEWS ANALYSIS
TECHNOLOGY GONE BAD Never mind the challenge of innovating within the industry – technology is opening up new exposures across multiple sectors, and insurance needs to take note
IT’S NOTHING new to say that technology is changing the world, but while much lip service is paid to how digital innovation is affecting the insurance industry internally, less is known about some of the new risks that technology is opening up in many lines of business. Current issues range from the problem of connected devices and who will be liable for them in the future, to the network of cybercriminals using digital techniques to execute sophisticated scams. “With the interconnectedness of the world, every company is becoming a tech company to a certain extent,” says Emy Donavan, Allianz’s global head of cyber. From semi-autonomous cars to household
I think actually they’ll be the ones that lead us down the way,” Donavan says. “What concerns me more are the non-tech companies that are now doing tech,” she adds, pointing particularly to product manufacturers that are starting to integrate connected technologies into their offerings. The problem is exacerbated by the fact that there is a limited number of people who can advise on these products and the surrounding liabilities. Manufacturers of connected consumer products may end up facing major issues and product recalls if they are unable to get a handle on the vulnerability gap these devices open up, which can include the threat of hacking, as well as malware programs that can break devices.
“If, as an organisation, you aren’t hardwired to think about [cybersecurity] exposures, you inherently won’t” Emy Donavan, Allianz appliances, connected devices are creeping into more and more people’s homes and lives. But while many tech companies have a good understanding of some of the exposures these products can bring, just as many firms do not. “Tech companies have this in hand, and
10
As there is so much focus on speed to market and early adoption, companies may well be pushing out products without an understanding of the exposures they could face. “I think that companies that haven’t yet been forced to think about security aren’t yet,”
says. “If, as an organisation, you aren’t hardwired to think about those kinds of exposures, you inherently won’t.” The potential shift in liability as a result of these devices’ exposures is yet to be worked out, and Donavan believes there needs to be far more communication between the insurance industry, its regulators and the technology community to figure out how they will respond to these challenges. “Who ends up holding the bag?” she says. “I don’t know the answer to that – but I think people should start to think about how they want that to look.” And it’s not just devices that are vulnerable – cybercriminals are now using technology to manipulate people in “a modern-day version of the old con scams”, says Greg Bangs, XL Catlin’s global crime insurance head.
www.insurancebusinessonline.com.au
10-11_New Analysis Subbed.indd 10
23/05/2017 11:48:01 AM
CYBERSECURITY: THE CURRENT LANDSCAPE There will be as many as 20.8 billion connected devices in use worldwide by 2020.
The huge DDoS attack on global internet access in October 2016, which blocked websites such as Twitter, PayPal and Spotify, was conducted by hacking into hundreds of thousands of internetconnected devices.
Sixty per cent of US enterprises were victims of social engineering attacks in 2016.
The average loss from CEO fraud is US $120,000 (A$160,228), but some companies have been tricked into sending as much as US $90m (A$120.17m) to offshore accounts. Sources: Gartner Research, Guardian.com, ISMG & Agari, Federal Bureau of Investigation
Social engineering fraud – in which criminals gather information from social media platforms and company websites to use
the company and convince employees to transfer them funds. CEO fraud is particularly rife in Europe, Bangs says, and is especially
“With the increasingly technologically superior capabilities of the fraudsters, it seems they are always one step ahead” Greg Bangs, XL Catlin as psychological manipulation – is one of the hottest talking points in the crime insurance space. Two of the most common forms of scam are vendor impersonation, in which criminals impersonate a business vendor to reroute payments to themselves, and CEO fraud, where thieves pretend to be executives within
difficult to protect against. “This one is a little more insidious because the fraudsters are very good at using psychological pressure points,” he says, “so when they’re talking to the individual to try to convince them, they recognise right away what the right buttons to push are.”
Bangs says while these scams are happening “all the time”, the picture is still a little cloudy when it comes to coverage. “It’s an interesting landscape; a lot of [insurance] companies don’t cover [social engineering fraud] at all because they’re not comfortable with it, so they stick with the standard crime coverage and say, ‘We don’t like that; it’s too exposed.’ ” Others, including XL Catlin, do offer coverage, but limits vary, as there’s still some hesitancy in the space as the risks develop. Loss-wise, Bangs says there’s been an “explosion” in the computer fraud and wire transfer area, which has insurers concerned. “With the increasingly technologically superior capabilities of the fraudsters,” he says, “it seems they are always one step ahead of the good guys.”
www.insurancebusinessonline.com.au
10-11_New Analysis Subbed.indd 11
11
23/05/2017 11:48:05 AM
UPFRONT
INTELLIGENCE CORPORATE ACQUIRER
TARGET
PRODUCTS COMMENTS
AUB Group
LEA Insurance Brokers
AUB Group announced its acquisition of a 50% stake in LEA Insurance Brokers
Aon
Cut-e
Financial terms of the deal were not disclosed
Aon
Mayfair Group
Aon completed a deal for Mayfair Group’s international health and benefits brokerage portfolio
PSC Insurance Group
Online Insurance Brokers (OLIB) BCS Broking RP Hoxton Park
PSC agreed to pay $4m to acquire OLIB. PSC agreed to acquire 50% of BCS Broking – 50% over three years with an initial purchase price of $1.2m. PSC acquired the remaining 50% stake of RP Hoxton Park
CFC LAUNCHES REVAMPED CYBER OFFERING
CFC Underwriting has upgraded its cyber proposition with first party cover on an each and every claim basis, meaning policyholders will not be restricted by a policy aggregate and will be covered for multiple cyberattacks. The updated policy will also offer full retroactive cover as standard, which will cover policyholders if they discover a breach during their policy period, even if the event occurred before taking the cover. The revamped cyber product will also feature cover for senior executives, who are increasingly becoming targets of cybercrime. The product suite will also include comprehensive computer crime cover, system repair costs and incident response costs.
EBIX ANNOUNCES PREMIUM FUNDING UPDATE
AUB GROUP ANNOUNCES LATEST ACQUISITION
In April, AUB Group announced the acquisition of a 50% stake in Queenslandbased broker LEA Insurance Brokers. LEA, which has offices in both Brisbane and on the Gold Coast, is a founding member of IBNA and a member of the Council of Queensland Insurance Brokers, and has more than 4,000 clients across Australia. It has a number of authorised representatives and a strong life insurance business alongside its general insurance operations. The acquisition adds to the AUB Group-owned Austbrokers network, with five additional bolt-on acquisitions throughout the network already announced or completed in FY2017.
12
Ebix has announced an update to its premium funding interface. The update sees a pay monthly premium funding option available for WinBEAT and CBS, with a roll-out expected later this year on eGlobal and Ebix Evolution. The pay monthly module, referred to as background funding, allows brokers and clients to access funding in a more streamlined way. Previously, a separate contract was required by brokers to be able to offer clients a monthly payment option. Now all invoices and statements can automatically include an insurance funding payment option.
www.insurancebusinessonline.com.au
12-13_Intelligence Subbed.indd 12
23/05/2017 11:49:16 AM
CHUBB UNVEILS NEW ACCIDENT AND HEALTH PRODUCTS
Chubb has announced new products in the retail, healthcare and technology sectors. The suite of new accident and health products aims to safeguard employees in three sectors with unique requirements. The new tailored solutions, called healthcare staff protection insurance, retail staff protection insurance and technology staff protection insurance, offer accident, injury and disability benefits and can be offered in addition to standard employee compensation schemes. The new products will offer wide-ranging work hours coverage, including assault, trauma and stress benefits, and also offer terrorism benefits to employees. The suite will also offer around-the-clock assistance and security advice, as part of Chubb Travel and Medical Assistance, with crisis management assistance provided by red24.
SOLUTION’S CORPORATE TRAVEL COVER
Solution Underwriting has announced a new corporate travel policy aimed at brokers and their SME clients. Underwritten by Lloyd’s, the policy will offer round-the-clock assistance from Solution Emergency Assist, supported by Customer Care. The cover will extend to pre-existing conditions with unlimited medical expenses for up to 24 months, financial collapse cover and private leisure travel for company directors. Currently, the cover is available through Anita Lane, director of Solution Underwriting, who is the contact person for the product. At a later date, it will be available online.
NEW CYBER PRODUCT FOR AIRLINES TAKES OFF
Willis Towers Watson and AIG have announced a new product to protect the airline industry from cyber exposure. The new product, called CyFly, is available worldwide. The new cover will offer an extension of business interruption to third parties, which is a key addition for the airline industry. The cover extends to both IT service providers and non-technology firms. It will also offer network business interruption cover at a pre-agreed minimum value. The changes to business interruption coverage mean that airlines will be covered for specific risks in their industry.
PEOPLE NAME
LEAVING
JOINING
NEW POSITION
Danny Byrnes
IAG
Accident and Health International
CEO
Richard Feledy
n/a
Allianz Australia
Managing director
James Baum
n/a
Aon Risk Solutions
Managing director of commercial and chairman of Aon Broking
Andrew Godden
Arthur J Gallagher
BMS Group
CEO, Australia
Ben Howell
n/a
Chubb
Head of accident and health, Australia and New Zealand
Dean Osmond
n/a
Chubb
Environmental risk underwriter
Steve Cooke
n/a
Cunningham Lindsey
Executive adjuster, major and complex loss global construction team
Paul Stanyon
n/a
Cunningham Lindsey
Senior marine surveyor, major and complex loss global marine team
Peter Tomkins
n/a
Gallagher Bassett
General manager, specialty markets
Sam Mayne
BMS Group
High Street Underwriting Agency
National underwriting development manager
Mark Baxter
n/a
QBE Insurance
Chief risk officer, Australia and New Zealand
Simon Allatson
n/a
Sportscover
CEO
James Leung
n/a
Willis Towers Watson
Regional director, business development and proposition, health and benefits, Asia and Australasia
Rory Morison
n/a
XL Catlin
Head international casualty, Asia-Pacific
GODDEN LEAVES AJG FOR BMS
Andrew Godden has been appointed CEO, Australia for independent specialist insurance broker BMS Group. Godden will arrive at BMS Group after having been Arthur J Gallagher’s chief executive for its Australian operations since 2010. He has more than 30 years of industry experience, including co-founding Specialist Broking Associates in 2003 (which was acquired by AJG in 2010). According to a statement, Godden’s appointment will further enhance the reach BMS has been developing in Australia and across the Asia-Pacific region. His appointment will take effect when his contractual obligations to AJG expire, and he will be based in Sydney.
MORISON TAKES ON ASIA-PAC ROLE
XL Catlin has promoted Rory Morison to head international casualty, Asia-Pacific. Morison has more than 15 years’ experience in insurance, having worked in the Australian and London Lloyd’s markets as a primary and excess underwriter for international casualty clients. In his new role, Morison will drive XL Catlin’s casualty business and market presence in Asia-Pacific. He takes on the role in addition to his position as underwriting manager, casualty insurance, for Australia. He will continue to be based in Melbourne.
www.insurancebusinessonline.com.au
12-13_Intelligence Subbed.indd 13
13
23/05/2017 11:49:21 AM
UPFRONT
INSURER UPDATE
INDUSTRY REACTS TO FEDERAL BUDGET How do industry leaders rate those aspects of the budget that will impact insurance?
Booth noted the suggested increase in jurisdiction for the new body represents the more worrying side of the changes. However, NIBA welcomes the government’s commitment to consult on jurisdiction with relation to general insurance and sub-limits within general insurance, which includes brokers. The ongoing need for greater mitigation funding remains a hot topic of conversation and, on that front, the industry was left disappointed by the budget. The government allocated just $26.1m for disaster resilience programs, which is well below the $200m a year recommended by the Productivity Commission.
“[The federal] government has to start taking this seriously” The industry has responded to the possible impact of the 2017-18 federal budget on the insurance space. In the budget, the government announced an overhaul of the manner in which financial disputes are dealt with, creating a one-stop shop for external dispute resolution, which could impact brokers. The new Australian Financial Complaints Authority combines and replaces the Financial Ombudsman Service, the Credits and Investments Ombudsman and the Superannuation Complaints Tribunal in an
NEWS BRIEFS
effort to reduce confusion for consumers, federal treasurer Scott Morrison announced. NIBA CEO Dallas Booth said that the changes may be unnecessary. “We are not sure why there is a need for brokers to be involved in a change of this nature [and] we are not sure why there is the need to have wholesale change of EDR in the first place,” Booth told Insurance Business. “There have been some instances of confusion … but I’m sure those matters could have been easily resolved without wholesale change.”
Insurers confirm commitment to ESL shake-up
Insurers have reiterated their commitment to pass on to clients savings related to the abolition of the emergency services levy (ESL). IAG, Suncorp, QBE, Allianz and CommInsure explained at an inquiry in Sydney in May how they’re preparing for the removal of the levy, on 1 July. Rob Whelan, Insurance Council of Australia CEO, said the removal of the ESL will help lower premiums and insurers will pass on “all savings attributable” to the removal of the ESL to their customers.
14
“The Insurance Council of Australia is disappointed the budget does not address the urgent need for a significant increase in spending on nation-building mitigation infrastructure and resilience measures,” Rob Whelan, CEO of the ICA, said in a response to the budget. According to Booth, NIBA shares the ICA’s disappointment. “Government has to start taking this seriously,” he said. “We think they got the message out of [Cyclone] Debbie, which was yet another reminder of the importance of mitigation. It just has to be done.”
AIG appoints new global CEO
AIG has announced the appointment of Brian Duperreault as president, CEO and director. Duperreault was previously chairman and CEO of Hamilton Insurance Group and, before that time, was president and CEO of Marsh & McLennan Companies. He worked for AIG for 21 years at the start of his career. In a statement, Duperreault said: “It is a privilege to return and lead AIG. I look forward to building on AIG’s nearly 100year heritage as one of the world’s leading insurers for its next century.”
www.insurancebusinessonline.com.au
14-15_Insurer Update Subbed.indd 14
23/05/2017 11:49:46 AM
Q&A
icare in 2017 John Nagle Group executive, workers insurance ICARE
Fast facts icare was established in 2015 as the NSW government’s insurance and care organisation. A $33bn not-for-profit social insurer, icare is today one of the largest insurance organisations in Australia.
How crucial a role is technology playing in the customer service experience you ultimately aim to offer? Technology is critical to icare’s new operating model, particularly in how it can help us make the entire workers’ compensation process – from purchase and renewals, to policy management and claims – simpler, easier and less complex for our customers. From the end of 2017, our self-service platform will offer more sophisticated functionality, like the ability to access policy data online, including premium rates and claims history. The site will also give our customers access to expert advice from icare workers insurance specialists, on how they can improve their workplace safety and premium performance. We’re very keen to harness the power of data analytics technology in transforming the business and to provide a world-class customer experience. We just kicked off our data and analytics project that’s focused on using our own data, as well as data from external sources, to better inform our business decisions and deliver a more customerfocused experience.
What will change in terms of the way in which brokers are part of the process? We believe that brokers will continue to operate as a key partner of icare, working with employers to assist them with buying a policy, advising them on how to better understand their premiums, and guiding them on how to improve their safety and risk profile. However, we envisage there will be some change to
QBE CEO talks $50m fintech plans
QBE revealed some of its fintech plans at its recent annual general meeting in Sydney. Earlier this year, the global insurer announced it would set aside a budget of $50m for investments in technology in 2017 alone. According to ShareCafe.com.au, group CEO John Neal said at the AGM: “Following due diligence, I expect we will form initial partnerships with three or four insurtech companies, and I look forward to sharing more detail of our progress at the annual general meeting next year.”
how they work with us. Historically, the broker role has been more focused on claims estimation. We see the future value brokers can add to our mutual customers is around evidenced-based loss prevention and return-to-work strategies for employers, which are the drivers for lower premiums.
Can you talk about how brokers can best ensure they can continue to play an important role in your future model? We appreciate the valued, trusted advisor role that brokers play with their customers, and we’re committed to developing our relationship with our broker network. With this in mind, the goal of our new claims operating model is to empower both brokers and employer groups as customers. This is a fundamental part of the simple streamlined nature of the new claims operating and service models icare is developing for employers. This may mean that brokers will need to update their offering – moving from a focus on claims estimates and altering WIC [WorkCover industry classification] descriptions, to ensuring employers understand the need to have proper return-to-work strategies and engagement with injured workers. These changes may initially prove challenging for some. However, we are very happy to engage and support the broker community with the insights and tools they need to support employers and show the value of their expertise … or to look at new service offerings around evidenced-based loss prevention.
Beazley reveals new cyber threat
The latest Beazley Breach Insights report, from the cyber specialist Beazley Breach Response services, says phishing scams aimed at accessing direct deposit funds have emerged as a growing cyber threat, particularly in higher education. Direct deposit phishing sees hackers try to access an employee’s email and, once inside, request a password reset for the firm’s payroll provider. Hackers then change an employee’s forwarding rule to send all emails from payroll to a junk email folder as funds are stolen.
IAG sees “ticking time bomb”
IAG has warned that faulty flexible hosing beneath sinks could be a “ticking time bomb” as they’re the leading cause of household water damage. Data shows that flexible hoses accounted for 22% of water damage claims in Australian households in 2016. Properties between 11 and 30 years old were most likely to suffer an escape of water claim, IAG noted. Cheryl Chantry, IAG’s executive general manager, short tail claims, said flexible hoses should be checked every few years to reduce risks.
www.insurancebusinessonline.com.au
14-15_Insurer Update Subbed.indd 15
15
23/05/2017 11:49:55 AM
UPFRONT
UNDERWRITING AGENCIES UPDATE NEWS BRIEFS Allianz and Dawes announce partnership
Allianz has become the new underwriter of Dawes motor insurance products, taking over from Great Lakes. Allianz will now underwrite a portfolio of exotic and prestige vehicle products, applying to all new business and renewal transactions from 1 May 2017. Simon Lightbody, CEO of Steadfast Underwriting Agencies, said the deal would benefit brokers. “We believe the continued focus of Dawes providing exemplary service and innovative solutions to brokers, backed by Allianz’s capital strength, is a dynamic combination that will benefit the Australian broker market.”
New marine partnership unveiled
A new strategic partnership has been forged between Proteus Marine Insurance – part of the NM Insurance Group – and QBE Insurance Australia for the Steadfast network. It will include new business development underwriters focused on supporting the Steadfast network locally, with QBE providing security, and sees Proteus acting as the underwriting agent for QBE for Steadfast brokers’ new business from 1 May. “We look forward to working with our partners to maximise the opportunities they have in this sector, and continue to be a partner of choice nationwide,” said Lyndon Turner, NM Insurance CEO.
Banks steps down
Accident and Health International (AHI) announced in April the resignation of CEO Peter Banks. Banks, who has been with the business for 18 years, has stepped down to “pursue new opportunities”, the company said
16
in a statement. Renato Foenander, who was acting CEO until the recent appointment of Danny Byrnes, wished Banks well and stressed that AHI would continue as normal. Banks was made CEO of AHI nearly two years ago, having worked his way up through the ranks in his career with the underwriting agency.
Pressure on insurance workers as terrorism rises
A worldwide rise in terrorism attacks in 2016 – including a 174% increase in Western countries – is making for an increasingly volatile operating environment for international business, according to Aon. Alongside terrorism, businesses around the globe are facing growing exposure to political violence risks. For the second year in a row, more country risk ratings were increased than decreased, Aon’s 2017 Risk Maps for Political Risk, Terrorism and Political Violence found. Aon’s Scott Bolton told Insurance Business the risk map’s findings revealed a greater need for brokers and clients to “engage and fundamentally understand” an entity’s exposures.
SURA Film and Entertainment marks 35 years
In May, SURA Film and Entertainment celebrated 35 years of supporting the film and television industry across Australia and New Zealand. Over that time, it’s played a vital role in many of the country’s biggest film projects, including Crocodile Dundee, BMX Bandits and The Dressmaker. While its name has changed (it was Cinesure when first established), the agency says what remains the same is its commitment to the highest standard of professionalism. Its leader is Joe Lo Surdo, a 25-year industry veteran.
‘DIVE IN’ DELVES DEEPER IN 2017 Attendees can expect a bigger and better festival in Australia this September The Dive In festival for diversity and inclusion in insurance has taken on a life of its own, Australian Lloyd’s chief Chris Mackinnon told Insurance Business recently. Last year, the festival involved 10 locations in Asia-Pacific, Europe and North America, including over 45 events in 16 cities. In 2017, the Australian festival will include at least eight events, with several to be held in Sydney and at least one each in Melbourne and Perth. “It’s really taken off, which is absolutely
“[The Dive In festival] has really taken off, which is absolutely spectacular” spectacular,” Mackinnon said. “We’re also working … on developing an Australian insurance industry survey around diversity and inclusion, so we can actually start benchmarking how we, as an industry, are performing in isolation of the banking and finance sector, which is where we’re currently lumped … We’re hoping that if we can get this going, we will be able to launch some data and findings at the 2017 festival.” Mackinnon continued: “The intention is to basically draw a line in the sand at the 2017 festival and tell everybody what we know, and then give people some tips and ideas and strategies about how to change and improve. And then in 2018, when we run the survey again, hopefully we can demonstrate that we are actually making a difference.”
www.insurancebusinessonline.com.au
16-17_Update UAs_SUBBED.indd 16
23/05/2017 11:50:17 AM
S
www.insurancebusinessonline.com.au
16-17_Update UAs_SUBBED.indd 17
17
23/05/2017 11:50:22 AM
PEOPLE
THE BIG INTERVIEW
SEEING BEYOND BORDERS Carol Barton, president of AIG Multinational, talks about protecting businesses as they expand their global footprint and contemplates what’s ahead for underwriters A SEASONED insurance industry professional, Carol Barton is the global leader of AIG’s multinational division, charged with providing solutions for organisations whose business interests cross borders – an increasingly important focus in today’s rapidly evolving world. “Twenty years ago, there were about 33,000 companies that did cross-border business globally,” Barton says. “Today, it’s probably 193,000 plus companies. It’s almost a business imperative to be multinational, but the landscape in multinational is changing. In every country, there are different regulations, a different cultural environment, and there is different employment law. From an insurance perspective, staying current and being compliant is critical.” AIG’s solution to these challenges, Barton explains, has been to focus on a few key areas: “What we have been doing is investing in people, process and technology to drive insights, solutions with risk transfer and risk management capabilities, and service in a globally consistent and seamless fashion.”
The risk landscape On the subject of new and emerging risks, Barton mentions the word on everyone’s lips: cyber.
18
“We’re seeing a huge uptick in take-up on [cyber insurance coverage],” she says. But she stresses that it’s not just about providing cyber risk transfer solutions. Also integral is assisting clients in preparing for a potential cyberattack – particularly in light of the escalation in cyber risk that’s been driven by heightened connectivity as a result of the internet of things.
Barton considers global aggregation exposure to be the greatest challenge facing the insurance industry today. “For me, the biggest challenge in terms of helping our clients is to really look at some of these emerging risks, look at the fact that most of them are aggregate exposures, and then managing that in a way that we will be there for our clients when an event occurs.”
“It’s almost a business imperative to be multinational, but the landscape in multinational is changing. From an insurance perspective, staying current and being compliant is critical” “While it is a plus in many regards to have so much connectivity … it is also creating a very porous environment where people can get in,” Barton says. She adds that part of the challenge of cyber is the fact it’s an aggregation risk. “It’s not just about an individual company; it’s about how many potential companies might be impacted by the same event. It’s similar to supply chain risk, which is getting ever more complicated, as well, as a result of the internet of things.”
Another major challenge under Barton’s purview is contract certainty. “For multinational clients, it would be getting policies out in a way that gives them contract certainty when the loss occurs, and that has historically not been done,” she says. “We’re very focused on a new multinational, end-to-end process where we have taken the work and lifted it ahead of the effective date so that we end up with policies issued on or before the effective date. We rolled that out last year, and we are starting to get traction.”
www.insurancebusinessonline.com.au
18-21_The Big Interview Subbed.indd 18
23/05/2017 11:50:45 AM
Photo by Barbie Schwartz
www.insurancebusinessonline.com.au
18-21_The Big Interview Subbed.indd 19
19
23/05/2017 11:50:51 AM
PEOPLE
THE BIG INTERVIEW
It’s a work in progress, Barton adds, but it’s an effort to reshape the way business is conducted. “We are very excited about it because it will give our clients contract certainty and meet their governance objectives as well,” she says.
Tomorrow and beyond Barton expects the role of underwriters to change in the coming years, thanks to the proliferation and exploitation of information. “The availability of data and our enhanced ability to start to collect data and use it in a way that can inform underwriters should really help with the risk selection and underwriting process,” she says.
“You will still have your expertise, but I think underwriters will work more as a team to provide holistic solutions versus staying in their product silo.” In times ahead, Barton also foresees underwriters will have increased interaction with clients. “Underwriters will be interacting more with brokers and clients … and [there will be] a lot less focus on administrative, transactional, non-value accretive-type activities. I think it will be a lot of fun – it will be even more interesting than it is today.” In looking towards the future, Barton also emphasises the ongoing importance of the broker channel to AIG.
“We obviously see our broker partners as very critical and important, and we are always looking for continuous improvement opportunities and for feedback from them” “One of the trends we’re seeing is the ability to take claims data and use that for both underwriting risk selection and to help the client understand exposures that threaten their business, thereby allowing them to drive down their long-term cost of risk.” She also emphasises the significant role data can play in helping underwriters – and their clients – learn from losses. “The ability to share knowledge and understanding is critical, and insurance carriers are uniquely positioned to deliver. I think more and more, with technology, we will be able to do a better job at that.” Barton also anticipates that the future will bring greater appraisal of risk from a holistic perspective. “We have grown up as a very productoriented company – you had property people, casualty people, financial lines people … and now, I see that coming together in a more holistic view,” she says.
20
“We obviously see our broker partners as very critical and important, and we are always looking for continuous improvement opportunities and for feedback from them on how we are doing [and] what we can do differently … and then how they can support us, because a relationship is two-way.” As for the year ahead, Barton is focused on AIG’s global goals, including delivering on the two-year targets the company set in its January 2016 strategic update. “We are well on the way to delivering on that plan,” she says. “We have released $18bn to our shareholders. Our goal is $25bn over the two-year period, and we have every intention of returning the rest and achieving that target, as well as the other goals that we publicly stated. “We are committed to continuing to really sharpen our focus and being sure to work with clients, where we can add the most value.”
AIG BY THE NUMBERS
1919
Year when AIG was established by Cornelius Vander Starr, who started an insurance agency in Shanghai, China under the name American Asiatic Underwriters
1957
Year when AIG’s first office in Australia opened, in Melbourne
90 million
Number of AIG customers around the world
56,000
Approximate number of AIG employees worldwide
US$11.31bn
AIG’s revenue for the first quarter of 2017
www.insurancebusinessonline.com.au
18-21_The Big Interview Subbed.indd 20
23/05/2017 11:50:55 AM
www.insurancebusinessonline.com.au
18-21_The Big Interview Subbed.indd 21
21
23/05/2017 11:51:06 AM
FEATURES
R OF THE Y E E UR
AR
INS
BROKERS ON INSURERS
BROKERS
ON INSURERS
BROKERS NAME AUSTRALIA’S TOP INSURERS OF 2017 Which insurers are winning favour among Australian brokers right now? Insurance Business presents the results of its annual Brokers on Insurers survey
WHICH INSURER is providing a level of service to brokers that’s setting the standard for its competitors? Which insurer is impressing brokers most when it comes to the extent of product innovation in which they’re engaged? And which insurer continues to pip its competitors at the post when it comes to the speed of its claims turnaround times? Insurance Business has now conducted its Brokers on Insurers survey for five consecutive years, which seeks to answer those all-important questions with feedback from our broker readers. The time has now arrived to reveal the results of our 2017 survey. Yet again this year, Insurance Business asked brokers to rate several insurers across 11 categories, and to identify which individual aspects of their dealings with insurers have been most crucial in informing
22
their overall impression of those insurers. So, how precisely did insurers score in 2017? Have some improved in the eyes of brokers? And which insurer has succeeded in taking top honours – the title of 2017 Insurer of the Year? Let’s launch into the full results of the 2017 Brokers on Insurers Survey. We invite you to turn the page and find out exactly what our surveyed readers had to say.
BROKERS ON INSURERS 2017
Tim Garratt Editor, Insurance Business
www.insurancebusinessonline.com.au
22-33_Brokers on Insurers_SUBBED.indd 22
23/05/2017 11:53:02 AM
BROKERS ON INSURERS: THE METHODOLOGY Using our online newsletter and Twitter, we invited brokers to rate the performance of several insurers: AIG, Allianz, Berkshire Hathaway Specialty, Calibre Insurance, CGU, Chubb, QBE, Vero, XL Catlin and Zurich. We had 426 survey respondents who rated these insurers on a scale from one (very poor) to five (very good) over 11 categories. The categories were: Claims turnaround times New business turnaround times Brand recognition BDM support Broker training and development Online platforms Commission structure Product innovation Product range Overall service level Premium stability Brokers also rated the importance to them of each of these categories on the same one to five scale. An average was then generated for each insurer in each category, and an overall average was calculated based on each insurer’s performance across all 11 categories. Additionally, brokers were asked a number of questions about how insurers had performed in the most important areas, and about their best and worst experiences with insurers.
WHAT’S IMPORTANT TO BROKERS: THE TOP FIVE 5
4.76
4.61
4.50 4.24
4
4.13
3
2
1
0
Turnaround time claims
Overall service level
New business turnaround time
WHAT BROKERS WANT While various factors will influence a broker’s overall assessment of an insurer, there’s no escaping the fact that it ultimately comes down to how the organisation performs at crunch time. When a client is in their hour of need, how expediently does the insurer fulfil its contractual obligation to pay the claim? How does it support a client through the process, working to minimise the impact of any loss or damage incurred? It’s far from surprising that, once again in 2017, when asked which factors were of utmost importance to them in their dealings with insurers, brokers voted ‘turnaround times on claims’ as top of the list. Brokers must have confidence that they’re steering clients towards risk transfer solutions offered by
Premium stability
BDM support
insurers that can be counted on to come through when things go wrong. When Insurance Business asked brokers to cite the best thing an insurer had done for their business, or client, in the last 12 months, a substantial number of their responses related to claims. “Consistent turnaround times on enquiries and claims” was the response provided by one broker. Another was impressed by support received from one insurer on a particularly complex claim, while a third described an insurer as having gone “above and beyond for a big claim”. One broker recalled a recent experience of a colleague, who’d had three claims paid overnight within the past two months. Meanwhile, another broker singled out “consistent turnaround times on enquiries
www.insurancebusinessonline.com.au
23
FEATURES
BROKERS ON INSURERS
and claims” as what had impressed them most in their recent dealings with one insurer. “[It] makes our jobs easier,” the broker commented. Additionally, several respondents reported involvement in claims in the last 12 months in which insurers paid on an ex gratia basis. Of course, brokers appreciate not only when their insurer partners come through with payment on claims, but also when those insurers interact with them in a manner indicative of a bona fide partnership. One broker was pleased that one insurer had “acted as a true partner to a new program, rather than just a supplier of risk capital”. Another broker said an insurer had “supported me in a significant claim as they promised when I first secured the account”. Making a commitment is one thing, but following through is another entirely! Several brokers were pleased to report having been “listened to” by their insurers. “[The insurer] listened to my client needs and adapted,” one broker said. “[The insurer] has actually recognised what we are trying to achieve and finally listened to us,” said another. And in a day and age when workloads are greater than ever before and our society is ever-increasingly reliant on technology, making the effort to show up in person is genuinely appreciated by brokers. “[The insurer] offered to meet with a client for comfort, giving the client a chance to see they are real,” one broker reported. “[The insurer has] come out and discussed an account (like the old days)” was the most positive recent behaviour of an insurer, according to another broker, while a third was impressed with one insurer for having “made a big effort to meet with key stakeholders of my clients”. Further, one respondent praised an insurer for having “stayed in communication with us with product updates and training sessions available”.
24
THE OTHER SIDE Brokers were similarly candid in sharing their worst recent experiences with insurers. Among the most common complaints was a failure to pay claims and an overall poor level of service. One broker told Insurance Business a particular insurer’s claims service “leaves little to be desired”. Another broker reported their experience of an insurer declining a claim that they then took to the Ombudsman, who decided the claim ought to be paid. “This has occurred three times in the past 18 months,” the broker said. Brokers complained not only about failure to pay claims but also about particular insurers’ risk appetite. One broker complained of an insurer’s “inability to underwrite like they used to. It seems they have become button pushes – if it doesn’t fit
the system, they rarely look outside their guidelines”. Comments about “not wishing to write business” came up several times. Brokers were also concerned about premium increases. One complained that a client had been hit with a renewal rate that had been increased by 35% without consideration given to the client’s claims history. “Their reasoning was that they shouldn’t have offered such a cheap rate in 2016 and the market was hardening,” the broker said. Another reported an insurer having “increased premiums and halved limits without giving us a heads-up and … not giving us enough time to review it with the client”. That feedback serves as a salient reminder to insurers that, as rates harden, effective communication with brokers that are serving impacted clients is essential.
WHAT’S IMPORTANT TO BROKERS: THE REST 5
4
4.08 3.74
3.70
3.69
3.63
Training & development
Product range
Commission structure
3.48
3
2
1
0
Online platforms
Product innovation
Insurer’s brand recognition
www.insurancebusinessonline.com.au
22-33_Brokers on Insurers_SUBBED.indd 24
23/05/2017 11:53:03 AM
TURNAROUND TIMES (CLAIMS) had improved but they were concerned that some claims departments “are reactive rather than proactive”. Another said times had improved with most Improved insurers but they were continuing to experience “some issues” with specific insurers, “especially regarding updates and claim status”. Another broker suggested that rather than having improved or worsened, things had remained much the same. “Claims are hit and miss with most insurers,” the broker reported. “Sometimes claims are smooth, other times we are continually having to chase up assessors and insurers to get anything done.” The insurer to emerge with the gold medal in this critical area is Chubb, which is no stranger to success in the turnaround times (claims) category, having now taken gold in four out of our five annual surveys. Several brokers took the opportunity in our survey to acknowledge good work that’s been done by Chubb when it comes to claims. “Chubb claims settlement for a large loss was exceptionally well handled,” one broker reported. A second told us that Chubb claims are “always fast”. And when asked to cite the best thing an insurer had done for their business, or client, over the past 12 months, a third broker specifically cited Chubb’s claims services. “Client satisfaction has been excellent,” the broker said. Taking silver – the same medal it won in this category last year – is Allianz. One broker described the global insurer as “exceptional” when it came to claims. A second broker commended Allianz for having been “amazing help with a few of my large claims … I couldn’t thank them enough for the support the SA team has shown me”. Meanwhile, a third named Allianz’s assistance on claims as the best thing
HAVE TURNAROUND TIMES ON CLAIMS IMPROVED OR WORSENED OVER THE LAST 12 MONTHS?
38%
Chubb
3.48
Allianz
3.24
CGU
3.15
Industry average: 2.96 Insurers take note: brokers still fervently believe that getting the claims process right is the most critical component of the insurance transaction. Their Brokers on Insurers survey responses have affirmed that perspective each and every year, and this has again been the case in 2017. Unfortunately, more than six out of 10 brokers who responded this year told Insurance Business that turnaround times on claims had worsened over the last 12 months. “Claims have definitely taken a backwards step,” one broker said. “Simple processing with most of the larger insurers has become increasingly frustrating.” Another broker was more damning, reporting that claims are “disgraceful at the moment”. One broker said claims turnaround times
Worsened
62%
INSURER
RANKING 2016
MOVEMENT
RANKING 2017
Chubb
1
–
1
Allianz
2
–
2
CGU
3
–
3
Vero
5
4
BHSI
–
5
an insurer had done for their business over the past year. And in third place, taking home the bronze medal it earned in 2016, we find CGU. “CGU would be the most consistently good claims services provided at present,” one broker told Insurance Business. Another commended CGU on the way in which the insurer had recently worked with the broker on finding a resolution for a claim, acting in good faith and paying the claim in a timely manner and “at underwriter level, not dragging the issue through the various dispute services”.
www.insurancebusinessonline.com.au
22-33_Brokers on Insurers_SUBBED.indd 25
25
23/05/2017 11:53:09 AM
FEATURES
BROKERS ON INSURERS OVERALL SERVICE LEVEL
QBE
3.21
Allianz
CGU
3.19
3.17
Industry average: 2.92
INSURER
RANKING 2016
MOVEMENT
RANKING 2017
QBE
1
–
1
CGU
2
–
2
Allianz
4
3
Vero
3
4
BHSI
–
5
Brokers have spoken, and they’ve told Insurance Business that they want to be dealing with trained staff, people who are available when they need them and who respond to their queries in a timely fashion. On the question of whether or not overall service had improved over the past 12 months, one broker told us, “Generally, insurers are looking at ways to improve service, which is noticeable and welcomed.” A second said, “I must say the major insurers are trying to improve their service, however I find with staff movements, either internal or external relationships have to
26
TURNAROUND TIMES be constantly rebuilt, which causes service standards to worsen.” But another took a contrary perspective, telling us, “Our industry has clearly forgotten that we are a service industry.” They specifically cited a “failure to be able to ‘think outside the box’ or provide adequate turnaround times on requests and accurate documents and poor claims services”. For the second year in a row, brokers have put QBE at the top of the table for overall service level. “QBE has, on several occasions, stepped up to the plate to fill where another insurer has let us down,” one broker reported. “QBE provide fantastic support from the underwriters, unlike many of their competitors,” was the feedback offered by another. Securing the silver medal is CGU, remaining in the same space it occupied in 2016. “CGU have looked at our portfolio and have been able to show different patterns in what we are selling and maybe need help in upselling and offering to clients in a different way,” one survey respondent reported. And moving up into third place is Allianz. “Allianz provided access to a dedicated support team,” said one broker who cited that access as the single best thing an insurer had done for their business in the past 12 months. Another simply cited Allianz’s “overall service” as having been that highlight for their own business.
Improved
40.5%
HAS OVERALL SERVICE IMPROVED OR WORSENED OVER THE PAST 12 MONTHS?
Worsened
59.5%
BHSI
3.37
Allianz
CGU
3.29
3.26
Industry average: 3.08
INSURER
RANKING 2016
MOVEMENT
RANKING 2017
BHSI
1
–
1
CGU
3
2
Allianz
4
3
QBE
2
4
Vero
5
–
5
Asked whether turnaround around times on new quotes had improved or worsened over the past 12 months, our broker respondents were almost evenly divided. “New business continues to be hard to come by and … given opportunities, insurers are quick to respond,” one broker said. “Overall most have improved and are wanting to write new business,” another told Insurance Business. “Insurers understand the importance [of] respond[ing] quickly,” a third said.
www.insurancebusinessonline.com.au
22-33_Brokers on Insurers_SUBBED.indd 26
23/05/2017 11:53:14 AM
(NEW BUSINESS)
Improved
49%
HAVE NEW BUSINESS TURNAROUND TIMES IMPROVED OR WORSENED OVER THE LAST 12 MONTHS?
PREMIUM STABILITY
Worsened
51%
Some attributed a perceived improvement to the use of online platforms. “Electronic turnaround has sped the quoting process up” was one comment we received. Another broker simply said, “New online channels are improving processes.” On the other side of the coin, those who believed there had been a slip in turnaround times often attributed that change to decreasing resources in organisations. “Staff cuts are affecting response times, [with] requests not answered for over a week [on] several [occasions],” one broker said. Another broker said it “seems like there is less staff and [they’re] not as well versed in product knowledge”. “Too much cost cutting leads to poor service,” a further broker said. Additionally, one broker complained that “Anything a little different or complex seems to take longer to gain a response”. The general insurer to receive the highest overall score from brokers on this front in 2017 is Berkshire Hathaway Specialty Insurance. It’s the second consecutive win in this category for Berkshire Hathaway (and, incidentally, the company has only been open for business in Australia for two years). CGU collects its second silver medal here (moving up from the third place it secured in 2016) and Allianz is the bronze medal winner, which is also an improvement on their finish in this category in last year’s survey.
Around two thirds of brokers participating in the survey said premium stability had worsened over the past 12 months. “We feel we are now starting to experience a hardening of the market with premiums starting to climb,” one broker commented. “Seems as though some Insurers will now prefer to let business go that they have retained for a long time over a few dollars.” Additionally, another broker reported “a lot of movement, with rapidly decreased premiums now being increased again”. Further, one broker said, “Premium stability is at its worst I have seen in the industry in my 12 years. This only seems to apply to the major players. Underwriting agencies seem to be able to keep the premiums stable.” And another simply said, “Rates seem to be all over the place at the moment.” Conversely, comments of those who’d noted an improvement in premium stability included a broker who told Insurance Business that “other
Allianz
3.24
Chubb
3.10
QBE
3.05
Industry average: 2.95 BROKER FEEDBACK
“Rates seem to be all over the place at the moment” than CPI and a modest increase, things were reasonably stable in the small SME market”, while another said insurers’ premiums had remained “pretty consistent”. A third said there had not actually been an overall increase when taking into account “the increased volume and cost of claims. Effectively, insurers have done well to be competitive in their selected markets”. After picking up the bronze in this category last year, Allianz has moved up to take the gold in 2017. “Allianz … have been working hard with us to keep premiums at an acceptable level” was the specific feedback we received from one broker. Also taking a place on the medallists’ podium is Chubb, who walk away with the silver medal. And finally, receiving the bronze, QBE rounds out the top three.
INSURER
RANKING 2016
Allianz
3
1
Chubb
4
2
QBE
1
3
BHSI
–
4
Vero
–
5
MOVEMENT
RANKING 2017
Has premium stability improved or worsened over the last 12 months?
IMPROVED
34%
WORSENED
66%
www.insurancebusinessonline.com.au
22-33_Brokers on Insurers_SUBBED.indd 27
27
23/05/2017 11:53:18 AM
FEATURES
BROKERS ON INSURERS BDM SUPPORT
Improved
33% Vero
3.26
HAS BDM SUPPORT IMPROVED OR WORSENED OVER THE LAST 12 MONTHS? Worsened
67% Allianz
QBE
3.03
3.21 Industry average: 2.58 INSURER
RANKING 2016
Vero
4
1
QBE
1
2
Allianz
=2
3
CGU
=2
4
Zurich
–
5
MOVEMENT
RANKING 2017
Approximately one third of broker respondents told Insurance Business that BDM support from insurers had improved over the past 12 months. “Most big insurers have picked up their game, as more and more niche agencies enter the market and encroach on their market share,” one broker responded. For others, the answer wasn’t quite so straightforward. “Sometimes it depends on the issue, [and]
28
the size of the account may also impact how supportive BDMs can be,” said a broker. “Some have improved and some have worsened. Some BDMS we see every month but some we haven’t seen at all,” a third broker commented. In fact, several of the brokers who took part in the survey reported seeing less of BDMs, particularly outside of metropolitan centres. “Less commitment from companies to service regional areas” was one comment received. “[I’m seeing less of BDMs than I have in previous years” was another. A third broker said, “Currently a smaller brokerage [and] I expect not to be a priority target. [But] at least a phone call now and again would reinforce a relationship!” Some brokers expressed concern about the lack of authority of BDMs. “BDMs need underwriting authority, visits to the office are more worthwhile when deals can be done,” said one broker. “BDMs seem to have no or very little authority to discount rates,” said another.
BROKER FEEDBACK
“[I’m] seeing less of BDMs than I have in previous years” Finally, one broker criticised BDMs for “generally little knowledge and even less willingness to help”. The insurer receiving the gold medal for BDM support in 2017 is Vero, with one broker naming a BDM’s site visit to a remote regional centre as the best thing an insurer had done for their business over the past year. In second place is QBE which, one broker said, “continues to be great”, while another broker commented that QBE had improved its service to regional brokers. And the bronze medallist is Allianz, which, according to one broker, had “gone out of its way to show its face in our office”.
www.insurancebusinessonline.com.au
22-33_Brokers on Insurers_SUBBED.indd 28
23/05/2017 11:53:23 AM
ONLINE PLATFORMS In our changing world, it’s no longer enough to be better than your direct competitors; it’s about delivering best-in-class service experiences that meet customer expectations, which are driven by service they’ve received right across the spectrum. In the survey, one broker said “more online system access” was the best thing an insurer had done for their business over the past year. Another said, “Some insurers are making significant improvements to service standards and putting energy into updating online platforms … Certain other insurers seem to just leave things as they are.” A third broker commented that “Online services are finally being looked at, but probably need a bit of a lift overall”. But while it’s important for online systems to
INSURER
RANKING 2016
Allianz
5
1
CGU
1
2
Zurich
2
3
Vero
4
QBE
3
MOVEMENT
–
RANKING 2017
Allianz
CGU
3.44
3.42
Zurich
3.41
Industry average: 2.94
4 5
make life easier for all concerned, a number of brokers emphasised the need for insurers to realise that a good online experience can never entirely replace person-to-person interaction. Brokers
expect they’ll be able to continue speaking to live human beings when they need to do so. Taking out the gold medal in our online platforms category for 2017 is Allianz which, not too long ago, released its SME platform, Allianz Alive. Our runner-up is CGU and Zurich takes the bronze.
PRODUCT INNOVATION
Chubb
3.05
CGU
3.03
BHSI
3.02
Industry average: 2.86 The changing world also brings with it a host of new exposures for which customers will require appropriate risk transfer solutions. Typically, broker readers who participate in this survey are very consistent in ranking
INSURER
RANKING 2016
Chubb
4
1
CGU
1
2
BHSI
5
3
Allianz
–
4
Vero
–
5
MOVEMENT
RANKING 2017
the indicators in their dealings with insurers that are of greatest and least importance to them. Interestingly, in 2017 product innovation moved up one rank from eighth to seventh. It’s perhaps a testament to an increasing desire by brokers across Australia to see insurers working harder to tailor solutions for their clients’ unique exposures. Asked about the best thing an insurer had done for their business, or client, within the past 12 months, one broker told Insurance Business that it was an insurer having “created a tailor-made product while keeping the
BROKER FEEDBACK
“[The insurer] created a tailormade product while keeping the premiums modest” premiums modest”. A second broker simply answered “product innovation” in response to the same question, while a third broker congratulated one specific insurer’s underwriting team for “working with us to build solid products”. Taking the gold medal in the product innovation category for 2017 is Chubb, a significant move up from the insurer’s fourth place finish last year. The silver medal goes to an insurer that’s become a regular top three member, CGU. And taking the bronze medal for product innovation this year is Berkshire Hathaway Specialty Insurance, which recently celebrated the second birthday of its Australian operations.
www.insurancebusinessonline.com.au
22-33_Brokers on Insurers_SUBBED.indd 29
29
23/05/2017 11:53:29 AM
FEATURES
BROKERS ON INSURERS BROKER TRAINING AND DEVELOPMENT
Vero
3.08
Allianz
2.99
CGU
2.98
Industry average: 2.51
This year, broker training and development also moved higher on the list of factors that matter to brokers in their dealings with insurers (from 10th to eighth place). Several brokers who took part in the 2017 survey told Insurance Business that training was the best thing an insurer had done for their business over the last year. “Providing regular training to brokers”, “staff training in various policy sections”, “internal training for new staff ” and “stayed in communication with us with product updates and training sessions available” were among the specific answers brokers provided to that question. Further, one broker participant provided the following insight: “Those insurers who have invested in training and also employment of skilled underwriters will continue to reap the rewards of increased business from brokers, who want to deal with professionals who know the
INSURER
RANKING 2016
Vero
2
1
Allianz
5
2
CGU
1
3
Zurich
4
QBE
3
MOVEMENT
RANKING 2017
–
4 5
risks and how to underwrite them.” Winning the gold medal in the training and development category is Vero. One broker commended Vero specifically for the one-day seminars it had run. Taking silver is Allianz, and rounding out the medallists in this category is CGU, which received a strong endorsement in the survey from one broker, who said “CGU [is] providing exceptional training and personal development for brokers”.
PRODUCT RANGE As well as a high overall level of service, fast turnaround times on claims and a willingness to innovate, brokers need insurers that offer a range of products that will afford their clients suitable protection. One broker respondent to our survey acknowledged an insurer for the “larger product range” it offered, while another commended an underwriting agency for the “interesting alternative” product it offered, compared to what was available from a number of major insurers. On the other side of the coin, when asked about the worst thing an insurer had done for their business over the past 12 months, one broker answered, “Ignore our concerns when we tried to give them details on making particular products easier to place”. It’s clear from survey responses that brokers greatly appreciate having the ability to work with their insurer partners to develop tailored solutions to address their clients’ unique exposures. Additionally, it’s imperative that insurers ensure clear lines of communication
30
INSURER
RANKING 2016
MOVEMENT
RANKING 2017
CGU
1
–
1
QBE
2
–
2
Allianz
3
–
3
Vero
4
–
4
Zurich
5
–
5
with brokers about the coverage solutions they have on offer. This year, CGU once again takes the gold medal for product range. In fact, the Melbourne-headquartered commercial insurer has taken gold in this category now for four consecutive years. Taking silver for the second year in a row is QBE, and in third place (also a result it achieved in 2016) is Allianz. As it happens, the top five in 2017 precisely mirrored what we saw in the 2016 survey.
CGU
3.77
QBE
3.68
Allianz
3.65
Industry average: 3.17
www.insurancebusinessonline.com.au
22-33_Brokers on Insurers_SUBBED.indd 30
23/05/2017 11:53:35 AM
COMMISSION STRUCTURE In March, Robert Kelly, managing director and CEO of Steadfast, told Insurance Business he believed the market was on an upward trajectory. “The next three to four months will really see finality on the cycle, in terms of who is going to be emphatic on their price rising and who is going to still lie around, dropping their pants every now and then,” Kelly said. But he also believes that, as the market begins to turn, broker commissions may come into the spotlight. With price rises, brokers will need to explain the value of the work they have done on behalf of a client to ensure they remain a part of the process. Simply approaching a client and informing them of price rises will not be good enough. Kelly said brokers should look to give clients an overview of the whole market as a way of explaining premium rises as fees may “come under pressure”. He added that “Clients will look at the fee
INSURER
RANKING 2016
MOVEMENT
RANKING 2017
CGU
1
–
1
Allianz
2
–
2
QBE
3
–
3
AIG
–
4
Vero
–
=5
Zurich
4
=5
structure as opposed to the cost of insurance”. Coming out on top of the leader board with respect to commission structure is, once again, CGU. This makes it three gold medals in a row in this category for CGU. Meanwhile, earning its fourth consecutive silver medal for commission structure is Allianz. And finally, picking up its second consecutive bronze medal here is QBE.
CGU
3.43
Allianz
3.38
QBE
3.31
Industry average: 3.13
BRAND RECOGNITION
Allianz
4.19
QBE
4.17
CGU
4.14
Industry average: 3.24 INSURER
RANKING 2016
MOVEMENT
RANKING 2017
Allianz
2
1
QBE
1
2
CGU
3
–
3
Vero
4
–
4
Zurich
5
–
5
For the fifth year in a row, the brand recognition category of the Brokers on Insurers survey is a three-way race between Allianz, CGU and QBE. On this occasion, it’s Allianz who’ve snatched the gold medal, following a silver finish in 2016. For several years, the ‘Ahhh … llianz’ campaign has prominently featured on Australian TV screens. But recently, Allianz Australia launched a new brand campaign that has focused on being ‘inspired’ and utilises the hit track ‘Chase that feeling’ by Australian hip-hop group Hilltop Hoods. “The message and feeling of this campaign is very positive,” said Kylie Jones, head of creative services, brand and media at Allianz Australia, in a statement. “It has been made to motivate Australians to get out there and live their lives, knowing that Allianz has got their backs.” Few would argue against the notion that Allianz remains one of the most visible brands in the insurance space.
Switching spots with Allianz in 2017 is QBE, which recently kicked off a new campaign highlighting its sponsorship of the Australian Football League’s Sydney Swans, the NSW Swifts netball team and the Perth Glory A-League football team. It’s a campaign analogising the unpredictable nature of sport to the unpredictable nature of life, and emphasising the need to safeguard against the unexpected. Again occuping the bronze step on the podium is CGU, which has continued with its ‘See it through’ campaign, and this been especially prominent given its rescue of the world’s largest short film festival, Tropfest. It’s CGU that has helped Tropfest to be able to ‘see it through’: the sponsorship will see the world-famous festival through for a further three years. Congratulations to each of our category medallists for 2017.
www.insurancebusinessonline.com.au
22-33_Brokers on Insurers_SUBBED.indd 31
31
23/05/2017 11:53:39 AM
FEATURES
BROKERS ON INSURERS
INSURER OF THE YEAR
CGU
3.30
QBE
3.21
Allianz
3.33
Industry average: 2.94 The scores have been tallied and final overall results calculated, and in what was an exceptionally close contest that separated first and second by 0.03, Allianz has emerged as the brokers’ choice for Insurer of the Year for 2017. Not only did Allianz earn the top score overall, but it walked away with a top three finish in 10 of our 11 individual categories, including three gold medals. Following closely behind Allianz, our overall silver medallist for 2017 is CGU, which has also chalked up a medal finish in nine out of our 11 categories, including two gold medals. Both Allianz and CGU have also achieved the distinction of having ranked in the overall top three insurers in each and every one of our five annual surveys to date
32
– a considerable achievement! Also securing a place on the podium for another year is QBE, which has taken the bronze. Australia’s own global insurer finished in the top three in six of our 11 categories, including winning a gold medal for its overall service level. Insurance Business congratulates the top-ranked insurers for 2017. But while it’s important to take time to recognise the positive work undertaken within these organisations that’s led to securing broker votes, it’s also necessary to stress the fact that this survey contains vital insights for every insurer in Australia. For those serious about ensuring that broker partnerships remain integral to their business model, the survey provides a
INSURER
RANKING 2016
Allianz
3
1
CGU
1
2
QBE
2
3
Vero
4
–
4
Zurich
5
–
5
MOVEMENT
RANKING 2017
snapshot of the current thinking of insurance brokers in Australia. So, which insurers will take steps to respond to the feedback brokers have offered? And which insurers will find themselves at the top of the table in our 2018 Brokers on Insurers survey?
www.insurancebusinessonline.com.au
22-33_Brokers on Insurers_SUBBED.indd 32
23/05/2017 11:53:41 AM
INSPIRING BROKERS According to David Hosking, brokers are vital to Allianz Australia’s business – and that’s not about to change any time soon David Hosking, Allianz Australia’s chief general manager of the broker and agency division, says it’s an honour for the company to be recognised by its broker partners as Insurer of the Year. “Clients are best served when brokers and insurers work together in order to exceed expectations in terms of product quality, innovation and service. Through our broker relationships we aim to satisfy the needs of both our brokers and their clients. “This award is an acknowledgment of not only our leading market proposition, but also our people, who, despite challenging market conditions, continue to seek opportunities to add value to our partners and their
clients,” says Hosking. He describes strong broker partnerships as critical to Allianz’s business. “Without these, we don’t survive. It’s as simple as that,” Hosking says. “There are challenges at the moment – changes in consumer expectations, increased capacity, and we’re coming off the back of declining premium rates. During this period of change, it is vital that we strengthen and promote our partnerships with brokers. At Allianz, it is about relentlessly focusing on service and relationships and investing to make it easier to do business with Allianz.” Hosking says, in recent times, Allianz has delivered a number of key projects unique to the business, which are integral to helping it deliver a “consistent, sustainable and simplified experience”. He mentions the launch of Allianz Alive.
expanding ‘One Allianz’ offering. “We are uniquely placed to provide the broadest possible range of insurance solutions for brokers and their clients. We partner with specialist underwriting agencies and our global businesses to provide a single path to market where there is a clear and identifiable need for specialisation,” Hosking explains. So, what does it take to be a high performing insurer in this day and age? “Being a high-performing insurer means offering consistent and sustainable premiums, supported with a service offering that brokers and clients can rely [on] and being seen as easy to do business with,” he says. “We have adopted a customer-centric model where our client is at the centre of everything we do. As part of this model, we have dedicated experts available to support brokers and their clients at all points of the customer life cycle, including developing and delivering solutions, claims service and relationship management.” Hosking talks about times ahead. “We have seen an increase in the pace of change, which has provided real opportunities for us as an insurer to enhance the way brokers transact business with us through technology,” he says. “Following the successful launch of Allianz Alive for SME Packages, we will be rolling out
“During this period of change, it is vital that we strengthen and promote our partnerships with brokers” “Allianz Alive is our SME packages solution designed to make Allianz easier to do business with. The system features an intuitive and modern interface, indicative pricing capability, and a point of differentiation between policy and situation risks. It is supported by an advance rating algorithm to ensure consistent, sustainable pricing.” He also refers to Allianz’s Tailored Solutions Offering, focused on the mid-corp business that sits above SME and below the large corporate and international clients served by AGCS. Then there’s also its
Instalment Billing. Down the track, we will be adding Farm Pack to Allianz Alive, which will improve and automate existing underwriting processes for our brokers in the growing agricultural sector. We will continue to evolve our Tailored Solutions offering to make it easier to place the right risk with Allianz and continue to promote the specialist agencies that we have partnered with as part of our One Allianz offering.” Congratulations to Allianz Australia, the Insurance Business Brokers on Insurers Insurer of the Year for 2017.
www.insurancebusinessonline.com.au
22-33_Brokers on Insurers_SUBBED.indd 33
33
23/05/2017 11:53:46 AM
FEATURES
ENVIRONMENTAL LIABILITY INSURANCE
THE CLEAN-UP COVER Liberty International Underwriters’ Alan Thorn and Wotton + Kearney’s Raisa Conchin examine the increasing relevance of environmental liability insurance in Australia
Who needs it? Historically, environmental liability insurance was considered a necessity for only certain types of insureds, such as mines, chemical plants and waste management companies. However, in recent years, government agencies such as the Environmental Protection Agency (EPA) have been increasingly vigilant in identifying and responding to environmental events. Where a contaminant or pollutant is released into the environment, the EPA will commonly exercise its statutory powers to require a party to clean up the contamination. Clean-up obligations are usually imposed on the party responsible for the contamination, but they can also be imposed on the owner of the contaminated land (regardless of fault). Further, as this type of regulatory intervention becomes more common, it is not limited to large corporates and is often directed against SMEs. In Queensland, the scope of the EPA’s power to require individuals to undertake clean-up activities is particularly broad. The other issue is that these types of environmental events can be difficult to predict. In April 2017, a large volume of
34
fire-fighting foam was released from a Qantas hangar at Brisbane Airport into local waterways. The release had far-reaching implications for the local seafood industry. Given the nature of the insured location (an airport hangar), the risk of fire-fighting foam being released into the environment may not have been an obvious one. The upshot is that more companies and individuals need environmental liability insurance.
What is it? Environmental liability insurance provides first and third party cover for losses arising from a ‘pollution condition’. A pollution condition is generally defined as the release of a pollutant onto land or into surface water, groundwater or the atmosphere. The term ‘pollutant’ usually encompasses any solid, liquid, gaseous or thermal irritant, contaminant or pollutant. It includes pollutants such as soil, silt, sediment and mould. The cover under an environmental liability policy is far greater than the traditional view of pollution, which was historically limited to
inherently hazardous materials. The scope of the cover is determined by reference to a covered location. The relevant pollution condition must occur on, at or under – or must migrate from – the covered location. Some policies also cover pollution conditions arising in the course of transporting materials to and from the covered location. The first party cover is triggered by the insured discovering the relevant pollution condition. Cover is available for the insured’s own clean-up costs. There can also be cover for the costs of repairing or replacing any property damaged by the pollution condition and/or any business interruption losses suffered by the insured. The third party cover is triggered by the insured receiving a third party claim, which generally also includes a notice received from a regulator such as the EPA. This cover responds to claims against the insured alleging liability for personal injury, property damage or remediation costs. It extends to the insured’s costs of defending the relevant claim. Where the claim takes the form of a prosecution, there is generally cover for any fines or penalties imposed on the insured and the associated defence costs. The costs of defending a prosecution can quickly escalate, depending on the approach taken by the EPA and whether the suit is also being pursued against a director or officer of the insured (in which case the director/officer may need separate representation from the company). It is not unusual for the defence costs to exceed the amount of any fine or penalty ultimately imposed. There are other more specific forms of environmental liability cover. For instance, contractors can purchase environmental liability insurance, which covers their work on any premises (as opposed to a covered location). There is also specific insurance available
www.insurancebusinessonline.com.au
34-35_Ad led Environmental Risk_SUBBED.indd 34
23/05/2017 11:54:11 AM
Brought to you by
It is not unusual for the costs of investigating and remediating a significant pollution event to run to six or seven figures for underground storage tanks, commonly found in the ground underneath commercial premises.
Why buy it? Environmental liability insurance plugs a significant gap in the market, particularly in respect of clean-up costs, first party mitigation expenses and emergency response costs. A general liability policy does not provide first party cover for remediation costs. Further, the cover for third party claims is far narrower than under an environmental liability policy. For example, a notice received from the EPA will generally not qualify as a claim for compensation
for the purpose of the insuring clause. In addition, the third party cover is often restricted by a pollution exclusion, which excludes any claims arising from a gradual (as opposed to a sudden and accidental) pollution event. Some general liability insurers are taking a stricter position on the interpretation of these exclusions, leading to an increase in declined claims. Further, although insureds can purchase statutory liability cover for fines and penalties where permissible by law (either as a standalone product or as part of a management liability policy), this cover does not extend to clean-up costs.
Clean-up costs can be expensive. It is not unusual for the costs of investigating and remediating a significant pollution event to run to six or seven figures. In recent times, a largescale remediation program involving the removal of friable asbestos from a development site in Queensland cost insurers over $5m. Further, some remediation programs – such as where groundwater contamination has occurred – can take years to implement and monitor. An environmental liability policy can provide muchneeded cover for an insured dealing with the fallout of a significant environmental event, from both a first and third party perspective. Alan Thorn is a senior underwriter specialising in environmental impairment liability at Liberty International Underwriters. Raisa Conchin is a partner at Wotton + Kearney.
www.insurancebusinessonline.com.au
34-35_Ad led Environmental Risk_SUBBED.indd 35
35
23/05/2017 11:54:20 AM
FEATURES
BUSINESS INSIGHT
EVARI He’s the former local leader of one of the world’s biggest insurers. Now, Daniel Fogarty has turned his attention to driving change in insurance, launching a brand new insurtech venture
DANIEL FOGARTY is passionate about assisting small businesses. “Small businesses play a hugely important role in our economy … and they need to be properly insured so that when disaster strikes, they’ve got the financial means to recover and continue in business,” he tells Insurance Business. It’s that passion that’s led Fogarty to co-found Evari, a new insurtech start-up. “Evari is a direct to small business online insurance operation,” Fogarty says. “We’re thinking right the way across the value chain to re-think how small businesses buy and manage their insurances. With the technology we’ve got, we do have some amazing freedom and flexibility to do that well. “Our point of difference is we will be
delivering to customers in a way that makes most sense to them.” Fogarty says this opportunity brings together several skills he’s developed over his insurance career. “I’ve been fortunate to have some great experiences in the insurance industry, both in intermediated and direct insurance [and] in personal and commercial. I was also fortunate to go to business school in Silicon Valley and while I was there, this entrepreneurial bug caught me. I’ve seen how challenging it is to get change in a big company. Being in a small company, you can be more adaptable and flexible to the customer’s needs.” Fogarty’s Evari co-founders, Robert Jeffery and Brack Norris, are from backgrounds outside insurance.
LESSONS LEARNED FROM YEARS IN INSURANCE “Our customers just want to know they have the right cover [and] that it has been easy to purchase and maintain. But delivering against a simple goal is really difficult, because we know insurance is complicated, and we need to look after the best interests of the client while managing through the compliance issues to make sure we service them the right way, while also making a return to the shareholder. “What I’ve learned in my career is how to manage through this maze of challenging variables and to do it properly.”
36
“They come from strong technology backgrounds,” he says. “I’m a great believer in diversity, and diversity of thought is critical in achieving new ways of doing business. “Having those different backgrounds has been critical for us. We have a range of ages as well, and my two business partners have experience in the start-up world, whereas mine is big-company experience, so they’ve been helping and guiding me on the entrepreneurial journey.” Fogarty discusses the benefits of having such diversity in the Evari team. “My two business partners thought about this business firstly from a technology aspect, and now that we’re in business, we’ve got more people in our business with technology and customer experience backgrounds than we have with insurance backgrounds. They are challenging the insurers in the team on our thinking.” Fogarty talks about the opportunities the growing insurtech space in Australia affords the industry. “I’ve read that insurtech is maybe a Kodak moment for the insurance industry, whereas the way I like to think about it is, really, we’re at a Wi-Fi moment for the Australian insurance industry,” he says. “Our industry is really well developed by international standards; we have very smart people who really understand insurance; we have the access to technology; we now have increasing access to capital … and we have a marketplace where customers want to try new things.” Fogarty believes the Australian industry has all the attributes necessary to build an insurtech space that’s the envy of the rest of the world. He mentions the great technology available for the industry’s use today. “We’ve been using Amazon Web Services as the basis of a lot of things we’re doing. The technology that’s available through AWS is amazing, and we can build enterprise systems at a much lower cost than we could in the past.” Fogarty says that while the Evari team has
www.insurancebusinessonline.com.au
36-37_Business Insight Subbed.indd 36
23/05/2017 11:54:47 AM
FAST FACTS Specialty: Addressing business insurance needs of SMEs Website: www.evari.insure Locations: Sydney and Perth Co-founders: Pictured from left to right: Robert Jeffery, Brack Norris and Daniel Fogarty
Daniel Fogarty’s career in insurance: Currently serves as a director of the Board of the Australian and New Zealand Institute of Insurance and Finance (ANZIIF) Served as Zurich’s CEO of general insurance, Australia and New Zealand from mid 2012 to late 2015 Joined Zurich in 2009, becoming its chief operating officer in 2010 and then executive general manager, corporate in 2011
“We will be delivering to customers in a way that makes most sense to them” looked around for software, it’s attempting to build as much as it can on its own. “That gives us the flexibility to be able to meet the customer’s needs in the most appropriate way,” he explains. “One of the challenges that the insurers have at the moment [is] they have big clunky back-end systems that they have to navigate around to then drive the customer experience. We’re starting at the other end. We’re saying, ‘What is a great customer experience? How do we give the customer what they need so they can understand and buy and service their insurance in the way they want to?’ and then
deploy that back into the insurance process.” He says the Evari team is working hard in preparation for a mid-year launch. So, what’s ahead over the next 12 months? “It really depends on what the next six to nine months look like,” he says. “We’d like this to be a great success and we’ve got the flexibility and technology. But we’re going to start small, make sure we can meet customers’ needs well, make sure we have got the insurance angle absolutely covered here, and then expand out our business from there.” Fogarty hopes his efforts, and those of his
Held a number of executive general manager positions in general insurance over 5½ years at Suncorp/Vero Qualifications include a Bachelor of Commerce (majoring in accounting, finance and systems) from the University of NSW and a Master’s from Stanford Graduate School of Business, California
Evari colleagues, will encourage others to enter the insurtech space. “Hopefully, other people see me and others having a go at this and say, ‘Let’s see what we can change’, and together we’ll develop our industry into a much better space over the years to come.”
www.insurancebusinessonline.com.au
36-37_Business Insight Subbed.indd 37
37
23/05/2017 11:54:54 AM
FEATURES
D&O INSURANCE
SECURITIES CLASS ACTIONS CAUSING DISTRESS
The Australian directors and officers insurance market is distressed, and Swiss Re Corporate Solutions is seeking to assist brokers and corporate clients in this challenging area
THAT’S THE message from litigation risk expert Jeremy Scott-Mackenzie, who warns that a massive increase in securities class actions is having a damaging effect on the D&O market. “We have seen a continual increase in securities class actions in Australia, but even more concerning is that we have seen a spate of them in the first quarter of 2017,” explains ScottMackenzie, who is head of Casualty and FinPro Australia and New Zealand at Swiss Re Corporate Solutions. “Australia would normally see six to eight of these actions a year, but we have already had four in the first quarter – Bellamy’s Australia Limited [two actions filed], Spotless Group Holdings Limited, Sirtex Medical Limited and Woolworths.” With the Australian D&O insurance market premium worth in the vicinity of $280m, and the average securities class action costing between $50m and $70m for the insurer(s), some basic maths is all that’s needed to get an
38
idea of the size of the problem. “The first quarter of 2017 could cost the industry in excess of $300m, thereby draining the annual D&O premium pool in just the first quarter,” Scott-Mackenzie says. Scott-Mackenzie is the national president of the Australian Professional Indemnity Group,
“We also see increased underwriting scrutiny and increases in market pricing.”
Managing the merry-go-round So, with these challenges in mind, why does Swiss Re Corporate Solutions want a bigger slice of the D&O pie? Scott-Mackenzie explains that
“Australia would normally see six to eight of these actions a year, but we have already had four in the first quarter” Jeremy Scott-Mackenzie, Swiss Re Corporate Solutions a leading body that represents D&O insurers and brokers. He points out that many insurers operating in Australia are reducing their appetite in the D&O market. “One insurer, that 10 years ago would have provided $50m limits, is now only providing $10m,” he says.
there are still opportunities in the D&O space; it’s just that the risk needs to be shared across the market. “As with any other catastrophe insurance line, like property, we need to move to co-insurance, rather than everyone putting down $10m layers one on top of the other,” he says.
www.insurancebusinessonline.com.au
38-41_Ad Led D&O_SUBBED.indd 38
23/05/2017 11:55:16 AM
Brought to you by
“The benefit of that is that all of the insurers’ interests are aligned. “One of the concerns I have is that the primary insurer puts down $10m, which is going to be consumed irrespective of the conduct of the case. Therefore the primary insurer may not provide the client with effective claims management as they no longer have any financial interest.” Scott-Mackenzie believes that a co-insurance
SECURITIES CLASS ACTION Securities class actions are commonly brought about by lawyers, on behalf of shareholders, against listed companies, alleging that there has been a breach in the law. The breach is usually an allegation that the company in question has not kept shareholders informed, in a timely manner, about business performance, such as profit forecast downgrades. While class action law has been present in Australia since 1992, the first securities class action was against GIO in 2001, and the largest class action in Australia to date was against Centro, which settled for $200m plus legal costs.
www.insurancebusinessonline.com.au
38-41_Ad Led D&O_SUBBED.indd 39
39
23/05/2017 11:55:21 AM
FEATURES
D&O INSURANCE Brought to you by
SWISS RE CORPORATE SOLUTIONS Swiss Re Corporate Solutions offers innovative, high-quality insurance capacity to mid-sized and large multinational corporations across the globe. Their offerings range from standard risk transfer covers and multi-line programs to highly customised solutions tailored to the needs of their clients. Swiss Re Corporate Solutions serves customers from over 50 offices worldwide and is backed by the financial strength of the Swiss Re Group. For more information about Swiss Re Corporate Solutions, please visit www.swissre.com/ corporatesolutions or follow them on Twitter @SwissRe_CS.
‘RIGHT UP THERE WITH THE HILLS HOIST’ Litigation funders are an Australian invention, “right up there with the Hills Hoist”, Jeremy Scott-Mackenzie explains. “Litigation funders fund large corporate litigation and will take a percentage of any settlement.” There are now more than 20 litigation funders in Australia, most of which have been established in the past five years. Two major law firms – Maurice Blackburn and Slater and Gordon – have been very successful in the plaintiff space, Scott-Mackenzie adds. “But as we’ve seen them prosper, some smaller, less experienced law firms have tried to lodge securities class actions.”
40
approach aligns everyone’s interests, and so catastrophe risks become manageable, “rather than the merry-go-round that has occurred in the past 10 years of primary insurers getting burnt and exiting the D&O market, only for the newer entrants to suffer the same fate”. “We need a change of approach by insurers, which is already happening to some degree,” he adds. “Brokers are beginning to promote a co-insurance approach and are explaining the benefits to clients. It’s about a mindset change for all concerned.”
through different scenarios. Preparation can nip the claim in the bud, and avoid a multimillion-dollar securities class action.” Scott-Mackenzie says Swiss Re Corporate Solutions aims to make clients aware of common pitfalls that lead to securities class actions. “Both good news and bad news needs to get to the top as quickly as possible and then needs to be conveyed to investors as quickly as possible,” he says. “How does the company make sure that information doesn’t get buried? What is the company’s response plan if the Australian Securities and Investments Commission makes
“Brokers are beginning to promote a co-insurance approach and are explaining the benefits to clients. It’s about a mindset change for all concerned” Jeremy Scott-Mackenzie, Swiss Re Corporate Solutions Testing times There are many factors that drive litigation, and some industries have a higher exposure than others. Gaining a comprehensive understanding of how that plays out in the market is key to an insurer’s success in this area. Swiss Re Corporate Solutions invests a lot of time in understanding clients’ risk management and how they would approach securities class actions. “We engage with clients on their preparedness for securities class actions and, where appropriate, assist them in prevention and response measures.” A huge part of this effort involves assisting corporates in better meeting continuous disclosure regimes. “Risk managers and the C-suite are usually very receptive and appreciate of our insights,” Scott-Mackenzie says. “Part of this support is our local claims managers walking
allegations? Who are the company’s advisers when serious litigation occurs? What should the employees be told to do if there is serious litigation? Who is the company’s public spokesperson?” Scott-Mackenzie emphasises that these response plans must be tested on a regular basis. “A response plan may be in place, but few companies have practised it,” he says. “You must ensure that your planning is robust and actually works.”
Contact Jeremy Scott-Mackenzie Head Casualty & FinPro Australia & New Zealand Vice President - Corporate Solutions Direct: +61 2 8295 9875 Mobile: +61 405 513 099 E-mail: Jeremy_ScottMackenzie@swissre.com
www.insurancebusinessonline.com.au
38-41_Ad Led D&O_SUBBED.indd 40
23/05/2017 11:55:26 AM
www.insurancebusinessonline.com.au
38-41_Ad Led D&O_SUBBED.indd 41
41
23/05/2017 11:55:29 AM
FEATURES
TECHNOLOGY
BREAK FROM THE PACK
How do insurance businesses utilise technology to stand out today and tomorrow? A software solutions provider shares crucial insights
MELBOURNE-BASED underwriting agency Pacific Indemnity opened its doors in late 2015. It’s a business that prides itself on being easy to deal with and offering an efficient transaction process. In order to achieve its aims, the business engaged global software provider Gratex International. Jun Acance, Pacific Indemnity’s managing director, recalls the process of working with Gratex to ensure the implementation of a technology solution. “The first thing for us is we clarified the needs of our intermediaries and our own needs in regard to a system for the future,” Acance says. “Gratex [then] provided us with a solution.” Feedback on the system from Pacific Indemnity was then factored in, and then the system was tested with the agency’s intermediaries. “[Finally], we adjusted the system as required following the outcome of the testing, and then we launched. The result for us is that we have an insurance system and a portal that we believe is easy to use … [and] it allows us to improve our own and our intermediaries’ efficiency. “There’s also the ease of the portal that allows intermediaries to quote, bind, cover and issue policies for over 250 professions. We believe that our system is probably one
42
of the best in the market.” Acance emphasises the importance of using new technology in today’s marketplace. “I think we have to go where our buying public is … Technology in the insurance industry is relatively old, and we have to make sure that we cater for the needs of our stakeholders,” he says.
“It’s not mainly about feature and function, but how your business wants to build relationships, what data insights you need to run it, and how we can streamline processes. Everything has to start with business objectives, not with bits and bytes.” Gratex, Dovhun says, doesn’t push product and tell its customers how to shoehorn their
“It’s not rocket science to see that forcing our customers to ‘fit in’ destroys competitive advantage because everybody becomes homogenous” Peter Dovhun, Gratex International Gratex in the ecosystem Gratex International describes its work as making it easier and faster to do business between all stakeholders. “We enable digital transformation for the insurance ecosystem and deliver services and solutions that underpin the robustness of the industry and its ability to grow,” says Peter Dovhun, Gratex International’s managing director. “As a result, business decisions become safer, operations more efficient and customers get better, faster service.
business into predefined workflows. “It’s not rocket science to see that forcing our customers to ‘fit in’ destroys competitive advantage because everybody becomes homogenous,” he explains. “We believe that businesses needs differentiation to create value for their niche customers and compete effectively.” He continues: “It’s like encoding the unique DNA of a business while building the right system so you can scale and be agile. We start with extensive industry knowledge, overlay it
www.insurancebusinessonline.com.au
42-45_Ad Led Tech_SUBBED.indd 42
23/05/2017 11:55:57 AM
Brought to you by
with deep business analysis, and only then conceptualise the right solution. “At the same time, we have to be three steps ahead of the market, interpreting the technology of the future in the context of our clients’ business strategies and finding ways to unlock measurable business value. Our insurance industry experience and partner approach is key. Technology in itself, frankly, is useless.” Below, Dovhun and his Gratex team share with Insurance Business readers their seven integral insights about technology.
to understand interdependencies and how relationships can be improved through a connected world. Sharing data is a great example. “It’s simple. The better capital investment decisions by the insurers are, the better we deliver specialised products at lower cost to the insured. The way we can partner with Gratex gives us the data to close this loop for the benefit of the entire ecosystem through better partnering with both insurers and brokers,” says Angie Zissis, managing director of SURA.
Truth 1: Think ecosystem, not process
Truth 2: Don’t think feature, think future customer
If you are just looking at your business operations and efficiencies, you are missing the point. The insurance industry is an interconnected ecosystem, and a systemic perspective is needed
The customer experience is driving our industry. It is irreversible. It is crucial that your technology solutions can enable great customer interactions across any channel. Speed and turnaround times
are one of the most important factors. This means that you need to consider the customer journey all the way through the value chain, independent of the systems in play.
Truth 3: What you do tomorrow will be outdated the day after The rate of change is getting faster. What you do today is already redundant. What matters is that you invest in flexible systems that can change with you, at a reasonable cost. Business systems typically have an average life cycle of seven years. There is no way you can predict what you need over such a long time, but you can make certain that you can be agile. “Looking into the future, we will run more and more on digital platforms, work smarter and interact less with the underwriting agency.
www.insurancebusinessonline.com.au
42-45_Ad Led Tech_SUBBED.indd 43
43
23/05/2017 11:56:03 AM
FEATURES
TECHNOLOGY Brought to you by
GRATEX INTERNATIONAL Gratex is an end-to-end business systems solution provider, focused on the insurance industry, enabling digital transformation through the development, delivery and support of software, and the management of the underlying IT infrastructure. Gratex opens opportunities for our customers to gain a competitive edge by adopting new technology early and returning high value to their customers.
THE ELEPHANT IN THE ROOM At Gratex, we know that transformational technology projects are feared and that technology vendors are generally not highly esteemed. There are too many broken promises, failed projects, disappointing results and a sense of being held to ransom. It seems like once the deal is done, the chaos starts. There’s no doubt that it’s a difficult process, working through ideas and intangibles in a sea of IT acronyms. So what’s the answer? Gratex’s recommendation to mitigate concerns is to invest in prototyping as soon as possible. This will show you not only if a vendor understands you, but also if they can deliver to time and budget. It’s the best money you’ll ever spend, especially compared to expensive, long-winded and largely theoretical requests for proposal. Most importantly, you get to evaluate cultural fit and how effectively the vendor can work with your stakeholders to make things happen.
44
Brokers have to differentiate in the market, embrace more innovative products and develop strong customer relationships. This means they need technology to manage complexity and be agile,” says Phil Kearns, managing director, InterRISK.
as everybody else. Stay with your vision and your strategy. Make technology work for you, not the other way around. If you can imagine it, it can be done.
Truth 4: Data is your lifeblood – insist on one version of the truth
The old expectation of having to pay a high price tag to achieve high differentiation, or choosing to pay less for standard products, has been broken. You don’t have to choose any more. You can have both. Insist on getting return on investment as well as differentiating your business.
Accurate and timely data is the biggest issue for most businesses we work with. It’s painful to work with data from multiple systems that needs to be manually consolidated along with all the
Truth 6: Do both – cost down AND differentiation up
“Brokers have to differentiate in the market [and] embrace more innovative products … This means they need technology to manage complexity and be agile” Phil Kearns, InterRISK inherent risks of manual handling. Make sure that your system delivers a single version of the truth, with data that is granular enough to drill into detail and can be summarised into whichever report format you need. “To win the insurer’s confidence and trust we need to show results with accurate, detailed and timely data. Gratex designed a system architecture for us that delivers unified reporting across our highly specialised 22 agencies. Instead of aggregating data from five systems, we are getting one system and a single version of truth,” says Angie Zissis.
Truth 5: Be bold, be different Challenge the idea to adopt best practice when it comes to technology for your core business process. It simply means you are doing the same
Truth 7: If you aren’t connected, you don’t get to play Traditional boundaries and rules of engagement in the insurance industry are blurring as business-to-business relationships go online. To play you need to be connected and establish automated processes with any partner or customer, allowing them to communicate the way they want to. “We had a moment of truth, when we needed a B2B connectivity solution within four weeks to conclude a very important business transaction. We knew we were asking the impossible. Gratex analysed what needed to be done, said they will deliver. No other vendor could have completed this with such a short lead time. But Gratex did and we won the business,” says Mark Campbell, chief information officer at SURA.
www.insurancebusinessonline.com.au
42-45_Ad Led Tech_SUBBED.indd 44
23/05/2017 11:56:06 AM
www.insurancebusinessonline.com.au
42-45_Ad Led Tech_SUBBED.indd 45
45
23/05/2017 11:56:10 AM
FEATURES
NAS AND WESTCOURT
A COMBINATION FOR SUCCESS
Paul Ayton, managing director of NAS/Westcourt’s combined authorised broker business, talks to Insurance Business about working to create the country’s best AR network
SINCE SEPTEMBER 2016, Paul Ayton has led NAS/Westcourt’s combined authorised broker network, a network that came into existence when IAG acquired Perthheadquartered Westcourt General Insurance Brokers last July. The process of integrating Westcourt with IAG’s pre-existing authorised broker business, National Adviser Services (NAS), is ongoing. Combined, the network is today No.1 in the Australian authorised representative market. In May, Ayton announced a new leadership structure for the network, which sees Jenette Baker as head of risk and compliance, Donna Tingley as financial operations manager and Greg Dowd serving as its chief financial officer. Additionally, as part of IAG’s endeavours to reduce the number of insurance licences in the group, the business is currently incorporating a substantial number of CGU ARs into its fold. Talking to Insurance Business, Ayton discusses some of the integration work undertaken to date. “What we’ve really tried to achieve is to take the best of both organisations and make sure that we capture the value that was in both organisations,” he says. “We have tried to understand where that value lies, and we’ve also made sure that we articulate what our purpose is moving forward.” That purpose, he says, is to support communities so that they can sustain, grow and thrive.
46
“While they’ve never articulated it that way, both NAS and Westcourt, in their own ways, were already aligned to that purpose and were doing things that supported what we’re going to be trying to achieve,” Ayton says. “As a result of that, it’s not like we’ve had to make significant adjustments to the structure or the way we’re operating. It’s more tweaks and alignments to make sure that we’re getting the efficiencies that you can achieve by bringing two organisations together.” So, will the combined network come
both Westcourt and NAS. But we will be introducing a new brand, but specifically for our people and the industry, not necessarily an external brand.”
Being the best Looking down the track, he says the aim is to make the combined network the best, not the biggest. “If we’re the best, we’ll continue to grow,” he says. “We want to build a really strong foundation [and] we want to focus on our purpose and continue to have everyone understand what that looks like.
“I think we’ve got some really great opportunities to re-establish what an intermediated insurance network can look like” Paul Ayton, IAG together under one banner? “We think there’d be benefits in having a combined brand as we bring not just NAS and Westcourt, but the CGU ARs together into one network,” Ayton says. “But externally … we’re very happy for [our authorised brokers] to use whatever branding they’re using at the moment – which, in many cases, is their own brand. And if they do want to associate, we still own
“We don’t necessarily have a view on how big or not we may be in the future. We’re excited about the authorised broking space in itself – it is the fastest growing area of commercial insurance.” Describing insurance as traditionally being “one of the least efficient commercial processes around”, Ayton says the network sees great opportunities to work with its strategic partners to continue to drive down
www.insurancebusinessonline.com.au
46-47_Authorised Rep Subbed Amended.indd 46
23/05/2017 11:56:57 AM
NAS AND WESTCOURT GENERAL INSURANCE BROKERS
1982
The year in which Westcourt General Insurance Brokers was established
2001
When NAS Insurance Brokers was formed
150
The number (approx) of broker businesses belonging to the Westcourt General Insurance Brokers network, with over 200 brokers working in those businesses
300
Today, NAS has more than 340 authorised brokers servicing over 40,000 clients
the cost of obtaining insurance. “We’re spending a lot of time sitting down and talking with our stakeholders to really identify where we can work together and be more collaborative and to find better outcomes in a whole range of areas, which should enhance the experience of a customer that’s working with one of our authorised brokers,” he says. “We’ve been very fortunate that we get to start with a clean slate, bringing three different networks together to establish a business the way that we want to do it. We want a business and people that align to our purpose of helping communities to sustain, grow and thrive. We understand that that’s not going to be for everyone. But for those who get it, I think they’re going to be able to be part of a network that’s really customerguided and purpose-led.”
Benefits and times ahead Ayton talks about the benefits he perceives for the network’s authorised brokers. “We want to make sure that we’ll have all the efficiencies and benefits you would expect from a network … and that’ll be things like supporting succession planning, providing learning and development opportunities, [and] making sure we negotiate great value propositions for our brokers’ clients through our underwriter relationships,” he says. “What will make us different in the long run is that, as we always have, we’ll allow the brokers to control and own their own businesses, be able to leverage off the benefits that we’ll be able to deliver through our partnerships and scale, but really look to help their communities in different ways with that focus on our purpose of helping them to sustain, grow and thrive.
“We think that’s a different lens and a different way of looking at the market, and a different way I think to truly realise the value of the advice that they’re currently providing.” Discussing short-term priorities, Ayton says there’s significant time currently being spent on transitioning CGU ARs into the network. “There are a number of opportunities we’re looking at in relation to our underwriting partnerships and we’re looking forward to coming together for the first time as one network at our national conference in August. We’ve got a number of initiatives that we want to release there,” he adds. “I think we’ve got some really great opportunities to re-establish what an intermediated insurance network can look like and put us in quite a different space to where we’ve been.”
www.insurancebusinessonline.com.au
46-47_Authorised Rep Subbed Amended.indd 47
47
23/05/2017 11:57:06 AM
FEATURES
LEADERSHIP DEVELOPMENT
A GENERATION SET UP FOR FAILURE? Much like millennials have changed the way we work, soon they will change the way we lead. However, Hiam Sakakini suggests the old leadership development models will not work for this generation
WE’VE NOW moved firmly into an era in which millennials are taking on the responsibility of managing people. The problem is their predecessors haven’t given serious consideration to the unique ways millennials learn, adapt and grow as
48
professionals, and consequently are not arming them with the critical leadership capabilities that ensure future sustainability of an organisation. I see it everywhere: senior leaders taking a page from the old textbook How to Manage
and Grow a Workforce. But this advice simply doesn’t work any more for the 6.1 million millennials in the workforce today. How scary to think we are potentially missing easy opportunities to engage this segment of future leaders. Having spent a significant portion of my career both managing a team of millennials and learning about their needs, it has become apparent to me that this old way of developing our future leaders doesn’t develop leaders any more. To get some perspective, let’s look at the trends Gen Yers bring with them: • Millennials typically have itchy feet and tend not to stay in a position longer than two to three years maximum. • They like to work in sprints – short projects with rotating teams increase their productivity and engagement. You’ll notice that emergent leaders will feel compelled to solve a problem presented through a project and then retreat to being part of the team once the problem they noticed is solved. • They prefer a leader who is involved and inclusive, a mentor and a coach, as well as a friend. Someone who is accessible, not hierarchical. Someone who genuinely cares about them as a whole person – not just during their working hours.
www.insurancebusinessonline.com.au
48-49_BizStrat Leadership Subbed.indd 48
23/05/2017 11:57:25 AM
• They need immediate feedback on their performance. They want it straight after a milestone is achieved. They are natives of the digital world, which has propelled the art of instant feedback. • They are driven by their core values, which anchor their every decision. This seems to be instilled by a great relationship with their parents, who tend to be the key influencers in their decision-making. • They enjoy a challenge; they like to be constantly stimulated, and they aren’t afraid to stretch themselves out of their comfort zones – especially when the project has impact. So, with all these trends in mind, the challenge now is how do you grow leaders who typically don’t spend very long in a single role or with one employer? What strategies do you need to implement to fulfil their need to feel challenged and learn best on the job? And how do you factor in their care about impact, not status and titles? How you incorporate all of this into a journey that develops leaders for the future will determine the long-term success and stability of your organisation.
It starts with managers of managers Typically, promotion and, therefore, by default, succession planning rewards bottom-line results. Type A personalities who are quite driven, fearless, competitive and focused do exceptionally well as individual contributors rising through the ranks because they are as goal driven with their careers as they are with their KPIs. They get noticed; they openly ask for a promotion, and they are seen as natural leaders over and above those who seem too emotional. I will admit that, as a young saleswoman at Google who loved to smash through every target handed to me, I was that person. Before I knew it I had a team and was expected to teach them the tips and tricks that I knew instinctively. The problem was I was never equipped to coach and, as a result, I faltered … badly.
HR FUNDAMENTALS: OLD VS NEW Old school
New school
Hire for a specific team
Hire for personal values and cultural fit
Hire for skills and experience
Hire for motivation, growth mindset and aptitude for change
Promote based on bottom-line results and short-term achievements
Promote on results combined with behaviours and long-term impact
Develop leaders through high-potential fast-track plans and programs
Develop leaders through experiential on-the-job projects that bake in coaching, reflection, tools and guides
Give feedback at performance review time
Give feedback in real time
How can managers of managers play a crucial role?
1
Pay attention to how your superstars are achieving their KPIs. Are they collaborative? Are they inclusive? Do they ask for feedback from their teammates as well as from you? Are they helping their team towards achieving their collective goals? Rewarding the how as much, if not more, than the what through your competency and behaviour frameworks will by default get the right future leaders into the next leadership layer. Support your new managers with learning the art of coaching. This is a new skill that typically only gets taught after an individual contributor becomes a manager, and is crucial to their success and the success of their team. Be the meta-coach.
2
Deconstructing leadership learning This is a challenge! And it will require investment of time and the support of a good internal or external learning and development business partner, but the investment will pay off. Within everyday workplace teams, projects and initiatives, there exist golden opportunities to learn valuable leadership lessons. This all starts with a) identifying the learning opportunity; b) keeping the right tools, principles and techniques at your fingertips
to match the scenario at hand; c) having the guidance of an experienced facilitator who allows the team time to stop, reflect, give feedback and experiment. I don’t think leadership programs will entirely be replaced by this approach. However, the tools and principles that lie within them can be deconstructed into bite-size, easy-to-use downloadables, facilitator guides and how-to videos that can be used within the life cycle of any project or initiative. Capitalising on the learning opportunities within everyday business projects will mean a richer experience for all involved and potentially less time and money spent on formal leadership learning courses. Ultimately, the ramp-up time to upskill future leaders will be significantly shorter, coinciding with the trends of millennials and their itchy feet! PS: an interesting side effect will be more ROI for your L&D budget. Hiam Sakakini is the co-founder of Think Change Grow and is the former head of leadership development at Google APAC. During 14 plus years of working in Fortune 500 companies in a range of roles, Hiam has developed a passion for pinpointing the simplest strategies to help individuals and teams build the skills, confidence and competence needed to become genuinely customer-focused and deliver outstanding bottom-line business results. Visit thinkchangegrow.com.
www.insurancebusinessonline.com.au
48-49_BizStrat Leadership Subbed.indd 49
49
23/05/2017 11:57:28 AM
FEATURES
BURNOUT
Avoiding burnout Leadership expert Karen Gately explains the six typical drivers of burnout in business leaders and offers practical tips to help you avoid them HAVE YOU ever reached the point where you felt like you simply couldn’t go on? Have you found yourself losing concentration and lacking the motivation to do the things necessary to drive the performance of your business? It’s common for CEOs and senior leaders to experience periods of disengagement from their roles and teams due to the extreme exhaustion they feel, and many fail to recognise the state of burnout they have reached. Burnout is a state of emotional, mental and physical exhaustion caused by excessive and prolonged stress. Typically reflected in our energy and behaviours, burnout unquestionably undermines any CEO’s ability to lead a thriving organisation. Despite its devastating impacts not only on job performance but also on quality of life, many of the senior leaders I work with fail to take the necessary steps to avoid reaching this state of exhaustion and disengagement. The following are six typical drivers of burnout in business leaders, with tips on how to avoid them.
1
Overcommitting
There are always more things you could do in any given day. But the reality is that it isn’t possible to explore, plan and execute all of the ideas and even priorities you are likely to have. Your ability to invest energy and resources wisely depends on your ability to know what matters most. While deciding what you will do is important, arguably more so is deciding what you won’t.
50
TIP Create a business plan on one page. Identify the priorities that will have the greatest influence on your success, and anchor your focus, and that of your team, to them. Review progress regularly, and identify ways in which you need to bring back focus to these critical objectives. Strike things off your to-do list that add little value and distract you from your main mission. Learn to say no.
2
Avoiding
The need to make tough decisions and have difficult conversations is inevitable when leading a team or organisation. And yet so many of the leaders I work with
“Strike things off your to-do list that add little value and distract you from your main mission. Learn to say no” avoid them. The consequence of failing to address issues is continuing to live with the stressful impacts of underperformance and uncertainty. Fear of having the conversations or implementing the actions necessary to drive change is common among leaders who experience burnout.
TIP Work with someone who is able to guide you in shifting the thoughts and feelings that cause you to hesitate to do what is necessary. Find a mentor or coach you trust to challenge your thinking and hold you
accountable for dealing with issues that arise.
3
Executing poorly
Even when decisions have been made, executing them can be difficult. Most often what I observe are senior leaders who recognise what needs to be done but fail to act decisively. These leaders fail to apply disciplined approaches that ensure priorities are achieved. Commonly, a lack of planning, review, and deliberate decision-making about priorities and resource allocation leads to costly mistakes and wasted resources. The pressure
www.insurancebusinessonline.com.au
50-51_BizStrat Burnout Subbed.indd 50
23/05/2017 11:57:51 AM
conflicted between the demands of a job and the desire to be with friends and family. We are likely to reach burnout if we fail to give our minds, bodies and spirits the nurturing needed to thrive.
TIP Establish routines that ensure you take time out for you. Switch off the technology that allows you to stay connected with your work world, and spend time with the people you love and doing the things that energise your spirit. Maintain a level of activity and diet that allows your mind and body to be healthy.
6
Worry and regret
Reflect for a moment on how much time and energy you waste worrying about things that are outside of your control. How often do you worry about things that haven’t yet happened and may never happen? Do you expend vital energy on concerns that can’t be resolved? Feeling helpless and regretful drains our energy and is likely to erode our resolve to keep striving.
and workload demands on leaders and teams when things go wrong can be immense.
TIP Develop your organisation’s ability to manage projects well. Develop your own ability to set a clear vision, establish priorities and drive change. Also develop the capabilities of leaders at all levels of your organisation to drive strategic priorities through to successful implementation.
4
and resources in striving for standards beyond what our staff or customers expect is a common reason CEOs are overworked.
TIP Understand the 80/20 rule and apply it. The rule states that 80% of your outcomes come from 20% of your inputs. The important thing to understand is that in your life, 20% of the activities you do account for the majority (80%) of your happiness and success.
TIP Recognise when you are worrying. Start by asking yourself whether the problem is something that can be solved, and whether it can be solved by you. For example, is the problem something you’re actually facing, or is it just a “what if ”? Is your concern realistic? Can you do something about it or prepare, or is it really out of your control? If it’s an unsolvable worry, recognise that fact, put it out of your mind and move on. Avoiding burnout comes down to making necessary and balanced choices – those that allow you to deliberately invest time, energy and resources in achieving what matters most. Know when to let things go, choose to focus on today and keep an eye on the future.
Aiming for perfection
Let’s face it – worrying about being perfect all the time is stressful. Many of the perfectionists I have worked with have recognised this tendency in themselves but have failed to see the seriousness of its consequences soon enough. The simple truth is that none of us, or our businesses, are perfect. Investing unnecessary time, energy
5
Work-life imbalance
We all need time away from work to slow down, unwind and recharge. No matter how much we love our work, if the time we spend doing it disproportionately consumes our focus and energy, our health and relationships are likely to be impacted. It’s difficult to avoid feeling stressed when
Karen Gately is a leadership and people management specialist and the founder of Ryan Gately. She works with leaders and HR teams to drive business results through the talent and energy of people. Gately is also the author of The People Manager’s Toolkit: A Practical Guide to Getting the Best from People and The Corporate Dojo: Driving Extraordinary Results Through Spirited People.
www.insurancebusinessonline.com.au
50-51_BizStrat Burnout Subbed.indd 51
51
23/05/2017 11:57:59 AM
FEATURES
BUSINESS PARTNERSHIPS
GOING FOR THE WIN
Gary Pert, CEO of the Collingwood Football Club, talks about building successful business partnerships and driving a high-performance culture
THE COLLINGWOOD Football Club is the Australian Football League’s (AFL) most polarising club, but also remains one of its most successful. On May 6, Collingwood played its 125th anniversary game against its long-time rival Carlton. In 2017, the man at the helm of the club continues to be Gary Pert, who’s occupied the chief executive’s seat for 10 years now. It wasn’t his first stint with Collingwood; during his own 233-game, 14-year AFL career, Pert played 70 games for the Magpies. Under Pert’s leadership, Collingwood has financially doubled in size and qualified for three AFL grand finals, winning the premiership in 2010. In terms of its
sponsors. The insurer is one of the club’s four premium sponsorship partners, and it was announced in March that the partnership had been extended for a further five years.
Alignment Pert reflects on the history of the CollingwoodCGU partnership. “I remember back to the early conversations we had with CGU, when they were looking at sponsoring the club,” he says. “When we talked to them about what our values were as a club, what we stood for in the community and what we were trying to achieve apart from just winning games of footy on the weekend, it was amazing then to hear back
“We’re very transparent; we’re very open and we very much declare what we’re about and what are our priorities” membership base, the club recorded 42,498 members in 2008. In 2013, the figure had grown to 80,456. It’s also been under Pert’s leadership that CGU has become one of Collingwood’s key
52
from CGU about what their ambitions were and to see that alignment.” Pert talks about some of the initiatives that Collingwood has partnered with CGU to promote over the past seven years.
COLLINGWOOD FOOTBALL CLUB
1892
The year Collingwood Football Club played its first official senior game of football
2010
The last time Collingwood Football Club won the AFL premiership (defeating St Kilda in the grand final replay)
2011
The last time a Collingwood player won the prestigious Brownlow Medal (the recipient was Dane Swan)
“When we started talking to CGU about the fact that we were looking to support women’s sport with our women’s AFL team and netball team, CGU was the first of our sponsors to make a commitment to say that it was something that was very important to them as well, and they wanted to be involved and a key driver of those programs,” he says. Pert also mentions Collingwood’s Magpie Nest housing project, which provides housing for the homeless. “We’ve taken about 150 homeless people off the street and put them into houses and provided facilities and support around them to really help turn their lives around,” he says. “That’s something that, again, was very much aligned with what CGU wanted to do [to] make a difference in the community.”
www.insurancebusinessonline.com.au
52-55_Partnership Subbed.indd 52
23/05/2017 11:58:22 AM
Lost opportunity Asked about steps taken – or not taken – in business partnerships that prevent parties from ultimately achieving great success, Pert describes what he characterises as the “lost opportunity”. “I’ve seen sponsorships and I’ve talked to sponsors who have sponsored sporting clubs where they see that by signing up for the initial sponsorship, that’s all the work that’s done and now that they get their name up there on signage or even on a particular jumper, then that’s what it’s all about,” he explains. For Pert, there’s a lost opportunity when parties fail to realise that signing the deal should mark only the beginning of the process. “Once we start talking to clients like CGU and our other partners around the club, we want to know quite intimately what are the challenges? What are their ambitions? What are they trying to achieve? What do they want out of the partnership? And we also then present back to them where our challenges and our innovations and our growth is going to be,” he says. “It’s amazing out of those conversations how often we find programs and initiatives that we can do together. In many ways, these commercial partnerships are actually helping us grow and drive innovation in various areas.” Pert emphasises the need for potential partners to enter an agreement only where there’s a clear understanding of what they want to get out of the deal. “We agree upfront the goals and the benchmarks that we want to achieve,” he says. “We very much encourage that if you’re going to be spending money on this partnership, you’re going to be very clear on the sort of return and results that you want, and then we make sure that we work with our partners to deliver that and, in the majority of cases, over-deliver.” According to Pert, another factor of integral importance to successful partnerships is brand and value alignment.
www.insurancebusinessonline.com.au
52-55_Partnership Subbed.indd 53
53
23/05/2017 11:58:31 AM
FEATURES
BUSINESS PARTNERSHIPS
GARY PERT As an AFL player, Pert played for Fitzroy Football Club from 1982 to 1990, and then for the Collingwood Football Club from 1991 to 1995. Pert won the Fitzroy Best and Fairest Medal in 1989 and was named in the Fitzroy Team of the Century. Pert spent 12 years with the Austereo Network, including four years as general manager for Melbourne and five years as national sales director.
“Getting the best people is really important, then giving those people every opportunity to be their best”
Before joining Collingwood Football Club as CEO in 2007, Pert was managing director of Channel Nine Melbourne.
for and, in many cases, when I see sponsorships or partnerships that aren’t working with particular clubs, you can take it back to the point, that in many cases, they probably shouldn’t have been trying to work together in the first place, and there wasn’t that understanding and appreciation.”
“We’ve been talking to organisations where we’re just looking at them and thinking, ‘Do their values and integrity and their professional standards align with what we see as important and what we stand for?’ And if that’s not the case, it’s really important upfront not to go down that partnership path. “In many cases, the reason why we’ve had such long and successful partnerships is because they seem to be so easy, because we spend so much time allowing potential new partners to understand us. We’re very transparent; we’re very open and we very much declare what we’re about and what are our priorities. We expect that same sort of transparency from our potential partners as well. “Once you establish that, everything else seems to flow from it, but I would say that’s what organisations more and more are looking
54
The right line-up As Collingwood’s CEO, Pert has also achieved substantial success in creating a highperformance culture within the club. So, precisely what has he learned as to how to get the right people on board and inspire them to achieve optimal results for the business? “The way we do it … because it is such a high-performance environment and there are such high expectations and such high demands right throughout the organisation, [it’s about] making sure that we get people who are very much in line with our values as a club, so they will thrive within that environment,” Pert says. “These are people whose ambitions and goals about what they’re trying to achieve are very much what we’re trying to do as well. The values that we establish are what align our
on-field with our off-field as our club. We have the same set of values throughout the whole organisation, and that alignment and transparency are what creates the integrity through the club. “I think that’s a key element that you’ll see throughout all high-performance organisations. You’ll never find a situation where one particular area of the organisation is on one path with a different set of values and standards, and then there’s another on a completely different path. That alignment is critically important to us.” And for Pert, it’s not just about recruiting right, but also investment in those recruits. “We see that getting the best people is really important, then giving those people every opportunity to be their best. And that’s about having the best facilities and the best coaches and the best expertise and support, and then making sure that we’ve got people on-field and off-field that are constantly striving to be the best they can possibly be. “If you’ve got everyone through the whole organisation pushing to those sorts of ambitions, you’re on a pretty strong path.”
www.insurancebusinessonline.com.au
52-55_Partnership Subbed.indd 54
23/05/2017 11:58:36 AM
www.insurancebusinessonline.com.au
52-55_Partnership Subbed.indd 55
55
23/05/2017 11:58:41 AM
PEOPLE
OTHER LIFE
THE NEED FOR SPEED Peter Peirano’s passion for competitive drag racing dates back four decades and involves his whole family PETER PEIRANO, principal of Rockhampton-based Piranha Insurance Brokers, has a love of drag racing that began at the age of 17 at Surfers Paradise. Today, Peirano and his family own the vehicle
56
TELL US ABOUT YOUR OTHER LIFE Email ibo@keymedia.com.au
Time Traveler and are part of the Aeroflow Outlaw Nitro Funny Car Show, which takes them right across Australia. “I just love the fact that it is, for us and many other teams, a family event,” Peirano says. “The comradeship with our other drag racing families is just amazing.” Asked to name standout highlights from time spent on the track, Peirano mentions his son, Nathan, winning two Australian National Drag Racing Association gold Christmas tree trophies, as well as third place in the Aeroflow Outlaw Nitro Funny Car Spectacular Extravaganza, which saw him beat a USA nitro funny car world champion. And there’s still plenty more on the road ahead. “We have twice travelled Rockhampton to Perth and back to race,” Peirano says. “I just love it.”
1930S
Decade during which it’s said that drag racing began, in Southern California
1950
Year in which CJ Hart ran the first commercial drag race, in California
1973
Year in which the Australian National Drag Racing Association was created
www.insurancebusinessonline.com.au
56-IBC_Other Life Subbed.indd 56
23/05/2017 11:59:08 AM
56-IBC_Other Life Subbed.indd 57
23/05/2017 11:59:19 AM
000_OBC.indd 55
23/05/2017 11:45:07 AM