JANUARY 2018 ISSUE 15.01
Pull up your bootstraps Bank tightens serviceability requirements /08
Digging into the banks ACCC investigates interest-only rate repricing /12
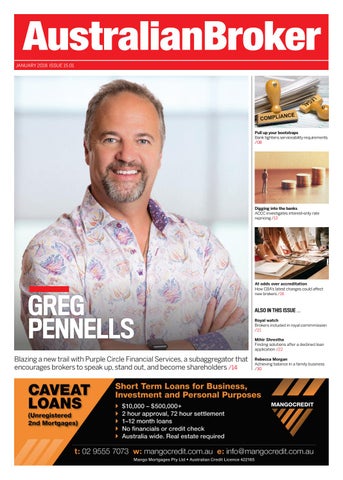
GREG PENNELLS Blazing a new trail with Purple Circle Financial Services, a subaggregator that encourages brokers to speak up, stand out, and become shareholders /14
At odds over accreditation How CBA’s latest changes could affect new brokers /16
ALSO IN THIS ISSUE ‌ Royal watch Brokers included in royal commmission /21 Mihir Shrestha Finding solutions after a declined loan application /22 Rebecca Morgan Achieving balance in a family business /30
NEWS
IN THIS SECTION
Lenders Investment firm takes 80% stake in non-bank /04
Aggregators Major lenders’ market share plummets /06
Technology Brokers to reveal lending data under CIF reforms /10
Regulators ACCC urged to look into interest-only repricing /12
Brokers Westpac tightens serviceability requirements /08
www.brokernews.com.au JANUARY 2O18 EDITORIAL Editor Otiena Ellwand News Editor Miklos Bolza Production Editor Roslyn Meredith
DATES TO WATCH
Upcoming can’t-miss events
ART & PRODUCTION Designer Martin Cosme Production Manager Alicia Chin
7 FEBRUARY
8 FEBRUARY
20 FEBRUARY
MFAA Sydney PD Morning
FBAA Perth Summit
ACCC’s policy update
Representatives from ASIC and the Combined Industry Forum will be talking about key regulatory changes and how these may impact your business in 2018
The FBAA will be talking about the Combined Industry Forum’s reforms and providing a regulatory update at this half-day summit in Perth
ACCC chairman Rod Sims will deliver his first public address for 2018 in Sydney on the watchdog’s activities last year and the challenges and priorities ahead
Traffic Coordinator Freya Demegilio
SALES & MARKETING Sales Manager Simon Kerslake Account Manager Rajan Khatak Marketing and Communications Manager Lisa Narroway
CORPORATE Chief Executive Officer Mike Shipley Chief Operating Officer George Walmsley Managing Director Justin Kennedy Publisher Simon Kerslake Chief Information Officer Colin Chan Human Resources Manager Julia Bookallil
EDITORIAL ENQUIRIES
Otiena Ellwand +61 2 8437 4792 Otiena.Ellwand@keymedia.com.au
SUBSCRIPTION ENQUIRIES
tel: +61 2 8O11 4992 fax: +61 2 9439 4599 subscriptions@keymedia.com.au
20-21 FEBRUARY Responsible Lending and Borrowing Summit A timely summit in Sydney to discuss open banking, unethical practices, erosion of trust, and interest-only loans. This year’s conference will have a stronger focus on the role of the consumer and the ethical practices needed to create greater disruption and opportunities for lending institutions
21 FEBRUARY
26 FEBRUARY
New wave banking
Competition in the Australian financial system
At this FinTech Sydney event, Eric Wilson of Xinja and Nathan Tesler of WildCard Money will talk about how the new digital banks (neo-banks) are challenging the traditional players
Productivity Commission Chairman Peter Harris will give an address in Melbourne on the draft report of the commission’s inquiry into competition in the Australian financial system
ADVERTISING ENQUIRIES
Simon Kerslake +61 2 8437 4786 simon.kerslake@keymedia.com.au Rajan Khatak +61 2 8437 4772 rajan.khatak@keymedia.com.au Key Media Pty Ltd Regional head office, Level 1O, 1–9 Chandos St, St Leonards, NSW 2065, Australia tel: +61 2 8437 4700 fax: +61 2 9439 4599 www.keymedia.com Offices in Sydney, Auckland, Denver, London, Toronto, Manila, Singapore, Bengaluru
16 MARCH
4-5 APRIL
Anti-Money Laundering Conference
Banking and Wealth Summit
Asset Finance Broker Forum
This Sydney forum is for banking and wealth leaders, regulators, policymakers and stakeholder groups to debate the future of financial services
FAST is hosting a number of Commercial and Asset Finance Summits across the country in April. This invitation-only event is designed to help commercial and asset finance brokers grow their businesses
This Sydney conference will take a closer look at who and how financial services organisations are doing business to better understand data and what it all means
2
www.brokernews.com.au
10-19 APRIL
This magazine is printed on paper produced from 1OO% sustainable forestry, grown and managed specifically for the paper pulp industry Copyright is reserved throughout. No part of this publication can be reproduced in whole or part without the express permission of the editor. Contributions are invited, but copies of work should be kept, as Australian Broker magazine can accept no responsibility for loss. Australian Broker is the most-often read industry publication, according to independent research carried out by the Ehrenberg-Bass Institute for Marketing Science at the University of South Australia in December 2008. The research also found that brokers rate Australian Broker as the best for both news content and feature articles, followed by sister publication MPA. Overall, on all categories, Australian Broker ranks top followed by MPA. The results were based on a sample of 405 respondents who were the subject of telephone interviews.
NEWS
LENDERS WESTPAC TO REFUND $11M TO IO BORROWERS 9,400 owner-occupier customers with interest-only loans will receive an $11m payout from Westpac, and 3,600 others will receive an interest refund, rate discount or both after an error was found in the bank’s system. The glitch prevented these IO loans from automatically switching to P&I at the end of the contracted period. As a result, customers did not start paying principal at the agreed time and now have less time to repay the amount. They would also have paid more interest. ABOUT
NAB REFUNDS $1.7M FOR OVERCHARGING INTEREST has refunded $1.7m to 966 home loan customers after it failed to properly set up mortgage offset accounts. Following an internal review prompted by customer complaints, NAB found that between April 2010 and August 2017 the bank did not properly link some offset accounts to broker-originated loans, resulting in overpayments of interest. The bank will also remediate customers who had an offset account during the relevant period but repaid their home loan before 2017. NAB
“Consumers should be confident that when they sign up for a home loan they are receiving all of the benefits that are being promoted” Peter Kell Acting chair, ASIC
4
www.brokernews.com.au
INVESTMENT FIRM TAKES 80% STAKE IN NON-BANK The partnership will see the lender grow further within the SME and business space through this new global network has announced a new strategic partnership that will see asset management firm Blackstone become a majority stakeholder in the company. The deal is effective immediately, with Blackstone taking up an 80% equity stake in the non-bank for an undisclosed sum. Blackstone’s support capabilities and global networks are set to help the non-bank strengthen its position in the SME and business lending market segments and ensure its continued growth in the future, La Trobe said. Under the arrangement, La Trobe’s Greg O’Neill will continue as president and CEO, and its executive team will remain in place. LA TROBE FINANCIAL
O’Neill will also continue to hold a 20% equity stake in the company. La Trobe will retain its existing board and appoint two additional representatives from Blackstone. Despite the stakeholder change, La Trobe will continue to operate its business as usual, with no impact on borrowing customers or changes to the terms and conditions of existing loans. It said it would not be changing its lending practices, underwriting guidelines or total commitment to responsible lending as a result of this transaction. “The opportunity to partner with Blackstone was the perfect fit for our staff, business and customers,” O’Neill said. With the specialist credit space experiencing a dramatic upheaval, it
is important for La Trobe to build on its capital position, expand its networks and draw on global best practice, he said. “Blackstone is an outstanding counterparty for our business, and we are delighted to partner with them. We look forward to working closely with them over the coming years to expand and substantially grow our retail and institutional investment programs and our specialist lending offerings.” La Trobe’s executives look forward to working with Blackstone to maximise the benefits for all customers, he added. Malcolm Jackson, managing director of tactical opportunities at Blackstone, also expressed his pleasure at partnering with La Trobe. “The calibre of the La Trobe management team, combined with their high-quality loan origination and underwriting ... and a strategy that is focused on realising growth opportunities at this important time in the cycle, means we look forward to a strong and productive partnership.”
NEWS
A G G R E G AT O R S ECHOICE SALE TO FINCONNECT CONFIRMED subsidiary Finconnect has purchased eChoice and 13 of its subsidiary companies and all operating assets, including the group’s intellectual property and platform and its digital home lending solutions. The sale does not include lender or broker agreements related to eChoice, as these are held by entities outside of the eChoice group. “Our understanding is that the lender and broker agreements will not be affected by the sale and will continue to operate in the normal course,” the administrators wrote. CBA
AGGREGATOR HEAD ELECTED AS LIXI CHAIR lending standards body LIXI has announced the appointment of Stephen Moore, CEO of Choice Aggregation Services, as chairman of the board. In today’s current industry landscape, data has never been more important, Moore said. “As our industry continues to evolve, LIXI can play a critical role in the evolution of data standards for improved data consistency and business efficiencies. It is my pleasure to be appointed chair and I look forward to supporting the industry.” INDEPENDENT
MAJOR LENDERS’ MARKET SHARE PLUMMETS The non-majors are chipping away at the major lenders’ mortgage market stronghold, according to the latest figures from AFG major lenders have
AUSTRALIA’S seen their home
loan market share plummet to a post-GFC low, likely due to the lending speedbumps implemented last year and increased scrutiny of the industry. According to AFG’s latest Competition Index, the major lenders saw their share of the mortgage market dip to 62.57% in the final quarter of 2017, with ANZ losing the most ground. Its share dropped 3.5% in this quarter. By comparison, the non-majors picked up market share and now claim 37.43%, the highest for 2017. Non-major market share has steadily risen since December 2016, when it was 36.91%. The majors lost ground in all
categories since the last index, including a drop of more than 3% in refinancing and more than 2% in fixed rates. Westpac was the only group as a whole that made up any ground among the majors. It finished the quarter at 20.33%, up from 19.19% at the time of the last index. Macquarie was one of the non-majors that saw a rise in the last quarter of 2017 to 4.70% from 2.91%, and AFG Home Loans saw a lift to 10.15% from 8.88%. The Competition Index calculates loans written through AFG channels only. While it does not give a complete picture of the market, it does give a good indication as to where mortgage flow is strongest.
The RBA noted in its December board minutes that housing credit growth had eased in the second half of 2017 due to the major banks restraining interest-only lending to comply with APRA’s measures announced earlier in the year. While growth in lending by non-ADIs had picked up, it said these institutions’ share of overall housing lending remained small. Mark Hewitt, AFG general manager broker and residential, said the intense scrutiny the major banks had been under likely caused them to be distracted. “With the recently announced royal commission into the banking sector, we all hope lenders can respond whilst still maintaining a focus on their customers,” Hewitt said. The royal commission, and the industry, need to focus on how competition can be further improved, and this should include the impact the government guarantee has on competition, he added.
“As our industry continues to evolve, LIXI can play a critical role in the evolution of data standards for improved data consistency and business efficiencies. It is my pleasure to be appointed chair” Stephen Moore Chairman, LIXI
VV$40,614,829,064 MAJOR LENDER MARKET SHARE DIPPED IN LAST QUARTER OF 2017 Source: AFG Competition Index
30% ANZ
CBA
NAB
Westpac
25%
18.31% 20% 15%
18.08% 15.01%
16.36% 16.24%
14.77% 9.88%
9.29% 7.65%
10%
8.21%
14.89% 15.10% 9.93% 9.55%
11.27% 8.53%
5% 0%
December 2016
6
www.brokernews.com.au
September 2017
October 2017
November 2017
NEWS
BROKERS MAJOR BANK TIGHTENS SERVICEABILITY who use digital credit platforms like AfterPay and ZipPay will now have to disclose what they owe on these transactions if they apply for a home loan through Westpac. Westpac announced in a broker note on 11 December that it would require borrowers to disclose these short-term buy-now, pay-later loans so the bank could better assess borrowers’ loan serviceability. “The customer has created a liability which must be captured in the loan application along with the monthly repayment,” the Westpac note said. CONSUMERS
MAJOR BANK UNVEILS UNSECURED SME LOAN has launched a $100,000 unsecured loan for small business customers, called QuickBiz Loan. The lender said the new product was designed to help business owners grow without the need for security requirements, such as real estate or savings. The loan is currently only available through NAB’s proprietary channel, with customers applying via a digital application process that takes up to 10 minutes. Annualised interest rate charges are 13.85%, with a loan term of 12, 24 or 36 months. NAB
“You’ll be very aware of the measures we took early in the year with APRA, which has had the desired effect of cooling the more enthusiastic element of the market” Scott Morrison Treasurer
‘SCALPEL-LIKE’ CHANGES HAVE HAD DESIRED EFFECT ON HOUSING
values was lower in November 2017 than in November 2016. “Can you imagine what the impact would be on Australia’s housing markets if you got out the tax sledgehammer, increased capital gains tax by 50%, and removed negative gearing?” This approach under Labor’s proposals would cause “serious damage” to the housing market and destroy consumer confidence, Morrison predicted. Globally, investors and ratings agencies have expressed concern about a hard landing in the Australian housing market, which is something the Coalition has worked hard to avoid, he said. “Now, the actions we’ve taken, both with the housing affordability package in the budget this year and the measures we’ve taken with the banks, but particularly with the regulator, has meant we’ve been able, so far, to ensure a soft landing of those markets, which is good for the economy.”
The Treasurer has cautioned against Labor’s ‘sledgehammer’ approach to moderating price growth Scott Morrison touted the cooling of the property market as evidence that the Coalition’s calibrated policy approach is working to rectify rampant housing growth. Speaking at a press conference on the ‘Mid-Year Economic and Fiscal Outlook’ in Canberra on 18 December, Morrison said he was “encouraged” by what he saw in the housing sector, and slammed Labor’s proposals for moderating growth as having a potentially devastating effect on property markets across Australia. “You’ll be very aware of the measures we took early [last] year with APRA, which has had the desired effect of cooling the more enthusiastic element of the market in the investor side, particularly in TREASURER
Sydney and Melbourne,” Morrison said. “So with the slightest change to interest-only lending we’ve seen Sydney house prices fall from double digits, from 15% to 5%, in six months.” This was achieved with the “slightest, calibrated, scalpel-like” changes to macroprudential policy, Morrison said. According to CoreLogic, national dwelling values started to level off in the third quarter of 2017, with the sharpest transition being in Sydney. Other capital cities, with the exception of Perth, have also seen their growth rates slow. Although the heat is coming out of the market, Sydney and Adelaide were the only capital cities where the annual change in dwelling
VV$40,614,829,064 GLOBAL HOUSEHOLD DEBT SINCE THE GFC Source: Bank for International Settlements
Percentage of GDP
Ratio of Australia’s household debt to GDP now exceeds 120% High and rising
High and flat/falling
Low and rising
Low and flat/falling
140
140
140
140
120
120
120
120
100
100
100
100
80
80
80
80
60
60
60
60
40
40
40
40
20
20
20
20
0
0
0
09
11
13
15
17
09
11
13
15
17
09
11
13
15
17
0
09
11
13
15
Year
8
Australia
Sweden
Spain
United States
Belgium
China
Euro area
Japan
Canada
Korea
United Kingdom
Netherlands
Brazil
Singapore
Germany
India
Switzerland
Norway
Italy
Mexico
www.brokernews.com.au
France
17
NEWS
TECHNOLOGY
BROKERAGE EMPLOYS CHATBOT ASSISTANT brokerage Diversifi has been the first to use a new lead management tool that comes with advanced chatbot AI. The Epictenet Broker Empowerment Solution merges fact find, referrals, live chat and loan calculators in one customisable package. Epictenet aims to empower brokers to do more without becoming dependent on a third party, said Ritesh Srivastava, the tech company’s founder and CEO. “Brokers have seldom had access to industry-leading technology, and Epictenet is trying to change that.” WA
BROKERS TO REVEAL LENDING DATA UNDER CIF REFORMS A new public reporting regime will see brokers offer key information to consumers, while aggregators and lenders report data to ASIC new public data reporting regime involving brokers, aggregators and lenders has been proposed by the Combined Industry Forum (CIF), in order to promote transparency around competition and achieve better consumer outcomes. The regime is part of the six principles found in a paper submitted to Treasury in response to ASIC’s broker remuneration review and the Sedgwick recommendations. “[This] is really about using disclosure transparency to produce better-informed decisions,” Mike Felton, CEO of the MFAA, told Australian Broker. “The main area about that is lender coverage and breadth of A
choice. That was something that was brought up in the ASIC report, which found that over 80% of business that a broker does is done with four lenders.” The reporting regime will align closely with what ASIC asked for in its remuneration report and will see individual brokers publicly disclose the following to consumers: a list of lenders available to the customer via the broker’s aggregator; the number of lenders used by the broker in the previous financial year; and the top six lenders and percentage of business written to those lenders in the previous financial year. New-to-industry brokers who have been operating for fewer than 12 months will not be required to provide figures pertaining to the
previous financial year. Aggregators and lenders will also be required to provide ASIC with crucial lending statistics. Aggregators will need to supply a list of all lenders on their panel and the percentage share of business written with each during the previous financial year. They will also need to supply the following information on their registered brokers: the percentage of brokers using three lenders or less; using between four and seven lenders; and using eight or more lenders. Finally, aggregators will need to supply the weighted average commission rate percentage earned in the previous financial year for residential lending. Lenders will need to provide ASIC with the weighted average pricing of home loans across different distribution channels throughout the previous financial year. Specifics of this will be defined at a later date. The CIF’s public reporting regime is due to be implemented by the end of 2018.
MUTUALS CONTINUE TO GROW THEIR RESIDENTIAL LOAN BOOK
100%
4.68%
4.54%
4.55%
4.75%
4.84%
2013
2014
2015
2016
2017
95%
90%
85%
80%
10
www.brokernews.com.au
Mutuals
has launched a postcode look-up tool to help brokers have more informed conversations with their clients following changes to the bank’s credit policies for certain postcodes. “Every postcode is different, and the new tool will help brokers better understand policies that may apply in different regions for different property types,” a CBA spokesperson said. The bank will continue to lend to all regions and postcodes, they said, adding that the changes had been made to ensure and maintain responsible lending standards. CBA
Source: KPMG Mutuals Industry Review 2017
The majors
CBA TOOL AIMS TO INCREASE TRANSPARENCY
YOUNGER AUSTRALIANS PLAN TO INVEST IN PROPERTY Source: Mortgage Choice Australian Financial Savviness 2017 Whitepaper
The financial strategies employed by older and younger Australians
Baby boomers
58%
77%
invest in shares in order to grow their wealth
read the news to stay abreast of what’s happening in the financial markets
Gen Y
71%
68%
81%
have invested or will invest in property to build their wealth
seek professional advice in order to make the right financial decisions
will ask family and friends for advice before making any financial decisions
VOI APP GEARED TOWARDS THIRD PARTY law firm MSA National has announced the rebrand of its popular verification of identity (VOI) app from IDme to IDyou. The name change came about to improve clarity around the app’s target audience. “A lot of brokers said, ‘I’m using the app to ID you. Why have you called it IDme?’” said MSA managing director Sam Makhoul. The app is built for brokers to help them identify their clients, and is one of the few remote VOI apps available for brokers, he said. AUSTRALIAN
NEWS
R E G U L AT O R S
HIGH-RISK LENDING HAS SLOWED DOWN – APRA lending “broadly continued to moderate” during 2017, APRA said in a 7 December paper. New lending at LVRs over 90% decreased from 8.1% in September 2016 to 6.9% a year later. “Other forms of higher-risk mortgage lending including interestonly lending at high loan-to-valuation ratios and high loan-to-income lending … have also moderated from 2015 peaks.” APRA said it would maintain its focus on constraining borrower leverage using its residential mortgage lending reporting form to capture additional information on borrower debt-to-income levels. HIGH-RISK
ACCC URGED TO LOOK INTO INTEREST-ONLY RATE REPRICING The House Standing Committee on Economics has suggested the regulator examine interest-only rate moves as part of its residential product inquiry ACCC has been called on by the House of Representatives Standing Committee on Economics to delve further into interest-only mortgage repricing by the four major banks. In the committee’s third report on the review of the four major banks released on 7 December, it proposed an added focus on the industry-wide repricing of both new and existing IO loans in June 2017. At the time, the major banks’ media releases indicated that the rate increases were primarily due to APRA’s regulatory requirements, but under further scrutiny the banks admitted that other factors had contributed to the decision, the report said. “In particular, banks acknowledged that the increased THE
COULD REGULATION EASE IN 2018? Moody’s Analytics report has forecast that APRA will ease up on some of its macroprudential measures in 2018 in response to changes made by the Reserve Bank of New Zealand. “An interesting tidbit we have observed in recent years: Housing regulation in New Zealand tends to lead Australia’s by at least a year,” Moody’s wrote. With RBNZ recently easing certain prudential measures after softer house price growth, analysts predicted that APRA might follow suit with some “minor reversals” in 2018. A
12
www.brokernews.com.au
interest rates would improve their profitability.” Analysts at CLSA estimated that the banks’ net interest margins increased by up to 12bps following the rate increases announced in March and June last year. The committee recommended that the ACCC examine internal documents from the four major banks to determine whether the information aligned with the banks’ statements that rate rises were a direct result of APRA’s regulatory requirements around IO lending. The investigation would fall under the ACCC’s present inquiry into residential mortgage products, which was established to monitor price decisions following the introduction of the bank levy.
The committee also urged ACCC to examine the banks’ decisions to increase rates for existing customers despite APRA’s speed limit only targeting new borrowers. “Further, the ACCC should consider whether the banks’ public statements adequately distinguish between new and existing borrowers. The ACCC should consider whether the media statements suggest rates on existing interest-only mortgages rose as a direct consequence of APRA’s regulatory requirement.” Granular analysis of the banks’ financial modelling is required, the committee wrote, in order to understand the financial impacts of these regulatory changes and compare that impact against any public statements by the banks. In the October committee hearings, the major banks said rates had been changed for two reasons: APRA’s regulatory requirements and to encourage existing borrowers to move from interest only to principal and interest.
IMPACT OF MORTGAGE REPRICING ON NET INTEREST MARGINS Source: CLSA
bps 14 12 10 8 6 4 2 0
Mar 17 Qtr ANZ
Jun 17 Qtr CBA
Sept 17 Qtr NAB
Dec 17 Qtr WBC
Mar 18 Qtr
Jun 18 Qtr
FE AT URES
SPECIAL REPORT
GIVING BROKERS A VOICE Industry pioneer Greg Pennells has blazed a new trail with his subaggregator, Purple Circle Financial Services – one that encourages brokers to speak up, share ideas and become company shareholders
KEY BUSINESS METRICS
41 brokers onboarded in a year
National presence, with brokers in NSW, Vic, Qld, SA and WA
Brokers average close to $2m in loans per month, twice the industry average
Brokers wrote more than $100m in loans in 12 months
Short-term goal: Onboard more than 200 brokers by December 2018
Long-term goal: Scale up to 1,000 brokers over the next three to five years
14
www.brokernews.com.au
are very few companies in the broking industry that would be likened to “a movement”, but that’s how one broker describes being part of Purple Circle Financial Services, one of the youngest subaggregators in the business. “What a lot of [brokers] are feeling is that they’re just a number in some of the big aggregators’ books … they get told what’s happening with them,” says Purple Circle’s founder and managing director, Greg Pennells. “What they’re getting with us is they’re actually not pawns at all, they’re right at the top.” About a year and a half since opening its doors in August 2016, Purple Circle now has 41 brokers on board across the country, nine staff members and three BDMs. Its brokers, the majority of whom are established brokers who decided to switch aggregators, as well as some new-to-industry members, are averaging around $2m a month in new loan settlements, about double the industry average. Pennells’ goal for 2018 is to welcome more brokers into the Purple Circle fold, a subaggregator that’s anything but average. Not only is the company’s name unusual; so is its business proposition. Its brokers are its clients, and also its owners. For entrepreneurially minded brokers, this has proved to be an attractive offer. Purple Circle’s intention is to make brokers feel part of “an invitation-only meeting of like-minded people”, which is actually the meaning behind its colourful name. In the Purple Circle world, brokers can earn shares in the company based on the volume of loans they THERE
write. Brokers get to decide on the split. For example, the lower the commission, the more shares they can earn and vice versa. Brokers receive the same services and tools that Purple Circle’s parent aggregator, Finsure, offers its members, such as use of its CRM, commission accounting services and ACL. In addition to earning income through the traditional upfront and trail channels, shareholder brokers are also entitled to enjoy an additional income stream in the form of company dividends, Pennells says. “Once the shares have been earned
“We won’t make any major decisions without consulting our brokers and asking them what they think … and if they don’t like it, we won’t do it, because they’re also owners, they’re also shareholders, and they have skin in the game. “They really enjoy having that voice and having a bit of control over their destiny, rather than just being in this ocean of change,” Pennells says. All brokers who are shareholders are entitled to see the company’s financials, such as its profit and loss statements, and they get to take a hands-on role in the decision-making. Shareholder brokers get to join a steering committee that represents the interests of the broking group as a whole, Pennells says. An elected broker from the committee sits on board meetings to tell the company heads what brokers want and need. In the last few months, four of Purple Circle’s first broker members have become shareholders.
“What a lot of [brokers] are feeling is that they’re just a number in some of the big aggregators’ books … what they’re getting with us is they’re actually not pawns at all, they’re right at the top” Greg Pennells, Purple Circle by the broker they come without encumbrances. You can sit back and enjoy company dividends, will them to your kids, sell them to other brokers, or anyone for that matter. And if the company is sold or floated in its entirety, you can enjoy the capital benefits that come from the sale. These are benefits that have never been passed through to brokers themselves,” he says. Allowing brokers to earn a stake in the company and have their voices heard has resulted in “a complete paradigm and cultural shift”.
“They speak to the other brokers and ask, ‘What do you need, what have you seen in the marketplace, what have you seen in other industries, what have you seen overseas?’ And then we sit down and brainstorm,” he says. Instead of dumping decisions onto brokers that have been concocted by executives in an ivory tower, the Purple Circle approach is to come up with strategies collaboratively that help the group grow collectively. “It’s completely transparent and our brokers really appreciate that. There’s no cloak and dagger, and
In partnership with
Greg Pennells, founder and managing director of subaggregator Purple Circle
there’s no, ‘We’re in it for us and they’re in it for themselves’. We’re just an open book,” Pennells says. Benefits for brokers Paul Lewis, director of South Australian-based Lighthouse Financial Services, joined Purple Circle from the very beginning and is now a shareholder. He said the decision to switch to a group that was developed and driven by one of the most respected and passionate industry pioneers was a “no-brainer”. While he’s been with three other aggregators in the past, none were like Purple Circle, which he says is “an aggregation group built by brokers for brokers and for brokers alone”.
Purple Circle has fostered a working environment that encourages brokers to share their input, knowledge and experience to drive change, Lewis says. In a time of flux for the industry, having an aggregator that supports and stands alongside brokers is important. “I believe that our industry is under attack, and we are in danger of losing our identity as finance professionals and even our relevance in the market. Purple Circle has the potential to be far more than just an aggregator; it provides the potential to have a voice in our industry,” he says. “Purple Circle is very different – it’s a movement. … Stay tuned. I believe we will make a real difference in our industry.”
Leading together As an early adopter of mortgage broking in the 1990s and co-founder of Choice Home Loans and Choice Aggregation Services, Pennells is no stranger to the challenges that come with starting up a business. Despite the challenges and the waves of change the industry is undergoing, he’s still managed to blaze a new trail with Purple Circle. “The setting up of the appropriate corporate structures to accommodate issuing shares to brokers was by far the biggest challenge so far,” he says. “Apparently, what we are doing with our brokers is unprecedented not only in the finance world but also in corporate Australia. Countless
hours were spent with lawyers and accountants to create a structure that makes it all work, and as essential as this was, it really pushed the grey matter to its limits.” Pennells is eager to keep pushing the boundaries, something he believes was more common in the industry’s early years when companies were driven by innovation, imagination and entrepreneurship. Lately he’s found that aggregators have shifted their attention to compliance and regulation, sometimes losing sight of brokers’ needs. “[That] is fair enough, but the problem is it’s created a bit of a sea of sameness where one aggregator looks exactly the same as the other. … Nobody is innovating.” Purple Circle is looking to shift the status quo. “We consider ourselves less of a broking business but more of a platform for ideas and innovation from our brokers,” he says. As a subaggregator it can rely on Finsure’s expertise and vast resources in the compliance and regulatory department and instead focus on its brokers’ business strategy, development and idea generation. Over the next few years, Purple Circle’s plan is to continue growing while still giving brokers a voice. Pennells is not shy about his ambition. He wants to end 2018 with 200 brokers on board. So how will he expand the company to ensure it retains its collaborative, transparent feel? Pennells says the company’s model is designed to grow to scale so that the feeling of connectedness that makes Purple Circle unique is maintained. The steering committee will add new members as the company does so that brokers continue to feel valued and fairly represented. “We’re going to start doing some things that no one’s ever seen before, and that’s going to attract more people to us, and it’s actually going to raise the support that all brokers with all aggregators will come to expect as a new standard,” he says. If you want to know what Purple has in store, Pennells says, “you’re going to have to watch this space”. AB www.brokernews.com.au
15
FE AT URES
NE WS ANALYSIS
AT ODDS OVER ACCREDITATION Many industry figures have embraced CBA’s recently unveiled changes to broker accreditation, but some question the bank’s decision not to work with new entrants and how that might affect the future of the industry
16
www.brokernews.com.au
hurdle for those who already face steep challenges. It will likely force brokers to establish their skills elsewhere and take their loans elsewhere, leaving them with
“From our perspective, we’ve already read the tea leaves and we want to move this from an industry to a profession, and to do that we need to improve education levels” Clive Kirkpatrick, Vow attrition rates are high. Of all those who joined the industry during those six months, 10.2% left, a trend that’s expected to continue. Barring new entrants from accessing the largest lender in the country could prove to be another
“no need for CBA in the future”, says FBAA executive director Peter White. “If you do not invest in those as they are growing, you stand a very strong chance of them being users of your competitors and never using
your offerings. So if you turn your back on young-to-industry brokers and they learn and use other market providers, then why would CBA think they would come to them in the future once they are industry adults?” White says. Not everyone sees CBA’s accreditation changes as being that significant, however. Most lenders have similar criteria in place, and the MFAA and the FBAA also have their own education standards. Brokers who have less than two years of loan-writing experience must obtain their mortgage broking diploma within the first 12 months of becoming an MFAA member. FBAA members are required to have their Cert IV, but White says the vast majority have also received the diploma or have pursued higher education degrees of their own volition. White is of the opinion that
ANZ AND CBA ARE THE TOP LENDERS FOR BROKER-ORIGINATED LOANS
8%
8.53%
11.27%
14.89% 15.10%
16.36% 16.24% 9.93% 9.55%
9.88% 8.21%
9.78% 9.61%
14.77%
18.08%
18.39% 9.14% 11.37%
14.17%
16.29% 12.30%
14.39% 12.47% 10.01% 11.06%
15.89% 11.78% 10.83% 10.59%
8.70% 11.62%
15.91% 12.81%
18.59% 8.13%
9.85% 7.99%
12% 10%
9.04% 8.51%
14%
13.17% 11.89%
16%
18.40% 16.53%
18%
18.38% 17.04%
20%
18.31%
Source: AFG Competition Index, December 2017
9.29% 7.65%
Where does this leave new brokers? The mortgage broking industry has been steadily growing over the last couple of years, with hundreds of new brokers joining the sector every six months. According to the MFAA’s latest Industry Intelligence Service report,
for 1 October 2016 to 31 March 2017, the broker population reached 16,009 brokers during this period, 500 more than in the previous six months. Broking is not an easy job and
15.01%
a fractious year between brokers and the CBA, the major bank did not go about ingratiating itself with the third party channel before the summer break. Instead it announced on 14 December that it would be freezing accreditation for the remainder of 2017 to implement new benchmarks designed to lift standards, emphasise education and “ensure the bank is working with high-quality brokers” in the new year. Starting in early 2018, the bank said mortgage brokers wishing to write CBA loans would need to hold at least a Diploma of Finance and Mortgage Broking Management; be a current member of either the MFAA or the FBAA; and be a direct credit representative or an employee of an approved aggregator/head group or an Australian credit licence holder. But the point that raised the most contention and debate among industry members was the CBA’s firm stance on only doing business with brokers who have at least two years’ experience writing residential loans. While many industry figures said they were supportive of CBA’s attempt to lift standards and consumer outcomes, they disagreed with the bank’s decision not to work with new entrants, saying it could prove damaging to the bank’s business and the future of the industry. AFTER
6% 4% 2% 0%
Dec-16 ANZ
Jan-17
Feb-17
Mar-17
CBA
NAB
Westpac
Apr-17
May-17
Jun-17
Jul-17
Aug-17
Sep-17
Oct-17
Nov-17
From left: Clive Kirkpatrick, general manager, Vow Financial; Peter White, executive director, FBAA; Rebecca Barbe, owner, Finance Solutions Queensland; Mark Vilo, head of bank intermediaries, Suncorp
effective learning and education should not be foisted upon people. “Undertake learnings because you want to and you believe it will be beneficial to you in your business or personal knowledge. Do it in your own time and pace, and in line with what is legally required by law,” he says. Where CBA has upped the ante compared to other lenders, however, is in making it mandatory to have a diploma, and specifying the amount of experience required. Sam Boer, CBA’s general manager of third party banking, explained in an earlier interview with Australian Broker that the two-year rule has always been part of CBA’s accreditation policy; it’s just that now the bank has decided to take a firmer position on it. “Two years has actually always been the policy, but what we noticed was that there were a lot of different mentoring standards being applied, and we felt that this really needed to be improved upon,” he said. “You wouldn’t expect to see too many exceptions to that rule, but what we’re seeing in recent times is that basically every accreditation has been an exception.” CBA said brokers would also be put under additional questioning during the accreditation process, with more scrutiny on the individual, the company they work for, the head group they’re partnered with, the quality of their business, and how they have been operating. “[This is] so we really understand who the person is that we’re dealing with and that they are in fact qualified to be able to operate and represent not only our brand but the industry to ensure these
new standards,” Boer said. Rebecca Barbe, broker and owner of Finance Solutions Queensland, says she doesn’t take issue with CBA’s accreditation changes because they underscore the importance of getting sufficient on-the-job training. “There are more people who enter this industry and think it’s an easy way to make money, and it’s not. If you have that mindset, that’s when things like compliance aren’t important to you, and compliance is such a huge part of this industry.” It’s not so much getting a formal education that matters but gaining experience working with clients, writing loans and reading financials, something new brokers should do by working as loan writers and getting
lender in the country is tightening its policies around the accreditation process, and he generally doesn’t consider the changes to be hugely significant. It’s more about the message behind it: it’s a flag to the market that education standards need to be raised across the board to ensure brokers and other industry players are suitably educated and are in an environment of constant learning, Vilo says. “It will impact the industry and it will create dialogue and it will create some action,” he says. “In terms of consumer outcomes, having a better-educated individual that’s been in the industry longer can help, but it doesn’t automatically
“You can’t become a broker without the big four on your panel, so it depends on what the [other lenders] do. Time will tell” Rebecca Barbe, Finance Solutions Qld a mentor early on, Barbe says. Overall, she doesn’t see CBA’s move itself as having a major impact on new brokers. It will only pose challenges for them if the other majors and some of the second-tier lenders follow suit. “You can’t become a broker without the big four on your panel, so it depends on what the others do. Time will tell.” Lifting the bar Mark Vilo, head of bank intermediaries at Suncorp, says it’s understandable that the largest
translate to a better broker.” Clive Kirkpatrick, general manager of Vow Financial, echoes these sentiments. He says the YBR group is broadly in agreement with what the CBA has put forward. “From our perspective, we’ve already read the tea leaves and we want to move this from an industry to a profession, and to do that we need to improve education levels,” he says. It’s not so much the level of qualification that’s an issue, he adds, but the ongoing and continuous education needed to help people
CBA’S NEW ACCREDITATION STANDARDS New accreditation criteria require brokers to:
hold at least a Diploma of Finance and Mortgage Broking Management
be a current member of the MFAA or the FBAA
be a direct credit representative or an employee of an approved aggregator/head group, or an Australian credit licence holder
have at least two years of experience writing regulated residential loans
www.brokernews.com.au
17
FE AT URES
improve. He says it’s about encouraging people who are better educated and can understand financials, who are good at building relationships with customers and can deliver better advice, to join the industry. “CBA can’t go at it alone. I would have thought it would have been better that the Combined Industry Forum (CIF) made this statement and the agreement and the action to move forward with education. But I’m glad that the CBA has put a line in the sand,” Kirkpatrick says. So far, it does seem that the CBA is going at it alone. The CIF actually made little mention of brokers’ expected education standards or requirements. It instead provided recommendations around educational content at conferences and professional development days and looked at whether there were any conflicts of interest if lenders and aggregators provided financial support for education and training. Both Kirkpatrick and Vilo do question, however, whether barring new entrants from writing loans with the bank could impact the CBA’s business and the sustainability of the profession. As brokers get older and start retiring from the industry, it’s important for the future of the profession that companies foster the growth and education of new entrants, Kirkpatrick says. “I just completely disagree with having a freeze on bringing new people into the industry. I just think it’s the wrong thing to do. CBA has taken a unilateral stance on that at the moment,” he says. With new brokers diverted away from CBA, it could actually benefit the other majors and non-majors. Suncorp will continue to support and educate new-to-market brokers, something Vilo says they often remember later when their careers have kicked off. “The challenge will be, for lenders like the CBA, ensuring that they get some currency from brokers who have been in the market for two years and have never done business with them,” he says. 18
www.brokernews.com.au
BROKER TURNOVER REMAINS HIGH Source: MFAA Industry Intelligence Service report
1 October 2016–31 March 2017
He also says Suncorp is satisfied with its current accreditation criteria. “Between now and the foreseeable future, we’ve got no plans to say to any broker that you need to have a minimum of two years of experience to be able to do business with us – not at all.” Two sides to every opinion Most people seem to be split on the changes and what their outcome will be. On the one hand, the more time and energy that’s invested in helping people understand a bank’s products, processes and policies, the better the broker will be at advising a customer, Kirkpatrick points out. “In the longer term, if CBA holds firm on that particular [two-year rule], then it would be detrimental to their business,” he says. But on the other hand, brokers shouldn’t be resistant or offended by CBA’s attempts to raise the bar. “We all owe it to our customers to provide better quality, so if [brokers have] got an issue around providing better-quality advice and delivering better-quality submissions to a bank, then that’s probably not a profession they want to be in for the long term.” AB
NT
10.1%
QLD
10%
WA
8.4%
SA
9.1% NSW & ACT
9.6% VIC
11% TAS
13.1%
Percentage nationally
10.2% Note: Broker turnover is calculated as the number of brokers who left/the number of brokers at the start of the period
www.brokernews.com.au
19
FE AT URES
OPINION
THE BEST BOOKS FOR BROKERS Marc Barlow, of Mortgage Broker Melbourne, shares his top titles for inspiring, thought-provoking reading that will get your business in good shape for the year ahead
most brokers, I began my career straight out of the bank after realising there was no such thing as a job for life any more. I had survived the most recent round of ‘job spilling’, which sounds innocuous but was actually a fiendish way of controlling the expense budget and keeping everyone on their toes. Team leaders were pit against each other to secure fewer jobs than there were before, with twice as many team members for only a tad more pay. It was like The Hunger Games. It occurred to me that perhaps being self-employed would bring more stability. I have previously written about the book that inspired me to take the plunge and start my own business, Rich Dad, Poor Dad by Robert T Kiyosaki. This was truly the catalyst, but it wasn’t the road map for succeeding in business; for that you need to read The E-Myth Revisited by Michael E Gerber. I learned some startling statistics on business failure from this book. About four out of every 10 businesses fail within the first year. And about 80% of those that make it through the first 12 months will fail within five years. Gerber goes on to explain why, and it’s quite enlightening. I won’t spoil the plot too much, but the book dispels the myth that all businesses are started by entrepreneurs – heroes who are somehow more dynamic than normal people and are willing to risk it all on some wild idea. The E-Myth talks about the more common case in which someone decides to leave their job and strike out on their own and become their own boss. The book explains the challenges this person will face and the introspection required for them to realise they don’t yet possess all the knowledge they need in order to succeed as a business owner.
Personally speaking, I never considered myself an entrepreneur either. Coming straight out of the bank, I thought: “How hard can it really be?” Those self-employed mortgage brokers reading this will all have got where they are via slightly different paths, although I’m sure we all started out thinking it was going to be easier than it turned out to be.
LIKE
20
www.brokernews.com.au
lofty goals as a national network, but a business that functions efficiently and doesn’t swallow up every aspect of your life. Another book I read very early on that helped me deliver quality service is part of The One Minute Manager series. Written by Ken Blanchard and Sheldon Bowles, it is called Raving Fans! The clue is very much in the title, of course. I needed referrals, so I didn’t just want satisfied customers; I wanted raving fans who would shout about my wonderful service from the rooftops to all their friends, family and colleagues. Ravings Fans! is written in a jaunty, parable style and will not take long to read. I found it was a bit of a page-turner. It follows a similar theme to The E-Myth, as it asks the reader to look inwards at what they consider to be exemplary service, and then to build a framework around that to create an experience that goes above and beyond the mediocre service most people accept. That theme needs to be woven through the entire fabric of the business, especially those who work within the organisation.
It is really a handbook for those who want to set up a systematised business of their own … [one] that functions efficiently and doesn’t swallow up every aspect of your life
Marc Barlow Mortgage broker, Mortgage Broker Melbourne
The E-Myth travels through the usual growth phases of any fledgling business, starting with the initial honeymoon period when the newly self-employed person is happily managing all aspects of the business themselves, then moving on to the growth stages and the challenges that they bring. Great suggestions are offered for dealing with these various stages. They involve looking inwards and finding the personal traits needed to deal with these challenges. Gerber coined the phrase “working on your business, not in it”, and discusses how to focus on the business itself, not just the product being sold. The book will help those looking to start a business rather than those simply looking to buy themselves a low-paid, high-hours job. It is really a handbook for those who want to set up a systematised business of their own, like a franchise – not necessarily with such
The book helps a business owner understand the needs of the client as well as the staff who help deliver the service. Everyone needs to buy into the idea and be rewarded for delivering, not simply penalised constantly for doing the wrong thing. Raving Fans! will help any business owner to gain a competitive edge through a genuine dedication to the end user of their product, and to change the ethos of their business in order to create lasting change. Both The E-Myth and Raving Fans! make for great reads and can be useful no matter what stage of the business cycle you’re in. AB Marc Barlow has been in mortgage broking for more than 10 years, after previously working with retail banks in Australia and the UK. He is currently a mortgage broker at Mortgage Broker Melbourne, based in the CBD.
IN THE NE WS
UNDER ROYAL WATCH Following further consultation, the government has decided to include the broking industry in the royal commission’s scope
commission should take into account the immense scrutiny that the broking sector has been and continues to be under and the important role brokers play in the lending market. Brokers have recently been the subject of or have been included in numerous reviews, including the ASIC remuneration review, the Sedgwick report, the Combined Industry Forum’s package of reforms, and the productivity
ASIC in its review of brokers. “The ASIC report recognised the important role that mortgage brokers can play in promoting good consumer outcomes and strong competition in the home loan market, and we are confident any other examination of our sector would find the same,” he said. He called on the royal commission and the industry as a whole to focus on how competition could be further
“The mortgage broking channel accounts for more than 53% of the Australian lending market, so it is unsurprising that we are in the mix” David Bailey, CEO, AFG David Bailey, CEO, AFG
royal commission will now include mortgage broking as part of its overall investigation into the alleged misconduct of the financial services sector, the government announced at the end of December. The government decided to expand the commission’s purview to include “people or entities that act as intermediaries between borrowers and lenders”, following further consultation with appointed commissioner Kenneth Hayne. The commission’s inquiry will now include “banks, insurers, superannuation trustees, holders of Australian financial services licenses and intermediaries, such as mortgage brokers”. Hayne will be examining allegations of misconduct to determine if any civil or criminal charges should be laid. He will also be tasked with determining whether conduct, practices or behaviour of a financial services business or THE
individual fall “below community standards and expectations”. The commission’s official terms of reference do not specifically include “mortgage brokers”. The letters patent to Hayne instead states that the commission will look into ADIs, general and life insurers, Australian financial services licence holders and intermediaries. National aggregator AFG said the
commission’s ongoing inquiry into competition in the financial system. “The mortgage broking channel accounts for more than 53% of the Australian lending market, so it is unsurprising that we are in the mix; however, 2017 has also been marked by significant regulatory scrutiny of our industry,” said AFG CEO David Bailey. Bailey expressed confidence that Hayne would recognise the vast amount of data already collected by
improved, including the impact of the government’s guarantee. “Ultimately, the findings of this inquiry should assist the government to promote a competitive and stable financial industry that contributes to Australia’s productivity.” The broking sector is vital to ultimately delivering that goal, he said. The commission’s interim report is due no later than 30 September 2018, with the final report expected no later than 1 February 2019. AB
ANZ’S OWNER-OCCUPIER LENDING INCREASED IN AUGUST Source: MyState poll
38%
14%
of brokers are in favour of the royal commission
Note: The poll was conducted prior to the government’s official announcement
24%
17%
Of those... said it was ‘definitely needed’
41%
of brokers are against a royal commission
24%
Of those... said it was needed ‘on balance’
said ‘no, it was not needed’
said there were ‘other more important issues to address’ in the economy
www.brokernews.com.au
21
PEOPLE
Have an interesting deal? Had a particularly difficult or interesting deal? Why not share it with us? Email:
Otiena.Ellwand@keymedia.com.au
A BIG DEAL
which had in turn affected their home loan application. THE SOLUTION
Mihir Shrestha, a mortgage broker at Origin Finance, learns that there’s always a story – and a solution – behind a declined loan application
Location: Gold Coast
THE FACTS
22
www.brokernews.com.au
Loan term 30 years
Aggregator Choice
Lender AFM
The clients were quite distressed as they’d already asked for an extension and had only three days left for finance. My first step was to get a rundown of what happened with the bank and the previous broker, to understand the clients’ situation. I wanted to know the
THE SCENARIO
My clients were a young couple in their early 30s who were planning for their first baby. They were living in Surfers Paradise in a two-bedroom unit. They wanted to upgrade to a house with a backyard in a family-friendly suburb. They found a property and made an offer, with 14 days to finance and 60 days to settlement. They went to their bank for the home loan and got conditional approval; however, the valuation came back $20,000 lower than the contract price. They did not have extra funds to contribute, so it could not go ahead as the bank couldn’t order another valuation. Looking for options, my clients got recommended to another broker. That broker applied for their loan but got declined. I met the couple through a mutual family friend at a dinner party. When the male client found out I was a broker, he told me about his situation and asked me questions. I told them to come see me the next day and I would try to help.
Loan size $515,000
After ascertaining the situation, I told the clients to be prepared to request another extension, and that I would do my best to get the loan over the line. I found a lender who did not credit score applications. The interest rate was still very competitive compared to the big four banks, so it didn’t disadvantage the clients. I also ordered an upfront valuation for the property. This time it came back only $5,000 short of the contract of sale, as opposed to $20,000. Before submitting the application, I contacted the lender BDM to stress the time constraint we were under, and also to run the scenario by him to ensure it would go through. We had to ask for an extension of four working days. With the help of the BDM and the assessor, we got full approval done on time and the client settled as per the contract. The clients were so thankful and relieved that they were able to get their dream house. THE TAKEAWAY
This experience was a learning curve for me. I was close to not offering my help to this couple when I was told that their own bank and another broker couldn’t help them. But due to our mutual friend, I decided to give it a go. As brokers, we need to take our time to learn about the clients and their situation. At times you may need to use a lender that’s not your favourite, but if you can help clients who are in a difficult situation get a loan, they will always be grateful. Having a good relationship with the BDM was a great help in pushing the loan through, given the time constraint. They are there to help us and they will benefit
My first step was to get a rundown of what happened with the bank and the previous broker, to understand the clients’ situation
Mihir Shrestha Mortgage broker, Origin Finance
reasons they’d been declined so I could tailor a solution to them. I prompted my clients to obtain their credit report. The report showed that they had numerous credit enquiries. The male applicant said he’d applied for a car loan through a dealership, but they hadn’t gone ahead with it. Instead, they’d taken out a small personal loan and had applied for a couple of credit cards. All of this had negatively impacted their credit score,
us and our clients. I remember my mentor telling me: “Make your BDM your best friend”. I have always thought of that and have applied that in my day-to-day life. I strongly believe self-reflection is another important thing for brokers to do. What worked? What didn’t? What will I do if a situation like this occurs again? These are the questions I ask myself with every deal. Even the best of the best have room for improvement, and I am just a rookie. AB
LENDER UPDATE
LEARNING THE 180-DEGREES WAY We learn from everything we do – not just at work but from life lessons and experiences – and this is something that should be fostered among your staff, writes Cathy Dimarchos, general manager of non-bank lender Sintex
THE CHOICE IS YOURS
The Sintex Team
At Sintex we have a diverse team, with each member bringing something different to what we do. There are also similarities among the team, namely that each person who works here has pushed themselves outside of their comfort zone in taking on new tasks, achieving the biggest learning curve of their careers. It is challenging, exciting and frightening all at the same time, but the key here is that they were prepared to accept the challenge and take a leap of faith in their teammates, allowing themselves to become vulnerable. MAGAZINE This type of trust builds an incredibleThe team. It creates belief only independent in oneself and also facilitates magazine dedicated the opportunity for personal growth and professionalindustry to mortgage development. news, opinion and I believe everything and everyoneanalysis can be taught; there are no ‘specialists’ in life. While some may have experiences that afford them foresight, this does not make them better equipped to manage a job than someone who has passion and dedication and is willing to listen and take on board what is presented to them. Asking questions – the right questions – and being a responsive listener goes a long
way in life and business. So, if you are prepared to walk the ‘pavement’ and make yourself vulnerable, welcome the ‘magic’ that will unfold. ‘Balancing life’ is a cliché that’s often referenced, yet it is a very important aspect of business. I say business because without people we have no business. It’s important to remember that while we have deadlines, customers, targets,
and they deliver. They also know that you have each other’s backs, when and if the need comes, to take care of the most precious thing in life … their family. Most of us have passion and dreams, but we seldom share them, especially with our work colleagues. This is part of our psyche, so ignoring it or allowing it to smoulder slowly is allowing a fire to burn out. It’s important to ensure that
Give [yourself ] time out regularly to feed that passion. WEBSITE By doing this, it provides clarity Breaking news, and serenity in-depth profiles, features, online
service level agreements and forum and everything that revolves around achieving the bottomAustralian line that we have set our eye on, it’s the team and each individual that will deliver that. Your team, your staff, our team – all need to know that family comes first, hence the reference to balancing life. When this is known and everyone has peace of mind, the efficiencies increase subconsciously. Each person knows what needs to be done,
we don’t get trapped on that merry-go-round that just keeps Broker TV and that we give spinning, ourselves time out regularly to feed that passion. By doing this, it provides clarity and serenity. Encourage this among your staff/teams. We have staff members who are passionate about photography, dancing, innovation and technology, animals and fishing, and each of these topics is discussed in the office daily.
Sharing in other people’s interests allows you to see them in a different light, and this extends your relationship. It’s the same with your customers. Remembering their children’s names and the things that are important to them shows that you have listened and that you care about what’s important to them. It is the small things that make a difference. My passion is equality and raising the quality of life of others, especially children. I am also very passionate about the Sintex team and their personal development. For me, it’s imperative that collectively ENEWSLETTER we take on board things that are important to us, including Daily news service processes that expedite and delivered straight streamline what we need to do work,inbox but more so, that we toat your every empower each person to guide morning that change while they engage with key parties. We are all a ‘collective’ in various things we do, and it is important to allow opportunities of magic to enter our lives. In doing so, this may mean that we have to step out of our comfort zones and place trust in others. Explore opportunities and take on feedback to help you be where you want to be, when you want to be there.
FOR MORE INFORMATION, PLEASE EMAIL EDITOR@BROKERNEWS.COM.AU www.brokernews.com.au
23
FE AT URES
Get involved in the discussion Share your thoughts at
brokernews.com.au
FROM THE FORUM
Top comments from trending stories on brokernews.com.au
BROKERS TO REVEAL LENDING DATA UNDER CIF REFORMS
CIF TO UPDATE COMMISSION MODEL BY 2018
A new public data regime involving brokers, aggregators and lenders has been proposed by the Combined Industry Forum to promote transparency around competition, and better consumer outcomes. The reporting regime will align closely with what ASIC asked for in its remuneration report and will see brokers publicly disclose the following to consumers: a list of lenders available to the customer via the broker’s aggregator; the number of lenders used by the broker in the previous financial year; the top six lenders and the percentage of business written to those lenders in the previous financial year.
The Combined Industry Forum has outlined a package of reforms, including proposed changes to the mortgage broking remuneration structure, to reduce the potential for conflicts of interest and poor customer outcomes. Upfront commissions will be paid on a “utilisation basis”, dependent on the facility limit drawn down; the amount drawn down net of offset account balances (if a loan has an offset account). Trail commission will be paid on the amortised drawn-down amount net of offset account balances or based on the facility utilised.
So in essence… more red tape, less money, more reporting, for the one section of the finance industry that isn’t getting consumer complaints. Ninety-two percent of complaints are directed at the banks’ direct channel, but they give up nothing, change nothing, according to these meetings. They change nothing of their process and will make more money due to commission changes. Consumers will get serviced less as brokers lose more money, and will have to start cutting back on the time they spend with each client. The spiral downwards of this great nation continues. Bottom Line on 13/12/17 at 9:31 AM
The CIF (did you vote for them?) is looking to further laden our industry with burdens that will complicate and take further time away from face-to-face with clients. It’s what we do best, having achieved a massive 55%+ market share, which started from zero not too many years ago. ASIC, you are most welcome to view my compliance plans, credit guides and examine the quality of outcomes I deliver to clients. I have embraced legislation and have been a diligent student of the Act. Meanwhile, you have store credit card and car dealer finance providers evading key responsibilities because of holes in the legislation. You have banks that charge higher rates to existing customers over new ones, profiteering excessively from rate margins on investment portfolios, random pricing and deplorable service standards. However, apparently it’s the professional mortgage broker that has to modify their behaviour.
Concerned broker on 12/12/17 at 9:13 AM
This is outrageous to pay upfront commission on a utilisation basis. It penalises good customers and brokers that have their affairs in order, rather than arranging borrowings at the last minute. The lenders are getting a ‘free-kick’ and the broker has invested much time and energy to ‘preposition their customers’. This proposal is not about better customer outcomes, it’s about the non-payment of commissions. I would encourage all borrowers to have surplus funds in an offset if servicing is evident. There are many ‘rainy day’ events in life, sickness, loss of job, unforeseen expenses, and foreseen expenses. To have only two to three months’ savings in your everyday account is poor financial management and can only lead to hardship should the rainy day approach. Then what will happen to your ability to raise funds when you need it most? No assistance from the lenders and your credit rating is stuffed as we go to positive credit reporting. Morton on 12/12/17 at 9:51 AM
There doesn’t seem to be a lot of changes compared to what we already do. If you have been giving your clients great loans, simply due to who you have accreditation with, then all should be good. I think this is going to be aimed at those brokers who just deal with one or two lenders only and have therefore sacrificed their customer by not offering better outcomes available.
This has nothing to do with the consumer outcome. It’s all about the banks and how much they can take back from the broker. So is this the beginning of getting rid of brokers? The more income you take away, the less brokers will want to be involved in lending and more for the banks. MFAA, FBAA and aggregators are supposed to be working for the brokers. You all get paid by brokers and you would think it would be in your best interest to back the broker and … pay us what are our rightful dues. Very disappointing and frustrating that these bodies are acting on behalf of brokers and none of these bodies will reduce their fees, so why should we?
Peter on 13/12/17 at 10:58 AM
VPO Mortgages on 12/12/17 at 10:48 AM
Steve McClure on 13/12/17 at 9:47 AM
24
So, are they suggesting that if funds are held in an offset account for a few days or weeks until, say, a property deposit is due you won’t get an upfront on that portion? Lenders will automatically draw down the full amount at settlement in most cases so the client has no option but to put the funds in their offset, albeit temporarily. Brokers shouldn’t be penalised for that.
www.brokernews.com.au
CAUGHT ON CAMERA Connective brokers came together at five remarkable locations over October and November for the aggregator’s 2017 state-based conference series. Delegates heard from a diverse range of industry experts and successful broker peers on topics spanning new business development strategies, marketing techniques, health and mindfulness, and much more. Connecting more than 550 member brokers and representatives from 38 lender partners, the events in each state culminated with the Connective Excellence Awards, an initiative designed to recognise and celebrate the outstanding achievements of Connective brokers over the past year.
www.brokernews.com.au
25
DATA
WESTERN AUSTRALIA
NSW SPOTLIGHT
While Perth is still in a slump, there are opportunities for investors Though rental rates remain quite low, investors with a long-term investing strategy may be considering buying in Perth while properties are still affordable and tenant populations are increasing. According to Shane Kempton, COO of Professionals Real Estate, heightened levels of investment in the resources sector are attracting more tenants, causing rental stock to fall. If this trend continues and the vacancy rate drops to below 3.5%, landlords could find themselves able to raise rents again. This is then likely to bring in more property investors. Kempton highlights the southeastern corridor of Perth as having potential for growth, given the existing infrastructure, including public transport, shops and schools. Prices in suburbs like Kenwick are also very reasonable, considering its location near the Perth CBD. Even then, some experts are hesitating as to whether Perth is really recovering at last. Area
Type Median value
Perth
H
$500,000
Quarterly
12-month
growth
growth
-2.4%
-2.5%
WA Country
H
$330,000
-5.0%
-5.1%
Perth
U
$390,000
-4.9%
-3.6%
WA Country
U
$249,500
-17.9%
-0.7%
SOUTH AUSTRALIA
Unit lifestyle is being encouraged and adopted in SA Houses continue to be more popular than units in SA, with residents mainly seeking good-sized detached dwellings, such as renovated character-style properties. However, zoning changes in several council areas of Adelaide are spurring high-density infill development, according to Herron Todd White’s Month in Review report for October 2017. “There is increasing developer activity in areas where higher-density developments are being approved. Suburbs such as Magill, Tranmere and Prospect are experiencing good demand from developers as a result,” the report states. More properties are also being constructed on small blocks of land, and smaller homes like townhouses are also gaining ground, as long as they are located near the fringes of the CBD. These dwellings mainly cater to the rental market and small households. Area
Type Median value
Quarterly
12-month
growth
growth
SYDNEY'S COOLDOWN
Sydney’s property market is beginning to balance out as APRA regulations constrain new loans to investors
a strong trend of soaring growth over the past several years, Sydney may be inching closer to the next stage of the property cycle as price hikes start to ease up. “We have noticed a gradual cooling of the market over the last quarter of 2017, as auction clearance rates are sub-70%, [there’s] less aggressive bidding at auction and lower attendance at open homes,” says Rich Harvey, CEO of Property Buyer. Harvey considers the recent implementation of governing regulations to be a factor in the property market’s shift. APRA restrictions have limited loan activity, causing lenders to be stricter with regard to serviceability requirements. Interest rates have gone up as well, especially for interest-only loans; as a result, fewer investors are taking out such loans and demand has gone down. Meanwhile, first home buyer figures went up with the introduction of the First Home Buyers Assistance Scheme, which aims to balance the proportions of buyer types in the market by giving owner-occupiers more buying opportunities. With investors outnumbering owneroccupiers, the market is going through an adjustment period. Auction clearance rates have fallen from the 80% range to below 70%, and average time on the market has increased. Nonetheless, Sydney’s performance isn’t expected to take a severe dip. “Assuming [the RBA] isn’t too aggressive in raising interest rates, the ongoing Sydney infrastructure boom, declining apartment completions, strong jobs growth and steady population growth should see dwelling prices increase at a steady but slightly reduced rate in 2018,” Harvey reports. AB
H
$446,500
-2.1%
2.8%
Median price (houses)
SA Country
H
$285,000
-5.0%
1.9%
$1,564,626
Adelaide
U
$375,000
0.0%
4.7%
SA Country
U
$190,000
3.1%
-1.3%
www.brokernews.com.au
Northwest Sydney Vibrant communities announced for Bella Vista and Kellyville Precincts
Medowie About 480 new homes planned for community north of Newcastle
Wilton North New green spaces, schools and shops slated to create thousands of jobs
Train line Government considers Sydney Metro Sydenham to Bankstown train line
SUBURB TO WATCH: ALEXANDRIA
Adelaide
26
OPPORTUNITIES AND KEY INFRASTRUCTURE
FOLLOWING
Median price (units) $822,295
Source: CoreLogic
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
15.5%
53.9%
96.2%
2.5%
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
9.6%
37.1%
59.1%
4.2%
AUSTRALIAN CAPITAL TERRITORY
Property sales in Canberra reflect a buoyant market SUBURB SPOTLIGHT: ALEXANDRIA
House prices are soaring in this industrial suburb of Sydney Situated just 4km from the Sydney CBD, Alexandria sustains a very strong house market. Prices soared by 15% in the year leading up to October 2017. The median house price has now passed the $1.5m mark, and the growth trend seems to be consistent based on the suburb’s performance over the past decade. Even with rental yields being low, investors can certainly benefit from significant capital growth. While houses are performing better than units, the latter market is also progressing at a good pace, as values went up by 9.6% during this period.
HIGHEST-YIELD SUBURBS IN NEW SOUTH WALES Suburb
Type
Median price
Quarterly growth
12-month growth
Broulee
H
$528,100
2%
19%
Broken Hill
H
$115,000
6%
7%
Malua Bay
H
$485,000
-6%
9%
Long Beach
H
$580,000
12%
20%
Wellington
H
$146,500
3%
2%
Canberra’s popularity is evident from the resale statistics. According to CoreLogic’s Pain and Gain report for the June 2017 quarter, almost all houses and units set for resale sold at a profit (97.8% and 79.3%, respectively). Even the regional market performed strongly in this regard. The report's findings also showed the difference between owner-occupiers and investors in terms of handling resale transactions: Canberra investors were 3.5 times more likely than owner-occupiers to resell properties at a loss. “For owner-occupiers, the results show the benefits of selling in a buoyant market. Because of taxation rules, investors may be more prepared to sell at a loss because they, unlike owner occupiers, can offset those losses against future capital gains,” says Cameron Kusher, CoreLogic research analyst. Area
Type Median value
Quarterly
12-month
growth
growth
Canberra
H
$650,000
-5.1%
7.3%
Canberra
U
$424,250
-3.0%
1.2%
www.brokernews.com.au
27
DATA
QUEENSLAND
H
$426,000
-3.1%
1.8%
Brisbane
U
$409,950
0.1%
-1.9%
QLD Country
U
$378,000
-1.8%
3.8%
VICTORIA
MEDIAN HOUSE AND UNIT PRICES
A stable economy keeps the Melbourne market going strong
$1,000,000
Area
Type Median value
Quarterly
12-month
growth
growth
Melbourne
H
$702,000
-2.5%
11.3%
VIC Country
H
$325,000
-3.8%
4.8%
Melbourne
U
$520,000
1.0%
3,2%
VIC Country
U
$267,500
1.9%
2.7%
28
www.brokernews.com.au
$600,000 $500,000 $400,000 $300,000 $200,000 $100,000 $0
$551,275
$700,000
$758,500
$800,000
$701,000
Melbourne’s population growth is attributed to the state’s ability to generate more jobs than anywhere else in Australia. “With immigration accounting for 55% of Australia’s population growth, 36% of our new migrants are moving to Melbourne, with many of them being at the household formation stages of their lives,” says Michael Yardney, CEO of Metropole Property Strategists. While most of these migrants will start out as tenants, they will eventually move on to buy properties of their own, adding to demand. The implementation of the First Home Owner Grant has also enabled new buyers to come in and snap up apartments, strengthening this market. However, as with Sydney, Melbourne is also beginning to show signs of a slowdown after several strong years, even though it remains the second-best property market in the country.
PERTH Total auctions
62
Sold
14
Not sold
16
Clearance rate
46.7%
Houses
$940,000
$900,000
65.0%
Sydney Melbourne Brisbane Adelaide
Perth
Hobart
Units
Darwin
$430,000
QLD Country
Clearance rate
$690,000
3.3%
42
$345,000
0.8%
Not sold
$520,000
$530,000
78
$328,500
growth
H
Sold
$400,000
growth
Brisbane
163
$393,750
12-month
Total auctions
$516,000
Quarterly
ADELAIDE
$331,750
Type Median value
Across the combined capital cities, auction volumes remained high, with 3,353 homes taken to auction returning a preliminary clearance rate of 63.1% for the week ending 10 December. This was an increase from the week prior when the final clearance rate across the capitals recorded the lowest reading, not only this year but since late 2015/early 2016, at 60.3%. The lower weighted clearance rates of late can be attributed to the continual softening conditions across the two largest markets of Melbourne and Sydney, with clearance rates tracking below 70% across Melbourne for five consecutive weeks now. However, volumes across the city have been consistently higher, with volumes this week reaching their second-highest level this year (1,837), while Sydney’s clearance rates have tracked around the mid- to high-50% range over seven consecutive weeks. Across the smaller markets, Canberra recorded the highest preliminary clearance rate this week, with 66.7% of homes selling, while Brisbane returned the lowest, with only 46.6% of auctions successful.
$450,000
Area
WEEK ENDING 10 DECEMBER 2017
$389,700
“There is a significant oversupply of new highrise, off-the-plan apartments overshadowing the inner-city area and nearby suburbs, with owners now giving significant incentives to attract tenants at a time of rising vacancy rates,” says Michael Yardney, CEO of Metropole Property Strategists. This is the result of the construction boom in Brisbane that produced many apartments in over the past five years, causing prices to drop. In fact, resales of off-the-plan units usually result in a 20–25% loss. With unit supply expected to increase further, the situation in the inner city is not expected to get better. The rise in vacancy rates has been difficult, especially for landlords, who have resorted to offering heavy incentives just to secure tenants, such as free rent for a month if they sign a 12-month lease. Nonetheless, development approvals have already fallen by over 50%, which could help balance demand and supply in the near future.
CAPITAL CITY AUCTION CLEARANCE RATES
$535,000
Brisbane’s property market is still expected to underperform
Canberra
CAPITAL CITY HOME VALUE CHANGES Capital city
Weekly change
Monthly change
Year-to-date change
12-month change
Sydney
-0.2%
-0.7%
3.8%
4.2%
Melbourne
-0.1%
0.4%
9.1%
9.6%
Brisbane
0.1%
0.0%
2.4%
2.5%
Adelaide
0.1%
0.2%
2.8%
3.1%
Perth
0.1%
0.5%
-2.0%
-2.4%
Combined 5 capitals
-0.1%
-0.1%
4.7%
5.0%
*The monthly change is the change over the past 28 days
BRISBANE CANBERRA Total auctions
106
Sold
56
Not sold
28
Clearance rate
Total auctions
183
Sold
61
Not sold
70
Clearance rate
46.6%
66.7%
SYDNEY Total auctions
990
Sold
430
Not sold
302
Clearance rate
58.7%
TASMANIA
MELBOURNE Total auctions
1,837
Total auctions
12
Sold
1,023
Sold
5
Not sold
5
Not sold Clearance rate
494
Clearance rate
67.4%
TASMANIA
Area
What does the future hold for Hobart? While Rob Zubin, principal at My Property Hunter, is confident that Hobart’s near future will be bright due to active infrastructure construction and adequate investment in the area, he’s not so sure about its long-term prospects. “At the moment, we have a very strong cycle, but one thing I can guarantee is that at some point in time we’re going to have a low cycle, and I don’t know when that’s going to be.” Metropole Property Strategists’ CEO Michael Yardney concurs. “The Hobart property market was the best-performing market over the last year, but keep in mind it is a very small market and it doesn’t take much to influence it,” he says. Yardney points out that dwelling values in Hobart rose by less than 30% in the past decade.
50.0%
Type
Median value
Quarterly growth
12-month growth
Hobart
H
$390,000
-0.6%
6.8%
TAS Country
H
$270,000
0.0%
3.8%
Hobart
U
$300,000
-0.3%
1.7%
TAS Country
U
$229,500
-7.8%
5.8%
All data sourced from CoreLogic.com.au
www.brokernews.com.au
29
PEOPLE
IN THE HOT SEAT Mortgage broker Rebecca Morgan, of Sattout Accounting Services, on working with and prioritising family, and starting a new chapter in 2018 What makes mortgage broking an interesting career? I have always been driven by helping people. Whether it was A in my previous career in HR or with my community work, I get great satisfaction from it. I see my role as an enabler and an educator – helping people navigate through the system to find a solution that helps them meet their goals. They may be buying their first home in a tough market, building a property portfolio to secure their financial future, purchasing premises to grow their business, or building their dream property. Whatever their goal, I find it very rewarding to get their finance in place and introduce them to other like-minded professionals.
Q
What are some of the benefits and/or challenges of working in a family business? We run Sattout Accounting Services in a very collaborative A way, and keeping everyone happy all of the time can be a challenge. We see each other every day, but there is very little time for socialising, so we have to be mindful of enjoying our time together outside of work. I am probably the worst at avoiding work talk at family functions. We each have our specialty areas and this helps make the workplace harmonious.
Q
Do you have any advice on how best to manage work-life commitments? I keep family at the forefront of all my decisions, A and mortgage broking is a great career that allows this. I schedule my work week around what is important at home, and try to make sure I am present as a parent, wife, sibling and daughter. There are times when my workload can feel overwhelming, and I am getting better at looking after myself, ‘eating the frog’, and focusing on the most important tasks first. There can be many distractions in our roles, so I try hard to delegate where I can without compromising the customer experience.
Q
What are you looking forward to in the new year? Sattout Accounting Services is relocating to A new premises in 2018. I am looking forward to having a fresh, new work environment and the capacity to expand the team. I see 2018 as an exciting one for mortgage brokers who focus on solving problems for their clients and finding solutions to help them grow. AB
Q
30
www.brokernews.com.au
Wednesday 6th June • Westin Hotel Sydney
MAKE 2018 YOUR BEST YEAR YET • Generate more leads
• Learn from the experts
• Write more loans
• Network with other brokers
• Build your business
• Gain CPD hours
GET YOUR TICKETS TODAY Event partner
Breakfast sponsor
Gold sponsor
Exhibitors
Refreshment Sponsors
Supporting publications
www.brokerbusinessexchange.com.au
Organised by
www.brokernews.com.au
31
32
www.brokernews.com.au