DECEMBER 2017 ISSUE 14.24
Steady demand for SMSF loans Making them part of your business offering /16
Preparing for a rate rise Is the current serviceability buffer enough? /18
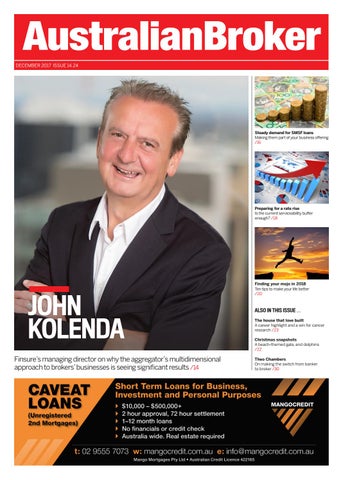
JOHN KOLENDA Finsure’s managing director on why the aggregator’s multidimensional approach to brokers’ businesses is seeing significant results /14
Finding your mojo in 2018 Ten tips to make your life better /20
ALSO IN THIS ISSUE … The house that love built A career highlight and a win for cancer research /23 Christmas snapshots A beach-themed gala, and dolphins /22 Theo Chambers On making the switch from banker to broker /30
NEWS
IN THIS SECTION
Lenders Royal commission remit “fair” and “reasonable” /04
Aggregators Brokers “have courage to confront change” /06
Technology Custom video platform to engage broker clients /10
Regulators Government floats higher ACL fees /12
Consumers Aussies split over house prices /08
www.brokernews.com.au DECEMBER 2O17 EDITORIAL Editor Otiena Ellwand News Editor Miklos Bolza Journalist Nicola Middlemiss
2017 IN REVIEW
A snapshot of the major market shakeups this year
Production Editor Roslyn Meredith
ART & PRODUCTION Designer Martin Cosme
16 MARCH
31 MARCH
19 APRIL
ASIC’s remuneration review
APRA’s lending caps
Sedgwick report
ASIC releases its Review of Mortgage Broker Remuneration, thrusting brokers into the spotlight and prompting the industry to come together to respond
The regulator introduces speed bumps to quell the flow of new interest-only lending and manage lending to investors
The ABA-backed review looks at adjusting how bank staff and third parties receive payment for selling bank products. The banks are quick to announce that they’ll implement the recommendations
Production Manager Alicia Chin Traffic Coordinator Freya Demegilio
SALES & MARKETING Sales Manager Simon Kerslake Account Manager Rajan Khatak Marketing and Communications Manager Lisa Narroway
CORPORATE Chief Executive Officer Mike Shipley Chief Operating Officer George Walmsley Managing Director Justin Kennedy Publisher Simon Kerslake Chief Information Officer Colin Chan Human Resources Manager Julia Bookallil
EDITORIAL ENQUIRIES
Otiena Ellwand +61 2 8437 4792 Otiena.Ellwand@keymedia.com.au
SUBSCRIPTION ENQUIRIES
tel: +61 2 8O11 4992 fax: +61 2 9439 4599 subscriptions@keymedia.com.au
9 JUNE
27 JUNE
25 AUGUST
Combined Industry Forum
Three-way deal
CBA buys Aussie
Mortgage industry associations come together to hash out how to respond to ASIC’s report on mortgage broker remuneration and work towards self-regulation
REA Group acquires a majority stake in broking franchise business Smartline. At the same time, NAB’s Choice Home Loans brokers are offered an opportunity to rebrand as realestate.com.au Home Loans brokers
CBA and Aussie Home Loans finalise the sale of the remaining 20% share, giving CBA complete ownership of the franchise
ADVERTISING ENQUIRIES
Simon Kerslake +61 2 8437 4786 simon.kerslake@keymedia.com.au Rajan Khatak +61 2 8437 4772 rajan.khatak@keymedia.com.au Key Media Pty Ltd Regional head office, Level 1O, 1–9 Chandos St, St Leonards, NSW 2065, Australia tel: +61 2 8437 4700 fax: +61 2 9439 4599 www.keymedia.com Offices in Sydney, Auckland, Denver, London, Toronto, Manila, Singapore, Bengaluru
11 SEPTEMBER
15 NOVEMBER
5 DECEMBER
Liar loans
Pepper Money
Last cash rate call
UBS’s “$500bn in ‘Liar Loans’?” report finds a third of all mortgage applications across direct and third party channels to be inaccurate, with misrepresented loans more common among brokers
Shareholders approve a takeover bid of Pepper Money by Red Hot Australia Bidco, an entity owned by global investment firm KKR Credit Advisors
The RBA decides to keep the official cash rate on hold at 1.5%, making this the 16th consecutive month of rates on hold since they were cut by 25bps in August 2016
2
www.brokernews.com.au
This magazine is printed on paper produced from 1OO% sustainable forestry, grown and managed specifically for the paper pulp industry Copyright is reserved throughout. No part of this publication can be reproduced in whole or part without the express permission of the editor. Contributions are invited, but copies of work should be kept, as Australian Broker magazine can accept no responsibility for loss. Australian Broker is the most-often read industry publication, according to independent research carried out by the Ehrenberg-Bass Institute for Marketing Science at the University of South Australia in December 2008. The research also found that brokers rate Australian Broker as the best for both news content and feature articles, followed by sister publication MPA. Overall, on all categories, Australian Broker ranks top followed by MPA. The results were based on a sample of 405 respondents who were the subject of telephone interviews.
NEWS
LENDERS BROKERS SPLIT OVER ROYAL COMMISSION recent survey is offering insight into how brokers feel about the banking royal commission, and it seems opinions are most definitely split. The poll, conducted by MyState Bank, found that 14% of brokers think the inquiry is ‘definitely needed’ while a further 24% feel it’s needed ‘on balance’. However, almost a fifth (17%) are firmly against the inquiry, while 24% feel there are ‘more important issues to address’ within the Australian economy. A
NAB REACHES 22% OF COMMERCIAL BROKERS is celebrating the success of its Commercial Broker platform after the latest data revealed the channel now represents around a quarter of the bank’s new business lending. Established just five years ago, NAB Commercial Broker also accounts for around 22% of Australia’s broader commercial market. The impressive upwards trajectory includes year-on-year settlement growth of over 40%, with the number of broker loans written increasing by 27% annually.
BROKERS WEIGH IN ON THE PROPERTY MARKET Source: MyState Bank Survey
5% believe many potential buyers are taking a breather, waiting to see which way the market moves
35% say house prices have become too high for first home buyers
12% believe the reduction in foreign buyers is a contributing factor in
34%
market movements
say price drops in Sydney and Melbourne are the result of supply exceeding demand
14% believe falling prices are a result of the market peaking
NAB
“Our small business team has received terrific feedback from many brokers who are now assisting a client with their business needs, where in the past the client only sought their help for a home loan” Chris Thomas General manager, NAB Commercial Broker
4
www.brokernews.com.au
ROYAL COMMISSION REMIT ‘FAIR’ AND ‘REASONABLE’ The draft terms of reference outline misconduct, practices and behaviour as key areas of focus the announcement of a royal commission into the banking sector, Prime Minister Malcolm Turnbull released an associated draft terms of reference which outlines the scope of the inquiry – and it seems misconduct is set to be the primary focus. The commission is charged with investigating the nature and extent of misconduct by financial services entities; conduct, behaviour and practices that fall below community standards; and misuse of superannuation members’ retirement savings. The commission will also need to determine whether misconduct is due to “particular culture or governance practices” within a FOLLOWING
business, or if it’s a result of other factors such as risk management, recruitment or remuneration. The terms of reference also charge the commission with examining the effectiveness of current mechanisms in assisting consumers in the case of financial misconduct; as well as current legislation, internal systems and industry self-regulation in identifying and addressing misconduct within the industry. Potential changes to legal frameworks, financial services practices and regulators to further minimise misconduct will also be considered. Patrick McConnell, honorary fellow at Macquarie University’s Applied Finance Centre, told
Australian Broker that the conditions laid out in the draft were both fair and comprehensive. “There’s enough in the terms of reference to delve into the two major issues: the various misconduct scandals that we’ve seen, and also the regulation of that misconduct,” he said. With regard to potential changes to regulation itself, McConnell said this pertained solely to “containing systemic risk” – a narrow definition that eliminates amendments at the macroprudential level. This was necessary and reasonable so as to avoid overextending the inquiry, he added. “Most of the scandals we’re looking at – none of them affect the prudential status of the banks. They only affect the conduct,” he said. He noted that the effectiveness of the commission would depend on two factors: the commissioner chosen, and the way the government opted to run the inquiry. A total of $75m will be allocated to the commission.
NEWS
A G G R E G AT O R S AGGREGATOR BRINGS ON 249 BROKERS has seen a solid year of growth across the board, including expanding its broker network by 249 countrywide. Speaking at a PD day late last month, one of the firm’s regional heads said total settlements in residential, commercial and asset finance had hit $16.7bn when there was still three months left in the year. The figures put FAST in good stead to beat the $20.3bn brought in for the whole of 2016, said Rob Ryan, head of NSW/ACT and Queensland. FAST
MERGER WITH REGIONAL BANK ON THE CARDS has signed an agreement for a proposed merger with WA bank Goldfields Money in a move that will come as a blow to Firstmac, which made its own unsuccessful acquisition bid in October. If the merger goes ahead, Goldfields shares will be valued at $1.50 – a significant increase from the $1.27 to $1.39 ballpark offered by Firstmac. Goldfields directors have called the Finsure offer “transformational” for the bank and say it will provide “substantial value” to its shareholders. FINSURE
BROKER CHAMPIONS ‘HAVE COURAGE TO CONFRONT CHANGE’ Australia’s highest-level brokers have several key qualities in common, says the head of a leading national aggregator at the top of their game
BROKERS exhibit several key
qualities, including an eagerness to embrace change, attention to customer needs, and the ability to build relationships. These traits were highlighted at Connective’s latest national conference, where the aggregator’s broker champions spoke about operating a successful brokerage in a highly competitive market. “[The best brokers] have the courage to confront change and [make] change [an] opportunity,” said Connective director Mark Haron. “They’re used to being adaptive and making the most of those opportunities.” Haron pointed to Jeremy Fisher – founder and director of 1st Street
6
www.brokernews.com.au
Home Loans – as a perfect example of a broker adapting to change and reaping the rewards as a result. “He’s really embraced the compliance and regulatory requirements that are coming into the market,” Haron said. “ANZ used him and his business as a ‘test and learn’ environment to see how further oversight and documentation of customer outcomes from a loan process are being implemented,” he added. The top brokers also displayed high attention to detail with respect to both customers and employees, putting them at the centre of everything they did. “They genuinely care about their staff as well. They support and they work very closely with
their staff and develop their staff,” he told the audience. “In each of those businesses – the Connective Champions – they don’t go looking for staff; people come and find them and want to work with them because that attitude and that caring is very obvious.” While speaking about how 1st Street had achieved such success, Fisher said respecting bank staff and building relationships with BDMs and credit assessors was highly important. “If there’s no respect from our side to theirs, they’re not going to look after you,” he warned, noting that the quality of applications was crucial to building respect. Fisher also stressed the importance of discussing more than the interest rate with clients, in order to ensure the longevity of the relationship. “I don’t want to talk about rate,” he said. “If a client’s coming to you and chasing rate the very first time they speak to you, they’re going to be out the door six months later when they get a better rate.”
“If a client’s coming to you and chasing rate the very first time when they speak to you, they’re going to be out the door six months later when they get a better rate” Jeremy Fisher Director, 1st Street Home Loans
NEWS
CONSUMERS WA MOVES TO ALL-DIGITAL REFINANCING has joined the digital loan revolution, becoming the third state to adopt paperless processing for all loan refinances. The milestone was reached on 1 December, which was the state’s deadline to switch to the new Property Exchange Australia (PEXA) platform. Mike Cameron, PEXA’s group executive of customer and revenue, said conducting refinances online often halved the total transaction time. “What once took an average of 40 days is now down to about 20 days, thanks to the new digital way.” WA
AUSSIES SPLIT OVER HOUSE PRICES survey by ME has found that 37% of Australians want house prices to fall, but almost the same proportion – 38% – would prefer them to rise. Traditionally, property owners want prices to rise, while non-owners want them to fall, but views are changing. “That property owners were willing to see asset values fall is a sure sign house prices had reached heights many think are unfair,” said home loan expert Patrick Nolan. Only 28% of Australians would benefit if property prices rose, while 47% would benefit if they fell, ME found. A
“The number one reason to settle properties online is to remove the consumer frustration and pain points that often occur when home sales are finalised using outdated pen-and-paper conveyancing methods” Mike Cameron Group executive of customer and revenue, PEXA
STUDY CLAIMS AUSTRALIA HAS OVERSUPPLY OF HOUSING The paper flies in the face of both industry and government findings, which claim the complete opposite much attention has been directed towards the housing shortage in some of Australia’s largest and fastestgrowing cities, a new study by the Australian National University (ANU) says the country actually has a significant oversupply of housing. The Regional Housing Supply and Demand in Australia working paper, prepared by associate professor Ben Phillips and researcher Cukkoo Joseph of the ANU Centre for Social Research and Methods, analysed 15 years’ worth of census data and building approvals to draw its conclusions. “Between the years 2001 and 2017, we estimate the Australian housing market experienced an oversupply of 164,000 dwellings,” the report said. “However, there are significant THOUGH
regional differences with some regions experiencing significant undersupply while others have significant housing surpluses.” According to the researchers, the majority of Australia’s housing surplus is in the inner-city areas of the major capitals, with inner Brisbane, Melbourne and Sydney all being oversupplied due to recent growth in unit developments. Many regional markets, especially those in mining-sensitive areas such as North Queensland and Western Australia, also have housing surpluses. In contrast, regions in the middle and outer rings of the major capitals, particularly Sydney, face modest housing shortages. On a state level, the most oversupplied areas are the two
territories: the NT and the ACT. Queensland has a significant oversupply, NSW has a relatively minor oversupply, and Tasmania has a mild housing shortage. “The surplus [of 164,000 dwellings] is not particularly substantial, but certainly suggest that housing supply in and of itself is probably not the primary driver of house-price growth in Australia. There are other factors that are going on,” Phillips said. “We’ve looked at factors like changes in household types and dwelling types and unoccupied dwellings which we don’t think have been taken into account in other studies in any substantial way in the past, and certainly not at the regional level. “The standard line of governments and industry seems to be that housing supply is a big problem in Australia. No doubt there are some areas where it is. But overall we don’t see the housing shortage that’s often talked about – in fact we see that there is a surplus.”
VV$40,614,829,064 AUSTRALIANS REVEAL THEIR RELIANCE ON HOUSING PRICES Source: ME Bank Survey, November 2017
1,500 Australian adults surveyed
8
43%
10%
38%
37%
28%
47%
are reliant on future house prices to achieve future life/financial goals
are completely reliant
want property prices to increase
want prices to fall
say they will benefit if prices rise
say they will benefit if prices fall
www.brokernews.com.au
NEWS
TECHNOLOGY
FINTECH SECURES $120M IN FUNDING lending fintech MoneyMe has announced it has secured $120m to use for future growth and expansion. The asset-backed wholesale securitisation facility includes $100m from global investment manager Fortress Investment Group, as well as $20m in bonds issued by corporate advisory firm Evans & Partners. MoneyMe will use these added funds to grow its market share, branch into new lending products, and expand into additional delivery channels over the next three to five years. CONSUMER
CUSTOM VIDEO PLATFORM TO ENGAGE BROKER CLIENTS The platform also aims to reduce errors in the loan application process and shorten time to settlement
law firm MSA National is rolling out a new customised video product to help brokers and lenders connect more efficiently with new and existing borrowers. According to founder and managing director Sam Makhoul, the MyVideo platform is designed to deliver personalised messages to clients so information is more easily digestible and resonates for longer. Through the firm’s market-first technology, videos will be created instantly using customised data and audio extracts. Makhoul believes the platform will improve delivery of information to the borrower while boosting total engagement levels. “In our experience, engagement
with text is under 20%, which means that a lot of very important information is just not getting through to the borrower,” Makhoul told Australian Broker. “With video, engagement is over 80%.” At present, both MyState and Advantedge have partnered with MSA to deliver MyVideo to their clients. This is expected to go live this month. “We have showcased MyVideo with a few other clients, who have all seen the potential this service has to deliver material improvement to their customer experience. We expect to have a number of clients live in 2018.” The fact that a lot of home loan information is transferred by text means that many customers do not complete or sign home loan
AUSTRALIAN
documents correctly. This then leads to errors and delays, he said. Sending the same data by video means clients retain information to a higher degree and are more inclined to return documents in the proper manner. For the broker and customer, fewer errors mean loans can be settled more quickly and with less hassle, Makhoul said. “That means the borrower gets his money sooner, the broker gets his commission sooner. The broker also has a happy lifelong customer who is more willing to refer friends to the broker.” MSA hopes to improve the efficiency of information delivery to reduce errors, provide the borrower with a smoother experience, and eliminate pain points. “A home loan is likely the largest and most complex transaction that most borrowers will ever enter into. It is therefore important that we try to improve the delivery of information to ensure the complexity of this transaction feels invisible to the borrower.”
FINTECH BARRIERS DIFFER ACROSS AGE GROUPS
Was not aware they existed
23% 19% 24%
Did not have a need to use them
5%
12%
17% 13% 15% 9%
13% 10% 10% 5% 4%
8%
10% 5% 3% 2%
4% 2%
5%
8%
10%
12%
16%
25%
18% 17% 22% 14%
30%
15%
0%
18–24
25–34
35–44
45–54
55–64
65–74
75 and above
Preferred to use a traditional financial services provider Did not see the advantage of fintechs over traditional services
Age Note: The question was put only to respondents who had used no fintech services in the last six months. However, the analysis is re-indexed to show as a percentage of all survey respondents.
10
www.brokernews.com.au
firm Carrott has expanded its microsavings app into the home loan space to help consumers use small payments to pay off their mortgages faster. Originally built around superannuation and assisting people in saving for retirement, the company decided to expand out into home loans and HELP debt at the beginning of November. “Carrott’s a micro-savings platform. What we do is round up your everyday transactions from your debit card or credit card to the next dollar,” CEO Christian Raftery explained. FINTECH
Source: EY FinTech Adoption Index 2017
20%
FINTECH TO HELP MORTGAGEES $5 AT A TIME
FINTECH ADOPTION RATES ACROSS THE WORLD Source: EY FinTech Adoption Index 2017
69% 52%
na
23%
UK
BE &X LU
Ca
n pa
Ja
18%
40%
India
13% 14%
China
42%
il
az Br
da
re
26%
Ireland
Neth
37%
Spain nds
Mex
erla
27%
37%
a trali Aus
Sing apo
ico
e nc
Ge
a Fr
Hong Kong
Kor ea
d Sou th
rla n tze Sw i
35%
ca
32%
an y
ri Af
32%
h ut So
30%
USA
27%
36%
rm
35% 33% Average adoption
33%
Note: The figures show fintech users as a percentage of the digitally active population.
UNIQUE BROKER LICENSING MODEL LAUNCHED Risk Services, a compliance consultancy for credit licensees, has launched a one-of-a-kind third party credit licence model that offers greater flexibility for brokers. Pursuit Broker Services lets brokers utilise any aggregator they choose while working as an authorised credit representative under Pursuit’s licence. Brokers will also be offered compliance support, with the entire package coming at a flat fee. QED director Greg Ashe said the goal was to help brokers with compliance while allowing them to run their businesses as they see fit. QED
NEWS
R E G U L AT O R S
NO ADDITIONAL RISK FROM BROKERS – S&P on the major banks’ use of brokers, leading analysts at S&P Global Ratings have said that trends in the third party channel do not indicate any additional risks for the industry. “We do not see any significant difference in the outcomes [between broker and proprietary] but that data itself is constrained because [it] does not come through any period of significant stress,” said Sharad Jain of S&P. While there may seem to be additional risks through brokers, current data does not back this up, he said. COMMENTING
GOVERNMENT FLOATS HIGHER ACL FEES A consultation paper has been released detailing new licence application fees under the proposed ASIC industry funding model government has added more changes to its proposed industry funding model for ASIC, including higher fees for Australian credit licence (ACL) holders. The consultation paper released on 22 November details a new fee-for-service model that would retrieve funds from those creating the need for added regulation. This would include individuals and firms applying for or modifying an ACL. Minister for Revenue and Financial Services Kelly O’Dwyer said this was a key recommendation of the Murray Financial System Inquiry and would ensure that ASIC had the funds and resources it needed. THE
CIO SEES RESI LENDERS REFUND $135K conducted by the Credit and Investments Ombudsman during the last quarter have resulted in compensation payments of more than $135,000 having to be made by two residential lenders. One lender was obligated to refund and/or waive over $107,000 charged to 584 loans after failing to deduct the reduced input tax credit from enforcement costs. A second lender refunded almost $29,000 out of a total of $50,000 to 53 out of 92 consumers after overcharging in relation to break costs. INVESTIGATIONS
12
www.brokernews.com.au
“The industry funding model is an important component of the government’s plan to improve consumer outcomes in the financial services sector,” O’Dwyer said. Proposed changes to fees for those wishing to apply for an ACL are as follows: individuals other than credit providers ($1,798); individual credit providers ($3,468); other body corporates other than credit providers ($2,065); other body corporate credit providers ($4,624). Previously, fees for ACL applications were as low as $523 for electronic application processes, with charges calculated according to the type of organisation and certain financial figures, including volumes of credit advanced and
value of property rented to consumers in the year prior. For those seeking to vary authorisations or conditions on their current ACL, the government has proposed the following fee structures: individuals other than credit providers ($1,156); individual credit providers ($2,183); other body corporates other than credit providers ($1,284); other body corporate credit providers ($2,826). It currently costs $115 to change details of an ACL electronically, and $140 by paper. ASIC has welcomed these changes, saying that 10% of its regulatory activities will be covered through these fees-for-service. The remaining 90% will be recovered through industry-funding arrangements. “The current fees for these activities do not reflect their actual cost, and the government is seeking input from industry on changes to address this,” said ASIC commissioner John Price.
VALUE OF NEW HOME LOANS SETTLED BY BROKERS Source: MFAA Industry Intelligence Service
For the period October 2016–March 2017
$218,437,115 $4,878,133,806
$38,686,312,653
$27,337,632,486
$13,622,377,723
$9,309,389,733 $557,719,838 NSW/ACT
VIC
QLD
WA
SA
TAS
NT
FE AT URES
SPECIAL REPORT
AN AGGREGATOR AT THE COALFACE Managing director John Kolenda tells Australian Broker how Finsure’s multidimensional approach to brokers’ businesses and its relationship-driven support has seen the aggregator’s recruitment numbers soar
the managing director of Finsure, an aggregator with 1,300 brokers, 35 staff and a $27bn loan book, there’s no doubt John Kolenda is a busy man, but he still makes time to meet and mentor brokers individually. “I love helping out brokers,” he says, boasting like a proud parent about some of the standout businesses and marketing strategies Finsure’s brokers have developed with the aggregator’s assistance. He names brokers who have refined their brand identity, who are giving back to their communities and have grown their businesses from single operators to teams of 20. “I met yesterday with two brokers, and I spent over five hours of my time going through their individual business plans. Now I do that as the managing director. I’ll still take their call on the weekend if they have an issue; that’s what I expect every one of my employees to do,” he says. “Everyone within the company is accessible. You can ring anyone. You go to the person who you believe can help you with the solution.” Finsure has only been around for six years, but its comprehensive business-to-business value proposition was inspired by Kolenda’s experience as a broker himself for a couple years. “It was constructed from the point of view of a broker and what their needs and wants are as an individual, whether a small business or a large-scale business,” he explains. Finsure offers a range of in-house services to meet brokers’ diverse business needs and assist them in growing their volumes. Those services include a simple, intuitive AS
14
www.brokernews.com.au
proprietary CRM to help brokers save time, effort and money to prioritise the customer journey; lead generation in their local areas; outbound call centre services; a range of website templates for brokers to design their own branded websites, which Finsure will host; legal and taxation services; recruitment services to find ideal candidates for brokers’ businesses; multivertical sales options to facilitate additional revenue opportunities; training and mentoring services, including a 24-month broker academy to train new entrants; annual business planning and sales coaching. The aggregator’s multipronged strategy has been commended by the industry. In October it was crowned Aggregator of the Year (over 500 brokers) at the Australian Mortgage Awards, and in November it was recognised as one of Australia’s fastest-growing companies with
its second consecutive listing in the Australian Financial Review’s Fast 100 list. Finsure’s focus next year is to continue building on its strong service offerings and support programs, helping brokers to become the sole point of contact for their clients. A partnership with Freedom Insurance will provide brokers with access to mortgage protection and other insurance products to offer their clients; and integrating utility services into the settlement process will help clients avoid unnecessary headaches, Kolenda says. In return, the broker will be paid a referral fee. “Through experience we found that if the process is simple and easy and makes sense, you’re more likely to get buy-in from the customer and the broker,” he says. To complement Finsure’s asset and commercial finance training program that helps brokers learn how to write
these loans themselves, the aggregator will also be launching an asset referral solution with fair commission splits for those who would rather not expand into those areas. Finally, Finsure will also be beefing up its compliance team to keep brokers informed and up to date with ongoing regulatory and policy changes in the market, and to help them build their own processes and structures to stay compliant. With all the changes in technology and the regulatory landscape, brokers need an aggregator that can provide a supportive foundation and keep them up to speed so there’s no disruption in their workflow. “Broker market share will go up,” Kolenda says. “Broker access to the broader solutions will help more customers than a traditional one-lender, one-dimensional relationship.” Why brokers are choosing Finsure When Nathaniel Nhan Truong was considering starting his own broking business, he turned to Kolenda for advice. “From the start, I was reluctant and unsure whether to move from a banking role to broking. But meeting with John on numerous occasions, he encouraged me and told me that he
KEY COMPANY FIGURES
1,300
brokers in the network
6
years in business
$27BN
total loan book
35
staff employed Nathaniel Nhan Truong, director of The Loan Lounge
In partnership with
John Kolenda (right), managing director of Finsure, at the aggregator’s office in Sydney
would support our business if I came on board, so I decided to make the move,” he says. “I trusted John’s experience as he has walked the path before, and that experience has helped our business make the right decisions at each stage of the business cycle.” Truong established The Loan Lounge in 2015 and has had incredible success, settling more than $33m last year. He was named one of MPA magazine’s Young Guns of 2017 and was a finalist at this October’s Australian Mortgage Awards for the Young Gun of the Year – Independent award. He has since added a second broker and a back-office staff member to his team. “At each stage of the business, whenever I was stuck and had questions I would sit down with the Finsure team or John and he would guide me on what to do next – this helped us to focus on the right things and take our business to the next level,” Truong says.
Truong has carved out a niche for his business, making lending and borrowing about social good rather than just profit. His motto at The Loan Lounge is “Finance a difference”, which he does by donating 10% of the firm’s trail to organisations that work
The aggregator is looking for brokers like Truong, who feel the same way about their clients. It’s these positive experiences with Finsure – and the results its brokers are achieving – that are helping to get the word out about the aggregator
“Everyone within the company is accessible. You can ring anyone. You go to the person who you believe can help you with the solution” John Kolenda, Finsure to abolish slavery and end human trafficking. “To see stories of victims set free gives our business purpose and meaning,” he says. What the future holds for Finsure Finsure’s purpose and culture is about making a positive difference in the lives of its brokers, Kolenda says.
and pique other brokers’ interest, Kolenda says. “From the top down, every one of our employees will help any broker with any problem … we would expect the broker to do exactly the same by their client. “They’ve got to do the right thing; they’ve got to be reputable, they’ve
got to be honest, they’ve got to be transparent, and if they’re not the same way we are, it’s never going to work. And that’s paramount. You just don’t need brokers for brokers’ sake,” Kolenda says. For brokers looking to switch from another aggregator, Finsure’s process is simple. For residential brokers, it involves filling out about 20 pages of a 130-page PDF document. The document then prepopulates every lender accreditation form for them. Sign, send and Finsure completes the rest. With strong recruitment numbers to close the year, Kolenda wagers that the aggregator will surpass its target of 1,500 brokers by end-June 2018. “We engage in dialogue with a lot of brokers, and we look at tailoring business-to-business solutions that will actually help them and give them solutions that make us a very compelling partner of choice.” The future is busy and bright for both Finsure and Kolenda. AB www.brokernews.com.au
15
FE AT URES
MARKET REPORT
SMSF LENDING: BACK TO BASICS La Trobe Financial’s Cory Bannister and Thinktank’s Peter Vala give brokers a refresher on what they need to know to write SMSF loans, and explain why this growing sector is worth exploring in 2018
Why should brokers consider adding SMSF loans to their business proposition? Cory Bannister: Brokers A should consider offering SMSF loan products as part of their overall diversification strategy as it is such a significant growth area that is likely to include a number of their current and future clients. Unless brokers cater for their clients’ full finance needs, there is an increasing risk that they will leave you for someone who can, as often consumers are looking for a one-stop shop.
Q
Peter Vala: From our experience at present, one in five commercial loans we see are in an SMSF structure of some form, so by not becoming involved you can miss out on up to 20% of deals in the market. SMSF transactions have a long duration, meaning your customer will remain with you for a longer period of time, allowing you to assist with other financial services products that best suit their needs. What should brokers be aware of when dealing with SMSF loans, and what are some of the misconceptions around them? PV: We think that the degree of A difficulty faced by a broker in delivering an SMSF loan to a client is overstated and is in part confused with the advice that should be provided by other qualified/licensed advisers. Remember, you can’t give advice on the SMSF; you are just delivering the loan.
Q
16
www.brokernews.com.au
CB: Any broker willing to undertake training and education for SMSF lending is capable of dealing in this space, and while there is a technical element, it is not overly difficult once you are across the specific product particulars and the requirements under the SIS [Superannuation Industry (Supervision)] Act. That said, SMSF lending is a niche area and should only be carried out by brokers looking to deal regularly in this space. How big is the SMSF market currently, and is it growing? CB: SMSFs continue to have a A significant influence in the overall growth of the $2.3trn Australian superannuation industry, with SMSF assets growing by $219bn, or 55%, in the five years to 2016. Looking at growth in the number of SMSFs, this too has been on an upward trajectory, growing on average 6% year-on-year from 440,000 SMSFs in 2011 to 577,000 in 2016.
Q
PV: The ATO periodically reports statistics, and for June 2017 total SMSFs in existence were reported as 596,516, with 1,124,453 members. The value of borrowings by limited recourse borrowing arrangements [LRBAs] has more than tripled since June 2013, which is put down to choice. That choice is much greater in SMSFs than other forms of superannuation savings.
Q A
What sort of client would an SMSF loan suit best? PV: Whether an SMSF is best suited to a client should be
discussed with their financial planner. However, we find the majority of our borrowers who are self-employed are seeking to acquire a freehold asset to house their trading business. They end up paying rent to themselves, and when they retire, that income and any capital gain is potentially tax free.
documents that they have been using for our other loan products. Having an experienced team on the road, combined with accessible credit staff in the office, means that we can assist brokers using a consultative approach from submission through to approval. Having direct access to the decisionmakers results in a much smoother end-to-end process. Essentially, if you can write a standard residential or commercial loan product with us, you will be able to write SMSF loans, as the process and documents are the same, including online lodgement capability. PV: With the assistance of our aggregator partners, we hold regular training sessions that specifically cover lending to SMSFs for commercial property purchases. Thinktank also provides every broker with a dedicated relationship manager that can workshop and assist with any submission that comes to hand. In addition, our website contains a comprehensive schedule of supporting documentation
“One in five commercial loans we see are in an SMSF structure of some form, so by not becoming involved you can miss out on up to 20% of deals in the market” Peter Vala, Thinktank CB: We would recommend that the clients have an SMSF in place already, unless they are coming to you with advice from an adviser and are in the process of establishing an SMSF. It is not recommended to encourage clients to establish an SMSF unless they receive independent advice from an appropriate adviser first. How are your companies making it easy for brokers to write SMSF loans? CB: We have purposely A engineered this product, like all of our products, to be userfriendly for all brokers, removing many of the barriers to entry that can often be attached to specialist products. Brokers do not need separate accreditation and can use our standard forms and
Q
which provides valuable guidance in covering off the vast majority of requirements involved in SMSF LRBA transactions, including clearly describing what requirements there are of each of the parties associated with the loan. The website also offers a rich source of educational material that is there to help enhance the understanding of SMSF terms and processes to the benefit of brokers and their clients. Most importantly, though, an experienced relationship manager is always on hand to help out whenever needed. What changes do you foresee occurring in this space, and what does the future hold for SMSF loans? PV: We have been A experiencing an increasing volume of LRBA applications over
Q
Peter Vala, head of sales and distribution, Thinktank
the past year and a trend towards larger amounts, both of which look set to continue. The percentage of owner-occupied security properties is also increasing. In some cases this also includes a greater degree of complexity, so for many of our brokers this means developing a greater degree of expertise in this segment of the market. Our view on this issue rather mirrors our own experience. Like many things that you start, they develop as you gain experience. With SMSF LRBAs, this includes structuring transactions to accommodate partners wanting to acquire their business premises, dealing with aspects of SMSF regulations such as ‘in specie’ contributions, and inevitably resolving split-ups in
these business partnerships or relationship break-ups such as divorces. All of these are real added-value activities and can differentiate you in terms of the service you provide.
Cory Bannister, vice president and chief lending officer, La Trobe Financial
release of the David Murray-led Financial System Inquiry report back in December 2014, where a total ban on all borrowing within superannuation was recommended. The Turnbull Government rejected
“Any broker willing to undertake training and education for SMSF lending is capable of dealing in this space” Cory Bannister, La Trobe Financial CB: There has been much conjecture about the future of SMSF loans since the Labor Party’s proposal to ban LRBAs by SMSFs to purchase property. This position received subsequent backing following the
this recommendation; however, they have since taken steps to limit the amount of debt SMSFs take on to invest in property by including the leverage in their superannuation balance and transfer caps, which
took effect from 1 July 2017. There are no current foreseeable headwinds in the SMSF lending space from a legislative perspective, other than a potential change of government. With a federal election unlikely until late 2018, the next 12 months are unlikely to produce much change. For brokers, the last 12 months have seen a number of lenders leave and re-enter the SMSF lending market, largely as a result of macroprudential regulation that has required the banks to curb their investment lending, of which SMSF forms a part. We expect this toe-in, toe-out environment to continue for many, and therefore would encourage brokers to partner with lenders providing a stable SMSF offering to provide a better experience for their clients. AB www.brokernews.com.au
17
FE AT URES
NE WS ANALYSIS
PREPARING BORROWERS FOR THE UNKNOWN Talk of the cash rate rising has some people worried. Will the current standard serviceability buffer be enough to protect borrowers, or is a domino effect of defaults on the horizon? Nicola Middlemiss reports
regulator APRA tightened lending criteria earlier this year and increased its scrutiny of banks’ lending practices – but with the cash rate likely to rise in the not-so-far-off future, some industry figures are now wondering if the restrictions fall short of what is actually needed to prevent borrowers from defaulting on their home loans. In March, when the new lending caps were introduced, APRA reiterated the importance of the interest rate buffer, which it had earlier recommended be set at at least two percentage points. The regulator said “a prudent ADI would use a buffer comfortably above this”, but it set no further limits. Harald Scheule, associate professor of finance at Sydney’s University of Technology, is among those questioning the efficacy of APRA’s buffer. “I do not think that a 2% buffer is sufficient, as interest rate changes are likely to be greater in the medium term,” Scheule tells Australian Broker. “APRA has acknowledged this by making clear that 2% is only the bare minimum.” Scheule is an expert in risk management and has undertaken consulting work for a wide range of financial institutions in Asia, Australia, Europe and North America. He says if the cash rate rises, as suggested by the RBA, it’s inevitable that some mortgage holders will be unable to meet their repayments. “Rising interest rates will impact borrowers with limited free cash flow. This may include leveraged interestINDUSTRY
18
www.brokernews.com.au
only borrowers and borrowers that have recently purchased a property,” he warns. “Mortgage delinquency rates will increase.” A recent survey by home loan
the RBA were to raise the official cash rate by 1% from its current record low of 1.5%, it would have an “adverse impact”, with 43% indicating they would spend less, and 27% of
“Rising interest rates will impact borrowers with limited free cash flow … [including] leveraged interest-only borrowers and borrowers who recently purchased a property” Harald Scheule, UTS lender ME asked 2,000 mortgage holders about potential interest rate rises and found the issue was causing major concern among homeowners. More than half (56%) said that if
investors saying they would sell their investment property. “The prospect of rate rises is probably already impacting consumer sentiment, with 62% of borrowers
RATE OF MORTGAGE ARREARS ACROSS STATES
expecting their lender to increase interest rates on their home loan in the next 12 months,” the survey said. If a future rate rise does lead to increased mortgage delinquency, Scheule says banks are likely to tighten lending standards even further and drop the loan amounts offered to applicants. That combination could further constrain interest-only borrowers seeking to refinance at the end of their interestonly terms. “This means more mortgage stress, as many had expected to roll over the interest-only period indefinitely, but now they are forced to make principal repayments next to interest payments,” Scheule says. As loan supply is increasingly restricted alongside rising delinquency rates, housing prices will begin to tumble, and Scheule says Australia will be well on its way to a burst housing bubble. “The cycle between delinquencies and tightening bank lending standards continues, and as a result there’s a noticeable drop in loan supply and a fall in house prices,” he explains. When asked if banks and brokers are doing enough to protect borrowers, Scheule admits it’s a
BANKS’ NON-PERFORMING HOUSING LOANS REMAIN LOW
Source: ABS, RBA, Securitisation System
Source: APRA, RBA
Balance-weighted share of securitised loans; 90+ days in arrears
%
Domestic books, share of housing loans
%
%
%
0.8
0.9
0.9
0.6
0.6
0.6
0.4
0.3
0.3
0.2
0.0
WA 0.8 SA
0.6
QLD VIC
0.4 VIC NSW 0.2
Sept Dec 2015
Mar
Jan Sept Dec 2016
Mar Jan 2017
2005
2009
2013
2017
0.0
Harald Scheule, associate professor of finance, UTS
Stephanie Duncan, mortgage broker, Tiffen & Co
difficult question to answer but says the best thing brokers can do is provide balanced advice and education to their clients. “High professional standards for both banks and brokers are critical to the resilience of our financial system,” he says. “This includes consumer awareness of risks. The impact of payment shocks via interest rate increases or loss of employment should be discussed.” Tony MacRae, general manager of third party distribution at Westpac, agrees that high professional standards are a necessity in any market but says the situation isn’t as bleak as it’s sometimes portrayed. “The number of our customers in arrears on their loans is at historically low levels, and we don’t expect this to
Tony MacRae, general manager of third party distribution, Westpac
increase in the short or medium term,” he says. MacRae says Westpac remains conservative in its lending and has long included a range of protectionary measures in its processes, such as the addition of buffers and floor rates to account for possible future interest rate increases. “Our credit policies are informed by our deep experience and understanding of the mortgage market,” he says. “They include consideration of customers’ specific circumstances, including income and expenditure, previous repayments history and the overall customer relationship.” MacRae also says the bank has employed a range of measures to help it meet APRA’s benchmark of 30%
for new interest-only lending, including adjusting its interest rates and lending policies. However, what MacRae says Westpac has seen is an increase in the number of customers taking out or switching to principal and interest repayments – something Canberra broker Stephanie Duncan, of Tiffen & Co, has also noticed. According to Duncan, who has been recognised as one of the most successful female brokers in Australia, the trend suggests clients are fully aware that the interest rates are likely to rise, and they understand the impact this will have on their financial situation. “The increase in repayments to mortgage holders if rates are to rise is somewhat expected by consumers. It
is not going to come as a surprise that rates will be increasing in the short to medium term,” she says. “Most of my clients are opting for P&I repayments so as to take advantage of the record lows in anticipation of better preparing themselves for the future rates rises,” she adds. Duncan agrees that the banks are being incredibly cautious with lending in the current climate, which is helping to offset much of the risk that mortgage holders could potentially face. “There have certainly been some fairly significant changes to policy that have reduced overall lending amounts and, in turn, the risk to consumers,” she says. However, Duncan says there are some significantly more pressing problems that the industry should be dealing with. “My biggest issue is not the tightening of policy and reduced lending capacities but the inconsistency of assessment and discrepancies between credit assessors,” she continues. “With so many changes in such a short space of time, I feel the education on credit is lacking. This results in multiple touches to a file, and when there is no ownership of a file and it is being touched by different assessors this can result in a very slow and frustrating approval process.” Duncan also suggested that clients are more likely to be adversely impacted by lenders’ mortgage insurance rather than increasing interest rates. “In my experience there has been an increase in family guarantee lending and gifts from family becoming a new norm for most young people borrowing these days due to the high cost of living,” she says. Based on this, Duncan says the bigger issue for clients is raising a large enough deposit to avoid LMI when entering the market, rather than the problem of having enough regular income to service the loan. AB www.brokernews.com.au
19
PEOPLE
OPINION
HOW TO FIND YOUR ‘MOJO’ MSA National founder and managing director Sam Makhoul explains how to harness your ‘mojo’ to find success in life and business. He provides Australian Broker readers with suggestions on how to reset their equilibrium going into 2018
the people around you. Life will never go 100% your way. Not even 50%. The people who walk around with their mojo intact are the ones who accept that external discomforts are a part of living and that the only people who are not stressed are dead. You gotta have fun When we were children, our whole existence was about exploring and having fun. Consequently, our creativity was limitless. The few that carry this fun and playfulness into their adult life go on to invent and create the most amazing human discoveries: Albert Einstein, Leonardo Da Vinci, to name a couple. So my advice is to stop feeling guilty whenever you get the urge to do nothing, or to daydream or hang out with friends. Have fun whenever you get the chance. Your mojo loves to have fun.
8
mojo is that magical quality that attracts good things to you. We are all born with it but lose it on the way to adulthood. We may experience glimpses of it, but it is elusive and vanishes quickly. Finding and hanging on to your mojo happens when you balance the mind-body connection. Here’s how…
Go green inside and out Looking at the colour green lowers blood pressure and dissipates stress. Walk in the park daily; go for a hike on weekends. Surround yourself with plants at home. (Book recommendation: Plant Style by Alana Langan.) Drink green smoothies and eat at least two green
Keep a ‘hero’ file Treasure and file away all the cool stuff people say about you, whether it’s an outstanding work reference, a testimonial from a client, or a thoughtfully written card from a friend or partner. We all indulge in negative self-talk. A hero file helps you snap out of it.
The people who walk around with their mojo intact are the ones who accept that external discomforts are a part of living and that the only people who are not stressed are dead
5
YOUR
1
Go fearless In sport and in business, if you start batting on the back foot you will stop scoring runs and eventually be bowled out. You are most successful when you work like you have nothing to lose. How do you do that? Build up enough savings so that you could get through six months of the toughest financial times. Having this safety net gives you a fearless mindset.
2
salads daily. Besides being healthy, plant foods are full of life force that give you that glow. Look your best How you look impacts the way you feel. When you dress and look your best, you will simply feel more confident and ‘with it’. (Caution: You cannot eat like crap and cover it up with clothes and make-up. You still need to eat clean and stay lean.) Choose clothes that are true to your personality. Stay away from fads. Get a style coach. Read Women in Clothes by Sheila Heti and Off the Cuff: The Guy’s Guide to Looking Good by Carson Kressley.
6
Get out of your head You will never find your mojo if you are constantly thinking and using your mind as a storage device. Do a daily ‘brain dump’ in your diary. Keep nothing in your head. This will help you sleep better and get into the zone of creativity.
3
It’s NOT about you Never ever make your life about making money and material things. Your primary purpose as a human being is to serve and inspire others: your customers, your colleagues, your friends, your family… How do you do that? Listen more empathically and give more than expected. Your mojo lives in that space called compassion.
4
20
www.brokernews.com.au
Don’t stress about stress External stress is everywhere. It only affects your mojo when it consumes you. Some people live through war and take it in stride. Others go into meltdown when someone cuts them off on the road. Seriously? Stop trying to make your external surroundings perfect. Stop putting high demands on yourself and
7
Sam Makhoul Founder and managing director, MSA National
Savour your food Your appetite for food parallels your appetite for life. Food that is full of flavour not only nourishes the body but
9
brings passion to the surface. They call it ‘soul food’ for a reason. Enjoy the variety of foods out there, but try to eat true to your cultural heritage. There is nothing more satisfying than eating food that your parents and grandparents cooked. Savour what you eat slowly, focusing on the smell, texture, colour and taste. Eat outdoors, eat with your hands, eat with friends, and above all please do NOT eat in front of the TV/computer. Change your environment, often New routes, new destinations, new friends, new experiences. These all keep your five senses engaged. When you do the same thing every day, your senses become dull. Parts of your brain consequently shut down. Scientists are now realising that Alzheimer’s and dementia are cases of ‘use it or lose it’ (google ‘The Nun Study’). New perspectives, new sights, new smells, new flavours all keep your brain firing and your mojo dancing. There is a difference between life and living. AB
10
www.brokernews.com.au
21
PEOPLE
CAUGHT ON CAMERA The Finance Brokers Association of Australia held its 2017 annual conference at Sea World on the Gold Coast on 24 November with the theme ‘Go beyond!’ As usual it was followed by a gala dinner that included the FBAA’s highly sought-after Awards of Supremacy. Delegates took over the Sea World theme park in their Hawaiian shirts and summer dresses at the industry’s largest beach party, which began with an amazing performance by the dolphins. The evening included a beachside carnival and buffet; a DJ spinning his tunes from the Sea World monorail; bands and entertainers; and even a dunk tank, ensuring FBAA executive director Peter White had a rather wet night!
22
www.brokernews.com.au
Have an interesting deal? Had a particularly difficult or interesting deal? Why not share it with us? Email:
Otiena.Ellwand@keymedia.com.au
A BIG DEAL
PJ Patterson, CEO of Keystone Financial, explains how a successful auction for his clients turned into a career highlight and a windfall donation for children’s cancer research Images: Jason Kirk Photography
THE FACTS
Location: Appin, NSW
Lender NAB
Client Young married couple
Goal To buy first home
for the Children’s Cancer Institute. It was constructed in a mere 28 days. The house, land, materials and labour were entirely donated and all the proceeds went to the institute. When I got the phone call from John, the buyer of the home, first thing Monday
THE SCENARIO
My story is about a deal that started in the most normal fashion but ended up becoming something very special. In late September I was referred clients who, by all accounts, were stock standard first home buyers. They came to me to get a pre-approval, having already approached their current bank with no success in obtaining this. In reviewing their situation, I could not understand what the issue was, so I happily began the application process. I gathered all the requisite information and submitted it. They were pre-approved, no issue. Armed with that, the clients went off to an auction in their local area. I never could have expected what happened next. The clients attended an auction for a new home in Appin, NSW, and much to their elation they were the winning bidders and got the property for $700,000. But there was something really special about the home they fought for and won at auction. It is known as the ‘house that love built’. The house is actually the third ‘Build for a Cure’ home, sold to raise funds
Loan size $630,000
my clients, as well as for the Children’s Cancer Institute. You see, not only did John and Hannah get a fantastic brand-new home, but it came fully furnished with over $100,000 worth of appliances and furnishings as well. That was very exciting indeed, but to also know that $700,000 had just been raised to aid the fight against childhood cancers was really overwhelming. I have never had anything quite this significant happen to me as a professional broker, and it seemed like random luck for it to have occurred both for my clients but also for me. Furthermore, I have also pledged to donate $2,000 to the institute. THE TAKEAWAY
As soon as I had the contracts, we got the deal formally approved through NAB, and my clients were well and truly relaxed. When I met up with them recently to sign the mortgage documents, I got the impression that this life-changing event still hadn’t fully registered. I’m sure it finally did when the loan settled at the end of November and they got the keys. But there was one other thing I realised I must do. I did not know if I would ever get this type of situation falling into my lap again, so I wanted to take advantage of the marketing opportunity. Luckily I had been ramping up all my digital marketing activities in the last year, getting to know my way around Facebook, LinkedIn and the like, so I saw this once-in-a-career chance to attach my brand to the story, and pounced on this marketing opportunity. I offshore my digital marketing, and we immediately got to work on a Facebook post, Twitter announcement and keywords that would hopefully give me some free marketing. It worked well, with my brand getting a bit more recognition and more hits on the website.
To also know that $700,000 had just been raised to aid the fight against childhood cancers was really overwhelming. I have never had anything quite this significant happen to me
PJ Patterson CEO, Keystone Financial
morning following the auction, the awesomeness of the situation didn’t really sink in. However, once I read an article about the sale on the Domain website, I was stoked. Upon reading the story of the home, how quickly it was constructed, and the generosity of the builder and all the tradies, I knew something special and life-changing had just happened to
I feel great about the outcome of this experience, and I’ve learned even more about effective marketing as a result. I’m sure everyone in the industry will relate to my key takeaways from this experience: treat every client well and don’t pass judgment until you get to know their situation. Always look for other opportunities to leverage something. AB www.brokernews.com.au
23
PEOPLE
CAUGHT ON CAMERA NextGen.Net recently held its annual cocktail party to thank customers and industry partners and celebrate another successful year. The event was held at the iconic Museum of Contemporary Art at The Rocks and was attended by lenders, aggregator groups, brokers and other industry collaborators from across the country. The fabulous Adam Spencer, Australia’s favourite mathematician, who was guest speaker, shared amazing insights into the future of mathematics and science, as well as a good understanding of how he almost impressed Cameron Diaz.
24
www.brokernews.com.au
Wednesday 6th June • Westin Hotel Sydney
AUSTRALIA’S LEADING INDEPENDENT NATIONAL BROKER EVENT
SAVE THE DATE Register today to get the best seat at the best price
Event partner
Breakfast sponsor
Gold sponsor
Exhibitors
Refreshment Sponsors
Supporting publications
www.brokerbusinessexchange.com.au
Organised by
www.brokernews.com.au
25
DATA
WESTERN AUSTRALIA
QLD SPOTLIGHT
The Perth property market shows signs of entering a stable period According to Hayden Groves, president of the Real Estate Institute of WA, market conditions levelled out in the September 2017 quarter. “Conditions across both the sales and rental market were fairly stable. Both the median house and rent price held up ... while stock levels in both sectors had reduced over the month,” he says. According to REIWA data, the number of properties listed for sale inched downwards slightly in September. The rental market has felt this pick-up as well, with the number of dwellings for lease falling by 3%. “It’s very encouraging to see stock levels across the market continue to reduce, especially when we compare levels for both sectors on an annual basis. If this trend continues, we should see a better balance between supply and demand of stock start to emerge,” Groves says. Joonadalup South, Kwinana, Belmont and the western suburbs were regarded as top-selling submarkets in the state. Area
Type Median value
Quarterly
12-month
growth
growth
Perth
H
$500,000
-2.4%
-2.5%
WA Country
H
$330,000
-5.0%
-5.1%
Perth
U
$390,000
-4.9%
-3.6%
WA Country
U
$249,500
-17.9%
-0.7%
SOUTH AUSTRALIA
Adelaide's variable market seems to reflect the national property scene “Like the rest of Australia, the Adelaide property market is very fragmented, with some suburbs showing three times the capital growth of others,” says Michael Yardney, CEO of Metropole Property Strategists. He notes that while dwelling values in general increased by 5.5% in the year to October 2017, the continued lack of economic development is worrying. “I know some investors are looking for opportunities in Adelaide, hoping (‘speculating’) prices will increase, but there are few growth drivers in Adelaide, with fewer than 8,000 new jobs created there [in 2017],” Yardney says. The findings of CoreLogic’s Pain and Gain report for the June 2017 quarter seem to support this view: 7.5% of houses and 12.4% of units in Adelaide were resold for less than the purchase price, while areas like Walkerville, Norwood and Mitcham reported significant levels of resales at a profit. Area
Type Median value
Quarterly
12-month
growth
growth
FORECAST MELLOW FOR BRISBANE Brisbane may disappoint, but the performance of the regional market looks to be picking up the slack
economy is seeing strong growth, a welcome respite after the fallout from the mining downturn. “The next three years look decidedly better for property markets across Queensland. To the year ending August 2017, the volume of jobs in the Sunshine State increased by 3.7%, above the 2.6% national average,” reports Simon Pressley, managing director of Propertyology. With the employment market getting a boost, interstate migration has followed suit: an average of more than 3,000 people entered the state over for the six quarters leading up to August 2017. “While the state’s southeast often attracts the headlines, central and north Queensland have (arguably) better potential for improvement. Harvey Bay, Toowoomba, Gladstone, Rockhampton, Mackay, Townsville and Cairns perform the role of a capital city to their respective regions,” Pressley adds. “Each of these cities can look forward to increased demand for local goods and services from improving sectors such as tourism, health, agriculture and mining.” QUEENSLAND'S
Oversupply brings Brisbane down Although population growth is picking up in Queensland, Brisbane’s property market is still expected to underperform. “There is a significant oversupply of new high-rise, off-the-plan apartments overshadowing the inner-city area and nearby suburbs, with owners now giving significant incentives to attract tenants at a time of rising vacancy rates,” says Michael Yardney, CEO of Metropole Property Strategists. “Unfortunate buyers of off-the plan apartments in Brisbane are selling at a considerable loss, particularly if they bought in one of the many high-rise towers in suburbs like Hamilton, Bowen Hills and Fortitude Valley.” AB
H
$446,500
-2.1%
2.8%
Median price (houses)
SA Country
H
$285,000
-5.0%
1.9%
$824,747
Adelaide
U
$375,000
0.0%
4.7%
SA Country
U
$190,000
3.1%
-1.3%
www.brokernews.com.au
The Sunshine Coast is enjoying billions of dollars worth of infrastructure developments, making way for population to grow from 298,000 to 500,000 by 2041 Some of these developments include the expansion of the local airport, construction of the new $430m CBD at Maroochydore, an $81m expansion of the Sunshine Coast University, a $1.8bn investment in the new hospital precinct at Kawana, and $10bn in residential developments creating around 70,000 new home sites. These infrastructure developments position the Sunshine Coast housing market for strong growth moving forward. In terms of building approvals, we are currently outperforming all other regions in Queensland in both residential and non-residential areas. In the last 12 months many of our suburbs have achieved growth of 10% or better, with a handful achieving higher than 13%. Property on the Sunshine Coast, while growing, is still much more affordable than in the major capital cities, and with the aforementioned developments expected to create thousands of jobs, it's easy to see how we could reach a population of half a million in the next 24 years. Kaia Hunter Senior broker, Mortgage Choice, Buderim
SUBURB TO WATCH: DUTTON PARK
Adelaide
26
BROKER PERSPECTIVE
Median price (units) $463,445
Source: CoreLogic
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
8.8%
17.0%
24.5%
3.1%
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
-6.2%
-8.9%
43.3%
5.0%
AUSTRALIAN CAPITAL TERRITORY
The outlook for the nation’s capital is bright OPPORTUNITIES AND KEY INFRASTRUCTURE
Smart thinking
Shop and play
Health hub
Cross River Rail
Sunshine Coast University set to take over another campus in $81m expansion
Sunshine Plaza adds high-ropes course to shopping centre redevelopment plan
$1.8bn hospital development fuelling healthcare industry in Kawana
Rail network expansion plan will make travelling across SE Queensland faster
HIGHEST-YIELD SUBURBS IN QUEENSLAND Suburb
Type
Median price
Quarterly growth
12-month growth
Yatala
U
$322,500
-14%
-20%
Moura
H
$92,500
-3%
-22%
Mount Morgan
H
$89,500
-11%
-19%
Blackwater
H
$90,000
4%
-27%
Dysart
H
$85,000
-8%
33%
With property values rising by almost 8% in 2017, Canberra stays on the heels of Melbourne and Sydney as one of only three states to experience real growth after accounting for inflation. “The medium- to long-term outlook for Canberra property is good as it has a strong public sector, a strong and stable employment market, a belowaverage unemployment rate and above-average household incomes,” says Michael Yardney, CEO of Metropole Property Strategists. “All this points to continued property price growth in the future, but at a more moderate rate likely to be in the order of 3–4% over 2018.” Domain Group figures certainly confirm that the market is continuing to surge upwards as the end of the year approaches. Over the September 2017 quarter, Canberra had the highest growth rate among the capital cities, with the median house price rising by 4.4%. Units did not fare as well as houses, but they still reported a 1.9% boost in values. Area
Type Median value
Quarterly
12-month
growth
growth
Canberra
H
$650,000
-5.1%
7.3%
Canberra
U
$424,250
-3.0%
1.2%
www.brokernews.com.au
27
DATA
NEW SOUTH WALES
Sydney may be inching closer to the next stage of the property cycle as price hikes ease up
CAPITAL CITY AUCTION CLEARANCE RATES
growth
growth
Sydney
H
$945,000
-8.7%
8.0%
NSW Country
H
$445,000
-3.3%
6.7%
Sydney
U
$716,500
-3.2%
4.3%
NSW Country
U
$390,000
1.3%
5.0%
MEDIAN HOUSE AND UNIT PRICES
Melbourne has the formula for sustaining growth down to a fine art
$1,000,000
Quarterly
12-month
growth
growth
Melbourne
H
$702,000
-2.5%
11.3%
VIC Country
H
$325,000
-3.8%
4.8%
Melbourne
U
$520,000
1.0%
3,2%
VIC Country
U
$267,500
1.9%
2.7%
28
www.brokernews.com.au
Sold
69
Not sold
34
Clearance rate
67.0%
PERTH Total auctions
43
Sold
7
Not sold
11 38.9%
$1,100,000
Sydney Melbourne Brisbane Adelaide
Perth
Hobart
$500,000
$410,000
$337,500
$0
$400,000
$100,000
$504,125
$200,000
$338,000
$300,000
$440,000
$500,000 $400,000
$551,000
$700,000 $600,000
$755,000
$800,000
$712,500
$900,000
Houses
$945,000
“The current market is driven by a shortage of homes, as well as the increasing number of Chinese buyers,” says Glen Coutinho, director of RT Edgar. “This shortage, plus low interest rates, is driving prices up. General economic conditions are healthy, with low inflation.” Coutinho points to stability and good opportunities for education and employment as further reasons for the state’s popularity with overseas investors, since there is likely to be sustained demand from tenants. “For investors to make money, they must buy with a 10-year vision. Having a home/land is the key to growth. There is and will continue to be a shortage of homes in good areas,” Coutinho explains. “Suburbs in tight supply are generally the eastern suburbs and Bayside, as well as private school belt areas. The riskier investment will be buying off plans or buying in suburbs without infrastructure.” Type Median value
153
Clearance rate
VICTORIA
Area
Total auctions
Darwin
Units
$428,000
12-month
ADELAIDE
$660,000
Quarterly
$390,000
Type Median value
There were 3,409 homes taken to auction across the combined capital cities for the week ending 26 November, returning a preliminary auction clearance rate of 66.9% and overtaking the week before as the third-busiest week for auctions so far this year. Once final results are collected, the combined capital city clearance rate tends to revise down, so at this stage it’s looking like the final clearance rate will be in the mid to low 60% range for the sixth week running. Sydney and Melbourne, the two largest auction markets, have seen clearance rates increase week-on-week after both cities recently recorded their lowest clearance rates for the year so far. However, as usual, these clearance rates will revise lower over the week. Over the same week last year, a total of 3,398 homes were taken to auction across the combined capital cities, and a clearance rate of 73.0% was recorded.
$527,750
Area
WEEK ENDING 26 NOVEMBER 2017
$375,000
“We have noticed a gradual cooling of the market over the last quarter of 2017, as auction clearance rates are sub-70% [and there’s] less aggressive bidding at auction and lower attendance at open homes,” says Rich Harvey, CEO of Property Buyer. “We expect the market in 2018 to continue to stabilise, and investors will need to consider renovations, granny flats, subdivisions, smallscale developments and other strategies that add value in order to manufacture equity growth, rather than buying and hoping.” Harvey considers the recent implementation of governing regulations to be a factor in the property market’s shift. APRA restrictions have limited loan activity, causing lenders to be stricter with regard to serviceability requirements. Interest rates have gone up as well, especially for interest-only loans; as a result, fewer investors are taking out such loans and demand has gone down.
Canberra
CAPITAL CITY HOME VALUE CHANGES Capital city
Weekly change
Monthly change
Year-to-date change
12-month change
Sydney
0.0%
-0.5%
4.5%
6.1%
Melbourne
0.1%
0.4%
8.8%
10.4%
Brisbane
-0.1%
0.0%
2.3%
2.5%
Adelaide
0.1%
0.0%
2.7%
3.9%
Perth
0.2%
0.0%
-2.4%
-2.7%
0.0%
-0.1%
4.8%
6.1%
Combined 5 capitals
*The monthly change is the change over the past 28 days
BRISBANE CANBERRA Total auctions
128
Sold
72
Not sold
37
Clearance rate
Total auctions
152
Sold
68
Not sold
50
Clearance rate
57.6%
66.1%
SYDNEY Total auctions
1,200
Sold
565
Not sold
289
Clearance rate
66.2%
TASMANIA
MELBOURNE Total auctions
1,727
Total auctions
6
Sold
1,005
Sold
1
Not sold
2
Not sold Clearance rate
451
Clearance rate
69.0%
TASMANIA
Area
While growth remains centred in the capital, demand is starting to spread out “There has been significant growth in the inner-city suburbs within a fiveminute drive radius of Hobart. There’s growth of 10–15% annually,” says Rob Zubin, principal at My Property Hunter. “It’s definitely rippling out into areas up to 20–25 minutes from Hobart, purely because of pricing and economics and the high demand, and also the low vacancy rates. For all properties, we’ve got a less than 1% vacancy rate.” Zubin certainly sees Hobart’s positive performance extending through to the next couple of years, as he believes the area is in the growth phase of the property cycle. Limited dwelling stock has helped keep occupancies tight and demand high. “People are struggling to get rental properties, and as a result yields are improving and rents are increasing.”
33.3%
Type
Median value
Quarterly growth
12-month growth
Hobart
H
$390,000
-0.6%
6.8%
TAS Country
H
$270,000
0.0%
3.8%
Hobart
U
$300,000
-0.3%
1.7%
TAS Country
U
$229,500
-7.8%
5.8%
All data sourced from CoreLogic.com.au
www.brokernews.com.au
29
PEOPLE
IN THE HOT SEAT Theo Chambers, CEO of Shore Financial, talks about leaving CBA for broking, what it takes to be a smart and efficient brokerage, and the book every investor should be reading
Who or what inspired you to become a broker? I got a mortgage for my first property through a broker even A though I worked at CBA in lending. My broker was able to get me a more competitive and appropriate home loan product whilst also being far more informative about the overall ins and outs of the process. It made me realise that I may be working on the wrong side of the process. Coincidentally, my broker offered me a job. At the time, I wasn’t too excited about the offer as I still had a banker mentality towards the profession. However, as I became less motivated and passionate about my corporate job, I eventually resigned and applied. I became a broker in January 2011. It’s been one of the best decisions I have ever made.
Q
What are some of the changes in store for your brokerage in 2018? We are becoming far more centralised and digitised. A The future requires robust, efficient and effective broking businesses, and that calls for centralised systems and processes. We’ve witnessed many brokers become crippled with upset clients due to assistants resigning or going on leave. A centralised processing team allows staff to take time off whenever they want and accounts for turnover without causing unnecessary inconveniences for the broker and client. Our business is focused on online marketing and obtaining new clients in an organic yet strategic manner. Radio and TV ads are a thing of the past. Facebook, AdRoll and remarketing can be far more targeted and specific. Our brokerage wants to become a leader in this space.
Q
What’s one memorable experience you’ve had as a broker? Assisting clients in achieving what they thought was an A impossible dream. Many clients may speak to one bank and fall under the impression that they cannot purchase what they were hoping to. Generally that’s how they become introduced to our service and then we help make the impossible possible.
Q
What are you reading and why? Rich Dad Poor Dad, by Robert Kiyosaki, educates people on A general financial habits and reiterates the importance of investing in various assets whilst being more aware of financial independence. It’s a must-read for those who consider themselves to be investors or who are focused on accruing wealth regardless of personal limitations. AB
Q
30
www.brokernews.com.au
www.brokernews.com.au
31
32
www.brokernews.com.au