NOVEMBER 2017 ISSUE 14.22
Improving broker-banker relations ANZ launches a nationwide strategy to improve cooperation /04
Bank competition behind low lending standards APRA’s chairman describes a “race to the bottom” /12
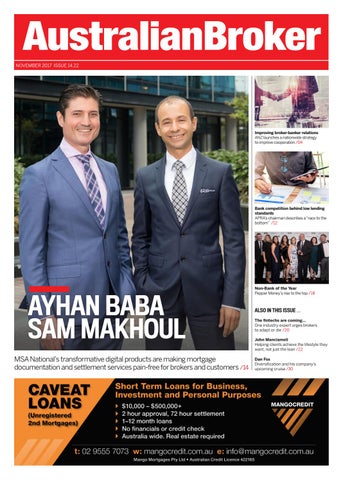
AYHAN BABA SAM MAKHOUL MSA National’s transformative digital products are making mortgage documentation and settlement services pain-free for brokers and customers /14
Non-Bank of the Year Pepper Money’s rise to the top /18
ALSO IN THIS ISSUE … The fintechs are coming… One industry expert urges brokers to adapt or die /20 John Manciameli Helping clients achieve the lifestyle they want, not just the loan /22 Dan Fox Diversification and his company’s upcoming cruise /30
NEWS
IN THIS SECTION
Lenders ANZ aims to improve broker and banker relations /04
Brokers NAB aggregators recruit 338 brokers /06
Technology Loan platform breaks ground in transparency /10
Regulators Competition behind low lending standards: APRA /12
Consumers Mortgage tycoon charged in $30m tax fraud case /08
www.brokernews.com.au NOVEMBER 2O17 EDITORIAL Editor Otiena Ellwand News Editor Miklos Bolza Production Editor Roslyn Meredith
DATES TO WATCH
Upcoming can’t-miss events
ART & PRODUCTION Designer Martin Cosme Production Manager Alicia Chin
16-30 NOVEMBER
24 NOVEMBER
24 NOVEMBER
FAST PD Days
FBAA National Industry Conference
MFAA WA Golf and Sundowner
This year’s conference on the Gold Coast will equip brokers and other industry members with useful knowledge and practical strategies to help them succeed in an increasingly challenging market
Head to the green instead of the office and enjoy a day of golf and networking with industry colleagues at the Wembley Golf Course outside Perth – or come for the views and buffet BBQ as the sun sets
FAST is hosting five PD Days across the country in November. The events will include a business and industry update, growth and networking opportunities, and business strategy insights
Traffic Coordinator Freya Demegilio
SALES & MARKETING Sales Manager Simon Kerslake Account Manager Rajan Khatak Marketing and Communications Manager Lisa Narroway
CORPORATE Chief Executive Officer Mike Shipley Chief Operating Officer George Walmsley Managing Director Justin Kennedy Publisher Simon Kerslake Chief Information Officer Colin Chan Human Resources Manager Julia Bookallil
EDITORIAL ENQUIRIES
Otiena Ellwand +61 2 8437 4792 Otiena.Ellwand@keymedia.com.au
SUBSCRIPTION ENQUIRIES
tel: +61 2 8O11 4992 fax: +61 2 9439 4599 subscriptions@keymedia.com.au
28 NOVEMBER
1 DECEMBER
1 DECEMBER
Webinar on using digital to improve efficiency
Bowling with the FBAA
Anti-Money Laundering Conference
In this MFAA webinar, ANZ explains the tools it offers to help brokers and customers grow their businesses and transact with the bank digitally to improve efficiency
Escape the humdrum of the office and take to the bowling lanes to settle your scores. The FBAA is bringing the fun to Victoria, so start handpicking your team
The program will explore the systems and processes that need to be in place for organisations to better understand their customers and the volume of data they are managing in today’s heightened climate of risk
ADVERTISING ENQUIRIES
Simon Kerslake +61 2 8437 4786 simon.kerslake@keymedia.com.au Rajan Khatak +61 2 8437 4772 rajan.khatak@keymedia.com.au Key Media Pty Ltd Regional head office, Level 1O, 1–9 Chandos St, St Leonards, NSW 2065, Australia tel: +61 2 8437 4700 fax: +61 2 9439 4599 www.keymedia.com Offices in Sydney, Auckland, Denver, London, Toronto, Manila, Singapore, Bengaluru
5 DECEMBER
6 DECEMBER
7 DECEMBER
How to convert leads online
Networking breakfast
AFG Awards – Sydney
The MFAA presents a lunchtime webinar on converting online leads, turning cold leads into warm leads, and increasing your conversion rate
Suncorp is hosting a networking breakfast for Connective brokers in both Adelaide and Perth on 6 December. Get to know the bank’s BDMs and their local team
AFG will unveil its Top 20 groups and Top 40 loan writers in NSW and ACT, along with a host of other awards for best performers, at the combined AFG Awards and Christmas function at Doltone House in Sydney’s Hyde Park
2
www.brokernews.com.au
This magazine is printed on paper produced from 1OO% sustainable forestry, grown and managed specifically for the paper pulp industry Copyright is reserved throughout. No part of this publication can be reproduced in whole or part without the express permission of the editor. Contributions are invited, but copies of work should be kept, as Australian Broker magazine can accept no responsibility for loss. Australian Broker is the most-often read industry publication, according to independent research carried out by the Ehrenberg-Bass Institute for Marketing Science at the University of South Australia in December 2008. The research also found that brokers rate Australian Broker as the best for both news content and feature articles, followed by sister publication MPA. Overall, on all categories, Australian Broker ranks top followed by MPA. The results were based on a sample of 405 respondents who were the subject of telephone interviews.
NEWS
LENDERS BROKER SHARE OF WESTPAC LOANS RISES brought in 42.7% of its loans through the third party network as of September this year, up slightly from 42.1% recorded the year before. The bank’s annual financial results, released on 6 November, also found that a total of $11.4bn worth of loans were switched from interest-only to principal and interest. The vast majority of these changes ($7.9bn) were initiated by customers, while $3.4bn was due to borrowers reaching the end of their interest-only period. WESTPAC
REGULATORY EFFECTS ON LENDING GROWTH Source: QBE Australian Housing Outlook 2017–2020
Year-on-year lending growth based on three-month rolling average 50%
Investor loans (value ‘000s) Upgrader/downsizer loans (no.)
40%
First home buyer loans (no.)
30% 20% 10% 0% -10% -20%
APRA HAS ‘EYES ON’ NON-BANKS will be tasked with APRA infiltrating the non-bank sector and will have “eyes on the ground” to enhance its data gathering, Treasurer Scott Morrison told the Financial Services Council on 30 October. “Such access will allow it to react quickly when unfortunate trends arise.” This “future-proofing measure” will be added to APRA’s reserve powers over lending activity within the sector. Firstmac, Liberty, Pepper and RESIMAC previously warned that any APRA powers should be “limited to exceptional circumstances”.
“What we are doing is centring our minds on the customer and not focusing on what door a customer walks in first, second or third.” Simone Tilley General manager of retail broker distribution, ANZ
4
www.brokernews.com.au
-30% 2012
2013
2014
20151
20162
20173
1 Banks tighten lending policy in response to APRA directives in Nov 2014 and July 2015 2 Banks reassess lending policy as loan growth slows below APRA’s preferred rate 3 APRA directives to reduce interest-only lending
ANZ AIMS TO IMPROVE BROKER AND BANKER RELATIONS The big four bank has launched a nationwide strategy to enhance cooperation between direct and third party channels after noticing a disparity in their financial performance has commenced a
ANZ nationwide strategy of
collaboration between brokers and branches to swap information, bring both channels together, and create a better experience for customers. The idea for greater coordination between the two channels emerged when Simone Tilley, ANZ’s general manager of retail broker distribution, noticed a disparity in financial performance between third party and direct. By educating branch staff on the reasons why consumers choose brokers, there was an opportunity to focus on the customer and create a rich onboarding experience, Tilley told Australian Broker. “The message I’m sending … is that I don’t want to be winning at
the expense of others.” To accomplish this, ANZ branch managers are encouraged to attend broker professional development days. This achieves a twofold goal: introducing branch managers to brokers and educating branch managers about building trust and rapport within the broker network. If branch managers keep brokers informed of the loan application progress at all times and assist with matters such as documentation sign-ups and needs analysis, this can create “symbiotic benefits” for both parties, she said. For the past six months, ANZ has been quietly rolling out this scheme across hundreds of branches and 4,000 branch staff nationwide, working closely with state heads of
the business and branch networks. “We are aligning our BDMs with districts across the country so that there’s strong unity from within.” The bank is also using branch huddle days to explain the importance of the broker network, how to build respectful relationships with brokers, and how not to go down a path of conflict, Tilley said. “[We’re] really trying to educate from a grassroots foundational level so that we’re able to drive the message across the business.” Another initiative involves supplying branch managers with reports around funds under management for brokers within the nearby area to enhance clarity regarding which brokers are settling business. ANZ then facilitates introductions between the branch managers and these brokers, Tilley said. “Where we have got those linkages taking place, there are … treasured partnerships being formed because the branch managers get to know the brokers.”
NEWS
BROKERS BROKERS BEHIND $3.7BN OF LIBERTY LOANS lender Liberty Financial has reported an increase in new loan originations, an expanded broker network, and growth in the commercial and auto space. The latest Liberty financial results show that brokers were responsible for bringing in $3.7bn of new loans for the lender, including a 64% increase in commercial loans and a 39% increase in auto loans. Liberty now has $7.5bn worth of total assets, a 40% increase on the 2016 financial year. NON-BANK
REAL-TIME LEARNING PLATFORM UNVEILED mortgage franchise Yellow Brick Road has launched a new learning platform for member brokers on its aggregation network, Vow Financial. The platform was developed around experimental learning – or learning by doing – and offers brokers bite-sized learning via text, podcasts, videos and more, Vow general manager Clive Kirkpatrick said. Learning areas include broker induction, lending policies, regulation and compliance, and sales and marketing. Business management and financial planning will be added at a later date. NATIONAL
NAB AGGREGATORS BOOST NUMBERS WITH AN ADDITIONAL 338 BROKERS The major bank’s financial results show growth in lending volumes and drawdowns within the third party channel third party channel at NAB has grown over the last financial year in terms of loan volumes, drawdowns and sheer broker numbers. In its annual financial results released on 2 November, the bank revealed it had recruited an additional 338 brokers across its aggregators, PLAN, Choice and FAST, within the 12 months prior to 30 September. This brings the total number of brokers across the bank’s aggregation network to over 4,600. Residential lending volumes for brokers increased by 12% to $98.5bn, and drawdowns attributed to the third party rose by 42% during the same time period. “We would like to thank each of our brokers and aggregators for their THE
6
www.brokernews.com.au
ongoing support. Strong growth in drawdowns through brokers – from 34.4% to 42% this financial year – demonstrates an incredibly important part of what we do as a bank,” Anthony Waldron, executive general manager of NAB broker partnerships, told Australian Broker. These financial results reflect NAB’s strategy to become the bank for brokers, he said. “Our business is defined by great partnerships – with our aggregators who continue to do an excellent job in providing brokers with the right support to run and grow their businesses, and with our brokers who continue to provide the best experience for their customers.” NAB’s total housing lending portfolio sat at $292.6bn at the
end of September. Of this, 58.0% was made up of owner-occupier, 42.0% of investor, and 29.8% of interest-only loans. Residential lending market share rose slightly to 15.7%, while average LVR at origination sat at 69.0%. The bank saw $8.4bn worth of loans converted from interestonly to principal and interest. Of these, $3.5bn came from early conversions, with customers seeking to switch and take advantage of the lower P&I interest rates. “Principal and interest rates are significantly lower than interest-only, so there’s a real incentive for people to move into those,” NAB CEO Andrew Thorburn said during the financial results briefing. Looking at loan defaults and arrears, 0.59% of the total loan portfolio was 90-days-plus past due. At the other end of the spectrum, 72.5% of customers were more than one month in advance, including those with offset facilities. On average, NAB’s home loan customers are 30 monthly payments in advance.
“We are focused on giving more choice to brokers and customers and, at the same time, ensuring the experience of dealing with Liberty is personalised, fast and professional.” John Mohnacheff Group sales manager, Liberty
NEWS
CONSUMERS 73% OF INVESTORS OPTING TO USE BROKERS lending restrictions are driving more property investors to seek assistance from mortgage brokers, a new survey has found. Property Investment Professionals of Australia’s third annual Property Investor Sentiment Survey revealed that 73% of investors have used a broker, up from 65% two years earlier. The report also found that over the next 12 months 83% of investors intend to use a broker for their next loan – an increase from the 71% recorded in last year’s survey. TIGHTER
RESI LENDING SURGES BY $5BN of residential lending across Australia’s banks grew by $5bn during the month of September, driven primarily by greater volumes of owner-occupier mortgages. Owner-occupier lending grew by $4.9bn from the month before, while investor lending increased by a measly $218m, according to APRA’s Monthly Banking Statistics. The total volume of residential lending now sits at $1.58trn, representing a 0.32% increase from the previous month. VOLUMES
“Our survey results show that rather than be defeated, educated property investors are opting to use professionals to assist them to achieve their goals – regardless of the lending environment.” Ben Kingsley Chair, Property Investment Professionals of Australia
MORTGAGE TYCOON CHARGED IN $30M TAX FRAUD CASE The founder of RAMS Home Loans and part-owner of LJ Hooker Home Loans has been charged in connection with avoiding tax obligations in excess of $30m mortgage industry magnate has been charged with tax fraud offences worth more than $30m following a complex eight-year investigation that involved crossborder collaboration. The Australian Federal Police (AFP) allege that John Kinghorn, 76 – founder of RAMS Home Loans, which was acquired by Westpac in 2008, and part-owner and director of LJ Hooker Home Loans – fraudulently concealed his beneficial ownership and control of corporate entities, avoiding associated tax obligations in excess of $30m. Kinghorn has been charged with one count of dishonestly influencing a Commonwealth public official and A
one count of defrauding the Commonwealth. The maximum penalty for these offences is up to 10 years’ imprisonment. Kinghorn appeared in court in Sydney on 31 October and did not enter a plea, according to the ABC. The matter will return to court in February. The ABC reported that court documents show he allegedly concealed his beneficial ownership of two companies, Kalomo Pacific Leasing – based in Jersey, UK – and Kalomo Corporation Limited, from the tax office between 2004 and 2007. “Serious financial crime poses a threat to Australia’s economy,
financial markets, regulatory frameworks, superannuation and tax system,” said AFP assistant commissioner Neil Gaughan in a news release. “Commonwealth fraud offences have a significant impact on the Australian public – every dollar represents funds that could have been put to use for the benefit of the whole community. “This result should serve as a warning that we will use every capability at our disposal to bring allegations of fraud before court.” Gaughan said the investigation required extensive cooperation within the Serious Financial Crime Taskforce and with international agencies. “I’d like to commend the officers involved in this complex and lengthy investigation for their persistence and dedication to ensuring the integrity of Australia’s financial frameworks,” he said. LJ Hooker Home Loans declined to comment.
VV$40,614,829,064 MORTGAGES DRIVE LENDING IN SEPTEMBER OWNER-OCCUPIER Owner-occupied (Sept)
Investor (Sept)
Owner-occupied (Aug)
Investor (Aug)
$18.7bn $18.4bn $8.2bn $8.3bn
$12.7bn $12.9bn $5.2bn $5.3bn
$28.6bn $29.4bn $11.9bn $12.1bn
$33.5bn $33.2bn $9.6bn $9.6bn
$22.6bn $22.4bn $11.7bn $11.7bn
$60bn
$16.2bn $16.2bn $11.1bn $11.1bn
$9.9bn $9.7bn $2.8bn $2.8bn
$120bn
$144.0bn $143.1bn $104.2bn $104.0bn
$277.0bn $82.6bn $82.5bn
$180bn
$168.6bn $167.3bn
$240bn
$275.6bn $133.9bn $134.3bn
$300bn
$149.2bn $148.5bn
$244.6bn $243.7bn
Source: APRA’s Monthly Banking Statistics, September 2017
Macquarie Bank
ME
Suncorp
$0 ANZ
8
www.brokernews.com.au
CBA
NAB
Westpac
AMP Bank
Bank of Bendigo and Queensland Adelaide Bank
ING
NEWS
TECHNOLOGY
NON-CONFORMING LOANS MADE EASY thousand brokers have used the Pepper Product Selector online conversion tool since it launched in June, giving them the ability to provide customers with an indicative offer in less than two minutes. It returns a product match, indicative interest rate and associated fees. “To see this tool go from a sketch on paper to a live online customer conversion tool and then to achieve this kind of market penetration – it’s been a terrific success,” said Pepper’s director of sales, Aaron Milburn. A
LOAN PLATFORM BREAKS GROUND IN TRANSPARENCY One leading tech company has focused on proving real-time transparency and security for brokers, lenders and regulators transparency a major focus of government and regulators, loan platforms such as NextGen.Net’s ApplyOnline have had to step up and produce better processes to help brokers, aggregators and lenders stay compliant amid stricter conditions. This means proactively producing quality data and results at the point of sale rather than in hindsight, said Tony Carn, sales director of NextGen.Net. NextGen.Net has introduced software that aligns loan applications with a lender’s credit policy for an added level of transparency, Carn said. “Another key area is alignment of a loan with the requirements of that lender, ie what information do they WITH
need to provide, what policy attributes it needs to have, but also what documentation and verification the borrower needs to provide to the broker and ultimately the lender.” This provides transparency among multiple parties, including the broker, lenders and third parties, such as mortgage insurers, lawyers or regulatory bodies. “It’s critical that data is transparent and auditable and measurable by the licence holder,” Carn said, “and not only is it transparent but it’s transparent in real time.” Lenders can use ApplyOnline to track applications as submitted by the broker, including back-channel messages, he added. This means
that lenders can see all data submitted rather than simply the data requested within their credit policies. Regulatory bodies are the latest group to turn their eyes towards these types of lending platforms, even calling on brokers to provide this added data, Carn said. Of course, the need for transparency has to be balanced with confidentiality, security and privacy concerns for borrowers, and NextGen.Net is investing heavily in these areas, he added. “Everybody in the world is vulnerable, and no one is 100% [prepared for] the risks that we face as an industry. It’s how we actually prepare and how we invest to protect ourselves and mitigate those risks as strongly as possible.” Certain risks around privacy are “enormously overlooked”, especially by those without direct responsibility for them, he warned. This includes aspects like encryption of data and poor online habits.
WILL YOU STRUGGLE TO MEET P&I REPAYMENTS ONCE YOUR IO PERIOD EXPIRES? Source: PIPA Investor Sentiment Survey report, September 2017
13%
12%
N.A.
Yes
55% 20% Unsure
10
www.brokernews.com.au
No
FINTECH TO LINK BANKS, BROKERS AND REGULATORS fintech MoneyCatcha has partnered with HSBC Australia in a trial of its two blockchain platforms with the aim of improving loan turnaround times and reducing compliance spending for the banks. MoneyCatcha has developed loan processing platform Homechain and regulatory risk review tool Regchain, both of which are powered through the same internal blockchain engine. The fintech has partnered with HSBC Bank to trial the use of its Regchain software, which helps regulators capture and review information from lenders. AUSTRALIAN
NEWS
R E G U L AT O R S
BROKER LOANS LARGER THAN DIRECT: ANZ to a question from Australian Broker during ANZ’s financial results briefing, CEO Shayne Elliot said broker-originated loans were larger and performed slightly worse than those brought in through proprietary channels. “You’re more likely to go to a broker if you’ve got a big mortgage, because saving a few basis points here and there is a bigger dollar amount,” he said. Broker-originated loans performed “a little bit worse than the average”, but he emphasised that this was “really minor”. RESPONDING
COMPETITION BEHIND LOW LENDING STANDARDS, SAYS APRA The APRA chairman has described a historical ‘race to the bottom’ in lending standards as banks battle over market share chairman says it was intense competition in the banking industry that led to an erosion in lending standards and pushed the regulator to act. Facing the Senate Economics Legislation Committee on 26 October, APRA chairman Wayne Byres described a “race to the bottom” as banks and lenders fought over market share. “As we found ourselves in an environment of higher house prices, higher household debt, historically low interest rates, and what has become quite subdued income growth, [we expected] to see the prudent banker tightening their standards… We didn’t see that happening,” he said. APRA’S
WESTPAC TIGHTENS UP RESPONSIBLE LENDING has brought in a number of responsible lending changes affecting how brokers enter in requirements and objectives (R&O) questions for clients. Effective from 14 November, brokers will be required to complete additional R&O questions and declarations for clients taking out certain loan types. The questions are designed to help brokers understand their client motivations, align the products to their needs, and prompt brokers to explain consequences of each choice to the client. WESTPAC
12
www.brokernews.com.au
This meant banks were less concerned about the borrowers’ ability to pay back their loans, with lenders instead finding ways to offer more money, he said. Benchmarks on investor and interest-only lending were introduced to reinforce and maintain lending standards at a “sensible level” regardless of where housing, interest rate or macro-economic cycles went in the future. “[It] took the pressure off individual institutions to think they had to keep winning market share. The way they were winning market share was eroding standards. Now there’s a limit to how much you can do that, so it’s taking that pressure off.”
Discussing APRA’s investor speed limits, he said slowing down investor lending was not the objective in and of itself. “[By] constraining banks’ and lenders’ capacity to rapidly grow, they’re less inclined to erode the standards. It takes some pressure off that erosion and reverses that trend.” As for interest-only lending, Byres admitted that these loans did have their place. “There will be borrowers who for good reason prefer to have interest-only loans. It does mean their debt is staying high. They’re not paying anything back. They’ve got very high debt while interest rates are very low, but that will not necessarily be here forever.” Finally, Byres said APRA was reluctant to impose limits on high-LVR lending as this would most likely affect first home buyers. However, he noted that levels of high-LVR loans were contracting by themselves.
NUMBER OF PROPERTY INVESTORS IN WEALTHIEST INCOME BRACKETS HAS GROWN Share of all property investors by income* %
* Income is total income minus gross rent
Source: RBA Financial Stability Review
2003/04 2013/14
30
20
10
0
< 18.2
18.2–37
37–87
Income brackets – $’000
87–180
180+
COMPARISON OF HOUSING PRICES IN SELECTED MAJOR CITIES Source: RBA Financial Stability Review
31 December 2010 = 100
Index
Canada
Index
New Zealand
200
200 Major cities*
150
150
100
100 National average
Index
Norway
Index
Australia
160
160
130
130
100
100
70
70 2009
2013
2017
2009
2013
2017
* Simple average; major cities include Greater Toronto and Greater Vancouver (Canada); Auckland (New Zealand); Greater Oslo (Norway); Sydney and Melbourne (Australia)
CCR MANDATORY FROM NEXT YEAR government has drawn a line in the sand for the comprehensive credit reporting (CCR) regime, which Treasurer Scott Morrison has said will become mandatory from 1 July next year. Currently, less than 1% of all CCR data is shared in the public realm, he said. The four major banks will be the first to face mandated reporting, allowing the smaller lenders time to develop their systems. The big four will be required to have 50% of their credit data ready for reporting by 1 July 2018. THE
FE AT URES
SPECIAL REPORT
A DIGITAL TRANSFORMATION POWERED BY PEOPLE MSA National is a law firm creating cutting-edge digital products to provide customers with a seamless and stress-free experience from home loan approval to settlement. Leadership team Sam Makhoul and Ayhan Baba explain how they’re transforming the customer experience and putting brokers at the centre of it
National is trying to make the process of getting a home loan forgettable. The law firm’s founder and managing director, Sam Makhoul, and its CEO, Ayhan Baba, believe they can ultimately make the home loan approval-to-settlement process – and all of the paperwork, red tape and stress that come with it – invisible to the customer, thus ensuring the broker has a customer for life. By reimagining and overhauling the customer experience through the creation of their innovative digital tools, IDme VOI app, NewGen Digital Docs and MyVideo, they are already well on their way to making this vision a reality. “When you eliminate the noise and complexity, the process becomes invisible to the customer. It just happens effortlessly,” Makhoul says. “It is not about us, and it is not about the home loan product or the bank that funds it. We are all the support crew for the broker, who should be the only face that the customer remembers from the whole experience. The process of getting the home loan should be forgettable.” MSA
From law firm to fintech MSA National has always been a law firm ahead of its time. Its journey from solely handling legal matters to excelling in fintech began in 1999 when it launched an online portal called LoanTrak that allowed brokers to track their loans online in real time. Its vision was to create an end-to-end white-labelled paperless solution that allowed the customer to sign their documents on 14
www.brokernews.com.au
screen and then settle and fund their loan electronically. It wasn’t until 2016, when Victoria became the first state to accept electronically signed mortgages, that MSA was able to accelerate its
headaches and heartaches caused by two seemingly innocuous tasks: verifying a client’s identity and signing loan documents the old-fashioned pen and paper way. With clients carrying around their
“Change pushes us outside our circle of comfort and into the circle of uncertainty. ... We all ignore change at our business peril” Sam Makhoul, MSA National digital quest and break new ground in transforming the customer experience. NAB and Macquarie were some of the early adopters who wanted to engage and partner with MSA. Brokers are well aware of the many
personal identification documents in hard copy, there are inherent risks. Pieces of paper go missing, documents get signed in the wrong places, and as a result, turnaround times get drawn out. With these challenges in mind,
MSA decided to develop its own suite of digital products that would tackle and eliminate these pain points. Fourteen lenders, including RAMS, Aussie Home Loans and Pepper, and about 37 aggregators and mortgage managers are now using MSA’s digital products, most in conjunction with its documentation and settlement services. With end-to-end mortgage processing centres in each state and no offshore operations, customers have a seamless experience from credit approval through to settlement, with a single, local point of contact throughout, Makhoul says. “We never develop anything from the point of view of protecting the business. We do it because we love and embrace change,” he says. “Every idea comes out of a position of empathy for the customer. We are not in love with our digital products, rather we are in love with what they can deliver to the customer.” IDme VOI app Technology that allows brokers to do things quickly, conveniently and remotely from the road has become increasingly important for business. The same goes for their time-poor customers, many of whom don’t even live in the same city where they’re buying property. Customers used
KEY BUSINESS METRICS
More than
$3BN
Over
250 + staff
15
settlements per month
Established in
SEPTEMBER 1995 MSA has a
CHIEF FITNESS OFFICER
robots across all states
and a full-time
MASSEUSE 14
lenders
37
mortgage managers/aggregators
From left: MSA National founder and managing director Sam Makhoul and CEO Ayhan Baba
to have to line up at Australian Post and pay $44 for each VOI, but not any more. With MSA’s IDme app, brokers can conduct a remote verification of identity of their customer for free. The app has simplified the VOI process, reduced the cost and improved security. Customers can use their smartphone to take photos and upload identification documents, and submit these directly to a lender or to their broker on a secure web platform in minutes. Brokers no longer need to stay up to date with the complex and everchanging VOI regulations because the app updates automatically, Baba says. “It’s paperless and makes the
broker look impressive in front of the customer, and importantly, it is much more secure,” he adds. NewGen Digital Documents With customers now expecting most documents and dealings to be received, transferred and transacted online, it only makes sense for mortgage processing to follow suit. NewGen Digital Docs makes the complete home loan pack paperless, allowing the customer to sign and send back their mortgage documents instantly from anywhere in the world. It means no more paper, lost mail, delays or express-post costs, Makhoul says. With digital signing, MSA has
reduced the risk of errors and incomplete forms, leading to quicker verification and settlements. MSA says it has saved customers about five days on their turnaround times, and in most cases refinances can be settled within two to four days of approval. “We and the broker have complete visibility, which makes it more effective when we do follow-up calls to the customer. This is truly transformative. We have been working with digital signing since October last year, and the impact on the customer experience has been outstanding,” Baba says. MyVideo For the YouTube generation and those with limited attention spans,
delivering news, information and instructions via video has proved to be an effective method for MSA. Its market-first MyVideo product, which delivers customised content to a customer in the form of a video, has shot customer engagement figures through the roof, Baba says. “Customer engagement with email and other text correspondence is down around 15–20%. People just don’t like to read any more. But with video, the engagement skyrockets to 80% and over, which means whatever message we deliver is more likely to be absorbed and understood by the borrower,” he says. MSA found that customers seem to retain the information from video www.brokernews.com.au
15
FE AT URES
From left: Sam Makhoul and Ayhan Baba, MSA National
much better than via text, making them more inclined to sign and return their documents faster. MSA is now in discussion with several lenders about deploying MyVideo, but it will go live first with MyState Bank in late November. Collaboration, not competition While there may be a lot of fintech players vying to enter the space and transform the customer experience, MSA is not too concerned about the competition. “We are not trying to compete with lenders and fintechs, but rather to partner with them to provide a viable outsourcing alternative for the backend settlement process. We want to plug in our back end with their front end. The customer experience today more than ever relies on this close collaboration between the lender and 16
www.brokernews.com.au
its settlement agent,” Makhoul says. Doing away with paper, delays and unnecessary expenses are just some of the benefits of going digital, but Baba says the customer still wants a human
Makhoul and Baba attribute much of the firm’s success to its culture, which emphasises the importance of empathy and humility. “We believe these are two essential
“We are all the support crew for the broker, who should be the only face that the customer remembers from the whole experience” Sam Makhoul, MSA National connection when applying for their loan and coordinating settlement. “It is this blend that will win the hearts of customers and their mortgage brokers. At the end of the day we are still people serving people,” Baba says.
qualities that translate into an outstanding customer experience. We nurture those qualities not by having posters around the place and paying lip service to them. We walk the floor and interact with our team daily and situationally,” Baba says.
Shaking up the space In 2018, MSA will ramp up its robotics automation strategy used internally to increase operational efficiency. This will free up staff from doing repetitive data-driven tasks to focus on deepening their interactions with customers and brokers, Baba says. Enhancing existing client relationships and evolving its products to meet the changing needs of brokers and customers will also continue to be an integral part of MSA’s growth, Makhoul says. “We will always strive to do the simple things really well. Quality documents, zero errors, fast turnaround, quick response times, friendly and obliging service. Without these attributes our digital tools are benign. Our value remains our fast processing powered by people,” he says. AB
www.brokernews.com.au
17
FE AT URES
BUSINESS PROFILE
LEADING THE WAY AS NON-BANK OF THE YEAR Mario Rehayem, Pepper Money’s country CEO for Australia, explains how the non-bank lender grew its footprint this year by boosting its service, support and training of brokers, and how it plans to remain ahead of the pack in 2018
Money’s plan this year was to “make it as easy as possible for brokers to serve their customers”, a focus that clearly paid off with record-setting results for the non-bank lender. Pepper brought in $2.6bn of mortgages during the 2016 calendar year, a 26% increase from the year before, according to its financial results released in April. And brokers deserve some praise: they are currently responsible for 94% of the lender’s originations, a rise of 20% year-on-year. Pepper has come a long way since 2001, when it was a little-known start-up with a quirky name. Now its name is a fixture in the non-bank lending landscape, where it has become a leader in specialist lending in Australia and around the world, with businesses in the UK, Spain, Ireland and elsewhere. On 27 October Pepper’s support of the third party channel was recognised at the Australian Mortgage Awards where it won the Non-Bank of the Year trophy against eight other nominees. “Winning awards like these takes passion, commitment and persistence from everyone. It is an award that each and every employee at Pepper Money has contributed to and can be proud of,” says Pepper Money’s country CEO for Australia, Mario Rehayem. “We’ve worked hard to build a reputation as a company that challenges the accepted and provides brokers with flexible and innovative lending solutions.” PEPPER
What did Pepper achieve in 2017? With its attention set on making business smoother and simpler for brokers and their customers this past 18
www.brokernews.com.au
year, Pepper released its Customer Conversion Toolkit, boosted its professional development training, and launched a mainstream advertising campaign to raise awareness of its products directly with consumers.
broker position a specialist loan with a client, particularly those who are uncertain about using these types of products. Part of that toolkit is the Pepper Product Selector, which provides
“We believe what sets us apart is our overarching mission – to help people succeed. This mission underpins our customer service, strategic direction and company values” Mario Rehayem, Pepper Money The Customer Conversion Toolkit, which it introduced this year, is a set of tools that simplifies the process of determining whether a client is eligible for a specialist loan, and helps the
customers with an indicative offer in less than two minutes. It has been embraced by the broker community, Rehayem says. More than 1,000 brokers are using the tool since it was
launched in June, and many of them are now writing non-conforming loans as a result. Pepper is also heavily invested in educating and supporting brokers’ professional development through a number of initiatives. Its national Insights Roadshow specialist lending masterclass attracted a record attendance of 1,500 brokers across five states, up 50% from last year. It added six new online learning modules to its Better Business Hub, which each come with CPD points upon completion. The concise videos available on the hub website are designed to drive business improvement and assist brokers in better understanding their self-employed clients. Pepper also backs the growth of the third party channel by providing online and face-to-face education programs to new-to-industry brokers, including supporting the MFAA’s New Entrant Program.
SERVICE, SPEED, PRODUCTS: PEPPER’S OFFERINGS
Service levels Applications up by 46% since June 2016 Pepper reviews on average 930 applications/month Over the last 12 months, Pepper has reviewed 14,000 applications. Only 8% of these have been declined
Turnaround times Same-day decision on applications lodged by 1pm AEST, maintained in 80% of cases 95% success rate in meeting the two-hour turnaround SLA for scenario requests
Three products, one form One application form accesses three credit policies attached to a range of home loan products
Some of the Pepper team with their award for Non-Bank of the Year at the Australian Mortgage Awards
What does Pepper have in store for brokers in 2018? While Pepper achieved much in 2017, “we aren’t going to rest on our laurels in 2018”, Rehayem says. “In fact, we are already planning a bigger and better Pepper Money offering for brokers next year. We’ll also act on implementing the feedback we’ve received from brokers around the kind of products and services they want to see from us.” Pepper’s goal is to continue lifting its overall market share by responding quickly to new trends and providing brokers and their customers with the solutions they need on a daily basis, he says. If the takeover bid by global investment firm KKR Credit Advisors proceeds, Rehayem says it’s fair to say that brokers “will see even more from Pepper Money in 2018”. “Pepper, with the support of KKR, will look to provide brokers with some exciting new products and initiatives that help people succeed,” he says. “What won’t change is the same high level of service Pepper Money has provided to brokers over the course of the last 16 years.” One of the changes in the market that isn’t going away, however, is the shifting regulatory environment. Rehayem says the focus for 2018 will be on how quickly brokers and lenders can respond and adapt to these evolving market conditions. “The advice I’m giving is as relevant in 2018 as when I first gave it – Know
Your Customer is critical. The scrutiny around record-keeping and the quality of interview notes brokers keep on their customers is only going to intensify,” he says. Brokers have a duty of care to their customers, and they need to protect themselves, so Rehayem urges them to be diligent in the questions they ask and accurate in how they document customers’ living expenses to better understand the volatility of their incomes. “A broker should be asking these questions regardless of whether the lender is requesting this information or not. Consider getting a recording device for all of your customer interactions,” he suggests. “In addition to this advice, brokers should ensure they partner with a lender that can respond to changing market conditions promptly.” Pepper has positioned itself as a flexible and transparent alternative for those shut out of funding by traditional lenders, and has leveraged customers’ dissatisfaction with the banks. “We believe what sets us apart is our overarching mission – to help people succeed. This mission underpins our customer service, strategic direction and company values. In daily interactions with customers and business partners this translates into an enthusiastic desire to find win-win solutions, a flexible approach and honest communication,” Rehayem says. AB
Mario Rehayem, country CEO for Australia, Pepper Money www.brokernews.com.au
19
PEOPLE
OPINION
THE FINTECHS ARE COMING. ADAPT OR DIE… What will the broking sector look like in the next five years? Who will have the biggest home loan stake? Graeme Salt, a director of the Futurus Group – which oversees a $60m monthly loan book – has a sobering warning for the broking profession
KEY FIGURES
5,021
lawyers, conveyancers and financial institutions engaged with the PEXA network
$77BN
worth of property transacted electronically via PEXA
623,369
property transactions completed by members of the e-conveyancing network
WA and VIC will begin lodging all property transactions electronically in 2018, followed by NSW in 2019
NSW and VIC
now completing all refinances online; SA to follow suit in early 2018
20
industry is on the cusp of radical change – not incremental or step change. Where we once disrupted the might and heft of the big banks, we’re now staring down the barrel of change ourselves. Let me be blunt: it’s a case of adapt or die. The best way to predict the future is to create it now. Don’t wait. OUR
www.brokernews.com.au
When brokers were the disruptors By way of an analogy, when brokers first emerged 30 years ago they were in a sense the ‘fintechs’ – or financial technology outfits – of that era. They were the new disruptors on the block. For those of you who’ve been around for a while, back in the 1980s brokers wore out a lot of shoe leather meeting face-toface with clients. When they returned to the office to finish loan applications, they spent a good chunk of their day using the new-fangled fax machine that retired some of the former pen and paper working ways that saddled our industry with manual processes – the days when Aussie and Wizard had a sizeable market share. Stay with me, Gen Y folks! A fax machine was a past tool of the trade that transferred documents by sending a signal down a telephone line to another receiving machine. Will the new fintechs drive out existing players? A new breed of digital disruptors is once again overhauling our home lending market – leapfrogging the computer era
and catapulting us into the digital age, whether we like it or not. Put simply, those who fail to grasp how to use high-tech smarts to get closer to customers will quickly fail. The fintechs are coming. They’re pushing forward fast and moving well ahead of the regulatory world. They disrupt quickly while legislation is belatedly changed. Much later. So it’s incumbent on us to better educate clients about the benefits ahead of this sea change. Now. Not in one year or 18 months and certainly not in
Worst-case scenario: loans through Amazon or Google A classic example of the picture I’m painting here has been seen in the arrival of UBER. A few short years ago it was just a blip on the radar. When it burst out of the starting blocks onto our roads, no one knew how to deal with it. Fintech aims to be consumer focused. On the one hand we all know that banking is moving into a new world. We know it will be different, but we’re not exactly sure what it will look like. On the other hand, the worst-case scenario is that Amazon or Google will offer loans in the next five years. This is why brokers have to understand that the world has changed, otherwise they’ll be out of business. The good news is that electronic property transactions are now here. Let’s embrace the high-tech expertise this is
We know we can often close home sales faster and more efficiently than banks can. And let’s be honest, broking moved into the fintech space a few years ago now Graeme Salt, director, Futurus Group three or five years’ time. I tell all my mentees who we train through our learning academy to position themselves as trusted advisers – pivoting quickly and nimbly, second-guessing what homebuyers want. This agility has been our silver bullet for capturing about 60% of the total home lending market share to date. Quite simply, we do it better than the banks. Once again, if we get the settings right by getting closer to our customers and embracing the latest tech know-how in the market, we’ll come out on top.
promising. We know we can often close home sales faster and more efficiently than banks can. And let’s be honest, broking moved into the fintech space a few years ago now. But many brokers are nervous and don’t know what it means. One way we can step up to this challenge is by explaining to homebuyers how technology is their best friend. Our customers are already using really cool toys at home with smartphones and tablets. They’re now demanding these high-tech innovations – it’s what they expect. The banks
Graeme Salt, director, Futurus Group
are increasingly realising that customers want more than to settle their properties using relic quill and ink methods that have held this industry back for so long. PEXA soon to hit milestone: $100bn in online transactions If brokers haven’t heard about Property Exchange Australia – or PEXA – they need to quickly get up to speed with this innovation. Let me explain what I mean in the context of refinancing a mortgage. This is relevant as some commentators are forecasting that interest rates will move upwards in the near future, bringing more business our way.
In the past, the simple task of changing lenders took more than a month and involved cumbersome manual paper exchange in the back offices of mortgage lenders. Today, with PEXA, that all happens online, and the time from start to finish has been cut in half. PEXA was launched a few years ago. It was a niche player then as the banks continued to muddle and slog their way through archaic paper transactions. Customers hated the delays that this imposed on them. In the course of the next few months, PEXA will pass its next milestone by transacting a massive $100bn worth of property online.
PEXA is changing the face of broking. It’s already here and can be used – harnessed – to get you closer to your clients. Brokers need to get on board or they’ll be left behind. If you’re a broker and can’t work in a PEXA environment, how will you work with paperless mortgages? Rising interest rates – where we can really make a difference The Futurus group of companies is increasingly seeing its property settlements finalised through PEXA now that the state governments are mandating electronic property transactions. Pin these deadlines on your office
wall or put them in your calendar: In Western Australia, all property transactions will be lodged electronically from May 2018, followed by Victoria in October and NSW in June 2019. Refinances went digital in Victoria and NSW on 1 August this year. My advice is, get to know what PEXA is all about. Get comfortable with it. There’s an app that PEXA offers lawyers and conveyancers called SettleMe, and we’re really excited by it. Through our training company, Walker & Miller, we explain that where brokers can really excel is in explaining to their clients exactly what happens during the settlement phase. I use the example of being a midwife who delivers our clients their dream home. The PEXA SettleMe app makes that happen. It’s a real-time tracking app that puts buyers and sellers in the picture so that they know at each stage exactly what’s happening as properties change hands. In the past when we settled through the banks we heard nothing. But with PEXA the end customer is fully in the picture all the way through the final home sale process. Refinancing is a good note to finish on. Over the course of the next few years that’s where much of the broking business will come from. The commentators and market watchers are forecasting that interest rates will trend upwards in 2018. I predict at least one rise – and possibly two next year. That’s where we can really make a difference with our clients when they come to us asking for a better rate. Get comfortable with the uncomfortable now before it’s too late. AB
Graeme Salt is a director of the Futurus Group, which oversees a $60m monthly loan book through Origin Finance, Walker & Miller Training, Realestate.com.au Home Loans and Chan & Naylor Finance. www.brokernews.com.au
21
PEOPLE
Have an interesting deal? Had a particularly difficult or interesting deal? Why not share it with us? Email:
Otiena.Ellwand@keymedia.com.au
A BIG DEAL
John Manciameli, CEO at Slipstream, on what happened when he started asking his clients the right questions to help them create the lifestyle they never thought possible
$250,000 in profit from the sale. This financial gain helped them realise their dream of buying their first home. They put a big deposit on a brand-new four-bedroom owner-occupied home for circa $700,000 in Shellharbour, south of Wollongong, an area that hadn’t seen capital growth yet. It also allowed them to buy another investment unit in Brisbane. THE TAKEAWAY
Location: Sydney
THE FACTS
My clients were young teachers in their late 20s who were renting an apartment overlooking the Port Hacking River in South Sydney for only $180 a week. Their initial goal was to get onto the property ladder in Sydney as first home owners, but after looking for months they were disillusioned because they couldn’t afford to buy in the location they loved, and the only place they could afford was on the edges of Sydney, far away from family and friends and with a big commute to work.
www.brokernews.com.au
Client Young married couple
Goal To get onto the property ladder
I was the first finance professional to ask them about their property and lifestyle aspirations, rather than just focusing on how much they could borrow
THE SOLUTION
22
Lender St. George
Park (near Parramatta). This property would only cost them $20 per week to hold. Two years later, Harris Park was ranked as one of the fastest-appreciating suburbs in Sydney. Over that time, I kept reassessing their personal situation. As their desire to start a family became more pressing, they
THE SCENARIO
After carefully assessing their financial situation, I introduced them to the concept of ‘rentvesting’; this meant they could continue living where they loved, while investing in another area they could afford. My clients were relieved to learn they had options they hadn’t considered before. I referred my clients to an investment property research house, which presented to them compelling data to invest in Harris
Loan size $490,000
My clients could have gone down the path that most of their friends had travelled: mortgaging themselves to the hilt and struggling to make ends meet, especially when they would be forced to live on one income once they had children. Despite the fact that my clients had met with three other brokers, I was the first finance professional to ask them about their property and lifestyle aspirations, rather than just focusing on how much they could borrow, repayments, etc. For me the moral of this story is that as brokers we need to dig deeper to understand the reason why our clients have come to see us – whether it’s to pay off their home quicker, build wealth, or even retire earlier – and then suggest pathways they can consider. Slipstream has such a good due-diligence process that when I refer my clients to one of the trusted investment property research houses and buyers’ agents that have been vetted, I know that many of the risks associated with investing have been mitigated. I believe in ensuring that my clients benefit from holistic advice, so just as I refer my clients to an accountant, financial planner or solicitor, it feels quite comfortable to refer them to trusted investment property research houses and buyers’ agents as well. My clients are now only 31 years old, and not in their wildest dreams did they think they would be in the position they are in today. The feel-good factor from playing a
John Manciameli CEO, Slipstream
mentioned their aspirations of buying an owner-occupied residence sooner than anticipated in their five-year plan. Through a series of consultations with the investment property research house and myself, my clients were impressed by how much capital growth had been achieved, and they decided to place their Harris Park property on the market. They made
part in helping them achieve their dreams is incredible. Also, from a business perspective, instead of just the one-off fee generated from a simple mortgage transaction I was also able to generate income from the loans on all the properties, as well as the referral fee from the investment properties. Even better, I gained clients for life who continue to send me referrals. Everyone wins. AB
SINTEX NON-BANK LENDER UPDATE
DON’T PUT UP WITH POOR SERVICE AND SLUGGISH TURNAROUND TIMES – THERE ARE BETTER OPTIONS OUT THERE Cathy Dimarchos, general manager of non-bank lender Sintex, explains why brokers are seeking out its products and services over those of the banks More and more brokers are looking at how they can embrace a more holistic approach to lending. They’re keen to look at alternatives if it means they don’t have to tolerate poor service levels or send different loans to different lenders. In recent times, we have seen service levels blow out to 14 days, and in some instances even longer. Professional brokers providing a valuable service to customers need to be asking why timelines are blowing out so much and what their alternative options are. It’s not good enough to tell a customer that their application is sitting in a queue waiting a week to get a conditional approval. Furthermore, it’s not fair on the broker. Why aren’t brokers being told upfront that a deal is not going to work, instead of having to wait for a week or so only to find out that
the lender’s alternative offer would be an option, or prompt the broker to look elsewhere if need be. At Sintex we have a diverse product offering (commercial and residential) and we are seeing the advantages this has for brokers, especially when loans are not crosscollateralised, like the banks typically insist on. Smaller broker groups are quick off the mark to make the change and extend their lending offerings. We are seeing good-quality business being sent to us that would normally go to the banks or other lenders. Brokers don’t seem to face the same types of obstacles that larger companies face; they simply include the product in their product suite, tell their network and referral base that they now offer alternative options, and immediately see the
We are transparent and willing to help, which I suspect is the reason why we are seeing an increase in volumes and accreditations a totally different type of offer has come back? If a lender can’t offer a broker a deal based on the application that was submitted, they should know right off the bat and tell the broker. This would save the broker and their client time, effort and disappointment. It would give the broker the opportunity early on to talk to their customer to discuss if
enquiries come through. It’s a delight to see that brokers are breaking down the barriers and misperceptions that commercial loans are difficult. Take the initiative and talk with the team at Sintex. We are, and always have been, in business for relationships, and this helps us build a great rapport with our network. We are transparent and
Cathy Dimarchos, Sintex
willing to help, which I suspect is the reason why we are seeing an increase in volumes and accreditations. Our niche is small-ticket, non-specialised commercial loans; therefore keeping it simple makes the process for the broker and the consumer easy. We have and always will have quick turnaround times, and this ensures a positive outcome all around.
Tristan O’Bree, our new BDM in NSW, has a ‘can-do’ attitude. He is service-focused and ready to help out in any way he can. He’s breaking down barriers, and as a result we have had brilliant feedback on his service levels. If you have thought about Sintex but haven’t made the change, then don’t stand back. Take a leap of faith – you will be pleasantly surprised.
www.brokernews.com.au
23
PEOPLE
CAUGHT ON CAMERA Specialist lender Bluestone Mortgages marked a milestone occasion at its Billion Dollar Celebration at the Museum of Contemporary Art on 20 November. The lender reached $1bn in settlements since returning to the marketplace in FY14, more than half of which were originated over the past year. The lender attributes this achievement to organic, structured growth that has come from listening to broker feedback on what they want in the self-employed lending space. About 96% of the lender’s loans are brought in through the broker channel. “The performance of the business in the last 12 months has been nothing short of unbelievable,” Royden D’Vaz, head of sales and marketing at Bluestone Mortgages, previously told Australian Broker.
24
www.brokernews.com.au
www.brokernews.com.au
25
DATA
WESTERN AUSTRALIA
VIC SPOTLIGHT
Recovery is at hand for Perth as property values begin to stabilise in many parts of the state
MELBOURNE LEADS THE WAY
Perth’s market is still crippled, but pockets of the state are beginning to return to pre-boom levels. “This marketplace continues to show signs of improvement. Vacancy rates have begun to fall and have remained in the mid-7% bracket for some weeks now, which compares to recent times when they were consistently over 10%,” reports Charles Tarbey, chairman and owner of Century 21 Australasia. “The state economy is also showing signs of growth again, so I remain of the view that WA is an area investors should be looking at very closely.” This development is in line with the WA government’s initiative focusing on job creation in order to rebuild confidence in the state following the mining crash. The government predicts that the economy will bottom out this year, with growth expected to start heading up again in 2018. Area
Type Median value
Unlike Sydney, Melbourne is holding steady due to economic stability and relative affordability, but supply could be a problem
Quarterly
12-month
growth
growth
Perth
H
$500,000
-2.9%
-2.5%
WA Country
H
$330,000
-6.3%
-5.4%
Perth
U
$395,000
-3.7%
-2.1%
WA Country
U
$270,000
-10.4%
-3.4%
SOUTH AUSTRALIA
The Adelaide market exhibits stability in the midst of seesawing activity nationwide The SA economy is still in the process of regaining its footing following the recent downturn of the manufacturing industry. General dwelling values and rental rates continue to fall in Adelaide as employment remains an issue. However, there is confidence that the state will bounce back in the long term. “There are seeds of hope as more defence projects ramp up and other initiatives like the Northern Adelaide food bowl expansion come online,” says Pat Gerace, CEO of the Urban Development Institute of Australia SA. “The make-up of residential housing in Greater Adelaide continues to evolve. There are a number of popular greenfield development areas such as Mount Barker that offer affordable products that are both attractive and unique.” Demand levels are not astronomical in this capital city as population growth remains low. However, property values are still increasing at a modest rate. Area
Type Median value
the pace of Sydney’s growth begins to slow, Melbourne is stepping up as the rock of the two, with a resilient market. “This comes down to affordability, job growth and population growth,” says Jane Slack-Smith, director of Investors Choice Mortgages. “Melbourne has also had first home buyer stamp duty incentives, ie $0 up to $600,000 – like Sydney – and discounts of up to $750,000. The difference is that $600,000 will get a whole lot more value than the same amount will buy in Sydney.” Such incentives have typically helped drive a property market, and this looks to be the case in Victoria. Ballarat and Geelong are other growth areas that could prop the state up should the capital begin to slip – their low prices and considerable returns are certain to bring in investors. Geelong is also benefiting from the commencement of several infrastructure projects – such as the expansion of Deakin University and Geelong Hospital – to support different industries and remove its dependence on the manufacturing and processing sectors. The commute from Geelong to Melbourne has also been improved by the Princes Highway upgrade and the Regional Rail Link project. According to Lindy Lear, general manager of Rocket Property Group, beachside suburbs in the vicinity of Barwon Heads and Ocean Grove offer good value and are an alternative to more expensive pockets like Torquay. “Supply of land is limited in some of these areas, and buyers (and renters) want their properties to be in the best position nearer to special schools, recreation facilities, and new shopping centres planned or under construction, so moving quickly to secure available land and house packages at a good price is crucial,” Lear advises. AB AS
Quarterly
12-month
growth
growth
H
$450,000
0.0%
2.9%
Median price (houses)
SA Country
H
$285,000
-5.0%
1.8%
$329,668
Adelaide
U
$383,750
5.1%
4.3%
SA Country
U
$205,000
14,4%
2.6%
www.brokernews.com.au
Brokers are benefiting from strong price growth in the Melbourne house market In my view, the Melbourne market has performed extremely strongly in recent times in terms of house price growth. This has resulted in strong broker activity from a volume perspective (ie number of new loans/clients) and we expect this to further strengthen for the rest of this year, particularly in the first home buyer segment (<$600,000 price range) following changes to stamp duty concessions. The industry as a whole is also facing some headwinds and challenges that are impacting our clients in relation to key changes in lending frameworks and lender policies. The last year has seen an unprecedented number of changes in banks’ policies and pricing as a direct response to regulatory changes, making the environment more complex than ever and harder to confidently navigate. The key challenge has been a general reduction in lender risk appetite demonstrated by reduced borrowing capacity for clients across the board. Whilst these changes create challenges, they also result in significant opportunities as the role of a broker in educating, guiding and assisting clients towards achieving their goals has never been more relevant or more important. Daniel Hustwaite Principal, Aqua Financial Services
SUBURB TO WATCH: MELTON
Adelaide
26
BROKER PERSPECTIVE
Median price (units) $272,551
Source: CoreLogic
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
17.6%
30.0%
36.7%
4.7%
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
11.7%
12.8%
21.9%
6.1%
AUSTRALIAN CAPITAL TERRITORY
Growth has pushed Canberra’s property prices to just behind those of Sydney and Melbourne
OPPORTUNITIES AND KEY INFRASTRUCTURE
YarraBend
M-City
Lincoln Square
Market greenhouse
Riverside suburb in development 10 minutes from Melbourne CBD
$1bn mixed-use development in Clayton for 4,000 residents, workers and shoppers
City seeks feedback on plan to expand historic square in Carlton
Designs wanted for greenhouse atop Queen Victoria Market pavilion
HIGHEST-YIELD SUBURBS IN VICTORIA Suburb
Type
Median price
Quarterly growth
12-month growth
Inverloch
U
$383,750
7%
28%
Nhill
H
$120,000
-9%
-13%
Warracknabeal
H
$113,000
-10%
-5%
Mortlake
H
$155,750
-4%
9%
Lucknow
H
$205,000
-1%
-9%
Canberra has maintained a trend of consistent growth, which proves why job availability is so crucial to capital city performance. “We have seen steady growth in this market – a key influence is that job security is high, given government employment plays a major role,” explains Charles Tarbey, chairman and owner of Century 21 Australasia. Tarbey believes Canberra’s positive performance is set to continue to the end of the year. However, with the median house price in the city coming in just below the Sydney and Melbourne median, affordability could be an issue for buyers. According to REIA president Malcolm Gunning, Canberra’s median house price increased by 10.2% in the 12 months to June 2017. Most of the demand is in the inner city, where sales volumes are high despite the hefty price tags. Tenants are also jostling for space as vacancies tighten. Area
Type Median value
Quarterly
12-month
growth
growth
Canberra
H
$675,500
0.6%
6.5%
Canberra
U
$427,000
-3.2%
2.2%
www.brokernews.com.au
27
DATA
QUEENSLAND
An improving economy and rising interstate migration rates have put Brisbane in a solid spot
CAPITAL CITY AUCTION CLEARANCE RATES
growth
growth
Brisbane
H
$525,000
0.5%
3.0%
QLD Country
H
$433,850
-1.4%
1.8%
Brisbane
U
$407,500
-0.1%
-2.1%
QLD Country
U
$377,000
-2.1%
4.1%
NEW SOUTH WALES
MEDIAN HOUSE AND UNIT PRICES
The slowdown of the Sydney property market is a long time coming
$1,000,000
Type Median value
70
Not sold
30
Clearance rate
70.0%
PERTH Total auctions
46
Sold
12
Not sold
10
Clearance rate
Sydney Melbourne Brisbane Adelaide
Perth
54.5%
Hobart
$575,000
$300,000
$400,000
$380,500
$0
$499,000
$100,000
$332,500
$200,000
$440,000
$300,000
$522,000
$500,000 $400,000
$728,000
$700,000 $600,000
$720,000
$800,000
Darwin
Units
Canberra
CAPITAL CITY HOME VALUE CHANGES Capital city
Quarterly
12-month
growth
growth
H
$970,000
-3.5%
7.2%
NSW Country
H
$450,000
-2.0%
6.5%
Sydney
U
$733,092
0.3%
3.9%
NSW Country
U
$385,000
2.5%
4.3%
www.brokernews.com.au
Sold
Houses
$945,000
$900,000
Sydney
28
143
$1,100,000
With the median dwelling price in suburbs near Sydney shooting past $1.3m, the easing of property values in the metro is a welcome occurrence. It is already nigh on impossible to find a house priced below $1m less than 25km from the CBD. This high market entry price prevents the discounts on stamp duty for first home buyers (for properties up to $800,000) from facilitating growth as they normally do. “The mid-year APRA-induced lending changes resulted in a large slowdown for investment lending,” says Jane Slack-Smith, director of Investors Choice Mortgages. “Combining this with tougher servicing calculators, reducing the ability to tap into any equity growth, higher interest rates for investors and even higher for interest-only loans and low rental yields, then Sydney should continue to see an easing of price growth.” Area
Total auctions
$430,000
12-month
ADELAIDE
$600,000
Quarterly
$400,000
Type Median value
The combined capital cities saw the number of auctions held reach a new year-to-date high for the week ending 29 October, with a total of 3,690 auctions. This surpassed the previous 2017 high recorded over the week prior to Easter when 3,517 auctions were held. The higher volumes returned a preliminary auction clearance rate of 67.8%, rising from a final clearance rate of 64.7% the previous week, when fewer auctions were held (2,519). The week’s surge in volumes can be attributed to increased activity in Melbourne, currently Australia’s hottest auction market. Volumes across that city reached their highest on record during that week, with 1,983 auctions held recording a preliminary auction clearance rate of 71.7%. Sydney also saw a substantially higher volume of auctions, with 1,196 homes taken to auction, recording a clearance rate of 64.1%. Sydney’s clearance rate had been consistently below 65% since the first week of October. Activity across the remaining auction markets was varied, with Brisbane recording the lowest preliminary clearance rate at 47.1%. Historically, auction volumes have peaked around late November/early December. If this trend holds true this year, new records could be set for auction volumes as the spring season concludes.
$520,000
Area
WEEK ENDING 29 OCTOBER 2017
$395,000
Queensland’s economy is on the up, and it’s inspiring interstate migration as buyers seek to capitalise on the affordable housing and stabilising job market in this region. “The established housing market, townhouses and new land are very strong around Brisbane,” explains Matt Lewison, director at OpenCorp. “There is a shortage of developable land for new housing within 30km of the Brisbane CBD. Still, it’s lots cheaper than Melbourne and Sydney and very strong on the affordability index.” The northern and eastern suburbs are doing very well, with townhouses in close proximity to the CBD recording low vacancies. Thus Lewison expects growth to pick up in this area as residents grow more confident about the state’s economic prospects. The positivity extends into the Brisbane-Gold Coast corridor, where sales levels are boosted by the strength of the Gold Coast’s economy.
Weekly change
Monthly change
Year-to-date change
12-month change
Sydney
-0.1%
-0.4%
4.9%
7.9%
Melbourne
0.2%
0.5%
8.5%
11.1%
Brisbane
0.0%
0.2%
2.3%
2.7%
Adelaide
0.0%
0.0%
2.7%
4.7%
Perth
0.0%
0.0%
-2.4%
-2.6%
0.0%
0.0%
4.9%
7.1%
Combined 5 capitals
*The monthly change is the change over the past 28 days
BRISBANE CANBERRA Total auctions
128
Sold
84
Not sold
25
Clearance rate
Total auctions
188
Sold
56
Not sold
63
Clearance rate
47.1%
77.1%
SYDNEY Total auctions
1,196
Sold
568
Not sold
318
Clearance rate
64.1%
TASMANIA
MELBOURNE Total auctions
1,983
Total auctions
6
Sold
1,201
Sold
3
Not sold
2
Not sold Clearance rate
475
Clearance rate
71.7%
TASMANIA
Area
Tasmania remains popular with investors, but developers may be overestimating its appeal to tenants Tasmania continues to attract both investors and first home buyers as it is still one of Australia’s most inexpensive property markets. In particular, Hobart is a big draw because of its current strong economy. “Tasmania is hot at the moment in the eyes of the country, highlighted by the strong capital growth and rent returns on offer,” says Josh Hart, director at One Agency Launceston. With quality accommodation being scarce in both Hobart and Launceston, this could be a great opportunity for investors to buy property to rent out to holidaymakers and take advantage of the booming tourism industry. “You just need to look online on Airbnb or Stayz to appreciate the great returns and nightly stay rates,” Hart points out.
60.0%
Type
Median value
Quarterly growth
12-month growth
Hobart
H
$380,000
-2.6%
6.2%
TAS Country
H
$268,000
0.4%
1.4%
Hobart
U
$285,500
-9.7%
1.5%
TAS Country
U
$233,000
-6.4%
4.2%
All data sourced from CoreLogic.com.au
www.brokernews.com.au
29
PEOPLE
IN THE HOT SEAT Dan Fox, managing director of Fox Finance Group, talks about his company’s diversification strategy, future challenges for brokers, and the comedy cruise he’s hosting for 22 of his staff and partners
Who or what inspired you to become a broker? Working for several lenders in the early part of my career A taught me an enormous amount about credit, but it also caused much frustration. Many times I was unable to help some of my good clients as I only had access to one lender’s products, which did not suit all customers. It was this frustration that drove me to establish Fox Finance Group and become a broker in 2006. Now I have access to many lenders’ products, and in general I can help more clients now.
Q
What’s been your experience of diversifying your business? The Fox Finance Group business is very well diversified A now, with the following business units: Fox Car Loans, Fox Home Loans, Fox Business Loans and Fox Wealth Solutions. What I have learnt in the last 11 years is that one man alone can’t do it all. By partnering with like-minded finance professionals I have been able to achieve a high level of success in our diversification strategy. Separate to the Fox Finance Group I am also a director of a boutique subprime auto lender, UmeLoans.com.au. Our lending business is very complementary to our broking business and allows us to help more clients than just the products offered by traditional lenders.
Q
What do you think will be some of the big challenges for brokers next year? The two main challenges I see in 2018 for brokers are the A speed at which we can meet clients’ ever-increasing expectations, and the continuous increase in compliance obligations. We are working with some amazing IT people who are helping us meet these challenges and stay ahead of the competition.
Q
What’s one upcoming activity/vacation/event you’re looking forward to? At the end of each year, I take our staff and partners for an A annual Christmas party and conference. In the past, we’ve gone to Phuket, Las Vegas and the Gold Coast. This year it’s a three-night P&O Comedy Cruise. Twenty-two staff and their partners are coming, and I’m sure it’s going to be a blast! AB
Q
30
www.brokernews.com.au
www.brokernews.com.au
31
32
www.brokernews.com.au