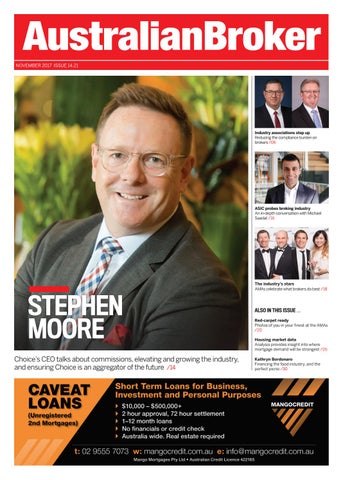
NOVEMBER 2017 ISSUE 14.21
Industry associations step up Reducing the compliance burden on brokers /06
ASIC probes broking industry An in-depth conversation with Michael Saadat /16
STEPHEN MOORE Choice’s CEO talks about commissions, elevating and growing the industry, and ensuring Choice is an aggregator of the future /14
The industry’s stars AMAs celebrate what brokers do best /18
ALSO IN THIS ISSUE … Red-carpet ready Photos of you in your finest at the AMAs /20 Housing market data Analysis provides insight into where mortgage demand will be strongest /26 Kathryn Bordonaro Financing the food industry, and the perfect picnic /30
NEWS
IN THIS SECTION
Lenders Mortgage Choice boss disputes ASIC’s IO findings /04
Associations Reducing compliance burden on brokers /06
Technology Partnership makes funding for SMEs quick and easy /10
Regulators ASIC requires $9m to regulate credit intermediaries /12
Consumers Adult industry decries banks’ prudish lending standards /08
www.brokernews.com.au NOVEMBER 2O17 EDITORIAL Editor Otiena Ellwand News Editor Miklos Bolza Production Editor Roslyn Meredith
DATES TO WATCH
Upcoming can’t-miss events
ART & PRODUCTION Designer Martin Cosme Production Manager Alicia Chin
5 NOVEMBER
14-15 NOVEMBER
15-16 NOVEMBER
Gong MS Ride
Millennial 20/20 Sydney
BOSS Leadership Summit
Pepper Money is inviting brokers to join its team ride for charity from Sydney to Wollongong on a 58km or 90km course
This global summit – in Sydney for the first time – will bring together millennial experts from across the finance, innovation and e-commerce spaces. Executives from Westpac, CBA, Lendi and BrickX will be in attendance
At this Sydney event, the CEOs of the ABA, NAB and Suncorp will give their expert perspectives on transformation, adaptation and the qualities required of future leaders
Traffic Coordinator Freya Demegilio
SALES & MARKETING Sales Manager Simon Kerslake Account Manager Rajan Khatak Marketing and Communications Manager Lisa Narroway
CORPORATE Chief Executive Officer Mike Shipley Chief Operating Officer George Walmsley Managing Director Justin Kennedy Publisher Simon Kerslake Chief Information Officer Colin Chan Human Resources Manager Julia Bookallil
EDITORIAL ENQUIRIES
Otiena Ellwand +61 2 8437 4792 Otiena.Ellwand@keymedia.com.au
SUBSCRIPTION ENQUIRIES
tel: +61 2 8O11 4992 fax: +61 2 9439 4599 subscriptions@keymedia.com.au
16-30 NOVEMBER
24 NOVEMBER
24 NOVEMBER
FAST PD Days
FBAA National Industry Conference
MFAA WA Golf and Sundowner
This year’s conference on the Gold Coast will equip brokers and other industry members with useful knowledge and practical strategies to help them succeed in an increasingly challenging market
Head to the green instead of the office and enjoy a day of golf and networking with industry colleagues at the Wembley Golf Course outside Perth, or come for the views and a buffet BBQ as the sun sets
FAST is hosting five PD Days across the country throughout November. The events will include a business and industry update, growth and networking opportunities, and business strategy insights
ADVERTISING ENQUIRIES
Simon Kerslake +61 2 8437 4786 simon.kerslake@keymedia.com.au Rajan Khatak +61 2 8437 4772 rajan.khatak@keymedia.com.au Key Media Pty Ltd Regional head office, Level 1O, 1–9 Chandos St, St Leonards, NSW 2065, Australia tel: +61 2 8437 4700 fax: +61 2 9439 4599 www.keymedia.com Offices in Sydney, Auckland, Denver, London, Toronto, Manila, Singapore, Bengaluru
28 NOVEMBER Webinar on using digital to improve efficiency In this MFAA webinar, ANZ explores what tools it offers to help brokers and customers grow their businesses and transact with the bank digitally to improve efficiency
2
www.brokernews.com.au
1 DECEMBER
1 DECEMBER
Bowling with the FBAA
Anti-Money Laundering Conference, Sydney
Escape the humdrum of the office and take to the bowling lanes to settle your scores. The FBAA is bringing the fun to Victoria, so start handpicking your team
The program will explore the systems and processes that need to be in place for organisations to better understand their customers and the volume of data they are managing in today’s heightened climate of risk
This magazine is printed on paper produced from 1OO% sustainable forestry, grown and managed specifically for the paper pulp industry Copyright is reserved throughout. No part of this publication can be reproduced in whole or part without the express permission of the editor. Contributions are invited, but copies of work should be kept, as Australian Broker magazine can accept no responsibility for loss. Australian Broker is the most-often read industry publication, according to independent research carried out by the Ehrenberg-Bass Institute for Marketing Science at the University of South Australia in December 2008. The research also found that brokers rate Australian Broker as the best for both news content and feature articles, followed by sister publication MPA. Overall, on all categories, Australian Broker ranks top followed by MPA. The results were based on a sample of 405 respondents who were the subject of telephone interviews.
NEWS
LENDERS BOQ BROKER NETWORK EXPANDS TO OVER 7,500
INVESTOR HOUSING LOAN APPROVALS TRENDING DOWNWARDS Source: ABS, APRA, RBA
Share of total loan approvals by state, excludes refinancing* %
numbers at the Bank of Queensland have expanded as the lender enhances its loan products and develops its Virgin Money offerings. BOQ’s latest half-yearly financial results show that more than 7,500 accredited brokers are distributing the bank’s loan products, including those of Virgin Money. In the second half of FY17, 28% of all mortgage settlements for the group originated through intermediary channels. Most of its accredited brokers are located outside of the bank’s Queensland home base. BROKER
John Flavell CEO, Mortgage Choice
4
www.brokernews.com.au
40
40
20
20
% QLD
WA
40
40
20
20
0
0 2007
TEACHERS
“Our brokers aren’t going to put customers in a particular product for the sake of it. They will make sure it’s the right product for them.”
VIC
%
NON-MAJOR GROWS BROKER LOANS BY $400M Mutual Bank has grown its third party originated loans by $400m year-on-year in an upward trend it associates with a multibrand strategy and expanding national footprint. Teachers funded $674m in broker loans in FY17, up from around $247m in FY16. As well as growing the business across TMB and its subsidiaries, Firefighters Mutual Bank and UniBank, the bank has added new offices in Queensland and WA. At the end of June, it had around 2,800 brokers writing its loans.
% NSW
2012
2017
2007
2012
*Seasonally adjusted three-month moving average; investor refinancing based on RBA estimates
MORTGAGE CHOICE BOSS CHALLENGES ASIC’S INTEREST-ONLY FINDINGS The CEO of Mortgage Choice has rejected claims that brokers are bringing in higher volumes of interest-only loans recent update on an ongoing review by ASIC has found that mortgage brokers are more likely than lenders to recommend interestonly loans to borrowers, a finding that the head of Mortgage Choice has shot down based on the major franchise’s own figures. CEO John Flavell said its data showed the opposite – that brokers are now writing fewer interest-only loans. The proportion of interest-only loans written by brokers within the franchise dropped from almost 36% in May to just over 14.5% in September, Flavell told the Australian Financial Review. “Our brokers aren’t going to put customers in a particular product for the sake of it. They will make A
sure it’s the right product for them.” Mortgage Choice brokers currently write one in every 20 residential mortgages in Australia. In an interview with Australian Broker, Flavell said interest-only loans were “absolutely not” the disaster portrayed in recent research and media reports. “There are many reasons why owner-occupiers and/or investors may choose to have an interest-only product,” he said. For instance, an owner-occupier may use an interestonly loan to free up some cash flow when renovating their home. Flavell said both APRA and ASIC wanted borrowers to show good reason for choosing an interest-only product, which was indeed fair. Regarding ASIC’s recent IO
claims, Flavell said he didn’t believe the regulator’s data was wrong, but he refrained from commenting on what was happening at a national level across the market. Instead he pointed to figures drawn from the franchise itself. “From our own data we can see that the proportion of interest-only loans written by our mortgage brokers each month has dropped considerably since April 2017.” This drop has been driven by rate increases on these IO products, he said. “As such, for some investors and owner-occupiers, an interest-only loan no longer represents the best solution for their needs.” Australia’s major banks have cut back their interest-only lending by $4.5bn over the past year; however, other lenders have partially offset this decline by increasing their share of interest-only lending, ASIC found. The 16 lenders reviewed provided $14.3bn in interest-only loans to owner-occupiers in the June 2017 quarter, down from $19bn in the September 2015 quarter.
NEWS
A S S O C I AT I O N S FBAA CALLS FOR BROKERS TO BE PROACTIVE the current official cash rate remains steady, brokers should be taking this time to explain and prepare their clients for future changes, suggests FBAA executive director Peter White. “One of the best things people can do is ensure the interest rate structure on their loan is suitable for their future, and that’s where brokers can help.” Brokers can advise borrowers and assist with their short- or medium-term plans to see whether a fixed or variable rate is most suitable, he said. WHILE
ABA SELECTS NEXT MAJOR BANK CHAIR CEO Shayne Elliott has been appointed the new chair of the ABA and will officially begin his term in December. The chair position rotates between the CEOs of the major banks. Elliott will succeed the current chair, NAB CEO Andrew Thorburn. “While we have made significant improvements in recent times, rebuilding community trust is a long-term issue, and change within the industry needs to be bolder and faster,” Elliott said. ANZ
INDUSTRY ASSOCIATIONS AIM TO REDUCE COMPLIANCE BURDEN ON BROKERS The FBAA and MFAA have a number of initiatives on the go to help brokers through increasingly complex regulation the FBAA and the MFAA
BOTH have responded to
increased regulatory oversight by providing brokers with a number of tools and support strategies to reduce their compliance workload. The FBAA is planning to launch a new webinar series in early 2018 focused on regulatory change and upheaval. It will initially focus on where the ASIC broker remuneration review is at once the Combined Industry Forum sends its completed industry paper to the Treasury later this year. Other topics may also include ASIC’s review of add-on insurance in the motor sector. “We’re working with industry on PD days, seminars, and so on. The webinar series will further expand
6
www.brokernews.com.au
on this style of content to prepare people to be able to deal with any potential regulatory change and engage in direct interaction to get their feedback on what’s going on and where the hurt factors may be,” FBAA executive director Peter White told Australian Broker. White stressed, however, that the added regulatory pressure was actually a good thing, despite the perception that it hurt brokers as small businesses. To avoid outside scrutiny and attacks, he said the industry needed to be at the top of its game by meeting all compliance obligations. “As small business owners, it’s not easy at all, but if you’re going to be in this space, this is what you’ve got to be prepared to deal with.”
The MFAA assists brokers by providing advocacy, education and tools, and continually consulting with industry to seek improvements, says CEO Mike Felton. Once regulations are in place the MFAA shifts its focus from advocacy to education, using its e-newsletters and website to communicate with brokers and ensure they understand their changed obligations. The MFAA also provides easy access to tools and information on current industry best practice, highlighting key aspects of legislation and aiming to ensuring responsible lending practices. It recently updated its preliminary credit assessment tool, and other resources on verification and disclosure. It also consults with members through the compliance and regulatory forum, other national forums, and broker regulatory roundtables held in six locations two to three times a year, to get coalface feedback on solutions and improvements.
“I have confidence that the vast majority of our brokers are doing the right thing by customers – indeed, all the available data supports this.” Mike Felton CEO, MFAA
NEWS
CONSUMERS INAPPROPRIATE FINANCE MOST COMMON COMPLAINT most common consumer complaint against brokers relates to inappropriate finance and responsible lending, the latest Credit Industry Ombudsman (CIO) Annual Report on Operations has found. About 360 complaints were received about brokers and aggregators in the 2016/17 financial year, accounting for only 6.1% of almost 5,900 total complaints brought to the CIO. While the CIO didn’t say how many member brokers it had, it reported that its total membership had grown from 23,000 in 2015/16 to just over 24,800 in 2016/17. THE
EQUITY ISSUES FOR 345,000 MORTGAGE HOLDERS 345,000 (or 8%) of mortgage holders have little to no real equity in their homes, representing a “considerable risk” to the housing market, Roy Morgan’s Single Source Survey has found. Reasons could include borrowers maintaining debt for other purposes instead of paying off their mortgages; and the use of interest-only loans. “If home-loan rates rise, the problem would be likely to worsen as repayments would increase and home prices decline, with the potential to lower equity even further,” said Norman Morris of Roy Morgan. AROUND
“Our systemic issues investigations led to refunds or compensation of about $180,000 being paid to consumers.” Raj Venga Ombudsman, CIO
ADULT INDUSTRY DECRIES BANKS’ PRUDISH LENDING STANDARDS The industry association claims the banks discriminate against adult businesses, making it difficult for them to obtain finance and non-major banks are refusing finance to those in the adult industry, according to a new report by the industry’s national body, the Eros Association. The Financial Discrimination Against Adults-only Businesses report contains survey results from 24 adults-only businesses, including retailers, wholesalers and entertainment providers. “Findings of Eros’s survey reflect a long trend of industry based discrimination against adults-only businesses in Australia,” the report said. It noted “the prevalence of industry-based discrimination by financial service providers, in MAJOR
particular the rejection of financial services, such as merchant facilities and business loans, to adults-only businesses”. Sixteen of the 24 research participants claimed recent discrimination by one of the big four banks, while four cited discrimination by a non-major. Fifteen said they were rejected for merchant services, five for a business loan, one for a business debit card, one for a mortgage in relation to freehold property, and one for a personal loan. Twenty-three applications were direct to bank, while one was through a broker. Reasons given for the alleged discrimination included that the
client was part of the adult industry (14); that adult products had a high risk of chargebacks or fraud (three); and ethical/moral reasons (two). A CBA spokesperson said the bank actively considered “the environmental, social and economic impacts of our clients’ activities, and we only lend to businesses and projects where we understand and believe those risks are well mitigated”. Westpac said it assessed all applications for loans and merchant facilities on a case-by-case basis for the adult entertainment industry. “However, we do not provide facilities, including merchant facilities, to customers known to be operating brothels,” a spokesperson said. As part of its due diligence processes, a NAB spokesperson said the bank reviewed all customer applications for banking services on a case-by-case basis.
VV$40,614,829,064 CIO’S TOP 5 MOST COMMON COMPLAINTS AGAINST BROKERS AND AGGREGATORS
8
14.9%
11.5%
10.9%
9.3%
8.4%
Inappropriate finance, including responsible lending
Failure to act with due skill, care and diligence
Misrepresentation/misleading conduct
Complaint about credit provider’s fee or interest rate
Failure to follow instructions
www.brokernews.com.au
NEWS
TECHNOLOGY
WESTPAC INTRODUCES NEW VALUATION TOOL is offering a new property valuation tool for brokers that will “automatically select the most effective valuation pathway for each loan application process”, explains a broker note from 9 October. The tool is expected to produce a smarter, more efficient and more streamlined outcome for clients by helping brokers determine, in seconds, which valuation strategies may apply to a property, the bank said. WESTPAC
PARTNERSHIP TO PROVIDE SMES WITH QUICK AND EASY FUNDING The agreement will open up new lending options to more than 1,000 small businesses through a digital retail platform
lender Prospa has partnered with retail marketplace MyDeal to bring new lending options to small business owners. More than 1,000 businesses will now be able to access up to $250,000 worth of finance under the newly created MyDeal Marketplace Loans, with some able to receive funds within 24 hours. Matt Bauld, Prospa’s general manager of sales and business development, told Australian Broker that the lender was always seeking new ways to help small business owners access finance. “One of the reasons we’ve grown as quickly as we have is that early on we recognised the value of working with partners,” he said. FINTECH
Prospa now has more than 4,000 trusted referrers, including brokers, aggregators such as AFG, Connective and Finsure, and industry associations such as the MFAA. The lender also works with brands such as Westpac, NMRA Insurance and Xero. “The common element to all these relationships is helping more small business owners to access finance quickly and easily, whenever they need it,” Bauld said. Although MyDeal has traditionally acted to promote greater volumes of sales for its member businesses, its main mission has been to help these retailers succeed online, said Sean Senvirtne, CEO of MyDeal.com.au. “We are always looking for new ways to accelerate the growth of our retailers. [By] providing additional
support we believe this will enhance the experience for retailers who choose to list with MyDeal Marketplace.” Despite the new agreement between Prospa and MyDeal, it will be business as usual for referral partners such as brokers, Bauld said. “When they refer their small business clients to Prospa directly we’ll give those customers fast, easy access to finance and an amazing customer experience. Our partners will get happy customers, access to our marketing and education platform, and the potential for ongoing revenue.” This new partnership comes after five years of strong growth for Prospa. “For all that time, we’ve been advocating to brokers that they should consider diversifying to meet the growing demand from small business owners,” Bauld said. An increase in the number of brokers offering commercial finance has benefited small businesses as it’s led to more money being invested in their growth.
AUSTRALIA’S CHANGING HOME OWNERSHIP TRENDS Source: ABS, Australia’s Welfare 2017 report
Owner with a mortgage
Owner without a mortgage
50% State/territory housing authority
Private landlord
40% 30% 20% 10% 0% 1994–1995
2013–2014
Note: Excludes ‘Renter-other landlord type’ and ‘Other tenure type’, which were steady at around 1.5% and 2.5% respectively.
10
www.brokernews.com.au
REGIONAL LENDER UNVEILS BROKER PRICING TOOL has launched a new pricing tool that allows brokers to receive real-time responses when requesting personalised home loan rates for clients. It uses a structured approach to pricing approvals. While standard decisions will be automated, more complicated ones will be sent to a Bankwest business development manager instead. The tool, which is available on the bank’s Home Lending Portal, has been created through broker feedback and rolled out across Bankwest’s third party network. BANKWEST
NEWS
R E G U L AT O R S
RATE HIKES INDICATIVE OF COMPETITION ISSUES: ASIC Sims, chairman of the Australian Competition and Consumer Commission, has expressed concerns about action taken by the banks in relation to regulatory changes. Sims said interest rate hikes by the banks in response to APRA’s restrictions “reaffirmed” its concerns about competition in the sector. The ACCC has been tasked with inquiring into residential mortgage products, in particular price changes or proposed changes by the banks in response to the major bank levy. ROD
ASIC REQUIRES $9M TO REGULATE CREDIT INTERMEDIARIES The regulator has laid out its estimates of how much it will need to recuperate through the impending cost recovery scheme
has estimated it will cost just over $9m to regulate the country’s credit intermediaries during the 2017/18 financial year. The regulator released a report on 6 October, Cost Recovery Implementation Statement: Levies for ASIC industry funding (2017–18), which examined the total budgeted costs for basic enforcement and what would need to be recovered from each industry sector. The $9m in estimated costs for credit intermediaries consists of $2.7m for enforcement, $1.4m for property and corporate services, $1m for surveillance, $1m for IT support, and a host of other, smaller costs. ASIC reports that there are 4,861 credit intermediaries in ASIC
GOVT APPOINTS NEW ASIC CHAIR Shipton will replace Greg Medcraft as the chair of ASIC on 1 February 2018 for a five-year term. Shipton is currently the executive director of the Program on International Financial Systems at Harvard Law School, and previously worked as executive director, intermediaries supervision and licensing division, at the Hong Kong Securities and Futures Commission. Prior to that, he held various roles in investment banking in Asia and Europe and was a solicitor in Australia. JAMES
12
www.brokernews.com.au
Australia, including 36,149 credit representatives. “In 2017–18, we will continue our work promoting responsible lending practices and appropriate responses to financial hardship in the credit industry. We will continue to focus on the risk of loan payment stress resulting from inappropriate lending and changing economic conditions, with a particular focus on nonlender gatekeepers and high-risk products (ie small amount credit contracts and consumer leases),” the regulator said. This includes follow-up work with lenders regarding interest-only loans, a review of loan fraud in the Australian home loan market, and an investigation into responsible
lending compliance arrangements for large finance brokers and lenders dealing heavily in interestonly loans. ASIC did not release any new figures on exactly how much the levy would be for credit intermediaries, instead repeating its earlier statements describing a minimum levy of $1,000 and a graduated levy that will be based on the number of authorised credit representatives the entity has at the end of the financial year. Levies will be cumulative for firms that act in multiple roles as credit providers, intermediaries and small-amount lenders, ASIC said. “If a credit licensee holds authorisations as a credit provider and a credit intermediary and provides both small amount credit contracts and regular loans, they are required to pay the levy applicable for all three subsectors. Each graduated levy is calculated separately and only relates to the licensee’s involvement in that activity or subsector.”
AUSTRALIANS STRUGGLING TO MEET MONTHLY HOME LOAN REPAYMENTS Source: iSelect Home Loans
33%
25%
26%
54%
13%
of households have had their interest rate increase during the last year, despite the RBA keeping the official cash rate on hold for the past 12 months
of Australian mortgage holders say they are currently struggling to meet their monthly loan repayments
or over 700,000 say they would struggle to some extent to make their loan repayments if their interest rate was to increase by 1%
of mortgage holders are paying an interest rate of 4% or over
of mortgage holders are paying an interest rate of over 5%
TECHNOLOGY UPDATE
HOME OWNERSHIP RATES DECLINING Source: ABS Australia’s Welfare 2017 report
Age group
25–34
35–44
45–54
55–64
65+
All
0
20% 1988–1989
40%
60%
2000–2001
80%
100%
2013–2014
GOVT ‘ENCOURAGED’ BY RESPONSE TO BROKER REVIEW government has praised the banking and broking industries for coming together to tackle ASIC’s broker remuneration review. Minister for Small Business Michael McCormack backed recommendations made by ASIC that urged industry rather than government to act on its six proposals. “I agreed with that approach – and I’ve been encouraged by what’s been happening since,” he said in an address on 12 October. The joint industry forum includes representatives from the MFAA, the FBAA and the ABA. “That was an important step forward – and a welcome one – and this response will be taken into account when the government finalises its response to the review,” he said. THE
DIGITISING COMMERCIAL LOANS: LEADING LENDERS MAKE THE SHIFT Electronic lodgement of commercial loan applications is on track to become the industry norm in the future, forecasts NextGen.Net sales director Tony Carn. “It’s inevitable,” he maintains. “We’re in a transition period, with some people still saying commercial loans are too complex to digitise. But that attitude is changing fast. In some respects we’re where we were 14 years ago with residential mortgages, with the early adopters benefiting from being forward-thinking. “The industry began moving into the 21st century when NextGen.Net deployed the first digital residential mortgage in 2004. Today close to 100% of residential mortgages are written digitally.” Carn anticipates a transformation in the commercial lending space that will witness a significant decline in the traditional paper-based application and thereby “drag commercial loans into the digital age”. “Lenders are recognising that if they want to build scalable platforms to write serious volumes of commercial loans they need to do so electronically,” he says. “Otherwise they’ll have to engage additional staff and prepare for a lot of extra paperwork, because diversification is happening in the broker sector and commercial loans need to have traceability, clear communication and auditability. As the demographic of brokers is evolving, they too are demanding digitised solutions.” NAB is the first big four bank to utilise electronic lodgement for business finance products, demonstrating its commitment to the broker channel to offer business finance products of the same quality and in the same streamlined way as residential loans. NAB is in the process of implementing a NextGen.Net ApplyOnline electronic lodgement solution to enable distribution of business finance to the broker market. The ApplyOnline Commercial LIM will enable NAB to open up more opportunities and leverage brokers in the commercial space. “Hats off to NAB,” Carn declares. “They’re the first to deliver a comprehensive digital commercial loan solution in the lending space. “They’ve built the infrastructure and framework around accommodating commercial loans for brokers and delivering better turnaround times,
Tony Carn
reducing reworks and providing greater visibility and tracking, and backchannel messaging.” ApplyOnline provides lenders and brokers with ‘plug and play’ distribution into the broker market for an increasing number of product types. Once built into ApplyOnline, it can seamlessly plug any product into any broker. “That provides brokers ready access to electronic lodgement of commercial loans without lenders needing to invest millions of dollars in development, new platforms and bespoke mechanisms that cater to their individual policy requirements and different broker groups. A standardised approach will ensure commercial loan applications are as uniform as conceivably possible,” Carn says. “Plus full credit to Suncorp,” he adds. “They were the trailblazers in this space with the electronic lodgement of small business loan products; likewise ANZ in adopting electronic lodgement for asset finance. “Broker diversification is increasingly on the agenda. Electronic lodgement of commercial loans is making it a lot easier and more efficient for brokers, and therefore commercial lending is becoming far more accessible.”
FE AT URES
SPECIAL REPORT
THERE’S NO STOPPING CHOICE Stephen Moore could boast about his victories as the longest-serving CEO of Choice Aggregation Services, which marks its 20th anniversary this year, but instead he’s focusing on improving the industry, ensuring its long-term growth and sustainability, and positioning Choice as an aggregator of the future KEY BUSINESS METRICS
$65BN
20
Total loan book
Years in business
$17.5BN
Settlements in 2017 – up 8% since 2016
1,600
Brokers in the network – up by 400 since 2016
1 in 4
Brokers in the network writing commercial loans
AWARD-WINNING No. 1 on MPA Brokers on Aggregators list
NPS +40 High broker satisfaction
14
84%
High staff engagement score
www.brokernews.com.au
Moore has a lot to celebrate this year. The aggregator he’s been leading for the last seven years, Choice Aggregation Services, marks its 20th anniversary in 2017 with a $65bn loan book, 1,600 brokers in its network, and a net promoter score of +40. It was also voted top aggregator by brokers in Australian Broker’s sister publication MPA, an accolade that has thrilled Moore. It’s been a rewarding year, but the boss is not about to take it easy. Choice’s focus on and commitment to supporting brokers now and into the future is unwavering, he says. The year ahead is about nurturing the ongoing expansion of the broker proposition, especially in commercial lending; securing fair and equitable commission structures; lifting the bar on quality in the industry, and assisting brokers with compliance tasks; and increasing the efficient use of digital platforms. “The role of aggregators and partnering with the right aggregator has never been more important,” Moore says. Aggregators have moved far beyond being just basic providers of software and access to lenders, he explains. They must understand the different stages of development and different needs of each broker’s business and align themselves to becoming a broker’s “true business partner”. “The aggregator of the future is about understanding those differences and then tailoring support specifically to each individual’s needs; that’s certainly something we pride ourselves on at Choice,” he says. Moore is proud to recognise Choice’s milestones, but he’s also STEPHEN
not about to declare victory. “My philosophy about business is there is never victory. There are wins along the way that give indications as to whether you’re on the right track or not, but in the changing marketplace that we’re in, you absolutely need to continue to evolve what you do, and it is something that we are very focused on.” Market takeover Moore expects brokers’ market share to expand beyond 60% in the coming years. Commercial lending will be a key part of that, and will likely match
opportunities. Choice has developed a commercial lending module to introduce brokers to this type of lending. It teaches them how to work through the technicalities of these deals, identify and source commercial opportunities, and develop a marketing approach. Another area of potential growth for broker businesses is through the integration of complementary practices across the wealth and property industries, such as financial planning, accounting and consulting. Supporting commissions For the first time since the release of ASIC’s remuneration review and NAB’s submission to the Treasury, which covered the views of its three aggregators, including Choice, Moore expresses his opinion on brokers’ commission structure. “Commissions are fair and equitable, commissions are sustainable, and commissions are the
“We are fairly and squarely an aggregator first, and that is our primary responsibility, to support brokers in growing more successful businesses. That’s what has driven Choice” Stephen Moore, CEO, Choice Aggregation Services the growth that has been experienced in the residential space, especially when considering that 30% of the customers of Choice’s brokers are self-employed. “There is a natural synergy between looking after someone’s personal lending needs and extending that into ensuring their business needs are also looked after,” Moore says. In the last quarter, 25% of Choice’s brokers wrote a commercial loan, something Moore would like to see increase to 30% this coming year. The next step is providing brokers with the education to seize these
most affordable way for Australians to get credit advice, and for that reason we are absolutely supportive of commission and commission structures in the Australian landscape,” he says. Moore says he also sees the importance of having both an upfront and trail payment for the ongoing service and support brokers provide clients. NAB’s submission to the Treasury on ASIC’s review proposed changing upfront commission by paying it based on the amount drawn down by the customer, not the total facility amount, and paying upfront net
In partnership with
Stephen Moore, CEO, Choice Aggregation Services
of offset account balances. In regard to this, Moore says it’s fair and equitable that “brokers get paid when lenders earn”. “If the loan is not drawn down, a lender doesn’t make any money. Once a loan is drawn down, they do, and therefore a broker should,” he says. Lifting the bar In a market that continues to evolve, the status quo is not an option. Lifting the bar is the responsibility of brokers, lenders and aggregators, Moore says. “Compliance is not in fact about competitive advantage; compliance is about necessity, and it makes
complete sense to lift that bar when it comes to quality as an industry, so that’s something we’re absolutely committed to,” he says. That means improving and streamlining business processes to make sure everything is done at a high-quality level, from documentation and staff management to marketing and referrer management and outsourcing non-core activities – and, most importantly, retaining and providing a high-quality customer experience, Moore says. The Combined Industry Forum is working on closing some of the gaps in standards across the industry when it comes to best practice, he says.
“If we can agree on benchmark standards that apply consistency in processes, it benefits all participants, brokers, aggregators, lenders. Consistency of process and efficiency is ultimately a better outcome for consumers.” One thing that can’t be ignored, however, is that quality comes at a cost. “The challenge of course is to implement in the most cost-effective way, acknowledging that there is cost in effort but there is upside, and the upside is, with increasing confidence from consumers in the broker proposition, in turn comes further business growth.”
Digital and face-to-face Digital channels can enable business, and brokers shouldn’t back away from embracing technology, but Moore doesn’t see digital replacing high-quality face-to-face advice. The future is about how the two will complement one another. That was the thinking behind the new business with REA, which is now up and running under the realestate.com.au Home Loans brand. About 120 former Choice Home Loans brokers decided to join the new business, while 60 decided to opt out but still stay under the Choice Aggregation umbrella. Moore says it was up to each individual business to make the decision, and some decided that they already had enough self-generating business and referrals to go at it alone. The lead allocation system works as it did in the past to ensure an equitable distribution to brokers in the network. Customers will interact with the REA website, and if they decide they want to speak to someone face-to-face they can reach out to the contact centre and be referred to one of the realestate.com.au Home Loans brokers, who will continue to have access to their same panel of lenders. Choice is continuing to actively seek out opportunities to align either directly or in a preferred-provider capacity with a number of digital businesses, from those that might create new client opportunities to those that provide technology solutions to make business more efficient. Looking up from here Choice’s 20th year demonstrates its commitment to the broker market, Moore says, but it still remains a business that is “absolutely on the growth trajectory”. “We are fairly and squarely an aggregator first, and that is our primary responsibility, to support brokers in growing more successful businesses. That’s what has driven Choice traditionally and that’s what continues to drive Choice today.” AB www.brokernews.com.au
15
FE AT URES
PROFILE
FINDING COMMON GROUND ASIC’s Michael Saadat tells Australian Broker about the regulator’s latest deep dive into interest-only loans, its upcoming shadow shopping exercise, and a significant silver lining of its broker remuneration review
those who see ASIC as the ‘bad guy’, consider this: one of its senior executives working in the broker space has gone to brokers on two occasions for help in finding a suitable loan for his own home. Not only that, but one broker he visited came highly recommended by another colleague at ASIC. Apparently the broker was not trembling in his dress shoes when the ASIC man arrived at his door. “I don’t think that broker was terrified,” says Michael Saadat, ASIC’s senior executive leader of deposit takers, insurers and credit services. “It was a very pleasant experience for me, and I think it was a pleasant experience for the broker as well.” Saadat says he already had a positive view of brokers and this interaction was further confirmation of that. “If I didn’t have a positive view about brokers I probably wouldn’t have used a broker.” That Saadat, as a borrower, visited a broker personally is an interesting anecdote, but it doesn’t mean that ASIC, the regulator, is about to back off on its oversight and scrutiny of brokers. ASIC’s job is to continuously monitor all of the sectors it is responsible for, including brokers, to understand the industry’s evolution and identify and recommend areas for improvement. So, while the Review of Mortgage Broker Remuneration has been the hot-button issue this year, ASIC has been busy at work on a number of other reviews of the industry, including a deep dive into interest-only loans, an upcoming shadow shopping exercise, and what all this means for brokers. “We’re not just there to audit licensees and make sure they’re FOR
16
www.brokernews.com.au
meeting every single legal obligation they’ve got. We have to prioritise the areas where there is the greatest risk to consumers, so that’s a key part of our approach and the thinking we do around the kinds of reviews we do,” Saadat says. Promoting responsible lending is a priority for the regulator because a home loan is one of the most critical financial decisions a consumer will make, he adds. “Making sure the industry is operating appropriately is really important for the financial wellbeing of Australians, and that’s something that we take seriously and we’re prioritising.” Interest-only review ASIC’s investigation into interest-only lending is still underway, and depending on what the regulator finds, it could result in enforcement action.
The aim of the review is to determine whether lenders and brokers have recently been recommending unsuitable and more expensive interest-only loans to customers, particularly owneroccupiers. The review will assess the volume of interest-only loans being provided, in order to understand the different trends and identify any outliers, Saadat says. He says ASIC expects to see a reduction in the number of interestonly loans, reflecting APRA’s tighter lending standards and also lenders’ more robust approach to ensuring interest-only loans are the right product for consumers. The first phase of the review involved the collection of interest-only loan data from 16 lenders, spanning a two-year period up to June 2017. So far, ASIC has concluded that, while Australia’s major banks have cut back
Michael Saadat, ASIC
their interest-only lending by $4.5bn over the past year, other lenders have partially offset this decline by increasing their share. The first phase also found that borrowers who used a broker were more likely to obtain an interest-only loan, compared to those who went directly to a lender, something Saadat says is consistent with the findings in the remuneration review. “We know that a lot of work has been done by the industry over the last couple of years to improve standards and improve record-keeping, so we’re really interested to look at the current conduct out there and we’re hoping to see those improvements reflected in the files that we’re reviewing,” he says. ASIC has now progressed to the second stage of the review, which involves looking at hundreds of recent interest-only owner-occupier loan files from a subset of those 16 lenders and
KEY FINDINGS OF ASIC’S LATEST INTEREST-ONLY REVIEW Major banks cut back IO lending by
16
No. of home loan providers involved
$4.5bn
over the past year Those 16 lenders provided
$14.3bn in IO loans to owner-occupiers in the June 2017 quarter Borrowers were more likely to obtain an IO loan from a broker than if they went directly to a lender
down from
$19bn in the September 2015 quarter
Borrowers approaching retirement age continue to be provided with a significant number of IO owner-occupier loans
from brokers directly. ASIC has already contacted those brokers. ASIC will review those files to see how the consumer’s situation was described, why the interest-only loan was offered, and if it was appropriate for that consumer’s circumstances. “We’re looking at both the lender’s conduct and the broker’s conduct in that case to determine how they have gone about making sure that the consumer was given the product that met their requirements and objectives,” Saadat says. This review will also provide ASIC with an update on whether the recommendations of its September 2016 REP 493 review into interestonly loans and brokers’ inquiries into consumers’ requirements and objectives have been met. “Certainly all of the lenders and the brokers committed to implementing the improvements that we observed were necessary, and we are confident that things have been heading in the right direction, but this is something we can check as part of this second stage of the review.” If lenders and brokers are found to be doing a good job in determining and recording how a customer is approved for an interest-only loan and ensuring it is a suitable fit, then the review will be finished and ASIC won’t take any further action. “But if we do find things that we are concerned about, then we will look at what other options are available to us, including enforcement action,” Saadat says. Shadow shopping While ASIC dug into vast amounts of data to prepare the remuneration review, Saadat concedes that data
doesn’t always explain everything. Following what was observed through the remuneration review, and noting its limitations, the shadow shopping exercise was considered a “natural next step” to achieve a clear understanding of how the industry operates and to help inform ASIC’s regulatory approach. “Having used a mortgage broker myself very recently, I expect that the interactions that consumers are having with brokers are generally very positive, and we hear that from a range of sources,” Saadat says. “This is not about going into the review thinking that there are
ASIC should be aware of. “Anything that we find through shadow shopping will be more about understanding to what extent brokers are potentially not meeting their legal obligations, and whether ASIC, for example, needs to produce more guidance around what they can or can’t say to consumers or whether some other action is required,” he explains. In the past, ASIC has pointed to record-keeping as something brokers need to improve on, but that doesn’t mean brokers aren’t trying to make sure that customers are getting the right loan product; just that the loan file doesn’t adequately explain the
“It’s in the nature of being a regulator that you will have areas where there are disagreements or where people think a different approach should have been taken, but that’s to be expected” Michael Saadat, ASIC significant problems that need to be uncovered; in fact this is about really trying to understand how the interactions between the broker and the consumer are playing out, given that we don’t get any sense of that really from the loan files.” The point of the shadow shopping exercise, which is slated to occur within this financial year, is to understand how those interactions work in practice, and to determine whether there are any issues that
process that has occurred, he says. This operation will hopefully shed some light on that. But it will be a significant undertaking involving real consumers. “We will probably need to use a research firm to assist us with this, because this isn’t something that we do every day, so we need to get some expertise around how we manage that and ensure the sample is robust, that we’ve gone through all the right processes.”
Ongoing communication One positive outcome of the remuneration review from Saadat’s perspective is that it has increased interactions and engagement between ASIC and the sector. “We were conducting this major review and the sector was obviously very keen to understand what we were doing and to be part of the process,” he says. “Brokers don’t always necessarily have a full appreciation of what ASIC is trying to do, and what our expectations are, and so we’re constantly trying to make sure we’re communicating with industry to make sure the industry does know what we expect. What we want to avoid is a situation where people don’t understand what the regulator expects of them.” While it’s impossible to engage with every single broker directly, Saadat says ASIC does have constructive relationships with industry bodies and is in regular contact with the MFAA and FBAA. The parties might not always agree on everything, but ASIC does try to take their feedback on board, something that it did during the structuring of its cost recovery scheme. As a result of those discussions, ASIC made significant changes to the model to reflect the industry’s concerns, Saadat says. “It’s in the nature of being a regulator that you will have areas where there are disagreements or where people think a different approach should have been taken, but that’s to be expected, and I think it’s making sure that there’s good communication at all times and we’re keen to foster that.” AB www.brokernews.com.au
17
FE AT URES
AUSTR ALIAN MORTG AGE AWARDS
CELEBRATING THE INDUSTRY’S STANDOUTS
After a challenging year for broking, the 16th annual Australian Mortgage Awards on 27 October was a night to forget the hardships and set aside the to-do lists to celebrate the best brokers in the industry and the top-notch service they provide. Here are some of the industry’s stars
SIMON ORBELL
FBAA Broker of the Year – Independent
DIRECTOR & SENIOR MORTGAGE ADVISOR, SMARTMOVE Orbell was outside the awards ballroom congratulating and celebrating his colleague Misa Huynh when the award he was nominated for was being presented. He rushed back in just in the nick of time as he was being announced as the winner. He was totally shocked and stunned; after all, he had been nominated for this category so many times before he’d nearly lost count (somewhere around eight or nine times). “After having that happen so many times, you just don’t expect to have your name read out,” he said. “I only just got back in the room as they were announcing the last three finalists, so it was a complete shock – number one that I’d nearly missed the whole thing, and number two that my name was read out.” By Monday morning, it still hadn’t SIMON
totally sunk in. “Getting to the office today, everyone’s been so complimentary and congratulating me, but it still doesn’t feel real at the moment to be honest,” he said. Orbell said the award meant a lot to him because it was recognition of the effort that he’d put in, as well as the commitment and support that his family, colleagues and clients had invested in him. “It’s just lovely to be recognised, and there’s a real sense of pride as well. I get a real sense of pride to be named in such a prestigious environment,” he said. Orbell made sure his awards application this year included more testimonials from customers and industry participants, and he backed that commentary up with data. He
MISA HUYNH
believes that having those voices in there might have made the difference with the judges this year. As for where things go from here, he says nothing from a day-to-day perspective will change. “It will just provide new and existing clients with the reinforcement of how we do things and how we go about things, and it will also allow any new team members that are hoping to join our team to know that they’re joining an operation that believes heavily in training, believes heavily in the customer, and it will give them the confidence that we’re the right place for them from a longterm career perspective.”
ING Young Gun of the Year – Independent
MORTGAGE ADVISOR, SMARTMOVE Huynh came to Australia as an overseas student from Vietnam with very limited English. She was alone and knew no one. She never would have imagined that on 27 October 2017 she would be celebrated for being the best young independent broker in the country, a career she once knew nothing about. “It’s huge. It means everything to me. It showed me that hard work pays off,” she said. Huynh started working at Smartmove in 2013 after getting her master’s degree in accounting. She started as a mortgage documents specialist and supported Nichol Cullen, who soon became her mentor. After a year and a half under Cullen’s tutelage, Cullen encouraged Huynh to become a broker herself. MISA
18
www.brokernews.com.au
“I was so freaked out. I did not grow up here, I did not have anyone, and I didn’t have any friends. Where was I going to find clients?” she said. With her mentor’s assistance, Huynh was able to build her own network of clients. She’s now been a broker for a year and loves what she does. “I love my clients so much, and most of them became my friends. I love helping them and they show the love back by writing lots of Google reviews for me. Maybe the judges saw that,” Huynh said. Not only do customers rave about her, but Huynh also does good deeds outside of work. She’s fundraised to support infrastructure projects in Vietnam, including the construction of a new bridge to replace a dangerous
dilapidated one that linked two towns in western Vietnam. She raised more funds than she needed, so the extra was used to build two schoolyards. Now she’s looking to fund a road project in eastern Vietnam where flooding often makes it impassable. She’s incredibly modest about her volunteer work, but that’s one of the things that makes Huynh more than just a good broker: she’s a standout citizen. For aspiring young guns, her advice is this: “Do everything that you feel in your heart; just go for it. I’ve just really dedicated my time to it and I love it so much, so do what you’re passionate about and as long as you do that and you love your clients, everything else will come to you.”
IAN ROBINSON
Westpac Australian Broker of the Year
FOUNDING DIRECTOR, ROBINSON SEWELL PARTNERS Robinson may work out in the bush, but his name is one that everyone knows. Not only did he win the much-coveted Westpac Australian Broker of the Year award, but he also snapped up the ANZ Broker of the Year – Commercial award and the Pepper Money Broker of the Year – Specialist Lending award. While Robinson has been crowned many times in the past, this was his first win at the AMAs. “It was completely unexpected without a doubt; it caught me by surprise. I’m very excited to share this with my teammates,” he said. Specialising in corporate, commercial and agribusiness finance in regional Australia, it’s not uncommon for Robinson and his colleagues to drive 400–600km just to meet a client. “We operate in the country, we work with a lot of farmers, so there’s a lot of commitment and time involved in working with our clients. It’s a long game and very much a IAN
relationship-driven business that we’ve got, and I think it pays off by putting the time in,” he said. When asked what this award might mean to his farmer clients, Robinson said: “They just know that they’re getting looked after and they’re getting support that quite often they’re not getting just because they live in remote areas. The banks just can’t operate in those regions, so we’re there to fill that gap and then give them all that support and knowledge they need to have good banking relationships.” His advice to others is to realise that it’s not a straight line to get to Broker of the Year. It takes perseverance, resilience and a lot of hard work, he said. “There are still challenges in there as well which no one ever sees, but just getting through the tough times and sticking with your knowledge base.” Robinson Sewell Partners has a big year ahead. It recently expanded to Tasmania and South Australia and is
LEE WISNIEWSKI
looking to continue its national expansion by adding brokers in Queensland and Victoria and eventually moving into Western Australia. “We’re speaking to new candidates as we speak, and business is growing; it’s very exciting,” Robinson says. As for the significance of the awards to him, he said: “They’re certainly there to remind me, every day that I see them, what we’re working for and what we’re working towards, and it gives us the motivation to keep going.”
Commonwealth Bank Australian Young Gun of the Year
BROKER, LOAN MARKET Wisniewski runs a lean operation in Melbourne with one full-time loan writer and a contract loan processor, but that didn’t stop him from making a big impression on this year’s AMA judges. Wisniewski won both Young Gun of the Year – Franchise and the overall CBA Young Gun of the Year awards. He believes his wins have to do with his business maturing this year, putting on staff and implementing new processes to create efficiencies and better serve customers. Wisniewski says he has also embraced new technology to the point where his team is probably working less than it did the year before because they’re being more efficient. In their first full year of broking, his team settled $44m and is on track to settle $60m–$80m in the next 12 months. “I knew I had a better year this year than I did last year when I was a finalist, but honestly I didn’t think I LEE
would actually get a win, and I’m chuffed that I did,” Wisniewski said. “It’s such good competition, and our industry is full of great people and very high achievers.” For those aspiring young guns, Wisniewski compares breaking into broking to this analogy from Loan Market’s chairman Sam White. Picture a spaceship with huge fuel tanks trying to get aloft. “You need so much fuel to just get off the ground, never mind through the atmosphere, but once you get up there you can make a really big difference; you just need to break through that. And it’s just a lot of hard work at the start, but hang in there,” he said. White said these wins demonstrated Loan Market brokers’ passion and dedication to their profession. “We are so proud of Lee Wisniewski. Winning Young Gun of the Year 2017 in the franchise category is an incredible achievement on its own, but to also be named Young Gun of the Year for Australia
with less than two years’ experience is testament to his relentless determination and commitment to his customers.” For the year ahead, Wisniewski plans to bring on a new broker support officer to help him build capacity to meet more people face-to-face. He is also dedicated to continuing his work with his charity partners. “Next year is just really working on getting me in front of more people and then of course helping more people in our community as a result.” AB www.brokernews.com.au
19
PEOPLE
CAUGHT ON CAMERA A crowd of more than 650 of the country’s top mortgage and finance professionals dressed to dazzle attended the 16th annual Australian Mortgage Awards at The Star Sydney on 27 October. Awards were presented in 31 categories, covering brokers, BDMs, aggregators and lenders, revealing the best in the broking industry. Sponsored by official partner Westpac for the ninth consecutive year, the night had plenty of highlights, from the hilarious finalists’ introduction video to the whoops of sheer joy and delight when a winner’s name was called. There was champagne, conversation and a popular photo wall where the night’s accomplishments were captured. After the awards ceremony, the elated crowd filled the dance floor to groove to Furnace and the Fundamentals, ending the night on a memorable note. Photography by Simon Kerslake
20
www.brokernews.com.au
www.brokernews.com.au
21
AUSTR ALIAN MORTG AGE AWARDS
FINSURE CROWNED BEST AGGREGATOR
Finsure explains how it won the Aggregator of the Year award (over 500 brokers) at the AMAs by providing holistic solutions to brokers, exemplary service, and leading member support programs KEY COMPANY FIGURES
1,300
brokers in network
$27BN
loan book
6 years
in business
35
staff employed
From left: Ray Esho, ING national sales manager and award presenter, and Simon Bednar, Finsure general manager of sales
six years ago Finsure was a new name in the industry with not even one broker on board. Now it boasts a network of 1,300 and is officially at the top of its game, winning the Aggregator of the Year award (over 500 brokers) against some veteran industry players at the 2017 Australian Mortgage Awards. “When Finsure was announced as the winner against some fantastic competition it was just an incredibly proud moment,” says Simon Bednar, Finsure’s general manager of sales, who accepted the award at the gala on 27 October. “This is an amazing achievement for the company, especially considering it has only been six years since we started.” Bednar says the award – the first win for the company at the AMAs after being nominated twice before – is “the pinnacle for our industry” and is a credit to all of Finsure’s staff and broker partners. Finsure managing director John Kolenda called the recognition from the industry a “major landmark for the company”. “The ability of the company to increase its growth rate has been a tribute to the talented and JUST
22
www.brokernews.com.au
hard-working team at Finsure as well as our amazing broker partners. “While thrilled with our achievements, we are determined to keep growing and continue our amazing journey,” he said. Finsure’s rapid expansion to 1,300 members, the latest 300 of whom were recruited in less than a year, is attributed to the aggregator’s ability to provide market-leading holistic
aggregator that will support them effectively and help them develop all aspects of their business, not just grow their loan book, and that will continue to invest and add value to their proposition, Bednar says. “A good aggregator can make every difference to a broker’s business. We see ourselves as a business partner in every single one of our brokers’ businesses. Across our organisation,
“The ability of the company to increase its growth rate has been a tribute to the talented and hard-working team at Finsure as well as our amazing broker partners” John Kolenda, managing director, Finsure solutions to brokers, and leading member support programs. Its above-and-beyond service to brokers’ businesses ensures strong retention. As a result, the group expects to have more than 1,500 brokers by the end of 2018 and a $30bn loan book. Brokers want to partner with an
we dedicate ourselves to servicing our broker partners in the same way an exemplary broker would service their clients,” he says. Finsure offers a range of in-house services to meet brokers’ diverse business needs and that will assist them in growing their volumes.
Those services include a simple, intuitive proprietary CRM to help brokers save time, effort and money to prioritise the customer journey; lead generation in their local area; outbound call centre services; a range of website templates for brokers to design their own branded websites, which Finsure will host; legal and taxation services; recruitment services to find ideal candidates for brokers’ businesses; multi-vertical sales options to facilitate additional revenue opportunities; training and mentoring services, including its 24-month broker academy to train new entrants; annual business planning and sales coaching. “Rapid changes in technology and a vastly different regulatory landscape have resulted in brokers requiring their aggregator to specialise in more areas. We are intent on building a complete business-to-business solution that will help our business partners stay ahead of the game,” Bednar says. “Every division within the group understands its role is to help our brokers with their business, and any solution they need we will be there to assist them.” AB
DIVERSIFICATION UPDATE
IVO DE JESUS SUPERCHARGED HIS BUSINESS THROUGH INVESTMENT PROPERTY REFERRAL John Manciameli talks to Ivo De Jesus, CEO of Sanford Finance
Ivo De Jesus
What first inspired you to help your clients with their investment property aspirations? I’ve actually always had an interest in A property, and I’m a bit of an investment property enthusiast myself, to be honest, so it felt very natural to build my business around my passion. My key target market is property investors, and my approach is to introduce the concept of having an investment property strategy and diversifying their portfolio. I’m lucky in that I practise what I preach so I can share my insights and experience to be able to assist either a first-time property investor or a seasoned investor.
Q
Why did you choose to work with Slipstream? As an aggregator of investment A property research houses and buyers’ agents, Slipstream’s ethos is built on creating ethical long-term relationships and educating clients about the investment opportunities that exist, which really resonated with me. When I first met John from Slipstream, I quickly discovered we shared the same values and passion for the investment property industry. I established a good relationship with John and realised he shared the same vision of building wealth
Q
John Manciameli
creation opportunities for clients. What are the key benefits of working with Slipstream? Slipstream has changed the way I do A business. It has supercharged every aspect of my business, starting with the conversations I have with my clients about their investment property aspirations. Slipstream has also made me comfortable about referring clients on to the quality research houses and buyers’ agents they have vetted; this due diligence process Slipstream does is really important to me in this unregulated market. Working with Slipstream has also taught me to adopt an educational approach with clients and to share information with them along every step of the way. Through the tools, software and advice Slipstream offers, you are truly positioned to be the adviser for clients who are keen to invest in property.
Q
What feedback have you received from clients you’ve worked with? My clients keep coming back to me A time and time again. They are all
Q
very happy with their investment property decisions and understand they’re in it for the long term. A few clients weren’t sure about investing interstate and were concerned about heading into the unknown; however, Slipstream’s partners have all been thoroughly assessed against strict performance criteria, so there’s a level of trust there they haven’t felt before. How much has Slipstream impacted the bottom line of your day-to-day business? Every client who comes to my A business is now either a current investor or a future investor; what that means is these are clients for life. It has enabled me to widen my business offering while keeping the element of trust throughout the referral process.
Q
What’s the most important piece of advice you would share with other brokers? Give it a go and listen to what John A has to say; you might learn something! The expert advice, tools, education and processes Slipstream offers will grow your business exponentially and help you to truly diversify your offering.
Q
www.brokernews.com.au
23
24
www.brokernews.com.au
www.brokernews.com.au
25
DATA
VICTORIA
WA SPOTLIGHT
Regional cities outside of Melbourne are coming to the fore as alternatives and are capturing buyers’ interest “Over the last seven years ending 2016, Bendigo’s property price growth was more than double the rate of Brisbane’s. The economic profile of Bendigo oozes diversity and resembles that of a capital city, [and] there are a few good infrastructure projects which we have catalogued as positives,” says Simon Pressley, managing director of Propertyology. Geelong is another city that has significant potential. According to ABS data, the population in this city, the second-largest in Victoria, is expected to increase by over 30% in the next two decades as it receives the overflow from Melbourne’s boom. The state has thus been taking initiatives to diversify Geelong’s economy and add to its infrastructure. “The affordability of the area, with many suburbs around Geelong having median house prices of around $400,000, is also an excellent pull factor for the region,” adds Lindy Lear, general manager of Rocket Property Group.
Area
Type Median value
Quarterly
12-month
growth
growth
Melbourne
H
$720,000
8.3%
10.3%
VIC Country
H
$330,000
0.0%
3.5%
Melbourne
U
$522,000
6.5%
2.5%
VIC Country
U
$262,500
1.0%
0.4%
SOUTH AUSTRALIA
Given Adelaide’s affordability, demand from investors has been picking up throughout the city “The house price increases on the eastern seaboard have seen Adelaide come to the fore as an alternative property investment location,” says Gregg Harris, general manager of NAB Retail. “It is becoming increasingly popular for Sydneysiders in particular to buy properties more than 1,000km away in Adelaide. There are plentiful, affordable investment options, all within 10km of the city’s CBD – more than a quarter of Adelaide’s homes have a median value of $400,000 or less, according to the latest CoreLogic data.” Hotspots in the area include Campbelltown and Greenwith in the northeast and Happy Valley in the south, as per the winter Price Predictor Index report from Hotspotting’s National Top 50 Locations for Consistency. Factors contributing to their popularity include accessibility to the CBD, the availability of public transport, and amenities such as schools, shopping centres and green spaces. Area
Type Median value
Quarterly
12-month
growth
growth
CAUTIOUS APPROACH TO PERTH Positivity peeks into the Perth market, but a lack of stability stays experts’ optimism with regard to long-term growth Multifocus Properties & Finance CEO Philippe Brach, investing in Perth at this point is still far too risky, given its lack of economic stability. “There are probably good opportunities now in Perth, but it’s more a gamble than an educated investment decision,” he explains. “Prices [could] start ticking up very drastically, and suddenly Western Australia is going to do great again. But when you make an investment decision, you go to an area where you’ve got many pillars of industry and a growing economy that is promising, rather than something that’s not 100% sure.” The city of Geraldton has been taking steps to add to its industrial power through the commencement of various infrastructure projects. “Construction of the world’s largest satellite – inland from Geraldton – is scheduled to commence late next year, with anticipated direct and indirect employment opportunities to flow,” says Simon Pressley, managing director of Propertyology. “Science, tourism and renewable energy are among the industries offering plenty of upside to have a positive influence on Geraldton’s property market in years to come.” Coupled with the affordability of quality properties, this means Geraldton’s high vacancy rate could drop in the near future. AB FOR
H
$450,000
0.0%
3.3%
Median price (houses)
SA Country
H
$295,000
-0.4%
1.8%
$910,408
Perth
U
$385,000
5.5%
4.3%
SA Country
U
$205,000
12.2%
4.8%
www.brokernews.com.au
With the latest quarterly figures confirming a drop of 1.3% in the housing market and 6.7% in the apartment market, Perth now offers an abundance of opportunity Year-on-year figures demonstrate negative growth of 2.3%. However, over the past four to six weeks we have personally experienced a change in sentiment. Not only have we been contacted by a number of pre-approval clients who have committed to formal offers, but the number of first home buyers we have assisted into properties in the $450,000 to $600,000 range has increased. The conversations with all these clients have a common theme – ‘FOMO’ (fear of missing out) on the bottom of the market. For investors, the news isn’t as positive, with a 2.8% decrease last quarter in the median weekly asking rent. We are cautioning our clients against high-density unit and apartment purchases in the immediate future due to a heavily saturated market, and we should expect to see a further decrease in the December quarter for this sector. However, with economic data reflecting jobs growth these last 12 months and commentary around a Metronet-led recovery, we are cautiously optimistic that this will see the market return to positive growth by the end of the March quarter. Michael Deegan Director, DO Financial
SUBURB TO WATCH: BOORAGOON
Adelaide
26
BROKER PERSPECTIVE
Median price (units) $530,208
Source: CoreLogic
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
-0.6%
5.1%
13.4%
2.9%
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
-3.1%
-3.5%
-1.2%
3.6%
AUSTRALIAN CAPITAL TERRITORY
A shake-up in the location of government departments could take a toll on the market
OPPORTUNITIES AND KEY INFRASTRUCTURE
Riverside destination
Perth Stadium
WA Museum
Yagan Square
Project will transform Perth’s eastern gateway, adding homes for 7,000 people
New sporting and entertainment venue to seat 60,000
Major museum redesign will display the state collection in innovative ways
Newest foodie haven in Perth is growing its offerings
HIGHEST-YIELD SUBURBS IN WESTERN AUSTRALIA Suburb
Type
Median price
Quarterly growth
12-month growth
Newman
H
$150,500
-8%
-23%
Kambalda
H
$100,000
-9%
-14%
Rangeway
H
$110,000
-14%
-15%
Derby
H
$175,000
-3%
-35%
Utakarra
H
$130,000
-22%
-19%
“There has been talk of decentralisation of government departments in Canberra to reach the northern part of Australia – it could have a pretty strong detrimental impact on the Canberra market,” REA Group chief economist Nerida Conisbee states. “That’s probably the biggest risk factor at the moment in the market. It depends on what they do, the scale of what they’re proposing. It’s something you do need to look at if you’re looking to invest in that location.” If only a few departments are relocated, the effect on the market is expected to be minimal; however, if many jobs will be uprooted, Canberra could be badly shaken. Nonetheless, apartments near the University of Canberra and the Australian National University should still be profitable investments, as would apartments near city centres like Woden and Belconnen.
Area
Type Median value
Quarterly
12-month
growth
growth
Canberra
H
$675,000
1.5%
6.2%
Canberra
U
$430,000
-2.3%
3.0%
www.brokernews.com.au
27
DATA
QUEENSLAND
12-month
growth
growth
Brisbane
H
$525,000
1.0%
3.0%
QLD Country
H
$435,000
0.6%
1.5%
Brisbane
U
$400,000
-1.2%
-2.4%
QLD Country
U
$375,000
-2.6%
3.1%
NEW SOUTH WALES
MEDIAN HOUSE AND UNIT PRICES
While Sydney awaits new supply, one expert recommends considering properties beyond the capital
$1,000,000
Type Median value
Sold
54
Not sold
25
Clearance rate
68.4%
PERTH Total auctions
42
Sold
11
Not sold
8
Clearance rate
Sydney Melbourne Brisbane Adelaide
Perth
57.9%
Hobart
$565,000
$281,000
$393,350
$390,000
$0
$510,000
$100,000
$318,750
$200,000
$442,750
$300,000
$525,000
$500,000 $400,000
$725,000
$700,000 $600,000
$720,000
$800,000
Darwin
Units
Canberra
CAPITAL CITY HOME VALUE CHANGES Capital city
Weekly change
Monthly change
Year-to-date change
12-month change
-0.2%
-0.3%
5.2%
9.1%
Melbourne
0.2%
0.7%
8.3%
11.6%
Brisbane
0.1%
0.4%
2.3%
2.9%
Adelaide
0.1%
-0.1%
2.7%
4.9%
Perth
0.2%
0.2%
-2.3%
-2.7%
0.0%
0.2%
5.0%
7.9%
Sydney
Quarterly
12-month
growth
growth
H $1,025,000
9.6%
6.8%
NSW Country
H
$541.500
0.3%
7.0%
Sydney
U
$750,000
4.9%
3.8%
NSW Country
U
$385,000
4.1%
3.9%
www.brokernews.com.au
93
Houses
$940,000
$900,000
Sydney
28
Total auctions
$1,100,000
“A good Plan B is to go a bit outside of Sydney and look for areas that benefit from the ripple effect of Sydney property prices. That would be Wollongong, Central Coast, and Newcastle, which are very good areas,” suggests Philippe Brach, CEO of Multifocus Properties & Finance. For Brach, NSW continues to be the top prospect in the national property market. “New South Wales is the powerhouse of Australia – it’s the best-performing state. I don’t think [Sydney’s] going to stop growing. The problem is the fact that yields are so low. For a normal mom-and-dad investor, although capital growth is good, your cash flow is so bad it’s just not sustainable from that point of view.” The northwest region of Sydney is becoming an attractive alternative, given predictions of future growth. Area
ADELAIDE
$401,000
Quarterly
$395,000
Type Median value
Auction clearance rates held firm for the week ending 15 October, buoyed by stronger results across the Melbourne and Canberra housing markets. There were 2,497 auctions held across the combined capital cities that week, up from 2,318 the week before. A preliminary clearance rate of 70.6% reflected an increase from the week before when the final clearance rate came out at 64.4%, the lowest clearance rate since January 2016. While CoreLogic expects the clearance rate to bounce back, it said it would be interesting to see how it holds up when the final figures are released. Over the corresponding week last year, auction volumes were similar, with 2,443 properties taken to auction. The clearance rate last year was stronger, at 76.2%. The highest preliminary clearance rate for the week this year was recorded in Melbourne (74.8%), followed closely by Canberra (74.5%).
$525,000
Area
WEEK ENDING 15 OCTOBER 2017
$612,500
“Cash flow for a property in Brisbane is going to be a lot better than cash flow for a property in Sydney, simply because of the national yield of the market. If you buy a property in Brisbane today, it’s probably going to be slightly cash flow positive,” says Philippe Brach, CEO of Multifocus Properties & Finance. Suburbs that are in particular demand are those situated 20–40km from the Brisbane CBD. They offer good value for money at affordable prices, while generating a high yield. “If you can’t find a place 12–20km from the CBD, and you realise that your yield is around 4.8–5%, then it’s still a good investment,” Brach comments. However, he advises against investing in areas like Coomera, the north of the Gold Coast and the area west of Brisbane, given the considerable construction happening and the small chance of capital growth.
CAPITAL CITY AUCTION CLEARANCE RATES
$362,000
Brisbane’s allure lies in its high potential for rental returns
Combined 5 capitals
*The monthly change is the change over the past 28 days
BRISBANE CANBERRA Total auctions
61
Sold
35
Not sold
12
Clearance rate
Total auctions
170
Sold
65
Not sold
65
Clearance rate
50.0%
74.5%
SYDNEY Total auctions
916
Sold
477
Not sold
209
Clearance rate
TASMANIA
MELBOURNE Total auctions
69.5%
1,208
Total auctions
7
Sold
779
Sold
2
Not sold
263
Not sold
2
Clearance rate
Clearance rate
74.8%
TASMANIA
Area
Despite Tassie’s positive performance, economist warns investors to be careful A considerable chunk of the demand for Hobart property comes from overseas investors in China. However, REA Group chief economist Nerida Conisbee has warned investors to be careful. “It is a small market, and the entire population is roughly the size of the Gold Coast. So it’s not a big population; it’s not a growth economy,” Conisbee says. Philippe Brach, of Multifocus Properties & Finance, adds that Tasmania’s lack of industrial drivers prevents it from experiencing significant growth and activity over the long term. The fact that Tasmania is an island poses a problem as well, as it is disconnected from the rest of the country. “There’s no pressure on property prices, there’s no major centre of industry. Apart from tourism, there’s not much of an economy down there."
50.0%
Type
Median value
Quarterly growth
12-month growth
Hobart
H
$390,000
1.0%
6.6%
TAS Country
H
$270,000
3.3%
1.9%
Hobart
U
$290,000
-6.5%
1.5%
TAS Country
U
$235,000
-1.2%
3.5%
All data sourced from CoreLogic.com.au
www.brokernews.com.au
29
PEOPLE
IN THE HOT SEAT Kathryn Bordonaro, co-founder of Foodie Finance, talks about tailoring her business to suit her food industry clients, and how to have a perfect picnic on a train
Why did you create Foodie Finance? My co-founders, Tanya Lawrence, Nick Michaelides and I, are A all from different multicultural backgrounds. We all love to grow, cook and eat, and it’s a bond that makes for a great working relationship. As a result, we have a large client base in the food industry and we have gained a lot of knowledge about the food industry over our years as brokers. Foodie Finance was created to deliver a finance broking offering that shows understanding and commitment to this industry no matter where the customer fits into the ‘field to fork’ cycle.
Q
What are some challenges the food industry faces in getting finance? The food industry is notorious for long hours, so many of our A clients are super time-poor. They know they need a new piece of equipment, or want to start an additional site, but often these decisions get put on the too-hard list. We don’t work nine to five; we fit ourselves into our customers’ schedules. If they have to sign paperwork at 6am while setting up for the breakfast coffee rush, we’ll do that. Hopefully we get a strong coffee, too. We also understand the difference that specialised equipment can make to a food business, and we can frame this so financiers are comfortable with their lending decisions.
Q
Can you tell us about one memorable meal you’ve had? A meal that lingers long in my memory is not a formal MichelinA starred restaurant but instead my sister and I having a train picnic as we travelled from Lyon to Venice. We had shopped at the famous Les Halles market, and tucking into a pistachio-studded saucisson baked into a brioche, with the breathtaking beauty of the Alps outside my train window and a trail of crumbs down my shirt, is a memory that will sustain me for a long time.
Q
How did you get into broking? Working in an equipment finance company in a credit role was a A natural fit for me: my dad had an earthmoving business and the rest of my family were farmers, so I grew up around heavy machinery. After about 10 years, my employer restructured, I had a child, and broking was the perfect way to juggle work and home. I have never lost the buzz of putting a deal together and being able to get a client approved. AB
Q
30
www.brokernews.com.au
www.brokernews.com.au
31
32
www.brokernews.com.au