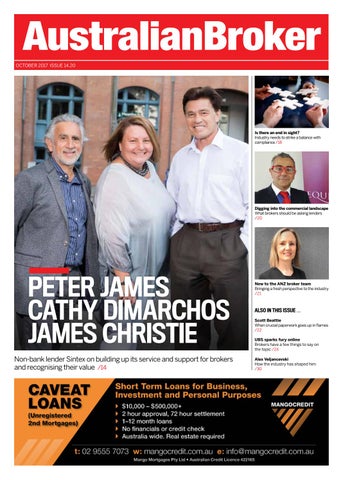
OCTOBER 2017 ISSUE 14.20
Is there an end in sight? Industry needs to strike a balance with compliance /18
Digging into the commercial landscape What brokers should be asking lenders /20
PETER JAMES CATHY DIMARCHOS JAMES CHRISTIE Non-bank lender Sintex on building up its service and support for brokers and recognising their value /14
New to the ANZ broker team Bringing a fresh perspective to the industry /21
ALSO IN THIS ISSUE ‌ Scott Beattie When crucial paperwork goes up in flames /22 UBS sparks fury online Brokers have a few things to say on the topic /24 Alex Veljancevski How the industry has shaped him /30
NEWS
IN THIS SECTION
Lenders Government-backed bank proposed for SMEs /04
Aggregators Hero Broker slams aggregator “monopoly” /06
Technology A connective tech solution /10
Regulators Heat turns up on bank-owned aggregators /12
Consumers Low rates fail to halt mortgage stress /08
www.brokernews.com.au OCTOBER 2O17 EDITORIAL Editor Otiena Ellwand News Editor Miklos Bolza Production Editor Roslyn Meredith
DATES TO WATCH
Upcoming can’t-miss events
ART & PRODUCTION Design Manager Daniel Williams Designer Martin Cosme
23 OCTOBER
24-26 OCTOBER
Suncorp CEOs insights panel
Women in Leadership Conference
A panel of Suncorp executives will meet at Randwick Racecourse to discuss the major events impacting the finance industry locally and globally, future trends in banking and customer behaviour, and the impact of regulatory changes on intermediaries
This Sydney event features some of Australia’s most successful business women, including the CEOs of Suncorp, the City of Sydney and Mirvac, who will share their stories of leadership struggles and accomplishments, and teach women how to drive career growth
25 OCTOBER Loan protection webinar At MPA’s lunchtime webinar you will learn about loan protection and why more and more brokers are making this an integral part of their offering
Production Manager Alicia Chin Traffic Coordinator Freya Demegilio
SALES & MARKETING Sales Manager Simon Kerslake Account Manager Rajan Khatak Marketing and Communications Manager Lisa Narroway
CORPORATE Chief Executive Officer Mike Shipley Chief Operating Officer George Walmsley Managing Director Justin Kennedy Publisher Simon Kerslake Chief Information Officer Colin Chan Human Resources Manager Julia Bookallil
EDITORIAL ENQUIRIES
Otiena Ellwand +61 2 8437 4792 Otiena.Ellwand@keymedia.com.au
SUBSCRIPTION ENQUIRIES
tel: +61 2 8O11 4992 fax: +61 2 9439 4599 subscriptions@keymedia.com.au
27 OCTOBER
3 NOVEMBER
5 NOVEMBER
Australian Mortgage Awards
MFAA NSW Golf Day
Gong MS Ride
This Australian Broker-sponsored awards show at The Star Sydney celebrates 16 years of excellence in the mortgage broking industry
Head to the green instead of the office and enjoy a day of golf and networking with industry colleagues at the annual MFAA NSW Golf Day at Twin Creeks Golf and Country Club 45 minutes west of Sydney’s CBD
Pepper Money is inviting brokers to join its team ride for charity from Sydney to Wollongong on a 58km or 90km course
ADVERTISING ENQUIRIES
Simon Kerslake +61 2 8437 4786 simon.kerslake@keymedia.com.au Rajan Khatak +61 2 8437 4772 rajan.khatak@keymedia.com.au Key Media Pty Ltd Regional head office, Level 1O, 1–9 Chandos St, St Leonards, NSW 2065, Australia tel: +61 2 8437 4700 fax: +61 2 9439 4599 www.keymedia.com Offices in Sydney, Auckland, Denver, London, Toronto, Manila, Singapore, Bengaluru
15-16 NOVEMBER
16-30 NOVEMBER
24 NOVEMBER
BOSS Leadership Summit
FAST PD Days
The CEOs of the ABA, NAB and Suncorp will give their expert perspectives on transformation, adaptation and the qualities required of future leaders at this Sydney event
FAST is hosting five PD Days across the country in November. The events will include a business and industry update, growth and networking opportunities, and business strategy insights
FBAA National Industry Conference
2
www.brokernews.com.au
This year’s conference on the Gold Coast will equip brokers and other industry members with useful knowledge and practical strategies to help them succeed in an increasingly challenging market
This magazine is printed on paper produced from 1OO% sustainable forestry, grown and managed specifically for the paper pulp industry Copyright is reserved throughout. No part of this publication can be reproduced in whole or part without the express permission of the editor. Contributions are invited, but copies of work should be kept, as Australian Broker magazine can accept no responsibility for loss. Australian Broker is the most-often read industry publication, according to independent research carried out by the Ehrenberg-Bass Institute for Marketing Science at the University of South Australia in December 2008. The research also found that brokers rate Australian Broker as the best for both news content and feature articles, followed by sister publication MPA. Overall, on all categories, Australian Broker ranks top followed by MPA. The results were based on a sample of 405 respondents who were the subject of telephone interviews.
NEWS
LENDERS MORTGAGE CUSTOMERS’ SATISFACTION DROPS
INTEREST-ONLY BORROWERS USING BROKER CHANNEL MORE LIKELY TO BE FINANCIALLY STRESSED Source: UBS Evidence Lab
50%
customers at the major banks have again reported lower satisfaction levels than non-home loan customers, according to Roy Morgan. Their satisfaction levels declined by 0.4% over the last month to 75.7%, while levels for non-home loan customers dropped by only 0.1% to 79.8%. “Mortgage customers … account for around three quarters of the total banking value or footings in the market, making satisfaction a key metric in growing and retaining customers in this segment,” said Norman Morris of Roy Morgan.
46%
MORTGAGE
45%
35%
25%
Kate Carnell Australian Small Business and Family Enterprise Ombudsman
4
www.brokernews.com.au
20%
20%
17%
16% 14%
15% 8%
5%
UBS FOLLOWS UP CONTROVERSIAL REPORT
“Our own inquiry into small business loans in 2016 found that there was almost a complete asymmetry of power in the relationship between banks and small business borrowers.”
30%
30%
10%
hot on the heels of its FOLLOWING controversial ‘liar loans’ report, global investment bank UBS has released a second paper on interest-only lending, again putting brokers in the firing line. The new report is based on results from a survey of 907 respondents. It suggests that about a third of interest-only borrowers are unaware of the type of mortgage they have, citing financial illiteracy. UBS found that those who got their loan via the broker channel were more likely to be under high financial stress.
42%
40%
0% Broker Does not add financial stress
Low stress
Banker Moderate stress
High stress
GOVERNMENT-BACKED BANK PROPOSED FOR SMES The Small Business Ombudsman has floated the idea of a government fund to help smaller players access credit amid tighter lending by the banks Australian Small Business and Family Enterprise Ombudsman has urged the government to create a fund that caters to the lending needs of small business owners across the country. In a submission to the Productivity Commission’s Inquiry into Competition in the Australian Finance Industry, Ombudsman Kate Carnell said there “was almost a complete asymmetry of power in the relationship between banks and small business borrowers”. Thanks to prudential rules brought in since the GFC, Australia’s banks have tailored lending to be secured against real property instead of financial aspects of small businesses, such as cash flow. “The prevailing focus of bank THE
lending against real property security has the effect of increasing the cost of capital on other lending. It has also contributed to reducing the ability of small business to obtain funding secured against other business aspects such as cash flow.” Restricting finance for businesses with limited access to property has come at a cost to small businesses and family enterprises, Carnell said. “The focus on ‘bricks and mortar’ funding is constraining capital for businesses with good cash flow and business prospects, but lacking in real property holdings that may be mortgaged. As a result, for many small businesses funding is simply unavailable at a reasonable cost.” The Ombudsman floated two proposals to tackle this issue. First
she suggested the Productivity Commission should explore whether prudential standards were “too tight” from a risk perspective and consider any flow-on effects, this would have on banks lending to small businesses. Alternatively, she said a government-backed approach could be used to assist SMEs that was similar to the Commonwealth Government Clean Energy Finance Corporation (CEFC). “The [CEFC] was set up because of the barriers to entry into clean energy and the need for a bankfriendly business case in order to entice banks to lend in this area. Banks and the CEFC share the risk on these loans.” This could be a useful model to emulate and provide governmentbacked small business loans, Carnell said. She also acknowledged the many alternative sources of funding that had emerged via fintechs, but said the variation in products made it difficult for small businesses to make informed decisions.
NEWS
A G G R E G AT O R S NEW FINSURE CFO WILL HELP LEAD GROWTH has announced that Kylie Turner will join its senior management team as CFO as the aggregator focuses on future expansion. “Kylie’s proven record of success driving profitable and sustainable business growth through the provision of strategic advice and commercial insights to the executive will be of great assistance in helping Finsure achieve its targets,” said Finsure managing director John Kolenda. He said he expected Finsure to have more than 1,500 brokers on board by the end of 2018, and a $30bn loan book. FINSURE
BUILDING SOCIETY UP BY 800 BROKERS Building Society has reported a significant increase in its broker network after ramping up its partnerships with four major aggregators. It’s had long-standing relationships with Mortgage Choice and PLAN, and started partnering with AFG and Connective about three years ago. During FY17, the lender brought in total home loan approvals of around $2.2bn, with approximately 55% coming through brokers. Its home loan portfolio now sits at $8.5bn, thanks to a growth rate of 8.5% over the financial year. PERMANENT
FINTECH SLAMS AGGREGATOR ‘MONOPOLY’ In a submission to the government, online platform Hero Broker has claimed ‘powerful mortgage groups’ have colluded to stop it from entering the market heated statement by emerging fintech Hero Broker has accused major aggregator groups of working together and stacking the deck against newcomers to the industry. In a submission to the Productivity Commission’s Inquiry into Competition in Australia’s Financial System released on 27 September, Clint Howen, founder of Hero Broker, called upon the commission to examine the role played by aggregators in the market. Hero Broker is a digital platform that allows borrowers to bypass the need to use a mortgage broker and instead shop online for a loan and apply direct via the platform. Howen recounted his experiences with the major aggregator groups, A
6
www.brokernews.com.au
claiming that Hero Broker was denied entry into the market despite meeting ASIC’s compliance regulations. He claimed there was a “collective discussion” between key figures within the mortgage industry to protect themselves. “We at Hero Broker have operated in a compliant and legal manner, and this is recognised by ASIC. However, our competitive edge was prevented from entering the market from powerful mortgage groups,” Bowen wrote. While first being welcomed by AFG, Bowen said the aggregator made an about-face and eventually terminated its contract with the fintech. Other aggregator groups later said they had been “told not to work” with Hero Broker.
In response to Australian Broker’s request for comment, an AFG spokesperson said the aggregator had “decided that Hero Broker’s business model did not align with our own and we did not wish to work with Hero Broker”. “There is no aggregator conspiracy, and AFG wishes Hero Broker well in their business endeavours,” the spokesperson said. Bowen suggested otherwise in his submission, claiming that aggregators were using their power within the industry to reach beyond their purview of providing a service, and were instead “actively shutting down” newcomers who they perceived as a threat. “The Hero Broker experience to date has seen aggregators behaving like a monopoly, with a collective control of more than 50% of the market,” he wrote. “This isn’t in the name of competition and to offer better services to Australians, but instead to their detriment, thus potentially costing Australians billions.”
“The Hero Broker experience to date has seen aggregators behaving like a monopoly, with a collective control of more than 50% of the market.” Clint Howen Founder, Hero Broker
NEWS
CONSUMERS BROKERS ‘MORE SCRUPULOUS’ THAN EVER lending standards and “forensic” client assessment criteria mean that brokers and banks cannot be pushing consumers into larger mortgages, according to CEO of Mortgage Choice John Flavell. “The banking industry is highly regulated and both brokers and lenders are more scrupulous than ever,” he said. “Borrowers aren’t being forced into higher loans; they are simply choosing to borrow more in order to purchase their desired asset.” This is especially true with property prices continuing to rise across the country, he said. TIGHTER
INVESTOR LENDING PLUNGES BY $3BN levels of lending by Australian banks have dipped due to significant decreases in the volume of investment loans, according to the latest figures from APRA. The Monthly Banking Statistics show $1.57trn on the total loan books of banks during the month of August, a decrease of 0.1% from $1.58trn the month before. The drop was due to a decrease in investment lending, with total investment loan books at the banks dropping by $3bn (or 0.5%) from $553bn to $550bn. OVERALL
“The banking industry is highly regulated and both brokers and lenders are more scrupulous than ever.” John Flavell CEO, Mortgage Choice
LOW RATES FAIL TO HALT MORTGAGE STRESS There’s been an increase in the number of households under mortgage stress despite a decline in owner-occupier interest rates stress is on the rise in more households across Australia despite a fall in interest rates, new research from Roy Morgan has found. A survey of more than 10,000 owner-occupier mortgage holders has shown that mortgage stress increased to 17.3% of borrowers in July, equating to an annual rise of 0.3 percentage points. At the same time, the standard variable interest rate measured by the RBA averaged 5.25% in the three months ending July 2017, down from 5.40% recorded in the same time period a year earlier. Between these two yearly periods, the number of mortgage MORTGAGE
holders deemed to be ‘at risk’ rose from 17.0% to 17.3%, while those ‘extremely at risk’ increased from 12.4% to 12.8%. Roy Morgan found that the main reason for these trends is that household incomes have not kept pace with loan volumes. Over the past year, the median household income only increased by 2.0%. In contrast, the median amount borrowed increased by 7.4% and the median amount outstanding rose by 13.1%. “It appears from this research that fewer people are taking out home loans and those that do have increased their borrowings, most likely as a result of low
interest rates and rising house prices,” Roy Morgan industry communications director Norman Morris said. “With median household incomes among borrowers showing low growth over the last year, they are not paying off their loans as quickly and as a result [loans outstanding] are growing faster than household incomes.” The result is that one in six borrowers face a potential problem, he said. “When rates eventually rise, this is likely to lead to an even lower number of borrowers but existing mortgage holders who have borrowed in a low interest rate environment are likely to face increased levels of mortgage stress. “The final impact, however, will also be determined by what happens to household incomes, which are currently showing very modest growth.”
VV$40,614,829,064 AUSTRALIAN HOUSE PRICES HAVE SOARED FAR ABOVE ACTUAL CONSTRUCTION COSTS Source: Master Builders Australia estimates
Index: 1970=100 600
House prices have grown 3.6 times faster than construction costs since 1970
Real construction costs 500
600 500
Real house prices 400
400
300
300
200
200
100
100 1970
8
www.brokernews.com.au
1974
1978
1982
1986
1990
1994
1998
2002
2006
2010
2014
NEWS
TECHNOLOGY
WHOLESALE FUNDER LAUNCHES BROKER APPS funder Advantedge has launched a number of digital tools aimed at improving the home loan process for brokers and customers. Brokers now have access to two mobile apps – IDme and ZipID from MSA National and Equifax respectively – to collect customer identification documents. The apps assist brokers in submitting a quality application the first time around, resulting in a smoother settlement process. This also ensures greater transparency, with brokers receiving notifications when customer documents are received, signed and submitted. WHOLESALE
AGGREGATOR UNVEILS TRULY CONNECTIVE TECH SOLUTION The new system will allow integration between hundreds of software platforms and the creation of bespoke programs for brokers aggregator Connective has unveiled a new strategy for the development of its Mercury CRM system that will dramatically expand the capabilities of member brokers. At a PD day in Sydney on 26 September, director Mark Haron spoke about the Mercury API and the myriad of broker tools that could stem from this system. API stands for application program interface and is a set of digital rules that allow different software to interact seamlessly. The Mercury API, which allows the CRM to interact with hundreds of apps, was developed when Connective decided to leave some functionality up to the user. “In this process, it allows [brokers] NATIONAL
to choose the best tools that suit what you want to do with your business and the direction you want to take your business,” Haron said. The Mercury API will allow the services that brokers currently use, such as Xero, MailChimp or Microsoft, to work within the CRM system itself so that the programs are able to share and move data between them. Connective has made the API easy to navigate for brokers, Haron said. “Some Connective brokers with a little bit of insight in IT have managed to integrate the API themselves without any experts there,” he said. The Mercury API can also make use of ‘connectors’ – pre-built tools that integrate Mercury with other
apps – and Connective is already integrating with the Zapier and Microsoft Flow platforms. “These are built by Connective on top of our API. They don’t need a lot of skills in terms of coding and development.” As an example of how broad the benefits are, Haron said Zapier had already built API integration hubs for over 750 apps developed by other companies, including accounting platforms such as Xero. Haron also revealed that Connective was currently conducting a pilot with the MyMarketing platform, which both aggregator and member brokers could use to develop customised marketing campaigns. “The tool we’re using for that is called Active Campaign. One of the reasons we’ve picked that is that it has that API capability. We’ll be able to plug that into Mercury.” Through this, brokers will be able to quickly make changes to any newsletter they send out without the need for input from Connective, he said.
RATE OF GROWTH IN HOUSING MARKET SLOWING Source: ABS, CoreLogic
Quarterly change in combined capital city dwelling values
6%
CoreLogic
ABS
4% 2% 0% -2% -4% Aug-05
10
www.brokernews.com.au
Aug-07
Aug-09
Aug-11
Aug-13
Aug-15
Aug-17
E-CONVEYANCING PLATFORM REMOVES PAIN POINTS platform Titlexchange has partnered with two leading brokerages and is in talks with more to eliminate inefficiencies. Used by more than 1,000 brokers at both HashChing and eChoice, the platform automates the conveyancing process and matches buyers and sellers with a local conveyancer. “The lack of standardisation and automation in the conveyancing process is a real problem,” said managing director of Titlexchange Gerard Healy. “We want to automate and streamline the process for consumers, conveyancers.” E-CONVEYANCING
AD
NEWS
R E G U L AT O R S
MORTGAGORS STRUGGLING UNDER RATE HIKES significant percentage of mortgage holders are struggling to cover their monthly repayments, while a large proportion have already been slugged with higher interest rates despite the official cash rate remaining steady at 1.5%. The research commissioned by iSelect suggests that 33% of 1,000 surveyed households have seen their interest rates increase in the past year, which could be connected to the fact that 25% said they were experiencing difficulty in making their mortgage repayments. A
HEAT ON BANK-OWNED AGGREGATORS Several non-major banks have called for greater scrutiny of bank-owned aggregators to boost competition in finance
joint statement by five leading non-major banks has called for policy reform around brokers and aggregators that are owned by the major lenders. In their submission to the Productivity Commission’s Inquiry into Competition in the Australian Financial System, AMP Bank, Bank of Queensland, Bendigo and Adelaide Bank, ME and Suncorp zeroed in on these bank-owned aggregators as a “fundamental” area that must be addressed “if we are to realise a truly competitive sector”. They proposed that any aggregators and brokers owned by the major banks should publicly report on the proportion of loans directed to their owners. “While we do not suggest that A
REG TREND ‘HOSTILE’ TO SMALL BUSINESSES brokers in Australia may be feeling squeezed by government regulation, this trend is not unique to this country but one being experienced by small businesses worldwide, says Adrian Pay, EMEA director of regtech firm Dynamic-GRC. The industry has seen an influx of heavier regulation because brokers have not been effective in lobbying government against these changes, he said. Moving forward, he said industry associations had a huge role to play in helping brokers save time in keeping up with rapid changes. WHILE
12
www.brokernews.com.au
major banks should be restricted from owning broker networks, we do believe that where this occurs, it should be managed in an open and transparent way to ensure customers are able to make fully informed decisions.” They pointed to the findings of ASIC’s Review of Mortgage Broker Remuneration that major bank ownership of broker platforms influenced the proportion of loans the owner received from its brokers. “This is a regulatory concern because mortgage brokers are obligated to ensure consumers get the most suitable loan product,” the banks wrote. With smaller physical branch networks and a dependency on unbiased distribution channels, “regional banks support strong
regulation in this area, including effective ownership disclosure obligations”. In a separate submission to the Productivity Commission, NAB said vertical integration (VI) of banks and aggregators provided benefits to both consumers and brokers. The three NAB-owned aggregators – PLAN, Choice and FAST – represent around 30% of brokers in the market and offer access to approximately 40 lenders and their products, the bank wrote. “NAB’s continued investment in aggregator systems and processes supports brokers to run their businesses,” it said. “This VI model offers significant benefits to consumers, provided the appropriate remuneration, compliance and governance structures are in place. NAB, and each owned aggregator, has rigorous processes to manage conflicts, including perceived conflicts, to protect the interests of customers and brokers.”
BANKS ARE LEADING CHANNEL FOR CONSUMER CREDIT DISPUTES AT FOS Source: FOS Annual Review 2016-17
69%
Bank Credit provider
23% 3%
Data collector or buyer
2%
Credit reporting agency
1%
Credit union
2%
Other* 0
10%
20%
30%
40%
50%
60%
70%
*Including finance broker, mortgage broker, mortgage aggregator and mortgage manager
80%
HOME LOANS AMONG TOP CREDIT-RELATED DISPUTES ACCEPTED BY FOS Source: FOS Annual Review 2016-17
Credit cards
38%
Home loans
27%
Personal loans
21%
Investment property loans
5%
Hire purchase/ lease
2%
Line of credit/ overdraft
2%
Non-FSP debt
2%
Other*
4%
0
10%
20%
30%
40%
50%
60%
*Construction loans, equity release, interest-free finance, short-term finance, not yet determined
ABA RESPONDS TO WA BANK TAX REVIVAL Treasurer Ben Wyatt has said the state’s controversial bank tax could still be on the table, but the decision is now in the federal government’s court. “The state got rid of its bank taxes as part of the GST deal. But if the GST system isn’t working, then we will have to look at a bank levy,” Wyatt said. ABA CEO Anna Bligh expressed her disappointment that the WA government was targeting one industry in an attempt to restore the state’s budget. WA
FE AT URES
COVER STORY
A SYMBIOTIC RELATIONSHIP Non-bank lender Sintex has responded to the tightening of the banks’ lending criteria by opening up its broad spectrum of products to brokers directly, a move it says acknowledges that growing its business is closely intertwined with supporting and serving the third party channel KEY BUSINESS METRICS
11+2
staff members + directors
145
brokers have direct access to Sintex’s product offering
80%
of Sintex business written through a broker, either directly or through an accredited mortgage manager
$796,000
average commercial loan size settled in last 3 months (including SMSF)
$430,000
average residential loan size settled in last 3 months (including SMSF)
Under
14
Under
62%
69%
weighted average original LVR for residential loans
weighted average original LVR for commercial loans
www.brokernews.com.au
Sintex “we’re definitely not suits”, says the non-bank lender’s general manager, Cathy Dimarchos. Minutes after we meet, she proves it: she hands me a small bag containing two of her handmade soaps, a side gig she started to fund her volunteer projects in Tanzania. Dimarchos is a former ‘suit’, otherwise known as a banker, as are the company’s founders and directors, James Christie and Peter James. She left corporate banking 20 years ago, discouraged by where it seemed to be heading, and now assists the two directors in overseeing a family-friendly atmosphere at Sintex. “I like to actually feel that our business is about people and families, and we treat our customers in kind. It’s really hard to do that with the banks: everybody is on KPIs; it has AT
Corporation, it only branched out into residential lending about five years ago. It now boasts a suite of commercial and residential products covering the FHB, SMSF and full- and low-doc spaces. Resi Mortgage was sold to YBR in 2014. Since Sintex doesn’t sit on any major aggregator panels, it has traditionally relied heavily on mortgage managers for distribution, and it has often been used by them as a white-label product. While that is still a very important source of business, over the last five years Sintex has been gradually granting accreditation to brokers with an ACL to work with them directly. It now has 145 brokers on board. The relationship between brokers and Sintex is mutually beneficial, Christie says. “The broker network offers a solution for both the customer and for us, in that they can
“For us it’s not about volume; it’s actually about the longevity of a relationship. That’s what we’ve always been in the business for – long-term relationships” Cathy Dimarchos, general manager become a very different business,” Dimarchos says. Sintex’s name may be unfamiliar to some brokers. Established as a wholesale commercial funder in 2004 to complement the founders’ retail business, Resi Mortgage
deliver the client’s information that will facilitate the customer’s needs in a suitable loan from Sintex. If anyone is looking for growth in their business, it will inevitably need to include the broker network.”
The Sintex team
What brokers can expect from the non-bank lender is innovation, an array of product choices, a competitive price and return, and stellar service and speed of reply, James says. Its turnaround time for all loan applications is within 48 hours. Sintex was one of the first lenders to offer long-term solutions to borrowers for its commercial loans, and it controls its own IT software and CRM through its affiliated company, Loanworks Technologies. “The broker channel’s expansion is a reflection of the banks tightening their lending parameters. Growth is our main
In partnership with
goal, as with growth we are able to present new products to market. We are also working to make the process as automated as possible without deleting the most important one-to-one contact in the process,” James says. While the accreditation process is quite rigorous, Dimarchos says those who are serious in the business will already have what they need, including the necessary references, qualifications (ACL, Cert IV) and a police check. Once completed, brokers will gain direct access to credit. Dimarchos knows brokers have heard this line before, but she says Sintex takes that commitment seriously.
The credit team crunches the numbers, but the back office and customer service staff are trained to help and support
the time to run through a deal with [brokers]. They will even sit there and do a capacity calculator for them and say, ‘No, this is where
“If anyone is looking for growth in their business, it will inevitably need to include the broker network” James Christie, director them in that process to prevent a backlog and make sure it’s a smooth experience for brokers and mortgage managers. “Credit will sit there and take
you’ve overlooked something in financials or tax returns’, so it is genuine direct access to credit,” Dimarchos says. As Sintex bolsters its BDM team
this year, those employees will also be trained in credit before hitting the road. “Whilst our BDMs are salespeople, they actually need to understand credit and what will make a deal a deal,” she says. If a deal doesn’t make it across the line, it goes back to Dimarchos for review. She tries to figure out what stopped it and whether there’s any solution, then provides feedback to the broker. “I think people are quite surprised by that. It’s time that we put in. We could just let a deal walk out the door, but it’s not about that,” she says. Russell Henshaw, state sales manager at mortgage manager Australian Financial, has been working with Sintex for the last 12 years. His firm has written both commercial and residential loans with Sintex, including for first home buyers with little to no genuine savings, investors looking for a high LVR, commercial purchases and refinances, and commercial SMSF loans. “We have built up a very good relationship with the credit and settlement staff. They are very quick in answering any questions or scenarios we have. This enables us to reply to our broker network in a timely fashion. They also try their best to assist if at all possible, whether it is a loan application or a settlement issue,” he says. As brokers seek out alternative ways to satisfy their clients’ increasingly diverse and complex needs, their interest in Sintex and what it offers is growing. Sintex is already seeing that come to fruition and is moving to a larger office space a few floors down in its Sydney building to accommodate its burgeoning team. “For us it’s not about volume; it’s actually about the longevity www.brokernews.com.au
15
FE AT URES
From left: Peter James, Cathy Dimarchos and James Christie
of a relationship. That’s what we’ve always been in the business for – long-term relationships,” Dimarchos says. Survival of the fittest As much as Dimarchos distances herself from the rigid corporate suit stereotype, she admits that coming from an old-school banking background has given her a different way of looking at lending. Instead of relying on a matrix, as contemporary bankers do, Sintex looks at a whole spectrum of criteria to get a holistic view of the borrower’s profile now and for the future. “When staff come in here to do credit, they’re trained the old traditional way. It’s about a commercial proposition. It’s not about fitting a matrix. It’s about 16
www.brokernews.com.au
how does this deal actually really work; how can we make it work?” she says. One thing Sintex doesn’t do is cross-collateralise. “We don’t
customers have peace of mind that their loan will be available for the ‘life of the loan’,” Christie says. The GFC hit Australia four years after the company was founded,
“The broker channel’s expansion is a reflection of the banks tightening their lending parameters. Growth is our main goal, as with growth we are able to present new products to market” Peter James, director revalue securities and we don’t have annual reviews; as long as the clients’ loans are being maintained and repayments are being met, the
and yet Sintex was one of the non-bank lenders that survived. Sintex is now one of the cohorts defining the accelerating non-
bank space. Dimarchos thinks non-banks will claw back a bit of their pre-GFC market share, and as a result will provide consumers with a more even playing field. What the GFC did prove is that, no matter what the challenges are, the mortgage industry is resilient and will move forward and adapt as necessary. For brokers looking to plan for the future, Dimarchos suggests looking at the big picture. “For me, it’s about having the broker take one step back and having a holistic view of what they’re doing for that customer sitting in front of you. I think when you do that, these challenges are actually not challenges; it’s actually crystallising now what you should be discussing with your customer.” AB
www.brokernews.com.au
17
FE AT URES
NE WS ANALYSIS
TOO MUCH TO HANDLE? Brokers’ compliance responsibilities keep piling up, and yet with the industry deliberating over how to proceed with ASIC’s many recommendations on responsible lending, increased oversight and interest-only loans, there doesn’t seem to be any chance of this abating. But is all this compliance necessary? Anthony Knight, principal at Mortgage Choice in Erina, started as a mortgage broker 20 years ago, an average residential loan application took him about two hours to complete. Today, applications can take about seven to eight hours each. SMSF loans are even more time-consuming. A recent application Knight completed for a $450,000 loan included 300 pages of documents. One email had 23 attachments. Part of the reason it takes so much longer for brokers to complete a loan application these days is the significant increase in compliance requirements, a trend that is not going away. How the industry moves forward with the recommendations of ASIC’s Review of Mortgage Broker Remuneration report will partly shape how much more oversight and compliance brokers will have to contend with in the future. While compliance can be timeconsuming, one industry association says it is integral to improving the trust and confidence of consumers and regulators for long-term industry sustainability. But with no obvious end in sight to the amount of work involved, some brokers are wondering whether too much compliance could backfire.
equals money’ equation. But he also knows that it’s here to stay. “As our industry grows and matures, we are seeing increased regulation and external reviews aimed at improving consumer outcomes. These will inevitably lead to increased compliance obligations,” Felton told Australian Broker. He points to ASIC’s report on interest-only lending from September 2016, which highlighted that there was room for improvement in how brokers were demonstrating that interest-only products met consumers’ requirements and goals. The report suggested that brokers record a concise narrative summary of a consumer’s requirements and objectives and explain why a product and lender were chosen, to reduce the risk of being deemed non-compliant. It also recommended brokers provide
Effective compliance is essential MFAA CEO Mike Felton has a measured perspective on compliance. He recognises its importance in ensuring brokers do the right thing by their customers and protect their businesses from undue risks. At the same time, he acknowledges that it can be costly in terms of the ‘time
Transactions
6%
Disclosure
6%
WHEN
18
www.brokernews.com.au
that information to the borrower to demonstrate their understanding of the consumer’s needs and confirm that with their client. ANZ has taken heed of the directive. It recently released a 10-page “customer interview guide” for brokers, which outlines its minimum requirements for how brokers should be documenting conversations with borrowers. This prompts brokers to ask clients about their Netflix and Spotify subscriptions, as well as their alcohol, tobacco and gambling habits, to get a better understanding of their real living expenses. The guide “becomes a source of truth”, the bank said, which shows evidence of the broker’s conversation and can be referred to at any time by anyone to show there was justification for providing the client
with a particular loan. “In light of these reports and the ASIC interest-only review that is now underway, compliance will become more important than ever to protect our businesses, consumers and our industry,” Felton says. The answer is not necessarily more compliance, but finding a way to make compliance effective and efficient without adding unnecessary red tape, a task the joint industry forum is working on as it moves towards self-regulation. One thing is clear, Felton says: there are likely to be increased monitoring requirements going forward. Compliance support The sixth proposal of ASIC’s remuneration review addresses the oversight and governance of brokers. It suggests lenders and aggregators take a role in ensuring that brokers abide by consistent processes and reporting standards, and monitor their consumer outcomes. At FAST, CEO Brendan Wright says the aggregator has introduced a raft of support strategies to help member brokers stay on top of compliance changes. Its partnership managers and credit advice consultants, and its business operating platform Podium,
FOS-ACCEPTED CONSUMER CREDIT DISPUTES BY ISSUE Source: FOS Annual Review 2016-17
27%
Financial difficulty 23%
FSP decision 14%
Privacy and confidentiality 10%
Charges Instructions
7%
5%
Service 2%
Other* 0
5%
10%
15%
20%
*Advice, outside Terms of Reference, not yet determined
25%
30%
35%
40%
Raj Venga, ombudsman, CIO
Brendan Wright, CEO, FAST
Mike Felton, CEO, MFAA
Anthony Knight, principal, Mortgage Choice Erina
provide brokers with support and information to achieve their compliance objectives. “The area for everybody to be mindful of is recording information. Everybody’s busy – the consumer, the broker, the lender – so just take the time to succinctly record the outcome for that particular client at that particular time. That’s where there is an opportunity to be consistent and disciplined in that space,” he says. Knight says it’s a relief to him that the Mortgage Choice compliance team does the research and provides its brokers with a breakdown of the legislative analysis. The team tells brokers what to do and what new paperwork is required. The brokers then implement the changes into their workflow.
“I feel more comfortable having that backing and that expertise behind us to make sure we’re doing the right thing,” Knight says. “It would be very hard, I think, to sit there and work that out yourself. There’s no way in the world that you could make sure that you’re meeting with every legislative requirement without that backing.” The MFAA provides advocacy, education, tools and consultation to improve and reduce its members’ compliance workload. It successfully lobbied the government to change its original proposal for the ASIC Industry Funding Model, which would have placed a significant compliance burden on its members. It’s also updated its preliminary credit assessment tool and other resources on verification.
Is compliance working? One of the targeted areas that ASIC is looking at is responsible lending, and no one – not the big banks, brokers, aggregators or minor lenders – is exempt from scrutiny. “That’s where brokers, for example, have completely separate obligations under the law than the actual lenders,” says Raj Venga, ombudsman of the Credit and Investments Ombudsman (CIO), which deals with consumer complaints related to financial services providers. “The lender cannot rely on the broker entirely to do the responsible lending checks, and the broker cannot not do it and assume the lender will do it, because each of them is equally responsible.,” Venga says. Only 6% of the complaints the
CIO receives are against brokers and aggregators. Likewise, the Financial Ombudsman Service (FOS) says only 2% of its complaints are about brokers, aggregators, and mortgage managers. In comparison, 46% of CIO complaints are about residential lenders, and FOS has determined that 69% of its consumer credit disputes involved banks. “There’s a low interest rate environment and the housing market has been going gangbusters for the last few years; you’d think that we would see a lot more bad behaviour, with people trying to capitalise on this market, but we’re not seeing it yet,” Venga says. Felton says great improvements have been made over the past two years by both brokers and lenders in verifying income, expenditure and the suitability of products for customers. “I have confidence that the vast majority of our brokers are doing the right thing by customers. Indeed, all the available data supports this. Where we need to improve is best practice in documentation and compliance so our members can always easily demonstrate that when required.” Next steps forward While the increase in compliance might have had a cleansing effect on the industry and forced some of the ‘cowboys’ out, Knight doesn’t think any more compliance is necessary. “Unfortunately there’s been a knee-jerk reaction in regard to political pressure and lack of understanding of the role brokers play within the industry,” he says. “It’s a point of trying to strike that balance between making an industry really struggle under the weight of legislation versus being able to allow them to go out and do the thing that 99.9% of them want to do, which is go out and help customers benefit from competition. “I look forward to everyone catching their breath and realising where things are at and moving forward with a better balance in that regard.” AB www.brokernews.com.au
19
FE AT URES
OPINION
COMMERCIAL RENAISSANCE Dean Koutsoumidis, managing director of non-bank lender Equity-One, tackles the changes and challenges affecting commercial lending, and explains why brokers shouldn’t be afraid of having frank discussions with lenders
We provide an alternative for creditworthy, strong borrowers who simply are not being accommodated by the banks right now. Whilst we are happy to fund commercial property acquisitions, refinance, or cash-out on residual stock to further fund commercial opportunities, we do not lend on the increased value derived from DAs or ‘end-value’ rationales. Any good development starts with a good asset purchase for a fair price. We value it as such, with the understanding that even if the proposed development does not proceed the underlying asset value will not be compromised as it should have intrinsic value.
A
What questions should brokers be asking lenders? It really is about their relevance in the A marketplace. For example, our one-year fixed rate loans allow borrowers to repay after three months with no interest break fee/costs. This provides them with short-term solutions without paying typical ‘short-term prices’. Brokers are savvy and will quickly evaluate whether a lender is relevant and has a point of difference. Our strong suit is the ability to talk through and work with brokers to help them in whatever area they need. We are
Q
Has there been an escalation in commercial property value, and if so, how has this affected the market? Commercial property has, without a A doubt, enjoyed considerable growth in recent years. Not only has this been spurred by SMSFs and overseas buyers looking for stable economies and good assets, but the sector has experienced something of a renaissance as buyers are desperate for yield
What are some trends in commercial lending? Specialising in the commercial space A has always provided lenders with an opportunity to establish a niche in the market. Commercial lending today is no different, but it has been the subject of considerable attention. The most significant development is the gradual yet powerful impact of credit tightening by major lenders, which customers have endured since late 2015. Be it due to APRAinfluenced constraints, cost of capital, or general bank appetite for this sector, the result for borrowers has been significant and palpable. Borrowers who have traditionally experienced strong and fruitful dealings with their banks are all of a sudden not able to engage with them. This does not appear to have had a material effect on the value or liquidity of commercial assets, but rather the flow of commercial enquiry has been redirected to non-bank lenders. They are in vogue, again.
Q
Q
Do you expect restrictions similar to those placed on the residential sector to play out in the commercial space? Despite all the chatter about this, I feel A there are two types of people in this room: those who don’t know, and those who don’t know that they don’t know. The authorities have the ability to make sweeping changes in a variety of areas; however, some feel calm needs to be adopted. One of the key objectives of regulatory restrictions is to ensure the banks’ integrity and stability in the event of a financial shock. It is widely accepted that the prudential controls of the Australian banks are of the highest standard. The key focus is to ensure that this does not deteriorate. The need for these controls is also due to their dominance in market share. Smaller commercial lenders not only fall outside the banking system, they do not enjoy the same market share.
“If a lender’s products or service falls short, it is of high value if a broker feels comfortable enough to express that to them” in a low-yield, low-inflation world. Whilst growth in commercial property has been healthy, the real surge has been in development-related sites. Purchasers with appetites to buy sites valued in accordance with a projected end value have become prolific. Whilst buyers may be bullish in this area, it is for lenders to exercise caution. This, however, is not a unique or new risk. Valuing security with a moderate and considered approach should never go out of fashion irrespective of how heated a market becomes.
Q
20
www.brokernews.com.au
What are some of the challenges you expect in commercial lending? Like many businesses, lenders need to A evolve and stay relevant to their customers. This is because new lenders are always entering the market. Fintechs have yet to largely impact the market, but it is a challenge that will no doubt influence current business models. Finally, the major banks will be ‘back in the game’ again. Their current pull-back should be viewed as a phase and not a permanent fixture.
Q
Dean Koutsoumidis Managing director, Equity-One
Q
How does Equity-One take a prudent approach to lending?
deliberately old-fashioned in that we value personal service. Brokers shouldn’t be deterred from having an active dialogue with lenders. If a lender’s products or service falls short, it is of high value if a broker feels comfortable enough to express that to them. After all, the lender wants to accommodate them where they can. Brokers may be surprised what a frank conversation can achieve. How do you think APRA’s increased oversight of non-banks will affect the sector? If changes are measured, considered A and done via an effective consultative dialogue with market players, then I think it will be just another evolvement of regulation in this industry. This may well be a welcome change. Like any changes, however, the fear is that regulators will throw the baby out with the bath water. Overreaching changes have the potential of damaging a sector which provides a legitimate alternative for commercial borrowers who enjoy respite from the major banks from time to time. The government insists it wants to broaden competition, so any unmeasured approach may have the opposite effect. AB
Q
IN THE NE WS
RELATIONSHIP BUILDER Karen Brown tells us how she plans to get to know brokers and bring a fresh perspective to the industry as ANZ’s new national partnerships manager for residential brokers
which were ASX listed. While she was focused on an entirely different sector in that role, she said there were some similarities to her new position. “Some of the consistent themes include relationship management, as well as managing the impact of increased competition, digital disruption and regulatory changes, so I intend to bring an inquisitive mindset to my new role and draw
While working with brokers directly will be new to Brown, she has used a broker’s services herself, as a borrower. “I plan to take the time to get to know brokers and aggregators, not only at conferences and PD days but also by joining along with some of ANZ’s business development managers when they’re on the road, so engaging with brokers to get a deeper understanding of their
“I like to work collaboratively to build trust and integrity through interaction”
Karen Brown, ANZ
and insights with a view to improving mutual customer outcomes and ensuring that we’re meeting our responsible lending obligations,” she said. Prior to this appointment, Brown was a relationship manager at ANZ, with responsibility for overseeing large media, telecommunications, entertainment and technology companies, some of
businesses, what customer conversations they’re having, and any challenges they’re facing,” she said. Brown says she likes to work collaboratively to build trust and integrity through interaction. “I’m really open to speaking with brokers. Feel free to come up and speak with me. I’d love to hear people’s feedback and views,” she said. While Brown has no further long-distance hiking plans in the works, she is well prepared to take on any steep climbs the industry may present. AB
ANZ’S OWNER-OCCUPIER LENDING INCREASED IN AUGUST Source: APRA’s Monthly Banking Statistics
200 180 160 140 120 100 80 60 40 20 0
Owner-occupier
Investor July August
$792bn
$bn
are some things you should know about Karen Brown, ANZ’s new national partnerships manager for residential brokers: she’s managed relationships with ASX-listed companies in the media and entertainment world, she’s hiked the rugged 100km Kokoda Track, and she’s more than ready to tackle the ups and downs ahead for the broking industry. “I was looking for a new challenge in my career, and the national partnerships manager role provides me with great scope to develop some new skills while working in a dynamic, changing industry,” Brown told Australian Broker. Brown will be responsible for managing relationships with the bank’s key third party channel partners, navigating the regulatory changes impacting the broking industry, and communicating ANZ’s views and responses to these changes to aggregators. “This will include sharing data HERE
upon all of that experience that I’ve had,” she said. Given her diverse professional background and experiences, Brown says she’ll bring a “fresh lens” and a slightly different perspective to the industry. “I hope this will enable me to build upon the already strong customer service proposition ANZ has in the market in terms of its consistency, responsiveness and strong relationships, and I really intend to use a valuesbased approach to navigate through the changes in the industry,” she said.
$166.1bn
$167.3bn $82.7bn
Owner-occupier change: +$1.2bn
$82.5bn
Investor change: -$0.2bn
www.brokernews.com.au
21
PEOPLE
Have an interesting deal? Had a particularly difficult or interesting deal? Why not share it with us? Email:
Otiena.Ellwand@keymedia.com.au
A BIG DEAL
deadline on the commercial purchase was fast looming! THE SOLUTION
Want to know how to settle a deal when a council office containing critical files burns down and your clients go on vacation during the approval process? Just ask Cube Home Loans broker Scott Beattie
THE FACTS
Loan size and term $520,000 for 30 years
Client De facto couple
Goal Commercial premises for yoga studio
Location Gold Coast
22
www.brokernews.com.au
Funder RedZed and Liberty Commercial
doing and what it meant for her. The clients also went overseas during the approval process. Once we got conditional approval, the clients moved to valuation of their residential property (at their cost), and as they were overseas we had to wait for the bank transfer to hit the lender’s account as they didn’t want to pay on credit card. The valuation went ahead; however, it indicated that there were renovations that were not yet council approved, causing a reduction in the valuation amount as the non-approved renovations were excluded.
THE SCENARIO
A referral from one of our lead sources, the clients approached me needing a low-doc loan so they could purchase a commercial building to host their yoga studio. They had bank statements and an accountant verification/declaration. Both applicants were separately self-employed and had a relatively low LVR on their current home, with some other minor debts. The plan, given the equity in the home, was to refinance their ANZ home loan, consolidate their debts, and provide sufficient cash to purchase the commercial dwelling and fit it out on a low-doc basis. So, Loan A for personal and Loan B for commercial were secured against their principal place of residence to keep the loan at residential rates. After lengthy discussions with the clients, the accountant and the mortgage manager, and in conjunction with the verifiable income available, we provided a solution with a low-doc refinance and cash-out against their PPOR with two loan splits (private and business/Loan A and B). There were many complications, including that the male applicant was extremely time-poor and the female applicant had little financial understanding, so it was very time-consuming to explain things in a way that ensured she knew what we were
Lender Better Mortgage Management
Thankfully we were dealing with a mortgage manager with multiple funders, so we were now able to add the commercial property to the mix on a ‘no doc’ basis via Liberty Commercial. The only downside was that there were only 10 days left to go from lodgement to approval with a commercial valuation. We ended up doing two separate loans with three separate loan splits: one loan split against the commercial purchase and two loan splits against the couple’s home (one split for the refinance of the owner-occupier loan and one split for the shortfall of the commercial purchase). When the first two loans were finally approved, they were posted to the clients by the respective lenders. Unbeknownst to us, the clients didn’t have a mailbox at their home so the loan documents were ‘parked’ at the local post office. Only when we checked with the clients to ask if they had received the documents did they think to verify at the post office. Once the documents were in the clients’ hands, we were able to certify and witness the documents to be returned for settlement. THE TAKEAWAY
The big advantage with this transaction was the combination of our experience as brokers and the mortgage manager’s, along with the relationship that we had with them and the clients. We were able to reassure the clients that, although there were some challenges, we were able to provide a solution and largely with the same lender, in this case Better Mortgage Management. Ultimately, the clients got the solution
Once the clients returned from overseas and tried to source copies of the approvals, unbelievably, they couldn’t because the council office had burnt down
Scott Beattie Broker at Cube Home Loans in Queensland
Once the clients returned from overseas and tried to source copies of the approvals, unbelievably, they couldn’t because the council office had burnt down, destroying the plans and records. (This was apparently done pre-electronic copies.) The new problem was that without the council-approved plans the valuation was short and the finance
– their private and business debt was separated, the commercial property was purchased, and they were able to open their yoga studio at their new premises. The absolute takeaway is to communicate with your clients, keep them reassured, and ensure that you keep up to date with lender training so you ensure the best possible outcome for your clients. AB
www.brokernews.com.au
23
PEOPLE
Get involved in the discussion Share your thoughts at
brokernews.com.au
FROM THE FORUM
Top comments from trending stories on brokernews.com.au
RESEARCH FIRM CALLS FOR BROKER REFORMS IN ASIC SUBMISSION
UBS FOLLOWS UP CONTROVERSIAL ‘LIAR LOAN’ REPORT
Mortgages are not simple consumer credit products, and broker commissions create a poor alignment between broker and consumer interests, says financial consultancy firm Rice Warner in its submission on ASIC’s Review of Mortgage Broker Remuneration. The submission suggests that the duties and remuneration structure of mortgage brokers be brought into alignment with those of financial planners implemented after the Future of Financial Advice (FOFA) reforms. To determine how broker remuneration should work, Rice Warner recommended that “the principles and provisions established by the [FOFA] reforms in respect of remuneration, and especially conflicted remuneration, should be the industry benchmark”.
Following hot on the heels of its controversial ‘liar loans’ report, global investment bank UBS has released a second paper on interest-only lending, again putting brokers in the firing line for “factual inaccuracies”. The new report is based on results from a survey of 907 respondents. It suggests that about a third of borrowers with interest-only loans are unaware of the type of mortgage they have, citing financial illiteracy as a prime factor. UBS found that those who got their loan via the broker channel were more likely to be under high financial stress from recent rate rises.
After 20 years in the finance industry, much of it in senior management roles working for an international bank, I have rarely seen such a poorly ‘researched’ research report. The author and peer reviewer completely fail to consider the consequences of what would happen if their recommendations were implemented. The playing field is already tilted in favour of the banks, and the outcome of implementing this would move virtually all clients into their arms, giving the banks greater opportunity to gouge their clients. Smaller banks who see a significant part of their business delivered through the broker channel would also suffer, with the big four being the winners.
Just had a look at my loans written over the past 12 months, and knowing I have to do a ‘know your client/needs analysis’ with each one, each of those clients that took out interest-only loans in my opinion knew they were taking out interest-only loans. It’s documented by me in my notes, on the application form the clients sign, and also in the loan contract the clients sign. If UBS thinks people are not aware they are taking out interest-only loans, then I think UBS needs to get off their high horse and give the Australian borrowers a bit more credit for having some intelligence. Tim H on 5/10/17 at 9:19 AM
Rob – Perth on 07/09/17 at 10:26 AM
I wonder if the writer of the research paper, or the person who peer reviewed it, also spoke to a reasonable number of people who had approached brokers/credit advisers for advice/assistance? If he did so in preparing his paper, did he ask them if they would be prepared to pay a reasonable fee to their broker/credit adviser for the actual cost of providing the advice? I would be prepared to suggest that almost 100% of people using a mortgage broker for a residential transaction do so in part because there is no direct or indirect cost to them. The fundamental lack of understanding of the value of trail commissions to the relationship with a client is quite surprising. There is also no apparent awareness of the difficulty in collecting fees without the formal tripartite relationship between the borrower, lender and adviser. Credit Adviser on 07/09/17 at 9:12 AM
Oh UBS, your survey is really an advert; you need to survey a lot more people to statistically prove your assumptions. Your analysts are merely putting your opinion out there; hope they’re getting paid well because professionally no one will touch them after this. Us Aussies are not idiots. Certainly my clients aren’t, and for you to publicly name Australians as morons is appalling, shame on you. All this coming from one of the dodgiest financial institutions out there. Fairs Fair on 5/10/17 at 10:46 AM
I honestly think if any further air is given to this issue that brokers and the general population as a whole would be better served by having the actual details on this. What’s the sample size, what was the spread amongst states/age groups/income brackets? … Was there a decent spread, was it online only, what were the questions and were they objective or leading, and when was the survey done? Nick on 5/10/17 at 9:32 AM
24
I trust that Rice Warner disclosed their ‘conflict of interest’ in this piece of research being closely aligned with the superannuation and insurance industry. Let’s face it: fee for service only works for the higher net worth clients. Mums and dads will be priced out and will end up going directly to their bank. Back to the ‘good old days’, when they were not offered any choice and ended up paying more.
When will some organisation, such as MFAA or FBAA, or a ‘consumer watchdog’ group who supposedly act in the best interests of the public, blow the whistle publicly on UBS and their disgusting motivations, so that any publishing by them is simply binned as rubbish?
Sydney Broker on 07/09/17 at 9:14 AM
Ben on 5/10/17 at 11:46 AM
www.brokernews.com.au
CAUGHT ON CAMERA NAB hosted the ‘Connecting Brokers with our Bankers’ event in September at its new flagship branch in Sydney’s CBD to celebrate the success of its Customer Adviser Broker Program, an initiative that promotes better relationships between the retail channel and the broker network. Attended by over 80 brokers, this was one in a series of events NAB is hosting across Australia to discuss how the Customer Adviser Broker Program benefits brokers and their customers. The program helps brokers connect with NAB staff, including retail bankers, BDMs and broker distribution support staff, while successfully onboarding customers. NAB has been rolling out the Customer Adviser Broker Program over the last 12 months and has placed over 20 bankers that are dedicated to managing broker-introduced customers in NAB branches across the country.
www.brokernews.com.au
25
DATA
VICTORIA
SA SPOTLIGHT
Despite the influx of new stock, Melbourne’s economic strength keeps the capital going steady “It has a tendency to overbuild, but at the same time it’s a city that’s much more affordable than Sydney, so in a lot of ways the amount of development taking place is good for economic growth,” says Nerida Conisbee of REA Group. “A lot of that stock seems to have been absorbed – there’s a lot of interest from interstate and overseas buyers. There might not be enough tenants for all that development, though at the moment the vacancy rate is quite low.” Prices have increased as a result of this demand. CoreLogic’s Home Value Index results indicate that Melbourne’s dwelling prices jumped by 3.1% in July 2017. Population growth has been steady due to high job creation. The implementation of first home buyer incentives is also contributing to the rising interest. Nonetheless, growth conditions have slowed: the quarterly peak growth rate for 2017 dropped from 5.5% to 4.2% in the same month. Area
Type Median value
Quarterly
12-month
growth
growth
Melbourne
H
$720,000
8.3%
10.3%
VIC Country
H
$333,000
0.0%
3.5%
Melbourne
U
$522,000
6.5%
2.5%
VIC Country
U
$262,500
1.0%
0.4%
WESTERN AUSTRALIA
Following a period of downs, recent upticks in some suburbs are indicating a promising future for Perth “We’re starting to see some signs of positivity, but it’s very early days. The first sign was price growth in the Western Suburbs and those Northern Beaches suburbs,” says Nerida Conisbee, of REA Group. “Prestige suburbs are really starting to grow. Although Perth overall is going backwards, those suburbs saw 10–15% price growth over the past 10–12 months.” Conisbee believes interest in Perth is starting up again at least in part because many people consider the market to have bottomed out. “Economic growth is mildly starting up again, and there seems to be more sustained interest in Perth,” she adds. However, buyers do need to temper their expectations and not expect significant cash flow. “I think it’s close to bottoming out – it’s very difficult to tell. But don’t look to buy now and sell in 12 months. Area
Type Median value
Quarterly
12-month
growth
growth
UNDER THE RADAR Well-performing suburbs in specific areas keep Adelaide steady, despite limited upside and a weak economy
Adelaide, no news is good news as it continues to truck on in the middle of the pack, relative to property markets nationwide. According to CoreLogic, transaction volumes have remained generally stable. “Adelaide is OK. I think in terms of demand, it’s not as bad as Perth or Darwin, but it’s not as good as, say, Queensland,” says Nerida Conisbee, chief economist at REA Group. Certain parts of the metro are performing well, like Adelaide Hills and the suburbs in the inner-urban areas, indicating that select spots have potential for growth. “It’s a market that has pockets of very high demand. It’s not a growth economy historically – population growth isn’t strong. You’re not going to get the same levels of capital growth as Melbourne and Sydney have experienced over the last few years, but there are some areas that people do seem to want to be in and that seem to be seeing quite good price growth,” Conisbee explains. Nonetheless, economic issues continue to plague the state. While the submarine project won by Adelaide could generate employment opportunities, Philippe Brach, CEO of Multifocus Properties & Finance, believes the number of jobs created will not change the game for Adelaide. “They’re losing a lot more jobs in the manufacturing industry than they’re gaining. It’s one of those areas where there’s nothing much happening, so it’s just bumping along. The upside is fairly limited when you compare that to the eastern seaboard, that is, Melbourne, Sydney, Brisbane,” Brach says. AB
H
$505,000
-1.0%
-2.5%
Median price (houses)
WA Country
H
$340,000
-5.9%
-4.9%
$440,157
Perth
U
$400,000
-2.4%
-2.4%
WA Country
U
$285,000
-2.9%
-5.1%
www.brokernews.com.au
Dwelling values in Adelaide have increased by 5.2% over the past year, but by only 0.2% in the last three months The slowdown in property price growth in the last quarter could be attributed to the winter months when activity is usually at its lowest. Historically, the Adelaide property market is relatively stable and consistent. We tend to grow, plateau, grow, plateau, and repeat, as compared to the rollercoaster of the eastern seaboard. Over the past year there has been less stock on the market, and recent figures from CoreLogic confirm this. They show that the number of newly advertised listings in SA are 4.8% lower than they were a year ago, with also a slight decrease in total listings. The Adelaide property market has not been helped by the wet-blanket approach by APRA and the lenders in their attempt to cool the overheated housing markets in Sydney and Melbourne. And the lack of stamp duty concessions for first home buyers here in SA compared to other states is obviously not helping to stimulate the property market either. There are still opportunities for those looking to buy; people just need to have the right advice and guidance from mortgage experts and tax specialists.
Weng Wong Director, Equatorial Finance Solutions
SUBURB TO WATCH: SEACOMBE GARDENS
Perth
26
BROKER PERSPECTIVE
FOR
Median price (units) $424,896
Source: CoreLogic
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
2.9%
8.8%
14.9%
4.6%
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
0.6%
6.9%
9.6%
4.6%
AUSTRALIAN CAPITAL TERRITORY
Investors flock to Canberra, which offers stability and reasonable growth potential OPPORTUNITIES AND KEY INFRASTRUCTURE
Water infrastructure
Future planning
Flashy laneways
Netball fans rejoice
Northern Adelaide Irrigation Scheme expected to create 3,700 full-time jobs
Green light given to reinvigorating the city’s Central Market Arcade
Concept design revealed for Bentham Street – part of $14.6m laneway transformation
Two of Adelaide’s top netball facilities set to receive a $7.7m upgrade
HIGHEST-YIELD SUBURBS IN SOUTH AUSTRALIA Suburb
Type
Median price
Quarterly growth
12-month growth
Coober Pedy
H
$78,000
20%
18%
Peterborough
H
$78,500
-17%
-8%
Whyalla Stuart
U
$76,000
-11%
-24%
Whyalla Norrie
U
$85,000
-1%
-37%
Solomontown
H
$112,500
-9%
-33%
“Canberra is essentially driven by government activity. It is a lovely place, and it’s a city that was created to be in between Sydney and Melbourne for particular reasons. The more people you have in government, the more Canberra is going to profit. We’ll always have a government based in Canberra,” says Multifocus Properties & Finance CEO Philippe Brach. With this economic driver, Brach believes Canberra is a good alternative to markets on the east coast, like Sydney and Melbourne. As a result, price growth in Canberra is now the second strongest across the country. “The type of property that people want to live in in Canberra can range from apartments to big homes. It really reflects the fact that it is a government city, and lots of people move there because they’ve got jobs in government,” says REA Group chief economist Nerida Conisbee. Area
Type Median value
Quarterly
12-month
growth
growth
Canberra
H
$675,000
1.5%
6.2%
Canberra
U
$430,000
-2.3%
3.0%
www.brokernews.com.au
27
DATA
QUEENSLAND
Brisbane’s unit market is bloated, but houses near the capital offer value for money
CAPITAL CITY AUCTION CLEARANCE RATES
growth
growth
Brisbane
H
$525,000
1.0%
3.0%
QLD Country
H
$435,000
0.6%
1.5%
Brisbane
U
$400,000
-1.2%
-2.45
QLD Country
U
$375,000
-2.6%
3.1%
MEDIAN HOUSE AND UNIT PRICES
Sydney remains a very strong market, but lack of affordable housing continues to be a major problem
$1,000,000
Not sold
6
Clearance rate
79.3%
PERTH Total auctions
13
Sold
6
Not sold
2
Sydney Melbourne Brisbane Adelaide
Perth
75.0%
Hobart
$518,500
$290,250
$385,000
$400,000
$0
$505,000
$100,000
$306,500
$200,000
$435,000
$300,000
$545,000
$500,000 $400,000
$740,000
$700,000 $600,000
$728,000
$800,000
Darwin
Units
Canberra
CAPITAL CITY HOME VALUE CHANGES Capital city
Quarterly
12-month
growth
growth
H $1,025,000
9.6%
6.8%
NSW Country
H
$541.500
0.3%
7.0%
Sydney
U
$750,000
4.9%
3.8%
NSW Country
U
$385,000
4.1%
3.9%
www.brokernews.com.au
23
Houses
$950,000
$900,000
Sydney
28
Sold
$1,100,000
“Fundamentals are still holding up in the Sydney and Melbourne economies and they’re doing very well, but I don’t think price growth will be quite as strong as it was over the last 12 months,” says Nerida Conisbee, chief economist at REA Group. “The reason primarily is access to finance. The cost of finance interest rates is going up. Also, markets like Sydney are becoming a little too expensive, and I think affordability is really starting to push a lot of buyers out of the market, and they are either going to other areas or backing off and waiting to see what happens.” Although actions are now being taken to increase the budget for property construction in the state, Conisbee believes the policies hindering offshore investors could end up being a detriment to the market. Type Median value
40
Clearance rate
NEW SOUTH WALES
Area
Total auctions
$401,000
12-month
ADELAIDE
$633,000
Quarterly
$391,250
Type Median value
The combined capital cities saw significantly fewer auctions in the week ending 1 October, with a total of 953 held. This was likely due to most states having long weekends, as well as both the AFL and NRL grand finals taking place. Despite lower auction volumes, clearance rates held firm, returning a preliminary result of 69.4%, rising from 66.2% the week prior when final results saw volumes reach their highest level since May this year (2,782). Melbourne was the main driver of the strong clearance rate, with a preliminary result just under 90%. Over the same week last year, activity was equally subdued, with 872 auctions held and 75.8% successful. Brisbane was the only capital city to see a rise in volumes week-on-week.
$530,000
Area
WEEK ENDING 1 OCTOBER
$362,000
Brisbane is the market to be in if you’re looking for cash flow, but apartment values are being weighed down by excessive development. Brisbane’s dwelling prices slipped by 0.6% over July 2017, according to CoreLogic data. “Pricing in particular is subdued, and growth is subdued. Vacancy rates are rising for apartments,” says Nerida Conisbee of REA Group. “I think the problem areas are places where stock may have been developed to sell to investors – maybe lower-quality stock. Some of the stuff that’s not selling well or is seeing high vacancies is stock that people don’t particularly want to live in. Stock that will do well are the better-quality, better-located developments.” By contrast, houses are performing well in this area, especially with the recovery of the state economy. “The Queensland economy is growing, and it’s still seeing population growth. Job growth is fairly mild at the moment, but it will get stronger,” Conisbee says.
Weekly change
Monthly change
Year-to-date change
12-month change
Sydney
-0.1%
-0.2%
5.3%
10.5%
Melbourne
0.3%
0.8%
8.0%
12.1%
Brisbane
0.2%
0.3%
2.0%
2.9%
Adelaide
-0.1%
0.1%
2.7%
5.1%
0.1%
0.1%
-2.4%
-2.9%
0.1%
0.2%
4.9%
8.6%
Perth Combined 5 capitals
*The monthly change is the change over the past 28 days
BRISBANE CANBERRA Total auctions
44
Sold
28
Not sold
9
Clearance rate
Total auctions
140
Sold
42
Not sold
45
Clearance rate
48.3%
75.7%
SYDNEY Total auctions
597
Sold
309
Not sold
138
Clearance rate
69.1%
TASMANIA
MELBOURNE Total auctions
118
Total auctions
1
Sold
76
Sold
1
Not sold
9
Not sold
0
Clearance rate
Clearance rate
89.4%
TASMANIA
Area
The Apple Isle is in a boom period, but questions abound regarding how long its popularity will last Hobart continues to be one of Australia’s top-performing property markets. As construction activity remains light, vacancies continue to tighten. “Three consecutive years of fewer listings, combined with significantly heightened buyer activity, means that buying property in Hobart now is akin to a flock of seagulls fighting over a chip,” says Simon Pressley, managing director of Propertyology. “The volume of properties for sale in July [2017] was a whopping 23% lower than 12 months earlier. It’s now incredibly difficult to find that right property.” In addition to the limited development, affordability remains one of the main reasons the Hobart market is in such demand. “We’re seeing quite a few entrepreneurial-type people moving there to get affordable housing,” says Nerida Conisbee of REA Group.
100%
Type
Median value
Quarterly growth
12-month growth
Hobart
H
$390,000
1.0%
6.6%
TAS Country
H
$270,000
3.3%
1.9%
Hobart
U
$290,000
-6.5%
1.5%
TAS Country
U
$235,000
-1.2%
3.5%
All data sourced from CoreLogic.com.au
www.brokernews.com.au
29
PEOPLE
IN THE HOT SEAT A horrific first home buying experience inspired Alex Veljancevski, director of Eventus Financial, to become a broker, so others wouldn’t have to go through what he did. Here he tells us what he’s been up to, how the industry has shaped him, and what he’d serve the MFAA’s CEO for dinner
Who or what inspired you to become a broker? When I purchased my first home in 2010, I had a horrific buying A experience. I had no idea what I was doing, and the bank that I was dealing with for my loan approval would not answer my phone calls for extended periods at crucial moments. As a result, I felt alone in the process and it was an emotional rollercoaster. This experience inspired me to become a mortgage broker so I could provide others with exceptional service in an industry that can, at times, be overwhelming or stressful for many people.
Q
You were selected as one of MPA’s Young Guns in 2016. What has changed since then? That feels like a lifetime ago! So much has changed since then A that I don’t know where to begin. When I was awarded the MPA Young Gun 2016 award, I had only been in business for seven months and I was very fresh to the industry. Since then, I have opened up a second office in Bardwell Park in inner-west Sydney, and another loan writer has joined Eventus Financial. We are growing at a very rapid pace, and we’re constantly developing new processes to increase efficiencies within the business.
Q
What do you wish you’d known when you started out as a broker? The industry has been experiencing constant change since A I started as a broker. Therefore I cannot really say that I wish I knew anything in particular, as all the obstacles and challenges that have been presented along the way have helped me become a better broker.
Q
What was your first job? My very first job was as a Christmas casual at Kmart when I was A 15 years old. I don’t think I was any good though, as they didn’t extend my employment after Christmas!
Q
If you had the MFAA’s CEO over for dinner, what would you serve? Would I have to cook it? Cooking is not my forte, but for the A MFAA’s CEO I’d give it a crack. Perhaps I will whip up some grilled salmon with lemon butter sauce and some broccolini and carrots on the side! AB
Q
30
www.brokernews.com.au
THE CHOICE IS YOURS
MAGAZINE The only independent magazine dedicated to mortgage industry news, opinion and analysis
WEBSITE Breaking news, in-depth profiles, features, online forum and Australian Broker TV
ENEWSLETTER Daily news service delivered straight to your inbox every morning
FOR MORE INFORMATION, PLEASE EMAIL EDITOR@BROKERNEWS.COM.AU www.brokernews.com.au
31
32
www.brokernews.com.au