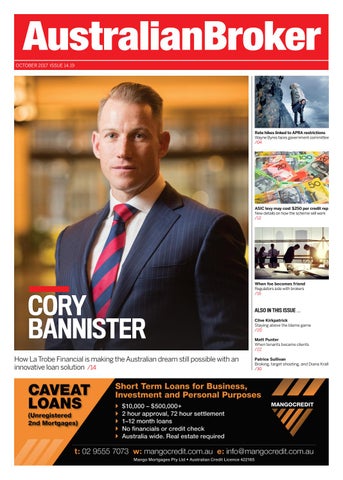
OCTOBER 2017 ISSUE 14.19
Rate hikes linked to APRA restrictions Wayne Byres faces government committee /04
ASIC levy may cost $250 per credit rep New details on how the scheme will work /12
CORY BANNISTER How La Trobe Financial is making the Australian dream still possible with an innovative loan solution /14
When foe becomes friend Regulators side with brokers /16
ALSO IN THIS ISSUE ‌ Clive Kirkpatrick Staying above the blame game /20 Matt Punter When tenants became clients /22 Patrice Sullivan Broking, target shooting, and Diana Krall /30
NEWS
IN THIS SECTION
Lenders Rate hikes a result of regulation, says APRA /04
Aggregators Majors’ market share rebounds
Brokers FBAA tackles mental illness
Regulators ASIC levy may cost $250 per credit rep /12
/10
/06
Consumers New loans vulnerable to market shocks /08
www.brokernews.com.au OCTOBER 2O17 EDITORIAL Editor Otiena Ellwand News Editor Miklos Bolza Production Editor Roslyn Meredith
DATES TO WATCH
Upcoming can’t-miss events
ART & PRODUCTION Design Manager Daniel Williams Designer Martin Cosme
10 OCTOBER – 1 DEC
11 OCTOBER
11 - 13 OCTOBER
Connective Conference 2017
Banking Innovation 2017
Credit Law Conference
Connective is bringing its conference to Vic, WA, Qld, NSW and SA on various dates from October to December. The conference promises to inspire brokers with new business development strategies, marketing techniques, insights from industry experts, and workshops on health, mindfulness and more
This Sydney-based conference will feature presentations from experts and disruptive innovators within the financial services space who will outline what the future holds for banking practices
The 27th annual event in Surfers Paradise brings together banks, credit unions, regulators, associations and market disruptors to discuss the future of credit and lending
Production Manager Alicia Chin Traffic Coordinator Freya Demegilio
SALES & MARKETING Sales Manager Simon Kerslake Account Manager Rajan Khatak Marketing and Communications Manager Lisa Narroway
CORPORATE Chief Executive Officer Mike Shipley Chief Operating Officer George Walmsley Managing Director Justin Kennedy Publisher Simon Kerslake Chief Information Officer Colin Chan Human Resources Manager Julia Bookallil
EDITORIAL ENQUIRIES
Otiena Ellwand +61 2 8437 4792 Otiena.Ellwand@keymedia.com.au
SUBSCRIPTION ENQUIRIES
tel: +61 2 8O11 4992 fax: +61 2 9439 4599 subscriptions@keymedia.com.au
24 - 26 OCTOBER
25 OCTOBER
Women in Leadership Conference
Loan protection webinar
This Sydney event features some of Australia’s most successful businesswomen, including the CEOs of Suncorp, the City of Sydney and Mirvac, who will share their stories of leadership struggles and accomplishments, and teach women how to drive career growth
At MPA’s lunchtime webinar you can learn about loan protection and why more and more brokers are making this an integral part of their offering
27 OCTOBER Australian Mortgage Awards This Australian Broker-sponsored awards show at The Star Sydney celebrates 16 years of excellence in the mortgage broking industry
ADVERTISING ENQUIRIES
Simon Kerslake +61 2 8437 4786 simon.kerslake@keymedia.com.au Rajan Khatak +61 2 8437 4772 rajan.khatak@keymedia.com.au Key Media Pty Ltd Regional head office, Level 1O, 1–9 Chandos St, St Leonards, NSW 2065, Australia tel: +61 2 8437 4700 fax: +61 2 9439 4599 www.keymedia.com Offices in Sydney, Auckland, Denver, London, Toronto, Manila, Singapore, Bengaluru
3 NOVEMBER
5 NOVEMBER
24 NOVEMBER
MFAA NSW Golf Day
Gong MS Ride
Head to the green instead of the office and enjoy a day of golf and networking with industry colleagues at the annual MFAA NSW Golf Day at Twin Creeks Golf and Country Club 45 minutes west of Sydney’s CBD
Pepper Money is inviting brokers to join its team ride for charity from Sydney to Wollongong on a 58km or 90km course. Meet some pro riders and brush up your skills at a practice clinic on 12 October
FBAA National Industry Conference
2
www.brokernews.com.au
This year’s conference on the Gold Coast will equip brokers and other industry members with useful knowledge and practical strategies to help them succeed in an increasingly challenging market
This magazine is printed on paper produced from 1OO% sustainable forestry, grown and managed specifically for the paper pulp industry Copyright is reserved throughout. No part of this publication can be reproduced in whole or part without the express permission of the editor. Contributions are invited, but copies of work should be kept, as Australian Broker magazine can accept no responsibility for loss. Australian Broker is the most-often read industry publication, according to independent research carried out by the Ehrenberg-Bass Institute for Marketing Science at the University of South Australia in December 2008. The research also found that brokers rate Australian Broker as the best for both news content and feature articles, followed by sister publication MPA. Overall, on all categories, Australian Broker ranks top followed by MPA. The results were based on a sample of 405 respondents who were the subject of telephone interviews.
NEWS
LENDERS PEPPER’S NEW AUSTRALIAN CEO
NEW INTEREST-ONLY LOAN APPROVALS HAVE DROPPED OFF SIGNIFICANTLY Source: APRA
Interest-only loans as a % of all new residential mortgage loan approvals
lender Pepper Money has appointed Mario Rehayem country CEO for Australia following recent growth of the Pepper business in its home market. “Mario has been a driving force behind the significant growth in Pepper’s Australian mortgages and personal loans business. During the past four years, annual volumes have continued to grow strongly under his leadership. The appointment of an Australian CEO reflects the Pepper leadership and reporting structure globally,” said Group CEO Mike Culhane.
40%
NON-BANK
35%
30%
25%
ME BRINGS IN $3.9BN OF LOANS VIA BROKERS lender ME has recorded NON-BANK its “biggest year to date”, with more than $3.9bn worth of loans coming through the third party channel. The bank’s financial results for FY17 showed home loan settlements were up 36% to $6.2bn, and its home loan portfolio increased by 12%. This means more than 60% of all settlements were originated via brokers. “Demand from brokers has continued to stay strong due to consistently competitive home loan rates and consistently high levels of service,” said broker GM Lino Pelaccia.
“Under my leadership, I intend to ensure that Pepper remains nimble and ready to take advantage of the changing landscape for lending in Australia, whilst always keeping the needs of the broker and the customer front of mind.” Mario Rehayem Country CEO for Australia, Pepper Money
4
www.brokernews.com.au
20% June-16
September 16
December-16
RATE HIKES A RESULT OF REGULATION, SAYS APRA The regulator’s chair has faced a government committee, answering questions about how the banks have implemented its investment and interest-only speed limits would not have increased their investment and interest-only rates were it not for speed limits imposed by APRA, the regulator’s chairman Wayne Byres has said. Byres made this statement at a hearing of the House of Representatives Standing Committee on Economics regarding APRA’s 2016 Annual Report on 13 September. Committee chair David Coleman brought up comments by CBA which alleged that rate hikes were implemented “in line with what our regulators require”. Byres said, “Many banks make similar statements and we’ve been blamed for all sorts of things.” APRA was “deliberately silent” on how banks should implement and BANKS
meet the investor lending and interest-only benchmarks, he said. “There have been changes to lending standards, reductions in maximum LVRs and other things. But there is no doubt that banks have used price as one way in which they have influenced customer behaviour,” he said. Byres acknowledged that rate hikes were indeed linked to restrictions brought in by APRA. “Based on what I know … the banks would not have made these interest rate changes if it were not for these regulatory initiatives.” Coleman remained unsatisfied, pointing out that rate changes affected banks’ existing books despite speed limits only applying to new lending. He asked Byres whether
March-17
June-17
these rate increases were a requirement rather than just a response to APRA’s restrictions. At first refusing to give a direct reply, Byres said bank statements linking rate hikes to regulatory measures were “vague and ambiguous”. Coleman then expanded his question, pressing Byres about a hypothetical situation in which a bank says, “We’ve done X in order to meet our regulatory requirements”, when in reality the bank has just used the regulatory requirements to increase interest rates in a manner that is in no way justified. “I don’t think that is OK. But I don’t have evidence that is the case,” Byres said. However, he stressed that APRA was not to blame for any rate hikes, saying “a direct assertion that we made them put up interest rates is clearly not true”. “We left it open to them how to respond to achieve the benchmarks we set. There are a range of levers they could pull,” he said.
NEWS
A G G R E G AT O R S AGGREGATOR APPOINTS NEW CEO veteran Scott McTeare will join My Local Aggregation, the aggregation arm of My Local Group, as its new CEO. He will drive its recruitment of brokers, as well as lead generation. My Local Group CEO Jaci Smith said: “This appointment allows me to focus on launching our other My Local Brands coming in 2018, including an all-in-one CRM designed to support financial advisers who are writing loans, and … adding real estate agents and accountants.” INDUSTRY
MAJORS’ MARKET SHARE REBOUNDS losing market share to the non-major lenders, the big four banks are making a comeback, bringing in more loans through the broker channel. These results come from the latest AFG Competition Index, which found that the major banks’ market share was 65.9% at the end of August after hitting a low of 63.3% in June. ANZ took the “lion’s share” of the fixed rate business, jumping from 10.5% in June to 20.8% in August. AFTER
SUBAGGREGATOR PARTNERS WITH INSURER The arrangement offers member brokers access to new income streams that align with clients’ residential finance needs subaggregator Diversifi has partnered with insurer Ensurance, allowing member brokers to offer home and contents insurance to their clients. Diversifi, which aggregates through Choice, teamed up with Ensurance after learning it offered insurance quotes directly through an online platform, Rose De Rossi, director of Diversifi, told Australian Broker. “We’re always looking at new income streams for our brokers or offerings for our clients – something that complements the home loan or finance options that they take with us.” Ensurance also has a multiinsurance offering, which makes PERTH-BASED
6
www.brokernews.com.au
the arrangement even more attractive, De Rossi said. Diversifi has added this platform to its website, which is easy for clients to access themselves through a simple login link. “We’re not actually providing any advice. We’ve just got the facility there if they want to use it, and they can make their own decisions as to whether they go ahead,” she says. “If they’re with a broker, the broker can sit with them and guide them through. They’re not actually providing a quote; they’re just going over the way to access the site and what clients need to do. The site then provides all the insurance quotes over a number of insurance companies and the client can take the next step themselves.”
In the event that a client decides to take out insurance through the platform, Diversifi gets sent a certificate of currency, which is one requirement for taking out a home loan. The subaggregator’s brokers will also gain commissions paid on the upfront of each policy sold. As part of the compliance process, all clients are asked whether they want to obtain a home and contents insurance quote at the start of the home loan process. “We’re making it very open. We’re telling them that they need to organise this. We can help them with it or they need to handle it on their own.” Since commencing the partnership two or three months ago, the subaggregator has brought in 10 policy quotes, two of which have been converted, she said. Diversifi currently has 11 loan writers and six agencies across Australia. Of these, five are in Western Australia and one is in Brisbane.
“We’re always looking at new income streams for our brokers or offerings for our clients – something that complements the home loan or finance options that they take with us.” Rose De Rossi Director, Diversifi
NEWS
CONSUMERS NEW LOANS VULNERABLE TO MARKET SHOCKS household debt and low wage growth continue to compound mortgage risks in the Australian market, Moody’s Investors Service has warned. Despite stable market conditions and predicted real GDP growth of 2.7% in 2018, loans underpinning residential mortgagebacked securities are at risk. “Mortgage loans originated in the past 12 months at the peak of the recent house price cycle and at worsening affordability levels will suffer the greatest losses in the event of a negative shock or interest rate increases,” said Moody’s Ilya Serov. HIGH
HIGH MONTH FOR UNIT COMMENCEMENTS saw an “unusually high” month for apartment and unit commencements in August, according to CoreLogic. “We saw the total value of new development applications in the pipeline over August recording an estimated $17.5bn,” said CoreLogic commercial analyst Eliza Owen. There was $5.6bn worth of construction commencing in August – nearly half (46%) in the apartment and unit space. Owen said this figure was above the six-month average share (31%) of apartment and units typically being built. AUSTRALIA
“Mortgage loans originated in the past 12 months at the peak of the recent house price cycle and at worsening affordability levels will suffer the greatest losses in the event of a negative shock or interest rate increases.” Ilya Serov Associate managing director, Moody’s Investors Service
8
www.brokernews.com.au
HIGHER CGT DISCOUNT FOR INVESTORS IN ‘AFFORDABLE’ PROPERY The government has released draft legislation that will increase capital gains discounts for investors dealing with affordable property newly released draft legislation, investors will be able to take advantage of a 60% capital gains tax (CGT) discount within the affordable housing space. In a joint statement on 15 September, Treasurer Scott Morrison and Assistant Minister to the Treasurer Michael Sukkar said the measure was “critical” to the government’s comprehensive housing affordability plan for Australians. “From 1 January 2018, residents investing in eligible affordable housing will be entitled to a capital gains discount of up to 60% if they UNDER
hold the investment for at least three years, rather than the standard 50% discount,” they said. The additional 10% will apply if a residential dwelling has been used to provide affordable housing for at least three years (1,095 days) over one or more time periods. The government has defined ‘affordable housing’ as residential premises both certified and exclusively managed by a community housing provider. Owners will not be eligible to receive a National Rental Affordability Scheme (NRAS) incentive, such
as a tax offset or payment, during the NRAS year. “These affordable housing measures provide an additional incentive to individual and institutional investors to increase the supply of affordable housing by allowing investors … to retain an increased amount of the capital gains they realise from their investments in affordable housing,” the draft legislation reads. These changes are listed in the Treasury Laws Amendment (Reducing Pressure on Housing Affordability No. 2) Bill 2017 and will amend both the Income Tax Assessment Act 1997 and the Taxation Administration Act 1953. The Treasury has asked for interested parties to comment on these proposed laws by either email or post. Submissions will be accepted up until 28 September.
NEWS
BROKERS
ONE IN FOUR CUA LOANS THROUGH BROKERS largest credit union, CUA, has reported that more than one in four of its loans came through the broker channel in FY17. “Around 41% of CUA’s mortgage lending was broker originated in FY17, which was relatively consistent with the previous year. We will continue to work closely with our growing network of more than 1,100 brokers to ensure we offer a consistent, high-level of service that matches their needs,” said CUA national manager of brokers Natasha Kelso. AUSTRALIA’S
BROKERS ‘CAN’T TURN A BLIND EYE’ TO MENTAL ILLNESS, SAYS FBAA The industry association says brokers need to be aware of the negative effects that their ‘highly stressful’ career could have on their mental health stresses come at brokers from multiple angles, which is why the FBAA recently held its first professional development day focusing exclusively on this topic, executive director Peter White told Australian Broker. “We are in a highly stressful environment. Living on commissions is not an easy gig, let alone the regulatory stress that we’re put under. It comes in different directions to us, and it’s just something we can’t turn a blind eye to.” More than 130 brokers attended the event in Melbourne on 14 September. Five specialist speakers presented, including Pedro Diaz, founder of the Workplace Mental MENTAL
Health Institute, and Beyond Blue ambassador Tony McManus. “Everybody was very supportive and very much on par with needing to have this conversation on mental health. As an industry, we tend probably not to talk about this,” White said. According to ASIC data, there are more than 26,000 consumer brokers in Australia, including those beyond the home loan space, White said. “With one in five people suffering a mental health disorder right at this moment, the person within a couple of desks of you is probably having struggles of their own.” It’s important for brokers to know the dark path these struggles could lead to, especially with one person committing suicide every three
hours in Australia from a mental health issue, he said. “We need to have the conversation sooner rather than later to make sure that people are OK, because once you get beyond that, that’s when you need professional intervention. Sometimes that comes a bit too late.” White believes the stigma around talking about mental health issues stems from broking being a traditionally maledominated industry. “Blokes just don’t talk about it, and they should. It’s not tough to talk about problems like this. Of course it’s not exclusive to men, but I think that’s part of the historic problem. We want to see those barriers removed. And of course this isn’t just a male problem. Sometimes it affects women as well, and in some areas more so.” The topic of mental health will also be on the agenda at the FBAA’s industry conference in November, with a presentation from Angry Anderson of Rose Tattoo.
THIRD PARTY SHARE OF HOUSING APPROVALS ON THE RISE Source: APRA
Non-majors
Majors
Total (all ADIs)
56% 50% 49%
46% 39%
10
www.brokernews.com.au
Jun 2017
Mar 2017
Dec 2016
Sep 2016
Jun 2016
Mar 2016
Dec 2015
Sep 2015
Jun 2015
Mar 2015
Dec 2014
Sep 2014
Jun 2014
Mar 2014
Dec 2013
Sep 2013
Jun 2013
38%
SMARTLINE WINS FRANCHISE AWARD has been recognised as the second-best franchise in Australia at this year’s Topfranchise Awards. “Smartline really is all about people, both from a client perspective and a franchisee perspective,” said Ian Winn, Smartline’s CEO. The franchise came first in the marketing category and did well in both the lifestyle and expansion categories. Despite not gaining the top spot this year, Winn said he was still pleased that Smartline’s overall rating had improved. He noted that there were still some areas for improvement. SMARTLINE
IF SMES WERE PM FOR THE DAY, THE FIRST THING THEY’D FIX… Source: Scottish Pacific SME Growth Index September 2017
24.3%
Streamline BAS reporting
22.1%
Fair Work Act
21.3%
Reduce company tax
8.2%
Remove payroll tax
4.5%
State compliance duplication
1.8%
Late payments penalty law
9.8%
Lighter governance/ compliance
8.0%
More equitable leave provisions
0
5%
10%
15%
20%
25%
30%
RESTRICTED POSTCODES IN BRISBANE AND PERTH has unveiled tighter lending policies for apartments in certain postcodes of Brisbane and Perth. The bank will restrict owneroccupier and investment lending to a maximum 80% LVR for apartments in designated areas in Brisbane, and will restrict investment lending to a maximum of 80% LVR for apartments in certain parts of Perth. “This update for a handful of Brisbane and Perth locations is part of our ongoing efforts to ensure we are lending responsibly and in consideration of all our regulatory responsibilities,” an ANZ spokesperson told Australian Broker. ANZ
NEWS
R E G U L AT O R S
‘BAD REGULATION COSTS THE COMMUNITY’, SAYS ASIC evidence points to regulation’s negative effects on industry, ASIC says a broad-picture approach is needed to draw out the benefits that such regulatory guidance provides. Despite the Productivity Commission’s 2006 findings that regulation introduces costs and impedes innovation, ASIC commissioner John Price said it was more prudent to consider the benefits that businesses receive. “Regulation is not bad. Bad regulation costs the community, but good regulation actually delivers for the greater good,” he said. WHILE
ASIC LEVY MAY COST $250 PER CREDIT REP More details have emerged about how much ASIC’s cost recovery scheme will set credit providers back
has revealed further details about the cost recovery model and annual levies that will affect all industry sectors under its jurisdiction. ASIC senior executive leader of deposit takers, credit and insurers Michael Saadat spoke about the scheme at the CIO’s Dispute Resolution Conference 2017 in Sydney on 12 September. He revealed that certain entities under ASIC would be slugged with two levies, and gave a rough estimate of how much credit intermediaries would be charged per credit rep. “Industry funding for ASIC will increase transparency, making industry more accountable for its behaviour by ensuring that those who are creating the need for regulation bear the costs. It is a ASIC
EX-AUTO FINANCE MANAGER CONVICTED OF FRAUD Robert Con Foo, of Victoria, has been convicted after pleading guilty to one charge of dishonestly using his position as a car finance manager with the intention of personal gain. He was fined $2,500 and ordered to pay costs. In October 2015, Con Foo falsified two letters from accounting firms that were used in support of car loan applications submitted to BMW Australia Finance on behalf of two clients. “Submitting fake documents so that your client can get a car loan isn’t a smart sales tactic – it’s illegal,” said ASIC deputy chairman Peter Kell. CHRISTOPHER
12
www.brokernews.com.au
critical component of the government’s plan to improve consumer outcomes in the financial services sector,” Saadat said. For credit providers, there will be a minimum levy of $2,000 plus 15 cents per $10,000 of credit provided greater than $100m, excluding small-amount credit contracts. For licensed credit intermediaries, there will be a $1,000 minimum levy plus a graduated component based on the number of authorised representatives under the intermediary as of 30 June 2018. The graduated component had yet to be fully determined, Saadat said. “It’s based on the total number of credit reps that will be in place at the end of June next year. As a guide, we expect it to be between $150 and $250.”
Licensees that act as credit providers and intermediaries would pay both levies, he added. Responding to questions about how costs would be determined, Saadat said ASIC had no control over the levies as the cost recovery scheme was a government initiative. “Our budget allocation is set by the government. The government then has passed legislation to recover those costs from the sectors that we regulate. It is a government decision.” While further details will be released in the coming months, Saadat also gave a rough guide to how the scheme will be implemented. In January 2018, an online portal will be launched to collect information from ASIC’s regulated population to allow invoices to be calculated. In April 2018, ASIC will then publish “indicative levies” for FY17/18. Between July and October 2018, all regulated entities will complete an online form for that financial year.
AUSTRALIANS’ TRUST IN THREE KEY INSTITUTIONS DIMINISHED IN 2017 Source: ABA
100%
2016
90%
2017
80% 70% 60% 50%
52%
57% 48%
45%
42% 32%
40%
100% 90% 80% 70%
52%
48%
50%
37%
60% 50% 40%
30%
30%
20%
20%
10%
10%
0%
0%
Business
Media
Government
NGOs
Financial services
TECHNOLOGY UPDATE
ANZ HELD LION’S SHARE OF MARKET IN AUGUST Source: AFG Competition Index
18.28% 20.82%
ANZ
18.50%
SALLY PROWSE GROWS HER BUSINESS BY 40% THROUGH INVESTMENT PROPERTY REFERRAL John Manciameli talks to Sally Prowse, CEO of Sandcastle Finance
19.99% 18.16%
14.25% 10.48%
CBA
10.95% 12.10% 16.79%
9.73% 17.72%
NAB
9.03% 11.09%
Sally Prowse
13.79%
What first attracted you to help your clients with their investment property aspirations? I’ve always had a passion for A property, and I completed a Property Investment Advisers course just before I started working with Slipstream, where I discovered some of the basic foundations. I love exploring the future with my clients and asking them: where do you want to be in 10–15 years’ time?
Q
9.66% 12.26%
Westpac
8.13% 12.91% 8.17%
0 Total
5% Fixed rate
10%
15%
Refinance
20%
25%
Investor
30% FHB
Why did you choose to work with Slipstream? Anyone who has started working A in the investment property space, whether it’s with their clients or just for themselves personally, will know how many cowboys there are out there. The industry is completely unregulated at the moment and so one of the biggest things that attracted me to work with Slipstream is that they are an aggregator of accredited research houses and buyers’ agents who you can really trust. I had the opportunity to meet the panel at the first Slipstream workshop I attended, and the high standard was obvious. They really understood the whole process from beginning to end and immediately set to work helping me to set out a realistic and manageable process I could follow.
Q
BROKERS ASSISTING SMALLER ADIS: APRA brokers have been recognised by APRA for their role in expanding the distribution networks of smaller residential lenders. In a recent submission to the Productivity Commission on competition in the Australian financial system, APRA wrote: “While smaller banking providers do not always offer the same account-based service or features, for instance widely available ATM or branch networks, they are to a large degree able to obtain wide distribution through the use of brokers and technological advances.” In addition to the four major banks, 38 smaller Australian-owned banks, 12 foreign banks, and 60 other ADIs offer residential mortgages. MORTGAGE
What are the key benefits of working with an independent aggregator of investment property research and buyers’ agents? A huge issue is knowing who to A trust in the sector, and this is a crucial component of the referral business, so knowing Slipstream has this covered is a huge weight off my mind.
Q
John Manciamelli
Slipstream’s vetting process for the research houses and buyers’ agents is really strict – this is the way you know you’re working with the best of the best in the industry. The other unique benefit of working with Slipstream is the access to expert advice, as well as opportunities to share and collaborate on ideas around marketing, business growth and investment opportunities. What feedback have you received from clients you’ve worked with? I work with mainly female clients, A and for many this is their first exploration into property investment. They honestly say to me it’s like a light bulb has been switched on. I have clients who are now on their third investment property, and they can’t get enough – they’re surprised at how easy it all is when you partner with the right companies, and wonder why they didn’t start sooner!
Q
How much has Slipstream impacted the bottom line of your day-to-day business? I’m delighted to say that last year A I saw a huge 40% profit increase, which I can attribute to this extension of my business. I started working with Slipstream in late 2015, so this is an incredible result to achieve in just two years.
Q
What’s the most important piece of advice you would share with other brokers who haven’t diversified their offering? I would tell them you have A nothing to lose. With the criteria around lending tightening all the time, this is an easy low-risk way to diversify your business while still operating in the property market.
Q
FE AT URES
COVER STORY
KEEPING IT IN THE FAMILY Australia’s housing affordability crisis isn’t going away, and with more first home buyers relying on their parents to fill the income gap, innovative solutions are needed now more than ever. La Trobe Financial’s Cory Bannister explains how the non-bank lender is making the Australian dream still possible THE P2C PROCESS
Parent / family
Investment interest & principal received; capital protected
P2C investment; CPI + 0.5% yield
La Trobe Financial P2C® Program
Interest & principal to LFS
La Trobe Financial loan to child
Child
14
a home is a cultural rite of passage in Australia, but this financial achievement has become increasingly out of reach for most young adults. According to a recent housing report from the Committee for Economic Development in Australia (CEDA), the median real house price has almost quadrupled since 1970, while annual wage growth continues to deflate, hitting a record low of 1.9% earlier this year. Giving up avo on toast for breakfast every Saturday isn’t going to make up for this massive shortfall, so there’s no wonder that strapped-for-cash young Aussies are turning to their parents for help. The ‘Bank of Mum and Dad’ has lent around $65bn to its children, making it the fifth-largest lender in the country after the major banks, research from financial comparison site Mozo.com.au has found. The study surveyed 1,002 Australians and found that one in three families have offered financial assistance to their children, and yet the majority – 67% of parents – don’t expect to be repaid. While turning to mum and dad for financing may seem like the easiest and most logical option, it’s not always a foolproof plan. Leading non-bank lender La Trobe Financial offers first home buyers a much-needed alternative. It was ahead of its time in 2014 when it created the Parent-to-Child Loan (P2C), a combined credit and wealth OWNING
www.brokernews.com.au
management product designed in response to the growing housing affordability crisis. It remains the only product on the market that formalises and protects parents who provide financial assistance to their child without putting their own credit record at risk, or requiring a personal guarantee where they’re using their own home as security. Many parents want to help their children get on the property ladder, but they may feel uncomfortable about handing over such a large lump sum as a
brokers to look to other segments to replace that business and to prepare in case of further restrictions. There are both short-term and long-term benefits for brokers who deal with first home buyers, Bannister explains. “In the short term, they fill a void left by other segments, and the long-term benefits begin by establishing a client relationship early in the credit life cycle. That is likely to provide many additional opportunities as the FHBs mature in their credit requirements – breeding plenty of repeat business.” How does P2C work? The P2C loan is based on the same model as the peer-to-peer loan. In this case, the parent is investing in their child’s loan. This can range from a partial amount to the full amount of the loan, and
“Many parents are choosing the benefits of providing a loan directly to their child to assist with the purchase. This is often the best option for parents” gift. Furthermore, gifts do not count as genuine savings, and lenders will require at least a 10% genuine deposit when assessing any home loan application. “As a lender known for innovation and focusing on underserved markets, P2C was a logical product development for us. The response to P2C has been very encouraging and extremely rewarding,” says Cory Bannister, vice-president and chief lending officer at La Trobe Financial. With the property investor market being subdued by regulators, it’s a smart idea for
is often anywhere from $50,000 to $500,000. The parent does not take a share of ownership in the property. The parent gets to set the dollar amount, the loan term (up to 25 years), and the initial interest rate (a minimum CPI + 0.5% is required) on the money they invest in La Trobe Financial’s independently managed Credit Fund. La Trobe Financial disburses the funds to the child and collects repayments. As long as the child makes their requisite loan repayments, the parent will receive a portion of
Cory Bannister, vice-president and chief lending officer, La Trobe Financial
their money back each month. La Trobe Financial deducts a 0.75% per annum management fee from the investor’s return and charges the borrower a $15 per month fee for managing the loan. Since the parent’s contribution is secured by way of a registered mortgage, they have rights to the money at all times in the event of non-payment by the child or following a marital or deceased estate dispute. There are protections in place for the child as well. They cannot capriciously be evicted, nor can their rate be changed by their parent in the case of a family feud, as the P2C loan is
managed independently. The contribution can be made individually, collectively with other family members, or via company or family trusts. This allows parents to help make their child’s dream a reality, while protecting their own investment and potentially saving their child thousands of dollars in lenders mortgage insurance by allowing them to purchase a property with the minimum deposit. Prior to this being available, parents had to guarantee the child’s loan or co-purchase the home, placing their own home and retirement savings at risk. This also meant that the child
missed out on the First Home Owners Grant and stamp duty concessions. “Increasingly, many parents are choosing the benefits of providing a loan directly to their child to assist with the purchase. This is often the best option for parents, as a loan is more transparent and will tend to give parents greater security in the event things go wrong,” Bannister says. This sort of secure intergenerational wealth transfer remains more relevant than ever, as the Mozo and CEDA studies show. In NSW, parents lent on average $88,250 per family, totalling
$32.7bn, the most of any state. Victoria and South Australia ranked second, lending around $63,000 per family, according to Mozo. While extremely generous, this is putting a strain on parents’ wallets, causing many of them to delay their well-earned departure from the rat race in order to help their children. “We know mums and dads around the country are assisting their children into home ownership, passing on the fruits of their baby boomer labour and prosperity. However, often it is with considerable risk to their ‘investment’, credit record or, even worse, their own homes,” Bannister says. This product benefits those who cannot afford permanently to tie their money into their child’s property, he adds. Despite maintaining a “fundamentally optimistic view” about Australia’s financial future, Bannister says La Trobe Financial acknowledges the real challenges young adults are up against when it comes to home ownership. CEDA’s research shows that there’s no quick solution to the housing affordability problem. Demand pressures and supply constraints will likely continue over the next 40 years, particularly in capital cities with booming populations. And if prices continue to increase at the rate they have, first home buyers’ ability to raise deposits will be outpaced and parents will be relied on even more. Bannister believes this is where brokers can help. “Brokers can step in and show leadership by discussing P2C with their clients, specifically how it protects parents’ investments and benefits the children.” AB www.brokernews.com.au
15
FE AT URES
NE WS ANALYSIS
WHEN FOE BECOMES FRIEND In a rare moment of celebration for brokers, ASIC, APRA and the RBA all spoke about the benefits the third party channel provides consumers, while a new report from UBS sparked outrage about brokers misrepresenting more loan applications the Sedgwick and ASIC reviews, regulatory changes and increasing angst and scrutiny of the broking profession, mid-September provided a rare ego boost for an industry that’s taken a bruising this year. In a rare showing, ASIC, APRA, the RBA and the major banks expressed some positive opinions about brokers and the outcomes they provide consumers. While they were not all talking at the same time or about the same thing, brokers were recognised in a favourable light by the regulators in a variety of ways – at a House of Representatives’ committee, in submissions made to the Productivity Commission Inquiry, and at an industry conference. AMID
Banks back brokers In separate submissions from RBA and APRA to the Productivity Commission Inquiry into Competition in the Australian Financial System, brokers were given kudos. The RBA recognised that the widespread use of brokers had created increased industry competition in residential lending, had led to greater lending efficiency, and had provided access to a wider range of products. “For borrowers, brokers reduce search costs by efficiently comparing deals across lenders. The introduction of a wider range of mortgage products, partly in response to prudential regulations, has increased the benefits for consumers of using brokers,” the RBA wrote. APRA noted the significant role brokers have played in expanding the distribution networks of smaller 16
www.brokernews.com.au
residential lenders, helping them gain market share. “While smaller banking providers do not always offer the same account-based service or features, for
competitively priced products, appear to have assisted smaller providers in gaining market share in the supply of residential mortgages.” NAB, CBA and Westpac also
“The introduction of a wider range of mortgage products, partly in response to prudential regulations, has increased the benefits for consumers of using brokers” RBA instance widely available ATM or branch networks, they are to a large degree able to obtain wide distribution through the use of brokers and technological advances,” the regulator wrote. “These factors, in addition to
expressed the importance of brokers in improving competition in the financial system. NAB said brokers are useful because they can assist “time poor customers to assess mortgage products across different financial
institutions and offer a differentiated and competitive value proposition compared with banks”. The lender also remarked that the 16,000 brokers in Australia, many of whom are small business owners, “form a significant part of the Australian economy”. CBA said it believed “brokers should and will continue to play an important role in the mortgage market”. Westpac said smaller lenders find brokers particularly useful. “These companies may offer competitive rates and quality products, notwithstanding that they may lack the presence (including physical footprint), size and marketing of bigger institutions,” the bank said. An increasing broker market share offers customers a greater variety of choice and has supported market penetration of smaller lenders, Westpac added.
MORE INACCURACIES FOUND IN MORTGAGE APPLICATIONS VIA BROKER CHANNEL Source: UBS Evidence Lab
90% 80%
79% 78%
2015
75%
2016
67% 68%
70%
61%
2017
60% 50% 40% 28%
30% 18%
20%
22%
24%
26%
16%
10%
1%
4% 3%
4%
7%
11% 2% 2%
0%
0%
1%
1%
0%
Bank – completely factual and accurate
Broker – completely factual and accurate
Bank – mostly factual and accurate
Broker – mostly factual and accurate
Bank – partially factual and accurate
Broker – partially factual and accurate
Bank – would rather not say
Broker – would rather not say
UBS, the outlier While brokers deserve a pat on the back after reading those submissions, the usual bearer of bad news for brokers – UBS Bank – released yet another searing takedown of the third party channel. In its latest report referring to $500bn in ‘liar loans’, UBS analysts found that brokers let through a higher percentage of misrepresented loans compared to the banks. The report used data collected during an online survey of 907 Australians who had taken out a mortgage in the last 12 months. It asked borrowers 70 questions about their background, motivations, purchase method and expectations. From that, the analysts deduced that a third of loan applications from the direct and third party channels were inaccurate. While the number of “completely accurate” mortgages submitted through both brokers and branches dipped from 2016 to 2017, discrepancies were higher among brokers. During that time period, the level of accurate mortgages fell from 68% to 61% for brokers and from 78% to 75% for branches. The analysts noted that “of concern” was the increasing number of people who took out a mortgage via the broker channel with a “partially factual and accurate” application. This increased from 4% in 2015 to 11% this year. “Given the rising level of misstatement over multiple years, we estimate there are now around $500bn of factually inaccurate mortgages on the banks’ books,” the UBS analysts wrote. (‘Liar loans’ was a term coined in the US during the
GFC for mortgages where documentation was inaccurate.) “While household debt levels, elevated house prices and subdued income growth are well known, these findings suggest mortgagors are more stretched than the banks believe, implying losses in a downturn could be larger than the banks anticipate,” they wrote. The MFAA questioned the way UBS had represented the results, given that they do not reflect the same findings as ASIC’s Review of Mortgage Broker Remuneration, which analysed 1.4 million home loans worth $5.5bn, collected 157 data points for each, and surveyed 3,000 consumers on their opinion of brokers.
executive director Peter White questioned the validity of the data. “I want to see their data analysis,” he said. “We need to see the questions they asked participants. UBS must prove there is no steering of answers or influences to produce outcomes which are not factual or fair or commercially sound.” During a House of Representatives Standing Committee on Economics on 14 September in regard to ASIC’s Annual Report, senior executive leader of deposit takers, credit and insurers Michael Saadat was asked about the UBS report. “Where we would disagree with that UBS report is in relation to where things stand today as distinct
“Given the rising level of misstatement over multiple years, we estimate there are now around $500bn of factually inaccurate mortgages on the banks’ books” UBS “UBS has implied in its commentary that brokers are not fulfilling their obligation to act as professionals, or that they are placing consumers into high risk lending that they cannot afford. The findings simply do not match the reality of the consumer experience, nor ASIC’s actual data into mortgage outcomes,” the MFAA said. The FBAA said UBS was “reckless with its analysis”, which was based on “implied presumptions”. FBAA
from where they possibly were many years ago. We think things have improved significantly in terms of responsible lending,” he responded. While he acknowledged that there was still more work to be done, and that ASIC had a number of reviews underway examining the broking industry and its compliance, he reiterated that “things have improved”. Saadat pointed to one of the observations in the UBS survey, which stated that consumers reported that they did not feel that
BROKERS HAVE INCREASED COMPETITION AMONG LENDERS Source: APRA, RBA
Third-party originated loan approvals
%
55%
Other lenders
50%
45%
Major banks
40%
35%
30% 2009
2011
2013
2015
2017
www.brokernews.com.au
17
FE AT URES
loan underwriting standards had changed over the past couple of years and they didn’t think it was any harder to get a loan. “For many consumers, the additional work and additional steps that banks and other lenders are taking to verify someone’s financial situation won’t be apparent to them,” he said. “So we think consumers are probably not the best judge of what banks are doing behind the scenes to make sure borrowers can afford the loans they’re being provided with.” Saadat said ASIC has a project underway at the moment that is looking at loan fraud more systematically to identify more comprehensive solutions.
MORTGAGES SECURED BY BROKERS VS BANKS IN 2017 Source: UBS Evidence Lab
Don’t blame the brokers Meanwhile, the day after the UBS report was released, a senior executive of the Credit and Investments Ombudsman (CIO) said that only about 6% of complaints sent to their office related to brokers and aggregators, with disputes much more likely to stem from residential lenders. “We don’t get huge amounts of broker complaints. In respect to statistics, it’s probably on a much lesser end,” Danielle Gewerc, CIO senior manager of dispute resolution, said during a broker Q&A session at the CIO’s Dispute Resolution
Brokers
misstep by brokers, she added, especially around the failure to sufficiently examine a client’s living expenses. In a comment on Australian Broker’s website in response to the UBS story, broker Ray Weir wrote that the only area open to misrepresentation was the living expenses budget. “The stated living expenses can’t be below the ‘Household Expenses Measurement’ issued by the Bureau of Statistics, or the lender will query
“We think things have improved significantly in terms of responsible lending” Michael Saadat, ASIC Conference on 12 September. In comparison, 46% of CIO complaints are about residential lenders, Gewerc said. Of the 6% of broker complaints, the majority are for failure to act with due care and skill, inappropriate finance, misrepresentation and misleading misconduct, and other issues. Inappropriate finance is the biggest 18
www.brokernews.com.au
the budget. Many lenders now require a living expense budget to be completed and signed by the borrowers,” he said. “While deliberate fraud will occasionally occur in any financial activity by an individual or business, I find it hard to believe loan fraud is widespread. If it was, I’m sure we’d see considerably more loan delinquency.” AB
63% 61%
39% 37%
Completely factual and accurate Not completely factual and accurate Broker suggested I misrepresent Broker did not suggest I misrepresent
Banks
92% 75%
25%
8% Completely factual and accurate Not completely factual and accurate Banker suggested I misrepresent Banker did not suggest I misrepresent
www.brokernews.com.au
19
FE AT URES
OPINION
PEAK PERFORMANCE With the significant focus on household debt, and regulators on a knife edge when it comes to the property market, brokers need to assert the critical role they play in the credit chain by staying on top of their game, writes Vow Financial’s general manager, Clive Kirkpatrick
Clive Kirkpatrick, general manager, Vow Financial
dramatically named ‘Liar Loans’ report from UBS is one more shot across the bow at the mortgage broking profession. It’s not the first, nor will it be the last. It follows a line of scrutiny – and sometimes criticism – of the profession in recent times. The ASIC Review of Mortgage Broker Remuneration was a major piece of the puzzle. It was the continuation of a review of all the players involved in providing credit. Alarmed by the high level of household debt Australians are carrying, ASIC decided to take a preemptive approach to regulation. This is certainly better than responding to a crisis once the damage is done, as with the Future of Financial Advice reforms. ASIC decided that it’s better to take the car in for a service and make small repairs, rather than wait for an engine failure on the side of the highway. The level of household debt in Australia certainly warrants attention, THE
20
www.brokernews.com.au
but if we look at the numbers, credit growth has moderated in the housing sector. As a ratio to GDP, credit is at historically high levels – more than 1:4. The explosion in credit pre-GFC saw housing debt balloon to an unprecedented size. Credit growth exceeded 20% in that era, whereas it now tracks at around 6–7%, albeit from a bigger base.
Victims of our own success? In addition to the macroeconomic factors, the broking sector is attracting attention due to its success. A true alternative to the first-party lending model, brokers provide flexibility, choice and specialist credit skills and knowledge. Our remuneration models are disclosed and transparent, and our first responsibility is to the customer. Customers like this, and that’s why brokers have captured more than half of the market. But like any sector facing disruption, some parties are nervous about change or have interests to protect. Why detractors such as UBS are taking aim at the profession is not immediately apparent, but in any debate like this we should look carefully at the motives of those taking a stand – who owns what, and how competition affects their interests. With household debt finely balanced, and regulators holding their breath in case any shocks hit the market, brokers are seen as a critical link in the chain because they help consumers access some of this debt. So, our challenge – as aggregators and individual brokers – is to demonstrate that we take this responsibility seriously. For Vow Financial and the Yellow Brick Road Group, there are two key planks to achieving this:
1
Quality assurance program – It’s not just about box-ticking
CREDIT RATIO TO GDP
compliance. We are very clear about the processes we are employing, and continuously improving, in order to foster high standards of lending. Education – We’re developing a learning and development approach that raises the bar, engages brokers and makes them want to learn. The education platform we’ll be rolling out shortly is unlike anything in the sector – it’s interactive, bite-sized and focused on all aspects of running a business, not just lending.
2
Individual brokers have a role to play too, by taking advantage of the tools that aggregators provide. In today’s market, processes and standards are always changing, so we need to invest time in staying up to date. When I was teaching my daughters to drive, I noticed that some road rules had changed since I got my licence many moons ago. But there is nothing in place to keep drivers updated. By contrast, our profession has plenty of channels to stay current. If everyone does this, and we have a high level of continuous learning, then the outcomes for our clients will be better. Moreover, our profession will be able to refute these criticisms and know that our own houses are in order. It’s neither an easy nor a quick process, but it’s worth doing, and it’s what we are committed to achieving. AB
CREDIT GROWTH BY SECTOR Sources: ABS, APRA, RBA
Sources: ABS, APRA, RBA
Ratio to nominal GDP
Year-end growth
Ratio
%
1:4
20
1:1
10
0:8
0
0:5
-10
Housing
Business Personal
1992
1997
2002
2007
2012
2017
2001
2005
2009
2013
2017
IN THE NE WS
ASIC’S AGENDA ASIC’s Michael Saadat provides details of the three reviews the regulator has underway, examining brokers’ role in interest-only lending, loan fraud allegations and reverse mortgages, writes Miklos Bolza starting with infringement notices under the NCCP Act. These amount to just under $50,000 for each infringement. … Where they are not paid, we will pursue the matter in court.” The review is focused on conduct that is occurring right now. ASIC has already obtained data from 16 lenders on the number of interest-only loans being written. “The specific lenders and brokers that will be the focus of our file reviews will be notified shortly. … Once we identify those outliers, we will write to obtain individual loan files to see whether those files have good records of requirements and objectives.”
requirements and objectives, but the outcome of those enquiries isn’t always well documented on the file.” Brokers or lenders providing high numbers of interest-only loans without sufficient recordkeeping will be dealt with through “swift enforcement action,” he said. “Our enforcement toolkit involves a range of sanctions,
LOAN BOOK BREAKDOWN FOR MAJOR VS NON-MAJOR BANKS Source: APRA
Other domestic banks
10%
OO Loan book
Investor Annual % charge
I/O OO = Owner-occupier
OO
Investor
$58.0bn
6%
+4.3%
0
8%
+4.2%
100
+10.9%
200
+4.4%
300
+7.8%
400
$141.2bn
12%
500
$502bn
14%
600
+6.4%
16%
700
$450bn
800
$792bn
Interest-only under investigation ASIC has undertaken a “targeted review” of both brokers and lenders to identify any firms providing high numbers of interest-only loans. “In particular, record-keeping continues to be an area of improvement,” Saadat said. “What we are told and what we know is that brokers do make enquiries about a consumer’s
$bn
Major banks
$60.8bn
has revealed details of an ongoing review into interest-only lending by brokers and lenders, as well as separate investigations into loan fraud and reverse mortgages. ASIC senior executive leader of deposit takers, credit and insurers Michael Saadat explained the scope of these investigations at the Credit and Investments Ombudsman’s Dispute Resolution Conference in Sydney on 12 September.
Reviewing reverse mortgages Finally, ASIC is conducting a review into the reverse mortgages space as part of a coordinated approach to investigating financial products and services that support Australia’s ageing population. It has been almost a decade since ASIC last reported on reverse mortgage lending and around five years since special protections were introduced in the National Credit Act for mortgage broking and lending, he added. “The aim of this review is to deepen ASIC’s understanding of lending practices, measure the effectiveness of and compliance with the special reverse mortgage protections, and get a better understanding of when and why consumers use reverse mortgages.” A public report is expected to be released in the first quarter of 2018. AB
Scoping out loan fraud The regulator is also “scoping a project” in relation to various reports of loan application fraud. Sadaat said ASIC regularly receives reports of alleged loan fraud from various individuals, including consumers, consumer advocates, other regulatory agencies, credit licensees and industry associations. “In many cases where ASIC is alerted to alleged loan fraud involving finance brokers or staff employed by lenders, these matters have been brought to ASIC’s attention by a licensee or an
Michael Saadat, senior executive leader of deposit takers, credit and insurers, ASIC
ASIC
industry association which has already suspended or terminated the individual’s employment, lender accreditation or aggregation agreement.” The proposed project will give ASIC a better understanding of the type and level of fraud in the industry, as well as potential practices that can be used to prevent, detect and respond to these actions.
I/O
4% 2% 0%
I/O = Interest-only
www.brokernews.com.au
21
PEOPLE
Have an interesting deal? Had a particularly difficult or interesting deal? Why not share it with us? Email:
Otiena.Ellwand@keymedia.com.au
A BIG DEAL
Matt Punter, managing director at The Savings Centre, on what happened when his tenants became a client of his brokerage, and how working with an experienced accountant was a game changer for them and a boon for future referrals
Location: Sunshine Coast
THE FACTS
Loan size and term $258,960 for 30 years
Lender AFM (Pepper)
weeks of this change, their BAS was brought up to date, which demonstrated increasing revenue and substantiated surplus funds. The ATO returns were also completed, and they revealed that the business’s latest financial year was far superior to the prior period, which put them in a visibly strong financial position. Once the paperwork was tidy and the client’s financials were clear, I contacted Rachel Walsh, a BDM at Australian First Mortgage, to identify an appropriate lender for the proposed loan amount. I believed that the couple deserved to obtain finance, but because they were self-employed they needed some additional support to help them demonstrate that they could meet the lender’s serviceability criteria. Walsh offered us some case study examples of other similar successful applicants so that we could guide our client through the process. The lender subsequently approved their application and we were able to deliver an extremely positive outcome for all parties. THE TAKEAWAY
Client Couple in their mid-40s, four kids
able to access finance, and they were even contemplating selling their land. After some initial investigation I found that their bookkeeper was quite behind with their BAS, and that their ATO returns were a bit of a mess. This made it somewhat tricky to verify income. After much discussion and
THE SCENARIO
The client was a self-employed couple with four children who had recently relocated to Australia from New Zealand with the dream of building their own home. They had purchased a block of land on the Sunshine Coast at 50% LVR with funds brought across from NZ. Upon arrival in Australia, the family moved into a rental property. Unfortunately, despite a clear credit history, several banks and two mortgage brokers declined their construction loan applications. As fate would have it, they were actually renting a property that my wife and I own, so we got to know their story and understand their struggles. We knew them to be good tenants who always paid their rent on time, and we knew that they had a strong cash position in business. It was evident to me that they were generating sufficient income to service the proposed construction loan, so I decided to help them, and I looked a little deeper into why they weren’t having any financial success. When I began working with the couple they didn’t believe that they would ever be 22
www.brokernews.com.au
Goal To build their dream home
This deal was a great example of how looking beneath the surface of a client’s situation can completely turn things around. Second opinions can be highly valuable, and the guidance of a good accountant was crucial to this deal. I also recognised the value of BAS statements for verifying income. This is something that I hadn’t previously harnessed but now find particularly useful as a source for businesses that are in the growth phase. While this case wasn’t a huge moneymaker in terms of loan size, I gained the respect of the accountant, who observed my problem-solving skills and clientcaring approach and subsequently referred more than $2m worth of new business to The Savings Centre. For me, the real reward is seeing my clients move on to the next stage in their
Second opinions can be highly valuable, and the guidance of a good accountant was crucial to this deal some frustration, I made a recommendation that they enlist the help of an experienced accountant for some sound advice. As it turned out, this expert advice was an absolute game changer for their application.
Matt Punter Managing director, The Savings Centre in Queensland
THE SOLUTION
The accountant immediately advised our client to replace their bookkeeper, which they quickly took on board. Within two
lives. Construction is nearing completion on this client’s property and in a few months the whole family will enjoy their first Christmas in their dream home. This has become one of my favourite ‘feel-good’ client stories, and it is the perfect example of why we, as brokers, shouldn’t be afraid of coaching our clients if there is something holding them back from reaching their personal or financial goals. AB
www.brokernews.com.au
23
PEOPLE
Get involved in the discussion Share your thoughts at
brokernews.com.au
FROM THE FORUM
Top comments from trending stories on brokernews.com.au
‘WE DON’T GET A LOT OF BROKER COMPLAINTS’, CIO SAYS
INACCURACIES ‘MORE PREVALENT’ THROUGH BROKERS
Only about 6% of complaints received by the Credit and Investments Ombudsman (CIO) relate to brokers and aggregators, versus the 46% that stem from residential lenders. “Funnily enough, we don’t get huge amounts of broker complaints. In respect to statistics, it’s probably on a much lesser end,” said Danielle Gewerc, CIO senior manager of dispute resolution, during a mortgage broker Q&A session at the CIO’s Dispute Resolution Conference 2017 in Sydney on 12 September. The majority of broker complaints are for failure to act with due care and skill, inappropriate finance, misrepresentation and misleading misconduct, and other issues. “We don’t get a lot of broker complaints. That’s a good thing,” Gewerc said.
A third of all mortgage applications across direct and third party channels over the past 12 months were neither factual nor accurate, and misrepresented loans were more common among brokers, new research by UBS has found. The Australian Banking Sector Update, entitled $500 billion in ‘Liar Loans’?, was compiled by UBS analysts and surveyed 907 Australians who took out a mortgage during that period. The main crux of the research was that only 67% of respondents said their mortgage application was “completely factual and accurate” – far fewer than the 72% who gave the same response in the 2016 survey.
Of course, the difference between brokers and bankers is that we value the relationship and take the time to understand the clients’ needs, not just push a product on their laps. I can tell you the fraudulent activity that comes out of the banks is always going to be higher as there is a small percentage of their files that actually get audited, opening doors to falsify information to satisfy sales targets; it’s been going on forever. Craig on 15/09/17 at 9:21 AM
Why does fraud happen in branches? Due to high targets. (So who is to blame, bank management or the loan manager?) Due to bonuses involved. (So who is to blame, process or bank manager?) No jail term if a banker commits fraud, but if a broker commits fraud it is a crime or a jail term. (Who is to blame, the bank that protects it or the authorities who go for the easy bait?)
Emanuel on 12/09/17 at 11:04 AM
I would like to see a breakdown of the 907 loans/borrowers that they surveyed. Was it a face-to-face survey or anonymous online? Where were the borrowers located geographically? Age groups? Income brackets? Credit history? Lenders? Loan types? Was the application done in person or online? It’s very easy to make broad statements and suggest particular conclusions if you don’t justify how valid your underlying data is. Stephen on 12/09/17 at 12:49 PM
Real statistics from a reputable source that has no agenda other than dealing with the facts. Alternatively, you can read and publish the UBS garbage. P.S. Heed the tip though: keep more comprehensive records.
Amazing survey results given that 95% of the information provided in a home loan application is verified by supporting documentation such as payslips, group certificates, tax returns, bank statements, loan statements, a credit report going back five years, etc. The only area open to misrepresentation, in my opinion, is the living expenses budget, but the stated living expenses can’t be below the “Household Expenses Measurement” issued by the Bureau of Statistics, or the lender will query the budget. Many lenders now require a living expense budget to be completed and signed by the borrowers. Other misrepresentations, such as overstating the value of an asset, such as a motor vehicle, have no material effect on the credit decision. It’s also impossible to hide a financial liability, which would be revealed in a credit report or by way of a direct debit on a bank or credit card statement. While deliberate fraud will occasionally occur in any financial activity by an individual or business, I find it hard to believe loan fraud is widespread. If it was, I’m sure we’d see considerably more loan delinquency.
Steve McClure on 15/09/17 at 9:38 AM
Ray Weir on 12/09/17 at 3:31 PM
MK on 15/09/17 at 9:49 AM
These are factual outcomes and are consistent with ASIC’s findings that brokers are good for competition. … Given the growing spread in interest rates, the client needs a broker more than ever. Rear Window on 19/09/17 at 9:30 PM
24
907 borrowers, oh, wow, what an effort to conduct research! If they were active in the Australian mortgage loan market, they would realise the kind of paperwork that is involved in a mortgage. Once more they have no clue, but they are brilliant at poking the wasp nest and at establishing useless statistics! At least they get free PR.
www.brokernews.com.au
CAUGHT ON CAMERA About 100 brokers attended ING’s Sydney Broker Roadshow on 25 August at the Waterview in Bicentennial Park, where the highlight was a Q&A panel with executive director of operations Adriana Sheedy, chief risk officer Ulrich Heitbaum, head of products Tim Newman, and head of distribution Mark Woolnough. The event featured a number of other speeches, including an opening address by CEO Uday Sareen, an economics update from treasurer Michael Witts, and a keynote address by futurist Steve Sammartino. This lunch capped off a nationwide tour, in which the heads of the non-major lender got to talk to brokers face-to-face and receive their feedback on the bank’s products, service levels and mortgage policies.
Uday Sareen, CEO, ING
Mark Woolnough, head of distribution, ING www.brokernews.com.au
25
DATA
VICTORIA
QLD SPOTLIGHT
Melbourne’s inner city continues to command value as one of the most popular choices for young homebuyers
BRISBANE IN DEMAND
“More and more young people are turning to Melbourne’s inner-ring markets as a way to maintain their lifestyles and a level of convenience, while finding an affordable entry to the market,” says F.R. Chee, a selling agent from CT Real Estate. Units in these markets are also attracting a lot of attention because they put residents within close proximity to amenities. The implementation of incentives for first home buyers is expected to boost this demand, especially as new entrants trade in the suburban-home dream for apartments with beautiful city views. Melbourne seems to be on the path towards overtaking Sydney as Australia’s most populated city.
Area
Type Median value
As Brisbane’s improving long-term prospects draw more eyes to its apartment market, houses continue to flourish, especially those around 10km from the CBD
Quarterly
12-month
growth
growth
Melbourne
H
$711,000
8.4%
9.0%
VIC Country
H
$333,000
0.9%
4.0%
Melbourne
U
$515,000
6.0%
1.1%
VIC Country
U
$262,000
-1.1%
0.0%
WESTERN AUSTRALIA
Fairly strong sales have helped temper the oversupply issue in the June 2017 quarter “Although we still have plentiful choice in the market, we do appear to have hit a ceiling and are no longer seeing the increases we once were. As long as transactions remain steady, we should see listing levels decline,” says Hayden Groves, president of the Real Estate Institute of Western Australia. In particular, the auction market is a significant aid for struggling vendors, since it facilitates quick transactions. “In this market, when there is plenty of competition between sellers to secure a buyer, standing out from the crowd is paramount. Selling at auction has plenty of benefits for the vendor, with a short but high-profile marketing campaign bringing serious buyers to the forefront quickly,” Groves says.
Area
Type Median value
within easy reach of the Brisbane CBD can be purchased in the sub-$600,000 price range and offer average returns of over 4.5%. A little to the south, the Gold Coast has also been recording considerable growth in the past year. “We put this down to how affordable the market is, but also to the upcoming Commonwealth Games, which have created a lot of jobs for the area and also appeal for the region,” says Jordan Navybox, general manager at Cohen Handler Queensland. In addition to affordability and falling stock, Brisbane is benefiting from an upswing in the incoming population – it is the second-fastestgrowing capital city in Australia, according to recent Census data. “Queensland has now produced five consecutive quarters of interstate migration in excess of 3,000 people,” says Simon Pressley, managing director of Propertyology. Interstate migration levels in the June 2017 quarter were the highest recorded in nine years as many investors from the south have been coming to try their luck in this affordable market with increasing upside. Infrastructure projects are in the works to further enhance Brisbane’s appeal, such as the Queens Wharf project. This entertainment hub in the heart of the CBD is expected to serve as a counterpart to Sydney’s Darling Harbour and the Crown precinct in Melbourne. “With 50% of the state’s population spread across a dozen major regional centres, Propertyology has observed signs of green shoots in strong cities such as Cairns, Townsville, Toowoomba and Beaudesert, where their respective economic outlooks have improved and housing remains exceptionally affordable,” Pressley says. AB HOUSES
Quarterly
12-month
growth
growth
H
$510,000
0.0%
-2.8%
Median price (houses)
WA Country
H
$346,000
-5.2%
-5.3%
$503,592
Perth
U
$410,000
0.6%
-2.4%
WA Country
U
$300,000
1.7%
-6.7%
www.brokernews.com.au
With 17 months to go until the Commonwealth Games, the Gold Coast property market shows no signs of slowing down The median house price has risen by a recorded 5.5% over the past five years. We feel the Gold Coast property market has matured and we may not see the big swings in property values like we have seen previously. Migration is strong and the area offers an enviable lifestyle, with warm weather, excellent schools and continued spending on infrastructure. Migration to the Gold Coast is still strong, with Pimpama and Coomera offering affordable living. Burleigh and Miami offer beachside living that’s still affordable. Property prices are being driven by a low interest rate and high rental yields. We believe the investment property market will slow due to regulatory changes by APRA and ASIC. But the Gold Coast residential owner-occupier market will continue to see strong growth. Property investors need to be wary of off-the-plan purchases, with many new high-rise unit blocks being constructed at present. We feel these carry a high level of risk and are subject to a drop in tourism and very high body corporate rates and management fees.
Peter Gwynne Mortgage broker at Financing Property on the Gold Coast
SUBURB TO WATCH: WHITFIELD
Perth
26
BROKER PERSPECTIVE
Median price (units) $237,209
Source: CoreLogic
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
-2.1%
0.9%
15.7%
4.7%
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
0.2%
3.1%
14.8%
5.7%
AUSTRALIAN CAPITAL TERRITORY
Despite the positive performance of the market, buyers do not seem assured of Canberra’s prospects
OPPORTUNITIES AND KEY INFRASTRUCTURE
Airport upgrade
Cremorne Theatre
Social housing
New England Highway
Rockhampton Airport is set to receive a $5m facelift
This performing arts hub is taking centre stage after a $2.3m upgrade
Rangeville housing complex to include 16 one-bedroom apartments
Additional lanes under construction between Yarraman and Toowoomba
HIGHEST-YIELD SUBURBS IN QUEENSLAND Suburb
Type
Median price
Quarterly growth
12-month growth
Blackwater
H
$87,500
-17%
-38%
Yatala
U
$390,600
10%
6%
Jubilee Pocket
U
$139,000
-1%
-10%
Dysart
H
$87,000
16%
24%
Manoora
U
$153,750
-2%
-1%
“Indicators such as forward work schedule expectations have dampened this quarter, dropping well below the March–June expectation high,” explains Adina Cirson, executive director of the Property Council of Australia ACT. Nonetheless, industrial performance is a source of hope for capital growth as the tourism and hospitality sectors flourish. According to Michael Yardney, CEO of Metropole Property Strategists, Canberra is the only capital city other than Sydney and Melbourne to have recorded real growth in property prices over the past decade, once inflation was accounted for. “[The] outlook for Canberra property is good as it has a strong public sector, strong and stable employment market, below-average unemployment rate and above-average household incomes.” Area
Type Median value
Quarterly
12-month
growth
growth
Canberra
H
$685,000
6.2%
6.6%
Canberra
U
$440,000
0.0%
3.5%
www.brokernews.com.au
27
DATA
SOUTH AUSTRALIA
While the number of auctions in Adelaide are going down, property values are going up
CAPITAL CITY AUCTION CLEARANCE RATES
$300,000
3.4%
2.8%
Adelaide
U
$375,000
4.2%
5.0%
SA Country
U
$183,500
-8.3%
1.3%
MEDIAN HOUSE AND UNIT PRICES
Due to limited stock and high demand, infrastructure projects could dictate how the Sydney market moves forward
$1,000,000
Area
Type Median value
Quarterly
12-month
growth
growth
Sydney
H
$1,010,000
9.8%
5.6%
NSW Country
H
$455.000
1.7%
6.0%
Sydney
U
$740,000
4.7%
3.6%
NSW Country
U
$378,500
2.3%
2.8%
28
www.brokernews.com.au
Sold
6
Not sold
11
Clearance rate
NEW SOUTH WALES
35.3%
$1,100,000
Houses
Units
$500,000 $400,000 $300,000 $200,000 $100,000 $0
$543,000
$700,000 $600,000
$720,000
$800,000
$710,000
$900,000
$900,000
“The biggest game changers that Sydneysiders will see is the current money being spent on big projects, all surrounding our roads and transport. “All this should affect prices and affordability as the city becomes a quicker place to travel to and from,” says Walter Nanni, buyer’s agent at Cohen Handler Sydney. These events in the property market could be the reason why confidence levels have slipped in NSW. According to the ANZ/Property Council Survey findings for July 2017, NSW suffered the most significant drop in confidence of all the states. This result highlights that consumers have lower expectations from Sydney in terms of capital and economic growth, even though the job market is anticipated to remain strong. “We need the state government to take action to strengthen the housing supply pipeline in New South Wales,” says Jane Fitzgerald, director of Property Council NSW.
33
Sydney Melbourne Brisbane Adelaide
Perth
Hobart
Darwin
$429,950
H
Total auctions
$625,000
SA Country
75.0%
$380,000
3.5%
18
$478,000
2.1%
Not sold
$290,250
$459,500
54
$390,000
growth
H
Sold
$400,000
growth
Adelaide
98
PERTH
$503,000
12-month
Total auctions
Clearance rate
$309,000
Quarterly
ADELAIDE
$425,000
Type Median value
There were 2,490 auctions held across the combined capital cities in the week ending 17 September, up from 2,258 the week before, making it the busiest week for auctions since the beginning of June. Based on preliminary results, the combined capital city clearance rate was recorded at 70.3% this week, up from 66.9% last week, although this will likely revised down over the next few days as the remaining results are collected. Over the corresponding week last year, auction volumes were lower, with 2,149 properties taken to auction and a clearance rate of 76.2% recorded. Melbourne had the highest number of auctions this week, with 1,268 auctions held, and a higher preliminary clearance rate week-on-week (73.6%), while the highest preliminary clearance rate was recorded in Adelaide (75.0% across 72 reported auctions).
$376,000
Area
WEEK ENDING 17 SEPTEMBER 2017
$519,500
Quality properties are seeing high demand due to limited supply, and auction bidding is increasingly the sale method of choice because of the transparency of the process. “Many astute vendors and their agents are seeing that, with less on the market, the benefit of the auction process is increasing,” says Real Estate Institute of SA president Greg Troughton. “The REISA is hopeful that auction will continue strongly as the optimum selling process, especially given the lack of stock available in the Adelaide marketplace.” Nonetheless, while Adelaide remains challenged on the economic front, the market isn’t expected to become a strong performer any time soon. “The submarine [project] is back on track, but it’s still a few years before [it will be] on the way properly. So now there’s going to be a gap in terms of work in the defence sector,” says Angie Zigomanis of BIS Oxford Economics.
Canberra
CAPITAL CITY HOME VALUE CHANGES Capital city
Weekly change
Monthly change
Year-to-date change
12-month change
-0.2%
-0.1%
5.4%
11.6%
Melbourne
0.1%
0.6%
7.5%
12.2%
Brisbane
0.1%
0.2%
1.9%
3.0%
Adelaide
0.1%
0.0%
2.8%
5.3%
Perth
0.2%
-0.4%
-2.5%
-2.8%
0.0%
0.2%
4.8%
9.1%
Sydney
Combined 5 capitals
*The monthly change is the change over the past 28 days
BRISBANE CANBERRA Total auctions
62
Sold
38
Not sold
14
Clearance rate
Total auctions
132
Sold
48
Not sold
50
Clearance rate
49.0%
73.1%
SYDNEY Total auctions
897
Sold
475
Not sold
209
Clearance rate
TASMANIA
MELBOURNE Total auctions
69.4%
1,268
Total auctions
0
Sold
810
Sold
0
Not sold
291
Not sold
0
Clearance rate
Clearance rate
73.6%
TASMANIA
Area
Given Hobart’s affordability and excellent prospects, private firms are looking into capitalising on its appeal now “Keep an eye out for large capital projects such as The Fragrance Group’s $240m application to build two hotels, including the tallest building in Hobart at 210 meters,” says Josh Hart, director at One Agency Launceston. “If approved, this will set a new precedent for Hobart and for future developments.” Mixed-use developments are helping to enhance the profile of Tassie cities outside Hobart as well. “Developments for accommodation, retail and leisure known as The Silos and Penny Royal have boosted confidence in a city [Launceston] that is only a 45-minute flight from Melbourne,” Hart explains.
N/A
Type
Median value
Quarterly growth
12-month growth
Hobart
H
$390,000
0.8%
6.9%
TAS Country
H
$262,500
-2.8%
1.9%
Hobart
U
$306,750
-1.3%
1.7%
TAS Country
U
$235,000
-2.1%
2.4%
All data sourced from CoreLogic.com.au
www.brokernews.com.au
29
PEOPLE
IN THE HOT SEAT Patrice Sullivan, finance specialist at Accredited Lending Services and 1300HomeLoan, talks about ASIC’s remuneration review, the importance of honesty and personalised service in broking, and her new hobby, target shooting Who or what inspired you to become a broker? I’ve been in the banking and finance industry for more than A 29 years and was lucky to know at a young age what I wanted to do. Working with a major bank led me into mortgages and then on to being a broker. I love providing clients with genuine, personalised service, which I believe is becoming rarer.
Q
What does your ideal Sunday look like? Sunday is gun day! I recently took up bench rest rifle target A shooting. It’s a challenging sport that requires calm and focus. I entered my first competition recently and scored 502 out of 550. I ended up in eighth place against people who have represented Australia.
Q
How do you see a broker’s job evolving over the coming years? A lot of clients are craving to deal with people who are honest and A upfront about what they are achieving with a loan. The old pushy ‘sales pitch’ method from the 1990s and early 2000s is starting to wear thin. Clients don’t need to be convinced; they just need to be educated so they fully understand what they’re getting. Many clients have been ripped off in some way in the past, therefore good, selfless service will win over a sales pitch.
Q
What do you hope comes out of ASIC’s remuneration review? I hope that the review is fair on brokers and makes no change to A the current commission structure. A lot of work goes into each loan settlement, and if a governing body is doing an assessment, they can’t just look at the ‘amount paid’ on each loan. They need to do a holistic review and take into account the amount of hours and hard work that it takes to be a professional broker – networking and sourcing leads, the paperwork involved in every application, and being on top of the ever-changing lending policies. This all takes time, and for most of us it’s not a comfortable 38-hour work week! How much would a government employee expect to be paid if they worked nights and on weekends?
Q
Q A 30
What was the last band you saw live and how were they? Diana Krall. She was excellent – a great jazz vocalist and pianist. AB www.brokernews.com.au
BOOK YOUR TABLE NOW
Friday 27 October • The Star Sydney www.australianmortgageawards.com.au Event Partner
Award sponsors
Official publications
Organised by
www.brokernews.com.au
31
32
www.brokernews.com.au