SEPTEMBER 2017 ISSUE 14.18
If it’s not broken, why fix it? Brokers get fired up over ASIC’s rem review /18
Underestimating the risks Concentration and mortgage stress in the housing market /20
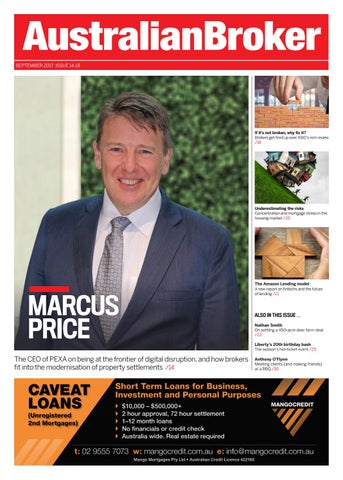
MARCUS PRICE The CEO of PEXA on being at the frontier of digital disruption, and how brokers fit into the modernisation of property settlements /14
The Amazon Lending model A new report on fintechs and the future of lending /21
ALSO IN THIS ISSUE … Nathan Smith On settling a 450-acre deer farm deal /22 Liberty’s 20th birthday bash The season’s hot-ticket event /25 Anthony O’Flynn Meeting clients (and making friends) at a BBQ /30
NEWS
IN THIS SECTION
Lenders NAB considers a ‘conflicts register’ for brokers /04
Associations MFAA finds broker retention rates troubling /06
Technology Helping brokers build leads with Chinese buyers /10
Regulators E-form issues result in broker’s ban /12
Consumers Families are using more of their income on housing /08
www.brokernews.com.au SEPTEMBER 2O17 EDITORIAL Editor Otiena Ellwand News Editor Miklos Bolza Production Editor Roslyn Meredith
DATES TO WATCH
Upcoming can’t-miss events
ART & PRODUCTION Design Manager Daniel Williams Designer Martin Cosme
27 SEPTEMBER
10 OCTOBER – 1 DEC
11 OCTOBER
Commercial lending webinar
Connective Conference 2017
Banking Innovation 2017
Australian Broker’s sister publication MPA is hosting this webinar at 12:30pm about the long-term benefits of diversifying into the commercial space and why and how brokers can break into this market
Connective is bringing its conference to Vic, WA, Qld, NSW and SA on various dates from October to December. The conference promises to inspire brokers with new business development strategies, marketing techniques, insights from industry experts, and workshops on health, mindfulness and more
This Sydney-based conference will feature presentations from experts and disruptive innovators within the financial services space who will outline what the future holds for banking practices
Production Manager Alicia Chin Traffic Coordinator Freya Demegilio
SALES & MARKETING Sales Manager Simon Kerslake Account Manager Rajan Khatak Marketing and Communications Manager Lisa Narroway
CORPORATE Chief Executive Officer Mike Shipley Chief Operating Officer George Walmsley Managing Director Justin Kennedy Publisher Simon Kerslake Chief Information Officer Colin Chan Human Resources Manager Julia Bookallil
EDITORIAL ENQUIRIES
Otiena Ellwand +61 2 8437 4792 Otiena.Ellwand@keymedia.com.au
SUBSCRIPTION ENQUIRIES
tel: +61 2 8O11 4992 fax: +61 2 9439 4599 subscriptions@keymedia.com.au
11 - 13 OCTOBER
24 - 26 OCTOBER
25 OCTOBER
Credit Law Conference
Women in Leadership Conference
Loan protection webinar
This Sydney event features some of Australia’s most successful businesswomen, including the CEOs of Suncorp, the City of Sydney and Mirvac, who will share their stories of leadership struggles and accomplishments, and teach women how to drive career growth
At MPA’s lunchtime webinar you can learn about loan protection and why more and more brokers are making this an integral part of their offering
The 27th annual event in Surfers Paradise brings together banks, credit unions, regulators, associations and market disruptors to discuss the future of credit and lending
ADVERTISING ENQUIRIES
Simon Kerslake +61 2 8437 4786 simon.kerslake@keymedia.com.au Rajan Khatak +61 2 8437 4772 rajan.khatak@keymedia.com.au Key Media Pty Ltd Regional head office, Level 1O, 1–9 Chandos St, St Leonards, NSW 2065, Australia tel: +61 2 8437 4700 fax: +61 2 9439 4599 www.keymedia.com Offices in Sydney, Auckland, Denver, London, Toronto, Manila, Singapore, Bengaluru
27 OCTOBER
5 NOVEMBER
24 NOVEMBER
Australian Mortgage Awards
MS Gong Ride
This Australian Broker-sponsored awards show at The Star Sydney celebrates 16 years of excellence in the mortgage broking industry
Pepper Money is inviting brokers to join its team ride for charity on a 58km or 90km course from Sydney to Wollongong. Meet some pro riders and brush up your skills at a practice clinic on 12 October
FBAA National Industry Conference
2
www.brokernews.com.au
This year’s conference on the Gold Coast will equip brokers and other industry members with useful knowledge and practical strategies to help them succeed in an increasingly challenging market
This magazine is printed on paper produced from 1OO% sustainable forestry, grown and managed specifically for the paper pulp industry Copyright is reserved throughout. No part of this publication can be reproduced in whole or part without the express permission of the editor. Contributions are invited, but copies of work should be kept, as Australian Broker magazine can accept no responsibility for loss. Australian Broker is the most-often read industry publication, according to independent research carried out by the Ehrenberg-Bass Institute for Marketing Science at the University of South Australia in December 2008. The research also found that brokers rate Australian Broker as the best for both news content and feature articles, followed by sister publication MPA. Overall, on all categories, Australian Broker ranks top followed by MPA. The results were based on a sample of 405 respondents who were the subject of telephone interviews.
NEWS
LENDERS
party loans across all large ADIs are on the rise, according to figures from APRA for the 12 months prior to 30 June. During that period brokers brought in $50bn for banks that process more than $1bn in residential loans. This was an increase of 5% from the $47bn brought into these larger lenders the year before. This breaks down as $37bn worth of loans through the major banks (an increase of 3%) and $9bn through the non-majors (an increase of 18%).
ADIS APPROVED $12BN MORE RESI LOANS IN 2017 Source: APRA
400
THIRD
Owner-occupied (left)
$bn
Total growth (right)
300
30
200
20
100
10
INVESTMENT LENDING PLATEAUS FOR BANKS July, residential lending dipped downwards, according to APRA’s monthly statistics reporting a total volume of $1.58trn. This represented an increase of only $5.8bn, far less than the $9.8bn increase reported for June. In July, owner-occupier lending sat at $1.02trn, with no increase on June. This accounted for about 65% of all resi lending. The remaining $553bn (or 35% of all lending) was made up of investment loans, a rise of $469m (or less than 0.1%) from June.
0
Anthony Waldron Executive general manager, NAB Broker Partnerships
4
www.brokernews.com.au
2012
2013
2014
2015
2016
2017
0
Year ending June
IN
“We know we need to increase transparency to protect the interests of customers and brokers, and we’re mindful that today’s actions will be judged by tomorrow’s standards.”
40
Investor (left)
%
BROKERS’ ADI LOAN APPROVALS UP 5%
Note: Only includes figures from ADIs with more than $1bn in residential loans
NAB PROPOSES CONFLICTS OF INTEREST REGISTERS FOR BROKERS The lender recommends that these ‘conflict registers’ be ‘monitored, managed and audited’ by aggregators to keep track of the soft-dollar bonuses their members receive lender NAB has proposed the creation of conflicts registers so brokers can record all soft-dollar benefits they receive from lenders. This suggestion was made as part of the bank’s submission to Treasury in response to ASIC’s Review of Mortgage Broker Remuneration. The submission was made public on 29 August, along with 26 others. NAB said the industry should move away from these types of benefits, acknowledging that soft-dollar benefits increased the risk of poor consumer outcomes. “NAB, as a lender and aggregator, does not provide soft dollar benefits to brokers that are linked to individual lender volumes. From time to time, NAB as a lender will MAJOR
provide hospitality to aggregators and brokers,” the submission said. NAB suggested that brokers be required to maintain a conflicts register for all soft-dollar benefits received, which would be made available to customers upon request. “NAB believes that across the industry these broker conflicts of interest registers should be monitored, managed and audited by aggregators as part of their role in monitoring brokers,” the bank said. “A uniform approach across the industry for brokers should be adopted.” The registers would be similar to the one NAB requires its employees to keep, which includes details of all gifts above $300 in value. “Once registered, a NAB employee’s
manager will then approve before their staff member offers or accept gifts or entertainment.“ However, the bank stopped short of recommending that all soft-dollar benefits should be eliminated, instead saying that benefits with a strong educational and business development component – which are not based solely on sales volumes – should be retained. “It is vital [for the aggregator] to provide broker members with professional development and training. PLAN, Choice and FAST receive funding, from lenders other than NAB, to help fund these events,” the bank wrote. “Conferences hosted by PLAN, Choice and FAST are lender agnostic and there is never qualifying criteria for broker attendance based on the volume of a specific lender’s loans a broker has written.” The bank said it conducted ongoing assessments of the attendance criteria for these events and reiterated that these should not be based purely on loan volume.
NEWS
A S S O C I AT I O N S ‘NOT EVERYONE IS BUILT TO BE A BROKER’, SAYS MFAA significant proportion of new brokers who are failing to reach success in the industry is troubling, says the MFAA’s communications head, Stephen Hale. The industry attracts 500–600 new members every six months, many of whom are coming from outside of banking and finance, Hale said during an industry roundtable hosted by Alphabroker Mentoring. “What disturbs us as an association is that the industry average of success for new-to-industry brokers is only 50%,” he said. THE
CONSUMER GROUPS JOIN BROKER COMMISSION TALKS third meeting of the combined industry forum included consumer representatives, something the forum had previously indicated was a key priority. Six new working groups were established at this latest meeting. They have been tasked with addressing issues such as commission models, enhanced governance and greater transparency. They will report back to the forum on a monthly basis. An initial response will then be supplied to the Treasury, ASIC and the industry by November. THE
RESEARCH FIRM CALLS FOR BROKER REFORMS IN ASIC SUBMISSION Report urges for an alignment between brokers and financial planners, as well as for commission to be outlawed are not simple consumer credit products, and broker commissions create a poor alignment between broker and consumer interests, according to one independent financial consultancy. These comments come from research firm Rice Warner’s submission to Treasury on ASIC’s Review of Mortgage Broker Remuneration. The submission, which was prepared by senior consultant Alun Stevens and peer reviewed by CEO Michael Rice, suggested that the duties and remuneration structure of mortgage brokers be brought into alignment with those of financial planners implemented after the Future of Financial MORTGAGES
6
www.brokernews.com.au
Advice (FOFA) reforms. To determine how broker remuneration should work, Rice Warner recommended that “the principles and provisions established by the [FOFA] reforms in respect of remuneration, and especially conflicted remuneration, should be the industry benchmark”. The firm proposed outlawing commissions, claiming that they created “a poor alignment of interests”. “Mortgage brokers would be able to charge an establishment fee which could be charged at the time of the transaction. Trail commissions make no sense for consumers,” Stevens wrote. “We consider that trail commissions should not be
paid when no service is being provided.” The firm also recommended a ‘Best Interests’ duty for brokers and aggregators that was equivalent to that imposed on financial advisers. “Financial advisers and mortgage brokers give advice that impacts on the long-term financial positions of their clients and they should have equal obligations to act in those clients’ best interests.” Consumer interests could best be served by reclassifying mortgages as financial products, Stevens wrote, as this would “immediately and definitively” resolve issues related to conflicts of interest around remuneration. “It would also address the quality of advice, the qualifications of brokers, the oversight and disclosure regime, and the need to act in consumers’ best interests. It would also recognise mortgages for what they are, long-term financial instruments, and not simply consumer credit.”
“Whilst broker numbers are growing at a healthy pace in terms of numbers, the market is not growing with them in terms of the dollars available for brokers to access.” Stephen Hale Head of communications, MFAA
NEWS
CONSUMERS CONSUMERS UNAWARE OF POSITIVE CREDIT REPORTING 90% of consumers want more competition in consumer lending, but only 15% are aware of positive credit reporting, according to research from GetCreditScore.com.au. Positive credit reporting shows lenders a more comprehensive view of a borrower’s risk profile by including aspects such as paying bills on time, keeping on track with credit repayments, etc. “Giving lenders a holistic picture of your financial behaviour means they can make more informed decisions,” said Luke Keller, head of GetCreditScore. NEARLY
TWO AD CAMPAIGNS HIGHLIGHT BROKERS’ VALUE Choice and Aussie Home Loans have launched separate ad campaigns aimed at bringing a more human face to finance brokers. The Aussie ads aim to show the “human difference” brokers provide to borrowers, and the Mortgage Choice ads aim to connect with consumers by positioning the firm’s brokers as part of the local community. Both campaigns put brokers front and centre, pitching them as trusted advisers who can help customers make more informed decisions. MORTGAGE
“Aussie brokers are the hero of our [ad] campaign and showing their many and varied faces reinforces the power of Aussie’s collective wisdom.” James Symond CEO, Aussie
FAMILIES FEELING THE PINCH OF UNAFFORDABLE HOUSING The amount that families are spending on their mortgages is edging up, consuming almost a third of their income housing affordability is on the decline, with families using a higher proportion of their income to repay their mortgages, new research has found. Adelaide Bank and the Real Estate Institute of Australia’s (REIA’s) joint Housing Affordability Report, released on 6 September, showed that the proportion of median family income required to meet the average loan repayment rose 1.0 percentage point to 31.4% in the June quarter. This represents an increase of 0.2 percentage points compared to the same quarter last year. However, the report also unveiled a more positive trend: the number of first home buyers rose by 14.0 percentage points over the quarter. Darren Kasehagen, head of NATIONAL
business development at Adelaide Bank, said this slight deterioration in housing affordability should not overshadow the increase in first home buyers. “Compared to the corresponding quarter in 2016, the number of first home buyers went up in Queensland, Western Australia, Australian Capital Territory and the Northern Territory, with both territories recording very solid FHB growth of 49.6% and 40.0% respectively,” he said. The total number of loans increased by 9.6%, while the number of loans specifically for first home buyers shot up by 14.0%. “First home buyers now make up 14.3% of total owner-occupied housing. This rate has been dropping
steadily over the past five years but seems to have stabilised over the past 18 months,” said REIA president Malcolm Gunning. Kasehagen was also keen to point out other trends among first home buyers, including the fact that the average loan size increased by 1.2% over the June quarter and 0.6% over 12 months to $365,600. The size of this average loan to FHBs increased in NSW, Victoria, Queensland and the NT and decreased in SA, Tasmania and the ACT. In the rental sector, the proportion of median family income required to meet rental payments declined by 0.6 percentage points to 24.3%, except in Tasmania and ACT. “Historically, rental affordability declined markedly from the June quarter 2007, reaching its lowest point in the March quarter 2010. Since then rental affordability has been showing a trend improvement reflecting the pickup in investment in housing from the end of 2011,” Gunning said.
VV$40,614,829,064 PARENTS HAVE BECOME FIFTH BIGGEST LENDER IN AUSTRALIA Source: Mozo.com.au
8
29%
67%
of parents assist children with a property purchase
of mum-and-dad lenders do not expect repayment
The bank of mum and dad is Australia’s
Parents have lent a total of
5TH LARGEST
$65.3BN
home loan lender
to their children
www.brokernews.com.au
NEWS
TECHNOLOGY
AGGREGATOR TO LAUNCH SME LOAN PLATFORM has announced the upcoming soft launch of a newly developed SME loan platform called AFG Business. Set to be rolled out in the second quarter of 2018 for commercial mortgages, it will later include asset finance and unsecured finance. “We’ll be building an initial panel of up to 10 lenders aimed at the core SME market. There will be simple training and direct accreditation for AFG brokers to help deliver streamlined, efficient business finance solutions,” said CEO David Bailey. AFG
APP HELPS BROKERS BUILD LEADS WITH CHINESE BUYERS A new digital app boasting more than 300,000 users aims to connect Australian brokers with Chinese investors interested in property in this country new platform focused on wealth education and creation offers brokers the chance to connect with local and overseas-based Chinese buyers interested in the Australian property market. Called Grei, the website and mobile app was officially launched in early September. But it has already been live for a year, during which time it has attracted an organic following of more than 300,000 Chinese-speaking users. The app combines wealth education resources, financial management tools and access to solutions providers in the same online location. Australian brokers can use the system to gain access to 1.2 million Australian-Chinese, as well as A
investors located in China and elsewhere abroad, and it presents a new lead generation opportunity for those targeting this segment of the market, said Grei co-founder and CEO Philip Peng. Brokers listed on the platform will sit alongside selected entrepreneurs and thought leaders, who will provide access to information and insights through articles, Q&As, webcasts, etc. Additionally, potential property investors can directly contact experts, including brokers. While Grei is currently offering a brief introductory promotion in which brokers can list for free, the standard listing price will be $2,500 per year. This fee will come with additional services, said Grei’s director of strategic partnerships
and brands, Stella Li. “We’ll help brokers set up their profile and market to the Chinese audience. Even if they’re Englishspeaking, there is no need to worry because we have our own team to tackle the language barrier,” she said. The initial annual fee will include a minimum of 10–20 generated leads for brokers. If brokers can bring in even more leads, this will then incur a further ‘leads fee’. The exact amount is yet to be determined. Profiles allow brokers to produce their own curated content, conduct digital Q&A sessions with interested users, and then get in touch with those users to generate leads. Brokers will also get assistance in building their brand among Chinese buyers, and gain access to online and offline events organised by the company. “This is a knowledge-sharing platform. For knowledge itself, there are no boundaries. ... We want to encourage best practices from developed countries to developing countries,” Peng said.
THE RISE OF FINTECHS IN AUSTRALIA Source: Scaling the Fintech Opportunity for Sydney and Australia report, KPMG
Fintech capital invested: US$675m in 2016 vs US$428m in 2014
59%
of respondents identified regtech, payments and blockchain as areas in which Australia has the potential to lead in fintech
10
www.brokernews.com.au
Fintech companies: 579 (employing >10,000 staff) in 2017 vs <100 in 2014
70% of respondents identified London, Silicon Valley and New York as global leaders in fintech vs 7% who thought Australia was leading
38%
of respondents identified government policy, support and vision, and regulatory environment as key to fintech growth
MAJOR BANK PORTAL TO BOOST BROKER KNOWLEDGE has unveiled a new content portal aimed at improving the knowledge and skills of its 13,500 accredited brokers. Ideas Hub for Westpac and Learning Lab for St. George, BankSA and Bank of Melbourne are designed to give brokers 24/7 access to information on products, processes and pain points, as well as ideas from Australia’s top thinkers. The idea was born out of a Westpac broker survey last year that identified a desire for better access to learning and development in an innovative, digital manner. WESTPAC
TECHNOLOGY UPDATE
SKILLS STAFF WILL NEED MOST IN NEXT 5-10 YEARS Source: NAB Moments that Matter, Understanding Australian SMEs
35%
Self-motivation
32%
Adaptability
31%
Service orientation
26%
Complex problem-solving
22%
People management Understanding various media platforms and how to communicate with them
21%
Creativity
20%
Business acumen
20% 19%
Critical thinking Ability to work/collaborate in a physical setting
18%
Social and emotional intelligence
18%
Computer coding
11%
Ability to work/collaborate in a virtual setting
11%
Ability to operate in different cultural settings
10%
Ability to translate detail into reasoning
Glenn Lees, Connective
8% 0
10%
20%
30%
40%
% of respondoents
CORELOGIC LAUNCHES UPGRADED HOME VALUE INDEX data and analytics specialist CoreLogic has unveiled the next generation of its Hedonic Home Value Index to provide greater insights into the Australian housing market on both a national and granular scale. It formulates a ‘value’ figure for each property using key attributes such as land area and number of bedrooms, bathrooms and car spaces, adding recent local sales figures. The Index is designed to measure pure returns and exclude value added through renovation and new construction. Estimated capital gains will be based on the change in the overall value of a consistent housing portfolio over each monthly time period. PROPERTY
CONNECTIVE SLASHES TIME AND COSTS WITH NEXTGEN.NET
NextGen.Net Assessment Metric API service is allowing Connective to determine the viability of loan applications within the aggregator’s ‘Mercury’ platform, thereby averting duplicate actions and ensuring that loan applications comply with lender policy. “We’re now saving hundreds of peoplehours a year by not having to duplicate functions and by avoiding doing work that the API can perform. Plus we now bill out once-only and that’s it,” proclaims Connective CEO Glenn Lees. “Our utilisation of NextGen.Net APIs and the provision of them to our brokers is a key tactical component in our future technology strategy. It’s central to our whole IT model.” Lees is effusive in his praise of the ApplyOnline system and its associated services, referring to it as “a core part of Connective’s innovative platform that gives brokers exactly what they want”. “ApplyOnline is the best-in-class application system and integral to our success,” he says. The Assessment Metric API removes the need for broker groups to provide resources in order to keep up with lenders’ changes. It is embedded into Connective’s CRM Mercury platform to provide up-to-date lender requirements to their brokers at the point of sale, before they launch the ApplyOnline lender module to submit the application. As Lees explains, “instead of needing to maintain a database of all the lenders’ different policy requirements, Connective brokers can automatically call the ApplyOnline API service and access that same information”. The Assessment Metric API is a single source of data for all lender requirements. NextGen.Net Customer Account Manager Anthony Leonard says the bottom line is that by handing loan viability assessment over to NextGen.Net, “the experts in this field”, Connective is paying less by doing away with replication.
Anthony Leonard, NextGen.Net
“The significant point to make about this API is that a lot of broker groups take the serviceability calculators from the lenders, and then have to reverse engineer and replicate what the lender is asking them to do in terms of serviceability,” Leonard says. “Our assessment service allows the broker to call the API, which has all the lenders’ serviceability rules embedded in it.” Via Mercury, Connective provides front-end support and identifies opportunities for brokers. ApplyOnline is the essential link between the brokers and the lenders, and the Assessment Metric API delivers further on this by preventing duplication. Lees says the functionality of the ApplyOnline borrowing capacity tool is invaluable because Mercury’s roadmap focuses on what Connective does best, CRM, and leaves the rest to experts in the respective fields. Currently, Lees is piloting two publicly available integration platforms, ‘Zapier’ and ‘Microsoft Flow’, which enable brokers to set up rules and use the digital marketing tool of their choice. “When we were first building Mercury we made the decision to only build things that make sense for us to build and hand over to others that which is not our area of expertise,” he says. “Mercury sits at the centre of a very broad and rich ecosystem and brokers get to choose the tools they want that are best suited to their purpose, which is why the NextGen.Net Assessment Metric API service is such a great asset. It serves the brokers and it certainly works for us.” “The API is saving Connective many hours that would have been wasted doing reverse engineering of serviceability calculators. This means that people who were once employed doing that are now doing value-add work,” says Leonard.
NEWS
R E G U L AT O R S
COMPETITIVE CONCERNS BEHIND RISKY LENDING: RBA around maintaining a competitive edge are one reason why banks have been allegedly unable to rein in risky lending of their own accord. Referencing the high levels of household debt around the country, RBA governor Philip Lowe said during a speech that the Reserve Bank had been working closely with APRA to ensure strong lending practices within the industry. As for why lenders did not try harder to constrain lending themselves, Lowe said institutions worried it would affect their competitive position and the market reaction. CONCERNS
E-FORM ISSUES LEAD TO BROKER’S BAN Difficulties in filling out an ASIC compliance form were part of a chain of events that caused one broker to be banned
Victorian mortgage broker was banned and has had her licence cancelled in part because of difficulties she had in filling out a digital compliance certificate, states a Federal Court appeals decision. Former finance broker Meenakshi Devi Callychurn, who ran Unique Mortgage Services (UMS), was granted the right to appeal the original decision made by the Administrative Appeals Tribunal when three Federal Court judges ruled in her favour on 5 September. Callychurn had appealed the Tribunal’s original decision once before but was unsuccessful. One reason that primary judge upheld the ban was because Callychurn had listed her former business partner as a “fit and proper person” when he was not. This was despite ASIC conceding that she had had difficulties in relaying this information to the regulator through its digital forms. Callychurn’s former business partner, Rudy Frugtniet, was the sole director of UMS until October 2011, when the Victorian Civil and Administrative Appeals A
WESTPAC FACES ASIC ALLEGATIONS method of assessing borrower suitability has come under fire from ASIC in an ongoing legal battle. The civil proceedings allege the bank failed to conduct proper assessments to ascertain whether borrowers could afford to repay their home loans. Westpac has denied this claim. ASIC claimed in court filings obtained by the Australian Financial Review that the bank’s reliance on the Household Expenditure Measure led to approvals in cases where a “proper assessment” based on actual spending would have unveiled a monthly financial shortfall. WESTPAC’S
12
www.brokernews.com.au
Tribunal disqualified him from practising as a lay associate of a legal practice within the state. He unsuccessfully appealed this decision and became unfit to act as UMS’s director from 12 January 2013. This put Callychurn in the role of sole director of UMS from October 2011 until April 2015, when she was eventually banned for a number of reasons, including “filing a false or misleading annual compliance certificate” in 2011 and 2012, which still listed Frugtniet as a fit and proper person. Court documents show, however, that she had attempted to notify ASIC of this change but was unsuccessful due to limitations in the digital format. While the Tribunal originally recognised that the computer issue was “not a circumstance that was created by [Callychurn]”, it said she should have adopted “the proper course” and contacted ASIC directly for further assistance. However, the Federal Court found two issues with this finding. “First, there was no evidence before the Tribunal that
‘contacting ASIC’ would have enabled [Callychurn] in some fashion or another to have completed the compliance certificate differently. “Secondly, as completed, the disputed part of the 2012 compliance certificate … on its face, must be read, as a matter of ordinary language, as asserting that [Frugtniet] was a fit and proper person, and company secretary, during the 2012 year and had only ceased to be so, on 12 January 2013, after that year had concluded.” Callychurn’s actions therefore did not show that she intended to commit a falsehood for two reasons, the Federal Court said. “First, she had correctly recorded him as having ceased to be a fit and proper person after the end of the relevant 2012 year for which she made the compliance certificate.” “Secondly, ASIC knew, or must be taken to have known, of how its own electronic form operated to prevent listing someone in the field for fit and proper persons at the compliance date where that person’s name appeared in the field for persons who had ceased to be fit and proper persons.” The Federal Court thus permitted a new appeal with the Administrative Appeals Tribunal, ordering ASIC to cover the costs.
RED TAPE HOLDING SMES BACK Source: NAB Moments that Matter, Understanding Australian SMEs
Dealing with red tape takes a lot of effort
69%
I spend too much time working ‘in’ the business instead of ‘on’ the business, on things like business development and planning
57%
I feel overwhelmed by the complexity of running a business and having to wear too many ‘hats’ at once
48%
I don’t fully understand the tax system that applies to me
44%
0
10%
20%
30%
40%
50%
60%
70%
% of respondents
FLEX COMMISSION BAN COMES INTO EFFECT has formally banned flex commissions in the car finance market. Flex commissions are paid by lenders to car finance brokers (typically car dealers), allowing dealers to set the interest rate on the car loan. The higher the interest rate, the larger the commission earned by a dealer. ASIC is banning these commissions because it has found that they lead to consumers paying excessive interest rates on their car loans. The ban comes after ASIC led a public consultation on banning these commissions. ASIC
FE AT URES
COVER STORY
PEXA’S QUIET REVOLUTION Marcus Price, CEO of PEXA, is spearheading the property industry’s transition from paper to digital settlements, a move that has challenged practitioners and lenders to adapt. He talks about being at the frontier of digital disruption and how brokers are going to fit into PEXA’s widening ecosystem
Marcus Price’s career, technology and change have been recurring themes, from starting three of his own technology companies to working at NAB. Those experiences, as well as his psychology degree and personal study of history, have served him well as the CEO of Property Exchange Australia (PEXA), where he is leading the $7.2trn residential property market and those who work in it into entirely new territory, digitising the settlement process to do away with lost cheques, postal problems and stressful in-person settlements. Modernising property settlements isn’t just about implementing new technology and hoping everyone jumps aboard. It’s about building people’s trust in the unknown and reshaping how they think and approach the settlement process. “E-conveyancing was not a technology problem; it was a people and business problem. There’s nothing particularly earthshattering about the technology we’re using here; it’s pretty straightforward stuff,” he says. “It’s about changing behaviours and changing processes, so I think a science degree in psychology was entirely the appropriate qualification,” he says. So far Price and the PEXA team have been incredibly successful in getting nearly 5,000 conveyancers and lawyers as well as 129 lenders to shelve their familiar paper THROUGHOUT
14
www.brokernews.com.au
processes. More than 550,000 digital transactions worth almost $70bn have been transacted through PEXA’s online platform since 2013. But Price’s work is not done yet.
things that’s going to creep up on you,” he says. There’s a “quiet revolution” going on in the end-to-end digitisation of the mortgage and lending processes, and Price sees
“Embrace the change and be part of it. Make sure that the industry we get at the end of this is the one you want to be part of ” Marcus Price, PEXA “I think people underestimate the impact of the change at this stage. It’s going to be quite significant and it’s going to take a little while; it’s one of those
brokers as being part of it. While brokers aren’t registered to be included in the PEXA workspace, they can reap some immediate benefits from seeing
their clients through a better, faster and cheaper settlement process. Price says settlement times for refinances, which as of 1 August must now be lodged electronically in Victoria and NSW, have dropped by about half through PEXA, and that could be reduced even further. That ease and speed of refinancing will be a boon for brokers and their clients when interest rates inevitably rise and people are stressed financially. Price also expects conveyancing fees to reduce over time, although the market sets its own rates. PEXA has a flat fee for service structure, which members are charged on successful transactions. “We can offer complete transparency of the settlement process, which is one of the big frustrations for mortgage brokers. They can get the business, but of course they can’t really offer their client the certainty of when settlement is going to happen,” he says. That will change, likely in the next six to 12 months, with the development of applications by banks and other parties that will link into the PEXA workspace, providing brokers and their clients with a way to view and track the progress of settlement, similar to how one can track an online shopping parcel in real time from warehouse to doorstep. PEXA already has an app that does this, called SettleMe, which is available to lawyers,
KEY BUSINESS METRICS
$70BN
value of property transacted electronically via PEXA
129
lenders
4,681
lawyers and conveyancers
550,000+
digital transactions completed
MORE THAN 450,000 paper cheques replaced by digital payments
As of 1 August 2017, refinances in NSW and Vic must now all be completed online
WA and Vic will begin lodging all property transactions electronically in 2018, followed by NSW in 2019
PEXA was formed in January 2010 in response to a Council of Australian Governments initiative to create a national e-conveyancing platform
Became known as Property Exchange Australia in January 2014 Shareholders are four major banks; NSW, Vic, WA and Qld governments; Macquarie Capital, Little Group and Link Group
Marcus Price, CEO of PEXA
conveyancers and their clients. Giving brokers this sort of access will offer them more certainty and clarity in regard to settlement, and it will cut out some of the phone tag between banks and brokers, he says. Once brokers see how convenient it is, Price believes they’ll start advocating for their clients to settle their property through a PEXA practitioner because of how much more reliable and less error-prone it is. “What [brokers] should do is start insisting on being part of that ecosystem of innovation, because they have a real role to play, in particular, in the customer experience part of it, which is really what the brokers are all about,” he says. “They really should demand, and will get, tools to give to their customers and tools to make that customer experience much better and more efficient.” One of those brokers eager to be part of the ecosystem is Marshall Condon, CEO of
Melbourne-based brokerage Neue Black. “That process of manually going to settlement with cheques and you’re 10 cents out is archaic at best. In the age that we’re in and with what we can do with technology, it makes sense that we bring it all online. But for us, we would love to be able to get access to PEXA so we can still keep involved with that process and make sure that the actual process is followed,” Condon says. As it stands right now, brokers have to call lenders and lawyers, and they have to call one another, just to find out what’s going on. “If we could be involved in the process and view the file moving forward, it’s a better outcome for everyone,” he says. A broker’s job isn’t done once they have the loan documents back, Condon says. “Our job is done when the loan settles, and that last part is a critical part … if you don’t get that right, your whole experience of the whole loan goes down the drain.
“We want to make sure it’s the best experience it possibly can be,” he adds. Some banks have already started responding. Brett Walker, Suncorp home lending manager, said the non-major’s next priority is improving its tracking transparency to give brokers a real-time view of the status of their clients’ applications. “We’ve got a sophisticated status tracking and workflow system internally; however, we know this is not fully transparent to brokers due to some technical limitations on messaging,” Walker says, adding that this will be improved throughout FY18. Suncorp wants to enhance this sort of self-service capability so brokers and customers can get a “snapshot view”, which will improve transparency, he says. Adopting change It doesn’t matter what kind of technological change society is facing – steam trains, electricity, internal combustion engines or
plastics – inevitably, humans will adopt the most efficient tool available, and that’s no different now with digital disruption. It’s more efficient to exchange information digitally, which is why the industry is phasing out paper. While brokers and banks have been supportive and eager to join this revolution, there are still some conveyancing practitioners who are afraid to let go of what they know, Price says. That, or they are such small operators they don’t feel they have the resources or time to change on their own. Price is not pushy about getting people to adopt PEXA. He has empathy for those who have been doing settlements the paper way for 30 years – using a system that’s been around for a century and a half – and he understands how hard it is to relinquish that control. That’s why he says it’s about balancing how much change people can absorb, providing them with the necessary tools and education, and having the infrastructure in www.brokernews.com.au
15
FE AT URES
place to support them through the conversion. “It’s a huge leap of faith and I never underestimate what it takes,” he says. Price says he’s proud of the industry for making this shift, and he values the trust it has in PEXA. While Price has made a point of helping practitioners through this transition, he doesn’t actually have to convince anyone to adopt PEXA, because state governments will be making it mandatory. In Western Australia, all property transactions will be lodged electronically from 1 May 2018, followed by Victoria in October and NSW in June 2019. The industry has to move in one direction together in order for the system to work, or one person working in paper could hold back the rest. Eventually there has to be a sunset clause on the old technology, he says. “You do need to shut the door on paper.” All in it together “We are not doing this to the industry; we are doing this for the industry. This is not our
Marshall Condon, CEO and founder of Neue Black
initially joined forces to seed PEXA’s growth, and now online, between practitioners helping each other through transactions and banks providing useful hints and responding to commentary, replacing the old us versus them mentality. In the future, Price sees PEXA’s “ecosystem” widening, further cementing itself as a
“E-conveyancing was not a technology problem; it was a people and business problem” Marcus Price, PEXA network; it’s the industry’s network. You don’t join PEXA to become a customer of PEXA; you join PEXA because you want to communicate with someone else,” Price says. PEXA is similar to Facebook in that way, he says. It’s a collaborative network business that only works if everyone believes in it and everyone is part of it. So far, he’s seen “unprecedented collaboration”, firstly between the state governments and banks who 16
www.brokernews.com.au
cornerstone of the property industry’s infrastructure, with applications providing brokers, real estate agents, and possibly even removalists and utility companies, with better access to the settlement process. “You can’t assume the world is going to stay the way it is. There’s going to be a lot of change the next couple of years,” Price says. “Embrace the change and be part of it. Make sure that the industry we get at the end of this is the one you want to be part of.” AB
PEXA IS TRANSFORMING AUSTRALIA’S RESIDENTIAL PROPERTY MARKET
Halving
Signing up
REFINANCE TIMES
129 LENDERS
by going digital
who digitally process 98% of mortgages
Removing more than
Finalising multi-lot property units
450,000
166x FASTER
relic bank cheques
than pen and paper methods
Ensuring property sellers receive sale funds faster online
Providing buyers and sellers with a digital app that tracks final stages of settlement
Saving trees. Paper contracts for
250 APARTMENT SALES use 30 large trees
www.brokernews.com.au
17
FE AT URES
NE WS ANALYSIS
IF IT’S NOT BROKEN, WHY FIX IT? In their submissions to the Treasury and in interviews with Australian Broker, mortgage brokers tell us what they’re really thinking about the ASIC remuneration review and how they see it all playing out the topic of ASIC’s Review of Mortgage Broker Remuneration and every broker has an opinion. Whether they’re willing to express that on the record is another matter. As expected, their opinions run the gamut. Some brokers are supportive of a few of ASIC’s findings, while others dispute the report’s merits and question why it was done it the first place. Some shrug and say they’re carrying on caring for their clients and would prefer not to get drawn into any controversy or negative stories in the press. But while many insist it’s “business as usual”, the importance of the review cannot be ignored, especially when the outcome could affect brokers’ income. In the last issue, we covered what the aggregators, banks, associations and consumer groups had to say in their public submissions. This issue, we’re turning to brokers. RAISE
Were brokers fairly represented? “My general overall view, and it has been this for some time, is that there’ve been a lot of people involved in this process and yet there’s never been a brokers’ representative,” Ben Anson, principal at Legend Finance in Sydney, told Australian Broker. “And yet if all the brokers, 10,000 of us, went on strike for a month tomorrow, we would grind lending in Australia to a halt. I think we have been treated quite disrespectfully, quite condescendingly, given that there’s no brokers’ representative.” 18
www.brokernews.com.au
Anson is not the only one who feels like brokers haven’t been fairly and sufficiently represented in this process – in ASIC’s review itself, then in the submissions, and now in the self-regulation process. Glen McKissack, CEO of Loans
called for upfront commission to be calculated net of offset account balances. “I am therefore concerned that this will be tainted by National Australia Bank and there clearly needs to be a view from a mortgage
“It belittles the industry by having unqualified brokers giving financial advice to clients” Shawn French, broker Actually, a company in Victoria with 38 mortgage brokers, said he had hastily amended his submission after discovering that his aggregator, PLAN, would be incorporated into NAB’s response. NAB’s submission to the Treasury
broking business,” he wrote. Another broker, Maria Rigoni, director of Universal Wealth Management in Victoria, said in her submission that she had given up being a member of either the MFAA or the FBAA. “I believe they
have a conflict of interest with lenders and cannot represent the mortgage brokers’ position in stakeholder meetings because of that conflict. They add no value proposition to my mortgage broking business.” More responsibilities, less commission? Prior to 2004, upfront commission was 1%, while today it’s 0.65%, Anson says. “How many jobs out there have taken a 35% pay cut? And yet our job load has increased because of all the additional compliance, credit reporting, the National Consumer Credit Protection laws, responsible lending. We’ve now become the compliance arm for the banks and the aggregators, our costs have increased and yet our remuneration has sunk.” While brokers now have more
BROKERS PLAY CRITICAL ROLE IN HOME LOAN MARKET Source: ASIC
$545bn
520,000
loans written
in outstanding loans It’s big business:
$175bn
$600k
in new loans
$500k
53%
growth
$400k
54.3%
$300k $200k $100k
of home loans sold went through a broker
$2.4bn in commissions were paid by lenders to aggregators
0
2012
2013
2014
2015
Number of loans written
think we do this. We work with the client to find a product which suits them and generally find a loan with the lowest possible rate which will reduce their monthly repayments.” So, what happens next? What brokers reiterated in their interviews with Australian Broker and in their submissions to the Treasury was that the current commission model works and it provides consumers with better choices and positive outcomes, something many backed up by referencing brokers’ 50% market share. “All of these changes of policies and reviews are still looking to fix a
were “undisclosed and unnecessary”. Many others agreed with this point. He and Shawn French, a broker at Smartline, also said brokers should be more qualified and have some minimum educational qualifications. “It is too easy for someone who has no experience and no qualifications to become a mortgage broker; hence it encourages unsuitable people to join the industry. It belittles the industry by having unqualified brokers giving financial advice to clients,” French wrote. While Anson, of Legend Finance, says he doesn’t want to see any changes to commission, except for
“Very few clients have shown any concern for how much I am paid for obtaining a loan that will ultimately help them achieve their goals” Glen McKissack, CEO of Loans Actually system that was not really broken. The government started looking closely into mortgage broking because people were chasing more and more brokers over banks – that in itself should be sufficient to determine that the presence of brokers delivers a better customer outcome,” says Xavier Quenon, director of Go Mortgage Corporation in Queensland. Broker Barry Thatcher said in his submission that what could be improved was the removal of soft-dollar bonuses, which he said
it going up, he believes ASIC will feel compelled to make modifications to justify “all the huff and puff that’s been going on”. Quenon echoed this, saying he hoped changes were not made just for the sake of it. “I am hoping that they are able to demonstrate to the government that the current system is mostly sound, even if some tweaks can be made on the edges,” he says. “Sometimes leaving the system the way it is is the best course of action.” AB
BROKERS SETTLED NEARLY $50BN IN HOME LOANS Source: MFAA’s quarterly market survey
Jan-Mar Apr-Jun Jul-Sep Oct-Dec Jan-Mar Apr-Jun Jul-Sep Oct-Dec Jan-Mar Apr-Jun Jul-Sep Oct-Dec Jan-Mar Apr-Jun Jul-Sep Oct-Dec Jan-Mar Apr-Jun 2013 2013 2013 2013 2014 2014 2014 2014 2015 2015 2015 2015 2016 2016 2016 2016 2017 2017
onerous responsibilities, their remuneration hasn’t reflected that. “How much more qualified do banks want us to be?” says Anson, who has three degrees, including an MBA. While all of the broker submissions rejected changing how commission is calculated, such as by LVR, many proposed setting commission at a standard level across all lenders. Hilko Siegers, director of Everfirst Financial Services in Perth, wrote that standardised commissions “remove one level of confusion for our clients”, but he warned that trail commission must be protected as it covers “non-paid process activities like discharges, loan switches and security substitutions, and all this before office, car, phone and other business activity running costs”. To draw the conclusion that commissions based on loan size have poor consumer outcomes is “both incorrect and unproven”, McKissack said. “The size of the loan is only important in the fact that it directly correlates with the client’s needs. … Very few clients have shown any concern for how much I am paid for obtaining a loan that will ultimately help them achieve their goals.” In many cases, it’s the client asking for a bigger loan amount for investment purposes or as an emergency buffer, not the other way around. Harj Dhillon, director of Central Lending Solutions in Perth, said in his submission that brokers in no way encouraged clients to increase their loan size. “This is ludicrous to
$49,462,793,648 $46,000,026,461 $50,186,797,460 $48,576,813,258 $46,384,652,957 $43,390,028,301 $49,872,636,110 $49,544,774,789 $47,174,030,668 $40,614,829,064 $43,702,286,402 $41,324,540,266 $39,316,257,254 $34,138,287,539 $36,871,974,415 $32,008,589,215 $30,611,631,280 $24,154,666,925 0
10
20
30
40
50
$bn
www.brokernews.com.au
19
FE AT URES
OPINION
RISKY BUSINESS Banks shouldn’t underestimate the risk of concentration in the housing market, writes Harry Scheule, an associate professor of finance at UTS Business School
Unlike other countries, Australian banks offer to lend for only up to five years at a fixed rate and the majority of loans are at a variable rate. This leaves Australian borrowers exposed to interest rate increases. In the past few years, interest rates have been lowered as RBA economists
view of Australian banks on the risk that mortgage stress poses to our economy and the banks’ own viability is worrying. Shayne Elliott, CEO of ANZ Bank, commented in the Four Corners report aired on 21 August: “The reality is that housing loans are pretty good because they’re quite diverse in terms of lots of relatively small loans across the country.” This view contradicts research from the United States, which has found that housing markets there are less diversified than previously thought. This means any house price shocks will likely occur simultaneously across the country, causing large cumulative losses for borrowers and banks via mortgage defaults. Australian housing markets are likely to be even more concentrated than in the US because of the population size of Sydney and Melbourne. APRA has already issued guidelines to the banks on tracking exposure to mortgages and limiting growth of loans to investors, in particular loans with interest-only repayments. An independent review by Stephen Sedgwick on behalf of the industry also recommended banks stop paying mortgage brokers based on the volume of loans they secure, in an effort to reduce risks. But these steps might not be enough to ensure security. THE
Australian banks’ exposure to mortgage risk Bank losses during the GFC were in large part driven by borrowers not being able to make their mortgage repayments. After receiving a loan, a borrower may experience income shocks, like loss of a job or demotion, and expense shocks, like higher petrol prices or interest rates, that affect their ability to service their mortgage. Australian mortgage contracts are risky for borrowers in international terms. 20
www.brokernews.com.au
them the highest loan amount. Lending standards should also consider the concentration of housing income and expenses in a borrower’s portfolio. Banks should promote fixed rate mortgages. This type of mortgage transfers interest rate risk from borrowers to the banks, which are better placed to manage this risk. This may come at an additional cost but should be small compared to the cost borne by consumers should the housing bubble ever burst. There also needs to be more scrutiny of the use of offset accounts and redraw facilities being used as an offset for outstanding loans. Borrowers often use these funds to purchase additional properties, and they may not be available in the case of a mortgage default. Instead of promoting offset accounts it may be better to give borrowers a prepayment on their mortgage, but not an option to redraw. Should consumers want to draw down on the equity in their homes, they could then apply for a second mortgage. Mortgage brokers should act as independent advisers, a tool for consumer
The Sedgwick banking review has been a step in the right direction, but the focus should be on banks rather than mortgage brokers have targeted low inflation rates. Interest rates are now close to zero, limiting the ability of the RBA to stimulate economic growth. There’s the possibility that the RBA could raise interest rates, causing shocks to mortgage borrowers. My research shows this shock could increase bank losses substantially. At the moment, 23% of consumer expenses are housing related and this number is likely higher for mortgage borrowers and could be growing. Interest rate increases, in combination with the current high debt levels, are therefore likely to increase inflation and trigger further interest increases.
Harry Scheule Associate professor of finance, UTS Business School
Dealing with the risk of mortgage stress Current bank portfolios are not well diversified if 60% of bank assets are in mortgages. Other loan classes, such as commercial real estate loans and small to medium enterprise loans, are also often property-backed. Bank lending standards need to be more consistent to avoid borrowers shopping around for the lender that offers
information and bank competition, as smaller lenders in particular rely on mortgage brokers. The Sedgwick report suggested the loan-to-value ratio of mortgages should be considered when paying mortgage brokers. This would mean that loans with high LVRs (where the borrower is more likely to default) would earn lower fees. The Sedgwick banking review has been a step in the right direction, but the focus should be on banks rather than mortgage brokers, as it’s ultimately the bank that is in a contract with the consumer. Some of this may require a fundamental value change. It’s not likely the Australian appetite for property will change, but this means we need to hedge our bets against any risks by improving diversification and the way banks finance mortgages. AB
This article first appeared on The Conversation and is republished with permission. More at theconversation.com.au.
IN THE NE WS
FUTURE FUNDING
A new report reveals the uncertainties and the possibilities that fintechs and data could have on the lending space
new report from the World Economic Forum, in partnership with Deloitte, has tried to predict how the increasing influence of fintechs will impact the future of the lending industry. Beyond Fintech: A pragmatic assessment of disruptive potential in financial services represents the culmination of three years of research into the transformative role of fintechs, exploring how they will drive change in the payments, insurance, digital banking, lending, investment management, equity crowdfunding and market infrastructure spaces. The report presents five key uncertainties the lending industry faces and suggests that one outcome could have disconcerting results for brokers. The uncertainties identified ask if platform-based lending will become a relevant distribution channel; if marketplace lenders will provide direct lending; how borrowers’ distribution channel preferences will evolve; how much more effective underwriting will become with new sources of data and analytical techniques; and what will be the long-term impact of marketplace lenders licensing their underwriting technology. The report describes the one outcome of these uncertainties that would be of most interest to brokers. It says: “Nonfinancial firms [could] move horizontally into financial services and disintermediate the traditional broker channel.” There are four stages to this outcome: A
As lending becomes commoditised, lenders look for new opportunities to acquire new customers and collect data on their existing customers.
1
Lenders form partnerships with non-financial platforms to use their data and offer loans through their user interfaces.
2
Lenders improve the sophistication of their underwriting, using their partners’ data to make highly targeted offers that anticipate customer needs.
3
Non-financial platforms effectively replace the traditional broker channel and derive additional customer loyalty from having customers locked into their ecosystem.
4
One of the best examples of a non-financial platform that’s emerged as an important source of underwriting data and credit distribution is Amazon Lending, which is shifting the balance of power towards customer platforms, the report states. Amazon offers credit to merchants who sell on its platform, using sales data to measure risk. If a merchant defaults on the loan, Amazon can choose to withhold sales on its platform. The company has already lent more than $3bn and is expanding this offering. “As partnerships between banks and non-financial firms proliferate, customers’ experience improves and choices become numerous,” the report states. What effect this will have on brokers is unclear. One possibility is that as customers’ gain better access to loans in-app, such as with merchants on Amazon Lending, brokers will find themselves distanced from their clients. Regardless of how the future does in fact unfold, there are a few main takeaways from the report. Until online lenders can find an alternative funding source, they will be limited in their ability to compete with the banks because of high and unstable funding costs. That said, online lenders are challenging banks on a different front: by simplifying and speeding up the credit process, they’re reorienting customers’ expectations, and mainstream lenders have to keep up. Finally, moving forward, lenders will increasingly look for new ways to collect and use data to inform lending decisions. AB www.brokernews.com.au
21
PEOPLE
Have an interesting deal? Had a particularly difficult or interesting deal? Why not share it with us? Email:
Otiena.Ellwand@keymedia.com.au
A BIG DEAL
THE SOLUTION
A referral led Sydneysider Nathan Smith, director at Birdie Wealth, into the country, where he worked the biggest land deal he’d ever had: a 450-acre expanse that his client wanted to turn into a deer farm. Here’s how research, persistence and help from a regional specialist at the bank got the deal across the line
Location: Wolumla, NSW
THE FACTS
Loan size $400,000
Client Young couple in their late 20s
22
www.brokernews.com.au
Goal Buy block of land for home and deer farm
investment property and the rent received on that property. It wasn’t quite residential, it wasn’t quite a working farm, so we were caught somewhere in between. The clients had already fallen in love
THE SCENARIO
This loan was for a young couple who wanted to purchase a block of land where they could build their dream home and eventually start a deer farm. They were both fly-in, fly-out workers in a WA mine, and they already owned a property in a large town nearby. They wanted to keep that house as an investment property and use the equity to buy the farmland. What made it memorable for me as a Sydneysider was the size of the block. It was 450 acres, making it as big as the whole country of Monaco! This was the biggest piece of land that I’d ever come across. Finding lenders who would consider a property of this size was the biggest hurdle. Most lenders are limited to 100–150 acres. When I mentioned it was a big block, they said, “Yes, we do that,” but when I told them how big, they didn’t want to touch it. The clients also wanted to keep their current property, so servicing was quite tight. It meant using things like the gearing on the
Loan term 15 years
We ran the scenario by numerous lenders who would give us limited commitment. One lender advised they had no restrictions on land size, so it fit their policy. We submitted the loan as it was a competitive product. The property was valued and the assessor stated that while they had no restrictions on land size, they had no appetite for this block. I had to be the bearer of bad news and advise my clients that the lender would not consider it. We then spoke to a specialist at ANZ who worked near the location and had a good understanding of the area. She had insight from doing these deals previously, so she was able to give great advice on how to position the file. She was fantastic in working out a solution, but we still needed to push to get the structure and set-up we were after. Through plenty of negotiation back and forth we finally got all conditions removed and the loan was formally approved. The deal went to settlement six weeks later. Having a regional expert at the bank was critical. Talking to someone who understood the area, where the block was, what it looked like, what it could and couldn’t be used for helped get the deal across the line. THE TAKEAWAY
This was certainly an interesting deal. That’s the beauty of the job; you never know what scenarios you’re going to come across. Regardless of how long you’ve been doing it, there’s always going to be something that comes across the table that you haven’t seen before. This experience highlighted the fact that behind every transaction there is a dream and a goal. The outcome of this deal would determine where their lives went. Going onto the land with them and being shown around made it very real. I felt, due to the
What made it memorable for me as a Sydneysider was the size of the block. It was 450 acres, making it as big as the whole country of Monaco!
Nathan Smith Director at Birdie Wealth
with the block and location, and after visiting post-settlement, I could see why. When you are on the land, you’re completely isolated; however, it is only a 20-minute drive from the beach and major shopping centres in Merimbula. They gave me a full tour of the property, showing me where they planned to build their home, roads and dams.
clients’ passion for this transaction and their attachment to the land, that a solution had to be found; it made me even more persistent to find a solution. My advice to other brokers in this position is to always be conscious that they play an important role in their clients’ lives. If you can be their trusted adviser, referrals and future business will naturally follow. AB
THE CHOICE IS YOURS
MAGAZINE The only independent magazine dedicated to mortgage industry news, opinion and analysis
WEBSITE Breaking news, in-depth profiles, features, online forum and Australian Broker TV
ENEWSLETTER Daily news service delivered straight to your inbox every morning
FOR MORE INFORMATION, PLEASE EMAIL EDITOR@BROKERNEWS.COM.AU www.brokernews.com.au
23
PEOPLE
Get involved in the discussion Share your thoughts at
brokernews.com.au
FROM THE FORUM
Top comments from trending stories on brokernews.com.au
BROKER CLIENTS NOT BETTER OFF, SAY CONSUMER GROUPS
‘NOT EVERYONE IS BUILT TO BE A BROKER’: MFAA
Mortgage brokers don’t always obtain better-priced loans for clients than the banks and they don’t always offer a diverse range of loan options, according to a joint submission to Treasury from CHOICE, Consumer Action, Financial Counselling Australia and the Financial Rights Legal Centre. While the submission mainly focused on ASIC’s remuneration review, it also made a number of suggestions outside of ASIC’s six proposals, including increasing standards in the industry. The groups claimed that some clients fail to receive the service they expect from brokers.
The MFAA says the significant proportion of new brokers who are failing to reach success in the industry is troubling. Speaking at an industry roundtable hosted by Alphabroker Mentoring on 18 August, MFAA head of communications Stephen Hale said the number of brokers coming into the industry from outside of banking and finance was on the rise. “What disturbs us as an association is that the industry average of success for new-to-industry brokers is only 50%,” he said.
I do agree that many brokers use a preferred lender, rather than the best loan they can for the client at the time. We all know that scrapping commissions is the mantra of the big banks, as they will not reduce loan interest rates, and make more profit. It will also drive more clients to go direct, and decimate the lenders that only have brokers for distribution.
Here’s a suggestion: improve the entry level so that your average Jo Blow who is, say, a plumber [doesn’t] decide on becoming a broker without any experience. It is the hardest it has ever been in finance, let’s not be naive about this, so how can a ‘rookie’ expect to survive without the minimum skill set and experience?
Brado on 31/08/17 at 8:47 AM
Head Carrot on 5/09/17 at 8:41 AM
The statement made by these consumer groups is majorly untrue! We as brokers always do what is right for our clients, and finding the right loan isn’t black and white; some direct channel lenders pick and choose their loans and this is determined on credit scoring and credit history, along with serviceability and conduct. The brokers who the consumer groups refer to are a minority and should be weeded out and clamped down on, for sure. Commission structures don’t determine where I place a client’s loan, nor do they for most other brokers. The commission we receive is for hard work and many hours of administration, meeting with clients and keeping in contact with them, and to say we only place a client with the highest commission-based lender is a lie. I spend hours of unpaid work to find a suitable solution for my clients, and whatever commission is paid to me by the suitable lender, then it’s deserved, not premeditated. Would these consumer groups like to go to work and not be paid for their hours worked on a daily basis? I bet not! Shame to these groups and anyone else who thinks we don’t do the right thing by our clients and the commission we deserve and earn is not warranted!
What do they determine as success, by the way? From what I see, a vast majority of new brokers out there do not understand simple lending practice, lending policy, how to get a loan approved and why it would or would not get approved, how to find issues and then a suitable lender, or work with the client to get them into a position to be ready. I think that becoming a mortgage broker needs to be harder. The Cert IV and diploma shouldn’t be a two-week online course. At least six months should be spent training. I don’t think that it is good for the industry as a whole, when anyone can just do an online course and join up, then start spruiking they are a mortgage broker and start lodging loans. As a whole, that kind of thing will damage our industry’s reputation with the public.
If mortgage brokers are not delivering good outcomes to clients, then why are most of our businesses built from cross-referrals from satisfied clients or referrals from other trusted advisers, like accountants and financial planners? And why has the percentage of clients using mortgage brokers increased significantly over the last decade?
Maybe it’s because the old-school brokers running the mentoring have no idea how to attract clients in these times. Times have changed, and the way they did it doesn’t work any more. The advice I got from my mentor was [through] friends and family (they don’t want us knowing their business and they know we are new), find a real estate agent and find an accountant (they have in-house or established relationships with experienced brokers). Any other ideas, I asked. Ummm, not really, maybe you should try and get a job with an established firm. But they want experienced superstars. Hmmmm, oh well, good luck, keep at it, see you next month. The mentoring was farcical and degenerated into a bunch of newbies asking each other how do you get your leads?
Mark L on 31/08/17 at 9:19 AM
Newbie on 5/09/17 at 12:10 PM
Glenn Rowan on 31/08/17 at 9:17 AM
24
Brado 5/09/2017 9:34 AM
www.brokernews.com.au
CAUGHT ON CAMERA Around 300 Liberty staff from across Australia and New Zealand were treated to a very special mid-year party recently. To everyone’s surprise, the party became an informal 20-year birthday extravaganza for the leading non-bank lender, with the likes of Jessica Mauboy, DJ Claire, previous Australian Idol finalists, and even fluorescent robot dancers performing into the wee hours of Saturday morning. The eclectic Bobby McGee’s in Melbourne was the perfect venue to host the event, with revellers partying on in Chinatown. Liberty turned 20 in August after another record-breaking year, thanks to the help of their valued business partners and LNS Adviser network.
www.brokernews.com.au
25
DATA
QUEENSLAND
VIC SPOTLIGHT
Migration inflow and affordability bring welcome demand to the Brisbane market Brisbane’s inner city has been tapped as a market facing oversupply, but things could be looking up for this area due to the quick action of the state government. “The state government saw this trend early last year and in turn have pulled back on building approvals,” reports Jordan Navybox, general manager at Cohen Handler Queensland. Brisbane recorded the lowest number of building approvals among all the capital cities, which could be easing buyer fears. As a result, vacancy rates have begun stabilising, and rental yields are back up to snuff in the inner city, indicating that the rental market is recovering, to the relief of investors. As a result, this may be a good time to look into this area while there’s an opportunity to buy at below-market prices. As Brisbane’s improving long-term prospects draw more eyes to its apartment market, houses continue to flourish, especially those located around 10km from the CBD. Area
Type Median value
Quarterly
12-month
growth
growth
Brisbane
H
$525,000
1.9%
4.0%
QLD Country
H
$435,000
1.2%
1.2%
Brisbane
U
$406,800
0.4%
-2.4%
QLD Country
U
$375,000
-1.3%
4.2%
WESTERN AUSTRALIA
Perth’s comeback could be choked by the state’s faltering economy “The weak economy is reflected in the state’s poor population data. Western Australia’s total population growth in 2016 was lower than the combined population increase of Casey and Hume (outer-Melbourne LGAs). Interstate migration data also shows people have been leaving in droves,” reports Simon Pressley, managing director of Propertyology. “Perth also has an oversupply concern, with WA producing 28,535 new dwelling completions in 2016 – sufficient for 70,000 people – while the population only increased by 16,835.” Nonetheless, the president of the Real Estate Institute of WA, Hayden Groves, offers an optimistic outlook for the property market. “Perth’s property market showed signs it had stabilised in the June quarter, with the latest preliminary data revealing there was little change recorded to key market indicators over the three-month period,” he says. Area
Type Median value
Quarterly
12-month
growth
growth
MELBOURNE’S GROWTH STORY
A rising population is driving up Melbourne’s capital growth prospects as supply levels settle down
seems to be on the path towards overtaking Sydney as Australia’s most populated city. “Melbourne is a population growth story: there are more buyers than sellers. For quality properties – both houses and apartments – it is not uncommon to see five or six parties bidding aggressively. The four or five who miss out will still require a property,” comments Scott Hall, associate at Cohen Handler. “As such, Melbourne is also a capital growth story, as more people require more housing.” While property values continue to go up in this city, the rate of growth has slowed. The oversupply issue in places like the CBD, Docklands and Southbank could also be related to the generic products in these markets. Hall emphasises the need to offer a variety of dwellings in terms of available facilities and size. “Modern apartments in [these areas] can be viewed more as a financial instrument (bond) than a property – they offer a relatively attractive yield but with very limited growth prospects; in many instances a decrease from the original purchase price,” Hall warns. “Stock levels are still relatively low, particularly in terms of quality properties. In part, we think fewer properties are coming to market because, as prices have increased the costs of moving, stamp duty, agents’ fees and marketing costs have made staying where you are and renovating a relatively more attractive option.” Hall tells buyers to identify suburbs that are just starting to gentrify and have renovation potential, which is an opportunity for homeowners to manufacture growth. This initiative could be crucial because landlords cannot easily raise rents in the current climate, with rental affordability in Melbourne being close to a historic low.” AB MELBOURNE
H
$510,000
0.0%
-2.8%
Median price (houses)
WA Country
H
$346,000
-5.2%
-5.3%
$1,243,196
Perth
U
$410,000
0.6%
-2.4%
WA Country
U
$300,000
1.7%
-6.7%
www.brokernews.com.au
The Victorian housing market is split into three major segments: up to $700,000, $700,000 to $1m, and $1m plus Every part of the Victoria market is behaving differently. I think there will be some challenges ahead for people who want to buy in the $1m range and above because of the fiscal policy changes and the crackdown on foreign buyers and others looking to access credit. That upper segment, in my opinion, is probably going to face a correction. How big that correction will be is hard to predict. The segment up to $700,000 will continue booming, simply because when the majority of people hear “no stamp duty”, they start to participate. People who used to invest in more expensive properties will probably be redirected because of the difficulty in getting credit. They’ll participate in that segment, driving up demand and exceeding supply. The pressure is on from both the regulators and the banks, which seem happy to change their policies on a nearly daily, even hourly basis, complicating things to absolutely unnecessary levels. That’s not helping brokers or their customers, especially when, parallel to this, talk about changing or even reducing our commission is ongoing. Eugene Sholomov Director, MINFIN Australia in Melbourne
SUBURB TO WATCH: BALACLAVA
Perth
26
BROKER PERSPECTIVE
Quarterly growth (units) $525,982
Source: CoreLogic
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
20.1%
41.7%
48.6%
2.6%
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
-4.1%
8.2%
17.7%
3.9%
AUSTRALIAN CAPITAL TERRITORY
Houses are booming in the national capital, but high unit supply levels are pulling the overall market down
OPPORTUNITIES AND KEY INFRASTRUCTURE
Victoria Market
Williamstown
Linear Park
On the horizon
Upgraded facilities to include new breakout spaces and parking
About 600 townhouses and apartments in the works near the CBD
Dandenong Corridor to be transformed into community green space
Thirteen-storey building with 200 units coming to the suburb of Highett
HIGHEST-YIELD SUBURBS IN VICTORIA Suburb
Type
Median price
Quarterly growth
12-month growth
Inverloch
U
$350,000
-8%
15%
Dimboola
H
$111,250
-12%
-3%
Murtoa
H
$104,000
1%
16%
Nhill
H
$132,475
-2%
-5%
St Arnaud
H
$117.500
-9%
-20%
Investors are flocking to Canberra as the city’s housing market continues to prosper. According to the Domain State of the Market report for June 2017, the median house price has surpassed $720,000. This boom is attributed to Canberra’s strong housing demand, with homes close to amenities, such as schools and public transport, faring best. However, the apartment market has found itself slipping, and the median value has fallen to approximately $400,000. But demand generated by tenants has steadied the unit rental market, which has maintained a strong weekly rental rate of $420 and ensured that investors are gaining solid returns. “With healthy market confidence and affordable unit prices, the city is bursting with possibilities,” the Domain report states. Area
Type Median value
Quarterly
12-month
growth
growth
Canberra
H
$685,000
6.2%
6.6%
Canberra
U
$440,000
0.0%
3.5%
www.brokernews.com.au
27
DATA
SOUTH AUSTRALIA
South Australia soldiers on, despite the migration outflow and economic instability
CAPITAL CITY AUCTION CLEARANCE RATES
Adelaide is getting sidelined by many investors, but the property market continues to perform steadily. “The Adelaide property market’s resilience has come to the fore. Despite noted headwinds, such as slow population growth and jobs uncertainty, Adelaide’s capital city dwelling values increased 2.4% in the year to June 2017, according to CoreLogic data,” reports Gregg Harris, general manager of NAB Retail. “It was one of only three capital cities to see an increase in stock levels over the 12 months ending in July.” The average time on market has lengthened for vendors, but from Harris’s perspective this could be good for buyers, as they can take more time to find the right homes. Moreover, the rental market looks to be getting stronger for investors. “It appears that market demand is pushing the rental price higher, which is good for investors,” Harris says. Quarterly
12-month
growth
growth
Adelaide
H
$459,500
2.1%
3.5%
SA Country
H
$300,000
3.4%
2.8%
Adelaide
U
$375,000
4.2%
5.0%
SA Country
U
$183,500
-8.3%
1.3%
NEW SOUTH WALES
MEDIAN HOUSE AND UNIT PRICES
Dwelling prices in Sydney continue to increase, but at a stunted rate compared to recent growth
$1,000,000
Type Median value
Sold
41
Not sold
20
Clearance rate
67.2%
PERTH Total auctions
31
Sold
7
Not sold
12 36.8%
Houses
Sydney Melbourne Brisbane Adelaide
Perth
Hobart
Units
Darwin
$428,950
$600,000
$359,000
$472,500
$306,250
$395,000
$486,000
$400,000
$0
$327,500
$100,000
$425,000
$200,000
$541,000
$300,000
$711,500
$500,000 $400,000
$700,000
$700,000 $600,000
$900,000
$800,000
Canberra
CAPITAL CITY HOME VALUE CHANGES Capital city
Quarterly
12-month
growth
growth
H
$1,010,000
9.8%
5.6%
NSW Country
H
$455.000
1.7%
6.0%
Sydney
U
$740,000
4.7%
3.6%
NSW Country
U
$378,500
2.3%
2.8%
www.brokernews.com.au
74
$900,000
Sydney
28
Total auctions
$1,100,000
For the first time in the past five years, CoreLogic data indicates that unit values in NSW have been stagnant. “The banks led by APRA have yet again tightened lending, making it harder for investors to obtain finance, in a bid to stop any bubble bursting,” says Walter Nanni, buyer’s agent at Cohen Handler Sydney. Indeed, with affordability being a significant problem for Sydney, the restriction on investor demand that has been slowing down growth could be the breakthrough that owneroccupiers need. First home buyers have been capitalising on the new benefits that allow them to get into the property market. “They finally have the edge over investors, which will make it interesting in the coming months as it could throw the market into a mini boom as they stir things up,” Nanni comments. Area
ADELAIDE
Clearance rate
$375,500
Type Median value
The combined capital city preliminary clearance rate increased to 70.2% this week, after last week’s revised final clearance rate fell to 66.4%, which was not only the lowest combined capital city clearance rate so far this year, down -0.1% from the previous low seen over the week ending 25 June 2017 (66.5%), but the lowest clearance rate since June 2016 across the combined capitals. It will be interesting to see what the final clearance rate looks like once the remaining records have been captured. Auction volumes increased week-on-week, with 2,225 properties taken to auction this week, up from 2,074 last week and higher than this time last year (2,062).
$520,000
Area
WEEK ENDING 10 SEPTEMBER 2017
Weekly change
Monthly change
Year-to-date change
12-month change
Sydney
0.1%
0.1%
5.6%
12.3%
Melbourne
0.2%
0.6%
7.4%
12.4%
Brisbane
0.0%
0.1%
1.7%
2.9%
Adelaide
0.1%
0.0%
2.7%
5.3%
-0.1%
-0.6%
-2.7%
-2.9%
0.1%
0.2%
4.8%
9.4%
Perth Combined 5 capitals
*The monthly change is the change over the past 28 days
BRISBANE CANBERRA Total auctions
72
Sold
45
Not sold
20
Clearance rate
Total auctions
137
Sold
43
Not sold
55
Clearance rate
43.9%
69.2%
SYDNEY Total auctions
810
Sold
449
Not sold
172
Clearance rate
TASMANIA
MELBOURNE Total auctions
72.3%
1,097
Total auctions
4
Sold
687
Sold
1
Not sold
251
Not sold
2
Clearance rate
Clearance rate
73.2%
TASMANIA
Area
The Apple Isle continues to gain momentum in the property market as prices soar At the end of July 2017, Hobart recorded a year-on-year increase of 6.5% in dwelling values, according to CoreLogic. The median property price came in at just under $340,000 – the lowest among all of the capital cities. “Australia’s most affordable capital city produced 15% price growth last financial year. It also has the best rental yields, lowest vacancy rates and tightest housing supply pipeline,” says Simon Pressley, managing director at Propertyology. “We forecast that it is the only capital city in Australia with double-digit annual price growth potential over the next couple of years.” A significant contributor to this growth is the boost in the job market.
33.3%
Type
Median value
Quarterly growth
12-month growth
Hobart
H
$390,000
0.8%
6.9%
TAS Country
H
$262,500
-2.8%
1.9%
Hobart
U
$306,750
-1.3%
1.7%
TAS Country
U
$235,000
-2.1%
2.4%
All data sourced from CoreLogic.com.au
www.brokernews.com.au
29
PEOPLE
IN THE HOT SEAT Anthony O’Flynn, director of IFA Mortgages and Finance, on moving from a major bank to broking, meeting his first client at a barbecue, and the lifelong friendship that came out of helping him buy his family’s first home in Australia
Who or what inspired you to become a broker? I worked as a senior credit manager at one of the majors for A over a decade, and I noticed more clients using brokers to originate their loans. One major broker was securing his clients lower rates than what we were offered as staff! Passionate about doing the best thing for every client, I wanted to extend the types of products I could offer, and found broking to be an enthralling way to save people thousands without charging them a cent.
Q
What is one of your most memorable broker experiences? I met one of my first broking clients at a family barbecue. A This friend of my father’s had recently arrived in the country with literally just the shirt on his back. I was disappointed that even as a senior credit manager I was unable to assist him because of his short-term employment and minimal savings. A few months after I left the bank and became a broker, he called me. This time I could access multiple lenders and finally found one that would take him on. He phoned me in tears, he was so proud and grateful for what we had done. It must have been such a huge victory, considering what he had been through. He, his wife and three children now live in that home, and I consider him a close personal friend.
Q
When clients come to you, what are their main concerns? Increasingly, it’s young families who can’t get a look-in in the A market because they’re being massively outbid by investors. Most don’t realise there are other ways to break through this first hurdle that don’t necessarily involve saving tens of thousands of dollars for their first deposit. I sit down and develop a strategy that accesses their own equity or allows them to jointly borrow, which gives their kids a leg-up and secures their own retirement. It’s a win-win!
Q
What are you currently watching? One of my colleagues has me well and truly hooked on Suits. A He thinks of himself as a bit of a Harvey Specter, closing deals with banks and pushing hard on credit assessors. Watching it now, they really don’t have a lot in common. AB
Q
30
www.brokernews.com.au
BOOK YOUR TABLE NOW
Friday 27 October • The Star Sydney www.australianmortgageawards.com.au Event Partner
Award sponsors
Official publications
Organised by
www.brokernews.com.au
31
32
www.brokernews.com.au