AUGUST 2017 ISSUE 14.14
Strapped for cash Credit intermediaries will owe ASIC $1,000 minimum under new framework /06
Closed for broker business Fintech says it can deliver a home loan in about 22 minutes /10
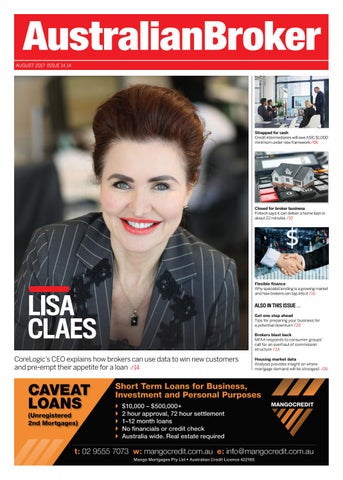
LISA CLAES CoreLogic’s CEO explains how brokers can use data to win new customers and pre-empt their appetite for a loan /14
Flexible finance Why specialist lending is a growing market and how brokers can tap into it /16
ALSO IN THIS ISSUE … Get one step ahead Tips for preparing your business for a potential downturn /20 Brokers blast back MFAA responds to consumer groups’ call for an overhaul of commission structure /24 Housing market data Analysis provides insight on where mortgage demand will be strongest /26
NEWS
IN THIS SECTION
Lenders ING has had success through brokers, says S&P /04
Regulators Credit providers slapped with new tax /06
Technology Fintech offers 22-minute home loan /10
Commercial 18% of Aussies have been turned down for a bank loan /12
Consumers Property market stays buoyant, with slight rise in home loans /08
www.brokernews.com.au AUGUST 2O17 EDITORIAL Editor Otiena Ellwand News Editor Miklos Bolza Production Editor Roslyn Meredith
DATES TO WATCH
Upcoming can’t miss events
ART & PRODUCTION Design Manager Daniel Williams Designer Martin Cosme
2 - 10 AUGUST
15 AUGUST
16 AUGUST
Commercial Broker Forum
MPA Aggregator Roundtable
FAST is hosting four commercial and asset finance conferences to provide brokers with state-related insights that reflect the local market. Invitations will be sent out to FAST brokers
MPA Magazine is hosting a lunchtime aggregators roundtable that brokers can watch online for free. The panel features seven aggregators: Plan, Choice, FAST, Connective, eChoice, Outsource and Specialist. They will discuss commissions, the Sedgwick review and compliance
National Finance Brokers Day Dino Pacella founded this event back in 2015 to celebrate brokers and educate consumers. The goal this year is to raise $50,000 through charity drives for sick children
Production Manager Alicia Chin Traffic Coordinator Freya Demegilio
SALES & MARKETING Sales Manager Simon Kerslake Account Manager Rajan Khatak Marketing and Communications Manager Lisa Narroway
CORPORATE Chief Executive Officer Mike Shipley Chief Operating Officer George Walmsley Managing Director Justin Kennedy Publisher Simon Kerslake Chief Information Officer Colin Chan Human Resources Manager Julia Bookallil
EDITORIAL ENQUIRIES
Otiena Ellwand +61 2 8437 4792 Otiena.Ellwand@keymedia.com.au
SUBSCRIPTION ENQUIRIES
tel: +61 2 8O11 4992 fax: +61 2 9439 4599 subscriptions@keymedia.com.au
17 AUGUST
23 – 25 AUGUST
26 - 27 AUGUST
MFAA Darwin Golf Day
Vodafone National Small Business Summit 2017
Property and Investing Expo
Small business leaders are invited to exchange ideas, shape policy and discuss the current interests and concerns of Australia’s small business owners at this year’s conference at the Event Centre Collins Square in Melbourne. Sessions will cover cybersecurity, banking and financial management, and regulation red tape
Free seminars and over 100 exhibitors will be at the Melbourne Exhibition Centre to provide investors with insights and contacts to help build their portfolio and establish successful strategies
Network with industry colleagues at this annual sell-out event at the Gardens Park Golf Links in Darwin. Register as an individual or as a team and practise your swing – there are prizes to be won
ADVERTISING ENQUIRIES
Simon Kerslake +61 2 8437 4786 simon.kerslake@keymedia.com.au Rajan Khatak +61 2 8437 4772 rajan.khatak@keymedia.com.au Key Media Pty Ltd Regional head office, Level 1O, 1–9 Chandos St, St Leonards, NSW 2065, Australia tel: +61 2 8437 4700 fax: +61 2 9439 4599 www.keymedia.com Offices in Sydney, Auckland, Denver, London, Toronto, Manila, Singapore, Bengaluru
10 OCTOBER – 1 DEC
11 - 13 OCTOBER
24 NOVEMBER
Connective Conference 2017
Credit Law Conference
FBAA National Industry Conference
The 27th annual event in Surfers Paradise brings together banks, credit unions, regulators, associations and market disruptors to discuss the future of credit and lending
This year’s conference on the Gold Coast will equip brokers and other industry members with useful knowledge and practical strategies to help them succeed in an increasingly challenging market
Connective is bringing its conference to Vic, WA, Qld, NSW and SA on various dates from October to December. The conference promises to inspire brokers with new business development strategies, marketing techniques, insights from industry experts, and workshops on health, mindfulness and more
2
www.brokernews.com.au
This magazine is printed on paper produced from 1OO% sustainable forestry, grown and managed specifically for the paper pulp industry Copyright is reserved throughout. No part of this publication can be reproduced in whole or part without the express permission of the editor. Contributions are invited, but copies of work should be kept, as Australian Broker magazine can accept no responsibility for loss. Australian Broker is the most-often read industry publication, according to independent research carried out by the Ehrenberg-Bass Institute for Marketing Science at the University of South Australia in December 2008. The research also found that brokers rate Australian Broker as the best for both news content and feature articles, followed by sister publication MPA. Overall, on all categories, Australian Broker ranks top followed by MPA. The results were based on a sample of 405 respondents who were the subject of telephone interviews.
NEWS
LENDERS Source: Australian Finance Group Mortgage Index
Loans settled
Bank has ceased cash-out on AMP refinanced owner-occupier interest-only loans for an “interim period”. This means affected mortgage holders cannot borrow additional capital for investment purposes. Additionally, the $750,000 cap on the current pricing special for Professional Package loans has been lifted. The variable rate for all new owner-occupier principal and interest Professional Package loans from $250,000 will now be 3.79% per annum. This offer is being put in place for a limited time, the bank said.
“Regulatory bodies have raised concerns about Australia’s household debt-to-income ratio, which has risen significantly over the past decade. … With this in mind, we’re making changes to our home lending credit policy.” Daniel Carde General manager of third party distribution, Homeloans
4
www.brokernews.com.au
30,371
45%
32%
34% $477,207
34%
32%
40% 35% 30% 25% 20%
$300,000
15%
7%
10%
10%
$400,000
$200,000
NON-MAJOR BRINGS IN TEMPORARY CASH-OUT BAN
$486,811
$500,000
29%
$700,000
35%
39%
$800,000
$600,000
28,637
39%
30,101
$900,000
31%
lender Homeloans has announced that it will increase broker commissions and implement tighter credit assessment criteria starting 31 July. All settlements for the lender’s FlexiChoice products (both prime and specialist) will pay an upfront commission of 0.65% (plus GST) and a trail commission of 0.15% (plus GST). Commission was previously 0.60% upfront and 0.10% trail on FlexiChoice Prime, and 0.60% upfront and 0.15% trail on FlexiChoice Specialty. NON-BANK
HOW LOAN FIGURES STACKED UP OVER THE LAST THREE QUARTERS
$484,295
NON-BANK RAISES BROKER COMMISSIONS
$100,000 $0 Average loan size
5%
Q4 2016/17 Investors
Q3 2016/17 First home buyers
Refinancers
S&P LAUDS ING BROKER APPROACH The ratings agency has said that the lender’s attitude to the third party is positioning it well to continue its current forward momentum relationship between ING Australia (trading under ING DIRECT) and its brokers has positioned the bank well in the current economic environment, according to analysts from ratings agency S&P Global. “Despite stiff competition, analysts said ING had experienced continued success in the third party channel. “We believe the bank’s approach to third-party brokers – primarily one premised on simple and consistent product structures and ease-ofengagement – positions the bank well to maintain its momentum within this channel, even though it leaves the bank susceptible to business disruption akin to outsourcing risk,” said Michael Puli, associate director of financial institutions ratings THE
10%
and co-author of the note. In the past, this reliance on the third party has played to the lender’s strengths. Whether this continues in the future will depend on the degree to which borrowers want to use mortgage brokers instead of approaching ING directly through its digital platforms, Puli said. “Where we do see brokers as a part of ING Australia’s ability to manage at the moment is the speed of their systems, their consistency, and the ease of interaction. Also brokers have offered ING a degree of diversification across the country which is supportive of their creditworthiness.” ING DIRECT has been better at leveraging the broker distribution network than some of its peers and
Q4 2015/16
0%
Upgraders
new market players, such as the mutuals, despite recent regulatory changes, Puli added. One risk to ING has to do with commission and broker incentives, Puli said. “A company with a branch network has complete responsibility over their bank staff. However, ING Direct is reliant on brokers sourcing business, so if there are any instances of unscrupulous brokers – and I think that there would be very few in this instance – then that may impact their business model.” Plans to move into non-mortgage lending would also diversify ING’s revenues and solidify its business profile over the next few years. Analysts affirmed the bank’s current A-issuer rating, saying the outlook on the long-term rating remains stable. Growth at ING Bank puts it on the same level as Suncorp, Bendigo and Adelaide Bank, and Bank of Queensland, with a cost-to-income ratio of around 38% – one of the lowest in the Australian banking sector.
NEWS
R E G U L AT O R S APRA CAPS UNDERMINING COMPETITION, SAYS COBA decisions by regulators are having adverse effects on competition within the banking sector, says Mark Degotardi, CEO of the Customer Owned Banking Association (COBA). He told the Productivity Commission Inquiry into Competition in the Financial System that APRA’s macroprudential crackdown on investment lending is creating an uneven playing field. “APRA’s 10% cap on investor lending growth entrenched the major banks’ share of this market,” he said. POOR
RATE RISES NOT NECESSARILY ALL BAD with mortgage stress and rising debt levels in the spotlight, potential cash rate rises by the RBA may not result in catastrophe, according to analysts from the Grattan Institute. “The risks of a rate rise are there but they’re probably not as much as they seem at first glance. Whatever happens to interest rates, higher rates may be a sign the economy is improving,” said associate Trent Wiltshire. An upward rate movement will not happen in the absence of outside factors, he said. EVEN
CREDIT PROVIDERS WILL OWE ASIC $2,000 MINIMUM ASIC has outlined how much credit providers will be required to pay under its new cost recovery framework cost recovery framework for ASIC has been finalised, with details revealing that the minimum levy for all credit providers will be set at $2,000. A graduated charge will be applied per $10,000 of credit provided, other than under a small-amount contract, greater than $100m. For credit intermediaries, a $1,000 minimum levy will be put in place. Additionally, a graduated levy will be charged based on the number of authorised representatives the intermediary had as of 30 June. The precise figures for the graduated charges will be based on ASIC’s 2017/18 budget by subsector, which will be published in October. The framework is outlined in the ASIC Cost Recovery Arrangements: THE
6
www.brokernews.com.au
2017–18 report and includes a method for how the levy will be calculated for various groups, including credit providers and intermediaries. The first invoices will be issued in January 2019 and will recover costs for regulatory services provided in the previous 2017/18 financial year. These invoices will be based on the number of regulated entities in a certain sector, as well as information gathered through ASIC’s new online portal. “We are pleased to be able to confirm the framework to help industry prepare for this new regime and thank industry members for their contribution,” ASIC chairman Greg Medcraft said. “ASIC will continue to support
industry to comply with their obligations as they become due. Further details will be provided in a Cost Recovery Implementation Statement later this year.” The methodology for credit providers has not changed from the initial measures proposed in November last year. The ASIC Supervisory Cost Recovery Levy Act 2017 was passed on 15 June and came into effect on 1 July, imposing an additional annual levy on entities regulated under ASIC. The government said the purpose of the bill was to “ensure that the costs of the regulatory activities undertaken by ASIC are borne by those creating the need for regulation, rather than Australian taxpayers”, and to improve ASIC’s transparency and accountability to the industry. Affected entities include those providing credit services and financial services, as well as companies registered under the Corporations Act.
“APRA’s 10% cap on investor lending growth entrenched the major banks’ share of this market and undermined competition.” Mark Degotardi CEO, Customer Owned Banking Association
NEWS
CONSUMERS CHINA TO SPEND $104BN ON PROPERTY THIS YEAR real estate investment from Chinese nationals is expected to hit $104.5bn this year, according to a new report from property portal Juwai.com. These figures are lower than the record highs of 2016 when China poured $133.7bn into property across the world. Australia received the second-largest share of this outflowing capital, Juwai’s Chinese Global Property Investment Report found. Chinese buyers were approved to purchase $23.8bn of property in 2015/16 and $18.4bn in 2014/15. GLOBAL
BROKERAGE TO DONATE 20% OF TRAIL brokerage Sherwood Finance has started donating 20% of its trailing commission to Mission Australia to aid disadvantaged children and families, people with mental illnesses and disabilities, and people seeking safe and affordable housing. “It provides greater value to clients who are potentially buying or refinancing as well as to the disadvantaged. I come from quite humble beginnings so I feel like I’m in touch with this way of being,” said managing director Daniel Donnelly. SYDNEY-BASED
“This bounce-back in home loan demand is hardly surprising. The fact is, the property market remains relatively buoyant, with historically low interest rates keeping the cost of borrowing low, and heat in the market.” John Flavell CEO, Mortgage Choice
NATIONAL HOME LOAN DEMAND ON THE REBOUND The latest figures from the ABS show owner-occupier lending is on the rise while investor lending tracks downwards for home loans has bounced back in the month of May, according to the latest figures from the ABS. National housing finance data released on 11 July found that 54,061 loans were approved in May, a 1% increase on the previous month. “This bounce-back in home loan demand is a positive sign for the property market and the broader economy,” Mortgage Choice CEO John Flavell said. “That said, this bounce-back in home loan demand is hardly surprising. The fact is, the property market remains relatively buoyant, with historically low interest rates keeping the cost of borrowing low, and heat in the market.” DEMAND
The value of all dwelling commitments rose by 1.3% to just over $33bn during the month of May. This included a 2.9% increase in the value of home loan approvals for owner-occupied housing and a 1.4% decrease for the value of investment loans. “Of course, I am not at all surprised by this. Over the past few months, Australia’s banks have been significantly tweaking their policy and pricing in relation to investment lending,” Flavell said. “In particular, we have seen some significant changes in the area of interest-only loans. Some lenders have raised their pricing, while others have adjusted their policy.” This has seen some property investors postpone their plans
for purchasing a home until a later date, he said. Tim Reardon, principal economist at the Housing Industry Association, said investment lending had decreased for the second month in a row – an issue that should continue to be monitored, he added. “This could be as a result of the APRA restrictions that were announced at the end of March impacting the confidence of investors,” he said. “This could also be due to the expectation that home price growth is likely to slow further.” Reardon also highlighted the influx of first home buyers into the housing market in May. “We have seen significant growth in lending to first home buyers in many parts of the country during the month, which has coincided with an increase in lending for new homes. This is likely to be due to the ongoing uptake of apartments that have come onto the market this year.”
OWNER-OCCUPIED HOUSING ROSE IN MAY 2017, WHILE INVESTMENT HOUSING SHRUNK Source: ABS, Housing Finance, May 2017
Trend estimates May 2017 $35,000
Seasonally adjusted estimates
Apr 2017 to May 2017: % change
May 2017
Apr 2017 to May 2017: % change
1.3%
-0.3%
$m
$30,000 $25,000 $20,000
$32,848
0.4%
$20,423
$15,000
$33,032
$20,717
-1.5% $12,425
$10,000
Value of dwelling commitments Total dwellings
8
www.brokernews.com.au
Owner–occupied housing
2.9%
-1.4% $12,315
Value of dwelling commitments Investment housing – fixed loans
NEWS
TECHNOLOGY
FRANCHISE FOSTERS ONLINE BROKER COMMUNITY Home Loans has launched Aussie Chatter, a ‘one stop shop’ for support and information for the franchise’s 1,000 brokers. “A key aspect for Aussie Chatter is that online support is available 24/7, which matches the variability of hours brokers operate,” said Richard Burns, general manager of customer experience and technology. “Our brokers can access knowledge articles through a Google-like search – of which there have been over 27,000 searches since going live – review lender updates, view news alerts and also raise enquiries with support in head office.” AUSSIE
FINTECH LAUNCHES WITH 22-MINUTE HOME LOAN The industry newcomer is pushing the idea of an ‘instant’ home loan approval process without the need for a mortgage broker fintech Tic:Toc has launched, with an offer of ‘instant home loans’ through a digital real-time loan processing system that connects customers directly to the lender. Emerging digital lending capabilities inspired CEO Anthony Baum in 2015 to formulate and create an instant loan process. Last year, the company partnered with Bendigo and Adelaide Bank, and officially launched this July. The firm spent the last two years validating the idea and developing the platform. “What we saw was an opportunity for a customer to complete a home loan application and be fully approved; and in the case of a refinance, even receive their full mortgage documentation in the same time frame it would take
them to complete an application normally,” he said. The decision-making and validation processes work in real time, with document generation for refinancing done in “close to real time”, he said. It takes approximately 22 minutes to complete the application online. The application processing is instant and will generate a fully approved home loan, Baum said. The system ensures Tic:Toc remains compliant with legislative requirements, such as Know Your Client and responsible lending, while following the underwriting parameters agreed to with Bendigo and Adelaide Bank, Baum said. Tic:Toc’s platform uses property eligibility algorithms, serviceability requirements, responsible lending
NEW
processes and digital ID and financial validation. “At the end of that process, you will get a response whether you’ve been approved, declined or referred. If the customer is approved and it’s a refinance, we will send through the documentation in as little as a few minutes. Sometimes it can take a bit longer depending on which state the client lives in.” If the customer is referred, there are factors about the loan that will need to be reviewed. This will take around 15 minutes, after which the application will get either approved or declined. The service is targeted at eligible customers: primarily borrowers in major cities and regional centres with over 20% equity in the property at launch. “For those customers, it’s all direct. There is no broker access. Customers have a choice – they go to a broker, they can go to a bank branch, or they can get their home loan approved or refinanced online in 22 minutes.”
VV MORTGAGE RISK LEVELS BY HOUSEHOLD INCOME Source: Roy Morgan Research
100% 90%
1 - Based on amount borrowed
85.3%
Mortgage risk level
80% 70% 60%
‘At risk’1 65.0%
50% 40% 24.4%
30% 20% 10% 0%
32.9% 18.3%
‘Extremely at risk’2
17.5%
19.3% 10.9%
Under $60k
$60k–$69k
$70k–$79k
$80k–$99k
Household income
10
2 - Based on amount owing
Base: Has an owner-occupied dwelling with mortgage, 12 months to April 2017
www.brokernews.com.au
0.8% 1.4% $100k–$149k
0.6% 0.7% $150k+
NON-MAJOR REVAMPS LOAN ORIGINATION SYSTEM Bank has unveiled a new loan origination system with benefits for brokers, including a simpler process and faster turnaround times. The LendFast platform is being rolled out gradually across the bank’s broker network. “It goes from end to end so the broker data and documents, once uploaded, go through the system with relatively low touch. The whole idea is to remove variability and cost and deliver a much faster turnaround time,” said Damian Percy, general manager of third party banking at Adelaide Bank. ADELAIDE
NEWS
COMMERCIAL
EQUITY FIRM IN PEPPER TAKEOVER BID Group has released confirmation of an ‘indicative non-binding proposal’ from private equity firm KKR Credit Advisors (KCA), bidding $650m for shares in the company. The announcement is in relation to a potential control transaction that would offer shareholders $3.60 per share and directors a dividend of up to $0.03 per share. The negotiations between Pepper and KCA are not yet complete, with entry into a binding transaction reliant on a number of factors, including the completion of due diligence and agreement by the two parties. PEPPER
UNDERSERVICED SMES LOCKED OUT OF FINANCE Structural work changes have led to more self-employed borrowers, a trend that presents new opportunities for brokers of consumers are potentially missing out on solid financial advice, falling through the cracks in a system that has turned away from self-employed borrowers. New research by Pepper Money has found that 3.6 million Australians, or 18%, have been turned down for a loan by a financial institution. Of those who were turned down, 54% were unaware that there were alternative options available. Pepper’s research also found that 26% of Australians turned down for a loan were refused because they were self-employed or worked part-time. These numbers suggest that a growing proportion of Australians are being locked out of the financial MILLIONS
REGIONAL BROKERAGE CROSSES STATE LINES brokerage Robinson Sewell Partners is expanding its national footprint by opening its first office in Clare, South Australia, which will be headed by broker Deb Purvis. This is the first step for Robinson Sewell in branching out across the country. “We’ve got an ambition to create a national footprint across all geographic codes in regional and rural Australia. Deb Purvis is a great start to opening up the South Australian footprint,” said director Ian Robinson. REGIONAL
12
www.brokernews.com.au
system and the support they require to meet their goals. “The gig economy and the rise in flexible work are leading to a growing number of Australians who fall outside the bank’s lending criteria,” said Mario Rehayem, Pepper Money’s managing director of Australian mortgages and personal loans. There is a need to educate these consumers about the alternative options available, he added. “The big banks have set criteria for loan applications that not everyone conforms to. We don’t expect this to change, though it means a significant number of Australians are missing out. There is an opportunity for brokers to help consumers understand their options and potentially access the real
financial support they need.” Through its partnership with the broker community, Pepper Money has allowed tens of thousands of Australians to access funds. “Our aim is to continue to build this partnership, raising awareness of alternative finance options while working with brokers to assist borrowers who are currently being turned down by the banks.” Pepper also seeks to help brokers cater to their clients in this ever-changing environment, Rehayem said. “We want to educate brokers about the full suite of options available to their clients – a no from a bank is not the last resort. There are a number of viable alternatives.” Over 90% of Pepper Money’s home loan applications are conditionally approved because the specialist lender takes a different approach to assessing borrowers. “We look at the whole picture of an individual’s circumstances when making a loan assessment to understand their real life.”
AUSSIES WITH UNCONVENTIONAL JOBS FACE HURDLES WITH BANKS Source: Pepper Money
18%
54%
10%
26%
of Aussies have been turned down for a loan by a financial institution
of Aussies don’t know where to go when they’re turned down for a loan
or 1 in 10 have been rejected by one of the big four banks
of Aussies turned down are self-employed or work part-time
WHITE LABEL UPDATE
COMMERCIAL FINANCE DECREASED SLIGHTLY FROM APRIL TO MAY 2017 Source: ABS
$m 50,000 Trend Seasonally adjusted
46,250
s
THE EVOLUTION OF WHITE LABEL LENDING: MORE THAN A SIMPLE SOLUTION The white label mortgage industry is growing rapidly as brokers realise the benefits to their business and clients. As the popularity of white label increases, we are seeing a shift in how these loans are used. Brokers are recognising that white labelling is more than just a simple, cost-effective solution; it is also a loan type that’s versatile and can be tailored to suit their customers’ financial needs.
42,500
38,750
35,000 May 2016
Aug 2016
Nov 2016
Feb 2017
May 2017
COMMERCIAL LENDER DOUBLES YEARLY LOAN VOLUME commercial lender Private Mortgages Australia (PMA) has celebrated three years in business by doubling its volume of newly settled loans over the past financial year. PMA managing director Tony Barbone said the firm’s success was a result of an increase in small-to-medium businesses needing alternatives to the banks. “While serviceability is the greatest concern for banks, we are primarily focused on securing the loan using property equity, which allows us to be a lot more flexible.” While Barbone was reluctant to mention the size of PMA’s loan book, it had increased by 151% in its second year and then a further 115% in its third, most recent year, he said. SPECIALIST
Greater understanding is leading to more complex use As brokers become more familiar with white labelling, we are seeing it used for larger and more complex transactions. Traditionally considered a great solution for ‘mum and dad’ borrowers, this evolving usage of white label shows that it is a fit-for-purpose product. For example, brokers with high net worth clients are embracing white label products for loan sizes of $1m plus. Brokers are also taking up white label products for customers who have complex loan structures, whether that involves incorporating companies, family trusts or having multiple loan splits. A greater range of customers are showing interest in white label, as they increasingly realise it can save them money over the life of their loan. Customers only have to pay one low annual fee while still having the essential features of a loan. Ultimately, they get the features they want, without paying for the unnecessary bells and whistles that can increase the price. White labelling can also make the home loan process hassle-free for the customer as they can leave their current banking arrangements where they are. It is also helpful for self-employed people who want to have their home loan separate from the rest of their business banking arrangements. In addition, customers with a variable rate home loan will have access to a redraw facility to help manage their cash flow. The right support systems to empower brokers Backing the evolution of white label is Advantedge’s strong support system, which ensures brokers conducting more
Brett Halliwell, general manager of Advantedge
sophisticated deals can rely on their lending team for direct assistance. The Advantedge scenarios team allows brokers to present a scenario and gain advice from our expert credit assessors on what is required for submission. For example, with complex deals the broker can ask how the lending team will treat certain aspects of income if complex structures are involved. With this support, it allows both brokers and customers to submit with confidence and to ensure a faster turnaround time. For particularly high-value loans, brokers can also gain access to the Personalised Lending Team. These are Advantedge’s most experienced credit assessors with the highest Delegated Credit Authority. Many have experience in commercial and business banking and understand complex business and trust structures. This team is available to assess all complex and high-value loans and can assist brokers to set up the loan according to the customer’s needs. The Customer Care team is also integral to driving the usage of white label. Brokers can contact the team directly to request customer loan details on their behalf, empowering brokers to offer excellent customer service. As brokers continue to use white label products and understand their benefits, the use of these products is certainly more than just a simple lending solution.
FE AT URES
COVER STORY
MAKE THE DATA WORK FOR YOU CoreLogic’s CEO, Lisa Claes, explains how brokers can harness the vast amount of data available at their fingertips to find new clients and become existing clients’ go-to experts on both the loan and the home
CAREER TIMELINE
Feb 2017 - present
CEO, CoreLogic International
Sept 2016 - Feb 2017
Managing director, CoreLogic Australia and New Zealand
2015 - present
Director and chair, LIXI
2013 - July 2017 Director, Loreto
Apr 2011 – 2016
Executive director, ING DIRECT
Jan 2009 – Apr 2011
Executive director, mortgages, ING DIRECT
July 2005 – Sept 2008
Executive director, sales and operations, ING DIRECT Australia
14
www.brokernews.com.au
thing most brokers probably don’t know about Lisa Claes is that when she’s not analysing vast amounts of data and putting her laser-sharp barrister’s brain to work as the CEO of CoreLogic, she’s letting her creativity flourish as an accomplished dress designer. Her clothing design is just a hobby, but Claes is convinced it improves her strategic thinking because it forces both sides of her brain to be equally active, energised and creative at work and during her leisure time. Claes can see and understand how things work and fit together in ways that most people can’t, allowing her to make numbers and data coherent and relevant to customers. She’s used to looking at raw materials – whether that’s silk or statistics – and visualising how it will all come together to form something of value, an advantage in both business and design. “Your role as the CEO is harvesting the talent and the depth in the organisation and bringing it together in a way that’s aligned and cohesive,” she says. “And that’s very creative, that’s fun.” Not everyone has what it takes to run a large data analytics company and design clothes, houses and furniture on the side for fun, as Claes does, but one lesson that can be taken away from her style of thinking and operating is how to become a more well-rounded individual by using all of the many skills, talents and tools at one’s disposal. ONE
How to be different in a dynamic market To become a well-rounded broker, one must do more than just provide
a customer with a loan. Since brokers are often one of the first professionals a customer sees as they start their home ownership journey, they are in an ideal position to prove themselves as critical advisers who can support their customers through the entire process. One of the ways brokers can achieve this is by leveraging and understanding the property market data at their fingertips and providing that knowledge and expertise as a ‘value add’ to their customers.
referrers. The broker can then focus on collecting data insights that will cater to those specific markets and provide that information to clients proactively. Another one of Claes’s suggestions is to ask a potential client four or five questions before they arrive for a meeting so brokers can prepare insights on the area or property they’re looking at that might impress them and give them confidence that they’re choosing the right partner. “I’m not suggesting that brokers become pseudo real estate agents at all. But I think that there is an implicit permission from potential borrowers that you should have knowledge about the property or the area which they’re about to buy into because it instills confidence, particularly if you can tell them something that is not publicly available,” Claes says. Understanding the data is not rocket science, she adds, but it does
“It’s about tailoring the data to target the customers you want and to tailor the data so you have a high retention and referral rate” “The way to ensure that you secure that relationship early, and you continue it so it endures, is to become the expert to your potential borrower, not only on the loan but also on the home,” Claes says. CoreLogic has a variety of tools that can unlock a world of information for brokers and make them whatever kinds of experts they want to be, whether that means specialising in a specific property, street, postcode or city. One method brokers can try is to apply crude segmentation to their customer base according to such things as where the majority are located, and whether they are high-value clients or healthy
take time to figure out, and brokers should decide what their strategy is in terms of how they’ll use and get the most out of the data for their customers. Some aggregators have subscriptions that they provide to their broker networks. In total, there are between 2,000 and 3,000 broker subscriptions, Claes says, but usage varies widely. CoreLogic offers training for groups of 20 people or more so they can learn how to get the most out of the data. “We want people to get their money’s worth because we are very proud of our products, particularly RP Data Professional Property Monitor; they’re flagship products.
The days when brokers called a customer on the anniversary of their settlement date is Broker 101. While that tradition isn’t dead, to stand out today brokers need to use whatever tools are available to them to reinforce their role as that trusted local expert in regard to the biggest asset in their customer’s wealth basket, Claes says.
Lisa Claes, CEO, CoreLogic
There’s a lot of investment from this organisation that goes into making sure they’re cutting-edge in terms of data quality, breadth and depth of functionality and timeliness,” she says. The property monitor tool can be integrated into an existing CRM platform and overlaid on the broker’s customer database to show when a home lists, what the asking price is, what it is sold for and when, what properties are under development in the area, and more. Brokers can use it to see when a customer lists their property so they can approach them about refinance. It can also be set up to provide digital alerts straight to the
broker’s phone or computer. CoreLogic’s first propensity product, which predicts when a home is likely to list before it does, was launched in February and has exceeded its target by 300%, Claes says. It was sold into the real estate market, but some smaller brokerage groups are now piloting it. The next propensity product, which will launch in Q3, will look at migration patterns between suburbs. The ‘propensity to list’ product could help brokers target their marketing at potential borrowers and give them a heads-up as to when to approach existing customers. “When there is transactional movement in an environment,
brokers have to get to the transactional activity quickly, and be proactive rather than reactive. … I would be building my business in that area, trying to pre-empt the appetite for the loan,” Claes says. All of these tools can be easily stratified according to the broker’s time, energy and appetite, she adds. “It’s about tailoring the data to target the customers you want and to tailor the data so you have a high retention and referral rate. I think in all businesses the ability to navigate data and get insights from data – we call it analytics – is becoming the holy grail of businesses and … brokers are not immune from that at all,” she says.
Reading between the numbers Claes’s reading of the data tells her that while the housing market has hit the peak of the mountain, there will be a slow run down the other side, mimicking past cycles, rather than an eruption. “You’ve seen an absolute pelting of interest rate rises from the banks across their investment books, and that’s clearly been in response to the prudential imposition that has required banks to hold more capital, so they’re raising their rates to maintain their return on equity in response,” she says. These speed bumps will dampen the investor segment. There will be some moderation in capital growth in Victoria and NSW, but investors will probably deflect to other states where the entry point isn’t so steep, such as Brisbane, Claes says. The alternatives are limited because other asset classes, such as bonds with their low rate of returns and volatile equities, are still not as attractive. What these hurdles will spark is a lot of refinancing, which is good for brokers because it’s almost impossible for a customer to be able to navigate the high level of variegation in the segment alone, whether it’s the rates that keep changing and increasing or the loan and credit risk conditions, she says. “It’s a minefield to navigate and I think this is where brokers can really assist, because what all of this noise and clutter will do, it will trigger transaction activity, switching, refinance – and in investors’ deflecting journey I think they’re going to need an adviser.” AB www.brokernews.com.au
15
FE AT URES
BUSINESS PROFILE
SPECIALIST LENDERS ON MYTHS, TECHNOLOGY AND THE FUTURE OF BROKING
Australian Broker spoke to five specialist lenders about why they’re perfectly positioned to help brokers cater to customers who require flexible finance solutions for whatever life event they’re going through
AARON MILBURN PEPPER MONEY
Q Steve is a 26-year-old truck driver who 12 months ago struck out on his own to set up a business. He has since secured several contracts with various well-known haulage companies and earns, on average, about $2,200 a week. He has a lease on his truck for $25,000. In the market for his first home, he had already started saving and also recently came into an inheritance. With his savings and the inheritance totalling $65,000, he felt he had sufficient funds to purchase a house. He wanted to enter the property market as soon as possible, so he approached a mortgage broker. Steve told his broker that, in addition to his savings, he had banked his earnings into his business account and had lodged quarterly business activity statements (BAS) with help from his accountant. But when it came time to apply for a loan, the banks wouldn’t lend to him. Instead, Steve’s broker was able to offer him a Pepper Money 16
www.brokernews.com.au
Specialist Alt Doc product. Steve was able to choose from three different methods of verifying his income, including six months of business bank statements or six months of BAS, or Steve’s accountant could complete Pepper Money’s Accountant’s Letter. At Pepper Money, we have used technology to make the process of determining whether someone is eligible for a specialist loan via the Pepper Product Selector incredibly easy. Through a couple of simple questions and your customer’s Access Seeker score, the Pepper Product Selector helps a broker match their customer to the most appropriate Pepper Money home loan product. It takes the hard work out of identifying the right product, and you have a genuine solution in the form of an indicative offer for your client in less than two minutes. Right now, brokers are having a hard time keeping up with the ever-changing credit policies of traditional lenders and the
Aaron Milburn, director of sales and distribution, Pepper Money
regulatory environment. As a result of these changes, the number of people requiring specialist lending is only growing, and it continues to grow year after year. Alternatives like Pepper Money exist to help those consumers who fall out of the increasingly restricted criteria set by the banks.
It’s vital that brokers familiarise themselves with the products of other lenders. It only takes 20 minutes a week, and it could make all the difference in the world to your customer’s personal situation. Besides, if you as a broker aren’t offering an alternative solution to your customer, the broker down the road will.
CORY BANNISTER LA TROBE FINANCIAL
Q Specialist lenders cater for niches within the mortgage market where a sector of consumers are left underserved by gaps in the market. This could be because of a number of issues and reasons; for example, the major lenders withdrawing products and changing policies, and new regulatory requirements, just to name a few, across different asset and borrower types. Some issues may even be unrelated to credit issues. An example may include SMSF loans – a ‘super-prime’ borrower often requiring a specialist lender to partner with. As such, borrowers are looking for a broker who has adopted a more holistic proposition. This has already started to happen with the recent disruption in financial services, particularly finance broking, where many ‘mortgage’ brokers became ‘finance’ brokers. This pattern will continue and is likely to result in a ‘diversify or die’ outcome for many. It’s not too dissimilar to the impact supermarkets had on high street butchers and grocers as consumers looked for the convenience of a one-stop shop. There have been many recent examples that highlight the importance of diversification, where broking businesses were set up specifically to write one particular product. We saw these businesses grow exponentially, and watched as these brokers rose through the ranks, winning awards for volume and growth in the industry. Unfortunately, this didn’t last long. For many of these businesses, when lender supply lines were cut unexpectedly, it
caused the brokers’ own supply capabilities to evaporate along with their business plans. Case studies of markets that have changed significantly over the past 12 months and may disrupt business models include SMSF loans, non-resident loans, development finance, commercial loans, investment loans and interest-only lending. We strongly believe that diversification is one of the most important fundamentals for any investment, and arguably, a finance broking business is just that, an investment. Therefore a strategy to diversify should be seriously considered in order to safeguard a broker’s business. Specialist lenders can make diversification easy. Other lenders may require finance brokers to sit a test or hold off on lodging applications until they can be formally accredited (when convenient for the lender in question); however, at La Trobe Financial accredited brokers are able to write all of our products without delay. We use the same forms and documents and follow the same approval process, ensuring that brokers who are not so familiar with a particular product can easily adapt, hence there is no need for any additional accreditation procedures. We are making it easier for brokers to diversify by delivering an improved broker experience through technology, with our focus specifically on two areas: 1) improving our online submission process by rolling out a new online application platform to allow quicker approvals; 2) improving
Cory Bannister, vice-president/chief lending officer, La Trobe Financial
our back-end loan closing software to ensure a clear path to settlement by inviting brokers, borrowers and their agents to enter a virtual settlement room where they can communicate freely with us and our solicitors in a closed environment, removing layers of communication, which ultimately means faster settlements. In addition, we have introduced an electronic method of identity verification which covers VOI, AML and KYC electronically through a broker’s smartphone.
In the next few months we will be implementing our loan and mortgage documents electronically via DocuSign. It is important to note that, whilst digital plays an important part in delivering a better user experience, we remain firm in our view that human interaction is a critical component of specialist lending, where there are no ‘vanilla’ transactions and listening to our brokers with an open and intuitive mind is required to find a suitable solution. www.brokernews.com.au
17
FE AT URES
DANIEL CARDE HOMELOANS
Q The Homeloans Group, which includes RESIMAC, has a long history of specialist lending, and we see brokers as playing a vital role in our distribution and being key to our success. Borrowers that fit into the ‘specialist’ category are faced with a number of challenges: traditional lenders don’t cater to this market, and so borrowers are then confronted with the vast range of solutions offered by specialist lenders that aren’t ‘one size fits all’. This is where the expertise of a broker comes in. The majority of specialist lending applications need a solution first and foremost, with interest rate and features a consideration after that solution is identified. And so the
different scenarios that present under ‘specialist’ mean it can be difficult for a borrower to navigate the market themselves. There is also a proportion of loans written by specialist lenders that are the result of a knockback from a more traditional lender, where the borrower approached the lender directly in the first place. A borrower is more likely to turn to a broker for help and advice following this knockback than to keep trying lender after lender. Brokers provide the best opportunity for specialist lenders. When you consider that brokers originate over 50% of all home loans written in Australia, it is far easier and much more cost-effective to educate the broker market on what a specialist
Daniel Carde, general manager third party distribution, Homeloans
lender can provide than to try to educate the general public. In addition, since 2015 there have been a number of market changes resulting from regulatory influences, with each lender responding to these changes differently. Brokers are therefore more relevant today than ever before, as they help Australian borrowers navigate these changes. The reality is brokers are key to the
future of lending in general, including specialist lending. Specialist lending creates a solid opportunity for brokers, and brokers provide an essential distribution channel for specialist lenders. The relationship between the two is therefore mutually beneficial, and brokers should harness the opportunity to service this sizeable segment of the borrower market.
ROYDEN D’VAZ BLUESTONE MORTGAGES
Q Myth 1: Default is a dirty word What people don’t realise is how quickly a default can happen. In many cases, the respondent is unaware of it until they go to apply for a mortgage. Geoff Wood, principal of My First Property Finance, recently had a Class A client who couldn’t obtain finance through her bank because she had defaulted on a phone bill from her previous property and was categorised as credit-impaired. Wood was able to sort it out with a Bluestone Mortgages loan. “In comparison to the mainstream lenders, we like working with Bluestone as they’re not phased by a default and gear their products to 18
www.brokernews.com.au
support people in this common situation,” Wood said. At the other end of the spectrum, there are customers who have had default creep up and get out of hand quickly. “There’s a lot of need for specialist lending solutions and there are a lot people out there that could benefit from this type of funding. I’m now actively focusing on specialist lending as I see an increasing need for this service,” Wood said. Myth 2: Non-conforming products are for unskilled workers Over 25% of all borrowers fit comfortably into the non-conforming
Royden D’Vaz, national head of sales and marketing, Bluestone Mortgages
space. This group comprises of any person, company or trust with a genuine requirement beyond the scope of traditional lenders, and is certainly not limited to unskilled applicants, or those with severe credit impairment. The sector was traditionally associated with blue-collar trades experiencing financial difficulty, but it’s now far
broader – which coincides with the exponential and continual growth of SMEs/the self-employed sector. The borrower is as likely to be a graphic designer as a project manager, accountant or plumber. Similarly, the industry spans each of the socio-economic groups and can help people of all income levels.
JOHN MOHNACHEFF LIBERTY
John Mohnacheff, group sales manager, Liberty
Q Technology is playing an increasingly crucial role in the way brokers operate. We live in a world that is rapidly changing and most of this change is driven by technology. In fact, we’ve become dependent upon these innovations to keep us informed and up to date with almost every aspect of our lives. The world of finance is no different, and that’s why we’ve continually invested heavily in technology over the last 20 years. At Liberty we’ve created, and continue to invest in, our proprietary technology, which means brokers can submit specialty loans as well as track the loan’s progress through our super-quick approval process. It also means we provide consistent decisions each time we receive an application, which is important for brokers and their customers. We’re now at a really exciting inflection point for our technology offering – and in the coming weeks brokers will learn more about the new tools we’ve built to save time and make their jobs a little easier. APRA’s heightened regulatory scrutiny has definitely changed the finance landscape and as a result brokers are adapting to remain competitive. Diversifying into new services is proving to be an effective way of helping
brokers grow their businesses. Liberty is still the only lender that can provide solutions for brokers right across the lending spectrum, including residential, motor, commercial, SMSF – for both prime and specialty loans. It’s for this reason that Liberty is often the first and last port of call for many brokers looking to grow new revenue streams. The key to diversifying all comes down to knowing solutions exist so you can make the right recommendation when customers ask. When the lender has a strong BDM support team, like Liberty, it’s easy to find those solutions quickly. At the end of the day, specialty lending is not something to be afraid of. It’s a home, car or commercial loan – the only thing that is different are the unique circumstances of the applicant requiring the specialist solution. Like any other deal, the broker is there to guide the customer towards a solution that suits their individual needs. One of the benefits of providing a tailored solution is the appreciation brokers receive from their customers. A broker who finds a way forward for a highly stressed client is the broker who earns customer loyalty and repeat business. AB www.brokernews.com.au
19
FE AT URES
OPINION
BECOME A ‘SMART OPERATOR’ Nick Young, managing director of trail book buyer Trail Homes, advises brokers on how to get ahead of their competitors by being strategic and proactive so they’re prepared in the event of a downturn required, so you have an additional source of revenue to residential lending. Asset finance, commercial loans and specialist lending are good options to investigate. Invest in professional contacts now, understand the respective processes and communicate to your clients that you’re expanding into
state of the housing market remains a hot topic, with general industry sentiment expecting that we’re entering (or are in) a natural slowdown, or ‘selfrighting of the ship’. While less lending and fewer new loans will inevitably increase competition, a slowdown typically extends the average life of a loan from five to seven years. The upside of this is that a broker’s trail book becomes more stable. THE
Use the downturn to your advantage Smart operators have the opportunity to rise in the time of a downturn, particularly against less savvy rivals. According to the Harvard Business Review, the first step is to assess your exposure – especially when the economic climate is becoming increasingly precarious – so you can identify where your company’s vulnerabilities lie and deal with them before matters become too unstable. The HBR recommends considering how a modest downturn, a more severe recession, and a full-blown GFC might impact on your business and your profits. Be sure to monitor industry analysis, rather than being guided by speculation. Each scenario will affect your business differently, so you need to come up with a strategy that will allow you to manage the unique challenges each one presents. Here are some tips for strengthening your business now so you’re prepared and ahead of the game for whatever might unfold: 1. Actively prioritise your clients: At the cusp of a softening market, it’s absolutely critical to prioritise communications with your clients before the market slows down. Get close to your clients and work harder to maintain the relationships you have. Schedule regular contact and reach out to your network with meaningful communications in the form of e-newsletters, meetings and reviews. 2. Diversify: Work out what complementary niche you’re interested in, or that you anticipate might be 20
www.brokernews.com.au
out how to minimise your weaknesses and capitalise on your strengths. In real terms, look at what you’re good at and what’s a natural extension of your abilities. Take this into account when considering your marketing activities and areas of diversification. 5. Aggressively manage working capital: Monitor and maximise your cash position. Take a hard look at all your costs, processes and infrastructure. Well-oiled processes and maximum efficiencies are crucial prior to a downturn. 6. Optimise your financial structure: Calculate your expected cash flow requirements, and work out contingency plans that coincide with your forecasts. In the meantime, actively reduce debt and liabilities, and consider funding alternatives such as lines of credit, business or personal loans as Plan B to coincide with a less desirable forecast. Another option is to sell a portion of your trail book for an immediate ‘self-funded’ cash injection without bundling in your clients in the transaction, if required.
Marketing is often the first element to be cut when times are tough. But beware: this strategy is a short-term gain that not only affects your credibility but reduces sales
Nick Young Managing director, Trail Homes Nick Young is a results-driven specialist who has more than 20 years of experience in the mortgage broking industry and now heads Trail Homes, Australia’s longestserving trail book purchaser.
different spaces. This will help create immediate and future opportunities, and will make you appear proactive versus reactive, which in turn builds trust and encourages engagement. 3. Maintain consistent messaging and marketing: Marketing is often the first element to be cut when times are tough. But beware: this strategy is a short-term gain that not only affects your credibility but reduces sales. If clients can’t find you, they won’t call you. To the contrary, we suggest building a reserve of funds to amp up high-return activities in quieter periods, but do this smartly. Make sure all marketing activities are sales-oriented, with an obvious call to action. Write relevant content, become well versed in social media, and use your marketing dollars to boost your presence with Facebook or LinkedIn ads. If you don’t have the skill set to do this, look at getting professional help where required. 4. Work to your strengths: It’s essential to understand your own strengths and weaknesses relative to your competitors. Think this through honestly and work
7. Rein in planned investments: Now is not the time for major purchases. Postpone spending, shed unproductive assets and focus on your cash flow. 8. Don’t bury your head in the sand or act rashly: It’s not rocket science that it’s not smart to either ignore the state of play or overreact and do something for the sake of action. Instead, complete forecasts for the next two years, and work out your response in advance should your numbers dip and/or reach critical levels. These don’t need to be novels. Keep the game plan short, sweet and realistic. 9. Realise that opportunities come from chaos: The upside of having your ducks in a row is that unexpected opportunities can emerge in times of economic turbulence. A well-considered, pre-emptive and realistic action plan not only buffers the impact of a downturn but also gives you a strategic advantage while your counterparts are scrambling. This may include identifying niches, systems and approaches or anticipating product demand. AB
IN THE NE WS
TECH FEARS UNFOUNDED
While rapid technological change will never completely eliminate the need for brokers, Viktor Desovski, director of mybrokeronline.com.au, says brokers must learn to stay relevant industries, not just the finance industry, are facing disruption and change as technology forces employers and employees to learn new skills and adapt more quickly than previous generations had to do. Consumers’ demands are changing too in light of what technology can offer. These changes are designed to support those who adopt new technologies, and eliminate or isolate those who choose to ignore them, says Viktor Desovski, director of mybrokeronline.com.au. However, Desovski says fears of technology completely removing the broker from the lending equation are unfounded. “Technology is improving the customer experience and is now complementing the finance journey. The digital landscape allows consumers to get more satisfaction in real time about their situation and is a faster way to provide that service.” In Desovski’s experience, consumers want to use technology to research and compile facts, but they still want to speak to someone in person who can verify what they’ve learned. “Removing the broker and connecting lender and borrower directly through technology relies on the assumption that the consumer knows or understands the terminology and complex lending structures they’re dealing with,” he says. “Some people will be fine with that, but others will want a professional to look at their loans and get advice.” Desovski says there are three reasons why brokers will be around for the long term regardless of advances in technology: • Brokers with experience in a range of clients and scenarios can make insights that technology may miss • Brokers can take into consideration information that the client does not know and then educate them • While technology may be able to offer a solution, it may not be the optimal solution for the client MANY
To keep up with technological advancements, Desovski recommends brokers adopt an ‘assisted self-service’ model designed to meet client support needs. This gives clients access to valuable information and updates through real-time, proactive notifications alongside the service, education and advice a skilled broker can provide. “The key in this model is that it relies on the broker-client relationship as a major component of the finance journey,” he says. Additional tools can be used to help the client ‘self-service’ their journey, such as online loan applications and e-signatures. Regardless of how many functions the technology or software offers, however, it’s about how the platform is applied and executed that will determine if consumers want to use it. “It’s improving the customer experience as they use the tools that are relevant to them at that point in time. It’s not about removing the broker; it’s about collaborating through the platform,” Desovski says. Making connections Mybrokeronline.com.au has built software around this assisted self-service model that clients can access through the website itself. It also partners with aggregators and lenders to deliver an end-to-end process. This extends from the front-end tools brokers use to the back-end platforms for aspects like loan processing. “We use the platform to collaborate and interact within this whole journey, from the front end to the broker and then to the back end. That whole journey is seamless to the customer and allows us to scale and offer a frictionless customer experience,” Desovski says. The improved website will let brokers offer better advice and interact with clients in real time while also offering document upload tools and video conferencing facilities. AB www.brokernews.com.au
21
PEOPLE
Have an interesting deal? Had a particularly difficult or interesting deal? Why not share it with us? Email:
Otiena.Ellwand@keymedia.com.au
A BIG DEAL
Daniel O’Brien, director of PFS Financial Services, saved his client thousands of dollars on interest repayments by delivering what the banks couldn’t
THE FACTS
Loan size $1.25m
Loan term 30 years
Client Male in his 50s
22
www.brokernews.com.au
Location Sydney’s Eastern Suburbs
wanted to leave all other non-loan facilities with his current bank, but to take away one of the securities – the client’s personal home. As security, the bank had both the client’s home and his commercial property. There
THE SCENARIO
A new client who was recently referred to me had a $1.25m commercial loan against his commercial property. The client was incurring an interest rate of 6.75% and $60 a month in ongoing fees. Being a commercial loan, the term was over 15 years and the client had principal and interest repayments. Apart from wanting to get a cheaper interest rate, the client was keen to improve his cash flow and have more repayment flexibility. He wanted a lower contracted repayment and to be able to pay more when he wanted to. Our plan was to restructure the loan to a much cheaper residential loan by altering the security arrangements (on remaining debts) at his current bank and going forward at a new bank for this loan. Initially the client was sceptical that his rates could be reduced by more than 2%. He was also heavily intertwined with his current bank due to numerous business banking facilities, an overdraft, credit cards, personal guarantees and fixed and floating charges over his company. We also had to get involved with the client’s accountant to confirm that the financial restructuring would not have any negative tax implications. Once the accountant confirmed that our structure was suitable and it wouldn’t result in any negative impacts, the client couldn’t wait to sign up. The potential savings were very significant. The wrinkle in this deal was the business banker at the client’s current bank. We
Goal To reduce interest rate
no ongoing fees. This is saving him over $30,000 per annum in interest! Our client really appreciated the fact that we thought outside the box in his case. It was clearly a commercial loan for a commercial purpose. The particular bank we went to was okay to refinance commercial or business purpose loans as long as the security was residential. The client had owned the property for eight years and had previously just had to ‘grin and bear’ the traditional loan for that asset, which was a much more expensive commercial loan. Some of the bankers at the big banks can get a little institutionalised. They get sloppy, lazy and forget what they are there to do: look after the best interests of their clients. Instead they often look after the bank’s best interests as it’s easier and quicker. It definitely takes more time and effort to be creative and think outside the box to achieve a better client outcome. I guess this is why the broker market share grows every year. We work for the client, not the bank! THE TAKEAWAY
I feel that this deal is a good example of the value of using a mortgage broker as opposed to going directly to the banks. As a broker, we have numerous banks to choose from. Often this advantage is marketed on a price basis, ie brokers can find you the best deal. But to me, the real value of a broker and having access to multiple banks is that we have more
Our role, in a nutshell, is to use our knowledge and experience to make getting a loan quicker, easier and less stressful for the client was plenty of equity in the commercial property to support what was left, but the business banker was reluctant to let anything go. Seeing as we were taking away a $1.25m loan, the banker wasn’t happy. But at the end of the day, he couldn’t get anywhere close to matching what we could do. THE SOLUTION
Daniel O’Brien Director, PFS Financial Services in Sydney
Once we were able to remove the client’s residential property from his current banking arrangements, we were able to restructure the commercial loan as a residential home loan against his residential property. He had substantial equity in this residential property, so we essentially just swapped security properties for this particular loan. We were able to get the client’s rate down from 6.75% to 3.88% with
options and more possible solutions. Every bank has a niche policy and every bank has its own strengths and weaknesses. Our role, in a nutshell, is to use our knowledge and experience to make getting a loan quicker, easier and less stressful for the client. Obviously, price is important, but I think the aforementioned items provide a client with more value overall. This scenario offered my client major savings, but it was not achieved by doing a product search on some software. It was achieved through 19 years of knowledge, experience and passion. The client was very happy with the outcome; he has a way better deal now. He also decided to keep his repayments the same as he had on the old loan. This means he is now paying off $30,000 more in principal every year. AB
s
TECHNOLOGY UPDATE
BROKERS REALISING THE EFFICIENCIES OF ‘APPLYONLINE’
Helena Christakos, customer relationship and training manager at NextGen.Net
ApplyOnline, the industry standard for electronic lodgement of loan applications, plays a key role in brokers’ lives. However, not all brokers are aware of the many tools within the state-of-the-art platform, and are missing the opportunity to improve their day-to-day efficiencies, which is why NextGen.Net is investing heavily in training. “Often a solution is as simple as showing brokers a feature that’s been around for years,” says NextGen.Net customer relationship and training manager Helena Christakos. “I love it when people get great results after learning about a tool that they didn’t even know existed.” Christakos has implemented a posttraining survey and admits feeling “incredibly satisfied” when she reads the feedback. “It’s always so positive,” she says. “I get a real kick out of helping people. A lot of success comes from just showing them the easiest way to use the system.” After Christakos’ training sessions, the majority of brokers say their confidence in using ApplyOnline has improved significantly, with over 60% saying their increased understanding of ApplyOnline will save them time on a day-to-day basis. NextGen.Net provides complimentary training as part of its service to all customers. A variety of customised
training modes are available, including face-to-face, broker workshops and webinars. Christakos’ role is as a point of contact for users who want to understand how to interact more effectively with the technology platform in order to achieve the best outcome, which is of course ultimately, faster turnaround times. “My aim is to show brokers, who are generally working against the clock, that by using ApplyOnline correctly the whole process can be easier and more efficient,” she says. Christakos, a former broker with over 10 years’ experience in the finance industry, is also a qualified trainer and assessor who has held professional training roles for over three years. She brings a wealth of experience and knowledge to the NextGen.Net customer engagement team. She says pointing out how to take advantage of underutilised features in the ApplyOnline Supporting Documents module receives the loudest applause during training sessions. “Surprisingly, a large percentage of brokers are unfamiliar with the drag-and-drop feature in our Supporting Docs service,” she says. “We have a new version of Supporting Docs that has launched in the market with a few banks, and one of the things I have
done recently is show brokers how to upload documents in bulk. Most brokers don’t realise they can do that. “The feedback I get when I quickly take them through the process is ‘OMG that’s amazing. Thank you so much’.” Christakos admits that the misconception that ApplyOnline is complicated confounds her. “I have no idea why people think it’s complicated, especially when it comes to supporting documents,” she exclaims. “Our Supporting Docs service is the talk of the town, but some people still think it’s easier to email, which of course is completely erroneous.” Encouraging more BDMs to participate in training sessions is currently on Christakos’ agenda. “I’m always handing out my business cards,” she laughs. “I want BDMs to understand some of the common errors and misconceptions. I also want feedback from them. “My aim is to promote the fact that training is a two-way communication because we’re here to listen as well as to guide and enlighten. We are always looking at ways to improve what we do so we give a better user experience based on broker feedback. “The bottom line is that I’m passionate about helping brokers achieve the maximum benefits from ApplyOnline.”
www.brokernews.com.au
23
PEOPLE
Get involved in the discussion Share your thoughts at
brokernews.com.au
FROM THE FORUM
Top comments from trending stories on brokernews.com.au
MFAA BLASTS CONSUMER GROUPS FOR COMMISSION CALLS
ASIC COST RECOVERY FRAMEWORK FINALISED
A joint submission by consumer advocacy groups in response to ASIC’s Review of Mortgage Broker Remuneration has been panned by the MFAA as “ill-informed” and “detrimental”. CHOICE, Consumer Action, Financial Counselling Australia and Financial Rights Legal Centre recommended a complete overhaul of the current broker commission structure, saying that “commission payments must be restructured so that payments are not linked to the amount a customer borrows”. They also suggested removing upfront commissions and replacing them with fixed fees for advice, as well as scrapping trail commissions.
The cost recovery framework for ASIC has been finalised, incorporating changes made after industry consultation. Based on the metric of credit lent, the minimum levy will be set at $2,000 for all credit providers, plus a graduated charge per $10,000 of credit provided (other than under a small-amount contract) greater than $100m. For credit intermediaries, a $1,000 minimum levy will be put in place. A graduated levy will be charged based on the number of authorised representatives the intermediary had as of 30 June.
Well done MFAA for the rapid response to the submission that seems to be based on a distinct lack of knowledge of the industry. These reports do nothing to assist the consumer and seem to be written to “muddy” the waters and create confusion for borrowers, who over time have voted in significant numbers to say that brokers give a better outcome than direct channel processes. With brokers, borrowers have a choice; without them they do not. With brokers, the industry has to compete for business; without them, it has less incentive to do so. With brokers, borrowers are assisted through the lending process; without them, there is less assistance. How can this be a detrimental outcome? Ken on 13/07/17 at 9:11 AM
Basically CHOICE is asking to shut down the broking industry, as its proposal would put all brokers out of business and create massive unemployment. Feels like a bank’s ambit claim through a third party, given no organisation could be that out of touch with the reality of the industry it is commenting on. Reality on 13/07/2017 at 9:33 AM
Client: Hello Mr Broker, I’d like a $500,000 home loan, please. Broker: Happy to assist. My “Fee for Advice” is $2,000. Client: What? You expect me to pay you? Forget that idea, I’ll just go straight to a bank. Broker (six months later): I have no clients any more as clients are not prepared to pay for my services. I think I’ll get a job with one of the big four banks, they need heaps of staff now that brokers are out of business. Now I only need to sell one brand of product and I only need to know one credit policy. I get a guaranteed salary, four weeks paid annual leave, no business overheads, no staff payroll to worry about as I sacked my four staff who are now on Centrelink. I work 9 to 5, no more 8 pm or weekend after-hour client meetings an hour drive away. Client: Hello, Mr Banker, I’d like a $500,000 home loan. Banker (former broker): Sorry, application declined, you don’t fit our credit policy. Client: Do you know which lender I can talk to? Banker (former broker): Yes, but I work for XYZ Bank now. Next, please. RobR on 13/07/17 at 10:33 AM
24
www.brokernews.com.au
So what do licensees with a number of credit reps do? We have no idea what to charge our credit reps and what fee we are incurring now. Imagine if I said to a client: “I will organise your loan now but I won’t tell you what your repayments and interest rate are but you will have to pay whatever it is in full next year”. Ridiculous that these incompetent people are meant to be monitoring us when they can’t even introduce a single fee and tell us what it is. David on 14/07/17 at 11:29 AM
So commissions are to be reduced, but a one-person operation needs to find another $1,000. Must be the only occupation where everybody keeps decreasing their income rates, whilst constantly wanting more in return. Australia: Closed for business. Sigh… on 14/07/17 at 11:52 AM
Since we’ll effectively be paying the wages of ASIC staff, can we have a say on how many fat cats are employed there? According to their last annual report, 903 of their 1,826 employees (49.5%) are employed on executive level and above. One boss per worker sounds a bit steep. They paid out $8.3m in bonuses last year and over $7.3m of this was paid to the bosses (executive level and above). David R on 14/07/17 at 11:53 AM
Absolute crap. This is disgraceful and considering the amount of mandatory fees, income tax, GST, fuel tax, council rates, unfair levies and sky rocketing electricity costs, they can stick it. We should all threaten to go on the dole. … Forget the dole idea, I want an executive job at ASIC. Brendan Phillips on 14/07/17 at 12:10 PM
As usual, they have no idea how the industry works. Whatever happens it will mean more cost and red tape to our already overburdened businesses and further consolidation = more control by the big players. Time to look for a PAYG job where I can rock up my 9-5 for a salary and let someone else worry about this. Papery on 14/07/17 at 12:26 PM
CAUGHT ON CAMERA To thank clients for their business while also giving back to the community, Melbourne-based brokerage Entourage Finance hosted its first ladies lunch at the Rockpool Bar and Grill on 15 June. More than 30 women attended the event, which was hosted by Emma Hawkins, the wife of Geelong forward Tom Hawkins. Bec Daniher, the daughter of former AFL player Neale Daniher, who are both campaigners for motor neuron disease, also attended to promote the FightMND organisation. Entourage donated money to the cause and encouraged attendees to do the same. “All our business comes from referrals. Instead of spending $5,000 on Google AdWords, I’d rather spend $5,000 on a lunch and give back to our clients as a way of thanks, because I know it always comes back,” said Entourage Finance director Damien Roylance.
www.brokernews.com.au
25
DATA
WESTERN AUSTRALIA
SA SPOTLIGHT
Many Western Australians are leaving the state as the market tries to anticipate the bottom of the cycle According to CoreLogic’s Quarterly Housing and Economic Review for April 2017, the state experienced its highest rate of negative migration in the year to September 2016, which could throw a wrench into investors’ plans to profit off the very affordable property prices. “Investors should remain wary of negative migration from the state and what this means for their ability to find and maintain tenants,” says Charles Tarbey, chairman and owner of Century 21 Australasia. Nonetheless, Tarbey also believes that Perth is beginning to find its footing. “Of late, conditions are showing signs of balance. CoreLogic data showed that dwelling values in Perth were down 0.4% over the quarter to the end of May. This may represent a good opportunity for investors, and as such, some areas appear to be experiencing increasing investor interest.”
Area
Type Median value
Quarterly
12-month
growth
growth
Perth
H
$510,000
-1.9%
-2.5%
WA Country
H
$360,000
0.0%
-6.4%
Perth
U
$410,000
0.2%
-3.5%
WA Country
U
$285,000
0.0%
-7.3%
NEW SOUTH WALES
Negative affordability talk and tighter lending regulations mean investors are staying away Sydney is typically one of Australia’s best markets, but findings from the May 2017 quarter suggest that this capital is currently in for a bumpy ride. Property prices slipped by 1.3% in the past month, according to CoreLogic, suggesting that lending restrictions may finally be taking a toll. “Regulatory bodies are placing a continued focus on investment loans, and we have seen banks independently increasing rates. As a result, we are seeing declining demand from investors in some parts,” says Charles Tarbey, chairman and owner of Century 21 Australasia. “We are starting to see supply lines slowly increasing, which may lend itself to softer market conditions over the next quarter. More stock and fewer buyers may lead to less bullish growth than we have previously seen.” Tarbey pinpoints the outer ring as an area where stock on the market is rising. Area
Type Median value
Quarterly
12-month
growth
growth
THE ADELAIDE ALTERNATIVE
Adelaide vacillates between a market that is met with apathy and one that offers the promise of growth
affordability becoming such a major issue in capital cities like Sydney and Melbourne, Adelaide’s low-priced properties have surfaced as an alternative for investors and first home buyers alike. “South Australian first home buyers are paying up to $500,000 less than their Melbourne and Sydney counterparts when they take the plunge and enter the property market,” says Gregg Harris, general manager of NAB Retail SA. “If spent wisely, $400,000 to $600,000 can buy a modern four-bedroom family home on a large block of land within a short commute from the CBD.” According to CoreLogic, over a third of properties in Adelaide are priced within this range, while over a quarter are priced between $200,000 and $400,000. This could be the push the market needs. “The state’s northern suburbs are seeing many housing developments underway. It’s a hotspot for first home buyers and property investors as many newly built homes provide low maintenance accommodation options,” Harris points out. “[However,] there’s [also] much to like about Adelaide’s southern suburbs. The region is home to some of the country’s most enviable coastlines. It is a highly liveable area with accessible local infrastructure, including shopping centres, health care centres and schools.” However, Jane Slack-Smith, director of Investors Choice Mortgages, warns against diving head first into the Adelaide market. “South Australia still has a lot of its economic success linked to the mining industry, and it may be just getting a surge of attention at the moment. But the long-term fundamentals mean you really need to do your research to scout out the money-making opportunities,” she says. AB WITH
H
$905,000
-9.5%
3.6%
Median price (houses)
NSW Country
H
$445,000
1.1%
5.7%
$763,924
Sydney
U
$710,000
-0.3%
2.9%
NSW Country
U
$365,000
0.0%
2.9%
www.brokernews.com.au
There are many well-publicised economic issues affecting South Australia’s housing market at the moment Unemployment levels are approaching 7% in SA and there have been a number of high-profile business closures, putting a ceiling on overall growth in housing prices and financing. However, some popular metropolitan postcodes have enjoyed more than reasonable levels of interest from owner-occupiers. Properties in the western seaboard suburbs, in the leafy green eastern suburbs and the Hills area have attracted strong numbers, keeping their days on market at satisfactory levels. The challenges created by restrictions on investment lending have had a dampening effect on interstate investors looking for profitable returns. But rental returns of 5% – simply not achievable on the eastern seaboard – can still be had. It will always be the case, however, that strong propositions can be accommodated. Another point of discussion at the moment are the recent incentives to tackle living and investing in Adelaide’s CBD, which have had lukewarm results. It seems it will require more than government encouragement to soak up the apparent oversupply there, at least in the short term.
Colin Ellks Lending adviser, KeyInvest Lending Services
SUBURB TO WATCH: COLLINSWOOD
Sydney
26
BROKER PERSPECTIVE
Median price (units) $309,150
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
13.3%
15.8%
21.5%
2.9%
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
-2.0%
1.7%
12.0%
4.4%
AUSTRALIAN CAPITAL TERRITORY
Steady growth in the ACT market is supported by employment security and high levels of rental demand OPPORTUNITIES AND KEY INFRASTRUCTURE
Festival Plaza
Urban recharge
Darlington upgrade
Flinders Link
Upgrade expected to generate economic growth and create a world-class destination
The transformation of an old hospital into a mixed-use area continues
A 3.3-km Main South Road upgrade improves Adelaide’s North-South corridor
$85m project extends Tonsley rail line, creating a connection to Flinders University
HIGHEST-YIELD SUBURBS IN SOUTH AUSTRALIA Suburb
Type
Median price
Quarterly growth
12-month growth
Coober Pedy
H
$65,000
-3%
-17%
Port Pirie West
H
$101,500
-8%
-7%
Whyalla Norrie
U
$85,750
-14%
-41%
Whyalla Stuart
U
$85,000
-15%
-27%
Risdon Park
U
$95,000
-13%
-21%
Canberra remains in a strong position as housing prices soared over the May 2017 quarter. Charles Tarbey, chairman and owner of Century 21 Australasia, believes ACT’s growth is supported by the positive economy. “There is security in the market, thanks to government employment, which is supported by a goodquality supply line,” he says. “We have seen the market grow steadily over the year, with CoreLogic reporting a 5.7% yearon-year increase in dwelling values to the end of May. I believe it will continue to [grow].” Canberra joins Melbourne as one of the best performers in the national property market in recent months, taking over from Sydney. In this political hub of the nation, the auction market performed admirably in May, with the overall clearance rate clocking in at 70%. This represented a near-10% increase compared to the previous year. Area
Type Median value
Quarterly
12-month
growth
growth
Canberra
H
$675,500
4.7%
6.7%
Canberra
U
$428,000
-2.7%
2.4%
www.brokernews.com.au
27
DATA
Quarterly
12-month
growth
growth
Brisbane
H
$514,000
-2.1%
3.5%
QLD Country
H
$430,000
0.0%
2.0%
Brisbane
U
$403,000
-1.0%
-2.4%
QLD Country
U
$375,750
0.2%
2.9%
VICTORIA
MEDIAN HOUSE AND UNIT PRICES
With levels of interstate migration into Victoria continuing to set records, demand for properties keeps climbing
$1,000,000
Type Median value
Quarterly
12-month
growth
growth
H
$650,000
-5.1%
8.1%
VIC Country
H
$326,000
0.0%
3.2%
Melbourne
U
$480,000
-3.4%
1.0%
VIC Country
U
$258,000
-2.1%
1.6%
www.brokernews.com.au
62
Sold
34
Not sold
23
Clearance rate
59.6%
PERTH Total auctions
41
Sold
8
Not sold
14
Clearance rate
36.4%
Sydney Melbourne Brisbane Adelaide
Perth
$550,000
$286,500
$371,000
$415,000
$0
$500,000
$100,000
$315,000
$200,000
$430,000
$300,000
$529,500
$500,000 $400,000
$700,000
$700,000 $600,000
$960,000
$800,000
Houses
$730,000
$900,000
Melbourne
28
Total auctions
$1,100,000
According to the April 2017 Quarterly Housing and Economic Review published by CoreLogic, Victoria had the highest net migration gain out of all states in the year to September 2016. For Charles Tarbey, chairman and owner of Century 21 Australasia, this result is unsurprising given the strength of its market. “The Victorian market is a standout in Australia, and Melbourne continues to outperform other Australian capital cities,” Tarbey says. “The state offers not only many affordable areas to purchase property but good prospects for employment. The opportunities for work are as strong as in Sydney; however, property can be secured at a more affordable price in comparison, so it will likely continue to attract plenty of investment interest.” ABS data indicate that, as of the end of 2016, over 2,000 people were migrating to the capital each week. Area
ADELAIDE
All data sourced from CoreLogic
$376,000
Type Median value
The combined capital city final auction clearance rate increased to 68.4% for the week ending 13 July. However, auction volumes were lower week-on-week, with a total of 1,766 auctions being held. Melbourne was the strongest-performing capital city auction market for the week ending 13 July, with 72.9% of the 818 auctions reported to be successful, increasing from the 70.8% across 874 auctions in the week prior. Across Sydney, 68.6% of the 656 auctions cleared last week, the fifth week in a row in which the city has recorded a clearance rate around the high-60% mark. Performance was mixed across the remaining capital cities, with clearance rates improving in Adelaide and Brisbane but decreasing in Canberra, Perth and Tasmania. The Geelong region in Victoria was the best-performing non-capital-city region in terms of clearance rate, with 80.8% of auctions successful, while Queensland’s Gold Coast had the highest number of auctions at 44.
$520,250
Area
WEEK ENDING 13 JULY 2017
Hobart
Darwin
Units
$393,000
Growth is limited due to high unit stock, but low prices maintain the appeal of Brisbane and the Sunshine Coast to Sydneysiders. “Brisbane is continuing to face challenges due to increases in supply, particularly in apartment stock,” says Charles Tarbey, chairman and owner of Century 21 Australasia. “[However,] whilst growth has been more subdued, with Brisbane recording a 0.3% lift in dwelling values over the month of May, it is likely that the market will continue to attract interest from the southern states.” Tarbey points out that median house prices in Sydney are more than double those of Brisbane, “so the Brisbane capital city market, as well as Sunshine Coast areas, will likely remain appealing due to more affordable price tags with accompanying lifestyle benefits on offer”.
CAPITAL CITY AUCTION CLEARANCE RATES
$610,000
Significant levels of unit supply have been both a boon and a bane to Brisbane thus far
$444,000
QUEENSLAND
Canberra
CAPITAL CITY HOME VALUE CHANGES Capital city
Weekly change
Monthly change
Year-to-date change
12-month change
Sydney
0.6%
3.4%
6.9%
13.1%
Melbourne
1.4%
4.3%
7.6%
15.5%
Brisbane
0.3%
0.5%
1.8%
3.7%
Adelaide
0.1%
-1.0%
1.6%
2.2%
-0.6%
-0.8%
-1.9%
-2.4%
0.7%
2.7%
5.4%
10.6%
Perth Combined 5 capitals
*Brisbane results are for the combined Brisbane and Gold Coast region. The monthly change is the change over the past 28 days.
BRISBANE CANBERRA Total auctions
65
Sold
37
Not sold
22
Clearance rate
Total auctions
114
Sold
54
Not sold
43
Clearance rate
55.7%
62.7%
SYDNEY Total auctions
656
Sold
409
Not sold
187
Clearance rate
68.6%
TASMANIA
MELBOURNE Total auctions
818
Total auctions
10
Sold
563
Sold
5
Not sold
209
Not sold
4
Clearance rate
Clearance rate
72.9%
TASMANIA
Hobart continues its reign as Australia’s most affordable capital, displaying strong growth prospects “[Hobart] has emerged as a strong performer in recent CoreLogic reports, recording a 5.8% increase in year-on-year dwelling values as of the end of May,” says Charles Tarbey, chairman and owner of Century 21 Australasia. “The combination of high-quality living and affordability make it an appealing investment location, and we have investors increasingly moving into the market.” However, Tarbey does caution investors to monitor rental yields and vacancy rates, since the market also faces the risk of soaring vacancy rates compared to other regions in Australia. At present, however, REA Group chief economist Nerida Conisbee suggests that tenant demand is quite high. “It’s the most affordable capital in Aussie, and there’s lots of interstate demand. There’s also lots of offshore interest from Chinese investors.”
Area
55.6%
Type
Median value
Quarterly growth
12-month growth
Hobart
H
$385,000
-1.5%
6.4%
TAS Country
H
$260,000
-5.1%
0.0%
Hobart
U
$308,000
2.7%
2.8%
TAS Country
U
$237,500
1.9%
0.0%
All data sourced from CoreLogic.com.au
www.brokernews.com.au
29
PEOPLE
IN THE HOT SEAT Rowena Myers, a finance broker at Home Loan Connexion, talks about being inspired by her own broker, and how she knows exactly what her clients are going through because she’s been through it all herself
Who or what inspired you to become a broker? From a very young age, I was finance-savvy and had an interest in A property. Being a property investor helped forge my path into broking. I was really inspired by my own broker, Sandy Joseph, who helped me create, build and successfully achieve my portfolio goals. Having worked with Sandy on numerous investment deals, I have gained invaluable knowledge that I am now using in my own practice. Having this knowledge allowed me to hit the ground running when I became a broker. Sandy has been there with me since the beginning, and her support kept me sane. I fully understand the importance of having a good broker behind you.
Q
What was your previous career and how has it helped you as a broker? I was previously a chemist. After being made redundant in 2016, A I followed my heart and completed my broker training. A job as a chemist requires analytical and critical thinking skills and excellent attention to detail, as it is a highly regulated industry. This is where I see the overlap across the two industries and where I see my skills being transferable. One of my strengths is being able to understand the compliance and policy sides of the finance industry.
Q
What have you learned from being a property investor yourself? Owning a property portfolio is possible, and confidence is key. A With the right strategy you can set yourself on the path to financial independence. The financial wealth you receive is achieved through a sound process that focuses on the overall strategy and not just individual transactions.
Q
What do you wish you’d known about the industry before you got into it? Becoming a broker is not a get-rich-quick scheme. It’s all about A time in the market, building relationships, determination and passion to stick it out, especially in the first six to 12 months when you are getting yourself established.
Q
How would you spend a lottery win of a million dollars? The sensible approach would be to reinvest the money wisely, but if A I were to create a lifelong memory, I would hire a plane with a close group of friends, fly to a paradise island and have lots of fun. AB
Q
30
www.brokernews.com.au
Book your table now
Friday 27 October • The Star Sydney www.australianmortgageawards.com.au Event Partner
Award sponsors
Official publications
Organised by
www.brokernews.com.au
31
32
www.brokernews.com.au