JUNE 2017 ISSUE 14.12
Under dark clouds ASIC looks for new ways to tackle the complex problem of mortgage fraud /16
Different markets, different constraints Blanket lending restrictions could have detrimental effects /20
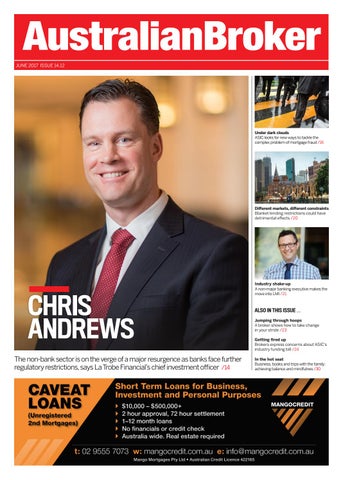
CHRIS ANDREWS The non-bank sector is on the verge of a major resurgence as banks face further regulatory restrictions, says La Trobe Financial’s chief investment officer /14
Industry shake-up A non-major banking executive makes the move into LMI /21
ALSO IN THIS ISSUE … Jumping through hoops A broker shows how to take change in your stride /23 Getting fired up Brokers express concerns about ASIC’s industry funding bill /24 In the hot seat Business, books and trips with the family: achieving balance and mindfulnes /30
NEWS
IN THIS SECTION
Lenders A digital bank plans its debut in Australia /04
Aggregators Connective adds to broker support team /06
Technology Paperless mortgages on the horizon /10
Regulators Brokers alarmed by seemingly endless regulation /12
Consumers Australian house price growth rate higher than international average /08
www.brokernews.com.au JUNE 2O17 EDITORIAL Editor Otiena Ellwand News Editor Miklos Bolza Production Editor Roslyn Meredith
DATES TO WATCH
Upcoming industry events and key dates
ART & PRODUCTION Design Manager Daniel Williams Designer Martin Cosme
1 8 J U LY – 3 A U G U S T
2 5 J U LY
2 7 J U LY
Women in Business
MFAA skills webinar
FAST is hosting five state conferences specifically geared towards helping women succeed in broking. Women have been recognised by a number of aggregators as a growing segment of the industry
Polish your skills during this one-hour webinar hosted by the MFAA on “Responsible Lending: The intricacies that most brokers don’t get – and need to know”
MFAA National Excellence Awards State award winners will head to this national event in Melbourne to vie for the top prize at the end of July. More than 300 finalists were selected from across the country in a number of categories. The awards recognise the association’s core values of professionalism and integrity
Production Manager Alicia Chin Traffic Coordinator Freya Demegilio
SALES & MARKETING Sales Manager Simon Kerslake Account Manager Rajan Khatak Marketing and Communications Manager Lisa Narroway
CORPORATE Chief Executive Officer Mike Shipley Chief Operating Officer George Walmsley Managing Director Justin Kennedy Publisher Simon Kerslake Chief Information Officer Colin Chan Human Resources Manager Julia Bookallil
EDITORIAL ENQUIRIES
Otiena Ellwand +61 2 8437 4792 Otiena.Ellwand@keymedia.com.au
SUBSCRIPTION ENQUIRIES
tel: +61 2 8O11 4992 fax: +61 2 9439 4599 subscriptions@keymedia.com.au
2 - 10 AUGUST
15 AUGUST
16 AUGUST
Commercial Broker Forum
MPA Aggregator Roundtable
FAST is hosting four commercial and asset finance conferences to provide brokers with state-related insights that reflect the local market. Invitations will be sent out to FAST brokers
MPA Magazine is hosting a lunchtime aggregators roundtable that brokers can watch online for free. The panel features seven aggregators: Plan, Choice, FAST, Connective, eChoice, Outsource and Specialist. They will discuss commissions, the Sedgwick review and compliance
National Finance Brokers Day Dino Pacella founded this event back in 2015 to celebrate brokers and educate consumers. The goal this year is to raise $50,000 through charity drives for sick children
ADVERTISING ENQUIRIES
Simon Kerslake +61 2 8437 4786 simon.kerslake@keymedia.com.au Rajan Khatak +61 2 8437 4772 rajan.khatak@keymedia.com.au Key Media Pty Ltd Regional head office, Level 1O, 1–9 Chandos St, St Leonards, NSW 2065, Australia tel: +61 2 8437 4700 fax: +61 2 9439 4599 www.keymedia.com Offices in Sydney, Auckland, Denver, London, Toronto, Manila, Singapore, Bengaluru
26 - 27 AUGUST
11 - 13 OCTOBER
10 OCTOBER – 1 DEC
Property and Investing Expo
Credit Law Conference
Connective Conference 2017
Free seminars and over 100 exhibitors will be at the Melbourne Exhibition Centre to provide investors with insights and contacts to help build their portfolio and establish successful strategies
The 27th annual event in Surfers Paradise brings together banks, credit unions, regulators, associations and market disruptors to discuss the future of credit and lending
Connective is bringing its conference to Vic, WA, Qld, NSW and SA on various dates from October to December. The conference promises to inspire brokers with new business development strategies, marketing techniques, insights from industry experts, and workshops on health, mindfulness and more
2
www.brokernews.com.au
This magazine is printed on paper produced from 1OO% sustainable forestry, grown and managed specifically for the paper pulp industry Copyright is reserved throughout. No part of this publication can be reproduced in whole or part without the express permission of the editor. Contributions are invited, but copies of work should be kept, as Australian Broker magazine can accept no responsibility for loss. Australian Broker is the most-often read industry publication, according to independent research carried out by the Ehrenberg-Bass Institute for Marketing Science at the University of South Australia in December 2008. The research also found that brokers rate Australian Broker as the best for both news content and feature articles, followed by sister publication MPA. Overall, on all categories, Australian Broker ranks top followed by MPA. The results were based on a sample of 405 respondents who were the subject of telephone interviews.
NEWS
LENDERS
sources have told the Australian Financial Review that executives at Macquarie Group are canvassing options for moving overseas following the $6.2bn bank levy announcement. A Macquarie spokesperson neither confirmed nor denied the claims. “As we have said over the years, Macquarie consistently looks at the most appropriate locations for its businesses and head office,” she said. “Whilst approximately two-thirds of our business is outside Australia, it remains a key market.” Macquarie currently has operations in 28 other countries. SENIOR
“Understand the implications the location of your property may have on your insurance or home loan contract.”
Paul Ranson CEO, B&E
4
www.brokernews.com.au
90% 80%
46.29% 48.28%
$656,800
$642,900
70% 60% 50%
$351,900
40% 30%
$320,600
$100,000
$326,100
$200,000
48.59%
$343,900
$300,000
$317,700
$400,000
$536,600
$500,000
51.07%
$255,800
$600,000
52.38%
$492,200
54.25%
$297,700
57.24%
$435,400
$700,000
47.00%
$316,300
47.31%
$690,100
$800,000
$864,900
$900,000
$263,200
MACQUARIE MAY RELOCATE OFFSHORE
Source: CommBank Connected Future Report, June 2017
$461,000
CEO of Tasmanian non-major B&E has urged state and local governments to protect homebuyers from the threat of climate change and rising sea levels. CEO Paul Ranson said buyers needed to think carefully about purchasing a home in a high-risk area. “Understand the implications the location of your property may have on your insurance or home loan contract,” he said. He called on government to implement strategies that deal with this, adding that prevention would be cheaper than mitigation. THE
NSW AND VIC RESIDENTS LEAST OPTIMISTIC ABOUT BUYING PROPERTY
$272,200
LENDER SOUNDS CLIMATE CHANGE ALARM
20% 10% 0%
$0
NT
WA
Average loan size (July 2016)
SA
QL D
TAS
ACT
Mean dwelling price (Dec 2016)
The CEO of a new incoming digital bank says it will eventually offer home loans, possibly with help from the third party channel may soon have its first ‘neobank’ with the arrival of Xinja, a digital-only firm that hopes to gain its banking licence and eventually expand into home loans. Xinja is a full-service digital retail bank built for mobiles. It mirrors the neobanks popping up globally in the UK, US and Europe. ‘Neobank’ refers to a bank without any traditional infrastructure such as branches or legacy IT systems, which often plague even the newer non-major banks, CEO Eric Wilson told Australian Broker. Over the past year and a half, Wilson, a former NAB executive, has been working to establish Xinja, and the company is in talks
VIC
Australia
Optimism: The Australian dream is still a reality
NEOBANK XINJA PLANS EXPANSION TO AUSTRALIA
AUSTRALIA
NSW
with APRA and ASIC to gain a credit and banking licence. Wilson hopes Xinja will become an ADI within a year, then start taking deposits in 18 months and offering mortgages in 18 to 24 months. At the time of writing, Xinja had raised just under $3m in funding in a single five-day funding round held at the beginning of May. It is now in the process of pre-registering customers. While Xinja has yet to make a decision about working with brokers in the future, Wilson said there was no reason not to utilise the third party channel. “More than half of Australian mortgages are done through brokers. They provide an
important, rational decisionmaking process. We think we’re going to have an utterly incredible product, so why would we deny ourselves that channel? Brokers have a really important part to play.” Wilson asked brokers to register on the bank’s website and provide feedback on the model there. “We’d be fascinated to talk to brokers to find out what their financial needs are,” he said. “It would be great to get their feedback and build Xinja with brokers in mind as well.” Speaking about digital-only mortgages, Wilson said that while these weren’t offered by all lenders across Australia, they were quite common elsewhere. “It’s not about replacing brokers because I think we still need that intelligent, rational review of products on the market. It’s about the ability to have an end-to-end process where you don’t have to speak to someone if you don’t want to.”
NEWS
A G G R E G AT O R S SUBAGGREGATOR TEAMS UP WITH TAX GROUP Circle has announced a joint venture with tax firm Citycorp, which owns Pop Up Tax Shop and Mr Tax Refund. The agreement gives the subaggregator’s member brokers access to 15 company owner locations and 16 franchises, which will service over 18,000 clients by June 2018. “We’re very keen to begin not only providing our clients with a more comprehensive offering, but also to enjoy the additional revenue streams the partnership brings through the integration of additional services,” said Citycorp CEO Stephen Burns. PURPLE
BROKING GROUP HITS $100M IN MONTHLY SUBMISSIONS brokerage and financial planning group RateOne has achieved $100m in monthly submissions in the four years since the company was launched. Co-founder Martin Fedmowski said an overhaul of the business’s processes two years ago was behind this rapid growth trajectory. “We implemented a back-end team of six in Melbourne and Manila who do all our processing – everything from submissions to data entry, settlements and tracking – and we provide that service to the 28 brokers on our team.” MELBOURNE-BASED
AGGREGATOR GROWS BROKER SUPPORT TEAM Connective has welcomed three new members in a recruitment drive that aims to provide greater services to brokers aggregator Connective
NATIONAL has welcomed three
new members to its broker support staff in a hiring spree that looks set to see the team continue growing in the future. Mark O’Shaughnessy joins as head of wholesale, a new role designed to reinforce the aggregator’s focus on best practice broker support services. O’Shaughnessy comes to the aggregator with 16 years of experience working at retail market players such as Medibank and Flight Centre, and brings a wealth of operational and sales leadership capabilities with him. “Mark will provide an integrated level of support and focus to our broker support team,” general
6
www.brokernews.com.au
manager for sales and distribution Gingkai Tan told Australian Broker. “We recently restructured our national resources to ensure we continue to provide industry-leading broker support and to additionally enable us to enter new business initiatives confidently and seamlessly as we grow the business.” As the second new hire, Sandra Ascenzo has stepped into the role of broker relationship manager team leader, taking over from Andrew Piltz, who has moved into a business analyst role in sales and distribution. Ascenzo is well known at the aggregator and has worked with member brokerages for a number of years. She joins Connective from My Local Broker, where she worked as lead broker support.
“There are a number of new and exciting projects underway at Connective and Sandra will play a key role in helping us deliver a best-in-class onboarding capability. When a broker joins the Connective community, it’s crucial they enjoy a positive and seamless integration into our business,” Tan said. Finally, Keerthi Damera joins the Mercury Helpdesk and will bring fast, efficient support around this CRM system to new brokerages coming on board. She comes from NAB where she worked on the bank’s service desk for five years. “Keerthi will join a very successful helpdesk team. Our helpdesk is currently sitting at a 99% satisfaction rating with our brokers, and we want to retain that. As we’re growing the business, Keerthi is a great addition to the team,” Tan said. Over the past 12 months, Connective has doubled its Mercury development team and hired more staff in broker-facing roles, including broker support managers and compliance support managers.
“We recently restructured our national resources to ensure we continue to provide industry-leading broker support.” Gingkai Tan General manager for sales and distribution, Connective
NEWS
CONSUMERS ANNUAL AUSTRALIAN HOUSE PRICES JUMP 7.7% has experienced an upward trajectory in property prices over the past year, which has pushed it up the international leaderboard. Knight Frank’s Global House Price Index – Q1 2017 saw Australia move from 37th place in the fourth quarter last year to 20th place by the first quarter this year. In the most recent quarterly index, Australia recorded an annual growth rate of 7.7%. This was higher than the international average of 6.5%. AUSTRALIA
FIRST HOME BUYER ACTIVITY TO SURGE IN NSW first home buyer amendments that will be rolled out by the NSW Government are likely to boost demand for this segment of the market. The new measures, which were outlined last week by Premier Gladys Berejiklian and Treasurer Dominic Perrottet, will provide first home buyers with a stamp duty exemption for properties with price tags under $650,000. This exemption, and a raft of other housing affordability measures, will come into effect on 1 July. THE
“The average age of a first home buyer has remained relatively consistent for the past few decades ... when we’re seeing other life markers such as the age of marriage and childbirth be pushed back later.” Claire Madden Social researcher and demographer
AVERAGE FHB AGE STABLE FOR LAST TWO DECADES First home buyers are still entering the property market at the same age despite escalating house prices average age of the Australian first home buyer has remained stable for the past two decades despite the price of property growing by 7.7% per year. A new paper from the Commonwealth Bank of Australia, CommBank Connected Future Report, found that buyers generally enter the market for the first time at the age of 32. This has remained unchanged for 20 years. To examine the market trends from the data, CBA partnered with Claire Madden, social researcher, keynote speaker and demographer. “It’s quite an interesting finding that the average age of a first home buyer has remained THE
relatively consistent for the past few decades, hovering at that 32 years of age mark, particularly when we’re seeing other life markers such as the age of marriage and childbirth be pushed back later,” Madden said. “What we are seeing is the journey for Gen Y to get to that point of home ownership has looked drastically different from their predecessors. “It means that in many cases they have stayed at home longer to enable them to save up for that deposit.” This was not to discount the obstacles that the younger generation had to overcome, she added, with increasing household expenses an example of this. “If we go back to 1970, 13% of
household expenditure was spent on housing. It had risen to 18% by 2012. For first home buyers, it was 21% of their gross weekly income.” Rising housing prices have also changed the property landscape, with the Australian ‘dream home’ transforming from a standalone weatherboard house on a quarter-acre block into smaller, more architecturally designed products, the report found. While 74% of those in cities and 81% of those in regional areas live in standalone homes, 48% of new residential approvals over the past year have been for medium- or high-density housing. “This is how people are responding to increased prices and greater demand,” Madden said. “What it does show us is that getting into the property market still resides deep in the Australian heart and is high on the aspiration list with young adults who are still in those key family forming years.”
PROPORTION OF FAMILY INCOME REQUIRED TO MEET AVERAGE LOAN REPAYMENTS IS GOING DOWN Source: Adelaide Bank/REIA Housing Affordability Report
40%
35%
30%
25%
20% 2000
8
2001
www.brokernews.com.au
2002
2003
2004
2005
2001
2007
2008
2009
2010
2011
2012
2013
2014
2015
2016
2017
NEWS
TECHNOLOGY
NEW FINTECH CEO GROWS BROKER TEAM CEO James Green has taken over as general manager of nationwide fintech Rate Comparison’s home loans division. Green says he has always had an eye on the fintech space and has decided to make the jump because of where the market is heading. One of his main priorities is to expand the broker team to 20 in the next six months. Green has already grown the team from three to six and is sending out feelers for more. EX-CENTURY 21
NATIONWIDE DIGITAL MORTGAGES A BOON TO BROKERS Plans to introduce a completely paperless mortgage process across Australia could see refinances completed in 20 minutes national transition to a completely digital mortgage application process will benefit the mortgage broking industry, according to an industry leader who is helping to drive this technological change. Marcus Price, CEO of Property Exchange Australia (PEXA), called the digitisation of lending processes one of the most significant changes facing the industry. PEXA was established in 2010 to meet the Council of Australian Governments’ goal of forming a single, nationwide e-conveyancing solution for the property industry. PEXA now acts as a gateway to government registries that have also digitised their processes. “When PEXA started in 2010, it A
was met with exhilaration but mainly cynicism,” Price said during a speech at the AB+F Randstad Leaders Lecture Series 2017 in Sydney on 1 June. “In most cases, we were told that this is an industry where it’s just not going to work. The state governments are never going to support this and cooperate, the banks will never use it, you’ll never get the data standards done, never get legislation passed,” he said. PEXA fought against this pushback and has made enormous gains since it first started transacting in 2015. Most of the firm’s achievements have been reached over the past two years, Price said. These milestones include signing up 115 financial institutions (representing 98% of
the financial market), 90% of large-volume practitioner firms, and over 4,000 legal and conveyancing firms. “There has been $50bn of property transacted already through the platform. Seventeen percent of all lodgments today are electronic – we haven’t really bubbled up to consciousness yet as it’s all happened very quickly – and 49% of refinances are electronic.” This type of digital transformation provides greater speed, efficiency and transparency, Price said, with PEXA able to do mortgage refinancing in 20 minutes from start to finish in the best-case scenario. The PEXA platform allows for electronic VOI, e-loan contracts, digital lodgments and tracking. The mortgage broking industry could become the core introducer of these e-products and services, Price said. “From their point of view, I think it’s going to reduce the paperwork they’ve got right now, and the administrative load.”
VV LENDING FINTECHS GROWING IN AUSTRALIA Source: EY Australia FinTech Census, 2016
25%
25% 21%
21% 20% 15% 10%
7%
5%
5%
4%
4%
3%
3%
3%
2%
1%
0% Lending
10
Personal Payments/ finance/asset billing management
www.brokernews.com.au
Data analytics/ big data
Institutional tools
Regtech
Money Insurance transfer/ remittance
Cyber security
Distributed Digital ledger currency
0% Digital identity
Other
WHOLESALE FUNDER PRAISES DIGITAL VALUATION general manager Brett Halliwell says NextGen.Net’s ApplyOnline BrokerOrdered Valuations service provides a more streamlined application process and is a win for all parties. Before it existed, brokers had to order a valuation through one system then jump onto another to lodge the deal. “It was cumbersome and messy so NextGen.Net created a solution by marrying the two systems,” he said. Brokers can now electronically order property valuations any time during the loan application process. ADVANTEDGE
NEWS
R E G U L AT O R S
ASIC CALLS FOR NEW REGULATORY TOOLS deputy chairman claims the current regulatory regime is “not up to scratch” and needs broader powers and tools to better meet the challenges of the future. In a speech on 6 June, Peter Kell identified what was missing from ASIC’s array of tools and what was needed to meet future demands. “In areas as diverse as mortgage broking, life insurance, small business lending and dispute resolution, inquiries have identified areas where the current regulatory regime is not up to scratch,” he said. ASIC’S
RAMPANT REGULATIONS BIGGEST CONCERN FOR BROKERS A new survey has exposed unease in the broker community due to recent lending restrictions introduced by the regulators a swathe of decisions to tighten responsible lending, brokers have expressed alarm at the rapid nature of these reforms. A survey conducted by MyState Bank collected results from more than 200 brokers and found the number one concern for over 50% of respondents was the speed at which regulators have changed aspects such as LVRs and loan availability to quash heated housing markets in Sydney and Melbourne. An additional 25% of brokers flagged the potential for further regulatory changes with limited notice as their primary concern, while 8% said the ability of their broking businesses to deal with these changes at short notice was more worrisome. Regulatory action overshadowed AMID
ASIC EXPLAINS DRAFT MEDIA RELEASE CONSULTATION has been asked to explain why it consults with lenders and other parties prior to publishing some media releases. At a Senate Budget Estimates Hearing on 31 May, ASIC deputy chair Peter Kell said it was policy to supply media releases in certain scenarios. “We do provide for a short window in which to check media releases in relation to negotiated outcomes, not to court-based outcomes. It only occurs after the outcome has been decided and determined,” he said. ASIC
12
www.brokernews.com.au
housing market concerns, with only 9.5% of brokers saying the potential for a significant slowdown was their main fear. These responses show that brokers believe regulators are not giving adequate notice or allowing consultation around regulatory changes, said MyState group executive broker distribution Huw Bough. “Mortgage brokers are a key mortgage distribution channel in Australia. Broker networks give consumers greater choice and encourage competition by enabling smaller challenger banks to offer products in markets right across the country,” he said. “As an integral part of our financial system, it is important that the broker industry’s views are
fully considered and taken into account in any industry change.” In the survey, which was carried out through the bank’s national broker network, more than 60% of those polled said regulators had failed to consider the wishes of consumers when making the recent changes. There also seems to be a move away from the big four banks, with 46% of respondent brokers saying a greater number of clients are now looking for a mortgage elsewhere. As a smaller bank, MyState is strategically reliant on the broker channel and is not conflicted on where it wants to compete, Bough told Australian Broker. “This enables us to have a healthy and deeper dialogue with brokers, act as a real business partner, and really focus on improving the broker customer experience. Because we succeed if our brokers succeed, our interests are aligned around helping brokers in a range of areas and doing what is best for the customer.”
MAJORITY OF FOREIGN BUYERS PREFER APARTMENTS Source: Knight Frank Foreign Investment in Australian Residential Property
% share of the total, by state, Q1 2017 70% 60% 50% 40% 30% 20% 10% 0%
NSW Houses
VIC Apartments
Land
Qld
WA
NSW AND VIC RESIDENTS PAYING LARGEST PROPORTION OF INCOME TO MEET LOAN REPAYMENTS Source: Adelaide Bank/REIA Housing Affordability Report
Repayments based on data for new borrowers Australia-wide
$2,086
$1,688
$1,644
21.1%
30.4%
26.7%
$1,987 23.4%
NT QLD WA SA NSW VIC
TAS
$1,545 26.2%
ACT
$2,619 $1,688
20.1% $1,639
36.1%
32.5% $1,389 23.6% Median weekly family income
Proportion of family income required to pay loan
REDUCED REGULATORY BURDEN OUR GOAL, SAYS GOV’T regulatory requirements are driving higher costs for business, with industry estimates suggesting financial services are expected to spend US$70bn (A$92bn) or more on compliance per year. Assistant Minister to the Treasurer Michael Sukkar said the government had “tried to reduce the regulatory burden on business and community. To date, we have been successful in reducing that by some $6bn”. INCREASING
FE AT URES
COVER STORY
RETURN OF THE NON-BANKS
will experience a resurgence back to those levels. Responding to the size of this uptick will be the number one challenge for the non-bank sector. Questions remain around APRA’s new powers But there is one thorn in the nonbank expansion plan that it is worth being mindful of. In the May federal budget, the Turnbull Government announced it would provide APRA with $2.6m over the next four years to allow it to exercise new powers in regard to the provision of credit by non-ADIs. In the brief three paragraphs outlining this investment in the budget, the government gave few details about what these new powers would entail, what they were intended to achieve and how they would affect the mortgage lending market. “These new powers complement APRA’s existing macroprudential powers. This funding will also allow APRA to collect data from these entities for the purposes of monitoring the non-ADI lending market,” the budget paper says. The government went on to say that these changes would form part of a “modernisation of the Banking Act 1959 to better support APRA’s use of the Banking Act for macroprudential purposes”. This will include making clear APRA’s responsibility for using geographically based restrictions
With banks facing increased restrictions and tighter lending standards, non-bank lenders are picking up more market share and are readying for a major comeback, explains La Trobe Financial’s chief investment officer, Chris Andrews
14
www.brokernews.com.au
‘tap on/tap off ’ risk. There is so much uncertainty created by this regulatory direction that perhaps it represents a generational shift
insurance companies and building societies held roughly 23% of the residential lending market share. Today, non-banks hold only 3–4%
“We are trying to build ahead of the curve rather than behind the curve, so our fast turnaround times are not impacted and we remain the number one shop for our broker clients” in what banks and non-banks will contribute to this very large market in the future,” he adds. Back in the late 1970s, life
($10bn per year) of the $350bn market, Andrews says, while banks absorb the rest. But he believes non-banks are on the upswing and
NON-BANKS’ SHARE OF INVESTMENT AND INTEREST-ONLY RESIDENTIAL LOANS IS ON THE RISE Source: APRA and Moody’s Investors Service
55% A
50%
B
45% 40% 35% 30% 25% 20% 15% 10% 5% Q4 2016
Q3 2016
Q2 2016
Q1 2016
Q4 2015
Q3 2015
Q2 2015
Q1 2015
Q4 2014
Q3 2014
Q2 2014
Q1 2014
Q4 2013
Q3 2013
Q2 2013
Q1 2013
Q4 2012
Q3 2012
Q2 2012
0% Q1 2012
lenders have perhaps entered a new golden era. So far, 2017 has been an outstanding year for non-banks, with many seeing loan volumes increase by roughly 25% because of recent lending restrictions placed on APRA-regulated entities, says La Trobe Financial’s chief investment officer, Chris Andrews. With banks facing increased regulatory burdens and capital requirements, the service gap left behind by the major lenders continues to grow. And as banks steer their appetites towards more vanilla-type loans, large segments of the borrower market remain untapped, primed for specialist lenders who can offer high-quality solutions in this new environment. “In our view, the market need for this type of specialist lender is currently in what is likely to be an extended growth phase.” Furthermore, the regulatory pushback on the banks is probably not going to wind down any time soon, creating ripples of tension in the broker-bank relationship, Andrews says. Barely a week goes by without repricing by one of the banks on their products, or news that they have removed a loan product, and brokers are just having to deal with it. Brokers were up against a similar attitude during the GFC, Andrews says, when several banks closed their broker operations entirely, causing much consternation for brokers and their borrower clients, who were left high and dry. “At the moment, brokers are looking for a lender whose policies and pricing are consistent and steady – and not subject to NON-BANK
Origination/Application quarter Legend
ADI investment loans to all ADI loan approvals Non-bank investment loans to non-bank RMBS portfolio* ADI interest-only loans to all ADI loan approvals Non-bank interest-only loans to non-bank RMBS portfolio*
Notes: Key to previous measures to slow the housing market A: Origination, security and stress test guidance and 10% speed limit for housing investment loans B: Mortgage risk weight changes On 31 March 2017, APRA also introduced a 30% limit for interest-only loans * Percent of origination in each quarter based on our rated non-bank RMBS loan-by-loan data
on the provision of credit where appropriate. “Whilst this announcement must be accepted at face value, the lack of detail provided to date represents a significant uncertainty on the regulatory landscape. As with all such measures, the devil lies in the detail,” Andrews says. As such, the non-bank industry is grappling with a few unknowns around this. The question is: will non-ADIs be regulated in the same way as ADIs? “The ability of non-ADIs to lend to segments that are out of favour with the banks is an important market outlet … and ensures that the composition and risk profile of the Australian mortgage market does not become too concentrated and homogenised,” Andrews says. Non-ADIs are funded by often-sophisticated investors within entirely separate regulatory frameworks, and the existence and integrity of these frameworks is called into question if APRA morphs into a “super-regulator” overseeing all credit activity in the country, Andrews explains. “Indeed, the presence of superregulators in other jurisdictions has been criticised as contributing to the global financial crisis by consolidating too many functions into the one regulatory remit,” he says. What people should know, however, is that just because non-banks haven’t traditionally been under APRA’s purview doesn’t mean the non-ADI sector is running rampant with the rules. “In our view, any in-depth analysis of the non-ADI sector will show credit standards as robust and responsible as any banks’,” Andrews says. La Trobe Financial, for example, has for many years benchmarked its credit program on the best that the ADI sector has to offer, he says. APRA’s Prudential Practice Guide on residential mortgage lending, which encapsulates the regulator’s views on sound lending practices, is consistent with La Trobe Financial’s internal standards, Andrews says. Growing with brokers in mind La Trobe Financial is working on expanding its third party distribution channel this year, which includes brokers and financial advisers, and it expects to be doing business with
Chris Andrews, CIO, La Trobe Financial
more than 2,000 brokers by next June, an increase of 500 brokers. “We respect the importance of these channels and have always supported finance brokers with a clear no-clawback policy on commissions,” Andrews says. As the operation grows, La Trobe Financial will be “recalibrating” its operations to ensure brokers’ needs continue to be met. The credit specialist is currently in the process of onboarding additional upfront sales staff and is making sure the back end is fully resourced to cater to growth. “We are trying to build ahead of the curve rather than behind the curve, so our fast turnaround times
are not impacted and we remain the number one shop for our broker clients to come to for service,” he says. La Trobe Financial has been helping brokers succeed in underserved markets since 1952, and it plans to keep delivering on that promise as times change. “In terms of disruption, 65 years in the space has taught us that change is constant,” Andrews says. And there’s no doubt there are more unknowns and uncertainties on the horizon. Regulatory change will continue to affect all participants in the credit market, and technological innovation will deliver new
efficiencies. But from where La Trobe Financial is positioned, the outlook is positive. Andrews believes change will most likely result in new and higher service offerings for clients, rather than wholesale disruption of industry participants as is sometimes suggested. “I really am committed along with all of my colleagues to seeing the resurgence of the non-banks and assisting Australian consumers get a better level of services and products than available elsewhere,” he says. “Working in this environment is both challenging and stimulating – it’s very rewarding, and the future looks bright.” AB www.brokernews.com.au
15
FE AT URES
NE WS ANALYSIS
UNDER DARK CLOUDS Mortgage fraud is back in the public eye again after it was revealed in May that ASIC executives are investigating how to proceed with a loan fraud review following a significant number of enforcement outcomes October, mortgage brokers were thrust under a dark cloud of suspicion after a report on loan fraud within the third party channel was released by UBS. As expected, industry associations criticised the report and disputed its findings; it filled the headlines of mainstream news reports and prompted regulators to acknowledge that mortgage fraud is a pressing issue that it’s grappling to address. The UBS report was far-reaching, tapping into responses from 1,228 mortgage holders through an anonymous 63-question online survey, and its findings cast a negative light on brokers. One statistic stood out in particular: of those who had secured a mortgage via a broker in 2016 and had misrepresented elements of their application, 41% said they’d done so on the suggestion of their broker. When the news of the report ran its course and mortgage fraud was no longer front-page material, there was probably a collective sigh of relief within the industry. But as with any contentious issue, it’s not so easily put to bed. In fact, it still remains a problem, as ASIC executives told an Economics Legislation Committee at the end of May. It was there that ASIC revealed it was investigating how to proceed with a larger loan fraud project that would look at tackling the issue more strategically. “Responsible lending, home loans and particularly mortgage broking have been an area of focus for ASIC for some time now,” Michael Saadat, ASIC’s senior executive leader, deposit takers, LAST
16
www.brokernews.com.au
credit and insurers, told Australian Broker in a written response. “We had a number of significant loan fraud enforcement outcomes, and we felt a broad review was
loan applications. “This has included misconduct by mortgage brokers, introducers and lenders’ staff,” he said. Between 2014 and 2016, ASIC
“We need a more systemic look at how we can reduce the incidence of loan fraud and how we can work with lenders to improve their procedures for detecting fraud” Peter Kell, deputy chair, ASIC necessary to look for trends, and see how prevalent it is in the industry.” Saadat said the regulator’s enforcement in this area had covered false documents and false information being used to support
banned 29 individuals or companies from providing credit services, 20 of whom were banned permanently. Over those two years, nine people were convicted of fraud or dishonesty offences related to the provision of false and misleading
information or documents to lenders in client loan applications. It’s not only ASIC and UBS exposing this dirty laundry. According to Veda’s 2016 Cybercrime and Fraud Report, falsifying personal details is the most common type of fraud. It said fraudulent personal loan applications represented 16% of total fraud, while fraudulent mortgage applications made up 13%. Veda, a data analytics company and a leading provider of credit information and analysis in Australia, calls growth in fraud through the broker channel an ongoing concern. Broker channel fraud made up 15% of all credit application fraud and grew 25% in H2 FY2016, Veda’s report said, putting it higher than the 13% of fraud sourced through bank branches. ASIC’s deputy chair, Peter Kell,
BROKERS ARE A LEADING CHANNEL SOURCE FOR FRAUD Source: Veda 2016 Cybercrime and Fraud Report
15.08%
12.78%
Broker
Branch
3.74% Dealer
3.16% Phone
0.29% Direct marketing
3.95%
4.02%
Other
Lender
56.94%
0.03%
Online Note: Channel source of fraud depicted as a % of all fraud
told the senate committee that some specific patterns had emerged that “indicate to us that we need a more systemic look at how we can reduce the incidence of loan fraud and how we can work with lenders to improve their procedures for detecting fraud”. Kell said fraud cases tended to fall into two categories – they could either be an individual broker who is committing fraud because they may, for example, have a gambling problem, or more elaborate cases of organised fraud involving amounts of well over $100m. “It is one of those things where you will always need to be alert and keeping an eye on it,” Kell told the committee. “We are seeing different approaches by lenders as to how they detect it. We think if there is an ability to share some of those learnings and to look at how that can be undertaken, that will help minimise [it].” The root of the problem All the blame of mortgage fraud cannot be foisted onto mortgage brokers, however. Borrowers themselves are a big problem. Of the UBS survey’s respondents, 28% said their applications were not factually accurate; half of these said they’d over-represented their household income and 26% said they’d under-represented their living costs, which has traditionally been an important indicator for assessing borrowers’ serviceability. Another troubling finding is that more of the respondents who secured their mortgage via a broker misrepresented documentation
(32%) than those who used the bank channel (22%). As UBS’s analysts point out, factual accuracy on mortgage applications is important, particularly in today’s environment of elevated economic risk in which house prices are rising and household indebtedness is ballooning. In addition, mortgages now represent 62% of major banks’ loan books. “We believe it is more important than ever that the banks tighten their mortgage underwriting standards and ensure applications are factually accurate. We continue to see the mortgage broker network as a potential area of weakness in this process,” the UBS analysts wrote.
into two precise categories, saying this is “manifestly incorrect”. “The fraudulent mortgage broker is a dying breed,” he says. That’s because together with data mining advancements by Equifax, cautious lenders and aggregators, and the rise of email communications between borrowers and brokers, it is made “patently clear to any broker that it is impossible to get away with fraud on a long-term basis”, Bransgrove says. As for doing so on a short-term, one-off basis, Bransgrove says there is simply not enough incentive for any broker to stick their neck out and risk their career and their trail commission. “All that remains are the very
“[Fraud] is still with us and we must be vigilant to continue to monitor and seek out those who would seek to break the law in this fashion” Peter White, executive director, FBAA But lawyer Matthew Bransgrove, author of Avoiding Mortgage Fraud in Australia, says the vast bulk of mortgage fraud is carried out by borrowers. He says his law firm is consulted by brokers all the time, who are constantly weeding out mortgage applications where false information has been provided by the borrower. Bransgrove also takes issue with Kell pigeonholing mortgage fraud
few personal implosions you see in any profession,” he says. “There might be the odd mortgage broker with a gambling or substance abuse problem who carries out a mortgage fraud as an act of desperation. In those circumstances it would literally be the broker using his knowledge to conduct an imposter fraud.” Likewise, FBAA executive director Peter White says the reason he challenged the findings
ARE MORTGAGE APPLICATIONS FACTUALLY ACCURATE? Source: UBS Evidence Lab
Mortgages secured by broker, 2016 vintage Completely factual and accurate
68%
32%
Not completely factual and accurate
Broker suggested I misrepresent
41% 59% Broker did not suggest I misrepresent Note: Responses based on mortgages secured by brokers in 2016
www.brokernews.com.au
17
FE AT URES
of the UBS report back in October was because it’s easy for someone to hide behind an anonymous survey and blame someone else for their misdeeds when there are no repercussions. Why would a broker risk their livelihoods or put their families on the line by misrepresenting or overstating a borrower’s income? White asks. While in White’s opinion there is no evidence to suggest that mortgage fraud is on the rise, he realises that one can’t claim ignorance and say it doesn’t exist. He says that’s why ASIC’s policing role to minimise the risk of any potentially fraudulent behaviour is so important. “None of us want any such people in our industry. It is still with us and we must be vigilant to continue to monitor and seek out those that would seek to break the law in this fashion.” Detecting fraud So how should brokers, lenders and regulators tackle this problem? “While banks have tightened underwriting following APRA’s ‘sound lending’ guidance, it does not appear to have prevented applicants ‘stretching the truth’,” UBS’s analysts wrote. Therefore UBS suggested “more rigorous auditing of applications appears essential, especially via the broker channel”. Bransgrove says that is already underway; it’s just that brokers don’t get recognised for it. “They get no credit for it and there is no facility to report it, and there is no mechanism for ASIC to prosecute it.” The onus of detecting fraud is not just brokers’ responsibility either. While brokers may be the first gatekeepers a borrower encounters, it’s lenders who have the advanced tools for detecting fraud, namely the Equifax shared fraud database that flags questionable applications, Bransgrove says. “This means that brokers are often fumbling in the dark in the effort to detect sophisticated fraud.” 18
www.brokernews.com.au
Increased persecution of brokers isn’t going to curb mortgage fraud either, if, as Bransgrove states, the majority of it is being done by borrowers. So what brokers need are more tools to expose fraudsters and take them out of circulation once and for all. He says ASIC should provide brokers with access to a database that allows them to report the fraudulent loan applications they come across. APRA chairman Wayne Byres told another Economics Legislation Committee last October that a large part of the agency’s work around fraud is to try to strengthen the way banks assess borrower serviceability. “Part of that work is strengthening the verification that banks undertake when they are looking at how the borrowers are able to service a loan,” he said. But when a senator asked if APRA audited this, Byres said they had not yet. “But we have told the larger institutions that we will be asking them to have their external auditors do a review of what are essentially fraud control mechanisms to ensure that there are mechanisms in place and those mechanisms are working,” he said. According to Bransgrove, there needs to be more cooperation between lenders and brokers, and he believes there is a strong argument for why brokers should
illuminating details. At the May committee meeting, Saadat elaborated on the intent of the project, saying that it was meant to “look more broadly than at isolated or individual instances of loan fraud to come up with a
“The vast bulk of mortgage fraud is carried out by borrowers” Matthew Bransgrove, lawyer and expert in mortgage fraud have access to the Equifax shared fraud database as well. The loan fraud project For now, ASIC’s prospective loan fraud project is still taking shape behind closed doors. The regulator is carefully considering what the project will look at and cover, but it hasn’t released many
strategy that can deal with it more comprehensively”. He also acknowledged ASIC’s shortcoming: it only has so many resources and it cannot take action on every single allegation brought forward. In his response to Australian Broker, Saadat said: “We are still scoping the loan fraud project, and
at this stage we are looking across all types of loan fraud.” ASIC receives information on fraud from a number of channels, including lenders, aggregators and brokers, industry associations, other regulatory agencies, consumers and consumer advocates, Saadat said. “We are working closely with industry on these matters. Lenders and brokers are obliged to take steps to ensure the information they are using to approve loans is accurate.” White sees ASIC’s loan fraud project as part of its duties as the industry’s policeman to ensure that those few who may take advantage of the system are caught and kept out of the industry. “At the end of the day, by understanding where there may be issues helps us all to focus on resolving and endeavouring to eradicate them,” he says. AB
MISREPRESENTATION: BANKERS VS BROKERS Source: UBS Evidence Lab
Over-represented household income
Overdeclared other assets
5% 18%
11% 14%
Under-represented other financial commitments (eg mortgages, personal loans, credit cards)
12% 18%
18% Others 8%
25%
Under-represented living costs
26%
36%
Would rather not say
29% 0% 5% 10% 15% 20% 25% 30% 35% 40%
Secured with bank
Secured with broker
www.brokernews.com.au
19
FE AT URES
OPINION
NOT ONE APPROACH FOR ALL With homeowners and homebuyers facing further blanket regulations on lending conditions, Don Crellin, managing director of Resolve Finance, explains how this could be detrimental to property markets outside of Sydney and Melbourne broadly supportive of regulatory intervention aimed at ensuring we have a healthy financial system. However, this is not only challenging for our regulators but also for our banks to respond while trying to best meet the needs of their customers. Our market is facing a number of simultaneous factors that we haven’t experienced before. While house prices are rising sharply in Sydney and Melbourne, they’re trending downwards in Perth. Rental vacancy rates and rental prices are also trending differently across the country. It’s clear that the broader Australian market isn’t behaving in a uniform way. We then need to include other factors such as historically low interest rates being sustained for a prolonged period of time. While the latest ABS data shows the acceleration in residential property price growth in Australia in late 2016, it’s dominated by Sydney and Melbourne’s higher activity, larger markets and continued strong price growth and is not an accurate indication of what’s happening in other capitals. Dampening the demand in specific market segments will be paramount to ensure a healthy and sustainable property market as the national government continues to encourage APRA and ASIC to put their weight behind blanket regulations on investment lending and interest-only lending. Sydney and Melbourne may need such restrictions, but a targeted and further refined regulatory approach is more appropriate to ensure that a broad-brush approach does not have adverse impacts on struggling markets outside these booming capitals. We have seen this play out in the New Zealand market when Auckland prices were spiralling upwards. Auckland property had grown to the extent that it was sitting at seven times the average household income in comparison to the rest of the country, where it was only about four times as much. Regulators approached the challenge by applying restrictions based on specific locations to normalise the market and
protect it against a financial system shock. It is understandable that regulators are concerned about the growing financial and economic risks in certain markets, along with the increasing household debt and low wages in a rising interest rate environment. To use a broad-brush approach like interest rates to curb activity is a relatively
I’M
20
www.brokernews.com.au
conditions for some Australian housing markets, but that hardly fits the bill for Western Australia. Increasing borrowing costs and tightening lending standards for residential borrowers in WA is the wrong policy for the market and risks damaging housing conditions in the west.” To understand the risk of dampening an already fragile market, it’s important to look at what the regulators have already put in place and what the banks’ response has been. Limits have been placed on the banks to cap their investment lending books to no more than 10% growth. In addition, APRA and ASIC (via the responsible lending provisions) have also jointly focused on interest-only lending and limited interestonly loans to 30% of new residential mortgages. They have emphasised the banks’ requirement to more carefully scrutinise those customers with higher LVRs who request interest-only payments. In turn, most banks have increased interest rates for investment loans and most have also now increased the rate for interestonly loans for both new and existing
Hitting struggling markets outside of Sydney and Melbourne with even tighter controls will be detrimental to Australia’s economic future
Don Crellin Managing director of Resolve Finance, a full-service finance provider with offices in Perth, Melbourne and Bunbury
blunt instrument with much wider impacts affecting both new and existing borrowers. And while macroprudential tools can be more specific in that they focus on new lending activity, individual markets and asset classes, it’s important to recognise that policies uniformly applied across all states aren’t the answer. The differing property markets of each state are highlighted in the latest ABS data: in the year to the December 2016 quarter, dwelling price growth remained fastest in Melbourne (+10.8%), followed by Sydney (+10.3%). Dwelling prices also grew over the year to the December 2016 quarter in Tasmania (+8.8%), the Australian Capital Territory (+5.5%), and Queensland (+3.8%). Dwelling prices continued to decline in Western Australia (-4.1%) and the Northern Territory (-7.0%). Since this data was released, WA’s Housing Industry Association executive director John Gelavis has been understandably vocal, explaining that the last thing WA needs is tougher home lending conditions. Gelavis has said: “It’s all well and good to talk up the need to tighten lending
customers. Regulators have also been providing guidance in other areas, such as including responsible lending provisions specific to the disclosure of a customer’s living expenses and how these are verified. The challenge is that when regulators provide guidance only rather than policy, banks react in very different ways. We now also see varying policies starting to emerge in regard to high LVR caps, how the broker is required to assess and verify living expenses, construction lending, and so on. Some banks have also tightened their assessment criteria for investment loans with higher LVRs and interest-only loans. If additional restraints take on the rumoured form of growth caps on LVRs, interest-only lending and further speed limits on investment lending, why not focus these tools on the specific markets where dampened demand is required and avoid impacting already struggling states? With a central, sustainable property market being key to Australia’s economic future and everyone’s end goal, surely it would make sense to recognise the significant differences in each current market and address them accordingly. AB
IN THE NE WS
GENWORTH POACHES BANKER Suncorp executive Steven Degetto gets set to take on a leadership role with the major LMI provider during a tricky financial time for the insurance giant profit after tax dipped in the first quarter, its underlying net profit increased by 10.7% to $68.3m in the first quarter of 2017 compared to $61.7m recorded in the first quarter of 2016. “Our results in the first quarter of
Genworth told Australian Broker. He will take up his position at the insurance provider in September. Once he does, he will be responsible for marketing and distributing Genworth’s products and services “to meet the evolving needs
“Steven brings to Genworth extensive business development leadership and experience in residential mortgages” Georgette Nicholas, CEO, Genworth
Steven Degetto, Genworth’s incoming chief commercial officer
Suncorp executive Steven Degetto has been appointed chief commercial officer at Genworth, one of Australia’s leading providers of lenders mortgage insurance, the company announced in early June. The recruitment was a bit of positive news for Genworth after it reported in May that its net profit after tax had tumbled 22.4% in the first quarter of 2017. Its net profit after tax was $67.3m in the first quarter of 2016, compared to $52.2m this year. It is also a big move for Degetto, who is currently head of life and wealth intermediaries at Suncorp. Genworth is under pressure as lenders move away from high-LVR loans as a result of increased regulatory scrutiny. APRA has limited new interest-only lending to 30% of total new residential mortgage lending, and within that has also placed strict limits on LVRs above 80%. According to the most recent statistics from APRA, $376bn worth SENIOR
of loans were approved in 2016. Of these, $31bn worth had LVRs over 90%, while $52bn had LVRs between 80% and 90%. As a result of these changing market dynamics, Genworth reported that its underlying net profit after tax in 2016 was $212.2m, down 19.8% compared to 2015, and new insurance written had declined by 18.4% to $26.6bn. However, while the company’s net
the year were in line with our expectations,” Genworth CEO Georgette Nicholas said in her address at the company’s AGM. “Our profitability remains strong despite revenue being pressured by a smaller high loan-to-value ratio market. At this time, our full year 2017 guidance is unchanged.” She said Genworth was supportive of regulatory measures that promote prudent residential mortgage lending standards. “We are working to develop solutions with policymakers and regulators that reinforce the importance of LMI to the Australian mortgage market and stability of the wider financial system, especially its value in helping first-time homebuyers,” she said. Degetto is still serving out his notice at Suncorp, a spokesman for
of lender customers”, the company said in a statement. He will also join Genworth’s senior leadership team and executive committee. “We are very excited and pleased to have an individual with Steven’s experience join our team as the new chief commercial officer,” Nicholas said. “Steven brings to Genworth extensive business development leadership and experience in residential mortgages as well as strong commercial acumen and an unwavering customer focus.” Degetto has worked at Suncorp since 2012, helping to drive its growth strategy and becoming a well-known and well-regarded figure in the third party industry. He has previously held senior positions at Macquarie Bank and Commonwealth Bank. AB
GENWORTH’S NET PROFIT FALLS Source: Genworth, first quarter 2017 earnings
Financial performance measures (A$m) 120
113.5
100 80
85.0 67.3
60
61.7
-4.9%
107.9
3.8%
88.2
New insurance written (A$bn)
10.7%
68.3
Gross written premium
-22.4%
52.2
40
Reported NPAT Underlying NPAT
20 0
Net earned premium
6.2
1Q16
9.7% Quarterly
6.8
1Q17
www.brokernews.com.au
21
22
www.brokernews.com.au
PEOPLE
Have an interesting deal? Had a particularly difficult or interesting deal? Why not share it with us? Email:
Otiena.Ellwand@keymedia.com.au
A BIG DEAL
prior to and as the building company was going bankrupt. My biggest concern for the clients was that they had already paid for lenders mortgage insurance on the vacant lot with NAB, which would not be refunded. While they would have had to pay an additional top-up on their LMI with NAB, any refinance with another lender would mean that they would have to pay the full amount of LMI all over again on the whole loan amount. I discussed this with the clients over several weeks and advised them again to try to save as much money as they could while waiting on the outcome of the building company’s bankruptcy. While we were waiting on that, I also helped them find other builders who were prepared to give them a quote on a house that was similar to their original dream design.
An application declined, a bank’s lending criteria changed and a building company gone bankrupt. Susan Lepidi, director of The Local Loan Company, knows what a challenging deal looks like
THE FACTS
Loan size $1,148,376
Loan term 30 years
Client Couple in their 30s
Goal Dream home
Lender CBA
been reduced and, more importantly, NAB’s lending criteria had also changed. NAB would no longer lend to people in the suburb of North Coogee. To add to this, while we were dealing with a
THE SCENARIO
My clients purchased their dream block of land in a coastal suburb west of Perth through NAB in August 2015. The loan that was required to complete the land transaction was $557,000. Over the next few months my clients prepared to build their dream home, and looked for a builder that would bring this to fruition. In February 2016 we put together an application to NAB asking for an increase of $600,000 so the clients could begin construction. Unfortunately, even though the female applicant had worked for the same company for five years, the assessor was uncomfortable with her employment status as she had only gone back to working full-time for two months. The application was subsequently declined, but the assessor advised that after six months in her full-time role he would be happy to re-evaluate the couple’s application. I advised the clients of the outcome and told them that after six months of being full-time the bank would be happy to revisit their application. We also discussed that during this time they should try to put more money away towards their savings to help reduce the amount they needed to borrow. Later that year, in September, we put the application to NAB again; however, at this point, the market conditions had changed. The value of their block had
Location North Coogee, Perth
THE TAKEAWAY
It seems that there was a silver lining for my clients after all. As luck would have it, several months later the old building company was bought out and the new owners were prepared to honour all the original contracts. From this stage it took another three months for the new builders to prepare the plans, specifications and contracts. After more than 12 months of working
We put the application up to NAB again; however, at this point the market conditions had changed. The value of their block had been reduced and, more importantly, NAB’s lending criteria had also changed shortfall in valuation and NAB’s lending criteria changes, the building company the clients planned to use went bankrupt. This just added another layer of complication and stress to the deal. The clients had already signed the building contract and had paid a deposit. Consequently, after exhausting all avenues with NAB, we had to withdraw the application. THE SOLUTION
Susan Lepidi Director of The Local Loan Company
During this ordeal, the clients were so desperate to build their dream home that they asked me to see if there were any other options available to them with a different lender. This all happened
with my clients through what would have to be one of my most challenging deals yet, in April this year we settled a loan through CBA. Although my preference would have been to stay with NAB, the valuation came in low and the bank still had restrictions on the area. On the bright side, my clients did take my advice in regard to savings and managed to reduce their LVR to below 90%. My clients were so thrilled with the outcome they couldn’t thank me enough. For me it was very fulfilling to have achieved the end goal for my clients. It was challenging because of the constant changing landscape of the bank’s lending criteria. AB www.brokernews.com.au
23
PEOPLE
Get involved in the discussion Share your thoughts at
brokernews.com.au
FROM THE FORUM
Top comments from trending stories on brokernews.com.au
ASIC LEVY TO HIT BROKER CREDIT REPS
GOV’T PASSES ASIC INDUSTRY FUNDING BILL
Incoming regulations from ASIC may mean credit representatives will be slugged with additional costs as large brokerages and aggregators deal with extra fees. The ASIC Supervisory Cost Recovery Regulations will commence in the second half of the year with the regulator attempting to recover costs of operations from firms and individuals in the credit industry and other sectors under its jurisdiction. ASIC will levy subsectors at a flat rate where costs remain stable, while introducing fluid levies in other sectors where regulatory costs vary significantly.
The ASIC Supervisory Cost Recovery Levy Bill 2017 has passed the Senate, allowing the government to introduce an industry funding model to improve consumer outcomes in the financial services sector. The bill aims to improve equity, encourage regulatory compliance, improve ASIC’s resource allocation and enhance ASIC’s transparency and accountability. The industry funding model delivers on a key recommendation of the 2014 Murray Financial System Inquiry as well as the 2013 Senate Inquiry into ASIC’s performance.
Government generally destroys any industry they get involved in with over regulation and red tape which increases costs for the end user. The problem we have is while the fees we pay will go up, our commissions may go down at the same time. Why this is exactly what the big banks want. Mike on 01/06/17 at 9:28 AM
“Improving equity, as only those entities that are regulated by ASIC and create need for regulation will bear its costs, rather than ordinary Australian taxpayers” … And these regulated entities don’t pay any taxes or bear the extraordinary costs of all the red tape imposed on them too? Where are those taxes going? Alfred Andrews on 15/06/17 at 5:26 PM
Just another bank-ordered underhanded tactic to make this industry as difficult as possible for existing brokers, and as unattractive as possible for new entrants. Broker on 01/05/17 at 9:44 AM
Don’t brokers already collect and pay taxes that indirectly support ASIC’s costs currently and provide their staff with a job? If brokers disappear, as it seems is ASIC’s wish with the way they are handling this, then those current taxes would not be retained. And from what they claim, that brokers are taking up so much time and cost, with brokers gone, it seems many ASIC staff would be out of a job. … Let’s pose another question – If broker credit reps are being slugged, are banks being slugged for their loans officers too? Aren’t they effectively credit reps? Oh no, that’s right – that would be bad for the banks. Only picking on brokers? Chris C on 02/05/17 at 9:32 AM
Good point Chris, if the bankers are credit reps as well shouldn’t this be taken into account? Or is this what the bank levy is aimed at targeting? They still haven’t clearly defined what the bank levy is going to be charged on, they simply have a figure of $6.2bn, but still don’t know how they got to that number. Definitely an uncertain time to be involved in the finance industry. That along with a flat fee commission structure that has been recommended in the recent finance industry reviews could completely shift the dynamics of our industry, effectively leading the way for a new “mass consumer” competitor to intervene with a “low credit rep” approach. “Apple Bank? Google Bank?” tootrue on 02/06/17 at 10:27 AM
24
www.brokernews.com.au
It is without a doubt that whatever fees or charges are forced onto brokers, they MUST and WILL be passed onto the consumer by way of up front fees or any other appropriate manner. Most of us have the ability to charge clients for clawback costs and we have the ability to recover this new cost. If we don’t have a provision for recovery of clawback costs built into our documentation, we should. If we, as brokers, are not advising our clients that these fees could be recovered (if they refinance or sell, etc., in the specified time frame) then we are doing ourselves a great injustice and further allowing the banks to control our income. Admittedly, clawbacks don’t happen often but they hurt financially when they do. With this new tax on brokers, we can accept it and do nothing or tell the client from the very beginning that this is purely a government fee, which must be passed onto the consumer. It took ages for the real estate industry to charge upfront for searches and advertising, but they finally did, and in most cases they are better off for it. Conveyancers were forced into identifying their clients and to do that they immediately set up a fee of around $50 per client just to complete the ID form. As brokers, we want some say and control of our financial future. Alfred Andrews on 15/06/17 at 5:26 PM
Great, more money for ASIC so they can tell us how we should structure our own finance. Just what we need. They treat Australian mortgage holders as fools and brokers as liars and do their level best to destroy what was once a good industry. Garry C on 15/06/17 at 10:21 PM
CAUGHT ON CAMERA One of the major challenges affecting the financial services sector is regulatory compliance. Regulatory technology, or regtech, is helping in many areas of compliance by interpreting legislation, designing new processes and managing data. The regtech space is constantly evolving and the implementation process is not without its challenges. On 7 June, the diverse innovations and unique obstacles affecting this industry were the topic of conversation at InnovationAus.com’s Regtech Australia forum in Sydney. The event featured speakers from Tyro, Google Australia, AUSTRAC, Red Marker, Westpac and ASIC, among others.
Jost Stollmann, founder, Tyro Fintech Hub
From left: Rebecca Lim, Mark Adams, Murray Bruce, Liming Zhu
Tony Prior, director – compliance, AUSTRAC
Participants at InnovationAus.com’s Regtech Australia forum
Assistant Minister minister to the Treasurer treasurer, Michael Sukkar (right)
Rebecca Lim, chief compliance officer and group general counsel, Westpac Group
Matt Symons (left), co-founder, Red Marker; Mark Adams, senior executive leader strategic intelligence, ASIC www.brokernews.com.au
25
DATA
SOUTH AUSTRALIA
NSW SPOTLIGHT
Looming economic woes leave Adelaide’s growth potential up in the air Adelaide has seen a rough few years, and unfortunately this trend looks like it will continue into the next five years. “That’s a very low capital growth city in general, and the rationale behind that is net migration over the last 30 years realistically has been almost zero. So there’s been an equal amount of people leaving as there has been coming to that city,” says Paul Glossop, director of Pure Property Investment. “It has created an issue with any additional demand in that market. No data that we’ve seen really suggests there’s going to be anything to heighten Adelaide as a higher demand area for people looking for jobs, especially with the Elizabeth and Holden manufacturing plant closures.” These closures are set to take effect in 2018, which means the repercussions should be felt all the way into 2019 and beyond.
Area
Type Median value
HOUSING MARKET TAKES A TUMBLE Affordability is causing the housing market to stumble as high house prices begin to take a toll on Sydney’s performance the strong performance of the Sydney market, rising values are making it increasingly difficult for buyers to afford property. Thus, apartments are coming to the fore. “For a lot of people, units have become the only option to enter into the market. They basically can’t afford a house,” says Cameron Kusher, research analyst at CoreLogic. “Changing demographics and the prevalence of single-person households are certainly a contributing factor, and that’s probably another reason why you’re seeing a stronger performance in the unit market. Also, Sydney’s been approving more units for construction than houses for the last two decades.” Apartment stock is increasing, especially in the metro areas – the inner city, Parramatta and Sydney Olympic Park. Sydneysiders have become accustomed to unit living, which makes the unit market stronger here than in other capital cities. Another way that buyers are handling the affordability issue in the metro is by looking beyond Sydney itself into other less expensive markets. For instance, Parramatta, which is regarded as Sydney’s second CBD, is in line to receive a major urban overhaul in the next few years. The construction of Parramatta Square is expected to bring new life into the commercial area; as a result, a significant increase in population in the near future is anticipated. “There will be a substantial increase in jobs in Parramatta, with approximately a 33% increase in office space between 2016 and 2021,” says Rich Harvey, CEO of Propertybuyer. Ged Rockliff, head of residential at Savills DESPITE
Quarterly
12-month
growth
growth
Adelaide
H
$450,000
3.4%
3.5%
SA Country
H
$288,500
1.2%
1.8%
Adelaide
U
$363,000
3.7%
3.6%
SA Country
U
$200,000
9.3%
0.8%
VICTORIA
Melbourne’s house and unit markets are moving in two different directions, with houses in highest demand Melbourne recorded a first when its median house price surpassed $800,000 over the March 2017 quarter, boosted by thriving auction and private sale performances. “Melbourne’s property market is experiencing a perfect storm, with price increases driven by strong buyer demand, solid population growth, record-low interest rates, and low stock on market,” says Joseph Walton, president of the Real Estate Institute of Victoria. “Competition for homes, particularly in Melbourne’s inner and middle rings, has encouraged more vendors to take their home to market, with multiple auction records falling this year.” House market growth has come primarily from middle-ring suburbs, such as Templestowe, although outer suburbs like Cranbourne North and Kilsyth were among the top growers in the city as well. House prices also sailed past $1.5m in the premium suburbs of inner Melbourne. Type Median value
Quarterly
12-month
growth
growth
The NSW market is extremely diverse. However, the Sydney property price boom, which started in 2012, has had a ripple effect across most of the state I expect to see this ripple effect intensify throughout 2017. The Sydney satellite regions like the Blue Mountains, Wollongong and Central Coast have been the primary beneficiaries of Sydney’s boom as people migrate in search of more affordable housing. I also expect that these markets, and more affordable Sydney markets, will benefit strongly from the introduction of the housing affordability package on 1 July. First home buyers can now avoid a significant stamp duty burden for purchases under $800,000. The impact of government regulation on our financial institutions should not be underestimated. Recent data from CoreLogic suggests that 46% of all residential lending in NSW is for investment purposes, which is a high proportion in historical terms. Federal government regulations on investment loan volumes and interest-only payment quotas are already making life less comfortable for investors. Aaron Sainsbury Mortgage adviser at Smartline
HIGHEST-YIELD SUBURBS IN NSW Suburb
Area
BROKER PERSPECTIVE
Type
Median price
Weekly median advertised rent
Gross rental yield
Broulee
H
$485,000
$1,400
15%
Melbourne
H
$650,000
-2.3%
6.7%
Malua Bay
H
$464,500
$1,000
11%
VIC Country
H
$325,000
1.6%
2.6%
Broken Hill
H
$107,500
$230
11%
Melbourne
U
$480,000
-4.0%
1.0%
Tuross Head
H
$395,000
$800
11%
VIC Country
U
$260,000
0.0%
1.6%
Sussex Inlet
H
$440,000
$750
9%
26
www.brokernews.com.au
OPPORTUNITIES AND KEY INFRASTRUCTURE
AUSTRALIAN CAPITAL TERRITORY
Canberra’s rising prices could be affecting affordability, with low supply acting as every buyer’s worst enemy
Express service trains
Mining communities
Westconnex
Circular Quay
Get out to the Blue Mountains faster with this new service
Additional program funding helps communities upgrade facilities
Final stage will provide vital link between M4 and M5 motorways
New Sydney CBD terminus will connect all modes of transport
Australia, adds that employment in Parramatta “is forecast to grow from around 157,000 to 186,000 [jobs] in the next four years”. Demand may also be spilling over into the Central Coast, the midway point between Sydney and Newcastle. Given the distance from Sydney, Central Coast properties are more affordable, while offering convenience for workers in either the capital or Newcastle.
This region has therefore been performing admirably, according to Oliver Myers Real Estate, and experiencing much infrastructure growth, with improved accessibility and new amenities. Both the residential and commercial sectors are reporting development throughout the area, meaning investors have the opportunity to get into a market with high potential. AB
SUBURB TO WATCH: CLOVELLY Median price (houses) $2,835,564
Median price (units) $1,273,257
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
16.0%
46.2%
61.8%
2.1%
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
21.1%
43.3%
58.5%
3.2%
Growth in Canberra’s house prices peaked over the March 2017 quarter, recording the highest rate among Australia’s capital cities during that period. “Canberra’s been a good performer; it’s had a couple of very good years, and it’s probably coming into its third strong year. There’s 3–6% year-on-year capital growth over the next three years,” says Paul Glossop, director of Pure Property Investment. For Glossop, decreasing rental yield would be the main problem for the property market since prices are continuing to rise. A factor contributing to this growth is that supply has not been catching up with the high demand, causing values to skyrocket in areas like Gungahlin and Belconnen. Thus, the suburbs outside of these regions could offer more opportunity for investors at present.
Area
Type Median value
Quarterly
12-month
growth
growth
Canberra
H
$640,000
-1.5%
5.0%
Canberra
U
$435,999
0.2%
2.4%
www.brokernews.com.au
27
DATA
QUEENSLAND
Experts put inner-ring suburbs on the ‘avoid’ list as unit oversupply cripples Brisbane’s inner city As the number of apartments under construction increases, pockets of Brisbane are feeling the effects of excessive stock. “In Brisbane, the areas of Fortitude Valley, Teneriffe, Newstead, South Brisbane and West End are seeing a massive surge in new unit supply at the moment,” says Cameron Kusher, research analyst at CoreLogic. “There’s clearly been an oversupply because properties sell for less than what they were purchased for. Now, people have been paying too much then having to resell it at a loss. I think we’ll continue to see [that trend] grow… I wouldn’t be surprised at all given that there’s a lot more stock under construction. So we’ll see higher levels of loss upon resale of units, particularly in the inner-city areas.” This situation is especially problematic due to the lack of job creation in these areas, according to Kusher.
growth
growth
Brisbane
H
$512,900
-2.3%
4.2%
QLD Country
H
$425,000
-1.2%
2.1%
Brisbane
U
$405,000
-2.4%
-2.4%
QLD Country
U
$373,000
-0.5%
4.0%
Sunshine Coast
RISING MARKET Adelaide
Echuca
Canberra
Launceston
Hobart
Lismore
Bendigo
Mount Gambier
Burnie
Tamworth
Devonport
START OF RECOVERY Brisbane
Mildura
Bundaberg
South West WA
Emerald
Townsville
Hervey Bay
Welingotn Beach
Ipswich
Whitsundays
Quarterly
12-month
growth
growth
$505,000
-3.1%
-2.8%
WA Country
H
$365,000
2.8%
-5.3%
Perth
U
$405,000
-3.3%
-3.5%
WA Country
U
$285,000
4.2%
-7.1%
Sydney Melbourne Brisbane Adelaide
Hobart
Darwin
$404,000
$590,000
$285,000
$515,000
Perth
$360,000
$0
$411,000
$100,000
$333,000
$200,000
$460,000
$300,000
$390,000
$500,000 $400,000
$520,500
$700,000 $600,000
$536,500
$800,000
Units
$663,250
Houses
$720,000
$900,000
H
www.brokernews.com.au
South East NSW
$1,100,000
Perth
28
NSW Mid North Coast
$1,000,000
Vacancy rates continue to soar as Perth struggles under the weight of oversupply and limited demand. “It is still very much a bargain-buying market and doesn’t have any good growth indicators associated with it for at least 18–24 months,” says Paul Glossop, director of Pure Property Investment. Migration is a significant part of the problem as residents of WA are leaving for states offering greater opportunities. “It points to further weakness in this market,” explains Cameron Kusher, research analyst at CoreLogic. “We see more houses and units reselling at a loss. The market is really being plagued by not having a lot of demand for housing at the moment.” Outer-ring suburbs are not faring well either; their rental markets are struggling as landlords face difficulty in finding tenants and new dwellings are selling at below cost. Type Median value
Gold Coast
The Herron Todd White residential property clock looks at which markets are performing well, which are on the rise, and which are on a downward spiral. The coloured entries in the tables indicate a positional change from last month. This issue’s property spotlight is New South Wales, which HTW, a property valuation and advisory group, says is still sitting at the top of the market. In the midst of a listings shortage, many property owners are choosing to upgrade their homes through renovation, according to HTW. Quality renovated properties attract good premiums at the time of sale as well. Sydney’s eastern suburbs, heritage areas and inner west are popular renovation locations. Illawarra is one of the housing hotspots to watch outside of Sydney, with a lot of residential construction underway. Younger owners are purchasing their first or second properties and are updating and rebuilding them. Similar activity is taking place in the more established suburbs north of Wollongong and in those in and around the Wollongong and Shellharbour CBDs.
MEDIAN HOUSE AND UNIT PRICES
Perth is expected to remain down in the dumps in the near future, with negative growth predicted for at least another 12 months
Area
Botany
$409,500
WESTERN AUSTRALIA
Melbourne
$1,000,000
Type Median value
12-month
APPROACHING PEAK OF MARKET
HOUSES
$745,000
Area
Quarterly
NATIONAL PROPERTY WATCH JUNE 2017
Canberra
CAPITAL CITY HOME VALUE CHANGES Capital city
Weekly change
Monthly change
Year-to-date change
12-month change
-0.2%
-0.8%
3.4%
11.4%
0.1%
-1.0%
3.2%
11.9%
Brisbane
-0.3%
-0.5%
1.3%
4.0%
Adelaide
-1.0%
0.9%
2.6%
2.4%
Perth
0.8%
1.9%
-1.1%
-0.3%
Combined 5 capitals
-0.1%
-0.5%
2.7%
9.0%
Sydney Melbourne
*Brisbane results are for the combined Brisbane and Gold Coast region. The monthly change is the change over the past 28 days.
Source: Herron Todd White June 2017 Month in Review residential report, htw.com.au
Peak of market
PEAK OF MARKET Coffs Harbour
Starting to decline
Approaching peak of market
NSW Central Coast
Newcastle
DECLINING MARKET
Rising market
Darwin
Declining market
Toowoomba
APPROACHING BOTTOM OF MARKET Perth
Approaching bottom of market
Start of recovery
Rockhampton
Alice Springs
Bottom of market
BOTTOM OF MARKET Cairns
Mackay
Gladstone
TASMANIA
Lifestyle and affordability are the main drivers of demand in Hobart, though the state’s appeal extends beyond the capital The opening of Mona (the Museum of Old and New Art) back in 2011 was a blessing for the Hobart market as it has been a significant factor in the capital’s turnaround through a revival of the local tourism scene. “Over the last three years, there’s been a large upswing in the city’s tourism dollars, particularly [from] Chinese tourists,” remarks Paul Glossop, director of Pure Property Investment. “There’s a lot of opportunity in the tourism sector down there, and it’s becoming more apparent.” After their maiden visit, many have decided to make their stays long-term, with buyers attracted to Hobart’s lifestyle and affordable homes. Possibly as a result of this migration, the service and forestry sectors have been picking up.
Area
Type
Median value
Quarterly growth
12-month growth
Hobart
H
$383,500
-1.7%
4.7%
TAS Country
H
$265,000
0.8%
0.0%
Hobart
U
$304,300
6.8%
1.7%
TAS Country
U
$240,000
4.3%
0.4%
Source: Except where otherwise stated, all data sourced from CoreLogic.com.au
www.brokernews.com.au
29
PEOPLE
IN THE HOT SEAT Finance broker Adrian Fisher talks about the transformation one goes through as a small business owner, the joy he gets out of helping people buy property, and why he’s got so many non-fiction books on the go
How did you get into mortgage broking? I love real estate and am an investor at heart. Buying property A is a huge investment, and helping others own provides huge satisfaction. But before I started I had no idea how difficult it would be or what a mortgage broker actually does. I don’t think most people do. It’s a lot of work, but satisfied clients have a deep attachment to their home and it’s a fantastic feeling sharing in that and building lasting relationships.
Q
What’s one of the most important lessons you’ve learned in your professional life? Owning your own business is transformative. You start the A business as one person and you develop as you go. The journey, the challenges, the path you take transforms you from the person you were to the person you need to be. My parents always said, “If it was easy everyone would do it”. The reason we admire those few who ‘make it’ is because deep down we all know how difficult it is to succeed.
Q
Can you briefly describe your perfect Sunday routine? Being with my family. We often go to Batemans Bay, but even a A quick trip down to Bulli for breakfast on the headland is great. I love those days when you become aware of everything. We have so much going on in our heads all the time that we need to focus on being present.
Q
What was the last book you read? I don’t read fiction any more; I don’t have the time. But I always A have a number of non-fiction books on the go. Right now, I have Gary Vaynerchuk’s Jab, Jab, Jab, Right Hook, Tim Ferriss’s Tools of Titans and Jim Rickards’s The New Case for Gold and The Road To Ruin. I read books to learn and get ideas from. I scribble all over them and highlight things, and as soon as I get an idea I run off and start working on it.
Q
What object can you not live without? Unfortunately, my phone. It’s my connection to everything. As A with most of us, our jobs, incomes and a large portion of our lives are directly associated with electronics. I try to disconnect often, but it’s not easy. AB
Q
30
www.brokernews.com.au
Book your table now
Friday 27 October • The Star Sydney www.australianmortgageawards.com.au Event Partner
Award sponsors
Official publications
Organised by
www.brokernews.com.au
31
32
www.brokernews.com.au