JUNE 2017 ISSUE 14.11
Uneven playing field What a sweeping credit ratings downgrade on second-tier banks means for brokers /18
Preparing for uncertain times La Trobe Financial on how diversification can insulate your business /16
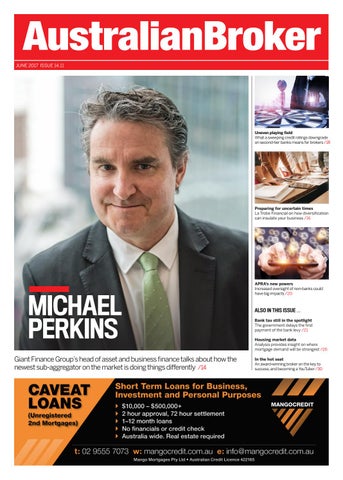
MICHAEL PERKINS Giant Finance Group’s head of asset and business finance talks about how the newest sub-aggregator on the market is doing things differently /14
APRA’s new powers Increased oversight of non-banks could have big impacts /20
ALSO IN THIS ISSUE … Bank tax still in the spotlight The government delays the first payment of the bank levy /21 Housing market data Analysis provides insight on where mortgage demand will be strongest /26 In the hot seat An award-winning broker on the key to success, and becoming a YouTuber /30
NEWS
IN THIS SECTION
Lenders Mortgage brokers wrote nearly half of new ADI loans /04
Aggregators Choice marks its 20th year with $60bn milestone /06
Technology Fintech slashes loan processing time /10
Commercial Opportunities for brokers with asset financing set to grow /12
Consumers Borrowers on the hunt for longerterm fixed rate home loans /08
www.brokernews.com.au JUNE 2O17 EDITORIAL Editor Otiena Ellwand News Editor Miklos Bolza Production Editor Roslyn Meredith
DATES TO WATCH
Upcoming industry events and key dates
ART & PRODUCTION Design Manager Daniel Williams Designer Martin Cosme
22 - 24 JUNE
30 JUNE
1 8 J U LY – 3 A U G U S T
AFG National Broker Conference
End of ASIC public consultation
Women in Business conference series
More than 1,000 people are expected to attend this two-day conference in Sydney. AFG promises compelling keynotes and conversations with industry leaders
Don’t miss the chance to have your say on ASIC’s Review of Mortgage Broker Remuneration. Interested parties are encouraged to submit feedback via the government’s Treasury website until 30 June
FAST is hosting five state conferences specifically geared towards helping women succeed in broking. Women have been recognised by a number of aggregators as a growing segment of the industry
Production Manager Alicia Chin Traffic Coordinator Freya Demegilio
SALES & MARKETING Sales Manager Simon Kerslake Account Manager Rajan Khatak Marketing and Communications Manager Lisa Narroway
CORPORATE Chief Executive Officer Mike Shipley Chief Operating Officer George Walmsley Managing Director Justin Kennedy Publisher Simon Kerslake Chief Information Officer Colin Chan Human Resources Manager Julia Bookallil
EDITORIAL ENQUIRIES
Otiena Ellwand +61 2 8437 4792 Otiena.Ellwand@keymedia.com.au
SUBSCRIPTION ENQUIRIES
tel: +61 2 8O11 4992 fax: +61 2 9439 4599 subscriptions@keymedia.com.au
2 5 J U LY
2 7 J U LY
2 - 10 AUGUST
MFAA skills webinar
MFAA National Excellence Awards
Commercial Broker Forum
Polish your skills during this one-hour webinar hosted by the MFAA on “Responsible Lending: The intricacies that most brokers don’t get – and need to know”
State award winners will head to this national event in Melbourne to vie for the top prize at the end of July. More than 300 finalists were selected from across the country in a number of categories. The awards recognise the association’s core values of professionalism and integrity
FAST is hosting four commercial and asset finance conferences to provide brokers with state-related insights that reflect the local market. Invitations will be sent out to FAST brokers
ADVERTISING ENQUIRIES
Simon Kerslake +61 2 8437 4786 simon.kerslake@keymedia.com.au Rajan Khatak +61 2 8437 4772 rajan.khatak@keymedia.com.au Key Media Pty Ltd Regional head office, Level 1O, 1–9 Chandos St, St Leonards, NSW 2065, Australia tel: +61 2 8437 4700 fax: +61 2 9439 4599 www.keymedia.com Offices in Sydney, Auckland, Denver, London, Toronto, Manila, Singapore, Bengaluru
16 AUGUST
26 - 27 AUGUST
11 - 13 OCTOBER
National Finance Brokers Day
Property and Investing Expo
Credit Law Conference
Dino Pacella founded this event back in 2015 to celebrate brokers and educate consumers. The goal this year is to raise $50,000 through charity drives for sick children
Free seminars and over 100 exhibitors will provide investors with insights and contacts to help build their portfolios and establish successful strategies
The 27th annual event in Surfers Paradise brings together banks, credit unions, regulators, associations and market disruptors to discuss the future of credit and lending
2
www.brokernews.com.au
This magazine is printed on paper produced from 1OO% sustainable forestry, grown and managed specifically for the paper pulp industry Copyright is reserved throughout. No part of this publication can be reproduced in whole or part without the express permission of the editor. Contributions are invited, but copies of work should be kept, as Australian Broker magazine can accept no responsibility for loss. Australian Broker is the most-often read industry publication, according to independent research carried out by the Ehrenberg-Bass Institute for Marketing Science at the University of South Australia in December 2008. The research also found that brokers rate Australian Broker as the best for both news content and feature articles, followed by sister publication MPA. Overall, on all categories, Australian Broker ranks top followed by MPA. The results were based on a sample of 405 respondents who were the subject of telephone interviews.
NEWS
LENDERS Source: APRA Quarterly ADI Property Exposures report, March 2017
$250,000
4,000,000
Huw Bough Group executive of broker distribution, MyState Bank
4
www.brokernews.com.au
$75bn
$60bn
3,000,000
$230,000
2,000,000
$220,000
$30bn
1,000,000
$210,000
$15bn
0
$200,000 Number of housing loans
THE
“We have been working hard to be the bank of choice for brokers and have deliberately aligned our success with that of our brokers. This strategy is working well”
$240,000
$90bn
March 2016
Quarterly statistics released by APRA shed light on Australian ADIs’ lending trends for residential mortgages half of new residential loans from Australian ADIs were originated via mortgage brokers, according to the latest statistics from APRA. The third party channel wrote $186.5bn worth (or 48%) of new loans approved to the end of March this year. Overall, residential mortgages from Australian ADIs have continued trending upwards, while high-LVR and interest-only lending has decreased. The quarterly report on ADI property exposures showed that the total value of residential loans reached $1.51trn as of 31 March 2017, an increase of $107.8bn (or 7.7%) from a year before. Owner-occupier loans amounted to $985.8bn, or 65.1%
New housing loans approved in the quarter
Note: Statistics are for ADIs with >$1bn in housing loans
RESIDENTIAL LENDING BREAKS $1.5TRN
NEARLY
$45bn
0 Average balance of housing loans
March 2017
$89.3bn
5,000,000
+9.6%
$81.5bn
$260,000
$259,400
6,000,000
FBAA CALLS FOR INDEPENDENT ACTUARY head of the FBAA says the independent body will examine numbers used by the big four banks in the media and ensure that all figures are accurate and representative of the truth. “Distinguishing fact from fiction is the major challenge,” said FBAA executive director Peter White. “Are we getting facts from the banks?” The actuary will look into the impact of these quoted figures on shareholders, interest rates and additional fees and charges to provide clarification over ‘knock-down effects’ from measures such as the government’s bank levy.
+3.9%
$249,600
+3.6%
5,761,800
broker-led mortgage strategy has led to strong investor appetite for the lender’s largest ever residential mortgage-backed securitisation (RMBS) transaction. Demand for the non-major bank’s recent $400m capital-raising – the sixth under the CONQUEST program – showed recognition of the strength and quality of the lender’s loan book, said group executive of broker distribution Huw Bough. Eighteen investors from Australia and overseas participated in the recent capital-raising. MYSTATE’S
ADI HOUSING LOANS ON THE RISE
5,560,000
BROKERS LEAD RECORD RMBS TRANSACTION
of total residential mortgage loans, with investment loans making up the remaining $528.7bn (or 34.9%). The volume of owner-occupier loans increased by $78.9bn (or 8.7%) in the 12 months since 31 March 2016, while investment loan volumes rose by $28.8bn (or 5.8%). The 31 ADIs with more than $1bn in term loans held 98.7% of all mortgages at the end of March this year, equalling a total of 5.8 million mortgages worth $1.49trn. APRA reported that the average loan size was approximately $259,000, an increase from the $250,000 recorded a year prior. Of the total number of residential home loans, $583.3bn (or 39%) were interest only.
In total, $387.7bn worth of home loans were approved by ADIs with greater than $1bn in term loans in the year ending 31 March 2017. This was an increase of $13.8bn (or 3.7%) from the same time period the year before. The major banks held $1.22trn worth of residential home loans, equating to 80.8% of the total Australian mortgage book. The big four approved $295.7bn worth of new residential loans in the 12 months prior to the end of March 2017, or 76.3%. Of the new mortgages originated with the major banks, $140.0m (or 47%) came through the third party channel. The other domestic banks with greater than $1bn in term loans held $193.2bn worth of residential mortgages. A total of $63.7bn in new loans was approved in the 12 months prior to 31 March, with $32.5bn (or 51.0%) coming through the third party.
NEWS
A G G R E G AT O R S AGGREGATOR SURPASSES $60BN MILESTONE Aggregation has a lot to celebrate this year. The group is marking its 20th anniversary with a trail book worth over $60bn and a network that’s expanded to 1,500 brokers. More than 20% of its members have been with the aggregator for more than 10 years, proving its offering resonates with a broad and loyal base. “We are thrilled to be marking our 20th year in business with such a strong backing. … These milestones are testament to the strength of our members,” said CEO Stephen Moore. CHOICE
‘EMPOWER’ PROGRAM FOR WOMEN IN BROKING a growing number of women making up Connective’s membership, the aggregator decided to respond by hosting a series of events aimed at supporting women in broking. The inaugural Connective Empower program was “designed to encourage women to unite in their ambitions, step into leadership roles, and work together to inspire and support greater success”, said Jen Dickson, general manager of marketing and events at Connective. It was also open to women outside Connective’s network and attracted business owners, loan writers, administrative staff and marketing professionals. WITH
COMMISSION CHANGES COULD HAMMER MORTGAGE FRANCHISE If lenders opt to pay lower commissions, one major franchise could be heavily impacted decisions to decrease broker commissions have analysts predicting a negative impact on mortgage franchises such as Mortgage Choice. Investment research firm Morningstar examined the headwinds facing Mortgage Choice and determined that although it is performing well now, potential changes to the broker commission model could be detrimental. Mortgage Choice pays franchisees 73% of upfront and 61% of trail received from lenders, putting it in a position to pass on the negative impact of lower commission rates to franchise owners, analysts said. However, despite the company’s strong market presence, it has been losing market share of the broker FUTURE
6
www.brokernews.com.au
segment as smaller players take a cut of the commission themselves, potentially leading to higher turnover within the firm. “Commission cuts from banks could encourage more franchisees to look for a better deal outside the Mortgage Choice franchise model,” analysts said. This trend may also have the same effect on other mortgage franchises around Australia. A downturn in the national housing market could also produce lower returns for Mortgage Choice over the long term, Morningstar predicted. “Future profitability relies heavily on the ongoing strength of the Australian housing market and the preparedness of the four major
banks to continue using mortgage brokers to distribute mortgages and continue to pay current levels of upfront commissions.” In the event that housing finance approvals decrease in a downturn, Morningstar analysts predict Mortgage Choice’s upfront commission income will be affected. Upfront accounted for 45% (or $39m) of gross broker commission income, while trail accounted for the remaining 55% (or $48m) in the first half of the 2017 financial year. Finally, Mortgage Choice is subject to regulatory changes by APRA and ASIC, both of which may affect the firm’s ability to grow, analysts said. “ASIC’s review into broker remuneration could result in regulatory changes requiring a rebasing and/or reduction in the current commission structure, and if lenders reduce commission rates or negatively alter commission structures, Mortgage Choice’s revenue and profitability would be under pressure.”
“Women play an important role in the mortgage broking industry, and there is more work to be done to cultivate better gender diversity” Jen Dickson General manager of marketing and events, Connective
NEWS
CONSUMERS CBA TOPS HOME LOAN SATISFACTION POLL latest Roy Morgan research polled more than 50,000 consumers and found that consumer satisfaction with the four major banks increased in April, taking current levels well above the long-term average. However, home loan customers continue to be worse off, with satisfaction levels sitting at 78.0% compared to 80.5% for other types of customers. Home loan customers at CBA experienced the highest satisfaction levels at 78.8%. This was followed by Westpac (78.5%), NAB (77.3%) and ANZ (77.0%). THE
BIG FOUR BANK REOPENS INVESTOR REFINANCING has announced it is once more offering new investor refinancing after putting the brakes on investor lending in February. The bank began accepting new refinance applications on 22 May for investment home loans with principal and interest repayments, subject to CBA’s normal lending criteria. “These changes follow APRA’s announcement in March for banks to reduce the number of interest-only home loans, and are aimed at encouraging customers to select P&I, where appropriate,” CBA said. CBA
“We know property prices are sky high. Compound that with low wage growth, high levels of household debt and out-of-cycle rate hikes and you can expect that consumers might be worried about maintaining a loan” Paul Thomas CEO, Gateway Credit Union
GROWING CONSUMER APPETITE FOR LONGER FIXED RATE LOAN TERMS Most Australians want lenders to offer fixed rate mortgage terms of 10 years or more, according to a new survey
significant proportion of Australians would like lenders to offer longer-term fixed rate home loan products, according to results from a new survey. The research was conducted by Gateway Credit Union and looked at results from over 1,000 respondents across the country. In total, 71.3% of those polled said lenders should offer longer-term fixed mortgages. Nearly half wanted 10-year fixed rate loan terms, while around 15% each wanted terms of 15, 20 or 30 years. Fewer than 10% wanted 25-year terms. These findings suggest that borrowers have been impacted by constant speculation around changing market conditions, said Gateway Credit Union CEO Paul Thomas. “We know property prices are sky A
high. Compound that with low wage growth, high levels of household debt and out-of-cycle rate hikes and you can expect that consumers might be worried about maintaining a loan, especially if they have no control over repayments because of a fluctuating rate,” he said. “A fixed rate home loan means borrowers would have peace of mind in uncertain times and the findings suggest that it’s a key consideration right now.” However, there are a number of reasons why demand for anything beyond a 10-year fixed rate loan term has dropped off significantly, Thomas told Australian Broker. “First, unlike our American counterparts, Australia has typically always been a variable rate home loan nation. Historically, we’ve
preferred variable rate home loans, which have been around longer than fixed rate products. “The other factor is the time horizon. Average mortgage churn occurs every five to seven years. Anything longer than a 10-year loan term may not be desirable because borrowers would want to avoid breaking the loan and paying associated break costs.” Lastly, it is difficult for borrowers to predict what will happen with interest rates over such an extended time period, Thomas said. “In my experience, a fixed rate home loan is all about certainty. Borrowers who want peace of mind that their rate won’t change for a set period are willing to live with a slightly higher interest rate.” Of the current loan terms available from Australia’s banks, more than one in two consumers (55.9%) would fix their loans for five years. This was significantly higher than the number of consumers who said they would choose a three-year (23.1%), two-year (15.1%) or one-year loan term (5.9%).
NUMBER OF FINANCIAL INSTITUTIONS CONSUMERS BANK WITH – BY HOME LOAN STATUS Source: KPMG, The Australian Home Loan Market 2017 survey report
No. of financial institutions
33%
32%
35%
8
www.brokernews.com.au
Home loan status
52%
48%
No home loan
Home loan
No. of financial institutions
28%
36%
1 2 3 or more
36%
NEWS
TECHNOLOGY
MORTGAGE FRANCHISE ADOPTS RAPID LOAN TECHNOLOGY broking franchise MoneyQuest has formally announced a partnership with a leading fintech firm to boost loan processing times for its brokers. The agreement will see the franchise network gain access to Proviso’s BankStatements – a platform that allows clients to quickly send bank transaction data digitally. “Almost instantaneously their bank statements are emailed to their mortgage broker – completely hassle free,” said MoneyQuest managing director Michael Russell. Special training will be provided to all MoneyQuest brokers on the use of the system, he added. MORTGAGE
P2P LENDER LAUNCHES GREEN LOAN MARKETPLACE Partnering with a national finance corporation, the marketplace will give brokers a new way to help clients save money lender RateSetter has partnered with the Clean Energy Finance Corporation (CEFC) to launch a new ‘green loan’ marketplace. Receiving a $20m kickstart from the CEFC, the marketplace is aimed at individuals and business borrowers seeking to finance the purchase of approved energy-efficient products and incentivise the uptake of clean energy technology. Retail investors will also be able to utilise the marketplace and earn attractive returns while improving Australia’s energy footprint. “This innovative facility offers the potential to improve the marketability of green assets, by bringing purchasers, installers and manufacturers closer together.
There have been green loans before, and there has been peer-to-peer lending, but combining the two into one platform is an Australian first,” said CEFC CEO Ian Learmonth. Daniel Foggo, CEO of RateSetter, said the partnership showcased the exciting opportunities that could be created for businesses and consumers when government agencies teamed up with the fintech sector. “We are delighted to have the CEFC’s financial involvement to develop this initiative to support the uptake of clean energy in the home, on the road and in the running of Australian businesses,” he said. Rates for investors and borrowers within the green marketplace are expected to be
PEER-TO-PEER
around 7% per annum, with loan terms mainly falling between three and seven years. “RateSetter green loans provide brokers with a new way to help their clients save money through the installation of clean energy products, including solar panel and battery systems, solar water systems and energy-efficient air conditioning. RateSetter green loans are available to accredited RateSetter brokers from today,” Foggo told Australian Broker. Investment in this transaction could pave the way for future rollouts of similar green platforms, CEFC debt markets lead Richard Lovell said. Growth in green funding has exploded over recent years. The recent Global Sustainable Investment Review reports that the total amount of money in funds with green or social investment principles increased from US$148bn to UD$516bn in Australia and New Zealand between 2014 and 2016.
VV HOUSING PRICES INCREASED IN MOST CITIES MEDIAN Source: Moody’s Investors Service – Housing Affordability Report, April 2017
900,000 800,000 700,000 600,000 500,000 400,000
Australia
10
www.brokernews.com.au
Sydney
Melbourne
Brisbane
Perth
Adelaide
Mar-17
Dec-16
Sep-16
Jun-16
Mar-16
Dec-15
Sep-15
Jun-15
Mar-15
Dec-14
Sep-14
Jun-14
Mar-14
Dec-13
Sep-13
Jun-13
Mar-13
Dec-12
Sep-12
Jun-12
200,000
Mar-12
300,000
TAX PARTNERSHIP FOR BROKERS eChoice has partnered with leading tax depreciation firm BMT to offer member brokers access to advice about tax changes announced in the federal budget. The government has proposed changes to rules around depreciation for property investors. “Now that changes to depreciation rules have become reality as part of the Federal Treasurer’s budget delivery, the intention is for our brokers to be able to connect their investor clients with the depreciation specialist at the point of sale,” said Blake Buchanan, general manager of aggregation at eChoice. AGGREGATOR
NEWS
COMMERCIAL
COMMERCIAL LENDER CREATES NEW BROKER LEADERSHIP ROLE has appointed industry veteran Robert Vrevc to the newly created role of NSW state manager. Vrevc was previously state manager at Capital Finance. He will be responsible for building strong relationships with broker groups and aggregators in NSW for FlexiCommercial, which provides equipment finance and cash flow solutions to brokers and their clients. Vrevc said he would be in charge of developing a young, energetic team to provide expanded offerings to brokers – a drastic move for a firm that has traditionally focused on consumers. FLEXICOMMERCIAL
SME LENDER CELEBRATES $50M IN LOANS Global small business lender Spotcap is marking its second successful year in operation with strong support through the broker channel its first two years in operation in Australia, global small business lender Spotcap has provided more than $50m in credit to local SMEs. Since its establishment in May 2015, the firm has released more than 75 iterations and updates as it has evolved, including real-time document classification, co-branding functionality for bigger partners, and integration of all major accounting providers. In the past two years, Spotcap has also entered the market in the UK and New Zealand. Lachlan Heussler, managing director of Spotcap Australia, said he was proud of the company’s achievements and contribution to the Australian fintech space. “On our second anniversary we IN
ASSET FINANCING TO REACH $12BN ANNUALLY amount of equipment and plant leasing by Australian businesses is set to grow. According to the ABS, $52bn will be spent on commercial assets by the end of this financial year. Of this, $40bn worth of equipment will be purchased outright, while $12bn will be leased. The latest Alleasing Equipment Demand Index shows that 30.6% of businesses plan on increasing their asset bases during the June quarter. This has gone up from 25.6% since Alleasing’s previous index. Within the mining sector, 26.4% of firms indicated they wanted to expand their asset bases. THE
12
www.brokernews.com.au
including 1,000 brokers sourced through aggregator AFG as well as other means. Other partners include accountants, bookkeepers, software vendors and other parties dealing with SME clients. Spotcap offers a number of support structures and a dedicated sales team for brokers, and has grown the channel over the past two years, Heussler said. “We also provide all of our partners with a ‘partner portal’ that makes it easy to refer us a deal. They can either type in their client’s email address and hit refer, or they can actually complete the vast majority of the application and hand it over to the client for completion.” Spotcap focuses on two areas, he said. As well as helping brokers finance their clients, the lender also allows brokers to be involved in unsecured SME lending and grow their own businesses. Spotcap hopes to bridge the funding gap in unmet lending for SMEs by banks.
can look back and be proud of all we have achieved as a business – particularly in the updates to our technology, and not just meeting but exceeding demand for an unparalleled client experience in obtaining business finance.” The majority of the $50m in credit was originated through Spotcap’s offline channels, Heussler told Australian Broker. “We source business from our SME clients in different ways, but by far the biggest is our offline partner channel, so working with intermediaries like brokers.” Spotcap works with a variety of brokers, including commercial finance brokers, residential lending brokers and equipment finance brokers. The lender’s network is approaching 5,000 partners,
AUSTRALIAN COMMERCIAL PROPERTY VALUES RISING SHARPLY Source: CBA, ABS
index
Australia
Ireland Canada France
150
Spain
US 100
New Zealand
Switzerland UK
50 2000
2004
2008
2012
Note: The indices take an asset’s value minus expenses and set it to a baseline of 100 in 2002.
2016
ADIS: COMMERCIAL PROPERTY HIGHLIGHTS Source: APRA
Commercial property exposures and limits
$bn
%
400
15
300
10
200
50
100
00
0
2012
2013
2014
2015
2016
2017
Commercial property exposures (left)
Exposures growth (right)
Commercial property limits (left)
Limit growth (right)
-5
Commercial property exposures and limits by type Office Retail Industrial Land development Other residential Tourism and leisure Other 0
20
40
60
80
100
$bn Actual exposures
Limits
MAJORS MOVE TOWARDS SIMPLIFIED SME LENDING response to Kate Carnell’s Small Business Loans Inquiry, the big four banks say they will amend their SME loan contracts. The inquiry raised a concern about non-monetary default clauses, such as financial indicator covenants, which link defaults to such things as loan-to-valuation ratios. For loans below $5m, banks must not default a loan if the small business customer has complied with loan payment requirements and has acted lawfully, Carnell said. She also pressed banks to remove conditions that allow them to invoke financial covenants or catch-all ‘material adverse change’ clauses. These changes are to be made by 1 July. IN
FE AT URES
COVER STORY
A BROKER’S BIGGEST CHAMPION Giant Finance Group entered the aggregation space just three months ago, but already it is making waves with its small-scale, relationship-focused business strategy that revolves around boosting brokers’ prospects
KEY BUSINESS METRICS
42
Brokers recruited since 1 March 2017
55
Average monthly new mortgage leads
$51,089,445
Record month submissions
$38,500,000
Record month settlements
$3,010,000
Biggest settled loan
14
www.brokernews.com.au
Finance Group’s (GFG’s) head of asset and business finance Michael Perkins wants brokers to ask themselves a few questions: When did they last see their BDM? How often does their BDM call to talk about their business? Have their volumes increased during their time with their aggregator? Do they feel supported and part of a team? GFG is the newest sub-aggregator on the block, having just opened three months ago, and Perkins is willing to bet there are some brokers who could benefit from the small-scale, customised service it has to offer. “I’m a big believer in thinking outside the box but always making sure that we put the customer – and in our world the broker – in the centre of all the decision-making. The decisions sort of flow around them. We aren’t going to do things if I don’t think it’s going to benefit our brokers,” he says. While the GFG office in Sydney’s Haymarket area is still being decorated, the company has already got 42 brokers on board, two BDMs in place and more than 50 leads coming in a month, he says. In May, GFG’s brokers submitted more than $51m in new loans. “Yes, we have been hit with a pinch of luck that we’ve grown so fast,” Perkins says, praising Finsure, the group’s parent aggregator, for its “impeccable” onboarding process. As a sub-aggregator, GFG is able to leverage its relationship with Finsure to offer competitive and cost-effective commission models backed by industry-leading software and resources. “Simon Bednar, the general manager of sales at Finsure, has been GIANT
a driving force in the success of GFG,” Perkins says. “Backed by one of the most resourceful teams, this poses an advantage to all brokers to leverage from these relationships.” Hands-on, small-scale service Delving into aggregation was a perfect fit for Perkins, rounding out his experience in the industry. Perkins started his career in commercial lending 22 years ago. He spent nine years with CBA and NAB in both BDM and credit manager roles. In 2005, he moved into asset finance at Dealer Direct Finance, and became a standalone finance broker 10 years later. Working in various positions in the industry has allowed him
Giant Finance Group .
is worth the commission earned. “Interestingly, most of our brokers choose to refer asset and business finance deals as the reward is excellent for little effort,” he says. Having written loans himself, Perkins also knows the frustrations
“I’m a big believer in thinking outside the box but always making sure that we put the customer – and in our world the broker – in the centre” to develop an in-depth, high-level understanding of loan structures, from commercial to residential and everything in between. Now he looks after all the asset and business finance lending within GFG. “Our brokers have a choice when it comes to such lending. They can simply refer the deal to GFG or they can take ownership of the deal themselves and use our support and lender accreditations to write and submit the business,” he says. This model gives brokers flexibility to decide whether the work required
brokers encounter, especially what it’s like to call several lender BDMs and not have one pick up and less than a handful return the call. As self-employed people competing against the million-dollars-a-year marketing campaigns of the major banks, brokers need an answer when a customer is in front of them, he says. “Sometimes a day is too long, so that’s what we do: we’re available.” Starting businesses, being involved in businesses: it’s all second nature to Perkins. Through the ups and downs he’s learned some important lessons
platform that gives brokers insight into customers’ spending habits so they can help their clients refine their goals. It will also assist brokers in meeting their compliance obligations under the NCCP, Perkins says. “I strongly believe that, as the industry continues to evolve, having diversified experience that extends past the realm of mortgage brokering will in itself be an extensive value proposition to any business in our industry, new or existing,” he says.
along the way that have shaped his guiding business philosophies: relationships are key, put customers at the forefront, be authentic and follow through. Not only is being available and accessible to brokers important to GFG, but Perkins also wants them to know they’re supported, so they feel comfortable picking up the phone and saying, “I don’t have leads; I need leads. I need help this month”, and then they get it. He wants to eliminate the red tape and other unnecessary difficulties of doing business by providing “some good old-fashioned service”. “The respect I have for brokers or anybody who’s self-employed and gets up in the morning and sits behind a desk like this, looks at a computer and says, ‘Great, now I need to work out how I’m going to pay my lease, my school fees, my mortgage, the hindrances that come with being a broker and make it happen,’” he says. Perkins says if brokers want to get the most out of their aggregators, they need to do their research, ask how many accounts each BDM manages and what sort of service they offer, and then keep tabs on whether they’re getting a return on their investment.
“I don’t understand how a BDM can effectively manage 300 relationships on a monthly basis. The result of that is, you’ve got a lot of brokers that actually need help and could be so much more successful if they had access to the help,” he says.
being an aggregator because people assume all the company is after is adding brokers to its ranks to make as much profit as possible. Perkins plans to challenge the sceptics. GFG offers a competitive flat fee and commission model and
“If you’re doing your cold calling, seeing your clients ... it’s only consequential that you’ll get the results” Growing with purpose While GFG is growing, its long-term goal is not to become a PLAN, an AFG or a Connective. “Even though I’m confident we could, I don’t see us growing anywhere past 100 brokers so that we can continue to effectively offer high-level service and offer a model where BDMs manage a maximum number of relationships. The industry is crying out for service models, and that’s just what we plan to deliver,” Perkins says. Still, he believes it’s difficult
is interested in attracting highly productive broker groups, or the eager up-and-comers who want to hit the next milestone. The subaggregator wants to assist brokers in building active referral networks, maintaining and sustaining mutually beneficial relationships, and working out their business strategies. In addition to facilitating asset/business finance, it has also introduced property and insurance business. The company will soon launch an industry-first technology
Not all about numbers GFG doesn’t dwell on numbers because, as Perkins says, “If you’re doing your cold calling, seeing your clients, doing your follow-ups, it’s only consequential that you’ll get the results”. The company’s BDMs are instead focused on keeping in regular, sometimes daily, contact with their brokers and providing quality service. “Our brokers are individually treated like a top 20% customer and can receive help to get any sort of finance deal approved,” he says. “In-house, we have the experience to provide this support, whether it’s residential, commercial, short-term cash flow lending or asset finance.” But there is one number Perkins likes talking about: a $3m residential loan, the first major settlement by one of GFG’s brokers. It was such a complex deal GFG had to hire an external accountant to assist with the financials, proving to what lengths the sub-aggregator was willing to go to help. It was a win for GFG and the broker, a new recruit who never would have dreamed of getting such a complex deal across the line in their first 12 months. “I was quite emotional about it, to be honest,” Perkins says. “I felt really accomplished that our broker and these clients had the confidence in us to manage these sorts of transactions, so I felt like it was sort of confirmation that we’re doing the right thing; it was confirming our original business belief.” AB www.brokernews.com.au
15
FE AT URES
BUSINESS PROFILE
TIME TO PLAN FOR THE FUTURE La Trobe Financial’s chief lending officer, Cory Bannister, tells brokers not to delay diversification, especially in a climate of increased regulatory uncertainty and changing lender appetite
deserve some congratulations: they’re writing nearly 54% of home loans, according to the latest MFAA Industry Intelligence Service report, showing they’re clearly valued as customers’ trusted advisers. “Broker market share is improving through the exceptional work being done by brokers to demonstrate the clear benefits they deliver to customers,” says La Trobe Financial’s chief lending officer, Cory Bannister, who believes it’s not unrealistic to expect that brokers will soon capture 60% of the market. But as change swirls in and around the industry, and brokers face increased pressure and scrutiny from all sides, how will they go about fulfilling this prediction? It has been said before and will be said again, but Bannister contends that “the key to future growth in market share … will come through catering for more of a customer’s needs over their life cycle – a diversified offering”. If a broker is unable to fulfil a customer’s requirements – be it a lease, risk insurance or commercial finance – they will likely turn to their main financial institution, and the broker could run the risk of losing that customer altogether. While it is a positive sign that brokers have scooped up more than half of the residential market, their commercial share is lagging at about 30%, “which tells you there is plenty of scope for further uplift in broker business”, Bannister says. “Let’s not forget that a rising tide lifts all ships, so if brokers capture more commercial share, it is likely to result in further increases in residential mortgages,” he adds. BROKERS
16
www.brokernews.com.au
Not only does diversification give a business the possibility of financial growth, but it also means protection from unpredictable market fluctuations. It prevents businesses
from many of the headwinds that are likely to be encountered over a life cycle,” Bannister says. “We have seen businesses grow during peak periods and the risk is an
“Diversification can insulate a business and investment from many of the headwinds that are likely to be encountered over a life cycle” from becoming over-reliant on one product or offering and the vulnerabilities that invites. “We strongly believe diversification can insulate a business and investment
external shock such as the GFC. These risks are mitigated by diversification.” While it’s easy to get distracted by daily tasks and set ‘working on the business’ aside, Bannister cautions
against delaying a diversification strategy to another day, particularly now, amid so much regulatory uncertainty and lenders’ rapidly evolving appetites. The recent modernisation occurring within financial services businesses, in which many ‘mortgage’ brokers have become ‘finance’ brokers, has allowed these companies to adopt a more holistic proposition, Bannister says. This will likely continue and result in a “diversify or die” outcome, he predicts. “[It’s] not too dissimilar to the impact supermarkets had on the high-street butchers and grocers as consumers looked for the convenience of a one-stop shop.” Don’t put all your eggs in one basket Brokers are the “lifeblood” of La Trobe Financial’s business, Bannister says, which is why the non-bank lender is continually trying to improve the broker experience from start to finish. The credit specialist wants to help brokers implement their diversification strategy, so it has eliminated the barriers to entry for many of its specialised products, including its commercial, SMSF and development finance offerings. By keeping its niche products accessible and removing the “stigmas of complexity”, it’s allowing even new brokers a chance to grow their business offering. The credit specialist prides itself on having applied a level of simplification that’s
PROS AND CONS OF BECOMING A ONE-STOP SHOP Source: La Trobe Financial
Benefits
Risks
Larger customer base
Stickier customer base
Increased revenue
Protection for your business
May require additional staff
Generalist rather than specialist
Trying too much too soon
Sponsored by
unique in the industry. “We have purposely engineered our products and processes to ensure all products look and feel the same, so if a broker can write a residential loan, they can write a commercial loan just as easily,” Bannister says. With other lenders, specialised products generally require additional accreditation and training, which can become a major reason why many brokers fail to execute their diversification plan, he says. The non-bank lender has also developed its forms and documents so that the same application form can be used across all its products, and similarly, the same income verification policies and documents are used regardless of product type. La Trobe provides customised training and education programs through its credit-skilled Senior Manager Client Partnerships and offers direct access to the decisionmakers in credit so brokers feel supported through the process. The credit specialist has already expanded its head office and will be adding to its national sales team in the upcoming financial year “to ensure we can continue to offer a high level of support to brokers, hopefully as part of their diversification strategy,” Bannister says. As La Trobe Financial moves ahead with its long-term strategy of diversifying its own suite of mortgage and investment products to suit every stage of a customer’s life, it will continue to work on making brokers’ access to niche products less cumbersome. “We will continue to assist brokers in navigating through what is a very challenging environment, stepping in where we can to assist with solutions for their clients,” Bannister says. One size does not fit all While diversification can be made to sound like a fail-safe business salve, it doesn’t suit every brokerage. Bannister recognises that there are many successful specialist brokerages that do just fine as they are. But he suggests that those brokers thinking of sticking to a monoline operation should “go in with your eyes wide open”. “That is, understand the risks associated with specialising in a particular market as to regulatory changes, economic conditions or moving lender appetite,” he says. Even in a monoline operation,
Cory Bannister, chief lending officer, La Trobe Financial
diversification is still possible. While a broker may choose to focus on a particular industry such as health, for example, diversification can be applied by adding risk or leasing to a mortgage offering, or expanding one’s lender panel so as not to be beholden to one particular policy setting or product offering, he explains. “Diversification can come in many forms. Our message is simply to fully understand the risks and benefits of whichever option you choose.” Banks to brokers As the major banks continue to make headlines following the release of the Sedgwick review into retail banking remuneration and the government’s new bank levy, non-bank lenders will likely keep accumulating market share. Likewise, as brokers address the ongoing issue of channel conflict, Bannister suspects more of them will seek alternative funders to the major banks to protect their client base from being cannabalised. All in all, things are looking up for non-banks, and for brokers. “We are already experiencing an increased demand from brokers looking to find alternative solutions for their clients, and we expect this to continue as consumers are exposed to the benefits that smaller, more agile operations can offer.” AB
KEY REASONS FOR CHOOSING A HOME LOAN ORIGINATION CHANNEL Source: KPMG, The Australian Home Loan Market 2017 survey report
New to financial institution
Existing financial institution
Broker
6%
12%
2.5%
They made it easy
8%
23%
29%
Business in one place
0%
30%
3%
Wanted to find best deal
56%
9%
50%
Ability to offset savings
3%
10%
1%
Family or friend recommended
13%
4%
0.5%
3%
6%
14%
11%
6%
0%
Package arrangement provided
Reputation
Other
www.brokernews.com.au
17
FE AT URES
Sharad Jain, Standard & Poor’s
ANALYSIS
MORE BAD NEWS FOR THE BANKS The major banks got slapped with the government’s bank levy and now 23 other financial institutions are facing a credit ratings downgrade. What does this mean for the banks and for brokers? Ben Kingsley, Property Investment Professionals of Australia
country’s medium- and smaller-sized financial institutions may have escaped the government’s $6.2bn bank levy proposed in the federal budget, but another announcement in late May will leave them pinched in other ways. Global credit ratings agency Standard & Poor’s (S&P) lowered the long-term issuer credit ratings of 23 financial institutions (including Bank of Queensland, Bendigo and Adelaide Bank, Liberty Financial and MyState Bank) by one notch each on 22 May. This sparked questions and concerns about what pressure this would put on second-tier banks, and who would bear the brunt of further funding costs. The agency said the move had come about because of the “continued build-up of economic imbalances in the country” due to the rapid rise of private sector debt and skyrocketing house prices, primarily in Sydney and Melbourne, which had exposed financial institutions to greater risks. Sharad Jain, S&P’s director of financial institutions ratings, said the agency had revised the outlook on a number of banks to negative late last year based on the same trend. “At that time, our expectation was whilst there had been rapid build-up in the last several years, in the near future this growth trend would abate and the build-up of balances would slow down,” he said during a conference call to explain the decision. But that didn’t happen. Instead, there continued to be accelerated THE
18
www.brokernews.com.au
growth in house prices, further driving up the risks of a sharp correction in property prices and the severe impact this could have on the economy and the banking system. “Where we sit now, we think that risk has become too
that the government would bail out the banks if it came down to it. “According to S&P, the four major Australian banks are materially driving the system-wide risks in Australia given their collective dominance, and yet
“The regulators have not micromanaged lenders in this way since the 1970s” Murray Cowan, managing director, Better Mortgage Management significant that the ratings are no longer consistent with where they were previously,” Jain said. Many of the smaller banks begrudged the fact that the four major banks and Macquarie weren’t subject to the downgrade as well, reflecting S&P’s expectation
[this] decision further entrenches their dominance and therefore the inherent risks,” ME Bank CEO Jamie McPhee said in a statement. Harald Scheule, an associate professor of finance at the University of Technology, Sydney, said that while it would depend on
the rating of the individual bank, a single-notch downgrade might imply increases in funding costs of 10 to 30 basis points on wholesale debt. The cost-of-capital impact is much lower on average as wholesale debt is only a fraction of all funds, he said. The banks affected also argued that the move was a step backwards in terms of improving competition in the banking sector, negating the government’s attempt to ‘level the playing field’ through the introduction of the bank levy. “[The downgrade] further reinforces the competitive inequity which hamstrings smaller banks and constrains competition,” said MyState Group executive of broker distribution Huw Bough. In order to deal with this issue, he said the government needed to implement the Murray
GROWTH IN HOUSE PRICES AND PRIVATE SECTOR DEBT Source: S&P Global Ratings
% 150 140 130 120
Total private sector debt as % of GDP
110
National house price index (inflation adjusted)
100 90 80 70 60 2011
2012
2013
2014
2015
2016
2017F
2018F
Huw Bough, MyState Group
Murray Cowan, Better Mortgage Management
report’s competition recommendations and raise the minimum average mortgage risk weight for large banks to at least the upper limit of 30%. McPhee said the current environment did not provide for “competitive neutrality” and was detrimental to consumers, a situation that would remain until both the gap in capital requirements was reduced and the cost of the major banks’ “too big to fail” funding advantage was removed. As for how or if this will affect mortgage brokers, it’s hard to say. Property Investment Professionals of Australia chairman Ben Kingsley said the downgrade had the potential to make the cost of sourcing funding for lenders a bit higher. That means banks will be looking for someone to pass on the costs to maintain their margins. Customers are one target and brokers’ commission could be another. “This second option would be a big call and could do more damage to their broker relationship both in the short or medium term. Their decision is really going to come down to just how much their cost of funding increases as to their course of action,” he said. While this change will likely affect the cost of funding over time, Bough said it was not yet known what the overall impact would be. Regardless, he said MyState would continue to offer a highly competitive proposition for brokers as they had been responsible for 95% of MyState’s home loan growth over the last 12 months. More realistically, instead of panicking about their commission, brokers should be preparing for further out-of-cycle interest rate
increases for their investor clients and those still willing to borrow on an interest-only basis, Kingsley said. Murray Cowan, managing director at Better Mortgage Management, said the same, adding that one repercussion could be a dip in popularity for some lenders, and more refinance opportunities for brokers. “Since the GFC, market conditions have been harder for smaller institutions,” Cowan said. “They finally received a competitive benefit from the introduction of the government levy … and now the recent S&P downgrade has seemingly neutralised those gains. The regulators have not micromanaged lenders in this way since the 1970s.” All of this could amount to an overall lack of confidence economically, he said. But Kingsley doesn’t think the downgrade will be a catalyst for any dramatic housing market fluctuations. “The last thing [the regulators] and the government want is a sharp correction in the property market, as a recession will be impossible to avoid in my opinion,” he said. “As the government has sensibly stated, the authorities are trying to orchestrate a subtle slowing of credit into the housing market to take the heat out.” Jain did have some words of reassurance for the banks: despite S&P’s view that the risk of a downside scenario and its impacts had increased, it considered the outlook for Australian banks to be relatively benign by global standards. “We see the banks pricing prudently for the risks they undertake; we see the profitability levels of the banking system as strong enough to contend with any crisis they may encounter.” AB www.brokernews.com.au
19
FE AT URES
OPINION
REGULATORY CHAOS The Australian government plans to extend APRA’s oversight to the non-bank sector, something former Pepper Group co-CEO Patrick Tuttle argues should be of concern to everyone the recent announcements made in the federal budget, including the significant regulatory changes buried in the fine print, coupled with the confused implementation of the proposed bank levy, and now Standard & Poor’s ham-fisted downgrade of the regional and smaller ADIs, I feel compelled to provide a non-bank perspective of recent events impacting the Australian mortgage market. There is not one single factor driving my concern but a series of actions and statements, many made by the government, which are also being blown out of proportion by commentators with only superficial knowledge of the facts. In a nutshell, I’m concerned that Australia is effectively taking itself into a housing and credit downturn, which could be far more dramatic and consequential than it might otherwise need to be. Recent data would suggest that house prices are already beginning to slow of their own accord. The worrying part about Treasurer Scott Morrison’s budget is that he simply appears to have brazenly copied swathes of the UK’s old playbook without carefully considering the significant differences between the Australian and UK banking and mortgage lending markets; in particular, the different level of distress felt in the UK at the height of the GFC in 2008 when many of these measures were first implemented. As for the bank levy, it should simply be called out for what it is: a tax on a highly profitable subset of five Australian banks to help fast-track a future budget surplus. Despite attempts to retrofit an underlying social purpose, the levy will not in any way “level the playing field” between the major banks, the regional banks, smaller ADIs and non-bank financial institutions. In the UK, the bank levy was in direct response to the taxpayer-funded bailouts of Lloyds TSB, HBOS and Royal Bank of Scotland in 2008/09, not simply a function of the
government’s desire to fill a long-term revenue hole in its budget. More worrying from a non-bank financial institution’s perspective was the following statement released by the Treasurer on budget night: “The government will also provide APRA with $2.6 million over four years from 2017–18 to allow APRA to
GIVEN
20
www.brokernews.com.au
They are far from being systemic or “too big to fail” and are almost exclusively funded via the wholesale debt capital markets, meaning they rely on the issuance of residential mortgage-backed securities (RMBS) to highly sophisticated financial investors both in Australia and offshore to provide their long-term source of funding. The Australian RMBS market is one of the most successful, liquid and wellregarded securitisation markets in the world. Sophisticated investors effectively regulate the types of mortgages underwritten by Australia’s non-bank lenders by requiring them to only issue securities backed by high-quality mortgage pools, which do not have excessive concentrations of loans by geographic region or product type. Why does the government need to tinker with this highly efficient market and the key source of competitive funding for Australia’s non-bank financial institutions? We should all be concerned by the unintended consequences of APRA being directed by the government to extend its prudential oversight to the non-bank
I’m hoping the government does not go down the path of regulating the non-bank sector out of existence
Patrick Tuttle Former co-CEO of Pepper Group, Australia’s largest non-bank mortgage lender
exercise new powers over the provision of credit by lenders that are outside the traditional banking sector. The government will also make it clear that APRA has the ability to use geographically-based restrictions on the provision of credit where APRA considers it appropriate.” The question remains as to what these mysterious “new powers over the provision of credit” are, and why they are needed in the first place. Fair enough that APRA has implemented macroprudential controls to limit the overall proportion of ADI lending directed towards investment property loans and interest-only loans. This has eased some excessive lending volumes across the broader market, particularly within the major banks. That said, is the government, through the auspices of APRA, now seeking to effectively dictate consumer credit and lending policies and practices for all non-bank financial institutions in Australia? If so, when was this objective ever stipulated in APRA’s mandate? Isn’t ASIC responsible for overseeing Australia’s non-bank financial institutions? Australia’s non-bank financial institutions only represent a small percentage of the total residential mortgage lending market.
finance sector. It could result in APRA imposing excessive controls that will impede the smooth functioning of this very successful, highly competitive and customer-focused segment of the Australian mortgage industry. It will also potentially create regulatory chaos between APRA and ASIC. By seeking to excessively regulate the non-bank sector, which is already subject to comprehensive regulation by ASIC, there is a real risk that the supply of credit to legitimate borrowers for legitimate purposes will dry up altogether, depriving consumers of genuine choice and inadvertently accelerating a credit crunch and a sharperthan-anticipated correction in house prices. I’ve no doubt that such an outcome would be unintended. But how often have well-meaning politicians and regulators delivered unexpected, unintended and unwelcome financial outcomes which adversely impact everyday punters? Hopefully common sense will prevail. I’m hoping the government does not go down the path of regulating the non-bank sector out of existence, thereby killing a healthy and viable source of competition within the Australian housing and home lending markets. AB
IN THE NE WS
BANK LEVY DELAYED ABA CEO Anna Bligh says the government has finally acknowledged that the bank levy is a tax on all Australians, reports Miklos Bolza documents from any bank affected by the levy and to report publicly on its findings.” The Treasurer said he expected the banks to balance the needs of borrowers, savers, shareholders and the wider community following
changes to the legislation proved they had to make some concessions after the banks explained the complexity of the levy and lobbied for amendments. “The government’s own figures and the government’s own
“The government’s own figures and the government’s own documents can see that the impact of this tax is likely to fall on savers, borrowers, lenders and shareholders”
Anna Bligh, CEO, Australian Bankers’ Association
Scott Morrison has delayed the first payment of the controversial bank levy, arguing that any added costs will be no excuse for the big lenders to alter mortgage or deposit rates. In his second reading of the Major Bank Levy Bill in Parliament House, Morrison said the first levy calculation and instalment would be postponed by three months, with the first payment now occurring on 21 March 2018. “The government is working with the banks to ensure a smooth transition to the new regime. To assist major banks to begin to comply with the levy, the first levy calculation and instalment will be delayed by three months – at no cost to revenue – to provide additional time for banks to make necessary systems changes,” he said. This means that the banks will have to pay for both the September and December quarters for 2017 on the same day. The levy for the 2018 March quarter will be payable TREASURER
on 21 June while the levy for the June quarter will be payable on 21 September. The levy does not give the banks an excuse to increase costs for customers, Morrison added. “That is why the government has directed the ACCC to undertake an inquiry into residential mortgage pricing. The ACCC will be able to use its information-gathering powers to obtain and scrutinise
the introduction of the levy. “The ACCC inquiry will illuminate how the banks respond to the introduction of the levy and give all Australians the information they need to get a better deal elsewhere from any of the more than 100 other banks, credit unions and building societies, as well as other non-bank competitors.” However, CEO of the Australian Bankers’ Association Anna Bligh said the tax had already had an impact on the public. Since the budget day announcement, $39bn had been wiped off the market value of the five largest banks, affecting anyone with superannuation, she said. Bligh said the government’s
documents can see that the impact of this tax is likely to fall on savers, borrowers, lenders and shareholders. It is a concession at last and an acknowledgement from the government that this is a tax on all Australians,” Bligh said at a news conference. “If this is a tax for budget repair then it is only fair that it be removed when the budget is repaired.” In his speech to Parliament, Morrison also effectively said the levy would not be raised, keeping the level at the previously proposed 0.06% per annum for any eligible licensed entity liabilities at the big five banks. AB
BUDGET REVENUE Source: Deloitte Federal Budget Report 2017–18
8,000 7,000 6,000
Bank levy
5,000 $m
Medicare levy
4,000
Total treasury revenue
3,000 2,000 1,000 0
2017–18
2018–19
2019–20
2020–21
www.brokernews.com.au
21
22
www.brokernews.com.au
PEOPLE
Have an interesting deal? Had a particularly difficult or interesting deal? Why not share it with us? Email:
Otiena.Ellwand@keymedia.com.au
A BIG DEAL
Nobody wanted to touch Scott Juda from Accrue Equity’s complex home loan deal backed by a rural family guarantor, but with tenacity and extensive research, he succeeded despite the odds
THE FACTS
Loan size $600,000
Loan term 30 years
Client Young working couple
Goal Purchase their first home
Lender CBA
spoke to people they referred me to in business banking, agribusiness, and even other award-winning rural brokers. Nobody in agribusiness would touch it because it was for a home loan, and no residential channel would touch it because there was a commercial security.
THE SCENARIO
The applicants, a young couple, wanted to purchase an owner-occupied property in Sydney using a family guarantee to cover the deposit. The purchase price was around $750,000 and they had funds for stamp duty and legal costs, etc., but they wanted to use a family guarantee for 20%. The problem was the parents [guarantors] had multiple parcels of rural land in regional NSW, and the land sizes were all larger than any lender’s acceptable rural limits. They were also primary production parcels. The guarantors wanted to offer the smaller of the blocks, which would have provided ample security regarding value and marketability. I’d been advised by a few lenders to cash out funds against the land to gift to the children [applicants], although the preference is to provide a guarantee so the children make the full repayments. The guarantor and borrowers don’t want the hassle of having split debts and repayments, not to mention, I’m pretty sure this is against most policies to ‘on-lend’. It’s worth noting that the land was marketable, which reduces the overall risk to the guarantors and bank as the residence is on the largest block. In the event that the lender would have to take the security, it’s in the lender’s best interest as there is still ample land to generate income and also to retain the family home. After talking to nearly every one of my BDMs and calling the credit hotlines twice to make sure, I
Location Sydney
guarantor’s security size, zoning and type of land use was out of the scope of the lender’s standard security policy. I then went back to the lender’s policies for guarantees, first home buyers and security to pull out the sections that were relevant to this deal, and I addressed the concerns in each policy. I compiled more notes and went back to my BDM and credit. I invested more time breaking down the details of the deal, addressing the potential risks to the borrowers, guarantors and lender. Once that was done, I then addressed how these risks had been mitigated within the structure of the deal and the common sense approach as to what would happen in the event of different circumstances. I also used the bank’s policy to shape another scenario that if the guarantors owned a studio apartment in Sydney to offer as security, which was worth significantly less and produced less income, the deal would have been a no-brainer and would have been approved straight away. Why should this have been treated differently? The deal was finally approved with some additional information to add comfort. The clients found their property shortly after and are now settling into their first home. THE TAKEAWAY
I learned that it’s worth fighting the good
I felt like I had hit a wall and nobody could assist my client or me as it appeared that nobody had ever tried this before I felt like I had hit a wall and nobody could assist my client or me as it appeared that nobody had ever tried this before. The only option was for land to be sold to release cash. THE SOLUTION
Scott Juda Finance broker at Accrue Equity in Sydney
I never give up. I just couldn’t believe that our farmers seem to get such a bad run with the banks. It made absolutely no sense to me that this couldn’t be done. I managed to find policies with one particular lender that were close enough to match to this scenario, but there were going to be a few exceptions required to get this across the line. Writing a strong credit memorandum was critical to address all these points. My BDM helped get it in front of the right people in credit to take a serious look at it. The application was declined initially as the
fight. I knew there was a deal to be done as someone should want these great clients. My clients are over the moon. The night before the approval finally came through, they had basically given up all hope and were thinking about starting to make other plans for their future. We have the ability to help people. We have transparency across a multitude of lenders and their policies, credit teams and BDMs, which give us the ability to find solutions. This is one of our biggest competitive advantages as brokers, which doesn’t just make the process easy for our clients, but possible. I’m proud to have been able to assist my clients in achieving their dream. From all the people who I had contacted during this process, the time and effort it took, and the research involved, I’m confident there would have been very few brokers or bank lenders that could have written this deal. AB www.brokernews.com.au
23
PEOPLE
Get involved in the discussion Share your thoughts at
brokernews.com.au
FROM THE FORUM
Top comments from trending stories on brokernews.com.au
ACCC MAY TURN EYE ON BROKERS
COMMISSION CHANGES COULD HAMMER MORTGAGE FRANCHISE
New powers given to Australia’s competition watchdog may go beyond simply asking banks to explain rate rises. Rod Sims, chairman of the ACCC, has indicated that the regulator could widen its scope to include second-tier banks and mortgage brokers. “Eventually we could look at a range of things, but for this first year, if we judge that the broker market needed to be looked at, we could do that,” he told Guardian Australia. “We haven’t formed that view yet. We’re just really focused on getting information from the five banks.” A spokesperson told Australian Broker that a new Financial Sector Competition Unit was being established to look into competition issues across the industry.
Future decisions to decrease broker commissions could have a negative impact on mortgage franchises. Investment research firm Morningstar looked at the headwinds facing Mortgage Choice and determined that although it’s performing well now, potential changes to broker commission could have detrimental effects. Mortgage Choice pays franchisees 73% of upfront and 61% of trail received from lenders, putting it in a good position to pass on the negative impact of lower commission rates to franchise owners, analysts said. Despite the company’s strong market presence, it has been losing market share of the broker segment as smaller players take a cut of the commission themselves, potentially leading to higher turnover.
Anything that shines more light on the “profit-procedures” of the banks will help our industry. The biggest threat to mortgage broking is still the lack of understanding and naivety amongst the general population of how (and why!) banks operate.
I never realised how much meat MC takes from the bone – there must be lots of fat in the hierarchy – at those splits one would have to be doubling up as an Uber Driver to feed the family.
Simon on 24/05/17 at 9:19 AM
Clarke Kent on 27/05/17 at 8:38 AM
Good, focus on us. Find out that we review our clients annually to make sure they’re on the best pricing. Find out that when every fixed rate comes off we ring the client and find out what’s best for them. Find out that most brokers are passionate about getting their clients the best deal. Find out that brokers don’t churn unless the client actually saves money by moving. (Or it’s already illegal.) Then maybe they’ll realise it’s the banks who screw over their existing customers, not brokers. Keeping existing clients on higher rates is how the banks take advantage of apathetic borrowers. Lucky my clients have me.
‘Putting it in a good position to pass on the negative impact of lower commission rates to franchise owners’ … Sounds to me like they should be cutting some ‘fat’ from the top! Why would anyone buy into that model?
Broker who cares on 24/05/17 at 9:24 AM
The greatest growth industry in Australia is in compliance and regulation. No value is added by this. Australia is now the most expensive place in the world to do business.
Tough times! on 26/05/17 at 10:32 AM
It’s hard to believe that brokers promote to their clients to save on the mortgage by offering a refinance, yet stay on commission splits (perhaps handcuffs/exit fees are the reason they stay?). But any broker who hasn’t reviewed their commissions split arrangements/franchise/ aggregator agreements, etc., is no different to a customer who banks with CBA, for example, and has always done all of their lending with them as it’s all they know! Cubeman on 29/05/17 at 9:22 AM
Nancy on 24/05/17 at 9:38 AM
In my 37 years in finance I have never seen the likes of this government-sponsored witch-hunt of our industry. I’m not defending the banks, but if they are as fed up as I am about constant over-regulation and interference in our industry, it’s no surprise they are thumbing their nose at the government. Through all these reviews there has been no evidence of a systemic problem in our industry. Sure, weed out the bad guys, but let the rest of us get on with helping our clients without the fear of whether or not we will have a sustainable broking business next week. If I could, I would retire right now. Why are we being treated like criminals? Tired on 24/05/17 at 2:23 PM
24
www.brokernews.com.au
Let’s keep it in perspective. The split sounds like a lot, but that’s what they are paying for the brand, advertising and leads. Each to their own. Perspective on 29/05/17 at 9:51 AM
Unfortunately, when an external impact occurs such as lower commissions, franchisors will shore up their profit centre and squeeze the branch. That means $26.50 per hour is now $22 per hour. Why wasn’t I $32 per hour when all was good? Been there and know the outcome. Not good! Mortgage No Choice on 29/05/17 at 10:46 PM
CAUGHT ON CAMERA The MFAA announced the winners of its 2017 NSW State Excellence Awards at a glamorous event at the Hilton in Sydney on 26 May. Out of the 450 submissions received from across the country, the industry association selected 315 finalists from all the states. Those who win at the state awards are eligible to win the national title at the ceremony in Melbourne on 27 July. The awards program recognises businesses that demonstrate the MFAA’s core values of professionalism, integrity, innovation and customer service. This year, the MFAA launched a few new categories, including the motor vehicle and equipment finance broker award, the mutual/specialty lender award, and two BDM awards, one for best aggregator BDM and the other for best lender/support service provider BDM. The judging process was conducted by independent industry professionals.
www.brokernews.com.au
25
DATA
NEW SOUTH WALES
SOUTH AUSTR ALIA SPOTLIGHT
Investment activity in Sydney is stalling at present “Investment activity is driven by a range of factors; it’s driven by sentiment, by people looking at the market and wondering where prices are going,” explains Rich Harvey, CEO of PropertyBuyer.com.au. “Some people in Sydney and Melbourne realise that prices won’t keep rising forever. Property markets do go through cycles, and even investors can still do well buying in Sydney and Melbourne if they know what to buy and where to buy for value.” The key to investing in a market that is peaking or topping out is strategy, Harvey says. To help address affordability problems experienced by first home buyers, unit developer Mirvac has implemented a plan to earmark some off-the-plan apartments for only a 5% deposit. But while AMP Capital chief economist Shane Oliver applauds this initiative, he believes more can be done. “We need structural change to improve the balance for first home buyers,” Oliver says. Area
Type Median value
Quarterly
12-month
growth
growth
Sydney
H
$935,000
-1.1%
4.2%
NSW Country
H
$435,000
1.2%
6.3%
Sydney
U
$705,000
1.4%
3.7%
NSW Country
U
$369,000
5.4%
3.5%
VICTORIA
Mixed messages from Melbourne’s property market As things stand, inner Melbourne appears to be gearing up to face an oversupply issue, which will affect growth rates. Melbourne, Southbank and Docklands have been highlighted by the ABS as the most at-risk suburbs, given that they are the sites of nearly half the 35,560 units to be released to the market in the next couple of years. Some factors that could deter interest include strict lending conditions and the ‘blacklisting’ of risky suburbs like Melbourne. In the latter case, buyers need to make a deposit of at least 20–30% in order to secure a unit. Meanwhile, the former primarily affects overseas investors and comes as a result of the RBA’s fear that apartment prices will plummet. Thus, investors ought to pay careful attention to the cons when looking into inner Melbourne’s unit market. By contrast, the house market reports low levels of supply in the inner city. Investors are therefore guaranteed good medium- and long-term returns.
BALANCED SUPPLY AND DEMAND Adelaide has experienced a slight boost over the past few months, and investors from other states are eyeing its potential South Australia’s economic troubles, Adelaide’s property market has been doing a good job of ensuring that demand and supply are balanced. “South Australia is very affordable for even the novice investor right up to the seasoned professional,” says Prue Muirhead, director of Muirhead Property Management and Your Investment Property’s 2010 Investor of the Year. “There are mini markets all around [the state] that have some fantastic capital growth. [Meanwhile,] some suburbs in Adelaide, like Port Noarlunga and Christies Beach, show very obvious signs of gentrification and new developments at a rapid rate.” In addition, the rental market is showing positive signs due to considerable demand. This is drawing investors, particularly from the eastern states, who are looking to capitalise on the solid yields. “Returns on rent in these markets should provide 5.5% on average for houses, with up to 6% for the purchase of an undervalued property,” Muirhead says. “Townhouses in these suburbs would bring approximately 5.5% returns but would have greater vacancy times as they appeal to a smaller market of renters. Generally, yields in South Australia will be higher for a unit than a house.” DESPITE
Type Median value
Quarterly
12-month
growth
growth
Adelaide: Australia’s ‘steady as you go’ state? Experiencing neither boom nor bust, Adelaide’s mortgage broking industry tends not to have the issues some states have with regard to valuations. We don’t have the massive infrastructure investments of other capital cities with estates, units and apartments popping up everywhere – the result of which makes it difficult for valuers to assess new property values with any degree of comfort, leading to a ‘conservative’ approach. Valuations in Adelaide tend not to have the same challenges; it’s a known market with a spread of industries underpinning consistent, albeit small, growth. Tighter restrictions on investor lending are seeing a decline in investor demand interstate, and we see this flowing back into the Adelaide market. The fact is we have the most affordable housing in mainland Australia, with the often talked about bubble being less likely to occur here than anywhere else. The challenges of course are loan sizes; I am often envious of our Sydney cousins writing that one loan for $1.5m; it takes me three or four loans to get there!
Units pose oversupply risk Nonetheless, demand remains stronger for houses than for units. “The majority of tenants are looking for a house with a yard. A house also provides options for development if the land is
David Garner Director, Go Loans in Kent Town, SA
HIGHEST-YIELD SUBURBS IN SOUTH AUSTRALIA Suburb
Area
BROKER PERSPECTIVE
Type
Median price
Weekly median advertised rent
Gross rental yield
Coober Pedy
H
$65,000
$170
14%
Melbourne
H
$660,000
2.8%
5.9%
Peterborough
H
$84,000
$158
10%
VIC Country
H
$322,500
2.4%
1.9%
Port Pirie West
H
$109,500
$200
9%
Melbourne
U
$490,000
-1.0%
0.6%
Whyalla Norrie
U
$92,875
$160
9%
VIC Country
U
$254,000
-0.4%
2.0%
Elizabeth South
U
$139,500
$225
8%
26
www.brokernews.com.au
OPPORTUNITIES AND KEY INFRASTRUCTURE
WESTERN AUSTRALIA
Is Perth’s economy evolving?
O-Bahn Access Project
Adelaide Bikeway
Morphettville
Streetscaping
Government builds a stronger public transport network in Adelaide
Upgrades continue on the busiest cycling route in Australia
Redevelopment is expected to bring 200 homes to the area
Laneways linking the Market and Riverbank areas get spruced up
sufficient in size,” Muirhead explains. “Generally speaking, tenants wanting to rent a home are more stable [in the] long term than tenants wishing to rent a unit.” Residents see unit rentals as being shortterm, and this low demand hits hard as more properties come onto the market in the same areas, such as the CBD and Glenelg. Thus, oversupply is a real concern.
At present, the key to succeeding in the SA market is to be able to hold on for longterm gains. “Consider buying properties with a land component that presents a future development option, or simply buy and don’t sell,” suggests Muirhead. “Just hold on for the long term and enjoy the better-than-national-average rental returns.” AB
SUBURB TO WATCH: HOPE VALLEY Median price (houses) $388,791
Median price (units) $278,884
The average vacancy rate in Perth is currently nearly 5%, which suggests that properties are difficult to lease out and rents are very low. With the constant drop in prices, however, the city is looking quite appealing to investors, especially with word that the economy could be on the verge of going up gradually. “There’s been a bit of an upturn in mining exports recently, which will give a boost to incomes and property prices in mining-focused areas like Perth,” says Steve Jovcevski, property investment and lending expert at Mozo.com.au. “A Perth investment has all the fundamentals of a good property buy. It’s a major city, with plenty of infrastructure and potential for growth in jobs and population. That means that even if there’s a slump at the moment, chances are the market will revive.” Nonetheless, Jovcevski agrees that investors must be prepared to handle the financial risks of investing in a market that’s in the midst of a slump.
Area
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
4.3%
10.3%
17.0%
4.5%
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
-4.9%
1.3%
11.7%
5.4%
Type Median value
Quarterly
12-month
growth
growth
Perth
H
$510,000
-1.5%
-3.5%
WA Country
H
$368,000
5.4%
-6.5%
Perth
U
$404,500
-3.7%
-2.6%
WA Country
U
$295,000
13.5%
-8.2%
www.brokernews.com.au
27
DATA
QUEENSLAND
CAPITAL CITY AUCTION CLEARANCE RATES
In the city, houses on smaller lots are becoming popular with buyers for lifestyle reasons
WEEK ENDING 18 MAY 2017
Houses on small lots are “a great alternative for people who still want to be able to have a pet, have control of their property, have very little maintenance, and be without any body corporate fees”, says Mark Bellingham, agent for Purple Bricks Queensland. First home buyers are also prepared to compromise on lot size if it means affordability, especially if it comes with convenience and accessibility. “People are always going to have some sort of block of land, but they’re also reticent to go further out. They want to stay closer to work,” explains Scott Hay, agent for Place Estate Agents in Coorparoo. “If I had more properties on small lots, I would sell them really quickly. I’d say that normally developers are buying blocks and putting apartments up, but with the current state of that market, that could change and we could see more of these small-lot homes go up.” Quarterly
12-month
growth
growth
Brisbane
H
$520,000
1.0%
4.0%
QLD Country
H
$420,000
-2.3%
1.5%
Brisbane
U
$400,000
-3.6%
-2.4%
QLD Country
U
$365,000
-2.7%
3.4%
58
Not sold
34
Clearance rate
63.0%
PERTH Total auctions
32
Sold
8
Not sold
11
Clearance rate
42.1%
Quarterly
12-month
growth
growth
$633,750
-1.3%
4.3%
Canberra
U
$426,100
-2.0%
1.2%
Sydney Melbourne Brisbane Adelaide
Perth
Hobart
Darwin
$409,000
$600,000
$310,786
$373,500
$410,000
$0
$505,000
$100,000
$331,000
$200,000
$450,000
$300,000
$392,000
$500,000 $400,000
$519,000
$700,000 $600,000
$535,000
$800,000
Units
$650,000
Houses
$705,000
$900,000
H
www.brokernews.com.au
Sold
$1,100,000
Canberra
28
102
$1,000,000
The anticipated establishment of a unit complex on the old site of Downer Primary School in Canberra is expected to boost the local retail industry, which will be revived in the near future. The unemployment rate is also falling in this city, having clocked in at 4.6% in February, showing a decline since last year. This reflects the successful outcome of the city generating over 7,000 jobs in 2016. In the process, however, the rental market has tightened for tenants, with rents spiking in the past 12 months even with considerable increases in investor activity. The rise in rents is supported by falling vacancy rates, which could make residents feel like they have little choice. Nonetheless, this just goes to show how Canberra has been coming out as top player in the national property market. Nick Georgalis, managing director of Downer unit complex ‘Midnight’, puts it best: “It’s not the bush capital; it’s an emerging city.”
Type Median value
Total auctions
MEDIAN HOUSE AND UNIT PRICES
Migration and supply do not just translate to positives for the property market; their impact extends to the economy as well
Area
ADELAIDE
$385,000
AUSTRALIAN CAPITAL TERRITORY
$971,500
Type Median value
$750,000
Area
The number of auctions scheduled to take place in the capital cities was projected to rise, especially in the two major markets of Melbourne and Sydney, according to CoreLogic’s auction market preview released 18 May. More than 2,600 auctions were being tracked by CoreLogic at the end of May, a higher number than the 1,920 auctions held over the same week in 2016. The number of auctions was also up from about 2,400 auctions held the week before. Across the smaller markets, volumes were also expected to increase, with the exception of Canberra, where volumes were expected to remain relatively steady. Kew and St Kilda in Victoria were the two busiest suburbs for auctions across the nation at the end of May, with 19 and 18 residential homes set to go under the hammer respectively, followed closely by Essendon and Mount Waverley, each with 17 auctions, both also in Victoria.
Canberra
CAPITAL CITY HOME VALUE CHANGES Capital city
Weekly change
Monthly change
Year-to-date change
12-month change
Sydney
0.0%
-1.0%
3.6%
11.4%
Melbourne
0.3%
-1.9%
3.1%
11.8%
Brisbane
-0.4%
-0.1%
1.6%
3.7%
Adelaide
0.8%
1.5%
3.7%
3.4%
Perth
1.1%
0.5%
-1.8%
-2.2%
Combined 5 capitals
0.2%
-0.9%
2.7%
8.8%
*Brisbane results are for the combined Brisbane and Gold Coast region. The monthly change is the change over the past 28 days.
BRISBANE CANBERRA Total auctions
80
Sold
52
Not sold
18
Clearance rate
Total auctions
128
Sold
59
Not Sold
41
Clearance rate
59.0%
74.3%
SYDNEY Total auctions
960
Sold
656
Not sold
225
Clearance rate
TASMANIA
MELBOURNE Total auctions
74.5%
1,098
Total auctions
9
Sold
776
Sold
2
Not sold
258
Not sold
6
Clearance rate
Clearance rate
75.0%
TASMANIA
Investors can reap high yields by leasing out properties in the Greater Hobart region Many buyers are choosing to rent out dwellings in Greater Hobart rather than occupy them personally. “With the strong yields in the rental market many properties are or are near positively geared, which allows owners to pay down their mortgages so payments are manageable when they choose to move into the property,” HTW indicates. As a whole, though, rental rates have fallen in Tasmania. “[This] could mean investors could come under pressure with an influx of rental stock on the market. Landlords should be cautious when looking to invest here,” says Charles Tarbey, chairman and owner of Century 21 Australasia.
Area
25.0%
Type
Median value
Quarterly growth
12-month growth
Hobart
H
$390,000
4.0%
4.6%
TAS Country
H
$270,000
3.8%
0.0%
Hobart
U
$300,000
6.6%
2.7%
TAS Country
U
$227,500
-0.5%
0.0%
Source: All data sourced from CoreLogic.com.au
www.brokernews.com.au
29
PEOPLE
IN THE HOT SEAT Kylie Platt is more than just a broker. She’s a YouTube star, a Bette Midler fan and a director of award-winning brokerage The Local Loan Company. She explains how her team won the Community Champion and Diversified Business awards at the MFAA WA conference Who or what inspired you to become a broker? I decided to become a broker when my children were young A and I was looking at getting back into the workforce. I knew I wanted a career that I could grow in as my children grew, and one that I could work around school hours. I wanted to assist people with their finances, educate them, have fun and be on a constant learning journey.
Q
How did it feel to win two MFAA awards at the WA conference? My business partner, Susan Lepidi, and I have a fabulous team A and it was a fantastic reward for our hard work. We have a vision of being a truly diversified business where our clients turn to us for all things finance – and we have put a lot of time and effort into developing this. The Community Champion award is really special – we have tried to contribute to several smaller causes/charities that need a helping hand.
Q
What sets your brokerage apart? We are blessed that our clients really support us. They have A come with us on this journey and we all feel like a family. We treat everyone equally and we have refined our customer service process, which has led to unbelievable loyalty and fantastic referrals from our clients. They are our best advocates. Our team is such a big part of our success; we all work towards the same goals.
Q
If you could work part-time as a broker and part-time as something else, what would your dream second job be? After having made videos for The Local Loan Company and our A financial education YouTube channel, Money Money Money, I have to say a TV presenter. It’s nerve-wracking, but great fun. Or even better, a champagne taster. Now that is truly a dream job I am qualified for!
Q
If you could meet any living celebrity or notable person, who would it be and why? Bette Midler. She is funny, she can sing, and she was unafraid A to blaze a trail. The Divine Miss M is still working at 71 on Broadway and her devotion to charity work is inspirational. I love that she is passionate – agree or disagree with her, you can’t help but admire her passion. AB
Q
30
www.brokernews.com.au
NOMINATIONS NOW OPEN
Friday 27 October • The Star Sydney www.australianmortgageawards.com.au Event Partner
Award sponsors
Official publications
Organised by
www.brokernews.com.au
31
32
www.brokernews.com.au