MAY 2017 ISSUE 14.10
Federal budget cheat sheet Industry experts explain key areas of the budget and how they’ll affect brokers /18
Brokers’ SME influence NAB launches small business toolkit to help brokers diversify /16
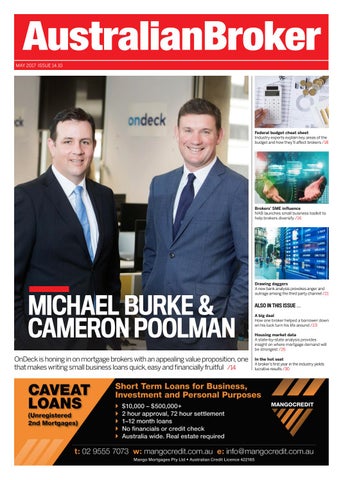
MICHAEL BURKE & CAMERON POOLMAN OnDeck is honing in on mortgage brokers with an appealing value proposition, one that makes writing small business loans quick, easy and financially fruitful /14
Drawing daggers A new bank analysis provokes anger and outrage among the third party channel /21
ALSO IN THIS ISSUE … A big deal How one broker helped a borrower down on his luck turn his life around /23 Housing market data A state-by-state analysis provides insight on where mortgage demand will be strongest /26 In the hot seat A broker’s first year in the industry yields lucrative results /30
NEWS
IN THIS SECTION
Lenders HSBC is back in business with Aussie brokers /04
Associations Banks say new levy is a tax on all Australians /06
Technology Fintech enables the borrower to become the broker /10
Commercial ASIC promises action on banks over fair SME contracts /12
Consumers Social media campaign urges public to take a stand against banks /08
www.brokernews.com.au MAY 2O17 EDITORIAL Editor Otiena Ellwand News Editor Miklos Bolza Production Editors Roslyn Meredith, Bruce Pitchers
DATES TO WATCH
Upcoming industry events and key dates
ART & PRODUCTION
3 1 M AY – 2 0 J U N E Pepper Money’s Insights Roadshow Following the success of the 2016 event, Pepper Money’s Insights Roadshow is back with masterclasses on specialist lending on various dates in Melbourne, Brisbane, Perth, Adelaide and Sydney
7 JUNE
8 JUNE
Regtech Australia Forum
Banking and Finance Ethics conference
InnovationAus.com is hosting a number of speakers at this forum in Sydney to discuss the biggest challenge affecting the financial services sector: regulatory compliance and the role of technology in that space
This Sydney conference provides an opportunity for those in banking and finance to openly discuss and explore ethical issues that are contributing to the erosion of public trust in the industry
SALES & MARKETING Sales Manager Simon Kerslake Account Manager Rajan Khatak Marketing and Communications Manager Lisa Narroway
CORPORATE
Design Manager Daniel Williams
Chief Executive Officer Mike Shipley
Designer Martin Cosme
Chief Operating Officer George Walmsley
Production Manager Alicia Chin Traffic Coordinator Freya Demegilio
Managing Director Justin Kennedy Publisher Simon Kerslake Chief Information Officer Colin Chan Human Resources Manager Julia Bookallil
EDITORIAL ENQUIRIES
Otiena Ellwand +61 2 8437 4792 Otiena.Ellwand@keymedia.com.au
SUBSCRIPTION ENQUIRIES
tel: +61 2 8O11 4992 fax: +61 2 9439 4599 subscriptions@keymedia.com.au
16 JUNE
30 JUNE
Housing Affordability
End of ASIC public consultation
Assistant Minister to the Treasurer Michael Sukkar provides strategies and insights to address housing affordability at a lunchtime speech in Melbourne
Don’t miss the chance to have your say on ASIC’s review of mortgage broker remuneration. Interested parties are encouraged to submit feedback via the government’s Treasury website until 30 June
1 8 J U LY – 3 A U G U S T Women in Business FAST is hosting five state conferences specifically geared towards helping women succeed in broking. Women have been recognised by a number of aggregators as a growing segment of the industry
ADVERTISING ENQUIRIES
Simon Kerslake +61 2 8437 4786 simon.kerslake@keymedia.com.au Rajan Khatak +61 2 8437 4772 rajan.khatak@keymedia.com.au Key Media Pty Ltd Regional head office, Level 1O, 1–9 Chandos St, St Leonards, NSW 2065, Australia tel: +61 2 8437 4700 fax: +61 2 9439 4599 www.keymedia.com Offices in Sydney, Auckland, Denver, London, Toronto, Manila, Singapore, Bengaluru
2 7 J U LY
16 AUGUST
MFAA National Excellence Awards
National Finance Brokers Day
The MFAA has announced 315 finalists for its upcoming awards program selected from more than 450 submissions. The awards recognise the association’s core values, including professionalism and integrity. The national event will be held in Melbourne
Dino Pacella founded this day back in 2015 to celebrate brokers and educate consumers. The goal this year is to raise $50,000 for sick children through charity drives
2
www.brokernews.com.au
11 - 13 OCTOBER Credit Law Conference The 27th annual event in Surfers Paradise brings together banks, credit unions, regulators, associations and market disruptors to discuss the future of credit and lending
This magazine is printed on paper produced from 1OO% sustainable forestry, grown and managed specifically for the paper pulp industry Copyright is reserved throughout. No part of this publication can be reproduced in whole or part without the express permission of the editor. Contributions are invited, but copies of work should be kept, as Australian Broker magazine can accept no responsibility for loss. Australian Broker is the most-often read industry publication, according to independent research carried out by the Ehrenberg-Bass Institute for Marketing Science at the University of South Australia in December 2008. The research also found that brokers rate Australian Broker as the best for both news content and feature articles, followed by sister publication MPA. Overall, on all categories, Australian Broker ranks top followed by MPA. The results were based on a sample of 405 respondents who were the subject of telephone interviews.
NEWS
LENDERS BANKS’ HALF-YEAR RESULTS “SUBDUED”, ANALYSTS SAY
HOUSING FINANCE FIGURES Source: ABS Housing Finance Figures, March 2017
Value of dwelling commitments Total dwellings
is “little to get excited about” looking at the banks’ latest financial results, with global investment bank UBS calling it a period of “subdued” activity and flat revenue. “Following a period of anticipation given mortgage repricing, the banks’ results were a bit of a fizzer,” analysts wrote in the UBS Banking Sector Update. ANZ’s revenue fell 2.8%, excluding property sales. NAB was down 0.2% and Westpac was down 0.1%. Commonwealth Bank’s revenue rose 3.4% (excluding Visa share sales). THERE
$m
Trend Seasonally Adjusted
has announced changes to its interest only loans in compliance with government efforts to reduce banks’ exposure to this type of asset. Effective 29 May, the maximum interest only period will be reduced from 10 years to five to allow “investment lending to align to the maximum for owner occupier lending”. This new provision will apply to all ANZ home loan and residential investment loan products. It will also waive the renegotiation fee for customers who want to shift their interest only to P&I repayments.
“[Having] HSBC want to jump into the industry is a real sign of confidence of where mortgage broking is going.”
James Symond CEO, Aussie Home Loans
4
www.brokernews.com.au
Mar
Jun
Sep
Dec
2016
33,500
32,500
32,500
31,500
31,500
30,500
30,500
29,500
29,500
Mar
Mar
2017
2016
Jun
The global bank’s products will be available exclusively through Aussie Home Loans’ brokers, starting in June is partnering with Aussie Home Loans to return to the Australian mortgage broking space after a 10-year hiatus, something Aussie CEO James Symond sees as a “vote of confidence” for his company and the industry as a whole. “Having the quality of an organisation like HSBC want to jump into the industry is a real sign of confidence of where mortgage broking is going,” he said. “Considering the ASIC report, Sedgwick report, bank levies; considering all the complications that the mortgage broking market always gets, it is such a good thing for the industry. HSBC is such a prestigious, prominent, global player and for them to be jumping into the
34,500
33,500
HSBC MAKES ITS BROKER-CHANNEL COMEBACK
HSBC
$m
Trend Seasonally Adjusted
34,500
ANZ TIGHTENS INTEREST ONLY LENDING PORTFOLIO ANZ
Value of dwelling commitments Owner occupied housing
mortgage broking marketplace is not to be underestimated in terms of the confidence they have in the industry.” The move marks HSBC’s bid to “reach out and resonate” with more customers – including non-residents who are “global premier clients” with the bank – following strong growth over the last few years, Alice Del Vecchio, HSBC Australia’s head of mortgages and third party distribution, said on 17 May. While she said HSBC is known for accommodating affluent customers and complex lending needs, the products will resonate with any consumer who wants good value outside the big four. “We do attract internationally minded customers. We know that,
Sep
Dec
Mar 2017
but I think the brand is so much bigger than that, and most of the consumers who come through and are on board are local Aussies just looking for better value.” The bank will roll out accreditation and online training throughout the month of June, with bank staff meeting as many Aussie brokers as possible face to face. The loans will be available exclusively through Aussie-branded brokers at first, but Del Veccio said HSBC has been in discussion with other groups. HSBC made the news in 2015 when it scaled back its lending to property investors in the wake of APRA’s decision to apply growth caps on investor lending at the end of 2014. APRA’s latest lending data shows HSBC’s loan book to be valued at $11.1bn, with more than half of that attributed to owner occupiers ($6.3bn). To put this into perspective, Citigroup has $6.8bn in housing loans and ING Direct has $41.8bn.
NEWS
A S S O C I AT I O N S BROKERS ORIGINATED MORE THAN HALF OF NEW LOANS boosted their market share in the March 2017 quarter, writing 53.6% of new residential home loans, according to Comparator, a CoreLogic research group. The results are based on data sourced from 19 brokers groups and aggregators. This was an increase from the 51.9% result in the December 2016 quarter, but was slightly down from the same quarter in March 2016, which was 53.7%. Finance brokers originated an estimated $46bn in new home loans, including home loan refinancing. BROKERS
FIRSTMAC AFTER-PARTY TO BE HELD AT FBAA EVENT a non-bank lender, has announced that its renowned late-night party will now be held after the FBAA’s national conference, instead of the MFAA’s event, which it has been a staple of since the early 2000s. Firstmac founder Kim Cannon said the decision was made after the MFAA switched to state-based conferences in 2016. “The annual conference was an industrywide event and not just a broker event,” he told Australian Broker. “It was an annual get-together of the industry to talk shop, and if brokers did turn up you could network with the various brokers and managers.” FIRSTMAC,
ABA DEMANDS FURTHER DETAILS ON BANK LEVY The industry association says it is “unacceptable” to keep the banks in the dark Australian Bankers’ Assocation (ABA) has asked for further information about the $6.2bn bank levy proposed in the 10 May federal budget. In a letter sent to Treasurer Scott Morrison on 12 May, ABA chief executive Anna Bligh said additional details were required if the banks were to comment on the draft legislation. The ABA has requested the following data from the Treasury: modelling on the economic impacts of the bank levy, including on households and businesses; technical analysis laying the foundations for the design of the tax, including how it would cover the banks; assumptions of total revenue projections collected from the bank levy over the forward estimates. THE
6
www.brokernews.com.au
Bligh said it was unacceptable to keep the banks and the community in the dark about a project that would have a major impact on the economy. “Senior executives of the major banks in good faith attended what they expected to be a comprehensive briefing from Treasury [on 11 May], only to find to their dismay that Treasury was also in the dark.” She said basic questions about how the tax was calculated and how the figure of $6.2bn was reached had yet to be answered. The meeting was slammed by those who attended, being described by sources as a “complete shambles” in The Australian. “These people were roaming across our balance sheets without any understanding of the components
and the likely impact on the economy,” one attendee told the newspaper. Bligh was sceptical of the government’s ability to be ready to implement the tax by 1 July. “The government seems to be putting intolerable pressure on its Treasury officials to meet a ridiculous political timetable.” She described it as “policy on the run”, which played fast and loose with the banking sector. “Serious questions need to be asked about the indecent haste with which this new bill is being shoehorned into parliament in a way that will avoid normal drafting and review processes and the scrutiny that should accompany such a critically important piece of legislation,” Bligh said. The banks were given until 15 May to make submissions, with the Treasury confirming it would provide draft legislation to the banks on 17 May. The banks will have 24 hours to respond and the draft will not be released for public consultation.
“This new tax is not a well thought-out policy response to a public interest issue, it is a political tax grab to cover a budget black hole.” Anna Bligh CEO, ABA
NEWS
CONSUMERS HOUSING MARKET WARRANTS “MONITORING” RBA has put the spotlight on movements in Australia’s housing market, noting that “careful monitoring” is required. Varying market conditions and excessive growth in housing credit were some of the considerations made when leaving the cash rate at 1.5% earlier this month, the bank’s board meetings released 16 May said. The additional supply of apartments scheduled to be completed over the next couple of years in the eastern capital cities was expected to put some downward pressure on apartment prices. THE
BUDGET WILL HAVE LITTLE IMPACT ON HOUSE PRICES effects of last week’s federal budget will range from negative to neutral, according to global ratings agency Moody’s, which gave an overall pessimistic critique of the government’s proposed measures. The agency said the budget’s housing affordability measure will have “little immediate impact”. While measures such as the first home buyers savings scheme, additional housing supply and further tax exclusions for property investors may improve affordability for local residents over the long term, these measures do not address risks. THE
BUSINESS COUNCIL URGES PUBLIC TO DITCH BANKS THAT RAISE RATES Any rate or fee changes would put further strain on an already financially overburdened public
peak industry body has called the banks “cheeky” for crying poor over the government’s proposed $6.2bn bank levy, and has launched a new campaign urging consumers to abandon those banks that inflate their fees and mortgage rates as a result. The Business Council of Co-operatives and Mutuals (BCCM) said that consumers should “vote with their feet” if the larger lenders hike rates and charges. The five banks affected by the levy have been critical of the government’s move, saying that the levy is not just on banks, but is a tax on every Australian and shareholder. The banks say the levy won’t be absorbed as Treasurer Scott Morrison A
“Switching banks is the best way for consumers to make it clear that they are not walking ATMs for the big banks.” Melina Morrison CEO, Business Council of Co-operatives and Mutuals
suggests, but will instead be put on the consumer. Melina Morrison, CEO of the BCCM, says that when the levy comes into force on 1 July, if the big banks do pass on the burden and Australians find themselves paying more fees or higher rates, they should make the switch to “the banks that consistently top the satisfaction surveys: mutual banks and credit unions”. With a 20 basis point rise already on the table, any change would put further strain on working Australians, she added. She also noted that the banks have already begun an expensive publicity campaign to justify higher fees to the overburdened public. “It is cheeky for the banks
to cry poor. Switching banks is the best way for consumers to make it clear that they are not walking ATMs for the big banks,” she said. Many of the smaller, customer-owned banks provided better value to everyday Australians, she said. “They have the advantage of being owned by their customers, so it’s in their interests to do the right thing by them.” To encourage this switch, the BCCM has launched a new website and social media campaign, #switchdontbitch. “We are urging consumers to switch rather than bitch. And we’re saying that 1 July, the beginning of the new financial year, is a great line in the sand date to make the switch,” Morrison said. She said she hopes people will share their switching stories on social media using the campaign hashtag to show others that there are alternative options and potentially better deals on offer.
AUSTRALIANS’ LIVING ARRANGEMENTS, BY AGE Source: KPMG, The Australian Home Loan Market 2017
% of respondents Young workforce
19%
3%
26%
52%
2% Established workforce
5%
Mature workforce
30% Rent
8
www.brokernews.com.au
59%
Mortgage
33%
61% Own property outright
Occupy without payment
9%
NEWS
TECHNOLOGY
NON-MAJOR UNVEILS MORTGAGE ROBOT -owned digital bank UBank has unveiled a new virtual mortgage AI to streamline how first home buyers and refinancers apply for a home loan. The program, called RoboChat, is now available on the home loan section of UBank’s website and has been trained to guide potential borrowers through the mortgage application process. RoboChat has been built with the IBM Watson Conversation API and gives real-time input to questions around the types of loans on offer, mortgage terms, interest rates and additional features such as redraw facilities. NAB
FINTECH LETS CONSUMERS BE THEIR OWN BROKER The digital platform uses technology to do the work of a mortgage broker, giving the borrower access to the process future of mortgage broking could be at risk with new technology coming on stream that replaces the need for them in the loan process. Fintech company Hero BroKer will soon be launching a platform that empowers the consumer by giving them access to the complete home loan application process for themselves. “By providing the right tools and technology to the borrower, we let them control their finances so they’re not reliant on a broker. They effectively become their own broker,” Clint Howen, founder of Hero BroKer, told Australian Broker. The Hero BroKer model is similar to other technology disruptors, such as Airbnb. THE
“Airbnb looked at a sea of houses. They built a platform that enabled everyone who had a house to be the hotel, instead of trying to be the hotel themselves. They’re the biggest hotel in the world and they don’t own a single property,” Howen said. Hero BroKer takes the borrower through a number of steps before they can obtain a loan. Videos give the borrower extensive explanations and breakdowns of various topics. “For instance, if they want information on a feature like an offset account, a little information icon goes to a video that explains what an offset account is, why would you use it, etc,” Howen said. The more details the platform receives from the borrower, the more specific the final home loan list will be, Howen said.
“They go through those steps and only get shown the loans that match their criteria. Instead of having hundreds of loans like on a comparison site, you’ll only see four or five.” The idea came about after Bowen had a poor experience with a mortgage broker and felt there was a gap in the industry that needed to be filled. “Instead of being a mortgage broker or a broking business, we want to be the largest financial broking platform in the world while not hiring a single broker. We want to let the consumer broker their own loans.” While the banks themselves are open to disruptive fintechs, Howen acknowledges that they are worried about upsetting the large mortgage broking groups who may be threatened by them. “Although the banks are open to new ideas, it’s a risk to do something that will piss off the mortgage broking industry,” he said. “That’s understandable because it is a risk.”
VV EXPECTATIONS VS ACTUAL CUSTOMER EXPERIENCE WHEN TAKING OUT A HOME LOAN Source: KPMG Mortgage Report 2017
-19% +
5
+3%
4.6
4.6 4.0
3.7
3.9
3.7
4.5
4.1 3.7
3.6
Importance
3.6 3.7
-19%
_
Expectations Actual customer experience 1 Empathy
10
*Based on customers’ experience through brokers and financial institutions
www.brokernews.com.au
Personalisation
Integrity and trust
Simplicity
Expectations Resolutions
MAJOR BANK LAUNCHES NEW BROKER PRICING TOOL robots and other disruptive technologies try to get in on the mortgage broker pie, other digital tools are being touted as useful aids to improve the broker-customer experience. One of the latest is NAB’s Instant Pricing Tool for Brokers that aims to provide a faster, simpler method for brokers to find competitive home loan rates for clients. Offering an on-the-spot price while enhancing the loan application process, the technology is an example of how NAB said it is listening to brokers. WHILE
TECHNOLOGY UPDATE
s
ADVANTEDGE AND NEXTGEN.NET TAKE THE LEAD IN STREAMLINING APPLICATIONS
Brett Halliwell
Pivotal to Advantedge Financial Services’ growth (its white label products are now available through 85% of brokers) is an unequivocal commitment to brokers. “We’re broker-centric,” says Advantedge general manager Brett Halliwell. “Our focus is squarely on brokers, which in turn is about helping customers. That means we need to be as efficient and effective as possible to make it easy for brokers to fulfil their role. Partnering this with an innovative IT supplier such as NextGen.Net, we’ve tied everything together.” Speaking about why he’s a fan of the NextGen.Net electronic lodgement service ApplyOnline, Halliwell points to NextGen.Net’s attention to detail. He highlights the broker-ordered valuations service. “We like our brokers to do the valuation upfront prior to submitting the deal, because in our quest to deliver better and faster service for brokers, our preference is to touch a deal once only, and to make that once-only touch an unconditional approval. That’s the ideal scenario and ultimately it means faster turnarounds and better service. “Before we launched the ApplyOnline broker-ordered valuations service, brokers had to order a valuation through one system then jump into another to lodge the deal. It was cumbersome and messy. So NextGen.Net created a solution for us by marrying the two systems, which has produced a more convenient broker experience.” Broker-ordered valuations are now part
Tony Carn
of an ApplyOnline integrated process, whereby brokers are able to electronically order upfront property valuations before they enter a loan application – at point of sale or at any time while completing the loan application. Halliwell says the benefits have been profound and feedback from brokers and Advantedge’s operations team “extremely strong”. Advantedge rolled out the brokerordered valuations service 12 months ago. Halliwell says it was the “convenience and simplicity” of the application and valuation processes through one system only that sold him. NextGen.Net sales director, Tony Carn, reiterates the simplicity that ApplyOnline broker-ordered valuations has introduced to the process. He talks of the “streamlined” system and the benefits of incorporating the valuation process into the application process, versus the outdated concept of treating them as non-integrated transactions. The benefits derived from integrating a valuation-ordering service include faster valuation turnaround times (by eradicating manual orders), enhanced broker experience (including better visibility of valuation status), the opportunity to ensure that loan applications meet lending scenarios prior to submission and no data rekeying (as all information entered for the valuation order filters through to the application within ApplyOnline). Additionally, ApplyOnline broker-ordered
valuations integrated with Advantedge back-end processes provide more efficiencies, plus enhanced tracking and reporting for reconciliation purposes. “The bottom line is that it’s about making brokers’ lives easier,” Carn says. “The concept is actually bigger that just the ordering of the valuation. It’s about continuing to move towards a simpler, more holistic, seamless process. “It’s about helping to further simplify what is generally an intricate process of coordinating an application and supporting documents, aligning to lender policy, doing a valuation, managing back channels and holding the hand of the borrower all the way through to settlement. “By making the valuation an integrated part of the process, we’re giving a better experience to the broker and, ultimately, the borrower.” Halliwell refers to it as “a win for all parties”. He says for Advantedge, making the broker-ordered valuations service available direct through ApplyOnline for all of their (existing and future) white label partners, was “a simple matter of rolling it out through the existing infrastructure”. “At Advantedge we pride ourselves on having great service levels: that is, the vast majority of applications completed within two days and a substantial proportion of them within 24 hours,” Halliwell says. “Having the valuation ordered and completed upfront and launched as a single point valuation functionality has been a significant part of our ability to deliver that market-leading service.”
www.brokernews.com.au
11
NEWS
R E G U L AT O R S
COURT DISMISSES PROSECUTION OF BRISBANE BROKER prosecution of Jenny Mao, who was charged with giving documents to a lender that were materially misleading, has been discontinued. The prosecution had been listed for a summary trial in April 2017. On 20 March 2017, the Commonwealth Director of Public Prosecutions (CDPP) sought to adjourn the summary trial order to allow a key and overseas-based prosecution witness to attend to give evidence. The court refused to adjourn the hearing. On 10 May 2017, the CDPP formally offered no evidence on the charge and the charge was dismissed by the Southport Magistrates’ Court. THE
ASIC TO PURSUE MAJORS ON SME LENDING The regulator has promised further action so the big four banks create reasonable, fair loan contracts for small business owners and the Australian Small Business and Family Enterprise Ombudsman (ASBFEO) have promised to hold the major banks to account when revamping small business loans. Following a round table by ASIC and ASBFEO, the big four banks pledged their commitment to a series of changes designed to protect small business owners from unfair loan conditions. These changes apply to loans entered into or renewed from 12 November 2016. ASIC deputy chairman Peter Kell said the regulator made it clear that lenders had to “significantly improve” their lending agreements to ensure they met the new rules. “It is important that the banks have committed to improving their small business loan contracts. ASIC ASIC
powers by APRA to oversee the non-bank sector will have a positive effect on the residential mortgage market, said analysts from global ratings agency Moody’s. If the policy proposed in the federal budget passes, the regulator would be able to set specific limits and ensure loan quality remains comparable to that of banks and other ADIs, Moody’s said. These measures would help curb riskier mortgage lending in the non-bank sector, thereby reducing any risks found in Australian residential mortgage-backed securities. BROADER
12
www.brokernews.com.au
HOW INCOME CHANGES AFFECT AFFORDABILITY Source: Moody’s Housing Affordability Report 2017, data from ABS, CoreLogic, Moody’s Investors Service, RBA
45%
Current affordability measure
40%
Affordability Measure
GOVERNMENT PROPOSES EXPANDING APRA’S POWERS
will be following up with the big four banks – and other lenders – to ensure that small business contracts do not contain unfair terms,” he said. Changes to SME contracts committed to by the big four banks include: • Removing entire agreement clauses, which absolve the lender from responsibility of conduct, statements or representations made outside of the contract • Removing financial indicator covenants, which give lenders the power to call a default when certain conditions are met regardless of whether the customer has met their financial commitments • Removing material adverse event clauses, which give lenders the power to call a default in the
event of an unspecified negative change to the customer’s situation • Limiting the operation of indemnification clauses, which broadly protect the lender against losses, costs and liabilities that may arise sometimes outside the control of the business owner • Limiting the operation of unilateral variation clauses to give business customers a minimum of 30 days’ notice for any changes to the contract Both ASIC and ASBFEO have warned that merely including the word reasonable in the SME lending contracts does not go far enough. ASBFEO Kate Carnell said her role was to ensure that the unfair contract term legislation was working across all industries, adding that it was clear what the word unfair meant in relation to the majors: protecting the interests of the banks against those of small business.
5% household income decrease
35%
5% household income increase
30% 25% 20% 15% 10% 5% 0%
Australia
Sydney
Melbourne
Brisbane
Perth
Adelaide
WHAT MATTERS MOST TO CONSUMERS Source: KPMG Mortgage Report 2017
Q
Are the following factors essential to you when taking out a home loan? (n=603)
Factor
% that considered it essential
99%
Competitive rates
83%
Ability to vary payments
Competitive fees
81%
Ability to offset against savings
80% 31%
Ability to fix rate
Ability to make payment holidays Building insurance included
22% 16% 0%
10%
20%
30% 40%
50% 60%
70%
80% 90% 100%
RBA WARNS HOUSING PRICES ARE A “TWO-EDGED SWORD” levels of debt and rising house prices could lead to serious economic impacts, Philip Lowe, governor of the RBA warned in an unusually dramatic speech in Brisbane on 4 May. He said the RBA was concerned about the effect that sharp cuts might have on average household spending. “It is likely that some households respond to a future shock to income or housing prices by deciding that they have borrowed too much,” he said. A sharp contraction in household spending could turn an otherwise manageable downturn into something a lot more severe. “The financial stability question is: to what extent does the higher level of household debt make us less resilient to future shocks?” The answer to this question was difficult to determine, he noted. “History does not provide a particularly good guide, given that housing prices and debt relative to income are at levels that we have not seen before, and the distribution of debt across the population is changing.” HIGH
FE AT URES
COVER STORY
RINGING IN THE FUTURE OF SMALL BUSINESS BROKING CEO Cameron Poolman and head of sales Michael Burke are leading OnDeck Australia through a growth spurt and making a big push into the broker channel. They explain why their product is worth your time
KEY BUSINESS METRICS
2015
Year founded in Australia
35
Number of employees
76%
Customer Net Promoter Score
9.3
Trustpilot score
US$6bn globally
Group total loan originations
Shareholding (AU)
55%
OnDeck US
15%
Other Australian investors
14
www.brokernews.com.au
30%
MYOB
though OnDeck, a specialist non-bank small business lender, has been operating in Australia for 18 months, employees still ring an old-fashioned hand bell when they acquire a new customer. It’s not just about celebrating their sales successes, but also for communicating milestones across the business and keeping office culture energised. “You sit there, the bell rings, people around the office – whether they’re in sales, operations, HR – clap. From my background, coming out of General Electric for 14 years, going to FlexiGroup, coming here, the culture is just so refreshing,” says OnDeck’s head of sales, Michael Burke, who started with the company in January. As the business expands this year, maintaining the bell, and what it represents, will be crucial. After all, valuing those small business roots helps it better cater to its customers – those cafes, restaurants, hair salons, repair shops and garages in need of fast cash – and appreciate the stress they experience. CEO Cameron Poolman understands this better than most. “I’ve been in their situation,” he says, “where you’re trying to grow your business and it’s hard getting a three-year business plan together to present to the bank, and it’s hard to get all your financials together and presented in a way that satisfies what they’re looking for.” Poolman trained as a mechanical engineer and worked in that field for five years. Armed with a master’s in marketing and an entrepreneurial streak, he founded GraysOnline. During his tenure as EVEN
CEO, it grew from a “few guys in a shed in Lakemba” into the largest e-commerce business in Australia with a few hundred staff and offices around the country. OnDeck wants to ease the pressures on small businesses by making it as painless as possible to get a loan. One of the ways it is doing that is by forming partnerships with brokers – some of the most plugged in people when it comes to the small business market, according to a 2017 East & Partners report that found more than 60% of Australian SME businesses use brokers for asset
account management. Alternatively, brokers can simply provide all contact details to OnDeck, who will manage the client through the process. What differentiates OnDeck from its peers is the speed and ease with which it does business. It offers unsecured loans of between $10,000 and $150,000 for six to 24 months. The application process takes 10 minutes and the transaction can be completed in as little as 24 hours. “While many providers in this space have requirements that are very in line with banks and traditional underwriting requirements … our credit assessment is built around the assessment of three months of bank statements only and a one-page simple application form,” he says. OnDeck uses analytics and data to assess the creditworthiness of a business based on operating performance, judging the health of
“At Grays we competed against Amazon – they’re way harder than the banks” Cameron Poolman, CEO, OnDeck and equipment finance. Burke says the company has always appreciated the importance of the broking channel to the small business economy, but made the strategic decision for the first 18 months to build and develop its product and process first, “so when we launched into the broker sector in February this year, we could stand behind the product and make sure that it was quite differentiated from our peers”, Burke says. “You kind of get one shot at the title as far as entering the broker market.” OnDeck has built an online portal that provides accredited brokers with real-time access to the status of client applications they have submitted, right from origination through to funding and
a business rather than the wealth of an individual. “If you go to the bank, they’re looking at you, your personal wealth, the equity you have in your home, because if you haven’t judged the health of your business correctly, they’re going after you,” Poolman says. “Our credit model works around cash flow, so we do need five deposits into the account every month.” It means, for example, that a hairdresser in Bondi who wanted to refurbish and upgrade her salon could do so; a plumbing company could invest in marketing; and a Bondi fish and chip shop that struggled through three weeks of rain could afford to brighten up its space for the Christmas rush.
Michael Burke, head of sales, OnDeck
It’s a compelling value proposition for brokers because it makes small transactions of $150,000 or under worthwhile. But Burke knows that attracting brokers is about more than just offering the right product. “Managing relationships with brokers ... you’ve got to make sure you get that balance right because we can’t be writing volume for the sake of writing volume; it’s got to be writing quality business,” he says. OnDeck is planning to add BDMs in each state to manage brokers and aggregators. It’s launching a marketing campaign to build brand recognition, and it’s relocating to a larger office on Sydney’s Pitt
Street – the former headquarters of LinkedIn – where there’s bound to be gold dust. “We’re growing hard, we’re putting on people, we’re relocating because we can’t fit here; we plan to have another eight people by the end of the year,” Poolman says. Regardless of what they dig up at the new office, Poolman estimates that loan originations will be up by 250% over last year. That hinges, in part, on establishing a strong broker channel, one of three pathways to get its products to market; the others are its direct channel and its strategic partnership with MYOB, a business accounting software provider.
The funnel effect Like most technology industries in Australia, Poolman anticipates the competition in online lending will shrink in the next few years to two or three key players. “People think [fintech is] low cost. It’s actually quite expensive to deliver a great service to customers and fund someone the next day. You do need to have a lot of people, technology and investment in these types of businesses,” he says. One of the obstacles is still lack of awareness. When small businesses try to access capital, he estimates only a quarter know alternative lending is there. The majority of small businesses either look to their
bank or to family and friends for advice, he says. Poolman believes it’s just a matter of time before the alternatives go mainstream. Other than NAB, banks are only starting to recognise the potential in this space, but it doesn’t come close to the convenience OnDeck offers, he says. “At Grays we competed against Amazon – they’re way harder than the banks. They’re seriously good at marketing and running their business, so I think in terms of where we are at the moment, we’re pretty comfortable that there’s a really good opportunity for us,” Poolman says. “[Amazon] used to keep me up at night.” Poolman and Burke plan to be one of the few companies left standing, and having a parent company in the US to look to helps. “Our US business OnDeck has been going for 10 years, so we’ve lent $6bn to over 60,000 businesses, and brokers are a really important channel in the US,” Poolman says. Getting access to that office’s ‘road map’ and seeing how the broker channel played out there has allowed OnDeck Australia to take a measured approach in entering the space. “We just don’t want to stuff it up. It is a competitive environment. There are a lot of people that say they’ve got a product similar to us, but we are absolutely focused on being number one.” Sound of the bell When the employee who began the bell tradition left the company, he took his noise-maker with him – it was a sentimental family object. “It was like disaster,” Poolman says jokingly. They went online, obviously, and found a replacement. “It’s really important culturally,” he says. “We’re really focused around what we’re achieving. It’s old-school, but it’s on the board; everyone is involved in credit,” he says. “It’s not just sales running originations, it’s everyone. … As we get bigger, we’ve just got to think through in our new office how to maintain that level of communication.” AB www.brokernews.com.au
15
FE AT URES
BUSINESS PROFILE
SME LENDING MADE EASY
NAB’s small business loan and prequalifying tool lets brokers cater to borrowers’ business needs while growing their own brokerages
with Steve Kane, general manager of broker distribution at NAB Q&A
Why do brokers stand out from the retail channel for small business lending? A quarter of brokers’ A customers currently are small
Q
proposition and grow their own businesses, they need to start focusing on small business lending as well as residential lending. As we all know, small businesses are the backbone of the Australian economy, so the opportunities to work within that market and to become even more entrenched as a
“For brokers to continue to evolve their service proposition and grow their own businesses, they need to start focusing on small business lending” Steve Kane, general manager, broker distribution, NAB businesses or self-employed clients. That means for brokers to continue to evolve their service
trusted adviser to those customers can happen by moving into the small business area. With the
Steve Kane, general manager, broker distribution, NAB
regulatory piece around responsible lending in the NCCP, it is important that brokers look at the holistic financial requirements of their customers. So, with 25% of
NAB SMALL BUSINESS INTRODUCTION With approximately a quarter of all applications coming from small business owners, brokers are playing an increasingly important role in helping small business owners secure the finance they need. At NAB we want more brokers to consider small business lending as a way to not only grow your business but also to holistically service more of your customers’ needs. We understand that diversifying into small business lending can be a big step, which is why we are here to help at every stage of the process. We recently strengthened the support we provide brokers with the launch of our market-leading prequalifying tool, as well as access to our expert small business BDMs. All of this is testament to NAB’s concept of ‘Broking for Life’, which celebrates the difference and meaningful impact that each broker makes throughout the customer life cycle. It’s never been easier to help clients to achieve their business ownership dreams. As Australia’s number one business bank NAB is committed to guiding brokers through the nuances of the small business landscape and further deepening the broker-customer relationship. – Steve Kane
16
www.brokernews.com.au
their existing customer base already working as small business owners, providing products and services that cater to this market is the next step. What is your new campaign for small businesses about? It’s really about simplicity. A It’s about enabling brokers to transition from purely residential mortgage lending into the small business space. It was important that we provide brokers with a set of products and services and a process that would allow them to easily operate in this growing marketplace. Whilst many brokers would find it daunting to move into commercial lending for the more complex, larger transactions, we felt that for the sub-$1m space, particularly the small businesses
Q
Sponsored by
operating in that area, it was doable if we provided the right product. That’s why we launched the NAB Business Options Loan. It is a tailored, flexible small business product for loans up to $1m, with a $0 application fee. We obviously entertain much larger transactions through our commercial broker offering, which goes right up to the full commercial and corporate lending. But we wanted to go out with a simple product that was easily understood by the customer and easily understood by the broker, so we took some existing products and customised them specifically for the broker channel. Can you tell us more about the ‘toolkit’ NAB has launched to go along with this loan? The new small business A toolkit helps brokers better understand their customers’ business and have informed conversations about structured risk on business lending products. The market-leading prequalifying tool guides brokers so they know what customer information to ask for when they’re putting together the application. Once completed, the tool then tells brokers whether the application would meet NAB’s criteria for the relevant facility. This isn’t an approval, but it gives the broker an idea of what we would approve, and it gives the broker confidence in the questions they’ve asked and the application they’ve prepared. The prequalifying tool is something we use internally as well, so it really gives a seamless and effective method for brokers to transition into the small business market. It helps them understand and get the whole picture from their customers when they’re submitting those applications.
Q
What other measures are in place to help brokers? We’ve set up a series of A support teams internally to handle broker-originated small business loans. We have increased our BDMs to 17. We currently have 20 experienced business bankers dealing with brokers, and we’re looking to grow that team as well. These bankers have a full credit approval authority for the
Q
home lending and business lending needs of small business customers, and are a single point of contact for brokers. Brokers can also look forward to digital applications for small business and residential lending to come this September.
CASE STUDY
What makes NAB stand out as a small business lender? NAB is Australia’s largest A business bank, and our support for small business is a significant part of the bank’s operation. It was important that we extend this into the broker channel in a more holistic way, so really what we’ve done is ensure that brokers and their customers get the opportunity to deal with NAB, with all the expertise that we offer in that area, and we’ve been able to tailor products and services to suit this particular market as well as the wider commercial broking market.
Q
What are some highlights of this campaign? When we ran the pilot A program with a number of brokers, we were getting very positive feedback about the efficiency of the process that the prequalifying tool gave them. For experienced commercial brokers, the tool was an added benefit from what they already knew. But for brokers who were transitioning from housing lending into small business lending, it was a great way for them to take their first step into diversifying their product offering. The tool is very effective in letting brokers understand how the credit decision is made, and also makes sure they ask the right questions of the customer so they can have confidence that they’re reasonably close to getting an approval. It enables faster turnaround times, more clarity around what’s required in these applications, and it’s also been a significant education process for the brokers moving into the small business market. It’s available to all brokers who hold lending accreditation with NAB. AB
Q
This interview has been edited and condensed.
Carlo Di Giovanni, director of CDG Finance, residential and commercial broker in Melbourne
“When I first started in the broking industry, I started writing small business loans on a small scale, but found that it took almost double the time to write a small business loan as it did to write a residential loan,” says CDG Finance director Carlo Di Giovanni. “So I mostly focused on residential deals and only dabbled in commercial. Thirteen years on, the commercial side has grown significantly, especially in the last three years. Now, about 60% of our business is residential and 40% is commercial. In that commercial lending space, 60% is for sub-$1m loans and the rest is above that. Our clients are predominantly self-employed. “Commercial lending is still challenging, but some banks, like NAB, have made it easier. The prequalifying tool simplifies the application process. It incorporates serviceability requirements and security, it tells you which questions to ask and gives you space to write commentary on the client’s background, financial conduct, purpose of loan and statement of position. Rather than a lengthy executive summary, all this information can be contained in the one document and provided to the NAB banker with the required supporting documentation. “The standard process of writing a business loan used to take up to 10 hours of touch time with the client, bank and BDM. Now I don’t have to write as in-depth a credit paper because of NAB’s prequalifying tool, which significantly reduces the amount of time spent on the application. Time savings is a big factor in what makes this tool so beneficial, but it also helps give me the confidence of putting up a deal because it prequalifies the information I’ve put into it. It’s not an approval, but the ‘tool’ informs you whether the deal you’re proposing meets NAB’s qualifying criteria. It is an efficient process that saves me time and gives me the confidence the deal has met the set criteria.”
www.brokernews.com.au
17
FE AT URES
Clive Kirkpatrick, general manager of Vow Financial
NE WS ANALYSIS
BUDGET BRIEFING FOR BROKERS Experts address some of the federal budget’s most significant policies to see how they’ll affect brokers and impact the industry
David Bailey, interim CEO of AFG
Banks become tax target The government plans to collect $6.2bn over the next four years from the country’s five major banks – ANZ, NAB, CBA, Westpac and Macquarie – to support budget repair, starting 1 July. The six basis point annual levy affects banks with liabilities over $100bn. At the time of print, Westpac and CBA were the only banks to declare how much the tax would cost. Based on initial estimates, Westpac said it would pay $260m per year and CBA said it would pay $220m per year, both amounts after tax. “This represents an additional and fair contribution from our major banks, is similar to measures imposed in other advanced countries, and will even up the playing field for smaller banks,” Treasurer Scott Morrison said during his 9 May budget speech. The measure was heavily criticised by the major banks and the Australian Bankers’ Association, which said the tax would hit customers and shareholders. “This new tax is not a well-thought-out policy response to a public interest issue; it is a political tax grab to cover a budget black hole,” said ABA CEO Anna Bligh. What does it mean for brokers? AFG interim CEO David Bailey said it was important that the ACCC keep an eye on the banks to make sure they didn’t use the levy as justification to implement changes designed to “reduce the financial viability of providing broking services and marginalise large portions of the lending sector, leaving them without a distribution network”. Brokers ensure there is competitive pressure on the major banks that dominate the lending market, he said. The ACCC and the Productivity 18
www.brokernews.com.au
Commission have been tasked with supervising mortgage pricing and will be conducting an inquiry into competition in the financial sector, which Bailey said was welcome news. The government said it would provide the ACCC with $13.2m over four years
rates, but they can’t actually control those rates. Brokers have an important role to play in this context, by helping to ensure the market is transparent, and by assisting customers to refinance if their rates do go up. Customers need to vote with
“Brokers have an important role to play in this context, by helping to ensure the market is transparent” Clive Kirkpatrick, general manager, Vow Financial to establish a “dedicated unit” to conduct regular inquiries into specific competition issues. But Clive Kirkpatrick, general manager of Vow Financial, told Australian Broker that the ACCC’s reach was limited. “The watchdog can look into how the banks are setting
their feet if they see an increase in costs,” he said. Mark Bouris, executive chairman of Yellow Brick Road Wealth Management, said the levy could drive up loan costs. “There are already forces at work that are increasing the cost of a mortgage, including
increased pressure from regulators. Slapping another tax on banks will add even more pressure. We won’t be surprised to see this passed on to the customer in the form of higher interest rates,” Bouris said. APRA’s widening scope Morrison promised to help APRA to “respond flexibly” to housing market developments that pose a risk to financial stability. He said APRA’s powers would be expanded to include non-ADIs. The regulator will also be able to apply loan controls differently based on location. The government is introducing a new accountability regime that will allow APRA to remove and disqualify banking executives and adjust banks’ remuneration policies. For breaching any misconduct rules, small banks will face fines starting at $50m, while large banks will face fines of $200m or more.
BUDGET OUTCOMES Source: PwC Australia
$6.2bn Bank levy
$1.2bn
Foreign worker levy increase
$8.2bn Medicare levy
$75bn (over 10 years) Infrastructure
$18bn (over 10 years) Schools
7.5% (a total of $2.9bn over 4 years)
University fees increase
Tim Lawless, head of research at CoreLogic
John Flavell, CEO of Mortgage Choice
What does it mean for brokers? Mortgage Choice CEO John Flavell applauded the government’s decision to “beef up the powers” of APRA and ASIC because they “play a pivotal role in ensuring our banking system continues to operate in a sound manner”. “Anything that can help deliver on that premise, and ultimately deliver greater surety of financial product and advice to Australian consumers, is a good thing,” he said. CoreLogic’s head of research, Tim Lawless, said this move was likely a response to the growing activity in the non-banking sector since APRA applied speed limits on investors. “These changes could make it harder for investors, foreign buyers and businesses, who are being turned away from the major banks, to fund their property purchases,” he said. Balancing supply and demand Morrison’s budget includes a number of measures meant to boost supply and subdue demand, especially from investors and foreign buyers. It introduced a First Home Super Savers Scheme that allows first home buyers to deposit a portion of their income into their superannuation to use to buy property. Contributions are limited to $30,000 per person. The government will also allow senior homeowners to contribute up to $300,000 into super from the sale of the family home, to encourage downsizing and free up supply of established housing. Furthermore, federally owned surplus land holdings will be offered up for residential development. Tweaks were made to negative gearing, including tightening up on the travel costs investors can claim on investment properties. Morrison announced a new $5,000 “ghost tax” on
foreign-owned properties left vacant for at least six months of the year, and made foreign buyers exempt from capital gains tax concessions. Developers will also now be barred from selling more than half of a development to foreign buyers. What does it mean for brokers? Flavell said while he supported measures that would address the housing affordability crisis and help first home buyers get a foot in the door, he didn’t think the superannuation scheme would have a huge impact. “At best, a couple who salary sacrifices a portion of their income into their super might be able to scrape together enough money to pay for the stamp duty charged in markets like Sydney and Melbourne,” he said. The Rudd Government implemented the “spectacularly unsuccessful” First Home Saver Account in 2008, Flavell said. It was withdrawn from the market six years later. “There is nothing to suggest that this new scheme will deliver a different result,” he told Australian Broker. What this new scheme does provide, however, is a great reason for brokers to get in touch with new and existing clients. “They can discuss the changes with their clients who may or may not know someone who is looking to ramp up their savings in order to buy their first home.” The biggest driver of price growth is supply, and the government didn’t do a lot to address this, Kirkpatrick said. The impact of the superannuation scheme will depend on the take-up among individuals. “Ultimately, first home buyers need brokers to educate them on how much they need to save for a reasonable deposit, to look critically at serviceability, and to ensure they have a manageable mortgage for their first property,” he said. AB www.brokernews.com.au
19
FE AT URES
OPINION
FINANCIAL FREEDOM STARTS NOW Your Wealth Matters director Julian Musgrave warns brokers not to rely on their trail alone to fund retirement
why that is: clients will refinance with another broker or lender, banks will inevitably change commission structures and rates, the government may change the rules (as it did with the financial planning industry), and let’s not forget the fact that aggregators actually get your money before you do.
broker’s trail book is a highly valued asset and source of income – the result of years of hard work in business. And yet it isn’t a solid and wholly dependable vehicle for providing financial freedom. Alone it won’t build an impenetrable financial wall around your family, fund a long-term, comfortable retirement, or leave behind a worthwhile legacy for the next generation. Compared to other business owners, brokers are in an advantageous position in that the products they sell generate an upfront and ongoing passive income. But as is the case across all industries, very few brokers are maximising the potential of that trail income to achieve financial freedom. That income is not guaranteed for the long term, and while it provides potential, it requires a strategic plan to make it sustain you now and last into the future. A
Myths around financial security Besides my broking experience and passion for the industry, what got me started working as a finance and business coach for brokers was the regularity with which they so confidently told me their clients needed help, but rejected the notion that they too needed help planning for their future. They regularly said, “I’m okay because I have my trail book.” Yes, your trail is passive income. If you stopped broking now and took back your time, your trail income would continue to flow in, but it would also begin to diminish. And it happens faster than you think. It won’t remain at the level it is now, and over the years it will more than likely fail to meet the needs of your lifestyle. The bottom line is that a broker’s trail income is not secure. We all know 20
www.brokernews.com.au
When this external income is built up, it replaces your need to exchange time for money now and for generations to come. It’s an income that, when turned on, pays for today and earns for tomorrow. The key to building an impenetrable financial wall around your family is to make sure that once it’s built it stays up. A trail book alone can’t do that. Case in point Ivy Dos Santos, director of Flair Financial in Mackay, Queensland, tells me she’s reached a crossroads in her life. “I’ve always been very driven in my work, but I’m at the point now where time with my teenagers and husband are the most important thing. I’ve spent years building a strong broking business, but now that free time is my main need, I’ve come to realise that I haven’t built something that’s going to go the distance financially. The numbers just don’t stack up.” So what should a broker do? I’ve
So long as your personal wealth is reliant on your job or business, you will have to keep selling your time to earn it When you think about it, you are relying on a lot of other people for your family’s financial safety.
Julian Musgrave Director of Your Wealth Matters
What does true lasting financial freedom look like? The main point to understand is that freedom lies outside your business. True financial freedom isn’t having a high-paying job or business that allows you to pay for everything and have a comfortable lifestyle. That’s not freedom because your personal wealth is tied to your job. You’re trading time for money, and so long as your personal wealth is reliant on your job or business, you will have to keep selling your time to earn it. Lasting financial freedom is having an income outside your business. The goal is to replace your regular income as quickly as possible and stop trading your time for money – to generate an external income that is unaffected by factors influencing and challenging your business or the broking industry. The beautiful thing for brokers is that you have a trail income that can significantly accelerate that additional income.
been working with Dos Santos to help her create what I call a ‘freedom generator’, which is the passive income that you generate outside your business to eventually secure your financial freedom. This residual income should be a diverse portfolio of assets that is not held to ransom by fluctuations in the housing or stock markets. “With a few harsh realities made obvious by Julian at YWM, a good old-fashioned regroup and change of focus, we’re on track with our ‘freedom generator’ and I can see financial freedom at the end of the tunnel,” Dos Santos says. Takeaway As a business owner, you need to make building your ‘freedom generator’ the white-hot focus of your business. Make your personal freedom an integral part of your business plan. You’ll thank yourself in the future. AB Julian is a former mortgage broker and is now a certified coach of the MindShift.money Cashflow Cure Program for business owners.
IN THE NE WS
A LOADED QUESTION A recent report from global investment bank UBS that suggested brokers were overpaid raised the ire of the industry, with member associations calling it misleading and incorrect provided on a simple, commoditised, single product, particularly when compared to the fees charged by financial advisers for ‘simple’ financial advice ($200 to $700),” the report said. Broker commissions now add 16 basis points per annum to the cost
trail commissions, which allow brokers to service loans over many years,” he said. White was similarly dissatisfied with the report, calling the data flawed and not based on fact. With the average price of a house on a
“The data is garbage and flawed because the analysis is not based in fact” Peter White, executive director, FBAA
Peter White, executive director, FBAA
expressed anger and dismay after analysts at UBS suggested mortgage brokers were overpaid and their commissions should be reined in. The report provoked a scathing response from industry associations questioning the quality and accuracy of the research. FBAA executive director Peter White called the report “absolute garbage” and wondered if the bank’s research department required a “serious overhaul”. MFAA CEO Mike Felton said the analysts based their findings on incorrect data. In the report, analysts Jonathan Mott and Rachel Bentvelzen pointed to a key recommendation in the ASIC and Sedgwick reviews that brokers’ remuneration should not directly link payments to loan size. “We believe this is appropriate given the blow-out in commissions paid to brokers, which exceeded $2.4bn in 2015,” the report, released 16 May, said. They described the payments as “an illustration of excesses built into the financial system following a BROKERS
26-year economic boom”. In comparison, they said the total cost of running the four major banks’ personal/consumer banking operations was $10.6bn in fiscal year 2015. The total commissions paid to brokers was equivalent to 23% of the cost base of those banks’ personal/consumer divisions in 2015. “Average commissions are now $4,600 per mortgage, which we believe is disproportionate for advice
of every mortgage in Australia, they added. Felton took issue with those numbers, saying the reason UBS came to that conclusion was because they divided the total amount of broker commissions in 2015, which includes upfront and trail commission, by the number of loans written in 2015. “This has given them a commission per mortgage that is about double what it actually is in the year of acquisition,” Felton said. While the total amount of commissions paid to the channel has increased, Felton said independent research had shown that the average gross earning for brokers was about $142,000 per annum, before any superannuation contributions, overhead costs or staff salaries. “This includes an average of $83,000 in upfront commissions and $59,000 in
national weighted basis around $656,000, and the average LVR written by a broker at 75%, this makes the national average size of a home loan written by a broker $492,600, he said. “At an average of 0.60% upfront paid to a broker, this equals $2,955, nothing like the $4,600 UBS is touting.” The report said commissions were factored into the banks’ cost of funding and had been a driving factor in mortgage repricing in recent years. The analysts expect banks to negotiate materially lower fee-for-service mortgage commissions in coming months and said the “value-add from mortgage brokers is likely to become marginalised”. UBS told MPA magazine that it stood by its research, pointing out that its analysts had used data provided by the ASIC and Sedgwick reviews. AB
MORTGAGE BROKERS AND AGGREGATORS’ MARKET SHARE Source: MFAA’s quarterly market survey; comparator analysis
Market share of new residential home loans originated by all mortgage brokers and aggregators as % of ABS Housing Finance commitmnents 55% 50%
51.9%
51.5%
52.6%
51.8%
Q1 2015
Q2 2015
Q3 2015
Q4 2015
53.7%
53.6% 50.1%
45%
51.9%
53.6%
40% 35% 30% 25% 20%
Q1 2016
Q2 2016
Q3 2016
Q4 2016
Q1 2017
www.brokernews.com.au
21
22
www.brokernews.com.au
PEOPLE
Have an interesting deal? Had a particularly difficult or interesting deal? Why not share it with us? Email:
Otiena.Ellwand@keymedia.com.au
A BIG DEAL
Aussie mortgage broker Simon Nesbit coached a customer through a period of hardship to achieve his property goals, proving brokers do play a meaningful role in people’s lives
THE FACTS
Loan size $887,000
Loan term 30 years
Client De facto couple
Goal Buy dream home
Lenders Aussie Home Loans
lender they were prepared to consolidate the remaining personal loan. Free of his previous financial burdens and with repayments only half what they were 12 months prior, the customer then chose to fix this loan while he focused on rebuilding his cash reserves.
THE SCENARIO
Mortgage broking in a small country town is more than just a transaction. We are community leaders, providing our expertise in mortgage advice. When I first met the client in 2013, he was in significant financial distress and was considering declaring bankruptcy. He had a substantial amount in unsecured debts, much of it on high-interest credit cards and a small unpaid default. He had a small mortgage on his home, but his lender had previously advised that he could not refinance and had instead offered him a personal loan. With monthly repayments almost as high as his income, a poor credit history and significant recent overlimits and late payments on his record, we were unable to arrange a new loan for him initially. I spent time with the customer to help him understand his debts, and he subsequently created a plan to gain control of them. The customer made a commitment to change his lifestyle to suit his new budget. Every month we had a quick chat, and the customer confirmed he had kept his credit cards under their limit and had made his loan repayments on time. After five months we had a potential solution. While many lenders were unwilling to consider an applicant with recent credit issues, we found a local lender who was prepared to assess the application without prejudice. This allowed for some debt consolidation, significantly improving the customer’s financial position. Over the next six months he was able to improve his position further, and with this additional history with the
Location Queensland
were missing and requested amendments. Once we received the updated contract, we requested the valuation. Following this, we obtained formal approval from the lender within 48 hours and the required deposit guarantee. As part of our standard post-approval process, we review and complete loan documentation with the customer. As I cross referenced the title details with those on the contract and the Queensland titles authority, I noticed conflicting information. We sought clarification from the agent and solicitor; however, neither were able to correctly identify the property as per title documentation. We obtained records of the property from the local council and the Queensland titles office, which showed a number of properties in this development had not been retitled due to duplication of street names, the ‘street address’ identifier used was insufficient – and the title was for another property entirely! After advising the agent and solicitor of their error, we used this new information to obtain a corrected valuation, a revised formal approval and corrected loan documentation. We were able to receive, complete and return the loan documentation all in five days to enable settlement to proceed on time. THE TAKEAWAY
Our responsibility does not finish with approval. This is often the most critical
Our responsibility does not finish with approval. This is often the most critical time … when errors and delays can become a significant emotional and financial burden THE SOLUTION
Simon Nesbit Aussie mortgage broker in Launceston, Tasmania
The customer returned for further assistance months later. He had a new partner, a new job, and they had just moved to Queensland. We set a strategy in place to assist with a planned future purchase, and three months later they had reliable income to meet loan requirements. We were unable to move the customer’s existing loan without significant expense, so we completed a preapproval application to ensure there were no lingering issues with his history. With equity available in his partner’s property, we were able to obtain a fully assessed preapproval. After some time they found the property of their dreams: a relatively new development close to work, the beach and the golf course. When we received the contract to arrange a valuation, I noted some property identifiers
time in a property transaction, when errors and delays can become a significant emotional and financial burden. If we had not completed our own independent review, it’s possible this loan would not have proceeded to settlement. It is a focus of our service to treat every customer equally. Some deals are simple; most are complex. Understanding not just the what but also the why is key to developing longterm customer relationships. I helped the customer understand that he needed to assess his finances, but it was he who proved his commitment over three years of hard work to achieve his goals. Now, he and his partner are in the home of their dreams, they have three investment properties, and the combined minimum repayments are still less than what the customer faced when I first met him more than three years ago. AB www.brokernews.com.au
23
PEOPLE
Get involved in the discussion Share your thoughts at
brokernews.com.au
FROM THE FORUM
Top comments from trending stories on brokernews.com.au
GOVERNMENT SUMMONS SENIOR BANK EXECS
MORTGAGE BROKERS ARE OVERPAID, UBS REPORT CLAIMS
The government called senior banking executives from the five biggest banks for a briefing on the proposed bank tax introduced in the 2017 Federal Budget. Finance, treasury and tax executives from CBA, Westpac, ANZ, NAB and Macquarie Bank were expected to attend. Sources told The Australian they had been given 24 hours to prepare commentary on the measure and learn about the design features of the tax. This came ahead of a tight deadline as the levy is to be implemented by 1 July.
UBS analysts are calling for the reining in of mortgage brokers’ commissions amid concerns that they are overpaid. The MFAA has disputed the report, claiming it used incorrect data. UBS analysts found total upfront and trail commissions paid to mortgage brokers totalled $2.4bn in 2015, while the cost of running the four major banks’ personal/consumer operations was $10.6bn in fiscal year 2015. “We find it astounding that the total commissions paid to mortgage brokers was equivalent to 23% of the cost base of the entire major banks’ personal/consumer divisions in 2015,” they wrote.
Credit for trying… but the cost will be passed on to brokers and customers by indirect means, in small portions. Banks are untouchable.
Another misinformed rubbish article – no guaranteed salary, superannuation sick leave, holidays leave loading, rising PI and compliance costs. Yeah, we are overpaid and on-call 24/7.
Really? on 10/05/17 at 2:13 PM
Keith Bridges on 19/05/2017 at 8:47 AM
We all know that the banks will pass this to the consumer and the government will let it happen, so really once again we as consumers/taxpayers meet another cost out of our hip pocket.
Perhaps the banks summoned the government, after all, they’re ... practically running the show! In the end, we will all pay for this.
This is ridiculous, even if the $142,000 per annum figure is correct. It makes no allowance for costs. After expenses like aggregator costs, car, fuel, stationery, mobile phone, land line, IT, rent of office, referral fees for some referrers, gifts for clients at settlement to rebuild the relationship often tarnished by bank delays, ongoing training and no overtime for seeing the client after 5 pm. Macquarie bank’s review consistently shows after expenses most brokers only retain around 48% of the gross income. Add to that the constant threat that a client will provide a fake document, which will result in the possible loss of your income and trail. And don’t even mention clawbacks. What other industry says work really hard for your client, do a great job, but if they decide to change their lifestyle we want your pay back? Sorry, but I think if anything, brokers are underpaid. Do people really forget that we already took a 33% pay cut due to the GFC?
Broker on 10/05/17 at 4:01 PM
Albert on 19/05/2017 at 8:56 AM
All the more reason now for the banks to cut costs by reducing what gets paid to brokers. Not a good outcome.
Just another pack of ill-informed and overpaid academics who have no clue about the industry yet are given the opportunity to threaten the livelihood of thousands of Australian families.
No name on 10/05/17 at 2:35 PM
Yep, agree and because they have a monopoly, the media can smash them on a current affair all they like. They’ll pass on the costs; everyone will still hate them. However they won’t lose much market share because the smaller banks can’t compete on credit policy. Either way the banks always win. Sally Field on 10/05/17 at 2:53 PM
Worried on 10/05/17 at 6:39 PM
Makes me sick on 19/05/17 at 8:59 AM
24
One would hope that this tax doesn’t get approved. Agree with all of the commentary above. The banks will pass this tax on to customers in the form of rate hikes for borrowers and rate reductions for people investing their money. The upside to all of this is that the tax is only hitting the big five. (Didn’t really think Macquarie would be the fifth!) This means that there will be plenty of opportunities for the smaller/second tier lenders to pick up their market share. Unfortunately this is most likely going to hurt the mortgage managers as these lenders will most likely pass the cost onto them as well in their wholesale funding.
They must be joking – the amount of time spent on an individual loan can be astounding even if it’s a small one; and the more complicated they get the more time required. Then there are expenses: staff, office, equipment, super and “compliance” paperwork is growing amazingly, etc. And I saw on TV last night the heads of various banks receiving $8m per annum plus bonuses and no mention of what the higher level “management” staff just below them receive. Borrowers also like the fact they can contact the same person year-in year-out who is aware of their situation, unlike any bank/bank staff member. Wake up!
SWLS on 13/05/17 at 8:46 AM
David on 19/05/17 at 9:18 AM
www.brokernews.com.au
CAUGHT ON CAMERA Australia’s largest communications agency specialising in financial services, Honner celebrated its 20th anniversary on 17 May at The Mint in Sydney. About 200 people attended the event, including clients from the banking, mortgage and finance sectors. Philippa Honner spoke about founding the company as a one-woman show in 1997 and building it into a respected voice in the financial services and communications fields. She also announced that Honner was establishing a marketing office in New York to drive business development in offshore markets, and teaming up with Victorian digital agency Spark Green to help financial firms build user-friendly websites and online platforms.
Honner celebrates 20 years in business
The Honner team
From left: Cameron Poolman, OnDeck; Charlene Baston, OnDeck; Rashmi Punjabi, Honner; Oliver Wade, OnDeck From left: Jacqui Marshall, Investec Australia; Michael Clarke, Challenger; Philippa Honner, Honner; Milton Samios, Investec Australia
From left: Brendan Wright, FAST; Paul Cheal, Honner
From left: Kate Machin, Investors Mutual; Matthew Walker, WLM Financial; Cameron Poolman, OnDeck; Susie Bell, Honner www.brokernews.com.au
25
DATA
NEW SOUTH WALES
QUEENSL AND SPOTLIGHT
A lack of stock coupled with high demand pushes prices up further Sydney shows no signs of being dethroned as one of Australia’s most sought-after cities to live in. However, its high status is slowly working to its detriment. “If you’re looking at detached housing, nearly every suburb in Sydney is out of the reach of typical first-time buyers,” says Angie Zigomanis, senior manager of residential property at BIS Oxford Economics. “You’ve had prices rise, but low interest rates mean that these people can borrow more. But at the end of the day, banks still typically require some sort of deposit, so the more prices rise, the more difficult it will be to actually save an appropriate deposit for the house and apartment prices being achieved.” Population growth and underbuilding in NSW are contributors to this ongoing issue, as supply is currently lagging behind demand. Moreover, investors are facing their own struggles with surging prices, because these lead to the tightening of lending conditions by banks. Area
Type Median value
Quarterly
12-month
growth
growth
Sydney
H
$935,000
-1.1%
4.2%
NSW Country
H
$435,000
1.2%
6.3%
Sydney
U
$705,000
1.4%
3.7%
NSW Country
U
$369,000
5.4%
3.5%
VICTORIA
Melbourne remains the most consistent market – for now People continue to pour into Melbourne, but concerns that supply may outstrip demand linger. “Melbourne has been the most consistently performing property market over the last decade and is likely to retain that title in 2017,” says Michael Yardney, CEO of Metropole Property Strategists. “However, the markets will remain fragmented, with the current oversupply of new apartments creating a glut that will limit capital and rental growth in this segment of the market for a number of years.” Melbourne’s economic strength sustains the property market’s consistency by creating jobs and therefore enticing migrants. Based on the current rate, Victoria’s population is expected to increase by almost 1.5 million in the next decade. However, even with the influx of demand, the rental market is not looking so good for investors. “Overall, rental vacancy rates remain low and rentals are slowly rising, but not as fast as house prices, so yields for investors are falling,” he says.
CONSTRUCTION OVERBOARD Demand may not absorb growth in this city’s attached-dwellings sector
investors in the southern states are showing strong interest in Brisbane, the apartment market in this region is expanding at a far faster rate than buyer demand. Thus, while Brisbane has gained momentum over the past year, it is still regarded as an underperforming property market. “Brisbane is suffering from an oversupply of new apartments, mostly in the CBD, city fringe and inner suburbs,” says Michael Yardney, CEO of Metropole Property Strategists. “Even though forecast completions will decrease over the next few years, the current oversupply will limit capital growth and rental growth for a number of years.” By contrast, the house market should be trending along at the same rate as in 2016, with houses in the metro offering the highest yields and displaying the most growth potential. This has been triggered by the slight upswing in employment, bringing a similar increase in population. Housing stock hasn’t risen at the same rate as unit stock, so demand and supply are meeting well. WHILE
Affordability keeps Queensland on the map Low prices continue to be Brisbane’s ticket to fame. However, although the market is expected to tick upwards, it certainly won’t be growing at the same rate as the more popular capitals, as the volume of job growth isn’t there to sustain the property market. Outside the metro, however, light is being shed on areas such as Southeast Queensland due to heavy marketing. “Southeast Queensland is continually being promoted as a great area to invest, and as
Type Median value
Quarterly
12-month
growth
growth
The Sunshine Coast market is strong at the moment, driven by demand around the new public hospital at Kawana Apart from the new hospital, there are a number of other major projects underway, including the Aura masterplan development at Caloundra, the expansion of the Sunshine Coast Airport, and the new town centre at Sippy Downs. There is a lot happening on the Sunshine Coast at the moment, where population growth is expected to be significant over the next 10 years. In particular, the new CBD at Maroochydore will transform the area. The 53-hectare site in the heart of Maroochydore is expected to include commercial, retail, unit and housing development, which will be completed over the next 20 years. By 2040, around 550,000 people will be living on the Sunshine Coast, and our economy will be dynamic and diverse, with huge growth in education, healthcare and professional services and the emergence of new aviation, technology and renewable energy businesses. Colin Mason Director, SMS FINANCE, Sunshine Coast
HIGHEST-YIELD SUBURBS IN QUEENSLAND Suburb
Area
BROKER PERSPECTIVE
Type
Median price
Weekly median advertised rent
Gross rental yield
Collinsville
H
$60,000
$193
17%
Melbourne
H
$660,000
2.8%
5.9%
Yatala
U
$361,100
$916
13%
VIC Country
H
$322,500
2.4%
1.9%
Dysart
H
$72,500
$163
12%
Melbourne
U
$490,000
-1.0%
0.6%
Brandon
H
$122,500
$250
11%
VIC Country
U
$254,000
-0.4%
2.0%
Charters Towers City
H
$125,000
$255
11%
26
www.brokernews.com.au
OPPORTUNITIES AND KEY INFRASTRUCTURE
WESTERN AUSTRALIA
There’s potential for investors willing to play the waiting game Arts building upgrade
The Waterfall
Airport infrastructure
Gold Coast Integrated Resort
Non-profit organisation Metro Arts plans to refurbish its heritagelisted building
Residential tower proposed for South Brisbane brings subtropical theme to design
Construction has begun on the $120m Airport Taxiway Bridge, creating 300 new jobs
The resort will be able to host functions for more than 3,000 guests
such has been enjoying strong market activity of late,” says Charles Tarbey, chairman and owner of Century 21 Australasia. “The area has attracted attention not only due to price points but because of the great lifestyle offered, the favourable reputation of the area for local and international visitors, as well as its location and relative proximity to Brisbane.”
Southeast Queensland’s current upswing is indicative of how important tourist value can be to a struggling resource-focused state. “The towns that focus on tourism will benefit from rising tourism expenditure and the investment that’s needed to accommodate that as well,” explains Angie Zigomanis, senior manager of residential property at BIS Oxford Economics. AB
SUBURB TO WATCH: BURPENGARY Median price (houses) $419,753
Median price (units) $263,657
While new properties hit the market, night is falling on the City of Light as residents migrate out of the state. “Population growth has slowed and weakened as people who moved here from other states move back home again,” says Angie Zigomanis, senior manager of residential property at BIS Oxford Economics. “In the meantime, there’s a big pipeline of dwelling construction working its way through the system, as you can’t just build a dwelling instantaneously. And it’s working through at a time when the population flows are reversing.” Perth is expected to see more of a downturn, even though some have predicted that the market has bottomed out. “There’s probably still at least another 12 months to go, if not more, on the decline in mining sector investment. So, from an economic perspective, it’s going to be fairly challenging [during that time]. That points to weaker conditions in the housing market.” Area
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
1.4%
11.5%
17.2%
4.9%
12-month growth
3-year growth
5-year growth
Indicative gross rental yield
-1.3%
2.6%
4.2%
7.1%
Type Median value
Quarterly
12-month
growth
growth
Perth
H
$510,000
-1.5%
-3.5%
WA Country
H
$368,000
5.4%
-6.5%
Perth
U
$404,500
-3.7%
-2.6%
WA Country
U
$295,000
13.5%
-8.2%
www.brokernews.com.au
27
DATA
SOUTH AUSTRALIA
NATIONAL PROPERTY WATCH MAY 2017
12-month
growth
growth
Adelaide
H
$450,000
4.7%
3.9%
SA Country
H
$290,000
3.9%
1.1%
Adelaide
U
$356,250
1.8%
2.9%
SA Country
U
$206,250
11.2%
1.3%
AUSTRALIAN CAPITAL TERRITORY
MEDIAN HOUSE AND UNIT PRICES
Canberra in comfortable third place among Australia’s capitals
$1,000,000
Type Median value
Quarterly
12-month
growth
growth
Canberra
H
$633,750
-1.3%
4.3%
Canberra
U
$426,100
-2.0%
1.2%
28
www.brokernews.com.au
RISING MARKET Sydney
Echuca
Hobart
Launceston
Ballarat
Lismore
Bendigo
Mount Gambier
Burnie
Sunshine Coast
Devonport
Tamworth
START OF RECOVERY Bundaberg
Horsham
Cairns
Mildura
Hervey Bay
Townsville
$1,100,000
Sydney Melbourne Brisbane Adelaide
Perth
Hobart
$532,500
$360,000
$400,000
$0
$416,250
$100,000
$511,000
$200,000
$348,500
$300,000
$443,750
$500,000 $400,000
$535,000
$700,000 $600,000
$685,000
$800,000
$730,000
$900,000
Houses
$931,000
The ACT continues to enjoy a meteoric rise, putting it just behind Sydney and Melbourne in terms of popularity. According to Michael Yardney, CEO of Metropole Property Strategists, Canberra was one of only three capitals to record a cumulative capital gain of over 30% following the GFC. Recent ABS data suggests that this growth has been facilitated by the high demand created by increasing net migration levels, particularly from overseas. To provide adequate supply, housing construction has been at almost an all-time high. “The Canberra market continues to improve in performance and has positioned itself as a leader in growth figures of late,” says Charles Tarbey, chairman and owner of Century 21 Australasia. “Investment in the Canberra market may be a worthwhile consideration, given that it is our nation’s capital city and the areas of suburbia are areas that are very close to the capital city centre.”
Area
South East NSW
Darwin
Units
$399,250
Quarterly
$379,750
Type Median value
APPROACHING PEAK OF MARKET
The Herron Todd White residential property clock looks at which markets are performing well, which are on the rise, and which are on a downward spiral. The coloured entries in the tables indicate a positional change from last month. This issue’s property spotlight is Queensland, which HTW, a property valuation and advisory group, predicts is beginning to recover – on the housing front. When it comes to units, the market is starting to feel the pinch due to overbuilding in the CBD and high-density pockets in the outer suburbs. The stock needs to be listed at competitive prices to find buyers. For investors looking for long-term tenants, especially owners of older units, it can be a challenge. HTW says investors will have to stomach listing their units at lower rental rates to fill them. Housing markets to the north and west of Brisbane are doing well, with smart developers reducing land sizes to bring prices down, and sufficient infrastructure in these areas to make them convenient for first-time buyers.
$510,000
Area
UNITS
$605,000
Adelaide has experienced a slight boost over the past few months, but the future looks bleak for this capital city. “The Adelaide property market is likely to underperform again this year, with few growth drivers and high unemployment,” says Michael Yardney, CEO of Metropole Property Strategists. Angie Zigomanis, senior manager of residential property at BIS Oxford Economics, concurs, pointing to the closure of the Holden automotive plant, which will take away many employment opportunities. “There’s a broader impact to be felt across the city, so that’s going to be a major hit for the state. In the meantime, you haven’t got economy-driving growth at the moment,” Zigomanis says. “We’re seeing that interstate migration to the other states has increased over the last couple of years as well. Not a huge amount of shortterm upside at the moment.”
$406,000
With limited growth drivers, Adelaide could stumble
Canberra
CAPITAL CITY HOME VALUE CHANGES Capital city
Weekly change
Monthly change
Year-to-date change
12-month change
Sydney
-0.4%
-1.2%
3.7%
11.0%
Melbourne
-1.0%
-1.9%
3.3%
12.0%
Brisbane
0.1%
0.6%
1.9%
4.1%
Adelaide
0.6%
-0.6%
2.4%
1.7%
Perth
-0.1%
-0.7%
-3.1%
-4.5%
Combined 5 capitals
-0.5%
-1.1%
2.7%
8.4%
*Brisbane results are for the combined Brisbane and Gold Coast region. The monthly change is the change over the past 28 days.
Source: Herron Todd White May 2017 Month in Review residential report, htw.com.au
PEAK OF MARKET
Peak of market
Melbourne
Griffith
Coffs Harbour
NSW Central Coast
Gold Coast
Newcastle
Starting to decline
Approaching peak of market
DECLINING MARKET
Rising market
Declining market
Brisbane
South West WA
Canberra
Toowoomba
Perth
APPROACHING BOTTOM OF MARKET
Approaching bottom of market
Start of recovery Bottom of market
Alice Springs
Mackay
Gladstone
Rockhampton
BOTTOM OF MARKET Adelaide
Ipswich
Darwin
Whitsundays
Emerald
TASMANIA
Despite the capital’s growth, the upswing may only be brief With low property prices and strong efforts in the tourism industry, the Apple Isle is getting a lot of attention as the next property hotspot. However, some experts are wary about its long-term potential. “Hobart property prices look cheap when compared to other mainland capitals,” says Michael Yardney, CEO of Metropole Property Strategists. “However, I would be wary about buying Hobart property as the price differential between Hobart and the mainland capitals has always been significant. Even though economic growth and tourism have picked up recently, with minimal population growth there are few long-term growth drivers in this isolated property market.”
Area
Type
Median value
Quarterly growth
12-month growth
Hobart
H
$390,000
4.0%
4.6%
TAS Country
H
$270,000
3.8%
0.0%
Hobart
U
$300,000
6.6%
2.7%
TAS Country
U
$227,500
-0.5%
0.0%
Source: Except where otherwise stated, all data sourced from CoreLogic.com.au
www.brokernews.com.au
29
PEOPLE
IN THE HOT SEAT Steve Tully with Port Finance Group not only survived his first year as a mortgage broker, he excelled at it, writing $16m in loans. Tully explains how he did it, who he’d challenge to a tennis match and what’s next on his bucket list Who or what inspired you to become a broker? One of my closest friends has a very successful finance business A and I had seen first-hand the rewards of his hard work. After achieving success in the corporate world without truly reaping the benefits of my hard work, I wanted to set up my own business. With a background initially in finance, then sales management, I felt that my skill set was well-suited to mortgage broking. Networking and building relationships comes naturally to me and I felt my values, work ethic and love of helping people would help me succeed.
Q
What’s been most memorable about your first year in the industry? Not just surviving, but managing to write $16m in business A from a standing start and via self-generated leads. Receiving referrals from happy clients has also been very satisfying, as it reaffirms that I’m on the right track. I want to write $35m in my second year and know I will only come close to that number through hard work, providing my clients and referral partners with great service and aligning myself with top brokers who I can continually learn from.
Q
If you could play sports with anybody, who would you choose and why? I’m originally from Scotland and absolutely love the Australian A Open, so maybe a game of tennis with Andy Murray. He comes across as very down to earth and has a good sense of humour, so I think he would be good company.
Q
What do you wish someone had told you about the industry before you got into it? That it changes continuously and therefore you need to be A adaptable, proactive and willing to embrace change. Technology has been one of the biggest drivers of change and will no doubt continue. There has also been the Sedgwick and ASIC reviews, which will result in some changes, and the overseas lender and investment spaces, stamp duty and lender policies.
Q
What have you dreamed of doing that you haven’t got around to yet? Doing a major renovation or building a house. This will soon A become a reality as my wife and I are planning on renovating a house on the Mornington Peninsula next year and turning it into a long-term family home. Something else to tick off the bucket list! AB
Q
30
www.brokernews.com.au
NOMINATIONS NOW OPEN
Friday 27 October • The Star Sydney www.australianmortgageawards.com.au Event Partner
Award sponsors
Official publications
Organised by
www.brokernews.com.au
31
32
www.brokernews.com.au