MAY 2017 ISSUE 14.09
Drifting on the edge Why brokers should be preparing for a higher-rate, higher-risk environment /16
Making brokers superhuman Prescriptive analytics could help brokers do more and worry less /21
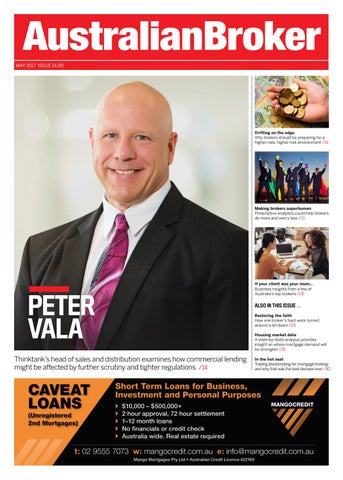
PETER VALA Thinktank’s head of sales and distribution examines how commercial lending might be affected by further scrutiny and tighter regulations /14
If your client was your mum... Business insights from a few of Australia’s top brokers /20
ALSO IN THIS ISSUE … Restoring the faith How one broker’s hard work turned around a let-down /23 Housing market data A state-by-state analysis provides insight on where mortgage demand will be strongest /26 In the hot seat Trading stockbroking for mortgage broking, and why that was the best decision ever /30
NEWS
IN THIS SECTION
Lenders Brokers help grow ANZ’s home loan portfolio /04
Associations FBAA raises concerns about volume hurdles /06
Technology New tech tools facilitate small business lending /10
Commercial APRA eyes commercial lending /12
Consumers RBA holds May cash rate, as most brokers and other experts had predicted /08
www.brokernews.com.au MAY 2O17 EDITORIAL Editor Otiena Ellwand News Editor Miklos Bolza Production Editor Roslyn Meredith
DATES TO WATCH
Upcoming industry events and key dates
ART & PRODUCTION Design Manager Daniel Williams Designer Martin Cosme
2 3 M AY – 2 5 M AY
2 4 M AY
3 1 M AY
CeBIT Australia
MPA Business Summit, Melbourne
Credit and Financial Services Law Training
MPA magazine’s High-Performance Business Summit features a line-up of award-winning brokers and brokerages that will provide insight and information regarding the skills and strategies businesses need to drive growth and generate revenue in the industry
Dentons law firm is holding a day-long training workshop in Sydney for anyone in a managerial, compliance or training role with an Australian Credit Licence or an Australian Financial Services Licence
This event is Asia-Pacific’s largest and longest-running business technology conference. It features more than 170 speakers and 100 start-up companies from fintech, government, cyber security and big data
Production Manager Alicia Chin Traffic Coordinator Freya Demegilio
SALES & MARKETING Sales Manager Simon Kerslake Account Manager Rajan Khatak Marketing and Communications Manager Lisa Narroway
CORPORATE Chief Executive Officer Mike Shipley Chief Operating Officer George Walmsley Managing Director Justin Kennedy Publisher Simon Kerslake Chief Information Officer Colin Chan Human Resources Manager Julia Bookallil
EDITORIAL ENQUIRIES
Otiena Ellwand +61 2 8437 4792 Otiena.Ellwand@keymedia.com.au
SUBSCRIPTION ENQUIRIES
tel: +61 2 8O11 4992 fax: +61 2 9439 4599 subscriptions@keymedia.com.au
3 1 M AY – 2 0 J U N E Pepper Money’s Insights Roadshow Following the success of the 2016 event, Pepper Money’s Insights Roadshow is back with masterclasses on specialist lending on various dates in Melbourne, Brisbane, Perth, Adelaide and Sydney
7 JUNE
8 JUNE
Regtech Australia Forum
Banking and Finance Ethics conference
InnovationAus.com is hosting a number of speakers at this forum in Sydney to discuss the biggest challenge affecting the financial services sector: regulatory compliance and the role of technology in that space
This Sydney conference provides an opportunity for those in banking and finance to openly discuss and explore ethical issues that are contributing to the erosion of public trust in the industry
ADVERTISING ENQUIRIES
Simon Kerslake +61 2 8437 4786 simon.kerslake@keymedia.com.au Rajan Khatak +61 2 8437 4772 rajan.khatak@keymedia.com.au Key Media Pty Ltd Regional head office, Level 1O, 1–9 Chandos St, St Leonards, NSW 2065, Australia tel: +61 2 8437 4700 fax: +61 2 9439 4599 www.keymedia.com Offices in Sydney, Auckland, Denver, London, Toronto, Manila, Singapore, Bengaluru
30 JUNE
2 7 J U LY
End of ASIC public consultation
MFAA National Excellence Awards
Don’t miss the chance to have your say on ASIC’s review of mortgage broker remuneration. Interested parties are encouraged to submit feedback via the government’s Treasury website until 30 June
The MFAA has announced 315 finalists for its upcoming awards program, selected from more than 450 submissions. The awards recognise the association’s core values, including professionalism and integrity. The national event will be held in Melbourne
2
www.brokernews.com.au
11 - 13 OCTOBER Credit Law Conference The 27th annual event in Surfers Paradise brings together banks, credit unions, regulators, associations and market disruptors to discuss the future of credit and lending
This magazine is printed on paper produced from 1OO% sustainable forestry, grown and managed specifically for the paper pulp industry Copyright is reserved throughout. No part of this publication can be reproduced in whole or part without the express permission of the editor. Contributions are invited, but copies of work should be kept, as Australian Broker magazine can accept no responsibility for loss. Australian Broker is the most-often read industry publication, according to independent research carried out by the Ehrenberg-Bass Institute for Marketing Science at the University of South Australia in December 2008. The research also found that brokers rate Australian Broker as the best for both news content and feature articles, followed by sister publication MPA. Overall, on all categories, Australian Broker ranks top followed by MPA. The results were based on a sample of 405 respondents who were the subject of telephone interviews.
NEWS
LENDERS ANNUAL MORTGAGE LENDING INCREASES BY 7.5%
ANZ’S HALF-YEARLY FINANCIAL RESULTS: LENDING NUMBERS Source: ANZ’s half-yearly financial results, ending 31 March 2017
lending by authorised deposit-taking institutions (ADIs) increased by 7.5% to $1.54trn over the 12 months to 31 March, according to APRA’s monthly banking statistics. This equated to a 0.47% increase over the month of March. Owner-occupier loans increased by 0.49% to $988bn, while investment loans rose by 0.43% to $545bn (making up 35.3% of the total ADI loan book). The total loan books for the big four banks are as follows: CBA $412bn; Westpac $381bn; ANZ $243bn; NAB $240bn. OVERALL
62% owner-occupier loans
992,000
34%
total home loan portfolio
6%
$3.4bn
investor loans
50%
SEDGWICK MAY TRIGGER FLIGHT FROM IN-BANK BROKER CHANNEL Sedgwick review’s proposed changes to bank staff ’s commission structure could mean in-bank brokers quit their jobs and venture out on their own, a leading union representative has said. In an interview with the Australian Financial Review, national secretary of the Finance Sector Union Julia Angrisano said overhauling remuneration for bankers while maintaining upfront and trail commissions for brokers would create an uneven playing field.
$256bn
home loans – an increase of 1.6%
loans written by brokers in 1H17
loans to first home buyers
total cash profit
THE
“It’s a little simplistic to say there is a housing bubble. Where there is an issue, there is clearly an issue around housing affordability” Shayne Elliott CEO, ANZ
4
www.brokernews.com.au
BROKERS WROTE HALF OF ANZ’S LOANS, BOOSTING MORTGAGE FILE The major bank’s home loan portfolio has grown $13bn this financial year Australia and New Zealand Banking Group’s half-yearly financial results show solid growth across the lender’s residential mortgage portfolio. The number of home loans rose to 992,000 from 976,000 from the first half of the 2016 financial year to the first half of the 2017 financial year. This puts the total funds under management in ANZ’s home loan portfolio at $256bn, which is $13bn more than the year before. Of this total, 62% were owner occupier loans while 34% were investor loans, signifying a shift from the same period the year before, when 60% of all lending was to owner-occupiers and 36% to investors. Six per cent of all THE
mortgages were taken by first home buyers, while 5% were low-doc loans. The number of borrowers ahead on their mortgage repayments dropped by 1% over the year, and the number now sits at 39%. The broker channel has grown, with 50% of all loans in 1H17 written through the third party, compared to 48% the year before. According to data from APRA, ANZ wrote 15.6% of all loans, placing it third out of the big four in terms of market share. In a conversation with BlueNotes, ANZ’s news publication, Shayne Elliott questioned the accuracy of labelling all of Australia as being in a housing bubble.
“There is absolutely not a housing bubble today in Western Australia. The housing bubble that people talk about is really restricted to Sydney and Melbourne more or less, and even then … there are pockets where prices are continuing to rise, and there is absolutely evidence today where prices are stabilising and falling in some areas,” he said. Elliott said it was “a little simplistic” to say there was a housing bubble. He said the clear issue was around housing affordability and people’s inability to even afford a deposit. “There are some challenges in the business. We are a big player in that market, we have a responsibility to respond to those customers’ needs in terms of how to make that easier for people and convenient, but to do it in a responsible way,” Elliott said. The bank’s total cash profit was $3.4bn, a 23% year-on-year increase.
NEWS
A S S O C I AT I O N S SMALL BUSINESS MINISTER LAUDS BROKERS am in awe of what you do,” said Minister for Small Business Michael McCormack to a roomful of brokers at an event hosted by the MFAA on 26 April. The minister spoke of the challenges and opportunities brokers face in regard to housing affordability, the banking sector, innovation, regulation and the government. McCormack briefly touched on ASIC’s broker remuneration review, saying that while it made proposals to tweak the structure, it didn’t recommend government action. “I
BROKING EXPERT TO BUILD INDUSTRY MENTOR COMMUNITY high level of attrition among new brokers has pushed one industry professional to try to help those just entering the field to establish themselves. Aaron Christie-David, managing director at Atelier Wealth, said he had approached the MFAA to find solutions after data revealed that 50% of new industry brokers failed in their first 18 months. Some of the common challenges brokers face include a feeling of loneliness, a lack of knowledge around credit policy, and differences between perception versus reality. A
VOLUME HURDLES ‘COMPLETELY WRONG’, SAYS FBAA Consumer outcomes at risk when brokers are bound by lender restrictions on loan volumes conditions that brokers write a certain number of loans per month or year to retain accreditation need to go, said Peter White, executive director of the FBAA. Speaking in front of the Senate Standing Committee on Economics in a government inquiry into consumer protection in the banking, insurance and financial sector on 26 April, White said these restrictions – called minimum volume hurdles – were reducing brokers’ abilities to write loans for whatever lender they desired. “What that creates is a very bad consumer outcome because a broker can only give guidance on loans for lenders that they’re LENDER-IMPOSED
6
www.brokernews.com.au
accredited to,” he said. These restrictions mean that while a broker may be doing the right thing for the borrower with regard to the panel of accredited lenders they have access to, there may be another outside that scope which is more suitable. “Unfortunately they can’t reach into that because they are constrained by the aggregator’s agreements and those accreditations. That’s generally restricted because they don’t have volumes to reach that lender,” he told the panel. White also criticised elite broker clubs, saying he would outlaw them if he could. With brokers given access to better speed of applications, this was “unreasonable” and
“completely unfair” to the borrower, he said. “You have an innocent borrower at the back end there. He’s sitting behind a broker who may only give a specific lender one deal every three months,” he said. “That gets penalised because they don’t have the volume. It’s got nothing to do with the borrower.” When asked about soft-dollar benefits, White said these incentives needed to become more transparent, although completely outlawing them might not be the best solution. There was also nothing wrong with the current base model of commissions that brokers are paid today, he said, referring to the FBAA’s global research that found Australian brokers were paid below the global average. As for trail, White said this provided a number of positive consumer outcomes when it was introduced.
“If you can’t trust your broker, who can you trust?”
Michael McCormack Minister for Small Business
NEWS
CONSUMERS VOTERS SUPPORT NEGATIVE GEARING REFORMS across party lines and age groups are backing a controversial crackdown on property investors to improve housing affordability, with 54% supporting reforms to negative gearing and capital gains tax, according to a poll conducted exclusively for The Australian. Voters are throwing greater support behind the two reforms amid tense political clashes over tax breaks worth $8bn annually, lending weight to an argument within the government to overhaul capital gains tax. AUSTRALIANS
NEW BLUEPRINT FOR HOUSING AFFORDABILITY Lloyd-Hurwitz, CEO of real estate group Mirvac, has a six-point plan to deal with housing affordability. Her plan focuses on increasing housing supply for owner-occupiers and getting it to market faster and cheaper. Her proposals include improving planning reforms, reinstating the National Housing Supply Council, rolling out successful state initiatives federally, reconsidering current tax burdens, improving government support, and creating a build-to-rent sector. SUSAN
“With household debt levels at record highs, and the large majority of this debt related to housing, higher mortgage rates have the potential to take some heat out of the market” Tim Lawless Head of research, CoreLogic
RBA HOLDS CASH RATE FOR NINTH MONTH IN A ROW Both brokers and economic and finance experts widely predicted the May cash rate call
housing market was likely front and centre in the Reserve Bank’s decision to keep the official cash rate on hold again this month at 1.5%, said CoreLogic’s head of research Tim Lawless. “Capital city dwelling values have increased by almost 10% since the latest round of rate cuts in May and August last year, led by gains of around 13% in Sydney and Melbourne,” Lawless said. The RBA’s decision to hold the cash rate for the ninth month in a row was widely anticipated by economic and finance experts across the country given the current national and international environment. Finder.com.au’s monthly survey found that 34 out of 34 economists predicted that rates would remain steady while around 96% of THE
mortgage brokers polled by HashChing said the same. While a broad range of economic factors would have been considered by the RBA board, Lawless said the surge in housing prices coupled with a rebound in investmentrelated credit growth was likely the major cause for concern. However, there were indications of a softer market as capital city dwelling values fell flat in CoreLogic’s latest April figures. With investor mortgage rates already on the way up and further hikes predicted, higher interest rates had the potential to take some of the heat out of the housing market, especially in the investment sector, Lawless said. “A housing market slowdown would relieve one of the key concerns the RBA has relating to
financial stability; however, the Reserve Bank would likely be seeking confirmation of a slowdown from a longer trend of slower capital gains and lower credit growth.” John Flavell, CEO of Mortgage Choice, was also unsurprised that the RBA left the cash rate untouched, especially with Australia’s robust housing market, slight increases in inflation, and low unemployment levels. Despite the RBA’s decision to keep the cash rate at 1.5%, Flavell said several out-of-cycle rate moves had already been made by the banks. “Over the last couple of months, there has been a lot of volatility in the global markets, which has resulted in increased funding costs for many of Australia’s lenders, which has led to higher home loan interest rates across the board,” he said. “Australia’s lenders have made some changes to their pricing and policy, and I would expect to see more of this over the coming weeks and months.”
BROKERS SURVEYED ON INDUSTRY ISSUES Source: HashChing
95%
91%
70%
72%
91%
of brokers thought the RBA would keep interest rates on hold in May
of brokers believe other lenders will increase their rates after CBA and Westpac’s recent increases to fixed rate home loans
of brokers believe using superannuation funds for housing deposits will not be beneficial in helping first home buyers
of brokers are not in favour of a crackdown on capital gains tax concessions for property investors
of brokers do not agree with the Sedgwick review’s opinion that mortgage broker commissions need to be more tightly regulated
*More than 300 brokers participated in the survey
8
www.brokernews.com.au
NEWS
TECHNOLOGY
CO-FOUNDER LEAVES AUSTRALIA’S NEWEST BANK FOR TECH START-UP co-founder of Australia’s newest bank, Tyro Payments, has left the organisation to pursue other business opportunities. Andrew Rothwell, who was also the bank’s head of sales, departed on 19 May to join a start-up technology business. CEO Gerd Schenkel thanked Rothwell for his outstanding service and contribution in his 14 years working for Tyro. “Andrew’s passion for start-up businesses is infectious, and he can be proud of the long-term shareholder value he has helped generate since co-founding Tyro in 2003,” Schenkel said. THE
NEW TOOLS RELEASED TARGETING SME LENDING An aggregator and online lender have separately released two new tools aimed at facilitating small business lending lender Spotcap and national aggregator eChoice have simultaneously released two digital tools to assist clients and brokers with small business lending. Spotcap’s offering is an online portal to help explain and create further awareness of the different non-bank lending options available for small and medium-sized businesses. The portal is available in the form of an interactive microsite containing information on the different finance sources available. It was created in response to a recent market survey by Pureprofile which found that over half of approximately 1,000 respondents were unaware of the different non-bank lending choices available. ONLINE
The tool was developed in conjunction with a number of other fintech lenders and will help clarify how the different options can act as an alternative to more traditional instruments, such as the banks. “We want to equip SME owners with the information they need to fund the growth of their businesses, in ways that suit their circumstances and requirements,” said Lachlan Heussler, managing director of Spotcap Australia. “Not all financial products suit all businesses, and we want to make potential borrowers aware of both the range of options now out there, and which could work for them.” Aggregator eChoice has also come out with its own purpose-built portal and service aimed at the self-employed sector.
“The new www.selfemployedloans. com.au portal provides specialist loan and service packages for the sector and brings an aggregated offering to the market through partnerships with established industry lenders and ancillary product providers,” said CEO of eChoice Peter Andronicos. “As a digital and broker-supported service, the portal provides a ‘supermarket’ of opportunities for the growing number of selfemployed borrowers to investigate their options, not only for property purposes but also commercial, business and asset financing.” The portal will extend the aggregator’s footprint as a provider of lead generation solutions, while broadening its range of retail products delivered through the broker channel. In today’s expanding market, self-employed borrowers should be aware that many lenders have a range of suitable loans available as long as income can be substantiated, Andronicos said.
VV GLOBAL INVESTMENT IN FINTECH COMPANIES TOTAL Source: Pulse of Fintech Q4’16: Global Analysis of Investment in Fintech, KPMG International (data provided by Pitchbook). 21 Feb 2017
Deal value
1,255
Deal count
1,076
1,065 818 576 445
319
10
$9bn
$6bn
$4bn
$12bn
$29bn
$47bn
$25bn
2010
2011
2012
2013
2014
2015
2016
www.brokernews.com.au
SME LENDER UNVEILS NEW FACE-CAPTURE TECH fintech Sail Business Loans has unveiled a new biometric security system that allows instant ID verification of clients through a simple selfie. The “natural face capture” technology confirms a user’s identity against official identification, such as a passport or driver’s licence. The platform verifies that the documents have not been tampered with or forged, at a level of accuracy on par with airport grade security. The system then confirms within 60 seconds that the identity and location of the user matches that of the uploaded documents. AUSTRALIAN
NEWS
COMMERCIAL
PROPERTY COUNCIL QUESTIONS VICTORIAN ‘GIVE AND TAX’ BUDGET Property Council of Australia has mixed views on the budget released by the Victorian Government on 2 May, describing it as a “give and tax” budget. While it welcomed the commitment to infrastructure and housing, it flagged the government’s over-reliance on revenue from property taxation. Victorian Property Council executive director Sally Capp said 44% of revenue in the state budget came from property tax. “You can see that as property values have risen, that has worked very well, but obviously there’s always a risk.” The budget was a missed opportunity to deliver meaningful tax reform, she said, an aspect that hadn’t been reviewed in over 15 years. THE
APRA TO INVESTIGATE COMMERCIAL LENDING The regulator has announced plans to delve further into commercial lending standards lending has not escaped the watchful eye of APRA. Chairman Wayne Byres told an audience at the Committee for Economic Development of Australia’s 2017 NSW Property Market Outlook in Sydney on 28 March that the regulator planned to conduct further investigation into commercial property lending standards this year. “Sound lending standards are vital for the stability and safety of the Australian banking system, and given the high proportion of both residential mortgage and commercial property lending in loan portfolios, there will be no let-up in the intensity of APRA’s scrutiny in the foreseeable future,” he said. COMMERCIAL
RELIANCE ON HOUSING BRINGS RISKS: CITI Australian Government’s reliance on housing to rebalance the economy comes with a number of inherent risks, analysts from Citi Research have said in a new report. These include signs of oversupply in some east coast apartment markets; stretched housing valuations in Sydney and Melbourne; an increasing share of interest-only loans; and a recent upswing in the share of investment mortgages, among other issues. Despite measuring only 5% of GDP, housing activity made up just over half of all private sector growth in the past three years, with employment in the construction sector accounting for almost 25% of the total increase in labour during that time. THE
12
www.brokernews.com.au
residential lending. APRA undertook a review of commercial property lending in 2016, which looked at portfolio controls and underwriting standards of several domestic and foreign bank branches in Australia. “The review found that major lenders were well aware of the need to monitor commercial property lending closely, and the need to stay attuned to current and prospective market conditions,” he said. “But the review also found clear evidence of an erosion of standards due to competitive pressures – for example, of lenders justifying a particular underwriting decision not on their own risk appetite and policies but based on what they understood to be the criteria being applied by a competitor.” APRA was keen to genuinely scrutinise the banks’ commercial lending practices and challenge the notion that growth in this sector was achievable in the current credit environment without the quality of lending suffering, Byres said.
Given the more heterogeneous nature of commercial property lending, Byres said it was difficult to implement the same benchmarks that had been applied to residential lending. But he warned that did not imply that APRA had any less interest in the quality of commercial property lending. APRA would keep “the need for additional guidance material on commercial lending under consideration”, he said. For all the focus on residential property lending, Byres said it had traditionally been the commercial real estate cycles that caused stress in the banking system. Therefore APRA was always watching the trends and standards in this area, as well as the inter-relationship between commercial and
COMMERCIAL REAL ESTATE LENDING BY SECTOR Source: APRA
% of common equity Tier 1 capital 60% Dec 13
50%
Dec 14
Dec 15
Dec 16
40% 30% 20% 10% 0% Office
Retail
Industrial
Land and residential development
Other domestic
Overseas
WHITE-LABEL UPDATE
s
WHITE-LABEL: A SUCCESS ACROSS INDUSTRIES The popularity of white-label loans is rising as brokers increasingly recognise the benefits to their business and clients. However, some customers may be unfamiliar with the concept of white-label home loans. To help explain this to customers, we can look at the success of white-label products across other industries – so brokers can show their clients that white-label is a successful business model that they probably take advantage of every day! In this article, we’ll look at three white-label strategies employed across the supermarket and pharmaceutical industries and how they are applicable to the lending landscape. 1. White-label has been embraced by customers across industries White-label is a great success in the supermarket space, and a 2016 Canstar Blue study shows 65% of consumers are now buying white-label grocery products over big-name brands. Two of the stand-out examples are Coles and ALDI. The evolution of Coles’ white-label products began in November 2015 when the retailer eliminated home brand labels, including Smart Buy. These labels fitted under an outdated model of white-label, where the product was seen as low quality as well as low price. In recognition of the fact consumers were no longer buying these ‘cheap’ products, Coles invested heavily in relaunching its white-label products under a new singular Coles brand, which was positioned as great quality at affordable prices. The move has been a resounding success and sales have dramatically increased. Coles brand even began outperforming some of the popular brand names! ALDI, too, has consistently positioned itself as providing products that are both high quality and low cost. It even uses a ‘blind taste test’ model, putting its white-label products through the paces against the leading brand names. Clearly, ALDI consumers know they are onto a winning white-label model and the figures speak for themselves, with ALDI sales jumping 60% between 2013 and 2016 as their reputation as a high-quality provider grew. In the same way, the white-label loan industry is flourishing as brokers and their customers realise the products are much more than just a cost-effective solution – they provide value. The percentage of brokers with access to Advantedge’s white-label products surged to 85% at the end of 2016 from
Brett Halliwell, General Manager, Advantedge Financial Services
35% in 2015, underpinned by the growing understanding we provide a quality loan type that benefits brokers and their customers, and comes with great service and support programs. 2. White-label solutions have evolved from ‘cheap’ to ‘good-value, quality’ products Not all strategies are created equal. Woolworths has fallen behind the other two supermarket giants in terms of its white-label offering because it only competes on price. It currently has a multi-layered white-label offering, including Gold, Select, and Homebrand. Each of these labels are marketed differently: Gold is for premium quality, Select is the midtier range, and Homebrand is a no-frills budget option. Interestingly, when private label was first introduced 11 years ago, it accounted for 12% of Woolworths sales. This has fallen to 10%, just as the white-label brands of its main rivals have flourished. Woolworths is now moving to a model that is about quality as well as low cost. It plans to remove the Homebrand and Select products from its range as of 2018 and replace them with Woolworths brand products, similar to the Coles model. Like Coles and ALDI, Woolworths realises consumers will no longer settle for ‘cheap’. There is enough choice in the market that consumers don’t have to sacrifice quality to get the best price. This resonates with the broking
industry as Advantedge’s white-label offer is no longer just about price, it’s also about service and a quality loan that provides the essential home loan features without customers having to pay for things that they don’t need. 3. A trusted adviser helps white-label flourish Finally, it’s useful to look at the success of white-label in the pharmaceuticals industry. Here the pharmacist is a trusted expert that consumers go to for advice, and it is their recommendation of the generic product over the branded alternative that gives the consumer confidence in its quality. Brokers are in a similar position as they are the experts guiding customers through a complicated lending system. If brokers can offer customers an exclusive loan, one that isn’t available through online and retail channels, and one that delivers quality at a sharp rate, then they are providing immense value. Looking at the evidence from the supermarket and pharmaceutical sectors, what we have found is clear: the formula for a successful whitelabel offering is the combination of a competitive price and a high-quality product delivered with exceptional service. Importantly, growing consumer appetite for white-label products across different sectors is now also reflected in the broking industry. According to the latest MFAA Quarterly Comparator Data, white-label now accounts for 6.6% of overall home loans which has doubled over the last two years.
FE AT URES
COVER STORY
ALL EYES ON COMMERCIAL LENDING Thinktank’s head of sales and distribution, Peter Vala, explores how regulatory and industry changes in residential lending could flow through to affect commercial lending
THINKTANK SNAPSHOT Established January 2006
$980,000,000 Total originations
$640,000 Average loan size
<1%
Current >30 days’ arrears
64.4%
Weighted average LVR
99.5%
Loans introduced by brokers
5%
NCCP-regulated loans
14
www.brokernews.com.au
has expressed increasing interest in the commercial property market, with chairman Wayne Byres indicating a potential investigation into commercial lending standards later this year. APRA has signalled mounting concern over bank exposure to apartment construction, and Byres warned in his speech at the Committee for Economic Development of Australia’s (CEDA’s) 2017 NSW Property Market Outlook in late March that there would be “no let-up in the intensity of APRA’s scrutiny” of both residential and commercial property lending. Up to this point, the regulator’s actions have largely focused on taking the heat out of the housing market by demanding more resilience of the banking system, with speed limits on lending to investors, and banks being forced to hold more capital against their home loan books. “Commercial lending, due to its diverse nature, is much more difficult for the regulator to influence beyond a variety of indirect measures being imposed on banks,” says Peter Vala, head of sales and distribution at Thinktank Commercial Property Finance. He anticipates those measures might include more prescriptive lending guidelines and greater transparency in reporting, which may lead to increased capital requirements for certain types of exposures. “Either way, the banks are on notice. The consequence of this has been revealing itself APRA
as some lenders become more selective in the loans they are prepared to write and they are pulling back in areas of the market where they may be overweight,” Vala says. Commercial brokers and borrowers shouldn’t be as affected as those in the residential sector, though Vala says having access to a wider panel of bank and non-bank lenders is a worthwhile strategy as risk appetite and available loan options adjust to more intense regulatory intervention.
the cost of financing and will increase with the consumer price index. These assets will also be bought and sold more frequently, with the value being a function of the underlying return profile. By comparison, the income from a residential investment property will normally be insufficient to meet the interest and holding costs. The owner counts on capital appreciation over time and has other reliable sources of income to make up the shortfall. With an interestonly home loan, the buyer is exposed to a persistent net negative return until they sell, which justifiably concerns APRA and the Reserve Bank, Vala explains. While those measures are not necessary in commercial lending, Thinktank does encourage brokers and borrowers to consider principal and
“Commercial lending, due to its diverse nature, is much more difficult for the regulator to influence” He also suggests brokers develop an open and honest relationship with their lenders’ relationship managers to stay up to date on any changes. Not one and the same As Byres pointed out in his CEDA speech, benchmarks applied to residential lending won’t work the same way for commercial lending. So, while banks are tightening interestonly loans in the residential space, that’s not the case with commercial. A commercial loan functions with the greatest financial efficiency on an interest-only basis, Vala says. The income from the property will normally exceed
interest repayments in this low interest rate environment. Thinktank offers longer-duration commercial terms of between 25 and 30 years to make cash flow more manageable for borrowers. These loans operate in much the same way as a home loan does on a set-and-forget basis, Vala says. One thing Vala believes brokers should be aware of is the difference between a 15-year “notional term” and a standard 15-year loan term on commercial facilities. Some banks use the former to calculate the monthly loan repayments, while only committing to an actual term of one to five years. In doing this, the loan is amortising at
principal and interest, which is being driven by the same cost-of-funds argument,” Vala says. At Thinktank there is no difference in interest rates between commercial owneroccupier and commercial investment property loans, he adds.
Peter Vala, head of sales and distribution at Thinktank Commercial Property Finance
a rate over 15 years, yet the commitment is only for five years. Once those five years are up, the borrower has to reapply or refinance, shouldering the cost of a new valuation, the establishment fee and legal fees. Some banks do this because it means the cost of capital is much lower for shorter commitments and they can deliver a lower headline rate of interest to the customer, Vala says. Thinktank recently refinanced an $800,000 loan from a major bank that had originally been for the purchase of a commercial property. The bank provided a 15-year notional term, with five
years’ interest only. At the end of the interest-only period, the borrower’s monthly repayment soared from $4,333 to more than $9,000. Vala says this is an example of the “repayment shock” some lenders push onto borrowers. Thinktank formalised a standard 25-year principal and interest loan, which reduced the loan repayments to $5,363 per month, with an option to increase loan repayments to accelerate the amortisation if required. Interest rates in commercial In the past couple of months, major and non-major banks have
increased mortgage rates for investors while generally leaving owner-occupier loans alone. This contrast is not as prevalent in the commercial lending space, Vala says, though different institutions can adopt varying approaches to risk and product options. Some institutions will alter the maximum LVR for a commercial loan, depending on the use of the property. “While we do not expect to see interest-only pricing vary between investment and owner-occupation, we are starting to see a movement towards interest-only attracting a slightly higher rate than
A minefield for brokers It doesn’t appear as though Australia is headed for a repeat of the same sort of credit crunches experienced in the past, although the provision of institutional credit is becoming more selective. The drivers of this are more around sustainable health of the property market and the economy than a drying up of credit supply. “If anything, there is an oversupply of credit at the moment, which is being reflected in both the level of debt currently in the system and the yields being paid on assets of practically all types,” Vala says. “For good-quality lending in residential, commercial and other business financing, we anticipate that conditions will remain favourable for the medium term, absent of a major shock or development probably emanating from offshore.” Regulatory changes are putting new pressures on the market and its players to adapt. Many more product options have emerged, as well as tiered pricing and variations in eligibility. This is primarily for the benefit of the lender to increase cost of capital, creating a minefield for brokers and their clients to navigate, Vala says. But there is no reason to despair: in times like these, skilled brokers are even more valuable. And Vala says brokers who remain close to their clients and lenders will be able to work through the options to source the best client-focused financial solutions available. AB www.brokernews.com.au
15
FE AT URES
NE WS ANALYSIS
HIGHER RATES, HIGHER RISK APRA’s decision to cap the volume of interest-only loans is just one sign of a more fraught housing market to come. As Ben Abbott finds, brokers should be preparing their businesses and their customers now for a higher-rate, higher-risk environment Rachelle Eyndhoven, director of Sphere Finance
APRA decided to limit bank interest-only loans to 30% of new lending in late March, Digital Finance Analytics principal Martin North saw the move as too little, too late to save the housing market from a coming correction. “My view is that the latest APRA changes are merely a touch on the tiller,” North told Australian Broker. “Cutting back on interest-only loans makes sense, but it does not get to the heart of the housing finance conundrum. APRA is playing at the edges.” However, while the decision may not be sufficient in North’s view, he argues that it was a wise move. “We have seen a rise in interest-only loans to around 40% of major bank lending, and most of these are aligned with investors. The problem is interestonly loans are riskier because borrowers are not paying off the capital they owe.” The property market may be entering a new phase, and it could end up hitting opportunistic interest-only borrowers the hardest. For example, North says interest rates will continue to increase this year, by about 50 to 70 basis points for investor loans. This will be driven partly by the need for banks to access higherpriced international capital markets to fund their books, and by the likelihood of further requirements for banks to hold more capital. Banks also need to limit investor loan growth to 10%; to rebuild margins destroyed WHEN
16
www.brokernews.com.au
through heavy discounting last year; and to be ready for renewed deposit competition. “Owner-occupier loans may increase a little less [than investor
borrowers will need to exercise a new level of caution by allowing for a substantial rise in rates, being conservative on cash flow and income expectations, and
“Most banks’ underwriting assumptions were made in times when incomes were rising faster than home prices and mortgages, but the world has changed” Martin North, Digital Finance Analytics loans], but irrespective of what the RBA may do to the cash rate, international rates and mortgage rates are going higher. The era of ultra-low cash rates is passing,” North says. This means that brokers and
ensuring loans are ‘not unsuitable’ in the new environment. “Most banks’ underwriting assumptions were made in times when incomes were rising faster than home prices and mortgages, but the world has changed, and
behaviour must change also,” North says. Only interest Kevin Lee just sold his Smartline mortgage broking franchise. Having written a billion in finance over 18 years, he’s now embracing his true passion – helping Mr and Mrs Average become ‘successful’ investors. However, being active on behalf of investors means he needs to keep a close eye on the pockets of excess in Australia as they’ve developed. “Yes, some parts of Australia are definitely in ‘bubble’ territory, especially Sydney,” says Lee, founder of Smart Property Adviser. “The other areas of major concern are Melbourne and Brisbane apartments, as both have a terrible stigma over them at present,” he says. Lee says it’s interest-only loans
BURNT-OUT BORROWERS Source: Finder.com.au
Equivalent rate rise that would increase repayments by $100 for an average $360,600 mortgage
57%
Percentage of mortgage holders that could not handle a $100 increase in their loan repayments
5.28%
0.45%
Average standard variable rate that would tip these borrowers over the edge this year
Kevin Lee, founder of Smart Property Adviser
Tanya Sale, CEO of Outsource Financial
that could provide Australia’s ‘Big Short’ moment. “In recent years more owneroccupiers have been opting for interest-only loans than ever before,” he says. “Interest-only loans are typically set up as interest only for the first five years. Some lenders will let you stretch that to 10 years, or more. But it’s what happens next that catches most people out, because they aren’t aware these loans literally are a ticking time bomb for unsuspecting borrowers.” The majority of mortgagors expect to be able to refinance at the end of their loan term into another five-year interest-only period, or a principal and interest loan over 30 years, Lee says. “But – and it’s a big but – that loan could become a major hurdle when they find it now requires principal and interest repayments and the original loan term still applies. In this uncertain financial world we are now in, unless you can convince your bank not to, your repayments will be restructured as P&I over 25 years,” he says. North says banks have played a role in creating this problem. “A recent survey we did suggested that more than half [of interest-only borrowing customers] had no plans, despite earlier guidance from the regulator that they should not lend interest only unless the borrower had a plan,” he explains. “Of course, people expect to be able to pay from capital gains on the property, and in a rising market this may be feasible, but if prices were to fall many borrowers could not repay and
Martin North, principal of Digital Finance Analytics
would be forced to sell.” The UK provides an example of this. “When they clamped down, many borrowers were shocked to find they could no longer get an interest-only loan. In addition, some owner-occupier borrowers get an interest-only loan so they can get a larger loan. Again, regulators say this should not be the case, but we see evidence of this happening. As a result, they are more exposed.” Outsource Financial CEO Tanya Sale says APRA’s move will target these fringe borrowers. “What we will see become extinct is the borrower that obtained interest-only simply because they just could not afford a principal and interest facility,
Rating the reckoning The interest-only loan intervention by APRA is unlikely to stop a market correction, according to North. While he says the regulators had a chance a few years back to intervene, the RBA’s desire to use housing as a replacement for mining to keep the economy going meant it ignored the effect of rate cuts, and stubbornly allowed credit to rise too fast. “APRA and ASIC were also unwilling or unable to get lending under control, so we have spiralling home prices – and not just in Sydney and Melbourne; sky-high household debt; and now pressure on households who have big mortgages thanks to static real income growth, rising costs of
“What we will see become extinct is the borrower that obtained interest only simply because they just could not afford a principal and interest facility” Tanya Sale, Outsource Financial yet by obtaining an interest-only loan they were able to get into the property market,” Sale says. “In this situation what we saw was borrowers being tempted to spend more money than they actually had because they relied on property values increasing, which does not always happen. This is the behaviour APRA and ASIC are wanting to eliminate and ensure that the customer outcome is a positive one.”
living and rising mortgage rates,” he says. “The RBA cut too far, and now are caught between trying to control household debt, growth, and lifting rates. Whatever is done, I suspect we are beyond an orderly adjustment.” However, some brokers are more upbeat. Sphere Finance director Rachelle Eyndhoven is an investor herself, and services an owner-occupier principal and interest loan as well as several
OUR ‘BIG SHORT’? The end of a five-year interestonly loan term can be painful for some borrowers – and may just be Australia’s ‘Big Short’. For example, a $505,600 interest-only loan at a rate of 3.69% requires a repayment of just $359 a week. However, under a 25-year principal and interest scenario, that jumps sharply to $596. Suddenly – and often unexpectedly in the case of unsophisticated owneroccupiers looking for capital gains – an investor needs to find another $237 a week to pay the bank.
Kevin Lee, of Smart Property Adviser, says this is a huge problem for ‘Mr and Mrs Average’. “If that loan is for ‘the place they call home’, to make it even more painful, it’s an ‘after tax’ repayment. It only gets worse when you factor in that our interest rates are at an all-time low and can’t stay that way forever. Interest rates will increase plenty from here on, most likely in 2017,” Lee says.
When they do – even by as little as 1% – Lee says it could be game over for tens of thousands of speculators.
www.brokernews.com.au
17
FE AT URES
interest-only investment loans. “Capping interest-only loans in my opinion does not serve myself or my clients,” she says. “However, if there is a lever being pulled to slow the rapid growth of the property market, and this is seen as in the best interests of the economy, we need to accept it and shift our sales to accommodate the new climate.” Eyndhoven says each borrower will need to make their own decision on how to adjust to any changes going forward. “Some lenders are still offering five years fixed for investors under 4% if they pay principal and interest. So, for a $400,000 loan, the monthly repayment for five years is locked in at $1,907 per month. When rates were 7%, the interest-only repayment for that same debt would have been $2,333 per month, or even at 5% that would have been $1,666 per month interest only. Personally, I would think the principal and interest is looking very attractive and certainly not making property ‘hard to hold’.” If the broker channel has had a role in growing the volume of interest-only loans, Eyndhoven says it’s because it made sense for investors. “It makes no sense when rates are the same and there is a non-tax deductible debt to pay the tax deductible one down. Sphere Finance advises clients who wish to pay extra on lending to focus those extra repayments on the owner-occupied debt. If the rate difference in the new landscape makes it commercially viable to pay P&I on all lending, then that is what we will advise.” And investors are still willing to invest, she says. “Having held multiple properties in 2009, when rates were close to 7%, this is still a viable climate in which to invest. It may slow some people buying that should not invest, though; I believe you should be able to afford the loans at principal and interest or at higher rates to 18
www.brokernews.com.au
protect yourself against market changes.” A cautious approach Brokers will need to change their approach to the market for their clients’ sake, if they haven’t already. For example, North says responsible lending obligations that require ‘not unsuitable’ loans will definitely demand new caution from brokers. “While this obligation is weak, it means in a market where prices are rising, loans are harder to get and household finances are in worse shape, brokers and lenders need to exercise caution, ensuring adequate buffers against rising rates and flat incomes.” While many are already doing this, North suggests that others are still too optimistic for current conditions. “Be cautious. Make sure you understand the true state of household finances and how they would cope with a 2–3% rate rise. Do not assume income growth. Do not assume capital growth. This is what responsible lending demands,” he says. This caution should extend to interest-only loans. “Those with existing interest-only loans coming up for review will find it harder to get a rollover, and may be forced into a P&I loan, which is more expensive – this needs
more court cases as the market unwinds. It cannot be business as usual.” Tanya Sale says borrowers who are becoming anxious with the
“Personally, I would think the principal and interest is looking very attractive and certainly not making property ‘hard to hold’” Rachelle Eyndhoven, Sphere Finance careful management,” North says. Brokers who don’t may face the consequences, he adds. “If they are more aggressive, remember there is recourse if households can prove the advice was unsuitable. I expect to see
spotlight on out-of-cycle rate rises and interest-only loans may question their loan structure. This environment will give brokers an opportunity to showcase the value they can provide. “This becomes an opportunity
for brokers to position themselves with the consumer-borrower to educate and guide, not looking back at the past but to their wants and needs in the future, which could be a totally different path to the one they’ve taken,” Sale says. Kevin Lee agrees. “Brokers should be looking at how they can genuinely help their clients to restructure, make principal and interest repayments on their loans, employ rapid debt reduction techniques on their credit card and personal loans – whatever it takes to help them get through what looks like a very torrid and stressful period ahead.” He says that for the quality brokers in the market, this approach will pay off in the end. “In that way they will always be top of mind when we eventually ‘turn the corner’, and being top of mind equals referrals.” AB
APRA’S DEMANDS OF ADIS
Limit the flow of new interestonly lending to 30% of total new residential mortgage lending
Place strict internal limits on the volume of interest-only lending at loan-to-value ratios (LVRs) above 80%
Ensure there is strong scrutiny and justification of any instances of interest-only lending at an LVR above 90%
Manage lending to investors to comfortably remain below the previously advised benchmark of 10% growth
Review and ensure that serviceability metrics, including interest rate and net income buffers, are at appropriate levels
Continue to restrain lending growth in higher-risk segments (eg high-loan-to-income loans and high-LVR loans)
www.brokernews.com.au
19
FE AT URES
IN THE NE WS
TIPS FROM TOP BROKERS Elite brokers regaled a large crowd at MPA’s Sydney Business Summit with entertaining tales and helpful hints on how to thrive in a rapidly changing industry and why brokers shouldn’t be fixated on loan volume While it used to be a no-no to pay for referrals, demands are changing. “There’s so much work and not as much reward as what we were getting a couple of years ago,” Ezzy said, adding that her business has had to adjust its stance on this front
tight, it’s hard to come across a loan.” If brokers invest providing the best service they can offer now, when lending does start flowing more freely again those brokers will be miles ahead, Karam said. Brokers know that brokers are
“If you’re treating your client as your mother, you don’t want to shove her into a loan” Deanna Ezzy, finance strategist, Trilogy Funding
Deanna Ezzy, finance strategist, Trilogy Funding
your client like they’re your mother”, and remember “beggars can’t be choosers”. Those were just two of the tips – and amusing remarks – that escaped the lips of Australia’s top mortgage brokers at a panel discussion on business strategies at MPA’s High Performance Business Summit in Sydney on 3 May. The four brokers on the panel – Andrew Algie, director of Addisons Advisory Group; Ruan Burger, managing director of Time Home Loans; Deanna Ezzy, finance strategist at Trilogy Funding; and George Karam, director of BF Money – spoke about how to attract new leads, how their businesses were responding to changes in the industry, and what numbers mattered to them most. The brokers emphasised the importance of building strong relationships with referrers, but also said referrers were increasingly asking to be compensated. In 2015, a total of $67m was paid to referrers, up from “TREAT
20
www.brokernews.com.au
$13m in 2012, according to the ASIC report on broker remuneration. “The first rule is: they’ve got to like you. … Secondly, you’ve got to like them. But beggars can’t be choosers, so let them like you first,” Burger told the crowd of about 170 brokers, provoking laughter. But sometimes it’s not that easy and it just comes down to what’s in it for them, he said.
and offer compensation to some. Regardless of how clients get to you, Ezzy’s rule of thumb is to “treat your client like they’re your mother, if you like your mother”. As for other challenges in the industry, including increased scrutiny of brokers’ remuneration structure, APRA’s crackdown on interest-only loans, and the hot housing markets in Sydney and Melbourne, Karam said it was in this restricted environment that brokers could shine. “In terms of the property space, I think this is the greatest thing that has happened to the broking market for a long, long time,” Karam said. “This is the best opportunity to articulate the value proposition, what a good mortgage broker does. … When lending is quite loose, it’s easy to get the deals done; when it’s
obsessed with numbers, but when the panellists were asked what figures mattered to them most, their answers caught some off guard. Karam said his office rarely discussed loan volume. “We are not giving out the money, so who cares? It’s time versus reward, so that’s why revenue is a really big metric for us. If you’re doing well then you become efficient, and if you’re efficient then you’re delivering really good service. If you’re delivering really good service then you’re getting paid and [getting] additional referrals.” Algie said that while volumes were a way of gauging the success of a business, they weren’t everything. “If you focus on the number and not the process or the people, the numbers won’t come anyway.” AB
VALUE OF PAYMENTS TO REFERRERS FOR HOME LOAN SALES Source: ASIC’s March 2017 Review of Mortgage Broker Remuneration
Professional services business – direct Professional services business – through referrer aggregator Non-professional services business – direct Property developers Other
2012
Clubs, schools and other NPOs – direct
2015
Non-professional services business – through referrer aggregator Clubs, schools and other NPOs – through referrer aggregator $0m
$5m
$10m
$15m
$20m
$25m
$30m
$35m
OPINION
NEW TECH, NEW POWERS Prescriptive analytics can spot issues, identify trends and predict future outcomes, helping brokers – and regulators – do their jobs better, writes Veriluma CEO Elizabeth Whitelock their client relationships. By reducing the incidence of cognitive bias, prescriptive analytics can act as a powerful tool to build trust, giving borrowers the confidence that their broker is truly acting in their best interests. Cognitive bias is an error in
analytics is having a significant impact on the way many industries now operate, and technology research firm Gartner identifies the emerging technology as one of the key areas to watch over the next five to 10 years. It is increasingly useful for its ability to spot new trends or potential issues based on data, facts and opinions to determine the probable outcome of a future event. It can go even further by suggesting, or prescribing, the best course of action to take in order to achieve the most desirable outcome. While prescriptive analytics may sound like the stuff of science fiction, it is already demonstrating its usefulness in numerous industries, from defence to legal services. Now, it’s even being applied to the mortgage and financial services industries, in which it can operate behind an aggregator’s CRM system to reduce broker or adviser bias and error, and suggest suitable mortgage and loan products that have the highest likelihood of approval. But with all these added benefits for brokers, there are also perks on the other side of the fence for regulators. The technology could be used to improve regulators’ oversight, helping identify whether any of Australia’s 23,000 brokers have conducted any illegal activity. PRESCRIPTIVE
Improving trust in advisers Prescriptive analytics is not intended to replace the experience and expertise of brokers and advisers. Rather, it is designed to work alongside them to reduce the time spent sifting through loan products, as well as the possibility of human error, in order to achieve the best possible outcome for the borrower and help brokers grow
Connecting the dots In 2015, a law firm was able to use machine learning to identify a link between spikes in the profit and loss statements of three major UK investment banks and a regular poker night attended by the heads of trading of those banks, who were later found to have colluded on trades. This is a great example of technology empowering businesses and regulators, but it was ultimately reactive – the illegal activity had to have happened before it could be tracked down. However, we know collusion is a recognised risk in this industry, so how can companies prevent it, not just detect it once it has occurred? The beauty of prescriptive analytics is its ability to predict outcomes ahead of time, rather than waiting until after an event has happened to trawl through data and connect the dots. The technology allows regulators and organisations to monitor financial advisers in order to understand what incidences of wrongdoing might look
Increased trust in advisers will lead to increased volumes and growth of the bottom line for the industry
Elizabeth Whitelock CEO of Veriluma, a prescriptive analytics software provider
reasoning, evaluating or remembering, which can lead advisers to mistakenly recommend a product based on their preferences and beliefs, regardless of objective information to the contrary. Even the most experienced and well-intentioned financial advisers can be subject to biases in their decision-making and advice. A peer-reviewed German study from 2010 revealed that cognitive factors do in fact impact on decision-making within the financial market after it found that stockbrokers were guided more by past experience and existing beliefs than logic and rational thinking. Brokers often may not realise they are exhibiting cognitive bias, and may recommend a particular product based on the success of previous loan applications with other clients. Prescriptive analytics can identify bias in its early stages before it becomes entrenched in the way a broker operates. By providing additional checks and balances to confirm product recommendations, the technology gives brokers the peace of mind that there won’t be any inference of bias, error or wrongdoing.
like, enabling them to proactively regulate advisers by connecting seemingly unrelated events to links in behaviours and illegal activity. Prescriptive analytics tests hypotheses and evidence ahead of illegal activity taking place. The lesson here is that we shouldn’t be waiting for data to tell us what’s already happened; instead we need to look to the future to predict what will happen next. Prescriptive analytics can be mobilised to analyse a variety of scenarios, from regulators detecting illegal behaviour by traders, to identifying the most likely loan product for approval, to even identifying fraudulent applications from borrowers. The use of prescriptive analytics is predicted to grow in the financial services sector, and it will serve as a useful tool to improve regulatory oversight and ensure the reputation of advisers and brokers is continually enhanced. Increased trust in advisers will lead to increased volumes and growth of the bottom line for the industry as a whole, resulting in better advice for customers and increased customer confidence. AB www.brokernews.com.au
21
GROW YOUR BUSINESS AND INCREASE YOUR REVENUE Gain insights from industry award winners and take your business to the next level in 2017
2016
2016
AUSTRALIAN MORTGAGE AWARDS
6
AUSTRALIAN MORTGAGE AWARDS
UT O D L O Sydney • 3 May S
Melbourne • 24 May
SEE YOU IN MELBOURNE!
Register now at hpbsummit.mpamagazine.com.au Event partner
Gold sponsors
22
www.brokernews.com.au
Exhibitor
Official publication
Organised by
PEOPLE
Have an interesting deal? Had a particularly difficult or interesting deal? Why not share it with us? Email:
Otiena.Ellwand@keymedia.com.au
A BIG DEAL
Peter Morgante, director of finance at LKFS Financial, helped restore two disillusioned borrowers’ faith in the broker channel by doing his research and going the extra mile to secure them a loan
Location: Gawler, South Australia
THE FACTS
Loan size $312,912
Loan term 30 years
settle this transaction based on successful cases I’d completed previously. Knowing there are a few lenders who would accept this transaction, I reviewed eight lenders’ credit policies and highlighted the minimum requirements needed to be eligible for a home loan application with them. I presented this information to the clients at our appointment. Even if I’ve used a lender before for the same type of scenario, I still go back and double check the policies to make sure nothing has changed. In addition, I also call the broker assist line to confirm so I have all the information I need for my clients. The decision was made to go with CBA because of the competitive rate, the features and flexibility of the loan, and the clients already banked with CBA and so were familiar and comfortable with its service. I advised the clients that all applications are subject to credit approval; however, based on their circumstances, they met this lender’s policy. Based on this information, they were happy to proceed with an application. THE TAKEAWAY
Client Young couple
would be easier than securing a home and land package. After the meeting with that broker, they were despondent. They put the process on hold for eight months until they were referred to me by an existing client who I had helped through the exact same situation.
THE SCENARIO
I have completed many challenging, complex and memorable deals in my three years as a mortgage broker, but the one that stands out the most is a recent one I settled for a young couple. In early 2016, the couple went to another broker to complete a home and land package. The applicants, a man and a woman, are casual/permanent part-time employees in their respective jobs, working 30 to 38 hours per week. They’ve been in those positions for more than 12 months. They saved the minimum 5% deposit over that 12-month period to complete a home and land package and were keen to commence the process. When they approached that broker, he told them he couldn’t assist them because no lenders would accept casual employees and they didn’t have enough money for a deposit. He advised them that they needed to have full-time employment and should look at buying an established home instead because it
Goal Build first home
The clients ultimately got their desired outcome: being able to build/buy their first home. In addition, it gave them hope knowing if one door closes another can open; you just need to ask the right questions. It may take a bit longer to get your desired outcome, but it doesn’t hurt to get a second opinion. From this experience, I learned how to use my previous experiences to my advantage, and I learned not to assume lenders can or can’t assist certain clients based on their circumstances. Brokers should always call the broker assist line and read the lenders’ credit policy to make sure they can still assist their clients, especially those deals that are more complex. I also realised that some brokers aren’t willing to go the extra mile. I get great enjoyment out of
I get great enjoyment out of helping people achieve their dreams and their goals. I feel proud when clients come to me when they feel something can’t be done THE SOLUTION
Peter Morgante director of finance at LKFS Financial, St Peters
I initially spoke to the woman applicant over the phone to arrange a time to meet. The first thing she said was: “Please don’t promise something if we can’t do it now.” I told her that there was no guarantee, but I was quietly confident that we could
helping people achieve their dreams and their goals. I feel proud when clients come to me when they feel something can’t be done. It reaffirms to me, as a broker and as an individual, that with a bit of research, planning and the proper execution, things can happen. In this circumstance, we were able to assist them straight away. AB www.brokernews.com.au
23
PEOPLE
Get involved in the discussion Share your thoughts at
brokernews.com.au
FROM THE FORUM
Top comments from trending stories on brokernews.com.au
BROKER ASSOCIATIONS DISAPPOINTED WITH SEDGWICK REVIEW
VOLUME HURDLES ‘COMPLETELY WRONG’, SAYS FBAA
Australia’s two national mortgage broking associations have expressed their concerns around some of the Sedgwick review’s recommendations to alter broker remuneration. The final report released on 19 April made 21 recommendations, three of which directly involve the third party channel. The MFAA said the observations and recommendations made around the broker channel did not present realistic solutions. The FBAA said the review admitted there was nothing systemically wrong, but it still made three recommendations to change broker remuneration.
Lender-imposed conditions that brokers should write a certain number of loans per month or year to retain accreditation need to go, said Peter White, executive director of the FBAA. White told a Senate Standing Committee on Economics on 26 April that these restrictions – called minimum volume hurdles – were reducing a broker’s ability to write loans for whatever lender they desired. “What that creates is a very bad consumer outcome because a broker can only give guidance on loans for lenders that they’re accredited to,” he said.
I don’t see that anyone should be surprised with the report. It was commissioned by the banks, so it was always going to give the banks the opportunity to screw brokers. The banks state that we are their partners, however I feel we are like the toothache that they have to tolerate, and they would be happy to get rid of us, or as a minimum reduce our profitability. I am also concerned about aggregators being owned by banks. I have been told that our aggregator will be looking after the brokers’ interests in this matter and not putting the banks’ interests first. I am not so certain that this will happen. We need to put all bank owned aggregators on notice, that if this occurs, we will be looking for non-bank owned aggregators. If we moved, it would result in lower profits for bank owned aggregators. This is not a game – it is our livelihood.
I don’t have an issue with broker elite clubs getting priority service. As a lending advisor, the time it takes to get approval is part of the decision making process. However, priority service shouldn’t be based on dollars or number of deals submitted. I believe it should be based on the quality of the applications submitted. If a broker is continually sending in applications that are entered correctly into the software, with quality notes and comprehensive and clear supporting document files that are indexed correctly with upfront valuations completed, they should receive priority processing.
John Whitten on 21/04/17 at 9:03 AM
If you write larger loans you would know that they are (mostly) much more work. Some of what is implied is the belief that brokers “sell” people larger loans than they need, which is just ridiculous. The loan is a by-product of the decision to purchase. You don’t upsell the debt! And if you do, the banks should claw back undrawn funds after a set period. That’s fine, though payments should still be linked to loan size, otherwise who would want to write complicated self-employed (larger) deals? As [FBAA executive director] Peter White said, whoever wrote this clearly does not understand lending. Barney on 21/04/17 at 09:37 AM
As a member of 15 years with a now bank owned aggregator, I am extremely concerned about my future. Unfortunately, if I change aggregators, I lose my trail, so changing is not a real option. I haven’t heard a squeak from my aggregator and very much doubt if I will. More chance of Wayne Bennet demanding that the referee send one of his players to the sin bin!! Sam on 21/04/17 at 09:55 AM
24
www.brokernews.com.au
David on 28/04/17 at 11:39 AM
Yeah, but they currently can’t process anything but the simplest applications without error, so what is the chance they incorporate this fairly? Zero. Also how does the lender judge your quality of submission if you’ve only sent one deal to them in the last few years? Most active brokers are doing what three or four loans a month, so I don’t know what the answer is here, but what I do know is that if I need an approval quickly, being Diamond or Platinum or whatever, is a really good outcome for my client. Marty McDonald on 28/04/17 at 03:04 PM
Bravo FBAA and about time!! It is so obvious that minimum volume hurdles create a conflict of interest for a broker that it amazes me that ASIC has not even stumbled upon this, let alone properly considered it. Personally, I simply do not hold accreditation with lenders who impose volume hurdles or charge fees for accreditation or renewal of accreditation and this is set out in my Credit Guide along with an explanation which in effect states that I do not deal with lenders who are in my view as a Credit Licensee “non-compliant” with both the letter and the spirit of the law. Patrick McMenamin on 28/04/17 at 12:56 PM
Well done! How about the claw back clause? Two years is just too long. Tana on 28/04/17 at 11:12 AM
CAUGHT ON CAMERA
MyState presents a $20,000 cheque to Tour de Cure on the Hobart waterfront
MyState CEO and managing director Melos Sulicich participated in his fifth Tour de Cure Signature Tour from 24 March to 1 April, leading a team of three MyState executives and senior managers in this challenging 1,270km cycling event from Hotham to Hobart. The group of 175 riders and support crew raised more than $1.8m for life-saving cancer research, support and prevention projects across Australia. Along the way, they visited regional communities and donated $10,000 each night to local cancer projects across Victoria and Tasmania. The tour also visited local primary schools, presenting Tour de Cure’s Be Fit, Be Healthy, Be Happy program to more than 4,500 children, helping to raise awareness that one in three cancers are preventable by making simple, healthy lifestyle choices.
MyState CEO Melos Sulicich (centre) presents a $10,000 cheque to the Leukaemia Foundation
Tour de Cure’s MyState cycling team, including Melos Sulicich, Paul Moss and Justin Marney, visited staff at its Launceston branch
www.brokernews.com.au
25
DATA
NEW SOUTH WALES
WESTERN AUSTR ALIA SPOTLIGHT
Long-term tenants in western Sydney have been emboldened to become buyers As more tenants opt to buy their own homes in western Sydney, the rental market is suffering, as the resulting vacancies have generated an oversupply of properties for lease. “With rental yields currently at circa 4% in areas such as Wilmott and Blackett, other areas such as Blacktown are experiencing yields as low as 3%. These tight yields are mostly on the back of a soft rental market and as such may deter many investors,” states the Herron Todd White Month in Review report for February 2017. Many investors are turning south to Wollongong, which offers greater bargains than Sydney. “[Our buyers] are mostly from western Sydney, selling for great prices and making a sea change at a still very affordable price,” says Jason Hines of Peter Fitzgerald Real Estate. For Rich Harvey, founder and director of Propertybuyer, Wollongong’s beaches and proximity to the NSW capital are major factors driving its attractiveness. Area
Type Median value
Quarterly
12-month
growth
growth
Sydney
H
$970,000
7.8%
3.4%
NSW Country
H
$435,000
1.9%
6.3%
Sydney
U
$710,000
2.9%
3.8%
NSW Country
U
$363,000
4.5%
3.8%
VICTORIA
Units may be able to generate higher returns on investment than houses Villa units and two-bedroom apartments can go for roughly $500,000 in inner-northern Melbourne, specifically in Brunswick, Northcote and Coburg. Consistently performing suburbs in the inner city include Port Melbourne, St Kilda, South Yarra and Richmond, and established apartments are expected to be particularly popular compared to new, off-the-plan units. However, Herron Todd White says this market could be risky for buyers since oversupply is a real possibility in the near future, given the large number of apartments scheduled for completion. Herron Todd White highlights the innernorthwestern area of Melbourne as being especially sensitive to this problem. West Melbourne, Travancore and Parkville are danger zones, which have seen falling prices. By contrast, properties in the southeastern corridor are recording considerable growth following 2016’s surge. In the outer-eastern ring, the property market has been steady.
Area
Type Median value
Quarterly
12-month
growth
growth
IS PERTH READY TO RECOVER?
Even though prices continue to drop in Western Australia, property experts have high hopes for Perth’s recovery
Western Australia’s property market isn’t expected to start booming any time soon, property prices are finally steady after a continuous drop over the last few years, says Geoff Baldwin, managing director at RE/MAX WA. Baldwin is hopeful the market will continue to strengthen throughout the year and show an increase in prices. There’s been renewed interest from Sydney and Melbourne investors who have cast their gaze towards WA, he says. “It wasn’t that long ago that Perth prices almost caught up to Sydney’s and were on par with Melbourne’s. We are now a long way behind both of those cities; however, in real estate, history has a habit of repeating,” he says. While experts like Baldwin have adopted a positive attitude, others say it’s important to remember that the state is still struggling somewhat to get past the mining downturn. “Western Australia is still coming to terms with the end of the mining boom, and confidence did slip back into negative territory,” says Ken Morrison, chief executive of the Property Council of Australia. But while confidence in Perth remains shaky, the property market is expected to stabilise by the end of the year. For Peter Peard, chief executive of Peard Real Estate, now is the time for buyers to get in on the action. “We keep on saying we are at the bottom, but it feels like we are at rock bottom. WHILE
BROKER PERSPECTIVE
The Perth real estate market has shown a certain lack of confidence over the last year or so The suite of changes in the investment lending space has impacted investors and their ability to add to and grow their portfolios. While APRA’s lending changes reduced people’s capacity to borrow, there is still considerable interest in well-priced, high-quality properties. The lending changes have cooled the overall lending market, particularly in the investment space; however, we understand why these changes were made. Our client base seems to be sitting back to see what the market does. While many are content to rest on their current portfolio, there has been an increase in other enquiries of late. People are looking to take advantage of historically low interest rates by refinancing their existing lending. With owner-occupier interest rates as low as they are, a number of first home buyers are looking to get into the market. The Perth market has seen a fall in prices, so there is good value for buyers just entering and those trading up. Paul Prindiville Finance manager/team leader at Blackburne, West Perth
HIGHEST-YIELD SUBURBS IN WESTERN AUSTRALIA SUBURB
TYPE
MEDIAN PRICE
WEEKLY MEDIAN ADVERTISED RENT
GROSS RENTAL YIELD
Broome
U
$195,000
$349
9%
Melbourne
H
$676,000
9.0%
5.9%
Rangeway
H
$128,000
$220
9%
Vic Country
H
$320,000
1.6%
2.3%
Pegs Creek
H
$235,000
$400
9%
Melbourne
U
$495,000
1.0%
0.0%
Kalgoorlie
U
$175,000
$290
9%
Vic Country
U
$260,000
2.6%
3.7%
Millars Well
H
$250,031
$388
8%
26
www.brokernews.com.au
OPPORTUNITIES AND KEY INFRASTRUCTURE
We are seeing some real bargain buying and the buyers are starting to respond and coming into the home opens,” he says. Factors that could entice first home buyers into the market include the increase in the First Home Owner Grant to $15,000 by the state government, and the waiver of stamp duty on purchases of up to $430,000 for first-time buyers. “There couldn’t be a better time to buy a new apartment or build a new home. Or if
you’re upgrading, then the bargains are there for the picking,” Peard says. Stockland and Mirvac developers also report that price growth is weak to steady in Perth, thus investors should be able to get reasonable returns. However, buyers do still have to be careful, especially when considering larger, more affordable properties outside the city, since regional areas – such as the southwest – continue to struggle. AB
MORTGAGE MARKET ACTIVITY Region
Month-on-month change
Month-on-month change (trend)
National
115.8
-17.9%
8.1%
New South Wales
156.2
-20.0%
10.1%
Queensland
98.9
-21.7%
5.2%
South Australia
75.2
-11.4%
4.3%
Tasmania
85.7
-19.3%
6.8%
Victoria
131.1
-15.2%
9.4%
Western Australia
86.4
-16.4%
6.2%
WA PRICE PERFORMANCE Type
Median value
Quarterly growth
12-month growth
Perth
H
$518,000
0.6%
-3.7%
WA Country
H
$355,500
1.6%
-6.5%
Perth
U
$406,500
-4.1%
-3.0%
WA Country
U
$285,000
9.6%
-8.2%
SUBURB TO WATCH: NORSEMAN Median price (houses) $79,101
Median price (units) n.a.
Riverside A mixed-use development brings hustle and bustle to the riverfront
WA Museum
Perth Stadium
An improved display space will give the state collection a boost
The 60,000-seat venue is a major attraction for international events
QUEENSLAND Index value
Area
Perth City Link Transit hub connects the CBD with Northbridge for the first time in 100 years
Affordability continues to define Brisbane’s property market Areas outside the metro are expected to become more popular with those people who have been priced out of Brisbane city. The property markets in the fringe suburbs have also been remarkably active, with investors looking into house and land packages. Meanwhile, the establishment of facilities and infrastructure in the western corridor approaching Ipswich has brought new life to the region. Areas beyond the metro are also experiencing a resurgence, and Toowoomba is primed for major development. Current projects include the Toowoomba Second Range Crossing and the extension of the Grand Central Shopping Centre. The northern end of the Gold Coast is presently being regarded as a growth corridor, with new estates coming in. It has been supported by recent developments, including the upgrade of Exit 54 and the near-completion of the new Westfield shopping precinct, Coomera Town Centre.
Area
12-month growth
3-year growth
5-year growth
Average rental yield
-36.5%
-17.5%
-15.0%
n.a.
12-month growth
3-year growth
5-year growth
Average rental yield
n.a.
n.a.
n.a.
n.a.
Type Median value
Quarterly
12-month
growth
growth
Brisbane
H
$524,000
2.5%
3.8%
QLD Country
H
$426,000
-0.9%
1.3%
Brisbane
U
$400,000
-3.1%
-1.9%
QLD Country
U
$370,000
0.0%
3.7%
www.brokernews.com.au
27
DATA
NORTHERN TERRITORY
CAPITAL CITY AUCTION CLEARANCE RATES
Quarterly
12-month
growth
growth
Adelaide
H
$440,000
1.1%
3.3%
SA Country
H
$285,000
2.1%
0.2%
Adelaide
U
$352,500
0.1%
2.9%
SA Country
U
$193,750
-4.1%
0.3%
MEDIAN HOUSE AND UNIT PRICES
Canberra’s property market offers a rosy outlook
$1,000,000
Area
Type Median value
Clearance rate
100%
ADELAIDE Reported auctions
74
Sold
47
Not sold
27
Clearance rate
63.5%
PERTH Reported auctions
23
Sold
8
Not sold
15 34.8%
$1,100,000
Quarterly
12-month
growth
growth
Canberra
H
$648,000
4.5%
4.2%
Canberra
U
$425,500
-2.2%
0.7%
www.brokernews.com.au
0
Clearance rate
AUSTRALIAN CAPITAL TERRITORY
Sydney Melbourne Brisbane Adelaide
Perth
Hobart
$500,000
$313,500
$400,000
$0
$417,500
$100,000
$510,000
$200,000
$336,500
$300,000
$440,000
$500,000 $400,000
$547,250
$700,000 $600,000
$690,000
$800,000
$730,000
$900,000
Houses
$972,500
“Canberra has seen value growth lift over the past year, and with the improving economic conditions and a tightly managed supply of new housing, it may actually see an acceleration in value growth throughout 2017,” says Cameron Kusher, research analyst at CoreLogic. Ken Morrison, chief executive of the Property Council of Australia, adds that the ACT is one of two states in which he does not “see industry concerns about the state government performance, in terms of planning and managing growth”. Indeed, infrastructure projects are currently underway that will add to Canberra’s appeal, according to Herron Todd White’s Month in Review for February 2017. The construction of a light rail system will add another public transport method that connects metro suburbs such as North Canberra to the CBD, adding value to these areas. Undersupply is another factor contributing to soaring prices in the ACT, although this may be alleviated soon by the recent boost in housing approvals.
28
Capital city auction clearance rates rebounded during the week of April 16–23 from 69% the previous week to 74%. The auction clearance rate that week was recorded across 2,350 auctions. Melbourne and Sydney’s auction clearance rates both rose slightly from the week before. In Melbourne, the auction clearance rate was 78% across 1,226 auctions, while in Sydney it was recorded at 74% from 811 auctions. While Sydney’s clearance rates saw a slight increase, they remain lower than they were over the Easter long weekend and have nudged lower through April than they were in February and March. Meanwhile, Canberra and Tasmania were the only major markets tracked in which clearance rates fell.
$366,250
Type Median value
Not sold
WEEK ENDING 23 APRIL 2017
$519,500
Area
1
Darwin
Units
$395,000
Improvements to infrastructure are adding an attractive air to well-located suburbs in this city, with projects like the Torrens to Torrens Road Project and the O-Bahn tunnel helping the local economy by providing jobs and increasing accessibility. The Darlington Upgrade Project will also improve access to Adelaide via the Southern Expressway. In the Month in Review report for February 2017, Herron Todd White highlights Christies Beach and Seaford as affordable options for buyers. These suburbs are near Port Noarlunga, and are now more accessible due to the electrification of the Seaford railway line. “There are increasingly improved facilities in these areas, due to the increasing development – both infill and in the Seaford Meadows South development,” the report says. With supply levels staying low, suburbs in prime locations maintain an air of desirability, such as those within 10km of the city, at the fringe of the metro, and near the beach.
Sold
$612,500
Adelaide looks set to maintain its moderate growth trend
1
$410,000
SOUTH AUSTRALIA
Reported auctions
Canberra
CAPITAL CITY HOME VALUE CHANGES CAPITAL CITY Sydney
WEEKLY CHANGE
MONTHLY CHANGE YEAR-TO-DATE CHANGE
12-MONTH CHANGE
-0.3%
-1.0%
4.6%
13.6%
Melbourne
0.3%
0.5%
5.1%
14.7%
Brisbane
0.5%
1.0%
1.7%
3.7%
Adelaide
-0.3%
0.5%
2.1%
1.6%
Perth
-0.1%
0.2%
-2.3%
-4.8%
0.0%
-0.1%
3.7%
10.2%
COMBINED 5 CAPITALS
*Brisbane results are for the combined Brisbane and Gold Coast region. The monthly change is the change over the past 28 days.
BRISBANE CANBERRA Reported auctions
60
Sold
41
Not sold
19
Clearance rate
Reported auctions
102
Sold
54
Not Sold
48
Clearance rate
52.9%
68.3%
SYDNEY Reported auctions
723
Sold
537
Not sold
186
Clearance rate
74.3%
TASMANIA
MELBOURNE Reported auctions
1,159
Reported auctions
10
Sold
905
Sold
6
Not sold
254
Not sold
4
Clearance rate
Clearance rate
78.1%
TASMANIA
Hobart’s excellent performance is due in large part to the city’s thriving commercial scene “Property and construction is driving a boom period in Hobart’s economy,” says Brian Wightman, Tasmanian executive director of the Property Council of Australia. “Increased demand for office space is a welcome sign and presents further opportunity to embark on reforms which will deliver a generation of continuous economic growth.” The tourism industry is a cornerstone not just of the economy but of the property market, according to Herron Todd White in its February 2017 Month in Review report. The effectiveness of this sector has increased investor activity.
Area
60.0%
Type
Median value
Quarterly growth
12-month growth
Hobart
H
$390,000
5.4%
4.5%
TAS Country
H
$269,000
5.5%
0.0%
Hobart
U
$295,000
3.5%
3.0%
TAS Country
U
$226,000
2.7%
-2.9%
Source: All data sourced from CoreLogic.com.au
www.brokernews.com.au
29
PEOPLE
IN THE HOT SEAT Leaving stockbroking in 2012 was the best thing to happen to Broker Intelligence owner and director Adrian Willenberg, who can now be found settling deals and chasing Pokémon with his son Who or what inspired you to become a broker? I wanted to be my own boss and have flexibility. At that time, A my son Alex was only 12 months old. I didn’t want to work in the corporate world again; slaving away for someone else all day was not appealing. I was always good with numbers and dealing with people, and the thought of earning an ongoing trail commission was too good to pass up. I spoke to various mentors and decided to join Masters Broker Group. This is the best job in the world. I can’t think of anything I’d rather do – except perhaps be a scuba-diving instructor.
Q
Where did you start your career in finance? I started working in stockbroking in 1993, predominantly as a A principal trader. I was paid to trade the stock market on a daily basis, buying and selling shares all day. It was a great job with a nice salary and huge bonuses, but the global financial crisis hit around 2008 and the computerised trading system took over, wiping out us humans. Plenty of good people left the industry, and I was made redundant in 2012. In hindsight, this was the best thing to ever happen to me. I started my business in 2012 and I haven’t looked back.
Q
What makes broking an exciting, interesting or challenging job? Why do you keep doing it? Like every job, broking has its ups and downs. The real thrill is A helping clients achieve their financial goals, whether that’s buying their first home or investing in their 10th property. And I’ve got the best flexibility. I’m one of the few dads at school drop-off and pick-up, and I often stop work at 3.30pm to kick the footy with my son, go for a bike ride or hunt some Pokémon, then it’s back to work once he’s in bed.
Q
What hobby or activity do you enjoy doing most during your spare time? My boy Alex is the centre of my world, and I love spending time A with him. He’s heavily involved in Auskick and Little Athletics, and I do some coaching too. I enjoy going to footy and tennis, and I’m a keen scuba diver too. I love being underwater.
Q
What have you dreamed of doing but haven’t had a chance yet to do? I’ve travelled to South America, which was just amazing, and I’ve A also been to Bali and Fiji a few times. I’ve never been to Europe though; I’ve always wanted to go. I’d like to see London and Scotland, so hopefully that’s on the hit list sooner rather than later. AB
Q
30
www.brokernews.com.au
NOMINATIONS OPEN 29 MAY
Friday 27 October • The Star Sydney www.australianmortgageawards.com.au Event Partner
Award sponsors
Official publications
Organised by
www.brokernews.com.au
31
32
www.brokernews.com.au