ISSUE 109 I HSE & TRAINING
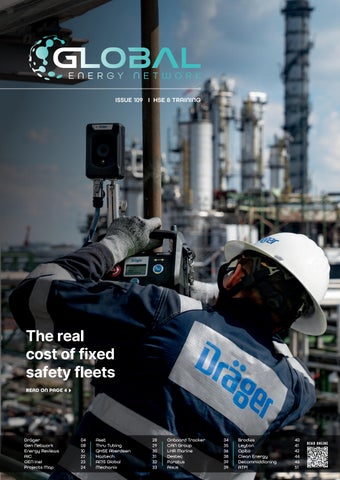
The real cost of fixed safety fleets READ ON PAGE 4 }
Dräger Gen Network Energy Reviews AIC GEN Inel Projects Map
04 08 10 22 23 24
Aset Thru Tubing QHSE Aberdeen Haztech AMS Global Mechanix
28 29 30 31 32 33
Onboard Tracker CAN Group LHR Marine Destec Paratus Aisus
34 35 36 38 39 39
Brodies Leyton Opito Clean Energy Decommiddioning ATPI
40 41 42 44 46 51
READ ONLINE
CONTENTS
Contents
ISSUE 109 Health & Safety
08
04
26
Health & Safety Skills & Training
The Network
10
Aset............................ 28 Thru-Tubing.............. 29 QHSE Aberdeen.......30 Haztech .................... 31 AMS Global................32 Mechanix................... 33 Onboard Tracker......34 CAN Group................ 35 LHR Marine................36 Destec ....................... 38 Paratus....................... 39 Aisus.......................... 39
Energy Reviews
24
GENI Intel Project Tracker
40
The real cost of fixed safety fleets
41
Brodies
Leyton
43
44
46
48
50
Appointments
Clean Energy
Decommissioning
Contracts
ATPI
Skills & Training
Welcome to the October issue of GEN magazine. Health, safety, skills and training remain fundamental to the success of the global energy industry. As operations become increasingly complex and working environments continue to evolve, having the right people, expertise and safety systems in place is essential to maintaining safe, efficient and resilient operations.
November International Growth
With this issue being distributed at AEW alongside the GEN team, we explore the people, technologies, training and expertise supporting HSE across the global energy sector, from developing the skills of the workforce to ensuring safety-critical equipment is ready when it is needed.
Issue
We are delighted to welcome Dräger as our cover partner. Their article, The Real Cost of Fixed Safety Fleets, looks beyond the initial investment in safety equipment to examine the wider costs of ownership, including maintenance, calibration, compliance, storage and the challenges of scaling provision during turnarounds, up-manning and unexpected events.
Be Part of
The Next GEN of Media
it!
Contact hello@globalenergynetwork.net
This issue also features contributions from AIC, ASET, Thru -Tubing, QHSE Aberdeen, Haztech, AMS Global, Mechanix, Onboard Tracker, CAN Group, LHR Marine, DESTEC, Paratus, AISUS, Brodies, Leyton, OPITO and ATPI, alongside the latest news, energy reviews and project intelligence from across the GEN Network. As always, our sincere thanks go to all our partners and contributors for their continued support. We hope you enjoy this issue and the insight it brings from across our industry.
READ ONLINE www.globalenergynetwork.net/magazine
3
4
Cover Feature
The real cost of fixed safety fleets
The energy sector has invested substantially in culture, training and process over the past two decades, and the results show. What is harder to keep pace with is the operating environment those commitments now sit inside, because it has changed considerably.
Turnarounds are shorter and more intense than a decade ago, with more work compressed into smaller windows, leaner teams, ageing assets and far less tolerance for delay. What ownership doesn’t show you When a business signs off on a fleet of gas monitors or breathing apparatus, the invoice is only the first number that matters. What happens over the following five, six, seven years, the maintenance, the calibration, the people needed to manage it all, is where the real cost sits, and it is rarely the number anyone budgets against. One offshore firefighting training facility, running breathing apparatus sets daily to train operatives bound for the North Sea, tried to squeeze extra life out of its kit past the standard service interval rather than retire sets on schedule. It is a natural instinct, the kit still looks fine, but it almost always backfires, costing more in breakdowns and downtime than a timely replacement would have done. Maintenance is the part organisations underestimate most. Refineries running mixed fleets from several manufacturers are often unable to say with confidence how many hours their own people spend on calibration, servicing and asset tracking, only that the number is high. The true resourcing cost of in-house ownership rarely gets tallied up; it sits scattered across technicians, storerooms and spreadsheets rather than on a single line finance can see.
globalenergynetwork.net I October 2026
When the calculation changes
The cost of standing kit
Ownership is not the wrong answer everywhere. For day-to-day activity and planned work with a known hazard profile, a well-maintained owned fleet earns its keep, and demand that is predictable and consistent is exactly where the case for ownership is strongest.
Equipment left dormant between shutdowns ages in storage, with sensors drifting and service schedules slipping. When a turnaround arrives months later, reactivation costs can equal or exceed what a managed arrangement would have cost from the outset. There are known cases of kit needing calibration overseas, with a six-week turnaround landing just three weeks before a job was due to start.
Where the calculation changes is at the margins, and in this sector the margins matter considerably. Turnarounds compress large volumes of work into short windows, and up-manning events bring sudden spikes in headcount that a standard fleet was never sized to cover. Unplanned incidents, unexpected HSE requirements, or a confined space scope that reveals a different hazard profile than anticipated are the moments that test whether a safety programme is genuinely flexible, or just adequate under normal conditions. Regulation adds its own layer of unpredictability. Bump testing, the daily check confirming a gas detector’s sensor path is working, was a grey area twenty years ago, and some sites are still catching up on regimes built with little manufacturer guidance at the time. More recently, the IMO’s MSC 581.110 regulation on CO2 detection in enclosed vessel spaces caught operators out the same way. Some were already ahead of it, though many were not, and that gap, between knowing about a requirement and meeting it, is where a fixed, owned fleet struggles to respond in time.
Ownership creates its sharpest strain during the turnaround itself, when kit has to move fast across a site with dozens of contractors on the books. If equipment goes missing, and on a big turnaround it usually does, someone has to track it down, work out who had it, and absorb the cost.
Built for scale, not just stock Scalability in this sector is rarely theoretical. A turnaround for one client might need 50 gas detectors for one phase and 300 for the next, or an incident on an offshore platform might mean 200 workers requiring protection within hours. An HSE visit that identifies a compliance gap demands a solution before the shift ends, not in a fortnight. Demand will fluctuate. What matters is whether safety provision is structured to respond when it does.
What a managed model changes A managed rental model approaches this differently. Working directly with the manufacturer means sales, hire, operations and project management teams work together from the planning stage, so equipment arrives pre-configured, calibrated, compliant and ready for
Cover Feature Confidence, not just convenience Flexibility and scale matter, but they are not sufficient alone. The question worth asking is simple: if you were putting the equipment on yourself, would you be confident in it? Most people send their car to an approved garage rather than the cheapest option, because the stakes are too high to cut corners on something they depend on. The same logic applies here: confidence means equipment serviced, calibrated correctly, and returned to a verified state of readiness, and for operators who take safety seriously, that standard is not one to negotiate on.
Where this is heading Fixed gas detection, portable monitors and breathing apparatus currently feed into separate systems, leaving safety managers working across multiple dashboards. The direction of travel is towards a single, real-time view of an entire fleet across assets and vessels at once, extending managed provision well beyond availability into continuous insight on the condition, location and usage history of every asset. If a business is reviewing its safety strategy today, it needs to look beyond just owning or renting and closer at the costing of the alternative: the hours spent managing a fleet, the risk of falling behind on compliance, the equipment sitting idle, and the exposure when something breaks with no contingency in place. The organisations best placed to manage a leaner operating environment are those treating safety procurement not as a one-off capital decision, but as an ongoing commitment that is backed by a partner with the inventory to scale, the expertise to advise, and the systems to deliver.
deployment. Buffer stock is built in as standard, so a fleet undergoing maintenance can be swapped out without losing uptime, and tracking and recharging for lost or damaged kit is handled as part of the service rather than left to the site to chase. That coordination also removes a layer of manual cost. Dräger’s Rental Robot X-Care, launching later this year, bump tests kit automatically the moment it returns to the docking station, removing the need for a technician to do it by hand. Utilisation is tracked at unit level too, with pay-for-use structures reflecting actual demand rather than the overhead of a fixed fleet sitting largely idle between shutdowns. The data this generates, patterns in damage, breakage and use across multiple jobs, surfaces training gaps and site procedures no static fleet audit would reveal.
The market backdrop Wood Mackenzie expects UK North Sea upstream investment to fall this year to its lowest real-terms level since the 1970s, part of a widening gap between UK and Norwegian spending as operators pull back on capital commitments. That makes CapEx sign-off for a large purchase harder to secure, and rental, with its fixed monthly cost and no upfront outlay, correspondingly more attractive. The same shift from equipment ownership to equipment access is starting to play out well beyond oil and gas, across power generation, energy-from-waste and other sectors where safety-critical kit sits idle for long stretches between projects.
5
Monitored Zero-Energy Zone
Dual Leak-Tight Seals Double Block & Bleed Isolation Isolated Pipeline
The BISEP® has an extensive track record and provides pioneering double block and bleed isolation while maintaining pipeline flow. Fail-safe hydraulically activated dual seals provide tested, proven and fully monitored leak-tight isolation, every time, any pressure.
size range:
3” - 56”
max pressure:
153bar / 2220psi
type approved
Contributions Design
newsdesk@globalenergynetwork.net
Jennifer McAdam jen.mcadam@globalenergynetwork.net
Advertising Editorial
hello@globalenergynetwork.net Tsvetana Paraskova
FEATURING
Highest-impact, safety-critical training
PARTNERS
World-class safety-critical training and learning solutions for people and workforces in oil & gas, wind, power, and beyond. Globally recognised, locally delivered across the UK, the Americas, and the Middle East.
Training Services Simulation & Technology Workforce Development Managed Services
TRAVEL MANAGEMENT PARTNER The ATPI Group delivers world-leading corporate travel and events solutions to organisations operating in a variety of specialist sectors around the world.
LOGISTICS PARTNER Leading provider of logistics services to this industry, offering its customers airfreight, road freight, sea freight, project forwarding, customs compliance, training and consultancy, packing, crating, lashing & securing services warehousing, distribution, freight management, rig relocation and mobilisation services and offshore logistics. Disclaimer: The views and opinions published within editorials and advertisements in this publication are not those of our editor or company. Whilst we have made every effort to ensure the legitimacy of the content, GEN cannot accept any responsibility for errors and mistakes.
WANT TO BE PART OF IT? VIEW our media pack at
globalenergynetwork.net or scan the QR code
3tglobal.com
Spotlight on THE This month's 'New Members' spotlight:
Our expert course designers create highly customized training materials tailored to your industry’s specific needs. We use various delivery methods, including e-Learning, classroom training, and practical hands-on sessions, both on-site and at our training facilities our courses cover a wide range of topics.
We are the leading provider of Hydraulic Workover-, Snubbing-, Wireline-, P&Aand Well Control Services with more than 950 wells restored and 26 years of experience. Balance Point Control has a long-term team of highly competent professionals. From the management who interact with our clients, through to their extensive and qualified PM team.
www.blueoceandecom.com
www.safer-training.com
www.bpc.nl
In today’s world things have never moved faster.
A privately owned Australian based Demolition, Dismantling, Remediation and Recycling Contractor with Australia wide capability specialising in Industrial, Oil, Gas and Power Generation sectors.
Blue Ocean Decom delivers agile, engineeringled decommissioning and asset removal solutions for the offshore energy sector. Built on more than 20 years of decommissioning experience, we combine proven field expertise with innovative engineering to safely and efficiently execute some of the world's most complex offshore projects.
T12 remain current to meet the challenges of this ever-changing world. We collaborate with clients across multiple industries delivering powerful and effective solutions. By working together, we can meet the engineering and technical demands, the worlds biggest challenges have to offer, securing the future for new generations.
The family Owners and Directors of Ausdecom have over 100 years of experience in the demolition of heavy x industrial facilities Australia wide.
www.t12engineering.com
www.ausdecom.com.au
Wellvector The Data Mining Engine For Unstructured Well Data Wellmine turns a raw well archive into an auditable, engineer-verified well – exportable x to Excel
www.wellvector.ai
This month's 'Renewed Membership' spotlight:
DNV is the independent expert in risk management and assurance, operating in more than 100 countries. Through its broad experience and deep expertise
At WellSense, we’re on a mission to extend the life of oil and gas fields, maximize well performance, and ensure effective well abandonment through innovative, practical solutions.
and inspires and invents solutions.
We’re an experienced team of engineers, innovators, and problem-solvers. Above all, we’re collaborators – working with customers worldwide to optimize well development, integrity, production, and abandonment operations.
www.dnv.co.uk
www.well-sense.co.uk
DNV advances safety and sustainable performance, sets industry benchmarks,
Join The Network today! Contact: hello@globalenergynetwork.net
Wellcem is an oil service company headquartered in Norway with branches located around the world. Wellcem’s vision is to be a leading provider of technology for Plugging, Lost Circulation, Leak Stop, and Sand Consolidation in Oil and Gas Wells.
www.wellcem.com
The Next GEN of Media www.globalenergynetwork.net
The Network News
NETWORK news FIND ALL THE FULL NETWORK NEWS ARTICLES @ globalenergynetwork.net
ADC Continues to Support Offshore Ghana
THREE60 Energy Reports Strong Growth and Increased Profitability in 2025
CRC Evans Opens One of the World’s Largest Integrated Specialty Welding and Protective Coating Facilities
THREE60 Energy, a global lifecycle solutions company delivering engineering, operations and systems across the oil and gas, decommissioning, new energy and defence & industrial sectors, has announced another strong financial performance for the year ending 31 December 2025.
CRC Evans, a global leader in specialty welding and protective coating solutions for energy and critical industries infrastructure, has officially opened one of the world’s largest end-to-end coating facilities, doubling the size of its operation in Burnley, UK.
Once the rig has been selected, ADC will conduct a comprehensive condition and acceptance audit to provide operational assurance and minimise the risk to performance.
The Group grew revenue to £189.4 million, while delivering significant improvements in profitability. Adjusted EBITDA increased by 30% year-on-year to £14.7 million, with operating profit rising by 35%, reflecting continued growth across the business and the benefits of THREE60’s increasingly diversified and integrated service offering.
The new 90,000 sq. ft Burnley Centre of Excellence, Pioneer House, represents a major investment in CRC Evans’ global growth and diversification ambitions, responding to growing demand for the company’s technical expertise across established and emerging energy and critical infrastructure markets.
Haztech Solutions welcome Tayla Le Quesne and Nick Conti as Operations Coordinators
DeepOcean and TFKable Group to develop integrated inter-array cable offering with cable-laying vessel
Three months ago Haztech Solutions welcomed Tayla Le Quesne and Nick Conti as Operations Coordinators.
DeepOcean and the controlling entity of TFKable Group, comprising Tele-Fonika Kable, JDR Cable Systems and their affiliated and associated entities, have agreed to establish a joint venture focused on integrated engineering, procurement, construction and installation (EPCI) services for inter-array cable projects in the offshore wind sector.
ADC has been active in Ghana for over a decade and are set to return to the country to support both National and International Operator clients. The first project is a continuation of an existing contract that has seen ADC support the Operator with a technical comparison of a shortlist of potential drilling units, risk assessed and ranked based on the technical capability to meet the project demands of the operating environment.
An electrician by trade, Nick brings a practical understanding of what a job requires in the field. Tayla’s background in logistics and operations brings the planning and systems discipline alongside it. Together they coordinate Haztech’s EEHA, E&I and secondment work, from initial enquiry through to close-out. To find out more about Haztech’s capabilities, or for assistance scoping an upcoming package of work visit www.haztechsolutions.com.au
The Next GEN of Media
A newbuild, dedicated inter-array cable laying vessel is also planned to become part of the joint venture’s offering. The planned collaboration will combine TFKable Group’s subsea cable technology and manufacturing capabilities with DeepOcean’s expertise in offshore engineering, installation and seabed intervention.
Partnership set to unlock international growth for subsea controls specialist Leading subsea controls specialist J+S Subsea Limited has stepped up its plans to grow in a key international market by forming a new partnership. The Aberdeen-based company has teamed up with Perth, WA-based Pulse Technology Hub to create a united platform for growth across Australia and the wider APAC region. The venture will enable J+S Subsea Limited to access Pulse’s local knowledge, experienced team, and in-country facilities, preceded by six months of collaborative strategic market research to maximise regional growth potential. It is expected that the relationship will spark the creation of an unspecified number of jobs at J+S Subsea Limited, both in the UK and in Australia, as the alliance gathers pace.
Feature your company news in the next issue of Global Energy Network Magazine in print and online - Join The Network today! Contact: hello@globalenergynetwork.net
9
10
UK
Energy Review The future of the fiscal regime for the UK North Sea and major new oil and gas projects pending final government approval featured in the oil and gas industry in the UK Continental Shelf in recent weeks, alongside many project development and decommissioning contracts. In early September, Offshore Energies UK (OEUK) wrote to the Chancellor John Healey asking for urgent talks ahead of October’s Budget to re-affirm the Government’s commitment to a new tax regime for North Sea oil and gas production. Geopolitical volatility is affecting energy security and eroding investor confidence in the North Sea. OEUK argues that bringing forward the Oil and Gas Revenue Levy (OGRL) from 2030 to early 2027 would be a “win-win” for Britain, offering additional government funds that could be used to address the cost of living crisis. OEUK has calculated the new tax would unlock £50 billion worth of investment supporting jobs and providing a major boost to the economy. By investing more the energy sector pays more tax not less, the trade body said. OEUK’s renewed call for reform comes six months after the previous Chancellor, Rachel Reeves, told energy companies that the government supported in principle the end to the Energy Profits Levy and the introduction of a new windfall mechanism. The Oil and Gas Revenue Levy – the Treasury’s permanent successor tax to the Energy Profits Levy – proposes a 35 percent levy on revenues when the price of a barrel of oil is above $90 and a therm of gas is above 90p, in addition to the ring fenced corporation tax rate of 30 percent and the supplementary charge of 10 percent. “The future of the sector and Britain’s ability to continue domestic oil and gas production depend on a fiscal landscape that encourages investment,” OEUK Chief Executive David Whitehouse said. In the letter to the Chancellor, Whitehouse wrote “The case for acting quickly is compelling. North Sea oil and gas production is down 7.2 per cent and 8.5 per cent respectively year-on-year, according to the latest government figures.”
By Tsvetana Paraskova
According to OEUK, a stable fiscal regime and regulatory support for North Sea developments, including for the Rosebank and Jackdaw projects, would also boost British and European energy security, at a
time of ongoing geopolitical turmoil in the Middle East. “Investment in the UK offshore energy sector can help support your government’s reindustrialisation aspirations, sustain good energy and manufacturing jobs, and boost supply chain firms in communities across the country,” Whitehouse noted. The 2026 Energy Safety Awards ceremony, jointly hosted by Offshore Energies UK and Step Change in Safety at P&J Live in Aberdeen, recognised inspiring individuals, teams, and companies from across the energy sector. DNV Spadeadam Research & Development, DNV, was recognised for major hazard awareness, TAQA UK was awarded for workforce engagement, Ithaca Energy for sharing and learning, and IKM Testing UK was recognised for decommissioning safety. Separately, the finalists for the 2026 OEUK Awards have been revealed, recognising the people and companies helping to deliver secure, homegrown energy for the UK. Winners will be announced at a gala awards ceremony on 19 November at P&J Live in Aberdeen. Finalists for the Excellence in Decommissioning award have also been chosen, and the winner will be announced during OEUK’s Offshore Decommissioning Conference on 24 November. Anasuria Operating Company, Apollo, Ithaca Energy, NES Fircroft, and TAQA UK are the company finalists in the People & Culture category. Finalists in the Outstanding Contribution to Energy Security category are Adura, bp, EnQuest, Ithaca Energy, and Restrata. The category Outstanding Contribution to Energy Decarbonisation, sponsored by the North Sea Transition Authority (NSTA), have the following finalists: Adura, Fugro, NEO NEXT+, and Serica Energy. The SMEs Aize, Elementz, and rahd.AI are the finalists in the category Innovative Supply Chain Company of the Year: SME, sponsored by the Net Zero Technology Centre.
Energy Review UK & North Sea Innovative Supply Chain Company of the Year: Large Enterprise, sponsored by Net Zero Technology Centre, has Aker Solutions, ASCO, and Boskalis Subsea Services as finalists. The Environmental Excellence award, sponsored by NEMS, has shortlisted bp, Eni UK, Kishorn Port Ltd, NEO NEXT+, and Ocean Winds. EnQuest is interested in buying bp’s UK North Sea oil and gas business, EnQuest’s chief executive Amjad Bseisu told CNBC in early September. Earlier this summer bp said that it was launching a process to market its North Sea business for a potential sale, following months of media speculation that the supermajor would be looking to exit the UK North Sea upstream. There is still a “tremendous opportunity” in the UK oil and gas sector, EnQuest’s Bseisu told CNBC. In its half-year report, EnQuest said it is focused on enhancing the next phase of operations at the Kraken oil field east of Shetland, one of the biggest subsea heavy-oil field projects in the UK sector of the North Sea. Work to mature the Kraken Enhanced Oil Recovery (EOR) project advanced materially in the first half of the year. Following the initial round of polymer testing reported in March, an improved polymer chemistry has been selected for the project. With the new polymer delivered ready-made and blended into the injection water in-line, the design is significantly simplified, reducing topsides complexity and lowering both facilities modification costs and polymer unit cost, EnQuest said.
“As decommissioning activity continues to accelerate across the UK Continental Shelf, we’re proud to be supporting operators with the safe delivery, expertise and leadership needed to execute these programmes successfully,” said Walter Thain, Group CEO of THREE60 Energy. Spirit Energy has successfully completed a £40 million decommissioning operation in UK waters, combining multiple operations within a single campaign to plug and abandon (P&A) three subsea wells, removing more than 234 tonnes of subsea infrastructure and with 100 percent of the recovered materials to be reused or recycled in UK yards. Working alongside more than 30 UK supply chain partners, including DeepOcean and Well-Safe, Spirit Energy safely and successfully delivered key plug and abandonment activities on the Seven Seas and Grove G5 production wells, and the Grove Deep exploration well, located in the UK Southern North Seas between April and July this year. Baker Hughes has announced a significant award from bp to provide offshore stimulation services across the company’s UK North Sea operations. The award supports both new well development and enhanced recovery from mature fields. Supported by a UK operating base and an established local supply chain network, a vessel-based stimulation solution has been chosen to enhance operational reliability, minimise non-productive time, and optimise recovery.
Well-Safe Solutions has signed a strategic partnership agreement with NMC Energy to support ongoing operations, including the recently awarded Apache Beryl and Forties decommissioning contracts, and to pursue future project collaboration opportunities. Under the partnership, NMC and Well-Safe will provide operators solutions for critical subsea and platform interface services, including pipeline and flowline flushing, platform integration of decommissioning equipment such as modular platform rig solutions, EDC (Engineering Down and Clean), and topside preparation for heavy lift operations. Ocean services provider DeepOcean has successfully completed subsea construction and tie-in work at the Teal West development in the Central North Sea for Anasuria Operating Company. DeepOcean’s scope of work included the installation of a flexible production riser and flowline, together with an umbilical connecting the Anasuria FPSO to the Teal West subsea Christmas tree. Flotation Energy has signed a Memorandum of Understanding with Harbour Energy to collaborate on the assessment of North Sea offshore electrification opportunities. The agreement brings together Harbour Energy’s extensive experience as a North Sea operator with Flotation Energy’s floating offshore wind and electrification expertise, to explore potential scenarios and build greater understanding of the technical, regulatory, and commercial considerations involved.
Consulting, engineering and operations group Wood has secured an engineering, procurement, construction and commissioning (EPCC) framework contract with Serica Energy to support the extension of the life of the Bruce platform in the UK North Sea. Under the five-year framework contract, Wood will deliver a portfolio of engineering services covering EPCC on the asset which will support the extension of production through to 2030 and beyond, while improving operational efficiency and reliability. THREE60 Energy is doubling its North Sea decommissioning scope after successfully completing the transition of three additional offshore assets under its decommissioning contract with a major North Sea operator, exercising an option included within the original agreement and expanding the programme to six assets.
© Deepocean
11
12
Theme Header
EU Energy Review The future of Europe’s upstream amid the shift toward energy security, agreements to increase Norway’s oil and gas supply to Europe, and progress in key renewable energy milestones and projects featured in Europe’s energy sector in the past few weeks. Oil & Gas Europe’s upstream is entering a new development and investment phase as energy security has become an important factor to consider in government policies, Wood Mackenzie analysts say. Norway’s stable investment environment and the government decisively in favour of the oil and gas industry, the single biggest job provider in the country, have made Norway and the oil and gas on its continental shelf the most reliable energy source for European energy systems. The overriding mandate in Europe, except for the UK, has been security of supply since the 2022 crisis, according to WoodMac. Many countries are urging operators to maximise domestic production, especially natural gas, to reduce reliance on imports, with Germany, the Netherlands, and Italy being the prime examples of this new drive toward energy security. While the North Sea gas production matures, exploration and production in southeast Europe and the Mediterranean is ramping up, with Turkey, Romania, Cyprus, and Greece all vying to become major gas producers and exporters to boost Europe’s energy security, Wood Mackenzie reckons. Moreover, the international majors are securing frontier exploration acreage in southeast Europe, which, if successful, could secure material long-term supply growth, potentially reducing reliance on gas imports, according to the analysts. Norway’s energy major Equinor has launched production from the Troll Phase 3 stage 2 subsea project at the Troll A gas field, which would raise gas deliveries to Europe from Troll A and the Kollsnes processing plant.
By Tsvetana Paraskova globalenergynetwork.net I October 2026
The project accelerates production of 55 billion standard cubic metres of gas from the Troll West reservoir. This volume equals nearly two years of France’s gas demand, Equinor said.
“Troll is the backbone of Norwegian gas exports to Europe. This project accelerates production from the reservoir, helping maintain today’s high level of gas exports from Troll and Kollsnes for as long as possible,” said Lill Harriet Brusdal, vice president for Troll and Kvitebjørn. Equinor has also recently signed a 15-year agreement with German energy company Uniper to supply natural gas to Germany. Under the agreement, Equinor will deliver more than 30 TWh, or about 2.8 billion cubic metres, of natural gas per year to Uniper. Deliveries will begin on 1 January 2027 and run until 31 December 2041, with the gas delivered at Trading Hub Europe, the German gas market area. Pricing will reflect market terms, while other commercial details are confidential, Equinor said. Separately, Equinor and Poland’s top refiner ORLEN have strengthened their energy partnership with a crude oil agreement. Equinor has signed an agreement with ORLEN for the sale of crude oil from the Johan Sverdrup field for three years starting from the beginning of September 2026.
Low-Carbon Energy The total capacity of the UK’s pipeline of onshore wind farms at any stage of development, including projects at an early stage of development through to those which are fully operational, has reached a milestone of 50 gigawatts GW), according to RenewableUK’s latest EnergyPulse Onshore Wind report. The UK now has a total pipeline of 50,134 megawatts (MW), or 50 GW of onshore wind capacity - an increase of 6.5 percent from the previous report a year ago, when the pipeline stood at 47 GW, per the report. One gigawatt of onshore wind generates enough electricity to meet the annual needs of over 650,000 UK homes, RenewableUK notes.
Energy Review Europe In 2025, the first full calendar year since the lifting of the onshore wind ban in England in July 2024, a total of 233 MW was submitted into the planning system.
EU solar installations increased by 1.9 percent in the first half of 2026, driven by renewed energy security concerns, the association said.
The report highlights the fact that planning submissions of onshore wind projects across the UK hit a record 5,043 MW in 2025, up by 47 percent compared to the previous peak in 2013 of 3,440 MW, two years before the start of the 2015-2024 ban on onshore wind in England.
Policy support, however, falls short of expectations and goals, and Europe is still heading for a slight contraction in solar deployment this year due to weakening policy support, according to SolarPower Europe’s EU Solar Market Update: 2026 Mid-Year Analysis.
In specific projects, plans to A DNV-led joint industry project produce floating offshore wind (JIP) with eight companies foundations at Port of across the European Ardersier in Scotland have offshore wind supply taken a step forward chain showed that with the approval of standardising turbine Europe’s offshore wind more than £778,000 in designs and securing targets show the scale Scottish Government predictable project funding. The Highlands of long-term demand, pipelines could and Islands Enterprise but the industry also reduce the average (HIE) gave the approval lifetime cost of needs visible, investable to the funding after electricity from North close collaboration with project pipelines Sea offshore wind by up Scottish Enterprise’s to 28 percent by 2050 in international arm, Scottish a high-volume scenario. Development International “Europe’s offshore wind targets show the scale of long-term demand, but the industry also needs visible, investable project pipelines”, said Ditlev Engel, CEO, Energy Systems at DNV. “Steadier demand and longer production runs can make better use of existing capacity and show where investment is needed in support of the business case, firm delivery is the most important KPI of all and for bringing down the cost.” Europe is heading for a record year for wind power capacity additions in 2026, a report by the WindEurope association showed. In the first half of the year, Europe installed 8.8 GW of new wind power capacity, up by 30 percent compared with the same period of 2025. Thanks to high installation activity over the summer, WindEurope now expects Europe to install 24 GW of new capacity by the end of 2026. While the jump in installations is good news for Europe’s energy security and competitiveness, structural problems persist and imminent policy choices on permitting, grids, and electrification will determine whether the wind ramp-up will continue, WindEurope said. Solar power capacity and solar-generated electricity have helped the European Union save more than 30 billion euros in avoided gas imports in the six months since the Iran war began, industry body SolarPower Europe said in a September report.
(SDI), to secure the project for Scotland.
The funding will support an 18-month front-end engineering design (FEED) study led by the France based company BW Ideol, a subsidiary of BW Ideol AS, which plans to develop an industrial facility at the Port of Ardersier dedicated to the serial production of its Damping Pool concrete floating foundations. The Siemens Gamesa blade factory in Hull has started production for Ørsted’s Hornsea 3, the world’s single largest offshore wind farm, which will produce more than 2.9 GW of clean energy, enough to power more than 3.3 million UK homes.
“This is what good growth in every postcode looks like - world-leading offshore wind blades built in Hull, powering clean homegrown electricity for millions of homes from off the coast of Yorkshire,” UK Energy Minister Michael Shanks said. Renewable energy company Anesco has successfully secured project financing with Lombard to support the development and operation of three UK sites. The financing covers a portfolio of projects at different stages of delivery: Woodwalton, a 21-MWp solar farm in Cambridgeshire that is fully operational and generating clean energy; Rothienorman, a 50MW/100MWh Battery Energy Storage System (BESS) in Scotland, now in the final stages of construction ahead of commissioning; and Coven, a 48.5-MWp solar farm in Staffordshire that recently achieved financial close, enabling the next phase of its development. A total of 14 energy companies and organisations from Northern and Central Europe have established the Baltic Energy Initiative, a new Baltic alliance in which the partners will work together on projects designed to strengthen energy security and competitiveness across the region, covering offshore wind, LNG and bioLNG, hydrogen, carbon capture and storage (CCS), nuclear power and small modular reactors (SMRs). The signatories are Eesti Energia, Enefit, Fortum, KN Energies, DNV Energy Systems, Topsoe, Siemens Energy, Adven, Steady Energy, P2X Solutions, Latvenergo, Gasgrid Finland, ORLEN, and Orsted.
13
14
USA Energy Review US oil and gas production is growing and shipments are soaring as global energy prices rise and trade flows in the Middle East remain disrupted. While the United States ramps up crude oil, fuel, and LNG output and export capacities, the Department of the Interior is looking to auction more acreage of federal land for oil and gas drilling and production. US Oil and Gas Exports Surge amid Hormuz Disruption Operators in the biggest US shale play, the Permian region of western Texas and eastern New Mexico, are producing more oil and gas by drilling longer, horizontal wells and increasingly incorporating so-called super-lateral wells that exceed 15,000 feet, the US Energy Information Administration (EIA) has said in an analysis. A decade ago, short-reach wells measuring less than 5,000 feet were common and they accounted for 43 percent of the wells completed in 2015. By 2025, they accounted for just 4 percent of horizontal wells. As the short-reach well share plummeted, the share of new wells classified as mid-length laterals, or wells measuring between 5,000 feet and 15,000 feet, jumped from 57 percent of completions in 2015 to a peak of 90 percent in 2021, before settling at 81 percent in 2025, according to Enverus data analysed by the EIA. The reduction in the share of mid-length lateral wells in the past five years was the result of the rise of the so-called superlaterals, with ultra-long lateral wells exceeding 15,000 feet, or about three miles. Such wells were virtually nonexistent prior to 2020, but they accounted for 15 percent of all new Permian well completions in 2025, the EIA noted. New horizontal well completions in the Permian have consistently hovered around 6,000 per year since 2022, while the average lateral length of a new horizontal Permian well soared by 77 percent in the last decade, rising from 6,149 feet in 2015 to 10,867 feet in 2025, Enverus data showed.
By Tsvetana Paraskova globalenergynetwork.net I October 2026
Enverus, the energy data analytics platform, has also recently ranked the most active US land drilling contractors and drilling customers, providing a snapshot of market leadership based on the latest available drilling data as of the first quarter of the year.
Among US land drilling contractors, Helmerich & Payne, Inc. ranked first with 15.85 million feet (ft) of total drilled measured depth across 776 wells. Patterson-UTI Drilling Company came in second with 9.51 million ft across 442 wells, Nabors Industries, Ltd. ranked third at 6.55 million ft, and Ensign Energy Services, Inc. ranked fourth with 4.21 million ft. Among drilling customers, Exxon led the ranking with 5.44 million ft drilled across 229 wells. EOG moved up two positions to No. 2 with 3.39 million ft, while Devon, Occidental, and ConocoPhillips rounded out the top five with 3.30 million ft, 3.28 million ft and 2.60 million ft, respectively, according to Enverus’ insight. “These rankings give the industry a consistent way to benchmark activity across leading contractors and operators while accounting for the reporting lags that are part of oil and gas data,” said Mark Chapman, principal analyst – OFS at Enverus Intelligence Research. US liquefied natural gas (LNG) exports averaged 17.4 billion cubic feet per day (Bcf/d) in the first six months of the year, up by 23 percent compared to the same period in 2025, as export capacity increased, the EIA’s Natural Gas Monthly for September showed. The EIA has estimated that US LNG exports will average 17.3 Bcf/d in the second half of 2026 before surging to 18.7 Bcf/d in the first half of 2027. “Export capacity additions from startup production at new terminals and expansions at existing terminals boosted LNG exports at the fastest rate since the United States began largescale exports in 2016,” the EIA said. Plaquemines LNG is exporting at full capacity, and Corpus Christi Stage 3 is currently exporting from six of seven liquefaction trains. These terminals, when complete, will increase nominal US export capacity by a combined 4.0 Bcf/d. Golden
15
Pass LNG began exports in April 2026 and is expected to increase exports from Train 1 through the end of 2026, adding another 0.7 Bcf/d of nominal export capacity. Golden Pass LNG Train 2 is expected to be completed in late 2026, according to the EIA data.
The effort aligns with the US Administration’s orders, including with President Donald Trump’s Executive Order 14154, “Unleashing American Energy,” aimed at increasing energy exploration and production on federal lands in an affordable and reliable manner.
US LNG exports have remained strong throughout the summer Furthermore, the BLM has as the disruptions at the opened a 60-day public Strait of Hormuz By harnessing Utah’s comment period on a intensified competition abundant geothermal new proposal to between Europe and resources, we are not only streamline oil and gas Asia for available spot supporting American Energy supply while Qatar’s permitting in Alaska. Dominance and creating LNG cargoes were robust economic opportunities The proposed rule mostly trapped and for local communities, but we aims to cut red tape are also strengthening our unable to leave the and accelerate national and military Persian Gulf. infrastructure security long into the future Market disruptions from development across the the closure of the Strait of 23-million-acre National Hormuz contributed to a Petroleum Reserve in Alaska — doubling of US LNG shipments to Asia driving forward American Energy in the first half of 2026 compared with last Dominance following a formal petition year. Exports to both Europe and Asia were both higher on a volume basis, rising from the Alaska Oil and Gas Association. by 1 percent and 108 percent from a year earlier, respectively. Exports to Latin In addition, public lands in southeastern America and the Caribbean and the Middle New Mexico could raise US oil and gas East and North Africa also jumped, by 46 output under a proposed final revision to a percent from last year. land-use plan for the Carlsbad Field Office, the BLM said. The proposed Interior Looks to Expand Oil resource management plan would make and Gas Leasing across US 97 percent of public lands managed by The Interior’s Bureau of Land Management Carlsbad Field Office available for energy (BLM) has announced in recent weeks and mineral leasing alongside expanded new oil and gas lease sales and intention grazing and recreational opportunities. to expand these in several US states. The BLM has announced an oil and gas lease sale scheduled for 27 October 2026, which would offer 20 oil and gas parcels totalling 3,388 acres in Montana, North Dakota, and South Dakota. The BLM completed scoping on these parcels in May 2026 and held a public comment period that closed in July 2026 on the parcels and the related environmental analysis. All parcels in a federal oil and gas lease sale include appropriate stipulations to protect important natural resources. The BLM is also considering a proposal to allow oil and gas leasing on about 5,200 acres of the federal mineral estate underlying the Ouray National Wildlife Refuge near Vernal in northeast Utah. The proposal includes a “no surface occupancy” requirement, meaning that, if approved, any future lease development would have to be accomplished through directional or horizontal drilling from well pads outside the refuge.
Record Geothermal Lease Sale The BLM also received the highest parcel bid at $4,168,725 and highest per-acre bid at $1,207 in a geothermal lease sale in Utah held in August. The Bureau accepted winning bids on 32 parcels in Utah totalling 72,398 acres for $24,706,280 in total receipts for a geothermal lease sale, the second largest lease sale in total dollars in the BLM’s history. “By harnessing Utah’s abundant geothermal resources, we are not only supporting American Energy Dominance and creating robust economic opportunities for local communities, but we are also strengthening our national and military security long into the future,” said Doug Burgum, Secretary of the Interior and Chairman of the National Energy Dominance Council.
INTEL
On The Pulse of Global Energy One platform. Infinite Intelligence. Market intelligence for the global energy sector: tracking tenders, deals, assets, and offshore activity shaping the industry.
Join the industry leaders who stay ahead of the curve. GENIntel
The Next GEN of Media www.globalenergynetwork.net
16
MID Energy Review East
The Middle East conflict continued to roil global oil and gas markets, and an escalation of hostilities in early September sent Brent crude oil prices past $100 per barrel again for the first time since July 24.
Global gas markets are also reeling from the reduced LNG supply out of the Strait of Hormuz, just as Europe and Asia are competing for gas supply to stock up for the winter. Fuel markets are the tightest of all energy commodity markets amid low flows of refined petroleum products out of the Strait of Hormuz and damaged refineries in the Middle East, as well as crippled Russian diesel output and exports due to incessant Ukrainian drone attacks on Russian refineries.
OPEC Keeps Production Goals Flat As Supply Remains Restricted The seven OPEC+ countries, which had restricted oil supply since 2023 and unwound all their nominal reductions earlier this year, decided in early September to maintain their required production for October 2026, too. Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria, and Oman reaffirmed their commitment to market stability and said they would continue to hold monthly meetings to review market conditions. While OPEC+ has now unwound, on paper, all previous cuts, a large part of the crude oil, fuel, and LNG production in the Middle East remains trapped at the Strait of Hormuz, as of the first half of September. So output and supply from OPEC producers and from the Middle East is well below the quotas of the individual OPEC+ producers. For example, a Bloomberg survey showed that OPEC’s crude oil production slumped in August from July, ending a two-month recovery streak, as Saudi Arabia, OPEC’s top producer and the world’s biggest crude oil exporter, reduced supply due to shipping threats in the Red Sea that added to the Strait of Hormuz crisis.
By Tsvetana Paraskova globalenergynetwork.net I October 2026
The Bloomberg survey estimated OPEC’s crude oil output at about 19.91 million barrels per day (bpd) in August, down by 900,000 bpd compared to July. Saudi Arabia’s production was estimated to have declined by 1 million bpd, which was only marginally offset by output gains in Iraq and Venezuela, according to the survey.
As of early September, global LNG supply remained 9 percent lower compared to the same time last year as the Middle East conflict continued to restrict LNG shipments out of the Strait of Hormuz, Rystad Energy estimated. Attacks on LNG carriers, liquefaction facilities, and an import terminal in Egypt have kept Qatari and UAE volumes constrained even as loadings pick up, the independent energy intelligence firm said. The decline in Hormuz shipments left global LNG supply 9 percent below last year despite a modest month-onmonth recovery. Rystad Energy’s base case still points to an uneven reopening of the Strait of Hormuz by the fourth quarter, the intelligence firm said.
Middle East Conflict Disrupts Global Refining Beyond crude oil exports, the Middle East conflict is significantly tightening global fuel markets as refiners in Asia, Europe, and the United States are unable to offset the loss of refining capacity and supply from the Middle East and Russia. The re-escalation in the Middle East in early September sent global middle distillate cracks to record highs. Diesel prices globally are soaring, with diesel cracks at all-time highs, as supply remains constrained in the Middle East and Russia, while maximised refinery runs elsewhere cannot offset the supply lost to the US-Iran war and Ukraine’s drone attacks on Russian refineries. The decline in refined product supply from the Middle East and Russia has widened the divergence between crude oil and fuel markets, analysts say. Refining has become the weak link in the global oil markets as “Refinery margins have surged, inventories remain tight and refined fuels are increasingly trading at premiums that reflect physical scarcity rather than the underlying cost of crude,” Ole Hansen, Head of Commodity Strategy at Saxo Bank, wrote in an analysis in early September.
Energy Review Middle East As refined products and gas remain structurally tight, crude oil price spikes would intensify the pressure on transport, industry, utilities, and households, Hansen said.
Saudi Aramco’s New Tech and Minerals Mining Initiatives
“To conclude, the future of industry will inevitably become more intelligent. But it must also be trusted and scalable. That is the opportunity we see at Aramco,” the executive said.
Saudi state oil giant Aramco is focused on the physical, operational, and global This raises “the likelihood that challenges in AI, Ahmad O. the current energy shock Al-Khowaiter, Executive Vice translates into persistently President Technology and higher consumer prices Innovation at Aramco, said and a more difficult ...the likelihood that at the annual LEAP 2026 inflation outlook for the current energy shock tech conference in central banks,” the translates into persistently Riyadh. strategist noted.
higher consumer prices and a more difficult inflation outlook for central banks
If the Middle East conflict extends to the end of this year, global crude runs would be cut by an estimated 1.4 million (bpd) in the fourth quarter of 2026, led by Asia, according to a Wood Mackenzie analysis.
The disruption of supply from the Middle East has sent shockwaves through Asian refining, fundamentally altering crude supply routes, product market dynamics, and the long-term competitive landscape for the region’s refiners, according to WoodMac. Persistent Ukrainian drone attacks on Russian refineries have compounded the disruption, tightening the global refining system further. “The scale of disruption to global crude runs is without modern precedent,” Alan Gelder, SVP refining, chemicals and oil markets research at Wood Mackenzie, said at Wood Mackenzie’s Asian Oil, Refining and Chemical Markets Briefing. “While Asian refiners are navigating an immediate margin opportunity, the more important question is how they choose to respond.” The war has accelerated the structural diversification of Asia’s crude supply base, said Sushant Gupta, director, oils and refining research at Wood Mackenzie. “Refiners that can optimise across a wider crude slate particularly grades with higher middle-distillate yields will be best positioned to capture value in this evolving environment,” Gupta added.
Aramco has also announced agreements and a Memorandum of Understanding (MoU) with a potential combined value of more than $3.7 billion with French companies. The collaborative efforts with French firms are expected to strengthen Aramco’s supply chain ecosystem, enhance operational continuity and efficiency, advance industrial AI and digital technologies, and deliver economic value to the Kingdom and France, the Saudi company said.
Aramco relies on intelligence, trust, and scale to innovate with AI, the executive told the delegates at the event.
The Saudi oil giant’s billions of data points from wells, pipelines, refineries, terminals, and laboratories do not create value. The value comes from combining the many data points with huge computing power and world class technical expertise to put into models which help our engineers, operators, and technologists make better decisions, Al-Khowaiter said.
Aramco and Saudi Arabia’s mining giant Maaden have announced the signing of a shareholders’ agreement to form a Joint Venture to unlock new opportunities in mineral exploration and hard-rock mining in the Kingdom of Saudi Arabia. Combining the strengths of two leaders in their respective fields, the joint venture would focus on copper and other minerals critical to the energy transition. The joint venture is expected to be 51 percent owned by Maaden and 49 percent by Aramco and would focus on exploration across Zone4, also known as the Transition Zone, within the Arabian Platform.
“This is why we are moving AI deeper into the core of our business. We are using it to enhance exploration, optimize production, improve reliability, accelerate engineering, strengthen maintenance, and even keep our people safe.” The use of AI detects anomalies, recommends responses, and automates workflows, empowering our people to focus on higher-value decisions, the executive said.
Spanning approximately 182,000 square kilometres, nearly 10 percent of Saudi Arabia’s total land area, the expected exploration area stretches along a 100-kilometre-wide zone running parallel to the Arabian Shield.
“It’s not a matter of reducing our manpower, it’s about doing more with our existing workforce,” Al-Khowaiter added.
“Over 90 years, Aramco has accumulated and analyzed the largest amount of geological and geophysical data ever acquired in a single basin for the Kingdom,” said Saleh M. Al Saleh, Aramco Vice President of Transition Minerals.
AI is not replacing Aramco’s industrial knowledge, it is amplifying it, he said, noting that the company’s TecShift initiative aims to attract early-stage startups from across the world to its headquarters in Dhahran.
“This partnership intends to leverage this legacy information to find minerals in the JV area within the basin.”
Middle East Review SPONSORED BY
WIDER AFRICAN ENERGY SUMMIT
17
18
NOR Energy Review
Norway Hopes Future Discoveries Could Sustain Oil and Gas Output Norway needs significant discoveries to maintain the high level of production after 2030, the offshore regulator said in its annual report, while the top operators on the Norwegian Continental Shelf (NCS) announced strategic updates and field stake reshuffles in search of the next major discoveries.
Oil and Gas Production Outstrips Resource Growth Resources on the NCS remain plentiful, but without significant discoveries in the coming years, Norway risks a steep drop in oil and gas production after 2030, the Norwegian Offshore Directorate said in its annual Resource report 2026 in August. The Resource Report 2026 showed that remaining resources are at an estimated 7 billion standard cubic metres of oil equivalent. Around half of these resources have not yet been discovered. By comparison, about 9 billion scm oe have been produced and delivered, the directorate said. The activity level on the NCS remains high. Oil production in 2025 reached its highest level since 2009, and investments for 2026 are estimated at NOK 230 billion, or about $24.6 billion. The high level of investment reflects strong confidence in the resource base and future profitability, the regulator said. With significant discoveries needed to keep production at current levels as production from maturing fields decline, Norway needs more exploration, both close to existing infrastructure and in less explored areas, according to the regulator. The petroleum sector is the largest industry in the Norwegian economy, measured in terms of value added, government revenues, investments, and exports. The petroleum industry is expected to account for 22 percent of total value added and 47 percent of export values this year.
By Tsvetana Paraskova globalenergynetwork.net I October 2026
“More than 210,000 people are directly or indirectly linked to the industry. What happens on the shelf in the coming decades is therefore not just about oil and gas, but about incomes, jobs and expertise for society as a whole,” the directorate said in the report.
Over the past decade, Norway has seen a consolidation drive that has led to a more concentrated industry landscape, the regulator noted. The number of companies on the NCS has more than halved since 2013. Large international companies have pulled out, and the development of new projects on the shelf is now largely dominated by Norwegian-based companies such as Equinor, Aker BP, and Vår Energi. “A more concentrated industry player landscape can diminish both the geoscientific diversity of ideas and the competition for attractive acreage, which has historically been crucial for large discoveries,” the directorate noted. In short, Norway’s petroleum industry is in a good position currently with profitable operations and confidence in investments. But operators need to make new discoveries soon, including large ones, and develop smaller field tie-backs more swiftly, to avert a decline in oil and gas output after 2030, the directorate’s report found.
Discoveries and Recovery The regulator has recently announced that operator Equinor and its partner Aker BP have discovered gas and condensate in the “Linga” prospect in a production licence 16 kilometres northwest of the Balder field and 205 kilometres west of Stavanger. Preliminary estimates indicate the size of the discovery is between 0.1 and 2.1 million standard cubic metres (Sm3) of recoverable oil equivalent. The discovery was made in the third well drilled in production licence 782 S, which was awarded in 2015. The licensees are now reviewing the result from all three
Energy Review Norway wells to consider further exploration potential in the production licence, the directorate said. The Norwegian Offshore Directorate has identified three discoveries on the NCS that may be suitable for enhanced recovery using advanced methods (EOR). One of these discoveries remains unclaimed. The Linerle discovery in the Norwegian Sea contains a projected 33.7 million Sm3 of oil. The discovery lies about 25 kilometres from the Norne field. Linerle is one of few discoveries on the NCS that contains relatively high viscosity oil, which is uncommon on the NCS. The companies will be able to apply for Linerle in upcoming APA licensing rounds, the regulator said. Previous studies indicate that conventional recovery methods can be expected to yield a relatively low recovery rate of 17 percent, so Linerle would benefit from a renewed assessment that would consider improved recovery using advanced chemical EOR methods. “Linerle is a realistic opportunity to test whether chemical EOR can generate values offshore,” said Ove Bjørn Wilson, senior reservoir engineer at the Norwegian Offshore Directorate. This method has been used on several fields on the UK shelf and has yielded good results, Wilson added. Apart from Linerle, the Slagugle project in the Norwegian Sea and Frigg near the Hugin field in the North Sea have been identified as potential candidates for using such methods. “In order to reduce the anticipated production decline on the NCS, it’s important that the companies devote greater efforts toward considering EOGR opportunities,” Wilson noted. “Advanced EOGR can generate considerable values, but there is a risk of overlooking attractive opportunities.” Meanwhile, the Norwegian Offshore Directorate’s “Improved Recovery Award” went to Okea for working to revitalise the Draugen and Brage fields. Okea took over operatorship on Draugen in 2018 and on Brage in 2022. Since the operator swap, the company has worked hard to revitalise the fields, which has resulted in increased reserves and resources, higher production, and extended lifetimes, the regulator said.
“The NCS relies on bold players who are committed to optimising value creation from fields in the tail phase in order to ensure that all profitable resources are produced,” the regulator’s jury awarding the prize wrote in its decision.
Operators Boost Exploration Cooperation and Reshuffle Portfolios Equinor, Aker BP, and Vår Energi have established a strategic exploration collaboration to pursue some of the largest remaining opportunities on the NCS. Their goal is to increase the chances of major discoveries that can support new standalone field developments and longterm value creation offshore Norway. The three companies have agreed to combine expertise, data, technology, and exploration capacity to pursue select high-impact exploration opportunities. Over the next four to five years, Equinor, Aker BP, and Vår Energi plan to mature and test a portfolio of about 20–25 exploration opportunities, with an ambition to drill around five high-impact exploration wells per year. “Near-field exploration remains crucial, but we also need to pursue the bigger opportunities to sustain activity and value creation beyond 2035,” said Kjetil Hove, executive vice president for Exploration & Production Norway, Equinor. The strategic collaboration “has the potential to unlock access to material new discoveries that can support longterm production, create value for our stakeholders and contribute to maintaining Norway’s position as a secure and responsible supplier of energy to Europe,” said Vår Energi CEO Nick Walker. DNO ASA has announced an agreement with Equinor under which select non-core license interests will be transferred to Equinor in return for a significantly reduced decommissioning deposit and a corresponding improvement in near-term liquidity. As part of its 2025 acquisition of Sval Energi AS, DNO assumed an obligation to pay a post-tax deposit for decommissioning liabilities to Equinor in August relating to the Ekofisk and Martin Linge assets. The deposit would be held by Equinor until the fields have been decommissioned long into the future. Under the terms of the new agreement, the deposit is reduced to a one-time payment, improving near-term liquidity including tax effects by more than $35 million. In exchange, DNO will transfer licence interests to Equinor, as follows: 20
percent in PL293B and 293 CS (Kveikje discovery), 29 percent in PL827 S (Heisenberg discovery), and 10 percent in PL1245 (exploration license containing the Romsås prospect). Aker BP has entered into two separate transactions that strengthen its positions close to existing infrastructure on the NCS. In the North Sea, Aker BP has agreed to acquire Apache’s interest in the Losgann/Froskelår discovery near the Alvheim area. In the Norwegian Sea, Aker BP has agreed to buy operatorship and a majority interest in the Slagugle area, close to the Skarv field. Meanwhile, Aker BP has started production from the Skarv Satellite Project, which comprises the Alve Nord, Idun Nord, and Ørn fields in the Norwegian Sea. These developments represent approximately 120 million barrels of oil equivalent of recoverable resources and support further value creation by increasing flexibility and extending the life of the infrastructure around Skarv, the company said.
Norway Boosts Offshore Wind Collaboration Norwegian Offshore Wind has signed a Memorandum of Understanding (MoU) with three of Taiwan’s premier technology and industrial research hubs to focus on the joint development and operational governance of offshore test sites for ocean renewable energy, and the building of resilient cross-border supply chains serving both demonstration and full-scale commercial projects. At the ONS conference in Stavanger, Norwegian Offshore Wind signed the MoUs with Taiwan’s Metal Industries Research and Development Centre (MIRDC), Industrial Technology Research Institute (ITRI), and Ship and Ocean Industries R&D Center (SOIC). “Taiwan is among the absolute frontrunners when it comes to 2050 offshore wind targets, and floating wind will be key to unlocking their deepwater potential,” said Arvid Nesse, CEO of Norwegian Offshore Wind. “Establishing structured collaboration on testing and supply chain development benefits developers and suppliers on both sides of the globe.”
19
20
Theme Header
AUS Energy Review Australian energy firms are ramping up gas projects, starting new production, and aim to develop additional resources, as gold and minerals output in several states has also surged in recent months. Gas Projects Energy major Santos said in its half-year results that the Barossa LNG project delivered seven cargoes by the end of June with another five cargoes delivered since 1 July. The recently started-up project is currently producing at around 550 mmscf/d. In recent weeks, Santos “continued to progress Barossa through commissioning towards steady-state production, while the base business continued to perform strongly,” Santos Managing Director and CEO, Kevin Gallagher, said. Barossa is safely progressing through commissioning to steady state production, with current production around 550 mmscf/d and planned to increase further to around 600 mmscf/d by end of the third quarter, the executive said in the middle of August. “At steady state production the current cargo cadence is one approximately every eight days, while Darwin LNG delivered 100 percent plant reliability in the first half,” Gallagher added. Separately, Santos has entered into a binding agreement to acquire a 30-percent interest in the Meridian CSG project for about US$85-$90 million as part of a sale to the GLNG joint venture partners and has completed the sale of its interest in the Mahalo joint venture, valued at around US$23-44 million.
By Tsvetana Paraskova globalenergynetwork.net I October 2026
The GLNG joint venture partners – Santos, TotalEnergies, PETRONAS, and KOGAS – have entered into binding agreements to acquire 100 percent of the Greater Meridian CSG project (Meridian) in Queensland, which was underpinned by a long-term supply contract with GLNG. Each GLNG partner will acquire a pro-rata share in line with its GLNG joint venture interest, with Santos acquiring a 30-percent interest and becoming operator of the project upon completion of the transaction.
The acquisition is consistent with Santos’ strategy of disciplined growth around existing infrastructure, with synergies expected as operations are integrated with Santos’ other CSG operations in Queensland. Meridian will become a fifth production hub for GLNG, Santos said. Meridian is a producing CSG project near Moura in Queensland, comprising 280 producing wells with gas export capacity via the GLNG Gas Transmission Pipeline and Jemena’s Queensland Gas Pipeline. About 90 percent of the current production supplies GLNG under a long-term gas sales agreement and the remainder delivers domestic gas customer Queensland Nitrates at Moura. The other oil and gas major, Woodside Energy, said in its half-year results that the Scarborough Energy Project is now 98 percent complete and remains on track to deliver first LNG cargo in the fourth quarter of 2026. During the first half, Woodside completed all upstream infrastructure, and subsequent to the period, achieved ready for start-up and first gas at the floating production unit. The company said its focus remains on disciplined commissioning and start-up of all facilities to ensure safe and reliable operations from day one. APA Group in early September announced the commissioning of first gas from Tamboran Resources Corporation’s and Daly Waters Energy’s Shenandoah South Pilot Project, marking a major milestone for the Beetaloo Basin and the Northern Territory. Beetaloo gas will flow through APA’s newly constructed Sturt Plateau Pipeline (SPP), linking with APA’s Amadeus Gas Pipeline to move Beetaloo gas north to support energy security across the Northern Territory. Hancock Energy, owned by Australian mining billionaire Gina Rinehart, is advancing its Perth Basin gas development, making progress with approvals that would lead it to give the green light to a new investment in West Australia by the end of the year.
Energy Review Australia In August, planning authorities approved Rinehart-chaired Hancock Prospecting’s AUS$850 million Belisama gas hub proposal in the Perth Basin, after the Environmental Protection Authority waved the project through without assessment. Assuming all approvals are obtained, the Belisama Gas Project would result in investment of AUS$1.5 billion, Hancock said at the end of August. Belisama is a conventional gas project in West Australia’s Perth Basin, which could meet 20 percent of West Australia’s gas needs when in full production. “Belisama is positioned to be able to bring substantial new gas supply to market from 2029, and provide reliable energy to support West Australia homes, industries, jobs and living standards,” Hancock executive chair Gina Rinehart said. “Hancok is prepared to invest significant private capital to develop new gas supply for WA, delivering benefits for West Australians, but notes that projects of this scale need stable and sensible government policies that encourage investment and development so we can get gas reliably to West Australians.”
Gold Exploration and Mineral Production On the Rise The June 2026 quarterly mineral exploration expenditure statistics for Australia showed a national jump in mineral exploration of 24.8 percent to AUS$1.19 billion. The data, released by the Australian Bureau of Statistics (ABS), reveals the enthusiasm for gold exploration, the Association of Mining and Exploration Companies (AMEC) said. Gold exploration dominated exploration expenditure, up by 23.6 percent to $565.6 million during the June quarter of 2026. “These results reveal an extraordinary quarter for Australian gold exploration, with more than half a billion dollars spent searching for gold in just three months,” AMEC’s Acting CEO, Neil van Drunen, said. “Gold exploration expenditure has jumped almost $108 million in a single quarter and is now 40 per cent higher than this time last year.” Strong demand for gold has recently provided confidence to explorers to get drill rigs on the ground, as confirmed in the latest statistics figures, van Drunen said. In the minerals industry, the Northern Territory reported that the sector delivered AUS$6.1 billion in value in 2025-26, the
highest ever and a 40 percent annual increase. Gold was the largest contributor, with production increasing to 13.36 tonnes and the value of gold sales rising by 60 percent to AUS$2.67 billion, supported by sustained record gold prices. Manganese, bauxite, and zinc-lead production were the other key contributors to the production value of NT’s minerals sector. “The 2025-26 result also reflects the continued diversification of the Territory’s resources sector, with lithium sales returning and a magnesite bulk sample sale contributing to the mineral production value for the first time,” the Northern Territory’s Department of Mining and Energy said.
Renewable Energy Advances Rooftop solar met 99.9 percent of South Australia’s total electricity demand on 30 August, reducing electricity demand from grid-scale generation to just 2 MW at 1:30 pm (AEST) – a new winter record, the Australian Energy Market Operator (AEMO) said. Mild temperatures and clear skies across the south-east of the country saw a new winter minimum operational demand record of 11,992 MW set at 1:30pm for the National Electricity Market (NEM), surpassing the previous winter record of 12,144 MW in August 2024, according to AEMO. “These records demonstrate how rapidly the electricity system is changing, with high renewable generation increasingly being balanced in real time by batteries, hydro and gas, supported by the transmission network,” AEMO said. “For AEMO, these conditions reinforce the need to plan for a power system that is increasingly dynamic – with the flexibility, storage, transmission and operational capability needed to maintain a secure and reliable supply as the energy transition accelerates.”
The state of Victoria has just launched Australia’s first offshore wind auction in the Gippsland offshore after Minister for Energy and Resources, Jaclyn Symes, opened the Request for Proposal process for Victoria’s first 2 gigawatts (GW) of offshore wind. This capacity will provide enough energy to power around 1.5 million homes each year. Contracts are expected to be integrated into the national Electricity Services Entry Mechanism (ESEM), providing a pathway towards Victoria’s target of 9 GW of offshore wind. The auction will close in August 2027, with contracts expected to be awarded in 2028. “This auction is a giant leap towards getting Australia’s first offshore wind projects built - attracting billions in investment, creating thousands of jobs and delivering the reliable power we need as coal retires,” Symes said. “Victoria has some of the best offshore wind resources in the world. This auction is about harnessing that advantage and building the next generation of energy right here in Victoria.” Renewables currently account for 45 percent of the state’s total electricity generation. Australia’s peak industry body for the renewable energy sector, the Clean Energy Council (CEC), welcomed the launch of the offshore wind auction, saying that “Victoria is uniquely positioned to harness world-class offshore wind resources at a time when the state’s economic and population growth will drive significantly higher demand for electricity into the future.” “Offshore wind as part of a diverse energy mix provides protection against volatile global conditions by providing secure supply locally,” CEC Chief Executive, Jackie Trad, said.
21
UK & EUROPE
•
MIDDLE EAST
•
AFRICA
•
ASIA-PACIFIC
•
WORLDWIDE
FOR ENERGY & INDUSTRY From Aberdeen to the World Apex Industrial Chemicals Limited (AIC) is an independent UK specialty chemical manufacturer with more than 40 years of experience designing, formulating and supplying high-performance chemistry. From our Aberdeen base, we support industrial, oil & gas, energy and marine requirements worldwide with responsive manufacturing, technical expertise and practical, application-led solutions.
READY - GLOBALLY
GLOBAL CAPABILITIES
Critical infrastructure operates in very different conditions from region to region. Climate, water chemistry, scale, corrosion, residues, contamination, logistics and project size can all change the maintenance challenge.
Pipeline & Tank Cleaning
AIC focuses on the application first - matching chemistry and technical support to the actual operating requirement rather than applying a one-size-fits-all approach. GLOBAL POSITIONING Application-led chemistry tailored to project conditions, asset type and operating environment. International supply capability across the UK & Europe, the Middle East, Africa, Asia-Pacific and further global markets. Practical support for operators, contractors and maintenance programmes where reliability and turnaround matter.
Vessel & Rig Cleaning NORM Scale Removal Scale, Rust, Wax, Tar & Crude Removal Corrosion Removal & Prevention Specialty & Custom Chemical Solutions Bulk Supply for Large-Scale Projects Laboratory Testing & Technical Support BUILT FOR INTERNATIONAL PROJECT DELIVERY AIC combines in-house formulation, manufacturing and laboratory capability with responsive supply, technical documentation and international logistics support - from individual requirements to bulk project volumes.
40+ years of specialty chemistry | ISO 9001 | ISO 14001 | ISO 45001
DESIGN. FORMULATE. MANUFACTURE. SUPPLY. SUPPORT. GLOBALLY.
www.apexchemicals.com
SCAN TO VISIT ❱
intel
& Training Monthly intelligence summary forHSE the GEN supply chain community. Rig and vessel markets, operator activity, regional signals and the GENI Index.
83
GENI INDEX · WEEK 40 · 28 September 2026 Global Energy Network Intelligence Index · Sub-indices updated weekly
23
/100 overall
2 on Week 39
Supply chain at a record 93. The whole fall sits in M&A, 10 down on one deal. Drilling & Exploration
92
Renewables & Transition
86
M&A & Capital Flow
72
Geopolitical Risk
71
Supply Chain Confidence
93
THE RIG MaRKET
Baker Hughes week to 25 September 2026 · North America count
US Total Rigs
599
US OIL Rigs
Canada Rigs
Gas rigs 135, up 1 and the highest since July 2023. Gas activity is holding up because LNG and power demand are contracted years ahead.
The largest Canadian weekly move in the GEN Intel series. 18 above the same week last year and the full recovery of the prior fall.
455 3
4
Third consecutive weekly rise. Permian at 270. Up from 591 in the week to 11 September, rising against a falling WTI price.
208 11
GENI INDEX REGIONAL HEATMAP OCTOBER 2026 Signal status and primary commercial driver by region · GEN analysis, 19 August to 28 September 2026
REGION
SIGNAL
KEY DRIVER
GEN VIEW
UK North Sea
WATCH
Rosebank and Jackdaw consent decisions pending. Serica acquires Pharos Energy for $194.5m.
Rosebank consultation closed 17 August. Preparatory work can continue but no production until consent. Mid cap consolidation in late life UK portfolios continues. Culzean recorded with spare host capacity and a field life to 2040, a tieback case for nearby discoveries.
Norway NCS
STRONG
Odfjell $518m Gjøa rig fixture in Week 39
A fixture of this size takes a rig out of the NCS market for a multi year programme. Suppliers to the Gjøa area should approach Odfjell and the operator on well services and logistics now, while the programme is being planned.
Middle East
DISRUPTED
Hormuz flows level at 33.7m barrels a week. Iran proposes a seven day route to reopening.
Third commercial Hormuz mechanism in six weeks failed to hold. Saudi East West pipeline hit by drone damage on 10 September. Work is still being awarded: SLB takes more than 450 Aramco wells under three year contracts. Qualify with the well services holder now.
West Africa
STRONG
TotalEnergies and AMNI sanction Ima gas, Nigeria. TotalEnergies takes Mopane operatorship, Namibia.
Ima supplies about a third of the gas for Nigeria LNG Train 7, with all key contractors Nigerian. In Namibia, TotalEnergies now operates both Venus and Mopane. A three well Mopane appraisal starts this half. Venus FID is the one to track before year end.
Black Sea
ACTIVE
Third Sakarya extension to Subsea7 in five weeks. Neptun Deep production platform installed.
Sakarya work is going to an existing alliance with Saipem, with no competitive event. Neptun Deep moves from fabrication into hook up, commissioning and production support, bought locally through OMV Petrom rather than Vienna.
SE Asia
ACTIVE
PTTEP and Valeura sanction Bussabong, Gulf of Thailand. Vantris takes about RM1.8bn of Petronas and PTTEP work.
Bussabong ties two wellhead platforms into Bongkot with no new processing. The Vantris award covers transportation and installation across a portfolio, not a single campaign. Malaysian content rules apply, so partner through the holder.
GoM (US)
MIXED
WTI down 7.87 percent to $92.41. Brent up to $104.32. Spread widens to $11.91.
Scarborough was 98 percent complete at the end of June. The project now moves from construction into operations and maintenance. Pluto Train 1 modifications and Train 2 commissioning are the near term scopes for Perth based suppliers.
Europe Transition
ACTIVE
Six European projects recorded at execution stage. Fortum and Google sign a 22 year nuclear power purchase agreement.
OMV Sarasdorf hydrogen reaches execution, a reference configuration OMV is likely to reuse. Carbon storage is now buying: tubulars for wet carbon dioxide service in Greece and abandonment ahead of storage in the Irish Sea.
AUS & APAC
STRONG
Woodside Scarborough first gas achieved. First LNG cargo on track for Q4 2026.
Two signals pulling opposite ways. Government led work is progressing and creating precedent, while the private financial assurance regime has just failed in public. Reform is still pending. Perth and Emma Davidson are the contact route.
FID CONFIRMED · Week 39
aWaRD · Week 39
M&a · Week 39
23 September 2026
22 to 24 September 2026
September 2026
Ima Gas Development, Nigeria
SLB: more than 450 wells for Saudi Aramco
Serica Energy acquires Pharos Energy
Three year contracts, the largest well commitment recorded by GEN Intel this year. One of three categories handed to a single holder in one week, with Vantris in Malaysia and Subsea7 at Sakarya. Sub supply structures are set in the first quarter after award. Approach SLB now.
$194.5m. Mid cap consolidation across late life UK and Egypt portfolios. A new owner reviews its supplier base, so incumbents should expect contracts to be retendered and challengers should make contact before the review, not after it.
TotalEnergies (40 percent, operator) and AMNI (60 percent). Single shallow water platform near Bonny Island with a 22km pipeline to Nigeria LNG. Plateau 350 MMcfd from 2028. Development cost about $1.1bn. Shore power, no flaring. All key contractors Nigerian.
The Next GEN of Media
Log in to GENIntel for more information - www.globalenergynetwork.net Log in to GENIntel for more information - www.globalenergynetwork.net
24
HSE & Training
Intel
PROJECT INTELLIGENCE
1
2 54
3 6 10
7
9
11
8 12
UK North Sea
01
UK North Sea
02
USA: Louisiana
03
Rosebank Field Development: West of Shetland
Jackdaw Gas Condensate Development: Central North Sea
Delfin FLNG 1 and FLNG 2: Offshore Louisiana
OPERATOR: Adura (Shell and Equinor JV) / Ithaca SP E&P
OPERATOR: Adura (Shell and Equinor JV)
OPERATOR: Delfin Midstream with GIP, MOL, Vitol and
EST. VALUE: Multi billion
EST. VALUE: $5bn for FLNG 1 STATUS: FLNG 1 in execution: FLNG 2 targeting FID
EST. VALUE: £8.7bn STATUS:
Consultation closed 17 Aug: consent decision pending
The largest undeveloped oil field in the UK sector, about 130km northwest of Shetland, with resources of more than 350 million boe. Adura puts peak output at about 69,000 bpd, roughly 10 percent of expected UKCS oil production, with 3,500 jobs at peak construction. Oil goes to a redeployed FPSO and gas by pipeline to Sullom Voe. The court ruling allows preparatory work to continue, but no oil can be produced until the Secretary of State agrees to a fresh consent.
globalenergynetwork.net I October 2026
STATUS:
Fresh consent decision pending
A not permanently attended wellhead platform with four wells, about 250km east of Aberdeen, tied back to the Shearwater hub through a 31km pipeline. The jacket was installed in August 2023, the topsides in October 2025 and the pipeline laid in July 2024. The wells are at an advanced stage of drilling. The asset is close to ready, so hook up, commissioning and start up scopes follow quickly once consent is given.
Diameter in 2026
FLNG 1 took FID on 3 June 2026: the first US floating LNG facility and the largest FLNG project anywhere at 4.4 mtpa, with production scheduled for 2030. Delfin has now signed MidOcean Energy to take up to 50 percent of FLNG 2 and placed a limited notice to proceed with Siemens Energy for critical equipment. FLNG 2 replicates the first design and targets FID before the end of 2026. The port is designed for three vessels and up to 13.2 mtpa.
Upstream oil and gas developments to watch, operator, location, value and supply chain insight.
HSE & Training
The Next GEN of Media
Compiled by GEN Intel Access the full interactive dashboard and pipeline data today at globalenergynetwork.net
Romania: Black Sea
04
Türkiye: Black Sea
05
06
Saudi Arabia
Neptun Deep Gas Development: Romanian Black Sea
Sakarya Gas Field Development: Western Black Sea
Aramco Well Delivery Programme: SLB Three Year Contracts
OPERATOR: OMV Petrom (operator) / Romgaz
OPERATOR: Turkish Petroleum (TPAO)
OPERATOR: Saudi Aramco
EST. VALUE: Multi billion
EST. VALUE: Not disclosed
EST. VALUE: Multi billion STATUS:
Production platform installed
STATUS:
The offshore production platform is now installed, moving the project from fabrication into hook up, commissioning, completion and production support. That is a different supplier set from the construction phase and it is bought locally through OMV Petrom in Bucharest rather than through OMV in Vienna. OMV holds 51.2 percent of OMV Petrom. Emma Delaney became OMV chief executive on 1 September.
Nigeria
Third Subsea7 extension in five weeks
STATUS:
Subsea7 took its third Sakarya extension inside five weeks in September, working inside an alliance with Saipem. None of the three extensions went through a competitive event. The field is Türkiye's largest gas development and scope is being added to existing holders rather than tendered. Suppliers looking for Sakarya work should approach the alliance members directly for sub supply.
07
Namibia
● Awarded: more than 450 wells
SLB will deliver more than 450 wells for Saudi Aramco under three year contracts, the largest well commitment GEN Intel has recorded this year. It was awarded while Hormuz flows remain constrained and the East West pipeline recovers from drone damage on 10 September, which shows Aramco is fixing capacity for the long term. The sub supply structure is set in the first quarter after award and then held for the term.
08
09
Colombia
Ima Gas Development: OML 112 and 117, Bonny Island
Venus and Mopane: Orange Basin
Sirius Gas Hub: Block GUA OFF 0, Caribbean
OPERATOR: TotalEnergies (40%, operator) / AMNI (60%)
OPERATOR: TotalEnergies (operator of PEL 56 and PEL 83)
OPERATOR: Petrobras (44.44%, operator) / Ecopetrol
EST. VALUE: About $1.1bn development cost
EST. VALUE: $10bn or more
EST. VALUE: Multi billion Third discovery confirmed: development advancing STATUS:
STATUS:
FID CONFIRMED 23 Sep 2026: first gas 2028
A single shallow water platform connected by a 22km pipeline to Nigeria LNG, with a plateau of 350 MMcfd, more than 60,000 boe per day. AMNI puts gross reserves at about 1.28 Tcf of non associated gas. Ima will supply about a third of the gas for Nigeria LNG Train 7, which lifts capacity from 22 to 30 mtpa. Shore power, no flaring and permanent methane monitoring. All key contractors will be Nigerian companies.
Thailand
STATUS:
Venus FID awaited: Mopane appraisal starting
TotalEnergies completed its 40 percent operated stake in PEL 83 from Galp in early September and now operates both of Namibia's largest discoveries. A three well Mopane appraisal campaign starts in the second half of 2026, with a Mopane FID targeted for 2028. Venus is planned around a 160,000 bpd FPSO with subsea tiebacks. TotalEnergies has said it is ready to take FID once terms with the government are finalised.
10
(55.56%)
The Sandia 1 well, announced on 3 August in 1,251m of water about 42km offshore, confirmed gas 18km from Sirius and 9km from Copoazu. It is the third discovery in the block. The partners are advancing Sirius toward development with first gas indicated around 2029. Three finds close together make a shared development and a common export route more likely, which improves the economics for all three.
11
Malaysia
12
Australia: WA
Bussabong Gas Field Phase 1: Block G3/65, Gulf of Thailand
Petronas and PTTEP Offshore Portfolio: Transportation and Installation
Scarborough Energy Project: Offshore Western Australia
OPERATOR: PTTEP Energy Development (60%, operator)
OPERATOR: Petronas / PTTEP
OPERATOR: Woodside Energy
EST. VALUE: About RM1.8bn
EST. VALUE: $12bn
/ Valeura (40%) EST. VALUE: Not disclosed
● Awarded to Vantris: September 2026
● FID CONFIRMED 22 Sep 2026: first gas end 2028 Two wellhead platforms with 24 well slots each in
STATUS:
75 to 90m of water, tied in by a 9km, 12 inch subsea
installation work across a portfolio of Petronas and
pipeline to the Bongkot central processing platform.
PTTEP assets. It is a multi asset arrangement rather
No new processing capacity is needed. Output
than a single campaign, with Malaysian content rules
of about 30 MMcfd in 2029 rising to 40 MMcfd in
applying. With installation now held by one contractor
2030. The field is split into fault block compartments,
for the term, suppliers of vessels, fabrication and
so Phase 1 is a repeatable template and further
marine services should approach Vantris for sub
platforms are likely to follow.
supply rather than wait for individual project tenders.
STATUS:
Vantris has taken about RM1.8bn of transportation and
STATUS:
First gas achieved: first LNG cargo Q4 2026
Scarborough was 98 percent complete at the end of June, on budget, and first gas from the reservoir followed in July. The FPU has completed its umbilical and riser connections and is commissioning its topsides. The final Pluto Train 1 modification module has arrived in Karratha. Gas runs 433km to Pluto Train 2 for export, with eight initial production wells and 13 over field life. Operations and maintenance scopes are next.
WORLD PROJECTS
Powered By
Intel
26
HSE & Training
The Importance of Health and Safety in the Energy Industry By Tsvetana Paraskova
Health, safety, and environment (HSE) guidelines and their strict implementation and adherence are of crucial importance to the energy industry and its smooth functioning.
globalenergynetwork.net I October 2026
HSE & Training
T
he well-being and safety of personnel and safe and reliable operations require rigorous evaluation and management processes at corporate level. Energy companies and their supply chain partners and contractors need to manage safety and asset integrity and monitor political and geopolitical risks, environmental and reputational risks, as well as ensure as safe a working environment for their personnel as possible. Job safety analyses, hazard identification (HAZID) studies, and Hazard and Operability (HAZOP) studies are used to identify potential hazards at the earliest possible stage, evaluate risks, and have preparedness for any scenarios. The use of digital tools has jumped in recent years as companies and contractors are using drones, Internet of Things (IoT) sensors, and smart devices to assess risks and measure volumes of potentially hazardous substances at energy infrastructure sites. Companies have operations management systems to help them verify process safety or flag potential hazards. Many firms in the energy sector have started to use various forms of AI for visual analysis, operations connected with IoT applications, and digital twins, for example, to identify, assess, and mitigate potential risks, as well as to ease the work of employees. As the energy industry and energy trade flows fundamentally changed this year with the conflict in the Middle East and the disrupted passage through the Strait of Hormuz, the industry faces new challenges in bolstering the health, safety, and environment (HSE) guidelines and preparedness.
UK Health and Safety Insight The health and safety of personnel remain the foremost priority for all operators in the energy industry. The UK is no exception to this and members of the Offshore Energies UK (OEUK) are actively participating in work groups and initiatives to share lessons learned and promote good practice, the industry body said in its latest health and safety report. The report included for the second consecutive year data on wind aviation, acknowledging the increasingly integrated nature of the offshore energy sector, even though wind operations accounted for just 1.5 percent of total flying hours. Recent years have seen increasing adoption of technologies that use big data to generate new safety insights. These innovations are helping organisations identify risks and improve
safety outcomes across operations. In 2025 OEUK launched the Hydrocarbon Release Database AI Assistant that continues to unlock insights from otherwise unstructured data, the association said in its report. The latest findings showed that despite decommissioning of some installations, hydrocarbon releases (HCR) remain stubbornly high. No major releases were reported in 2024, but a notable proportion of incidents are linked to aging assets. This highlights the need for robust asset integrity management, according to the OEUK. The maintenance backlog has improved significantly. A total of 60 percent of process hydrocarbon releases can be attributed to maintenance and integrity practices. This suggests that effective backlog management remains a critical process safety indicator, directly impacting the risk of incidents, OEUK’s report said. The offshore industry made considerable progress in reducing the average number of hours maintenance backlog per installation since its peak in the fourth quarter of 2021 with a total of 6,962 to a total of 2,212 at Q4 2024, a 68 percent reduction in hours. Despite these improvements, further progress is needed, OEUK noted. Another issue has emerged that many safety incidents have been associated with older assets in recent years, highlighting the challenge of maintaining integrity and safety standards as infrastructure ages. The workforce continues to face health challenges, including high blood pressure, diabetes, and increasing mental health concerns, OEUK noted. The frequency of mental health-related medevacs, while variable, remains a significant issue, the association said. Workplace stress is a contributor to poor workplace mental health, as are shift work and periods away from home and the work environment offshore, OEUK said. The population is now better informed and more aware of mental health issues, and recent campaigns to encourage people to speak up and identify concerns have been effective with stigma being reduced. OEUK continues to work to improve the quality of the OEUK medical with governance, including a new Code of Conduct for examining doctors and quality seminars, both introduced in 2025. The UK offshore sector continues to set global benchmarks for safety performance, but the latest available data reveal both progress and persistent challenges that demand ongoing vigilance and proactive management, the industry association said.
A new cross-industry safety policy is set to come into effect in the UK in November 2026. The new policy has been designed to address risks associated with emergency evacuations, rescue procedures, and lifesaving equipment. It encompasses marine rescue, lifeboat loading, stretcher rescue, helicopter transport, and confined spaces. During the transition phase, operators will continue to address these risks for all offshore personnel across every offshore installation. The decision to implement a safe weight limit for offshore workers follows extensive review by industry experts over the past few years, during which all possible alternatives to a weight restriction were thoroughly investigated. As no practical solutions were identified, a 124 kg limit will be implemented from 1 November 2026.
Global Workplace Safety Culture The oil and gas sector was the most mature industry in terms of safety culture in 2025, with strengths in hazard awareness and workforce competency, a survey by ISN, a global leader in contractor and supplier information management services, showed earlier this year. In addition, utilities showed improvement in overall safety culture maturity from 2024 to 2025, influenced by stronger frontline worker perceptions, signalling the impact of focused day-to-day engagement. The report examined macro-level trends and risk factors identified through more than 450 global safety culture assessment engagements conducted through CultureSight, ISN’s safety perception assessment. Drawing on survey data from more than 400,000 anonymous employee and contractor responses, the survey showed how safety culture maturity, leadership alignment, and psychological safety influence serious injury and fatality (SIF) risk across industries. Across all sectors, contractors had a more positive perception of their clients’ safety cultures than employees did, according to the survey. In the oil and gas industry, for example, responses from contractors put the safety culture score at 81.5. This was 1.4 points higher than the overall score in the responses of employees. ISN attributed the lower scores in the employee responses to their involvement in day-to-day operations, greater exposure to incident reporting, and heightened expectations.
27
TRAINING FOR OFFSHORE MARINE OPERATIONS DYNAMIC POSITIONING | STABILITY BALLAST CONTROL | JACK-UP OPERATIONS Photo: CADELER
THEORY WORK
EXPERIENCED INSTRUCTORS
REALISTIC SIMULATED LEARNING
PREPARE ONSHORE. PERFORM OFFSHORE. Marine training built around your business – combining specialist expertise, practical learning and bespoke solutions, with flexible delivery at ASET, remotely or at your premises.
aset.co.uk | 0300 330 5559 | asetbookings@aset.co.uk
ENQUIRE HERE
29
Thru-Tubing Systems: Seeing It Thru With Global Innovative Well Intervention Solutions For nearly three decades, Thru-Tubing Systems has helped oil and gas operators solve complex downhole challenges through innovative rigless intervention, well abandonment and thru-tubing technologies. In an industry where every well presents its own challenges, finding the right solution can mean the difference between an idle asset and a producing well. Since 1997, Thru-Tubing Systems, Inc. (TTS) has built its reputation around solving those challenges, developing proprietary tools and systems that enable operators to perform complex well interventions efficiently and, in many applications, without the need for a conventional workover rig. It is an approach captured by the company’s philosophy: “We see it thru.” Persistence, determination and innovation have been at the heart of TTS since its inception. The company specializes in rigless intervention and well abandonment, with extensive experience in slim-hole, or monobore, wells and through-tubing completions. Today, TTS offers proprietary Packer Systems, Tubing Plugs, Thru-Tubing Plugs and Sand Control Systems, providing operators and service companies with technologies designed to address a wide variety of downhole conditions. Behind those products is more than 250 years of combined experience in well completions and interventions. That depth of knowledge allows TTS to develop equipment around the realities encountered in the field while providing customers with practical technical guidance and cost-efficient solutions.
Innovation Driven by Experience Innovation has remained a defining characteristic of TTS throughout its history. With 13 patents and counting, the company continues to develop new tools and processes for oil and gas operators around the world. Its focus on proprietary technology has helped TTS establish a strong presence in the global Intervention and Plug & Abandonment (P&A) marketplace. The benefits can be particularly significant when rigless intervention is possible. Conventional workover operations may
require substantial equipment, personnel and logistics. TTS technologies provide operators with alternatives for addressing certain downhole challenges through existing tubing and completion configurations, creating opportunities to reduce intervention costs and improve operational efficiency. Those capabilities can be especially valuable for operators managing mature assets and idle wells. With the right intervention strategy, wells that might otherwise remain offline can be evaluated for remediation and potentially returned to production.
Quality From Design to Deployment In well intervention, innovation must also be supported by quality and reliability. TTS’s Quality Management System has been audited by the American Petroleum Institute (API) and validated as meeting the requirements of API Specification Q1, 9th Edition, including design and development. TTS holds API Specification Q1 Registration No. Q1-4872. The company has also received a Certificate of Authority to apply the API 11D1 Monogram to its packers and plugs and holds ISO 9001:2015 certification. That focus on quality continues beyond manufacturing. TTS provides training for employees as well as service companies utilizing its products. Training can be conducted at TTS facilities or customer locations, and complete product documentation accompanies each sale. This emphasis on knowledge transfer helps ensure TTS technologies are properly understood and successfully deployed in the field.
Safety and Responsibility TTS also maintains a strong commitment to health, safety and environmental responsibility. The company’s goal is simple: everyone who works at TTS should return home safely every day. Safety is considered both a responsibility to employees and an essential component of the company’s long-term success and relationships with customers.
CONVENTIONAL MONO-BORE Vent Screen Gravel Pack with Cement Cap Isolation
Vent Screen Gravel Pack with Packer Isolation
TTS also seeks continuous improvement in reducing its environmental impact through energy and water conservation, responsible use of natural resources, waste reduction, recycling and reducing the use of toxic materials.
A Growing Global Footprint Nearly three decades after its founding, the reach of TTS extends well beyond its beginnings. The company’s technologies and services have now been deployed in 33 countries, with more than 3,200 service projects completed and over 12,500 products sold and installed. Thousands of projects have been performed directly by TTS personnel, while thousands more have been completed by third-party service companies utilizing TTS products. That combination of field experience, trained service partners and proprietary technology has allowed TTS to support operators across a diverse range of producing regions. Looking ahead, TTS plans to continue strengthening its position in rigless intervention, well abandonment, thru-tubing and completion technologies through product development, technical expertise and close collaboration with its customers. As fields mature and operators continue seeking safer, more efficient and costeffective ways to intervene in existing wells, TTS remains focused on what it has done since 1997: developing practical solutions to difficult downhole problems.
Whatever the challenge, TTS sees it thru.
Thru-Tubing Systems, Inc. (TTS) TTS: Engineering - Innovation - Service | API Q1 certified. (Registration No. Q1-4872)
30
HSE & Training
ISO Standards Are Changing
Is Your Management System Ready? The publication of ISO 9001:2026 and ISO 14001:2026 marks an important change for organisations operating certified Quality and Environmental Management Systems.
T
hese revisions are not simply about changing clause numbers or updating the wording in your procedures. They reflect the changing environment in which businesses now operate, including increased customer expectations, climate change, resource efficiency, supply-chain pressures, leadership accountability and the need to demonstrate measurable performance. Every certified organisation will need to understand what the new requirements mean, assess the impact on its existing management system and prepare for transition.
That does not mean starting again. A well-designed management system should evolve with your organisation. The transition is an opportunity to review what is working, remove unnecessary complexity and ensure your system continues to support the way your business actually operates.
globalenergynetwork.net I October 2026
At QHSE Aberdeen, we can help you understand not only what has changed, but why it has changed and how it applies to your organisation.
Our experienced Lead Auditors can provide: • ISO 9001:2026 and ISO 14001:2026 gap analyses • Management system reviews and transition planning • Practical support to update policies, processes and documentation • Internal audits and certificationreadiness reviews • Ongoing advisory or fractional QHSE support • Training for managers, internal auditors and employees We believe that management systems should add value—not create paperwork for the sake of it. Our approach is practical, proportionate and tailored to the size, risks and objectives of each organisation.
Build Knowledge Within Your Own Team Successful transition depends on more than updating documents. Your people need to understand the changes, how they affect their responsibilities and how the revised standards can support better decisionmaking and continual improvement. Our focused half-day transition courses provide a clear and practical overview of the changes to ISO 9001 and ISO 14001. Courses are available throughout the year, or we can come to your premises and deliver tailored transition training directly to your team. We also provide public and in-house CQI and IRCA Certified auditor courses, helping organisations build lasting knowledge and auditing capability within their own workforce. As a consultancy certified to ISO 9001, ISO 14001 and ISO 45001, we practise what we preach. Our Advisors are experienced Lead Auditors who understand the standards from both an operational and auditing perspective. Don’t wait until your next external audit to discover what needs to change. Start preparing now and turn the transition into an opportunity to build a simpler, stronger and more effective management system. Speak to QHSE Aberdeen about transition support or team training.
HSE & Training
Under one roof: two Perth specialists close the gap in hazardous area compliance Haztech Solutions and MOXI HA Services have co-located in Osborne Park, bringing EEHA training, inspection and rectification into a single relationship.
H
azardous area compliance in Australian industry rarely fails for want of effort. It fails at the joins.
On a typical site, one company delivers the EEHA training. A second carries out the inspections. A third holds the electrical licence needed to close out the findings. A fourth maintains the verification dossier. Each does its part competently, and the non-conformances still carry forward from one audit to the next, because nobody owns the space between them. Haztech Solutions and MOXI HA Services have been working that problem jointly since 2025. This year the two businesses have taken the next step and co-located at Haztech’s Osborne Park facility at 18 Carbon Court. The move puts MOXI’s nationally accredited EEHA training rooms upstairs, Haztech’s Ex equipment workshop below, and the field crews of both businesses mobilising from the same yard. For a Perth operator, that means personnel can be trained and assessed, a sample of an equipment register inspected, and a rectification package scoped, in the course of a single visit.
Set end to end, the two cover the full hazardous area lifecycle — classification, competency, installation, inspection, rectification and dossier assurance — measured against the AS/NZS 60079 series and IECEx.
Why the join matters The stage most compliance stalls at is rectification. An inspection produces a register of findings, and the report then sits open while a separate contractor is scoped. By the time a crew is on site, the site has moved on and the window has closed. Between MOXI and Haztech, that gap closes: the team raising the findings and the licensed crew closing them out sit on the same contract, so rectification starts while the access and the window are still there. Both businesses continue to operate independently, and both remain available to clients separately. Nothing changes for existing clients of either business; the partnership adds capability rather than replacing arrangements already in place. The two businesses work across oil and gas, LNG, mining and mineral processing, marine and shipyard, and utilities infrastructure: the sectors where hazardous area classification, Ex equipment and verification dossiers are a standing regulatory obligation rather than an occasional project requirement. Both businesses are offering a complimentary hazardous area coverage review: a short assessment of an operator’s current position across classification, competency, inspection and dossier, and a plain read on where the weakest link sits.
What each business brings MOXI HA Services operates as a Registered Training Organisation (RTO 51160). Alongside accredited EEHA training and verification of competency, MOXI delivers hazardous area classification, design review, and dossier build and audit support. Its delivery footprint covers Perth, Queensland, New Zealand, Singapore, Malaysia and South Korea. Haztech Solutions provides the field capability: EEHA inspection crews, electrical and instrumentation construction and maintenance, QA/QC, and technical secondment into client teams. Haztech’s’ head office operates from Perth, with national and international scope.
Transforming bold visions into safer, intelligent realities www.haztechsolutions.com.au
31
32
HSE & Training
globalenergynetwork.net I October 2026
33
It went in the record as a cut. It was a crush. Paul Harris helped write the world's first performance standard for back-of-hand impact protection. He argues the hand injury most common in energy operations is still being recorded as something else entirely, and still being protected against with the wrong glove. In 2017, Paul Harris sat on the small ISEA working committee that created ANSI/ISEA 138, the first performance standard written for back-of-hand impact protection. He is now Vice President of Research and Development at Mechanix Wear. His argument is not that hand protection failed. It is that many of these injuries were never what the record said they were.
The grape Harris came to that committee with field data from prior work with one of the largest operators in global oil and gas. What it showed was not what the industry assumed. “The majority of the injuries were related to pinch and crush in the fingers, getting caught between heavy gauge steel pipes and equipment,” says Harris. “It was described to us as similar to squeezing a grape until it bursts open.” When a finger is crushed between two surfaces the skin bursts. The wound presents as an open laceration and goes into the record as a cut. “Many of these incidents were recorded as cuts due to the burst,” says Harris, “but in actuality a cut liner would not prevent this from happening.” An operator reviewing their own injury data sees cuts, and responds rationally by specifying higher cut protection. The hazard was compression, which a cut liner does not address at any rating. Their data keeps pointing at the wrong answer, and every review cycle confirms it.
What the standard changed The committee consulted a leading hand surgeon on the energy loads behind the injuries reaching his emergency room, and tested the gloves then on sale. “We found that some were actually magnifying the impact force transmitted to the wearer’s hand, versus protecting them,” says Harris. ANSI/ISEA 138 was drafted on that evidence and adopted in 2019. Where the impact marking under EN 388 is a single pass or fail awarded on the knuckles, ANSI/ISEA 138 tests the fingers too, and classifies a glove on whichever region performs worse. It grades what reaches the hand across three levels: Level 1 at or below 9 kilonewtons, Level 2 at or below 6.5, Level 3 at or below 4. The two answer different questions. EN 388 confirms a glove has cleared a threshold. ANSI/ISEA 138 says by how much, and on the part of the hand most often caught. Nothing stops a UK safety manager asking a supplier for both, and the answer is informative either way. Harris is careful about what that is worth. A standard has to be repeatable, so it has to be narrow. One mass, one energy, one fresh glove, one temperature. “A standard establishes the floor,” he says. “It was never intended to be a design brief.”
The part nobody solved Over 35 years, he says, the pattern holds: fit, feel, function and comfort decide whether a glove stays on a hand. Protection that gets removed protects nothing.
When impact gloves took off around 2010, manufacturers reached for solid slabs across the back of the hand, Mechanix Wear included. They restricted movement and pulled tight whenever the wearer closed a fist. Around 2016 the industry cut segmentation into them. Flexibility improved. The tightness did not. “For the most part,” says Harris, “these designs have not evolved much in the last ten years.” Readers can test that in two seconds. Put on the impact gloves your teams are issued and close your fist. “The skin is the largest organ of the human body,” says Harris. “Your elbow moves without restriction or binding, no matter the bend angle, no matter the movement underneath your skin. We started asking why dorsal impact protection does not do that.” He will not go further than that, and says so plainly. The standard he helped write tells a safety manager that a glove has cleared the floor. What it cannot tell them is whether anyone designed that glove for the task their people are actually doing, or whether the injury in their records is the injury that happened. Paul Harris is Vice President of Research and Development at Mechanix Wear and served on the ISEA working committee that developed ANSI/ISEA 138. Paul has 30 years' experience in the glove, eyewear and garment PPE.
Mechanix Wear designs and manufactures performance hand protection for industrial, energy and utility applications globally.
www.b2b.mechanix.com
34
HSE & Training
Bringing People Home Safely: Managing a Globally Mobile Workforce The offshore industry has transformed how it monitors assets, equipment and operational risk. Similar advances are taking place across hazardous, highly regulated onshore environments, such as renewable turbine farms and nuclear facilities. Yet, amid all these challenges and changes to the sector, bringing people home safely to their families is undoubtedly the single most important thing the sector can do.
T
he Health & Safety aspects of minimum manning requirements, site specific emergency response, equipment specific knowledge and team competence are difficult to manage - and carry large human and operational costs when things go wrong. Fines, suspended operations, lost chargeable days, cancelled jobs, lost contracts, injuries and fatalities can all have devastating impacts. As globally mobile workforces become more complex, the need for agile, scalable solutions that provide safe, efficient answers to complicated logistics has never been greater.
Managing Workforce Complexity at Scale Deploying thousands of people across multiple locations presents significant challenges. Workforce movements, personnel, training, accommodation, travel, shifts, and site requirements all need to be coordinated and monitored. Gaps in certification can create operational headaches and can lead to delayed mobilisation, and changes to shift patterns, often making it difficult to keep everyone informed. Crucially, organisations need to account for every member of personnel and ensure their safety.
Managing training, certifications, visas, taxation requirements, travel arrangements and working patterns across various sites and sectors can create significant administrative issues. If this information is managed manually, there is a greater scope for human error.
By connecting workforce information with mobilisation and travel planning, organisations can respond more effectively when schedules change or disruptions occur. This can help teams react quickly to changes in shifts, travel and accommodation arrangements.
A connected source of workforce information empowers organisations to make decisions based on the most up-todate data. They can identify an individual with the required competency for a role, establish who is on site, and adjust travel and accommodation arrangements when a shift changes.
In an emergency, immediate access to accurate personnel information is especially important. Knowing who is on site, where they are expected to be and how to contact them enables organisations to respond appropriately.
Workforce data is more than an administrative resource. It gives organisations the visibility they need to manage people safely and respond effectively when plans change.
Keeping Pace with a Moving Workforce Built, developed and based in Aberdeen, Onboard Tracker is a crew management platform that supports industries across the energy, renewables and marine sectors. Since its launch in 2012, the platform has grown to track over 160,000 personnel, over 120 countries, across more than 11,000 on and offshore sites.
Why Accurate Workforce Data Matters
The platform brings together key workforce information in a single connected system, providing greater visibility across competence and certification, mobilisation, personnel-on-board (POB) information, travel and other workforce requirements. Crucially, this information does not sit in isolation. Onboard Tracker cross-checks planning and scheduling against the training, certification and competence requirements associated with the individual’s occupation, client and site.
Accurate data supports safe planning, travel and accommodation arrangements and emergency response, and its importance becomes particularly clear when circumstances change unexpectedly. Transport disruption, weather delays, operational incidents and schedule changes can quickly affect plans, making an up-to-date view of where people are, what arrangements are in place and what needs to happen next essential.
This gives teams a real-time, traffic-light view of mobilisation readiness, allowing them to see whether an individual meets the requirements for a particular assignment and highlighting potential gaps before they mobilise. By bringing these different data points together, organisations can help ensure that only appropriately trained, certified and competent personnel are mobilised to the job, strengthening both compliance and workforce safety.
Coordinating these moving parts becomes harder when records sit across disconnected systems and spreadsheets. Time-consuming administrative tasks can place additional pressure on already stretched teams.
globalenergynetwork.net I October 2026
Delivering the future of crew management. onboardtracker.com
The key to its success is Onboard Tracker’s constant drive to enhance the platform and remain in step with evolving customer needs. The latest module development, Timewriting, was developed following feedback from users at OnboardXchange 2025, Onboard Tracker’s annual super user forum and introduced in August to simplify workforce time capture. Because Onboard Tracker already holds information on scheduled movements, jobs and assignments, the platform can use that existing data to pre-populate up to 90% of a worker’s timesheet, leaving users simply to review, amend and submit. Across a large workforce, the time spent completing, checking and chasing timesheets can quickly become a significant administrative burden. Automating much of that process gives valuable time back to operational teams, allowing them to focus their attention on higher-priority activities that support the safety and efficient delivery of projects.
Complex Operations Require Clarity Digitalising workforce management does not remove the complexity of offshore operations. It gives organisations the information and oversight needed to manage it more effectively. Clear visibility of people’s competencies, locations, movements and requirements enables safer, more informed decisions at every stage of the workforce lifecycle. Ultimately, behind every workforce plan, mobilisation schedule and compliance record is an individual. For the organisations responsible for them, the priority must always be to help people carry out their work safely and return home to their families.
35
Built-in, Not Bolt-on The race to adopt Artificial Intelligence (AI) has led almost every technology vendor to incorporate AI into their product offering, however in many cases the result is an add-on chatbot that sits alongside existing software that otherwise works much as it did before, rather than fundamentally transforming how the software operates or the value it delivers.
W
hen it comes to Asset Integrity management, the consideration from integrity professionals is not solely whether a platform includes AI, more so what information the AI can access, what tasks it can support and whether its outputs can be trusted in support of the integrity assurance decision making process. These AI considerations are becoming increasingly significant as asset owners and operators continue to manage growing volumes of integrity data in support of regulatory compliance, which can make finding the right information at the right time challenging for the system users.
So, what’s the solution? In our case it’s TEQ. Integrated directly within ENGAGE, CAN Group’s cloud-based asset integrity management platform, TEQ is an agentic capable AI that works with live inspection and anomaly data under the same permissions and audit controls as the integrity and engineering professionals using it. It gives immediate access to the information they need, helping them move from searching for data to making informed decisions more quickly.
Why the data model comes first ENGAGE was built around a simple principle: asset integrity management is fundamentally a data challenge. Inspection records, anomalies, corrosion monitoring, work scopes, deferrals and fabric maintenance only become truly valuable when they are structured in a way so that relationships remain clear throughout an asset’s life. Which anomalies belong to a particular circuit? Which inspections resulted in specific actions? Who did what? This underlying structure is not always visible to the end user, but a strong logical data schema is what enables more effective use of AI-powered tools. A language model pointed at a collection of documents can summarise information,
however the same technology working within a structured integrity dataset can help answer practical operational questions such as; which anomalies have exceeded their target dates? Where are my red flags or warnings in my data? Can a summary of upcoming work be prepared from existing records? This is where TEQ excels. Users can ask TEQ a question and receive a consolidated response drawn directly from their own live integrity data. The ability to rapidly aggregate outstanding anomaly actions, understand the inventory history, review inspection trends or assess outstanding integrity risks which can all directly influence the quality and speed of key engineering decisions.
Agentic, not conversational Many AI solutions act as conversational assistants to respond to questions. An ‘agentic’ capability can carry out tasks within a system, bringing together information from different modules, assembling outputs and highlighting areas that may require attention. In an asset integrity environment, that means less time searching for information and more time assessing risk and determining appropriate actions. TEQ has been designed with this approach in mind – to do more. Working directly within ENGAGE, it pulls together information from across the platform to support engineers with real operational tasks. Whether preparing for an integrity review, planning inspection activity or assessing outstanding risk, TEQ gathers the latest overdue actions, open anomalies and recent inspection findings for a specific asset, rather than simply directing the user to the relevant screens. This helps engineers spend less time compiling information and more time applying their expertise and knowledge where it matters most – assessing and decision-making. Two principles underpin its design. First, TEQ operates within existing user permissions and can only access information available to the individual using it. Second, it does not make integrity decisions. It has been designed to support engineers, not replace them. Anomaly assessments, deferral justifications and
fitness-for-service judgements remain the responsibility of qualified engineers. Its role is to reduce the time spent gathering and organising information by providing faster access to trusted data, so that engineers can focus on assessment and decision-making.
A platform, not a feature TEQ is more than an AI add-on. It forms part of CAN Group’s broader ENGAGE development programme, with the roadmap extending into areas such as reporting, work pack management and field data capture. The introduction of TEQ reflects the maturity of the platform and the structure of the data it manages. For organisations managing late-life assets, contractor transitions or geographically dispersed portfolios, the benefit is consistency. Integrity data can be structured once, maintained within a single system and accessed by authorised personnel wherever they are located. CAN Group delivers asset integrity projects and solutions across multiple regions worldwide, through its strategic locations in the UK, North America and West Africa. This global footprint ensures that ENGAGE can be supported by experienced asset integrity teams across international regions.
Delivering Excellence Over the coming years, the industry is likely to distinguish between AI capabilities that are effective in demonstrations and those that deliver value in day-to-day operations. In asset integrity management, that difference often comes down to data quality, traceability and trust. AI can only work with the information it is given, which means the foundations matter. Wellstructured data creates context, consistency and confidence in the outputs generated. ENGAGE was built on that principle from the outset. TEQ is a practical extension of that foundation, helping engineers access and use the information they already hold more effectively. It supports CAN Group’s goal of delivering asset integrity excellence: making informed decisions that protect people, extend asset life and maintain safe, reliable operations.
To find out more about how ENGAGE connects asset data with integrity decisions, visit www.engagecloud.net
36
HSE & Training
globalenergynetwork.net I October 2026
HSE & Training
37
MAKING AND MAINTAINING THE RIGHT CONNECTION
WHAT WE DO Destec Engineering has specialised in the manufacture of high pressure Flanges, Seals & Connectors for the Oil, Gas & Renewable Energy Industries for over 50 years.
❱ ON-SITE MACHINING ❱ BOLT TENSIONING ❱ SPECIAL PURPOSE MACHINE TOOLS ❱ LASER ALIGNMENT SERVICES ❱ NDT SERVICES ❱ REGENERATOR & VESSEL HEAD REMOVAL
OUR PRODUCTS ❱ G-RANGE CLAMP CONNECTOR ❱ COMPACT FLANGES ❱ DOOR CLOSURES ❱ SEAL RINGS ❱ BOILER INSPECTION CAPS ❱ SUBSEA SINGLE BOLT CLAMP CONNECTION sales@destec.co.uk
CE WWW.DESTEC.CO.UK Q D
HSE & Training
39
Where Technical Excellence Meets Commercial Edge Across energy, construction, manufacturing and beyond, strong performing businesses share something beyond technical depth.
A
deliberate, practical grip on the commercial and contractual elements of their activities. It isn't a separate skill bolted onto good engineering. It's the other half of it.
Alongside it sits a dedicated Negotiating Value Across Supply Chains workshop, built for anyone who negotiates with customers, suppliers or partners, whatever their job title.
Paratus Commercial Services, founded by Steve Johnson, exists to build that edge. Steve's own background spans operational and leadership roles across SMEs, multinationals and Tier 1 contractors, and Paratus works with organisations across that same range, in energy and equally in any other sector that buys, sells, negotiates or contracts.
Beyond training, Paratus provides interim and fractional commercial leadership for businesses bridging a recruitment gap, scaling through change, or developing a successor into a senior role. It also runs structured, facilitated sessions for contractual and operational lessons learned, plus tendering and bid planning sessions for customers and suppliers preparing to compete or procure with confidence.
At its core is the ECITB accredited Commercial and Contracts Awareness & Risk workshop (Training Standard TS PC02-02), delivered publicly or in-house, at a venue of the client’s choosing, including globally. It has already given over 150 delegates, from engineers and project managers to procurement and operations professionals, a practical, jargon-free grounding in commercial risk and contract fundamentals.
Steve Johnson, Director, Paratus Commercial Services Limited
Paratus also helps develop practical processes, procedures and templates that hold operational performance and commercial governance in genuine balance. Every engagement is shaped around the client's own contracts, risks and people. Because the return on investment that matters, is the one you can put to work immediately.
steve@paratuscommercial.com www.paratuscommercial.com
From Inspection Data to Future Insight: The Results Behind Project c|Ai|sson How accurately can the future condition of an offshore asset be predicted?
A
ISUS recently set out to answer that question through Project c|Ai|sson, an in-house developed AI platform designed to forecast asset degradation using existing inspection data. While inspections provide a snapshot of condition at a specific point in time, Project c|Ai|sson is focused on what happens next, helping operators understand how corrosion and deterioration are likely to develop before the next inspection takes place. To validate the technology, AISUS conducted a blind trial on a North Sea caisson. Using inspection data collected in 2014 and 2019, the team generated a prediction of the asset's condition in 2023 without access to any of the actual 2023 inspection results. When the latest inspection data was revealed, the prediction was compared against measured condition across more than 20,600 individual locations on the asset. The results showed a strong match between the forecast and the real inspection findings. On average, the difference
between predicted and actual condition was just 0.25 mm, thinner than a credit card, while 98% of locations were predicted to within 1 mm of the measured result. The project has been developed by AISUS' dedicated Data & AI team through a longstanding Knowledge Transfer Partnership with Robert Gordon University. The collaboration has brought together offshore engineering expertise, artificial intelligence and data science, helping transform research into a practical solution for industry. Building on the programme's success, AISUS is now recruiting its fourth KTP Associate to continue advancing predictive corrosion and asset risk-ranking technologies. For operators managing ageing infrastructure, the significance is clear. Rather than relying solely on periodic inspections to understand asset condition, Project c|Ai|sson demonstrates how historic inspection data can be used to provide credible, evidence-based insight into what lies ahead.
For more information visit www.aisus.co.uk
40
Legal
Class actions and energy in Scotland: what does an opt-out future mean for the sector? Scotland’s energy sector is no stranger to high-value, high-profile disputes, but to date these have primarily been amongst commercial enterprises, regulators and public sector bodies, with limited scope for US-style class actions in this jurisdiction.
Fiona Chute and Craig Watt Brodies LLP
R
eform could be on the horizon thanks to proposals that would allow group proceedings to be brought on an ‘opt-out’ basis, exposing energy businesses to potentially much larger claimant groups and higher value claims.
In Scotland the ability to raise class actions (or group proceedings as they are known here) was only introduced in 2020, and only on an ‘opt-in’ basis. With the number of class actions rising rapidly around the world, and Scotland now actively considering a move to ‘opt-out’ procedure, what does this mean for Scotland's energy sector?
What are class actions and who can bring them? Class actions are claims where two or more parties collectively raise a claim in a single action. Those parties could be individuals or businesses but must have suffered a loss in the same or, at least, a similar way. They are usually raised against large businesses, with claimants seeking financial payments for alleged wrongdoing, with examples in recent years including claims for product defects, misleading advertising, environmental claims, competition law claims and securities litigation.
What is the difference between 'opt-in' and 'opt-out' procedure? For class actions brought under 'opt-out' procedure, all individuals and businesses who meet the relevant criteria to fit into that 'class' are automatically entitled to compensation if the claim is successful. They do not require to actively 'sign up' but can 'opt out' of receiving compensation. 'Opt-out' class actions are available in a number of countries such as the US, and in the UK for 'competition' claims. In Scotland, actions can currently only be brought by way of 'opt-in' procedure which requires claimants to actively sign up to be part of the claim. However, in October 2025, a working group established by the Scottish Civil Justice Council (SCJC) launched a formal Call for Evidence on whether an ‘opt-out’ procedure should be introduced. Responses revealed a divergence of opinion between those who argue that ‘opt-out’ procedure would close a gap in access to justice, particularly for individuals whose losses are too small to justify pursuing a claim on their own, and those who argue that it could encourage speculative litigation and increase costs. The SCJC has since indicated that a formal public consultation will be needed before final decisions are taken on any new court rules.
What impact would introducing 'opt out' procedure to Scotland have on Scotland's energy sector? Simply put, without the need to actively sign up, it is likely that 'opt out' procedure will result in larger claimant groups and higher overall payouts. Moreover, obtaining funding for class actions is easier the higher the potential end payout. As such, there is a risk that the introduction of 'opt-out' procedure in Scotland could entice litigation funders and law firms to raise more class actions which would otherwise be difficult to pursue due to low engagement. More funders may move into the Scottish market, potentially with the energy sector in their sights. Press reports suggest that some plaintiff law firms have already gathered groups of small businesses (SMEs) together and have launched a class action in England in relation to alleged "secret commissions" paid to brokers for introducing SME's to energy companies, with the sum sought currently estimated at £25m. They may also have a keen eye on potential class actions on behalf of consumers for alleged overcharging or arising from service interruptions. One could also envisage the 'opt out' procedure being used where downstream operations result in environmental issues. Multi-million-pound claims remain a real risk for many businesses in Scotland under an 'opt in' procedure. Whilst the multi-billiondollar pay-outs that have been seen in the US may seem a world away, they would become closer with the introduction of an 'opt out' procedure. Energy companies would be well advised to start assessing their exposure now, rather than waiting for the rules to change.
Read Brodies’ report ‘Evolution not revolution: Investing in the energy transition’ at
globalenergynetwork.net I October 2026
brodies.com/energy-transition
Innovation & Technology SPONSORED BY
The UK’s largest innovation funding consultancy Leyton is an international consulting firm that helps businesses leverage financial non-dilutive incentives to accelerate their growth and achieve long lasting performance. We simplify your access to these complex incentives. Our combined teams of highly skilled Tax and Technical specialists, enhanced with cutting-edge digital tools developed internally, maximise the financial benefits for any type of business.
LEYTON.COM
Managing Technological Risks in the Rapidly Evolving Energy Industry The rapid pace of technological innovation has transformed the energy industry, offering tremendous potential for growth, sustainability, and improved efficiency.
T
hese innovations include the widespread adoption of renewable energy sources like solar, wind, hydro, and geothermal power, the integration of smart grid technology, advanced batteries, and advanced data analytics to provide valuable insights into energy production and maintenance. These are just examples of a wide range of novel solutions which can revolutionise the industry. However, it is crucial to effectively manage the associated technological risks, such as ensuring cybersecurity, protecting critical infrastructure, and addressing potential challenges related to the integration of these innovative technologies. These steps are essential for a smooth transition and successful integration of these advancements into the energy landscape. Integrating new technologies, such as renewable energy solutions and smart grids, into existing energy infrastructure poses significant challenges. Issues of compatibility, operational disruptions, and unforeseen complications often arise during the implementation phase. However, since the energy industry relies heavily on complex, interconnected systems that encompass a variety of technologies, equipment, and software applications this task is far from being straightforward. A failure or malfunction in one part of the system can have cascading effects, leading to operational disruptions, or even safety incidents. To mitigate these risks, energy companies must proactively identify and manage their technological dependencies by implementing backup systems, redundancies, and robust maintenance and monitoring procedures. As such, effective risk management requires thorough planning, pilot projects, and close collaboration with technology providers to ensure smooth integration and minimize potential disruptions. Nevertheless, the fast pace of technological advancements adds to these challenges, making it difficult for
Author: Mariusz Kucharek PhD R&D Manager, Leyton UK
companies to stay ahead. Investing in cutting-edge technologies can be risky, as there is always the possibility that a chosen solution may quickly become obsolete. To navigate this uncertainty, energy companies need to carefully evaluate emerging technologies, conduct comprehensive cost-benefit analyses, continuously monitor industry trends, and collaborate with research institutions and technology providers to remain at the forefront of innovation. Additionally, with the increasing reliance on digital systems, the energy industry is more exposed to cyber threats. Hackers and cybercriminals pose a significant risk to the industry’s critical infrastructure, including power grids, control systems, and data networks. Combined with the increase in the amounts of data the energy industry generates, through the use of novel sensor data, customer information, and operational records, this represents a complex task. All stakeholders in the energy sector must invest in robust cybersecurity measures to protect against cyber-attacks and potential cyber threats. Regular audits, employee training, network monitoring, and incident response plans are essential to safeguard critical infrastructure. Additionally, effectively managing the data generated by the industry presents its own set of risks. Ensuring data security, privacy compliance, and maintaining data quality are important aspects within the technological risk landscape. Robust data governance frameworks, data protection measures, and data analytics capabilities are necessary to minimize data-related risks and optimize the value derived from data assets. Ensuring effective management of technological risks is crucial for the energy industry to take advantage of the benefits offered by technological advancements. This often requires extensive research and development efforts. This includes evaluating
emerging technologies, assessing their feasibility and performance, and addressing integration challenges and compatibility issues. R&D efforts might also focus on developing robust cybersecurity measures, predictive maintenance technologies, and advanced energy storage solutions. By investing in R&D, the energy industry can effectively manage and mitigate technological risks while driving innovation and ensuring a reliable and resilient energy supply. The United Kingdom is at the forefront of advancements in the energy industry, particularly when it comes to mitigating technological risks. The country has made significant investments in research and development, establishing itself as a hub for innovation in renewable energy, smart grids, and energy storage. These investments have not only brought economic benefits but have also contributed to reducing carbon emissions and promoting sustainable development. The UK government has implemented various initiatives to support these advancements, including funding programs, grants, and collaborations with industry and academic organisations. These initiatives aim to encourage the adoption of emerging technologies and promote cybersecurity measures. To support these efforts, companies engaged in pioneering projects can explore the potential benefits of funding schemes such as HMRC’s R&D Tax Relief Scheme. This scheme provides financial incentives for companies investing in research and development activities. Leyton, a renowned innovation funding leader, offers expert guidance and support to help firms secure financial backing for their research and development initiatives. Leveraging Leyton’s extensive experience ensures that companies can confidently apply for R&D funding, maximising the rewards for their innovative endeavours.
For more information visit: leyton.com
41
Innovation People &on Technology the Move People on the Move
43
Appointments, promotions and industry moves across the global energy sector this month
UK & EUROPE ConocoPhillips
Ryan Lance Moves to Executive Chair
3T
Douglas Stewart as Group Chief Financial Officer (CFO) & Rachid Lakhdar as
Closes 14 years as president and chief executive and a 42-year career with the company. The longest-serving chief executive at a major oil company. Oversaw the 2012 strategic repositioning and the $38 billion Anadarko acquisition.
Managing Director of its MENA region training operations. The appointments come as 3t accelerates its next phase of growth, building on its established position in energy sector
Scottish Renewables
GB Energy (UK)
Susie Lind Chair Finley Becks-Phelps appointed to the board
Dan McGrail
As the organisation rebuilds its leadership following Claire Mack's departure earlier in 2026.
Helmerich and Payne
Todd Scruggs Senior Vice President and Chief Financial Officer Effective 1 July. Currently Vice President Corporate Finance and Treasury.
Chief Executive of RenewableUK, seconded as interim Chief Executive of GB Energy for six months. Based in Aberdeen at GB Energy's Scottish headquarters. Recruitment for the permanent CEO began in the same announcement.
Venterra Group
Philippe Kavafyan Chief Executive Officer For offshore wind energy, taking the role effective 16 October.
DNV
J+S Subsea
Joshua Clover
Scott Lee
Country Manager for the Americas,
Business Development Manager
Industrial Services division, adding senior regional leadership to one of the world's largest independent assurance and risk management providers serving the energy and maritime sectors.
J+S Subsea has welcomed Scott Lee to the team as Business Development Manager, strengthening the company’s business development capability as it continues to grow its client base and presence across the subsea and offshore energy sectors.
africa
NORTH aMERICa Chappal Energies
Gulfport Energy
Michael Humphries
John Reinhart
Interim Chief Executive Officer
President, Chief Executive Officer and Director,
With immediate effect, as the Nigerian upstream company progresses development of its domestic portfolio.
Elected to depart the company and resigned from the board with immediate effect. Domenic Dell'Osso Jr. confirmed as his successor, effective 28 May 2026.
aSIa
aUSTRaLaSIa Chevron Bangladesh
Shu Xiong President and Managing Director Succeeds Eric Walker, who served in the role for six years.
The Next GEN of Media
Victoria, Australia
Jaclyn Symes Minister for Energy and Climate Taking the Victorian portfolio at a time when the state is accelerating its renewable build-out and managing the east coast gas supply challenge.
The full weekly appointments digest is available every Thursday via The Wire, part of the GEN Intel report suite at www.globalenergynetwork.net
44
Clean Energy
Clean Energy sponsored by:
Over 30 years of delivering innovative subsea excavation and trenching solutions for the oil & gas, renewables, decommissioning, and wider energy sectors. www.rotech.co.uk
Global round up, September 2026 THE MONTH IN CONTEXT
Crisis accelerates the transition: clean energy takes two thirds of global investment The six weeks to 28 September 2026 confirmed that the Iran war and Hormuz crisis are accelerating the energy transition. Global clean energy investment is on track for $2.3 trillion in 2026, two thirds of the IEA's $3.4 trillion total.
O
ffshore wind delivered key milestones. Germany inaugurated He Dreiht, its largest operational offshore project, and Gennaker secured more than EUR 3 billion at financial close, the largest Baltic Sea project to date. South Korea's auction drew double the capacity offered, and UK AR8 results are due before year end, following AR7's record 8.4GW.
In floating wind, China Three Gorges installed a 16MW platform off Guangdong, the largest single-unit floating turbine, and SeaTwirl and Hunter Floating Offshore Wind agreed a five-year programme off Newcastle, NSW, for Australia's first demonstration. Solar-plus-storage attracted record firsthalf investment, with US state markets offsetting federal headwinds. The Trump administration's offshore wind buyouts have cost nearly $2 billion in compensation to developers including TotalEnergies and RWE, and a New York-led state coalition is challenging them in court. Capital, sub-federal policy and technology momentum are enough to sustain growth whatever oil prices do. The supply chain's job is execution.
EUROPE The 960MW He Dreiht offshore wind farm was inaugurated in the German North Sea, with 64 turbines making it Germany's largest offshore wind farm at the time of commissioning. The project marks a further step in Germany's offshore wind expansion as the country moves to reduce its dependence on gas imports following two successive years of supply crisis. 50Hertz and NEPTUN SMULDERS Offshore Renewables signed a contract for the construction of a 2GW offshore converter for the LanWin3 North Sea grid connection project, one of the largest single offshore converter scopes awarded in Europe this year. Construction of the jacket for TenneT's 2GW IJmuiden Ver Gamma offshore converter platform also began at Heerema Fabrication Group's yard in Vlissingen. Skyborn Renewables reached financial close for the 976.5MW Gennaker offshore wind farm in the German Baltic Sea, securing more than EUR 3 billion. The project will deliver 63 turbines generating approximately 3.8 TWh annually, commissioning targeted for mid-2028. Foundation, inter-array cable and installation supplier agreements have been converted to firm contracts. Orsted installed the final turbine at the 704MW Revolution Wind array off the coast of Connecticut and Rhode Island, completing what was the largest offshore wind installation programme in New England at the time of completion. The UK Allocation Round 8 application window progressed through September, with over 17 gigawatts of offshore wind capacity eligible to compete. Results are expected in the fourth quarter of 2026. The round builds on AR7's award of
globalenergynetwork.net I October 2026
Clean Energy 8.4GW at strike prices around £91 to £95 per MWh, the largest renewable energy auction in UK history. CWP Energy warned that £60 billion of private investment in Scottish onshore wind could be at risk due to restrictions on development around the Eskdalemuir seismic array, raising questions about the practical ceiling on consented capacity in Scotland's most productive wind regions.
aSIa PaCIFIC SeaTwirl and Australian company Hunter Floating Offshore Wind signed a five-year memorandum of understanding on 22 September 2026 for a proposed 20MW floating offshore wind demonstration project off Newcastle in New South Wales. HFLOW is responsible for project development, permits, stakeholder engagement, financing and grid connection. SeaTwirl will contribute its technology, a reference design and engineering support. TotalEnergies and Nextnorth completed financial close and started construction on a 440 megawatt-peak solar project in the Philippines, one of the largest solar developments in Southeast Asia, with the project expected to generate electricity for several hundred thousand households annually. China Three Gorges' installation of a 16MW floating offshore wind turbine on a semisubmersible platform 70 kilometres offshore Yangjiang in Guangdong delivered what is described as the world's largest single-unit floating wind platform. The unit generates approximately 44.65 GWh per year, at nearly three times the capacity of its predecessor at more than 50 percent lower cost per kilowatt. South Korea's first-half 2026 offshore wind auction attracted record interest, with nine projects bidding 3.6GW against approximately 1.8GW of available capacity.
aMERICaS Investors spent a record amount in the first half of 2026 on projects combining renewable energy, mostly solar, with colocated battery storage. The Rhodium Group projected renewables would be set for big growth over the next several years despite the US federal political environment, with solar and storage leading. California became the eighth US state to file a lawsuit against the Trump administration over its programme of buying out offshore wind leases and redirecting developers toward fossil fuel investment. The legal challenge covers the $1 billion payment to TotalEnergies and subsequent similar deals with other developers. The US is building substantial solar and storage capacity regardless of federal policy headwinds, with state-level targets and declining technology costs keeping the build rate high across key markets including Texas, California, Florida and the mid-Atlantic corridor. Argentina secured up to $6 billion in US financing support for its LNG programme, a decision tied directly to the energy security arguments that accelerated following the Hormuz supply crisis. Vaca Muerta gas, if commercialised at scale, represents one of the most significant non-Middle East energy supply options available to global markets.
©Слава Ли
GLOBaL The IEA's World Energy Investment 2026 report confirmed global clean energy spending is on track to reach $2.3 trillion this year, out of a total energy investment figure of $3.4 trillion, as the energy transition continues to attract capital despite short-term fossil fuel demand elevated by the Hormuz crisis. Global offshore wind capacity is on track to quadruple to 420GW by 2035, according to GWEC's 2026 Global Offshore Wind Report, with annual installations expected to double in 2026, triple by 2031 and surpass 50GW per year by 2035. More than 50GW is currently under construction worldwide. GWEC's eight-point action plan called on governments to expedite development to shield economies from future energy crises. The World Wind Energy Conference 2027 will be held in Oman, co-organised by Nama Power and Water Procurement and WWEA, with support from Oman's Ministry of Energy and Minerals, signalling the Gulf's growing engagement with the global renewables agenda.
GEN Clean Energy & Renewables SPONSORED BY:
45
46
Decommissioning
Global round up, September 2026
Dated 19 August to 28 September 2026.
THE MONTH IN CONTEXT The UK North Sea decommissioning market is running ahead of every forecast made for it five years ago. OEUK now projects decommissioning could account for more than 30 percent of all UKCS oil and gas expenditure by 2030, with the possibility of surpassing capital expenditure as early as 2028 if investment uncertainty persists. The North Sea Transition Authority's formal investigation into operators behind on inactive well plug and abandonment work has changed the tone of conversations across the basin: compliance is now a board-level matter, and operators who had been deferring late-life decisions are moving faster. The supply chain is under pressure as a result. There are not enough semi-submersible well intervention vessels globally to meet demand at the rate the NSTA is requiring, day rates in both the well intervention and heavy-lift markets have risen 8 to 15 percent annually since 2023, and booking slots run 18 to 24 months ahead. That environment rewards operators who plan early and penalises those who do not.
EUROPE aND NORTH SEa Hornbeck Offshore Services, which completed its merger with Helix Energy Solutions earlier in 2026, secured a multi-year North Sea decommissioning contract through its Helix Well Ops UK subsidiary. The contract, awarded by an undisclosed major operator, covers riserless plug and abandonment operations using either the Well Enhancer or Seawell purpose-built RWIVs. The integrated scope includes a subsea intervention lubricator well access system, ROVs, saturation diving, project management and engineering services. The firm duration is two years with customer extension options, commencing in the second quarter of 2027. Ocean Installer was awarded a sizeable contract by TotalEnergies for decommissioning work across the Byggve, Skirne and Atla fields in the North Sea. The contract is described by Moreld as sizeable, meaning between NOK 100 million and 500 million in expected value. Most of the recovered equipment will be recycled or reused. The offshore campaign is scheduled for 2027. TAQA UK awarded Allseas a major contract to decommission the Brae Alpha platform topsides in the Central North Sea, the latest milestone in one of the UK's largest ongoing decommissioning programmes. Allseas separately awarded Able Group contracts to dismantle and recycle TAQA UK's Cormorant Alpha and Tern platforms, which together represent one of the largest single decommissioning assignments ever undertaken on the UKCS.
globalenergynetwork.net I October 2026
Boskalis Subsea Services formally launched its Decommissioning Collective, a multi-operator campaign delivery model. Harbour Energy is among the first participants, with planning underway across multiple assets covering up to 3,000 days of work over the next decade. Boskalis has backed the model with more than £250 million of UK subsea capability investment. UK North Sea operators signed up to a charter for joint decommissioning campaigns, as the industry responds to NSTA pressure to increase the pace and reduce the unit cost of late-life asset removal across the basin.
47
P&A Decision 7YTTSVX 7]WXIQ
WEST aFRICa and MIDDLE EaST
aSIa PaCIFIC DeepOcean is executing a major subsea decommissioning project offshore Western Australia, including the suspension of subsea trees, removal of flowlines, umbilicals and a disconnectable turret-mooring buoy. The 2026 campaign is managed from Perth, drawing on Shelf Subsea's regional expertise and DeepOcean's North Sea decommissioning capability. ABL Group was appointed marine warranty surveyor for Australia's largest ever offshore decommissioning campaign, supporting Esso Australia's planned Gippsland Decommissioning Campaign 1 in the Bass Strait. The programme covers up to 13 offshore platforms beginning in 2027 as part of the Gippsland Basin Joint Venture's infrastructure retirement programme. ©EnerMech
C
M
Y
CM
MY
CY
DecomX
Decom Engineering and Unique Group signed a memorandum of understanding to jointly deliver integrated subsea decommissioning services across the Middle East and Asia Pacific, creating a combined capability covering well P&A, subsea infrastructure removal and material recycling across two growing decommissioning markets.
CMY
K
aMERICaS EnerMech was awarded its first major Gulf of America decommissioning campaign by ExxonMobil, covering a complete flowline decommissioning package for the Hoover Diana development. The contract marks EnerMech's entry into the Gulf of America decommissioning market and builds on the company's established North Sea decommissioning capability. CB&I is set to acquire Petrofac's Asset Solutions business, bringing 3,000 employees and a portfolio of operations, maintenance and decommissioning services under its umbrella. The deal strengthens CB&I's international footprint and diversifies its revenue beyond EPC work.
GEN VIEW The NSTA's publication of its first operator performance table and the opening of formal investigations into multiple operators for missed P&A deadlines marks a shift in how decommissioning is managed in the UK. This is no longer a cost to defer. It is a regulatory obligation with enforcement consequences. The Boskalis Decommissioning Collective and the operator charter for joint campaigns are responses to the same structural problem: individual projects are too expensive, supply chain slots are too scarce, and the basin needs a higher-volume, lower unit cost model to clear the backlog within a realistic timeframe. Watch how many additional operators join those initiatives over the next two quarters. That number will tell you more about the pace of North Sea decommissioning than any forecast. DEXS, GEN's global decommissioning conference, launches in Rotterdam in April 2027. Full programme details and delegate registration open this month at globalenergynetwork.net/dexs.
From barrier concept to ALARP proof faster, clearer, and regulator ready.
Find out more at: www.geoactive.com/decomx
DecomX
geoactive.com/decomx
48
Contracts
Global round up, September 2026 THE MONTH IN CONTEXT
© pexels-aron-razif
Westwood's mid-year count puts offshore EPC contract award value on track to close 2026 at approximately $59 billion, a 28 percent increase year on year and the highest figure since the pre-2015 supercycle. Year to date award value stands at around $43 billion, meaning the final quarter needs to deliver approximately $16 billion to meet the forecast. That is a large number but a credible one given the projects in the queue. The structural context behind those figures has changed materially since the start of the year. The Hormuz crisis wiped roughly 1.1 billion barrels from the global supply balance between late February and the signing of the peace framework in June. The immediate consequence for the contracting market has been paradoxical. Middle East award activity was disrupted in the first half but is now recovering sharply, with post-crisis infrastructure repair and accelerated development programmes driving a wave of EPCIC awards that are large even by regional standards. At the same time, Atlantic Basin producers — Norway, Brazil, West Africa, Guyana — who spent the first half of the year being asked to produce every possible barrel, have now converted that revenue into capital budget increases that are showing up in the contract books of Subsea7, TechnipFMC, Saipem and their subcontractors. The offshore market is not facing a demand problem. It is facing a capacity problem. Engineering hours, fabrication slots, installation vessel availability and project management bandwidth are all tightening simultaneously across a market that has spent a decade underinvesting in all of them. The contractors who built backlog at the top of the previous cycle and maintained engineering capability through the trough are now running at or close to capacity. The supply chain behind them is not. Lead times on long-lead items
globalenergynetwork.net I October 2026
including flexible risers, umbilicals and subsea trees are extending. Day rates for heavy lift and pipelay vessels have risen materially. The second half of 2026 will test whether the industry can deliver on its own most optimistic forecast.
EUROPE aND NORTH SEa
Vår Energi is becoming the standout Norwegian client for integrated scopes Two separate awards from the same operator in the same period tell a clear story about how Norway is moving. TechnipFMC was awarded a large integrated EPCI contract from Vår Energi covering the Ofelia and Gjøa Nord developments in the Gjøa area of the Norwegian Continental Shelf, following a five-year collaboration agreement signed in 2025. The combined Gjøa Subsea project encompasses Ofelia, Gjøa Nord and the Cerisa discoveries, with estimated recoverable resources of approximately 76 million barrels of oil equivalent. Jonathan Landes, President of TechnipFMC's Subsea division, said Vår Energi was applying a portfolio approach across the Gjøa area to reduce project cycle time and improve returns, an approach that requires deep collaboration and is directly enabled by TechnipFMC's integrated execution model. First oil from the development is targeted within two years of contract award.
Subsea7 is simultaneously working its own Vår Energi relationship from a different angle. The $150 million to $300 million Goliat Gas Export Project contract awarded to Subsea7 in May was the first project to emerge from the strategic partnership agreement between Vår Energi, Subsea7 and OneSubsea signed in March 2026. The 12.7 kilometre pipeline will route Barents Sea gas to the Hammerfest LNG facility on Melkøya through the existing Snøhvit system, a tie-back that makes commercial sense only because the infrastructure is already there. Subsea7 Vice President for Norway Erik Femsteinevik described it as a milestone demonstrating the strong foundation of trust already established between the organisations. Offshore operations are scheduled for 2027 and 2028. Separately, Subsea7 also holds the $300 million to $500 million EPCI contract for ConocoPhillips Skandinavia's Previously Produced Fields development in the Greater Ekofisk Area, covering subsea structures, umbilicals, risers and flowlines tied to the Ekofisk complex. The PPF project will bring three shut-in fields — Albuskjell, Vest Ekofisk and Tommeliten Gamma — back into production through 11 new wells from four subsea templates, targeting 55 million barrels of oil equivalent in net proved plus probable reserves with first gas in the fourth quarter of 2028. Two frameworks signal where the next five years of Norwegian contracting are going. Both the Subsea7-Vår Energi strategic partnership and the TechnipFMC five-year collaboration agreement with Vår Energi are structured to pull projects through pre-FEED and FEED into EPCI without a competitive break at each stage. For operators trying to hit first oil within two years of sanction, that model reduces schedule risk significantly. For contractors not inside those frameworks, it reduces their addressable market on the NCS.
Wood secures five-year Aramco long-term agreement Wood confirmed a five-year LongTerm Agreement with Saudi Aramco covering engineering, design and project management services across the Kingdom's oil and gas, refining, petrochemical and lower-carbon hydrogen programmes. Approximately 900 Wood employees are based in-kingdom alongside its Reading office in the UK. The agreement, which carries a three-year extension option, builds on a collaboration spanning more than 30 years. In the current market, where Aramco is simultaneously repairing Hormuz-related infrastructure
Contracts damage, accelerating its offshore expansion programme and advancing the Uthmaniyah Gas Compression Plant, the scope of work available under a framework of this duration is substantial.
WEST aFRICa
MIDDLE EaST
The Subsea Integration Alliance, operating through Subsea7 and SLB OneSubsea, was awarded a substantial EPCI contract by ExxonMobil Affiliate Esso Exploration and Production Nigeria for a deepwater subsea tie-back on the Redevelopment 2.0 Likembe Project in Block 15 offshore Angola, valued between $150 million and $300 million. Project management runs from Subsea7 offices in Paris, Luanda and Lisbon with umbilical work led from SLB OneSubsea's centre of excellence in Moss, Norway.
The two largest single offshore EPCIC awards of the period both landed in the Gulf Saipem secured a $1.8 billion EPCI contract for a Middle East offshore development covering engineering, procurement, construction and installation of offshore and subsea facilities. The client and field were not publicly named. The award builds on Saipem's established regional fleet and infrastructure track record and follows a separate €900 million Aramco EPC award for the Uthmaniyah Gas Compression Plant onshore earlier in 2026, keeping Saipem simultaneously active on offshore and onshore gas scopes in the Kingdom. L&T Energy Hydrocarbon Offshore simultaneously secured an ultra-mega contract — its designation for awards above ₹150 billion — valued at more than $1.57 billion for a major Middle East offshore development covering engineering, procurement, construction, installation and commissioning across multiple offshore facilities with subsea infrastructure and substantial fabrication requirements. Senior Vice President Parthasarathi Chatterjee said the project exemplified the scale and complexity of offshore developments that LTEH Offshore is uniquely positioned to deliver. The client, country and field were not named. Two awards above $1.5 billion each from the same region in the same period is a significant signal. Middle East EPCIC contracting has historically been dominated by a small number of integrated players with established regional relationships and in-country fabrication capability. The barriers to entry are high. Both Saipem and L&T clearing those bars simultaneously at the top of their respective size brackets confirms that the post-Hormuz recovery programme is generating real contract volume rather than just pre-FEED activity. ADNOC Gas took a final investment decision on the first phase of the Rich Gas Development Project, awarding $5 billion in contracts across the Asab, Buhasa and Habshan onshore facilities and the offshore Das Island liquefaction facility. The contracts cover expansion of processing units to boost throughput and operational efficiency across the integrated gas value chain, and represent one of the largest single FID-linked contract packages awarded in Abu Dhabi in several years.
Angola has two large subsea scopes running simultaneously
BP also confirmed a final investment decision on the Greater PAJ development in Blocks 31 and 31/21 offshore Angola, targeting peak gross production of approximately 95,000 barrels of oil equivalent per day. The project adds to what is already a highly active Angolan contracting environment in 2026, with Eni's Baleine Phase 3 FID in Ivory Coast and Petrobras's growing pre-salt production in Brazil together driving a sustained run of deepwater award activity across the South Atlantic Basin.
aSIa PaCIFIC & aMERICaS
Delfin FLNG 1, Sépia 2 and Saipem Guyana close out a strong quarter The $5 billion Delfin FLNG 1 final investment decision in the US Gulf is the headline project decision of the period, the world's largest FLNG project at 4.4 million tonnes per year with construction contracts held by Samsung Heavy Industries and Black and Veatch. The significance goes beyond the single project. Delfin FLNG 1 is the third major US Gulf LNG FID in 2026, alongside Venture Global CP2 and Caturus Commonwealth LNG. Combined, the three projects represent more than 25 million tonnes per year of committed new export capacity due to enter service before 2032 and between them they will sustain one of the largest single-country LNG construction programmes outside of Qatar for the next six years. Subsea7 was separately awarded a supermajor contract by Petrobras for the Sépia 2 field in the pre-salt Santos Basin, 280 kilometres southeast of Rio de Janeiro at a water depth of 2,170 metres. The scope covers engineering, procurement, fabrication, installation and pre-commissioning of subsea umbilicals, risers and flowlines for 17 wells including two from the original Sépia 1 project and
Be in the know! Become a NETWORK member and sign up to GENIntel today
one gas export line with 18 risers. Project management and engineering have commenced immediately from Subsea7's offices in Rio de Janeiro, Paris and Sutton, with offshore operations scheduled from 2029. Subsea7 classifies the contract as supermajor, meaning a value above $1.25 billion. Saipem confirmed the Longtail subsea EPCI preliminary award from ExxonMobil Guyana among its largest Q2 contract awards, covering engineering, procurement, construction and installation of the SURF system for the Stabroek Block development at approximately 1,750 metres water depth. The preliminary award was valued at around $150 million, with the full contract potentially reaching $750 million to $1.5 billion once final approvals are received. Longtail is designed as Guyana's first offshore development focused on non-associated natural gas rather than oil, with peak production potential of up to 1.2 billion cubic feet per day and approximately 250,000 barrels of condensate per day, targeting first production in 2030.
GEN VIEW
The market is executing. The question is cost. TechnipFMC put its total subsea opportunity pipeline at approximately $30 billion over the next 24 months in its second-quarter results, growth of more than 30 percent over the past two years, and raised fullyear 2026 subsea inbound order guidance to $10 billion. Westwood puts the EPC contract award market on track for $59 billion for the full year. Saipem's first-half results included the Longtail preliminary award, two Middle East offshore EPCI contracts and the Uthmaniyah Gas Plant onshore scope among its largest awards. Subsea7 holds PPF Ekofisk, Sépia 2 and Goliat Gas Export simultaneously. The supply chain has not seen demand conditions like this since the 2012 to 2014 peak. The difference is that in 2012 to 2014, the market was adding capacity as fast as it could. Today it is not. Vessel day rates, fabrication slot costs and engineering labour costs are all rising from a base that was already tightening before the Hormuz crisis accelerated the demand signal. The contracts being signed in September 2026 will be executed between 2027 and 2030. The cost environment in which they are executed will be materially different from the one in which they were tendered. That gap is where margins will be made or lost, and it is the story GEN members in project management, supply chain and commercial roles should be watching most closely going into the final quarter of 2026.
49
50
Global Events Floating Offshore Wind V 7-8 October 2026 , P&J Live Aberdeen, UK energy is Futue V 7-9 October 2026 , Istanbul, Türkiye Africa Energy Week V 12-16 October 2026 , Cape Town, South Africa Mainstream UK Summit V 20-21 October 2026 , Birmingham, UK Adipec V 2-5 November 2026 , Abu Dhabi, UAE
Wider African Energy Summit V 1-2 December 2026 , London, UK
Your Trusted Global Travel Partner
Africa's Energy Boom: Turning Business Travel Challenges into Strategic Opportunities Africa is entering a new era of energy investment. Offshore oil discoveries, LNG developments, refinery upgrades, and renewable energy projects have made the continent an attractive energy destination - one with an increasingly strategic role in supplying international markets.
Despite momentum, Africa is often viewed through the lens of complexity. While operating across a vast and diverse continent presents challenges, these are outweighed by the opportunities available to organisations that understand local landscapes and have the right partners in place.
suppliers, accommodation availability, visa processes, and ground transportation can significantly improve the traveller experience while supporting compliance with local requirements.
Successful expansion into Africa is not simply about reaching a destination; it's about navigating regulations, local content requirements, transportation networks, and cultural environments efficiently and safely. This is where specialist travel management becomes a strategic advantage.
Energy projects rarely operate from single locations. Travellers move between headquarters, remote field locations, offshore & onshore operations, and neighbouring countries. Managing this level of mobility requires more than booking flights: without the right travel infrastructure, project delays, increased costs, and traveller disruption become significant operational risks.
A Continent of Opportunity Africa remains one of the world's largest, untapped energy frontiers. Because of this, there is significant demand for regional business travel as projects expand across multiple countries. Like every global region, Africa presents operational challenges that require careful planning: • Diverse visa and immigration requirements • Varying aviation infrastructure • Different currencies • Complex travel logistics to remote projects • Security and duty of care considerations • Varying business practices and regulations However, these challenges are not unique to Africa; they exist in different forms across international markets. The difference is having the right local expertise to navigate them effectively.
Local Content: A Business Imperative A defining characteristic of Africa's energy sector today is the growing emphasis on Local Content. Governments are strengthening legislation designed to ensure that local businesses, employees, and suppliers benefit directly from energy investments. Rather than viewing Local Content as a compliance exercise, forward-thinking organisations recognise it as a strategic advantage. Understanding regional airline networks, payment methods, local travel
VIEW ALL EVENTS AT
www.globalenergynetwork.net/ globalenergynetwork.net I October 2026 gen-networking-events/
Pam Kitching, Managing Director, Africa
How ATPI Helps Navigate Africa
ATPI understands that travel across Africa requires specialist knowledge, regional expertise, and technology built specifically for the continent. Our extensive African network combines local market expertise with global travel management capabilities, enabling clients to travel confidently across multiple jurisdictions while maintaining compliance, visibility, and traveller safety.
ATPI BAO (Booking Africa Online) is our
online booking tool developed to address the realities of African business travel. Unlike traditional tools, ATPI BAO is designed around the region's travel ecosystem, offering: • • • • • •
Access to GDS and non-GDS airlines Integration with regional travel suppliers Local currency and in-country billing Duty of care and traveller tracking Corporate travel policy compliance 24/7 specialist travel support
By combining technology with local expertise, ATPI BAO helps organisations simplify travel planning while improving visibility, compliance, and operational efficiency. Success in Africa depends on more than identifying opportunities; it requires understanding local markets, embracing Local Content principles, and partnering with organisations that understand the unique complexities of operating across Africa. With the right travel partner and technology, organisations can navigate the continent, keep people moving, and focus on delivering successful energy projects.
If you would like to find out how ATPI can help streamline your travel management, email:
atpienergytravel@atpi.com
HSE & Training
ENERGY AND CREW TRAVEL REIMAGINED Smarter technology for complex crew and business travel Smarter systems. Seamless execution. Total control.
51