Forecast · 2021 — 2030
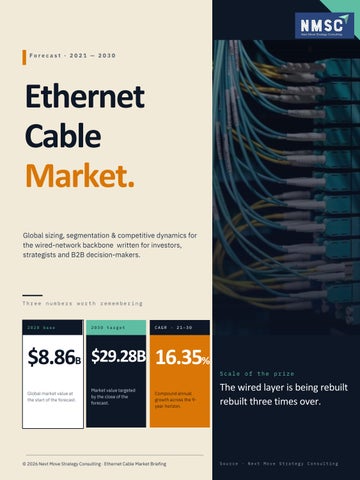
Ethernet Cable Market. Global sizing, segmentation & competitive dynamics for the wired-network backbone written for investors, strategists and B2B decision-makers.
Three numbers worth remembering
2020 base
2030 target
CAGR · 21–30
$8.86B $29.28B 16.35% Scale of the prize Global market value at the start of the forecast.
Market value targeted by the close of the forecast.
Compound annual growth across the 9year horizon.
© 2026 Next Move Strategy Consulting · Ethernet Cable Market Briefing
The wired layer is being rebuilt rebuilt three times over.
Source · Next Move Strategy Consulting
02 · Market shape
Three axes structure every commercial decision.
The market is defined by what is shipped, where it is shipped, and how the cable is shielded. Each axis carries distinct margin pools and growth velocities.
By type
By application
Copper cable
Residential
Network cable · Power-overEthernet (PoE)
Industrial
Fiber-optic cable cable
Single-mode · Multi-mode
Transportation · IT & Telecom Oil & Gas · Energy & Power
Commercial Office buildings · Healthcare · Retail
Fiber accelerates with hyperscale buildouts; copper retains the installed-cost edge across shortreach links.
By cable structure
Unshielded Twisted Pair Office & residential default — costefficient, easy to terminate.
Shielded Twisted Pair Industrial & high-EMI environments — better performance, higher security.
Industrial is the fastest-mover on absolute volume; commercial is the most diverse in deployment architecture.
Geography (next slide) North America holds the lead on installed base & IT firm concentration. Asia-Pacific is the fastest-growing due to population scale & internet penetration.
© 2026 Next Move Strategy Consulting — Ethernet Cable Market Briefing
STP is forecast to show sizeable growth as industrial & shielded deployments scale.
03 · Growth drivers & opportunities
Five forces underwriting a 16.35% runway.
Compounded
16.35
%
Demand is not pulled by one sector — it compounds across data centers, edge nodes, industrial sites and premises networks at the same time. Compound annual growth across the 2021 – 2030 horizon.
01
5G & edge buildout Small-cell, fronthaul and edge-node deployments shorten runs and multiply port counts per site.
3.31×
02
Hyperscale data-center capacity
03
Power-over-Ethernet (PoE)
04
Industrial automation & IoT
AI training clusters and large cloud regions require hundreds of thousands of new structured-cable drops per facility.
Rising watt budgets per port re-rate copper as both data and power — lighting, access control and switches all converge on a single drop.
Factory floors, transportation systems and energy sites pull shielded twisted pair into harsher environments at scale.
The size the market is forecast to expand over nine years.
+$20.4B
Dollar value added between 2020 and 2030 — the prize the participants will compete for.
Caveat
Wired install cost & portability drag — wireless substitution remains the structural offset to monitor.
05
Asia-Pacific internet penetration Population scale, expanding middle class and a new build-out cycle make APAC the single largest incremental pool.
© 2026 Next Move Strategy Consulting — Ethernet Cable Market Briefing
04 · Competitive landscape
Ten players, Three pl atf orm bets. The field is consolidating around product launches, channel partnerships and bolt-on M&A — large industrial conglomerates compete with specialist cabling houses, often inside the same bid.
Belden Inc.
Prysmian Group
Leviton Manufacturing
Specialty cabling & signaltransmission platform across industrial & broadcast.
Global cable & optical-fiber heavyweight with strong telecom & energy exposure.
US-based structured-cabling vendor with deep commercial & data-center footprint.
The Siemon Company
SAB Brockskes
Nexans SA
Specialist in flexible & halogen-free industrial cables for harsh environments.
French multinational with full fiber, submarine & building-cable portfolio.
Southwire Company
Hitachi Ltd.
Siemens AG
North-American wire & cable maker with utility, commercial & residential breadth.
Conglomerate with infrastructuresystems exposure across rail, energy & data networks.
Industrial-automation giant — network cables bundled with factory & building systems.
Premium IT infrastructure focused on data centers & high-performance copper/fiber.
Schneider Electric SE Energy-management & automation specialist — sells cabling alongside EcoStruxure architecture and panel-level hardware.
Strategies being deployed A · Product launches
B · Channel & SI partners
C · Bolt-on M&A
Higher-category copper, Cat 8 + single-mode fiber lines, armored industrial assemblies.
Bundled bids with hyperscalers, system integrators & data-center operators to lock in volume.
Bolt-on acquisitions absorb regional specialists — geographic reach & shielded-product IP are the most-cited drivers.
© 2026 Next Move Strategy Consulting — Ethernet Cable Market Briefing
05 · Regional outlook & caveats
Today it is North America. Tomorrow it is Asia-Pacific. Geography sets the cadence: legacy installed base in the West versus an aggressive new-build cycle across emerging Asia.
Region 01 · North America
Region 02 · Asia-Pacific
Where share sits today.
Where growth compounds.
Holds the major share today on the back of an established IT-firm footprint, mature data-center clusters and a deep structured-cabling installed base.
The fastest-mover on the back of population scale, expanding connectivity, and new infrastructure cycles in China, India and Southeast Asia.
· U.S. anchors enterprise spend and hyperscale retrofits. · Canada & Mexico add industrial & logistics corridors.
· China & Japan drive fiber and high-specification copper demand. · India absorbs residential & IT-telecom rollout. · Australia & RoAPAC round out enterprise deployments.
· High replacement velocity in copper categories. Why investors care Why investors care
Highest absolute revenue density, highest vendor mindshare, slowest regional growth rate.
The biggest incremental pool. Local manufacturing partnerships are the most-cited route for new entrants.
Region 03 · Europe
Region 04 · Rest of World
Mature & standardization-led
Latin America · Middle East · Africa
Germany, UK, France & Italy lead the bid book; demand is driven by industrial retrofits & FTTx rollouts.
Smaller pools with rising urbanization & FTTH projects. Watchlist tier for now — present in the base case.
© 2026 Next Move Strategy Consulting — Ethernet Cable Market Briefing
06 · Where to next
C ontinue the conversation. Reach the NMSC research desk for in-depth segmentation, country-level forecasts and custom strategic guidance across the wired-network value chain.
Website
Direct
nextmsc.com
+1 857 758 5017
info@nextmsc.com
Request the full report Single-report & enterprise licensing available.
Follow
NMSC
in
f
© 2026 Next Move Strategy Consulting — All rights reserved.
YouTube
X
◎