Investor Briefing · 2025 → 2030
Enterprise Smartphone Market Mobile devices are now the
.
operating system of enterprise work
An executive read on the global B2B mobility market — sized, segmented, and stress-tested for capital allocators weighing device makers, EMM platforms, and enterprise buyers.
Market Value · 2025
Forecast · 2030
CAGR · 2025–2030
North America Share
$48B
$95B
14.5%
37%
Triangulated global enterprise smartphone revenue
Implied serviceable market, bullish scenario
Compounded; device-side revenue, blunt estimate
Largest revenue pool in 2024; mature refresh cycle
Market Trajectory
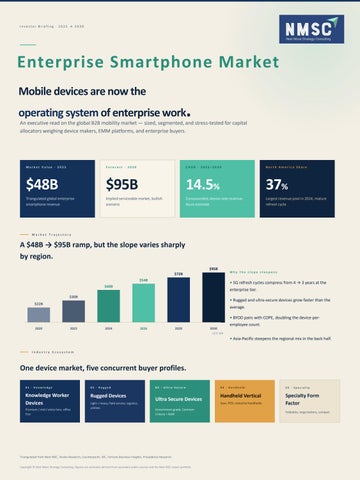
A $48B → $95B ramp, but the slope varies sharply by region. $95B
Why the slope steepens
$72B
$54B
• 5G refresh cycles compress from 4 → 3 years at the
$40B
enterprise tier.
$30B
• Rugged and ultra-secure devices grow faster than the
$22B
average.
• BYOD pairs with COPE, doubling the device-per2020
2022
2024
2026
2028
employee count.
2030 U SD B N
• Asia-Pacific steepens the regional mix in the back half. Industry Ecosystem
One device market, five concurrent buyer profiles. 01 · Knowledge
02 · Rugged
Knowledge Worker Devices
Rugged Devices
Premium / mid / entry tiers; office first
Light + heavy; field service, logistics, utilities
03 · Ultra-Secure
Ultra Secure Devices Government-grade; Common Criteria + NIAP
Triangulated from Next MSC, Straits Research, Counterpoint, IDC, Fortune Business Insights, Precedence Research.
Copyright © Next Move Strategy Consulting. Figures are estimates derived from secondary public sources and the Next MSC report portfolio.
04 · Handheld
05 · Specialty
Handheld Vertical
Specialty Form Factor
Scan, POS, industrial handhelds
Foldables, large-battery, compact
Growth Drivers & Opportunities Section 02 / 05
Four demand mechanics & three regional tailwinds the market underwrites. Headline CAGR hides the parts of the market growing twice as fast. Drivers below feed the curve; the regional map underneath shows where the next dollar lands.
Driver 01
Driver 02
Productivity is now measured in apps, not seats.
BYOD doubles the device count without doubling the budget.
CRM, ERP, SCM, SFA and field service workflows are mobile-first by default. Enterprises re-allocate IT budget from desktops to handsets at roughly 1.4× the prior run-rate.
COBO, COPE and BYOD segmentation lets buyers tune capex vs opex. The CYO trend keeps expanding the addressable footprint even as average ASPs tighten.
Driver 03
Driver 04
Vertical devices growth at ~2× the headline.
5G + edge intelligence collapses the refresh gap.
Rugged + ultra-secure + handheld verticals track 12-15% CAGR — fastest in the mix, with logistics, healthcare and public safety as the densest buyer cohorts.
5G-capable shipments carry the bulk of new enterprise orders; on-device AI compresses refresh from 4 to roughly 3 years at the premium tier.
Where the Next Dollar Lands
Revenue pool is mature in the West; growth velocity is in the East. North America 37% share · 11% CAGR
Europe 28% share · 12% CAGR
Asia-Pacific 27% share · 17% CAGR
Rest of World 8% share · 14% CAGR
2024 share of revenue
Fastest-growing region this decade
Emerging pool
Sources: Next MSC report portfolio · Straits Research · Counterpoint Research · IDC · market.us (BYOD) · Ericsson Mobility Report. Copyright © Next Move Strategy Consulting. Estimates triangulated from public secondary sources.
Competitive Scenario Section 03 / 05
Two anchor vendors, one rugged tier, and twenty specialists circling them. Vendor Share, Global Smartphone Shipments
Mass-market base is a duopoly — the enterprise share tilts differently. Samsung
21% Enterprise Rugged + Vertical Pool
Apple
$10B
20%
Xiaomi
Global rugged smartphone spend by 2034 (12.6% CAGR per The Insight Partners)
11%
7%
Motorola
5%
$3.4B
~3×
2025 base
Volume-ready verticals
Vendors leading here: Zebra · Honeywell · Panasonic Connect · Kyocera · Sonim · Getac.
% of unit shipments, global smartphone market, IDC Q1 2026 + Cross-checked Counterpoint 2025.
Positioning Matrix
Enterprise breadth × vertical depth. Moves to Watch
Niche specialists
CATEGORY LEADERS
Three strategies shaping share shifts.
Honeywell
Zebra
Vertical mobility
Vertical depth
Enterprise rugged
01 · Ecosystems
Sonim
Ultra-rugged niche
Pixel for Work
Samsung's Galaxy Enterprise Edition + Knox Suite extends long-term support and centralized control into regulated industries.
02 · Acquisitions
Apple Platform winner
Motorola
Samsung
Mid-tier play
Broadest lineup
Cisco's IMImobile pickup, plus consolidators in rugged + handheld, are splicing software into the device-purchase decision.
03 · DaaS & Leasing Commodity consumer-OEM
PLATFORM WINNERS
Device-as-a-Service wins procurement-led buyers; OPEXEnterprise breadth
Sources: IDC Worldwide Quarterly Mobile Phone Tracker (Q1 2026) · Counterpoint Research 2025 · The Insight Partners · NMSC report.
Copyright © Next Move Strategy Consulting. Positioning interpretations are analyst-grade judgment, not source figures.
only purchasing widens the buyer universe beyond IT.
Strategic Outlook · Investor Lens Section 04 / 05
Three audiences, three reads of the same curve. Implications, risks, and the four moments over the next 18 months where theses will either harden or break.
For capital allocators
Rugged + AI-on-device is where alpha hides.
For device vendors
For enterprise buyers
Sell the platform, not the hand-set.
Plan a three-tier portfolio; do not standardize.
· EMM/UEM bundling raises switching costs and average contract value.
· Tier-1 OEMs (Samsung, Apple) are pricing power plays, not growth.
· Vertical-specific SKUs (logistics, healthcare, public
· Knowledge workers → flagship tier, 3-year refresh.
safety) win RFPs at premium ASPs.
· Vertical specialists (Zebra, Honeywell, Getac) compound at 1.5–2× the headline.
· Long-tail support commitments (5–7 years) are now
· DaaS roll-ups turn devices into recurring gross profit — re-rate candidates.
table stakes in regulated verticals. · Distribute through carriers + DaaS partners, not just direct enterprise sales.
· Watch ASP discipline more than unit volume.
· Field & logistics → rugged mid-tier, 4-year lifecycle. · Regulated & executive → ultra-secure top tier. · Mix COBO, COPE, and BYOD — do not pick one modelwide.
Watchlist · Next 18 Months
Four moments that will harden or break the thesis.
Q4 · 2026
Q1 · 2027
Mid · 2027
Late · 2027
Watch 01
Watch 02
Watch 03
Watch 04
Apple's enterprise monetization disclosure
First cohort of DaaS mega-contracts at US Fortune 500
APAC rugged adoption breaks the 2.5M unit barrier
Regulated AI assistants ship on every flagship SKU
If Korean, Japanese and Indian
If on-device enterprise AI hits general
logistics rollouts cross the prior
availability, refresh cycles compress
ceiling, vertical specialists re-rate sharply.
another 6–9 months.
Whether Apple CarPlay + Apple Business Manager break out as a separately-reported segment will move the duopoly narrative.
A wave of 50k+ seat DaaS awards reshapes revenue visibility for OEMs in the back half.
Watchlist items reflect directional analyst judgment; dates are illustrative, not commitments by named issuers.
Copyright © Next Move Strategy Consulting. Forward-looking views, not investment advice.
Section 05 / 05 · Get in touch
Thank you.
For in-depth strategic guidance on the enterprise smartphone market — sized, segmented, vendor-mapped, and tuned to your buyer cohort.
Reach the analyst team
Three channels, one conversation.
Official Website
Direct Line
nextmsc.com
+1 857 758 5017
info@nextmsc.com
Browse the full report portfolio and sector deep-dives.
Speak with the analyst team — weekdays, 9 AM – 7 PM ET.
Custom research requests, briefings and proposal desk.
Complete Report
Get the full enterprise smartphone briefing. Request access → Analyst team responds within 1 business day.
100+ pages · Forecast through 2030 · vendor profiles · bottom-up sizing
Follow Us
YouTube
linkedin.com/company/ next-move-strategy-consulting
facebook.com/ Next-Move-StrategyConsulting
youtube.com/channel/ UCJuVRxfBo-Dsog7BgDE4uPQ
twitter.com/nextmsc
instagram.com/ nextmsc