Frozen Potato Market · Industry Brief
01 / 05 Analyst edition · 2026
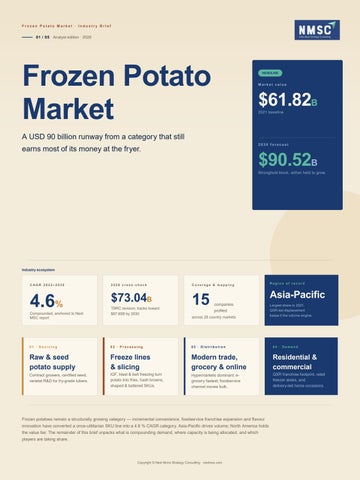
Frozen Potato Market
HEADLINE
Market value
$61.82B 2021 baseline
A USD 90 billion runway from a category that still 2030 forecast
earns most of its money at the fryer.
$90.52B Stronghold block, wither held to grow.
Industry ecosystem
CAGR 2022–2030
2026 cross-check
4.6%
$73.04B
Compounded, anchored to Next MSC report
TBRC revision; tracks toward $87.65B by 2030
Coverage & mapping
Region of record
15
Asia-Pacific companies profiled
across 28 country markets
Largest share in 2021. QSR-led displacement keeps it the volume engine.
01 · Sourcing
02 · Processing
03 · Distribution
04 · Demand
Raw & seed potato supply
Freeze lines & slicing
Modern trade, grocery & online
Residential & commercial
Contract growers, certified seed, varietal R&D for fry-grade tubers.
IQF, blast & belt freezing turn potato into fries, hash browns, shaped & battered SKUs.
Hypermarkets dominant; egrocery fastest; foodservice channel moves bulk.
QSR franchise footprint, retail freezer aisles, and delivery-led home occasions.
Frozen potatoes remain a structurally growing category — incremental convenience, foodservice franchise expansion and flavour innovation have converted a once-utilitarian SKU line into a 4.6 % CAGR category. Asia-Pacific drives volume; North America holds the value tier. The remainder of this brief unpacks what is compounding demand, where capacity is being allocated, and which players are taking share.
Copyright © Next Move Strategy Consulting · nextmsc.com
Frozen Potato Market · Section 02
02 / 05 Drivers & opportunity
What is compounding the demand. Frozen-potato growth is structural. Five tailwinds stack; high-margin SKUs and emerging-market demand are where the next dollar lives.
Now buyi ng
The opportunity map NA value tier
36.8% North America share of global frozen fries & potatoes, 2023 (Market Reports World).
Indian runway
9.49%
A
Five demand drivers
01
Convenience & ready-to-cook
02
Time-pressed households re-anchor grocery baskets around freezer-aisle staples.
03
QSR franchise expansion McDonald's, KFC, Subway and Domino's localise menus across emerging Asia & LatAm.
05
Plant-based & flexitarian Potato sits cleanly inside vegan, halal and vegetarian plates — a global posture shift.
CAGR 2026–2034; market projected to reach USD 4.5B by 2034 (IMARC).
Restraint, named
Cold-storage & logistics
04
cost Female workforce participation Larger dual-income cohorts compress cooking time and lean on shelf-stable meals.
The single biggest brake on the category — and the lever for any operator with a regional cold-chain advantage.
Where to act
Flavour & SKU innovation Tater tots, hash browns, battered/cooked, topped & stuffed SKUs convert a once-utilitarian basket into an indulgence occasion with higher price-per-kg.
APAC capacity & partnerships Premium formed & flavoured SKUs Owning a regional cold chain QSR-aligned private label
B
Where the next dollar lives. High-growth segments & regions
S ha r e / CAG R
Frozen fries
~35% rev. share
Asia-Pacific
dominant 2021
Categories most exposed to the convenience and vegan tailwinds sit on the growth side of the deck;
regions most exposed to cold-chain friction sit on the watchlist.
Hash browns & shaped India (IMARC)
rising fastest 9.49% CAGR '26–'34
Frozen fries remain the workhorse — within the broader frozen French-fries sub-market, frozen variants held 82.85% share in 2026 (Fortune). Hash browns and formed SKUs are where flavour-led growth runs fastest, especially in retail and quick-service menus.
Copyright © Next Move Strategy Consulting · nextmsc.com
Frozen Potato Market · Section 03
03 / 05 Competitive scenario
Four giants hold the fryer. A second tier is on the move. Suppliers in frozen potatoes are consolidating and overlapping. Long-term supply agreements, capacity expansion and bolt-on M&A in Europe and Asia-Pacific are reshaping where the next ten share points come from. A · NA Frozen-Fry Share
Top four control 97% of the U.S. frozen fry aisle. Lamb Weston · 40%
McCain · 30%
Simplot 17%
Sourced from Morningstar / Potato Insights 2023–24 cycle
Others
Cavendish 10% 3%
Approx. NA frozen fries only
B · Tier & Stance
Who's positioned where. Tier 1 · Listed
Tier 1 · Private
Tier 1 · Private
Lamb-Weston
McCain Foods
J.R. Simplot
NA volume leader; foodservice and retail breadth; expanding EU & APAC capacity via targeted acquisitions.
World's largest frozen-potato producer; "1 in 4" global fries; deepest emerging-market franchise footprint.
Vertically integrated; signed a long-term strategic supply agreement with Kraft Heinz, February 2022.
Tier 1 · NA / Canada
Tier 2 · Europe
Tier 2 · Specialists
Cavendish Farms
Aviko · Agristo · Farm Frites
Family-owned; export-heavy; Canadian production base; expanding frozen and formed SKUs.
European consolidation cluster; Aviko added a Unilever potato plant in 2020; cross-border capacity adds.
Kraft Heinz · Frostkrone · Alexia Brand-backed and premium-SKU specialists; private label defence against regional players.
C · Active strategic moves
Three moves that named the new playbook.
June 2019
September 2020
February 2022
Lamb Weston × Ready Meals
Aviko × Unilever potato plant
Kraft Heinz × Simplot
Acquired an Australian frozen-potato processor to extend APAC capacity and product breadth.
Acquired a Unilever potato facility to scale granules & flakes and broaden frozen-potato capability.
Long-term supply agreement — vertical linkage between a major brand and an integrated supplier.
15 companies are profiled across the Frozen Potato report; share splits above are best-available estimates for the North American frozen fries sub-market. Tier-2 players are quietly taking share in Europe and select APAC pockets; watch capacity announcements as the cleanest leading indicator.
Copyright © Next Move Strategy Consulting · nextmsc.com
Frozen Potato Market · Section 04
04 / 05 Regional & segment outlook
Where the volume lives. Where the margin pools.
Four regions, seven product shapes, three channels. Read together they show where capacity pays back fastest — and which combinations are overtraded.
Field texture
Pre-freeze raw potatoes — the supply side of every SKU downstream.
A · Geography
Four regions, four stances. AP AC
Nor t h Am e r i c a
Europe
Rest of World
Volume engine
Value tier
Consolidator
Earliest growth
Largest share, 2021. QSR franchise
~36.8% of global frozen fries +amp;
Mature category with active
LatAm, MEA & Africa: smallest base,
expansion (McDonald's, KFC,
potatoes share in 2023. US frozen-
consolidation between Aviko, Agristo,
fastest opportunity. QSR chain rollout
Subway, Domino's) and on-demand
food
Farm Frites and Bart's. Premium and
is the demand unlatcher.
delivery platforms (Swiggy, Zomato,
production USD 35.6B in 2022, +1.3%
private-label defence.
Uber Eats) keep reshaping the basket.
per IBISWorld.
China · Japan · India · Korea · ASEAN
U.S. · Canada · Mexico
LatAm · Middle East · Africa
UK · DE · FR · NL · Nordics · Iberia
B · Product shape
C · Channel & process
Fries lead; formed and flavoured run hot.fries French
How it moves and freezes.
Hash browns
~35% rev. share rising fastest
Shaped
kids + indulgence
Mashed
steady, retail-led
Battered / cooked
foodservice angle
Topped / stuffed
premium indulgence
Channel 1
Modern trade
Channel 2
Online grocery
Channel 3
Foodservice
dominant fastest +
bulk volume
long tail
Others
Freezing technique
Individual Quick Freezing
Why this matters
Fries + hash browns + shaped together carry ~70% of category revenue. The remaining 30% — battered/ cooked, topped/stuffed — is where price-per-kg runs above average and category mix is being negotiated. Pair the regional split with the channel mix and the strategic answer turns obvious.
Blast freezing
IQF plus belt freeze
Estimates for product-mix share are anchored in public category reads (FactMR, NMSC product taxonomy); channel split anchors to the report's distribution view. End-user mix remains commercial vs. residential — foodservice-led APAC, retail-balanced NA.
End-user split
Foodservice
Retail
Commercial + Residential
~58%
~42%
Foodservice anchors emerging APAC & LatAm; retail freezer-aisle rebounds in NA & Western Europe with flavour-led innovation.
Copyright © Next Move Strategy Consulting · nextmsc.com
05 / 05 In-depth engagement
Thank You.
Follow
Stay close to the data we track. LinkedIn
in
Next Move Strategy Consulting linkedin.com/company/next-move-strategy-consulting
f
Next Move Strategy Consulting facebook.com/Next-Move-Strategy-Consulting
Let's frame what's next,
YouTube
together.
youtube.com/channel/UCJuVRxfBo-Dsog7BgDE4uPQ
Reach out for segment-level forecasts, custom country cuts, supply-chain teardowns and M&A target diligence across the frozen-potato value chain.
@NextMSC channel
X (Twitter)
𝕏
@nextmsc twitter.com/nextmsc
◎
@nextmsc instagram.com/nextmsc
Reach us Phone
+1 857 758 5017 Email
info@nextmsc.com
Anal yst desk
Reports, custom cuts and country briefs land every week. Pick the channel that fits how you work; we will route the right dataset to the right seat.
Website
nextmsc.com Edition
Frozen Potato Market · 2026 Analyst Brief 5 slides · canvas 3:4 · prepared for investor & B2B review. Next step
Read the complete Frozen Potato report at nextmsc.com — or request a custom country cut.
Copyright © Next Move Strategy Consulting nextmsc.com · +1 857 758 5017
Slide 05 of 05