Research Tokyo Logistics Market Dynamics Q3 2026
Tokyo Fundamentals (for this quarter) •
Demand remains strong, driven primarily by e-commerce and 3PL companies
•
Vacancy rate declines for the fifth consecutive quarter to 7.3%
•
Rents continue to rise amid higher construction costs and improving market fundamentals
Net absorption Completions Vacancy rate Gross rent Rent growth Y-o-Y Stage in rental cycle
215,500 tsubo 202,800 tsubo 7.3% JPY 4,904 per tsubo p.m. +3.8% Rents Rising
Note: Tokyo logistics refers to the Greater Tokyo prime logistics market. Data is on an NLA basis.
Demand from e-commerce companies and 3PL providers remained strong in Q3 2026, with net absorption reaching 215,500 tsubo. Demand was also driven by retailers expanding their distribution networks and by growth in inbound cross-border e-commerce. Leasing activity continues to progress steadily, although vacancy absorption is taking longer in fringe submarkets such as the Ken-O Expressway area and in other areas facing heightened competition.
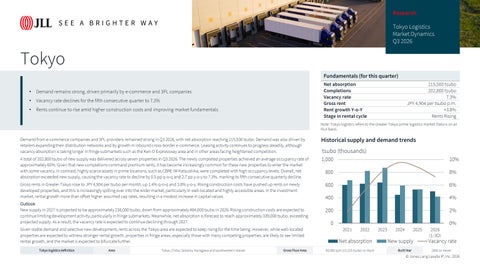
Historical supply and demand trends
A total of 202,800 tsubo of new supply was delivered across seven properties in Q3 2026. The newly completed properties achieved an average occupancy rate of approximately 60%. Given that new completions command premium rents, it has become increasingly common for these new properties to enter the market with some vacancy. In contrast, highly scarce assets in prime locations, such as CBRE IM Katsushika, were completed with high occupancy levels. Overall, net absorption exceeded new supply, causing the vacancy rate to decline by 0.5 pp q-o-q and 2.7 pp y-o-y to 7.3%, marking its fifth consecutive quarterly decline.
1,000
10%
800
8%
600
6%
400
4%
200
2%
Gross rents in Greater Tokyo rose to JPY 4,904 per tsubo per month, up 1.4% q-o-q and 3.8% y-o-y. Rising construction costs have pushed up rents on newly developed properties, and this is increasingly spilling over into the wider market, particularly in well-located and highly accessible areas. In the investment market, rental growth more than offset higher assumed cap rates, resulting in a modest increase in capital values. Outlook New supply in 2027 is projected to be approximately 238,000 tsubo, down from approximately 484,000 tsubo in 2026. Rising construction costs are expected to continue limiting development activity, particularly in fringe submarkets. Meanwhile, net absorption is forecast to reach approximately 339,000 tsubo, exceeding projected supply. As a result, the vacancy rate is expected to continue declining through 2027. Given stable demand and selective new development, rents across the Tokyo area are expected to keep rising for the time being. However, while well-located properties are expected to witness stronger rental growth, properties in fringe areas, especially those with many competing properties, are likely to see limited rental growth, and the market is expected to bifurcate further. Tokyo logistics definition
Area
Tokyo, Chiba, Saitama, Kanagawa and southwestern Ibaraki
Gross Floor Area
tsubo (thousands)
0
0% 2021
2022
2023
2024
2025
Net absorption
New supply
50,000 sqm (15,125 tsubo) or more
Built Year
2026 (1-3Q)
Vacancy rate 2000 or newer
© Jones Lang Lasalle IP, Inc. 2026
Research Tokyo Logistics Market Dynamics Q3 2026 Jones Lang LaSalle K.K. Tokyo Headquarters Kioi Tower, Tokyo Garden Terrace Kioicho 1-3 Kioi-cho Chiyoda-ku, Tokyo 102-0094 +81 3 4361 1800
Kansai Nippon Life Yodoyabashi Building 3-5-29 Kitahama Chuo-ku, Osaka 541-0041 +81 6 7662 8400
Fukuoka Fukuoka Daimyo Garden City 2-6-50 Daimyo, Chuo-ku, Fukuoka-shi Fukuoka 810-0041 +81 92 233 6801
Nagoya JP Tower Nagoya 1-1-1 Meieki, Nakamura-ku, Nagoya-shi Aichi 450-6321 +81 52 856 3357
For more information, please contact Manabu Taniguchi Senior Director Research - Japan manabu.taniguchi@jll.com
Hiroshi Okubo Head of Research Research - Japan hiroshi.okubo@jll.com
COPYRIGHT © JONES LANG LASALLE IP, INC. 2026 This report has been prepared solely for information purposes and does not necessarily purport to be a complete analysis of the topics discussed, which are inherently unpredictable. It has been based on sources we believe to be reliable, but we have not independently verified those sources and we do not guarantee that the information in the report is accurate or complete. Any views expressed in the report reflect our judgment at this date and are subject to change without notice. Statements that are forward-looking involve known and unknown risks and uncertainties that may cause future realities to be materially different from those implied by such forward-looking statements. Advice we give to clients in particular situations may differ from the views expressed in this report. No investment or other business decisions should be made based solely on the views expressed in this report.
© Jones Lang Lasalle IP, Inc. 2026