Research Osaka Logistics Market Dynamics Q3 2026
Osaka Fundamentals (for this quarter) •
Demand remains robust, although new supply outpaced net absorption this quarter
•
Vacancy rate edges up to 3.0% but remains low
•
Rents are expected to continue rising amid higher construction costs and a tight supply-demand balance
Net absorption Completions Vacancy rate Gross rent Rent growth Y-o-Y Stage in rental cycle
23,700 tsubo 57,900 tsubo 3.0% JPY 4,368 per tsubo p.m. +2.9% Rents Rising
Note: Osaka logistics refers to the Greater Osaka prime logistics market. Data is on an NLA basis.
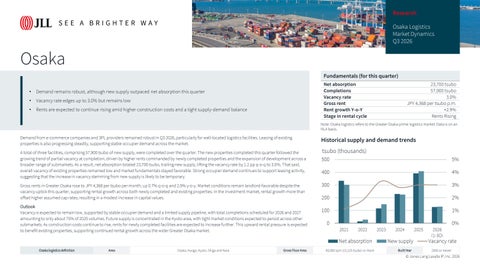
Demand from e-commerce companies and 3PL providers remained robust in Q3 2026, particularly for well-located logistics facilities. Leasing of existing properties is also progressing steadily, supporting stable occupier demand across the market. A total of three facilities, comprising 57,900 tsubo of new supply, were completed over the quarter. The new properties completed this quarter followed the growing trend of partial vacancy at completion, driven by higher rents commanded by newly completed properties and the expansion of development across a broader range of submarkets. As a result, net absorption totaled 23,700 tsubo, trailing new supply, lifting the vacancy rate by 1.2 pp q-o-q to 3.0%. That said, overall vacancy of existing properties remained low and market fundamentals stayed favorable. Strong occupier demand continues to support leasing activity, suggesting that the increase in vacancy stemming from new supply is likely to be temporary. Gross rents in Greater Osaka rose to JPY 4,368 per tsubo per month, up 0.7% q-o-q and 2.9% y-o-y. Market conditions remain landlord-favorable despite the vacancy uptick this quarter, supporting rental growth across both newly completed and existing properties. In the investment market, rental growth more than offset higher assumed cap rates, resulting in a modest increase in capital values. Outlook Vacancy is expected to remain low, supported by stable occupier demand and a limited supply pipeline, with total completions scheduled for 2026 and 2027 amounting to only about 75% of 2025 volumes. Future supply is concentrated in the Kyoto area, with tight market conditions expected to persist across other submarkets. As construction costs continue to rise, rents for newly completed facilities are expected to increase further. This upward rental pressure is expected to benefit existing properties, supporting continued rental growth across the wider Greater Osaka market.
Osaka logistics definition
Area
Osaka, Hyogo, Kyoto, Shiga and Nara
Gross Floor Area
Historical supply and demand trends
tsubo (thousands) 500
5%
400
4%
300
3%
200
2%
100
1%
0
0% 2021
2022
2023
2024
2025
Net absorption
New supply
50,000 sqm (15,125 tsubo) or more
Built Year
2026 (1-3Q)
Vacancy rate 2000 or newer
© Jones Lang Lasalle IP, Inc. 2026
Research Osaka Logistics Market Dynamics Q3 2026 Jones Lang LaSalle K.K. Tokyo Headquarters Kioi Tower, Tokyo Garden Terrace Kioicho 1-3 Kioi-cho Chiyoda-ku, Tokyo 102-0094 +81 3 4361 1800
Kansai Nippon Life Yodoyabashi Building 3-5-29 Kitahama Chuo-ku, Osaka 541-0041 +81 6 7662 8400
Fukuoka Fukuoka Daimyo Garden City 2-6-50 Daimyo, Chuo-ku, Fukuoka-shi Fukuoka 810-0041 +81 92 233 6801
Nagoya JP Tower Nagoya 1-1-1 Meieki, Nakamura-ku, Nagoya-shi Aichi 450-6321 +81 52 856 3357
For more information, please contact Manabu Taniguchi Senior Director Research - Japan manabu.taniguchi@jll.com
Hiroshi Okubo Head of Research Research - Japan hiroshi.okubo@jll.com
COPYRIGHT © JONES LANG LASALLE IP, INC. 2026 This report has been prepared solely for information purposes and does not necessarily purport to be a complete analysis of the topics discussed, which are inherently unpredictable. It has been based on sources we believe to be reliable, but we have not independently verified those sources and we do not guarantee that the information in the report is accurate or complete. Any views expressed in the report reflect our judgment at this date and are subject to change without notice. Statements that are forward-looking involve known and unknown risks and uncertainties that may cause future realities to be materially different from those implied by such forward-looking statements. Advice we give to clients in particular situations may differ from the views expressed in this report. No investment or other business decisions should be made based solely on the views expressed in this report.
© Jones Lang Lasalle IP, Inc. 2026