
MARKET REPORT
MIDYEAR • TETON VALLEY
MARKET REPORT
MIDYEAR • THE TETON VALLEY MARKET
Q2 2026 reflected a steady but increasingly segmented period for the Teton Valley real estate market. The valley recorded 265 transactions, compared with 269 one year earlier, while total dollar volume declined 12% to $187.2 million. Rather than signaling broad-based price erosion, the decline was largely driven by changes in the mix of properties sold, particularly the absence of farm and ranch transactions. Because vacant land, attached housing, single-family homes, and commercial properties have significantly different price points, each segment provides a more accurate view of market performance than a single blended average.
Single-family homes were the strongest residential segment during the quarter. Sales increased 21% to 86, while total dollar volume rose 3% to $108.4 million. The median sale price increased 5% to approximately $1.12 million, even as the average declined 18% to $1.26 million, indicating more activity in the middle of the market and fewer high-end transactions. Victor led the segment with 39 sales, up 56%, and $46.6 million in volume, up 57%. Tetonia and Alta also recorded sales gains, while Driggs experienced fewer transactions and lower dollar volume. Active singlefamily inventory declined 25% to 151 listings, pending activity increased 15% to 38, and average market time remained nearly unchanged at 172 days.
Condominium and townhome activity softened as buyers became more selective. Sales declined 19% to 44, while total dollar volume decreased 17% to $24.1 million. Pricing remained comparatively stable, with the average sale price increasing 2% to $548,000 and the median rising 1% to approximately $518,000. Driggs accounted for 35 of the quarter’s 44 attachedhome sales and recorded modest increases in average and median pricing. Victor recorded nine sales, unchanged from the prior year, although its average and median prices declined. Active inventory contracted sharply to 37 listings, while pending transactions fell to eight, resulting in a smaller forward sales pipeline.
Vacant land remained the valley’s most active property segment, recording 128 transactions compared with 124 one year earlier and accounting for nearly half of all Q2 sales. Total dollar volume remained essentially unchanged at $48.4 million, down 1%. The average sale price declined 2% to approximately $378,000, while the median increased 28% to $285,000. This divergence suggests continued demand for more attainable parcels alongside fewer premium acreage transactions. Driggs and Tetonia generated the strongest momentum, with sales increasing 14% and 60%, respectively, while Victor and Alta recorded fewer transactions. The segment ended the quarter with 219 active listings, 46 pending transactions, and an average market time of 143 days.
Commercial activity increased modestly, with six sales compared with five in Q2 2025. Total dollar volume rose 6% to approximately $5.5 million, while the average sale price increased 1% to $910,000 and the median climbed 22% to $1.1 million. Active commercial inventory declined 14% to 12 listings, while pending activity increased from two to four transactions. Farm and ranch activity moved in the opposite direction, with no transactions closing during Q2 2026 compared with seven sales and approximately $21.4 million in volume one year earlier. The absence of these higher-value transactions accounted for most of the market’s decline in overall dollar volume.
Overall, Q2 2026 demonstrated a resilient but highly segmented Teton Valley market. Single-family activity strengthened, vacant land remained active, condominium and townhome demand softened, and the absence of farm and ranch transactions weighed heavily on total dollar volume. Stable overall transaction counts reflected continued demand, but the results varied considerably by housing type and community. Successful outcomes increasingly depended on location, condition, property type, and realistic pricing rather than broad market appreciation.
TOTAL DOLLAR VOLUME 12% DECREASE YOY $187.2M
AVG SFH SALES PRICE 18% DECREASE YOY $1.3M
MEDIAN SFH SALES PRICE 5% INCREASE YOY $1.1M
265
TOTAL TRANSACTIONS 1% DECREASE YOY
441
ACTIVE LISTINGS 49% DECREASE YOY
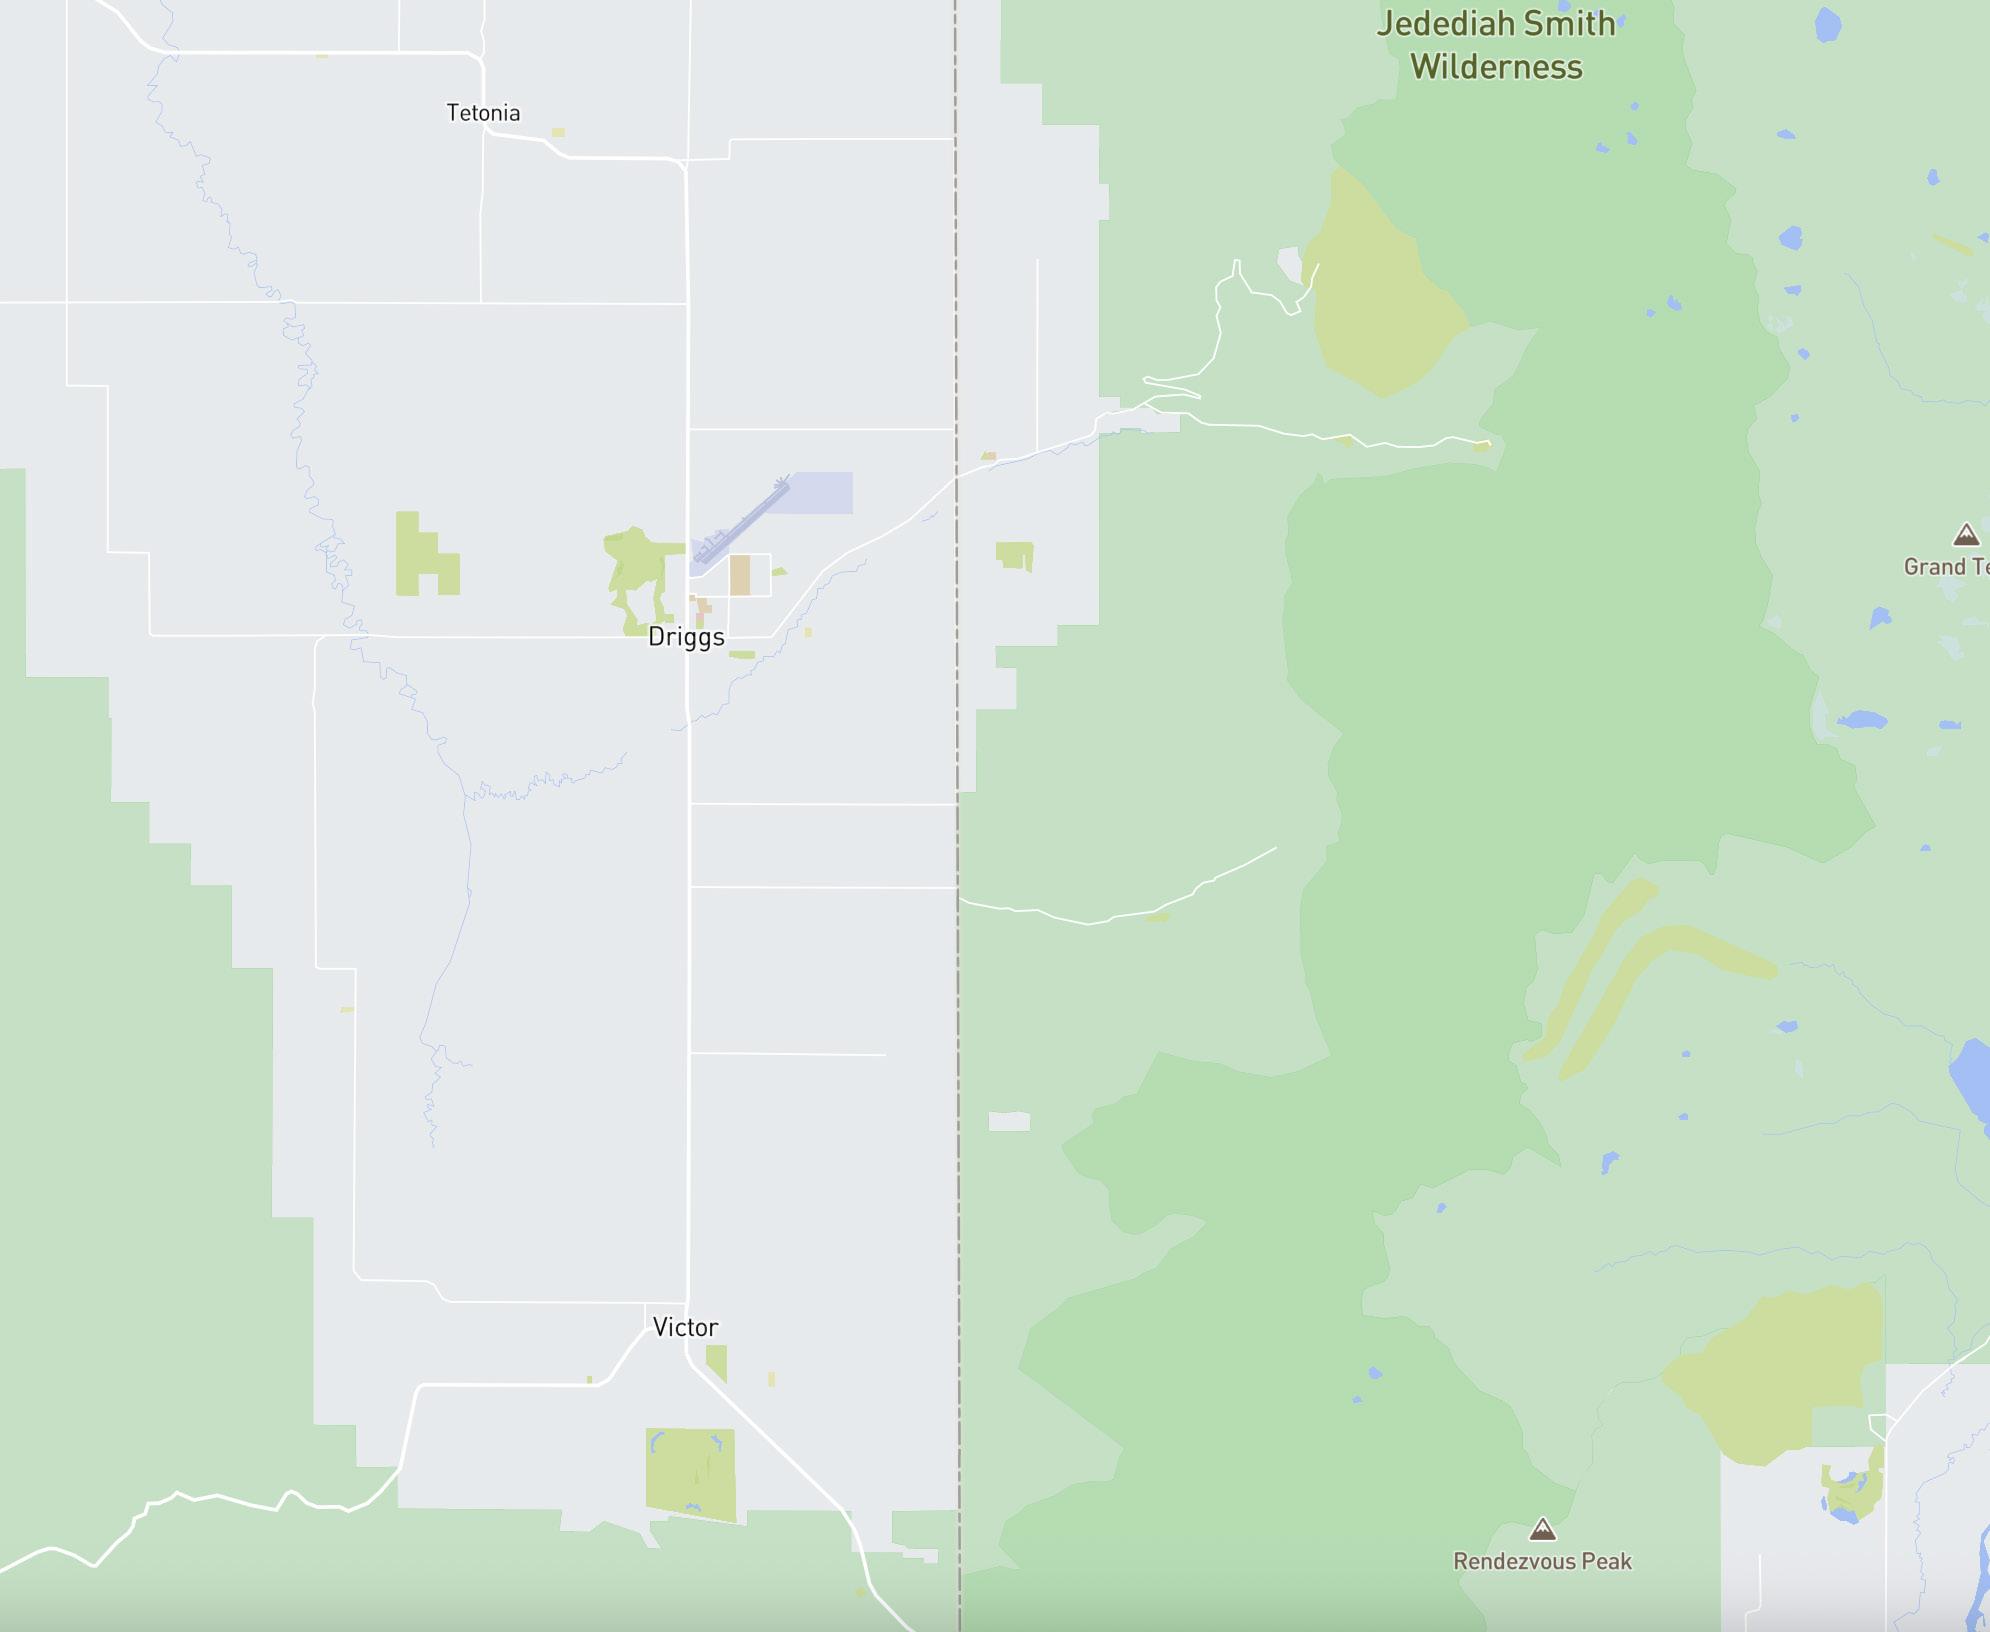
VICTOR, IDAHO (94)
DRIGGS, IDAHO
ALTA, WYOMING
(117)
(6)
TETONIA,
IDAHO (48)
SINGLE FAMILY HOMES
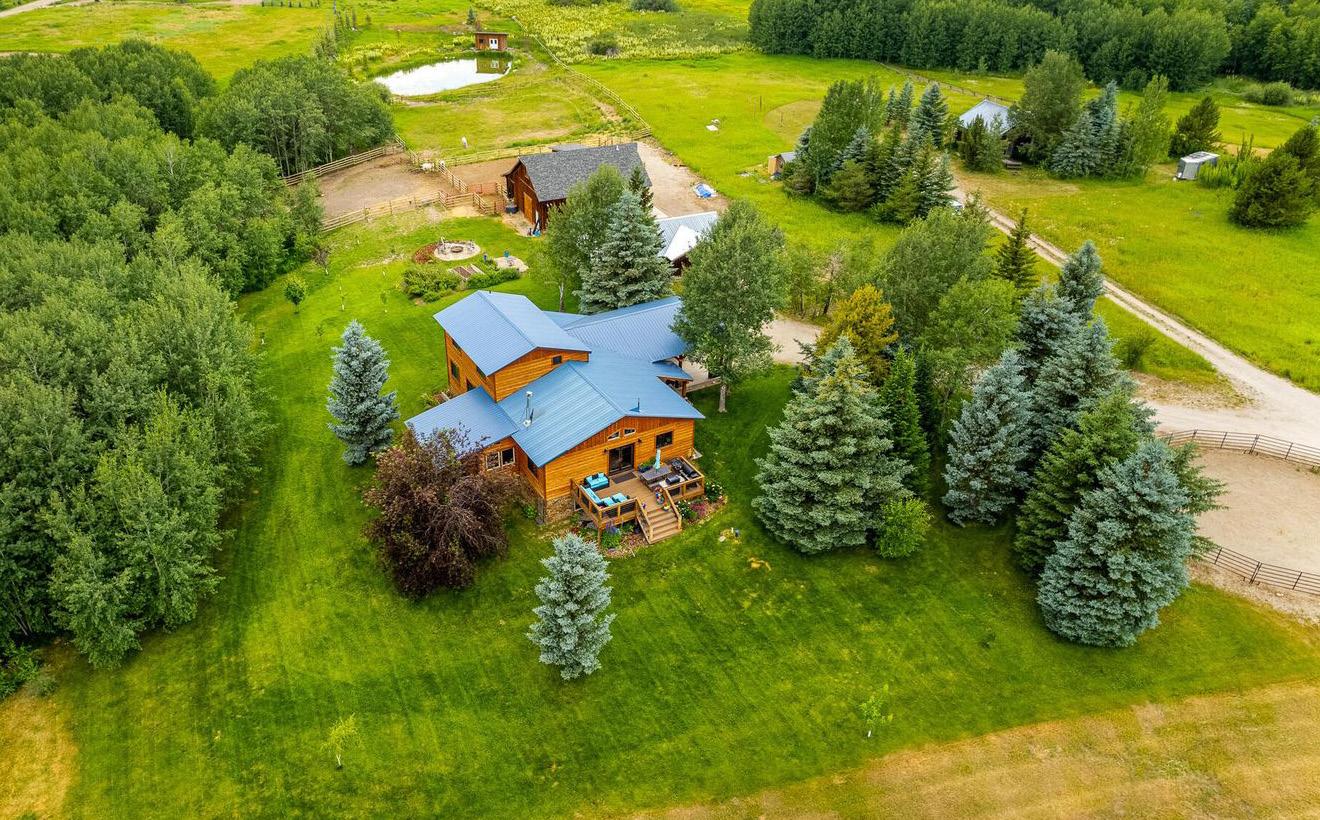
SOLD · LISTED AT $3,390,000 · ALTA REPRESENTED BY ANDREA LOBAN OF THE FALL LINE REALTY GROUP
Single-family homes posted stronger transaction activity in Q2 2026, with sales increasing 21% year over year to 86. Total dollar volume rose 3% to $108.4 million, indicating broader market participation even as the mix of sales shifted away from the highest-priced properties. Victor led the quarter with 39 sales, up 56%, while Tetonia and Alta also recorded meaningful gains. Driggs was the only major submarket to decline, with sales falling 12%.
Pricing results were mixed across the valley. The average sale price decreased 18% to $1.26 million, while the median increased 5% to $1.12 million. Victor’s median rose 15%, Tetonia’s increased 24%, and Alta’s climbed 71%, while Driggs recorded declines in both average and median pricing. The quarter’s highest sale was $4.5 million, down 14% from the prior year.
Market conditions remained relatively balanced. Active listings declined 25% to 151, while pending listings increased 15% to 38. Average days on market was essentially unchanged at 172 days. Overall, Q2 reflected healthy demand for well-positioned singlefamily homes, with stronger sales activity offset by more selective pricing and substantial differences among submarkets. Limited inventory continued to support competitively priced properties, while buyers remained deliberate.
MARKET STATS
MARKET STATS BY AREA
CONDOS/TOWNHOMES
Condominiums and townhomes entered Q2 2026 as a smaller but relatively stable pricing segment of the Teton Valley market. Sales declined 19% year over year, from 54 to 44 transactions, while total dollar volume fell 17% to $24.1 million. Despite the reduction in activity, average and median pricing held firm, suggesting that values remained resilient even as buyers became more selective.
The average sale price increased 2% to approximately $548,000, while the median rose 1% to $517,500. Driggs continued to anchor the segment with 35 sales, representing nearly 80% of all condo and townhome transactions. Although sales in Driggs declined 22%, its average price increased 7% and its median rose 6%. Victor recorded nine sales, unchanged from the prior year, but both average and median pricing declined.
Available inventory contracted sharply, falling 82% to 37 active listings, while pending activity declined 76% to eight. Average days on market was nearly unchanged at 200 days, indicating a measured sales pace despite reduced supply. The quarter’s highest sale reached $850,000, while the lowest closed at $269,500.
Overall, Q2 2026 reflected a balanced but quieter condo and townhome market, with stable pricing offset by lower sales, fewer pending contracts, and significantly reduced inventory.
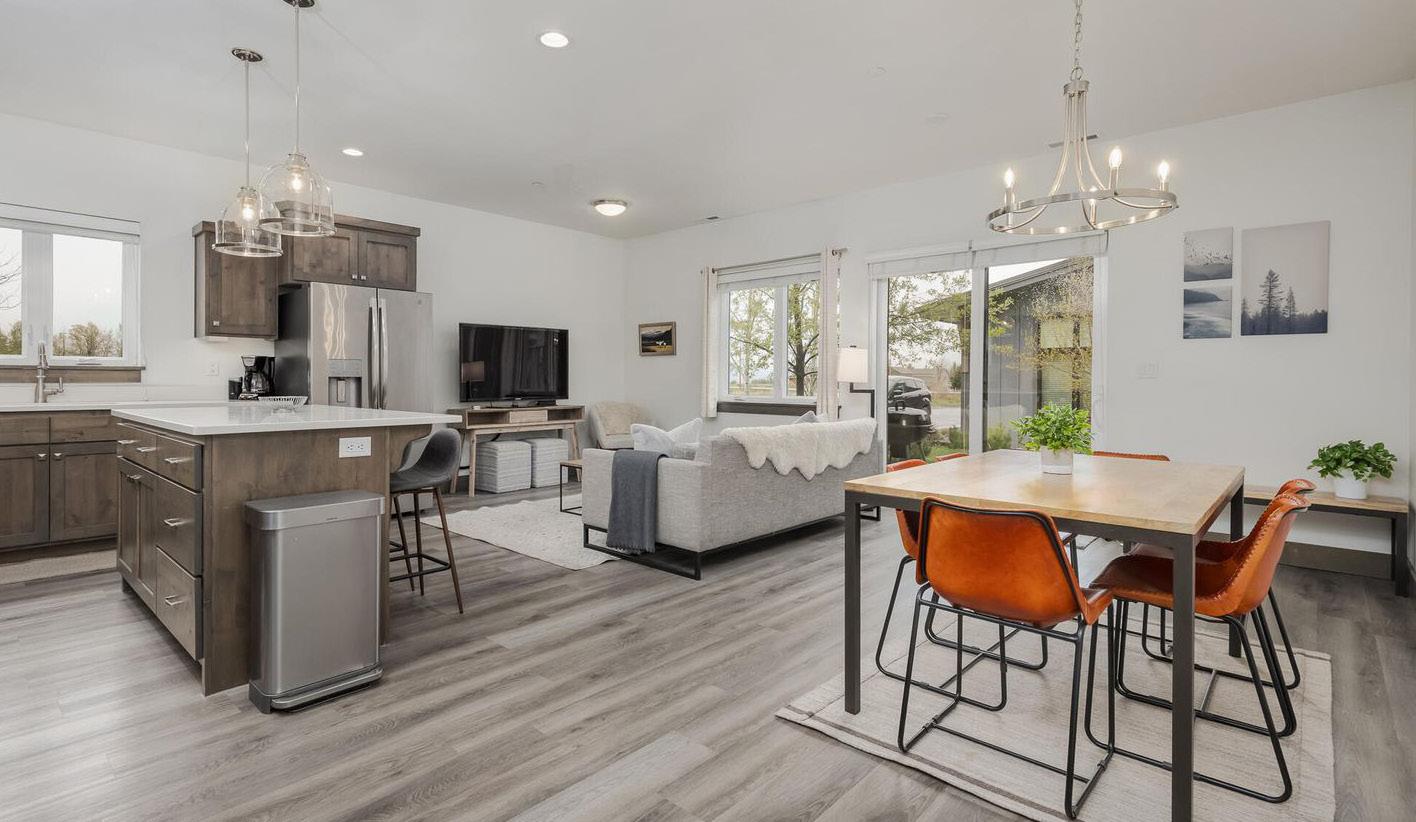
SOLD · LISTED AT $659,000 · VICTOR REPRESENTED BY ANDREA LOBAN OF THE FALL LINE REALTY GROUP
MARKET STATS
VACANT LAND
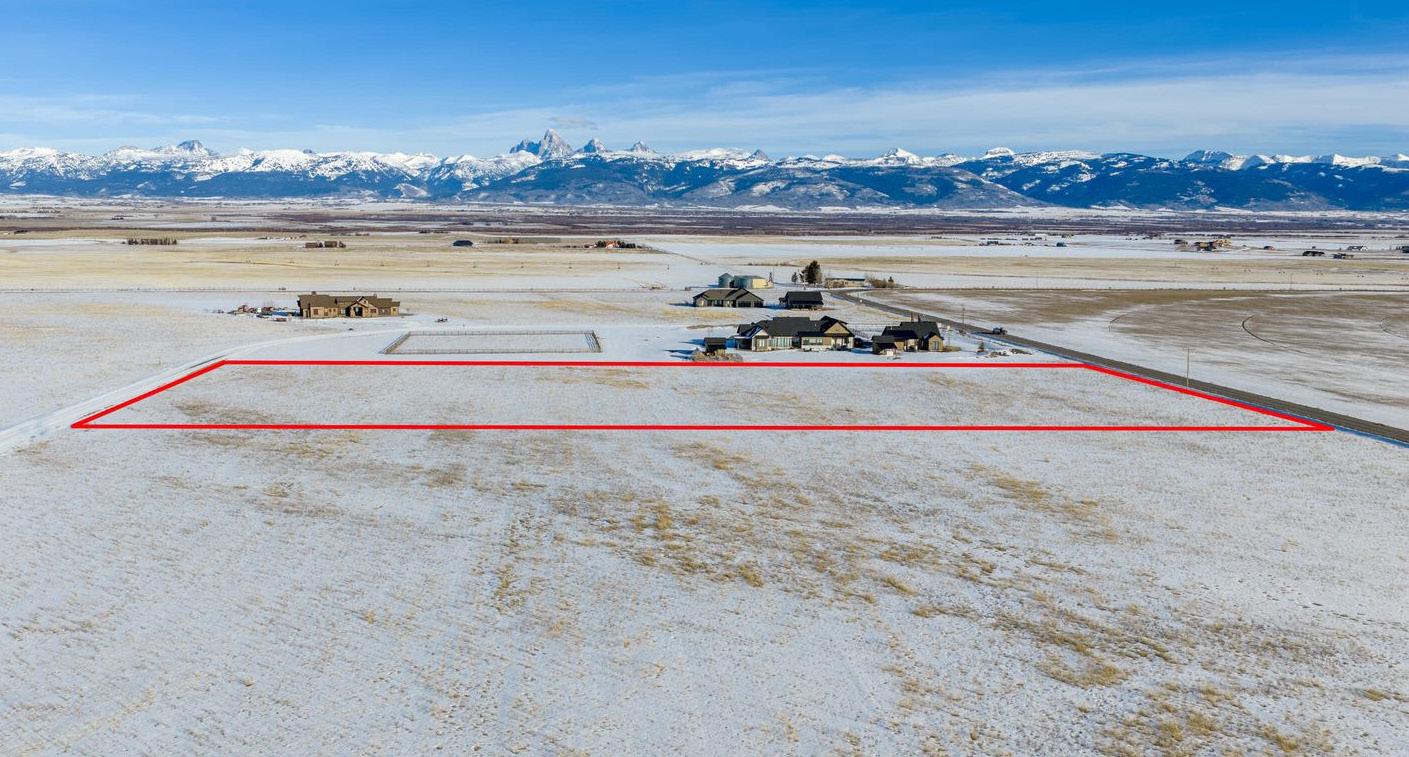
SOLD LISTED AT $340,000 DRIGGS REPRESENTED BY CARL
STRUTTMANN
The Teton Valley vacant land market gained modest momentum in Q2 2026, while performance varied by location. Based on submarket totals, sales increased from 124 to 128 transactions, while total dollar volume remained nearly unchanged at $48.4 million. This combination points to steady demand, but also reflects a market in which buyers continued to evaluate location, infrastructure, and development costs carefully.
Pricing strengthened at the midpoint of the market. The median sale price increased 28% to $285,000, while the average price was approximately $378,000. Driggs recorded the strongest dollar-volume growth, rising 59% as sales increased 14% and the median price climbed 35%. Tetonia also gained momentum, with transactions increasing 60% and its median rising 19%. Victor remained the most active submarket with 44 sales, although activity declined 23%, while Alta posted softer results across sales, pricing, and volume.
Pending listings increased 44% to 46, while average days on market declined 7% to 143 days, suggesting more efficient absorption. Active inventory totaled 219 parcels, providing buyers with a meaningful range of options. The quarter’s highest sale reached $5 million, up 30%, while the lowest sale declined to $75,000. Overall, Q2 2026 reflected a stable land market. Demand favored well-positioned, build-ready parcels, while pricing and location remained critical to successful outcomes.
MARKET STATS
Experience the Compass Real Estate difference by working with Jackson Hole’s leading real estate experts. We are a team of trusted advisors working collaboratively to leverage our collective knowledge and expertise to deliver fundamentally different services. For us, nothing matters more than creating a legacy of excellence that honors and celebrates our people and the exceptional place we call home.
To start your search of all active Jackson Hole listings, scan the QR code.