Market Becoming More Inventory-Rich While Still Benefiting From Strong Luxury Buyer Engagement
COMMUNITY UPDATES
SouthPark, Carmel, & Quail
Myers Park & Eastover
Lake Wylie & The Palisades
Providence, Weddington, & Waxhaw
Ballantyne & South Carolina
Center City Luxury Condos & Townhomes
FORECAST
Charlotte Market Sees Record Sales at Ultra Luxury Level
FEATURED LISTINGS
View Our Featured Listings on IvesterJackson com Visit Our Blog And Follow Us On Social Media For Market Forecasts, Interviews, and Marketing Ideas
IvesterJackson com/Blog @IvesterJacksonCharlotte
Market Becoming More Inventory-Rich While Still Benefiting From Strong Luxury Buyer Engagement
The Charlotte luxury and move-up market strengthened considerably during the second quarter of 2026 compared to the second quarter of 2025, with the strongest gains occurring in suburban luxury communities Ballantyne, Palisades, and especially Providence South, Weddington, and Waxhaw all posted meaningful increases in closed sales and showing activity, indicating buyers remain active despite higher inventory levels Luxury demand above $1 million continued to outperform many mid-market segments, particularly in Ballantyne, Providence, and Myers Park SouthPark remained more mixed, with softness in the $1 million to $2 million segment offset by stability at the ultra-luxury level Inventory has expanded throughout most communities, creating a more balanced environment than last year and generally extending absorption timelines into the 70-to-120-day range Showing activity increased in nearly every suburban market, suggesting buyer demand remains healthy even as purchasers take longer to make decisions Overall, the second quarter reflects a market that is becoming more inventory-rich while still benefiting from strong luxury buyer engagement
SOUTHPARK, CARMEL, & QUAIL
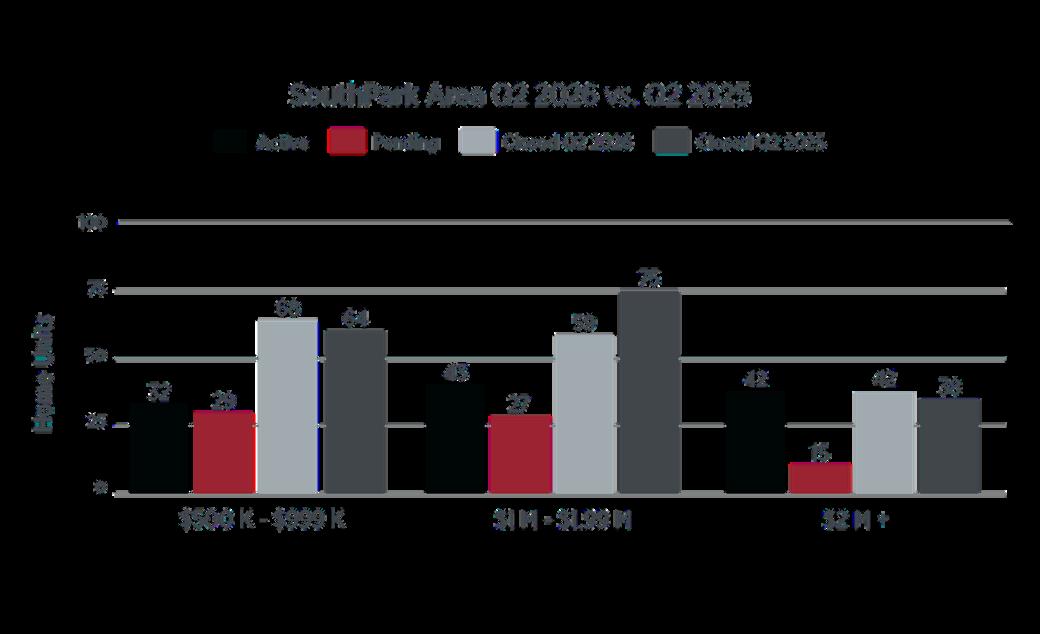
SouthPark remains a mixed market The $500K to $999K segment improved modestly from 64 to 68 closings, +6 3%, while the $1M to $2M segment declined from 75 to 59, -21.3%. The ultra-luxury $2M+ category increased from 38 to 42 sales, +10.5%.
With 117 active listings and 71 pending contracts, inventory equates to approximately 66 days of supply, indicating generally healthy market conditions despite uneven performance by price tier.
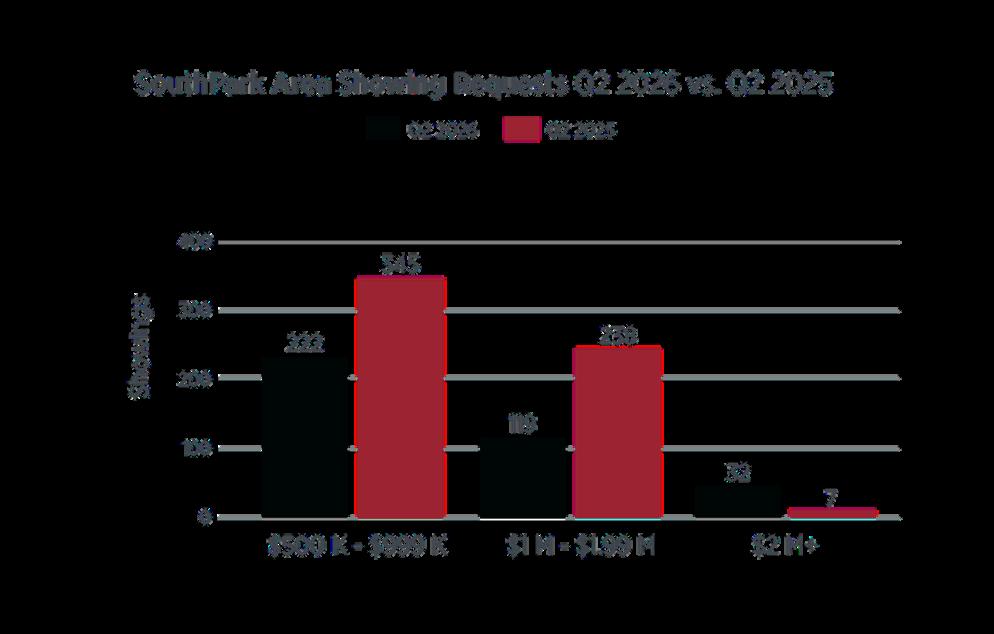
Showing trends varied dramatically:
$500K-$999K showings declined 35 7%
$1M-$2M showings declined 50 0%
$2M+ showings increased 357%
The largest variance in the report occurs here, where ultra-luxury buyer interest has surged while traditional luxury segments experienced noticeably softer traffic
SOUTHPARK AREA Q2 HOMES
SOLD & SHOWINGS
MYERS PARK & EASTOVER
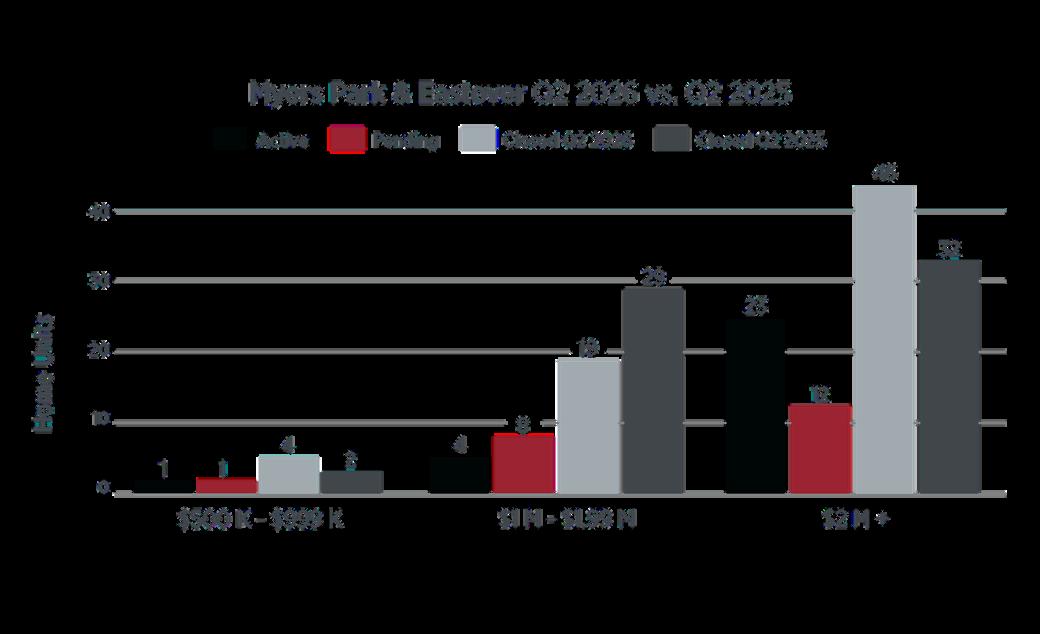
Myers Park and Eastover continued to demonstrate strength in the premium luxury category The $1M to $2M segment declined from 29 to 19 closings, -34.5%, while $2M+ sales jumped substantially from 32 to 46, +43 8% Sales below $1M remain too limited to establish meaningful trends
Active inventory totals 28 homes while pending sales total 21, yielding approximately 53 days of inventory supply, making this one of the tighter luxury markets in Charlotte
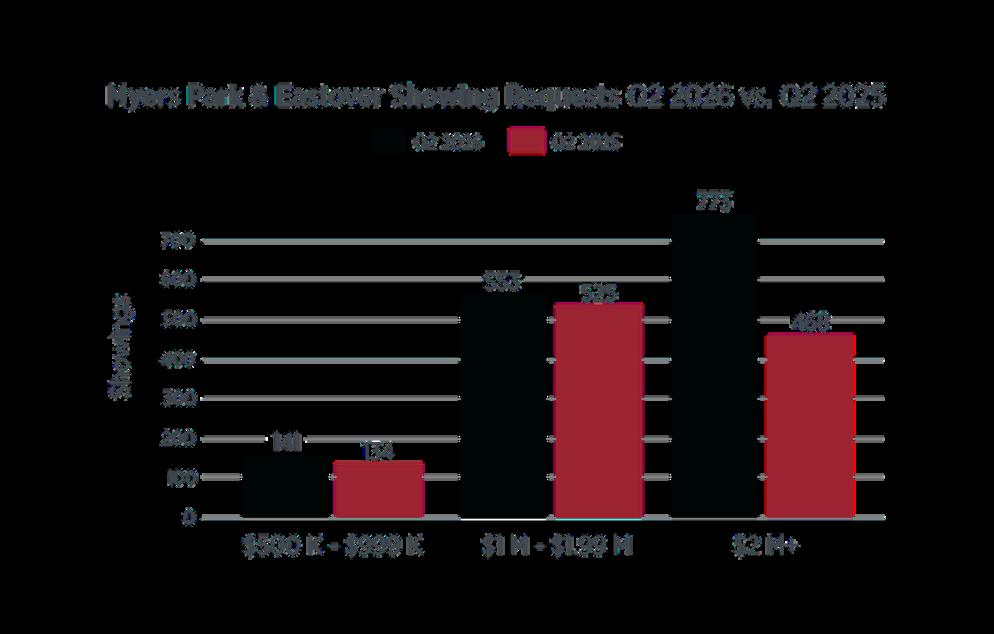
Showing Patterns Were Highly Segmented:
$500K-$999K showings increased 5.2%
$1M-$2M showings increased 5 3%
$2M+ showings increased 65 2%
The surge in ultra-luxury showings directly corresponds with higher closing totals, reinforcing continued demand for premier properties in Myers Park and Eastover
MYERS PARK & EASTOVER
HOMES SOLD & SHOWINGS
LAKE WYLIE & THE PALISADES
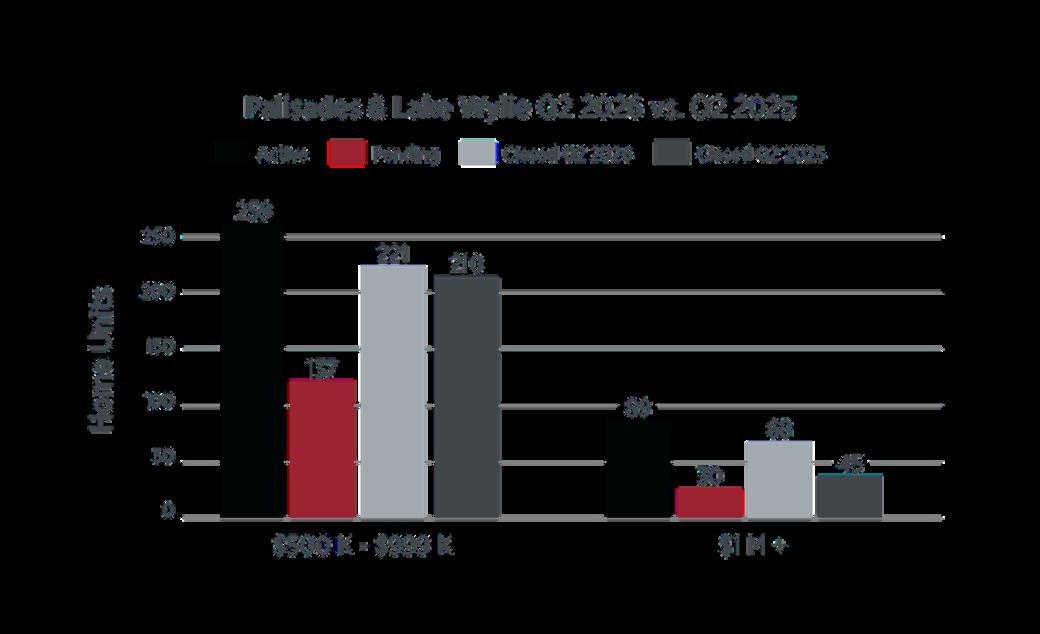
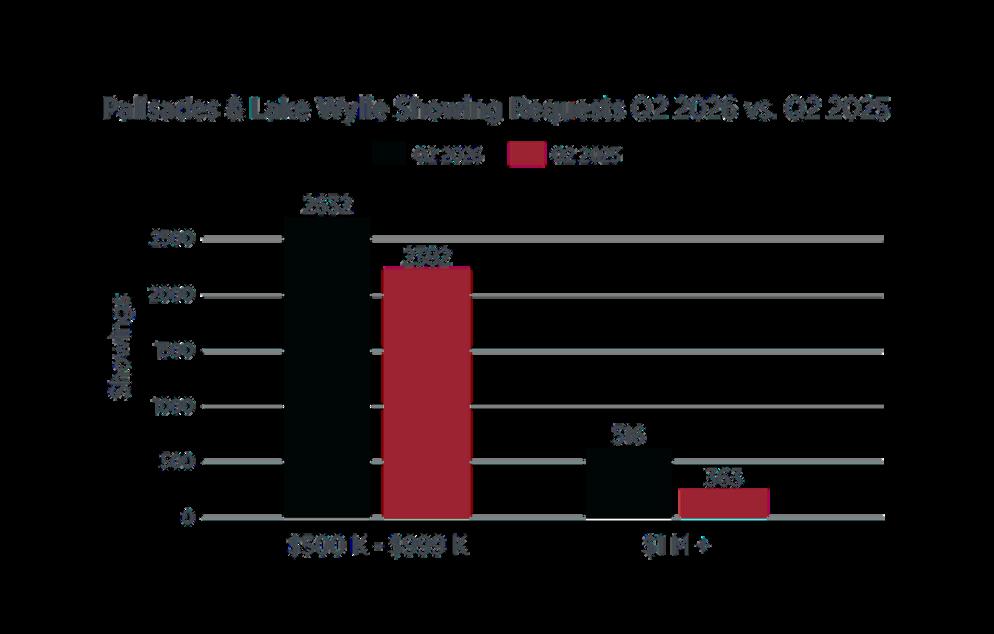
Palisades posted a solid improvement in quarterly closings The $500K to $999K segment increased from 210 to 221 sales, +5.2%, while luxury sales rose from 45 to 68, +51 1% Demand is strongest at the upper end of the market
Active inventory stands at 348 homes with 167 pending contracts, resulting in approximately 83 days of inventory supply. This represents slightly slower absorption than Ballantyne but remains healthy overall
Showings Rose Notably:
$500K-$999K showings increased 10 5%
$1M+ showings increased 42.1%
Luxury showing growth closely aligns with the substantial increase in closed sales, indicating genuine demand expansion rather than merely increased buyer curiosity
LAKE WYLIE & PALISADES
Q2 HOMES SOLD & SHOWINGS
PROVIDENCE, WEDDINGTON, & WAXHAW
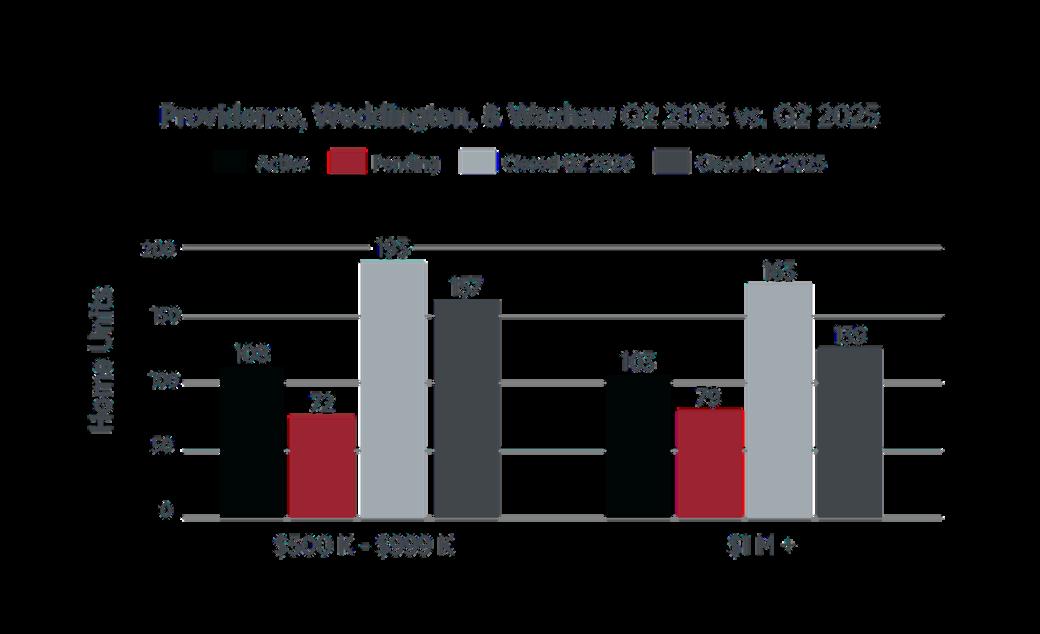
Providence South, Weddington, and Waxhaw delivered the strongest performance among all communities analyzed. Mid-market sales climbed from 157 to 193, +22 9%, while luxury closings increased from 139 to 163, +17 3% This market continues to attract significant move-up and luxury demand
Inventory remains well-controlled with 211 active listings versus 151 pending homes This equals roughly 56 days of inventory, making it the tightest suburban market in this analysis
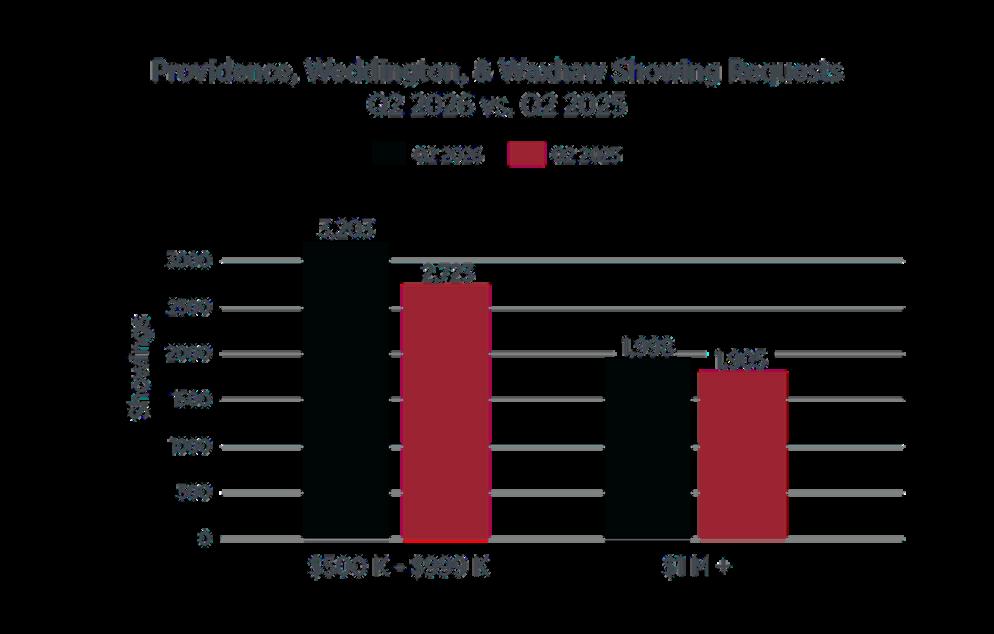
Showing Activity Supports The Strong Performance:
$500K-$999K showings increased 17.6%
$1M+ showings increased 4 9%
While luxury showings grew modestly, sales increased much faster, suggesting stronger conversion rates and serious buyer intent in the luxury segment.
PROVIDENCE,WEDDINGTON, & WAXHAW Q2 HOMES SOLD &
SHOWINGS
BALLANTYNE & SOUTH CAROLINA
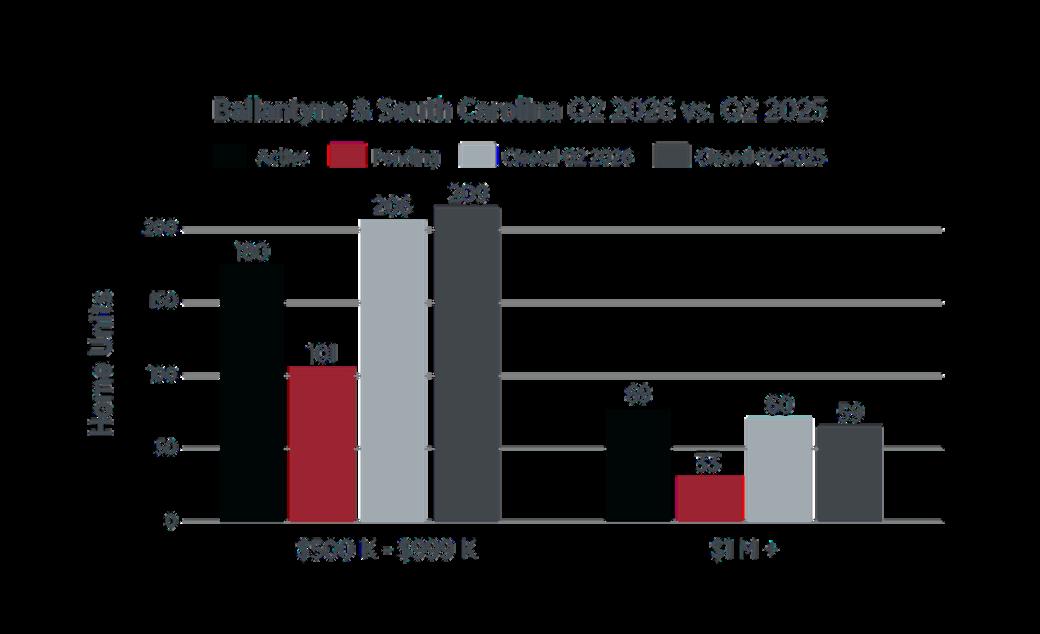
Closed sales remained generally stable year-over-year, with the $500K-$999K segment essentially flat, 206 vs 209 sales, while luxury sales rose slightly, 60 vs 59 The market is showing resilience with no meaningful pricing pressure evident in either direction Luxury $1M+ closed sales increased slightly but remained essentially flat year-overyear
Active inventory totaled 249 homes against 134 pending contracts Using 40 days per pending contract cycle, this represents approximately 74 days of available inventory, indicating a balanced market with moderate absorption
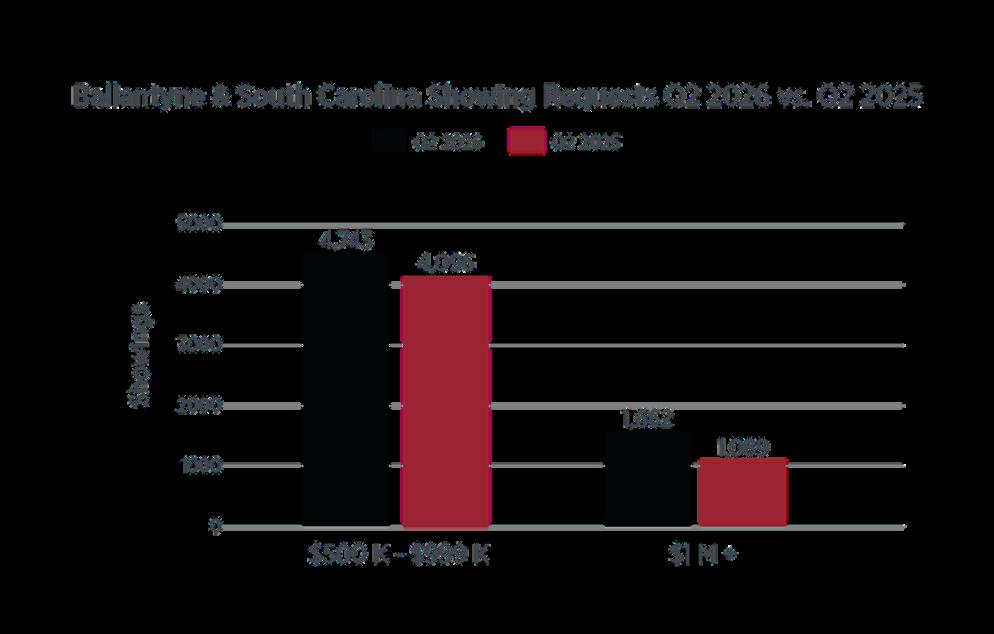
$500K-$999K showings increased 15 8%: 4,743 vs 4,096
$1M+ showings increased 52.6%: 1,662 vs 1,089
The increase in showings greatly exceeds the relatively flat sales growth, suggesting buyers are actively shopping but taking longer to transact
BALLANTYNE & SOUTH CAROLINA Q2 HOMES SOLD & SHOWINGS
CENTER CITY LUXURY CONDOS & TOWNHOMES
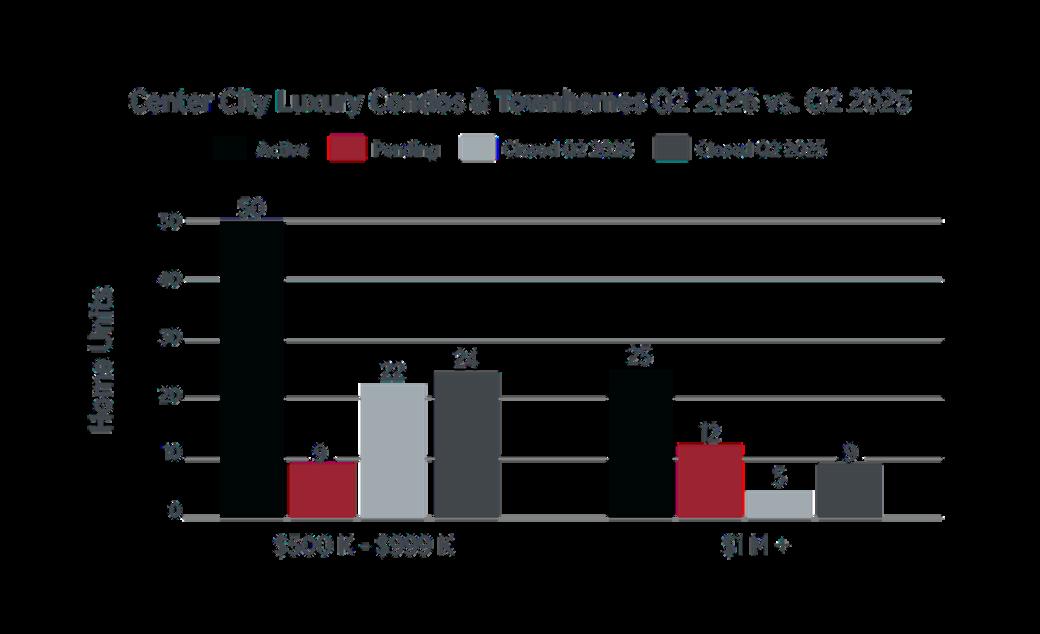
The condo market remained relatively flat overall Mid-range condo sales slipped from 24 to 22, -8 3%, while luxury condo sales declined from 9 to 5, -44 4% Demand appears weaker than the detached housing market.
Inventory totaled 75 units against only 21 pending contracts, producing approximately 143 days of supply, the slowest absorption rate among all categories reviewed.
The elevated inventory relative to pending contracts indicates buyers have abundant choices and little urgency Even with stable mid-market activity, the luxury condo segment remains challenged and is likely to experience longer marketing times than the single-family luxury market
CENTER CITY CONDOS & TOWNHOMES Q2 HOMES SOLD
While elevated equity markets powered the ultra luxury segment above $2 million in list price, including a state record Ivester Jackson | Christie's $15 million dollar closing in the Quail Hollow area, the more interest rate sensitive mid-market and entry level luxury segments saw flat/mixed results In some areas, new construction options drove results, while inventory levels continue to push up, though they have stabilized in the 75-100 day level for the most part, despite interest rates and inflation concerns. Overall traffic and interest continues to be solid at the upper ranges of the ultra-luxury market, which typically becomes more cyclical as we get closer to November. Currently, the balance of the third quarter looks to produce solid results paralleling the equity markets at the upper end, while stable activity appears to be the trend in the mid-range segments.