October 2020
The Danish Property Federation’s Market Statistics – Vacancy • Now the residential vacancy decreases • Corona has not yet affected the vacancy • Small increases in retail and office properties • Decrease in vacancy for industrial properties
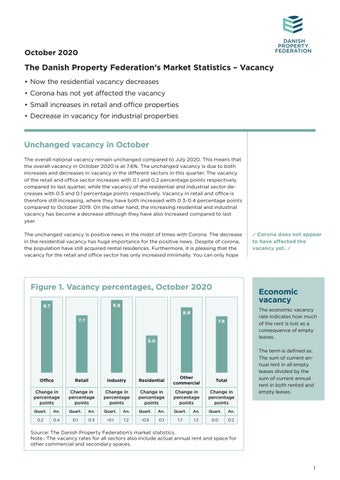
Unchanged vacancy in October The overall national vacancy remain unchanged compared to July 2020. This means that the overall vacancy in October 2020 is at 7.6%. The unchanged vacancy is due to both increases and decreases in vacancy in the different sectors in this quarter. The vacancy of the retail and office sector increases with 0.1 and 0.2 percentage points respectively compared to last quarter, while the vacancy of the residential and industrial sector decreases with 0.5 and 0.1 percentage points respectively. Vacancy in retail and office is therefore still increasing, where they have both increased with 0.3-0.4 percentage points compared to October 2019. On the other hand, the increasing residential and industrial vacancy has become a decrease although they have also increased compared to last year. The unchanged vacancy is positive news in the midst of times with Corona. The decrease in the residential vacancy has huge importance for the positive news. Despite of corona, the population have still acquired rental residences. Furthermore, it is pleasing that the vacancy for the retail and office sector has only increased minimally. You can only hope
Figure 1. Vacancy percentages, October 2020
Economic vacancy
9.8
9.7
The economic vacancy rate indicates how much of the rent is lost as a consequence of empty leases.
8.8 7.7
Corona does not appear to have affected the vacancy yet.
7.6
5.0
Office
Retail
Industry
Residential
Other commercial
Total
Change in percentage points
Change in percentage points
Change in percentage points
Change in percentage points
Change in percentage points
Change in percentage points
Quart.
An.
Quart.
An.
Quart.
An.
Quart.
An.
Quart.
An.
Quart.
An.
0.2
0.4
0.1
0.3
-0.1
1.2
-0.5
0.1
1.7
1.2
0.0
0.2
The term is defined as: The sum of current annual rent in all empty leases divided by the sum of current annual rent in both rented and empty leases.
Source: The Danish Property Federation’s market statistics. Note.: The vacancy rates for all sectors also include actual annual rent and space for other commercial and secondary spaces.
1
Danish Property Federation Market Statistics – Vacancy, October 2020
that the extended support packages from the Government can help keeping future vacancy increases in the business sector at an acceptable level. Positive tendencies in North Denmark Apart from the positive news in the residential and industrial sector, it is also encouraging to see the development taking place in North Denmark. The numbers from October 2020 show that the vacancy in the North Denmark Region is decreased in all sectors since last quarter. The numbers even show that the vacancy in North Denmark has decreased compared to October 2019.
Aalborg sees decreases in vacancy.
The positive results from the North Denmark Region are especially driven by the progress in Aalborg. The numbers also show that the vacancy in Aalborg has decreased since last quarter and has decreased compared to the same time last year. It is especially the retail sector, where Aalborg has seen the vacancy decrease with 1.3 percentage points compared to three months ago. Furthermore, the retail vacancy has increased with 0.7 percentage points compared to last year. In the residential sector, Aalborg has been placed high compared to the rest of the country, but this quarter, the residential vacancy decreases quarterly and annually with 1.0 and 0.8 percentage points. In the office sector, the decrease in vacancy is slightly smaller. It has increased with 0.3 percentage points since last quarter , and 0.8 percentage points since last year.
Figure 2. Development in economic vacancy Percent
25.0
20.0
25
Tomgang i procent
20
15.0
15
10
5
10.0
0 Hele landet
Region Hovedstaden Region Midtjylland A+B
C+D
Region Syddanmark
E+F+G
5.0
2002 2003 2004 2005 2006 2007 2008 2009 2010 Office
Retail
Industry
Residential
Jul.
Jul.
2019
Jan.
Jul.
2018
Jan.
Jul.
2017
Jan.
Jul.
2016
Jan.
Jul.
2015
Jan.
Jul.
2014
Jan.
Jul.
2013
Jan.
Jul.
2012
Jan.
Jul.
2011
Jan.
Jul.
Jan.
Jul.
Jan.
Jul.
Jan.
Jul.
Jan.
Jul.
Jan.
Jan.
Jul.
Jul.
Jan.
Jul.
Jan.
Jul.
Jan.
Jul.
2000 2001
Jan.
Jul.
Jan.
Jan.
0.0
2020
Total
Source: The Danish Property Federation Market Statistics and own calculations based on data from IPD Danish Property Index and Ejendomstorvets Market Index. Note.: Data from January 2014 and onwards is from the Danish Property Federation’s market statistics. From 2001 to 2013, numbers from IPD Danish Property Index are processed based on differences in level in 2014. In 2000, office data from Ejendomstorvets Market Index is included. The calculation methods are not similar which is why there i a gap in data between October 2013 and January 2014. From January 2014, the calculation is quarterly, while it is annual before 2014. From 2014, the data used is more detailed.
2
Danish Property Federation Market Statistics – Vacancy, October 2020
Office – Increase in vacancy In October 2020, the office vacancy is 9.7 percent. That is a small increase of 0.2 percentage points compared to July 2020 and an increase of 0.4 percentage points compared to the same time last year. Office vacancy is thus 1.2 percentage points higher than the average from 2000-2020. The national increase also appears in the Capital Region, the Region of Southern Denmark, and the Central Denmark Region, where the office vacancy has increased with 0.1, 0.6 and 0.5 percentage points compared to July 2020. It looks differently in Region Zealand and the North Denmark Region where the office vacancy has decreased with 0.30.4 percentage points compared to last quarter. These changes mean that the Region of Southern Denmark is the region with the highest office vacancy of 13.0 percent. Historically, it also appears that Southern Denmark in general has had a high office vacancy as it has decreased 0.9 percentage points since last year. This decrease could have been even bigger if the office vacancy had not increased with 0.6 percentage points in this quarter. At the other end, there is the Central Denmark Region with an office vacancy of 7.9 percent with is the lowest among the regions. This is despite increasing office vacancy in the region since the last quarter and last year. Compared to the same time last year, the office vacancy has increased with 0.6 percentage points in the Central Denmark Region. If we look at the regions, it is still the remote areas that have the highest office vacancy. In all regions, it can be seen that the large cities have the lowest vacancy rates. However, it can also be seen that the office vacancy in the large cities, except Aalborg, has increased since July. Office vacancy has increased with 1.4 percentage points in Odense to 10.4 percent while the office vacancy in Copenhagen and Aarhus has increased with 0.4 and 0.6 percentage points. In Aalborg, the office vacancy decreases with 0.3 percentage points to 7.7 percent. Compared to last year, the office vacancy in Aalborg has decreased with 0.4 percentage points. The office sector in Aalborg thus continues its positive trend with a decreasing vacancy. However, Aarhus is still the city with the lowest office vacancy with 7.1 percent. This is despite increasing trends in the city where the office vacancy has also increased with 0.6 percentage points compared to the same time last year.
The North Denmark Region continues its positive trend.
Aarhus still has the lowest office vacancy.
3
Danish Property Federation Market Statistics – Vacancy, October 2020
Economic vacancy rate October 2020 (percent)
Quarterly change (percentage points)
Annual change (percentage points)
9.6
0.1
0.6
Copenhagen Centre
8.8
0.4
3.5
Other City of Copenhagen
9.4
0.6
1.9
Northern Zealand
10.7
-0.2
-3.4
Other Capital Region
10.2
-0.6
-2.2
12.2
-0.3
-0.9
Eastern Zealand
12.9
-1.9
-0.4
Western and Southern Zealand
11.8
0.9
-1.3
The Region of Southern Denmark
13.0
0.6
-0.9
Odense
10.4
1.4
1.4
Triangle Area
12.8
-1.4
-7.1
Other Southern Denmark
15.8
1.4
1.2
7.9
0.5
0.6
Table 1. Office Capital Region
Region Zealand
Central Denmark Region Aarhus Other Central Denmark North Denmark Region Aalborg Other North Denmark Total
7.1
0.6
0.6
10.7
0.1
1.1
9.5
-0.4
-2.3
7.7
-0.3
-0.8
20.1
-1.1
-9.4
9.7
0.2
0.4
Source: The Danish Property Federation Market Statistics.
4
Danish Property Federation Market Statistics – Vacancy, October 2020
Retail - Slight increase in vacancy The retail vacancy increases slightly with 0.1 percentage points compared to July 2020. It means that retail vacancy is at 7.7 percent in October 2020. It is 0.3 percentage points higher than the retail vacancy in October 2019. Thereby, the retail vacancy is thus 0.9 percentage points higher than the historical average from 2000-2020. The quarterly increase also takes place in the Capital Region and Region Zealand, where there has been an increase of 0.2 og 0.3 percentage points respectively. In the Central Denmark Region and the North Denmark Region, the retail vacancy decreases with 0.2 and 0.9 percentage points respectively compared to last quarter, while it is unchanged in the Region of South Denmark. Despite the relatively large decrease in North Denmark, the Central Denmark Region is still lower with a retail vacancy of 6.8 percent. At the same time last year, the retail vacancy in Central Denmark was even lower, when it was at 0.3 percentage points lower than the vacancy in this quarter.
The Central Denmark Region still has the lowest retail vacancy.
In the Central Denmark Region, Aarhus (6.9 percent) has a higher vacancy than Other Central Denmark (6.7 percent). However, the difference is minimal as Aarhus has a retail vacancy which is 0.2 percentage points higher than in Other Central Denmark. However, it can be seen that the minimal difference is due to the changes compared to last quarter. Here, the retail vacancy has increased fairly significantly with 0.7 percentage points in Aarhus, while is has increased with 0.5 percentage points in Other Central Denmark. Compared to the same time last year, they have both increased with 0.2-0.4 percentage points.
Aarhus sees a significant decrease.
Compared to other cities, the retail vacancy in Aarhus is low. However, they do not have the lowest retail vacancy among the cities. In Copenhagen Centre, Odense and Aalborg, the retail vacancy is at 7.5, 9.6 and 5.9 percent respectively. Aalborg thus has the lowest retail vacancy among the cities. This is aided by a decrease of 1.3 percentage points compared to July and a decrease of 0.7 percentage points compared to the same time last year. On the other hand, Odense sees an increase of 1.1 percentage points compared to last quarter and an annual increase of 2.5 percentage points.
Lowest retail vacancy in Aalborg.
5
Danish Property Federation Market Statistics – Vacancy, October 2020
Economic vacancy rate October 2020 (percent)
Quarterly change (percentage points)
Annual change (percentage points)
7.5
0.2
0.1
Copenhagen Centre
8.7
0.6
1.1
Other City of Copenhagen
5.4
-0.4
-0.6
Northern Zealand
8.7
-0.5
0.3
Other Capital Region
7.6
0.4
-0.3
8.6
0.3
1.7
Eastern Zealand
8.3
0.4
0.6
Western and Southern Zealand
8.9
0.1
2.6
The Region of Southern Denmark
9.6
0.0
0.1
Table 2. Retail Capital Region
Region Zealand
Odense
9.6
1.1
2.5
Triangle Area
9.5
-0.7
-0.8
Other Southern Denmark
9.7
-0.1
-1.0
6.8
-0.2
0.3
6.9
-0.7
0.4
Central Denmark Region Aarhus Other Central Denmark
6.7
0.5
0.2
7.4
-0.9
-0.6
Aalborg
5.9
-1.3
-0.7
Other North Denmark
11.6
-0.2
-0.7
7.7
0.1
0.3
North Denmark Region
Total
Source: The Danish Property Federation Market Statistics.
6
Danish Property Federation Market Statistics – Vacancy, October 2020
Industry - Small decrease in vacancy Despite increases in industrial vacancy in recent quarters, it decreases with 0.1 percentage points compared to July 2020. It means that the industrial vacancy is at 9.8 percent in October 2020 and that it is 1.2 percentage points higher than the same time last year. The industrial vacancy is thus 1.7 percentage points lower than the average rate from 2000-2020. The overall decrease in industrial vacancy has been helped by quarterly decreases in both Region Zealand, the Region of Southern Denmark and the Region of North Denmark, where the vacancy has decreased with 1.3, 0.3 and 0.2 percentage points respectively. On the other hand, the industrial vacancy increases slightly in the Capital Region and Central Denmark with 0.1 percentage points compared to July. Therefore, Region Zealand sees the largest change in the industrial sector with a decrease of 1.3 percentage points in vacancy and is thus at an industrial vacancy of 8.6 percent in October. However, it is the Region of Southern Denmark and the North Denmark Region that have the lowest rates among the regions. The Region of Southern Denmark has an industrial vacancy of 5.5 percent while the North Denmark Region has a vacancy of 5.2 percent. These two regions also see significant annual decreases in industrial vacancy, where the Region of Southern Denmark has decreased with 2.6 percentage points since last year and the North Denmark Region has decreased with 5.2 percentage points since last year.
Lowest industrial vacancy in the Region of South Denmark and Region of North.
The Capital Region, however, still has a higher industry vacancy, which can also be seen in the areas in the region. Here, all the areas have an industrial vacancy of at least 10.5 percent. However, the industrial vacancy has decreased in Copenhagen Centre and Northern Zealand since last quarter with 0.3 and 0.7 percentage points respectively. On the other hand, the industrial vacancy has increased in Other City of Copenhagen and Other Capital Region.
Economic vacancy rate
Table 3. Industry Capital Region Copenhagen Centre Other City of Copenhagen
October 2020 (percent)
Quarterly change (percentage points)
Annual change (percentage points)
11.7
0.1
1.3
14.0
-0.3
3.0
11.7
0.5
-0.1
Northern Zealand
25.0
-0.7
-3.4
Other Capital Region
10.5
0.1
1.2
Region Zealand
8.6
-1.3
1.2
The Region of Southern Denmark
5.5
-0.3
-2.6
Central Denmark Region
7.2
0.1
4.6
10.1
0.5
4.7
North Denmark Region
5.2
-0.2
-5.2
Total
9.8
-0.1
1.2
Aarhus
Source: The Danish Property Federation Market Statistics.
7
Danish Property Federation Market Statistics – Vacancy, October 2020
Residential - Significant decrease in vacancy
Small leases have the lowest vacancy - and it is decreasing.
After small increases in residential vacancy in the last couple of quarters, the residential vacancy decreases in October 2020. The residential vacancy has decreased with 0.5 percentage points since July but has increased with 0.2 percentage points since October last year. It means that the residential vacancy is 5.0 percent this quarter. Residential vacancy is thus 1.5 percentage points higher than the average from the period 20002020. The residential vacancy should still decrease further - considering the demand for residences. The decrease is due to a decrease in all regions apart from Region Zealand, where the residential vacancy has remained at 4.9 percent. If you examine Region Zealand, it can also be seen that there are no changes in both Eastern, Western and Southern Zealand. The largest quarterly decrease can be seen in The North Denmark Region, where the residential vacancy has decreased with 0.9 percentage points to 7.0 percent, which is an annual decrease of 0.7 percentage points. Right behind is Southern Denmark with a decrease of 0.8 percentage points. It means that Southern Denmark has the lowest residential vacancy (4.0 percent) among the regions. However, it seems that the residential vacancy in Southern Denmark has been even lower, as it has increased with 1.2 percentage points since last year. In both the Capital Region and the Central Denmark Region, the residential vacancy has decreased with 0.5 percentage points.
Positive trends in Aarhus and Aalborg.
The decrease in the overall vacancy rate in the residential sector can also be seen in the different cities. Especially Copenhagen Centre and Aalborg with decreases of 1.1 and 1.0 percentage points respectively. In Aarhus, the residential vacancy decreases with 0.7 percentage points, while the residential vacancy has decreased with 0.5 percentage points in Odense since last quarter. It appears that Aalborg and Aarhus continues the trend with a decrease in residential vacancy. Both cities have experienced an annual decrease in residential vacancy of between 0.8-1.2 percentage points. Compared to last year, the residential vacancy has increased in both Copenhagen Centre and Odense with 1.0 and 2.5 percentage points respectively. However, the annual increase in residential vacancy in Odense comes from a low rate so that Odense together with Aarhus are the cities with the lowest residential vacancy with 4.5 percent. Aalborg and Copenhagen are two of the areas that experience decrease in the residential vacancy. It applies to both areas that there are more new rentals than change of addresses. Furthermore, it also applies that the residential vacancy decreases for smaller leases and the large leases. Compared to last quarter, the vacancy for leases in the size of 75-99 square metres increase slightly while the residential vacancy for leases below 75 square metres decrease and it is those rental properties that have the lowest vacancy - 4.5 percent in Aalborg and 3.6 percent in Copenhagen Centre. Nationally, leases below 75 square metres have a vacancy of 3.1 percent and compared to last quarter, it has decreased with 0.3 percentage points. Nationally, leases from 75-99 square metres have a vacancy of 5.1 percent and contrary to the tendency in Copenhagen Centre and Aalborg, the vacancy in these leases decrease by 0.4 percentage points.
8
Danish Property Federation Market Statistics – Vacancy, October 2020
Economic vacancy rate
Table 4. Residential Capital Region
October 2020 (percent)
Quarterly change (percentage points)
Annual change (percentage points)
5.1
-0.5
0.5
Copenhagen Centre
7.3
-1.1
1.0
Other City of Copenhagen
4.9
-0.8
-0.3
Northern Zealand
4.7
0.4
1.9
Other Capital Region
5.2
0.3
1.6
4.9
0.0
-0.5
Eastern Zealand
4.0
0.0
1.0
Western and Southern Zealand
5.2
0.0
-1.3
Region Zealand
Region Syddanmark
4.0
-0.8
1.2
Odense
4.5
-0.5
2.5
Triangle Area
3.9
-2.2
-0.2
Other Southern Denmark
3.4
-0.4
-0.6
4.7
-0.5
-1.2
Aarhus
4.5
-0.7
-1.2
Other Central Denmark
5.4
0.1
-1.3
7.0
-0.9
-0.8
6.9
-1.0
-0.8
8.1
0.5
-0.1
5.0
-0.5
0.1
Central Denmark Region
North Denmark Region Aalborg Other North Denmark Total
Source: The Danish Property Federation Market Statistics.
9
Danish Property Federation Market Statistics – Vacancy, October 2020
Geographical overview Copenhagen Centre
Christiansborg Christianshavn
Tivoli
Northern Jutland Region
Aalborg
Mid Jutland Region
Aarhus Northern Zealand Capital Region
Triangle Area
Copenhagen Centre Zealand Region
Southern Denmark Region
Odense
Western and Southern Zealand
Eastern Zealand
Other Copenhagen Municipal Other Capital Region
Source: The Danish Property Federation Market Statistics. Note: Copenhagen Centre consists of Copenhagen inner city covering the zip codes: 900, 1000-1431, 1434-1438, 1448-1559, 1562-1609, 1611-1614 og 1631-1634.
10
Danish Property Federation Market Statistics – Vacancy, October 2020
About the Market Statistics This web report is published 27 October 2020. Next scheduled publication is February 2021. The portfolios have approx. 220,000 leases corresponding to an annual rental-bearing value of DKK 37.2 bn and 34.2 m m2. In comparison, the statistical base in October 2019 was 180,000 leases with an annual rental-bearing value of DKK 32,3 bn and 30,2 m m2. Today, 16,300 properties* are included in the market statistics. It is the current annual rent that is included in the calculation of the economic vacancy rate. The economic vacancy rate is defined as: The sum of current annual rent in all empty leases divided by the sum of current annual rent in both rented and empty leases. The Market Statistics is based on quarterly processed property data for rentals and vacancies within the period in question. Compared to previous publications, the balance date has been changed from the last day of the last quarter to the first day of this quarter. This web report has thus been closed as of 1 October 2020 and is called October 2020. The quarterly change is from October 2020 (settled as of 1 October 2020) compared to July 2020 (settled as of 1 July 2020). The quarterly change is from October 2020 (settled as of 01 October 2020) compared to October 2019 (settled as of 30 September 2019). The published market data is updated and valid on the day of publication. As the market statistics are continuously updated with e.g. new historical data, there may be updates of historical data. It has been chosen not to publish data in the statistics where the basis has been evaluated not to provide valid and representative data or in combinations where only one or a few portfolios are represented. * The number of properties include properties and parent properties. A property can include one or more buildings and one or more residential or office units. A parent property includes a property, in which there are apartments, which are registered as independent properties. For these units it is the parent properties that are counted and not the individual apartment.
Further information If you wish to know more about this publication please contact Director in the Danish Property Federation
Morten Marott Larsen mml@ejd.dk Phone +45 28 45 56 51
This report is based on data from 2 + 3 Ejendomme, Aarhus Kommune, Aberdeen Asset Management, Advice, Advodan, Akelius, Alm. Brand, ALN Holding, Andersen Partners Ejendomsadministration, Anker Bay Petersen, AP Pension, Arbejdernes Landsbank, Arkitekternes Pensionskasse, Arup & Hvidt, ATP, Bagenkop Ejendomme A/S, Balder Ejendomme, Ballegaard Gruppen, Bangs Gård A/S, Bank Lauridsen, Barfoed Group, Bellevue 16 ApS, Bendtsen ApS, Bernhard Guhle, Bernstorrfhus, Bevica Fonden, Birch Ejendomme, BladhuseneApS, Blue Vision, Bodil og Co. I/S, Bolig Data Administration, Bolig og erhvervsudlejning I/S, Boligexperten Adm. A/S, Boliggruppen, Boligstandard ApS, BoStad A/S, Brdr. Christiansens Boligudlejning, Bregentved Gruppen, Broen Shopping, Bruno Dall, Calum A/S, Carlsbergfondet, CBRE, CEJ Ejendomsadministration, Cieslak Ejendomme, CK Holding Odense I/S, Claus Sørensen, CMNRE II FV181 PropCo ApS, CMNRE II Goose PropCo II A/S, Cobblestone, Coller Capital, Compaz Ejendomme A/S, Cosmo Ejendomme ApS, Connla Administraion, CS Pensionsfond, CW Obel Ejendomme, DADES, Danica, Dansk Administrationscenter, Danagraf A/S, Dansk Sygeplejeråd, Danske Bank, Danske Shoppingcentre, DATEA, DEAS, DEAS Invest 1, De Københavnske Ejendomsselskaber, Demant Advokater, Difko, DIKEV, DIP, DK Ejendomme, DNP Ejendomme, Domhusgaarden Ejendomsadministration, Domis Ejendomme, Dreist-Storgaard, Drachmann Ejendomsadministration, DSB Ejendomme, Egen Vinding & Datter ApS, Ejd. Selskabet Dronning Olgas Vej 15 ApS, Ejendommen Hauchsvej 16 I/S, EjendomDanmark, Ejendomskontoret, Ejendomsselskaberne, Ejendomsselskabet af 15. maj 1895, Ejendomsselskabet Aunbøll A/S, Ejendomsselskabet NEMP, Ejendomsselskabet Thy, Ejendomsselskabet Østervold, Elverhøj Investment Group ApS, Estate Invest, Etex Ejendomme, Erhverv Aalborg, EV bolig, Fast Ejendom Danmark, Flemming Jeppsson, Flemming Olsen, Flemming Sørensen, Fokus Asset Management, Forskningsfondens Ejendomsselskab A/S, Frederiksberg Fonden, Freja Ejendomsadministration, Friheden Ejendomme A/S, Færchfonden, Gammeltorv Ejendomme, Goldschmidt Ejendomme A/S, Grosserer Schiellerup og Hustrus Fonde, Gudbjørg og Ejnar Honorés Fond, Grønløkkevej 10, Grønnegaarden Ejendomsselskab, Hans Nielsen, HEA Ejendomme, Hegela Erhvervsudlejning, Heimstaden, Helle Duun, Hestia, Hjørnet, Home Holbæk, Hovedstadens Ejendomsadministration, Hosta Ejendomme, Humlebogruppen, Højgaard Ejendomme, Industriens Pension, Investorgruppen, Jammerbugt Kommune, Jens Garfalk, Jeudan, JH Administration, JJ Ejendomsadministration, Jorcks Ejendomsselskab, JØP, Kaj Pedersen, Kalkværksgrundene, Kalvebod Ejendomme, Karberghus, Kayhan Development, KEBLOH ApS, Kereby A/S, KFI Erhvervsdrivende Fond, KIRKBI, KHK’s Legat, KGV Aarhus ApS, KLP Ejendomme, Koncenton, Kongeegen, Kramers Legat, K/S Ingolf Nielsens Vej Sønderborg, K/S Roskilde Retail Park II, Københavns Kommune, Køge Kommune, Laros, Lars Wissing, LB Forsikring, Levring & Levring,Lindhart Ejendomsadministration, Lyngby Kommune, Lægernes Pensionskasse, Lærernes Pension, M7 Real Estate ApS, Michael Westh-Jensen, Midtbyens Ejendomme, Minova, Mogens Westh-Jensen, Moltzen Administration, Mogens Nielsen, Morten Norberg,MP Pension, MOWE Holding ApS, NEMO Ejendomsadministration, Nemp Ejendomsadministration, Niam, Niels Møller, Nielsen & Nielsen Ejendomme A/S, Nordea Ejendomme, Nordea Liv og Pension, North Property Asset Management, NREP, Odense Bolig ApS, Ole Hartvig, PBU, Pears, PenSam, PensionDanmark, Pensionskassen for Farmakonomer, PFA, Pfeiffer Ejendomme ApS, PIA, Rasch-Andersen Ejendomme ApS, Rathleff Ejendomme, International, Palæ Ejendomsadministration, Pitzner Ejendomme, PKA, PN Ejendomme, Postbudenes Byggeforening, Probus, ProDomus, Qvoutrup Administration A/S, Realdania, Revisorteamet, Roskilde Fællesbageri ApS, Rødovre Centrum A/S, Sampension, SEB, Samrådets Boligselskab / Dronning Louises Stiftelse, Siersbo ApS, Skovly Ejendomme, Sofus Administration ApS, SparNord Ejendomme Aalborg, Storck Holding, Svanholt Ejendomme, SPG Omsorg DK1, Steen & Strøm, Syddan A/S, Taurus Ejendomsadministration, TDC Pensionskasse, Thisted Kommune, Thylander Gruppen Sixpack, TLK Ejendomme, TLP ApS, Tom Jensen, Topdanmark, Totalbyg, Tox Development, Tryg, T.T. Invest ApS, UBSBOLIG A/S, Unico Finans ApS, Vagner P, Valby Maskinfabrik 1ApS, Valad, VEA ApS, Vestegnens Boligadministration, Vestjysk Ejendomsadministration ApS, Vestsjællandske Ejendomme ApS, Volantis A/S, VOPA Ejendomsadministration ApS, V.M. Brockhuus Ejendomme, Wagner Ejendomme, West Star Property Holding ApS, Wihlborg, Wind Administration, V12 ApS, Øens Ejendomsadministration, Aalborg Boligadministration og Aage Larsens Boligudlejning.
11
Danish Property Federation Market Statistics – Vacancy, October 2020
Appendix Figure 3. Spatial vacancy rate, October 2020 10.9 9.3
8.7 7.8
7.3 4.9
Office
Retail
Industry
Residential
Other commercial
Total
Change in percentage points
Change in percentage points
Change in percentage points
Change in percentage points
Change in percentage points
Change in percentage points
Quart.
An.
Quart.
An.
Quart.
An.
Quart.
An.
Quart.
An.
Quart.
An.
0.0
0.4
0.0
1.1
-0.3
-1.5
0.1
1.3
0.7
3.1
0.0
1.9
Source: The Danish Property Federation’s market statistics. Note.: The vacancy rates for all sectors also include actual annual rent and space for other commercial and secondary spaces.
Spatial vacancy rate
Table 5. Office Capital Region Copenhagen Centre
October 2020 (percent)
Quarterly change (percentagepoints)
Annual change (percentage points)
10.6
0.0
0.4
7.3
1.8
3.1
7.1
-0.6
-1.3
Northern Zealand
15.6
-1.4
1.0
Other Capital Region
14.7
0.0
0.6
15.1
0.6
2.6
Eastern Zealand
13.9
0.4
5.5
Western and Southern Zealand
16.0
1.0
1.4
The Region of Southern Denmark
14.0
-0.2
0.0
7.8
-0.8
-1.3
Triangle Area
18.5
0.1
3.1
Other Southern Denmark
16.9
0.2
-0.9
8.4
0.0
0.9
Other City of Copenhagen
Region Zealand
Odense
Central Denmark Region Aarhus Other Central Denmark North Denmark Region Aalborg Other North Denmark Total
7.3
-0.2
0.1
10.6
0.4
2.0
13.1
0.0
-2.0
11.8
-0.2
-3.1
18.0
0.7
10.9
0.0
Source: The Danish Property Federation’s market statistics. 12
0.4
Danish Property Federation Market Statistics – Vacancy, October 2020
Spatial vacancy rate
Table 6. Retail Capital Region Copenhagen Centre
October 2020 (percent)
Quarterly change (percentagepoints)
Annual change (percentage points)
7.0
0.2
0.8
7.9
1.5
1.5
Other City of Copenhagen
5.6
0.1
0.8
Northern Zealand
8.4
-1.1
1.5
Other Capital Region
7.5
0.0
0.5
7.5
0.3
1.7
Eastern Zealand
6.3
0.6
1.7
Western and Southern Zealand
8.6
0.2
1.5
The Region of Southern Denmark
8.7
0.0
0.8
Region Zealand
Odense
6.5
0.5
0.2
Triangle Area
9.7
-0.2
0.9
Other Southern Denmark
9.5
-0.1
1.1
7.4
-0.8
1.3
7.0
-1.1
2.6
Central Denmark Region Aarhus Other Central Denmark North Denmark Region Aalborg Other North Denmark Total
7.8
-0.4
-0.3
6.8
0.2
2.7
6.7
0.1
3.0
7.1
0.4
7.3
0.0
1.1
Source: The Danish Property Federation’s market statistics.
Spatial vacancy rate
Table 7. Industry Capital Region
October 2020 (percent)
Quarterly change (percentagepoints)
Annual change (percentage points)
10.0
0.1
-1.5
Copenhagen Centre
17.6
0.6
-0.2
Other City of Copenhagen
10.2
-0.7
-1.8
Northern Zealand
19.2
-0.3
-4.8
9.1
0.2
-0.9
8.1
-0.7
0.2
The Region of Southern Denmark
4.9
-3.4
-10.0
Central Denmark Region
7.6
1.0
2.5
12.9
0.4
8.5
Other Capital Region Region Zealand
Aarhus North Denmark Region Total
14.7
1.5
8.7
-0.3
-1.5
Source: The Danish Property Federation’s market statistics.
13
Danish Property Federation Market Statistics – Vacancy, October 2020
Table 4. Residential
Spatial vacancy rate October 2020 (percent)
Quarterly change (percentagepoints)
Annual change (percentage points)
4.3
0.0
1.3
Copenhagen Centre
5.7
-0.3
1.4
Other City of Copenhagen
4.4
-0.2
1.4
Northern Zealand
4.3
0.8
1.6
Other Capital Region
3.7
0.2
1.0
5.6
0.0
0.6
Eastern Zealand
3.2
1.0
1.0
Western and Southern Zealand
6.7
-0.3
0.8
The Region of Southern Denmark
3.8
0.2
1.6
3.5
0.0
2.4
Capital Region
Region Zealand
Odense Triangle Area
3.9
0.4
0.8
Other Southern Denmark
4.2
0.4
0.6
5.9
0.2
1.5
Aarhus
5.6
0.5
1.1
Other Central Denmark
6.9
-0.5
2.5
Central Denmark Region
North Denmark Region
7.9
0.2
0.9
Aalborg
7.9
0.3
0.9
Other North Denmark
8.0
-0.5
0.7
4.9
0.1
1.3
Total
Source: The Danish Property Federation’s market statistics.
14