Market Intelligence · Investor Brief
Report 02 · Global Sports & Recreation Series · September 2026
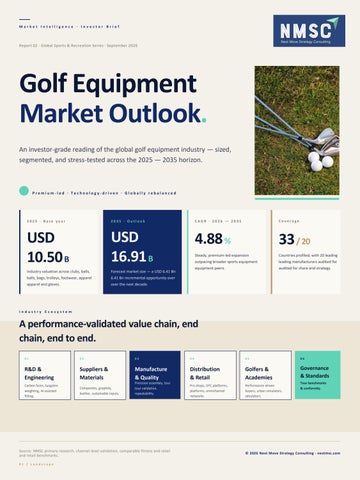
Golf Equipment Market Outlook. An investor-grade reading of the global golf equipment industry — sized, segmented, and stress-tested across the 2025 — 2035 horizon.
Premium-led · Technology-driven · Globally rebalanced
2025 · Base year
2035 · Outlook
CAGR · 2026 — 2035
Coverage
USD 10.50 B
USD 16.91 B
4.88 %
33 / 20
Steady, premium-led expansion
Countries profiled, with 20 leading
outpacing broader sports equipment
leading manufacturers audited for
Industry valuation across clubs, balls,
Forecast market size — a USD 6.41 Bn
equipment peers.
audited for share and strategy.
balls, bags, trolleys, footwear, apparel
6.41 Bn incremental opportunity over
apparel and gloves.
over the next decade.
Industry Ecosystem
A performance-validated value chain, end chain, end to end. 01
02
03
04
05
06
R&D & Engineering
Suppliers & Materials
Manufacture & Quality
Distribution & Retail
Golfers & Academies
Governance & Standards
Carbon faces, tungsten weighting, AI-assisted fitting.
Composites, graphite, leather, sustainable inputs.
Precision assembly, tour tour validation, repeatability.
Pro shops, DTC platforms, platforms, omnichannel networks.
Performance-driven buyers, urban simulators. simulators.
Source: NMSC primary research, channel-level validation, comparable fitness and retail and retail benchmarks. 01 / Landscape
Tour benchmarks & conformity.
© 2026 Next Move Strategy Consulting · nextmsc.com
Slide 02 · Demand & Opportunity Architecture
Growth Drivers. Where the next decade compounds. Four premium-led tailwinds, plus a USD 38 Bn indoor simulator lift, contribute a combined ~+3.1% net CAGR across 2026 CAGR across 2026 — 2035.
01 · PRIMARY DRIVER
02 · TAILWIND
+1.0% CAGR
+0.8% CAGR
Premium upgrade cycles
Indoor simulator ecosystems
Carbon-composite faces, tungsten weighting and AI-assisted fitting shorten
Year-round data-rich training in dense urban centres stabilises demand and
shorten replacement intervals and lift average selling prices across drivers and
pulls premium fitting traffic into a measurable funnel.
drivers and irons.
03 · STRUCTURAL LEVER
04 · PARTICIPATION TIDE
+0.7% CAGR
+0.6% CAGR
Direct-to-consumer reinvention
Women · juniors · family play
Brand.com, digital configurators and CRM-led retention are restoring gross-margin
Female participation up 46% since 2019; 3.4M U.S. juniors reshape entry-tier
visibility across premium hardware and consumables.
design and academy-led fitting funnels.
Where upside compounds
Regional opportunity ranking North America
Premium density · upgrades
Anchor market · 45%
Asia · Pacific
Simulator-led · tech adoption
Fastest evolving · 25%
Europe
Resilient mid · sustainability lens
Heritage · Steady · 22%
LATAM · MEA Emerging · niche · 8%
Tourism-led · selective premiumisation
Watch-out · −0.8% CAGR risk
Discretionary cost sensitivity in mid-tier categories — a cyclical, not structural headwind that strengthens premium-led portfolios.
Sources: NMSC growth driver matrix; secondary triangulation across distributor feedback & retail audits. audits. 02 / Drivers
© 2026 Next Move Strategy Consulting
Slide 03 · Market structure & leadership
Competitive Scenario. Concentrated, premium, defensible. Five brands defend ~54% of 2025 global revenue — but pricing power, fitting IP and DTC scale, not share alone, decide alone, decide who compounds margin through 2035. Estimated 2025 global share
% of 2025 revenue · illustrative triangulation
Callaway
18%
Three competitive plays
Topgolf Callaway Brands STRATEGY 01
16%
Acushnet Titleist · FootJoy
9%
TaylorMade
Performance-led cadence Multi-material R&D, tour validation, AI-assisted fitting — reset premium ASPs every 18–24 months.
drivers · irons · putters
6%
PING Custom-fit specialists
5%
Sumitomo Group
STRATEGY 02
Channel & DTC reinvention Brand.com and configurator funnels recapture gross margin and rebuild pricing discipline.
XXIO · Srixon · Cleveland
46%
Long tail
STRATEGY 03
Selective M&A & IP
regional & challenger brands
Acquiring simulators, golf-tech and apparel platforms into into vertically integrated ecosystems.
Pricing power is the battleground
Four tiers, very different economics ENTRY
VALUE / MID
HIGH-END
PREMIUM / LIMITED
Volume-led
Demand anchor
Brand-led
Top profit pool
Data-backed fitting, premium positioning,
Custom & limited. Niche volume, top-
Mainstream amateurs. Balances performance
positioning, stronger per-unit economics.
volume, top-line economics per unit.
and price; cyclical sensitivity.
economics.
unit.
Beginner & recreational customers. Threshold to category; modest unit ASPs.
Share figures triangulated across NMSC research, comparable filings & channel-level retail audits.
03 / Competition
© 2026 Next Move Strategy Consulting
Slide 04 · Regional & Segment Outlook
Strategic Outlook. Two geographies, two growth logics. A premium-anchored North America, a tech-intensive Asia-Pacific and a category mix dominated by clubs (≈36%) and balls (≈36%) and balls (≈42%) shape where 2035 upside compounds fastest. Regional Outlook · 2025 revenue share
REGION · 01
REGION · 02 · FASTEST
REGION · 03
REGION · 04
North America
Asia · Pacific
Europe
LATAM · MEA
45%
25%
22%
8%
share of 2025 revenue
tech-intensive buyers
tradition-driven
emerging · niche
Anchor of premium upgrades; simulator-
Japan, South Korea anchor premium;
UK & Germany lift resilient mid-to-
simulator-integrated retail & DTC depth
premium; China & India scale through
premium; sustainability is a tie-breaker.
depth compound margin.
through academies & simulators.
breaker.
Segment Outlook · category mix
UAE tourism-led premium; Brazil & Brazil & Mexico urban academies. academies.
% of 2025 category mix · NMSC triangulation
Golf Balls
42%
High-volume, repeat
Golf Clubs
36%
Largest revenue share
Footwear & Apparel
15%
Athleisure crossover
Bags · Trolleys · Other
7%
Adjacent & consumables
Three implications for 2026 — 2035
Where capital, design & channel should compound TAKE 01
TAKE 02
Defend premium dollars
Simulator + DTC flywheel
Capture ASP inflation in drivers & irons — premiumpremium-tier share gain compounds twice as fast. fast.
Convert simulator & academy traffic into fitted DTC fitted DTC — higher gross margin per buyer.
Regional & segment shares are 2025 estimates compiled by NMSC research; minor differences may exist across published sources. published sources. 04 / Outlook
TAKE 03
Open women & juniors funnels Modular portfolio, academy partnerships, inclusive inclusive fitting — entry-tier growth lane.
© 2026 Next Move Strategy Consulting
Slide 05 · Connect with strategic insight
Thank you. For in-depth market modelling, customised strategic advisory, and primary-research primary-research interviews across the global golf equipment value chain connect connect with our team.
Follow Next Move
f
in
X
YouTube
X · Twitter
/company
/Next-Move
/channel
@nextmsc
@nextmsc
next-move-strategy-consulting consulting
Marketing & insights briefings
Webinars & executive briefings
Market commentary & alerts
Visual snapshots
Direct lines
CALL
CALL TO ACTION
+1 857 758 5017
Get the full report
Direct line · business hours, US Eastern
Includes full segmentation, regional countrycountry-level data and competitor profiles.
info@nextmsc.com
profiles.
nextmsc.com →
Replies typically within one business day
Premium-led, technology-validated, geographically rebalanced — the next decade of golf equipment compounds where fitting, DTC, and simulatornative buyers intersect.
Confidential briefing for investor & B2B strategy audiences. Address: 1 Beacon Street, 15th Floor, Boston, MA 02108.
05 / Connect
© 2026 Next Move Strategy Consulting