Healthcare · Biotechnology · Investor Briefing
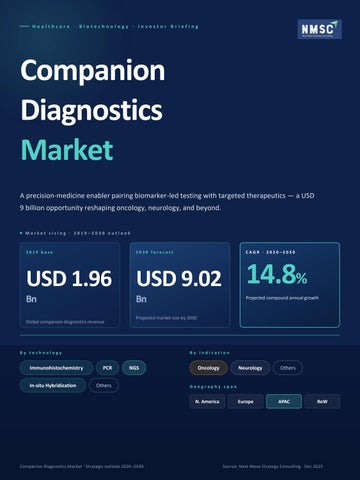
Companion Diagnostics Market A precision-medicine enabler pairing biomarker-led testing with targeted therapeutics — a USD 9 billion opportunity reshaping oncology, neurology, and beyond.
Market sizing · 2019–2030 outlook
2019 base
2030 forecast
CAGR · 2020–2030
14.8%
USD 1.96 USD 9.02 Bn
Bn
Global companion diagnostics revenue
Projected compound annual growth
Projected market size by 2030
By technology
By indication
Immunohistochemistry
PCR
In-situ Hybridization
Others
NGS
Oncology
Others
Europe
APAC
Geography span
N. America
Companion Diagnostics Market · Strategic outlook 2020–2030
Neurology
RoW
Source: Next Move Strategy Consulting · Dec 2025
Section 02 · Where growth comes from
Growth drivers & regional opportunities Demand is converging from four fronts: precision-medicine adoption, targeted-therapy pipelines, rising chronicdisease burden, and FDA momentum — with regional rotation toward Asia-Pacific unlocking the fastest 2020– 2030 expansion. Demand drivers
Regional opportunity map
Personalized & targeted therapy adoption
01
Payers and providers now require biomarker evidence before prescribing high-cost therapeutics.
Rising cancer & chronic-disease prevalence WHO: 1 in 6 deaths globally are cancer-related; 6.8M deaths annually from neurological disorders.
High sensitivity & fast turnaround time (TAT) reduce hospitalisation cost per treatment cycle.
Status
Europe
Mature
Region
Asia-Pacific
Top CAGR
Highest forecast CAGR — driven by China, India, Japan.
04
~60 FDA-cleared or approved CDx assays cumulatively; NGS-based tests cross 18% of approvals.
Lead
Mature markets; UK, Germany, France anchor.
03
FDA approval momentum & R&D investment
North America
Dominant today — established labs, R&D depth, payer reimbursement.
02
Speed, accuracy, and cost-effectiveness of CDx tests
Region
Rest of World
Emerging
UAE, Saudi, Brazil, S. Africa.
Clinical impact
Right drug. Right patient. Right time.
04 Demand drivers · 04 regions
CDx identifies patients most likely to benefit, suffer adverse events, or require dose adjustments — de-risking high-value therapeutics and accelerating reimbursement approvals.
Source: Next Move Strategy Consulting · Dec 2025
Section 03 · Who's leading
Competitive landscape A concentrated field of 10 anchor competitors — differentiated by technology stack, biopharma partnerships, and breadth of FDA-cleared assays. Scale players are extending lead via M&A and co-development with drug sponsors.
10
~60
18%+
Why consolidation matters
Anchor competitors
FDA-cleared / approved
Of approvals are NGS-
biopharma co-development pipelines —
profiled
CDx assays
based
Anchor players pair broad CDx menus with share follows scale.
Featured competitors
Roche
Thermo Fisher
Abbott
Qiagen
Agilent
Ventana Medical Systems
Life Tech & Oncomine Dx
Abbott Molecular
Qiagen N.V.
Dako Denmark
Danaher
bioMérieux
Myriad Genetics
ARUP Labs
Leica Microsystems
BioMérieux SA
Foundation Medicine
Roche affiliate (2018 acquisition)
Myriad Genetics, Inc.
ARUP Labs, Inc.
Key strategic moves
Play 01
Play 02
Play 03
Co-development with pharma
Strategic JV extensions
M&A & scale acquisitions
Thermo Fisher + Janssen Biotech (Mar 2020). Multi-biomarker CDx for oncology.
10 anchor competitors · 3 strategic moves
Roche / Foundation Medicine ~ $2.4B. Consolidated oncology CDx leadership. Thermo Fisher + Agios (Jun 2020). Global CDx for IDH-mutated glioma.
Source: Next Move Strategy Consulting · Dec 2025
Section 04 · Where to lean in
Strategic outlook & investment thesis Three structural theses frame the 2020–2030 opportunity. Two well-known constraints bound the upside. Watch the catalyst list for early signals on which players capture share next.
Forward theses
Thesis 01
Thesis 02
Thesis 03
NGS becomes the default platform
Pharma-CDx co-development at scale
Asia-Pacific takes share (highest CAGR)
Pan-cancer assays replace singlegene tests.
Therapy launches ship with diagnostic built-in.
China, India, Japan set the next decade.
NGS-based CDx already span 18%+ of FDA approvals — a structural shift toward one assay, many therapy decisions.
Drug sponsors now contract CDx partners pre-launch — biopharma pipeline becomes the pull-through, not the lab.
Improving infrastructure, medical tourism, and a chronic-disease demographic shift regional growth from follower to category leader.
Constraint register
Two known risks bound the upside i
What moves the next leg up
Costly R&D & validation burden Each new CDx must clear regulatory and clinical-validation gates — long cycles, large capex, and high failure risk per asset.
ii
Catalysts to watch
01
02
Liquid biopsy & ctDNA CDx clearing regulatory milestones.
03
FDA down-classification to Class II shortening launch cycles.
04
M&A consolidation among mid-cap diagnostic-platform players.
Reimbursement & payer variability Unfavorable coverage policies outside oncology slow diffusion — payer clarity is the gating lever for non-cancer indications.
03 theses · 02 risks · 04 catalysts
Pan-cancer companion approvals expanding beyond NSCLC & breast cancer.
Source: Next Move Strategy Consulting · Dec 2025
Section 05 · Let's connect
Thank you. In-depth strategic guidance, custom data cuts, and bespoke advisory — a direct line to Next Move Strategy Consulting.
Official website
Direct line
Inbox us
nextmsc.com
+1 857 758 5017
info@nextmsc.com
Reports, custom research, executive briefings.
Speak with our analyst team in business hours.
Briefings, sample reports, and procurement.
Get the complete report
See the full report
Full 300-page briefing · 163 tables · 133 figures nextmsc.com/report/companion-diagnostics-market
Visit nextmsc.com to unlock the full Companion Diagnostics Market report.
Follow us
Track healthcare, biotech, and diagnostics research as it lands. in
Next Move SC
f
YouTube
Next Move SC
@nextmsc
Companion Diagnostics Market · Investor Briefing
X
Twitter / X
@nextmsc
@nextmsc
Copyright © Next Move Strategy Consulting