How to establish a home renovation budget
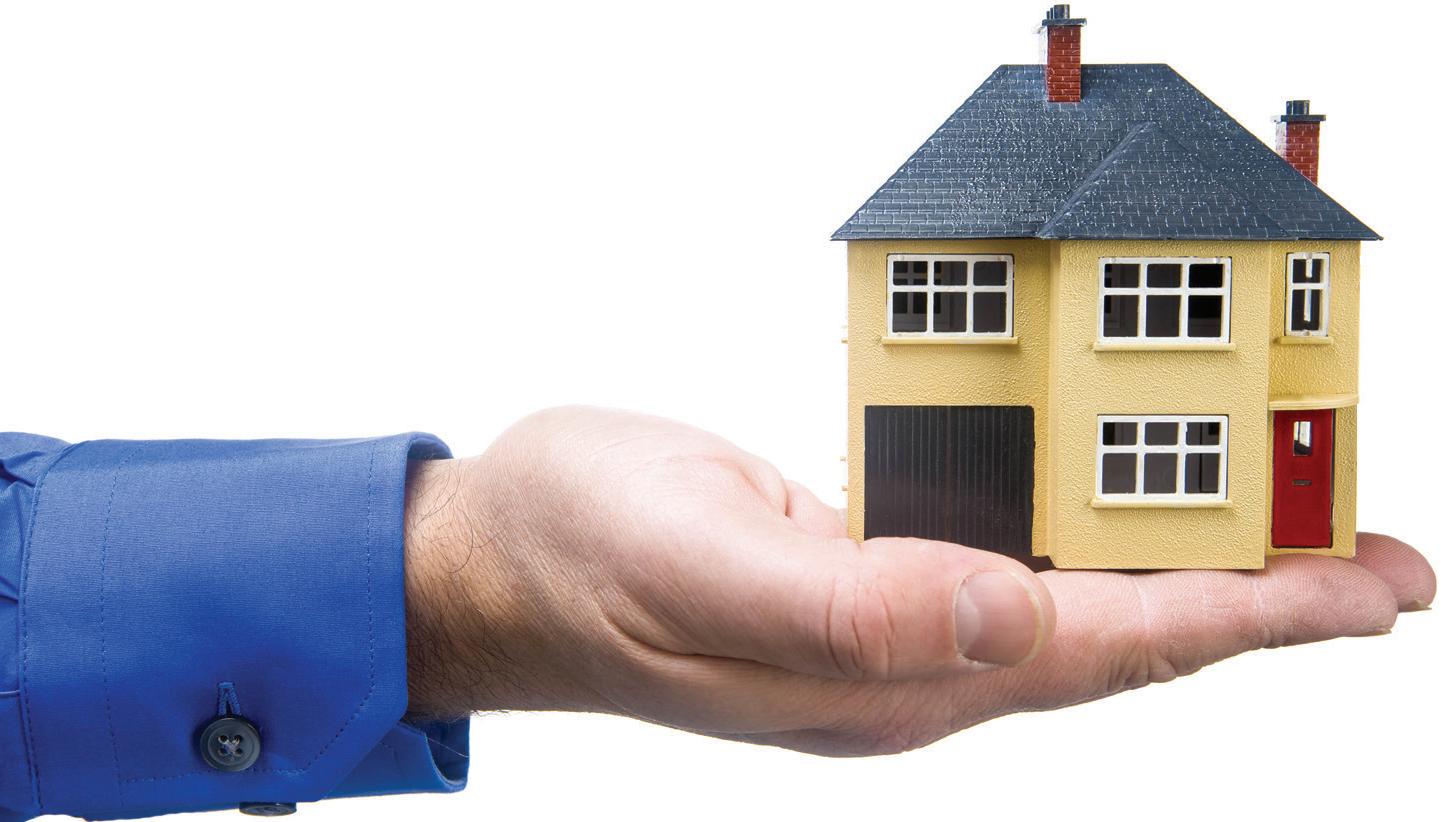
Homeowners know that the next home renovation project is always right around the corner. And that means finding ways to finance such undertakings.
When planning for renovations, the average homeowner underestimates their project cost by approximately 22 percent, according to the 2026 Remodeling Impact Report.
Establishing a pre-project budget can help avoid such surprises.
Don’t over-improve
A common mistake homeowners make is over-improving a home beyond the neighborhood value. A good rule of thumb is to employ the average percentage-of-home-value approach in an effort to stay within range of what’s acceptable.
Budget a kitchen renovation or finished basement at 10 to 15 percent of the home value. A master bedroom will come in at 5 to 10 percent of home value, while a small bedroom or office falls between 1 and 3 percent of home value.
These benchmarks are supported by the National Association of the Remodeling Industry and the National Association of Realtors.
Historically, a functional, modern kitchen is the top driver of home value, says Remodeling Magazine. Learn the breakdown
Homeowners should understand that materials, fixtures, appliances, and flooring, otherwise known as “hard costs,” will eat up 50 to 60 percent of their renovation budgets.
Labor, permits and design fees will comprise the next largest chunk, typically coming in between 25 and 35 percent. Homeowners also should factor about 15 to 20 percent of a budget to a safety net to cover unforeseen expenses, like mold remediation or structural issues.
Get three quotes
It’s important for homeowners to get several estimates before establishing a budget. Experts advise working with contractors that offer fixed-price contracts rather than those that list time and materials; otherwise, there may be a mid-project price hike that comes out of the blue.
A person also can ask contractors for a line-item bid so it’s possible to see where money can be trimmed through different material choices. With a list of desired items in hand, and acceptable substitutions if the cost comes in too high, homeown-
ers can create a budget that works.
Saving versus splurging
It’s important for homeowners to be realistic about their renovations. They can splurge on items that are seen or touched every day, like door handles, cabinet pulls and faucets.
Other items, like lighting fixtures or backsplashes, can be replaced down the road. It may be better to direct funds to structural elements or those “invisible renovations” like upgrading insulation or smart systems that save on energy costs and improve efficiency.
Keep a 20 percent cushion
Homeowners can determine the
affordability if a proposed project ends up costing 20 percent more or takes a few months longer. If the answer is no, homeowners should scale back the project budget until they have that financial safety net.
Alliant Credit Union says experts strongly recommend adding a 20 percent contingency cushion to a remodeling budget.
A home remodeling project is a big commitment of time and money. Budgeting correctly ensures that there are few, if any, surprises along the way.
Courtesy of Metro Creative Graphics
How to relieve funeral anxiety by pre-planning
The death of a loved is difficult to confront.
Emotions are elevated and grief is prominent. which can make it hard to make important decisions. Quite often several people need to come together to make decisions necessary for a family member’s funeral arrangements.
There also is a financial component to consider.
According to Lincoln Heritage Life Insurance Company, the average funeral costs between $7,000 and $12,000, which may or may not include viewing, burial, transport, casket and other fees. Surviving family members responsible for planning a funeral may be asked to contribute a portion of these expenses if other arrangements have not already been made, which can exacerbate stressful feelings during an already difficult time.
Funeral pre-planning is a good way for individuals to make a difficult time a little more manageable for their survivors.
Funeral homes frequently work hand-in-hand with individuals and families to customize pre-planning packages and facilitate the process. Here’s a rundown of pre-planning as individuals consider their options.
Explore your options
Pre-planning a funeral enables people to consider all of the options without the time constraints of making funeral arrangements directly after the passing of a loved one. A knowledgeable staff member at a funeral home, can explain the offerings and answer any questions.
Straightforward process
Unless an individual has planned a funeral in the past, there could be a lot of unknowns. Funeral homes handle these events every day and
can guide families through the intricacies of the process with ease.
Most have pre-planning kits that include all of the essentials of the process, such as choosing caskets, deciding on prayer cards and designing floral arrangements. Avoid confrontations
Working directly with a professional also helps alleviate the burden on family members, who may not agree on arrangements or concur on what they believe would be a loved one’s final wishes.
When pre-planning a funeral, individuals can spell out in their own words exactly what they desire and even finance the funeral in advance.
Establish a payment plan
A funeral home staff member can go over the various ways to fund funeral expenses and may work out a payment schedule to spread out the expense over a period of time. He or she also may explain how funeral prearrangement can be a way to “spend down” assets in a way that protects those monies from look-back periods when determining eligibility for certain assisted living or nursing facilities should that be required in the future.
Works with religious officials
Very often a funeral home is a con-
duit that facilitates all facets of the funeral process. They may reach out to a preferred house of worship to organize a mass or other religious service and will also contact the cemetery and work with them to secure a plot and deed. This also alleviates pressure down the line on grieving family members who need time to mourn.
Pre-planning a funeral merits consideration. Working with a trusted funeral home removes much of the pressure during such difficult times.
Courtesy of Metro Creative Graphics

Riding the ups and downs of the financial market is challenging, particularly as it pertains to figuring out the right time to buy a home.
After years of volatility, recent data indicates that the housing market might have hit an affordability ceiling, creating a much-needed period of rebalancing.
Although prices remain high, the bidding wars and back-office tactics that may have dominated past years have cooled considerably.
This means buyers may have a wider window in which to purchase a home that is more affordable, states Cotality, a data analytic service.
Those looking to buy now can explore options to ensure their next home does not bust their budget. Know the numbers
The first step to buying a home is understanding the median home price. According to data from Realtor.com and Redfin, the national median home price has stabilized at $429,156 in the United States.
At the same time, mortgage rates have eased. CREA Statistics says the national average home price in Canada was $663,828 in March 2026. The average 30-year fixed rate is now around 6 to 6.3 percent as of April 2026.
For the first time since 2022, the typical mortgage payment has fallen below the 30 percent affordability threshold. Rocket Mortgage says this is a standard guideline suggesting households spend no more than 30 percent of their gross monthly income on housing expenses.
Sit down with a lender
By working with a lender to run numbers, potential buyers can get a clear picture of what they can afford. Plus, a mortgage preapproval
How to buy a home you can afford
may be a necessity when putting in an offer on a property.
Lenders often lean heavily on the 28/36 rule to determine risk. This means that total monthly housing costs (principal, interest, taxes, and insurance) should not exceed 28 percent of a person’s gross monthly income, advises PNC Bank. Total debt payments, including that new mortgage, car loans, and student debt, should remain under 36 percent.
Account for hidden costs
Buyers may be inspired to widen their search criteria to find an affordable home. That could translate into choosing an older
home or one that requires more repairs and upgrades. It’s important that a budget include maintenance reserves for annual repairs, as well as construction costs for immediate needs.
Look for undervalued areas
Many areas of the country have featured recent corrections in the housing market, making housing more affordable. Corrections have occurred in parts of Florida, San Francisco, and Los Angeles, among other locales. Buyers can target these areas and consider widening their search radius, especially if they work remotely and need not worry about commuting.
Target “old” listings
Buyers can have a real estate agent sort listings by how many days homes have been on the market.
According to Mortgage Research, homes sitting on the market for more than 60 days are prime candidates for price cuts. Those homeowners also may be more inclined to negotiate.
Buying a home that is affordable requires diligence on the part of potential homeowners, who can consider the market and their finances and tweak search parameters to get the best deals. Courtesy of Metro Creative Graphics
ARealtor
Ho wT oC hoose ...
Real estate transactions involve many moving partsthatmust coordinateefforts&get resultsto make asuccessful transactiona reality. The leadership of this team is therealtor.
USINGAREAL ESTATE AGENT, BROKER,ORREALTOR
Areal estate agent has a professionallicense that is awarded by thestate after completingtraining dictatedbythatstate &having taken awritten licensingexam whichcoversfederalreal estate laws, generalreal estate principals&statespecific laws. Areal estate broker has additional educationcovering in-depth courseworkfocused on ethics, contracts, taxes&insurance. Typicallyabrokerhas aminimum of 3years experience as alicensed real estate agent. There are3types of brokers: principal,managing& associate. Arealtorisalicensedagent with membership in theNational Association of Realtors® &are heldto ahighercodeofconduct
HOWTOCHOOSEANAGENT
Consider interviewing at least 3agentstofind theone that fits your specific needs&demonstrates attentiontodetail, knowledgeof your housingmarket, anetwork of realestateconnections,engaging, honest personality, tenacity,selfmotivated&aproblem-solver mindset. Be direct&ask abouttheir experience,their clientload, how often youwill communicate&how, their percentage as alisting or buyers agent&iftheyare afull time agent as thesequestionswill impact the successofyourtransaction.A listing presentationcarries no obligation to list with that agent. Recentlawsin ever ystate have defined theduties of someonespecificallyretainedasa real estate agent. Most states requirea real estate agenttoexplain hisorher
role at theoutsetofany conversation Aprofessionalagent will promptly provide this information
LOOK FORANAGENT WHO:
•Isalicensedmemberofthe local boardorassociation of realtors.
•Listens to your expectationsof buying/sellingpropertyincluding future plans on potentialpurchases.
•Responds promptlytoyour questions&advises youonhow to prepare your home forthe market.
•Pointsout improvementsthatwill enhancethe desireability of your home
•Has researched your property & comparables currentlyavailableinthe public recordsand theMLS.
•Has experience workingwithyour type of property.
•Willingtoofferyou previous clients as references.
•Can recommendsupport professionals suchasroofers, appraisers,inspectors, mortgage brokers,etc
REALTORRESPONSIBILITIES
Some of theduties your agentwill performfor youinclude:
•Walk throughthe processofselling your home from beginningtoend.
•Provide comparable information about theprices forwhichother properties have sold andanalyzing data foryou to gain atrue comparison.
•Supply information regarding localcustoms ®ulationsyou maywanttoconsider as well as legal requirements.
•Share information aboutyourhome throughthe Multiple ListingSer vice andonother internet services.
•Place advertisements foryourhome.
•Field phonecalls.
•“Qualify” potentialbuyers to make sure they wouldbefinanciallyableto buyyourproperty.
•Negotiate thesales contract.
KIM RIDDLE, BROKER
423-280-5255
423-755-8830

kim@fbright.com
•Alertyou to potentialrisks.
•Offerprofessionalphotography

•Provide youwithutilityoptions,city &countyser vices.
•Helpyou preparefor asmooth closingofthe transaction.
REAL ESTATE TERMINOLOGY
•Appraisal
•Backup Offer
•Inspection
•Title Search
•Contingencies
•LandSur vey
•Seller &BuyerConcessions
•Counter Offer
•Above Market Price
•Termite Report
•Pre-Approval
•Loans:VA, FHA, Conventional
•ClosingCosts
•Agent Commission
•Equity
•Proof of Funds
•Active Contingency
•CommonAreaAssessments (HOA)
•RenttoOwn
•DownPayment
•Earnest Money
•E as ement
•Exclusive Listing
•Foreclosure
Kimisalicensed Broker with over 17 yearsofreal estate experience.She is anativeofMcMinn County &isproud to call it home.Kim &her husband, John, have two youngdaughters. They enjoythe outdoors & have ahobby-farm with severalhorses.