WHY ARE ASPHALT SHINGLES NOT LASTING LIKE THEY USED TO?
HOW INDUSTRY TRENDS ARE ELEVATING CAPITAL PLANNING
THE TOP 5 THINGS TO KNOW IF YOU’RE NEW TO LAKE AND POND MANAGEMENT
IS YOUR HOA BUDGET DROWNING IN OVERWATERING?
By Jarrod Cruz, 2026 President, Suncoast CAI Chapter
As we step into 2026, I’m filled with gratitude, pride, and excitement for what lies ahead for the Suncoast CAI Chapter. Last year, our Board of Directors set an ambitious goal: reach 800 members. Thanks to the dedication of our volunteers, the engagement of our business partners, and the enthusiasm of our managers and homeowner leaders, we didn’t just meet that goal—we surpassed it in January 2026.
This milestone is more than a number. It’s a reflection of a thriving, collaborative community that believes in elevating the community association industry across the Suncoast region. And now, as we continue with our forward momentum, we’re ready to build something even stronger.
Our 2026 Board of Directors has outlined a strategic set of initiatives designed to expand our reach, strengthen our value, and deepen our impact. I’m proud to share a high level overview of the work ahead—work that will shape the next chapter of our growth.
1. Membership growth remains a top priority, with a renewed focus on attracting community association managers and homeowner leaders —two groups whose engagement is essential to our mission. Our goal is not just to grow in numbers, but to grow in relevance—ensuring that every member feels the value of being part of CAI Suncoast.
2. Education is at the heart of CAI’s mission, and in 2026, we’re doubling down on delivering meaningful, accessible learning opportunities. By expanding both in‑person and virtual learning, we aim to make education more flexible, more engaging, and more impactful than ever.
3. Our chapter covers a large and diverse region, and we’re committed to meeting members where they are. This year, we will explore opportunities to bring events and programming to new areas, guided by data and member feedback. This initiative is about accessibility, representation, and ensuring that every corner of our chapter feels connected.
4. As our chapter grows, so does the importance of a strong, recognizable brand. In 2026, we will launch a comprehensive marketing effort to elevate the visibility of CAI Suncoast and communicate the value we bring to the industry. Our goal is simple: make CAI Suncoast a name that stands out—one that professionals, board members, and associations recognize and trust.
The initiatives outlined above reflect a chapter that is not only growing, but evolving. We are expanding our reach, strengthening our educational impact, deepening our partnerships, and investing in a brand that represents excellence.
But none of this happens without you.
Our members—managers, business partners, homeowner leaders, volunteers, and supporters—are the heartbeat of this chapter. Your engagement, your ideas, and your passion are what make Suncoast CAI one of the most vibrant chapters in the country.
As your 2026 President, I am committed to fostering a year of collaboration, innovation, and community. Together, we will continue building on the momentum we’ve created and set the stage for an even brighter future.
Here’s to a year of growth, connection, and opportunity. Here’s to the Suncoast.
President Jarrod Cruz
President Elect/At-Large
727.514.7970
Jocelyn St. Hilaire
813.949.6058
Immediate Past President Jaime Ballard 813.433.2000
Treasurer/At-Large
Secretary/Business Partner
Craig DiCecco
813-966-3995
Adam Gurley
727.475.5535
Business Partner Steve Nikoloff
727.738.1100
Homeowner Leader Jackie Stubba
612.802.6383
At-Large Bill Tayler
727.439.5878
At-Large Sandra Fuentes
813.209.9300
At-Large Kevin McNulty
813.639.3000
Suncoast CAI Chapter Executive Director Maria Medina, EdD
727.345.0165
Sidney Bezerra Jessica Safford
James Kellard Jocelyn St. Hilaire
Kim Morris Jackie Swisher, Chairperson
April Neary Kelly Vickers
Jarrod Cruz Maria Medina EdD (Suncoast CAI Executive Director)
DavidJ.Levy,PCAMNationalSalesManagerforRoofMaxxTechnologies,LLC.
Typically, roofs are one of the most important and most expensive components of a condominium community.
Learn why asphalt shingles are not lasting as long and how board members and community managers can utilize best practices to help their communities maximize the useful life of their asphalt shingle roofs.
What is driving the shorter useful life of asphalt shingles?
Liquid Asphalt: Asphalt shingles today have 25-33% less liquid asphalt than in the 1990s due to a global shortage of liquid asphalt, created by global changes in how crude oil is refined. Less liquid asphalt = higher prices AND less flexibility of the shingles.
Building Design: New construction designs often have reduced roof ventilation versus homes built before the 1980s. Older homes have large, open attics. Today, attics are much smaller as developers have added aesthetic features such as cathedral ceilings, skylights, dormers, and valleys, which dramatically reduce the air flow from your soffit vents (intake air) to your roof’s ridge vents (exhausted air). Hotter interior air just under the roof sheathing reduces the expected life of your roofs, of all types, but especially those covered with traditional asphalt shingles.
Weather: Hotter weather, in temperature and in frequency, has trended upward in the past 30 years. Summertime roof surface temperatures can be 40-80+ degrees higher than the air temperature, based on the sun’s orientation and the color of the roof. Florida’s harsh UV exposure leads to further reductions in roof life as compared to other parts of the country.
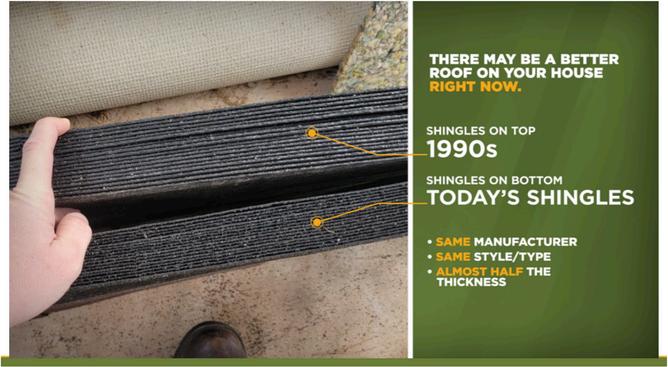
Fewer Inspections: Due to labor shortages, at the management office and at most contractors, there are very few proactive roof inspections at most condo communities.
What are the best-practices (solutions) to extend the useful life of asphalt shingles?
1. Ask your reserve study specialist about trends and best practices. They inspect dozens of HOA communities per year, per employee.
2. Inspect roofs at least every two years and immediately after big storms. In Florida, the first inspection should be around the 5th or 6th year. Request a summary inspection report with a link to all of the pictures taken. Some roofing firms provide this service at no additional cost.
3. Handle small repairs, reactively and proactively, to extend the useful life of your roof, at a very small investment. Doing your “punch-list” complex-wide, dramatically lowers the per-building cost.
4. Obtain an electronic measurement from a satellite-based firm specializing in roof imaging and measurements. Knowing the exact roof surface area for each building is helpful in ensuring accurate repair (or replacement) quotes. Some roofing firms provide this service at no additional cost.
5. Request training on roof maintenance and inspection from a reputable company that offers “lunch and learn” Zoom-based seminars. Some roofing firms, including Roof Maxx, provide this service at no additional cost.
6. Work with roofers who have experience with HOAs/Condos, nationally and locally.
7. Work with roofers who offer roof rejuvenation. Why? Roof rejuvenation is a proven solution. Since the mid 2010’s, advances in bio-science, allowed trained roofers, such as your local Roof Maxx dealer, to assist you with understanding roof rejuvenation instead of very costly total roof replacement.
In summary, the use of less liquid asphalt in manufacturing, along with other contributing factors, has shortened the lifespan of asphalt shingle roofs. Implementing these best practices will ensure your community maximizes the useful life of your roofs.
David Levy, Roof Maxx National Sales Manager, brings over 30 years of experience working with Multi-Family Communities, Landlords, and Management Companies and is a long-time CAI member. Roof Maxx specializes in roof rejuvenation; additional services include free third party satellitebased measurement on any asphalt shingle roof, roof inspections, roof cleaning, roof maintenance consultation and roof replacement consultation. For additional information visit www.roofmaxx.info/b2b.
Contact David Levy at 508-294-9460 or dlevy@roofmaxx.com
Much like business leaders, HOA boards manage financial resources and make strategic decisions that both preserve and enhance the community's value. With personal budgets wearing thin, every decision is under greater scrutiny, from increases in dues to the timing of capital projects. While temporarily limiting assessment increases or delaying projects may seem like a low-risk way to support residents in the short term, the potential consequences can be far more significant. As a matter of fact, underfunding reserves or deferred maintenance often signals increased risk to insurance providers and mortgage lenders.
Following the Surfside tragedy, the reserve study landscape has rapidly evolved. From legislation to insurance and lending, the impact is far-reaching. The following states, for example, have passed legislation aimed at ensuring structural and resident safety.
1. Florida – Now requires reserve studies for buildings with three or more residential stories. These communities are also required to fund reserves at the level outlined in the reserve study, and older buildings must conduct periodic structural inspections.
2. Maryland – Signed into law in 2022, all condominiums, cooperatives, and certain homeowners associations are required to conduct periodic reserve studies. These associations are also required to fund reserves at the level outlined in the reserve study.
3. New Jersey – Signed into law in 2024, condominiums, cooperatives, and certain homeowners' associations are required to conduct periodic reserve studies. They are also required to fund reserves at the level outlined in the reserve study.
4. Tennessee – Signed into law in 2023, unit owners' associations with $10,000 or more in common assets are required to conduct periodic reserve studies.
The law intends to inform the board of how much should be set aside in reserves to avoid future assessments. There are currently no statutory funding requirements.
Underwriting standards have evolved over the past several years as insurance providers mitigate risks associated with aging infrastructure. What was once a simple verification process is now a thorough review of structural conditions, maintenance history, and financial preparedness.
Communities that are unable to demonstrate proactive planning risk greater premium increases, reduced coverage, or difficulty securing a renewal.
Key insurance trends that communities experience include:
Rather than simply accepting that a reserve study exists, insurers regularly review recommended project timelines and whether structural projects have been completed. Any indication that a structural project is overdue, such as a roof replacement, inherently increases the carrier’s risk and likelihood of a future claim.
Historically, premiums were primarily reflective of the age of a property, building materials used, number of stories, and location.
Today, maintenance history, known deferred projects, and the adequacy of reserve funds, which increase the carrier's risk, are often reflected in premiums.
Increased risk is often associated with the terms of renewal. Associations that deviate from reserve funding or have a recent history of deferred maintenance are at greater risk of lower coverage limits, higher deductibles, risk-based exclusions, and, in the worst cases, denial of coverage.
Shortly after the Surfside collapse, Fannie Mae and Freddie Mac released new guidelines for securing loans backed by government-sponsored enterprises.
Meant to safeguard against safety and structural concerns, the new guidelines place greater emphasis on proper reserve
funding, proactive maintenance, and periodic building inspections.
With roughly 70% of conventional loans backed by Fannie Mae or Freddie Mac, the market is highly dependent on traditional lending. When a loan is denied for a condo real estate transaction, the association is at risk of landing on a ‘do not lend’ list –meaning no buyers will qualify for a government-backed conventional loan until the association sufficiently addresses any issues at hand.
Key mortgage trends that communities experience include:
1. Stricter Reserve Requirements –Lenders often require a recent reserve study and evidence or confirmation of proper reserve funding, which is outlined in the reserve study.
2.Increased Documentation Requests – It is not uncommon to have to provide detailed maintenance and capital project records, and inspection reports as part of the loan approval process. Lenders often review reserve studies to assess the extent of structural deterioration and potential water infiltration. If project timelines deviate from the study, supporting documents that validate the board’s decision may be warranted to continue the loan review process.
3. Impact on Buyer Eligibility – As lenders are hesitant to approve mortgages for condominiums that are deemed high risk, the pool of potential buyers shrinks, impacting residents’ ability to close on the sale of their home and potentially impacting property values.
It is becoming increasingly common for boards to address insurance and mortgage lender concerns.
While, for good reason, the reality is that, oftentimes, management and the board can lean on their reserve study provider to clarify concerns about reserve funding and deferred maintenance.
In a recent case involving a Midwest-based condo association, the board was unable to complete a brick masonry repair project in 2025, the year in which their reserve study recommended it. Due to weather constraints, the project was scheduled for 2026 instead. A mortgage application was denied due to deferred maintenance. Upon validating the board’s decision and confirming that there were no safety or structural concerns, the lender resumed the mortgage approval process.
As industry expectations continue to rise, boards can position their communities for greater financial stability and resilience against external risks.
1. Prioritize Structural and SafetyRelated Projects – Addressing high-risk projects, such as roofs, waterproofing systems, or structural concrete, demonstrates responsible stewardship and mitigates the risk of insurance and loan eligibility concerns.
2. Maintain Adequate Reserve Funding and Keep Your Reserve Study Current –Proper funding reduces the risk of future deferred maintenance and signals financial preparedness. Associations should update their reserve studies at least every 3 years, or sooner if funding levels change significantly or if major projects are deferred or completed.
3. Leverage Your Reserve Study Partner for Clarity and Documentation – When questions arise, oftentimes, your provider can discuss insurance and mortgage-related concerns and provide documentation to assist with renewal and loan processing – keeping the community’s insurance renewals and real estate transactions on track.
Insurance and lending trends will continue to evolve, driving the industry toward a more resilient future.
An increased focus on structural integrity and reserves supports a more proactive approach to addressing building deterioration when issues are minor, rather than waiting until they become more complex and more costly to address.
Lastly, communities that take a disciplined approach to capital planning will be best positioned to maintain coverage at the most affordable rates, mitigate risks of loan eligibility, and support home values.
Matt Kuisle, PE, RS is the Southeast Regional Executive Director at Reserve Advisors. Matt can be reached at matt@reserveadvisors.com.
If you’re a property manager or community leader suddenly tasked with overseeing a lake or pond, you might feel unsure where to begin. Maybe you’re new to managing waterbodies altogether, or perhaps you’ve done so before, but feel you still have a lot to learn. You’re not alone—many people in your position find lake and pond management intimidating.
Fortunately, with the right knowledge, you can approach this responsibility with confidence.
These are the top five things you need to know to successfully manage your waterbody, ensure it remains a valuable asset to your community, and help keep residents happy.
1. Most community waterbodies are manmade
Most urban ponds are man-made and designed primarily for stormwater collection. While they may offer aesthetic and recreational benefits like fishing or kayaking, their core purpose is to manage stormwater runoff during heavy rainfall, filter pollutants, and prevent flooding. Stormwater ponds contain important infrastructure that requires regular inspections. could lead to costly damage, safety risks, and regulatory fines.
2. Lakes and ponds are always changing
Keeping an eye on this equipment—and working with professionals when necessary—is crucial to maintaining the health and function of your stormwater pond. Neglecting these structures or failing to address potential issues
Lakes and ponds are dynamic ecosystems influenced by a variety of factors, including seasonal weather shifts, temperature fluctuations, and varying levels of sunlight. For example, warmer temperatures and abundant sunlight can promote nuisance plant or algae growth and diminish dissolved oxygen, which is essential to a healthy waterbody.
Additionally, practices such as gardening, landscaping, and dog walking can introduce runoff containing fertilizers, pet waste, and other contaminants into the water, creating imbalanced conditions. Environmental changes happen quickly, but with the right management practices in place, you can minimize the impact of these fluctuations.
3. Most urban waterbodies need to be managed
This is a common question for new lake or pond owners, and the short answer is: yes, most require year-round management to stay healthy and meet your specific goals, whether for stormwater collection, resident and recreation, or improved aesthetics and property values. On the other hand, poor management can rouse complaints, create safety risks, and contribute to more serious issues like cultural eutrophication—the accelerated aging process of a waterbody. Over time, stormwater ponds carry excess nutrients into the water that fuel nuisance weeds and algae and promote muck development.
Eventually, the waterbody will fill with muck and sediment until it can’t hold sufficient water levels. Proactive management can help slow this aging process, but it’s also essential to plan for future muck removal solutions like dredging. Dredging helps restore waterbodies to their original depth and volume, but is one of the costliest projects a community will ever face. In addition to ongoing management, budgeting far ahead of time (10-20 years) will help ensure you have the funds in place when the time comes.
When it comes to lake and pond management, there is no one-size-fits-all solution. This means that even if a neighboring community has a similar pond, their management approach could be completely different. Your custom management program will depend on factors such as the pond’s size, the surrounding landscape, and your budget. A program focused on keeping water clear and aesthetically pleasing will look very different from one aimed at creating fun fishing opportunities. Likewise, a waterbody surrounded by trees has different needs than one near a well-manicured lawn. Effective programs are designed with all of these factors in mind.
5.
Aquatic weeds and algae are often viewed as isolated issues, but they’re actually visible signs of water quality imbalances, such as high nutrient levels or dissolved oxygen deficiencies, or of underlying problems like muck accumulation. While reactive strategies like herbicides and algaecides can safely eliminate nuisance growth, they provide only temporary relief.
A preventative approach is essential to maintain lasting water quality balance. In addition to regular water quality monitoring tests, proactive solutions like nutrient management can help reduce the availability of nutrients in the water, limiting the potential for future growth. Fountains, surface aerators, and submersed aerators can help increase circulation and dissolved oxygen, making the waterbody more resilient to imbalances. Furthermore, mechanical hydro-raking can be used to scoop out nutrient-rich muck and debris in areas with severe accumulation.
Even for those managers who may be familiar with pond management best practices, there are always new innovations in water management to discover. Emerging photocatalyst solutions are now being used to help remove muck build-up, increase depth, and restore balanced water quality.
These environmentally-friendly options help break down muck and decay, leaving behind sand and a more balanced ecosystem. The toolbox of proactive management solutions is large and an experienced professional can help you incorporate these and many other sustainable tools to ensure lasting waterbody health.
The journey of lake and pond management doesn’t have to be overwhelming—it can be a rewarding opportunity to showcase your professional expertise and dedication to your community. With the right knowledge, you can create a thriving waterbody that elevates your community’s appeal, value, and reputation for years to come.
The event reached full vendor capacity, with all 50 exhibitor booths sold, and secured 140 pre-registered attendees. Actual attendance totaled 83 participants plus Managers and Associations that came with Management Companies = 103. Of actual registrations, attendance rates reflect a 59% attendance rate. The overall no-show count was 57 registrants (41%).
Of those unable to attend:
28 were Business Partners – representing 20% of total registrants and 49% of all no-shows
11 were Community Association Managers –representing 8% of total registrants and 19% of all no-show
14 were Homeowner Leaders – representing 10% of total registrants and 25% of all no-shows
Despite these absences, the program was highly successful. The room remained active and well-engaged, and both exhibitors and attendees reported strong, high-value networking opportunities and meaningful new connections. The soldout exhibit hall, combined with the positive feedback and level of interaction throughout the event, demonstrates continued industry support, effective audience targeting, and the overall strength of member engagement.
We are looking to improve our regular trade show experience for next year, feel free to submit feedback to: executivedirector@suncoastcai.com
The Editorial: "The Great Green Gauntlet: Conquering Irrigation Chaos & Saving Your HOA Bucks!"
Dear Fellow Board Members and Community Managers,
We've all been there: staring at the monthly water bill, wondering if our community common areas are secretly operating a synchronized swimming team for local ducks.
Maintaining that pristine curb appeal is crucial, but so is protecting our HOA's precious budget from unnecessary expenses.
The truth is, inefficient irrigation is often one of the silent budget-busters, costing our communities thousands each year. But it doesn't have to be a battle!
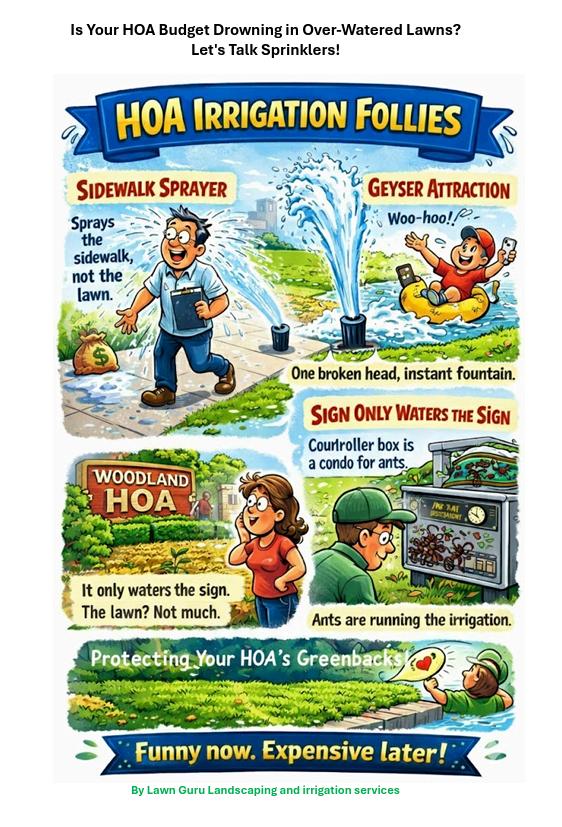
The Phantom Shower:
"One community had a sprinkler head that was systematically watering the main entrance sign —and only the sign—for two years before anyone noticed. Their sign was incredibly clean, but their water bill was legendary!"
The Geyser of Greed:
"Another HOA discovered a broken main line that turned a small section of their common area into a perpetual fountain. It looked lovely, but the repair cost of the water damage (plus the wasted water) nearly quadrupled their quarterly budget for landscaping!"
The "Scheduled" Deluge:
"After a week of non-stop rain, one board forgot to turn o their regular irrigation cycle. Their main park ended up looking like a swamp. Good for frogs, bad for homeowners."
These aren't just funny stories; they represent real money pouring down the drain.
Smart Strategies to Turn Your Irrigation System into a Budget Hero:
Regular "Sprinkler Patrols": Designate a board member or manager to do a quick walkthrough of common areas once a month while the irrigation is running. Look for broken heads, misdirected sprays (hello, sidewalk!), or excessive run-o .
Embrace Smart Controllers:
Investing in weather-based smart irrigation controllers can pay for themselves in months. They automatically adjust watering based on local weather forecasts, rainfall, and soil moisture. No more watering in a downpour!
Seasonal Adjustments are NOT Optional:
Florida's seasons, while subtle, demand di erent watering schedules. Reduce watering significantly in cooler, drier months.
Educate Residents (Gently):
Remind homeowners that their private irrigation a ects the overall community's water usage (and potentially rates). Oer tips for their individual lawns.
KathleenM.Walz,AttorneyatIcardMerrill
With the rise in utilization of technology in our everyday lives, it is only reasonable that the use of technology would also be implemented in Community Association governance as well. At a time when life is busier than ever and Associations are left at times scrambling for more votes and to meet the quorum requirements, Electronic Voting offers an easy alternative for residents who choose to opt-in.
The implementation and use of Electronic Voting in Community Associations offers opportunities for more engagement by residents and offers communities with multistate and multi-generational residents easier alternatives than mail-in proxies or in-person attendance. With the emergence of Electronic Voting, there have been numerous Electronic Voting companies that have been created to provide Electronic Voting platforms, which specifically tailor their services to Community Associations. However, despite the many benefits offered by Electronic Voting, Electronic Voting within Community Associations in Florida has restrictions, pitfalls and procedural
requirements that associations should be aware of when considering whether the Association should implement Electronic Voting in their Community.
There are many similarities between Florida Statutes Section 720.317, Electronic Voting in Homeowners’ Associations, and Florida Statutes Section 718.128, Electronic Voting in Condominium Associations, although they are not identical. The following are some key highlights which associations must keep in mind when implementing Electronic Voting in either a Homeowners’ Association or a Condominium Association. Both statutes allow Associations to adopt Electronic Voting by passage of a board resolution. Further, both statutes permit counting residents who vote electronically to be counted towards the quorum requirement at the meeting.
Additionally, both statutes impose similar technological requirements on the Electronic Voting platforms being utilized, including the ability to authenticate the identity of the owner submitting the vote, prevention of alteration of electronically submitted votes, the ability to produce a receipt for the owner who has submitted the vote and requiring the storage of electronically submitted ballots for the official records of the association. Both statutes also implement an opt-in and opt-out system, requiring that owners opt-in according to the procedure set forth by the board, the owner’s decision to opt-in must be respected until the owner validly opts out of the system according to the procedure adopted by the board.
There are some key differences between the statutes, which pose potential pitfalls for Associations, and which must be considered when implementing Electronic Voting. Under Florida Statutes Section 720.317(3) homeowner associations must provide fourteen (14) day written notice to owners prior to any board meeting to consider adoption of Electronic Voting, and compliance with this notice requirement must be made by affidavit. Additionally, Homeowners’ Associations should be sure to know whether they utilize secret ballots as electronic votes will follow the same requirements.
Condominium Associations are subject to additional considerations and complexities under Florida Statutes Section 718.128, which was updated by House Bill 913 adopted in 2025 and effective as of July 1, 2025.
Members of condominium associations are permitted to petition the board to adopt a resolution for Electronic Voting, if the petition is supported by a sufficient number of members and if certain procedural requirements are met. Any electronically submitted ballots should not be accessible to the association prior to the scheduled election. Most interestingly under Florida Statutes Section 718.128(7) (a) requires that Condominium Associations implement a “vote by email” system if the association has not yet adopted Electronic Voting. The Association must designate an email address for the receipt of ballots submitted by email. For any votes submitted utilizing this “vote by email” system, members are waiving their right to secrecy. For Associations not utilizing Electronic Voting, the association should create separate ballots which contain additional information for identification of the unit owner.
Further, Condominium Associations should be aware that the law requires a special disclaimer to accompany the ballot informing residents that they are waiving their right to secrecy. Emailed ballots must be received by the scheduled date and time of the meeting in order to be counted. Associations should be sure to review all email folders associated with the designated email address. Failure to comply with these requirements may result in elections and votes being challenged.
These differences between the governing statutes present just a few key considerations and legal requirements for associations looking to implement Electronic Voting. While the Florida Administrative Code contains some regulations on Electronic Voting, the F.A.C. has yet to be updated to clarify some of the emerging issues arising from the use of Electronic Voting.
Further, the Governing Documents for an Association may impose additional requirements on the association related to notice and other procedural requirements. As elections and ballots are highly regulated and may be contested, Associations should be sure to consult and seek guidance from their legal counsel concerning any questions regarding the Electronic Voting requirements. Ultimately, Electronic Voting is likely to change over time as the law continues to address various concerns and questions but is a useful tool for associations seeking to increase engagement amongst members.
Q1 Trending Topics on the Exchange:
Agenda limitations for board members that keep asking the same questions
Questioning the Value of CAI for Condominium Owners
Is it better to hold a Townhall meeting or a unit owners meeting; and more….
Guerilla Professional Pool Management Seminar
CES - AquaFinity
Topic: Guerilla Professional Pool Management Seminar
Date: April 9, 2026
Time: 8:30am - 10:00am
Location: Tampa Bay Downs
Charged Perspectives: Are EVs Autopiloting Your Building Into Disaster?
Topic: Charged Perspectives: Are EVs Autopiloting Your Building Into Disaster?
Date: May 14, 2026
Time: 8:30am - 10:00am
Location: St. Petersburg Marriott
Topic: Legal Panel
Date: June 11, 2026
Time: 8:30 AM – 10:00 AM
Location: St. Petersburg Marriott
Manager Membership
Olivia Bent
Conrad Cendrowski
Suzanne Macdonald
Jessica Marie Mesa
Suzanne Salah
Alex Valetta
Zachary Park
Margie E Sandler
Doug Higley
Nancy Ann Martin
Hailey Marie Tatgenhorst
Volunteer Leader
Ray Jablonski
Michele Andrews
Sonya Hanks
Chuck Hughes
John Laaninen
George Sommer
Dr. Swen Johnson
Rob Washburn
Shane Owens
Chapter BP
Niko Lyons
Vince Gilatta
Briana Madrid
Jayson Taylor Albright
Michael Wright, II
Barry W Watters
Michael Ryan
Business Partners
Albert Docobo
Michele Andrews
Sean Whitcomb
Allison Brandt, Esq.
Brian Rivera
Brian Keiter
Fazia Lewis
Josh Miller
Sean Hitchcock
Tom Crosier
Sammy Stephan Assaf
Thomas Mclaren
Kyle Bradley Staggs, Esq.
Nicholas Petrocelli
2026 DIAMOND CHAPTER SPONSORS
Bashor & Legendre
Blue Stream Fiber
Dixie Construction Services, Inc
Gardaworld Security Services
Gordian Business Solutions
Hotwire Communications
Landscape Workshop
Leland Management, Inc.
Management & Associates
Munyan Painting, Roofing, & Restoration
Resource Property Management
Truist Association Services
USI Insurance Services
2026 GOLD CHAPTER SPONSORS
Becker BurgSimpson
Centennial Bank
CES Aquafinity - Commercial Energy Specialists
Copperdoor Community Services
DRYmedic Restoration Services
I & E Construction
Naturzone Pest Control
P & R Pro Coatings, Inc.
PCS Insurance Group
RealManage
Russell Landscape
The Deft Group
Valcourt Building Services
Valley Bank
2026 PLATINUM CHAPTER SPONSORS
Acentria Insurance
ACPLM
Associa Gulf Coast
Bayshore Painters
Cadence Bank
Cogent Bank
Condominium Associates
EmpireWorks Reconstruction
First Citizens Bank
Gerstle, Rosen & Goldenberg, P.A.
Greenberg Nikoloff, P.A.
GreenTek Roofing & Solar Landcrafters
Marsh McLennan Agency
Morgan & Morgan Business Trial Group
Pinnacle Financial Partners
Rabin Parker Gurley, P.A.
Reserve Advisors
TWI Reconstruction
Village Management Software
Western Alliance Bank