www.claimscanada.ca
June/July 2017
Official Journal of the Canadian IndeÊpendent Adjusters’ Association
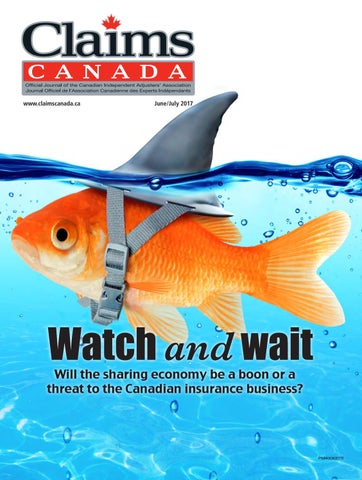
Watch and wait
Will the sharing economy be a boon or a threat to the Canadian insurance business?
PM40063170
Forensic Engineering We provide world-class engineering and consulting expertise in: • • • • • •
Civil/Structural Geotechnical Mining Construction Claims Personal Injury and Biomechanical Collision Reconstruction
• • • • • •
Electrical and Renewable Energy Environmental Health and Safety Remediation Materials Failure/HVAC Fire and Explosion Investigations Transportation Safety
-30- Forensic Engineering is a fully-independent, multi-disciplinary forensic firm. Our core team of 60+ professional investigators is enhanced through relationships with some of the top scientists, standard-makers and specialized consultants in North America.
The last word in forensic engineering www.30fe.com
30 Forensic Eng full page.indd 1
2017-02-23 2:46 PM
Contents June/July 2017 • VOLUME 11 • NUMBER 3
Cover Feature 12 Watch and wait
12
The sharing economy has yet to show its true colours as an influence on the insurance industry in Canada BY EMILY ATKINS
Spotlight 18 In the know Local knowledge is key to success for Algom Adjusters BY EMILY ATKINS
News Features 20 How AI is transforming property insurance BY DARA BANGA, FCIP, CFEI
23 Ontario Court of Appeal finds no conflict of interest in split decision BY MICHAEL S. TEITELBAUM
29
20
27 What an insured needs to know when defending a defamation action BY KAREN R. ZIMMER
29 To Admit or Not to Admit -- Expert evidence on trial BY DEBBIE ORTH
27
Departments 4 First Notice 10 Letters 31 On The Scene
Columns 7 President’s Message
• first notice FN Wet Spring causes heavy damage Several low-pressure systems that brought heavy rainfall to portions of Ontario, Quebec and the Maritimes last month cost “hundreds of millions” in US dollars and damaged more than 5,200 homes, according to Impact Forecasting’s latest Global Catastrophe Recap for the month of May. Following a wet April in Eastern Canada, numerous low pressure systems brought further rainfall to portions of Ontario, Quebec and the Maritimes from May 1 to 6, the heaviest of which fell on May 5 and 6 and resulted in several rivers overflowing their banks. Two people were killed in Quebec, where nearly 2,000 residents were evacuated, and significant flooding was also experienced across Ontario and in portions of New Brunswick and Nova Scotia. Among the worst affected communities were Ottawa and Gatineau, where both the Ottawa and Gatineau rivers breached their banks. In April, southern portions of British Columbia experienced prolonged periods of rainfall, leaving several rivers well above normal for the time of year. Further heavy rainfall on May 5 led to several of these rivers overflowing their banks. At least two people were killed and hundreds were evacuated as flooding
impacted BC’s Southern Interior. Significant damage to infrastructure and agriculture was reported, said the report from Impact Forecasting, Aon Benfield’s catastrophe model development team. Economic losses were anticipated in the tens of millions in US dollars. Later in the month of May, a powerful low-pressure system brought strong winds and storm surge flooding to southern portions of BC on May 23 before tracking into Alberta and Saskatchewan on May 24. Numerous trees were downed and significant property damage was reported in all three provinces. The report noted that nearly 200,000 customers were without power at the storm’s peak, with flooding reported along portions of BC’s coast and in the Okanagan region. Economic loss was estimated in the tens of millions in US dollars. South of the border, the US economy took a US$4 billion hit from severe weather in May, with insurance payouts approaching $3 billion, according to Aon Benfield. The most prolific event occurred in the Denver, Colorado region, where damage from up-to-softball-sized hail led to insurance payouts of more than $1.4 billion in the state alone. ●
Companies lack cyber coverage More than a third (36 percent) of surveyed Canadian firms do not have cyber security insurance, a concerning situation made worse by an incomplete understanding of how premiums are priced and failure to do everything possible to guard against breaches, says US-based analytics firm FICO. Fifty percent of surveyed respondents in the US and 40 percent for respondents globally said they had cyber insurance. While polled Canadian businesses are ahead of some countries with regard to cyber security risk insurance, they “still have a long way to go” to fully protect themselves in the event of a data breach, FICO cautions. Perhaps more positive, though, is the finding that “these organizations are significantly more responsible than many of their global counterparts when it comes to insurance.” Just 16 percent of surveyed Canadian organizations report they have no intention of taking out cyber risk insurance, considerably less than the 27 percent of US executives. “It’s important for businesses to assess the strength of their cyber security defences and to make sure they are covered if they are faced with a data breach,” Kevin Deveau, vice president and managing director of FICO Canada, said. “The ripple effect of a breach can be 4
Claims Canada
June/July 2017
felt throughout the organization for a very long time, especially now that Canada’s Digital Privacy Act will require organizations to report any breaches to regulators and customers,” Deveau maintained. Overall, 80 percent of respondents say insurers could do more to help organizational decision-makers understand how risk price structure is calculated. Results indicate that “there is still confusion in Canada and other countries about how cyber security insurance premiums are set,” FICO said. More than a quarter of respondents, 26 percent, feel the “introduction of an established industry standard to benchmark cyber security risk would be beneficial.” The observation reflects the finding that 20 percent of respondents believe “the premiums calculated based on their business do not accurately reflect their risk profile.” Even among those who do have cyber security insurance, just 18 percent of respondents say they have insurance that covers all likely risks. The survey involved senior officers and senior security executives at 350 companies based in Canada, the United States, the United Kingdom and Scandinavia this past March and April. Respondents represented firms in financial services, telecommunications, healthcare, retail, ecommerce and Internet service providers. ● www.claimscanada.ca
• first notice FN Supreme Court won’t hear fire case
Insurers feeling anxious about change
A disputed property insurance claim arising from a fire in Ottawa will not be heard by the Supreme Court of Canada. In a ruling released December 6, 2016, the Court of Appeal for Ontario ruled in favour of Intact, which wrote a policy that included replacement cost. After the fire, the owners wanted to construct new, larger buildings and claim from the insurer the replacement cost of the original buildings. The building owners unsuccessfully sued Intact for $2.43 million, which was the difference between the actual cash value that Intact paid and the replacement value they were claiming, plus building-code upgrades. The court agreed that Intact did not owe the insureds the cost of building code upgrades and only owed them actual cash value. The Court of Appeal upheld a 2015 Ontario Superior Court of Justice decision. In February, 2017, the owners applied for leave to appeal to the Supreme Court of Canada, which it denied on June 1. See Claims Canada, April/May 2017 page 18, for a full description of the case and its implications. ●
The global insurance industry’s ability to confront structural and technological changes is now the greatest risk it faces, according to a new survey of insurers and close observers of the sector. The Centre for the Study of Financial Innovation’s (CFSI) Insurance Banana Skins 2017 survey, conducted with support from PwC, surveyed 836 “insurance practitioners and industry observers” in 52 countries, including 38 in Canada and 23 in the United States, to find out where they saw the greatest risks over the next two to three years. The survey identifies the risks, or “banana skins,” facing the global insurance industry in the first half of 2017. Respondents were asked to score each of the 22 topical risks in the survey from one to five, where five is the most severe. Change management is at the head of a cluster of operating risks, which have jumped to the top of the rankings. Overall, the climate for insurers is becoming more challenging, according to respondents. The 2017 index, which measures the level of anxiety in the industry, is at a record high, while the industry’s preparedness to handle these risks has fallen from 2015. “The report raises concerns about the industry’s ability to address the formidable agenda of digitization, new competition, consolidation and cost reduction it faces, especially because of rapidly emerging technologies which could transform insurance markets, such as driverless cars, the ‘Internet of Things’ and artificial intelligence,” PwC said. Cyber risk follows close behind, with anxiety rising about attacks on insurers themselves as well as the costs of underwriting cybercrime. Other major concerns include the adequacy of insurer’s internal technology systems and new competition, particularly from the ‘insurtech’ sector. After the technology risks, the next cluster of high-ranking risks — interest rates, investment performance and macro-economic risk — shows that concern about economic instability remains high. “For the first time in six editions of this survey, operating risks pose the greatest threat to insurers,” said David Lascelles, survey editor, in the statement. “Structural and technological changes to the industry could upend traditional business models. At the same time, insurers are grappling with a very difficult economic climate, which helps explain why anxiety is at an all-time high.” ●
Drone activity to increase risks An agile and flexible response is needed in light of the new and little-understood risks expected to emerge with the anticipated increase in drone activity over the next few years, SCOR experts write in a recent technical newsletter. “Sales of drones for private use have exploded in the last few years but now, in addition, commercial drone activity is growing exponentially,” note co-authors Hans Kubli, senior underwriter, Aviation & Space Treaties, and Andrea Sommerlad, chief underwriting officer, Aviation & Space Treaties for SCOR. Current uses of drones include disaster relief, inspecting and exploring inaccessible places, precision agriculture, claims handling and logistics. Kubli and Sommerlad emphasize the need for a safety-first approach by drone operators. “To guarantee safe operation, authorities and drone manufacturers must respond fast to changes due to the rapid development of capabilities and the ever-increasing air traffic at low altitude,” they write. Pointing out that a very limited history of operation, reliability and actual claims is currently available, the newsletter notes, “insurers have taken a proactive approach to fill the gaps in knowledge and to offer a comprehensive cover for all stakeholders. They will play a vital role in making drones a prominent part of our future.” ● www.claimscanada.ca
continued on page 6...
June/July 2017
Claims Canada
5
• first notice FN
continued from page 5...
Internet of Things market booming Intel predicts “passenger economy” The global market for the Internet of Things (IoT) is expected to grow from US$170.57 billion in 2017 to $561.04 billion by 2022, according to a new report published by MarketsandMarkets. The market research firm said the IoT market size is expected to grow at a compound annual growth rate of 26.9 percent between 2017 and 2022. The major force driving the market includes the adoption of cloud platformas-a-service (PaaS). “The advent of advanced data analytics and data processing is also fuelling the growth of the IoT market, as advanced analytics and data processing are useful in deriving results from the high volumes of data collected using the machine-to-machine communication,” MarketsandMarkets said. North America is expected to hold the largest market share in the IoT market during the forecast period. “The countries in this region have established economies, which empowers them to strongly invest in [research and development],” MarketsandMarkets noted. Rapid digitalization across industry verticals, the increasing adoption of smart connected devices, and technological advancements have further fuelled the growth of the IoT market in this region. ●
6
Claims Canada
June/July 2017
Autonomous driving will cause a new “passenger economy” to emerge to support the idle time when drivers become riders, an economy that will be more than twice the size of the “sharing economy.” The findings were contained in a new study released by Intel Corporation, Accelerating the Future: The Economic Impact of the Emerging Passenger Economy. The study predicts these new lines of business will grow from US$800 million in 2035 to US$7 trillion by 2050 “as autonomous vehicles become mainstream,” Intel said. Highlights of future scenarios explored in the study include: “Car-venience”: “From onboard beauty salons to touchscreen tables for remote collaboration, fast-casual dining, remote vending, mobile health care clinics and treatment pods, and even platooning pod hotels, vehicles will become transportation experience pods”; Movable movies: Media and content producers will develop custom content formats to match short and long travel times; and Location-based advertising: This will become more keenly relevant, and advertisers and agencies will be presented with a new realm of possibilities for presenting content brands and location. ●
www.claimscanada.ca
Message from the President La Plume du président HEATHER MATTHEWS
Summer in Canada. The season of hot, steamy days and nights, patios, BBQs — and for some in the industry — it is catastrophe (cat) season. Storm season arrives, particularly on the prairies and Alberta, with its infamous hail and Ontario throws in some violent thunderstorms and the odd tornado. We also have hurricane season that heats up south of the border and occasionally our friends in Atlantic Canada get to bear that wrath as well. Each year we in the industry talk about cat planning, and for independent adjusters the key component is resources and making sure that we have enough of those key resources that can be mobilized quickly to address our clients’ needs. A well-prepared cat plan enables efficient handling of high-volume claims and results in higher customer satisfaction with fewer complaints, policyholder retention, positive brand awareness and better indemnity and expense control. The frequency and severity of natural disasters over the last 20 years has led to an increase in the number of independent adjusters with staff dedicated to handling cat claims both in the field and at the desk. In some firms, that is all that they do. With large cats and a busy hurricane season, high demand for independent adjusters may make it difficult to find enough adjusters to handle all of the increased volume. It is important early in the year to have discussions with insurers to converse over resources, fee schedules, process and procedures to ensure that there is a mutual understanding and plan to execute when the cat occurs. It is no longer “if’ we will have a cat, it is now just when and where. In the planning process the insurers can also forecast staffing and claims needs based on their policies in force in storm-prone areas of the country. Another recommendation would be for insurers to advise their brokers of their cat plan and any changes to the claims management process when a cat occurs. A pre-mortem with key stakeholders is always a good strategy to examine what can go wrong and how that can be mitigated before the storm and subsequent chaos hit. We would be remiss in discussing cat season, planning and resources without touching on licensing requirements. Each province has its own distinct requirements for the licensing of independent adjusters. If and when the IBC declares a cat, those provincial borders are opened up for adjusters from other provinces and or countries to enter and manage claims. In situations where there is a cat declared the borders open up but still with some administrative burden and work on our parts. For example, some regulators will accept online background checks while others refuse to recognize them as legitimate. Physical
L’été au Canada. La saison des journées et des nuits chaudes et humides, des patios, des BBQ et, pour certains dans l’industrie, c’est la saison des sinistres. La saison des tempêtes arrive notamment dans les prairies et l’Alberta avec sa tristement célèbre grêle, alors que de violents orages et même d’improbables tornades menacent l’Ontario. Nous avons aussi une saison des ouragans qui s’intensifie au sud de la frontière, une colère qui frappe occasionnellement nos amis du Canada atlantique également. Chaque année, dans l’industrie, nous parlons de planification des sinistres. Pour les experts en sinistres indépendants, la clé consiste à disposer de ressources, et à avoir l’assurance de disposer de suffisamment de ces ressources qui peuvent être mobilisées rapidement afin de répondre aux besoins de nos clients. Un plan de sinistre bien préparé permet une prise en charge efficace d’un volume élevé de réclamations et se traduit par des clients plus satisfaits, des plaintes moins fréquentes, une grande rétention des personnes assurées, une sensibilisation positive à la marque, une meilleure indemnisation et un meilleur contrôle des dépenses. La fréquence et la gravité des catastrophes naturelles, au cours des 20 dernières années, a mené à une augmentation du nombre d’experts en sinistres indépendants comptant sur du personnel attitré au traitement des réclamations en cas de catastrophe – sur le terrain comme derrière un bureau. Dans certaines firmes, c’est tout ce qu’ils font. Lors d’importantes catastrophes et de forts ouragans, une demande accrue d’experts indépendants pourrait entraîner une incapacité de trouver suffisamment d’experts pour prendre en charge la totalité de la hausse de volume. Il est important, en début d’année, d’avoir des discussions avec les assureurs pour discuter des ressources, des listes de frais, des processus et des procédures afin de s’assurer qu’il existe une compréhension mutuelle et un plan à exécuter lorsque la catastrophe survient. La question n’est plus de savoir «si» une catastrophe va survenir, mais plutôt où et quand elle surviendra. Au cours du processus de planification, les assureurs peuvent également prévoir les besoins de recrutement et de réclamations en fonction de leurs politiques en vigueur dans les régions propices aux tempêtes à travers le pays. Une autre recommandation serait que les assureurs avisent leurs courtiers de leur plan en cas de catastrophe et de toute modification du processus de gestion des réclamations lorsqu’un sinistre survient. Un pré-mortem avec les principaux intervenants constitue toujours une bonne stratégie pour examiner ce qui est susceptible de mal aller, et comment cela peut être atténué avant que la tempête ne survienne et que le chaos qui en découle ne frappe. Nous serions négligents d’aborder la saison des sinistres, la planification et les ressources sans toucher aux exigences en matière de permis. Chaque province a ses propres exigences en ce qui a trait à l’octroi de permis d’experts indépendants. Si et quand le BAC déclare une catastrophe, ces frontières provinciales sont ouvertes aux experts d’autres provinces ou pays pour qu’ils entrent et s’occupent de réclamations. Dans le cas où un sinistre est déclaré, les frontières s’ouvrent, mais il reste encontinued on page 8...
www.claimscanada.ca
June/July 2017
Claims Canada
7
...continued from page 7
police checks can take upwards of three weeks to process, depending on the jurisdiction; this, obviously, does nothing to address the immediate need for adjusters. If the event is severe, in that people’s lives and safety are threatened, the paperwork and fees are exempt, for example, in the case of forest fires. If a cat has been declared but lives/ safety are not threatened the paperwork and fees are required, for example, in the event of hail damage. In both scenarios adjusters are required as soon as possible and we need to continue, as an industry, to drive the regulators for efficient, streamlined, multi-jurisdictional licenses. Where an additional challenge occurs is in high volume situations that are not a declared cat but the volume still stretches our resources. The CIAA continues to push government regulators for streamlined licensing. The Atlantic Provinces have now moved to a harmonized license for adjusters for Nova Scotia, New Brunswick, Newfoundland and PEI. This will allow for speedy dispatching of qualified insurance adjusters to provide services to Atlantic Canadians in a severe weather or catastrophic event that requires a quick insurance response. The Atlantic Superintendents have agreed and recognized the protocols for adjusters’ mobility in these events. We are hopeful that this Atlantic move will now help to set precedent and acknowledgement across the country that this same practice is required on a national basis. Wishing everyone a safe, healthy and happy summer with a well-executed cat plan! ■
core un fardeau administratif et du travail de notre part. Par exemple, certains experts accepteront la vérification des antécédents en ligne, alors que d’autres refusent de reconnaître cette pratique comme légitime. Les enquêtes physiques de la police peuvent prendre plus de trois semaines à traiter, selon la juridiction; cela, évidemment, n’aide en rien la demande immédiate d’experts. Si l’événement est grave en ce sens que la vie et la sécurité des personnes sont menacées, la paperasse et les frais sont exonérés, par exemple dans le cas d’un feu de forêt. Si un sinistre est déclaré mais que la vie et la sécurité ne sont pas menacées, la paperasse et les frais sont requis, par exemple dans le cas de dommages causés par la grêle. Dans les deux scénarios, des experts sont nécessaires le plus rapidement possible et nous devons continuer, en tant qu’industrie, à insister auprès des organismes réglementaires pour obtenir des permis multi-juridictionnels efficaces et simplifiés. Un défi supplémentaire survient dans les situations de volume élevé qui ne sont pas dues à un sinistre déclaré, mais qui requièrent tout de même l’essentiel de nos ressources. L’ACEI continue de faire pression auprès des organismes de réglementation gouvernementaux pour un octroi simplifié des permis. Les provinces de l’Atlantique ont aujourd’hui adopté un permis harmonisé pour les experts de la Nouvelle-Écosse, du Nouveau-Brunswick, de Terre-Neuve et de l’Île-du-Prince-Édouard. Cela permettra l’envoi rapide d’experts en sinistres qualifiés pour offrir des services aux Canadiens de l’Atlantique lors d’intempéries violentes ou d’événements catastrophiques nécessitant une réponse rapide. Les surintendants de l’Atlantique ont approuvé et reconnu les protocoles facilitant la mobilité des experts lors de ces événements. Nous espérons que cette décision de l’Atlantique aidera à établir un précédent et à faire reconnaître dans l’ensemble du pays qu’une telle pratique est nécessaire à l’échelle nationale. En vous souhaitant à tous un bon été en santé, en sécurité et avec un solide plan en cas de sinistre! ■
NATIONAL EXECUTIVE 2016 - 2017 PRESIDENT Heather Matthews, CIP, CRM, CIOP Crawford & Company (Canada) Inc. 539 Riverbend Dr. Kitchener, ON N2K 3S3 Phone: (519) 578-5540 Fax: (519) 578-2868 E-mail: Heather.Matthews@crawco.ca 1ST VICE-PRESIDENT Monica Kuzyk, FCIP, CRM Curo Claims Services 125 Northfield Dr. W., P.O. Box 218 Waterloo, ON N2J 3Z9 Phone: (866) 952-2876 Fax: (519) 888-9704 E-mail: mkuzyk@curocanada.com 2ND VICE-PRESIDENT Lee Powell Vericlaim Canada 5915 Airport Road, Suite 201 Mississauga, ON L4V 1T1 Phone: (905) 671-7834 Fax: (905) 671-7819 E-mail: lee.powell@vericlaim.ca SECRETARY Jeff Edge, CIP, CFEI Leading Edge Claims Services Inc. P.O. Box 1399, 78 Highway 20 West Fonthill, ON L0S 1E0 Phone: (289) 897-8676 Fax: (289) 897-8677 E-mail: jeff@leadingedgecs.ca
8
Claims Canada
TREASURER John D. Seyler, CIP Integrated Insurance Resources 5080 Timberlea Blvd., Suite 214 Mississauga, ON L4W 4M2 Phone: (905) 238-4985 Fax: (905) 238-2735 E-mail: jseyler@integrated-ins.ca PAST-PRESIDENT Fred R. Plant, AIIC ClaimsPro 85 Englehart Street Dieppe, NB E1A 8K2 Phone: (506) 853-8507 Fax: (506) 853-8501 E-mail: fred.plant@scm.ca EXECUTIVE DIRECTOR Patricia M. Battle Canadian Independent Adjusters’ Association/ L’Association Canadienne des Experts Indépendants Centennial Centre, 5401 Eglinton Avenue West, Suite 100 Etobicoke, ON M9C 5K6 Phone: (416) 621-6222 Toll Free: 1-877-255-5589 Fax: (416) 621-7776 E-mail: pbattle@ciaa-adjusters.ca DIRECTOR Paul Féron, FCIP, CRM ClaimsPro 210 – 746 Baseline Rd. East London, ON N6C 5Z2
June/July 2017
Phone: (519) 645-6500 Fax: (519) 645-2250 E-mail: paul.feron@scm.ca
Phone: (905) 896-8181 Fax: (905) 896-3485 E-mail: apoon@cl-na.com
DIRECTOR Lorri Frederick ClaimsPro 120 Adelaide St. W., Suite 2401 Toronto, ON M5H 1T1 Phone: (905) 308-6292 Fax: (416) 360-7335 E-mail: lorri.frederick@scm.ca
DIRECTOR Marie C. Gallagher, FCIP, CRM Kernaghan Adjusters Limited 602 – 1 St. Paul Street St. Catharines, ON L2R 7L3 Phone: (289) 786-1074 Fax: (289) 723-1979 E-mail: mgallagher@kernaghan.com
DIRECTOR James B. Eso, CIP, CIOP Crawford & Company (Canada) Inc. 539 Riverbend Drive Kitchener, ON N2K 3S3 Phone: (519) 578-5540 Fax: (519) 578-2868 E-mail: Jim.Eso@crawco.ca DIRECTOR E. Grant King, BA, B.Ed., CIP Crawford & Company (Canada) Inc. 120 – 237 Brownlow Avenue Dartmouth, NS B3B 2C7 Phone: (902) 468-7787 Fax: (902) 468-5822 E-mail: Grant.King@crawco.ca DIRECTOR Albert Poon, CIP Cunningham Lindsey Canada Claims Services Ltd. 1102 – 50 Burnhamthorpe Rd. W. Mississauga, ON L5B 3C2
DIRECTOR Craig J. Walker, CIP, FCIAA, FIFAA Maltman Group International 2001 Sheppard Ave. East, Suite 810 Toronto, ON M2J 4Z8 Phone: (416) 492-4411 Fax: (416) 492-5657 E-mail: cwalker@maltmans.com DIRECTOR Gary Ellis, BBA, FCIP, RF, FCLA, FCIAA, FIFAA AMG Claims Inc. P.O. Box 20102 Sherwood Charlottetown, PE C1A 9E3 Phone: (902) 628-9091 Fax: (902) 628-9093 E-mail: gary.ellis@amgclaims.ca
www.claimscanada.ca
CIAA REGIONAL PRESIDENTS 2016 – 2017 NEWFOUNDLAND & LABRADOR Gejapathy Gopal, CRM ClaimsPro 27 Duffy Place, P.O. Box 8686, Station A St. John’s, NL A1B 3T1 Phone: (866) 726-7815 Fax: (709) 726-6106 E-mail: gejapathy.gopal@scm.ca NOVA SCOTIA Michael Connolly, BA, CFEI, CIP ClaimsPro 238 Brownlow Avenue, Suite 300 Dartmouth, NS B3B 1Y2 Phone: (877) 514-6269 Fax: (902) 425-9918 E-mail: michael.connolly@scm.ca NEW BRUNSWICK & PRINCE EDWARD ISLAND Greg Potten, BPE, CIP, CFEI AMG Claims Inc. 212 Queen Street, Unit 308 Fredericton, NB E3B 1A8 Phone: (506) 458-9000 Fax: (506) 458-9595 E-mail: greg.potten@amgclaims.ca QUEBEC/AESIQ Michel Lacelle, PAA/CIP ClaimsPro 255 Crémazie Est, 2e étage Montréal, QC H2M 1M2 Phone: (514) 340-8959 Fax: (514) 342-5474 E-mail: michel.lacelle@scm.ca ONTARIO Niki McConnell, BA (Hons.), CIP, CRM TC Insurance Adjusters Ltd. 6-2400 Dundas Street West, Suite 388 Mississauga, ON L5K 2R8 Phone: (877) 663-0701 Fax: (905) 916-0242 E-mail: nmc@tcia.ca MANITOBA Craig Shanks, BA, CIP Wheat City Claims Services Ltd. 64 Regent Cres. Brandon, MB R7B 2W9 Phone: (204) 725-7436 Fax: (204) 725-7437 E-mail: craig.shanks@mymts.net SASKATCHEWAN Lee Dixon, B. Comm., CIP Midwest Claims Services #7 – 1622 Ontario Ave. Saskatoon, SK S7K 1S8 Phone: (306) 668-0870 Fax: (306) 249-4114 E-mail: lee@midwestclaims.ca WESTERN Jody Schmidt, B. Comm., CIP Crawford & Company (Canada) Inc. 600, 10709 Jasper Ave. Edmonton, AB T5J 3N3 Phone: (780) 486-8024 Fax: (780) 486-9001 E-mail: Jody.Schmidt@crawco.ca PACIFIC Stacy Phillips, B.Comm., CRM, FCIP ClaimsPro 600, 1111 Melville Street Vancouver, BC V6E 3V6 Phone: (888) 681-6331 Fax: (604) 681-6388 E-mail: stacy.phillips@scm.ca
www.claimscanada.ca
National Standing Committees 2016-2017 ADVISORY Monica Kuzyk, FCIP, CRM Curo Claims Services 125 Northfield Dr. W., P.O. Box 218 Waterloo, ON N2J 3Z9 Phone: (866) 952-2876 Fax: (519) 888-9704 E-mail: mkuzyk@curocanada.com Lee Powell Vericlaim Canada 5915 Airport Road, Suite 201 Mississauga, ON L4V 1T1 Phone: (905) 671-7834 Fax: (905) 671-7819 E-mail: lee.powell@vericlaim.ca Fred R. Plant, AIIC ClaimsPro 85 Englehart Street Dieppe, NB E1A 8K2 Phone: (506) 853-8507 Fax: (506) 853-8501 E-mail: fred.plant@scm.ca Paul Féron, FCIP, CRM ClaimsPro 210 – 746 Baseline Rd. East London, ON N6C 5Z2 Phone: (519) 645-6500 Fax: (519) 645-2250 E-mail: paul.feron@scm.ca Lorri Frederick ClaimsPro 120 Adelaide St. W., Suite 2401 Toronto, ON M5H 1T1 Phone: (905) 308-6292 Fax: (416) 360-7335 E-mail: lorri.frederick@scm.ca James B. Eso, CIP, CIOP Crawford & Company (Canada) Inc. 539 Riverbend Drive Kitchener, ON N2K 3S3 Phone: (519) 578-5540 Fax: (519) 578-2868 E-mail: Jim.Eso@crawco.ca E. Grant King, BA, B.Ed., CIP Crawford & Company (Canada) Inc. 120 – 237 Brownlow Avenue Dartmouth, NS B3B 2C7 Phone: (902) 468-7787 Fax: (902) 468-5822 E-mail: Grant.King@crawco.ca Albert Poon, CIP Cunningham Lindsey Canada Claims Services Ltd. 1102 – 50 Burnhamthorpe Rd. W. Mississauga, ON L5B 3C2 Phone: (905) 896-8181 Fax: (905) 896-3485 E-mail: apoon@cl-na.com Marie C. Gallagher, FCIP, CRM Kernaghan Adjusters Limited 602 – 1 St. Paul Street St. Catharines, ON L2R 7L3 Phone: (289) 786-1074 Fax: (289) 723-1979 E-mail: mgallagher@kernaghan.com Craig J. Walker, CIP, FCIAA, FIFAA Maltman Group International 2001 Sheppard Ave. East, Suite 810 Toronto, ON M2J 4Z8 Phone: (416) 492-4411 Fax: (416) 492-5657 E-mail: cwalker@maltmans.com CIAA NATIONAL INSURANCE INDUSTRY ADVISORY BOARD Patti M. Kernaghan, FCIP, CRM Kernaghan Adjusters Limited 300 - 1445 West Georgia Street Vancouver, BC V6G 2T3 Phone: 1-800-387-5677 Fax: 1-800-387-5644 E-mail: pkernaghan@kernaghan.com Heather Matthews, CIP, CRM, CIOP Crawford & Company (Canada) Inc. 539 Riverbend Dr. Kitchener, ON N2K 3S3 Phone: (519) 578-5540 Fax: (519) 578-2868 E-mail: Heather.Matthews@crawco.ca Monica Kuzyk, FCIP, CRM Curo Claims Services 125 Northfield Dr. W., P.O. Box 218 Waterloo, ON N2J 3Z9 Phone: (866) 952-2876 Fax: (519) 888-9704 E-mail: mkuzyk@curocanada.com Fred R. Plant, AIIC ClaimsPro 85 Englehart Street Dieppe, NB E1A 8K2
Phone: (506) 853-8507 Fax: (506) 853-8501 E-mail: fred.plant@scm.ca Patricia M. Battle Canadian Independent Adjusters’ Association/L’Association Canadienne des Experts Indépendants Centennial Centre, 5401 Eglinton Ave. West, Suite 100 Etobicoke, ON M9C 5K6 Phone: (416) 621-6222 Toll Free: 1-877-255-5589 Fax: (416) 621-7776 E-mail: pbattle@ciaa-adjusters.ca Albert Poon, CIP Cunningham Lindsey Canada Claims Services Ltd. 1102 – 50 Burnhamthorpe Rd. W. Mississauga, ON L5B 3C2 Phone: (905) 896-8181 Fax: (905) 896-3485 E-mail: apoon@cl-na.com Marie C. Gallagher, FCIP, CRM Kernaghan Adjusters Limited 602 – 1 St. Paul Street St. Catharines, ON L2R 7L3 Phone: (289) 786-1074 Fax: (289) 723-1979 E-mail: mgallagher@kernaghan.com Craig J. Walker, CIP, FCIAA, FIFAA Maltman Group International 2001 Sheppard Ave. East, Suite 810 Toronto, ON M2J 4Z8 Phone: (416) 492-4411 Fax: (416) 492-5657 E-mail: cwalker@maltmans.com Ian Frost, FCIP Wawanesa Mutual Insurance Company 191 Broadway Winnipeg, MB R3C 3P1 Phone: (204) 985-3886 Fax: (204) 942-7724 E-mail: ifrost@wawanesa.com Tim Guernsey RSA Canada 18 York Street, Suite 800 Toronto, ON M5J 2T8 Phone: (416) 366-7511 Fax: (416) 367-9869 E-mail: tim.guernsey@rsagroup.ca Peter Hohman Insurance Institute of Canada 18 King Street East, 6th Floor Toronto, ON M5C 1C4 Phone: (416) 362-8586 Fax: (416) 362-1126 E-mail: phohman@insuranceinstitute.ca Glen Hopkinson XL Insurance Company SE 100 Yonge Street, Suite 1200 Toronto, ON M5C 2W1 Phone: (647) 277-8650 E-mail: glen.hopkinson@xlcatlin.com Dan Langer CICMA Ontario Chapter President c/o CIAA 5401 Eglinton Ave. W., Suite 100 Etobicoke, ON M9C 5K6 Phone : (416) 621-6222 Fax : (416) 621-7776 E-mail: danlanger@sympatico.ca Justin MacGregor Governor, IBAC 151 Rose Glen Rd. Port Hope, ON L1A 3V6 Phone: (905) 885-1551 E-mail: 2justinmacgregor@gmail.com Penny McCune SGI Canada 2260 11th Avenue Regina, SK S4P 0J9 Phone : 844 855-2744 E-mail : pmccune@sgicanada.ca Alex Walker, CIP Aviva Canada 2206 Eglinton Ave. E. Toronto, ON M1L 4S8 Phone: (866) 692-8482 E-mail: alex_walker@avivacanada.com Tina Gardiner, B.Sc.,CRM, CIP The Regional Municipality of York 17250 Yonge Street Newmarket, ON L3Y 6Z1 Phone: 1-877-464-9675 E-mail: tina.gardiner@york.ca
P.O. Box 76041 Oakville, ON L6M 3G3 Phone: (905) 825-0027 Fax: (905) 825-5543 E-mail: richard@azclaims.ca COMMUNICATIONS Richard Swierczynski, BA, CIP AZ Claims Services Inc. 1500 Upper Middle Rd., Unit #3, P.O. Box 76041 Oakville, ON L6M 3G3 Phone: (905) 825-0027 Fax: (905) 825-5543 E-mail: richard@azclaims.ca John D. Seyler, CIP Integrated Insurance Resources 5080 Timberlea Blvd., Suite 214 Mississauga, ON L4W 4M2 Phone: (905) 238-4985 Fax: (905) 238-2735 E-mail: jseyler@integrated-ins.ca Fred R. Plant, AIIC ClaimsPro 85 Englehart Street Dieppe, NB E1A 8K2 Phone: (506) 853-8507 Fax: (506) 853-8501 E-mail: fred.plant@scm.ca CONSTITUTION & RULES Paul Féron, FCIP, CRM ClaimsPro 210 – 746 Baseline Rd. East London, ON N6C 5Z2 Phone: (519) 645-6500 Fax: (519) 645-2250 E-mail: paul.feron@scm.ca CONVENTION Paul Hancock, B.Sc., CIP Crawford & Company (Canada) Inc. 300 – 123 Front Street West Toronto, ON M5J 2M2 Phone: (416) 867-1188 Fax: (416) 867-1925 E-mail: Paul.Hancock@crawco.ca DESIGNATION/EDUCATION Gary Ellis, BBA, FCIP, RF, FCLA, FCIAA, FIFAA AMG Claims Inc. P.O. Box 20102 Sherwood Charlottetown, PE C1A 9E3 Phone: (902) 628-9091 Fax: (902) 628-9093 E-mail: gary.ellis@amgclaims.ca Robert V. Pearson, CLA, FCIAA CIAA Honorary Life Member c/o CIAA National Office 5401 Eglinton Ave. W., Suite 100 Etobicoke, ON M9C 5K6 Phone: (416) 621-6222 Fax: (416) 621-7776 E-mail: info@ciaa-adjusters.ca Lorne Montgomery, CIP, FCIAA, FCLA Crawford & Company (Canada) Inc. 300-123 Front St. W. Toronto, ON M5J 2M2 Telephone: 416-867-1188 Fax: 416-867-1925 E-Mail: lorne.montgomery@crawco.ca EDITORIAL MMary Charman, CIP Crawford & Company (Canada) Inc. 1 – 120 Mulock Dr. Newmarket, ON L3Y 7C5 Phone: (905) 898-0008 Fax: (905) 898-1705 E-mail: Mary.Charman@crawco.ca John M. Sharoun, FCIP, FCIAA, CRM Crawford & Company (Canada) Inc. 300 – 123 Front Street West Toronto, ON M5J 2M2 Phone: (416) 867-1188 Fax: (416) 867-1925 E-mail: John.Sharoun@crawco.ca EMERGENCY MEASURES Richard Van Horne Action Investigations Inc. 2 Catelina Court Dartmouth, NS B2X 3G9 Phone: (902) 462-1222 Fax: (902) 462-3688 E-mail:richardvanhorne@actioninvestigations.ca
FINANCE John D. Seyler, CIP Integrated Insurance Resources CAREER RECRUITMENT PLANNING 5080 Timberlea Blvd., Suite 214 Mississauga, ON L4W 4M2 Richard Swierczynski, BA, CIP Phone: (905) 238-4985 AZ Claims Services Inc. 1500 Upper Middle Rd., Unit #3, Fax: (905) 238-2735
E-mail: jseyler@integrated-ins.ca Heather Matthews, CIP, CRM, CIOP Crawford & Company (Canada) Inc. 539 Riverbend Dr. Kitchener, ON N2K 3S3 Phone: (519) 578-5540 Fax: (519) 578-2868 E-mail: Heather.Matthews@crawco.ca Fred R. Plant, AIIC ClaimsPro 85 Englehart Street Dieppe, NB E1A 8K2 Phone: (506) 853-8507 Fax: (506) 853-8501 E-mail: fred.plant@scm.ca IBC: LIAISON, LEGISLATIVE & FORMS Paul Hancock, B.Sc., CIP Crawford & Company (Canada) Inc. 300 – 123 Front Street West Toronto, ON M5J 2M2 Phone: (416) 867-1188 Fax: (416) 867-1925 E-mail: Paul.Hancock@crawco.ca LICENSING J. Miles O. Barber, B.Comm. (Hons.), FCIP, CRM, RF Network Adjusters Ltd. 67 Folkestone Blvd. Winnipeg, MB R3P 0B4 Phone: (204) 897-5793 Fax: (204) 897-5797 E-mail: mbarber@mts.net MEMBERSHIP & QUALIFICATIONS Marie C. Gallagher, FCIP, CRM Kernaghan Adjusters Limited 602 – 1 St. Paul Street St. Catharines, ON L2R 7L3 Phone: (289) 786-1074 Fax: (289) 723-1979 E-mail: mgallagher@kernaghan.com NOMINATING Fred R. Plant, AIIC ClaimsPro 85 Englehart Street Dieppe, NB E1A 8K2 Phone: (506) 853-8507 Fax: (506) 853-8501 E-mail: fred.plant@scm.ca Heather Matthews, CIP, CRM, CIOP Crawford & Company (Canada) Inc. 539 Riverbend Dr. Kitchener, ON N2K 3S3 Phone: (519) 578-5540 Fax: (519) 578-2868 E-mail: Heather.Matthews@crawco.ca Lorri Frederick ClaimsPro 120 Adelaide St. W., Suite 2401 Toronto, ON M5H 1T1 Phone: (905) 308-6292 Fax: (416) 360-7335 E-mail: lorri.frederick@scm.ca James B. Eso, CIP, CIOP Crawford & Company (Canada) Inc. 539 Riverbend Drive Kitchener, ON N2K 3S3 Phone: (519) 578-5540 Fax: (519) 578-2868 E-mail: Jim.Eso@crawco.ca Craig J. Walker, CIP, FCIAA, FIFAA Maltman Group International 2001 Sheppard Ave. East, Suite 810 Toronto, ON M2J 4Z8 Phone: (416) 492-4411 Fax: (416) 492-5657 E-mail: cwalker@maltmans.com PRIVACY James B. Eso, CIP, CIOP Crawford & Company (Canada) Inc. 539 Riverbend Drive Kitchener, ON N2K 3S3 Ph: (519) 578-5540 Fax: (519) 578-2868 E-mail: Jim.Eso@crawco.ca Keith P. Edwards, FCILA, CLA, FUEDI-ELAE — ClaimsPro 120 Adelaide St. W., Suite 2401 Toronto, ON M5H 1T1 Ph: (416) 777-4479 Fax: (416) 360-7335 E-mail: keith.edwards@scm.ca PROFESSIONAL PRACTICES Fred R. Plant, AIIC — ClaimsPro 85 Englehart Street Dieppe, NB E1A 8K2 Phone: (506) 853-8507 Fax: (506) 853-8501 E-mail: fred.plant@scm.ca
June/July 2017
Claims Canada
9
Letters to the editor LTTE
Have something to say about an article you've read in Claims Canada? Please send your thoughts to the editor, Emily Atkins, Emily@newcom.ca.
Frank Cain writes: Good afternoon, In reading the article, “Property Loss Update: A review of recent cases, Part 2 - Carter et al V. Intact Insurance Company” (April-may 2017), I am surprised that there wasn’t mention of the broker’s involvement in duty of care. This case can be summoned up as typical of how things can go wrong when protocol is not followed. To illustrate: Why was the property not professionally appraised for replacement cost at the inception of the insurance or at a point when the value reached an exceptional limit? The validity of this is proven by the cost per sq. ft. of construction as shown to be $207 for the limit insured and $156 for the tribunal’s – a difference of 33%. If not as suggested by the preceding point, by what means or by whom was the insured limit of $7,614,750 established? Surely not by the broker, unless a qualified appraiser (and as reported to RIBO). Where is this information to be found? Did the broker explain the terms of the RCE regarding replacement to be of “like, kind and quality”? Augmenting, perhaps, with the words, equal in most or all ways to that existing. Did the broker explain that when loss or damage reaches more than 50% of the property most Building Departments will require total demolition (this would lead to a conversation regarding the immediately preceding point). Re Justice Phillips’ number two point: any number of conversations could have taken place regarding the ultimate The author replies: “These are very interesting observations from reviewing my article. The writer is a professional broker and his questions demonstrate many good points about what ground should be covered by a broker in selling their product. When writing this article the point of reference is first the Ontario Court decision. That judgement outlines one judge’s opinion. This decision was not accepted by the named insured, which led them to appeal the decision. Subsequently, the Ontario Court of Appeal heard the case in front of three appeal court judges. Their one-day hearing led to them taking seven months to write a unanimous decision that supported the decision of the original trial judge. The appeal court is our top court in Ontario so this decision is very significant. Any legal decision you review contains an overview of the facts. In this particular case, they reference a decision made in “Appraisal” where the building “replacement cost” is decided at about $5.7 million. The policy limit was about $7.6 million. What we don’t know from the decision is whether or not the “replacement cost” price agreed upon involved estimates to use
10 Claims Canada
June/July 2017
disposition of the subject of insurance. For example, was wreckage value insurance discussed if the owners had earlier proclaimed they would not rebuild should loss or damage be extensive, following such questioning by the broker? Again, this would open the door to other relevant points, as above. Reference to moral hazard is in my opinion beyond the bounds of rational thinking when the contractual concept of the insurance is based on established principles of good faith between the two parties. Unless the client deliberately sets out to tell the broker or insurer that he is falsifying his intentions of the insurance, one will never know until after the fact, and half a lie is always harder to prove than a whole lie. Number four of the Summary is directly aimed at the broker. What it is saying is that the broker had the last clear chance to make certain that all relevant points were made clear to the client or obtained when any doubt exists. Four years of loss value determination and settlement. If you need a special lesson as a broker on how to conduct yourself in dealing with a client, this would be it. Better to pass the business on to an outside associate or, perhaps more preferable for the sake of the house, to sit down and discuss with others in the brokerage the ways and means of handling such situations. It would be a slam-dunk idea to have the client with you, listening in, and asking all the questions he wants. part of the existing building to rebuild. For example, perhaps the building foundations were unaffected by the fire and could be re-used. So, looking at pure numbers can sometimes involve a bit of guesswork for the reader. However, I would say that the letter writer makes an excellent point about how a broker and/or insurer go about determining the policy limit on a building loss. They might be relying upon a building estimating tool or perhaps a simple formula of multiplying the square footage by a cost per square foot. As information technology increases there is not much doubt that this whole area will be tightened up as under-insuring a risk leaves premium on the table that an insurer wishes to collect. This particular judgement involves a key issue that has little to do with the replacement cost or policy limits. It’s all about what’s considered “material of like kind and quality". Like the letter writer, I have some different views on parts of this judgement but my views won’t count as much as the three esteemed judges who sat on this decision. Glenn Gibson www.claimscanada.ca
Canadian Insurance Claims Education Benevolent Foundation OBJECTIVE • To assist with funding needed to further education of Canadian students entered in an insurance claims related discipline.
• Applications must be received at the CIAA National Office by July 31st annually. • Awards will be announced at the CIAA Annual General Meeting in August.
VALUE • A minimum of one $1000.00 award annually.
DONORS • Canadian Independent Adjusters’ Association • Canadian Federation of Insurance Claims Associations
SUBMISSION • Applications are available at the Canadian Independent Adjusters’ Association National Office: CIAA Centennial Centre, 5401 Eglinton Ave. W., Suite 100 Etobicoke, ON M9C 5K6 Tel: (416) 621-6222 Fax: (416) 621-7776 E-mail: info@ciaa-adjusters.ca
www.claimscanada.ca
February/March
www.claimscanada.ca
2017
PRESSURE CHANGE
Official Journal of
Official Journal of
t Adjusters’ Association the Canadian Indeépenden
the Canadian Indépendent
December/January
2017
Published by:
Adjusters’ Association
eter reflects Risk barom ess ts to busin evolving threa
NEWCOM BUSINESS MEDIA INC.
PM40063170
PM40063170 p1 CLAIMS COVER
DECJAN2017
final.indd 1
2016-12-23
Emily Atkins Editor (416) 510-5130 emily@newcom.ca
Karen Samuels Production Manager (416) 510-5190 karens@newcom.ca
Christine Hirst Mike Wells Account Manager Account Manager (416) 510-5114 (416) 510-5122 christine@newcom.ca Official Journal of the Canadian Indeépendent Adjusters’ Association michael@newcom.ca Subscription inquiries (416) 614-5831
Ian Portsmouth Managing Director, Insurance Media Group (416) 510-6800 ian@newcom.ca
Chairman and Founder Jim Glionna
President Joe Glionna
Vice President, Operations Melissa Summerfield
Controller Anthony Evangelista
Gerald Heydens Art Director
Director of Circulation Pat Glionna Head Office 451 Attwell Dr., Toronto, ON M9W 5C4 (416) 614-2200 • fax: (416) 614-8861
www.claimscanada.ca Produced by the publishers of Canadian Underwriter magazine
A bi-monthly magazine (6x per year), Claims Canada is published by NEWCOM Business Media Inc. is located at: 80 Valleybrook Drive, Toronto, ON, M3B 2S9. Claims Canada magazine is the Official Publication of the Canadian Independent Adjusters’ Association [CIAA] and through its editorial content and circulation brings together the ‘entire property & casualty insurance claims market nationally’ with information and insight into the profession, business and people of insurance claims and loss adjusting. All key claims process stakeholders are reached as part of our readership community – including: both CIAA member and non-member independent claims adjusting firms; insurance and reinsurance company executive, claims management and
www.claimscanada.ca
10:00 AM
Regional Office 80 Valleybrook Dr., Toronto, ON M3B 2S9 (416) 442-5600 • fax: (416) 510-5169
claims adjusting personnel; corporate risk managers and loss control professionals; insurance brokers; insurance law firms; forensic engineers and accountants; appraisal, restoration, rehabilitation and collision repair professionals; Insurance Institute chapters; insurance associations, regulators and related claims market recipients. The contents of this publication may not be reproduced or transmitted in any form, either in part or in full, without the written consent of the copyright owner. Nor may any part of this publication be stored in a retrieval system of any nature without prior written consent.
June/July 2017
Claims Canada 11
Watch and wait
Will the sharing economy be warm and fuzzy or an existential threat to the insurance industry?
By Emily Atkins
T
The sharing economy is all around us. Many of us take part either deliberately or simply through expedience — think Uber or Airbnb — but it remains a nebulous concept, full of promise and more than a little confusion. That’s part of the reason the Insurance Institute of Canada decided to commission one of its annual emerging issues reports on the subject. Released this spring, Sharing Economy, Implications for the Insurance Industry, was authored by Paul Kovacs, founder and executive director of the Institute for Catastrophic Loss Reduction (ICLR), president and CEO of the Property and Casualty Insurance Compensation Corporation (PACICC), and Adjunct Research Professor, Economics, at the University of Western Ontario. A second impetus for the study is the sharing economy’s evolving nature. “We thought the sharing economy is really an important issue. It’s something that is not well understood in the industry and it’s changing in a fairly rapid way,” Kovacs said in an interview. “So we’re trying to figure out where we are right now in terms of what the issue is, and in particular what it means for insurance.” When he says they are trying to figure out what the issue is, Kovacs is being quite literal. When people talk about the sharing economy, they can mean wildly different things, with huge variations in the resulting implications for business. Get any two experts on the sharing economy together, he says, and the only sure thing is that they will disagree on what it is. This is because it is both a new phenomenon and one that is changing extremely fast. Its tentacles can be seen to reach into many different areas of economic and social interaction, with apparently as many perspectives on how to define it as there are startups that can carry the label. For the purposes of the paper, Kovacs decided on the Oxford English Dictionary definition: “An economic system in which assets or services are shared between private individuals, either free or for a fee, typically by means of the Internet.” The report elaborates, noting: “The current widespread use of the Internet supports the emergence of online platforms where consumers and providers can meet and agree to exchange goods and services — the sharing economy. This may be a commercial exchange where a fee is paid. Perhaps the exchange involves no payment, but a
www.claimscanada.ca
credit is banked to secure a service in the future. Several platforms bring together people who provide goods and services free of charge.”
Benefits As the report notes, the concept of ‘sharing’ connotes warm, fuzzy feelings, and many people feel good about participating in transactions that are individualized as opposed to institutional. As well, sharing enterprises promote optimization of assets. By having many people drive a vehicle a car-share program ensures that asset is used, not sitting and depreciating in someone’s driveway most of the time. Likewise, home sharing allows people with extra space to use it productively. This optimization confers personal benefits to the property owners — in the form of cash — and also contributes to lower impacts on the planet’s resources, thus making them sustainable activities. Another benefit is lower prices. Decentralization reduces the overheads associated with large corporations, and prices are able to fluctuate very directly with demand. As well, sharing enterprise allows people to engage in flexible employment, and it also encourages self-regulation through social media customer reviews, the report notes.
What’s at stake To understand its implications for the insurance industry, the report argues you must first understand the philosophical underpinnings of the sharing economy. At its heart is a notion of trust. People feel they can place more trust in an individual from whom they contract a service on relatively casual basis than they can in traditional institutions. Big corporations have lost the credibility they once had to tell us what we should worry about, Kovacs said. “There was a period 40, 50 years ago where insurance companies, banks, governments, the church, would all say, ‘Trust us’. The rapid expansion and growth and institutionalization of insurance came in a period where the car was just coming in and you were worried about home ownership, and the insurance companies said, ‘Trust us. Give us a relatively small amount of money, and if something bad happens we’re going be there for you’,” he said. “And the foundation of the sharing economy is ‘I’m not sure I want to trust one of these big, faceless groups out there.’”
June/July 2017
Claims Canada 13
...continued from page 13
Kovacs finds it fascinating that this shift in attitude is arising in the face of governments and corporations warning us about what we need to fear. The sharing economy reflects an opposing feeling. It’s people putting their trust in other individuals to follow through on a promise made to deliver a good or service. This trend, he asserts, may have seri-
ous implications for the way insurance is delivered. It is a trust-based business that relies on the consumer’s belief that the insurer will pay out when there is a legitimate loss. But this new economy is based simply on a perceived fellow-feeling between strangers. “Insurance needs trust and has been providing it for a long period of time.
And now a new model has shown up which is a whole different thing,” he says. “If that’s where the future’s really getting to then that could shake things up. Anyway, I don’t think it will get resolved any day quickly.”
Two prongs WHAT IS THE SHARING INTRODUCTION ECONOMY? The report points out that the sharing
Timeline footnotes 1
Timeline of technological advancements and examples marking the advent of sharing platforms
a b c d e f g h
https://en.wikipedia.org/wiki/Napster https://en.wikipedia.org/wiki/Zipcar https://en.wikipedia.org/wiki/BlackBerry https://www.lifewire.com/how-many-iphones-have-been-sold-1999500 https://www.airbnb.ca/about/about-us http://uberestimator.com/cities https://www.statista.com/statistics/269915/global-apple-ipad-sales-since-q3-2010/ Walsh, Bryan. "Today's Smart Choice: Don't Own. Share," as part of Time magazine's "10 Ideas That Will Change the World."
Image used with permission of IIC EMERGING ISSUES RESEARCH SERIES 14 Claims Canada
June/July 2017
10 www.claimscanada.
continued on page 16...
economy has implications for both the insurance product and the mechanisms of the insurance industry. On the first hand, the new sharing economy businesses are operating in a space that has not really been defined. They are typically quasi-personal, quasi-business operations that can leave the operator improperly or insufficiently covered against the risks of doing business. Until very recently policies have not been available for ride-sharing or roomand home-sharing providers. That is changing, with the province of Ontario, for example, introducing fleet insurance
The full 66-page text of Sharing Economy, Implications for the Insurance Industry is available to download at: http://tinyurl.com/iic-sharing
ty for adjusters to offer their expertise in helping the underwriters figure out what products will meet the needs of sharing enterprise. “I would love to see them get involved in that,” he says.
An existential question The second prong is much more difficult to get a handle on. The report notes that new insurtech and peer-to-peer insurance companies are making forays
into the insurance business around the world. There is an upsurge in enterprises offering insurance-like products that aim to compete with the established industry, as well as some offering services that dovetail with it. Insurtech, in particular, is opening up new avenues of data analysis that promise to enhance the traditional insurers’ ability to analyze risk and underwrite new lines. Many in the
MKA Canada Opens Office in Winnipeg
options for those in ride-sharing enterprises. Home sharing policies have also been recently made available, beyond the mandatory coverage required by some of the sharing sites.
An opportunity for adjusters But given the number of individuals taking part in sharing economy activities, Kovacs says it’s inevitable that there will be messy situations when these people try to make claims against policies that don’t exactly match their activities. “It’s not hard to come up with literally hundreds of different companies in Canada who are offering sharing-type services, and I think most of them do not know that they don’t have proper insurance right now,” he says. “ “I think the industry will awaken and see this amazing opportunity of lots of customers who want insurance, who want the right insurance, and I hope they involve the experienced claims people in the design and the follow-through in terms of those products.” He points out that it is the claims managers who know a great deal about what people actually need, because they are the ones who “actually go and sit with policy holders and help them.” Although this isn’t a new issue, that claims managers should be involved in the product design process, “it’s just pushed to a higher level” now.” Kovacs says there is a ripe opportuniwww.claimscanada.ca
We are excited to announce that we have expanded our operations in Canada with the opening of our Winnipeg Office. Since 2008, MKA Canada has offered creative solutions to the Construction, Legal and Insurance industries. Our Service Solutions: • Property Loss and Course of Construction Claims • Liability Claims • Construction Contract Disputes • Construction Scheduling and Delay Claims • Project Cost Reporting, Monitoring & Clerk of the Works
Winnipeg Office Contacts: Etienne Nel - enel@mkainc.com Barry Milliner - bmilliner@mkainc.com
WWW.MKAINC.CA
204.952.2193 June/July 2017
Claims Canada 15
...continued from page 15
insurtech space and sharing enterprises are choosing established insurance industry partners (for example, WeGoLook, which we profiled in the last issue of Claims Canada). Kovacs said that in his recent conversations with senior insurance executives, they are “ uniformly positive” about the opportunities for innovation that the insurtech industry is offering. “Their big challenge was that there was so much coming in the insurtech area that included claims and investing and under-
writing…how did they filter through the many different things coming at them and find the ones that would make the biggest impact and they really could work with.” But many in the peer-to-peer realm are critical of established insurance providers. And they are setting up as competitors to both brokers and insurers, offering risk pooling or custom coverages. These organizations — so far there are none in Canada yet — fly under the regulatory radar. In the jurisdictions
where they operate, they are “not subject to solvency and market conduct regulations applied to traditional insurers. The company does not put its own capital at risk when it deals with policyholders,” the report notes. So if they are not insurance, yet compete with the established insurance industry, there is great potential for disruption. “Time will tell if there is a clear and consistent distinction between insurance and non-insurance services when viewed by consumers, regulators, and the Canadian insurance industry,” the report says.
Where do adjusters fit?
KNOWLEDGE YOU NEED FROM THE PEOPLE YOU TRUST As a claims adjuster, building a strong team is essential to help you fairly assess the income losses sustained by injured parties. We provide enhanced services that insurance professionals depend on as they pertain to:
Kovacs says although the report did not focus on claims handling and adjustment, he sees several ways the sharing economy might have an impact. Professional claims adjusting has a cost, and if these sharing services are trying to be cheaper, they may eliminate the adjuster and opt instead for peer review. Some have even gone so far as to suggest that a claim’s validity be decided by a jury of fellow pool participants. However, Kovacs also sees an upside where it may end up falling to experienced adjusters to step in, as freelancers, to sort things out when these peer reviews turn out to be questioned by someone who feels they were treated unfairly. On the other hand, he says, “I did not see sharing-type products with a different claims management approach transforming insurance in other parts of the world. It isn’t the way it’s gone yet. Personally I think the public like what is in place and they know there’s a cost involved, but you get something of value for that.”
•
Accident Benefits
•
Tort and Personal Injury Claims
•
Commercial Losses
•
Business Interruption
Ripe and ready?
•
Forensic Investigations
The report notes that author Rachel Botsman “has identified four characteristics of industries ripe for disruption: complex experiences, broken trusts, redundant intermediaries, and limited access.” Although the exact fit of the Canadian industry to these hallmarks is a matter of debate, signs indicate it may be ready. The industry itself is working hard to streamline its interactions with consumers, particularly in the area of client interaction, indicating that it recognizes the importance of simpler, easier processes. By contrast, peer-to-peer operations and sharing enterprises certainly offer attractive simplicity in their person-to-person dealings. The report notes that while most
With over 100 offices, BDO has the industry knowledge and expertise to help you promptly resolve claims. Greg Hocking 416 775 7800 ghocking@bdo.ca www.bdo.ca
16 Claims Canada
June/July 2017
Janet Olsen 416 233 5577 jolsen@bdo.ca
Chetan Sehgal 416 775 7812 csehgal@bdo.ca
www.claimscanada.ca
“claimants express high satisfaction with the insurance industry” there are always some who have bad experiences. Coupled with the general trend towards a lack of trust in institutions, it is easy to see how the sharing offerings could pose a challenge to the established industry. The role of the broker is increasingly challenged by the advent and availability of sophisticated new technologies that ask the questions and provide answers to consumers any time, anywhere, fulfilling demand for immediacy and simplicity. Out of sync with Botsman’s criteria is the breadth of options available to Canadian consumers. “Insurance is the most competitive financial services industry in Canada, and consumers have many choices in terms of how they purchase protection,” the report states. It’s clear the Canadian industry is not immune to sharing economy competition and cooperation. The report asks the insurance industry to take notice of developments in the sharing economy because they threaten to disrupt the traditional way the insurance business gets done. The report makes recommendations designed to address both prongs of the sharing economy challenge to insurance. On the provision of insurance to sharing economy players, it suggests the industry should: • Work with regulators to ensure innovation is supported to create flexibility for insurers to meet sharing economy consumers, while also protecting the public. • Assess readiness for the sharing economy; identify how the insurance industry will develop that suit the evolving needs of sharing providers. • Partner with other stakeholders, including sharing organizations and governments, to better document the current and expected future state of the sharing economy in Canada. • Establish communications so participants from the sharing economy can express and successfully address their insurance needs and expectations. • Track and report on developments in the sharing economy around the world, including the availability of insurance and the evolution of regulations. Regarding the potentially disruptive business models being introduced, the report suggest the insurance industry should: • Track how non-traditional competitors affect insurance in countries with similar markets, like the United States and Britain. • Monitor traditional companies and intermediaries that partner with new entrants or introduce unconventional products and services based on sharing. • Support insurance regulators in protecting consumers from organizations offering insurance products that are not licensed, fail to comply with established solvency and market conduct regulations, and avoid taxation. • Prepare to respond to the direct challenges new competitors will aim at traditional industry practices; this includes planning to directly challenge false statements. • Anticipate that the advent of peer-to-peer insurance competition in Canada could be used by the industry to press for a review of the current regulations and tax burden facing the industry and its customers. It’s a wait-and-see game, the report concludes, change is coming, but in what form and how fast remains to be seen. “I think that sharing will be important, and even if we’re not clear all of what it means yet or what we should include in the discussion, I think it will be a process that will take time,” Kovacs concluded. • www.claimscanada.ca
Governments are paying attention…but not doing much Ontario: In October 2015, the province established the Sharing Economy Advisory Committee with representation from key ministries. Its mandate is to oversee the province’s approach and to “harness opportunities presented by the sector”. The committee aims to offer insight on policy, regulatory and legislative challenges typically associated with sharing economy business models. It will also be taking into account the views of traditional sectors to ensure initiatives do not unduly affect their competitiveness. It expected that new regulations might be required in some circumstances, while in others the regulatory burden might need to be reduced. By the 2016 budget, the province began to take more of a position, stating: “The sharing economy has significant potential [emphasis added] to create jobs and drive economic growth, productivity and innovation. The benefits of the sharing economy also include cost savings and greater choice for consumers, flexible employment opportunities and increased access to capital for small startups.” Since the 2016 Budget, the Committee has been meeting with municipalities and industry, and has sought public opinion through polling and focus groups. The province introduced automobile insurance for ride-sharing enterprises by approving a regulatory change under the Insurance Act that allows commercial fleet insurance to be offered for vehicles available for hire through an online application. The province cautions that “more changes will be necessary and the government remains committed to working with FSCO and insurance stakeholders to develop a long-term solution that will fully integrate sharing economy business models into Ontario’s auto insurance system.”
Alberta: The insurance regulator in Alberta established new coverages for ride-sharing providers in the past couple years, after working with the industry and the providers to examine the scope of the problem.
Quebec: In 2016 the Quebec regulator, the Autorité des marchés financiers (AMF), reminded people that insurance is regulated and providers of insurance through peer-to-peer risk-sharing platforms, like traditional providers, require registration and regulatory approval. Consumers were warned that AMF had yet to determine the compliance of peer-to-peer products and the companies offering them.
June/July 2017
Claims Canada 17
• spotlight S
In the know
Local knowledge is key to success for Algom Adjusters BY EMILY ATKINS
I
n northern Ontario, the towns of Elliot Lake and Espanola, along with Manitoulin Island in the northern part of Lake Huron, form a triangle right in the middle of the 300 kilometres that separate Sudbury and Sault Ste Marie. If you need a claim adjusted in this zone, Blair Boilard and his team at Algom Adjusters are the ones to call. Algom Adjusters was formed in 1977 by Roger Lauzon, who purchased a part of the former Algoma Adjusters and set up shop in Elliot Lake. Blair joined the company in 1990 as a “greenhorn” adjuster. He had started work as an insurance broker in 1987, and when Roger had an employee retire, Blair jumped at the chance to make the switch to claims. “I thought claims would be a very interesting side to the business, so I took him up on the offer,” he says. Blair then worked his way up through the ranks, earning his license and working towards his CIP designation (then the AIIC). He and Roger became partners in Algom Adjusters in 2010, and Roger has subsequently retired from the business. Blair is now the owner, and has two colleagues, adjuster Cheryl Sharratt, and Sherrie Boilard, Blair’s wife, who is the support person. Their youngest, Autumn, is working part time this summer, helping in the office.
Big or small Algom Adjusters not only covers a relatively large geographical area, it is also diversified in the kinds of files it handles. “Big or small, we do them all,“ Blair says. “Honestly, I’ve always joked with various insurers about that over the years, but we do all lines.” 18 Claims Canada
June/July 2017
The focus is on property, both private and commercial. He does a bit of casualty and a/b work and the company has a couple of municipal accounts. There are also business interruption claims, so “we are lucky — we are well rounded and see claims from all sides of business,” Blair notes. It’s a good space to work in, he adds. “We’re not counting on any one area for work.”
Who you know While the geography and scope may be large, it’s the small, tight-knit community that helps to define Algom’s success. “Being as small as we are, when we get a claim from whoever it is, they know who is handling their claim,“ Blair says. “We’re not passing it on to others, so I think we’re fortunate that way. We get work because of the good work that we do.” Reputation is absolutely essential, he adds. Living in a smaller community means he knows all the players. “We know the people, whether it’s the contractor, the lawyer, the doctor — whoever. And it helps to have some background information sometimes.” This knowledge comes in handy, Blair says. For example, if there is a need to do surveillance, he will engage in pre-surveillance. “So we’ll get all the goods on the individual because of the contacts that we have,” he says. That way he knows ahead of time if someone they are watching is planning an activity like climbing a tree to cut it down, or putting up a scaffolding to work on their house. Then he can arrange to have an investigator in place to record the action. Not only does this allow his investigator to get the information he needs to
make a case, it also saves his clients costs because he can target resources efficiently. “We’re really successful with that because we are the eyes and ears here. It’s the old school way of doing things and it still works,” he adds.
The local advantage Blair says that although being a small IA has its challenges sometimes when considering competition from the larger, national firms, he also notes that being smaller — and local — confers big advantages. He has built strong relationships with smaller insurers and mutuals. “They seem to be quite receptive to working with smaller companies like ours,“ he says. As well, geography is on his side, as any other adjuster would have to travel between 320 and 400 kilometers to get to Elliot Lake and back for an investigation. In Espanola, they are the closest IA to Manitoulin Island. Blair notes, “we still have lots of competition and that’s the nature of the business. Our industry is changing because we see contractors covering a large area and they are doing work directly for various insurers with no adjuster on site. But that’s just a sign of the times.” He notes that by being on site Algom has helped clients save costs. In one recent claim a contractor removed wet material from a garage bay and then introduced drying equipment, which was not required as the wet material had been removed. This simple application of “common sense,” Blair says, saved Algom’s principal $3,000.
Strength in numbers Blair has long been a believer in the power of the CIIA. Over the years he has www.claimscanada.ca
L-R: Cheryl Sharratt, Blair Boilard, Sherrie Boilard and Autumn Boilard of Algom Adjusters
attended many conventions and seminars, noting that he has met lots of fellow adjusters this way, many of whom he considers great friends. “There’s some great people in our industry and in our association,” he notes. “And they’ve done some great things over the years. I was impressed with the plan for insurance for the members.” One initiative he is particularly interested in now is finding a way for the association to offer a health benefit plan for members. “As a small IA we have a benefit plan for myself and my staff. But it would be pretty nice if we could, as an association, be a group and look to have the same coverages with much more feasible fees or rates,” he says. Blair also believes the association can help small IAs work on succession planning, which he knows is a serious issue for small companies, requiring a lot of forethought and consideration. He says that being in the north might be a hindrance or a help in his eventual search for someone to step in at Algom www.claimscanada.ca
Adjusters. However, he’s not quite there yet. “Cheryl and I are almost the same age actually, and we both enjoy doing what we’re doing. I’m here for probably another five to ten years for sure. When I am ready to slow down a little bit, then I would look at bringing in another junior person if they are interested.”
Endlessly interesting For the time being, thoughts of succession really aren’t top of mind, as Blair says. He loves his work, and the variety is brings. “You never know what tomorrow’s going to hold.” Sometimes its rough, he says, citing the collapse of the Algo Mall in Elliot Lake in 2012, which killed two, injured 19 and destroyed many businesses and the public library. “It was a pretty big hit for a small community,” he says. “But it’s turned a corner and a lot of it is due to insurance.” Satisfaction comes in knowing that he is doing a job that people appreciate and remember. He recounts being called to a remote property on Manitoulin Island
where the owner said he specifically asked for Blair because of a claim he had worked years before.
Keep it personal When asked about the keys to success in claims, Blair says keep on learning. “Take advantage of every educational opportunity that you have, and there are lots out there. And now with webinars there are even more opportunities and it takes less time, and it’s a lot less costly.” Perhaps it’s a product of his success in a small community where personal relationships play a large part in business, or maybe it’s the reason for it, but Blair also says that he would far rather attend a seminar or conference in person. “It’s when you have an opportunity to sit down with someone and have a coffee or a beer afterwards; you can learn just as much by interacting with people on a social level. If you take the time to just get to know people, have a conversation, I learn more sometimes outside of the seminar than I do inside.” • June/July 2017
Claims Canada 19
How AI is transforming property i BY DARA BANGA, FCIP, CFEI
Across industries, and around the globe, artificial intelligence (AI) is transforming customer service. It’s a major player in insurtech, which is taking on a new importance in the insurance industry – and it’s about time, too, according to Insurance Canada. “With a few exceptions, the vast majority of P&C insurers have lagged other industries in the application of technology,” said contributor Patrick Vice. So, what can artificial intelligence do for property claims in Canada? Let’s find out.
Artificial intelligence on the rise “According to a study by Oracle, nearly eight out of 10 businesses have already implemented or are planning to adopt AI as a customer service solution by 2020,” said Adelyn Zhou at Forbes. The study surveyed 800 business executives across France, the Netherlands, South Africa and the UK who do business in manufacturing, high-tech engineering, online retail and telecommunications. While Oracle didn’t focus specifically on the insurance industry, its findings are salient nevertheless. In the risk management realm, AI has the potential to improve efficiencies in risk analysis, customer interaction, decision-making and claims assessment. “AI’s initial impact primarily relates to improving efficiencies and automating existing customer-facing, underwriting and claims processes,” said PwC in a study published last spring. “Over time, its impact will be more profound.” Bringing AI to customer service – with chatbots For insurers who want to improve customer service with AI, there are two primary strategies. In the first, human reps can use artificial intelligence to help them become more efficient and effective in their existing job descriptions. In short, it’s a new tool with which reps can improve on their current tasks. In the second strategy, chatbots become the customerfacing agent, taking care of customers’ needs with no human involvement. For example, NextInsurance — a Silicon Valley insurtech company based in Palo Alto, California — just launched “the world’s first full insurance signup via Facebook Messenger,” it said, enabling American photographers and physical trainers to get business insurance from a chatbot. The benefits of using chatbots in this way are straightforward: They improve the customer experience while cutting costs for insurers. And, when it comes to property claims, improving the 20 Claims Canada
June/July 2017
experience isn’t just icing on a cake. It’s crucial. According to Canadian Underwriter, research shows that a positive customer experience is a key determinant in customer retention. Chatbots lower handling time by at least 10 percent, resolve more issues without needing to escalate (saving on the cost of more expensive support), increase first-contact resolution rates, and save insurers from having to train agents on basic tasks that chatbots can do for them, Zhou said.
How chatbots improve property claims Customer acquisition and support aren’t the only ways to put chatbots to work in insurance. Chatbots can revolutionize the claims process, as well. According to PwC, the “roboclaims adjuster” can leverage a variety of AI technologies to reduce processing time and costs. 1. Soft robotics. Bots use mining techniques to identify bottlenecks, optimize efficiencies, and improve conformance to standard claims processes. 2. Graph analysis. Bots use social networks to find fraud patterns in claims. 3. Machine learning. Bots use deep learning techniques to automatically categorize severity and build predictive models. www.claimscanada.ca
y insurance claims of how their claim is moving through the process, helping them maintain realistic expectations and feel more involved in the meantime. Turque isn’t just planning to do better at what’s already being done. They aim to expand on the conventional model at the same time, combining typical insurance products with legal and tax services as well. To repeat what PwC said earlier, the impacts of advanced technology in insurance are already significant, and will only grow “more profound” over time.
4. Sensors (IoT). Bots use home and industrial data from connected devices to build operational intelligence on the frequency and severity of property claims. 5. Simulation modeling. Bots build deep causal claims models and link them with products and distribution. It’s one thing to talk about how chatbots do things. It’s quite another to talk about how they make people feel. So, how do the points on this list translate to a better customer experience?
An opportunity for disruption Filing a claim in the conventional way is nothing to get excited about. It can take weeks for claimants to navigate the back-and-forth following a loss, get a decision, and receive their reimbursements. This is one place where artificial intelligence may well disrupt the conventional scene: In Toronto, for example, the P&C startup Turque plans to leverage advanced technology to deliver a “streamlined claims experience”. What specifically does that mean? In Turque’s case, customers will be able to access a “virtual vault” of data on their house coverage and deductibles. There, they’ll be able to file claims, upload media (photo, video and voice recordings), schedule repairs and take care of property emergencies. More importantly, it will give them a transparent view www.claimscanada.ca
Get ready for an insurtech breakthrough With all this activity brewing in the AI chatbot insurtech scene, one can expect good things. According to Mukul Ahuja, a business strategist at Monitor Deloitte, 2017 is going to be a breakthrough year for insurance in Canada. “To start with, global venture capital activity related to insurance startups hit its highest annual total in 2016 with $1.69 billion invested in 173 deals,” he said. “Meanwhile, Canada has emerged as a premiere test bed for fintech solutions broadly speaking, having evolved some key assets and raised more than $1 billion in start-up funding since 2010. Indeed, Canada has the highest concentration of tech firms outside of Silicon Valley (in Ontario), a well-established research and advanced education infrastructure, the largest financial sector in North America outside of New York, as well as important entrepreneurship and incubator spaces, such as Toronto’s MaRS Discovery District, the Ryerson DMZ, and Communitech in Kitchener.” Among other factors, such as the sharing economy, autonomous cars, the IoT and big data, AI is slated to play an important role here. While it’s hard to believe that AI will ever replace the need for thoughtful, thorough independent claims adjusters in the field, it’s easy to see how it could automate the resolution of simple claims and provide data to better inform complex claims decisions. At the end of the day, according to the German scientist Sebastian Thrun, AI isn’t actually about robots. “Nobody phrases it this way, but I think that artificial intelligence is almost a humanities discipline,” Thrun said. “It’s really an attempt to understand human intelligence and human cognition.” Perhaps no other AI application makes this clearer than customer service in insurance claims. First and last, the purpose of the tool is to deliver a positive experience for those who use it — and in so doing, to improve business outcomes for those who deploy it. Dara Banga, FCIP, CFEI, is the President of DSB Claims Solutions, headquartered in Brampton, Ontario. To learn more, visit www.dsbclaims.com.
June/July 2017
Claims Canada 21
Your Insurance News Source .ca
Sign-Up at http://bit.ly/cudaily to receive Canadian Underwriter’s free DAILY e-Newsletter each morning – containing all of the latest industry news, press releases, blogs, events, careers and more.
Ontario Court of Appeal finds no conflict of interest in In Whirlpool Canada Co. v Chavila Holdings Ltd., 2017 ONCA 81, a three-member panel of the Ontario Court of Appeal, with Chief Justice Strathy dissenting, found there was no conflict of interest in defence counsel, appointed under a contractual indemnification agreement, defending the Appellant, Whirlpool Canada Co. (Whirlpool). Defence counsel had been instructed not to raise a limitation defence argument on behalf of Whirlpool. While the case did not involve an insurance policy, it is of interest because the Court used duty-to-defend principles in its analysis, and the reasoning of both the majority and dissent have the potential to affect how the courts may approach the question of conflict of interest in the future. The majority of the Court of Appeal found the parties did not have adverse interests and that the representation of Whirlpool was not materially or adversely affected. For this reason, Whirlpool’s appeal from the judge’s decision that there was no conflict was dismissed. Dissenting, Chief Justice Strathy found defence counsel was in a conflict of interest after being instructed not to raise the limitation defence. Additionwww.claimscanada.ca
split decision BY MICHAEL S. TEITELBAUM
ally, the duty to defend in good faith was breached.
Background In 1997, Whirlpool sold land to two of the Respondents, Outrigger Investments Limited (Outrigger) and Chavila Holdings Limited (Chavila). The parties entered into an indemnity agreement at the time of the sale. Outrigger and Chavila agreed to indemnify Whirlpool for liability arising from the contamination of the lands in the vicinity of the property. 863800 Ontario Limited (863800), a company affiliated with Outrigger and Chavila, also purchased neighbouring land from Canadian Pacific Railway Company (CP) and Oxford Properties Group Inc. (Oxford). In 2004, 863800 brought an action against CP and Oxford for the contamination of the land it purchased. In 2012, after the pleadings had closed, CP and Oxford issued separate actions against Whirlpool seeking contribution and indemnity.
After the proceedings were brought against Whirlpool, Outrigger and Chavila confirmed they would defend Whirlpool. Further, 863800 confirmed it would not seek to collect any award it received against CP and Oxford, for which Whirlpool was required to indemnify CP and Oxford. After appointing Whirlpool’s defence counsel, Outrigger and Chavila instructed counsel not to raise a limitation period defence on behalf of Whirlpool. As companies affiliated with 863800, Outrigger and Chavila did not want Whirlpool “assisting” CP and Oxford in a limitation argument. In response, Whirlpool brought an Application arguing the appointed counsel was in a conflict of interest, and that Whirlpool was entitled to retain its own separate counsel paid for by Outrigger and Chavila.
The decision At first instance, the Court found there was no conflict of interest in appointed counsel taking instructions from Outrigger and Chavila. The nonpursuit of the limitation defence was of no consequence to Whirlpool given the indemnity agreement. Whirlpool would suffer no economic setback even if judgment were found against it. In response to Whirlpool’s argument that it may still suffer reputationJune/July 2017
Claims Canada 23
al damage and/or the indemnity may not be paid, it was found there was no specific evidence provided to support that argument. The Court found there were no instructions it could foresee being given by Chavila and Outrigger to appointed counsel that would harm Whirlpool to the benefit of 863800. 863800, Outrigger, Chavila and Whirlpool all had an interest in maximizing the liability of CP and Oxford. The application was dismissed. Whirlpool appealed the decision that the appointed counsel’s representation of Whirlpool did not place him in a prohibited conflict of interest. It argued that as companies affiliated with 863800, Outrigger and Chavila had an adverse interest vis-à-vis Whirlpool in the outcome of a limitation defence argument.
The majority decision Justice Benotto, with Justice LaForme concurring, dismissed Whirlpool’s appeal. They found the appointed
counsel was not in a conflict of interest in defending Whirlpool while taking instructions from Outrigger and Chavila. Justice Benotto reviewed the law on a lawyer’s duty to avoid conflicts of interest. The bright line rule, set out in R v. Neil, 2002 SCC 70, says a lawyer may not represent a client in one matter while representing that client’s adversary in another matter. Importantly, the bright line rule only applies where the immediate interests of clients are directly adverse. If the immediate interests of the clients are not directly adverse, the applicable test is whether there is a substantial risk that the lawyer’s representation of the client would be materially and adversely affected. Justice Benotto found Whirlpool and 863800 did not have adverse interests because: 1) Given that Whirlpool would be indemnified, Whirlpool had no “direct interest in the outcome” of
either action. For this reason, it was unlikely that appointed counsel’s representation of Whirlpool would be adversely affected by the instructions from Outrigger and Chavila; and, 2) Whirlpool agreed to the terms of the indemnity agreement at the time of the sale of the land. The agreement contemplated that litigation may occur and that Whirlpool knew that issues of reputational damage and damage to its credit rating could arise. Justice Benotto found those matters could not now be raised to ground a claim of conflict of interest. Benotto found that insurance law principles supported the decision that there was no conflict of interest. Outrigger and Chavila, in defending Whirlpool, were in a similar position to liability insurers, and must exercise reasonable care and skill and pursue Whirlpool’s best interests by minimizing its liability. Benotto found it was unlikely Outrigger and Chavila would
infringe the duty of utmost good faith to minimize Whirlpool’s liability. Indeed, Whirlpool’s interests overlap with the interests of 863800, Outrigger and Chavila in maximizing the liability of CP and Oxford. Moreover, Whirlpool’s interests would not be affected because of the indemnity agreement and 863800’s undertaking not to collect any damages for which Whirlpool is found liable.
The dissent Chief Justice Strathy dissented, finding Whirlpool was entitled to separate counsel for two reasons. First, the situation was contrary to the bright line rule. The interests of Whirlpool were directly adverse to the interests of 863800. It was in Whirlpool’s interests to raise a limitation defence, and it was not in the interests of 863800. The success of the limitation defence would mean the defeat of 863800’s action. His Honour reasoned
that Whirlpool should not have to rely on 863800’s undertaking, a party with which it has not contracted, and run the risk of a judgment going against it, and then having to enforce the indemnity. Chief Justice Strathy also disagreed that the indemnity agreement meant Whirlpool had no direct interest in the result of the action. A judgment against Whirlpool could cause reputational damage or damage to its credit rating. He found that Whirlpool should be entitled to raise every viable defence it wished in order to avoid calling on the indemnity agreement. Secondly, Strathy found that under insurance law principles, Chavila and Outrigger breached their duty to defend. The indemnity agreement was akin to a promise by an insurer to defend an insured. By agreeing to provide a diligent defence, Outrigger and Chavila must conduct the defence in good faith and exercise reasonable care and skill in doing so. The companies
have a duty not to “steer” the defence in favour of the indemnifying parties. By abandoning the viable limitation defence for the benefit of 863800, Outrigger and Chavila breached their duty to defend. As a result, Chief Justice Strathy would have found Whirlpool entitled to retain separate counsel at the expense of the Respondents.
Commentary The majority and dissenting decisions differed on three important points: First, whether or not Whirlpool had a direct interest in the outcome of the actions. The majority found that because Whirlpool was to be indemnified if liability were found against it, it did not have a direct interest in the proceedings. Chief Justice Strathy disagreed, focusing on other detrimental effects a judgment might have on Whirlpool despite the indemnity agreement, such as a judgment against it potentially impacting its business
reputation or credit rating. Strathy found that there is a benefit to avoiding liability entirely, instead of relying on indemnification. Secondly, both the majority and dissent relied on insurance law principles to support their respective conclusions. Outrigger and Chavila were found to be analogous to liability insurers, and Whirlpool to an insured. In a similar position to an insurer, the majority found that Outrigger and Chavila were bound by a duty of good faith, which they were unlikely to breach given the similar interests on liability. Conversely, Strathy found the two companies had already breached their duty to Whirlpool by instructing the appointed counsel not to raise a viable defence. Finally, there was an important disagreement on the practical importance of not raising the limitation defence. Both decisions recognized that CP and
26 Claims Canada
June/July 2017
Oxford had already raised the limitation period issue. Since it had already been raised, the majority viewed the issue as more theoretical, with little practical consequence. In contrast, Chief Justice Strathy found that the refusal to instruct on, and raise, a viable defence was important, despite the fact that the defence was already raised by the CP and Oxford. The differing views expressed in the insurance law principles analysis raise the possibility that the courts may become further engaged in the conflict of interest issue when addressing the duty to defend, and the right to appoint and instruct counsel. To date, generally speaking, unless the conflict is obvious, the courts have been inclined to rely on appointed defence counsel’s ethical obligations to defend a matter in their client’s best interests as long as this is the mandate given to defence counsel by the insurer. Argu-
ably, this comports with the practical approach taken by the majority, so this tack would prevail. If the Chief Justice’s stricter but possibly theoretical concerns about reputation and credit rating were always included in the determination then it appears there would be more potential for a conflict to be suggested. The question might then become whether or not there’s a conflict as long as some interest of the insured may be affected, and the insured wants to protect it. We will have to see whether, going forward, this becomes a matter of debate when the courts deal with the issue of conflict of interest in duty to defend cases. Many thanks to Andrew W. Cottreau, a student-at-law in Hughes Amys LLP’s Toronto office, for his excellent assistance in the preparation of this article.
www.claimscanada.ca
What an insured needs to know when defending a defamation action BY KAREN R. ZIMMER
I have defended professionals who have found themselves on the wrong side of a defamation action. Often my clients had a genuine need to voice criticisms of a person or company. Other times, it was just too easy for them to publish their own piece on social media, or to endorse and hyperlink to the defamatory words of others. It usually becomes quickly apparent that the defendant had not appreciated, at the time of publishing, the likelihood they would be sued, or what would be involved in proving they fall within the protection of defences such as fair comment, truth, or qualified privilege. In the insurance context, insureds are frequently and understandably unprepared for what a defamation defence involves. This discussion hopes to flesh out common misgivings that insureds have when sued in defamation. In some cases, understanding these points can assist the insured in www.claimscanada.ca
coming to terms with the fact that the best course of action may be to remove the publication and agree to a carefully drafted, and relatively palatable, apology and retraction. In other cases, these points simply prepare the insured for the road ahead.
which the Court believes a reasonable and ordinary reader or listener would take from the statement. A defendant is often shocked to learn he or she cannot simply take the meaning intended, and justify or otherwise defend that meaning.
The meaning defended is not the meaning intended by the author A publisher rarely appreciates that the meanings and innuendoes which will need to be defended are not the meanings and innuendoes the individual intended to convey or believed were being conveyed. In a defamation suit counsel will fight over the meanings of the words published. Plaintiff’s counsel will argue that the most ghastly and horrendous meanings were conveyed, while defence counsel will seek to minimize or deny these meanings. When considering meaning, the Court will not consider what the defendant meant to say, but rather will look at the words conveyed, consider the context, and then arrive at a meaning
The limits of truth The defence of truth (formerly referred to as “justification�) can provide a full defence to a claim in defamation. To succeed, the truth of every injurious imputation that the trier of fact finds to be conveyed by the publication must be proven on a balance of probabilities to be true. Those meanings will be fought over and not determined until trial. The Court will focus on the sting of the defamatory imputations, and whether the various stings are substantially true. There are risks in pleading truth where there is no evidence to support it. The failure to successfully prove facts pled to be true in a defamation action could encourage a finding of malice, which would defeat the fair comment and qualified privilege defences. June/July 2017
Claims Canada 27
Furthermore, it could also result in aggravated and punitive damages being awarded to the plaintiff. These types of damages are rarely covered in the insurance context, so insureds are well warned to keep this in mind.
"Fair comment” is not as easy as it sounds Often, my defendants say that what was said was “fair comment”; however, they do so without appreciating what is involved to successfully rely on this legal defence. To defend a statement as fair comment, an insured must meet the following stringent requirements: the comment must be on a matter of public interest; it must be a comment based on provable facts that are either stated with the publication or are otherwise known to the reader (such as being notorious); the comment, though it can include inferences of fact, must be recognizable as comment, as opposed to a statement of fact; the comment must satisfy the following objective test: could any man honestly express that opinion on the proven facts; and, the defendant must not have acted with malice.i Hence, the defamatory words must be recognizable to the ordinary reader as comment upon true facts, and not a bare declaration of facts. A comment contains an element of subjectivity and is capable of proof, whereas a statement of fact is capable of being determined to be accurate or not. An inference or deduction from facts may properly be regarded as comment, but an implication is regarded as a statement of facts.ii The difficulty is that the point at which criticism ends and accusation begins is not always easy to distinguish, and the line between them can be, and frequently is, very tenuous.iii In most cases where the defence of fair comment is successful, the facts on which the comment is based are clearly stated in the publication, and the opinion is expressed in a way that makes it clear that the opinion is an inference or a deduction based on the stated facts. Limitations of qualified privilege As noted above, there is often a real need to share a concern. There are certain occasions in which a person 28 Claims Canada
June/July 2017
can publish, in good faith, defamatory statements which turn out to be potentially untrue. Such an occasion of qualified privilege arises where: (i) persons of ordinary intelligence and moral principle would have felt a duty to communicate the information in the circumstances; and (ii) the information was conveyed only to the recipients who had an interest in receiving it. This reciprocity of interest is essential. A beautiful characteristic of this defence is that it protects all kinds of personalities. The Court is required to take defendants as it finds them, “according to their temperament, their training, their intelligence”. If an occasion of qualified privilege arises “he will be protected, even though his language should be violent or excessively strong, if, having regards to all the circumstances of the case, [h]e might have honestly and on reasonable grounds believed that what [h]e wrote or said was true”.iv This defence does not mix well with the Internet. When publishing on a website, the defendant is publishing to the world.v It does not matter if they believe the website on which they publish would only attract readers who would have an interest in the matter. Unless they are publishing to a website which requires the user to log in, and those members able to log in have an interest in the matter, serious challenges will arise in meeting the reciprocal interest element of this defence. A finding of malice defeats the qualified privilege defence and the fair comment defence. A Plaintiff can rely upon any conduct of the defendant leading up to the conclusion of trial in attempt to prove that the defendant was motivated by malice when publishing.
When it does not matter that the words were not your own The Internet opens up a whole new area of potential liability, namely the potential for Facebook and other social media users, website operators and Internet service providers to be liable for postings made by third parties on their site. One can be liable for defamatory statements posted by third parties if one knew or ought to have known of the defamatory publication and failed to remove it.vi While the simple act of hyperlink-
ing to a website that contains defamatory material is insufficient for liability to arise for any defamatory publication at the hyperlink, liability will arise if the hyperlinking is done in a way that includes an adoption or endorsement of the defamatory content of the hyperlink.vii When defending the defamatory words of others, the same challenges discussed above can arise when seeking the protection of truth, fair comment, and qualified privilege defences.
Conclusion An insured should have his or her eyes wide open to the above potential challenges in defending a defamation claim. Early on, counsel should take risk management steps, including ensuring there are no other defamatory publications out there to be discovered, and that the insured appreciates that his or her future conduct could be used in furtherance of the Plaintiff’s efforts to establish malice. This article has focused on technical defamation points which can work against the defence. Fortunately, there are various technical defamation points to be discussed another day, which can be used against a Plaintiff to dismiss or deter action. Simpson v. Mair, 2008 SCC 40 Kemsley v. Foot, [1952] AC 345 (H.L.) iii Boland v. The Globe and Mail Ltd., [1961] 21 D.L.R. (2d) 401 (Ont. C.A.) iv Harrocks v. Lowe, [1974] 1 All E.R. 157 (H.L.) v See for example Rubin v. Ross, 2013 SKCA 21 vi Weaver v. Corcoran, 2015 BCSC 165; Pritchard v. Van Nes, 2016 BCSC 686 vii Crookes v. Newton, 2011 SCC 47 i
ii
Karen Zimmer is partner at Alexander Holburn Beaudin + Lang LLP, a Vancouver-based law firm. She is the leader of the firm’s Defamation + Publication Risk Management Practice Group. Her libel and slander practice involves defending media, regulatory bodies, health authorities and professionals, school boards, colleges and universities, municipalities, non-profit associations, and other professionals. www.claimscanada.ca
To Admit or Not to Admit
Expert evidence on trial This year marks a decade since the release of the Report on Civil Justice Reform Project by the Honourable Mr. Justice Osborne. This article reviews the jurisprudence dealing with the proliferation of experts and expert bias to examine whether the Osborne Report’s objective of early dispute resolution and reducing use of judicial resources has been advanced. In 2015, in the case of the White v Burgess,1 the Supreme Court of Canada affirmed the previously established test for admitting expert evidence, which requires two steps: (1) meeting the Mohan factors, and (2) the court’s gatekeeping role.2 The Supreme Court noted the “unmistakable trend of the jurisprudence…has been to tighten the admissibility requirements and to enhance the judge’s gatekeeping role”. Unfortunately, this trend has not been demonstrated in the subsequent jurisprudence and instead the issue of bias continues to be dealt with at trial, with some exceptions. Two recent lower court decisions, Giordano3 and Bruff-Murphy4, dealt with the issue of bias in the context of a threshold motion and both addressed the concern through the weighting of evidence rather than admissibility of the evidence. In Bruff-Murphy, the court addressed admissibility of a defence expert who had been found biased in several prior cases. The court determined, despite concerns with the expert’s report, that the evidence should be proffered. At the threshold motion, Mr. Justice Kane raised significant concerns about the expert’s impartiality. The expert doctor testified he saw his role as determining whether the plaintiff’s description of their condition was accurate by looking for inconsistencies. Justice Kane commented that the doctor: • failed to put to the person the inconsistencies; • would not allow any audio recording of the assessment; • in addressing credibility of the party, the doctor went outside his terms of engagement; • conducted no testing nor requested treating doctors test results; • made comments out of context; • had a good memory for the points he was defending but not on other points. Justice Kane was clear that in future cases he would not qualify witnesses as experts whose reports present an approach similar to what was seen in that case. The case highlights the high threshold to have an expert disqualified. The same expert was the subject of another motion, in Daggit v Campbell,5 where defence sought an Order to appoint this doctor to do an Independent Medical Examination (“IME”). Madame Justice MacLeod-Beliveau commented in obiter that www.claimscanada.ca
BY DEBBIE ORTH
an extension of the court’s right to name a doctor for an IME is the discretion not to name a particular health practitioner if he/ she is found to be biased, which would be uncommon. These recent cases show clear judicial direction that this level of bias will not be tolerated and will be excluded at trial reinforcing that the “hired gun” methodology of choosing an expert is likely an unsuccessful strategy. However, leaving the determination of bias until the trial, or even after trial does nothing to address the objective to cut down the time and costs spent getting to trial. A slow shift in addressing these concerns earlier in the process has been seen through parties imposing terms on court ordered assessments. Although, this movement could have its benefits, little is to be gained where the opposing counsel unilaterally imposes restrictive terms not required by the Rules. The terms often incorporate uncontroversial requirements such as providing the expert’s CV, content in the report, form to be completed, an index of the documents or payment of reasonable expenses. Production of the doctor’s notes and recording the assessment are often requested and can, at times, be contested. However, parties often request much more invasive terms. Lavecchia v. McGinn6 dealt with an IME motion where the plaintiff requested that defence agree to the following additional terms: a) plaintiff was not to be asked to complete any documents such as questionnaires at the examination; b) doctor was not to express any opinions dealing directly or indirectly with liability; c) doctor was not to express any opinion on the credibility, character or truthfulness of the plaintiff; d) health records and information of the plaintiff were not to be June/July 2017
Claims Canada 29
disclosed to any other person or entity other than defence counsel. The court opined that term (a) has to be decided case by case, given that some disciplines utilize standard diagnostic tools and tests, which would be appropriate. The plaintiff conceded that terms (b) and (c) were too broad and as such were not ordered. It was recognized that determining issues of credibility are properly the adjudicator’s role. Term (d) is of particular interest; it was an indirect way to prevent a “ghost written” report. The parties agreed that the expert report must be written by the expert herself/himself and not by administrative staff or other individuals. The court commented on the need for greater rigour and predictability concerning the role and use of experts so as to save time at trial and promote settlements; it noted the cases of El-Khodr v. Lackie and Elbakhiet v. Palmer which raised concerns at trial about ghost writing and an expert opining on credibility. Master Macleod, in Lavecchia, supra, stated: I do not, however, accept that the best approach is to be found in plaintiffs seeking to unilaterally impose restrictive terms on the conduct of defence medicals. Nor is it reasonable to have actions grind to a halt while the parties attempt to negotiate terms of a consent order as has happened here. A standard form of order may well be a very good idea.
The 2017 case of Kushnir v. Macari7 addressed the issue of terms relating to ghost writing. The plaintiff sought an Order, inter alia, that the expert report be drafted solely and entirely by the assessing doctor, the research and medical record review be done by the assessing doctor and the records not be shared with any third parties. Defence argued that this was an attack on the integrity of the assessor and that the assessor takes responsibility for the report in signing it. Plaintiff argued that these terms were needed to ensure trial fairness. No specific wrongdoing was alleged against the proposed assessor. Citing the facts of El-Khodr, where the expert testified at trial that part of the report was written by somebody else, the court acknowledged the problem of ghost writing. The court was prepared to address same but found the conditions sought were overreaching and suggestive of inappropriate behaviour by the assessor. The Order encompassed a term that the report shall be written solely by its author and health records should not be disclosed to anyone other than defence counsel. The decision was not appealed. Unfortunately, in the broader context there is little progress in terms of achieving the long-term goals of early dispute resolution in order to reduce costs and conserve judicial resources. In the past two to three years, there is clear judicial commentary suggesting a slow shift towards addressing the issue of admissibility and the treatment of bias at an earlier stage of the action in the specific context of court ordered IMEs. At this juncture, this issue often entails the same amount of judicial and legal resources to address the terms and conditions requested by parties. Further, this also fails to have broader implication outside of the medical expert’s field. It is yet to be seen whether courts will provide clear guidance that can result in a standard form terms and conditions for IMEs, which would at least have the effect of leveling the playing field such that experts on both sides of the dispute would be subject to the same terms. Suffice it to say the courts have clearly indicated they will take a position on admissibility of experts in those extreme cases where it is warranted. Accordingly, it is incumbent upon the parties on both sides of the dispute to do their due diligence in advance of selecting an expert to ensure that expert will uphold their duty to the court. 2015 SCC 23 (CanLII), <http://canlii.ca/t/ghd4f>. In R v Abbey, 2016 ONSC 7 (CanLII), http://canlii.ca/t/gmr5x, the Court of Appeal introduced a two step inquiry to admit evidence. 3 2014 ONSC 7516 (CanLII), <http://canlii.ca/t/gg2d0>. 4 2016 ONSC 7 (CanLII), <http://canlii.ca/t/gmr5x>. 5 2016 ONSC 2742 (CanLII), <http://canlii.ca/t/gpqm3>. 6 2016 ONSC 2193 (CanLII), <http://canlii.ca/t/gp6zq>. 7 2017 ONSC 307 (CanLII), <http://canlii.ca/t/gx9g6>. 1 2
Debbie Orth is a partner at Bertschi Orth Solicitors and Barristers LLP and a member of the Board of Canadian Defence Lawyers. She practices in Insurance Defence and Commercial Defence focusing on accident benefits, personal injury coverage, educational malfeasance and property and casualty.
30 Claims Canada
June/July 2017
www.claimscanada.
• on the scene OTS Origin and Cause opened its Edmonton branch a year ago, in response to the high frequency of investigations they were conducting in the region. The company has now hired two new forensic experts – Allen Bauer and Mark Mason – to ensure the highest standard of technical excellence and customer service for their cliAllan Bauer ents in the region. “The insurance and legal community in Edmonton have been extremely supportive and welcoming to Origin and Cause since we opened our doors last year. The feedback we receive daily from our clients is incredible, and really makes me proud,” said Mazen Habash, president of Origin and Cause. Allen is a fire and explosion investigator with Mark Mason over 13 years of professional experience in fire suppression. He is a captain-qualified fire investigator with the City of Edmonton Fire Rescue Services Investigations Branch and has performed over 150 investigations. He is currently a member of the NAFI, FIAA and IAFF. Mark has worked for the provincial downstream hydrocarbon regulator in Ontario for approximately 14 years. In that time he has led, and assisted in, over 100 explosion and fire investigations. Mark has extensive experience in hydrocarbon appliance operation and failure mechanisms, and expert knowledge of all Canadian codes and regulations with respect to hydrocarbon fuels. Mark has CFEI, G1, LP, PM2 certifications and over 22 years’ experience in the hydrocarbon fuels industry. ●
Gillian Van Kempen has taken on the role of president of Best Buy Insurance. Gillian is the 4th generation of the Van Kempen family to join the insurance broker side of the business. The family’s roots date back over 70 years to 1946 when Gillian’s great-grandfather founded his insurance brokerGillian Van Kempen age in Toronto. Gillian received her honours Bachelor of Arts degree from the University of Toronto and went on to attain her CAIB, CIP, FCIP and CRM designations. She has served as president of the Insurance Brokers Association of Ontario’s Durham affiliate and continues to sit on numerous insurance industry boards, company broker councils. Gillian has been a licensed broker for 20 years and has worked in virtually every channel of the insurance industry. Best Buy Insurance is very pleased to benefit from her expertise in this new role. She succeeds her father, Kip Van Kempen. ● www.claimscanada.ca
30 Forensic Engineering, has appointed Jiwan Thapar, PEng, MEng, PSP, PMP, as practice lead within the Construction Services Group. Jiwan brings over 10 years of experience in consulting, engineering and construction management. He gained extensive experience in preparing and evaluating construction claims (delay, lost productivity and acceleration). He Jwan Thapar has represented both owners (public and private) and contractors for commercial matters ranging in value from $10 million to over $250 million. “I am happy to welcome Jiwan to the Construction Services Group as our new practice lead. On top of the great work experience and education, he is an incredible, dynamic individual that will be a fantastic fit for the organization,” said Doris Marshall, principal, construction claims of 30 Forensic Engineering. ●
Calvin Newman (left), chair of the CMH Foundation and president of Newman, Oliver & McCarten Insurance Brokers Ltd., receives $10,000 donation from Economical Insurance for new portable x-ray machine. Presenting the cheque from Economical is Jason McDowell, business development specialist. The 37-year-old portable x-ray machine used for bed-ridden patients in the Campbellford Memorial Hospital (CMH) will be replaced thanks to a $10,000 donation from Economical Insurance. This is the fourth $10,000 donation that Economical has made to the CMH Foundation in recent years for new medical equipment. The new portable x-ray machine for the Diagnostic Imaging Area of CMH will allow for faster treatment decisions for bed-ridden patients. “Diagnostic Imaging is one of the most important areas in the hospital,” said John Russell, executive director of the CMH Foundation. “The current x-ray machine has served the hospital well, but it’s seeing the end of its days here at CMH. With Economical Insurance’s generous support, we are now able to continue offering modernized care to our patients.” “We are proud to give back to CMH in association with Newman, Oliver & McCarten,” said Tom Reikman, SVP and chief distribution officer at Economical Insurance. “Newman, Oliver & McCarten has been our trusted broker partner in serving the needs of the community for nearly 120 years.” ● continued on page 32... June/July 2017
Claims Canada 31
• on the scene OTS
...continued from page 31
Sedgwick, and its subsidiary Vericlaim, announced the appointment of Lee Powell to vice president of the complex loss division of Vericlaim Canada. “His appointment is part of our focus on expanding our geographic coverage and commitment to building our business across Canada. The experience and expertise that Lee brings to Vericlaim will be a major asLee Powell set,” said Mike Holden, president of Sedgwick and Vericlaim Canada. Lee brings some 20 years of industry experience to Vericlaim Canada. Specialties include construction, petrochemical and oil and gas, equipment breakdown, commercial property, boiler and machinery, and product liability. He is a member of CIIA, and earned the CRM from the Global Risk Management Institute and holds the Chartered Insurance Professional designation. ● WINMAR International Inc opened a new location in Estevan, Saskatchewan, located at 238 3rd Street. With 22 years in the construction business, owner Kyle Jacques has been a longtime WINMAR family member, successfully operating WINMAR Moose Jaw for the past seven years and WINMAR Regina for five years. Kyle’s success has come from his commitment to providing outstanding customer service and quality workmanship. He and his team will strengthen the WINMAR organization but also its commitment to its insurance partners, the company said. ●
CIAA New Members — May 2017 CORPORATE MEMBERSHIP
Sage Claims Solutions Inc.
Hamilton, ON
INDIVIDUAL MEMBERSHIP
Claims Pro Deborah Brick Nikhil Joshi
Oakville, ON Oakville, ON
Level 1 Level 1
Cunningham Lindsey Stacie Karpenko
Winnipeg, MB
Level 1
Kernaghan Adjusters Ltd. Cindy Lambright Surrey, BC Level 1 Sage Claims Solutions Inc. Christine Andrews, CIP, FCIP, CRM Hamilton, ON
Level 3
Sedgwick CMS Canada Inc. Fred Duz, CIP Mississauga, ON Pierre-Marc Laurin Mississauga, ON Josie McKinnon, CIP Mississauga, ON
Level 3 Level 1 Level 3
T & L Adjusters Ltd. Marcus Ergezinger
Edmonton, AB
Level 1
Vericlaim Shauna Dobson, CIP Leslie Telch, CIP
Edmonton, AB Mississauga, ON
Level 3 Level 2
32 Claims Canada
June/July 2017
Sedgwick and Vericlaim also appointed Mike Alwyn as senior vice president of specialty services for Vericlaim Canada. “We have no doubt that Mike’s experience and expertise will be a strong asset to the organization,” said Mike Holden, president of Sedgwick and Vericlaim Canada. Mike brings 30 years of experience in claims adjusting with specialties in Mike Alwyn mining, commercial property, course of construction, and jeweler’s block/fine arts. Not only is he one of our industry’s most well-known Executive General Adjusters (EGA), but he also has an MBA and holds the Fellow Charted Insurance Professional (FCIP) designation. In addition, he is a recipient of the Canadian Insurance Claims Managers Association Award. Aside from the insurance industry, Mike was a member of the Canadian Forces Air Reserve, serving over 20 years, attaining the rank of Captain, and was awarded the Canadian Forces Decoration. ● Sharp Mobile Technology Ltd won the inaugural IBAA Hackathon on May 9th. The hackathon gave teams 24 hours to create a new technology that would help advance the broker channel. Sharp Mobile, an independent insurance technology company beat out stiff competition, including Intact Insurance, for their interactive broker chat called BRIE. BRIE (Broker Resource Information Engine), is an intelligent chat robot that can answer a diverse range of insurance questions that draw from various insurer underwriting manuals. Some of the questions used in the live demo at the Hackathon include: How much a client will pay in cancellation fees, information about a specific insurance company’s motorcycle policy, as well as requesting BRIE to text a pink card to a client. “As an insurance broker I was very excited to see what Sharp had submitted at the IBAA Hackathon. A lot of the pain points in document management, information lookup and market research seemed to disappear thanks to an AI chat bot named BRIE – the most amazing part being that she was developed in a mere 24 hours,” said Scott Romans from Ing+Mckee Insurance. ● Kernaghan Adjusters has added a branch in Barrie, Ontario, and hired Eric Gunnell as senior adjuster in the Barrie/ Newmarket region. He brings over 35 years of experience in the insurance claims industry. During his career, he has held various positions from assistant claims manager to independent adjuster. He is a well-respected, large-loss commercial adjuster with expertise in transportation, property, liability and catastrophe claims. Eric Gunnell Eric has worked in the UK, Australia and Canada. “The experience Eric has gained both internationally and locally has given him a unique perspective and understanding of all facets of the claims business,” said Dennis Schembri, VP Ontario Operations. ● www.claimscanada.ca
• on the scene OTS Sedgwick and Vericlaim have opened an office for Vericlaim in Montreal. Industry experts Denis L’Ecuyer and Pierre-Marc Laurin have joined the team as casualty claims examiners. Denis brings 45 years of experience in all lines of claims business to his new role. He specializes in liability, property Denis L’Ecuyer damage, commercial, industrial and institutional claims, as well as products liability and some liability bodily injury claims. Prior to joining Sedgwick and Vericlaim, Denis held management positions with major insurance organizations in Quebec. Denis speaks French and English. He has taken multiple AIAC courses from the Insurance Institute of Pierre-Marc Laurin Quebec and holds a general adjuster’s license in New Brunswick (all categories). PierreMarc has nearly a decade of experience in all types of commercial and personal losses, with a specialization in liability cases. He has handled claims across the region of Quebec for major accounts. Pierre-Marc joined Sedgwick in November 2016 as a resident examiner for Quebec. He has completed his collegial studies with the Vieux-Montreal CEGEP and is pursuing the CIP designation with the Insurance Institute of Canada. Pierre-Marc is bilingual in French and English and is a fully licensed adjuster for Quebec. ●
continued on page 34 ...
ClaimsPro has appointed Drew Knox to lead its Transportation, Equipment & Cargo division, a highly-specialized division of the company that offers claims services specific to the TEC sector as it pertains to collision, cargo, and liability insurance. ClaimsPro provides TEC services throughout North America. The TEC division is part of ClaimsPro’s Specialty Risk Division (SRD), led by Sean Drew Knox Forgie, Senior Vice President, SRD. Drew has 30 years’ experience in the insurance industry and extensive background in large commercial property loss as well as cargo losses of all types, both as an insurer and an independent adjuster. His previous experience includes time as a Staff Field Adjuster and Claims Manager with a large insurer. He is a member of the Insurance Institute of Manitoba and the Canadian Association of Fire Investigators. He is based in Winnipeg. ● Accident Support Services International Ltd (ASSI), facilitators of Collision Reporting to the Insurance Industry, announced that the Oakville, Ontario location of the Halton Collision Reporting Centre (CRC) has moved from Bronte Road to 95 Oak Walk Drive, Oakville. Accident Support Services International Ltd operates three Collision Reporting Centres in partnership with the Halton Regional Police Service. ●
With flooding caused by persistent rains having recently escalated into a state of emergency in areas of Quebec and Ontario, The Guarantee Company of North America (The Guarantee) responded with support to the Canadian Red Cross. The Guarantee has donated $10,000 to the Canadian Red Cross Spring Floods Appeal to assist individuals, families and communities affected by the flooding. “The Guarantee is pleased to support the Canadian Red Cross in their efforts to assist Canadians affected by the current state of emergency,” said Richard Pouliot, national VP, operations and distribution management. “We know that unforeseen events can be devastating and we hope our $10,000 donation will assist the Red Cross in supporting those in need who have been impacted by the catastrophic flooding.” ● www.claimscanada.ca
June/July 2017
Claims Canada 33
• on the scene OTS
...continued from page 33
The Centre for Study of Insurance Operations (CSIO) has made enhancements to its eDocs Availability Chart. This reference tool, originally launched in October 2016, shows which types of documents insurance companies send as eDocs for personal lines, commercial lines and farm policies. The improvements include a revised design for better user experience as well as additional information noting which insurers provide the Insured Copy as eDocs. Currently, eight insurers send the Insured Copy: Intact InsurSCM Insurance Services has made its initial entry into the US by acquiring Nixon & Company, Inc. Nixon & Company, Inc was founded more than 40 years ago and remains headquartered in St Louis, Missouri. It provides a new platform from which SCM will continue to build out its service offerings both domestically and into the Lloyd’s of London marketplace. SCM announced its intention to expand into the United States with the hiring of Scott Goodreau in the fall of 2016 as the company’s chief operating officer – USA. Scott, an executive with 20 years’ experience in the industry, has held diverse leadership positions for distribution, carrier, and technology companies. “This is a strong opportunity, not only for us as organizations, but for our clients,” he said. “SCM studied the US market closely before deciding that this was both the right time, and Nixon the right company, to begin our expansion into the United States.” ●
34 Claims Canada
June/July 2017
ance; L’Unique General Insurance; Norfolk Mutual Insurance Company; Optimum General Inc; Peace Hills Insurance; SGI CANADA; Trillium Mutual Insurance Company; and West Wawanosh Mutual Insurance Company. “We are quite pleased to increase the value of the eDocs Availability Chart through these enhancements,” said Catherine Smola, president and CEO, CSIO. “These improvements to the chart were made in direct response to enhancement suggestions we received from our members. ● The devastating losses in Kelowna, Slave Lake and Fort McMurray have led to a deeper understanding of the Wildfire Urban Interface Fire Risk in Canada. Fire Underwriters Survey (FUS), a division of Opta Information Intelligence, has developed a new model for insurers to better understand the risk of wildfire-related losses. A new Canadian Wildfire Grading Index will be released in British Columbia and Alberta in mid-2017, with a full rollout nationwide by year’s end. The system provides standardized risk benchmarks for all areas of Canada using GIS, geodatabases, weather databases, historical data, digital satellite imagery and advanced analytics tools. “This is another example of the Fire Underwriters Survey and Opta providing crucial fire protection data for Canadians,” says Greg McCutcheon, President of Opta. “We take great pride in helping insurers and all Canadians prepare and combat fire risk exposure.” ●
www.claimscanada.ca
• on the scene OTS Ribald humour and not-so-gentle ribbing were the order of the day at the 58th Quarter Century Club Luncheon and Roast of Tim Guernsey, RSA Canada’s VP of claims. Held annually to honour a claims industry veteran, the May 24th roast at Toronto’s distinguished Albany Club treated more than 170 guests to loads of laugh-out-loud jokes and jibes from master of ceremonies John Cherrie and roasters Dennis Schembri of Kernaghan Adjusters, Walter Aronovitch of AMR Barristers and Solicitors LLP, Murray Ritch of Ritch Williams Richards Lawyers, and Eric Grossman of Zarek Taylor Grossman Hanrahan LLP. ●
www.claimscanada.ca
June/July 2017
Claims Canada 35
• on the scene OTS What happens in the courtroom of a liability trial — and how can adjusters prepare? Attendees of the CIAA/CICMA Western Education Conference in Edmonton on April 25 had a chance to find out through a mock trial contested by legal teams from CBM Lawyers and Dean Duckett Carlson LLP. The trial featured the presentation of surveillance and Facebook evidence, and testimony from expert witnesses and an adjuster. A tradeshow, seminar on social media and an IBC presentation of claims-management lessons from the Fort McMurray fire rounded out the day’s events. ●
Transitioning from daytime to evening wear was unnecessary for any horse racing fans who attended the 23rd Annual Starlight Insurance Gala on May 6, because the event’s Run for the Roses theme was inspired by the day’s other big event: the 143rd running of the Kentucky Derby. The evening’s festivities, which included raffles and a silent auction, were in aid of the Starlight Children’s Foundation Canada, a charity “dedicated to bringing laughter, joy and hope back into the lives of children with serious illnesses.” Local TV newscaster Anwar Knight hosted the fete at Toronto’s Royal York Hotel. ●
HAVE A TION RESTORA ? N QUESTIO ent? Not a cli lem! No prob t! - no cos Email us tgeneral.ca s@firs question
First General
There when you need us most. 36 Claims Canada
June/July 2017
www.claimscanada.ca
• on the scene OTS Sub-par weather didn’t stop competitors from bringing their Agame or their winning attitudes to the CIP Society Fellows’ Golf Tournament on June 5. DiamondBack Golf Club in Richmond Hill, Ontario hosted this year’s edition of the annual event. With their team score of seven-under, Ray Arndt of Lyon & Butler Insurance Brokers, Jeff Skelton of Roughley Insurance Brokers, Rick Moore of Adriatic Insurance Brokers and Nazir Haji of AEGIS London took home the tournament’s big prize. ●
CHOOSE FROM CANADA’S TOP MEDIATORS AND ARBITRATORS
Marvin J. Huberman C.S., LL.M. ( ADR), C.ARB
Marvin’s experience encompasses expertise in risk management, insurance disputes, coverage issues, exclusion clauses, interpretation of policies, professional liability, corporate/commercial, administrative and public law. Let his trail of success in mediations and arbitrations work for you. Awarded The Lawyer International Global Award - 2017 - Law Firm of the Year – Commercial Arbitration – Canada. 1.800.856.5154 www.claimscanada.ca
adrchambers.com June/July 2017
Claims Canada 37
• on the scene OTS Banff is always a great place to be, but never more so than when the Annual Convention of the Insurance Brokers Association of Alberta is in town. Held May 7-10 at the Banff Springs hotel, the conference brought together more than 500 brokers and other insurance professionals for a golf tournament and tradeshow, the President’s Gala dinner and an educational program featuring such subject-matter experts as BMO Financial Group chief economist Doug Porter, Google Canada marketing chief Fab Dolan, and Blair Feltmate of the Intact Centre on Climate Adaptation. ●
38 Claims Canada
June/July 2017
www.claimscanada.ca
ARC G network eac
ARC Group Canada is a national network of independent law firms, each intimately connected to their local market.
Insura
Insurance and risk management Your customer has experts. a list of the vehicles that Regional strength. are covered by your fleet policy.National You have scope. a list of the vehicles that are covered by that policy. That is the ARC Group.
And your lists aren’t the same.
Go to AskARC.com
When the one vehicle that is involved in an accident is the one that doesn’t appear on both lists, do you know what happens next?
ARC does.
ARC Group Canada is a national network of independent law firms, each intimately connected to their local market. Insurance and risk management experts. Regional strength. National scope. Go to AskARC.com
The ARC Legal R Winter Issue – Ar A National Network of Independent Law Firms
When is a medical examination considered a second exam under Rule 36 of the New Brunswick Rules of Court?
The ARC Legal Reporter Blyth v. Crowther and Kelly Reported Case: 2009 NBCA 80 Citation: Winter IssueAt–Issue: Article #1When both the plaintiff’s physical and mental condition are in issue
the plaintiff undergoes a physical examination, will a subsequen psychiatric examination be considered an application for a examination?
Canada’s leading provider of pre and post-loss appraisal and consultation services. SPECS provides the insurance industry with expert, impartial, and comprehensive structural consultation. Our customers benefit from precise valuation of damages, accurate reserves, a reduction in claim cycle times and enhanced claimant satisfaction. Trust SPECS to assist with any residential, commercial, industrial or CAT claim.
SERVICES • PROPERTY LOSS SCOPE AND ESTIMATING • BID ANALYSIS AND MANAGEMENT • PROJECT MANAGEMENT AND CONSULTING DIVISIONS • TECHNICAL SERVICES • CONTENTS APPRAISAL • STORM AND CATASTROPHE BENEFITS • REDUCED CLAIM AND PROJECT TIMELINES • EFFECTIVE EXPENSE AND COST CONTROL • PRECISE VALUATION OF DAMAGES
2017 © All rights reserved. Specialized Property Evaluation Control Services Limited
specs.ca 888-737-7327