Don’t Stop Believing
By Marshall Thomas, President of F&W Forestry Services, Inc.
Timber prices are stable to declining— again—but there’s some good news. Our managers report conditions are normal to declining, landowner sentiment is “cautious,” and the outlook is “guardedly positive,” with some markets showing signs of recovery late in 2026. Things have been so bad for so long it’s hard to believe a positive outlook—I sure hope they’re right! See our Market Pulse on page 3.
Second-quarter lumber prices showed encouraging strength. The Random Lengths Framing Lumber Composite Price and Southern Pine Composite Price are both near their highest levels since 2022/23. Rising lumber prices are encouraging because stumpage usually follows (page 14).
The bad news: Random Lengths’ OSB Composite Prices have stagnated at low levels—more bad news for small, pulpwood-sized tree markets.
A recent ArborGen report tells the story from a different angle: U.S. tree seedling sales are down as landowners reforest fewer acres at lower planting densities, while sales of eucalyptus and pine seedlings in Brazil are way up. People plant trees based on where they expect markets to be when those trees are ready for harvest (page 5).
On the mass timber front, the new Assembly Studios Bandshell in Atlanta is described as North America’s first large-scale asymptotic timber gridshell (see page 5 to find out what that is). It’s one of several such projects; market impact remains small, but the trend is real and positive.
The EU’s Deforestation Regulation (EUDR) is set to take effect at the end of the year. The EU says it’s about
keeping deforestation-linked wood out of Europe; many of us see it as dictating how we manage our forests. In the U.S., it will add supply-chain costs without meaningful environmental benefits.
One new wrinkle could cut either way: planted forests that will ultimately resemble natural stands are now exempt from “degradation” status. That’s good news for the many Southern plantations managed toward a natural-stand outcome (prescribed fire and thinning)—but one question remains: once “natural,” can we still clearcut and start over?
Historically, wet winters pushed timber prices higher because many tracts became inaccessible, creating shortages. Today, we’re growing more wood than we harvest, so that relationship isn’t nearly as strong. Even so, areas with strong demand and unusually wet conditions could see localized price increases if NOAA’s forecast for a very strong El Niño proves accurate (page 8).
That’s it for market news—on to legislative news.
The Farm Bill moved a step closer to reauthorization: the House passed its version and sent it to the Senate. That’s good news, except an amendment particularly favorable to tree farmers narrowly failed. The amendment would have allowed fuels made from commercially grown trees to receive Renewable Identification Numbers (RINs), creating the same incentive that has helped corn ethanol compete. Sustainable Aviation Fuel remains a promising market for low-value timber, making this issue important to forest landowners (page 5).
Other legislative notes: the Emergency Conservation Program Improvement Act would provide advance (continued on page 11)
Sweeping Reorganization Moves Forest Service West
The U.S. Forest Service is embarking on one of the most significant reorganizations in its 120-year history, relocating its national headquarters from Washington, D.C., to Salt Lake City, Utah, while restructuring the agency’s management and research operations.
Announced by the U.S. Department of Agriculture (USDA) on March 31, the overhaul is intended to move agency leadership closer to the forests and communities it serves. USDA officials said nearly 90 percent of National Forest System lands are located west of the Mississippi River, noting that Salt Lake City is a more
logical base for agency leadership.
Under the reorganization, approximately 260 Forest Service positions currently based in Washington will relocate to Utah, while about 130 employees will remain in the capital. The transition is expected to be completed by summer 2027.
Forest Service Chief Tom Schultz described the move as part of a broader effort to better position the agency to address growing forest health challenges. According to Schultz, nearly two-thirds of the National Forest System—roughly 120 million acres—is at risk from wildfire, insects, or disease.
research with priorities such as active forest management, wildfire mitigation, recreation, and natural resource development.
For further information on material in this report or to discuss your forestry needs, contact the nearest F&W office or the Albany headquarters at:
PO Box 3610, Albany, GA 31706-3610
229.883.0505 / fax 229.883.0515 www.fwforestry.com
Marshall Thomas, President Jeff Jordan, Chief Operating Officer
Jody Strickland, Chief Business Officer
Sonya Farmer, Chief Financial Officer
Stephen Logan, Chief Information Officer
Brent Williamson, Forest Operations
Regional Market Conditions Contributors:
Southeast: T.R. Clark (LaFayette, AL), Bryan Croft (Orange Park, FL), Elvis Cook (Marianna, FL), Doug Hall (Albany, GA), Chad Hancock (Albany, GA), Robby Gordon (Macon/Eatonton, GA), Wade McDonald (Statesboro, GA), Matthew Malone (Fountains Inn, SC)
West Gulf: Eric Sumner (El Dorado, AR), Jason Potts (Corinth, MS), Chuck Beck (Antlers, OK), Chris Bartley (Huntsville, TX)
Central Hardwoods: Rick Sluss (Clinton, TN)
Mid Atlantic: Glen Worrell (Charlottesville, VA)
Northeast: Harold Burnett (Winthrop, ME), Charlie Stabolepszy (Montpelier, VT), Tom Gilman (Tupper Lake, NY), Lukas Myers (Herkimer, NY), John Helmers (New Oxford, PA)
Inland Northwest: Garrett Kleiner (Sandpoint, ID)
Northern California: John Vona (Redding, CA)
The F&W Forestry Report is produced by: Bates Associates
770.451.0370
batespr@bellsouth.net
©2026 F&W Forestry Services, Inc.
“This is about building a Forest Service that is nimble, efficient, effective, and closer to the forests and communities it serves,” Schultz said. “Effective stewardship and active management are achieved on the ground, where forests and communities are found—not just behind a desk in the capital.”
In addition to relocating the headquarters, the Forest Service is dismantling its traditional nineregion structure and replacing it with a new state-based organizational model. Fifteen state director offices, mostly located in the Western U.S., will oversee operations across one or more states, supported by regional service centers located in Albuquerque, N.M.; Athens, Ga.; Fort Collins, Colo.; Madison, Wis.; Missoula, Mont.; and Placerville, Calif. The USDA announcement said additional service center locations may be added as the transition progresses.
The Forest Service’s research enterprise will also be consolidated under a single leadership structure based in Fort Collins. As part of that effort, 57 of 77 research stations in 31 states will close or be consolidated. Agency leaders say the change will reduce duplication and better align
The announcement has generated mixed reactions. Supporters argue that moving leadership closer to the forests it manages will improve responsiveness, streamline decisionmaking, and strengthen collaboration with state forestry agencies. Critics, however, have expressed concerns about the potential loss of institutional expertise, the consolidation of research facilities, and the possibility that state interests could exert greater influence over federal land management decisions.
For private landowners and the forest products sector, the agency has emphasized that the reorganization is intended to improve active forest management and strengthen partnerships with states and stakeholders. Agriculture Secretary Brooke Rollins specifically cited the importance of supporting timber production and improving forest management practices that enhance forest health while increasing the availability of domestic wood supplies.
USDA officials maintain that wildfire response capabilities and frontline forest management activities will continue uninterrupted throughout the transition. The agency has also stated that no changes will be made to field-based firefighting operations as the reorganization is implemented over the next year.
The reorganization follows broader efforts by the Trump Administration to decentralize federal land management agencies and place leadership closer to the lands they oversee. Whether the restructuring ultimately delivers on promises of improved efficiency and forest stewardship will likely become clearer as the transition unfolds over the next several years.
Regional Timber Market Conditions
FOREST WATCH: REGIONAL OVERVIEW
Second Quarter 2026
F&W Forestry’s second installment of its regional timber market commentary finds conditions across the U.S. defined by contrasts: pulpwood continues to absorb the brunt of mill closures, tight quotas, and oversupply almost everywhere F&W operates, even as pine sawtimber, chip-n-saw, and poles hold steady or improve in several regions. Weather, fuel costs, and a handful of new mill investments shaped the picture nearly everywhere else. Click HERE to read the full commentary.
MARKET PULSE: ALL REGIONS
7 managers report stable conditions, 6 mixed, 3 soft, 3 improving, 1 somewhat volatile
Southeast (AL/FL/GA/SC)
West Gulf (AR/MS/OK/ TX)
Central Hardwoods (TN)
Mid Atlantic (VA)
Northeast (ME/NY/PA/VT)
Inland Northwest (ID)
Northern California
Mixed–Improving, with volatility in S.C.
Mostly stable but one mixed
10 report normal, 8 declining, 2 increasing
Large & small pine sawtimber, poles
Large pine sawtimber, chip-n-saw
Softening White oak, chestnut oak, hard maple
Softening Hardwood sawtimber
Mixed–Stable Sugar maple, white ash, oak, walnut
Stable Softwood sawtimber and poles
Stable 6”+/8”+ sawlogs and veneer logs
LANDOWNER ADVICE THIS QUARTER
Holding or selling selectively; pockets of active and opportunistic sellers
Pulpwood squeezed by mill closures; S.C. mills running well below capacity
Hardwood and pine pulpwood weak; 50% production cut at Clearwater Paper (Ark.)
Lower-grade hardwood and ties; McCreary Hardwoods closure (March)
Pine products under pressure; severe drought; rising fuel costs
Pulpwood and low-grade material; fuel costs; mud season delays
Pulp and pine under pressure as inventories build
Roseburg Weed closure removed ~60 MMBF; Douglas fir prices down
Steady to improving in several regions; fuller recovery still tied to late 2026
New chip-n-saw capacity in Ga.; Hampton Lumber facility (Fairfax, S.C.) due early 2027
Twain Lumber 2nd shift (Okla.); Canfor moving to two shifts (Ark.) this fall; pine beetle risk after ice damage (Miss.)
Clinch River Hardwoods reopening late 2026; possible turnaround in Q3/Q4
Outlook hinges on lumber demand, weather, and the Iran conflict; most sales held until mid-to-late summer
Strong sugar maple/white ash pricing; Maine mill closures offset by steadier demand elsewhere
Favorable window for forest-health and fuels-reduction harvests; fire risk and housing market are key watch items
SPI Eugene mill expected to pull from southern Oregon, improving Northern California log demand
“Exports are a bona fide market, and we need them to succeed, grow, and compete for wood.” —Wade McDonald, Statesboro, Ga.
“Move forward with solid wood product sales. Consider thinnings as a silvicultural must and not a profit activity. Plan for another potential mill closure by adjusting your reforestation regime.” —Bryan Croft, Orange Park, Fla.
ALSO NOTABLE THIS QUARTER
New capacity: Twain Lumber (Antlers, Okla.) adds a second shift; Canfor (El Dorado, Ark.) will move to two shifts after an August upgrade shutdown; Plantation Pine Products (Thomasville, Ga.) expected to start receiving small diameter chip-n-saw soon; Hampton Lumber (Fairfax, S.C.) expected to open in early 2027
Closure: Resolute pulp facility, Sylacauga, Ala. (also served Childersburg); McCreary Hardwoods (McCreary County, Ky.) closed in March
Reopening: Clinch River Hardwoods (Thornhill, Tenn.) expected to resume production later this year
Watch: Southern pine beetle risk following Mississippi’s winter ice-storm damage
RFS Amendment Falls Short In House—Fight Moves To Senate
The U.S. House of Representatives took a major step toward reauthorizing the Farm Bill in late April, approving the long-awaited legislation and sending it to the Senate.
The vote marked the first substantial effort to update federal farm and forestry policy after years of temporary extensions. In June, the Senate Agriculture Committee unveiled its own discussion draft, keeping momentum alive as Congress works toward a new five-year Farm Bill. For forest landowners, the process has brought both encouragement and unfinished business.
A LONG-SOUGHT RFS FIX
For forest landowners and the wood products sector, the most consequential debate in the House centered on an amendment offered by Reps. Cliff Bentz (R-Ore.), Bruce Westerman (R-Ark.), and Russ Fulcher (R-Idaho). The amendment sought to correct a longstanding flaw in the Renewable Fuel Standard (RFS) that has effectively excluded most forestderived biomass from qualifying as a renewable fuel feedstock.
Under the proposal, the definition of “renewable biomass” in the Clean Air Act would be broadened to make more forest-derived materials—including whole trees—eligible for renewable fuel production. Supporters argued that the change would open the door for greater use of woody biomass in the production of cellulosic biofuels and Sustainable Aviation Fuel (SAF), creating new markets for low-value wood, logging residues, and mill byproducts while supporting active forest management.
The case for the fix is simple: agricultural feedstocks already participate in the RFS; woody biomass has been excluded not by policy design but by a drafting flaw. Correcting it would allow forests to contribute to the nation’s renewable fuel supply without displacing existing
feedstocks or programs.
WHY IT MATTERS
The change could encourage new investment in rural communities where mills have closed, as biofuel facilities tend to locate where feedstock costs are lowest. And with SAF demand growing faster than domestic supply, woody biomass stands out as one of the most scalable feedstocks available to help meet that demand.
Perhaps most importantly, creating new markets for low-value wood makes forest thinning and hazardous fuels reduction projects financially practical, improving forest health while reducing wildfire risk.
The amendment drew support from the National Alliance of Forest Owners (NAFO), the Forest Landowners Association (FLA), state forestry associations, the American Farm Bureau Federation, and partners across the supply chain. Opposition came primarily from the American Forest & Paper Association (AF&PA), which argued that expanding RFS incentives to include woody biomass would raise wood fiber costs and put pulp and paper mill jobs at risk. The amendment ultimately failed by a narrow 216-210 vote.
Supporters characterized the outcome as a setback, not a defeat. The vote demonstrated bipartisan support for the proposal, raised awareness about the need for new markets for low-value wood and mill residuals, and kept the issue alive as the Farm Bill moves to the Senate.
MORE THAN AGRICULTURE
While the Farm Bill is often associated with row crop agriculture, it is also one of the most significant sources of federal support for private forest landowners. Conservation and forestry programs within the legislation provide cost-share funding, technical assistance, and other tools
that help landowners improve forest health, enhance wildlife habitat, and implement sustainable forest management practices. These programs represent the largest single source of federal funding available to private landowners for supporting sustainable management across the country’s privately owned forests.
The House-approved bill includes provisions to expand active forest management, strengthen markets for forest products, and support rural economies. It would continue funding for major conservation programs and would authorize a new Forest Conservation Easement Program aimed at protecting working forest lands and preventing conversion to non-forest uses.
ATTENTION TURNS TO SENATE
As this newsletter went to press, the Senate Agriculture Committee released its long-awaited discussion draft of the Farm Bill. The proposal mirrors many provisions of the House-passed bill and incorporates more than 100 bipartisan measures. Committee Chairman Sen. John Boozman (R-Ark.) has indicated that the committee is expected to begin marking up the legislation in July. At this stage, however, it remains unclear whether the Senate will consider language similar to the House amendment to update the RFS definition of renewable biomass. Forestry advocates are expected to continue pressing for the change as the Senate begins its work, viewing committee consideration as the next opportunity to expand markets for low-value wood, mill residuals, and sustainable aviation fuel feedstocks.
While the path to final passage remains uncertain, the Senate’s release of a discussion draft signals that work on a new Farm Bill is continuing—and that the effort to correct the RFS biomass definition is far from over.
ArborGen Results Reflect Ongoing Pulpwood Shift
Recent financial results from ArborGen provide further evidence of a trend that has been gradually reshaping global forestry markets for several years: the shift of pulp production and associated timber demand away from the U.S. and toward lower-cost regions such as Brazil.
The tree seedling company reported its strongest financial performance in five years, with revenue reaching $68.2 million. Much of that growth was fueled by Brazil, where strong demand for both pine and eucalyptus seedlings helped drive sales 14 percent higher in local currency and accounted for 44 percent of the company’s total revenue.
According to ArborGen, Brazil continues to be one of the world’s most dynamic forestry markets, benefiting from expanding pulp production capacity, growing demand for engineered wood products, and increasing adoption of advanced genetics. Demand for the company’s
protected, genetically improved eucalyptus clones increased 25 percent during the year, reflecting the industry’s focus on maximizing productivity from each acre planted.
At the same time, ArborGen’s comments regarding the U.S. South highlight the challenges facing traditional pulp-producing regions. The company noted that the industry changes experienced in recent years are creating “deeper, structural shifts” in the marketplace, driven by a long-term decline in pulp demand, subdued housing construction, and reduced mill production and harvesting activity.
Those trends are forcing companies throughout the forestry supply chain to adapt. While ArborGen’s U.S. sales revenue remained stable, seedling volumes declined 4 percent year-overyear. In response, the company is increasingly focused on higher-value products and advanced genetics that help landowners maximize sawtimber production rather than
pulpwood yields. Average selling prices in the U.S. South increased 6 percent during the year as customers shifted toward premium seedlings and containerized products.
CEO Justin Birch said the company’s strategy of diversifying beyond the U.S. market and expanding its presence in Brazil is paying off. “While market conditions in the U.S. South remain challenging, our deliberate strategy over the past five years to diversify market concentration and expand our presence in Brazil is delivering,” Birch said.
The contrasting performance of ArborGen’s two primary markets reflects broader global dynamics. Brazil’s highly productive plantation forests, favorable growing conditions, and expanding manufacturing capacity continue to attract investment, while the U.S. South increasingly relies on higher-value solid wood products and premium timber markets to drive returns.
Innovative Timber Gridshell Showcases Power Of Wood Design
A striking new timber structure in metro Atlanta is demonstrating how wood can be used to create innovative and visually dramatic architecture. The Assembly Studios Bandshell in Doraville, Ga., debuted ahead of the FIFA World Cup and features what engineers describe as North America’s first large-scale asymptotic timber gridshell.
The 4,000-square-foot bandshell is constructed from a lattice of timbers that are bent into shape during installation, creating a sweeping saddle-shaped canopy spanning 82 feet. Rather than relying on heavy structural materials, the design takes
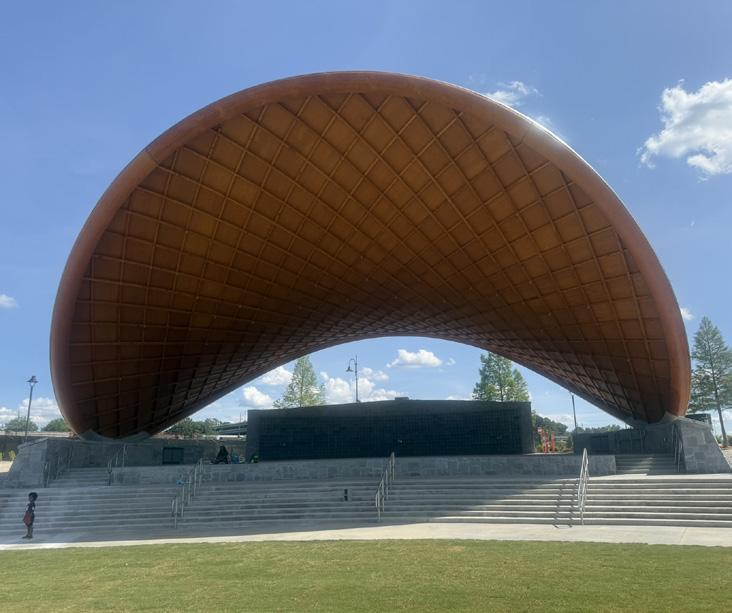
advantage of wood’s unique flexibility and strength, allowing the curved form to efficiently distribute loads through the timber grid.
The project highlights the
growing role of mass timber and engineered wood products in modern construction. The gridshell’s curved glulam ring beam and timber lattice showcase how wood can be used not only as a sustainable building material, but also as a medium for architectural innovation.
Once World Cup festivities conclude, the bandshell will serve as a permanent outdoor venue for concerts, movies, and community events, leaving a lasting example of how wood can combine performance, sustainability, and design in a single landmark structure.
EUDR Review Leaves U.S. Forestry Seeking More Relief
The European Union (EU) has completed its long-awaited review of the European Union Deforestation Regulation (EUDR), and the outcome offers little relief for U.S. forest owners and wood products exporters.
While the European Commission announced technical changes intended to simplify compliance, it declined to reopen the regulation or significantly ease requirements for suppliers in low-risk countries such as the United States.
The EUDR takes effect Dec. 30, 2026, for large and medium-sized companies and June 30, 2027, for small and micro operators. Companies importing covered products into the EU—including wood products—must demonstrate they are not linked to deforestation or forest degradation.
COMPLIANCE BURDENS REMAIN
U.S. forestry groups remain particularly concerned about the regulation’s geolocation requirement, which requires timber to be traced to the individual harvest location. They argue the requirement is costly, difficult to implement across fragmented private ownership and unnecessary given the nation’s strong record of sustainable forest management.
Although the Commission says its changes will reduce compliance costs, American forestry
organizations argue the benefits largely apply to companies operating within the EU.
The National Alliance of Forest Owners (NAFO) said the review contains “no meaningful simplification” for U.S. forest owners and warned that compliance burdens are already disrupting the American forest products supply chain. According to the organization, the regulation risks creating two classes of suppliers—large operators with the resources to comply and smaller family forest landowners who may find access to export markets increasingly difficult. Private landowners supply about 90 percent of the nation’s wood and fiber.
CLARIFICATION FOR FORESTS
One positive development involves planted forests. Updated guidance clarifies that certain forests established through tree planting or seeding that eventually resemble naturally regenerated forests should not automatically be considered degraded under the EUDR.
The clarification is particularly important for forests in the Southern U.S., where intensively managed pine plantations are the primary source of commercial timber. While some ambiguity remains, industry groups say the guidance better recognizes sustainable plantation forestry.
The Commission also proposed
several product-scope changes, but none significantly affect forest products. Wood residues such as sawdust and wood chips remain covered by the regulation.
PUSH FOR RISK-BASED APPROACH
Pressure for additional changes continues to build in the U.S. In a recent opinion piece, U.S. Ambassador to the European Union Andrew Puzder argued that the EUDR should exempt operators from countries that pose negligible deforestation risk and have demonstrated strong forest governance, specifically citing the U.S., Canada, Sweden and Finland. He argued that a risk-based approach would allow the regulation to focus its scrutiny on countries where deforestation remains a significant concern while avoiding unnecessary costs for low-risk trading partners and European consumers.
For now, however, the message from Brussels is clear: implementation is moving forward. As the compliance deadlines approach, U.S. exporters must continue preparing for the regulation while policymakers on both sides of the Atlantic debate whether a more risk-based approach can achieve the EU’s environmental objectives without creating unnecessary burdens for sustainable forestry.
Disaster Recovery Bill Strengthens Support For Landowners
Private forest landowners recovering from hurricanes, wildfires, tornadoes, floods, and other natural disasters could soon receive disaster assistance more quickly under the Emergency Conservation Program Improvement Act.
The bipartisan legislation, which
passed Congress with overwhelming support, reforms the USDA’s Emergency Forest Restoration Program (EFRP) and Emergency Conservation Program (ECP) by allowing eligible landowners to receive advance payments for restoration work rather than
paying costs upfront and waiting for reimbursement. Under the bill, nonindustrial private forest landowners may receive up to 75 percent of estimated restoration costs in advance, providing much-needed cash flow to begin (continued on page 7)
Weyerhaeuser Turns To AI To Digitize Forest Management
Artificial intelligence is rapidly transforming industries across the economy, and now the largest U.S. private timberland owner is betting that the technology can revolutionize forestry as well.
In a recent interview with The Wall Street Journal, Weyerhaeuser CEO Devin Stockfish outlined an ambitious strategy to leverage artificial intelligence, advanced analytics, and automation across the company’s nearly 11 million acres of timberlands in the U.S. and Canada. The effort is part of a broader initiative aimed at increasing annual profits by $1 billion by the end of the decade, with AI-driven efficiencies expected to play a significant role.
Weyerhaeuser’s vision extends well beyond traditional forest inventory systems. The company is developing a comprehensive “digital twin” of its timberlands using satellite imagery, drone photography, and LiDAR technology. LiDAR (Light Detection and Ranging) uses laser pulses to create highly detailed three-dimensional maps of terrain and vegetation, allowing foresters to measure tree height, canopy structure, stocking levels, and other forest attributes with remarkable accuracy. By combining these technologies, the company hopes to create a detailed digital representation of its forests that can track individual trees, monitor growth
Disaster Recovery Bill
reforestation and cleanup efforts immediately.
The legislation also expands advance payments for agricultural producers, extends the timeframe for using disaster assistance funds, and broadens eligibility for wildfire assistance to include certain human-
rates, improve harvest planning, and make more informed management decisions.
According to Stockfish, Weyerhaeuser’s decades of forest management experience position it well to capitalize on the technology. “We’ve been growing forests for 125 years. We probably have as much information and data about how forests grow as any organization on the planet,” he said. “The opportunity set here is really leveraging this new transformational technology to take all of that information and data and make everything we do better.”
The technology is already being applied to reforestation efforts.
Weyerhaeuser has trained AI models to analyze drone imagery and calculate seedling survival rates—work that traditionally requires foresters on the ground conducting field surveys. According to Stockfish, the approach provides faster, more accurate, and less expensive data collection while helping the company evaluate the success of its planting programs.
AI is also being integrated into harvesting operations. Last fall, Weyerhaeuser demonstrated a pilot project featuring a remotely operated skidder equipped with AI-assisted navigation and terrain mapping technology. The company believes such systems could eventually allow a single operator to manage multiple
pieces of equipment, improving productivity while helping address the ongoing challenge of recruiting and retaining skilled logging equipment operators.
The company is also working with technology partners to develop in-cab AI assistants that provide realtime recommendations to harvesting crews. These systems use digital forest models and management objectives to help identify which trees should be harvested and which should be retained during thinning operations, with the goal of maximizing long-term timber value and stand productivity.
While many forestry companies have adopted advanced mapping and inventory technologies over the past decade, Weyerhaeuser’s efforts illustrate how artificial intelligence is moving beyond data collection and into operational decision-making. As AI tools continue to mature, they may offer landowners new opportunities to improve forest productivity, optimize transportation and logistics networks, enhance reforestation success, and support more datadriven management practices.
Although forestry operations may never become fully autonomous, Weyerhaeuser’s investments suggest that artificial intelligence could become an increasingly important tool in the future of forest management.
(continued from page 6)
caused fires that spread through natural conditions.
Forestry organizations praised the measure as a long-overdue improvement that will help landowners restore working forests more quickly after disasters while protecting rural economies, wildlife
habitat, and the long-term supply of sustainable wood products. They also emphasized that additional funding for the restoration programs will remain important as severe weather events continue to impact forests across the country.
Super El Niño Could Reshape Forestry Conditions
A potentially historic El Niño is no longer just a possibility. NOAA confirmed in June that El Niño conditions have developed in the Pacific Ocean and forecasts indicate there is a 63 percent chance the event could become a very strong El Niño during the winter of 2026-27. While weather impacts remain uncertain, the forecast has already captured the attention of foresters because strong El Niño events can influence everything from timber harvesting conditions in the South to wildfire risk in the West.
El Niño occurs when sea surface temperatures in the tropical Pacific become unusually warm, altering rainfall and temperature patterns across North America. A Super El Niño refers to an exceptionally strong El Niño event. The strongest events in modern history occurred in 1982-83, 1997-98, and 2015-16 and produced significant weather disruptions across the U.S. and around the world.
For the forestry sector, the impacts are rarely uniform. While every El Niño develops differently and no single event guarantees specific local impacts, stronger El Niño events generally increase the likelihood of typical regional weather patterns. In fact, a Super El Niño could create sharply different conditions for forests
in the South and the West.
In the Southeast, where much of the nation’s timber production is concentrated, El Niño often brings wetter-than-normal conditions. Additional rainfall can improve soil moisture, enhance seedling survival, and support growth in recently established pine plantations. Reduced drought stress may also lower wildfire risk during the winter fire season. Conversely, excessive rainfall can complicate forest operations. Wet conditions often limit access to timber stands, delay harvesting and site preparation activities, and increase maintenance costs for forest roads. Logging contractors can face significant operational challenges when soils remain saturated for extended periods.
Western forests could face a very different set of risks. Strong El Niño events can alter snowpack accumulation and seasonal precipitation patterns, contributing in some regions to reduced summer moisture, increased drought stress, and elevated wildfire risk. Droughtstressed trees are also more vulnerable to insect infestations and disease, potentially resulting in additional timber losses.
These contrasting regional impacts could also influence timber markets. In the South, prolonged wet weather may temporarily reduce harvesting activity and tighten timber supplies. However, past El Niño events suggest that weather disruptions do not automatically translate into higher stumpage prices. Market conditions, mill inventories, and timber demand ultimately play a larger role in determining prices.
Meanwhile, severe drought, wildfire, or insect outbreaks in western forests could reduce timber inventories and disrupt wood supplies over the longer term.
The broader lesson is that a Super El Niño would likely create winners and losers across the forestry sector rather than a single nationwide outcome. Southern landowners might benefit from favorable growing conditions but face operational challenges, while western landowners could confront increased risks from drought, insects, and wildfire.
As the 2026-27 El Niño develops, forest landowners should closely monitor changing weather patterns and consider how shifting rainfall, drought, and wildfire risks could affect their management plans and timber markets.
Save America’s Family Forests Act Introduced
As forest landowners across the nation continue to recover from hurricanes, wildfires, tornadoes, and other natural disasters, a bipartisan group of lawmakers has introduced legislation designed to make reforestation more affordable and accelerate recovery efforts.
The Save America’s Family Forests Act would modernize federal tax policy by allowing forest landowners to recover reforestation costs more
quickly following timber losses caused by federally declared disasters. The bipartisan legislation is led in the House by Reps. Buddy Carter (RGa.), Aaron Bean (R-Fla.), Nathaniel Moran (R-Texas), Greg Murphy (R-N.C.), Terri Sewell (D-Ala.), Greg Steube (R-Fla.), and Mike Thompson (D-Cal.), and in the Senate by Sens. Bill Cassidy (R-La.) and Raphael Warnock (D-Ga.).
Under current tax law, forest
landowners may deduct only up to $10,000 in reforestation expenses during the year those costs are incurred. Any remaining expenses must be amortized over the following seven years. While that approach may work under normal circumstances, forestry advocates argue it creates a significant financial burden for landowners who must quickly replant large acreages after a catastrophic event.
(continued on page 9)
Save America’s Family Forests
The proposed legislation would increase the annual reforestation deduction from $10,000 to $30,000 for all forest landowners. More importantly, it would allow landowners impacted by federally declared disasters to immediately deduct up to $500,000 in reforestation costs, providing critical cash flow when it is needed most.
The issue has become increasingly important as forest owners face more frequent and costly weatherrelated disasters. In recent years, hurricanes such as Michael, Idalia, and Helene have caused billions of dollars in timber damage across the Southeast. Because timber crops require decades to mature, a single
storm can erase generations of investment overnight.
Supporters of the bill say faster cost recovery would help landowners begin replanting sooner, reducing the risk that damaged forestland is converted to non-forest uses. Maintaining working forests is important not only for timber production, but also for wildlife habitat, water quality, carbon storage, and the economic vitality of rural communities.
The legislation has received strong support from forestry and agricultural organizations nationwide, including the Forest Landowners Association, the Association of Consulting Foresters, the American
INLAND NORTHWEST TIMBER PRICES
Farm Bureau Federation, and state forestry associations. These groups argue that improving reforestation tax treatment is one of the most effective ways Congress can help keep forests productive and family-owned following major natural disasters.
For family forest owners, the measure represents more than a tax change—it is a recognition that timely reforestation is essential to preserving America’s working forests and the rural economies that depend on them.
FOR MORE INFORMATION ABOUT THE SAVE AMERICA’S FAMILY FOREST ACT, CLICK HERE QUICK LINK
LAFAYETTE, AL
ORANGE PARK, FL
MARIANNA, FL
ALBANY, GA
MACON, GA
STATESBORO, GA
FOUNTAIN INN, SC
CLINTON, TN
PARIS, TN
EL DORADO, AR
CORINTH, MS
ANTLERS, OK
HUNTSVILLE, TX
CHARLOTTESVILLE, VA
GA MACON, GA
STATESBORO, GA
FOUNTAIN INN, SC
CLINTON, TN
PARIS, TN
EL DORADO, AR
CORINTH, MS
ANTLERS, OK HUNTSVILLE, TX CHARLOTTESVILLE, VA
FL
ALBANY, GA
MACON, GA
STATESBORO, GA
FOUNTAIN INN, SC
CLINTON, TN
PARIS, TN
EL DORADO, AR
CORINTH, MS
ANTLERS, OK
HUNTSVILLE, TX
CHARLOTTESVILLE, VA
Timber Stumpage
PINE LARGE SAWTIMBER
SOUTHERN TIMBER PRICES (continued)
ORANGE PARK, FL
MARIANNA, FL
ALBANY, GA
MACON, GA
STATESBORO, GA
FOUNTAIN INN, SC
CLINTON, TN
PARIS, TN
EL DORADO, AR
CORINTH, MS
ANTLERS, OK
HUNTSVILLE, TX
CHARLOTTESVILLE, VA
Stumpage Price Averages By Region
GA
TX
VA
All prices based on sales handled by or reported to F&W offices. If no sales occurred, prior quarter ’s sales and other data are used to compile price range. Price ranges are due to proximity to mills, timber quality, logging conditions, type of harvest, and other local market conditions (i.e. weather, mill downtime, fuel cost, etc.).
Marshall Thomas
(continued from page 1)
restoration payments to disasterdamaged forests (page 6). The Save America’s Family Forests Act would raise the annual reforestation tax deduction and allow landowners hit by federally-declared disasters to immediately deduct up to $500,000 in reforestation costs (page 8). The Forest Service is reorganizing and relocating its headquarters to Salt Lake City, Utah (page 2).
AI is making its way into the woods. In a recent Wall Street
Journal article, Weyerhaeuser’s CEO discusses how the company is using AI, from digital data analysis to logging equipment operations. See page 7 for an idea of what AI in forest operations might look like.
Bottom line: markets remain steady, with hints of improvement later this year, while forestry legislation remains active. A $500,000 postdisaster reforestation deduction would meaningfully cut landowner risk, and AI may help trim operating costs at a
time when margins need it. Our state and national associations keep fighting in Washington—against onerous regulation like the EUDR, and for new markets like a reformed RFS. Nobody can call current conditions positive, but there’s real effort going into making things better. Forest landowners and foresters are patient people—we know that effort applied over time produces results. I have to believe that’s true here too.
Don’t stop believing.
Timber Stumpage Price Averages By Region
RED OAK (MBF) 2026 Second Quarter Price Range
NEW ENGLAND ADIRONDACKS, NY HERKIMER, NY NEW OXFORD, PA BLUEFIELD, WV
$800
$700
$200
WINTHROP, ME
MONTPELIER, VT
ADIRONDACKS, NY
HERKIMER NY
NEW OXFORD, PA
BLUEFIELD, WV
Herkimer, NY New England Adirondacks, NY
New Oxford, PA Blue eld, WV
Timber Stumpage Price Averages By Region
CHERRY (MBF) 2026 Second Quarter
ADIRONDACKS, NY HERKIMER, NY NEW OXFORD, PA BLUEFIELD, WV
$500
$300
Timber Stumpage Price Averages By Region
NEW ENGLAND ADIRONDACKS, NY HERKIMER, NY NEW OXFORD, PA BLUEFIELD, WV
WINTHROP, ME
MONTPELIER, VT
ADIRONDACKS, NY
HERKIMER NY
NEW OXFORD, PA
BLUEFIELD, WV
Second Quarter Price Range
WINTHROP, ME
MONTPELIER, VT
ADIRONDACKS, NY
HERKIMER NY
NEW OXFORD, PA
BLUEFIELD, WV
HARD MAPLE (MBF)
NORTHERN TIMBER PRICES (continued)
Lorem ipsum
Timber Stumpage Price Averages By Region
WINTHROP, ME MONTPELIER, VT
ADIRONDACKS, NY
WV
As a result of the federal government shutdown in 2025, the U.S. Census Bureau is behind in updating
starts, or residential construction data.
HOUSING PERMITS HOUSING STARTS RESIDENTIAL CONSTRUCTION
IN MILLIONS OF UNITS (2026 AVERAGE THROUGH MAY )
Source: US Department of Commerce
Source: US Census and F&W Forestry Services F&W’S LUMBER-USE ADJUSTED HOUSING STARTS IN MILLIONS OF DOLLARS (2026 AVERAGE THROUGH MAY) r = REVISED Source: US Department of Commerce
IN MILLIONS OF UNITS; TOTAL HOUSING STARTS WITH MULTIFAMILY STARTS REDUCED TO 40 PERCENT TO BETTER REFLECT LUMBER USAGE (2026 AVERAGE THROUGH MAY)
Source: Freddie Mac
SOUTHERN PINE–$/MBF
Source: Random Lengths Southern Pine Composite Index
DOLLAR
AGAINST 26 MAJOR TRADING PARTNERS Source: Federal Reserve
F&W Forestry Services proudly serves a broad client base with comprehensive forest management solutions. Our team takes the time to get to know you, your land, and your goals to create a personalized plan for success.
OUR MISSION
F&W’s mission is to help clients maximize the value and enjoyment of their land and forest resources according to their individual objectives, needs, and desires – whether economic, aesthetic, environmental, or recreational.
OUR SERVICES
Timber Sales
Property Management
Field Support Services
Forest Inventory & Mapping
Forestland Accounting
Technical & Analytical
Real Estate
Natural Capital