
Each year, the Canadian Franchise Association (CFA) sees the power of franchising enacted at the ground level—through our members, whose franchise systems and individual franchised small businesses are growing, contributing to their local communities, and generating livelihoods for the entrepreneurs that fulfill their dreams of business ownership through franchising.
But when we zoom out to the industry level, we see the big-picture impact of franchising in Canada. Despite the economic challenges and political instability of the past few years, franchising continues to grow. In 2019, this industry was worth just under $100 billion. As you’ll see in the pages of this report, by 2026, it was worth $143.3 billion. That’s an incredible amount of growth, all through a global pandemic and economic instability.
Today, franchising remains the country’s 12th largest industry. It is projected to grow by 3.7 per cent, increasing the total franchise-related GDP contribution to $148.6 billion by 2027.
Beyond GDP growth, Canadian franchisors continue to expand, with the number of franchise establishments projected to reach 70,482 by the end of 2026. The Canadian franchise industry’s contribution to provincial and federal tax revenue is also expected to increase to $36.5 billion, an increase of almost 4 per cent over 2025.
Members of the CFA community are a large part of this growth. Our members help the CFA achieve its purpose of helping everyday Canadians build their own business through the power of franchising. That’s why prospective franchisees Look for the Logo—the CFA member logo signifies credibility, indicating a brand that has signed on to the CFA’s Code of Ethics.
The Canadian franchise industry is projected to contribute $148.6 billion to the national GDP by 2027
12
12th
Franchising ranks as the 12th largest industry in Canada
As CFA members commit to being the best possible franchisors they can be, they provide the support franchisees need to thrive in their communities. These franchisees are local small business owners who are the backbone of the industry, serving and contributing to their local communities each and every day. The Canadian franchise industry is projected to employ almost 2 million people in 2026, and pay $75.6 billion in wages to Canadians (an almost 4 per cent increase from last year).
Growth is expected across all regions, with Alberta, British Columbia, Newfoundland and Labrador, and Prince Edward Island expected to see the highest percentage of franchise-related growth, and Ontario projected to add the highest number of franchised establishments.
The resilience and continued growth of the franchise industry would not be possible without the CFA community. Throughout 2026 and beyond, we will remain committed to Growing Together, in the face of any and all challenges. Our efforts continue to ensure the industry meets the expectations outlined in this report, as we focus on bringing even more local small business owners into our community through franchising.
Sincerely,
Sherry McNeil, President & CEO Canadian Franchise Association
Printing sponsored by
70,482 franchisees are projected to be operating their own small business by 2027
Almost
2 million Canadians are employed by franchising nationwide
The Canadian Franchise Association (CFA) helps everyday Canadians realize the dream of building their own business through the power of franchising. CFA advocates on issues that impact this dream on behalf of more than 600 corporate members and over 40,000 franchisees from many of Canada’s best-known and emerging franchise brands. Beyond its role as the voice of the franchise industry, CFA strengthens and develops franchising by delivering best -practice education and creating rewarding connections between Canadians and the opportunities in franchising. Founded in 1967, CFA consistently advances and supports the franchise community, and is the essential resource for information, insight, and expertise through its award-winning education, events, services, and websites: www.cfa.ca and FranchiseCanada.online.
The Canadian Centre for Economic Analysis (CANCEA) is Canada’s foremost independent socio-economic advisory and data firm.
We enable intelligent and responsible decisionmaking and dialogue through the provision of timely, data-driven social, economic and business insights and solutions that are trusted by over 400 leading organizations for their policy and business-critical forward-looking analysis.
Our services are powered by Canada’s largest, fully integrated socio-economic platform that simultaneously examines hundreds of topics by geospatially simulating over 40 million people and 2 million firms across more than 5 8,000 Canadian regions.
Equipped with this powerful socio -economic intelligence, our experts and analysts help clients to track, analyze and report the many factors that make up and drive complex regional-level socio-economic communities. This allows the implications of socio-economic micro and macro trends across many topics to be understood by our clients in support of their policy and business-critical decisions.
CANCEA does not accept any research funding or client engagements that require a predetermined result or policy stance or otherwise inhibit its independence.
In keeping with CANCEA’s guidelines for funded research, the design and method of research, as well as the content of this study, were determined solely by CANCEA.
This information is not intended as specific investment, accounting, legal or tax advice. This report was commissioned by the Canadian Franchise Association.
Check out our services and case studies and ask us how we can use Canada’s largest and most detailed socio-economic simulation platform to help you at https://www.cancea.ca
©2026 Canadian Centre for Economic Analysis
©2026 Canadian Franchise Association
Printed in Canada • All rights reserved
Citation:
The Canadian Centre for Economic Analysis. Canadian Franchise Industry Economic Outlook 2026. February 2026.
This report outlines the economic forecast for the Canadian Franchise Industry for the upcoming year and covers the net change in the number of franchise establishments as well as franchise -related economic indicators, such as gross domestic product (GDP), employment (number of jobs and full -time equivalents), and tax revenue generated by franchises. These results are further brok en down by province and selected industry sectors.
The Canadian franchise industry has over 1,100 brands with at least one Canadian establishment and over 70,400 franchise establishments in a variety of industry sectors. Canada’s 2026 outlook is expected to be modest, with growth slowed by ongoing uncertainty, still-restrictive financing conditions, and softer domestic demand. Provincial performance is likely to remain uneven, with resource -oriented provinces generally faring better
Nationwide, we anticipate the number of franchise establishments in the country to grow by about over 450, with over 90% expected to be supported by local investors. This growth supports the continued increases in GDP, wages, and taxation revenues as the sectors continues to grow.
T Table 1 Overview of the national outlook
In 2026, the nominal economic activity of the Canadian franchise industry is expe cted to grow by 3.68% (+$5 3 billion net increase), increasing the total franchise -related GDP contribution to $148.6 billion by 2027. With over 93% of franchise establishments not corporate owned, this franchise -related GDP contribution reflects the investment local businesses make in their community As illustrated in Table 1, the total number of franchise establishments in Canada is expected to grow by 0.65% to a total of nearly 71,000 franchise establishments. Furthermore, the Canadian franchise industry’s contribution to federal and provincial tax revenue is expected to increase, respectively, by 3.68% (+$685 million net increase) to $19.3 billion and by 3.65% (+$605 million net increase) to $ 17 2 billion by 2027 Higher prices and wages are driving most of the increases rather than growth in the number of franchises.
Total franchise-related employment in the country is expected to grow by 0.65% to 1.83 million jobs (1.57 million FTEs) by 2027, which is equivalent to 11,800 net new jobs (9,000 of which are directly due to franchises). Growth in employment is associated with a 3.68% increase in total franchise-related wages to almost $75 7 billion (a net increase of $2.7 billion in wages over the coming year). Part -time franchiserelated employment is expected to increase slightly less than full-time employment, by 0.63% (+3,200 net new jobs) to 518,400 jobs while full-time employment is expected to grow by 0.65% (+8,500 net new jobs) to 1.31 million.
At the provincial level, in absolute terms, Ontario is estimated to have the largest number of franchise establishments added, but among the lowest percentage growth, with an increase of 181 establishments (growth of 0.53%). Alberta (90 net new establishments ) and British Columbia (80) have the second largest number of franchise establishments added as well as higher than average growth rates. Alberta is followed by Newfoundland and Labrador with growth at a rate of 1.07%. Newfoundland and Labrador, along wit h Prince Edward Island also have higher growth rates in the number of franchises, though this amounts to only a handful of new franchises. Meanwhile, the lowest percentage growth after Ontario is projected to occur in New Brunswick and Quebec, where the number of franchise establishments is estimated to grow by 0.68%, and 0.55% respectively. A breakdown of the provincial and territory projections for the franchise industry is provided in Table 2 and Table 3.
Table 4 provides an overview of the top franchise industry sectors across total franchise -related GDP and total franchise-related employment in terms of full-time equivalents (FTEs) Sectors which may experience above average growth include professional and technical services and construction, though these sectors currently have smaller franchise footprints . The growth in the accommodation and food services sector, despite being the largest sector by number of franchises and employment, is expected to be softer given economic uncertainties Of the combined $33.2 billion of franchise-related GDP in the accommodation and food services sector, the majority, 92%, is from the food services sector.
T Table 4 Top sector outlook for 20271
The sectors with the lowest GDP growth from 2026 to 2027 (included in the “Rest of sectors” category) include utilities; wholesale trade; transportation and warehousing; mining; and agriculture
1 Refer to Figure 1 on the next page for an overview of industry sectors and the types of franchises that fall under each industry sector category.
Figure 1 below provides an overview of the North American Industry Classification System (NAICS) industry sectors and the types of franchises that fall under each sector category.
Accommoodation Services (NAICS 721)
Hospitality Products / Services
Hotels / Motels / Campgrounds
Commercial and Residential Services (NAICS 56)
Administrative and Support
Commercial - Janitorial Services
Employment / Personnel Services
Environmental Products and Services
Printing and Manufacturing (NAICS 31-33)
Building & Design Services
Commercial - Supplies / Equipment & Services
Printing / Copying / Shipping
Sign Products & Services
Wine Making
Other Services (except Public Administration) (NAICS 81)
Automotive & Truck Services / Products / Rentals
Event Planning Beauty / Cosmetics / Supplies
Fire Prevention / Safety & Security
Furniture / Upholstery Repair
Home - Inspection Services
Home - Maid / Cleaning Services
Janitorial & Maid Services
Lawn & Garden Supplies / Services
Remediation
Security Systems & Services
Travel
Dry Cleaning / Clothing Care
Hair & Nail Salons / Spas
Tanning Salons
Other
Professional and Technical Services (NAICS 54)
Accounting / Tax Services
Advertising / Marketing / Promotional Products & Services
Business Consultants / Services / Training
Computer / Software / Internet
Waste Management Legal
Arts, Health and Fitness (NAICS 71)
Health / Fitness / Nutrition
Sports / Recreation / Entertainment
Weight Loss Services / Body Contouring
Educational Services (NAICS 61)
Educational Products & Services
Real Estate and Business Services (NAICS 52-53)
Business - Supplies / Equipment & Services
Business Services / Office Space / Co-working Space
Financial / Cash Services
Insurance
Leasing and Holding Companies
Rental
Real Estate
Food Services (NAICS 722)
Food - Baked Goods / Coffee / Donuts
Food - Quick Service Restaurants
Food - Restaurants / Dining Rooms
Health Care (NAICS 62)
Seniors Services / Home Care / Transition
Social Assistance
Information and Cultural Industries (NAICS 51)
Magazines / Publishers
Painting Services
Photo Imaging / Photography
Scientific
Construction (NAICS 23)
Custom Deck
Home/Commercial Improvement / Renovation / Restoration
Retail (NAICS 44-45)
Automotive dealers
Children's Products & Services
Commercial / Residential Services
Food - Grocery / Specialty Shops/ Meal Assembly
Home - Decorations / Furnishings
Home Based Businesses
Mobile Businesses
Pets - Sales / Supplies / Services
Pharmacy
Retail
Water Treatment
Transport and Warehousing (NAICS 48-49)
Consumer Buying Services
Designated Driving / Transportation Services
The Canadian franchise industry is projected to grow by 457 net new franchise establishments in the coming year, an increase of 0.65% over 2026 to nearly 70,900 establishments As shown in Figure 2, this growth continues the increase since the 2021 pandemic numbers, though economic uncertainty, particularly related to supply chains, may act to slow growth
F Figure 2
Number of franchise establishments since 202 1 at the start of each year
Across the country, Ontario is expected to have the largest number of franchise establishments added (+181 net increase, growth of 0.53%) to over 34,400 establishments. This represents 40% of all new franchise establishments in Canada in the upcoming year. Ontario is followed by Alberta and British Columbia, each projected to grow by 90 and 80 net establishments, respectively , resulting in a total of 8,413 and 10,670 establishments respectively. In terms of percent growth, New Brunswick and Quebec are expected to experience the lowest growth rates after Ontario at 0.67% and 0.55%, respectively Further provincial breakdowns are provided in Table 5.
T Table 5
The total franchise-related GDP is estimated to be $148.6 billion in 2027, a 3.68% increase over 2026. In 2027, the direct GDP attributed to Canadian franchises is estimated to be $87 7 billion, which represents 59% of the expected total franchise-related GDP. Table 6 provides an overview of the direct and total franchise GDP growth projected during 2026 by industry sector T Table 6
The sectors with the lowest nominal GDP (included in the “Rest of sectors” category) include agriculture, forestry, fishing and hunting; mining, quarrying, and oil and gas extraction; utilities; wholesale trade; transportation and warehousing; information and cultural industries; health care and social assistance; management of companies and enterprises; and public administration.
The primary driver of the growth in total franchise-related GDP is the food and accommodation services sector, which is expected to increase by 3.66% to $42.0 billion (+$1.5 billion from 2026) with 92% arising from the food services component of the sector due to the much larger number of food service franchises This is followed by the retail trade and finance, which are each expected to increase by over $600 million from 2026). Combined, these three industry sectors represent nearly 52% of the growth in the totalfranchise related GDP.
If we consider direct franchise GDP contributions (i.e. GDP that is generated through the operation of franchise establishments and not through indirect and induced effects), the top three industry sectors with the largest direct franchise GDP percentage growth in Canada are projected to be:
• Professional and technical services, growing by $270 million (+3.89%)
• Construction and related services, growing by $110 million (+3.82%) and
• Manufacturing, growing by $130 million (+3.70%)
Figure 3 provides an overview of the change in total franchise-related GDP in the franchise industry between 2026 and 2027 by province. As evident below, the largest total franchise -related GDP is projected to occur in Ontario followed by British Columbia and then Quebec.
F Figure 3 Provincial and territories total franchise-related nominal GDP
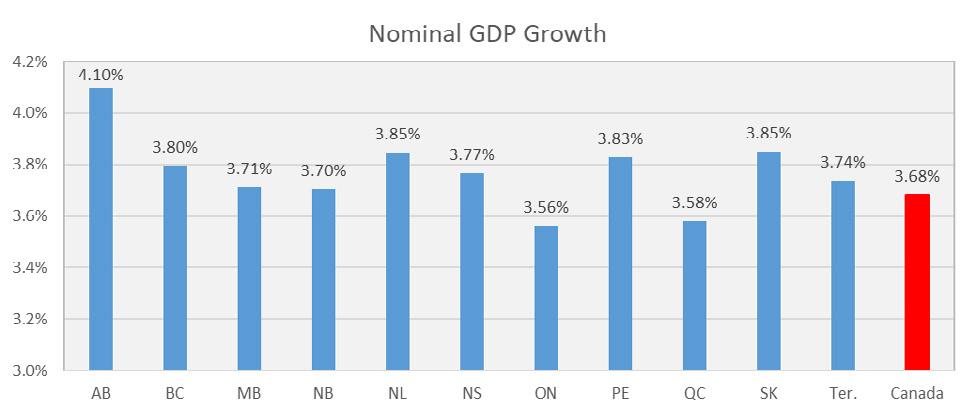
Each province and the territories projected to experience total franchise -related GDP growth not too far from the national average of 3.68% as illustrated in Figure 4. However, Alberta is expected to have the highest franchise-related GDP growth at 4.10% while Ontario will have the lowest at 3.56%.
The significance of franchise ecosystem to the Canadian economy is highlighted in Table 8 which shows that if franchises were considered its own sector, it would rank 12th in Canada.
The total franchise-related employment is projected to grow to 1.83 million jobs (1.57 million FTEs) by 2027, a 0.65% increase over 2026 and equivalent to 11,770 net new jobs Direct employment in Canadian franchises, representing 75% of the total franchise-related employment, is expected to grow by 8,970 new jobs (7,580 FTEs) by 2027, a 0.65% increase Table 9 provides an overview of the direct and total franchise employment growth projection by province.
T Table 9
Full-time total franchise-related employment growth is expected to be greater than part-time employment growth, which are expected to increase in 2027, respectively, by 0.65% (+8,530 net new jobs) to 1.31 million jobs and by 0.63% (+3,230 net new jobs) to 518,400. Table 10 further breaks down the employment growth across the provinces and territories by type of employment
T Table 10
New Brunswick
Edward Island
At the provincial level, in absolute terms, Ontario is estimated to have the largest number of total franchiserelated jobs added by 2027 (+4,800 new jobs, growth of 0.53%) to 908,000 jobs (778,000 FTEs). This represents 41% of the total franchise -related new jobs projected to be created by 2027 Alberta, given its continued economic growth, is the province with the next largest number of total franchise -related jobs added (+2,200 new jobs). At the same time, Atlantic provinces such as PEI and Newfoundland and Labrador are also projected to have relatively high percentage growth in franchise-related employment for 2026
However, in absolute terms Atlantic Provinces and the Territories are expected to add the fewest franchiserelated jobs, collectively adding just over 500 jobs. These regions have lower population sizes, and therefore, there is less demand for net new franchise establishments (i.e., some franchises may close , and new franchises may open, but net numbers are not changing as much as in other provinces).
In terms of the industry sectors that will contribute the most to the total franchise-related employment in 2026, the food and accommodation services sector (41.8%) and retail sector (13.9%) are projected to have the two largest contributions, making up over half of all franchise-related employment Figure 5 provides a breakdown of the sectors contributing to total franchise-related employment.
F Figure 5 Total franchise-related employment (FTEs) proportions
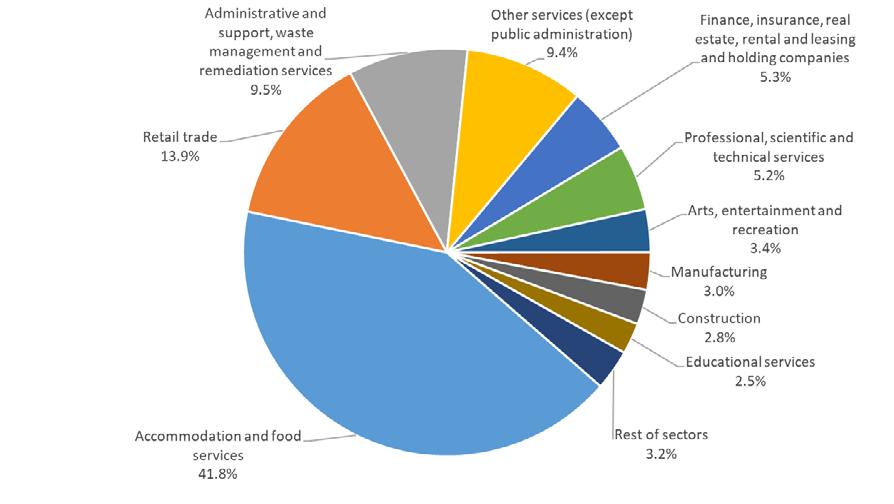
The “Rest of sectors” group include agriculture, forestry, fishing and hunting; mining, quarrying, and oil and gas extraction; utilities; wholesale trade; transportation and warehousing; information and cultural industries; health care and social assistance; management of companies and enterprises ; and public administration.
In terms of direct franchise employment, the food and accommodation services (47 1%) and retail (15 1%) sectors are also projected to contribute the most, followed by other services (excluding public administration) (10 4%) A further breakdown is provided in Figure 6
F Figure 6 Direct franchise employment (FTEs) proportions
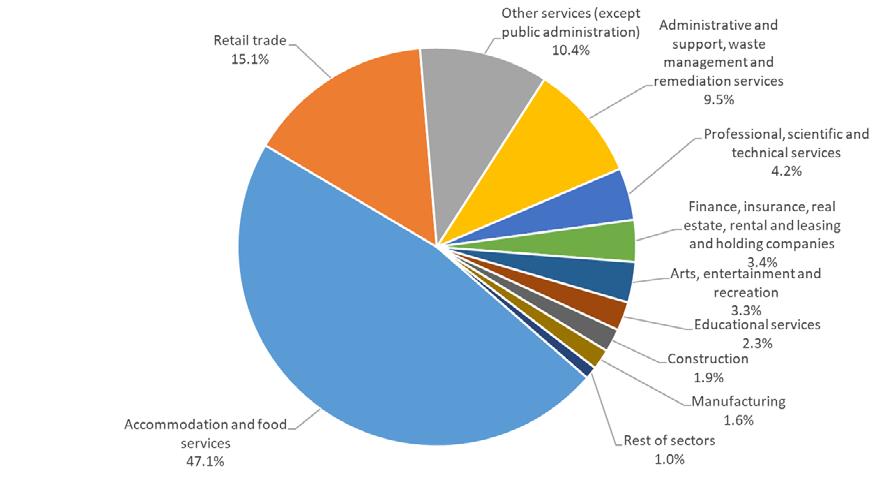
The “Rest of sectors” category includes the same sectors as in Figure 5.
The increase in franchise-related employment and wage growth is estimated to be associated with a 3.68% increase in the total franchise -related wages to $75 7 billion by 2027. This is a projected net increase of $2.7 billion in wages over the coming year. Table 11 provides a breakdown of the wage increases across the different provinces. T Table 11
The total franchise-related gross operating surplus2 (GOS) is estimated to be $49.7 billion by 2027, a 3.69% increase (+$1.77 billion net increase) over 2026 Table 12 provides an overview of the total franchiserelated GOS growth projected by province and territories. The largest increase in total franchise-related GOS is projected to occur in Ontario (+$827 million net increase, growth of 3.56%), followed by British Columbia (+$298 million net increase, growth of 3.79%) and then Alberta (+$278 million net increase, growth of 4.10%).
T Table 12 Provincial total franchise-related GOS growth
($ Billions)
The primary driver of the growth in total franchise-related GOS growth in the Canadian franchise industry is the food and accommodation services sector, which is estimated to increase by 3.67% by 2027 to $12 billion (+$420 million net increase from 2026). With food services franchises outnumbering the accommodation franchises by more than 10 to 1, over 90% of the GOS ($8.66 billion) is associated with the food services franchises. This is followed by the financial, insurance and real estate sector , which is estimated to also increase by 3.67% by 2027 to $7.29 billion (+$260 million net increase). Further breakdowns of the total franchise-related GOS growth by sector are provided in Table 13
2 Operating surplus is the return to capital of incorporated business. It consists of gross profits (including bad debts and charitable contributions) of corporations before income taxes, including capital consumption allowances, miscellaneous investment income, dividend pay net of dividend received, interest paid net of interest received, and inventory valuation adjustment. See full definition on the Statistics Canada website
The sectors with the lowest GOS growth ( included in the “Rest of sectors” category) include utilities; wholesale trade; transportation and warehousing; mining; management of companies and enterprises; and public administration.
By 2027, the Canadian franchise industry is projected to generate a total of $ 19.3 billion in federal taxation revenue (+$690 million net increase, growth of 3.68%) and $17 2 billion in provincial taxation revenue (+$600 million net increase, growth of 3.65%). Table 14 provides a breakdown of the federal and provincial taxation revenue projected to be generated by the Canadian franchise industry.
T Table 14 Federal and provincial taxation revenue generated
Given its size, Ontario’s franchise industry is expected to generate the most federal tax revenue out of all provinces at $9.67 billion (growth of 3.56%) and provincial tax revenue at $8 82 billion (growth of 3.56%) by 2027. In terms of taxation revenue growth , Alberta is estimated to see the largest percentage increase out of all the provinces and territories, with its tax revenue contribution growing by 4.10% to $2.40 billion federally and $1.22 billion provincially.
All provinces and territories are expected to see growth across all franchise -sector metrics, although growth is expected to differ considerably from province to province (and territories). The trends are presented by province in Table 15.
T Table 15 Provincial growth trends: establishments, nominal GDP, employment, GOS, wages and taxes
While GDP and employment are expected to grow across all industry sectors related to business, the professional and technical services sector is expected to have the greatest jobs growth rate of 0.83% The trends in expected franchise-related growth by industry sector is shown in Table 16 below.
T Table 16 Top industry sector growth trends: nominal GDP and employment
The sectors with the lowest nominal GDP and employment growth (included in the “Rest of sectors” category) include agriculture, forestry, fishing and hunting; mining, quarrying, and oil and gas extraction; utilities; wholesale trade; transportation and warehousing; information and cultural industries; management of companies and enterprises; health care and social assistance; and public administration.
In conclusion, our economic outlook for the upcoming year indicates that while the growth of franchise establishments will continue to be slow, we still expect to see positive gains in key economic indicators. This includes an increase in GDP, wages, and taxation revenues, as wages and prices continue to adjust after the periods of high inflation in the past years. As a result, we anticipate a franchise-related GDP growth rate of approximately 3.68% for the Canadian franchise industry, which will push its total franchise -related GDP contribution to $148 6 billion in nominal terms. These projections are a positive sign for the franchise industry and suggest that it will continue to be a significant contributor to the Canadian economy in the coming year. However, economic uncertainty, particularly around supply -chains and interest rates, will continue to be challenge.
Total franchise-related employment in the country is estimated to grow by 0.65% to 1.83 million jobs (1.57 million FTEs) throughout 2026 (equivalent to about 11,800 net new jobs, 8,970 of which are directly due to franchises). Total franchise -related employment growth is split between full-time employment, which is estimated to increase by 0.65% (+8,530 net new jobs) to 1.31 million jobs, and part-time employment, which is expected to grow by 0.63% (+3,230 net new jobs) to 518,000 positions. Growth in employment is associated with a 3.68% increase in the total franchise-related wages to nearly $75 7 billion (a net increase of $2.7 billion in wages over the coming year ).
The increased GDP, employment, and associated wages will result in an estimated 3.68% increase in federal and provincial taxation revenue contributed by th e Canadian franchise industry Federal tax revenue contributed by the franchise industry is estimated to reach $19.3 billion, while provincial tax revenue contributed by the franchise industry is estimated to reach $17 2 billion.
In terms of the provinces and territories , the largest increases in absolute terms in franchise-related GDP, employment, wages, GOS and taxation revenue are estimated to occur in Ontario, due to the size of the economy Total franchise -related GDP and wage growth in Ontario is projected at $2.6 billion and $1.3 billion (growth of 3.56%), respectively. Similarly, in terms of new franchise establishments, Ontario is expected to grow the most Of the 457 net new franchise establishments projected to be created countrywide, over 40% are expected to be in Ontario. However, growth rates of the franchise -sector are expected to be highest in Alberta with a 1.1% increase in the number of franchises, and 4. 1% increase in the total franchise-related nominal GDP in the province.
Agent
Agent-based modeling (ABM)
Direct Impact
Employment (Fulltime equivalents)
Employment (Total)
Franchisee
Franchising
Franchisor
Gross Domestic Product (GDP)
Gross Operating Surplus
Indirect Impacts
An autonomous individual, firm or organization that responds to cues from other agents and their environment using a set of evidence -based behavioural rules in response to those cues.
A framework for modeling a dynamic system, such as an economy, using individual agents, their mutual interaction with each other, and their mutual interaction with their environment(s).
The impacts directly involved in the operation of franchises. This includes the income and value of production of economic agents (i.e., workers and firms) directly involved in a franchise
Equivalent to person-years of employment refers to the amount of work typically performed by one person working full-time for one year.
The number of employed residents living in a region, in a given year. These residents may work within their region of residence or may commute outside of the region to work.
An individual or organization that gets granted and holds the rights contained in the franchise agreement for the sale of goods or the operation of a service.
Method of doing business in which one person, the franchisor, grants another, the franchisee, certain rights contained in the franchise agreement.
An individual or organization that grants the rights contained in the franchise agreement to a third party for the conducting of a business under their marks.
The total unduplicated value of the goods and services produced in the economic territory of a country or region during a given period.
Gross operating surplus is the surplus generated by operating activities after the labour factor input has been recompensed. It can be calculated from the value added at factor cost less the personnel costs. It is the balance available to the unit which allows it to recompense the providers of own funds and debt, to pay taxes and eventually to finance all or a part of its investment.
The indirect effects are the economic impacts that arise through business to business interactions throughout the supply chain.
Induced Impacts
Induced effects are the economic activity created through increased spending of those workers receiving incomes from franchises They can also occur due to reinvestment of business profits to expand capacity or replace depreciated capital stock. These purchases or activities can lead to further employment, wages, income, and tax revenue that reverberate throughout different industries.
Systems approach
System effects
Taxation Revenue
CANCEA’s cutting-edge and innovative “big data” computer simulation platform that incorporates social, health, economic, financial, and infrastructure factors in an agent-based system
The belief that in complex systems, the whole is not equal to the sum of its parts. Such an approach requires the understanding that different combinations of assets can have different values for agents and that agents have different constraints and desires, and cannot be treated as aggregates.
Impacts that transcend direct, indirect and induced effects, which are not traditionally measured by economics. These impacts arise from the relationship between every economic agent and the environment in which they operate, as they influence one another’s states and behaviours.
The tax collected by the provincial and federal governments and is made up of income, consumption, and corporate taxes.
The economic forecast of the Canadian franchise industry was conducted using CANCEA’s Prosperity at Risk® platform. Using over 170 tables from Statistics Canada, including Statistics Canada input -output data (I/O), and over 58,000 Canadian Census dissemination areas, the Prosperity at Risk® platform takes into account the demand and supply of commodities across industry sectors and unifies it with demographics, labour force dynamics, government finances, private capital investm ent, and the interdependencies of production to allow for the Canadian franchises to be quantified and forecasted.
As the Prosperity at Risk® platform is an agent -based, event-driven microsimulation platform, it is capable of capturing the direct, indirect, and induced contributions, as well as identifying the contribution at different regional levels. By incorporating household behaviour, industry and firm behavio ur, and federal and provincial tax rates, Prosperity at Risk® is capable of providing the economic impact across different economic indicators such as GDP (real and nominal), employment, wages, government reve nue, and household income. Furthermore, Prosperity at Risk® also captures the “system impacts”, which consider the broader impact of franchises
In addition to internal model validation, the output from the Prosperity at Risk® platform is regularly tested against the results of other models. Cross model validation ensures Prosperity at Risk® is producing baselines that are in accordance with other models Key models include:
• Public sector forecasts including Ontario Ministry of Finance (e.g., population and GDP) ; and
• Private-sector forecasts including major Canadian banks
For more information on the Prosperity at Risk® platform and its applications, please refe r to CANCEA (2017)
Bank of Canada. 2023. October 2023 Monetary Policy Report. Bank of Canada.
Canadian Franchise Association. 2017. Franchising in Canada: Policy Briefing. Toronto: Canadian Franchise Association.
CFA. 2017. "Franchising Research and Facts." Canadian Franchise Association. https://www.cfa.ca/newsabout-cfa-members/franchise -research-facts/.
Frazer, L., S. Weaven, A. Grace, and S. Selvanathan. 2016. Franchising Australia 2016. Griffith Business School.
Heintz, J., R. Polin, and H. Garrett-Peltier. 2009. How Infrastructure Investments Support the U.S. Economy: employment, productivity and growth. Political Economy Research Institute, University of Massachusetts Amherst.
International Trade Administration. 2016. 2016 Top Markets Report: Franchising. U.S. Department of Commerce.
PWC. 2016. The Economic Impact of Franchised Businesses: Vollume IV, 2016. Price Waterhouse Cooper.
The Canadian Centre for Economic Analysis. 2016. "The Economic Impact of Canadian P3 Projects: Why building infrastructure 'on time' matters."
The Canadian Centre for Economic Analysis. 2017. Understanding the forces driving the shelter affordability issue: A linked-path assessment of housing market dynamics in Ontario and the GTHA. The Canadian Centre for Economic Analysis.