
National Country Agency Team
Market Update
Summer 2026
A prime residential market update
This early summer market shows quality properties still generating strong interest, while assets with compromises in location, presentation, or overpricing are slower to sell. Matthew Allen, Partner and Head of National Country Agency Team (NCAT), explains that buyers remain active but have become more selective and value-focused.
Is there still a ‘race for space’?
Yes, but it has evolved. The post-pandemic “more space at any cost” mindset has been replaced by a location- and lifestyle-led search where “best in class” is the clear winner. Prime areas such as the Cotswolds, Cheshire and established commuter pockets across the Midlands have held firm, underpinned by long-term scarcity and enduring desirability.
What does today’s prime buyer want?
In today’s market, buyers are overwhelmingly gravitating towards finished, turnkey homes. Larger farmhouses and country properties that need significant improvement are less favoured, not because the appetite for character has gone, but because the unknowns around cost, contractors and timeframes feel harder to justify. By contrast, superb modern homes with strong eco-efficiency credentials, in the right location, continue to attract genuine demand. Homeworking space remains important, but it’s increasingly viewed as part of a complete lifestyle package alongside gyms, outdoor living and practical day-to-day flow.
London equity and the pull of the commute London is still in a recovery phase, and that matters because confidence and equity released in the capital
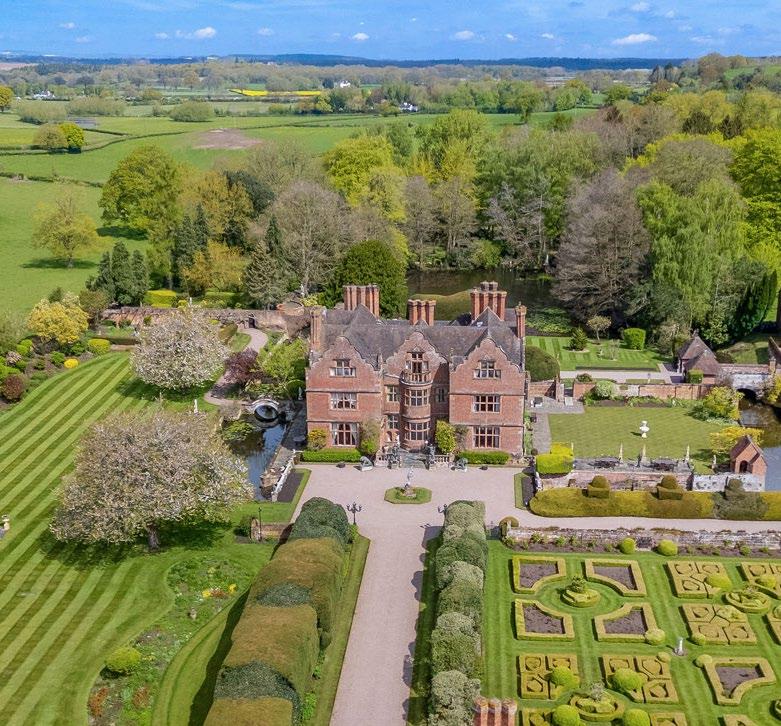
FOR SALE
Ludstone Hall
Claverley, Shropshire
Guide price | £3,950,000
typically filters into the country market. Hybrid working remains a factor, but there is now greater pressure for London-based movers to be at their desk in the City more often. The result is a renewed focus on homes that remain within striking distance of a daily commute, particularly across the Home Counties, whereas more remote relocations are facing tougher scrutiny unless the property is exceptional.
Is there enough quality stock at the top end?
Stock levels have risen during the spring and early summer market, but that supply includes some country houses that failed to sell last year. That makes pricing absolutely critical. There remains a gap between some vendor expectations and where buyers are prepared to position themselves, and it is often the more motivated or “forced” seller who ultimately must compromise. Correctly priced properties still transact well; over-ambitious pricing can quickly turn a great house into stale stock.
The Farmland MarketInsights and outlook
In 2025, the English farmland market saw an 8% fall in supply compared with 2024, although the 90,000 acres marketed remained high by recent historic standards. Farmers continued as the dominant buyer type, accounting for around 60% of all purchasers, while private investors and institutional demand softened. Values were broadly steady but slightly weaker overall, with average arable land falling around 4% and pastureland around 2%, though performance varied significantly by region, quality and land type. Smaller amenity holdings and high-quality commercial farms remained especially resilient, while uncertainty around tax reliefs, subsidy changes and business planning influenced both buyer and seller behaviour.
Looking ahead
We expect supply to continue to rise moderately throughout 2026, bringing supply at the end of H1 in line with, or above, the same period last year.
The reopening of the 2026 Sustainable Farming Incentive (SFI) is likely to have more impact on buyer demand than on supply. Those already planning to sell are unlikely to change course as a result.
The partial late-2025 U-turn on Agricultural Property Relief (APR) and Business Relief (BR) may lead some small and medium-sized operators to delay selling where this liability was a key factor in their decision. However, we believe the number of parties affected is very small.
Buyers
We expect the profile of farmland buyers in the remainder of 2026 to stay broadly similar to 2025, although farmer demand may increase due to more favourable APR thresholds and a stronger outlook for environmental scheme payments.
Corporate and private investor demand is expected to continue, particularly for carbon investment, offsetting and rewilding. Although these buyers make up only a small share of the market, their activity can still influence both demand and values.
Institutional and charity buyers are also likely to remain active, focusing on strategic holdings, longer-term tenanted opportunities with reversionary potential, and mixed-use assets that are not solely dependent on agricultural returns.
Traditional farmer buyers are likely to focus on local and neighbouring properties that offer expansion potential. However, input cost pressures, succession challenges and steady interest rates may make borrowing less attractive for some.
Vendors
We expect little change in the vendor profile in the remainder of 2026. Institutional sales may increase as lowyielding assets with liabilities are traded for more strategic holdings.
Farmers will remain the main vendor group.
Values
Our short-term outlook for farmland values remains firm, although transaction volumes in H1 2026 are likely to be limited, with most sales expected to complete in H2.
We expect arable and pastureland values to remain broadly firm, supported by the anticipated reopening of the SFI scheme and the reassurance that support will be available to help offset existing pressures.
Strategically located sites with long-term planning potential will continue to attract keen interest and strong values.
Trusted advisors and agents to some of the finest country houses, farms and estates across the UK. For more information, or to source exceptional propertiesboth on and off market - please contact a member of the team.
View our National Country Agency team brochure here
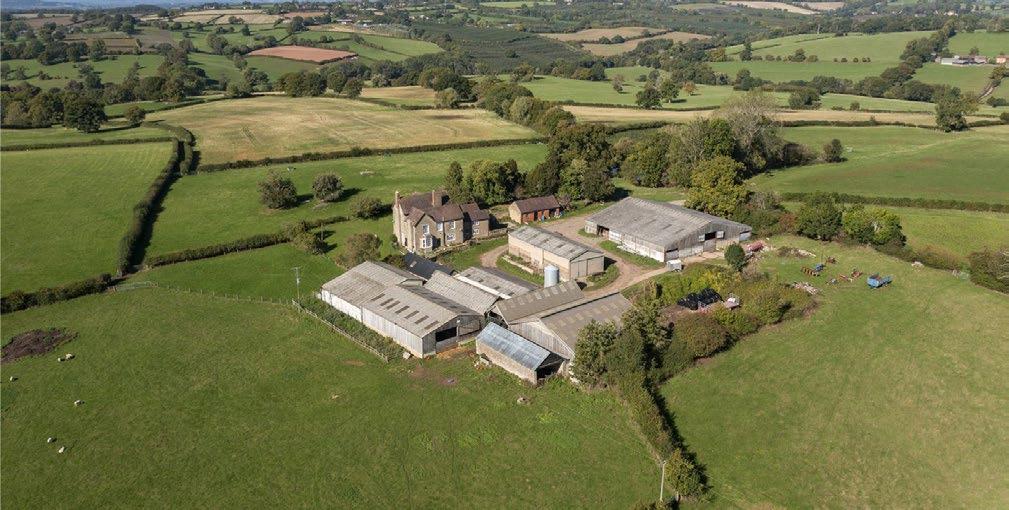
Cradley, Herefordshire Hill Farm
A beautifully situated vacant farm extending to about 617.40 acres (249.85 hectares). Available as a whole or in two lots.
Guide price | £6,650,000
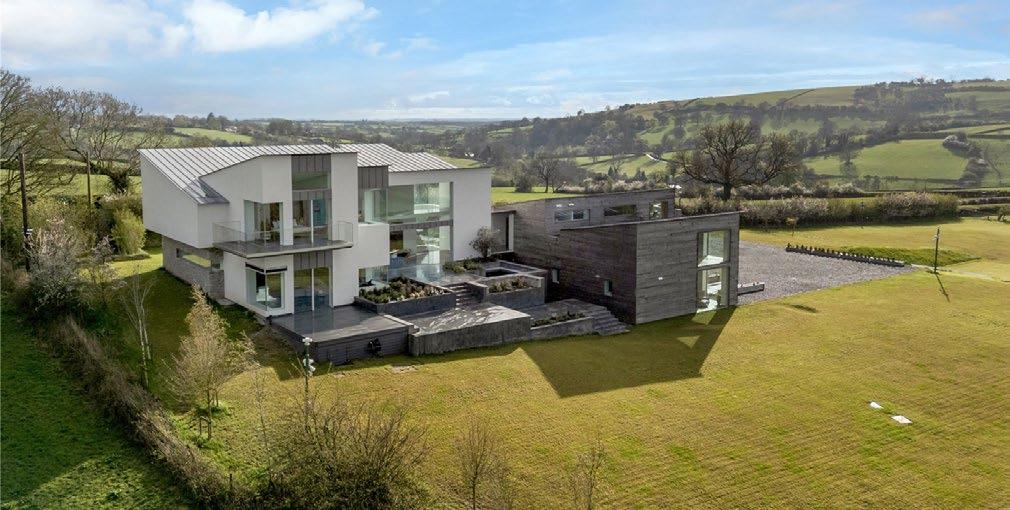
Derbyshire Goodacres
SALE Guide price | £6,000,000 A truly exceptional contemporary house with incredible views.
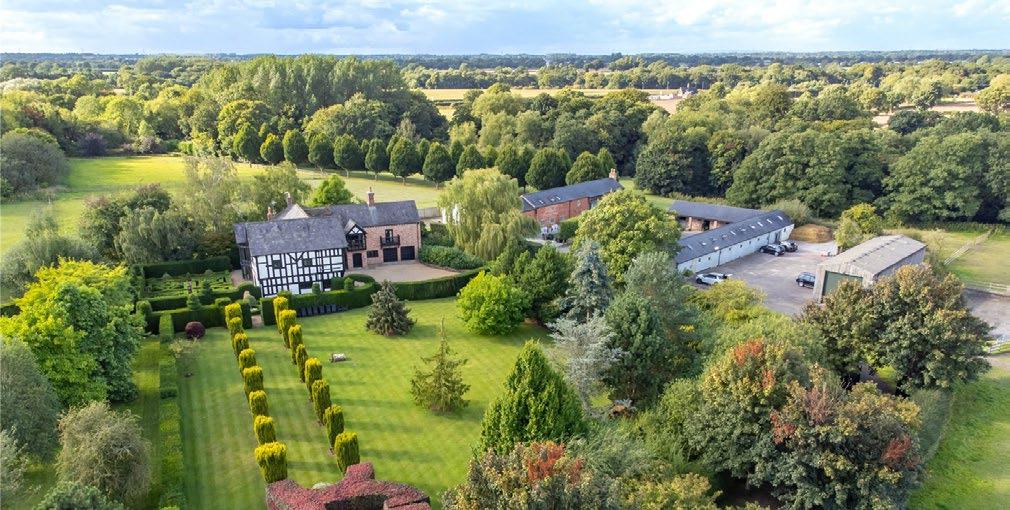
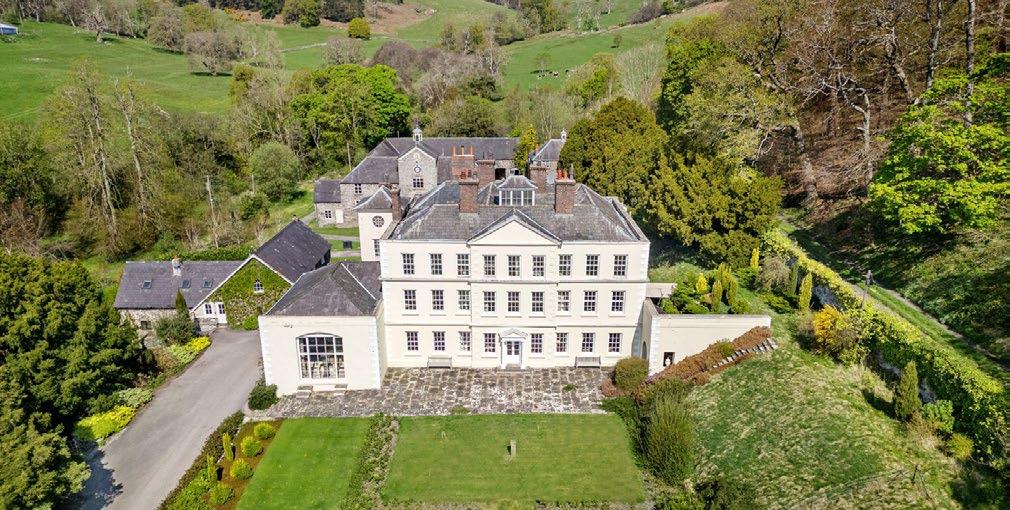
Guide price | £5,000,000 A magnificent country estate featuring a historic moat hall and beautifully restored Mill House in approximately 125 acres. Knutsford, Cheshire
Conwy
Guide price | £4,500,000 A charming 507 acre country estate in a tremendous setting above the Elwy River Valley.
Ashbourne,
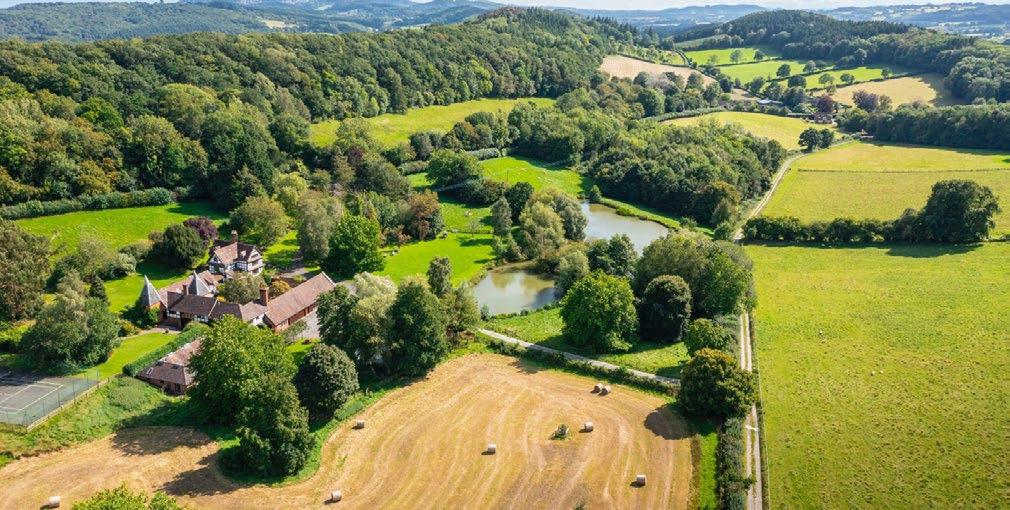
The Baston Hall Estate FOR SALE
Alfrick, Worcestershire
A picturesque country estate surrounded by rolling meadows and mature woodland, offering a setting of natural beauty and tranquillity.
Guide price | £4,250,000
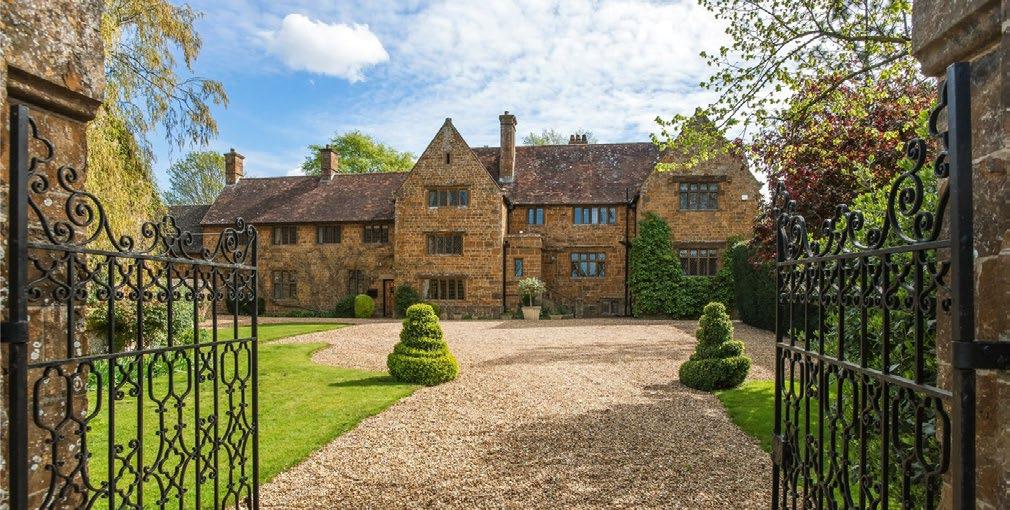
Northend Manor FOR SALE
Little Dassett, Warwickshire
An historic Manor House and substantial cottage set amidst beautiful grounds of about 14 acres.
Guide price | £2,950,000
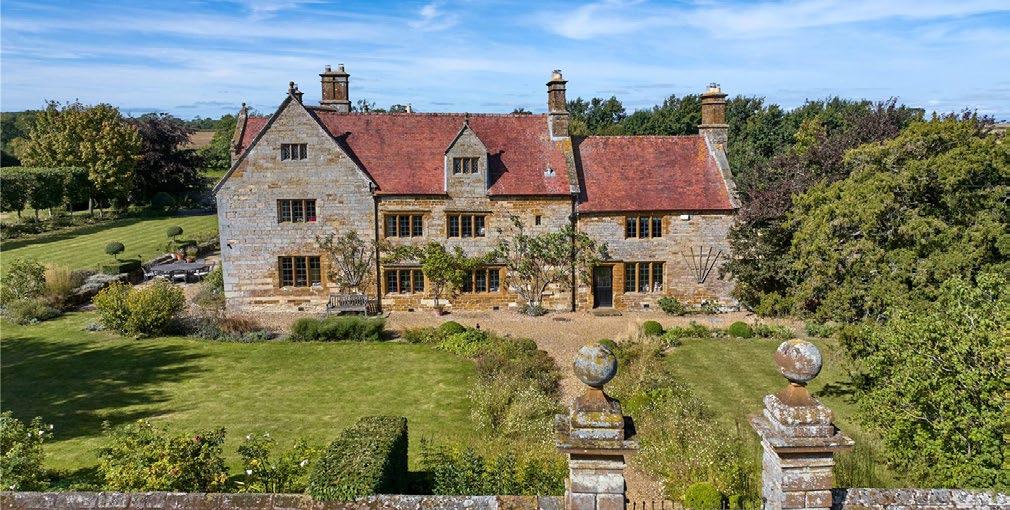
The Manor FOR SALE
Plumpton, South Northamptonshire
A beautiful rural Manor house situated in unspoilt undulating South Northamptonshire countryside.
Guide price | £3,250,000
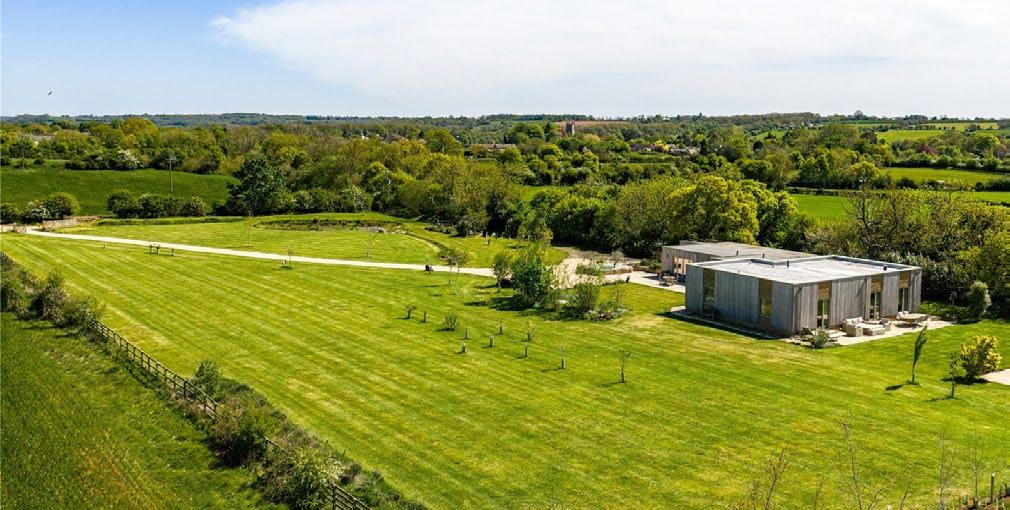
Radbourne House FOR SALE
Hook Norton, Oxfordshire
A stunning modern country property completed to the highest specification.
Guide price | £2,950,000
Get in touch on 0207 870 7799 or ncat@fishergerman.co.uk or by using the contact
Matthew Allen MRICS FAAV
Head of National Country Agency Team 07810 378190
matthew.allen@fishergerman.co.uk
Alasdair Dunne
Head of Rural and Residential Sales 07501 720412
alasdair.dunne@fishergerman.co.uk
Richard Gadd MRICS FAAV
Head of Farm Agency 07966 481487
richard.gadd@fishergerman.co.uk
Stuart Flint MRICS
London and Country 07501 720422
stuart.flint@fishergerman.co.uk