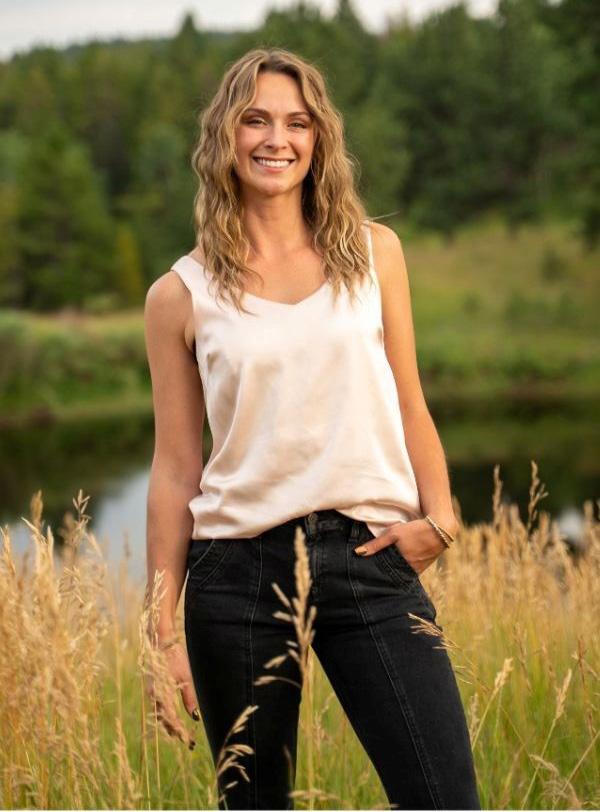
CORINNE PLAYFAIR IS A COLORADO REALTOR SPECIALIZING IN DISTINCTIVE MOUNTAIN, FOOTHILLS, AND LIFESTYLE PROPERTIES THROUGHOUT EVERGREEN, CONIFER GOLDEN, AND THE GREATER DENVER METRO & FOOTHILLS AREA. KNOWN FOR HER HIGHLY PERSONALIZED APPROACH, STRATEGIC MARKETING, AND EYE FOR PRESENTATION AND DESIGN, CORINNE IS PASSIONATE ABOUT HELPING CLIENTS SHOWCASE AND SELL HOMES IN A WAY THAT FEELS ELEVATED, AUTHENTIC, AND EMOTIONALLY COMPELLING.
WITH A BACKGROUND BUILT ON RELATIONSHIP-DRIVEN BUSINESS AND CREATIVE MARKETING, SHE BRINGS A THOUGHTFUL BALANCE OF PROFESSIONALISM, NEGOTIATION SKILL, AND GENUINE CARE TO EVERY TRANSACTION. WHETHER REPRESENTING LUXURY RETREATS, RANCH PROPERTIES, OR UNIQUE HOMES WITH CHARACTER, CORINNE IS DEDICATED TO CREATING EXCEPTIONAL EXPERIENCES AND RESULTS FOR HER CLIENTS.
DISCLAIMER
This Homebook is provided “as is” without warranty of any kind, either express or implied, including without limitations any warrantees of merchantability or fitness for a particular purpose. There is no representation of warranty that this information is complete or free from error, and the provider does not assume, and expressly disclaims, any liability to any person or entity for loss or damage caused by errors or omissions in this book.
The information contained in the REiSource report is delivered from your First American Title Insurance Company, who reminds you that you have the right as a consumer to compare fees and serviced levels for Title, Escrow, and all other services associated with property ownership, and to select providers accordingly. Your home is the largest investment you will make in your lifetime and you should demand the very best.
First American, the eagle logo, First American Title, and firstam.com are registered trade-marks or trademarks of First American Financial Corporation and/or its affiliates.
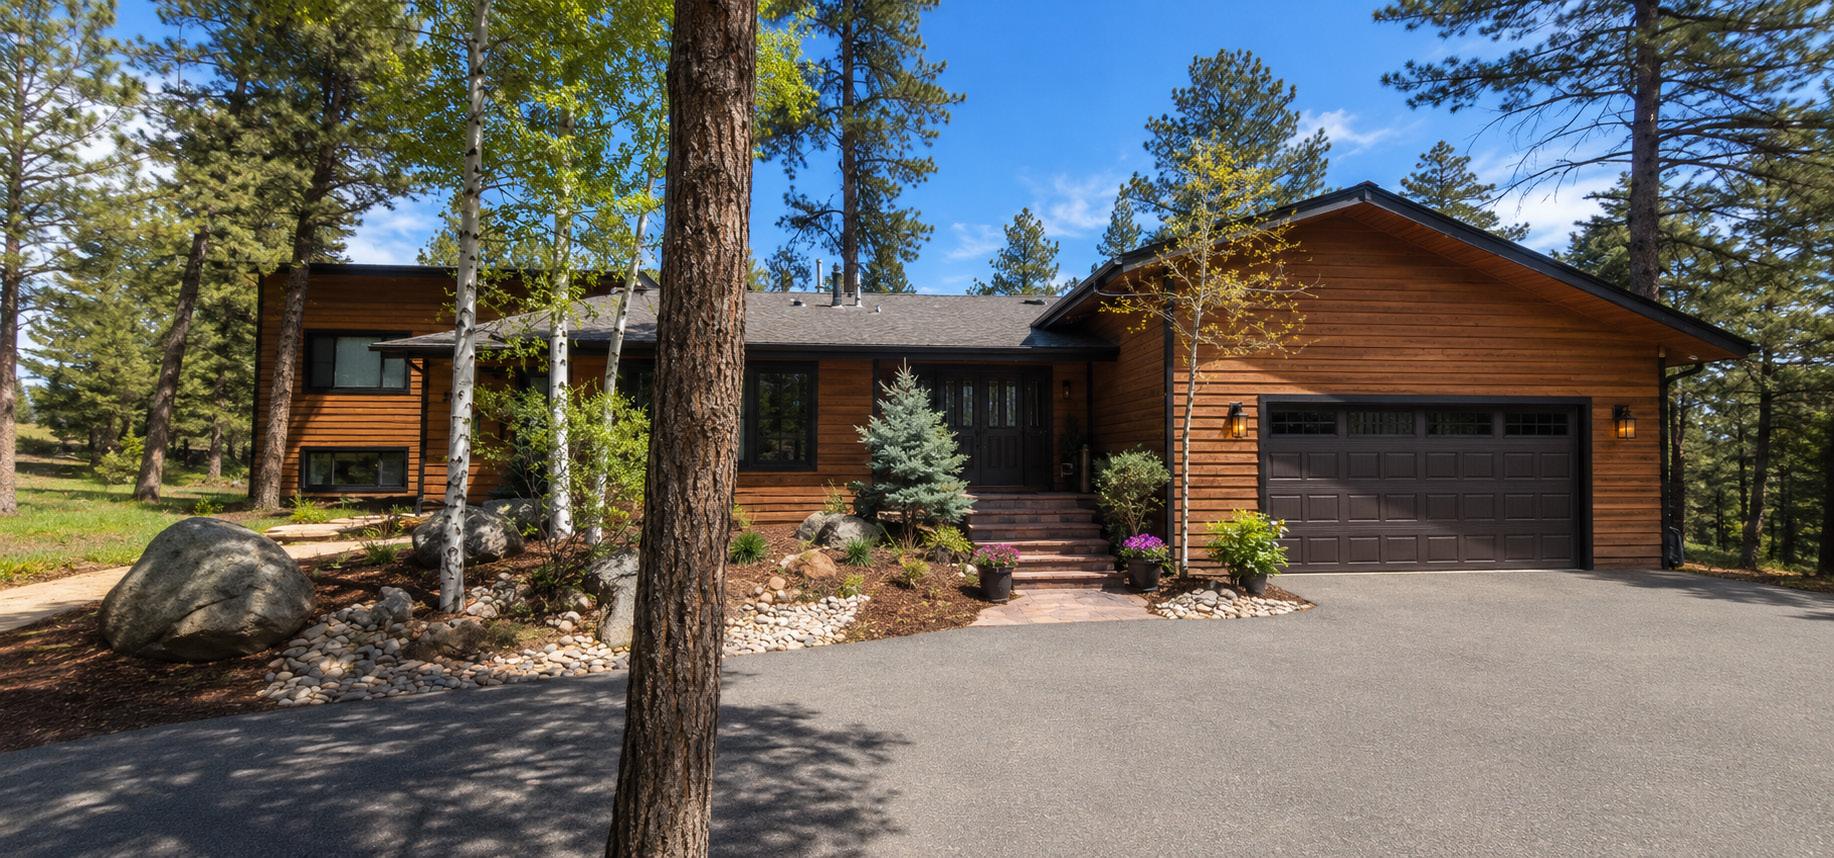
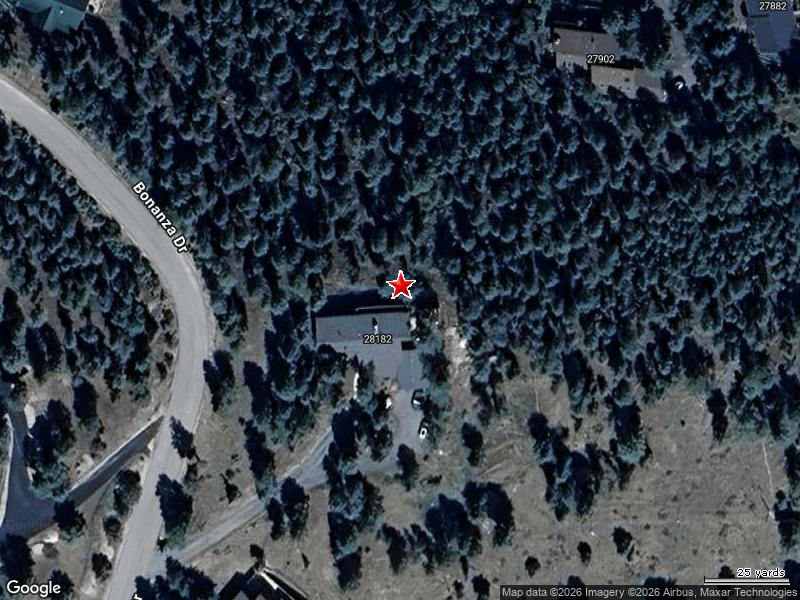
Subject Property : 28182 Bonanza Dr Evergreen CO 80439
Owner Information
Owner Name : Redel-gomez Angela
Mailing Address : 28182 Bonanza Dr, Evergreen CO 80439-6389 R062
Owner Occupied Indicator : O
Location Information
Legal Description : Section 03 Township 06 Range 71 Qtr Se Subdivisioncd 772400 Subdivisionname
Valley Hi Ranch Estates Flg 1 Block 003 Lot 0011 Size: 45259 Tract Value: 1.039
Section 03 Township 06 Range 71 Qtr Se Subdivisioncd 772400 Subdivisionname
Valley Hi Ranch Estates Flg 1 Block 003 Lot 0012 Size: 44431 Tract Value: 1.020
Sale Price : $1,067,000 1st Mtg Document # : 17571
Document # : 17570 1st Mtg Term : 30
Deed Type : Personal Representative's Deed
Title Company : Heritage Title Co.
Lender : * Other Institutional Lenders
Seller Name : Stockholm Dorothy L
Prior Sale Information
Prior Rec/Sale Date : 03/30/1999 / 02/26/1999
Prior Sale Price : $293,500
Prior Doc Number : F0835208
Price Per SqFt : $287.14
Prior Deed Type : Warranty Deed
Prior Lender : Norwest Mtg Inc
Prior 1st Mtg Amt/Type : $234,800 / Conv
Customer Name : De Anna Harwood
Customer Company Name : First American Title Prepared On : 05/28/2026
Property Characteristics
Gross Area : 4,341
Living Area : 3,716
Tot Adj Area : 3,716
Above Grade : 3716
Bedrooms : 5
Bath(F/H) : 4 / 1
Property Information
Land Use : Sfr
Zoning : A-1
Lot Acres : 2.06
Tax Information
Total Value : $1,080,437
Total Taxable Value : $67,528
Fireplace : Y / 2
Year Built / Eff : 1971 / 1987
Parking Type : Attached Garage
Garage Area : 625
Construction : Wood
Lot Size : 89,690
Heat Type : Forced Air
Cooling Type : Forced Air
Patio Type : Deck
Style : Split Level
Quality : Average
Sewer Type : Type Unknown
Water Type : Type Unknown State Use : Improved Resid Land
Tax : $6,214.56
Owner Name : Johnson Patrick W
Sale Date : 04/23/2004
Total Value : $157,015
Land Use : Sfr
Subdivision : Valley Hi Ranch Estates Flg 1
Owner Name : Johnson Patrick W
Value : $823,735
Recording Date : 04/30/2004
Price : $52,500
Tax : $903.14
Acres : 0.99
208423
Date : 09/27/1983
Price : $132,500 Bed / Bath : 3 / 3
Tax : $4,162.80 Land Use : Sfr
Yr Blt / Eff Yr Blt : 1983 / 1986
Subdivision : Valley Hi Ranch Estates Flg 2
Owner Name : Buskirk Nicholas David
Sale Date : 04/28/2022
Acres : 1.56
Area : 3,008
089442
Recording Date : 04/03/2025
Total Value : $990,676 Sale Price : $1,050,000
Bed / Bath : 3 / 4 Property Tax : $5,698.22
Land Use : Sfr Lot Acres : 1.00
Stories : 2
Yr Blt / Eff Yr Blt : 1994 / 2002
Living Area : 2,103
APN : 077663
28151 BONANZA DR Distance 0.06 Miles
Owner Name : Jackson Garry R
Total Value : $995,948
Recording Date : 08/27/1985
Sale Price : $159,900
Bed / Bath : 3 / 2 Property Tax : $5,153.36
Land Use : Sfr
Stories : 1
Yr Blt / Eff Yr Blt : 1969 / 1976
Subdivision : Valley Hi Ranch Estates Flg 1
Acres : 2.06
Living Area : 1,722
APN : 073244
Customer Name : De Anna Harwood
Customer Company Name : First American Title Prepared On : 05/28/2026
2026 CoreLogic. All
27882 BONANZA DR
Owner Name : Smith Clark Subdivision : Valley Hi Ranch Estates Flg 2
Sale Date : 12/29/2023
Recording Date : 01/02/2024
Total Value : $936,807 Sale Price : $850,000
Bed / Bath : 3 / 3
Land Use : Sfr
Stories : 1
Yr Blt / Eff Yr Blt : 1994 / 1995
Tax : $5,388.38
Acres : 1.15
Area : 1,845
089443
Owner Name : Shantz Stephanie Rae Subdivision : Valley Hi Ranch Estates Flg 1
Sale Date : 09/25/2023
Total Value : $1,052,357
Bed / Bath : 3 / 3
Land Use : Sfr
Stories : 1
Recording Date : 09/25/2023
Price : $900,000
Tax : $6,053.04
Acres : 1.00
Area : 1,847 Yr Blt / Eff Yr Blt : 1998 / 2002
077666 28232 BONANZA DR Distance 0.07 Miles
Owner Name : Castan Pedro Camacho
Sale Date : 09/28/2021
Total Value : $812,538
Bed / Bath : 4 / 4
Land Use : Sfr
Stories : 2
Subdivision : Valley Hi Ranch Estates Flg 1
Recording Date : 09/28/2021
Price : $720,000
Tax : $4,673.62
Acres : 1.00
Area : 1,517
Yr Blt / Eff Yr Blt : 1990 / 1995 APN : 077662 Customer Name : De Anna Harwood
Company Name : First American Title Prepared On : 05/28/2026
Owner Name : Hartland Christopher J
Sale Date : 12/07/2001
Subdivision : Valley Hi Ranch Estates Flg 2 Amd 3
Recording Date : 01/02/2002
Total Value : $897,057 Sale Price : $355,000
Bed / Bath : 3 / 5
Land Use : Sfr
Stories : 2
Blt / Eff Yr Blt : 1998 / 1998
Owner Name : Building Solutions Llc
Tax : $5,159.72
Acres : 1.48
Area : 2,161
446213
Recording Date : 12/11/2025
Sale Date : 12/02/2025 Sale Price : $380,000 Total Value : $327,063
Land Use : Sfr
Subdivision : Valley Hi Ranch Estates Flg 1
Owner Name : Brekke Marlyce A
Sale Date : 09/17/2004
Tax : $1,881.18
Acres : 1.02
073731
Subdivision : Valley Hi Ranch Estates Flg 2
Recording Date : 09/21/2004
Total Value : $772,806 Sale Price : $381,500
Bed / Bath : 3 / 3
Land Use : Sfr
Tax : $3,869.86
Acres : 1.05
Stories : 2 Living Area : 1,751
Yr Blt / Eff Yr Blt : 1992 / 1992
089470 Customer Name : De Anna Harwood Customer Company Name : First American Title Prepared On : 05/28/2026
Census Tract / block: 120.31 / 3 Year: 2020
COLORADO Denver Metro
SPORTS:
DENVER BRONCOS BRONCOS PARK POWERED BY COMMONSPIRIT
13655 Broncos Parkway Englewood, CO 80112 (303) 649-9000 denverbroncos.com
COLORADO AVALANCHE
BALL ARENA
1000 Chopper Cir Denver, CO 80204 (303) 405-1100 nhl.com/avalanche
COLORADO ROCKIES COORS FIELD
2001 Blake St Denver, CO 80205 (303) 292-0200 mlb.com/rockies
DENVER NUGGETS
BALL ARENA
1000 Chopper Circle Denver, CO 80204 (303) 405-1100 nba.com/nuggets
COLORADO RAPIDS
DICK’S SPORTING GOODS PARK
6000 Victory Way Commerce City, CO 80022 (303) 825-4625 coloradorapids.com
COLORADO MAMMOTH
BALL ARENA
1000 Chopper Circle Denver, CO 80204 (303) 405-1101 coloradomammoth.com
PARKS & RECREATION:
CITY PARK
Location: East of downtown Denver, near E. 17th Ave., York St., Colorado Blvd. and E. 23rd Ave.
City Park is Denver’s largest urban park, with more than 300 acres of lawns, lakes, walking paths, athletic fields, tennis courts, event space and major cultural attractions. The park is home to the Denver Zoo and the Denver Museum of Nature & Science, with Ferril Lake, flower gardens, monuments, picnic areas and some of the city’s best skyline-and-mountain views. City Park Golf Course remains a public urban course with views of downtown and the mountains.
City Park Jazz continues as a beloved free summer concert series. For 2026, the posted schedule runs Sunday evenings from June 7 through Aug. 9, though staging and seating may shift because the historic bandstand was damaged by fire. Definitely check the current schedule before publishing exact event details.
SKYLINE PARK
Location: Along Arapahoe Street between 15th and 18th streets in downtown Denver.
Skyline Park is downtown Denver’s three-block urban park along Arapahoe Street. It is currently being reimagined as a more active, accessible public space for residents, workers, students and visitors. Block 1, between 15th and 16th streets, reopened in 2025 with a Street Soccer USA synthetic turf field for drop-in play when not reserved for programming. Block 2, between 16th and 17th streets, is under construction as of February 2026, with completion anticipated in spring 2027.
CIVIC CENTER PARK
Address: 101 14th Ave., Denver, CO 80204
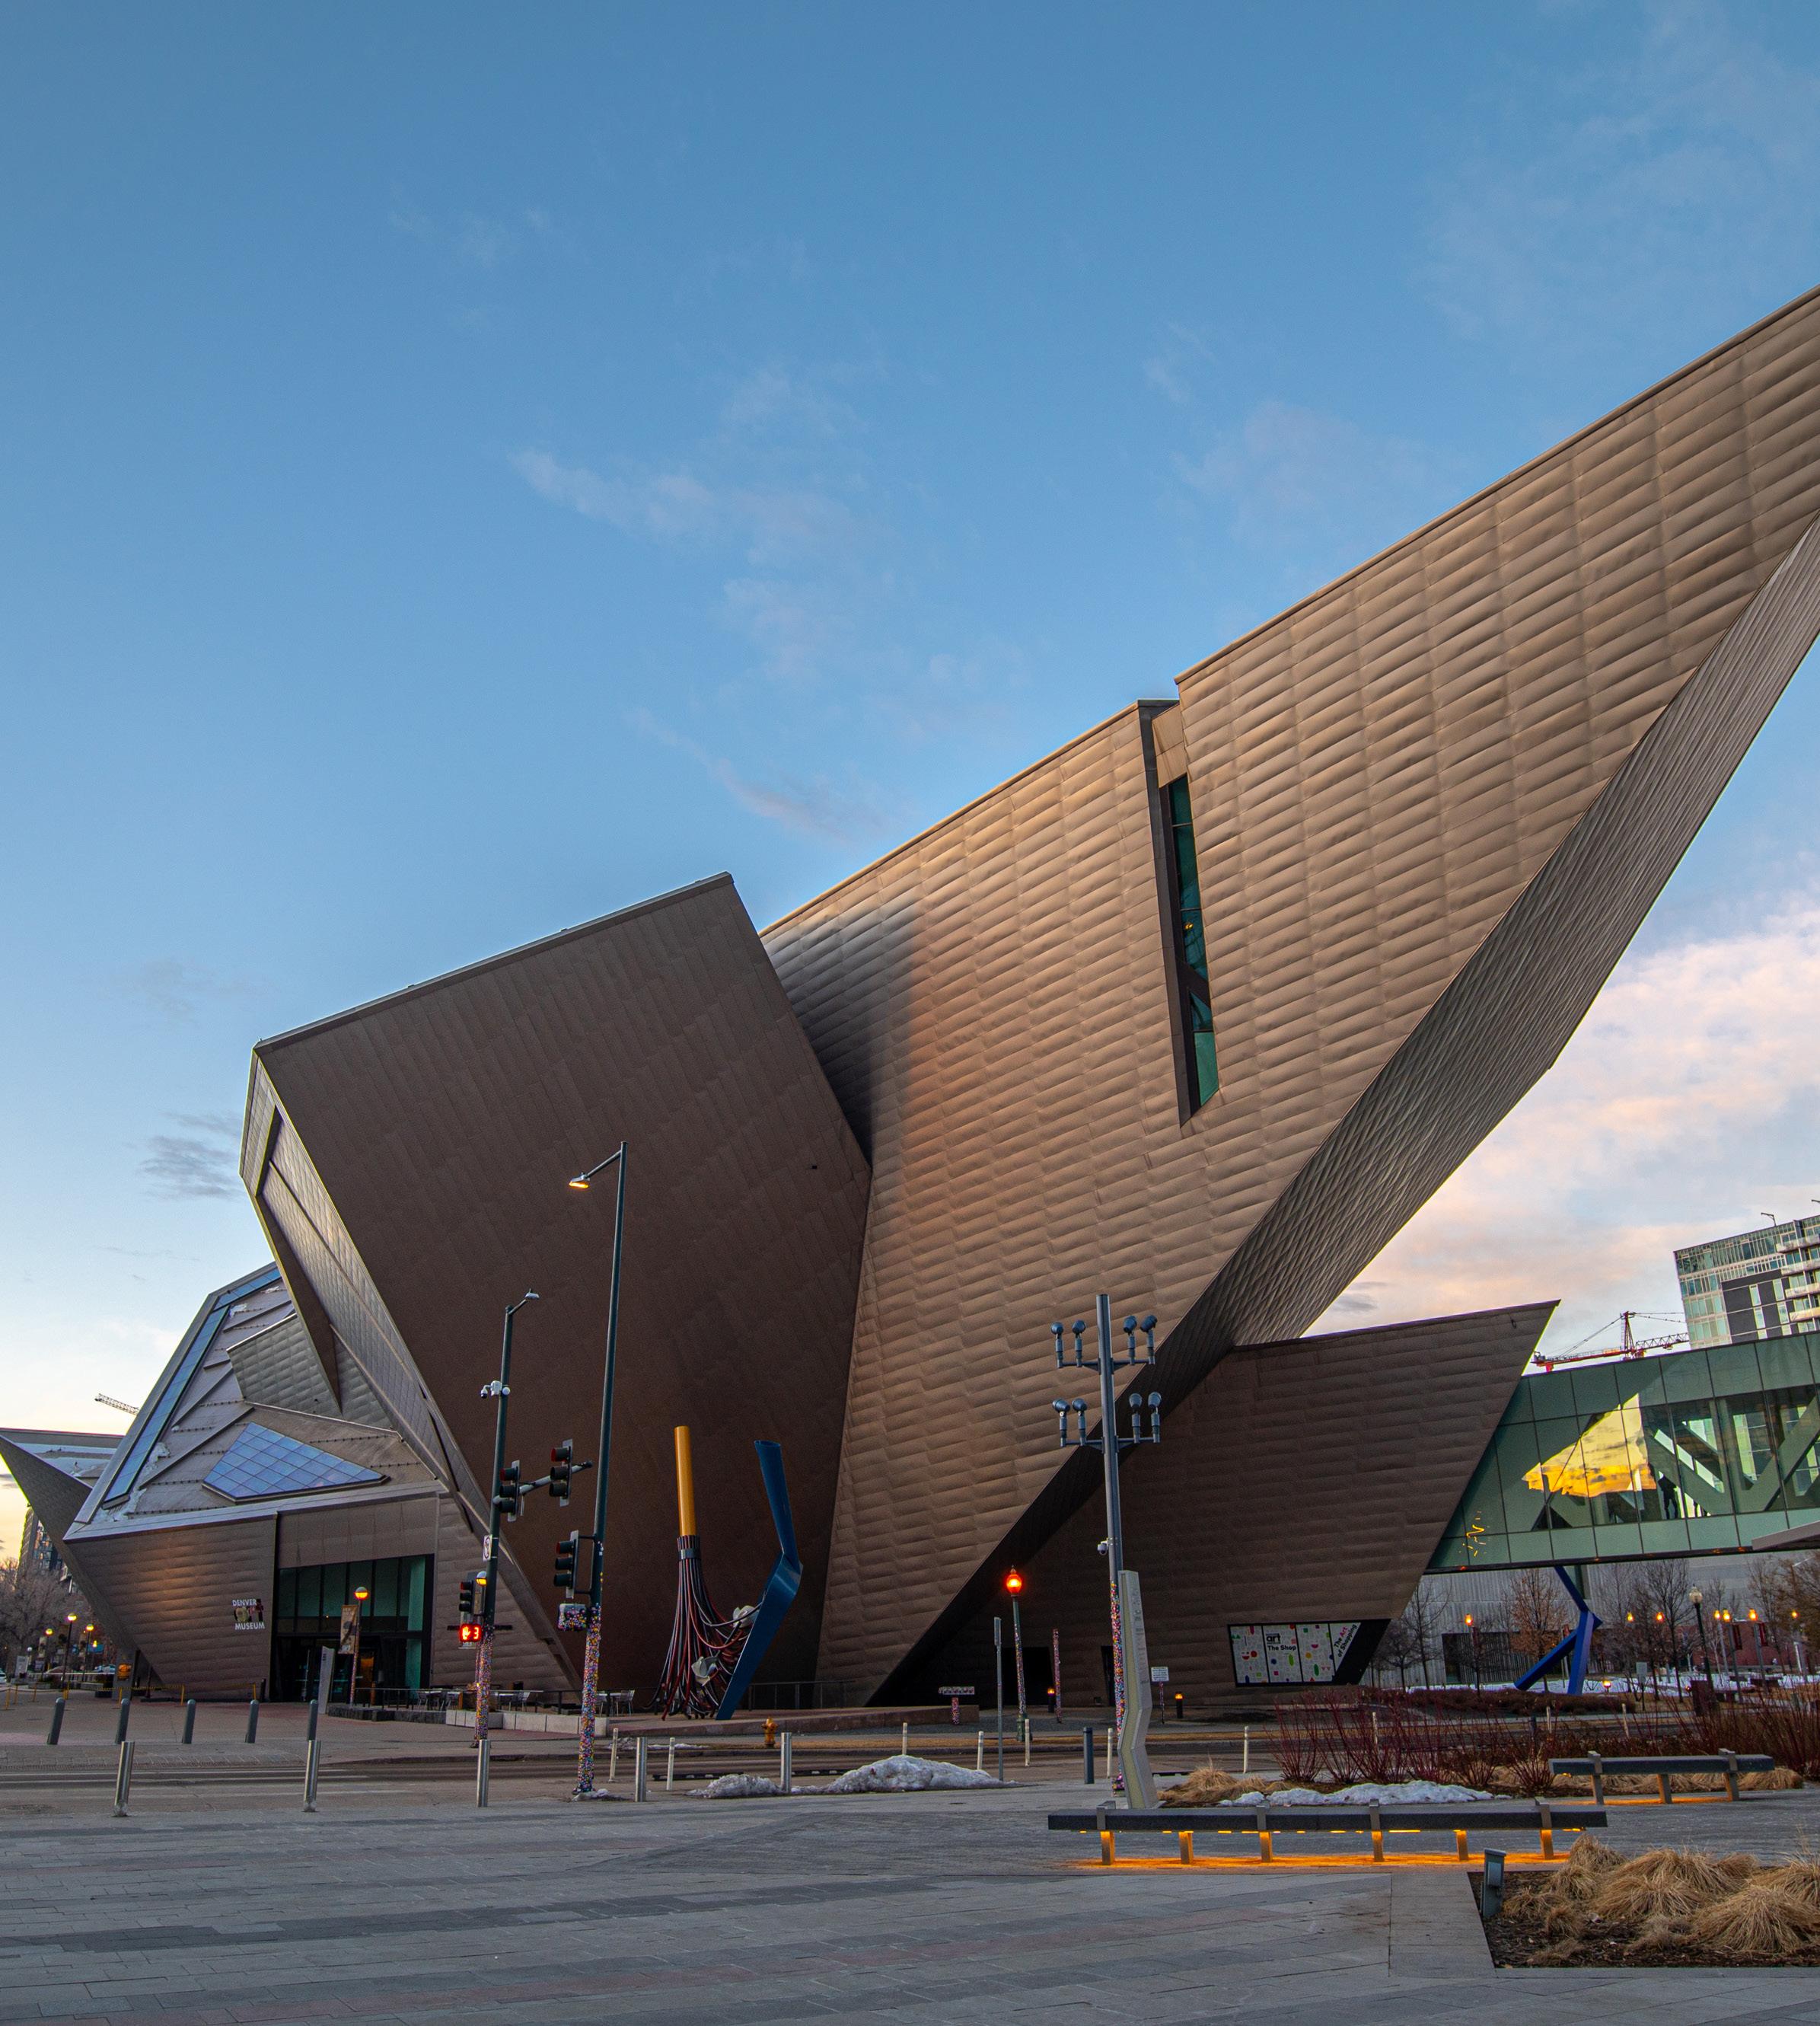
Civic Center Park remains Denver’s grand civic gathering space, known for its history, architecture, public art, gardens, events and central downtown location near the Colorado State Capitol, City and County Building, Denver Art Museum and Denver Central Library.
Important update: Civic Center Park is under major construction. Phase One of the Civic Center Next 100 project began in November 2025, with completion scheduled for summer 2027. Limited portions of the park remain open, but large events are affected during construction. Civic Center EATS is still active in 2026, scheduled Wednesdays and Thursdays from mid-May through mid-October on Bannock Street and the Civic Center Park Meadow.
CONFLUENCE PARK
Address: 2250 15th St., Denver, CO 80202
Confluence Park sits where Cherry Creek meets the South Platte River, near Lower Downtown and the REI flagship store. The area is considered part of Denver’s birthplace, with the confluence tied to the city’s 1858 origins. Today, it’s a popular urban riverfront park for walking, biking, kayaking, relaxing along the water and taking in downtown views.
COLORADO Denver Metro
ARTS & ENTERTAINMENT:
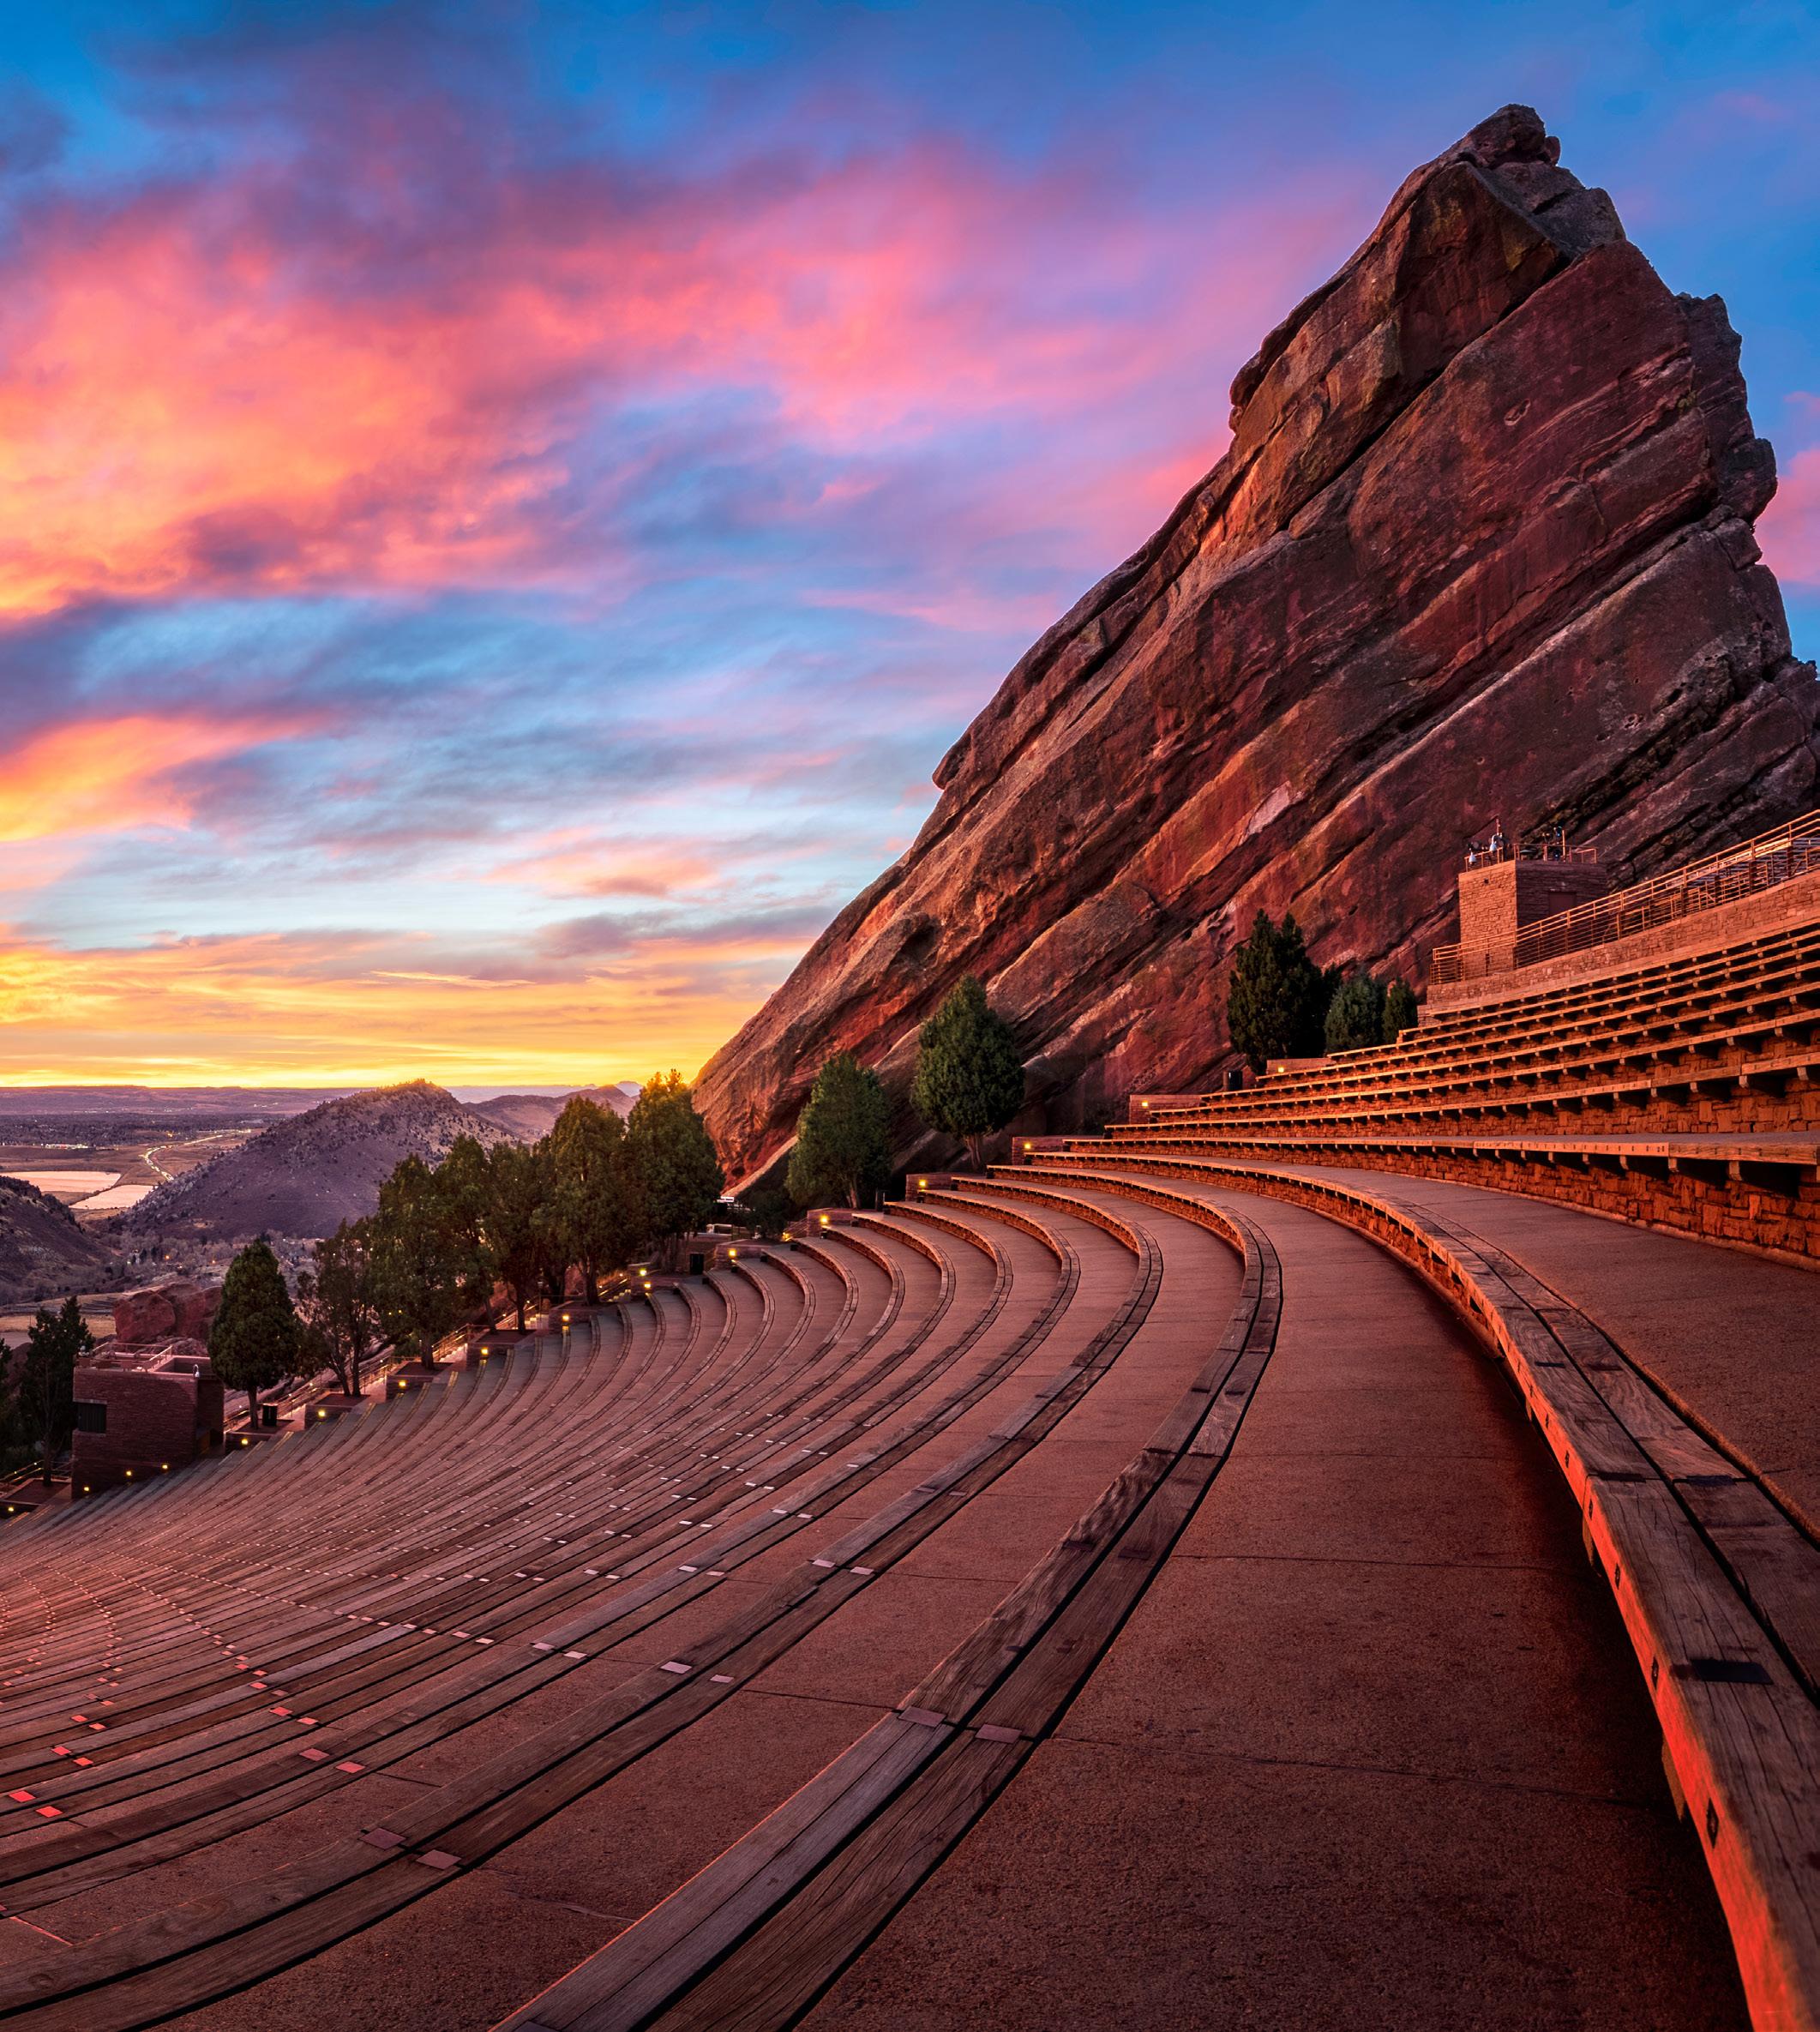
RED ROCKS PARK AND AMPHITHEATRE
18300 W Alameda Pkwy Morrison, CO 80465 (720) 865-2494 redrocksonline.com
ELITCH GARDENS THEME & WATER PARK
2000 Elitch Cir. Denver, CO 80204 (303) 595-4386 elitchgardens.com
WATER WORLD
8801 N. Pecos Street Federal Heights, CO 80260 (303) 427-7873 waterworldcolorado.com
CASA BONITA (RESTAURANT)
6715 W Colfax Ave Lakewood, CO 80214 casabonitadenver.com
MEOW WOLF DENVER: CONVERGENCE STATION 1338 1st St. Denver, CO 80204 (866) 636-9969 meowwolf.com/visit/denver
DENVER BOTANIC GARDENS
1007 York St Denver, CO 80206 (720) 865-3500 botanicgardens.org
HUDSON GARDENS & EVENT CENTER
6115 S Santa Fe Dr Littleton, CO 80120 (303) 797-8565 hudsongardens.org
COLORADO CONVENTION CENTER
700 14th St
Denver, CO 80202 (303) 228-8000 denverconvention.com
AMERICAN MUSEUM OF WESTERN ART – THE ANSCHUTZ COLLECTION 1727 Tremont Place
Denver, CO 80202 (303) 293-2000 anschutzcollection.org
ARVADA CENTER FOR THE ARTS AND HUMANITIES
6901 Wadsworth Blvd Arvada, CO 80003 (720) 898-7200 arvadacenter.org
DENVER CENTER FOR THE PERFORMING ARTS
1101 13th St Denver, CO 80204 Box Office counter: 1301 13th St. Denver, CO 80204 Ticket line: (303) 893-4100 Admin: (303) 893-4000 Website: denvercenter.org (303) 893-4100 denvercenter.org
DENVER MUSEUM OF NATURE & SCIENCE
2001 Colorado Blvd. Denver, CO 80205 (303) 370-6000 dmns.org
CHILDREN’S MUSEUM OF DENVER AT MARSICO CAMPUS
2121 Children’s Museum Dr. Denver, CO 80211 (303) 433-7444 mychildsmuseum.org
DENVER ART MUSEUM
100 W. 14th Ave. Pkwy. Denver, Colorado (720) 865-5000 denverartmuseum.org
SANCTUARIES & ZOOS:
BUTTERFLY PAVILION
(303) 469-5441 6252 W 104th Ave. Westminster, CO 80020 butterflies.org
THE WILD ANIMAL SANCTUARY
2999 County Road 53 Keenesburg, CO 80643 (303) 536-0118 wildanimalsanctuary.org
LUVIN ARMS ANIMAL SANCTUARY
3470 County Road 7 Erie, CO 80516 (720) 515-8577 luvinarms.org
DENVER ZOO CONSERVATION ALLIANCE
2300 N Steele St Denver, CO 80205 (720) 337-1400 denverzoo.org
DOWNTOWN AQUARIUM DENVER
700 Water St Denver, CO 80211 (303) 561-4450
aquariumrestaurants.com
downtownaquariumdenver
COLORADO Denver Metro
Denver
The Mile High City Exciting Things to Do in Denver
With sunny skies, fresh mountain air and adventure in every direction, Denver makes it easy to fill a day — or a whole getaway — with city energy and Colorado views. Set exactly one mile above sea level, the Mile High City blends urban culture with quick access to the Rocky Mountains.
Start outside. Denver offers nearly 20,000 acres of parkland, more than 250 urban parks and about 850 miles of paved, off-street trails for walking and biking. Spend the morning in a city park, cruise along Cherry Creek or the South Platte River, then use Denver as your basecamp for hiking, mountain biking, camping, fly-fishing and scenic day trips.
The city’s creative scene is just as vibrant. Explore major museums, boutique galleries, public art, live music venues and neighborhood art districts filled with color, food and local flavor. From RiNo’s murals to the Art District on Santa Fe, Denver turns a simple stroll into a tiny cultural treasure hunt.
There’s something here for every kind of traveler: romantic rooftops, family-friendly attractions, outdoor adventures, craft food and drink, unforgettable concerts and easy access to the mountains. Whether you’re planning a weekend getaway or a longer Colorado vacation, Denver is ready to be your launchpad.
SCAN CODE to explore more outdoor adventures, food and drink, arts and culture, and career opportunities in Denver.
denver.org/things-to-do
DENVER METRO
Jefferson County
JEFFERSON COUNTY: www.jeffco.us
ELECTED OFFICIALS & PUBLIC OFFICES
ASSESSOR
Scot Kersgaard 303.271.8600
CLERK AND RECORDER
Amanda Gonzalez 303.271.8168
CORONER
Dr. Annette Cannon 303.271.6480
COUNTY COMMISSIONER (DISTRICT 1)
Rachel Zenzinger 303.271.8525
COUNTY COMMISSIONER (DISTRICT 2)
Andy Kerr 303.271.8525
COUNTY COMMISSIONER (DISTRICT 3)
Lesley Dahlkemper303.271.8525
DISTRICT ATTORNEY (1ST JUDICIAL DISTRICT)
Alexis King 303.271.6800
SHERIFF
Reggie Marinelli 303.271.0211
SURVEYOR
Robert Hennessy 303.271.8700
PUBLIC TRUSTEE AND TREASURER
Jerry DiTullio 303-271-8580
JEFFERSON COUNTY COURTHOUSE & GOVERNMENT CENTER:
JEFFERSON COUNTY COMBINED COURT
720.772.2500
100 Jefferson County Pkwy. • Golden, 80401
JEFFERSON COUNTY GOVERNMENT CENTER
303.271.6511
100 Jefferson County Pkwy. • Golden, 80401
JEFFERSON COUNTY
MOTOR VEHICLE:
www.jeffco.us
303.271.8100
ARVADA
6510 Wadsworth Blvd. #320 Arvada, 80003
EVERGREEN
4990 County Hwy 73A Evergreen, 80439
GOLDEN
100 Jefferson County Pkwy #2540 Golden, 80419
LAKEWOOD
2099 Wadsworth Blvd. Ste K Lakewood, 80214
LITTLETON
11139 Bradford Rd. • Littleton, 80127
JEFFERSON COUNTY LIBRARIES: www.jeffcolibrary.org
ARVADA BALSAM TEMPORARY LIBRARY
303.235.5275
5751 Balsam St. • Arvada, CO 80002
ARVADA - Closed for redesign
303.235.5275
7525 W. 57th Ave. • Arvada, 80002
BELMAR
303.235.5275
555 S. Allison Pkwy. • Lakewood, 80226
COLUMBINE
303.235.5275
7706 W. Bowles Ave. • Littleton, 80123
CONIFER
303.235.5275
27122 Main St., #100 • Conifer, CO 80433
EDGEWATER
303.235.5275
1800 Harlan St. • Edgewater, 80214
EVERGREEN
303.235.5275
5000 County Road 73 • Evergreen, 80439
GOLDEN
303.235.5275
1019 10th St. • Golden, 80401
LAKEWOOD
303.235.5275
10200 W. 20th Ave. • Lakewood, 80215
STANDLEY LAKE
303.235.5275
8485 Kipling St. • Arvada, 80005
WHEAT RIDGE
303.235.5275
5475 W. 32nd Ave. • Wheat Ridge, 80212
DENVER METRO
Jefferson County
JEFFERSON COUNTY:
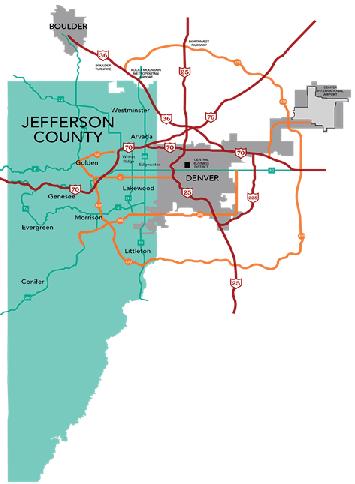
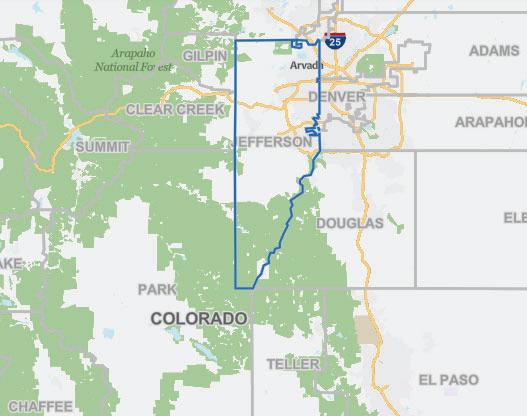
Jefferson County, commonly known as Jeffco, is located in north-central Colorado along the Front Range of the Rocky Mountains, directly west of Denver. The county is part of the Denver-Aurora-Centennial, CO Metropolitan Statistical Area, reflecting the updated federal metro-area naming used in the July 2023 delineations.
As of July 1, 2025, Jefferson County had an estimated population of 580,451, making it one of the most populous counties in Colorado. Golden serves as the county seat, while Lakewood is the county’s largest city.
Known as the “Gateway to the Rocky Mountains,” Jefferson County blends urban convenience with foothills, open space, and mountain access. The nickname Jeffco is widely used throughout the county, including in the names of local schools, agencies, districts, and businesses.
Jefferson County is home to several major institutions and employers, including the Molson Coors Golden Brewery, which traces its roots in Golden to 1873, and the Colorado School of Mines, a public research university focused on science and engineering.
The county also owns and operates Rocky Mountain Metropolitan Airport, formerly known as Jeffco Airport. Founded in 1960, the airport is located in Broomfield and serves as a major general aviation and reliever airport for the Denver metro area.
HISTORY
Jefferson County’s roots reach back to the territorial era. On August 25, 1855, Kansas Territory established Arapahoe County, which included much of what is now eastern Colorado to the Continental Divide. Gold discoveries in the late 1850s helped spark the Colorado Pike’s Peak Gold Rush and brought rapid settlement to the region.
In 1859, residents of the mining region, feeling distant from the governments of Kansas and Nebraska, formed the provisional Territory of Jefferson. On November 28, 1859, the Jefferson Territory legislature organized 12 counties, including Jefferson County. Arapahoe City was originally selected as the first seat of government, and Golden City was later chosen as the county seat in 1860.
Although the Jefferson Territory was never formally recognized by Congress, it helped lay the groundwork for Colorado’s territorial government. Congress created the Territory of Colorado on February 28, 1861, and on November 1, 1861, the first Colorado Territorial Legislature formally established Jefferson County along with 16 other original counties.
Jefferson County was named for Thomas Jefferson, the namesake of the short-lived Jefferson Territory and the third president of the United States. Over time, boundary adjustments, Denver annexations, and the creation of the City and County of Broomfield shaped Jefferson County into its present form.
GEOGRAPHY
Jefferson County covers approximately 774 square miles, including about 764 square miles of land. The county stretches from the urban western edge of the Denver metro area into foothills and mountain communities, giving it a diverse landscape of plains, mesas, canyons, and forested open space.
The county sits along the eastern edge of the Rocky Mountains and includes communities such as Golden, Lakewood, Arvada, Wheat Ridge, Edgewater, Evergreen, Morrison, and portions of Westminster and Littleton. Its location gives residents and visitors quick access to both downtown Denver and the mountain corridor — basically city life with a trailhead in its back pocket.
DENVER METRO
Jefferson County
JEFFERSON COUNTY Cont...
ADJACENT COUNTIES
Boulder County – north
Broomfield County – northeast Adams County – east City and County of Denver – east
Arapahoe County – east Douglas County – east
Teller County – south Park County – southwest Clear Creek County – west Gilpin County – northwest
DEMOGRAPHICS
As of July 1, 2025, Jefferson County had an estimated population of 580,451, making it one of Colorado’s largest counties. The county has about 241,735 households, with an average household size of 2.36 people. Jefferson County’s population is 49.7% female, with 17.7% of residents under age 18 and 18.8% age 65 or older. The county is predominantly White, with 75.9% identifying as White alone, not Hispanic or Latino. Hispanic or Latino residents make up 16.6% of the population, and the county also includes Asian, Black, American Indian, Pacific Islander, multiracial, and other racial groups.
The county is highly educated, with 95.8% of adults age 25 and older holding a high school diploma and 52.0% holding a bachelor’s degree or higher. The median household income is $110,656, and about 7.2% of residents live below the poverty line. Overall, Jefferson County is a large, diverse, and well-educated community with a strong economic base and a mix of urban, suburban, and foothills neighborhoods.
For county demographics and information visit the below website and enter your county and state, then click on the map next to total population for full details:
COLORADO
SPORTS TEAMS & FACILITIES:
DENVER METRO
DENVER BRONCOS
Empower Field at Mile High 1701 Bryant Street, Denver, CO 80204 denverbroncos.com
DENVER NUGGETS
Ball Arena
1000 Chopper Cir., Denver, CO 80204 nba.com/nuggets
COLORADO AVALANCHE
Ball Arena
1000 Chopper Cir., Denver, CO 80204 avalanche.nhl.com
COLORADO ROCKIES
Coors Field
2001 Blake St., Denver, CO 80205 coloradorockies.com
COLORADO RAPIDS
&
Dick’s Sporting Goods Park 6000 Victory Way, Commerce City, CO 80022 • coloradorapids.com
COLORADO MAMMOTH Ball Arena
1000 Chopper Cir., Denver, CO 80204 coloradomammoth.com
UNIVERSITY OF COLORADO cubuffs.com
DENVER UNIVERSITY denverpioneers.com
NATIONAL BALLPARK MUSEUM
1940 Blake Street – Denver, CO (303) 974-5835 ballparkmuseum.com
NORTHERN COLORADO
COLORADO EAGLES
Blue FCU Arena 5290 Arena Cir., Loveland, CO 80538 coloradoeagles.com
5580: Marshdale Elementary School | 1420: Jefferson County R-1
Plan Type Official Rating based on SINGLE-YEAR SPF Report
Performance Plan
John Irwin Award
85.0/100 Points Earned
The performance framework evaluates district and school performance on Academic Achievement, Academic Growth, and Postsecondary & Workforce Readiness indicators The percentage of points earned across all indicators determines the final accreditation rating for a district or the final plan type for a school, which is displayed above The cut points for final ratings established by the State Board of Education are shown at the right of this page Failure to meet finance, assessment, and safety assurances may result in a lowered rating Refer to the scoring guide near the end of this report for more details on how ratings are determined
InsufficientStateData: No reportable achievement and growth data
(-) No Reportable Data
*State accountability policy requires 95% student participation in state assessments Students excused from testing by a parent or guardian do not impact the Accountability Participation Rate that determines whether the overall rating is reduced by one level Districts or schools with less than 95% total participation in ELA and Math receive a "Does Not Meet 95% Total Participation" descriptor that is informational and does not impact framework calculations The descriptor does not impact framework calculations First-year in the U S Multilingual Learners eligible to take the ELP assessment count as participants for ELA
ACADEMIC ACHIEVEMENT
ACADEMIC GROWTH
This page displays the performance indicator data for the elementary school level For the 1-year report, calculations are based on 2025 state assessment results Multi-year reports include 2023 through 2025 results
Academic Achievement: mean scale scores represent outcomes for designated subjects and student groups; participation rates included on this page count parent excusals as non-participants
Academic Growth: median student growth percentiles and percentages of students on track to meet targets represent outcomes for designated subjects and student groups
For additional information regarding Academic Achievement and Academic Growth points, cut-points, and ratings, refer to the scoring guide at the end of this document.
Scoring Guide for 2025 District/School Performance Frameworks
2025 Final School Performance Framework
9428: West Jefferson Middle School | 1420: Jefferson County R-1
61.2/100 Points Earned Plan Type Official Rating based on SINGLE-YEAR SPF Report
Performance Plan
The performance framework evaluates district and school performance on Academic Achievement, Academic Growth, and Postsecondary & Workforce Readiness indicators The percentage of points earned across all indicators determines the final accreditation rating for a district or the final plan type for a school, which is displayed above The cut points for final ratings established by the State Board of Education are shown at the right of this page Failure to meet finance, assessment, and safety assurances may result in a lowered rating Refer to the scoring guide near the end of this report for more details on how ratings are determined
InsufficientStateData: No reportable achievement and growth data
(-) No Reportable Data
*State accountability policy requires 95% student participation in state assessments Students excused from testing by a parent or guardian do not impact the Accountability Participation Rate that determines whether the overall rating is reduced by one level Districts or schools with less than 95% total participation in ELA and Math receive a "Does Not Meet 95% Total Participation" descriptor that is informational and does not impact framework calculations The descriptor does not impact framework calculations First-year in the U S Multilingual Learners eligible to take the ELP assessment count as participants for ELA
2025 Final School Performance Framework
9428: West Jefferson Middle School | 1420: Jefferson County R-1 Middle School - (1 Year)
ACADEMIC ACHIEVEMENT
ACADEMIC GROWTH
This page displays the performance indicator data for the middle school level For the 1-year report, calculations are based on 2025 state assessment results Multi-year reports include 2023 through 2025 results
Academic Achievement: mean scale scores represent outcomes for designated subjects and student groups; participation rates included on this page count parent excusals as non-participants
Academic Growth: median student growth percentiles and percentages of students on track to meet targets represent outcomes for designated subjects and student groups
For additional information regarding Academic Achievement and Academic Growth points, cut-points, and ratings, refer to the scoring guide at the end of this document.
1886: Conifer Senior High School | 1420: Jefferson County R-1
Plan Type
Performance Plan
Grade Levels: H - (1 Year)
Rating based on SINGLE-YEAR SPF Report
82.5/100 Points Earned
The performance framework evaluates district and school performance on Academic Achievement, Academic Growth, and Postsecondary & Workforce Readiness indicators The percentage of points earned across all indicators determines the final accreditation rating for a district or the final plan type for a school, which is displayed above The cut points for final ratings established by the State Board of Education are shown at the right of this page Failure to meet finance, assessment, and safety assurances may result in a lowered rating Refer to the scoring guide near the end of this report for more details on how ratings are determined
Participation Rate Descriptor for Planning Purposes:
Summary of Ratings by EMH Level
InsufficientStateData: No reportable achievement and growth data (-) No Reportable Data
*State accountability policy requires 95% student participation in state assessments Students excused from testing by a parent or guardian do not impact the Accountability Participation Rate that determines whether the overall rating is reduced by one level Districts or schools with
participation in ELA and Math receive a "Does Not Meet 95% Total Participation" descriptor that is informational and does not impact framework calculations The descriptor does not impact framework calculations First-year in the U S Multilingual Learners eligible to take the ELP assessment count as participants for ELA
1886: Conifer Senior High School | 1420: Jefferson County R-1
ACADEMIC ACHIEVEMENT
ACADEMIC GROWTH
This page displays the performance indicator data for the high school level For the 1-year report, calculations are based on 2025 state assessment results Multi-year reports include 2023 through 2025 results PSAT/SAT cut scores for the multi-year reports were renormed based on 2025 results
Academic Achievement: mean scale scores represent outcomes for designated subjects and student groups; participation rates included on this page count parent excusals as non-participants
Academic Growth: median student growth percentiles and percentages of students on track to meet targets represent outcomes for designated subjects and student groups
For additional information regarding Academic Achievement and Academic Growth points, cut-points, and ratings, refer to the scoring guide at the end of this document.
Learners describes students that are Non-English
Not Applicable; (-) No Reportable Data
2025 Final School Performance Framework
1886: Conifer Senior High School | 1420: Jefferson County R-1
POSTSECONDARY AND WORKFORCE READINESS
REFERENCE TABLE: DISAGGREGATED GRADUATION RATES
CO SAT: represent outcomes for designated subjects and student groups; participation rates count parent excusals as non-participants For the 1-year report, calculations are based on 2025 state assessment results Multi-year reports include 2023-2025 results Cut-scores for the multi-year reports were re-normed based on 2025 results
Dropout Rates: represent percentages of students enrolled in grades 7-12 for districts and 9-12 for schools at any time during the year who left and did not subsequently enroll in another Colorado school 1-Year calculations are based on the 2024 End of Year (EOY) data submission Multi-year reports include 2022 through 2024 records
Matriculation Rates: represent percentages of high school graduates with a qualifying credential, enrollment, or enlistment status in a Career & Technical Education (CTE) program, a 2- or 4-year institute of higher education, a branch of the military, or a postsecondary program. Beginning in 2024, high school graduates who were enrolled in ASCENT, P-TECH, or TREP programs (i.e., Postsecondary Program) during their 5th year of high school count as successes. 1-Year calculations are based on the 2024 graduation cohort. Multi-year reports include 2022 through 2024 records.
Graduation Rates: represent percentages of students graduating high school within designated timeframes Ratings are based on the best of the 4-, 5-, 6-, and 7-year graduation rates AYGs designate Anticipated Years of Graduation, which are defined as four years after the year that students initially enroll in 9th grade Calculations for 1-Year and Multi-Year reports are based on data for students with AYGs between 2021 and 2024 For additional information about ratings, refer to the scoring guide on the last page of this report.
Scoring Guide for 2025 District/School Performance Frameworks
Scoring Guide for 2025 District/School Performance Frameworks
Public Schools :
Elementary Schools
West Jefferson Elementary School Distance 1.3 Miles
26501 Barkley Road Conifer CO 80433
Telephone : (303) 982-2975
Lowest Grade : Pre-K
Kindergarten : Yes
Enrollment : 252
School District : Jefferson County School District No. R-1
Highest Grade : 5th
School Enrollment :
Total Expenditure/Student :
Middle Schools
West Jefferson Middle School Distance 1.01 Miles
9449 South Barnes Street Conifer CO 80433
Telephone : (303) 982-3056
Lowest Grade : 6th
Kindergarten : No
Enrollment : 499
School District : Jefferson County School District No. R-1
Highest Grade : 8th
School Enrollment :
Total Expenditure/Student :
High Schools
Conifer Senior High School Distance 1.7 Miles
10441 County Highway 73 Conifer CO 80433
Telephone : (303) 982-5255
Lowest Grade : 9th
School District : Jefferson County School District No. R-1
Highest Grade : 12th
School Enrollment : Enrollment : 819
Total Expenditure/Student : Advanced Placement : No Customer Name : De Anna Harwood Customer Company Name : First American Title Prepared On : 05/28/2026
First American Title’s professionals are proud to provide the title insurance that assures people’s home ownership. Backed by First American Title Insurance Company, your transaction will be expertly completed in accordance with state-specific underwriting standards and state and federal regulatory requirements.
Count on us for stability.
First American Title is the principal subsidiary of First American Financial Corporation, and one of the largest suppliers of title insurance services in the nation. With roots dating back to 1889, we’ve served families for generations.
Count on us for convenience.
First American Title has a direct office or agent near you. We also have an extensive network of offices and agents throughout the United States, and internationally.
Count on us to meet your needs.
First American Financial Corporation offers more than title insurance and escrow services through its subsidiaries. Our subsidiaries also provide property data, title plant records and images, home warranties, property and casualty insurance, and banking, trust and advisory services.
Scan the QR code to learn more about your local First American Title.
Benefits of using a professional REALTOR®.
Congratulations on your decision to buy a home! It’s a challenging project, and there are many ways a professional can help. Here are some of the many ways you may benefit from working with a REALTOR®:
Many more home choices.
Your REALTOR® has thousands of homes to choose from through the Multiple Listing Service (MLS), so you’re more likely to find the home that’s just right for you and find it quicker. In fact, a majority of the homes for sale are listed by REALTORS® and aren’t available to you unless you are working with a REALTOR®
A number of transactions “fall out.”
Unfortunately, it’s true. Some transactions fall apart before closing. An experienced REALTOR® may be able to resolve problems and see your transaction through to a successful closing.
Knowledge of new home subdivisions.
New home subdivisions will welcome you and your REALTOR®. If you’re interested in buying a new home, take your agent with you on your first visit to each subdivision. Your professional REALTOR® is an important source of information who can supply background on the builder, nearby subdivisions, and the local community.
It’s a major investment.
You use a professional for your legal, financial and health needs. Why gamble on what may be your biggest investment without a professional at your side?
Help with FSBO’s.
If you consider a “For Sale By Owner,” take your REALTOR® along to help negotiate the contract.
There is less liability.
You may have more protection from legal and financial liability, especially as real estate transactions become more complicated.
The paperwork.
Your experienced REALTOR® will negotiate and prepare the purchase contract for you and assist you throughout the escrow process.
Key professionals involved in your transaction.
REALTOR®
A REALTOR® is a licensed real estate agent and a member of the National Association of REALTORS®, a real estate trade association. REALTORS® also belong to their state and local Association of REALTORS®
Real Estate Agent
A real estate agent is licensed by the state to represent parties in the transfer of property. Every REALTOR® is a real estate agent, but not every real estate agent has the professional designation of a REALTORS®
Listing Agent
A key role of the listing agent or broker is to form a legal relationship with the homeowner to sell the property and place the property in the Multiple Listing Service.
Buyer’s Agent
A key role of the buyer’s agent or broker is to work with the buyer to locate a suitable property and negotiate a successful home purchase.
Multiple Listing Service (MLS)
The MLS is a database of properties listed for sale by REALTORS® who are members of the local Association of REALTORS®. Information on an MLS property is available to thousands of REALTORS®.
Title Company
These are the people who carry out the title search and examination, work with you to eliminate the title exceptions you are not willing to take subject to, and provide the policy of title insurance regarding title to the real property.
Escrow Officer
An escrow officer leads the facilitation of your escrow, including escrow instructions preparation, document preparation, funds disbursement, and more.
Your escrow professional may:
Open escrow and, if instructed to do so, deposit your good faith funds in a separate escrow account.
Order a title search to determine ownership and status of the subject real property.
Issue a preliminary report and begin the process of eliminating the title exceptions you and your lender are not willing to take title subject to.
Request payoff information for the seller’s loans, other liens, homeowner’s association fees, etc.
Coordinate with the buyer’s lender on the preparation of the Closing Disclosure (CD).
Prorate fees, such as real property taxes, per the contract, and prepare the settlement statement.
Set separate appointments allowing the seller and you to sign documents and deposit funds.
Review documents ensuring all conditions and legal requirements are fulfilled; request funds from lender.
When all funds are deposited, record documents with the County Recorder’s Office to transfer the subject real property to you.
After the recordation is confirmed, close escrow and disburse\funds, including seller’s proceeds, loan payoffs, etc.
Prepare and send final documents to all parties involved.
Terms you should know.
Appraisal
An estimate of value of property resulting from analysis of facts about the property; an opinion of value.
Annual Percentage Rate (APR)
The borrower’s costs of the loan term expressed as a rate. This is not their interest rate.
Beneficiary
The recipient of benefits, often from a deed of trust; usually the lender.
Closing Disclosure (CD)
Closing Disclosure form designed to provide disclosures that will be helpful to borrowers in understanding all of the costs of the transaction. This form will be given to the consumer three (3) business days before closing.
Close of Escrow
Generally the date the buyer becomes the legal owner and title insurance becomes effective.
Comparable Sales
Sales that have similar characteristics as the subject real property, used for analysis in the appraisal. Commonly called “comps.”
Consummation
Occurs when the borrower becomes contractually obligated to the creditor on the loan, not, for example, when the borrower becomes contractually obligated to a seller on a real estate transaction. The point in time when a borrower becomes contractually obligated to the creditor on the loan depends on applicable State law. Consummation is not the same as close of escrow or settlement.
Deed of Trust
An instrument used in many states in place of a mortgage.
Deed Restrictions
Limitations in the deed to a parcel of real property that dictate certain uses that may or may not be made of the real property.
Disbursement Date
The date the amounts are to be disbursed to a buyer and seller in a purchase transaction or the date funds are to be paid to the borrower or a third party in a transaction that is not a purchase transaction.
Earnest Money Deposit
Down payment made by a purchaser of real property as evidence of good faith; a deposit or partial payment.
Easement
A right, privilege or interest limited to a specific purpose that one party has in the land of another.
Endorsement
As to a title insurance policy, a rider or attachment forming a part of the insurance policy expanding or limiting coverage.
Hazard Insurance
Real estate insurance protecting against fire, some natural causes, vandalism, etc., depending upon the policy. Buyer often adds liability insurance and extended coverage for personal property.
Impounds
A trust type of account established by lenders for the accumulation of borrower’s funds to meet periodic payments of taxes, mortgage insurance premiums and/or future insurance policy premiums, required to protect their security.
Legal Description
A description of land recognized by law, based on government surveys, spelling out the exact boundaries of the entire parcel of land. It should so thoroughly identify a parcel of land that it cannot be confused with any other.
Lien
A form of encumbrance that usually makes a specific parcel of real property the security for the payment of a debt or discharge of an obligation. For example, judgments, taxes, mortgages, deeds of trust.
Loan Estimate (LE)
Form designed to provide disclosures that will be helpful to borrowers in understanding the key features, costs and risks of the mortgage loan for which they are applying. Initial disclosure to be given to the borrower three (3) business days after application.
Mortgage
The instrument by which real property is pledged as security for repayment of a loan.
PITI
A payment that includes principal, interest, taxes, and Insurance.
Power of Attorney
A written instrument whereby a principal gives authority to an agent. The agent acting under such a grant is sometimes called an “Attorney-in-Fact.”
Recording
Filing documents affecting real property with the appropriate government agency as a matter of public record.
Settlement statement
Provides a complete breakdown of costs involved in a real estate transaction.
TRID
TILA-RESPA Integrated Disclosures
Planning to sell.
A homeowner’s checklist to prepare your home.
So you’re planning to sell your home. You and your real estate broker have decided on a price, based on current market values, but your home may sell faster and bring a higher price if it shows well. Potential buyers will get the best impression if your home is clean, neat, uncluttered, in good repair, light, airy, fragrant, and quiet. This checklist will help you get your home ready to show.
Clean everything in you home.
Cleanliness signals to a buyer that the home has been well cared for and is most likely in good repair. A messy or dirty home will cause prospective buyers to notice every flaw.
Let the fresh air in.
Get rid of odors that may be unfamiliar or unpleasant. People are most often offended by odors from tobacco, pets, cooking, and musty or sour laundry. Fresh flowers and potpourri can be used to your advantage. Other smells that attract positive attention include fresh baked bread and cinnamon.
Painting your home.
There’s nothing that improves the value of a home for a lower cost than a fresh coat of paint. And it’s so often easier to paint a room than it is to scrub it. Stick with neutral colors - off-white is the safest. Be sure to avoid black, violet, and pink.
Keep the noise down.
Silence is a restful sound that offends no one. Turn off the TV and radio. Soft instrumental music is fine but avoid vocals. If necessary, close the windows to eliminate any street noise.
Unclutter your home before you show it.
Have a garage sale. Empty closets. Throw away what you can’t sell. The less “stuff” in and around a home, the roomier it will seem.
Fix anything that is broken.
This includes plumbing, electrical systems, switches, windows, TV antennas, screens, doors, and fences; if it can’t be fixed, replace it or get rid of it (no window screens are better than broken ones). A buyer will make a much lower offer if your house is in disrepair and will probably still insist that everything be fixed before taking occupancy. You’re better off if you leave potential buyers no reason to offer less than you are asking.
Send your pets away.
Send them away or secure them away from the house when prospective buyers are coming. You never know if people will be annoyed or intimidated by your pets or even allergic to them. And you never want a prospective buyer to have to avoid animal droppings.
Send the kids to Grandma’s.
Send them to Grandma’s or take them on a walk around the block. Children can be noisy and distracting to someone interested in looking at a home.
Make a great impression.
“Home
staging is no longer optional in this real estate market, it’s a must.”
- Barbara Corcoran
Staging Tips
Grab them from the Curb
Make It Sparkle
Pay Attention to Color and Light
Depersonalize
Spruce Up Your Curb Appeal
Clean, Clean, Clean
Declutter
Neutralize
Remove All Big Clunky Furniture
Consider Replacing Furnishings
Invest in New Artwork
Make Repairs
Apply a Fresh Coat of Paint
Don’t Forget the Floors Spring for New Light Fixtures
Don’t Take it Personally
Don’t Do Major Renovations
Don’t Think the House Will Sell Itself
Don’t Run Out and Purchase All
New Furniture
Don’t Be Afraid to Ask For Help
Top 5 Dos
Top 5 Don’ts
This checklist will help you get your home ready to show.
Exterior
Clean around service areas/trash cans
Haul away rubbish
Straighten woodpile
Repair leaky faucets
Clean up pet droppings
Paint or varnish doors
Polish door hardware
Make sure doorbell/knocker works
Paint or replace street numbers on house
Make sure septic tank is odor free
Clean oil stains from driveway/street
Patch/reseal driveway if necessary
Replace, repair, and/or paint any damages:
Plaster
Wood siding
Trim
Rain gutters
Shutters
Doors
Window frames
Glazing
Screens
Hardware
Fences/gates
Outdoor lighting
Landscaping
Mow/edge lawn regularly
Aerate/feed lawn
Overseed bare spots in lawn
Water lawn regularly
Remove/replace dead plants
Prune overgrown/diseased/damaged shrubs
Prune or remove shrubs/trees blocking view from windows (unless view is undesirable)
Stake up any sagging trees/shrubs
Keep flower beds free of weeds
Trim around base of trees/walls/fences
Repair or remove any broken or damaged
landscape accessories such as:
Fences
Walls gazebos
Fountains
Trellises
Planters
Other
Replace any broken stepping stones
Adjust any sprinkler system; repair any broken/leaky heads
Install fences or shrubs to hide any unsightly views
Clean/Wash
Siding
Windows
Screen
Outdoor BBQ
AC unit
Pool/Spa
Put Light Bulbs In
Porch lights
Carport Garage
Closets
Keep closets clean and free of clutter
Throw out or pack away non-essentials
Adjust/repair sliding doors
Lubricate sliding door hardware
Paint, if needed
All Rooms, Clean especially around:
Doors
Windows
Light switches
Baseboards
Chair rails
Wash lace curtains and have draperies
cleaned if necessary
Remove or pull back dark curtains
Lubricate window slides (soap for wood
silicon or a candle stump for metal)
Make sure doors open smoothly
Clean ceiling light fixtures
Check for cobwebs in all corners
Fix any scratches in wooden floors
Replace worn/broken flooring
Remove or replace worn carpet
Use area rugs where needed
Empty wastebaskets
Make the beds
Fluff the pillows
Kitchen
Keep dishes and food out of sight
Clean appliances
Clean range hood, including light bulbs
Clean behind appliances
Keep floor clean
Clean light fixture
Make sure all electrical outlets work
Eliminate cooking odors
Deodorize garbage disposal, dishwasher, and refrigerator
Repair faucets
Put fresh shelf paper in cabinets
Organize cupboards
Clean out under sink
Replace garbage disposal gasket to reduce noise
Bathroom, Keep them spotlessly clean:
Shine mirrors
Keep wastebaskets empty and clean
Clean out cabinets and remove nonessentials
Keep fresh, clean towels on towel racks
Clean shower door – if sliding door, keep track well lubricated
Remove soap residue, mildew and mold from sink/tub/shower
Remove stains from porcelain sink tub toilet
Replace torn/moldy shower curtain
Bathroom (continued)
Clean tile grout
Make sure toilet flushes properly –replace mechanism if necessary
Clean exhaust fan/heater – replace if broken or noisy
Garage/Carport/Shed
Install 100-watt light bulb
Keep area clean/uncluttered
Hang up/put away tools
Clear away any cobwebs
Remove oil/paint stains from floor
Adjust tension rod to eliminate sag from overhead garage door
Lubricate/adjust/repair garage door opener
Paint if needed
Laundry Area
Clean out area behind washer/dryer
Eliminate any mildew odors
Basement
Eliminate any signs of dampness
Check for and eliminate cracks
Heating/Air Conditioning Unit
Vacuum
Replace filter
Clean intake vent
Remove any stored items
Make sure the temperature in your home is comfortable – keep it cooler in the summer and warmer in the winter. If it’s cooler outside and you have a fireplace, a nice fire will make your home seem cozy and inviting.
Provide an exhaustive written list of the features of your home.
Know the distance to schools and shopping centers.
Refer any prospect that calls or comes by to your broker for pre-screening and pre-qualification as well as for your own safety.
Tell your real estate agent all about the home-good and bad. Let the professional decide how to handle negatives and features or highlight the positives.
The life of an escrow.
Chooses a Real Estate Agent
Gets pre-approval letter from Lender and provides to Real Estate Agent.
Makes offer to purchase. Upon acceptance, opens escrow and deposits earnest money.
Finalizes loan application with Lender. Receives a Loan Estimate from Lender.
Completes and returns opening package from First American Title.
Schedules inspections and evaluates findings. Reviews title commitment/preliminary report.
Provides all requested paperwork to Lender (bank statements, tax returns, etc.) All invoices and final approvals should be to the lender no later than 10 days prior to loan consummation.
Lender (or Escrow Officer) prepares CD and delivers to Buyer at least 3 days prior to loan consummation.
Escrow officer or real estate agent contacts the buyer to schedule signing appointment.
Documents are recorded and the keys are delivered!
Accepts Buyer’s offer to purchase.
Completes and returns opening package from First American Title, including information such as forwarding address, payoff lender contact information and loan numbers.
Orders any work for inspections and/or repairs to be done as required by the purchase agreement.
Escrow officer or real estate agent contacts the seller to schedule signing appointment.
Documents are recorded and all proceeds from sale are received.
Upon receipt of order and earnest money deposit, orders title examination.
Requests necessary information from buyers and sellers via opening packages.
Reviews title commitment/ preliminary report.
Upon receipt of opening packages, orders demands for payoffs. Contacts buyer or seller when additional information is required for the title commitment/ preliminary report.
All demands, invoices, and fees must be collected and sent to lender at least 10 days prior to loan consummation.
Coordinates with lender on the preparation of the CD.
Reviews all documents, demands, and instructions and prepares settlement statements and any other required documents.
Schedules signing appointment and informs buyer of funds due at settlement.
Once loan is consummated, sends funding package to lender for review.
Prepares recording instructions and submits docs for recording.
Documents are recorded and funds are disbursed. Issues final settlement statement.
Accepts Buyer’s application and begins the qualification process. Provides Buyer with Loan Estimate.
Orders and reviews title commitment / preliminary report, property appraisal, credit report, employment and funds verification.
Collects information such as title commitment / preliminary report, appraisal, credit report, employment and funds verification. Reviews and requests additional information for final loan approval.
Underwriting reviews loan package for approval.
Coordinates with Escrow Officer on the preparation of the Closing Disclosure, which is delivered to Buyer at least 3 days prior to loan consummation.
Delivers loan documents to escrow.
Upon review of signed loan documents, authorizes loan funding.
The Buyer
The Escrow Officer
Chooses a Real Estate Agent
The Seller
The Lender
The Closing Process
We know the home buying process can be confusing. Let’s walk through a brief explanation of what happens after you sign the contract.
The signed contract and earnest money are delivered to the settlement agent (note: the title company often acts as the settlement agent). Now the title order begins and information such as taxes, loan payoffs, lien search, and other information is collected.
The title search will determine the legal owner of the property and any outstanding liens and/or assessments. This search is critical to making sure the property will transfer legally to the buyer.
Over the next few weeks the following will occur: inspections, repairs (if necessary), payoffs obtained from current lenders, HOA’s, lienholders, ect, and loan document preparation. It is important the buyers and sellers are responsive to requests for paperwork and information.
Once the invoices, payoffs, statements, and loan documents are received, the settlement statement is prepared. This document includes the closing calculations and is used to inform the buyer and seller of their bottom line figures.
The closing paperwork must then be signed by the buyer and the seller. This will include documents such as the deed, settlement statement, loan documents (if applicable), and others.
All payees, including the seller, payoff lenders, real estate professionals, and others are paid according to the settlement statement.
The final documents, including the deed and loan instrument, are sent to the county recorder’s office for recordation. After recording, the deed will be sent to the buyer. The title insurance policy is sent to the buyer and the lender.
Understanding title insurance.
The title industry and title insurance in brief.
Prior to the development of the title industry in the late 1800s, a home-buyer received a grantor’s warranty, attorney’s title opinion, or abstractor’s certificate as assurance of home ownership. The buyer relied on the financial integrity of the grantor, attorney, or abstractor for protection. Today, homebuyers look primarily to title insurance to provide this protection. Title insurance companies are regulated by state statute. They are required to post financial guarantees to ensure that any claims will be paid in a timely fashion. They also must maintain their own “title plants” which house duplicates of recorded deeds, mortgages, plats, and other pertinent county property records.
What is title insurance?
Title insurance provides coverage for certain losses due to defects in the title that, for the most part, occurred prior to your ownership. Title insurance protects against defects such as prior fraud or forgery that might go undetected until after closing and possibly jeopardize your ownership and investment.
Why is title insurance needed?
Title insurance insures buyers against the risk that they did not acquire marketable title from the seller. It is primarily designed to reduce risk or loss caused by defects in title from the past. A loan policy of title insurance protects the interest of the mortgage lender, while an owner’s policy protects the equity of you, the buyer, for as long as you or your heirs (in certain policies) own the real property.
When is the premium due?
You pay for your owner’s title insurance policy only once, at the close of escrow. Who pays for the owner’s policy and loan policy varies depending on local customs.
How title insurance differs.
Unlike other forms of insurance, title insurance emphasizes loss prevention for the insured. Title professionals perform labor-intensive work to find and address title issues that could threaten your homeownership. This upfront analysis gives you, as a policy holder, the peace of mind that your title risk has been effectively reduced. In contrast, insurance based on loss assumption (such as auto or property and casualty insurance) requires little upfront work because claims cannot be predicted or prevented, and premium funds are needed only in the event of an accident or other covered issue. These types of insurance also require annual coverage payments, unlike title insurance which is paid for only once upon the purchase of your home or establishment of a new mortgage.
The importance of title protection.
There are many title issues that could cause you to lose your real property or your mortgage investment. Even the most careful search of public records may not disclose the most dangerous threat: hidden risks. These issues may not be uncovered until years later. Without title insurance from a reputable and financially solvent company, the ownership of your home could be jeopardized.
Here are some examples of title issues that may occur:
Deeds by persons supposedly single, but secretly married.
Deeds in lieu of foreclosure given under duress
Marital rights of spouse purportedly, but not legally, divorced.
Impersonation of the true owner of the land.
Deeds by minors.
Deeds by persons of unsound mind.
Deeds to or from defunct corporations.
Defective acknowledgments by notaries.
Duress in execution of instruments.
Erroneous reports furnished by tax officials.
Forged deeds, releases, etc.
Mistakes in recording legal documents.
Surviving children omitted from will.
Administration of estate of persons absent but not deceased.
Birth or adoption of children after date of will.
Claims of creditors against real property sold by heirs or devisees.
Deed of community property recited to be separate property.
Deeds by foreign parties.
Seller’s Checklist
Prior to Closing:
Provide title company with current loan information so a payoff statement can be ordered from your lender. You will need to provide your Social Security Number and you may be required to sign a form authorizing your lender to provide the payoff to First American Title.
Complete a Confidential Information Statement if you have a common surname. Provide documentation of any change in marital status (divorce, marriage, death) during current ownership. If the property is inherited we will need a copy of the probated will.
Have your Power of Attorney approved prior to closing in the event you will not be present to sign documents.
Required at Closing:
Driver’s License Social Security Number
Bring extra house keys, garage door openers, warranties or operational manuals for appliances (heating, AC, stove, etc.) or let your real estate professional know where in the house they are located.
Avoiding Closing Delays:
Lenders and title insurers may require single owners who have married to have their spouse sign paperwork or a deed at closing. Discuss this with your escrow officer early in the transaction. The Confidential Information Statement should be completed and returned promptly. It will help clarify the identity of the actual person or persons named on judgments in the title search.
After Closing:
Cancel your homeowner’s insurance if you are moving from the property at closing. If you are remaining at the property after closing, you should notify your agent of this change.
Make sure your lender has your forwarding address. The lender will refund monies left in your escrow/impound account and send final paperwork regarding the paid loan.
Keep your final settlement statement with tax documents. You will need it when filing taxes.
Moving Address Change Checklist
Here’s a list of people, businesses and organizations who will need to know you’ve moved to a new location.
The Essentials:
Request a “Change of Address” form at a USPS post office
Friends and family
Financial Institutions:
Banks and credit unions
Credit card companies (including department store cards)
Lenders (mortgage, home equity, auto, student loan)