MAROONDAH
By Joe Lam





COLUMNIST CONTRIBUTORS
|
WEDDING PLANNER
COPYWRITER / ACCREDITED EDITOR
Are you our next Copywriter?
Are you our next Wedding Planner? ? ? ?
Are you our next Life Coach?
Are you our next Architectural Interior Design?
BOOKKEEPING
Are you our next Bookkeeper? ?
Fitness Trainer
Are you our next Fitness Trainer? ?
CLUB SPONSORS
joanna srtybosch erryn langley
ETHAN STRYBOSCH
JODIE MOORE
DEAN BOSMAN
About the Find Maroondah
By Warren Strybosch
The Find Maroondah is a community paper that aims to support all things Maroondah. We want to provide a place where all Not-For-Profits (NFP), schools, sporting groups and other like organisations can share their news in one place. For instance, submitting up-andcoming events in the Find Maroondah for Free.
We do not proclaim to be another newspaper and we will not be aiming to compete with other news outlets. You can obtain your news from other sources. We feel you get enough of this already. We will keep our news topics to a minimum and only provide what we feel is most relevant topics to you each month.
We invite local council and the current council members to participate by submitting information each month so as to keep us informed of any changes that may be of relevance to us, their local constituents.
We will also try and showcase different organisations throughout the year so you, the reader, can learn more about what is on offer in your local area.
To help support the paper, we invite local business owners to sponsor the paper and in return we will provide exclusive advertising and opportunities to submit articles about their businesses. As a community we encourage you to support these businesses/columnists. Without their support, we would not be able to provide this community paper to you.
Lastly, we want to ask you, the local community, to support the fundraising initiatives that we will be developing
The
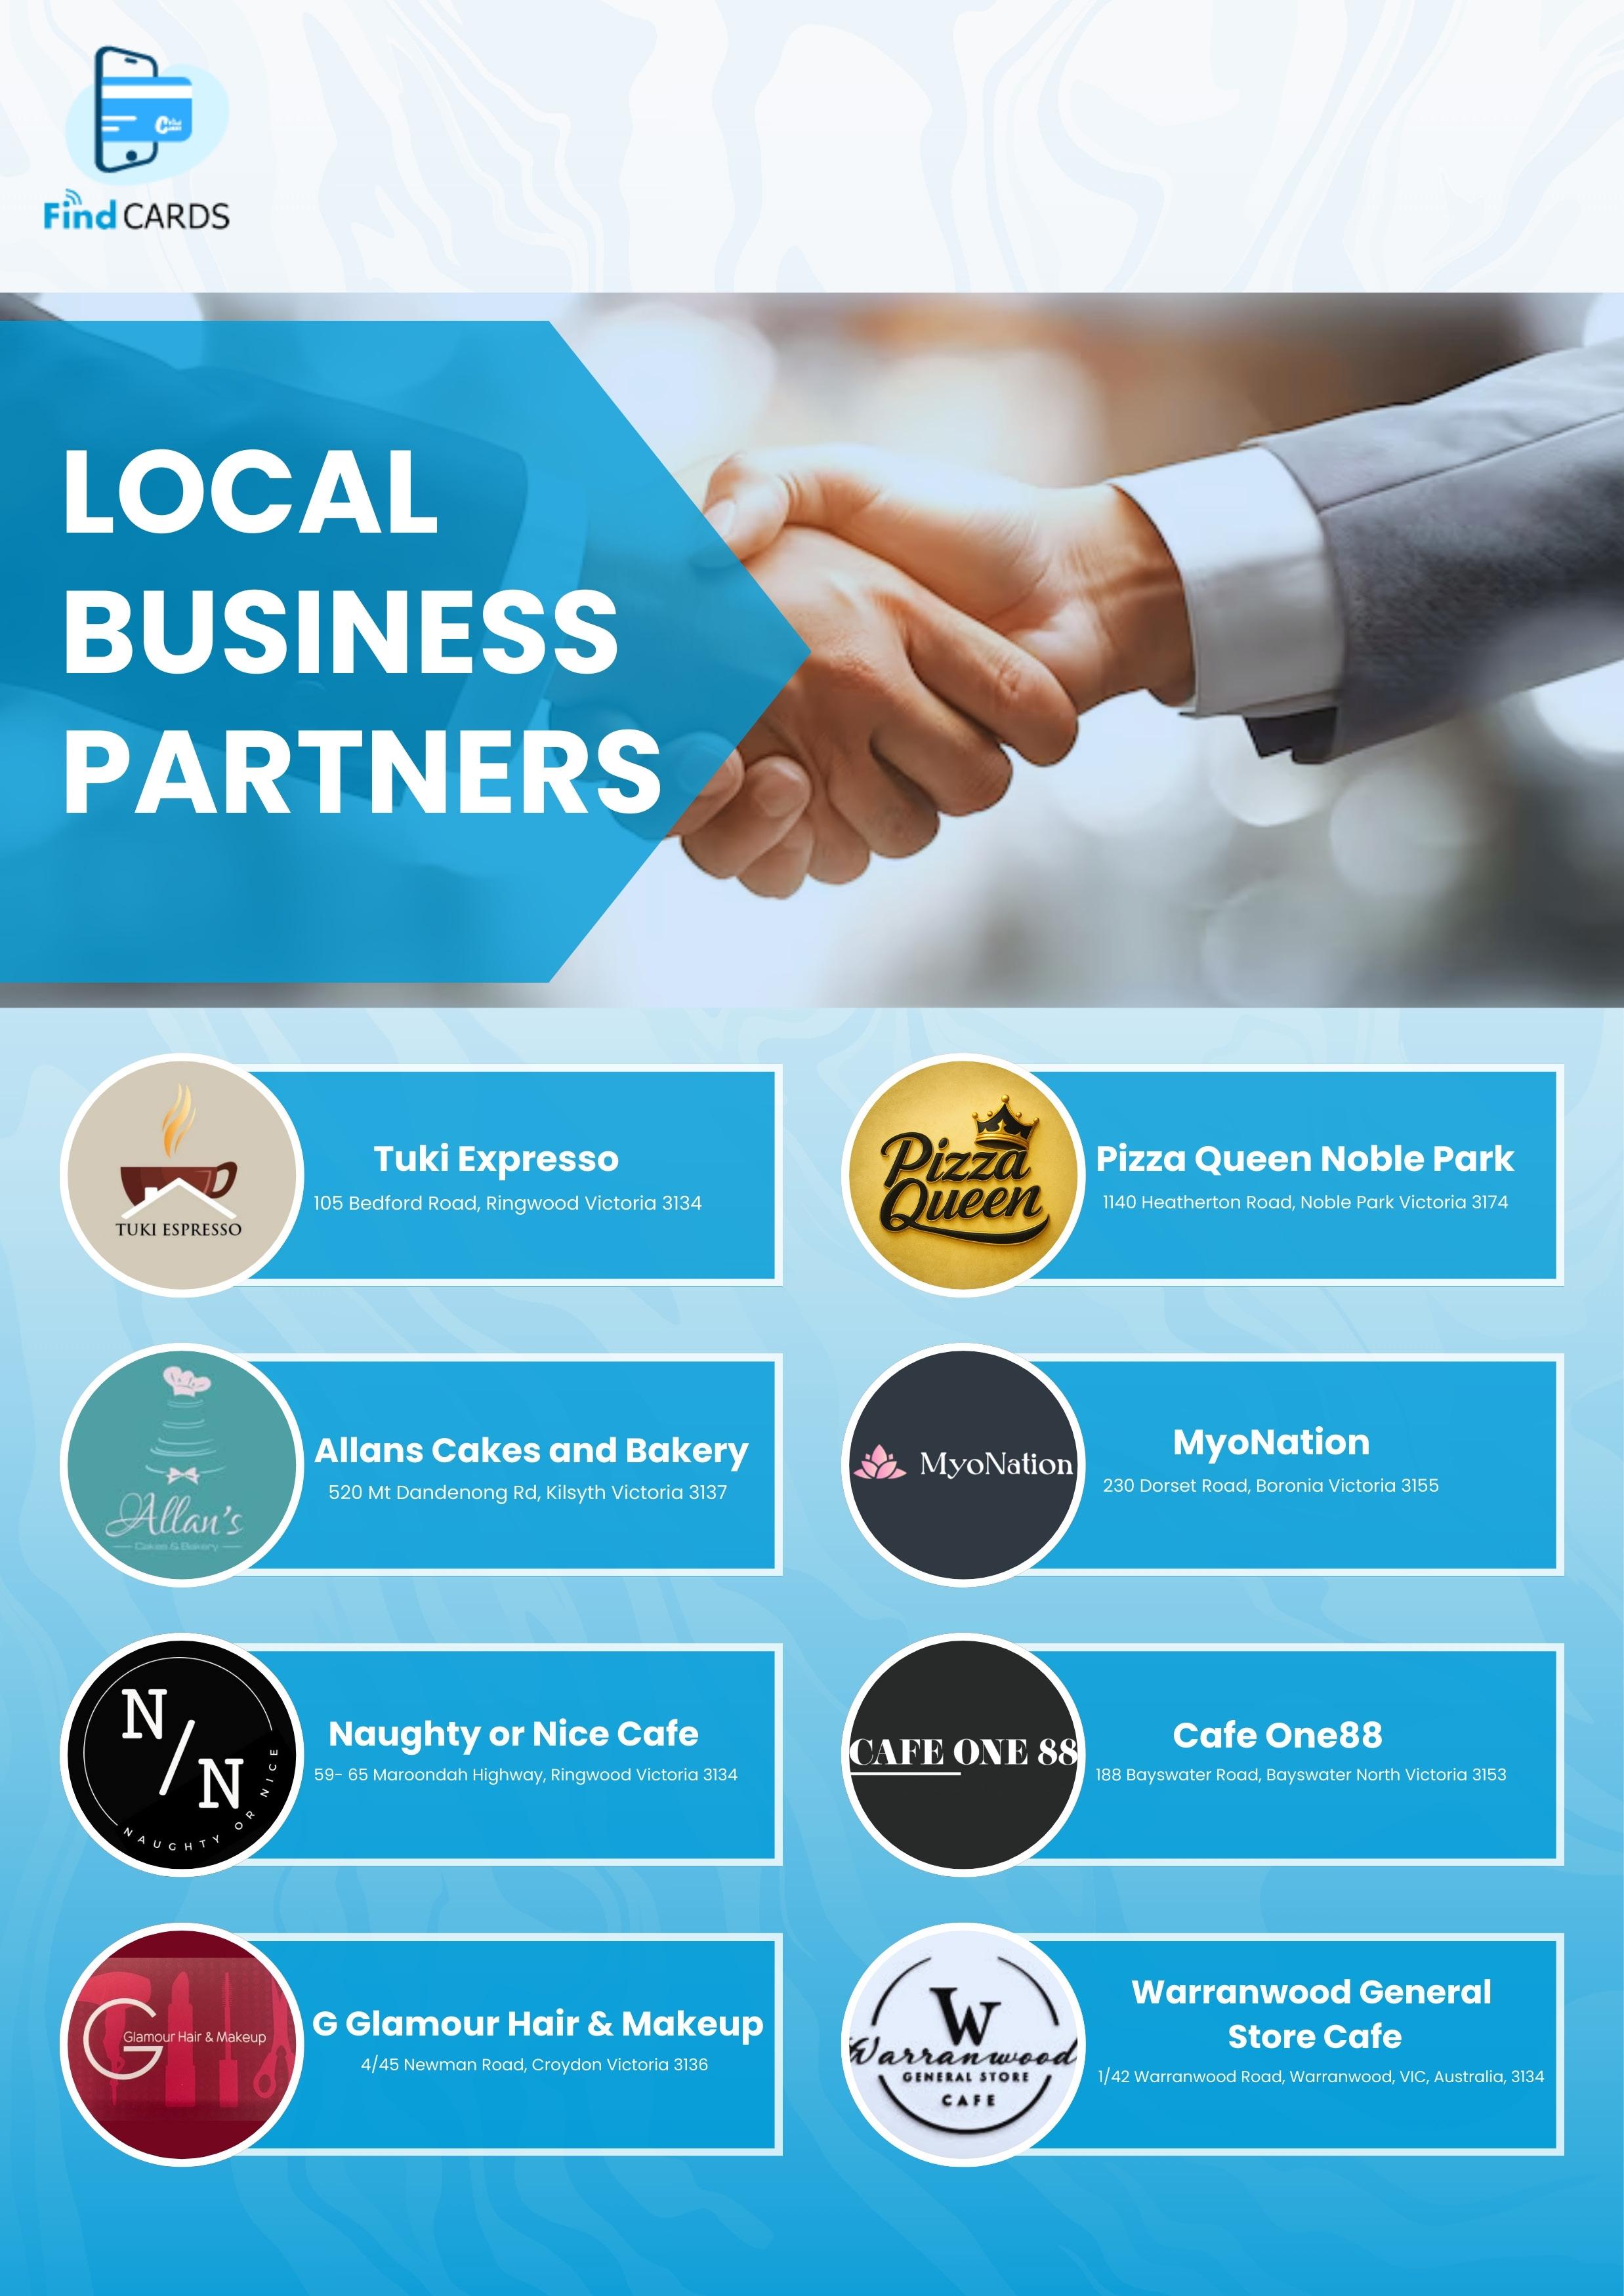
and rolling out over the coming years. Our aim is to help as many NFP and other like organisations to raise much needed funds to help them to keep operating. Our fundraising initiatives will never simply ask for money from you. We will also aim to provide something of worth to you before you part with your hard-earned money. The first initiative is the Find Cards and Find Coupons – similar to the Entertainment Book but cheaper and more localised. Any NFP and similar organisations e.g., schools, sporting clubs, can participate.
Follow us on facebook (https://www. facebook.com/findmaroondah) so you keep up to date with what we are doing.
We value your support,
The Find Maroondah Team.
Maroondah
EDITORIAL ENQUIRIES: Warren Strybosch | 1300 88 38 30 editor@findmaroondah.com.au
PUBLISHER: Issuu Pty Ltd
POSTAL ADDRESS: 248 Wonga Road, Warranwood VIC 3134
ADVERTISING AND ACCOUNTS: editor@findmaroondah.com.au
GENERAL ENQUIRIES: 1300 88 38 30
EMAIL SUPPORT: editor@findmaroondah.com.au
WEBSITE: www.findmaroondah.com.au
OUR NEWSPAPER
The Find Maroondah was established in 2019 and is owned by the Find Foundation, a Not-For-Profit organisation with a core focus of helping other Not-For-Profits, schools, clubs and other similar organisations in the local community - to bring everyone together in one place and to support each other. We provide the above organisations FREE advertising in the community paper to promote themselves as well as to make the community more aware of the services these organisations can offer. The Find Maroondah has a strong editorial focus and is supported via local grants and financed predominantly by local business owners.
ALL THINGS MAROONDAH
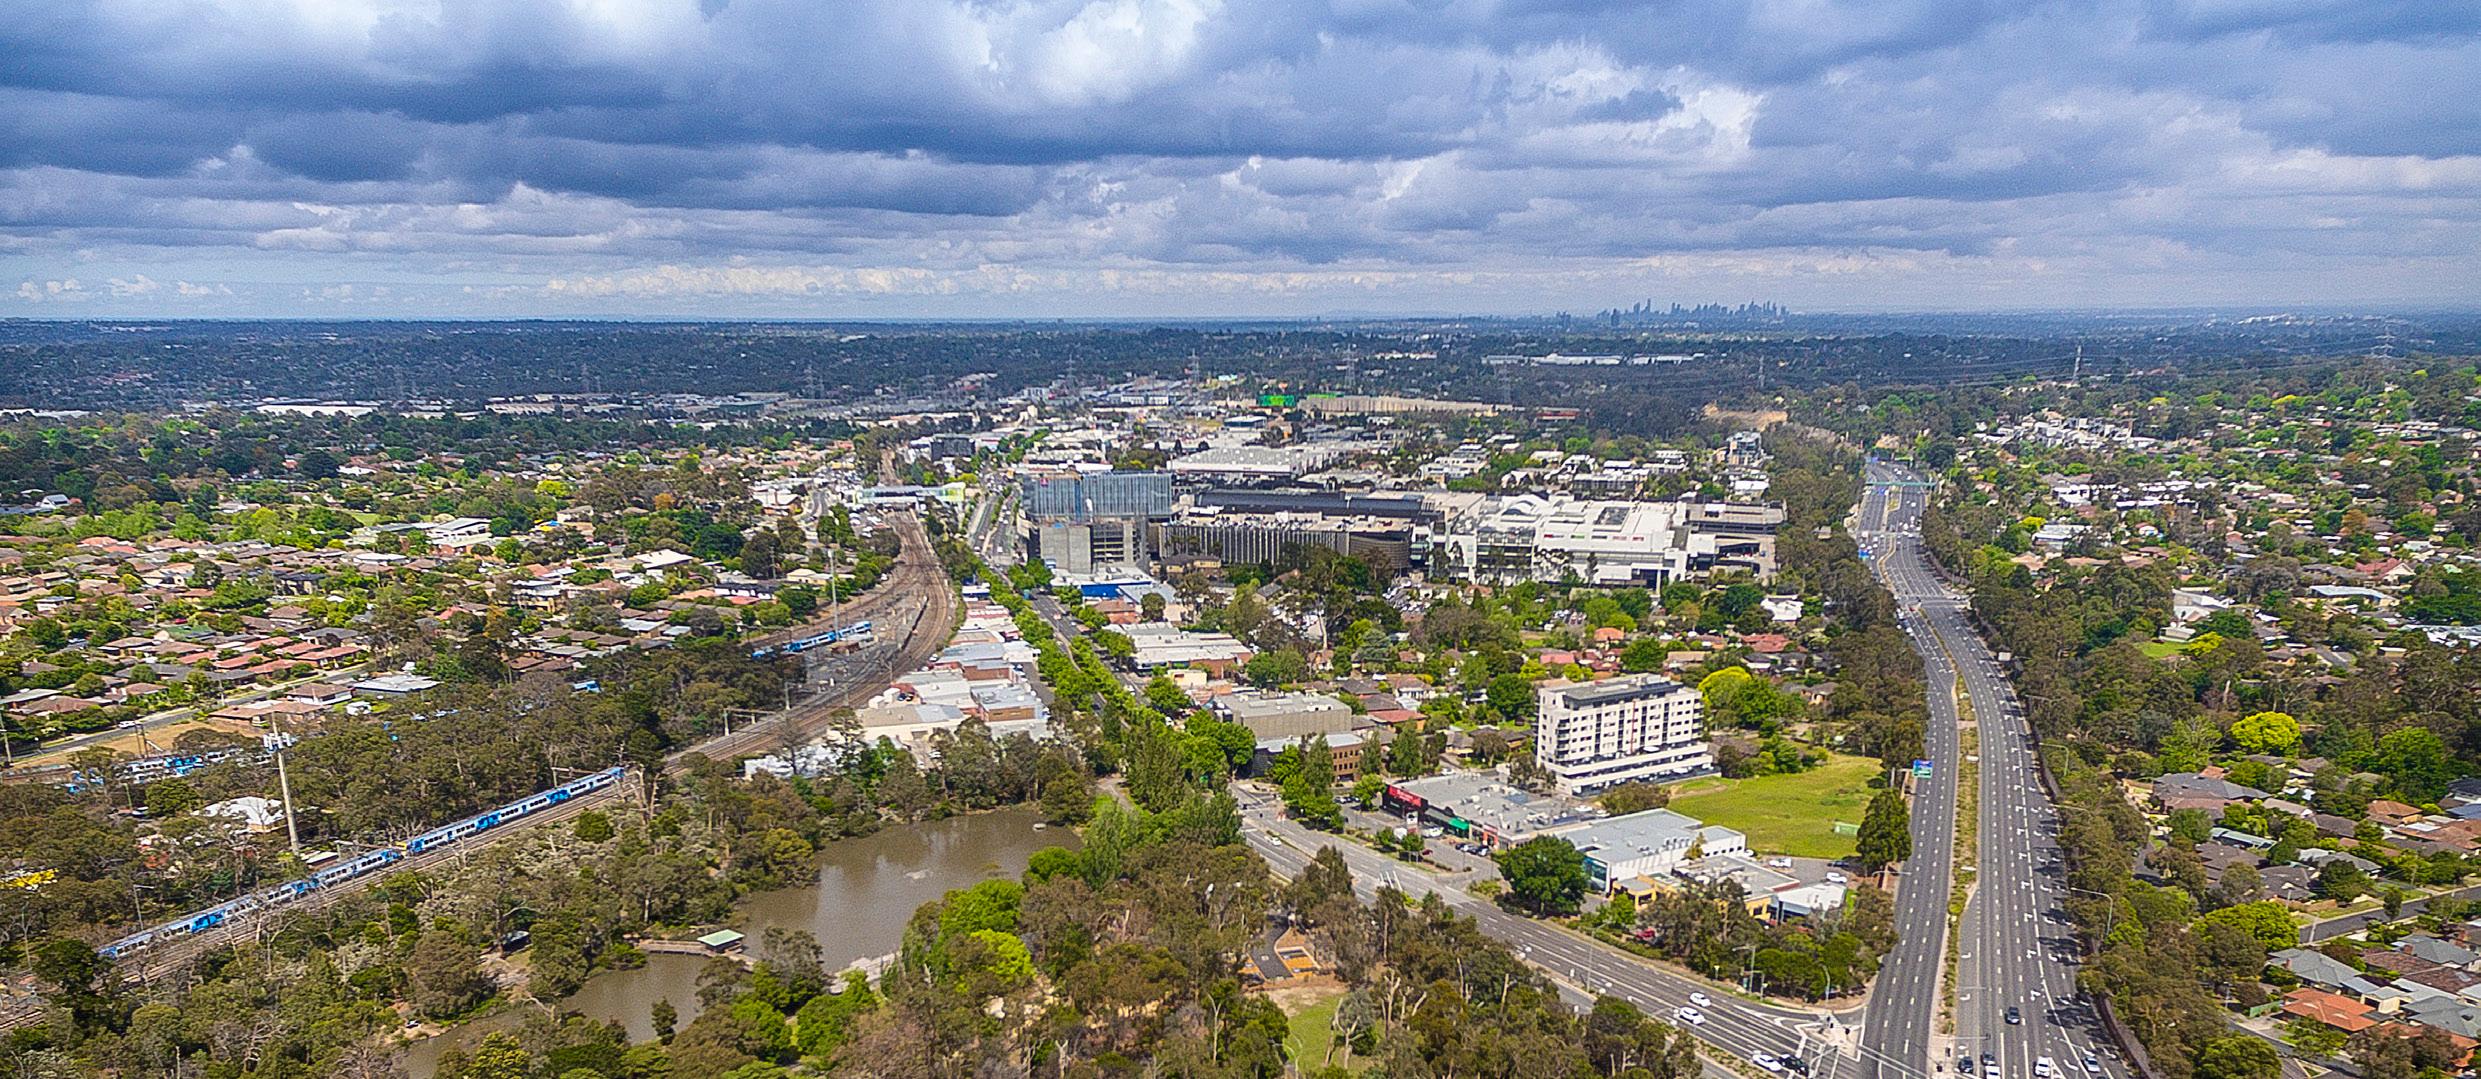
The City of Maroondah is a local government area in Victoria, Australia, in the eastern suburbs of Melbourne. Maroondah had a population of approximately 118,000 as of the 2019 report, comprising 9,000 businesses and nearly 46,000 households. The City of Maroondah was created through the amalgamation of the former cities of Ringwood and Croydon in December 1994.
ACKNOWLEDGEMENT
The Find Maroondah acknowledges the Traditional Owners of the lands where Maroondah now stands, the Wurundjeri people of the Kulin nation, and pays respect to their Elders - past, present and emerging - and acknowledges the important role Aboriginal and Torres Strait Islander people continue to play within our community.
DISCLAIMER
Readers are advised that the Find Maroondah accepts no responsibility for financial, health or other claims published in advertising or
“I Will Never Forget You”: Celebrating World Day for Grandparents and the Elderly
By Joe Lam
Grandparents and older people are the storytellers, mentors, and guardians of memory in our communities. They remind us of where we’ve come from and help guide us toward where we’re going. On 26 July 2026, Victoria will join the world in celebrating the World Day for Grandparents and the Elderly, a day dedicated to honouring their wisdom and ensuring they are never forgotten.
It’s Origins and Why It Matters Today
The World Day for Grandparents and the Elderly was proclaimed in 2021 by Pope Francis in Rome, inspired by the isolation that elders faced during the pandemic. This year’s theme, “I will never forget you” (Isaiah 49:15), offers comfort and reminds families to treasure older loved ones. The day encourages us to pause—grandparents sharing traditions, elders mentoring, families reconnecting—and calls communities to support healthy ageing. Across Victoria, celebrations include storytelling circles, concerts, teas, art workshops, and recognition events in Geelong and Maroondah, fostering intergenerational connection.
Local Places to Celebrate
Families can spend meaningful time together at:
• Geelong Botanic Gardens
• Eastern Beach Reserve
• National Wool Museum, Geelong
• Maroondah Federation Estate
• Ringwood Lake Park
• Maroondah Library
• Barwon Heads Bluff Lookout
• Café Biscotti, Ringwood
Gifts Beyond Material Things
The most treasured gifts are often intangible: a handwritten letter, a shared meal, an afternoon of storytelling, or simply listening. Acts of service—helping with gardening, cooking, or errands— show care. Organising a family gathering or recording oral histories can create lasting legacies.
Local Elders Making a Difference
Geelong and Maroondah are home to inspiring senior leaders:
• Margaret O’Donnell (Geelong) – mentor for young writers. Tom Richards (Geelong) – junior footy coach.
• Aunty Joan Clarke (Geelong) – Indigenous elder and cultural educator.
• Jeannette Hanley-Heath (Geelong) – established a nationwide registry supporting Kinship Carers and Grandparent Groups
• Helen Fraser (Maroondah) – advocate for seniors’ health.
• George Lim (Maroondah) – retired teacher leading history talks.
• Patricia Nguyen (Maroondah) – arts volunteer fostering creativity.
Indigenous Elderly Leaders
Equally vital are the voices of First Nations Elders, who carry cultural knowledge and strengthen community identity:
• Geelong: Aunty Mary Shuttleworth (Wadawurrung Elder, language advocate), Corrina Eccles (Wadawurrung cultural educator), Jasmine Skye-Marinos (First Nations women’s advocate).
• Maroondah: Aunty Daphne Milward (Yorta Yorta Elder, Aboriginal Advancement League co-founder), Aunty Irene Norman (Wailwan Elder, artist and poet), Uncle Bill Nicholson (Wurundjeri Elder, reconciliation leader).
A Heartfelt Conclusion
As we mark World Day for Grandparents and the Elderly, let us celebrate not only their years but their enduring spirit. Their wisdom guides us, their resilience inspires us, and their love binds us together. On 26 July, may we pause to honour them—not just with words, but with presence, gratitude, and joy. Truly, we will never forget you.
I remember a time in my life where, from the outside, everything looked connected.
There were people around me. Conversations happening. Messages coming through. Days filled with interactions.
And yet, underneath it all, there was this quiet feeling — like I didn’t quite belong anywhere.
It wasn’t loud. It wasn’t dramatic. It was just… there.
A sense that I was moving through spaces rather than being part of them. And I know I’m not alone in that.
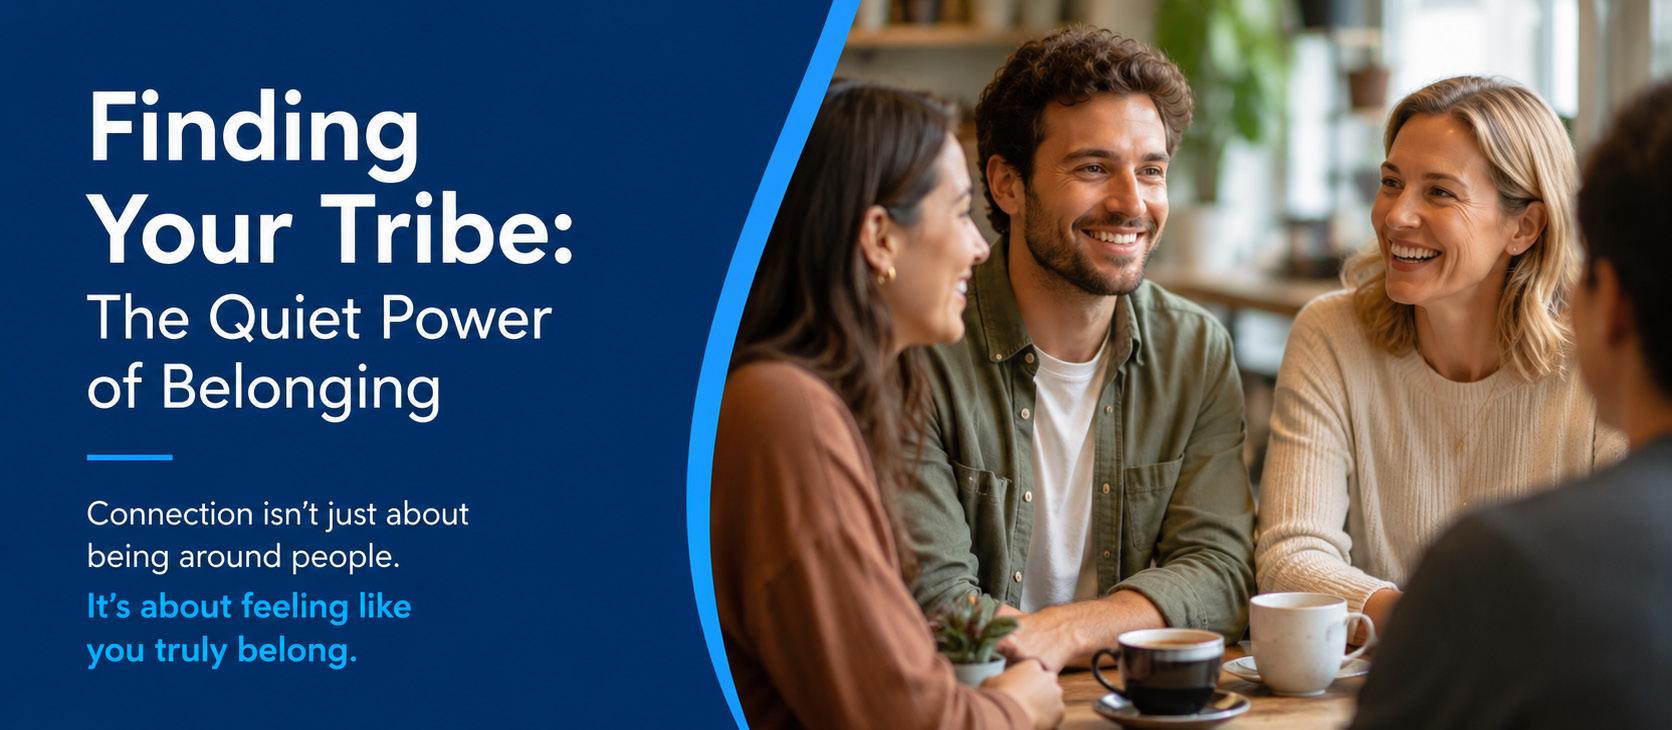
Because one of the things I’ve come to understand both personally and through the work I do is that being around people is not the same as feeling connected.
Where Belonging First Begins
For many of us, our first experience of belonging comes from family.
Family shapes how we see ourselves. It teaches us what connection looks like. It influences how safe we feel to speak, to be seen, and to be known.
When those connections are strong, they can become the foundation we build our lives on, a place we return to, no matter what.
But the reality is, for many people, that sense of belonging within family isn’t always there in the way we need it.
Sometimes it’s inconsistent. Sometimes it’s complicated. And sometimes, despite being surrounded by family, we still feel alone.
And that can leave a quiet question sitting underneath everything:
Where do I fit?
We’re Wired for Connection
As humans, we are deeply wired to belong. Not in a surface-level way, but in a way that sits at the core of who we are. The need to feel connected, understood, and accepted has always been essential to our survival, and it still is today.
Research consistently shows that strong social connections are one of the most powerful drivers of our wellbeing. Feeling connected reduces stress, improves mental health, and even supports physical health.
And when that connection is missing, we feel it. Not just emotionally, but physically and psychologically as well.
Creating the Family We Need
One of the most important things I’ve learned is this:
If we don’t experience belonging in the family we come from, we can still create the sense of belonging we need.
We can build our own “family”.
Not necessarily in the traditional sense — but through connection, shared experience, and genuine care.
Our tribe might not share our blood, but they share something just as important:
They see us. They accept us. They hold space for who we are, not who we think we need to be.
And sometimes, that kind of connection can be even more powerful.
The Difference Between Being There and Belonging
Over time, I’ve realised something important:
Belonging isn’t about how many people are in your life. It’s about how many people truly know you.
It’s the difference between:
• Being seen… and being understood
• Being included… and being accepted
• Being present… and feeling like you matter
Because holding back parts of yourself just to fit in is exhausting.
And true belonging doesn’t ask you to shrink.
Finding Your Tribe
Finding your tribe doesn’t happen overnight. For me, it happened in small moments.
A conversation where I didn’t need to explain myself. Someone sitting with me in something difficult without trying to fix it. A space where I didn’t feel like I had to perform.
Belonging Is Something We Build
Belonging isn’t something we wait for. It’s something we create.
In the way we show up for others. In the way we allow ourselves to be seen. In the spaces we help shape.
Sometimes it starts with something small:
• Asking someone how they really are
• Being honest about how you're feeling
• Letting someone in, just a little more than feels comfortable
These are the moments where belonging begins.
A Final Reflection
If belonging didn’t come easily to you early in life, that doesn’t mean it’s not possible.
It just means you may need to create it differently.
And that’s okay.
Because finding your tribe isn’t about waiting for the right people to find you, it’s about allowing yourself to step into spaces where you can be seen and choosing to stay when connection begins to grow.
The Better Health Victoria guide on strong relationships highlights that meaningful connection often grows from shared experiences, consistency, and simply giving yourself permission to show up.
You don’t need to get it perfect. You just need to begin.
MAREE SMITH
ATO Interest Rates Increase Again: What Business Owners Need to Know

ACCOUNTANT
Warren Strybosch
The Australian Taxation Office (ATO) has confirmed an increase in its interest rates for the September 2026 quarter, adding further pressure on businesses and individuals carrying tax debts.
Effective from 1 July 2026 to 30 September 2026, the General Interest Charge (GIC) will increase to 11.43% per annum, up from 10.96% in the previous quarter. This equates to a daily compounding rate of 0.03131507%.
The Shortfall Interest Charge (SIC), which applies where taxpayers have underpaid tax due to amended assessments, will rise to 7.43% per annum, with a daily compounding rate of 0.02035616%.
Interest payable by the ATO on overpayments, early payments and delayed refunds will increase to 4.43% per annum.
Why This Matters
The GIC is one of the highest interest rates many businesses will encounter. Unlike a standard loan, the charge compounds daily, meaning tax debts can grow rapidly if left unpaid.
For example, a business with an outstanding ATO debt of $100,000 could incur more than $11,000 in interest annually if the debt remains unpaid. As interest compounds daily, the actual cost can be even higher over time.
With the ATO continuing to take a firmer approach to debt collection, many business owners are finding that tax liabilities accumulated during challenging trading periods are becoming increasingly expensive to carry.
The Cost of Delaying Action
Many business owners view an ATO debt as a flexible source of funding because payment arrangements can often be negotiated. However, with GIC now exceeding 11%, the true cost of carrying that debt may be significantly higher than many traditional finance options.
In addition, recent changes have reduced the tax deductibility of certain ATO interest charges, making the effective cost even greater for some businesses.
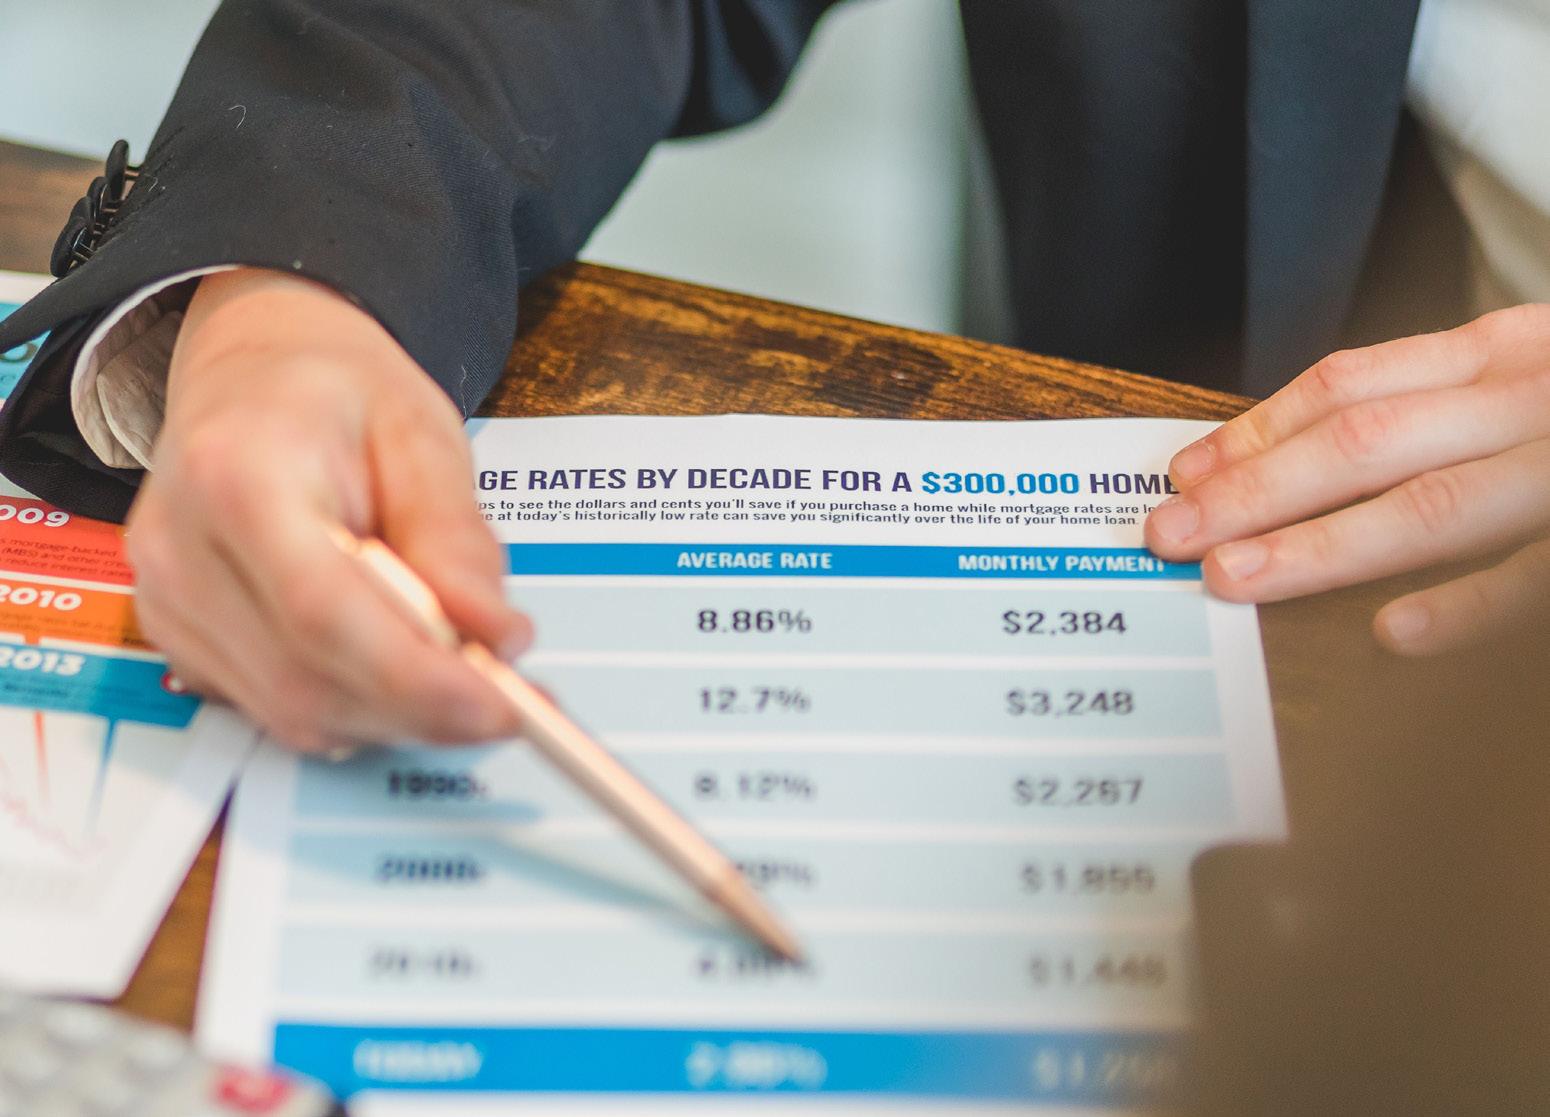
The longer a tax debt remains outstanding, the more difficult it can become to eliminate as interest continues to accrue and cash flow pressures compound.
Consider Reviewing Your Finance Options
Businesses with significant ATO debts may wish to review whether alternative funding arrangements could reduce their overall costs.
Depending on individual circumstances, some business owners may be able to refinance tax debts through commercial lending facilities, business loans, or property-backed finance. In many cases, the interest rates available through traditional lenders may be considerably lower than the current GIC rate.
Business owners who own residential or commercial property may also wish to speak with a mortgage broker about whether an investment loan, equity release strategy, or other lending solution could be appropriate. While borrowing to pay tax debt is not suitable for everyone, replacing an 11.43% compounding ATO debt with a lowercost funding arrangement may improve cash flow and reduce overall interest costs.
Importantly, any financing decision should be considered alongside
taxation, accounting and financial advice to ensure it aligns with the business owner's broader objectives and circumstances.
Seek Professional Advice Early
If your business has an existing ATO debt, now may be an appropriate time to review your position before interest costs increase further.
A discussion with your accountant can help you understand the full impact of the new rates, assess available payment arrangements, and identify strategies to manage outstanding obligations. Where appropriate, your accountant may also work alongside a mortgage broker or commercial finance specialist to explore funding options that could reduce the cost of carrying tax debt.
The Bottom Line
The increase in ATO interest rates serves as another reminder that tax debts should not be ignored. With the General Interest Charge now sitting at 11.43% per annum and compounding daily, the cost of inaction can be substantial.
For business owners carrying significant tax liabilities, reviewing finance options and seeking professional advice sooner rather than later could potentially save thousands of dollars in interest and help restore greater control over business cash flow.
Working Together for Wildlife Along Dandenong Creek
What does it take to improve habitat for native wildlife in one of Melbourne's busiest urban corridors?
First Friends of Dandenong Creek (FFDC) believes the answer is simple: partnership.
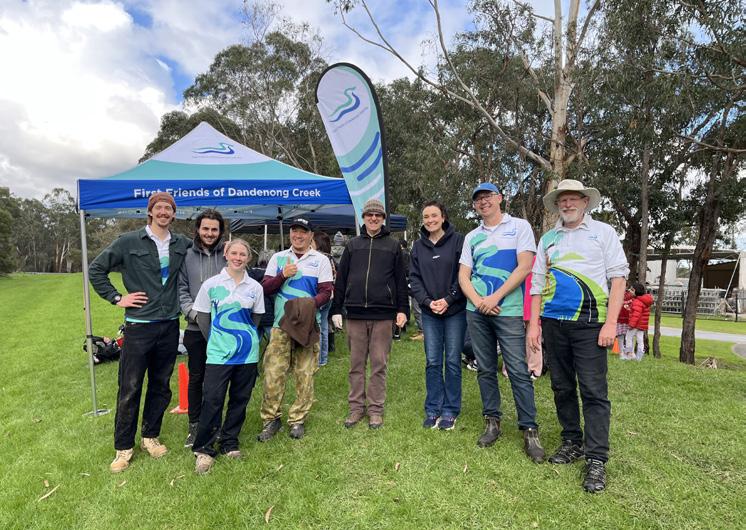
For more than 25 years, FFDC has worked alongside volunteers, community groups, businesses, councils and government agencies to restore and protect the Dandenong Creek corridor. While much has changed since the group was established in 1999, one thing has remained constant – meaningful environmental outcomes are achieved when people work together.
Each year, FFDC volunteers help establish more than 10,000 indigenous plants throughout the corridor, improving habitat connectivity and creating healthier ecosystems for native wildlife. These activities are supported by a broad network of partners, including local councils, Melbourne Water, Parks Victoria, EastLink and many others, all working towards the shared goal of a healthier and more resilient landscape.
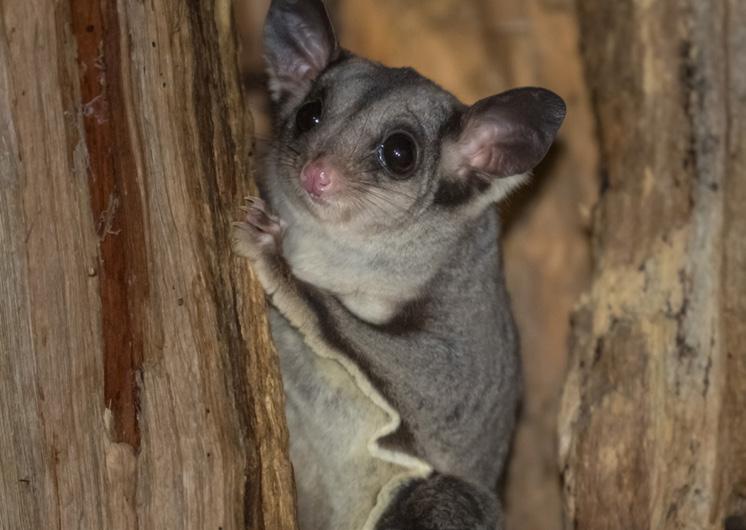
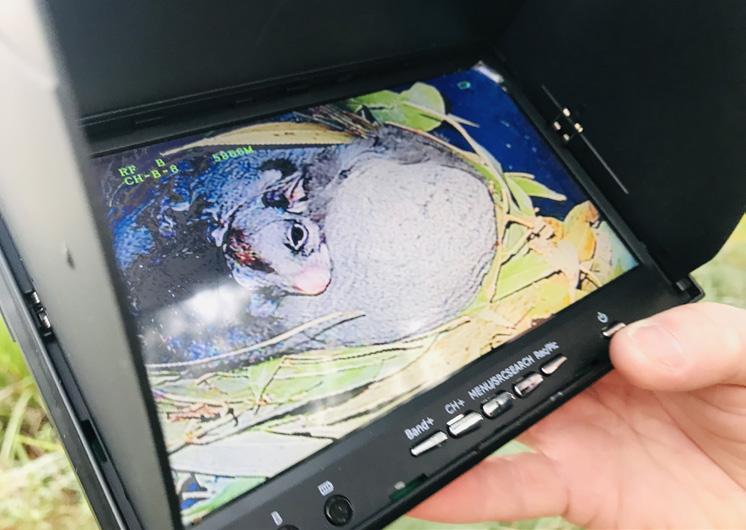
One of the group's most successful initiatives has been its sugar glider conservation program. Working with volunteers and partner organisations, more than 100 nest boxes have been installed throughout the corridor to provide additional habitat for these remarkable native mammals.
The nest boxes were built by the talented volunteers of the Ringwood Men's Shed, whose contribution has helped create safe nesting sites for sugar gliders across the catchment. Monitoring indicates that sugar glider numbers are increasing in areas where habitat improvements and nest boxes have been established, demonstrating the value of long-term community-led conservation.
Community involvement comes from many different directions. Local residents regularly volunteer alongside environmental groups, schools and organisations such as the Bliss and Wisdom community, whose members have enthusiastically supported planting and habitat restoration activities.
Businesses are also playing an increasingly important role. Through partnerships supported by Landcare Australia, corporate volunteer teams have contributed thousands of hours to environmental projects along the creek. These events not only deliver practical conservation outcomes but also help people connect with the natural environment and understand the importance of protecting local biodiversity.
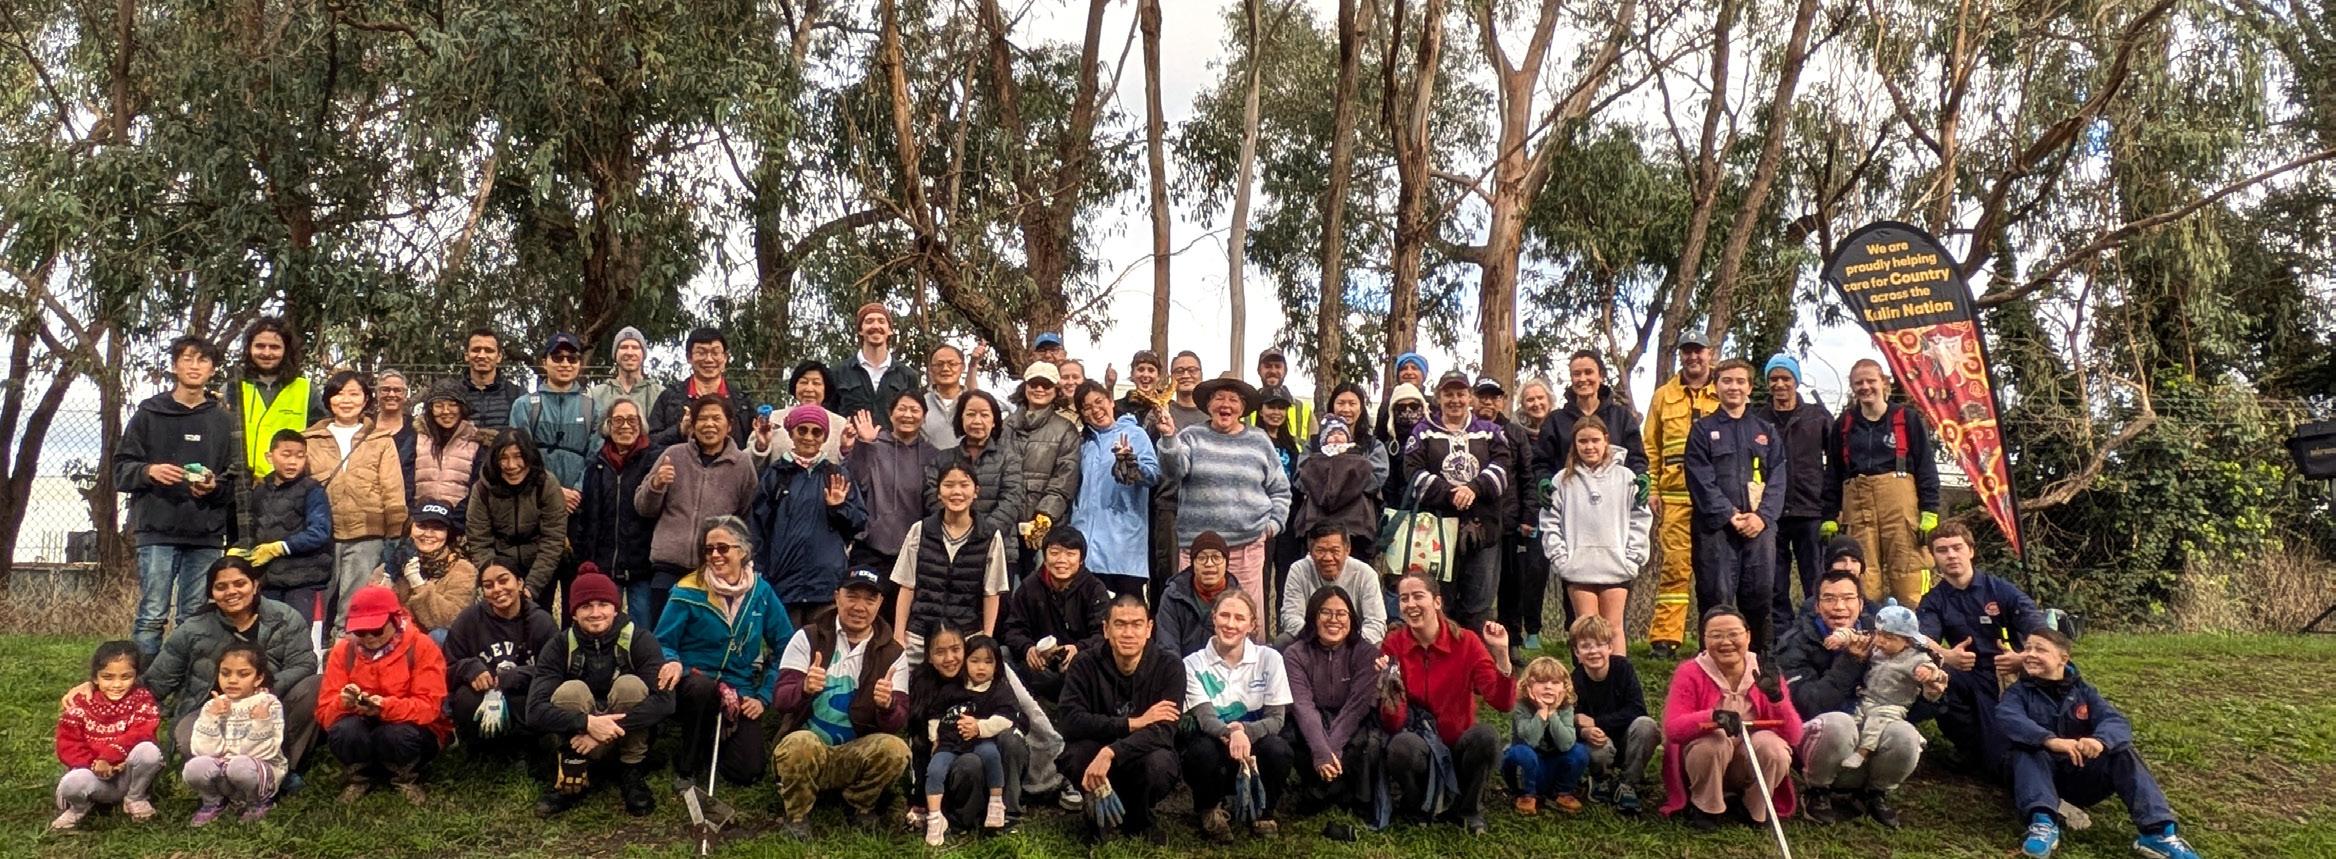
Recent planting events have highlighted the strength of this collective effort. More than 70 community members attended FFDC's World Environment Day planting event, establishing over 3,000 indigenous
plants in less than two hours. It was a powerful reminder of what can be achieved when a community comes together with a shared purpose.
While many of the improvements along the creek are immediately visible, much of FFDC's work is focused on long-term outcomes. Habitat restoration can take years, and sometimes decades, before the full benefits are realised. The trees planted today will provide future hollows, shade and food sources for wildlife, while stronger habitat connections help species move safely through the landscape.
For FFDC, conservation is about more than planting trees or installing nest boxes. It is about building a network of people who care about the future of their local environment and are prepared to contribute towards it.
Every volunteer, every partner organisation and every project plays a role in creating a healthier Dandenong Creek. Together, they are helping native wildlife thrive while leaving a lasting legacy for future generations.
Whether you're interested in volunteering, learning more about local wildlife, or simply following the progress being made along the creek, there are many ways to get involved. Visit www.ffdc. org.au to learn more, sign up for our newsletter, or connect with First Friends of Dandenong Creek on Facebook.
Anthony Bigelow
By Erryn Langley
As the calendar flips to July, a new financial year begins — and with it, a fresh opportunity to take stock, realign your goals, and build strong financial habits for the year ahead. Whether you're planning for retirement, growing your wealth, or simply trying to get better control of your cash flow, July is the ideal time to get organised.
Here are seven smart steps to set yourself up for a financially successful 2026–27.
1. Review the Year That Was
• Assess income, expenses, savings
• Did you meet your financial goals? What surprised you?
2. Reassess Your Financial Goals
• Update your short- and long-term goals
• Consider life changes (job, family, health, retirement plans)
3. Rebalance Your Portfolio
• Consider your preferred risk profile, do you need to rebalance your investments so that they are in line with your preferred asset allocation?
4. Plan Your Super Contributions Early
• Do you wish to set up monthly contributions (such as a salary sacrifice) to spread out cash flow?
• Consider carry-forward and bring-forward rules – if you are not sure what these are, do you need to seek professional financial advice?
5. Budget Refresh and Spending Audit
• Review your monthly cash flow
• Identify your planned budget, do you need to review your spending in any areas?
• Consider reviewing providers for things like car insurance, home insurance and health insurance. Could you save money by taking time to go through this process?
6. Documentation
• Would it help you to start the year off by keeping better records this year?
• Ensure you're keeping accurate records from the beginning of the financial year. Digital tools or apps can make this easy and efficient.
7. Estate Planning and Insurance Check
• Do you need to review beneficiaries, wills, powers of attorney?
• Check personal insurance cover (which may include Total and Permanent Disablement, Life cover, income protection and trauma cover), are these still appropriate for your circumstances?
The start of a new financial year is more than a date on the calendar — it’s an opportunity to take control of your finances and build momentum toward achieving goals.
Erryn Langley
Director and Financial Adviser - GradDipFinPlan
Authorised Representative No 1269525
T:1300 557 144 Email: erryn@cherrywealth.com.au
Website: www.cherrywealth.com.au
Office Address: Suite 4 / 4 - 6 Croydon Road, Croydon 3136
Postal Address: PO Box 657, Croydon VIC 3136
Financial Planning is offered via Cherry Wealth Pty Ltd ABN 14 653 375 458
Cherry Wealth is a Corporate Authorised Representative (No. 1314769) of Alliance Wealth Pty Ltd ABN 93 161 647 007 (AFSL No. 449221). Part of the Centrepoint Alliance group https://www.centrepointalliance. com.au/
Erryn Langley is Authorised representative (No. 1269525) of Alliance Wealth Pty Ltd.
This information has been provided as general advice.We may not have considered your financial circumstances, need or objectives. You should consider the appropriateness of the advice.You should obtain and consider the Product Disclosure Statement (PDS) and seek assistance from an authorised financial adviser before making any decisions regarding any products or strategies mentioned in this communication.
Whilst all care has been taken in the preparation of this material. It is based on our understanding of current regulatory requirements and laws as at the publication dates. As these laws are subject to change you should talk to an authorised adviser for the most up to date information. No warranty is given in respect of the information provided and accordingly neither Alliance Wealth nor its related entities, employees or representatives accepts responsibility for any loss suffered by any person arising from reliance on this information.
Financial Planner
10 herbs that have been researched for anxiety
NATUROPATH
By Kathryn Messenger
Anxiety disorders are often felt with symptoms such as worry, reduced concentration as well as with physical symptoms like insomnia, muscle tension, or digestive upsets. Pharmaceutical medications for anxiety usually target Gamma-aminobutyric acid (GABA), a neurotransmitter in the central nervous system, but these medications can have significant side effects. A scientific study found 10 herbs to be effective in treating anxiety by regulating GABA, and I’ll break these herbs down into different categories so that they’re easier to understand.
Just a quick warning about selfprescribing herbs at a therapeutic level. Usually, the amount you would have in a tea is a low enough dose that it is unlikely to cause any problems.
Some herbs are not meant to be taken long term, so always have your herbs checked with any medications you may be taking by a health care professional in case of interactions. If you do want to take therapeutic doses of herbs you would be best to get advice from a naturopath or herbalist, just to be sure of safety.
Anxiety with trouble sleeping
Hypnotic herbs: I know this sounds a bit weird and mystical, but it's actually just language that is not used the way
it used to be. In terms of herbs, this just means that they induce drowsiness or sleep.
These are not like drugs used for sleeping in that there is no hangover effect the next day, you would generally take these before bed, have a nice deep sleep and wake refreshed. The following herbs are all hypnotic herbs with their other actions for anxiety listed beside them:
Hops - mild sedative
Kava – anxiolytic (alleviates anxiety), mild sedative, muscle relaxant
Passionflower - mild sedative, anxiolytic
Valerian - anxiolytic, mild sedative
Other herbs for anxiety
This next group of herbs cover a variety of actions. When I’m choosing a herb to go into a herbal medicine mix, I’m very aware of the other symptoms in the person I’m treating. So, I would choose a different one depending on what else this person is presenting with.
Chamomile - mild sedative
Gotu kola - nervous system tonic, adaptogen
Gingko - cognition enhancing, neuroprotective
Withania - mild sedative, adaptogen
My favourite 2 herbs for anxiety
These next 2 herbs, I use a lot, the first one is calming to the digestive tract, I find it really effective in cases of anxiety that presents itself with digestive issues,
or if the person has digestive issues and anxiety, it also works really well. The second is my absolute go to for anxiety. It’s a nervous system tonic that’s calming, so it works to gently calm and relax the nervous system, bringing it into balance.
Lemon balm - mild sedative
Skullcap - nervous system tonic, mild sedative
Herbal teas
Some of these herbs you will find available as teas. This is a safe low dose way to take herbs. You will need to have the tea more than once each day and for at least a month or so, to see some difference in your anxiety. For a therapeutic dose of herbs, a naturopath or herbalist can help make up an individual herbal mix.
GABA-modulating phytomedicines for anxiety: A systematic review of preclinical and clinical evidence
Kathryn Messenger
BHSc (Naturopathy)
kathryn@wholenaturopathy.com.au
Suite 1 53/1880 Ferntree Gully Rd
Mountain Gate Shopping Centre Ferntree Gully, Victoria
Setting Up Payroll in Xero: Get It Right From Day One
By Jodie Moore
Setting up payroll is one of those jobs that’s easy to overlook—until payday arrives. The good news is that spending a little extra time getting everything set up correctly from the start will save you hours of headaches later.
Not only does a well-configured payroll system ensure your employees are paid accurately and on time, but it also helps you stay compliant with ATO requirements. With the introduction of Payday Super, it’s now more important than ever to have your payroll and superannuation processes working together seamlessly.
Here’s a simple guide to setting up payroll in Xero the right way.
Step 1: Gather Everything You Need
Before you jump into Xero, collect all the information you’ll need for each employee, including:
• Personal and contact details
• Employment status
• Tax File Number (TFN)
• Superannuation details
• Bank account information
• Tax declaration information
Having this information ready before you begin makes the setup process much smoother.
You’ll also need to make sure you’re on a Xero plan that includes payroll features suitable for your business.
Step 2: Set Up Your Payroll Accounts
The next step is connecting payroll to your accounting records.
Within the Payroll Overview,
you’ll:
• Add the bank account wages will be paid from.
• Select your payroll expense accounts.
• Select your payroll liability accounts.
If your business bank account already exists in Xero, simply select it. Otherwise, add it before continuing.
This ensures every pay run is recorded correctly in your accounts from the very beginning.
Step 3: Create Your Pay Schedule
Next, tell Xero how often you’ll pay your employees.
Whether you pay weekly, fortnightly or monthly, you’ll need to:
Choose the pay frequency.
• Give it a name.
• Set the start date.
• Enter the first payment date.
Once saved, Xero will use this schedule to create your future pay runs.
Step 4: Customise Your Payslips
A few small settings can make your payslips look much more professional.
You can choose whether to display:
• Annual salary
• Employment basis
• Your company logo
These settings only take a few minutes and give employees clear, consistent payslips.
Step 5: Add Your Employees
Now it’s time to add your team. For each employee, enter:
• Basic details
• Contact information
• Employment details
• Tax information
• Superannuation details
• Bank account information
It’s also worth inviting employees to Xero Me, where they can securely access payslips, submit leave requests and complete timesheets. This reduces paperwork and gives employees easy access to their payroll information.
Don’t Forget Superannuation
Super isn’t something you want to leave until later. In fact, with Payroll Super now in place, you simply can’t leave it.
Before you process your first pay run, make sure every employee has the correct super fund assigned.
You can add:
• Regulated super funds
• Self-managed super funds (SMSFs)
If an employee doesn’t provide their Superannuation Standard Choice Form, you’re required to search for their stapled super fund through the ATO before paying them into a default fund. Keep in mind that you must lodge the employee’s TFN declaration before you can perform this search.
Once your super funds have been added into Xero, assign the correct fund to each employee so contributions are allocated correctly during every pay run.
Why Automatic Super Is Now Essential
With the rollout of Payday Super, employers are expected to process super contributions much closer to the time employees are paid.
That means manual super processing every few months simply won’t be practical anymore.
Setting up Automatic Super in Xero from the beginning can save significant time, reduce the risk of missing payment deadlines and help keep your business compliant.
To register for Automatic Super you’ll need:
• Payroll administrator access.
• An Australian bank account connected to Xero.
• An active bank feed (this can take several business days to activate).
• A nominated payroll authoriser with an Australian mobile number for SMS approvals.
Once registered, Xero can automatically process super contributions as part of your regular payroll workflow.
This means wages and super can be processed together, making Payday Super compliance much easier and reducing the chance of forgotten or late super payments.
Check Your Employee Information
Before running your first payroll, doublecheck that each employee has:
• TFN recorded
• Mobile number
• Email address
• Gender
• Correct super fund
• Correct bank account
• Tax settings completed
A few minutes spent checking these details now can prevent rejected payments and unnecessary corrections later.
Ready for Your First Pay Run
Once your payroll accounts, employees, pay schedules and Automatic Super are all set up, you’re ready to process your first pay run with confidence.
Getting payroll right from day one means:
• Employees are paid correctly and on time.
• Super contributions are processed correctly.
• Your payroll records stay accurate.
• You remain compliant with ATO requirements.
• You spend less time fixing payroll mistakes later.
Payroll doesn’t have to be complicated. A thorough setup at the beginning— especially with Automatic Super enabled—creates a smooth, reliable payroll process that grows with your business and keeps you prepared for the new Payday Super requirements.
Help the local community know you exist and what sets you apart compared to other aged care facilities, Financial Planners and other providers in the local area.
We have developed Find Aged Care Services (www.findagedcare.services) so you can promote your facilities and services to the general public. You can also place any job vacancies on our website that is available in your facilities. For more information, please contact us at 1300 88 38 30 or email info@findagedcare.services
Maroondah Council News JULY 2026
National Tree Day
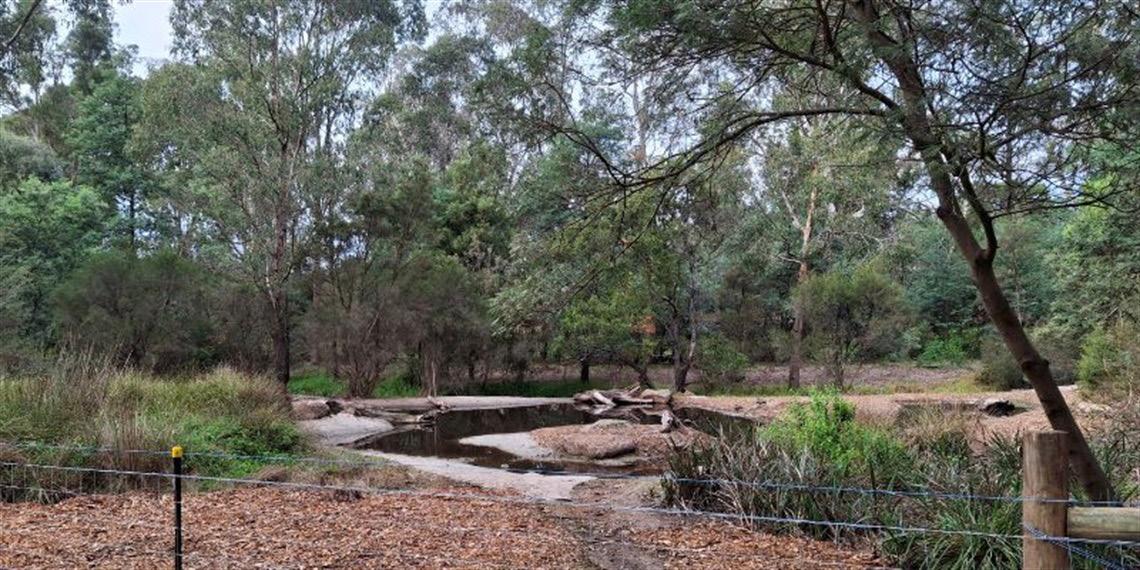
Join us and help plant 4,000 indigenous plants to enhance the biodiversity in the area and create more habitat for our native wildlife.
The plants for this event have been provided by local indigenous nursery CRISP and were funded through the 2025 Green Links Grant thanks to the Department of Energy, Environment and Climate Action (DEECA).
Event details
• Date: Sunday 26 July 2026
• Time: 10am onwards
• Venue: Mullum Mullum Creek, rear of 49 Sonia Street, Ringwood. Access is via Mullum Mullum Creek trail, east of Mullum Mullum Reserve carpark, or via the path cut through between 47 and 49 Sonia Street. We encourage attendees to walk or cycle along the creek where possible as parking will be very limited.
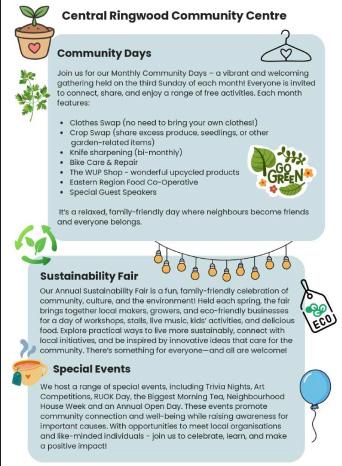
CRCC Community Hub Day - Bin Besties
Walking at Night
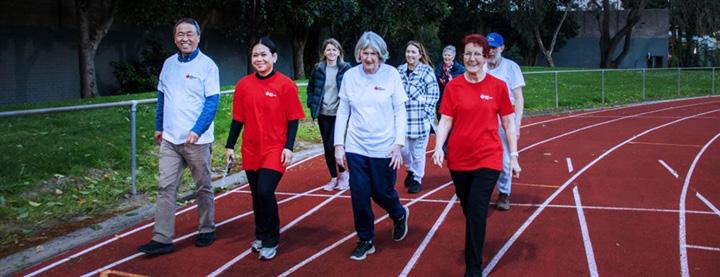
From June to October, the lights are turned on at Town Park athletics track in Croydon between 5.30 pm to 8.30 pm, so it is safer to get out and exercise, especially during the winter months.
Walking at night details
• Date: Thursdays (from 4 June)
• Time: 5.30 pm to 8.30 pm
• Location: Town Park Athletics Track - Croydon. Located behind the Arndale shops, Civic Square. Parking at Civic Square and entry from Norton Road
• Access: Flat athletics track perfect for walking and running, and pram/wheelchair access
• Toilets: On-site. Open until 8.30 pm
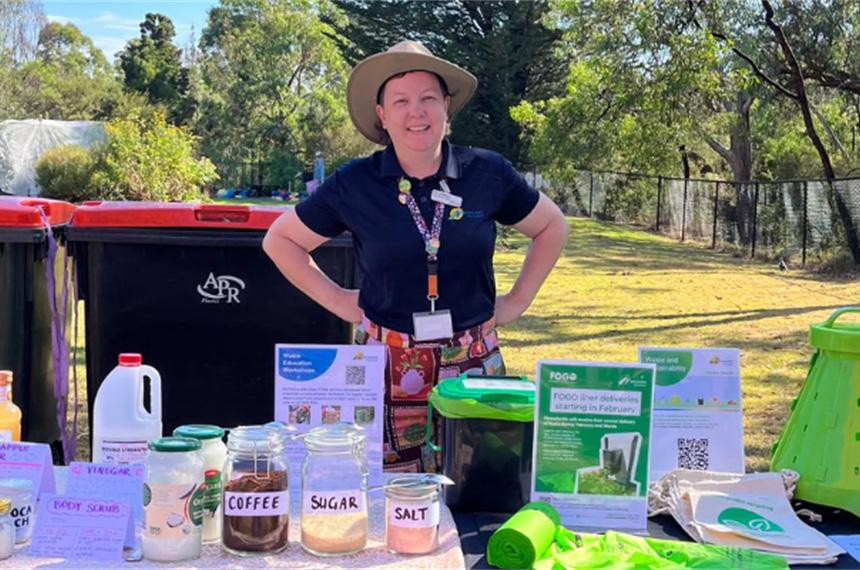
Pop down to the Community Hub day this July to chat to Council's Waste Educators about the upcoming bin lid swap, as well as getting the chance to chat about what can be recycled, what happens to your FOGO or how to dispose of tricky items around your home.
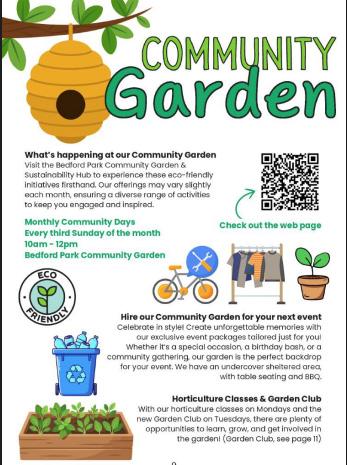
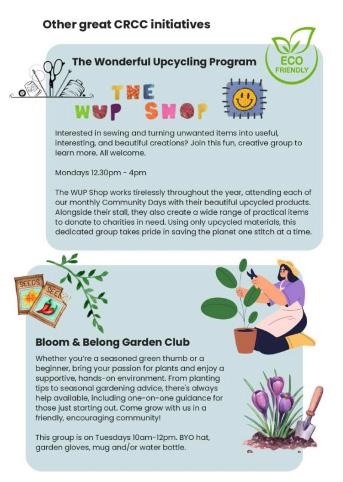
The Community Hub day also has a crop swap, clothes share, soft plastic recycling, The WUP shop and more!
Event details
• Date: Sunday 19 July 2026
• Time: 10am to 12noon
• Venue: Bedford Park Community Garden (behind Central Ringwood Community Centre)
• Cost: Free
When Thursday, 02 July 2026 | 05:30 PM - 08:30 PM Thursday, 09 July 2026 | 05:30 PM - 08:30 PM Thursday, 16 July 2026 | 05:30 PM - 08:30 PM Thursday, 23 July 2026 | 05:30 PM - 08:30 PM
Council is once again supporting National Tree Day by hosting a free planting day at Mullum Mullum Creek in Ringwood.
Get ready to embark on a nostalgic journey with hit parade, an extraordinary tribute to the unforgettable hits of the 1950s and 1960s. Led by the remarkable Glenn Starr.
This sensational show has been delighting audiences across the country and around the world for the past 10 years. From corporate events, venues and theatres to headlining on cruise ships, hit parade has become renowned for its exceptional performances and its unique repertoire that sets it apart from the rest.
Hit parade goes beyond the well-known classics, featuring a carefully curated selection of songs and artists that may not receive as much exposure in today’s music landscape. The show reintroduces the enchanting melodies and timeless voices of– Bobby Vee, Gene Pitney, Neil Sedaka, Del Shannon, Gerry and the Pacemakers, The Honeycombs, Guy Mitchell, Johnny Burnett, and many more. And of course, it wouldn’t be a tribute to the 50s and 60s without paying homage to the biggest icons of the era, including Elvis Presley, Buddy Holly, Roy Orbison, and The Beatles.
What sets hit parade apart is its ability to transport the audience back to their childhoods, invoking cherished memories and creating a powerful sense of nostalgia.
The Hit Parade of the 50s & 60s
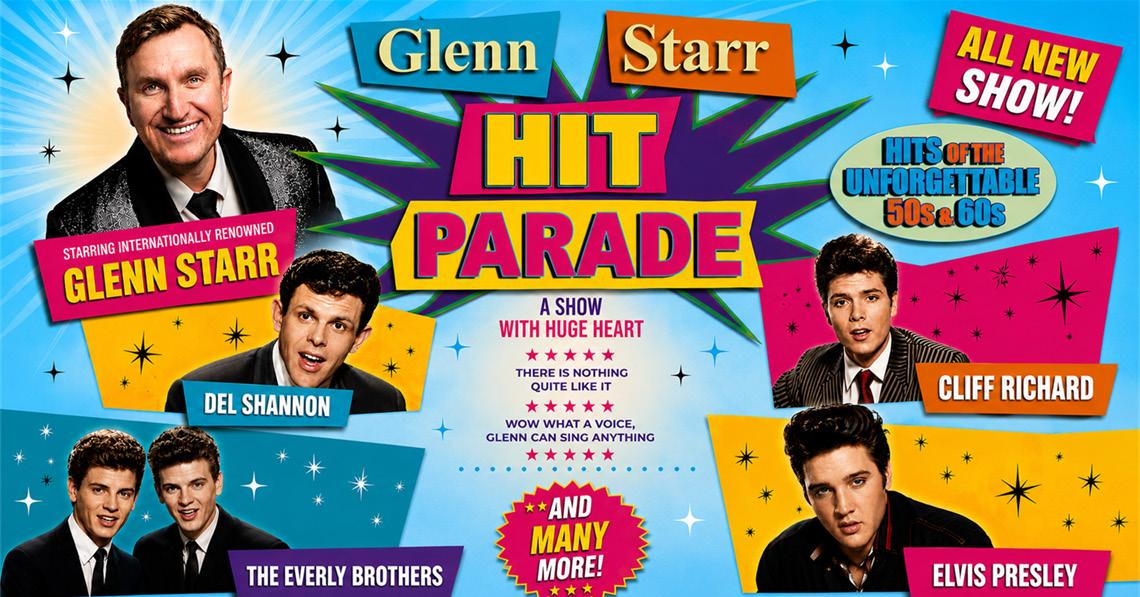
Audience members have been captivated by the show, with many exclaiming, “I’ve never seen a show like this!” It has been hailed as the best morning melodies show they’ve experienced. Even seasoned cruisers, who have spent 20 years sailing the seas, attest that they have never encountered a show quite as remarkable as hit parade.
When Sunday, 19 July 2026 | 02:00 PM - 04:30 PM
Parenting After Separation - webinar for parents and carers
This free webinar is for parents and carers who want to create a positive and supportive environment for their children after separation.
You will learn how separation and related confl ict can impact children, and practical ways to support your child as you move from being former partners to effective co - parents. This includes:
• focusing on children’s needs
• practical communication strategies
• why self - care matters
• how to work together as parents
• where to fi nd more information and support.
Session details
• Date: Monday 20 July
• Time: 7.30pm to 9pm
• Venue: Online via Zoom
• Facilitator: John Ravesi, Relationships Australia Victoria
• Cost: Free. Registrations are essential
• This session does not meet the requirements of any court or parenting orders.
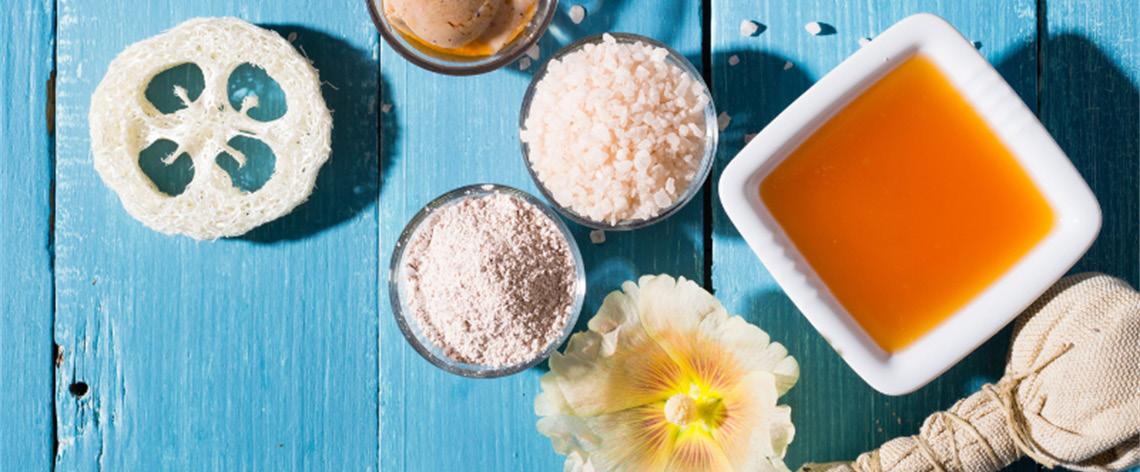
Take control of your skincare routine with Mademoiselle Organic this Plastic Free July. Learn how to ditch singleuse plastics from your skincare and craft your own highperformance deodorant. This workshop is all about straightforward solutions, natural ingredients, and making sustainability second nature. Walk away with a product you made yourself and the confi dence to keep your routine clean and green.
Event details
• Date: Wednesday 22 July 2026
• Time: 6pm to 7.30pm
• Venue: Realm Library (The Cave). 179 Maroondah Hwy, Ringwood
• Presenter: Mademoiselle Organic
• Cost: Free
• Bookings are essential
• Auslan Interpreters available upon request
About the presenter
Lily is a natural and DIY beauty coach and runs Mademoiselle Organic in Melbourne. In her workshops, online courses and blog, she teaches how to use organic and natural ingredients instead of harsh and polluting chemicals. All her workshops are vegan and inclusive. All the ingredients we'll use are biodegradable.


NOT-FOR-PROFIT FOR THE
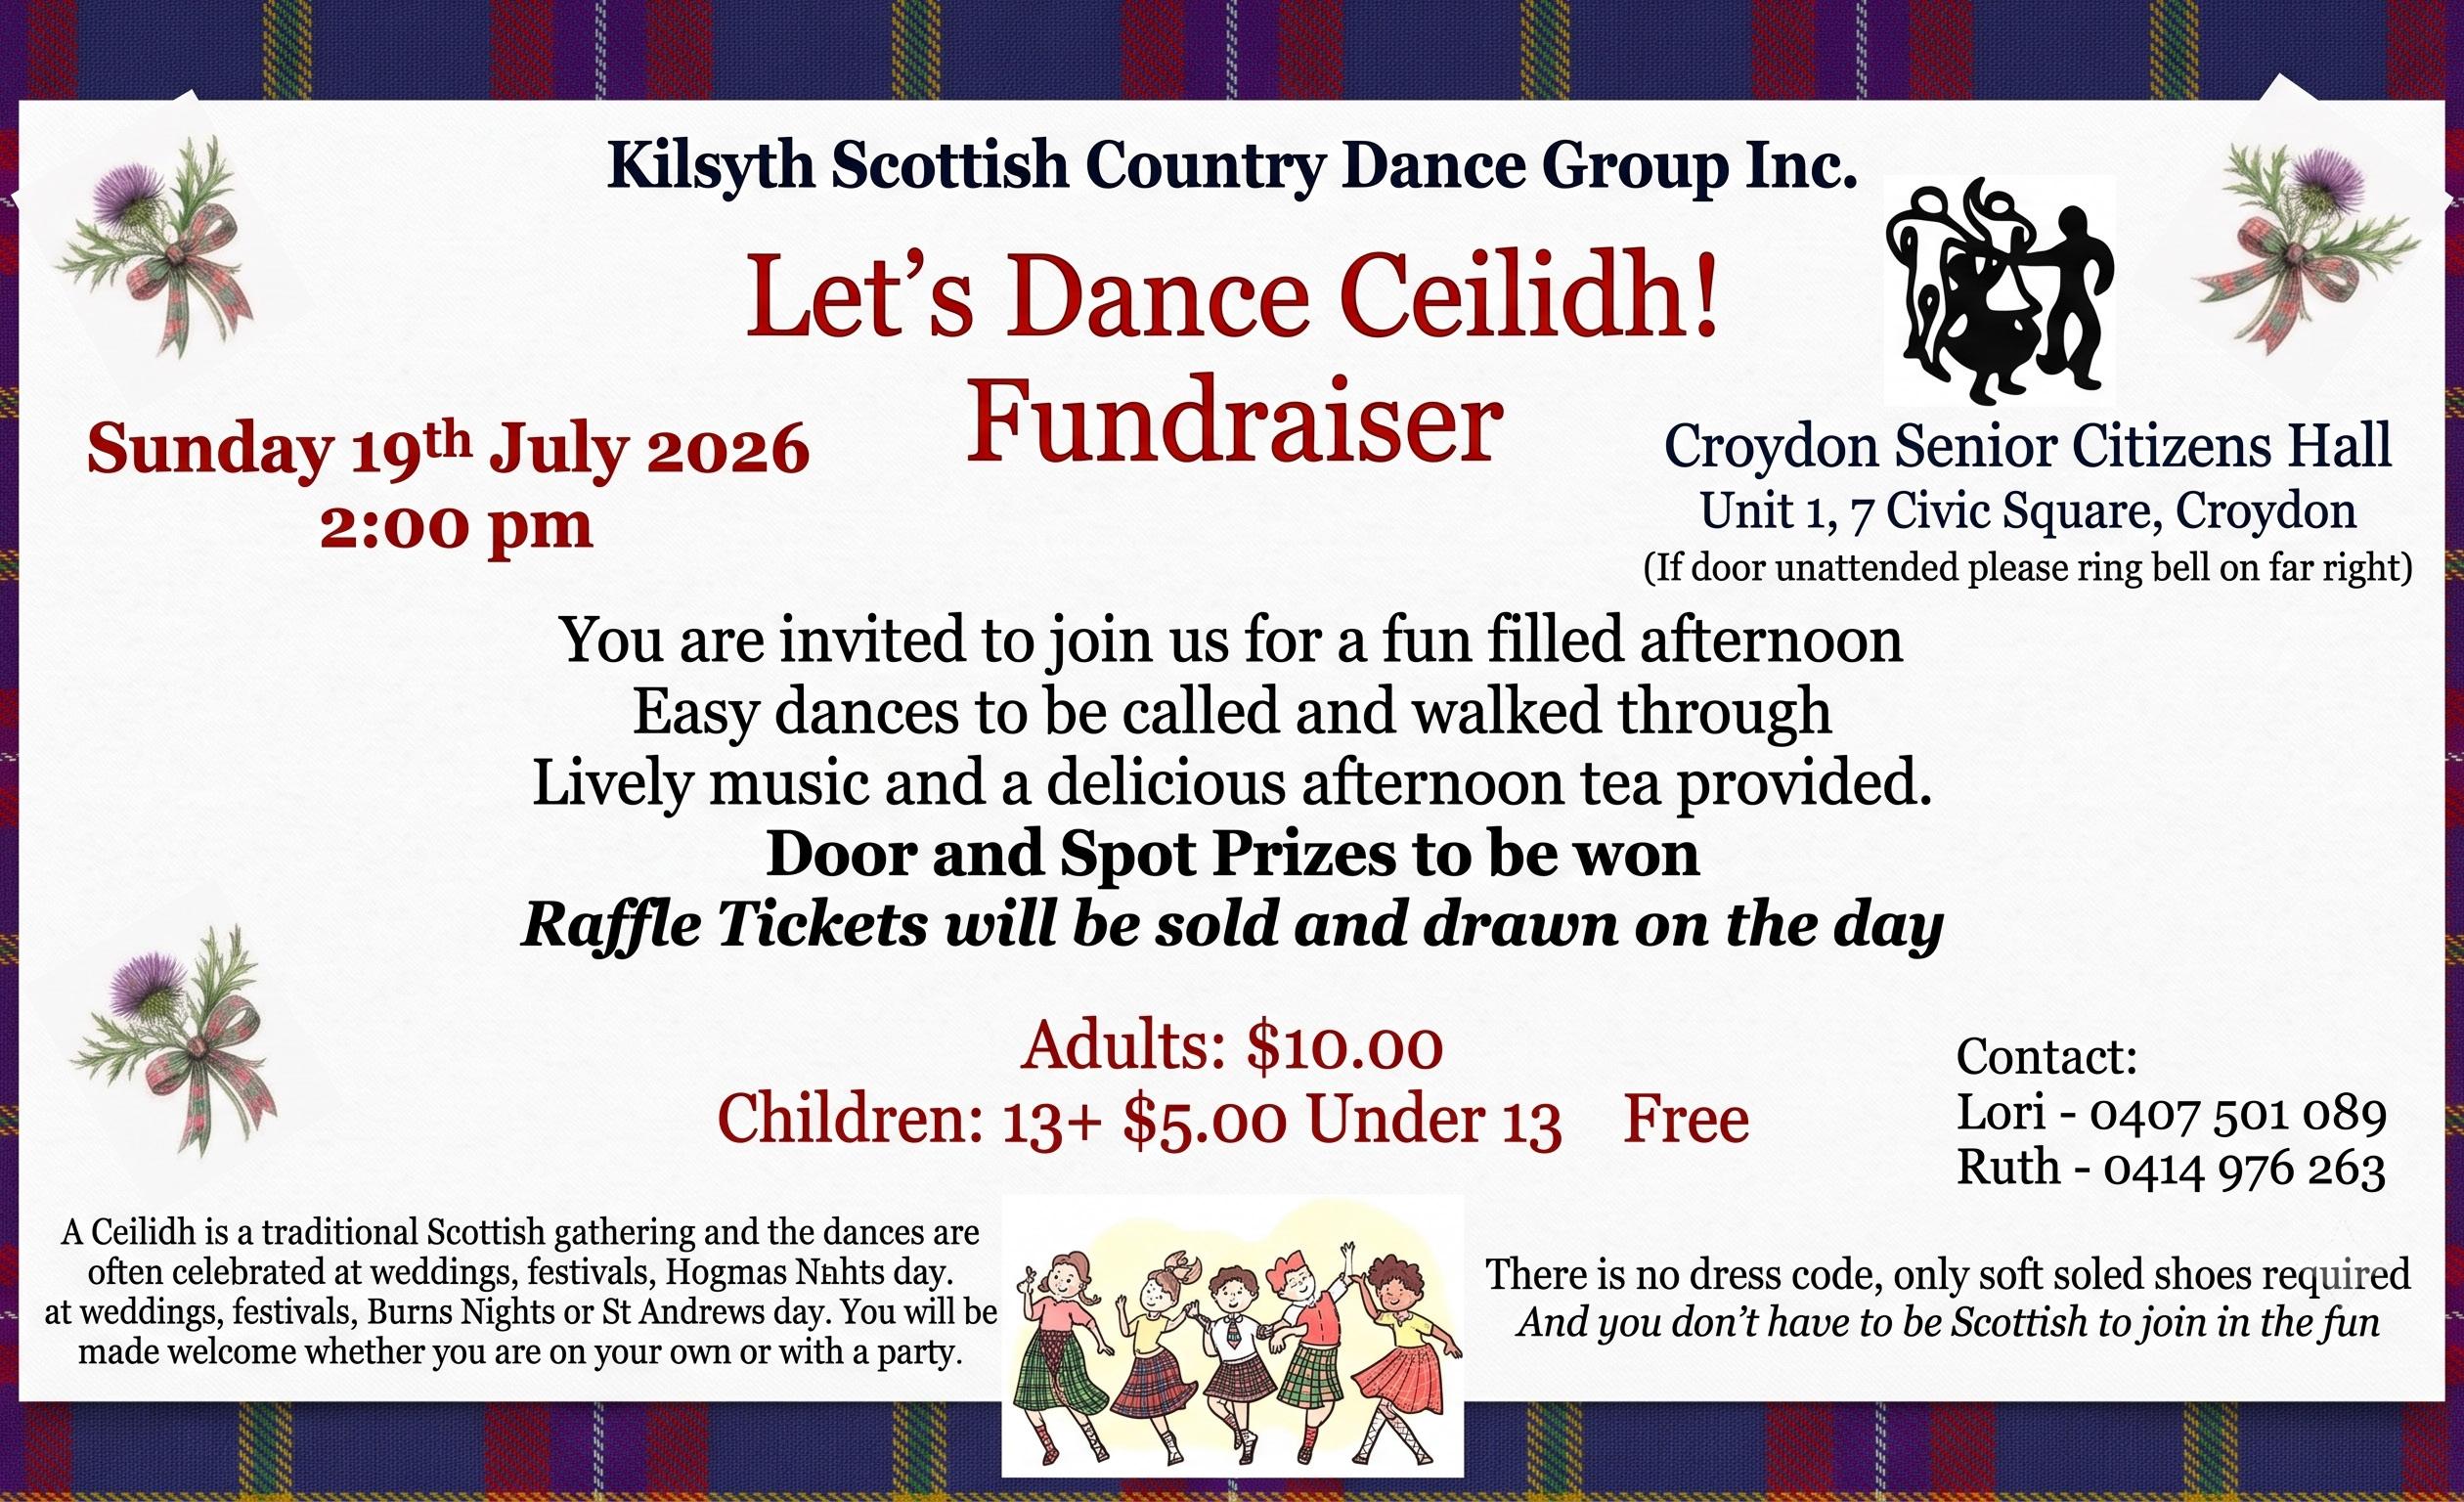
KILSYTH SCOTTISH COUNTRY
– Janet Johnston What members say about KSCD
"Scottish Country Dancing lets you catch up with the RSCDS family wherever you are in the world."
"Oh, the joy of great Scottish music, dancing and friends in the heart of marvelous Melbourne."
– Margaret Gawler
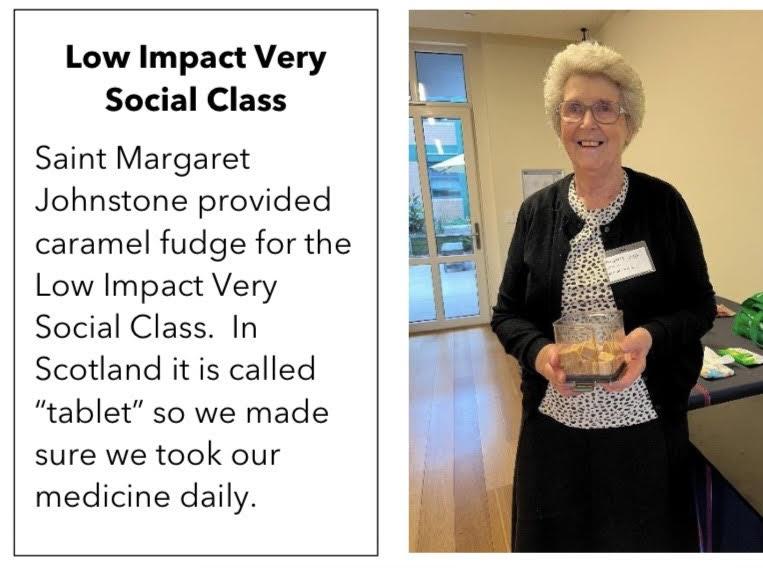
Celebrating 50 years scottish country dancing:
Our dancing group was started in 1976 by Kilsyth area. Originally, it was a children’s parents became enthusiastic, took over, Bobbie and Alan Malone moved to Bendigo to start the St. Andrew’s class in Bendigo.
We are a non-profit group, and we aim to teach those who are interested, the forming a dance. Scottish Country Dancing Scotland, and it is danced all over the World. we dance in sets of 6 or 8 dancers. There it is not something that happens overnight, laughter when we try to get it right. SCD is a great social activity. Our Group is small to see some new faces come along and
This year we are celebrating our 50th Anniversary held in the Whitehorse Club, East Burwood, all looking forward to this event as it will for this special occasion. If there is any aware of someone who danced at Kilsyth,
In 2012, a letter was asking for permission was refused. An article local Historian, Mr in touch with the Melbourne
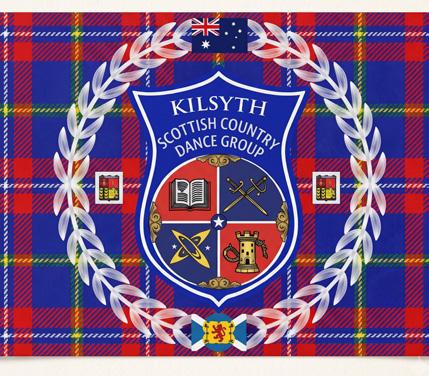
The Secretary passed contacted him. William designed our background is the Kilsyth Tartan, which old Coat of Arms of Kilsyth, Scotland. with the Australian flag, and the centre
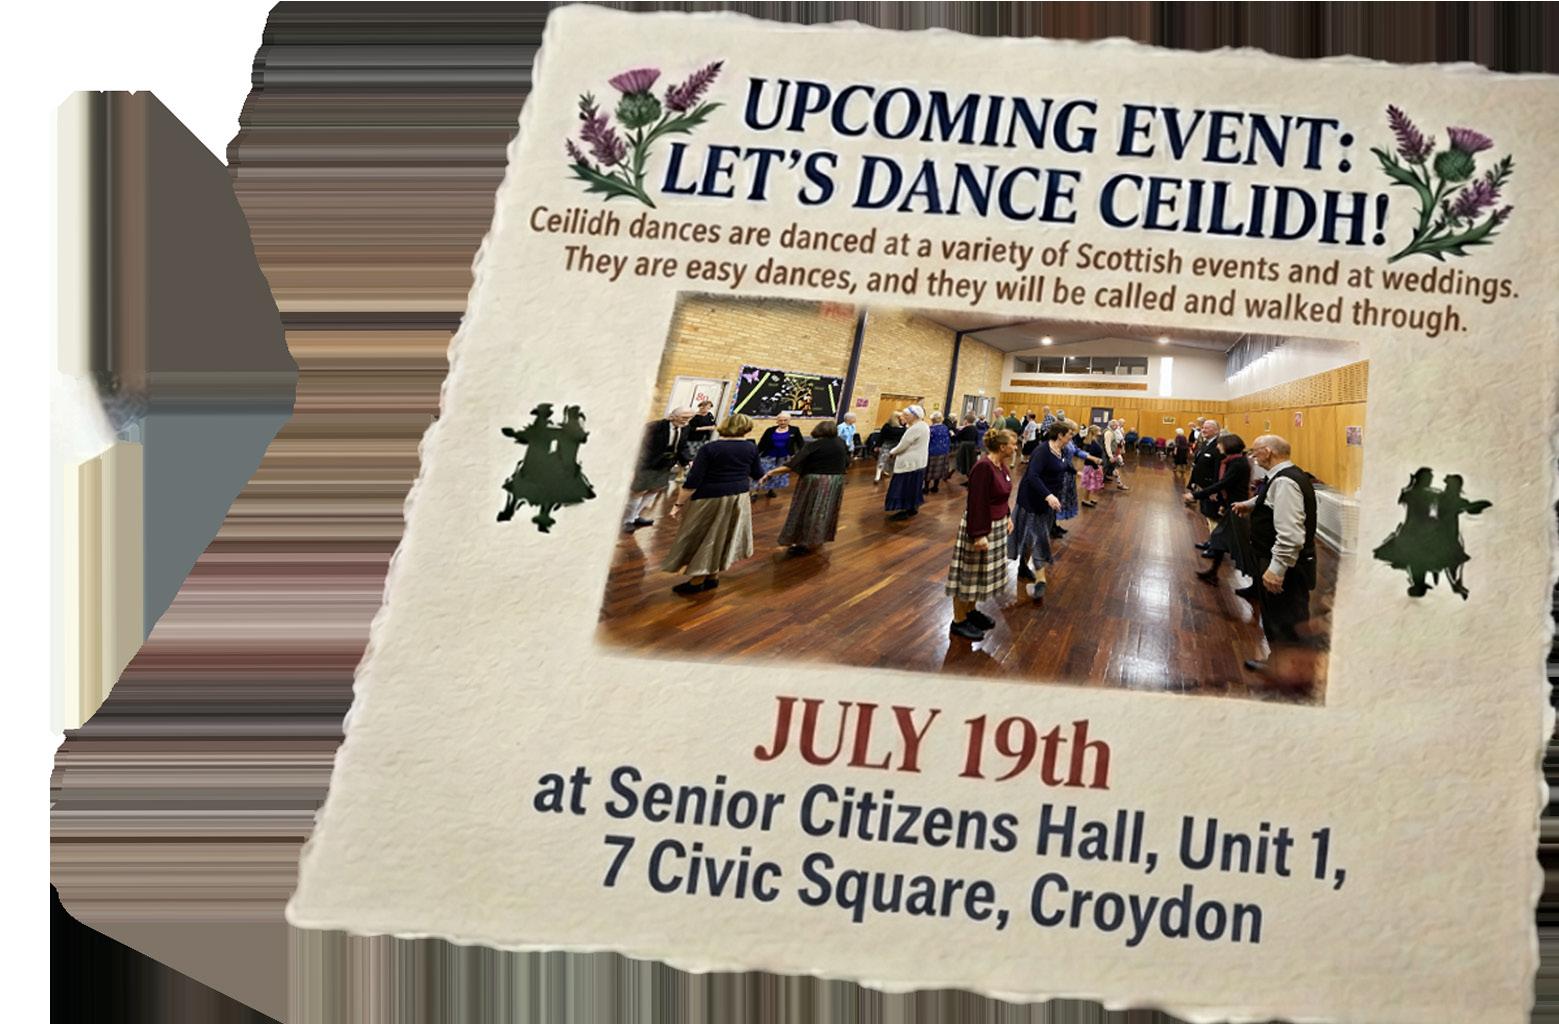
Why not come along and experience enjoyable, low-cost way to stay active, friendships in a welcoming community. before, you'll be warmly welcomed. discover why so many people
THE MONTH OF JULY 2026
COUNTRY DANCE GROUP INC
years of kilsyth dancing: 1976 -2026
by Bobbie Malone, who lived in the children’s class, but somehow or other, the over, and it became a class for adults. Bendigo in 1983, and Bobbie then went on Sadly, Bobbie passed away in 2012.
to connect with the community and the steps and formations that go into Dancing is the social form of dancing in World. Unlike Highland (solo dancing) There is some technique involved, and overnight, but we do have a lot of fun and SCD is good for the Mind and Body and small and friendly, and we would love and give SCD a go.
Anniversary with a Ball which is being Burwood, on the 17th October, 2026. We are will be a formal event with live music any reader of this magazine who is, or is Kilsyth, we would love to hear from them.
was sent to Kilsyth Council in Scotland permission to use their Coat of Arms, but this article was put in the local paper, a William Chalmers, read this and got Melbourne & District Branch of RSCDS. passed on his details to us, and we then logo, which we are very proud of. The which he designed, and it incorporates the Scotland. Centre top of the logo is embedded centre bottom is the Lion Rampant.
experience the fun for yourself? Scottish Country Dancing is an improve coordination and memory, and make lasting
Whether you're a complete beginner or have danced Join us for a class or our "Let's Dance Ceilidh!" and people love Scottish Country Dancing.
| www.crccinc.org.au
www.facebook.com
www.facebook.com www.facebook.com
www.facebook.com | www.crccinc.org.au
| www.crccinc.org.au
| www.facebook.com
www.easternsirenssynchro.com.au
ASIC Warns Australians to Think Carefully Before Switching Super Funds
RETIREMENT
By Warren Strybosch
Switching superannuation funds can sometimes be the right decision. A better investment menu, lower fees, improved insurance, access to specialist investment options or retirement income features may all justify making a change.
However, changing superannuation should never be based on fees alone. Every person’s financial circumstances are different, and what may be appropriate for one individual may not be suitable for another.
At Find Retirement, we believe every recommendation to switch superannuation should be based on whether it improves a client’s overall retirement outcome. While fees are an important consideration, they form only one part of a much broader assessment that includes insurance, investment options, taxation, retirement objectives, estate planning, service levels and the client’s individual circumstances.
This approach is consistent with the Australian Securities and Investments Commission’s (ASIC) recently released Report 833 (REP 833), which highlights concerns about inappropriate superannuation switching and reinforces that any recommendation to change funds should be made solely in the member’s best interests.
When Switching Makes Sense
ASIC has been clear that it supports members switching to another superannuation fund where doing so genuinely improves their retirement outcomes.
The regulator has long encouraged trustees and financial advisers to help members become more informed and confident in choosing the superannuation fund that best suits their needs.
A recommendation to switch may be appropriate where it provides an overall benefit after considering factors such as:
• Ongoing administration and investment costs.
• Advice fees and how they are charged.
• Insurance benefits and premiums.
• Investment choice and flexibility.
• Historical investment performance.
• Retirement income features.
• Tax implications.
• Estate planning considerations.
• The level of advice and ongoing service provided.
• The client’s personal objectives, financial situation and needs.
Importantly, no single factor should determine whether a person changes super funds. A lower-cost product is not necessarily a better product if valuable benefits or features are lost in the process.
ASIC’s Concern: Switching for the Wrong Reasons
While ASIC supports appropriate switching, it has expressed significant concern about what it describes as “inappropriate superannuation switching.”
According to REP 833, this occurs where consumers are encouraged or pressured to move their retirement savings into another super fund, a platform product or a self-managed superannuation fund (SMSF) despite receiving little or no benefit themselves.
ASIC is particularly concerned about business models where:
• advisers recommend unnecessary superannuation switches;
• clients receive generic or “cookie-cutter” advice that does not adequately consider their personal circumstances;
• excessive advice fees erode retirement savings;
• lead generation businesses refer large numbers of clients to advisers without providing appropriately licensed advice; or
• clients are recommended unnecessarily complex, illiquid or high-risk investments.
ASIC noted that these practices can significantly reduce retirement savings and referred to enforcement action involving the First Guardian Master Fund as an example of the potential consumer harm that can arise where inappropriate advice is provided.
Recent legislative changes may also reduce one historical reason for recommending SMSFs. Following amendments to the law, from 10 August 2026, SMSFs are prohibited from entering into new limited recourse borrowing arrangements (LRBAs) to acquire residential property, although existing arrangements are generally grandfathered. This change was introduced through the Treasury Laws Amendment (Improving Australia’s Financial Markets) Act 2026.
What ASIC Found
As part of REP 833, ASIC reviewed:
• Six superannuation trustees;
• $2.56 billion in advice fees; and
• 720,000 advised members
The regulator identified several areas requiring improvement.
Advice Fee Controls
ASIC found that many trustees had inadequate controls around advice fee deductions.
Some of the findings included:
• Percentage-based advice fee caps ranging from 1.66% to 10%;
• A maximum dollar-based advice fee cap of $25,000;
• One trustee proposing to increase its cap to $30,000; and
• Three trustees having no upper dollar limit on advice fees.
ASIC expressed concern that these arrangements could permit excessive deductions from members’ accounts, particularly where balances are larger.
Protecting Low-Balance Members
The report also found that protections for members with smaller balances were often insufficient.
Only one trustee required a minimum account balance before advice fees could be deducted, while another had additional protections for balances below $100,000.
ASIC indicated that stronger safeguards are needed to reduce the risk of balance erosion for members with lower superannuation balances.
Monitoring Financial Advice
ASIC also identified shortcomings in how trustees monitored financial advice.
Among the findings were:
• More than 2,580 advice reviews identified almost 250 adverse findings.
• One trustee completed only 21 advice reviews, with 75% containing adverse findings.
• Three trustees failed to conduct any advice reviews for at least one month during the review period.
• Monitoring of adviser activity, advice fees and investment flows often relied heavily on manual processes, increasing the potential for human error.
The regulator also found trustees were not always adequately monitoring indicators such as member churn, unusual investment flows or excessive advice fees.
What Should Consumers Consider Before Switching?
ASIC’s report should not discourage Australians from changing superannuation funds where doing so is genuinely in their best interests.
Rather, it reinforces the importance of ensuring any recommendation is based on a thorough assessment of the client’s circumstances rather than sales targets, referral arrangements or remuneration.
Before making a decision, consumers should ask questions such as:
• Why is this recommendation suitable for my circumstances?
• What benefits will I gain by switching?
• What benefits, insurance or features might I lose?
• What are the total costs, including administration fees, investment fees, adviser fees and transaction costs?
• Are there any tax consequences?
• How do the investment options compare?
• Will the expected long-term benefits outweigh the costs and risks of changing funds?
A quality financial adviser should be able to explain both the advantages and disadvantages of any recommendation and demonstrate why the proposed strategy is expected to improve the client’s overall retirement position.
Every Client’s Circumstances Are Different
While fees often receive the most attention, they represent only one component of an appropriate superannuation strategy.
In some cases, changing superannuation arrangements may reduce overall costs. In others, remaining in an existing fund may be the more appropriate outcome once insurance benefits, investment features, retirement income options, taxation and other factors are taken into account.
No recommendation should be based solely on fees or investment performance in isolation.
At Find Retirement, our philosophy is that every recommendation should be supported by a comprehensive comparison of the available options, with any proposed switch clearly demonstrating how it aligns with the client’s objectives and best interests.
The Bottom Line
Superannuation is one of the largest assets most Australians will accumulate during their lifetime. Decisions about changing superannuation funds should never be rushed or based solely on marketing material, cold calls or generic advice.
ASIC’s REP 833 serves as an important reminder that while switching super funds can deliver better outcomes in appropriate circumstances, every recommendation should be carefully considered, appropriately documented and focused on the member’s long-term interests.
If you are considering changing your superannuation arrangements, seek professional advice that carefully evaluates both the advantages and disadvantages of your existing fund and any proposed alternative before making a decision.
If you are about to retire,consider making an appointment with Find Retirement. The first meeting is free. Warren Strybosch, an award-winning financial planner and an accountant, will review your current super and go through the benefits of Find Retirement looking after you and your investments in retirement.
Warren Strybosch Award Winning Financial Adviser
Part of the Find Group of Companies
Financial Planning, SMSF, Super, Insurance, Pre-Retirement & Retirement Planning (Financial Planning) are offered via Find Wealth Pty Ltd ACN 140 585 075 t/a Find Wealth, Find Insurance and Find Retirement. Find Wealth Pty Ltd is a Corporate Authorised Representative (No 468091) of Alliance Wealth Pty Ltd ABN 93 161 647 007 (AFSL No. 449221). Part of the
Centrepoint Alliance group (www.centrepointalliance.com.au/fsg/aw).
Warren Strybosch
Authorised Representative (No. 468091) of Alliance Wealth Pty Ltd.
This information has been provided as general advice.We have not considered your financial circumstances, needs or objectives. You should consider the appropriateness of the advice. You should obtain and consider the relevant Product Disclosure Statement (PDS) and seek the assistance of an authorised financial adviser before making any decision regarding any products or strategies mentioned in this communication.
Whilst all care has been taken in the preparation of this material, it is based on our understanding of current regulatory requirements and laws at the publication date. As these laws are subject to change you should talk to an authorised adviser for the most up-to-date information. No warranty is given in respect of the information provided and accordingly neither Alliance Wealth nor its related entities, employees or representatives accepts responsibility for any loss suffered by any person arising from reliance on this information.
Social Security Thresholds Increase from 1 July 2026
Beyond the Aged Care Strategy: How Professional Investment Management Can Help Families Through One of Life’s Most Difficult Transitions
AGED CARE
By Warren Strybosch
Planning for aged care is often viewed as a numbers exercise. Can Mum or Dad afford residential aged care?
Should they pay a Refundable Accommodation Deposit (RAD) or Daily Accommodation Payment (DAP)?
Should the family home be retained or sold?
How will the estate be affected?
While these are all critical questions, they are often only the beginning of a much longer journey.
Once an older Australian enters residential aged care or begins receiving significant care at home, responsibility frequently shifts to an Enduring Power of Attorney (ePOA). This trusted individual—often an adult child—is suddenly responsible for managing hundreds of thousands, and sometimes millions, of dollars on behalf of their parent.
For many families, this can become one of the most stressful aspects of the aged care journey.
The Hidden Responsibility of an Enduring Power of Attorney
Acting as an Enduring Power of Attorney is a position of significant responsibility.
The appointed attorney is expected to act in the best interests of the person they represent, manage their finances prudently, maintain appropriate records and ensure sufficient funds are available to meet ongoing care costs.
As Australia’s aged care system becomes increasingly complex under the Aged Care Act 2024, this responsibility has grown considerably.
Parents are now more likely to spend years receiving homebased care before entering residential aged care. They may face ongoing co-contributions, accommodation costs, health expenses and changing cash flow requirements.
Managing investments is no longer simply about generating returns. It is about ensuring the right amount of income is available at the right time while preserving capital where appropriate and maintaining sufficient liquidity to meet future care needs.
The Family Dynamics
One of the greatest challenges faced by many Enduring Powers of Attorney has nothing to do with investments.
It is family.
It is common for one child to be appointed as attorney while several siblings remain beneficiaries of the estate.
Even where everyone has the best intentions, disagreements can arise.
Questions often include:
• Why was the home sold?
• Why wasn’t it sold sooner?
• Why were certain investments purchased?
• Why is so much cash sitting in the bank?
• Why did the portfolio lose value?
• Could Mum or Dad have earned a better return?
• Were investment decisions made in their best interests?
These questions often arise years after the decisions were made, when emotions are heightened following the death of a parent.
While no adviser can prevent family disagreements, having independent professionals involved in financial decisionmaking can provide an additional layer of transparency and accountability.
Going Beyond Advice
Many advisers provide an aged care strategy.
They prepare projections, explain accommodation options, estimate future care costs and recommend an appropriate funding approach.
At Find Retirement, we provide retirement and aged care advice, and we believe our role does not end once the strategy has been implemented.
We continue working with families by professionally managing the parent’s investments throughout their retirement and aged care journey.
This means the investment portfolio is continually monitored and adjusted as circumstances change.
As care costs increase, additional cash flow can be generated.
As legislation changes, strategies can be reviewed.
As markets fluctuate, investment decisions are made within an agreed investment framework rather than through emotional reactions during already stressful periods.
Supporting the Enduring Power of Attorney
Professional investment management also provides valuable support to the appointed Enduring Power of Attorney.
Rather than making every investment decision themselves, the attorney can rely on qualified investment professionals
operating within an agreed investment strategy that reflects the parent’s objectives, liquidity requirements and tolerance for risk.
This creates a documented investment process supported by professional advice, regular portfolio reviews and ongoing reporting.
For many families, this provides confidence that decisions are being made objectively and consistently, rather than relying solely on the judgement of one family member.
It can also assist the attorney in demonstrating that financial decisions were made prudently, transparently and with appropriate professional input.
A Practical Example
Consider Margaret, aged 84.
Margaret has entered residential aged care following a fall. Her financial position includes:
• Family home worth $900,000
• Investment portfolio of $550,000
• Cash of $25,000
Her daughter Sarah has been appointed as Enduring Power of Attorney.
Following the sale of Margaret’s home and payment of a Refundable Accommodation Deposit, Sarah is left managing several hundred thousand dollars to fund ongoing care fees, medical expenses and future lifestyle costs.
Sarah has two brothers who are equal beneficiaries of Margaret’s estate.
Every investment decision Sarah makes has the potential to be questioned.
Should she leave the funds in cash?
Should she invest them?
Should she take more or less risk?
Should income or capital growth be the priority?
Rather than carrying this responsibility alone, Sarah engages Find Retirement to manage Margaret’s investments.
An investment strategy is established based on Margaret’s expected care costs, liquidity requirements and estate objectives.
The investments are professionally managed, reviewed regularly and adjusted as circumstances change.
Depending on the client’s estate planning objectives, the investments can bypass the probate process and be paid directly to nominated beneficiaries, such as adult children, providing faster access to funds.
Sarah remains responsible as Enduring Power of Attorney, but she has the comfort of knowing investment decisions are supported by qualified professionals and documented through an ongoing advice process.
More Than Just Funding Aged Care
At Find Retirement, we believe successful aged care planning is about much more than calculating whether someone can afford care today.
It is about helping families manage what may be many years of changing care costs, investment decisions and family responsibilities.
Professional investment management helps ensure assets continue working to support quality care, preserve financial flexibility and align with the parent’s broader retirement and estate objectives.
Just as importantly, it provides ongoing support to the family member entrusted with managing those assets.
For many Enduring Powers of Attorney, knowing they are not making complex financial decisions alone can provide enormous peace of mind during one of life’s most challenging periods.
Because aged care isn’t simply about funding care.
It’s about protecting dignity, preserving family relationships and ensuring a lifetime of savings continues to work for the person who earned them.
Warren Strybosch Award winning Financial Adviser
Part of the Find Group of Companies
Financial Planning, SMSF, Super, Insurance, Pre-Retirement & Retirement Planning (Financial Planning) are offered via Find Wealth Pty Ltd ACN 140 585 075 t/a Find Wealth, Find Insurance and Find Retirement. Find Wealth Pty Ltd is a Corporate Authorised Representative (No 468091) of Alliance Wealth Pty Ltd ABN 93 161 647 007 (AFSL No. 449221). Part of the
Centrepoint Alliance group (www.centrepointalliance.com.au/fsg/aw).
Warren Strybosch
Authorised Representative (No. 468091) of Alliance Wealth Pty Ltd.
This information has been provided as general advice. We have not considered your financial circumstances,needs or objectives. Youshouldconsidertheappropriatenessoftheadvice.Youshould obtain and consider the relevant Product Disclosure Statement (PDS) and seek the assistance of an authorised financial adviser before making any decision regarding any products or strategies mentioned in this communication.
Whilst all care has been taken in the preparation of this material,it is based on our understanding of current regulatory requirements and laws at the publication date. As these laws are subject to change you should talk to an authorised adviser for the most up-to-date information. No warranty is given in respect of the information provided and accordingly neither Alliance Wealth nor its related entities, employees or representatives accepts responsibility for any loss suffered by any person arising from reliance on this information.
•
Special Tax Return Offer
$99 Returns - PAYG Only
We
Here are the steps involved:
1. Email to info@findaccountant.com.au requesting your PAYG return to be completed. Provide us with your full name, D.O.B and address
2. A Tax engagement letter will be emailed to you for signing via your mobile (no
3. You will be then sent a tax checklist to complete online. Takes less than 5 minutes.
4. We will then require you to upload your documents to our secure portal.
5. Once we have received all your documentation, we will complete the return.
6. We will email you the completed return with our invoices. Once you sign the return and pay the invoice we will lodge the return on your behalf.
1300 88 38 30
•
•
We specialise in the following:
• Biz Pack Insurance
• Landlord Insurance
• Public Liability Insurance
• Professional Indemnity Insurance.
We DO NOT provide advice or quotes for the following (you need to go direct and save):
• Car Insurance
• Home & Contents
• Caravan
• eBikes
We work with only the most reputable insurers to bring you a range of insurance options for you to choose from:
HELPING TO PROTECT YOU AND YOUR FAMILY
At Find we can help you find the ‘right’ personal insurance. Our aim is to help you obtain and retain the personal insurances that are appropriate for you and at cost that you can afford.
• Income Protection (IP)
• Life Insurances or Death Cover
• Total and Permanent Disability (TPD) Personal Insurances Include:
When your insurance are in place, our services do not stop there. We will provide you with an after care service that includes policy notifications, insurance report, help desk, reviews and help at claim time. We provide ourselves in providing honest advice that you can rely on.

warren@findinsurance.com.au

www.findinsurance.com.au


•
Best Kept Parenting Secret






INDEX
PROFESSIONAL SERVICES
• Lactation Consultant ----------- 35
• Swen Pouches ---------------------- 00
• Hair Dresser --------------------------- 00
• Chiropractor ------------------------- 00
• Beauty Therapy -------------------- 00
• Gym --------------------------------------- 00
• Massage Therapy ---------------- 00
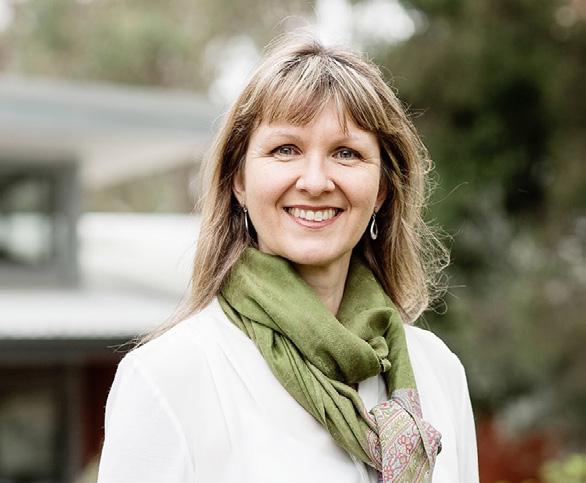
DR JOANNA STRYBOSCH
|
OSTEOPATHY
Osteopathy in Australia is a government registered, allied health profession. Osteopaths focus on improving the function of the neuro-musculoskeletal system (bones, muscles, nerves and connective tissues) to optimise health and well-being.
Joanna is highly qualified and experienced in the osteopathic assessment and treatment of babies and infants.
She can assist with the following assessments:
• Gross motor development (milestones)
• Primitive reflexes
• Tongue function and it’s relation to sucking skills
• Biomechanics of the jaw and mouth
• Help increase or decrease milk supply ADVANCED PAEDIATRIC OSTEOPATH & LACTATION CONSULTANT PROVIDING PERSONAL & CARING SUPPORT FOR YOU & YOUR BABY
LACTATION CONSULTING
IBCLC lactation consultants are recognised around the world as the experts in lactation care. They provide evidencebased knowledge to assist mothers to establish and maintain breastfeeding. As professionals, they are charged with promoting, protecting and supporting breastfeeding.
Joanna can help with a broad range of lactation consulting services, including:
• Teaching a new mum how to hold and position her baby to breastfeed
• Assess the suck, swallow and breathing of an infant
• Assess for tongue function and determine any evidence of restriction (tongue tie)
• Pre and post-frenectomy breastfeeding support
Discover
In-Kind Sponsorship with Find Maroondah Community Paper
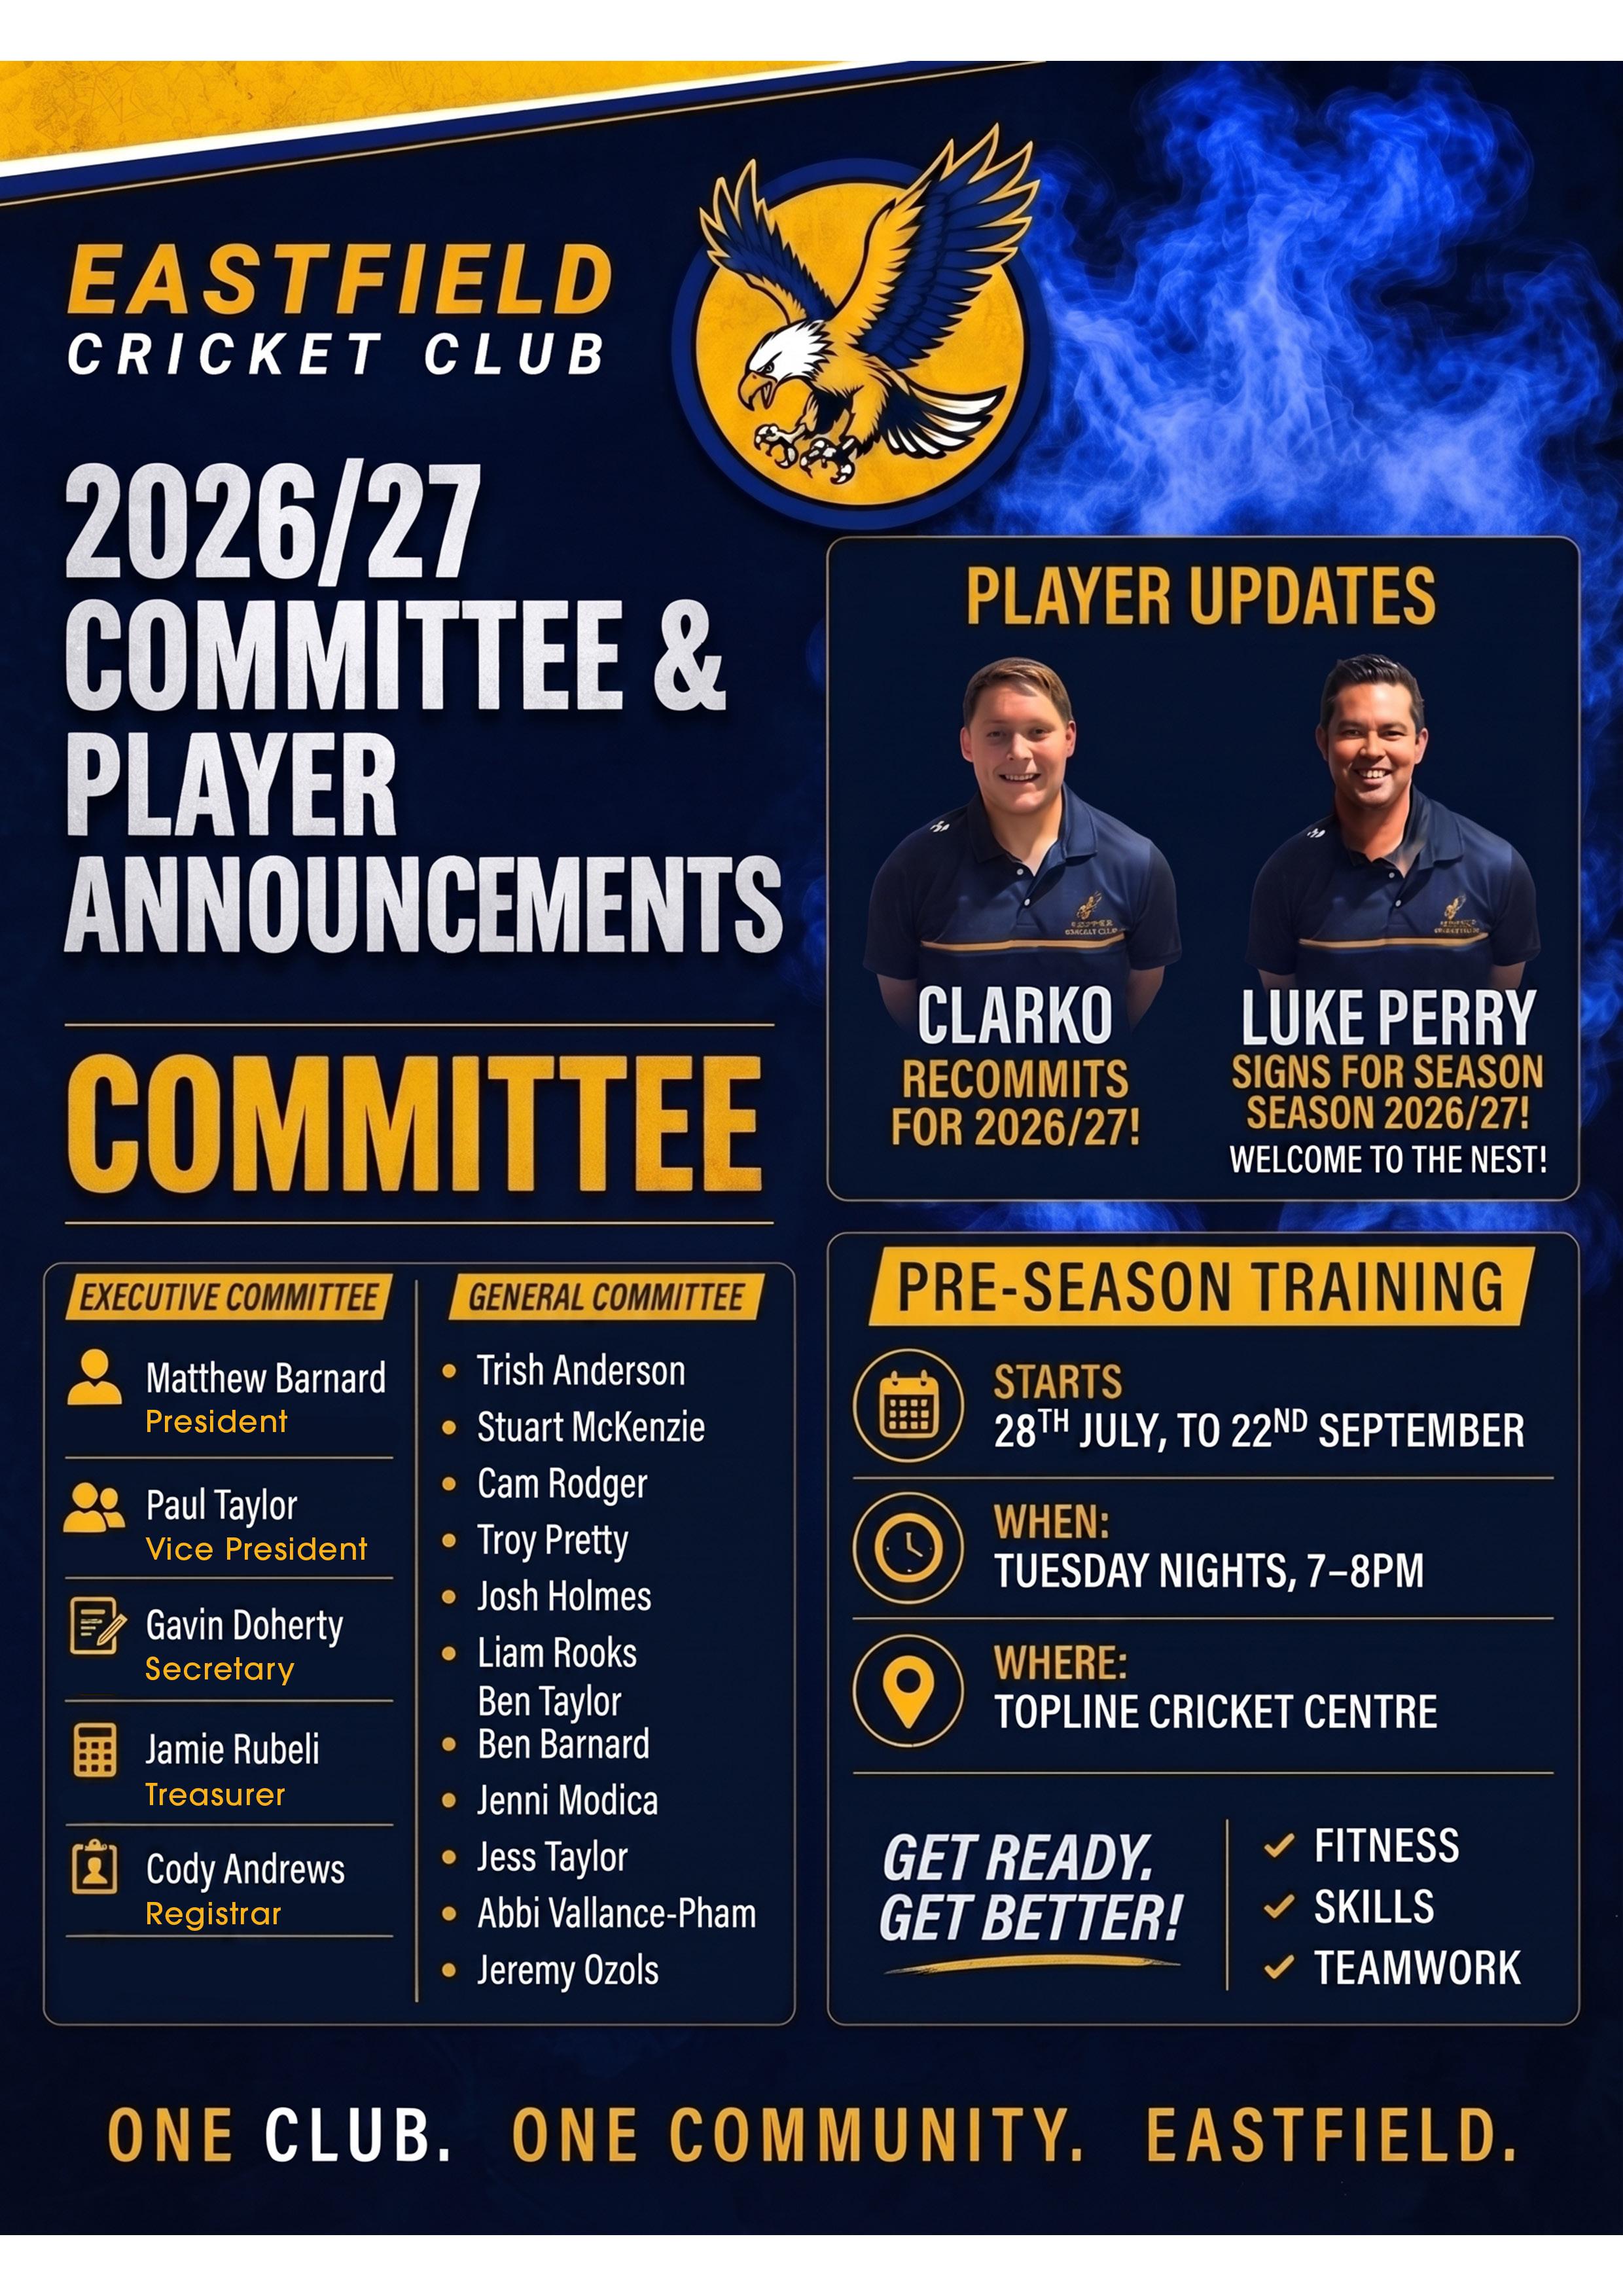
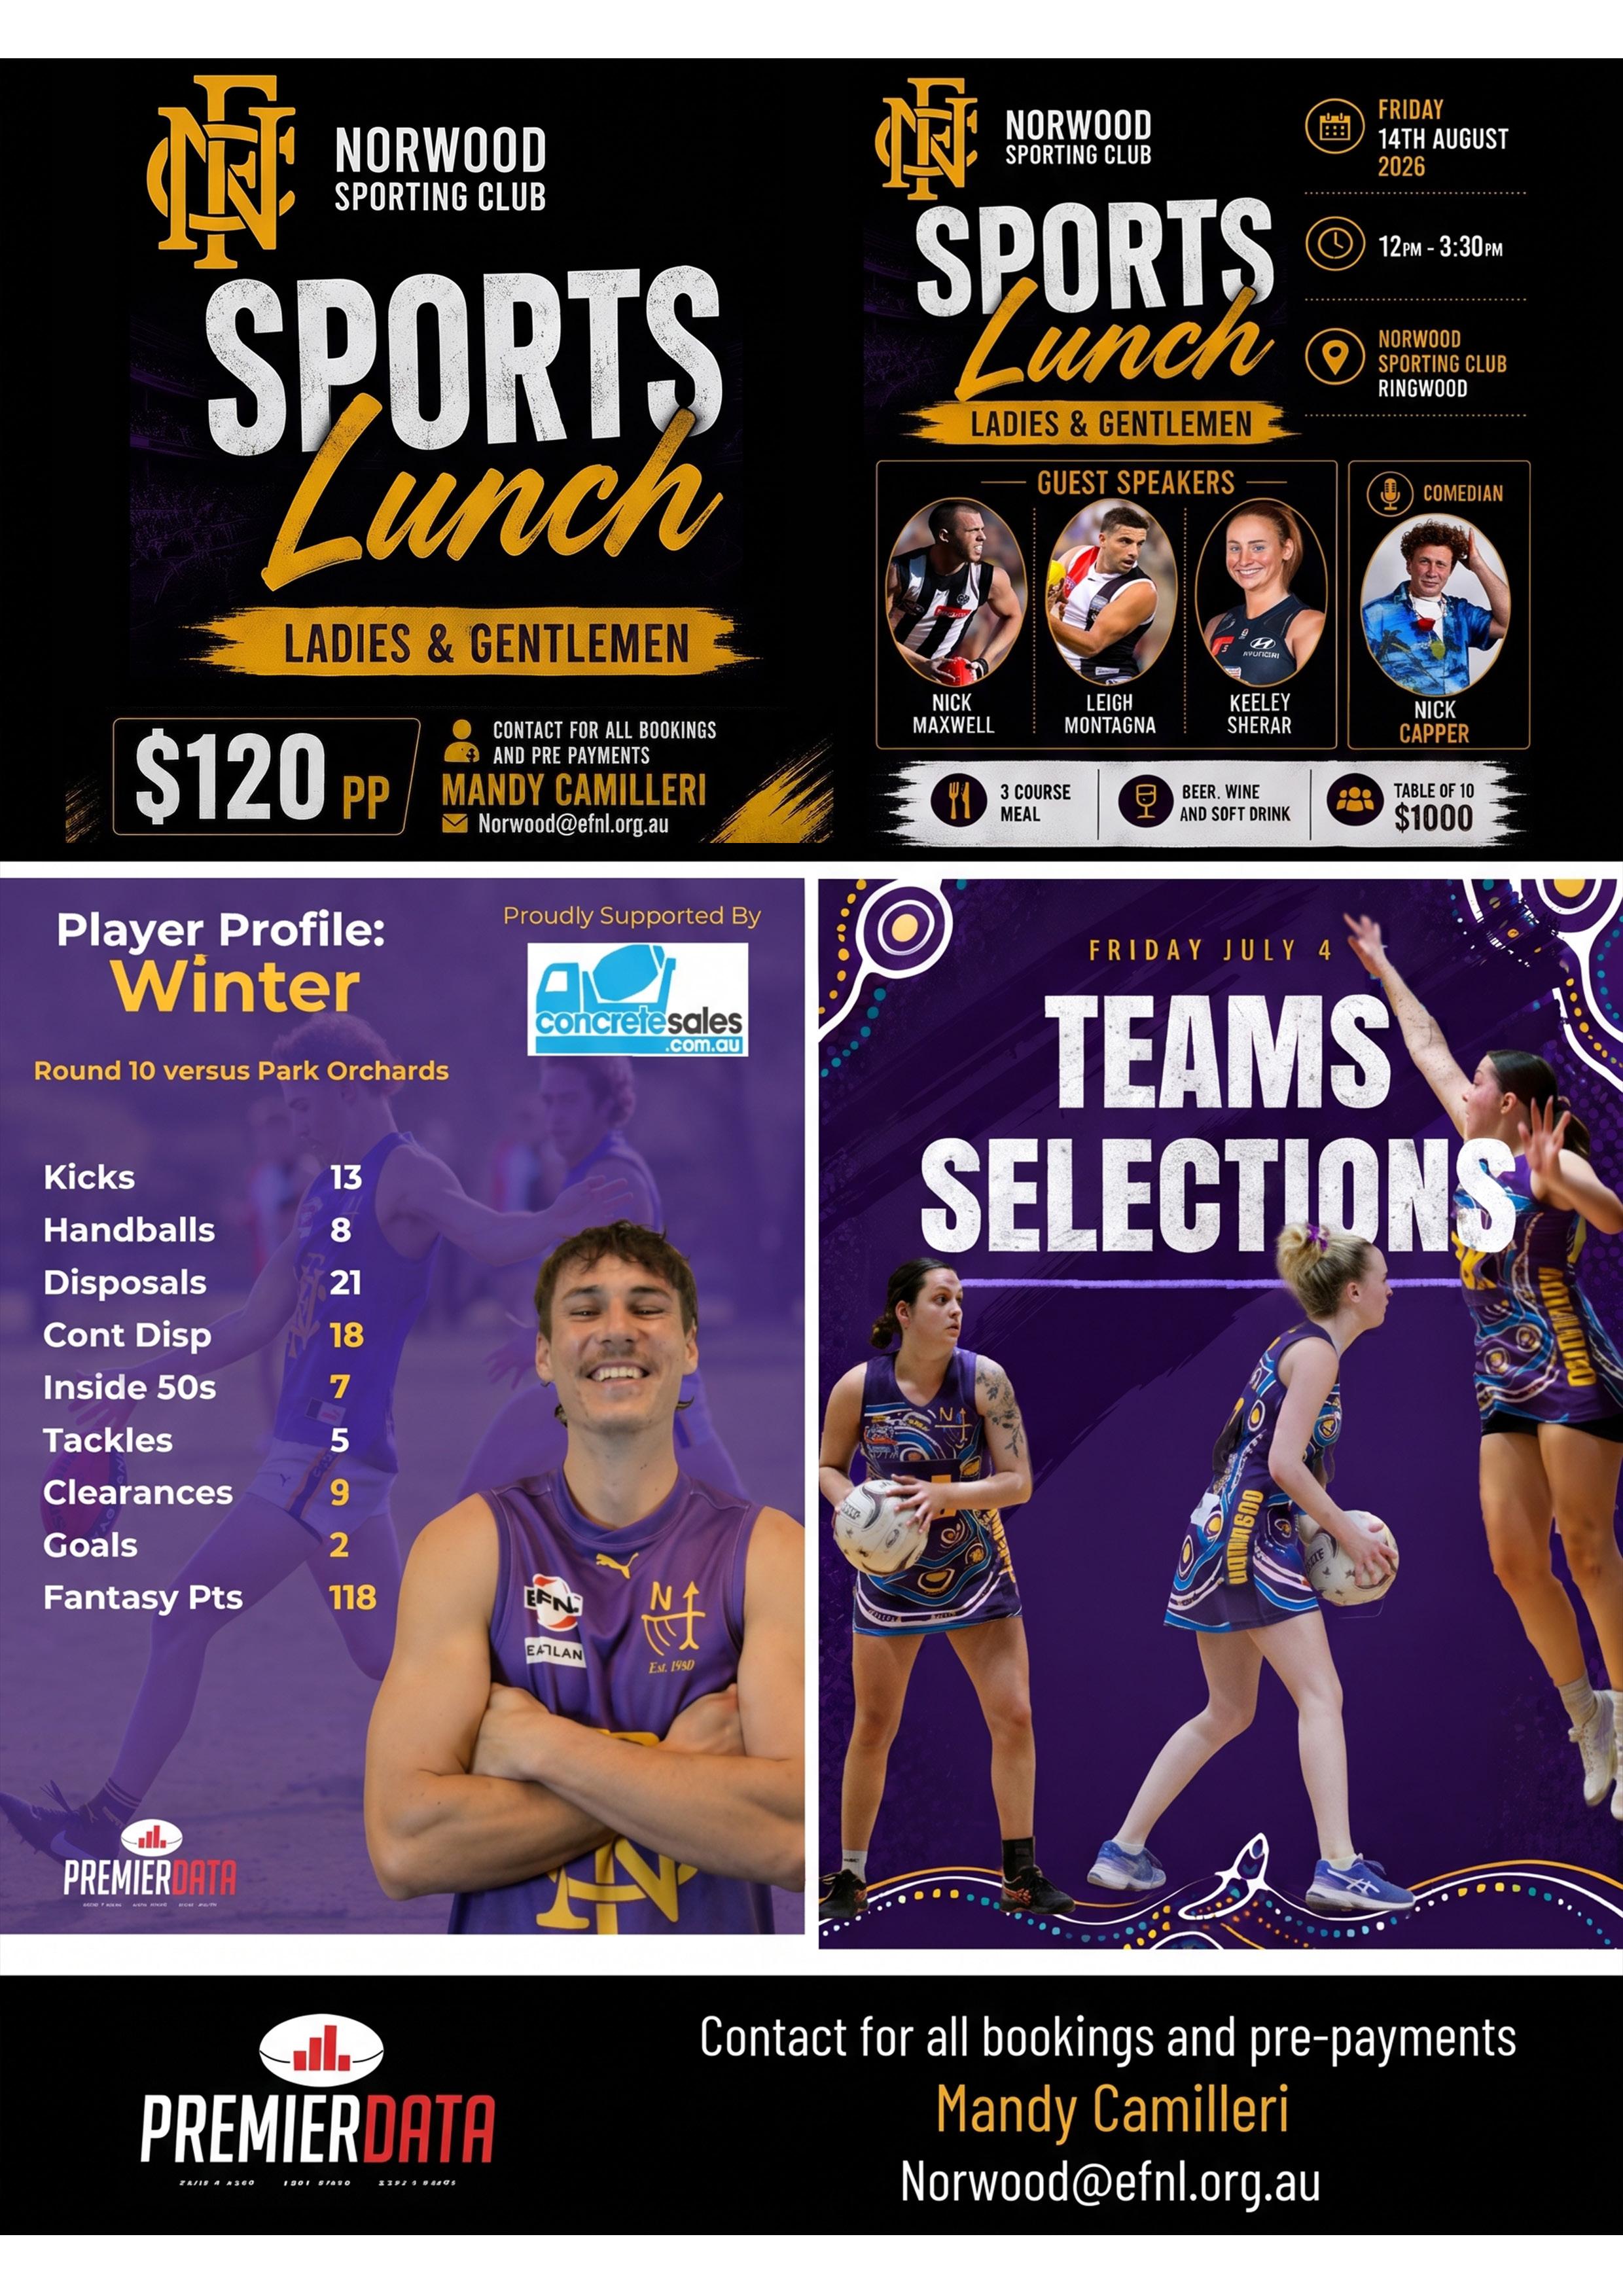
We invite a representative from each sporting club to submit team selections, results and any interesting stories relating to your club/sports.
For more information contact: Warren on 1300 88 38 30 or Email: editor@findmaroondah.com.au
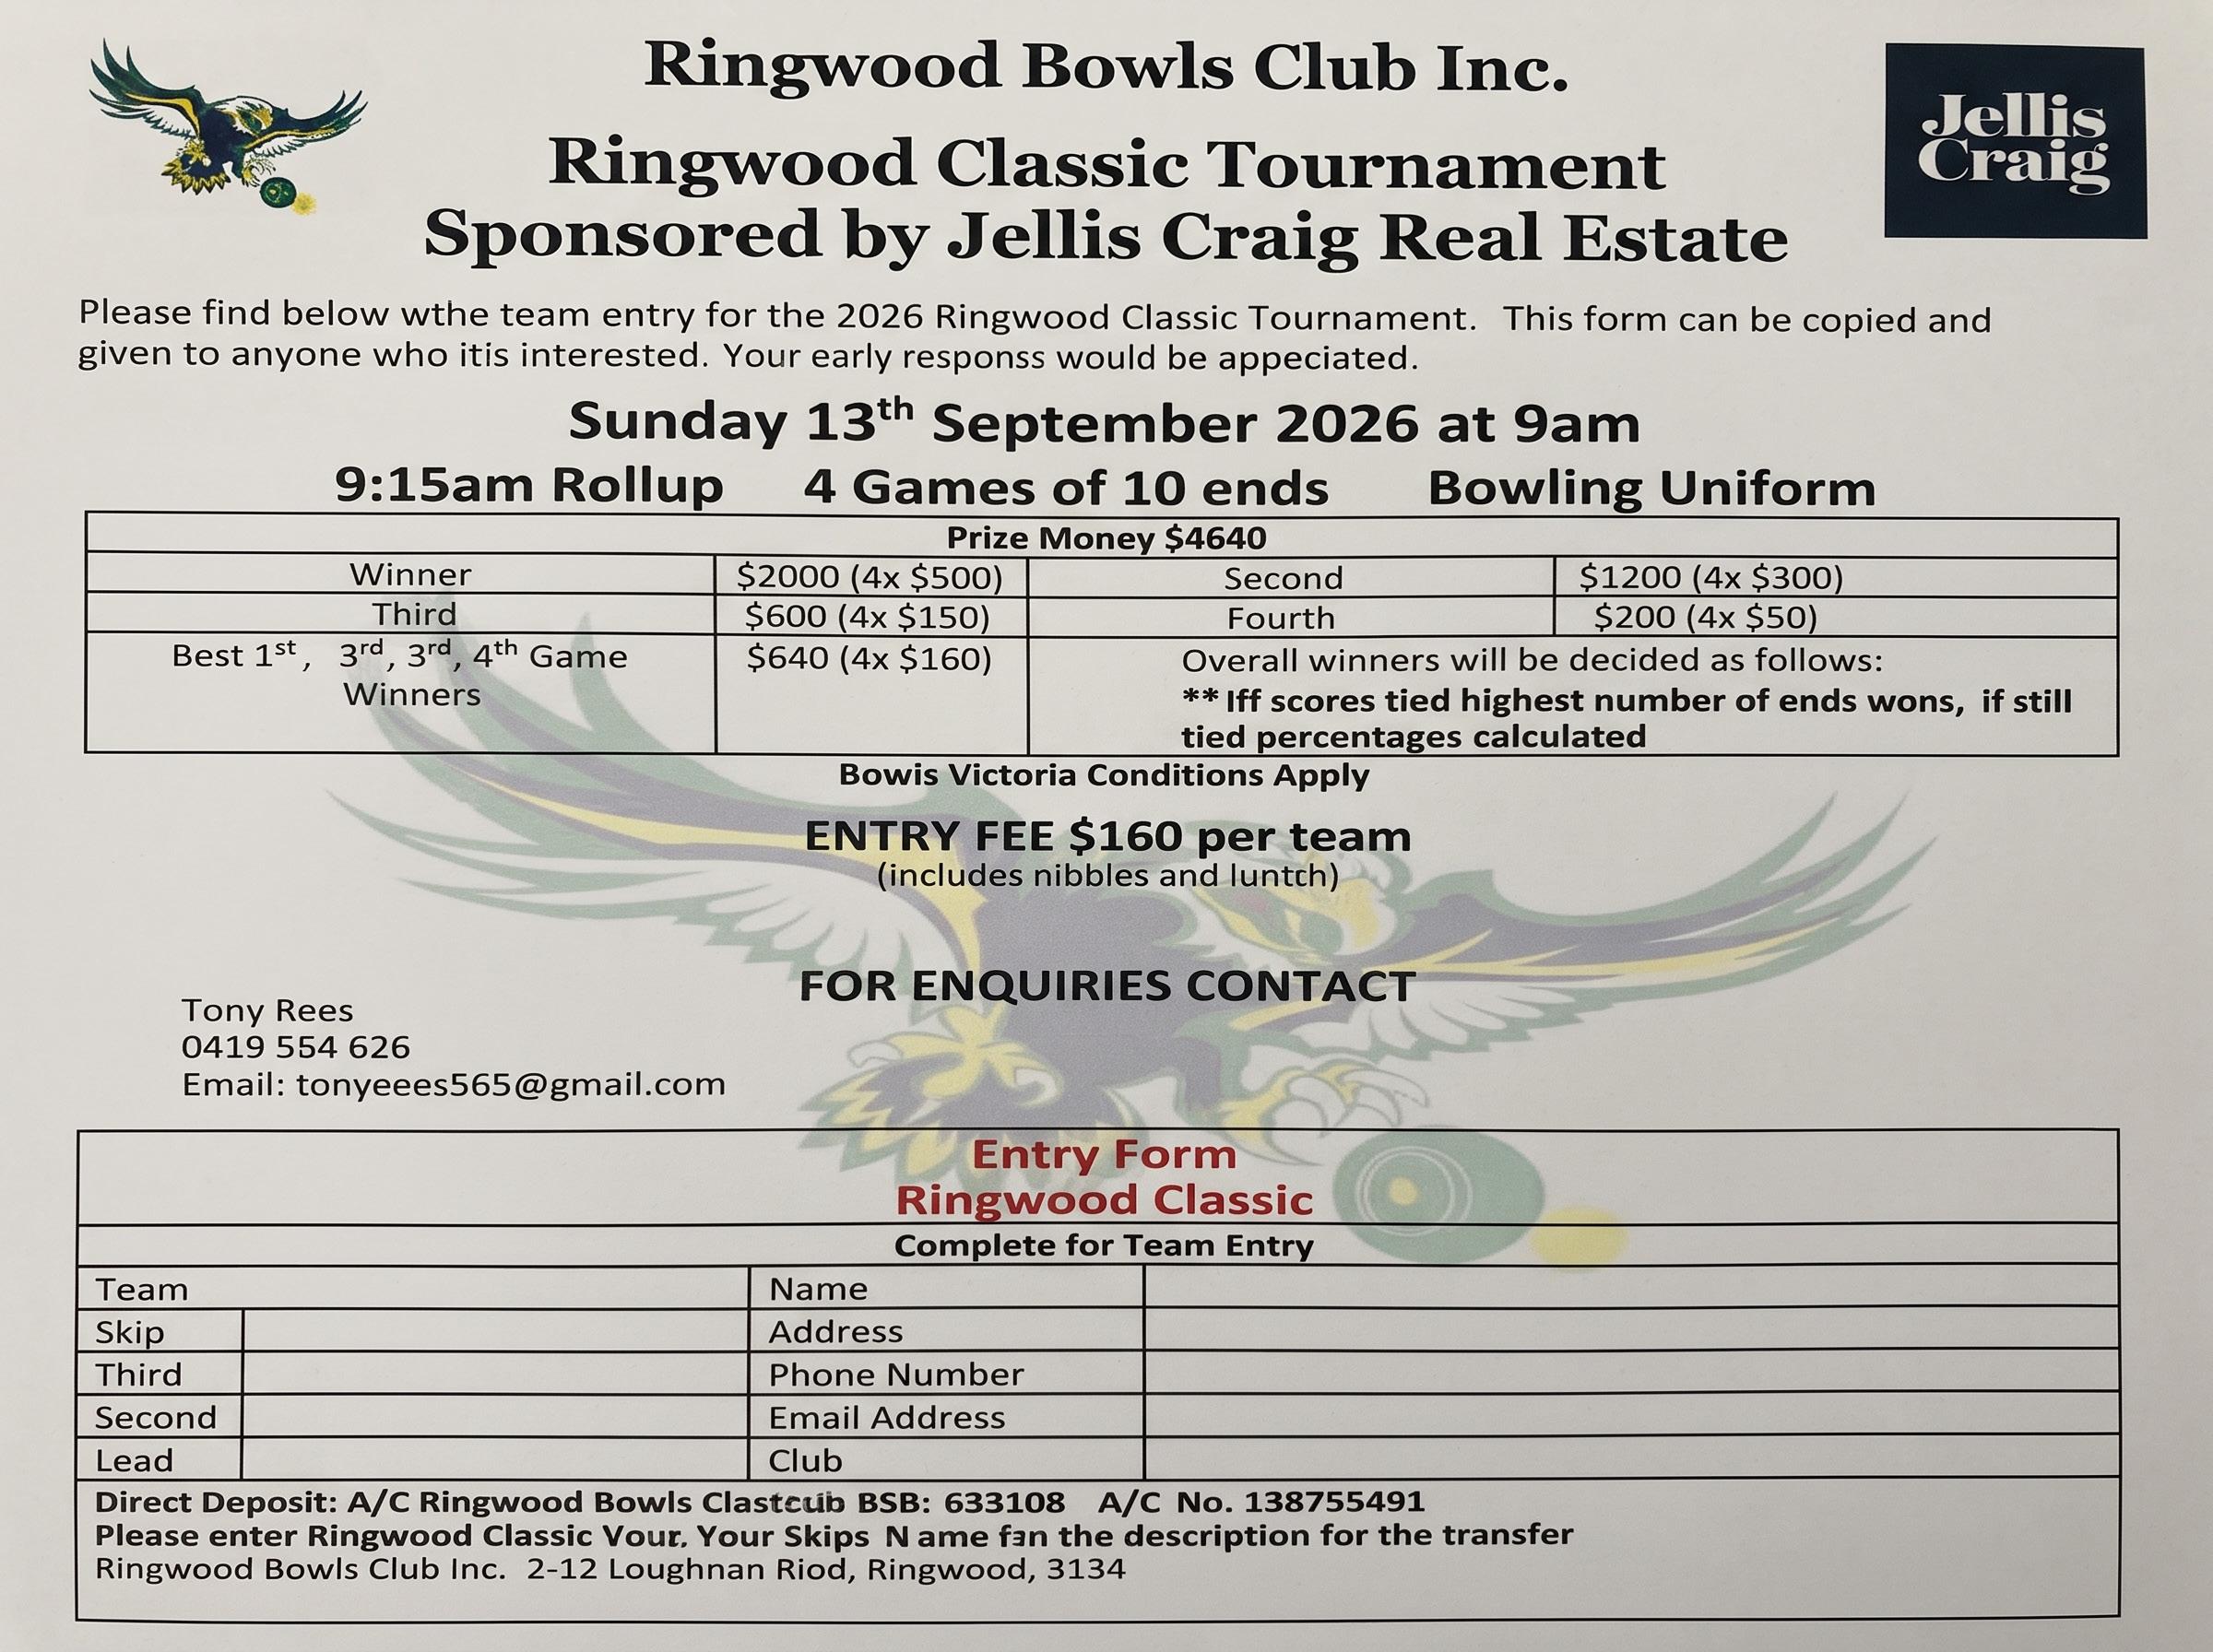
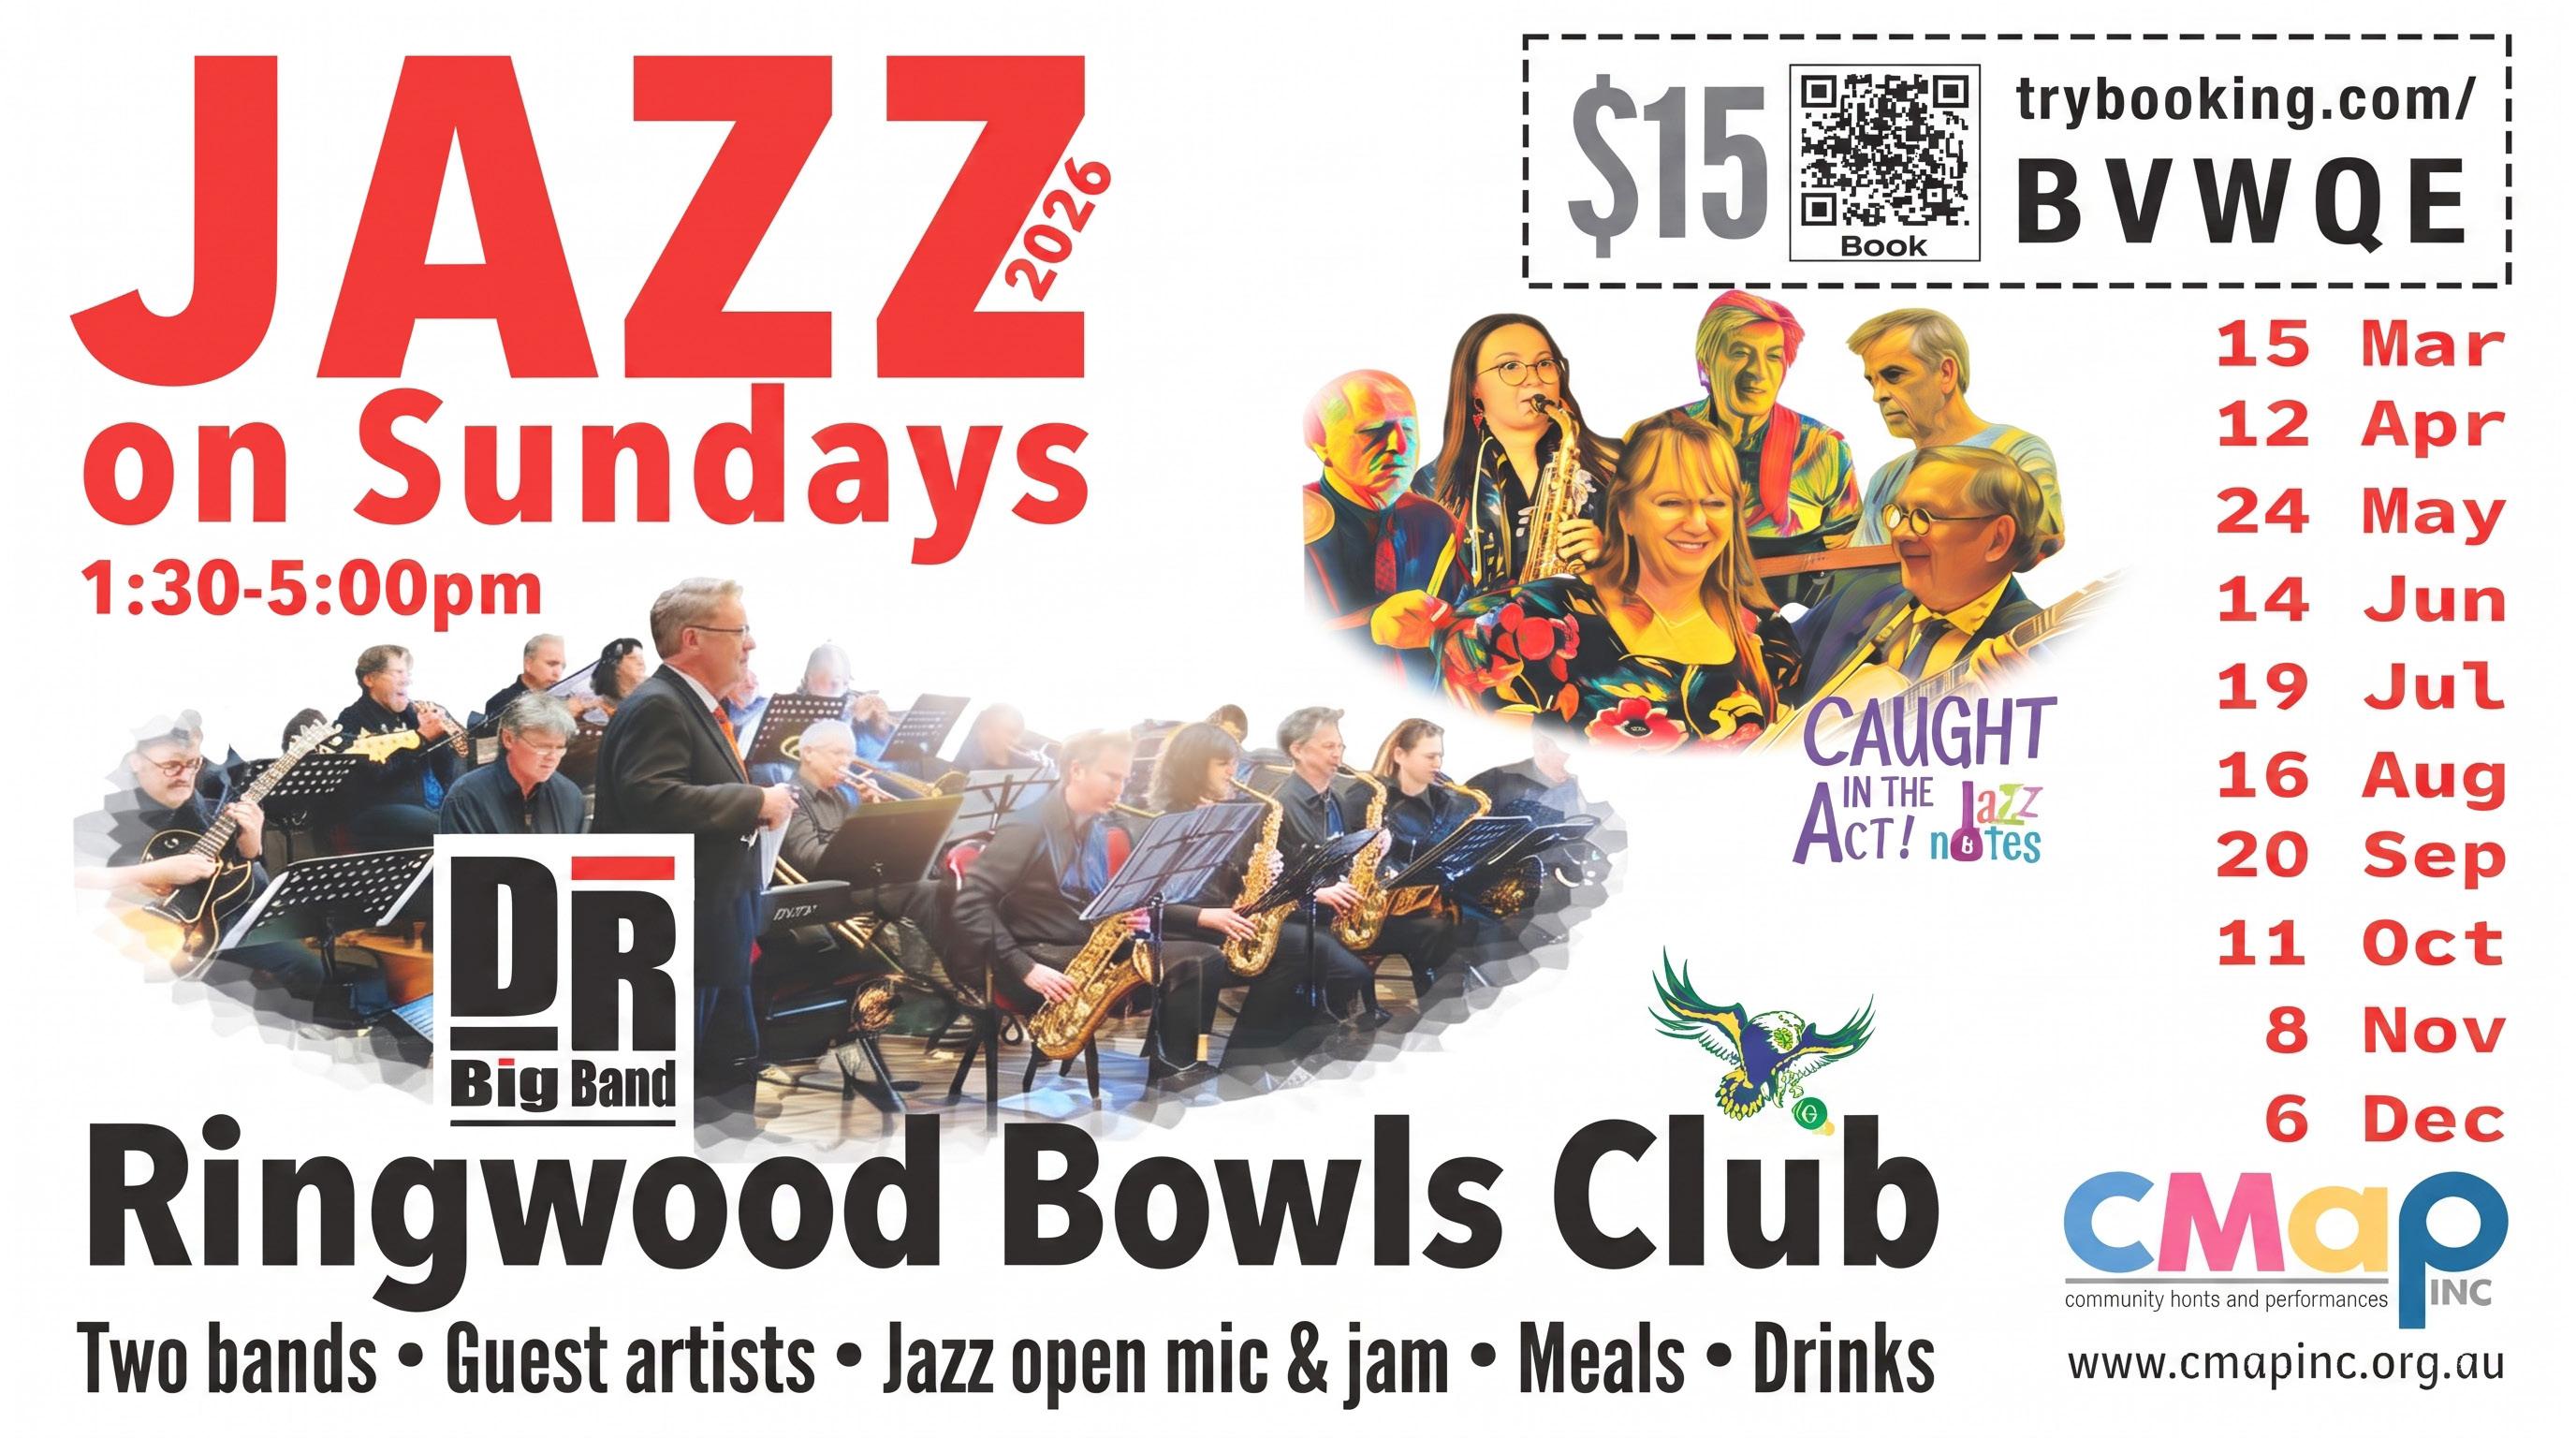
Ringwood Bowls Club Inc.
Do you have an upcoming events? Place your EVENT AD here for FREE in our community online paper.
SEND US YOUR NEWS!
Simply upload your ad at www.findmaroondah.com.au/nfp-free-advertising or you can email the ad to the editor@findmaroondah.com.au and we will do the rest for you.
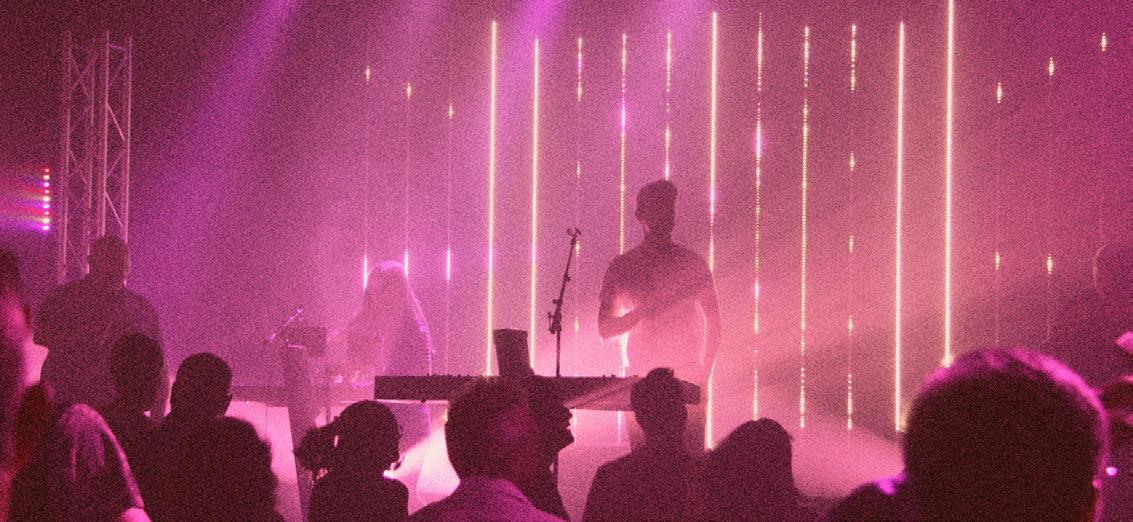
Hope City is a community partnering with Jesus to see His Church grow and to see people encounter God’s presence and be transformed by His Spirit and Word. We look to empower every believer in God’s purpose for their life so that the 7 Mountains of society will be impacted by God’s kingdom. We see a Church where every person experiences the goodness of God in their lives through energetic praise and intimate worship.


Religious Groups and Churches


find cards DIGITAL MEMBERSHIP
MOST POPULAR CATEGORIES