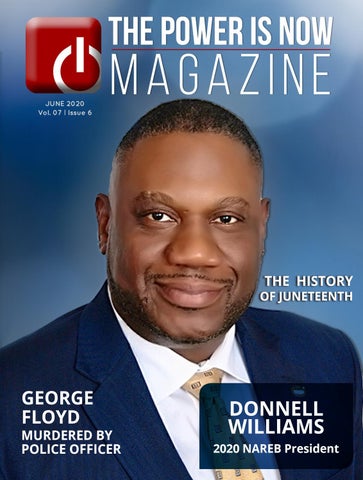
JUNE 2020 Vol. 07 | Issue 6
THE HISTORY
OF JUNETEENTH
GEORGE FLOYD
MURDERED BY POLICE OFFICER
DONNELL WILLIAMS 2020 NAREB President
HAVE YOU READ OUR PAST ISSUES YET? the power is now
magazine THE POWER IS NOW MEDIA INC. Vol. 07 | Issue 6
Eric Lawrence Frazier, MBA President and CEO Office: (800) 401-8994 Ext. 703 Direct: (714) 361-2105 eric.frazier@thepowerisnow.com www.thepowerisnow.com www.blogtalkradio.com/thepowerisnow EDITORIAL TEAM Eric Lawrence Frazier MBA Editor in Chief (800) 401-8994 Ext. 703 Sheila Gilmore Editorial Director Daniels George Managing Editor (800) 401-8994 ext. 712 daniels.george@thepowerisnow.com Goldy Ponce Arratia Graphic Artist and Design Manager goldy.ponce@thepowerisnow.com
CONTRIBUTORS The Power Is Now Research Team
CLICK HERE TO READ US ONLINE!
HEADQUARTERS The Power Is Now Media Inc. 3739 6th Street Riverside, CA 92501 Ph: (800) 401-8994 | Fax: (800) 401-8994 info@thepowerisnow.com www.thepowerisnow.com www.thepinmagazine.com
the power is now
magazine IMPORTANT STATEMENT OF COPYRIGHT:
LIVE HOMEBUYER SEMINARs 1ST AND 3RD TUESDAYS OF THE MONTH 7:30 PM TO 8:30 PM ERIC L. FRAZIER MBA
Host NMLS 461807 President and CEO o: (800) 401-8994 ext. 703 c: (714) 475-8629 eric.frazier@thepowerisnow.com www.thepowerisnow.com
Special Guests! for more details go to
thepowerisnow.com/events
The PIN Magazine™ is owned and published electronically by The Power Is Now Media, Inc. Copyright 2013-2019 The Power Is Now Media Inc. All rights reserved. “The PIN Magazine” and distinctive logo are trademarks owned by The Power Is Now Media, Inc. “ThePINMagazine.com”, is a trademark of The Power Is Now, Inc. “Magazine.thepowerisnow.com”, is a trademark of The Power Is Now Media, Inc. No part of this electronic magazine or website may be reproduced without the written consent of The Power Is Now Media, Inc. Requests for permission should be directed to: info@thepowerisnow.com
TABLE OF
CONTENTS 9. George Floyd - Murdered by police officer 14. Clean energy and climate stalilization will be a huge job creator 18. In addressing the COVID-19 Pandemic, Congress mustn’t exacerbate climate crisis 20. The plight of small businesses in California 22. New rules set before reoppening the economy 26. COVID-19 poised to upend normal seasonal housing 28. The pace of home sales reached new records in February Education for borrowers: 5 Cares Act details 30. you should know about 34. Zoom video and other video platforms to save time and conduct business 39. The curse of the decade. How COVID-19 is slowing Phoenix metro multi-family deal closures 43. The Phoenix housing market stabilizes 46. The foreclosure markets reaches record lows 46. The common refinancing mistakes homeowners are likely to make during this crisis 52. Helping homeowners avoid loan modification scams 55. Are you seeking forbearance on your mortgage? 58. About Donnel T. Williams and the Two Million New Black Homeowners Program 62. The best and possibly worst places for renters to hunker down during the Coronavirus pandemic in Irvine 65. The new reality of the housing maket in the Bay Area 68. Yes, Coronavirus slowed real estate activities, but it won’t stop the Bay Area real estate. 72. Use these 5 tips to help ace your rental
the power is now
magazine
application 75. Consider these 4 things before getting an FHA loan 79. Secured and unsecure loans 82. Bay Area home prices jumped in Marchmostly before the lockdown emergency 87. COVID-19 impacts Richmond 90. Expert advice: Should I buy a home with fears of a recession? 94. When is the right time to buy an investment property? 98. Best places to live in Los Angeles 101. How to negociate an offer on a home 107. Realtor selling tips. Selling a home safely during the COVID-19 pandemic 108. Mortgage fraud had dropped but it’s likely Coronavirus could bring a new wave 110. Tips on how to improve your credit score before you buy a house. 114. How COVID-19 is exposing flaws in the U.S. and world health System 118. Celebrating the Black Music Month in style 122. History of Junettenth
NEW REAL ESTATE ROUND TABLE Every Other Friday
YOUR VOICE IS YOUR BRAND! INCREASE LEAD GENERATION, AND GIVE YOU THE POWER TO CLOSE MORE DEALS!
10:00 AM - 11:00 AM
Promote Your Listings Online
• Streamed live on Facebook, and are • These sessions provide real estate agents rebroadcast on BlogTalkRadio which is and brokers a powerful marketing syndicated to iTunes, TuneIn and many opportunity to access The Power Is Now other online radio platforms. During the Network of Agents nationwide and our show each agent and their listings are audience of prospective buyers and sellers featured for approximately five minutes to that is 1 million strong and growing. discuss why buyers should consider buying their listing(s). In addition, each agent will be given a post-show opportunity to launch a customized marketing campaign to get additional exposure.
ERIC LAWRENCE FRAZIER MBA CalDRE: 01143484 | NMLS 461807 Mobile: (714) 361-2105
Office: (800) 261-1634 ext. 703 Email: eric.frazier@fbol.com Website: www.thepowerisnow.com
FROMtHEEDITOR
Dear Readers, Welcome to our mid-year issue for The Power Is Now Magazine. The Power Is Now is honored and considers it a privilege to serve you by providing quality issues of The Power Is Now Magazine. Our goal is not just to provide you with timely real estate news and developments, but to be your ally in the industry. The Power Is Now, Media Inc. stands for something. We uphold the value of the American Dream and believe that homeownership is available and possible for everyone ready to embrace the responsibility of homeownership and to do the work to establish a secure future for their families. Our ideology goes beyond the business of publishing for profit but empowering people with information that can change their lives. We believe that we have a responsibility to educate real estate professionals and the American public to make informed choices when purchasing a home or real estate investment. The Power Is Now will continue to be a sustainable enterprise to endow people for success in real estate. As the world continues its fight against COVID-19, we stand with you wherever you are. The number of cases in our country stands at 1.7 million people and over 100,000 deaths. Let us all take a moment of silence and remember the people who have lost their lives to this virus. My prayer goes to the first responders, and the health care works who stand on the front line against the disease. This month we spotlight the excellent work NAREB continues to do to
6
l
THE POWER IS NOW MAGAZINE | JUNE 2020
place 2 million Black families in homeownership in five years. The program dubbed 2MN5 is the organizations’ solution in response to the declining African American homeownership rates. Currently, the homeownership rate for African Americans is 44%, and the rate for Non-Hispanic whites is 73.7%. Additionally, this is not the only program that NAREB has embarked on; the organization is also doing the “House Then A Car” campaign that targets millennials. After college, millennials will focus on getting the latest models of cars in the market, putting their financial life in jeopardy. NAREB is encouraging young people to first purchase a home before making any significant financial decisions. Remember, homeownership is the key to wealth development. The earlier you get started, the better off you will be. According to the SHIBA Report, 1.7 million millennials have the purchasing power, but they have chosen not to buy. Most will prefer buying a car before buying a house, and it is these car loans that are preventing homeownership in the African American
WWW.THEPINMAGAZINE.COM
community. NAREB hopes that the campaign can change millennials’ priorities to real estate and begin to bridge the wealth gap between African Americans and NonHispanic Whites. I want to thank our power team for their continuous hard work and dedication to the company. We would be nothing without you. And to our readers, thank you for your continued support. We want the best for you, so we are committed to bringing the best of us. Please take a moment and share this magazine. Knowledge is power, and The Power Is Now. Have an excellent and prosperous month.
ERIC L. FRAZIER MBA President and CEO The Power Is Now Media, Inc.
l
7
Your loan officer should be as invested in your home as you are. Let’s feather your nest. First Bank Mortgage offers three tips to help you on the path to homeownership! 1. Start by checking your credit score. Your credit history is an important factor when you decide to apply for a loan. The score reflects how well you manage your debt. It’s important to discuss this, and other factors, with your First Bank home loan consultant. If you find that your credit score is too low, there are a number of steps you can take to improve your credit score. 2. Get organized. Getting a loan requires a few different documentations including, but not limited to, pay stubs, tax returns, and financial statements. You’ll also need to provide copies of additional monthly payments such as car loans, credit cards, and student loans. Keep all of this in mind, when you begin organizing. If you have this information readily available when you decide to apply for a home loan, it will make the process much more efficient. 3. Start Saving! Set up a designated savings account and start saving as much as you can each pay period to use as a down payment on the purchase of your new home. Although we offer first-time homebuyer programs with little to no down payment, it is still a good idea to have some available funds in reserve to use for a potential down payment, utilities, moving expenses, new home furnishings, or unforeseen emergencies. With some preparation now, you’ll be even closer to rolling out the welcome mat on your own, new home later. We’re here to help answer any questions to help make that dream a reality.
104 E Ontario Ave Corona, CA 92879 FirstBanks.com/Mortgage
Eric Lawrence Frazier MBA Vice President & Mortgage Advisor Office: Incomplete Fax: (314) 264-0211 NMLS: # 461807 eric.frazier@fbol.com https://www.firstbanks.com/hlc/EricFrazier/Eric-Frazier
GEORGE FLOYD
MURDERED BY POLICE OFFICER Another Tragic example of Police Brutality When will it stop?
T
he month of June kicks off Juneteenth celebrations for the African American community. Juneteenth is one of the oldest ceremonies honoring the end of slavery in the United States. It is a celebration that reminds African Americans that they are free and equal with their White counterparts. Nonetheless, freedom and equality are still something foreign in this country. For example, the case of George Floyd, who was brutally murdered by Derek Chauvin, Police Officer of the Minneapolis Police Department, he was not a threat, and he had surrendered himself to the authorities. However, it did not matter to the white police officer who shamelessly knelt on Floyd’s neck, pinning him to the ground for several minutes, even as Floyd pleaded, “I can’t breathe!” After calling for his deceased mother several times, he died under the police officer’s knee while the three other police officers with Derek Chauvin stood by and watched
WWW.THEPINMAGAZINE.COM
the life leave Mr. Floyd’s body, and did nothing. Police officer Derek Chauvin, feeling nor seeing any resistance from Mr. Floyd’s lifeless body, did not listen to the citizens witnessing this horrific murder, plead with him to get off his neck. Derek Chauvin kept his knee on George Floyd’s neck another three or more minutes. His callous indifference, lack of mercy and compassion, and display of evil are beyond words to adequately describe, but we will have the videos and the images forever. Thank God for cell phone video and live streaming. The entire world has witnessed, on video and national television, the senseless murder of another unarmed black man by a white police officer. Black men dying at the hands of the police is not news to the Black Community. The history of Black Life in Cities and States throughout America of images and stories of African American men killed by the police continues to be written today.
l
9
“I CAN’T BREATHE” are the same words
used by Eric Garner, who died in the arms of a police officer in the New York City borough of Staten Island as Daniel Pantaleo put him in a chokehold while arresting him. These are the injustices done to the minorities in this country of ‘freedom.’ Even though the police officer involved in the murder of George Floyd is now charged with murder and manslaughter, is arrested, and is sitting in jail, it still does not change the fact that Mr. Floyd is gone forever. He was a son, a brother, a friend, and will be missed. No amount of years in a cell can take away the pain caused to his family. It was murder, and I believe it meets the conditions for 1st-degree murder and the death penalty. Rioting is happening across the country because the other three police officers have not been arrested or charged. Why? And to add insult to injury, the criminal charge made so far does not begin to represent the crime committed by Derek Chauvin that was witnessed by the world. Until the State of Minnesota does the right thing, the people of Minnesota and people across the United States should continue to hold peaceful demonstrations in protest of extra-judicial killings. I am hurt and afraid that I am next or that one of my brethren will be next. A traffic stop could mean the end of my life. Try living with that fear, black or white. I am afraid for myself, my children, and my grandchildren. We live in the United States of Racism and Violence against Black People and have been dealing with this for 400 years. Our ancestors were brought here as slaves to this kind of America, and nothing has changed. How many Black men must die before we see change? That is the question that we and the media should be asking. That is the question our legislators should be asking. That is the question our leaders at the highest levels of Government and the criminal justice system should be asking. The question should not be how many buildings must burn down or city monuments destroyed, or retail stores and other places of business are burned to the ground? The questions should not be who are the outside detractors, terrorists, white supremacists, or foreign governments destroying property in the name of George Floyd and leveraging this event to 10
l
bring chaos and violence to America. Let us not forget that there are Americans damaging property and setting fires in response to the Government’s inaction and the systematic racism in this country. The fact that we see more white people in the protest does not change the reason why the protest exists. Nor does it change who is responsible for starting this violence through his act of violence in taking the life of an unarmed man. But this is how Americans, both black and white, respond to injustice. From the Boston Tea Party to the Civil Rights Movement, and the many black lives that have been senselessly murder by police. Violence, the destruction of property, and death have always followed. So, let us focus on the real issue because it is not property damage. It is police violence. It is systemic racism in the criminal justice system. Americans, and especially African Americans, want justice, and we want it now. Where are the critical questions that should be asked by the media? The critical questions are how many Black men must die before we see change? What is the Federal Government doing to expedite the right criminal charges on the other three men? Why is the murderer not being charged with 1st Degree Murder? Why is the DA’s office or the State Attorney general not working overtime to bring justice to the family? Where are daily press briefings on the case? But what do we get? Media coverage of the fires and rioting? We get media coverage of community organizers, mayors, and preachers telling us citizens to go home, be quiet, and stop being violent. “ This is going to get resolved soon. Trust us.” The response is the same after every Black Man is killed. The same message. The same actions by the Government. The same results of no criminal indictments and we go back to the same problem. Will White America change and fix these issues so that Black men and their families can live in peace in the United States? When can the white ma jority co-exist with the Black minority in America? Black Americans cannot solve this problem. Since when do the victims of injustice have to address the issues they are facing? Victims, we are but, we are not without the resolve to fight for what is right. We need all Americans to get involved to help make the necessary changes we all need to see in this country. THE POWER IS NOW MAGAZINE | JUNE 2020
A building can be rebuilt, and monuments can be restored. If businesses are set up correctly and are running, they can restart after a disaster or significant crime. But once a human life is taken, it cannot be resurrected. At least not in this life. I am grateful for my faith and George Floyd’s faith and our mutual belief that there is life after death in a better world than what we live in today. But his life ended to soon and was not ordained by God. God has a plan for all of us, and our life is not over until He says it is over. But man has free will and can take human life and can prevent the plans of God from coming to pass. Man can even take his own life and prevent the purpose that God has for his life. That is what being free means. The love of God constrains and influences us to use our freedom for good and love. Freedom is a choice. Death is a choice. Life is a choice. I choose life and life for all God’s people. I am in pain, and I am hurt by what has happened. I am tired of seeing black men die at the hands of the police repeatedly. I feel for George Floyd’s family. I am urging everyone to protest peacefully and live in unity with everyone. But, please do not allow the actions of a few, and the media’s attention to it, distract us from the real issue of police violence against black men. Every riot that has started in this country, which Black people are involved in, always begins with police violence and the loss of Black life. Do Black Lives Matter is a real issue and question for America? Let us keep our attention on the real problem and ignore the media, law enforcement, the mayors, the governors, business leaders, community leaders, preachers, and the President of the United States. They want to change the narrative to property damage and silence the protestors, and in doing so, maintain the status quo. Not this time. Enough is enough. This time they have crossed an entirely different line that has affected “We the People,” both WWW.THEPINMAGAZINE.COM
white, black, Asian, and brown. The diversity is unprecedented because we have never witnessed such brutality and inhumanity to man. To see a police officer, kill a black man on television is the worst thing and, ironically, the most important thing that could ever happen for America. The world is now a witness to the crime, and it cannot be ignored. George Floyd is a Martyr for change in policing and in criminal justice reform. If Derek Chauvin were a black man, he would have been waiting in jail for the charges to be filed instead of ordering pizza at home with his family. If the three other police officers were black men, they would be in jail, waiting for charges to be filed. But the standard operating procedure for any black man accused of a crime is that we are arrested, tried, and executed by the police officer. We rarely even see the courtroom. Our families may see a courtroom in a civil trial because, in a criminal prosecution, the perpetrators go free. There is a different standard of treatment in the justice system for White America than it is for Black America, and it must change. If the Government fails to convict any of these men, it will be the next blow to Americans everywhere. Will they fail? Probably not based on the track record of the American Judicial system. In addition to the racist history of Minnesota and the small population of Black people there, it is highly unlikely that anything will happen to these men other than temporary incarceration, release on bond, and judge not guilty. Dead Black men rarely see justice for their families. Change must come to America, or America will keep burning to the ground, and if so, hopefully, something new and better will rise from the ashes.
Eric Lawrence Frazier, MBA CEO The Power Is Now Media Inc.
l
11
IMPORTANT ANNOUNCEMENT IMPORTANT ANNOUNCEMENT IMPORTANT ANNOUNCEMENT FOR IMMEDIATE RELEASE:
May 27th 2020 CONTACT: Daniels George, Managing Editor daniels.george@thepowerisnow.com 800-401-8994 x 707
Listen to an Exclusive Interview with Jennifer Hernandez, John Gamboa and Robert Apodaca on The Power is Now Radio on June 5th, 2020 RIVERSIDE, CALIF. — May 27, 2020 Eric Lawrence Frazier, MBA the host and founder of The Power Is Now Media Inc. is pleased to announce that he will be broadcasting an interview with Jenifer Hernandez, a partner and lead of Holland & Knight’s west Coast Land Use and Environmental Group, John Gamboa, the Vice Chair of The Two Hundred Organization and Robert J. Apodaca, the Founder of ZeZeN Advisors, Inc., and a council member of the California Community Builders on The Power Is Now weekly News Update on Facebook.com/thepowerisnow on June 5th at 3.00 PM Pacific Standard Time. Jennifer Hernandez has practiced land use and environmental law for more than 30 years. She has been ranked as the only California Lawyer in the Chambers USA in the top tier of both the land use/ zoning and environmental lawyers. Additionally, Ms. Hernandez has also been recognized as the top environmental litigator of the year in the San Francisco Bay Area by Best Lawyers, and received a California Lawyer of the Year Award from the State Bar of California for her work on California’s largest and most innovative land ise and conservation agreement between her private landowner client and five ma jor environmental organizations, including the Sierra Club and Natural Resources Defense Council. Mr. Gamboa is the former Executive Director of the Greenlining Institute, and has a diverse experience serving in academia, the private sector and the non profit sector. Prior to the Greenlining Institute, he was Executive Director of Latino Issues Forum, Communications Manager at U.C. Berkeley, Executive Director of Project Participar, a citizenship program, and Marketing and Advertising Manager at Pacific Bell. As Executive Director for the Greenlining Institute, Mr. Gamboa focused on public policy issues 12
l
THE POWER IS NOW MAGAZINE | JUNE 2020
Jennifer Hernandez
John Gamboa
Robert Apodaca
that promote economic development in urban and low-income areas, and in developing future leaders within this country’s minority youth. Robert J. Apodaca has a 45-year professional and civic career that spans both private and public sectors and several industries. ZeZeN is a boutique financial services firm that connects institutional capital with developers and real estate owners. Following his service as Chairman and Trustee of Alameda County Retirement Board (pension fund), he joined the investment industry as a Senior Vice President & Partner of Kennedy Associates, an institutional investor for pension funds. New and retained accounts credited to his leadership included CalPERS, Chicago Transit Authority, San Diego County Retirement Board, Dallas Police & Fire, Kansas City Public Schools, NYC Fire Fighters and International Glass Molders. Mr. Frazier and the guests will be discussing about the charges leveled against the state of California for the climate policies that they say will disproportionately harm the poorest residents of the state, especially the minority groups of Latino and African Americans. The lawsuit contends that the most overwhelming, and unlawful and racist components of the climate policies target new housing and are contributing to resegregation. Did you know that over time, the State of California has continually imposed new costs and restrictions on home building which has contributed to the skyrocketing prices of homes in the state? This is one of a kind shows that you do not want to miss, it will be interactive, informational and quite in depth. Come learn about the various issues impacting our Golden State, and the redlining practices leading to segregation and contributing to the huge wealth gap between the poor and the rich in the state. The show will also cover each of the organizations aforementioned and the various steps and mitigation policies each one of them is taking towards ensuring that everyone, regardless of their color, race or gender is well taken care of, in terms of housing and an equal chance to wealth development.
About The Power Is Now Media
The Power Is Now Media Inc. is an online multimedia company founded in 2009 by Eric L. Frazier, MBA, and is headquartered in Riverside, California. We are advocates for homeownership, wealth building, and financial literacy for low to moderate-income and minority communities. The Power Is Now Media Inc. corporate office is located at 3739 6th Street Riverside, CA 92501. Ph: 800-401-8994 Website: www.thepowerisnow.com WWW.THEPINMAGAZINE.COM
l
13
Clean Energy and Climate Stabilization
will be a Huge Job Creator
as the Economy Rebounds
The current global crisis due to the fast-spreading and deadly Covid-19 has brought a halt to most of the large operations that were fuelled by fossil fuels in most parts of the globe. The halting of these operations has, in return, led to a significant reduction in carbon dioxide and other emissions into the atmosphere, such as greenhouse gas emissions. However, the reduction in emissions has resulted in a cleaner and less polluted atmosphere, which is evident, as shown by recent NASA satellite images of China. The images show that emissions in China have dropped by about 25% due to the lockdown implemented in its ma jor cities as a public health measure.
T
he NASA images are a perfect representative of what the future could look like if powered by clean energy. The images also prove that it is possible to achieve climate stabilization if we embark on using clean energy to fuel our daily activities. The fight for clean energy and climate stabilization has been going on even before the coronavirus hit the world. The previous fight to stabilize the climate through the use of clean energy has always proved to be in vain. It took a global pandemic for the world to realize that it is possible to stabilize our climate. Our leaders only need to come together and fix a few flaws, with one of the flaws being the massive use of fossil fuels. Several individuals, such as Tom Steyer, have been in the frontline in the efforts to come up with clean energy sources to replace the use of fossil fuels. Steyer is a wealthy former hedge fund manager who turned into a
14
l
climate change activist. Steyer later run for a presidential nomination under the Democratic Party with a progressive platform comprising of eliminating global warming emissions through massive investments in clean energy. In recent times before the pandemic, the use of clean energy had already picked momentum. It was already a ma jor source of employment to thousands of people in the U.S. But with the current economic situation, the story is changing. In March alone, the clean energy sector has laid off more than 100,000 employees countrywide including 20,000 individuals from California. However, on a normal occasion, clean energy sector employs more people that the fossil fuels sector. A report by the E2 shows that clean energy has outnumbered fossil fuel workers in a ratio of 3:1. Recently, Steyer was engaged in an interview with the L.A Times, concerning how the ambitious clean energy programs might help THE POWER IS NOW MAGAZINE | JUNE 2020
California and the US at large, recover from the damage brought by Covid-19. In the interview, Steyer was asked about the role he saw clean energy investment and climate stabilization would play in getting the economy back to thrive. He responded “We’ve always known that moving to a green and sustainable economy is a huge job producer. In California, it has already been a huge job producer…. But I think across the United States of America, the country is going to do a huge rebuilding program, and those are investments that will be in place for a long time.” Steyer, who is also co-chairing a task force on Business and Job Recovery by the California governor, was also asked how much more could California do with investments in clean energy and climate to get the economy moving again? His response was, “I don’t want to prejudge where we come out as a task force. And in any case it’s going to be the governor who ultimately decides what we actually put into effect. We’ve already got very ambitious goals in terms of when we’re going to be carbon-neutral, 2045.” In the interview, Steyer also expressed his hopes and emphasis on the need to take action instead of just mere plans to achieve a more sustainable California. Recent economic research has shown that setting up and running clean energy plants is actually way cheaper than running existing fossil fuel sources such as coal plants. The research further predicts that by the year 2025, almost all existing coal plants in the U.S. will be very costly to run as compared to building new wind and solar plants. In recent times, the need to stabilize the global climate through the use of clean energy has been gradually rising among any organizations and states in the U.S. A Clean Jobs America report by the E2 states that in 2018, the fastestgrowing job providing sectors in 12 states were in clean and renewable energy. The report also states that clean energy is also the fastestgrowing source of electricity generation, with California being the front most. This report resulted in speculation by the U.S. Bureau of Labour Statistics that clean energy will be a top job provider by 2026 with solar installers and wind technicians being the most hotcake positions.
the efforts towards transitioning to clean energy in most parts of the globe came to a standstill as all resources are now focused on fighting this deadly virus. Many factories have been temporarily closed down as others reduce their workforce by more than half due to reduced operations. Once the world is through with the current crisis, it is speculated that the fight to a stable climate will continue its course. The clean energy industry will be expected to resume its operations, and more jobs will be available in the industry. The industry is expected to play a significant role in recruiting a good number of people who lost their jobs during the Covid-19 crisis. On the other hand, many organizations and states will begin to pursue their transitioning into using clean energy due to its numerous benefits both to the economy and the climate at large. During this transitioning, there will be a lot of available niches that people can pursue both for economic benefits and to create a stable climate for ourselves and future generations. Works Cited https://www.forbes.com/sites/ energyinnovation/2019/04/22/renewableenergy-job-boom-creating-economicopportunity-as-coal-industry-slumps/ https://www.latimes.com/environment/ story/2020-04-21/why-tom-steyer-cleanenergy-investments-key-to-rebuilding-america https://atlanticcouncil.org/blogs/new-atlanticist/ the-implications-of-the-coronavirus-crisison-the-global-energy-sector-and-theenvironment/ https://www.weforum.org/agenda/2020/03/ clean-energy-coronavirus-crisis/
Due to the persisting adverse effects of Covid-19, WWW.THEPINMAGAZINE.COM
l
15
In Addressing The COVID-19 Pandemic, Congress Mustn’t Exacerbate Climate Crisis
O
n April 22 every year, the world comes together in unison to mark Earth Day. Earth Day is a celebration that is geared towards appreciating our planet as well as continue creating awareness for environmental protection. This year’s Earth Day marked the 50th anniversary of the celebration. Usually, people would go out to the streets and conduct peaceful demonstrations with posters and placards bearing environmental and climate protection messages. But this year, the celebration was not done as usual due to the outbreak of a global pandemic that has forced people to remain at their homes. This year’s celebrations were done online as the movement continued through the #ClimateStrikeOnline hashtag. The world is currently experiencing two global crises at the same time, which is climate change and Covid-19. The responsible global communities have stepped up to fight these two global challenges with their main focus being the deadly Covid-19. Governments, individuals and businesses have also embarked on a course to change their behaviours and take healthy measures to contain the situation. Individual governments have the obligation to protect their nation against any harm and this includes protection from environmental harm. To
16
l
adhere to this obligation, every state in the US has recently been implementing measures that will help in the fight against the coronavirus pandemic. But one thing we should keep in mind is that as much as we have a life-threatening pandemic, there is one that is a threat to the world right now and to the future generations; this is climate change. As a way to combat the deadly Covid-19, the US government has allocated a total of $2 trillion to the Coronavirus Aid, Relief, and Economic Security Act (CARES Act). The funds were only allocated to help in the fight against the spread of Covid-19. The $2 trillion CARES Act, however, does not allocate even a single dollar to support the clean energy sector as well as to continue supporting the climate change policy. This means that Congress is not supporting climate action in any way during this pandemic. As if that is not enough, the chairperson of the House Select Committee on the Climate Crisis on March 16, 2020, released a statement on the postponement of the planned release of the comprehensive climate policy recommendations. This move, she said, was due to the spread of the pandemic that needed more attention. In other news, the US Environmental Protection Agency (EPA) had earlier established environmental protection policies that were set to eliminate or at least reduce all forms of pollution through
THE POWER IS NOW MAGAZINE | JUNE 2020
emissions. The policies required organizations to stop air and water pollution by available means such as transitioning to use of clean energies. However, to the surprise of everyone, EPA recently suspended the environmental policies amid the Covid-19 global crisis. The suspension of the policies means that manufacturers and other polluters are allowed to go against the set laws as long as they base their violations on the impacts of Covid-19. EPA claimed that the current crisis has made it challenging for organizations and other businesses to protect its workers and the public in general from Covid-19 while at the same time adhering to the set environmental laws. Coronavirus, according to research, is a flu-like illness that attacks the respiratory system mainly the lungs. Americans who live in the cities are often exposed to air pollutants such as emissions from vehicles and other machines. These emissions with time, end up weakening the respiratory systems of many of the Americans who live in the cities. The outbreak of a virus that attacks the respiratory system means that many Americans who live in the cities are the most vulnerable when it comes to contracting the virus as their respiratory systems are already compromised. The Congress and the US government, in general, is ignoring this fact when they fail to support the climate change policy during this period. Instead, the government ought to understand that dealing with the two crises at once will be like a double-edged sword that will cut both sides and help in fighting Covid-19 while at the same time taking action towards the climate crisis.
WWW.THEPINMAGAZINE.COM
The Congress should borrow some examples from Europe who are also in a similar crisis but are not ready to loosen the climate action measures that were there before. A European leader had raised a concern to abandon the climate action measures during these times of crisis. In response to the concerns, a EU spokesperson stated,
“While our immediate focus is on combating Covid-19, our work on delivering the European Green Deal continues. The climate crisis is still a reality and necessitates our continued attention and efforts.� Although there has been a significant drop in emissions during this crisis period, the Congress should focus on implementing more environmental policies that will prevent the previous pollution from going back to how it was once things get to back normalcy. Congress should aim to address both the Covid-19 and climate change crises simultaneously to prevent further damages to human health. Works cited https://www.weforum.org/ agenda/2020/04/climate-changecoronavirus-linked/ https://www.greentechmedia.com/ articles/read/does-climate-changestill-matter-in-a-pandemic https://www.theguardian.com/ environment/2020/mar/27/trumppollution-laws-epa-allows-companiespollute-without-penalty-duringcoronavirus.
l
17
T
he economic jeopardy as a result of coronavirus is becoming more severe with each passing day. The effects of the jeopardy are worsening every day in different parts of the U.S. The $2 trillion stimulus package promised by the U.S. government may not be of ultimate help for the many small businesses and families in the U.S. and particularly in California. As the economy is experiencing further downfall, a large number of businesses have been witnessed shutting their doors due to a lack of customers and as a way of observing the public health safety measures to prevent the spread of coronavirus. As the funds are set to be disbursed, a report estimates that at least 48 million Americans will wait longer than others for the stimulus funds to reach them.
THE PLIGHT OF SMALL BUSINESSES IN CALIFORNIA
In the U.S., small businesses account for approximately half of private employment. A downfall of these small businesses may not only kill the dreams of millions of entrepreneurs but also risks causing a severe economic downfall due to the financial strain ripples through various economic aspects in the U.S. Among the small businesses that have been hardly hit by the effects of the coronavirus pandemic are the restaurants and other eateries. Carrie Reese, a 65year old owner of the M’dears Bakery & Bistro in South L.A, says that her business has dropped by 65% to 70% since the outbreak of Covid-19 in the U.S. The slowing down of her business has forced her to furlough most of her staff as the business can’t afford to pay them all. Reese further states that she pays the remaining employees order-by-order and when that is not enough to pay them all, she withdraws more money from her restaurant savings. To make the situation even worse, most of her customers choose to pay for her services via credit cards. This means that the payments will take some time, even days before they get cleared into Reese’s account. Sometimes, she says, “It’s embarrassing. It breaks my heart when people say ‘hey the check didn’t go through.” Reese’s business 20
l
As They Wait for Stimulus Aid THE POWER IS NOW MAGAZINE | JUNE 2020
is among the approximately 4 million small businesses having going through the worst of their times in California. Paycheck Protection Program (PPP) Recently, small businesses in California were requested to apply for the stimulus aid from the government known as the Paycheck Protection Program (PPP). This program is geared towards helping small businesses in California and other parts of the U.S. stay afloat. The PPP has an interest rate of 1% but can be written off under certain circumstances. The amount that can be forgiven is the amount of money spent on rent, payroll, utilities and other basic costs as stated that were incurred within the 1st eight weeks upon getting the loan. California is home to about 4 million small businesses. Out of these small businesses, only 3% of them received money from the PPP before the funds were announced to have run out sometimes in midApril. The federal government, however, has promised to release another stimulus aid soon. Reese made effort to apply for the PPP but on April 16, the American Small Business Administration (SBA) announced that it was not accepting new applications as they had run out of funds. Reese was very unfortunate since she had no other way of settling her debts. As most small businesses wait for the release of the next round funds, the businesses are at the edge of facing painful fallout. Most small businesses are not generating enough revenues to help in the smooth running of the business. Many people in California have been left unemployed due to the downfall of operations at their various places of work. California governor recently announced that more than 1 million individuals had filed for unemployment as of March 13. In San Jose, some small businesses have suffered a massive drop in revenue generation to a point WWW.THEPINMAGAZINE.COM
they cannot afford to pay for rent for the premises they are operating from. This challenge led the San Jose City Council to approve a moratorium after several renters sent eviction notices to small businesses that were not able to raise rent money. The council further approved the establishment of a common pool of public funds for tenants and small businesses that were not able to pay for the monthly rents. In efforts to save the crumbling small business sector, California governor, Gavin Newson, has given out a notice on the forward pushing of the due date for small businesses in California to file their tax returns. The deadline has been pushed to July 1, according to California governor. These changes only apply to companies whose tax returns are below $1 million annually. In further efforts to save the small businesses from crumbling to the ground, London Breed, the San Francisco mayor, declared a state of emergency in San Francisco and rolled out few measures in favor of small businesses. The mayor declared that deferments of 1st quarter tax payments for only small businesses with annual sales of to $10 million would be allowed until February 2021. The mayor also announced that there would be a delay in the collection of the Unified License bill from the city for at least three months. Small businesses in California are facing a lot of uncertainties as they wait for the release of the next stimulus aid from the government. Despite all these uncertainties, there is still hope as the coronavirus is eventually going to be out of the face of the world, and everything will be back to normalcy. Works Cited https://postnewsgroup.com/2020/04/19/californiasmall-businesses-struggle-while-waiting forstimulus-aid/. https://laist.com/2020/04/20/coronavirus_ california_small_bank_small_business_paycheck_ protection_program_exhausted.php. https://www.nytimes.com/2020/04/15/us/politics/ coronavirus-small-business-program.html. l
21
NEW RULES SET BEFORE REOPENING THE ECONOMY
I
IS IT TOO SOON?
n mid-April, the US president rolled out new federal guidelines that contain the conditions under which some parts of the US should consider reopening their economies. During the press briefing, the US president stated, “We must have a working economy. And we want to get it back. Very, very quickly. And that’s what’s going to happen.” The federal guidelines require some states in the US to start loosening some of the strict public health measures such as social distancing that were established to put the Covid-19 situation under control.
The guideline plan which has a total of 18 pages, is titled “Opening up America Again,” which clearly explains the events under which some parts of the country should begin allowing a gradual and wellmonitored event of a return to normalcy such as people to start attending their workplaces. However, the move to lift the restrictions will entirely be on the conclusion arrived at by the state governors. During the briefing, Trump stated that approximately 29 states are in a position to reopen relatively soon due various reasons. Trump states 22
l
that, “We have a lot of states that, through location, through luck and also through a lot of talent ... are in a very good position.” The states said to be in a good position were expected to loosen their restrictions by the beginning of May. The guidelines state that before beginning implementing the first phase, the number of cases or new infections of even flu-like symptoms in the area must be trending downward for 14 days. The guidelines further state that any individuals THE POWER IS NOW MAGAZINE | JUNE 2020
considered vulnerable should continue staying at home until declared safe to go to social places by a health expert.
safe enough is through conducting extensive tests to the people of America and ensure that the virus is vanishing from the face of America. The public cannot feel safe when the country continues to report Legal experts, on the other hand, claim that the new thousands of deaths from Covid-19 every passing day. federal guidelines will be challenging to implement as The economy should not be reopened when people the federal government cannot counter public health don’t feel safe to go back to their normal activities. measures issued by the different states. Therefore, Jeffrey Pfeffer, a professor of organizational behavior, the states are required by any law to adhere to the argues that there should be no trade-off between federal guidelines. However, the guidelines are putting public health and economics. He further states that the governors under a lot of pressure to let loose healthy people are more likely to be present at work, some of the restrictions. both physically and mentally, and also be more productive. He, therefore, says that the The move by the federal governments only time to get back to normalcy is has received a lot of reaction from when sufficient testing is done and the American people and different contact tracing to map the spread “We have a lot of experts as well. Health experts of the disease, which he states are and other business leaders not in place at the moment. states that, through warn that for the restrictions location, through luck to be lifted, the government Daily press briefings by the and also through a lot should first conduct a massive government indicate a rapidly testing exercise that will ensure rising number of infections and of talent ... are in a very the safety of Americans as they deaths due to Covid-19. It is good position.� go back to their workplaces. crystal clear that this is not the most suitable time to reopen the The issue of when to reopen the US economy for the sake of the economy has received several safety of Americans. Reopening the responses and suggestions from economy at this time may be too soon various concerned experts. Heidi Shierholz, which may risk re-introducing a second an economist, states that the matter should wave of spread of Covid-19. be directed to public health officials and not to economists. He further says that during such a crisis, the recommended public health policy is also the most suitable policy for the economy. Research has shown that areas that implement and strictly follow Works Cited public health measures such as social distancing https://www.theguardian.com/commentisfree/2020/ during pandemics like the Covid-19 revive and grow apr/16/when-is-the-right-time-to-reopen-the-usfaster when the pandemic is gone. economy-coronavirus-our-panelists-verdict. https://www.cnbc.com/2020/04/16/coronavirus-trumpRobert Reich, a professor of public policy at the issuing-guidelines-on-reopening-parts-of-us-amidUniversity of California, states that the economy outbreak.html. should not reopen because the president ordered so. https://www.theguardian.com/us-news/live/2020/ Instead, the economy should reopen when the public apr/16/us-coronavirus-latest-updates-trumpfeels safe enough. The only way for the public to feel guidelines-reopening-economy.
CaliforniansForAffordableHousing.Org
Myth vs. Fact MYTH
This proposition is necessary to maintain lower rents and control the housing crisis.
FACT
Governor Newsom just signed new statewide rent controls into law that went through legislative hearing and public input. This flawed, special interest proposition would go into effect before we even have a chance to see the benefits of the newly signed law. This proposition will only reduce the housing supply and drive rents and housing costs up even higher – making California’s housing crisis even worse.
MYTH
This proposition will make housing more affordable.
FACT
This proposition will do the exact opposite. By creating an inconsistent and unpredictable patchwork of local ordinances, this proposition will prevent critical affordable housing development and drive rents and housing costs up even higher. It will even increase prices for existing housing and make it even more difficult for families to purchase their first home. In fact, the proposition will put as many as 539 rental boards in charge of housing, with bureaucrats deciding what people can or cannot do with their properties, and will give the rent boards unlimited power to add fees on housing, which will ultimately be passed on to tenants in the form of higher rents. As a result, the proposition will increase the cost of existing housing and make it even harder for renters to find affordable housing in the future.
MYTH
This proposition will give renters immediate relief.
FACT
This flawed proposition does not force the state or any city to lower rents and does not enact any new tenant protections. The proposition... • • •
Will NOT provide any immediate relief for people facing higher housing costs. Will NOT increase funding for affordable housing. Will NOT force local communities to build the housing approved in their general plans.
MYTH
The proposition will help California’s economy.
FACT
The state’s nonpartisan Legislative Analyst’s Office found that this proposition would result in the loss of tens of millions of dollars in revenue for the state and local governments. This could result in less money for schools and emergency services, reduced new home construction, and a loss of thousands of well-paid construction jobs.
MYTH
This proposition will help restore California’s impoverished communities.
FACT
This proposition will encourage landlords to take their rental properties off the market and convert them into condos, tenants-in-common (TICs), and townhomes, further reducing housing supply and making the housing crisis even worse. It could even force thousands of renters – including seniors and others living on fixed incomes – out of their apartments and communities.
THE BOTTOM LINE:
The flawed rental housing proposition will make the housing crisis even worse. Vote NO on November 3!
Ad paid for by Californians to Protect Affordable Housing a coalition of housing advocates, renters, large and small businesses, taxpayer groups, and veterans
CaliforniansForAffordableHousing.Org
Fact Sheet California just passed the toughest-in-the-nation statewide tenant protection law that provides certainty on rent increases while ensuring critical affordable housing is still built in our state. But Michael Weinstein and his multi-million dollar special interest group recently qualified a proposition (Initiative 19-0001) for the November 3, 2020 statewide ballot that would undermine this new critically important law. These are the same special interests who spent more than $25 million on the flawed rental housing measure, Proposition 10 in 2018, which voters rejected overwhelmingly with a 59% NO vote. Don’t be misled. This new proposition is even more flawed than their last proposition. It’s bad for homeowners and renters – and will make California’s housing crisis even worse.
Undermines California’s New Statewide Rent Control Law •
•
Governor Newsom just signed new statewide rent controls into law and this flawed proposition would go into effect before we even have a chance to see the benefits of the new law, which was supported by a broad coalition of social justice groups, including the California Community Builders, the California State Conference of the NAACP, California YIMBY, The Two Hundred, the California Labor Federation, the State Building and Construction Trades Council and the Western Center for Law and Poverty. This new law, AB 1482, sets a statewide cap on annual rent increases (5% plus regional inflation) and prohibits unjust evictions – keeping families inside their longtime homes.
Does Not Enact Any New Tenant Protections •
This proposition does not force the state or any city to lower rents and it will not provide any immediate relief for people facing higher housing costs.
Widens the Inequality Gap and Disproportionately Benefits the Wealthy •
This flawed proposition allows wealthy individuals to take advantage of rental assistance and includes no guarantee that low-income renters will receive the help they need. Studies show that such policies disproportionately benefit the wealthy rather than helping those who need it most.
Reduces Housing Supply and Drives Up the Cost of Existing Housing • •
•
Housing costs are high because California hasn’t been building enough housing to keep up with population growth – we have a supply shortfall of about 3 million units. This proposition does not increase funding to build badly needed affordable housing. By creating an inconsistent and unpredictable patchwork of local ordinances, this proposition will prevent critical affordable housing development and drive rents and housing costs up even higher. It will also encourage landlords to take rental properties off the market and convert them into condos and townhomes, further reducing the rental housing supply and making the housing crisis even worse.
Accelerates Gentrification of Our Communities • •
This flawed proposition is not a guarantee that our communities and neighborhoods will be preserved. In fact, it will accelerate the pressures for gentrification by creating an economic incentive for landlords take their rental properties off the market and convert them to other uses. In one example, from 2000 through 2018, US Census Bureau data shows the African-American population remained essentially level for the state as a whole, yet their population in the 15 rentcontrolled cities dropped by 19% - a population shift of more than 130,000 out of these communities. The drop was even steeper in the Bay Area cities – the region creating most of the higher wage jobs in the state – at a total of 23%.
Ad paid for by Californians to Protect Affordable Housing a coalition of housing advocates, renters, large and small businesses, taxpayer groups, and veterans
As far as housing is concerned, the spring
During spring, the sellers listing prices usually are high until the high demand season is over. The listing prices become even higher during the summer season, according to previous events. Research shows that listing your home when the prices are at peak could add you a 1.1% on your listing price. During this year, the situation is different. At this time, the listing prices are supposed to be trending upwards, but instead, they are actually dropping. The unusual trend is as a During April and March, the activities of listing, buying, and selling of homes usually are at the peak. result of the effects of Covid-19. According to a survey conducted by NAR Flash If the “Stay at Home” campaigns remain until later on the economic pulse in mid-March, almost 50% in the year, most families that had halted their of real estate agents confirmed that there was a decrease in buyer interest as a result of the impacts home-buying plans may now begin to search for a of the pandemic. home to buy despite the ongoing crisis. The search period has always been the busiest time for home sellers and buyers. But for this year, the narrative has dramatically changed due to the spread of the deadly Covid-19 pandemic. The pandemic has rapidly spread in the US, forcing the states to put in place public health measures that forced people to remain at their homes and brought a downward trend of the economy.
COVID-19
POISED TO UPEND NORMAL SEASONAL HOUSING As the effects of the pandemic continue to persist, the prices of homes are likely to reduce. The drop in prices is a result of the release of the relief funds that have seen lenders offering options for mortgage forbearance. Also, on the other hand, the number of unemployed individuals is rising with each passing day. The loss of jobs could force many people to sell their homes, and this potentially leads to a drop in prices of homes. The decline in home prices comes as a surprise to many people as they expected home prices to shoot up due to loss of jobs and the persisting effects of Covid-19. Due to fear from the spread of Covid-19, many people who were planning to sell their homes during this year’s spring season will be forced to wait until the pandemic is over. No one would want to let agents and potential buyers to come and view their homes due to fear of getting into contact with a person with Covid-19. When the pandemic is over, many home sellers will now go ahead to place their homes under listings. On the other hand, there is a high chance that people who were planning to buy homes during the spring season are also waiting for the pandemic to go away in order to go on with their plans.
26
l
for a new and better home may also be compelled by the many hours and days that were spent at home hence making the occupants bored by their current place. 2020 is going to be no typical year in the housing market. The effects of Covid-19 have already shown that this year’s schedule is not going to be a normal one in terms of the occurrence of events. So it is best for potential buyers and sellers to ensure flexibility to be able to cope with these trying times.
References https://www.realtor.com/advice/buy/real-estateagent-wants-you-to-know-housing-marketcoronavirus/. https://www.realtor.com/research/initial-impactcovid-19-housing-market/. https://www.realtor.com/advice/buy/should-i-buy-ahouse-during-coronavirus-crisis/. https://www.realtor.com/research/covid-19-poisedupend-normal-seasonal-housing-trends-can-sellersexpect-year/
THE POWER IS NOW MAGAZINE | JUNE 2020
THE PACE OF HOME SALES REACHED NEW RECORDS IN FEBRUARY COVID-19 IS LIKELY TO BRING CHALLENGES TO BOTH BUYERS AND SELLERS
In February, before the onset of the severe Covid-19 crisis, the housing market was operating at a record pace. Sellers were continuing to gain more leverage while buyers were benefitting from the low mortgage rates. According to Realtors.com estimates for the speed of the market in February, supply reached 3.3% in combination of the 50 largest markets. Realtor.com arrive at the estimates by determining the ratio of the active listings to closings of home sales. The February pace was, however, recorded as the highest compared to the previous years. The estimates by realtor.com indicated a 0.3% rise in supply over January and a 15.6% drop when compared to February 2019. According to experts, a decrease in a month’s supply figures represents a fast and more seller-friendly housing market as it shows that there are more homes listed for sale as compared to the current rate of home buying. On the other hand, the February month’s drop in supply was an early indication that there would be an occurrence of a future decline in the housing market. This means that housing market experts were already aware of the coming deceleration even before the onset of the Covid-19 pandemic. Another indicator for the future slowdown in the housing market was the drop in supply rate in percentage as compared to the previous year’s February percentage. The 15.6% in months’ supply in February was significantly lower than the 22.6% in January and a 21.3% drop in
28
l
THE POWER IS NOW MAGAZINE | JUNE 2020
December last year. The decrease in the month’s supply is said to have been recorded since October 2019. As the Covid-19 crisis set in, the housing market stalled, presenting a particular challenge to both the home buyer and sellers. Since the onset of coronavirus, home buyers and sellers have found it so challenging to track the housing market to obtain the necessary information before making any transaction. Currently, each party (that is the buyers and sellers) is responding differently to the situation brought by Covid-19, which features dynamic shifts of both the buyers’ and the sellers’ markets. On the seller’s side, the rates of listings getting in the market have dramatically dropped. The drop in listing rates has resulted in a decline in inventory added to the national pool of listings. On the other hand, social distancing measures have led to a very low number of closed sales in the housing market. The drop in the rate of new listings has contributed to the small amount of listing inventory, which in turn resulted in a low number of closed sales recorded during these times of crisis. However, everything that has an alpha must also have an omega. The Covid-19 pandemic is going to be no more in a matter of time. Once this is over, the economic activities are expected to be back fully operational, and the housing market will be expected to reset back and pick up from where it left. According to experts, once these times have passed, listings and home sales will be most likely to shoot up in different phases. There will be a large inventory as the listings will be accumulating, and this will result in a significant rise in the numbers of a months’ supply. This upward trending of the rate of a months’ supply will, in return, result in a temporary shifting of the housing market to a buyer’s market. The rate of home buyers will gradually catch up with the accumulating listings, and they will eventually balance out. Interesting, right?
Works Cited; https://www.realtor.com/research/the-pace-of-home-sales-reached-newrecords-in-february-but-covid-19-likely-to-bring-challenges-to-both-buyersand-sellers-in-the-near-term/.
WWW.THEPINMAGAZINE.COM
l
29
Education for
Borrowers:
5
CARES ACT details you
should know about Like the disease that effected it, there is an unusual amount of uncertainty surrounding this Act. The Coronavirus Aid, Relief, and Economic Security else known as CARES Act was signed by the president on March 27 after having passed both the House and Senate. In its wake, the Act has brought uncertainty in the mortgage performance amidst the widespread hardships brought about by the virus. No one was expecting the virus, and even the country was not prepared for such an emergency, which makes the situation very complicated. One thing for sure is the inconsistency, and at times, there have been faulty messages about public loss-mitigation requirements, which has made the situation a lot worse. Much information about the virus and efforts made have now become a public spectacle, and much information is being publicized on TV, by politicians and news outlets, and while some pieces of what’s getting out to the public are somewhat accurate, most of it is not.
Given the overwhelming nature of what we are dealing with, this is totally understandable. 30
l
However, stirring winds particularly harder is the CARES Act and some other related policies. Now, the loss mitigation may be the most effective, supposing the single-family housing-finance industry stakeholders communicated clearly on some aspects of the law. Within the 800-page bill, there are some provision affecting the borrowers and employers, including the requirement for the coverage of COVID-19 testing and treatment. Additionally, there are other provision extending to and beyond the coronavirus into other aspect of the employer benefit designs and that has the potential to impact group health plans beyond the current emergency situation.
FIRST, YOU NEED TO UNDERSTAND NOT EVERYONE’S ELIGIBLE There is a mixed reaction around this new law. Some are happy at least; some are not and some are confused. Some borrowers think that a federally mandated penaltyfree payment break as a result of the coronavirus removes their obligation to make the payments for the time being. While that is true, in reality, it is available only upon request for certain government-related loans, pay attention to that as the borrowers that suspend their payments are still very much responsible for making them later. What does this mean, if you are capable of continuing with your payments, do not stop. The mortgage industry must come clear emphasizing this message to the public.
”If I were writing the script, I would say something like, ’Forbearance is not forgiveness, but there will be a deferred payment until you get back on your feet,’” said Faith Schwartz, a housing finance consultant who helped set loss mitigation policy during the 2008 housing crisis. ”Forbearance does not mean your payments are forgiven. You are still required to eventually fully repay your forbearance, but you won’t have to repay it all at once — unless you are able to do so,” the Freddie Mac script says. THE POWER IS NOW MAGAZINE | JUNE 2020
SECONDLY, THE CARES ACT IS VERY VAGUE ON REPAYMENT PATHS What the Act has been clear about is that loan servicers should not penalize borrowers for deferring their payments, however, what is unclear with the bill is that it doesn’t specify what happens afterward when the grace period ends. However, it is encouraging that some entities are already making plans and mapping those plans for how they will handle this. The best example is the Bank of America, which is currently implementing a plan to add payments deferred for the Coronavirus hardships to the end of portfolio loans’ terms and extend regular payments by the amount forborne. Therefore, it is important to seek direction with your loan servicer on the repayment plan afterwards, to avoid confusion and more hardship. One thing is certain, for the people seeking out ”breaks” in their payment without a repayment plan, they might face financial hardship.
THIRDLY, NOTHING’S FREE! ALL CORONAVIRUS ACCOMMODATIONS GET A PASS ON CONSUMER CREDIT RECORDS You need to understand that deferral requirements are restricted to certain federal loans. The CARES Act also has defined a broader mandate for the accommodations made to address the impact of the Coronavirusrelated hardships on other types of consumer debt. Under the provision, the borrowers that stick to the terms of that accommodation must be temporarily reported as current on their credit reports.
FOURTH, WHAT’S HAPPENING WITH THE COVERAGE OF COVID-19 TESTING AND TREATMENT? The best action is that group health plans have to cover COVID-19 screening and related office visits without cost-sharing. This has to include COVID-19 tests that may not have been approved by the FDA. Additionally, the group health plans must also include without costsharing, ”qualifying coronavirus preventive services,” which are items, services, and immunizations that are intended to prevent or even mitigate COVID-19 that receive a rating of ”A” or ”B” from the US Preventive Services Task Force (USPSTF) or even a recommendation from the CDC Advisory Committee on Immunizations Practices (ACIP) concerning the individual involved.
LASTLY, EVEN WHEN PAYMENT RELIEF ISN’T REQUIRED, IT MAY BE AVAILABLE
”This accommodation includes anything, whether it’s [one made for] a mortgage loan that’s not federally backed or any other type of loan like a credit card, a boat loan, a car loan, anything at all,” said John Ulzheimer, a former credit bureau employee and president of The Ulzheimer Group, a consulting firm in Atlanta. ”As long as there’s an accommodation that’s made by a lender and you live up to that agreement, then they have to report you as current.”
Some individual companies may opt to provide deferrals or other types of assistance in response to the coronavirus related financial concerns even when they are required not to do so. Again, this is best shown by the Bank of America, which has offered a three-month payment deferral without penalty. Borrowers can request this online or by phone for the many mortgages it holds in its portfolio. The bank has also said that it may extend that through the duration of the crisis if need be.
It is recommended that consumers check their reports to see if this requirement reflects on their statements as the credit reporting companies themselves are experiencing their own hardships.
Sources and Works Cited https://www.nationalmortgagenews.com/list/5cares-act-details-mortgage-servicers-mustensure-borrowers-know https://www.benefitnews.com/opinion/5-thingsemployers-need-to-know-about-the-cares-act
WWW.THEPINMAGAZINE.COM
l
31
ZOOM VIDEO AND OTHER VIDEO PLATFORMS TO S AV E T I ME A ND C O ND U C T B U S I NE S S According to a report by Global Market Insights, video conferencing, and other forms of remote collaboration are speculated to have a market worth $24 million by 2024. With such significant growth, there will be hundreds of platforms to choose from, such as Zoom, GoToMeeting, Skype, Microsoft Teams, among others. The video conferencing platforms are majorly used almost in all businesses to conduct meetings and webinars without the need
Z
oom Video conferencing and other video platforms will help you save on time and smooth running of your business through the following ways;
1. Video platforms are easy to set up, use, and manage
Most of the video platforms, such as Zoom, is very straightforward when it comes to using it. The process of purchasing and installing is also as easy and with no hidden fees. When using Zoom, joining a meeting is only one click away. Zoom is also usually very user-friendly, featuring an easy collaboration with straightforward participant controls. What all this means is that you don’t need to be an IT guru, or rather you don’t need a tech team to manage Zoom.
2. Save up on costs
The use of video conferencing in any business saves on a lot of expenses. When a meeting notification is sent, no one needs to start planning on how they are going to travel to their places of work to attend the meeting. You can simply do it from your PC or smartphone from wherever you are. Video conferencing also helps businesses save on cost since there will be no funds needed to set up anything.
3. Useful during short-notice meetings
Video conferencing plays the most significant part
WWW.THEPINMAGAZINE.COM
for a physical meeting. The technology of video conferencing has transformed the world of business in significant ways. Among the best new platforms is the Zoom Meeting software and app available in both a PC version and a mobile device version. The Zoom Meeting platform has made it possible for many businesses to save on so much time and other resources that would be used in holding organizational conferences.
when an organization needs to hold a meeting on very short notice. When a need arises, the targeted parties can easily be contacted and notified of the meeting on short notice, which they can be able to attend from wherever they are. You only need to pause what you are doing for a moment and participate in the meeting. This, for sure, saves the organization a lot of time and energy. Video conferencing platforms such as Zoom come with a perfect combination of unique features that are aimed to ensure you get the best out of your business meetings. Zoom has the unique feature of screen sharing as well as content sharing that enables you to share the content on your screen for demonstration. Zoom also can be used to effectively conduct group meetings and client meetings with multiple participants through a personal meeting ID. You can also use Zoom to carry out webinars, tutorials, and any other form of demonstration.
Works cited https://blog.zoom.us/wordpress/2020/01/24/zoomvideo-communications-small-business-benefits/. https://blog.prialto.com/3-reasons-why-zoomprovides-the-best-video-conferencing-software.
l
34
THE CURSE OF THE DECADE HOW COVID-19 IS SLOWING PHOENIX METRO MULTI-FAMILY DEAL CLOSURES
W
hen the novel coronavirus was first reported in the US, there was not much panic or threat. As the virus slowly and surely crept in and spread to a better part of the country, states and the federal government rushed to implement public health measures to put the coronavirus pandemic situation under control. By the beginning of March, almost the whole of the US was under lockdown. That meant that no businesses were operating unless for those that offer essential services. The effects of the pandemic were felt in every aspect of the US economy, including in the housing market. Although in early April, Valley housing experts stated that it was somewhat early to predict how the curse of the decade would impact the housing market in the US. On the other hand, Arizona real estate experts were contending to head into the uncertain economic situation claiming that the Phoenix metropolitan housing market was well-positioned to face the storm.
WWW.THEPINMAGAZINE.COM
Mark Stapp, the executive director at The Center for Real Estate Theory & Practice at the W.P. Carey School of Business at Arizona State University, commented that “It is very early in this process… Only in the last two weeks has there been any data to show any profound effect. You are starting to see Escrows cancel --We have about 30 days to see how this is going to play out here. The reality here is it is going to have profound impacts. It will pull things up short for quite a while. How long this lasts, and the financial ramification and how the federal government deals with it will play a ma jor role.” Before the onset of the coronavirus pandemic, Phoenix housing was progressing pretty well since the beginning of the year, sending an implication on the wellbeing of the housing market and promising better days ahead. When the pandemic was reported in the country, and its effects slowly spread, the narrative changed. Operations suddenly stopped temporarily as the stay-home directives took effect. Mr. Stapp states, “It is not a complete shutdown, but the agents I have spoken to say they are beginning
l
39
to see cancellations… We are talking to a few different Realtors, and it is almost one in four that are closing.” The economic disaster due to the pandemic has profoundly impacted the housing market and is going to be a blow to both the landlords, real estate dealers, and lenders. “Now we run the risk of a really significant financial disaster,” Mr. Stapp commented on the economic concerns of the pandemic. “It is going to come down to the level of empathy from landlords and lenders, in particular.” In another event, the senior managing partner for Phoenix-based ABI Multifamily, John Kobierowski, explains what the business is going through as a result of the impacts of the pandemic. In the middle of March, he was all excited about the 30 multi-family properties he already had in escrow. He has all the reasons to be excited as there was a good sign from investors from all over the country, having recently shown so much interest in buying metro Phoenix real estate multifamily houses.
40
l
In the previous year, Mr. John and his team had sold more than 130 multi-family apartments in Arizona. By March 2020, they had already sold off 24 multi-family properties with 33 others on the listing and 28 in escrow. This is such a perfect sign for a real estate dealer that deserves more than just excitement.
The financial situation due to the Covid-19 pandemic seems to be worsening, and Kobierposki is uncertain about the future. “Whatever is going to happen, I don’t see a bunch of new ones originating very quickly until people feel confident where the market is going,” he states.
As the situation keeps getting more severe with each Towards the end of March, the passing day, let us, however, narrative was a whole different not lose hope. Nothing lasts forever; not even the one with a whole different Covid-19 pandemic will. reality due to the effects of the In the meantime, let us coronavirus pandemic. “We’re in join our efforts to ensure a wartime situation,” John states. that we win this war. Keep “Everything is very fluid.” John adhering to the state gives an example of an event directives at all times. on March 20, where the money
to close two house deals were being wired but hung up in the process. “We got an email that said the system behind 90% of the bank wire transfers crashed on Friday.” He states. This meant that they had to do transactions via manual wire transfers. “The whole process of moving money around is slowing, and that affects buying and lending and is slowing commerce,” he adds. This situation leaves him full of uncertainties, and he is not sure how fast he can close escrow on the deals already in progress.
Works cited https://www.bizjournals. com/phoenix/ news/2020/03/24/howthe-coronavirus-is-slowingphoenix. https://www.yourvalley. net/stories/phoenixmetropolitan-housingmarket-braces-forglobal-pandemicimplications,151167
THE POWER IS NOW MAGAZINE | JUNE 2020
THE PHOENIX HOUSING MARKET STABILIZES AS SELLERS YANK LISTINGS NATIONWIDE
Peggie Simmons
M
arkets all over the country are in chaos. Buyers have been locked in their homes, and sellers are not listing for fear of selling during an economic crisis. While that is true for most areas, one market remains standing, defying all odds. The housing market in Phoenix appears to stay afloat; however, many real estate professionals say that the pandemic has brought change to the Phoenix market needed. While the Metro Phoenix market is healthy, that doesn’t mean that the economic downturn in the country will leave it unscathed. In the past few weeks listing have climbed 20%, which is a clear indication that the homeowners are struggling financially and are hoping to get out of their mortgages or short-term rental owners who do not have customers and are looking to sell. The number of homes for sale is still 32% below the same time last year according to an Arizona Housing expert Tina Tamboer of the Cromford Report. Nonetheless, most experts agree that for the coming months, the Phoenix housing market, like most others, will hunker down.
“People aren’t moving now, and that means they aren’t buying homes,” Elliott PollackVeteran Arizona economist said. “’ Phoenix’s strong population growth was driving the housing market. That’s over until this crisis is over.”
RE-SETTING THE MARKET In overall, however, the market itself is looking to be doing what it was needed to do, and most real estate experts say that the Phoenix market is in a state of reset. Before the pandemic hit, there were just 10,000 homes available for sale in the Phoenix market, with only a few houses in the market, that meant that most buyers were kept out of reach. Remember the Phoenix market has about 7 million people, and having just 10,000 properties for sale, was a meager number. Since the coronavirus hit, the number of homes has jumped to more than 14,000 available units of purchase. This just shows that the market is headed in the right direction since a stable housing market should at least have 20,000 to 25,000 units available which is good news for the buyers. This just shows how serious the seller is, after all, who would want to sell their home during a pandemic? Over the years, we have seen the median home prices rise rapidly, in April 2018, the median home price for homes in and around the Phoenix market area was $255,000. In 2019, it jumped to just over $267,500, and in March 2020, it was just under $299,400. What will happen is that, with more units available for sale in the market, the home prices will stabilize. And while it is still a seller’s market, we shouldn’t be worried about that. What’s truly interesting with the Phoenix housing market is that even though there are more houses for sale in the market, homes are being shown through virtual tours instead of open-house tours. l
43
HOUSING DATA TRENDS MONTHLY SALES The latest preliminary report from the Arizona Regional Multiple Listing Service shows that sales are up 18.5% month over month and 3.4 Y-o-Y.
NEW INVENTORY AND TOTAL INVENTORY New inventory is up+21.3% monthover-month while the year-over-year comparison increased by +0.9%. On the other hand, Total inventory has a monthover-month increase of +17.1% while yearover-year reflects a decrease of -21.3%.
Right now, it may feel as if the situation with this virus will not change. It is human 44
l
nature to feel that way, but one thing you should never do is to give up. Over the years, we have seen several ups and downs in the real estate in Arizona, but what’s happening right now is somewhat unique. If you want to stay ahead with what’s happening in the Phoenix housing market, get in touch with Peggie Simmons. Peggie Simmons is no ordinary realtor; she has 34 years’ experience as a real estate agent and broker in Tempe, Arizona, and currently serves as the Founder and CEO of Realty Marketing Group specializing in relocation, new homes sales, traditional homes, marketing & sales, short sale negotiations, foreclosures, luxury rentals, investments among many others. Despite doing her business in Arizona, she also has been a resident of the state since 1983, which makes her your ideal choice and your go-to real estate agent. Go ahead and take advantage of the situation right now while it still lasts. To learn more about Peggie, go to https:// thepowerisnow.com/vipagentsservices/ peggie-simmons-arizona/ and find out more.
Sources https://armls.com/docs/2020-MARCHSTATwith-commentary.pdf https://www.azfamily.com/news/ continuing_coverage/coronavirus_ coverage/covid-19-could-helpstabilize-phoenix-area-home-prices/ article_7d8b4110-7dc8-11ea-a1bb8f765812690b.html https://www.usatoday.com/story/money/ real-estate/catherine-reagor/2020/04/05/ dont-expect-metro-phoenix-housingmarket-crash-due-covid-19-sayexperts/5114064002/
THE POWER IS NOW MAGAZINE | JUNE 2020
THE FORECLOSURE MARKETS
REACHES RECORD LOWS Kamesha Keesee
F
oreclosure is the legal process through which a lender takes control of a property, evicts the homeowner, and sells the home after the homeowner is unable to make full payment of the principal and the interest payments on their mortgage as stipulated in the mortgage contract. The foreclosure process mainly derives its legality from the mortgage or the deed of trust contract, which gives the lender the right to use the property as security or collateral in the event that the buyer fails to uphold his or her repayment obligation. According to a report by ATTOM Data Solution, there were a total of 48,004 U.S. properties with foreclosure filings- default notices, scheduled auctions, or bank repossession, which represents the lowest number of total foreclosure filings recorded since 2005.
“
Foreclosure activity across the United States hit new lows in February, yet another marker of the nation’s long housing boom,” said Todd Teta, chief product officer with ATTOM Data Solutions. “However, as with just about anything connected to the housing market right now, the foreclosure situation is now totally in flux because of the everevolving coronavirus pandemic. Many lenders have suspended foreclosure proceedings, so the numbers will most likely continue to drop in the coming months. But after that, we may see an uptick in foreclosures as a result of dramatic economic impacts, such as more homeowners losing their jobs and falling behind on mortgage payments.
”
CoreLogic also reported that countrywide, 3.7% of all the U.S. mortgages were delinquent- at least 30 days past due, and this includes the foreclosures. Looking at these statistics, you will notice that there is a slight decline from December 2018 and the lowest in a month in almost 20 years.
Foreclosure Completion Numbers Continue Annual Decline Lenders repossessed 10,469 U.S. properties through completed foreclosures (REOs) in February 2020, up by 1 percent compared to January 2020 and down 8 percent from last year. This shows a second consecutive annual decline in completed foreclosures. The states that showed an annual decrease in REO in February 2020 included; Florida (down 47 percent); New Jersey (down 37 percent); New York (down 18 percent); Texas (down 16 percent), and Maryland (down 13 percent). The ma jor MSAs with a population of over 200,000 that saw the greatest number of REOs
included; Chicago, IL (614 REOs); Riverside, CA (529 REOs); New York, NY (446 REOs); Los Angeles, CA (368 REOs); and Philadelphia, PA (328 REOs). ATTOM additionally reported the highest foreclosure rates in New Jersey, Illinois, and Delaware noting that on a nationwide scale, one in every 2,841 housing units had a foreclosure filing in February 2020. In New Jersey, one in every 1,457 housing units had a foreclosure filing. In Illinois, one in every 1,507 housing units had a foreclosure filing, and in Delaware, one in every 1,628 housing units had a foreclosure filing. In South Carolina, one in every 1,688 housing units had a foreclosure filing, and lastly, in Maryland, one in every 1,713 housing units had a foreclosure filing. The metro areas with a population greater than 1 million with the worst foreclosure rates in February included Riverside, CA, Chicago, IL, Philadelphia, PA, Cleveland, OH, and Baltimore, MD. In February 2020, lenders started the foreclosure process on about 27,000 U.S. properties, which is up by 3 percent compared to January and down 9 percent from the same time in 2019. This is the 13th consecutive month showing an annual decline. The states that showed a double-digit increase in the foreclosure start from January included; Nevada (up 63 percent); Oregon (up 49 percent); Washington (up 47 percent); Texas
(up 28 percent); and Michigan (up 20 percent). This data has been provided by ATTOM Data Solution. To learn more, visit; https:// www.attomdata.com/news/markettrends/foreclosures/attom-data-solutionsfebruary-2020-u-s-foreclosure-marketreport/ If you’d like to understand more about the data given or learn more about real estate markets, especially the Inland Empire real estate, get in touch with Kamesha Keesee of the Kamesha Keesee Realty. Mrs. Keesee epitomizes hard work, resilience, compassion, and creative service delivery in every detail of your real estate transaction, from the start to the closing. Kamesha’s journey in real estate business began when she was 15 years old, where she was employed as a teller at Security Pacific Bank. Being energetic and as curious as she was, she quickly adapted to the changing employment environment and became a personal loan officer. This would be a remarkable point in her life as it was the first contact with the real estate industry. Even though her early career in real estate was not by choice, but by somewhat an accident, it would turn out to be the best turn of even for her. To learn more about Kamesha and her work, go to; https://thepowerisnow.com/ vipagentsservices/kamesha-keesee/. Kamesha Keesee President and CEO Kamesha Keesee Realty. Sources https://www.investopedia.com/terms/f/ foreclosure.asp https://www.attomdata.com/news/market-trends/ foreclosures/attom-data-solutions-february2020-u-s-foreclosure-market-report/
THE COMMON
REFINANCING MISTAKES HOMEOWNERS ARE LIKELY TO MAKE DURING THIS CRISIS
David C. Trubey
I
n the wake of the coronavirus pandemic, the Federal Reserve had to drop the federal funds rate to about 0% and 0.25% to stimulate the economy. The number one mistake that most people made is assuming that the drop in federal funds rate meant that the mortgage rates would fall into the same range too. But that’s not the case. Remember that the Federal Reserve interest rate, the prime rate, and the lender rate are all different rates. The federal funds rate is set by the Feds and is the rate that the bank pays to borrow
WWW.THEPINMAGAZINE.COM
Mortgage rates have never been this low. And again, the coronavirus pandemic is sending our economy in a tailspin, which has trapped so many people into believing that this is the right time to refinance their properties. This is a very risky move and one mistake that could cost these buyers tons of money in the long run. Therefore, if you think that this is the right time to refinance, do it with caution, but not before you read this article. Do not assume that a federal rate of 0% means 0% mortgage rate!
from each other. This will not any interfere with the mortgage rates, at least not directly; however, it does have a trickle-down effect. You have to understand that the mortgage interest rates are affected by many variables, and that includes where you live, your borrower’s profile among so many others. The prime borrower with a good credit score and debt-toincome ratio will get the cheapest rate. If you aren’t an ideal borrower, your rate will be higher. You must have noted that in the past few weeks, the interest rates
have been fluctuating. This might go on for a few more weeks before finally leveling out. Therefore, as a prospective buyer looking to refinance, do not do it with unrealistic expectations.
Having New Credit Accounts and Running up Debt
With what’s happening with the economy, certainly, most people are likely to fall in debt. Making a ma jor purchase on credit or even applying for new credit could lead to delays in the approval process, and in the worst case, you could even be rejected for a mortgage refinance loan.
l
49
Every time you open up a new credit channel, you increase the chances to lower your credit scores. Lower credit scores translate to higher mortgage rates. While at times, it is difficult to put an estimate to the number of points you lose due to a newly opened credit account and inquiries versus the missed payments and maxed-out credit cards. According to a study by FICO, on average, the people with the best credit scores have not opened a new credit account in more than two years.
Do Not Jump on The Refinance Trend Too Late
Well, a few weeks ago, we have seen an influx in the number of people opting to refinance, and if you are thinking along the same line, it may be already too late. With so many people rushing to refinance, lenders have been inundated by the demand, and the rates have risen.
“We are seeing a ma jor influx of refi applications to capture lower interest rates,” Nicole Rueth, a mortgage lender with Fairway Independent Mortgage Corporation, explains. And you’d think that it’s only the homeowners hoping to score a deal during the recession, plenty more are visiting the lenders to prepare for an uncertain future. Most experts are reporting to have seen a rise in the number of homeowners leveraging equity with the cash-out refis, intending to secure their future during the ongoing COVID-19 emergency. The Mortgage Bankers Association has also reported an increase in the number of refinancing applications up 79% and 479% Y-o-Y. And since the industry was unprepared for all these applications, many lenders were forced to hike up the rates to slow business. “Mortgage rates move according to supply and demand and liquidity in the market,” Mike Zschunke, a real estate specialist in Arizona, says. “The more people that want to refinance or that apply for new mortgages, the higher the rates will go.”
Do not Forget About the Fee Factor
Right now, it might be hard to get a reasonable refinance rate. However, that doesn’t mean that it is impossible to find a better rate than the one you have gotten. Yes, you have a reasonable rate, but that doesn’t mean you should run to refinance. Remember that the refinance process comes at a cost. There are plenty of fees involved, and sometimes the fees can make your refinance costs even more than you’d hoped for. “People should know that just because their new 50
l
interest rate may be lower than their current interest rate, it may not make sense,” says Roger Ma, a certified financial planner. “They need to consider how much longer they’ll be staying or keeping their current place, the upfront closing costs involved, and the ongoing interest savings.”
The Future is Uncertain, Hold off from Refinancing There are so many reasons that would push you to refinance, however, if you are planning to tap into your home equity, say maybe to consolidate your debt to pay for home improvements or other expenses, this is a risk you don’t want to take.
“We should be concerned about people refinancing too much equity out of their homes and not being able to afford the mortgage payment,” says Odest Riley Jr. of WLM Financial. “This is especially the case if the COVID-19 virus causes any type of economic downturn, which could tighten up a homeowner’s ability to keep up with their financial obligations.” I would urge you first to make that your new monthly payments will make sense if you opt to refinance. Also, keep in mind that the rates are not low for nothing. And given the uncertainty, nationally and internationally, I think it is worth playing safe for the time being. To learn more about purchasing decisions during this time of uncertainty, make sure to connect with David Trubey of Keller Williams Realty. Since 2001 David has lived and worked in the beautiful city of Corona, California. He went to High School there, and he arrived as the new construction in the area was nearing completion. He grew up originally in Los Angeles and lived in the City of Norwalk, CA, for 17 years. He knows his area well. To learn more about David, go to; https://thepowerisnow.com/ vipagentsservices/david-c-trubey/
David C. Trubey Realtor Keller William Realty Sources https://www.hsh.com/finance/refinance/refinancemistakes.html https://www.realtor.com/advice/finance/refinancingmistakes-homeowners-are-at-risk-of-making-today/ THE POWER IS NOW MAGAZINE | JUNE 2020
HELPING HOMEOWNERS AVOID LOAN MODIFICATION
SCAMS Ameer Elahee
A
fter the financial crisis of 2008, most of the homeowners in the United States were left in an impossible situation, and most of them lost their homes to foreclosures, simply because they couldn’t pay their mortgages.
In such a situation, what most homeowners try to do is to stave off the inevitable foreclosure through loan modifications, only to realize that their desperate acts led them to fall into a scam. Since the 2008 financial crisis, the housing market has improved dramatically. Right now, when I look at the housing markets and the trends in foreclosures in the last few months, I am so worried. It takes me back to the periods prior to the 2008-09 recession. The possibility of losing a home to foreclosure is a scary one. But the reality is, expert scam artists are devising their schemes, preying on the desperate homeowners. Many companies say that they will change your loan that will reduce your monthly mortgage payment, or even promise you that they can save your home. Some will tell you nearly all their customers were fully satisfied with their services. Others will tell you that they are affiliated with the government or your lender. Given the options, you definitely will choose these companies, Afterall, who would want to lose a roof over their heads? Unfortunately, the reality is that many of these companies will tell you half-truths and even lie to your face for them to sell their services to you. They will promise relief only for you to get distressed. The fact is, most of these companies will leave you in a bad financial situation than you were before. 52
l
Before we get into the ways NHPS is helping you stay safe, let us first examine what loan modification is. What is loan Modification
As a homeowner, when you fall behind with your mortgage payment, you have several options at your disposal to avoid losing your home. One of these options is a loan modification. A loan modification is a plan that will permanently restructure your mortgage by changing its terms. The terms may include reducing the interest rate and/or the monthly payment. A loan modification can also entail the conversion of the interest rate to one that is more financially feasible for the homeowner. For instance, modification may convert the rate from fixed to a variable rate. In some cases, the loan modification may even extend the length of the term of the loan. And it gets interesting. The first qualification to a loan modification is proof of financial hardship. The homeowner may be needed to provide proof of hardship and what better time than during the COVID-19 crisis. This is the time that so many Americans have lost their jobs, and raising a monthly payment may be hard.
THE POWER IS NOW MAGAZINE | JUNE 2020
Preying on the Vulnerable
Perhaps one of the most common scams entails a socalled agency. They will promise to help you obtain a loan modification for an upfront fee. This should be your first red flag as a homeowner can receive such counseling for free by contacting HUD. But they know their way, which explains why so many people fall for these low-lifes. As such, if you come across people who say they can help you as long as you pay them, run for the hills. These are people who just want to take your money and then runoff. Some of the things you should watch out include; if a person keeps on insisting that you do not contact anyone about the agreement, they are trying to reach with you, that should tell you something. Remember, these scammers can also be so egregious as to ask you to pay whatever mortgage payment they can muster up directly to them instead of the lender.
Take a look at the following message, given as an example of how these scammers will reach you in a message by FTC; “Stop foreclosure now!” “Get a loan modification!” “Over 90% of our customers get results.” “We have special relationships with banks that can speed up the approval process.” “100% Money Back Guarantee.” “Keep Your Home. We know your home is scheduled to be sold. No Problem!” NPHS Helping you to Avoid Loan Modification Scams If you’re struggling with your mortgage or trying to
WWW.THEPINMAGAZINE.COM
get your mortgage reduced, you can find help, free of charge, from NPHS. Loan-modification scams take many forms: Some mimic government foreclosureprevention programs, others guarantee to stop foreclosure for a significant fee, and still, others strip the homeowner of equity or of the home itself. NPHS is here to help. Give us a call at (909) 988-5979. If you get a message suspecting to be these scammers, contact us immediately and help us to stop these people. If you still don’t know the way forward, talk to one of the masterminds behind this program, Ameer Elahee, who also is a member of the VIP Agents, a program run by The Power Is Now Media. Find out more about the program here. Mr. Ameer Elahee is a very successful realtor, consultant, international speaker, and motivational life coach. One of Ameer’s true passion is real estate sales, first-time homebuyers, and homeownership education. Currently, Ameer is fulfilling his lifelong passion in real estate at Keller William’s, where he has achieved every milestone he could as a market leader in the organization where he is very involved. Talk to Ameer today and learn more about the Just how to stop these scammers from crushing your homeownership dream. To find out more about Ameer, go to https://thepowerisnow.com/ vipagentsservices/test/.
Ameer Elahee Real Estate Services Manager Neighborhood Partnership Housing Services, Inc. Sources https://nphsinc.org/2020/04/17/avoid-scams/ https://www.preventloanscams.org/avoid-loanmodification-scams/ https://www.consumer.ftc.gov/articles/0100mortgage-relief-scams
l
53
Are you se e k i n g for b e a r a nce on You r M ortg a ge? WATCH OUT FOR THESE RED FLAGS
Ruby Frazier
F
or distressed homeowners, forbearance is an option you’d like to try out. Forbearance is when your mortgage servicer or the lender allows you to pause or even reduce payments on your mortgage for a limited period. What you should keep in mind, however, is that forbearance does not erase what you owe on your mortgage. Any missed payments on your mortgage will have to be repaid in the future. As such, if you can make payments on your mortgage, you should continue making them. While most homeowners would welcome an opportunity for a break, there is a downside to mortgage forbearance. Unless you and your lender agree not to report the forbearance, any missed payments on your debts will be reported to the credit bureaus. However, mortgage forbearance is far less damaging to your credit score than a missed payment, and it will help you avoid foreclosure.
How does it work?
First, you have to contact your lender. Lender requirements of your qualification may vary, and the type of mortgage you have will also help determine what options you get. If you qualify for forbearance, your lender will then set up a forbearance agreement, and the terms may include; • •
The length of the forbearance period The amount of payment required during the
WWW.THEPINMAGAZINE.COM
• •
forbearance period Whether the lender will report the forbearance to credit bureaus How you’ll repay the lender after the forbearance period ends
Keep in mind that your loan will still accrue interest during the forbearance
When forbearance period lapses, you will have to pay your lender back in accordance to the forbearance agreement. There are several ways to go about a missed payment. For instance, with a reinstatement, you can repay with a lump sum. Additionally, you can have the missed payments rolled up to your monthly payments. Last but not least, you can have the missed payments to the end of the mortgage, which ultimately lengthens its terms. Supposing the forbearance period lapses, and still, your financial position and hardships persist, you can ask your lender for a mortgage loan modification. A loan modification will change the terms of your mortgage to help you manage your mortgage repayment.
IF YOU ARE LOOKING FOR A FORBEARANCE, WATCH OUT FOR THESE RED FLAGS. l
55
Remember, you have to pay your mortgage No matter how long the period lasts, you should always keep in mind that forbearance is not forgiveness. “Forbearance is not forgiveness,” said Karan Kaul, a research associate at the Urban Institute, a left-ofcenter nonprofit policy group. “You still owe the money that you were paying; it’s just that there’s a temporary pause on making your monthly payments.” For the homeowners with federally-backed mortgages, you are eligible for up to 180 days initially under the CARES Act. At that point, if you are still experiencing financial hardships, you can request an extension of up to another 180days of forbearance. The good news is that the stimulus package stipulates that during the forbearance, the mortgage servicers cannot make any negative reports about the borrower to the credit bureaus. Additionally, borrowers also will not owe any late fees or penalties if they are granted forbearance. First, understand who your mortgage servicer is Just because your struggling doesn’t mean that your servicer will be too understanding; as such, to get a forbearance, you need to request it from your servicer. Mortgage servicers are the companies that are receiving your monthly payments. You need to understand that your lender may be very different from your servicer; therefore, do your homework. Most lenders sell their servicing rights for mortgages to other companies. If you do not want to lose eventually, as a first step, figure out who your servicer is and understand how they operate. To find out who your servicer is, check your mortgage statement, and if you can’t find their information there, look it up by searching the Mortgage Electronic Registration Systems Website.
Your agreement should be in writing
“Once you’re able to secure forbearance or another mortgage relief option, ask your servicer to provide written documentation that confirms the details of your agreement and that you’re clear on what the terms are,” CFPB said on its website. I cannot stress enough the importance of having such a deal in writing. This will protect you should there be any errors in your mortgage statement or your credit report.
Be cautious of a balloon payment
After you have successfully secured your deal in writing from your servicer, the next step is to know your repayment options.
56
l
“You don’t want a surprise like finding out that six months of deferred loan payments are all due immediately upon the end of the forbearance,” Sharga said. “Most people simply won’t have six months’ worth of mortgage payments available.” Some of the options have been discussed in this article. However, some borrowers have expressed concerns after being offered a balloon payment option. With balloon payment, what that means is that the borrower will be required to pay back the entire amount owed for the forbearance period all at once. While this is one of the options, and the lender may offer it, a borrower is no under obligation to pay in that way. The homeowners should aim to negotiate the best possible repayment they are comfortable with. “All those terms are negotiable,” Sharga said. “Be diligent, be steadfast, and try and stand your ground.” I would urge you to continue making your payments if you can. And while it may give you a break, you will still have to pay the loan amount and the interest accrued. If you want guidance on how to go about the forbearance process, especially for homeowners in Riverside, talk to Ruby Frazier. Ruby is one of the most talented realtors in Riverside, and she is part of the VIP Agents program. A program run and powered by the Power Is Now Media. Find out more about VIP Agents program here.
R
uby is the President and CEO of Frazier Group Realty Inc., a full-service real estate company with a dynamic team. The company’s approach is tailored to each of our clients. Frazier Group Realty is located in the heart of Downtown Riverside, California, servicing the Inland Empire, Orange, and Los Angeles counties. Focusing on residential and commercial real estate as well as property management. Ruby’s objective is to assist buyers and sellers reach their real estate goals. To find out more about ruby, follow this link; https://thepowerisnow.com/vipagentsservices/ ruby-frazier/.
Ruby Frazier President & CEO Frazier Group Realty Sources https://www.consumerfinance.gov/coronavirus/cares-actmortgage-forbearance-what-you-need-know/ https://www.consumerfinance.gov/about-us/blog/guidecoronavirus-mortgage-relief-options/ https://www.marketwatch.com/story/are-you-a-homeownerseeking-forbearance-on-your-mortgage-watch-out-forthese-red-flags-2020-04-10 https://www.nerdwallet.com/blog/mortgages/mortgageforbearance/
THE POWER IS NOW MAGAZINE | JUNE 2020
NAREB is on a campaign trail to ensure that in the next five years, there will be an additional of at least two million new Black homeowners. This program is dubbed as the 2MN5 and isNAREB’s solution in response to the declining African American Homeownership rates. The program has short and long-term core objectives that purposes to eliminate the racial gap and the disparities in homeownership in the country. Currently, the homeownership rate for African Americans is 44%, and the rate for the Non-Hispanic whites is 73.7.
Donnell T. Williams About Donnell T Williams and the Two Million New Black Homeowners Program
7-POINT Activities To SupportNAREB’s Mission
58
l
The following are a set of activities that will support NAREB’s motto of Democracy in Housing: 1. Promoting, sponsoring, and encouraging African Americans to take part in housing and homeownership programs both in the public and private sectors. 2. Active advertising and marketing to the African American consumer on the financial and other benefits of homeownership. 3. Activism for access to
THE POWER IS NOW MAGAZINE | JUNE 2020
4.
5.
6.
7.
the credit and reform and the changing of the regulatory policies and the laws that will support an increased black homeownership rate. Activism at the community level where action-based outreach raises awareness and educates communities across the country of the importance and the crucial role of homeownership in plugging the gap between the whites and African Americans in the country. Advocacy and training in leadership development for the NAREB local leaders and other community and neighborhood stakeholders. Business development training and technical assistance for African Americans through NAREB’s share of the wealth series and NAREB university. Neighborhood and Community Development Projects that foster homeownership;
A Challenge NAREB Is Ready For
This is no easy challenge, and NAREB is fully aware of this fact. Eliminating a 30% gap in homeownership at a time when the sector is facing numerous challenges will not be easy. As such, it will take not only dedication but also organization discipline, advocacy, focus, and partnerships with faith, business, foundation, and the public sectors. This is a program that NAREB looks to implement both at the local and national levels with its staff, consultants, members, affiliates, faith-based institutions, community and neighborhood organizations, and public and sector institutions.
Measuring the Impact of The Program
NAREB will measure the progress and the impact of the program through the following criteria; • Increasing the homeownership rate in the communities of color over a time span of five years. • Increasing the size and scope of black businesses in the real estate industry. • Strengthening the foundation of black WWW.THEPINMAGAZINE.COM
wealth through real estate acquisitions. • Raising the awareness of the critical role that homeownership plays in wealth creation in the communities of color. • Transforming targeted neighborhoods in selected cities. • Advocacy at the national, state, and local legislative and regulatory reforms to promote democracy in housing that will help increase African American homeownership rates. This plan by NAREB is one of the most brilliant nationwide outreach programs. More homeowners will be added, and thus, the black wealth will begin to grow exponentially. This is not the only program that NAREB has embarked on, the organization is also doing the House Then A Car campaign that targets millennials. All these changes started happening when Donnell T. Williams was made the president of NAREB.
Who Is Donnell?
Donnell T. Williams is a record broker and the owner of a prestigious real estate firm, Destiny Realty, which is headquartered in Morristown, New Jersey. He serves as the current president of the National Association of Real Estate Broker, NAREB.
D
Donnell has been actively involved in trade associations, especially with NAREB’s efforts to promote a meaningful exchange of ideas about real estate business and how to serve its clientele best. Destiny Realty, which he leads, is one of the largest African American independently owned real estate brokerage firms in the state of New Jersey. His Leadership and Membership positions Mr. Williams has held several leadership positions, which has positioned him as the president of NAREB, where he encourages professional development and increased
l
59
industry knowledge. He has also worked to create an environment that fostered creativity in the workplace as a goal for the NAREB members.
Donnell Williams
Apart from his professional commitment to NAREB, Mr. Williams also holds membership in the North Central Jersey Association of Realtors and the New Jersey Association of Realtors. He is a member of the Board of Adjustment for Morris (N.J.) Township, and a member of the United States Developers Council.
In addition, Mr. Williams is a licensed realtor since 1992 and a licensed broker since 2001, he earned membership in the New Jersey Million Dollar Club (1995-2000). He also holds certification as a residential manager and housing counselor. Currently, he serves as a chairman of the Board of the New Jersey Association of Minority Real Estate Professionals.
Community involvement
As a resident of Morris Township, Donnell’s community and civic involvements include active membership as a Deputy Grand Master of the Most worshipful Oriental Grand Lodge, a Member of Morris Community Minority Concerns Advisory Committee and an NAACP Silver Level Lifetime member.
An Agenda for the Millennials
After his inauguration as the 31st NAREB president on August 1st in his speech, Donnell set a bold yet targeted an agenda to increase Black Wealth through homeownership with a special focus on reaching the country’s millennials. The 72nd Annual NAREB convention happened just a few days after the U.S Census Bureau released its 2nd quarter 2019 homeownership rates, which listed Black Homeownership rate at 40.6%, the lowest in more than 50 years. Which in comparison to the non-Hispanic whites, there was a 30 percent gap.
60
l
”Bold, energetic, and effective action must be taken to stop this unthinkable slippage in Black wealth. Homeownership and investment in real estate represent the tools Black Americans, in general, and millennials, in particular, can use to build or rebuild their wealth. My plan to reverse the downward slide is to reach the 1.7 million mortgage-ready Black millennials who make over $100,000 annually, but have delayed or not considered homeownership as part of their wealthbuilding strategy,” Williams stated. He also stated several initiatives that speak directly to the millennial demographics. In the spotlight, one program that drew a lot of applause from the audience when he said, ”Our people need to know that you are in violation if you drive a Land Rover and you pay rent to a landlord.” This is an initiative dubbed House Then a Car is set to launch shortly, and it concentrates its financial focus on attracting millennials and Gen-X-ers to home buying or investment in real estate investment opportunities to build sustainable wealth.
Donnell emphasizes that NAREB members Realtists have to embolden themselves as well as their potential customers. He noted, ”We must Educate, Empower, and Mobilize ourselves as well as the Black American public. Wealth building through homeownership is indeed possible, and we need to make that happen.” Sources; http://housethenthecar.com/ http://www.nareb.com/2mn5/ http://www.nareb.com/profile/dwilliams/
THE POWER IS NOW MAGAZINE | JUNE 2020
The BEST and Possibly WORST Places
for Renters to Hunker Down During the Coronavirus Pandemic in Irvine
Cornelius L. Jackson BACKGROUND Irvine is relatively a large coastal area situated in the state of California. Irvine, according to the 2018 Census Bureau Report has a population of 282,572 and 33 constituent neighbourhoods. It is the largest community in California. It is the safest city in America by the FBI for the past nine years. Irvine home prices are not only among the highest but also has consistently ranked among the most expensive in America.
Mostly, Irvine is a white-collar city with fully 93.67% of the workplace employed in white-collar jobs. This is well above the national average. Irvine is a city if professional, managers, and sales and office workers. There are so many people living in Irvine who work in the management occupations (15.62%), sales jobs (11.52%), and business and financial occupations (10.93%).
O
f importance to note is that Irvine is a city of artists. It has more artists, designers and people working in the media industry than 90% of the communities in America. Altogether, the concentration of artists in Irvine has helped shape Irvine’s character. Telecommuters make up a large percentage of the workforce in Irvine. 7.71% of the people in Irvine work from home. It may seem like a relatively small percentage, but as a fraction of the total workforce in America, it is a large population. These telecommuters are often people who work in the knowledgebased, white-collar professions. For instance, Silicon Valley has the highest number of telecommuters. Other people working from home are often self-employed.
62
l
THE POWER IS NOW MAGAZINE | JUNE 2020
LOW COST OF LIVING Irvine is one of the most affordable cities in California let’s break this down;
• Rent: the average cost of an a1-bedroom apartment in Irvine is around$1,690 and for a 2-bedroom apartment is $2,080. These prices make Irvine and Santa Ana area the 12th priciest place to live in the United States. • Transportation: for the monthly transit passes, that will cost you roughly $75 on average. • Food costs: for the residents in the Greater LA area, they usually spend 12.4% of their household budget on food. • Taxes: sales tax in Irvine is 6.5%.
BEST NEIGHBOURHOODS IN IRVINE CITY 1. Balboa Peninsula, 833 vacation rentals. 2. Anaheim Resort, 409 vacation rentals. 3. Balboa Island, 279 vacation rentals. 4. Monarch Beach, 173 vacation rentals. 5. Hermosa Village, 164 vacation rentals. 6. Corona del Mar, 535 vacation rentals. 7. Capistrano Beach, 416 vacation rentals. 8. Newport Coast, 515 vacation rentals. 9. Belmont Shore, 127 vacation rentals. 10. Lantern Village, 127 vacation rentals. 11. Southeast Anaheim, 197 vacation rentals. 12. Sunset Beach, 1,001 vacation rentals. 13. West Newport, 836 vacation rentals. 14. Old Towne, 30 vacation rentals. 15. Woods Cove, 110 vacation rentals. 16. Westside Costa Mesa, 48 vacation rentals. 17. Anaheim Colony Historic District, 244 vacation rentals. 18. Belmont Heights, 119 vacation rentals. 19. Valle Lindo, 21 vacation rentals. 20. Riverview West, 19 vacation rentals.
WWW.THEPINMAGAZINE.COM
Irvine is one of the best places to live in California. To get a tour of the area, contact Cornelius L Jackson today. To learn more about the program and how it is helping realtors, click here. As a highly successful realtor, broker, credit repair expert and former law enforcement officer, Cornelius Jackson uses his wealth of skills and experience to run his company, CLJ Realty Group. Cornelius considers himself a true “marketing broker” because he does not just list a property and forget about it – he expertly markets the listing to get the best sale possible. Cornelius has worked in real estate for fourteen years and started his company, CLJ Realty Group in Orange County, California, just over four years ago. To learn more about Cornelius, click here. As such, in a market that can quite confuse you, you need a person to help you navigate it cleverly, and that person is Cornelius. With more than 14 years in the industry, you can be sure to get valuable help and resources from Cornelius.
Cornelius L Jackson President & CEO CLJ Realty Sources: https://www.neighborhoodscout.com/ca/irvine https://www.firstteam.com/top-10-best-orangecounty-suburbs-to-live-in/
l
63
THE NEW REALITY OF THE HOUSING MARKET IN THE BAY AREA
C
Lewis Sanders III
oronavirus Stimulus Checks Do Less for the Bay Area Renters and Homeowners With the stimulus care package, checks have begun landing in the bank accounts. However, soon, the Bay Area residents will come to realize that this money will cover less for their housing costs than anywhere in the country. While there are some states and counties that stand to benefit more, only 8% of the homeowners in San Francisco will be able to cover their monthly mortgage payment with the amount they get from the CARES package. According to a new analysis by Redfin, 9 in 10 Bay Area homeowners will have less than half their monthly mortgage and utilities paid by the $1,200 stimulus check. Remember, this is the smallest relief for any region in the country, and even for a twoincome family receiving $2,400 in aid would come up short of paying the Bay Area mortgages and utilities. The amount that Americans will receive from the stimulus check will depend on their income. The higher-earning Americans will receive a smaller amount and, in some cases, nothing in the stimulus. The households with children will receive $500 more funds per child. Redfin also found that over three-quarters of the renters in the large metros could cover a month of their housing expenses with a $1,200 check. Comparatively, with the same amount, Redfin found that slightly less than half of all the homeowners nationwide will be able to cover a month’s mortgage payment. Renters in Bay Area Are Likely to Suffer More While the stimulus check is likely to do more for renters in most parts of the country, renters in the Bay Area are likely to see relatively less relief than anywhere else in the country. Just 1 in 5 renters in San Jose and 1 in 3 in San Francisco and the East Bay would see the ma jority of their housing costs paid with the $1,200 check. WWW.THEPINMAGAZINE.COM
“That’s not going to help too much,” said Redfin senior economist Schery Bokhari. In some cities, with a $1,200 check, the money can go quite far. In about 12 cities all across the country, more than 90% of the renters would be able to cover at lease all of the costs associated with housing. Buffalo, N.Y leads, as 94% of the city’s renters could cover their rent at $1,200. The median rent in Buffalo is $809. Even with the Coronavirus pandemic, Bay Area housing costs remain relatively high. The median sales price for a single-family home in seven Bay Area counties in February was $888,100, according to Zillow. And despite the falling housing inventory and the shelter-in-place orders, the demand has kept on rising.
“Inventory is extremely low,” said San Mateo County agent Wilson Leung. “People are still motivated to buy.” According to Zumper, In April, the median rent for a two-bedroom apartment in a place like Oakland was $2,990 in San Jose- $3,030 and $4,540 in San Francisco. Most of the cities and counties where the renters and homeowners are well off are located in the Midwest and South. These areas have lower housing costs and tend to be the cheapest. Nonetheless, other factors could help alleviate the situation for the residents struggling to meet their mortgages and rents. For instance, the out-of-work Californians have received an extra $600 weekly supplement to unemployment payments, helping to bridge gaps in lost incomes. The Situation Might Get Worse before Getting Better Things look much worse in the San Jose and San Francisco metros. Redfin ranked the two in 50th and 49th, respectively, among the 50 largest metros it l
65
UPCOMING EVENTS UPCOMING UPCOMING EVENTS EVENTS studied. The median monthly mortgage payment for a place like San Francisco and East Bay was $3,100, while the median in San Jose was $3,370. Additionally, the pandemic has not eased the tension therein between the supply and demand forces in the housing market. Both the buyers and sellers are pulling back in equal measures, which has left the prices in the area intact. During the first week of April, the demand for customers taking their first home tour dropped 26 percent Y-o-Y, and at the same time, the housing listings on Redfin website also dropped 44 percent from the previous year. If you are looking for market insights about the Bay Area, talk to Lewis Sanders. He is an industry expert operating in the Bay Area. Lewis is part of the Power Is Now VIP Agents program. Find out more about the program here. Lewis is a licensed real estate expert for many years. He started working in the communications business learning to establish himself with the public and local communities by serving as a barbershop business owner in the Bay Area. There he discovered his hidden talent and skills through helping my clients as he entered the mortgage industry, which led to his career as a licensed real estate agent. To find out more about the Bay Area, contact Lewis. If you would like to purchase a property in the Bay Area, Lewis has the best houses at a very affordable rate. The good news is that you do not have to worry about down payments, Lewis will show you an easy way to get into a home with zero money down. Find out more about Lewis and his work here.
Lewis Sanders III President & CEO Sanders Realty Group Sources https://www.redfin.com/blog/governmentcoronavirus-stimulus-package-impact-onhomeowners-renters/ https://www.mercurynews.com/2020/04/16/ coronavirus-stimulus-checks-do-less-for-bayarea-renters-homeowners/ https://www.marketwatch.com/story/these-arethe-cities-where-stimulus-checks-will-helphomeowners-and-renters-the-most-2020-04-17
THE POWER IS NOW EVENTS: FIRST TIME HOMEBUYER SEMINARS FIRST TIME HOMEBUYER SEMINARS LIVE ON FACEBOOK
NATIONAL EVENTS: NAREB
HOMEOWNERSHIP WEEKEND June 20th – June 21th, 2020 NAREB 73RD ANNUAL CONVENTION – DETROIT August 9th – Aug 16th, 2020 DETROIT MARRIOTT at the Renaissance Center 400 Renaissance Dr W, Detroit, MI 48243
NAHREP
SNEAK PEEK! WHAT TO EXPECT IN THE FOURTH CORONAVIRUS STIMULUS PACKAGE – POWERED BY QUICKEN LOANS June 3, 2020 NAHREP AT L’ATTITUDE GRAND HYATT SAN DIEGO, CA September 24–27, 2020
AREAA
NORTHEAST REGIONAL RETREAT June 11, 2020 SOUTHWEST REGIONAL RETREAT June 26, 2020 NORTHWEST REGIONAL RETREAT July 16, 2020
REOMAC
ECONOMIC OUTLOOK: COVID-19 AND THE STATE OF THE REAL ESTATE MARKET June 2, 2020 REOMAC 2020 ANNUAL SUMMIT & EXPO Sunday, July 19 - Tuesday, July 21, 2020 Gaylord Rockies Resort and Convention Center
CAR and NAR
REALTORS® CONFERENCE & EXPO Nov 13-16 New Orleans, LA
YES, CORONAVIRUS SLOWED REAL ESTATE ACTIVITIES
BUT IT WON’T STOP THE BAY AREA REAL ESTATE, AGENTS
Kenneth Session
This year would probably have been the best year for the real estate industry, but even now, when it comes to the Bay Area real estate market, things are heating up more than it was expected at the start of the year. But one thing is sure, the novel Coronavirus is behind the recent surges in home buying. The bidding wars are back, fiercer than ever in many neighborhoods across the East Bay as the buyers get in the market. One of the
“That means U.S. companies don’t have products to sell, which means it’s going to slow economic activity, and investors will seek bonds and bonds drive mortgage rates so mortgage rates will fall or stay the same. “ Corona Spurred A Buyer Frenzy
In a way, the Coronavirus has brought more demand, creating a buyer frenzy. Buyers feel energized right now, mainly
68
l
reasons for pulling buyers in the market is low-interest rates, which could be sustained all through summer because of the virus. The economic activities have been slowed globally, and while that hurts the economy of a country, it may be good news for the real estate buyers. Right now, millions of Chinese workers have been quarantined; the products they produce won’t be shipped as Ben Bauer, a mortgage banker with Delta Lending Group, explains.
because of the low-interest rates and mortgage rates. As 2019 closed, the demand was very low, but right now, there are more buyers, and they are motivated. The government lockdown on real estate sales was loosened last month, and the agents and other professionals are now deemed as essential workers, even a good percentage are the realtors who had continued their home shows during the shelter-in-place restrictions. Nonetheless, some new Bay Area guidelines still ban open houses and close contact. Right now, Bay Area agents, inspectors, and homebuyers are
just waiting for a green light to take the opportunities passing them by aggressively. And even though the restrictions were loosened, strict caveats have to be adhered to; no flyers, appointments only, no more than two family members in a house. Once you are inside the house, strict social distancing mandates apply, and the home must be unoccupied by the seller. “Virtual showings are highly encouraged,” advised public health officials in Santa Clara and San Mateo counties. We all know what a world real estate industry is. It is touchy, and
THE POWER IS NOW MAGAZINE | JUNE 2020
its messy people want to see and feel what they are committing to, and as such, pictures and videos can only do so much as inciting a buyer’s imagination, hearts and checkbooks. Agents are forced to work twice as hard, driving back into the neighborhoods with gloves, masks, and as many hand sanitizers as they can get.
The Industry is too Large to go unnoticed
The California real estate industry (residential & commercial) is worth $445 billion and has been a vital fuel in the state’s economy. The relatively high home prices in the Bay Area have made multibillionaires out of long-time homeowners and the long-time renters out of the would-be owners. Bay Area’s housing market began to rebound in the first two months of the year, followed by some substantial gains in the median home prices and a strong buyer demand after months of flattening prices in 2019. Following the Coronavirus, lockdowns were imposed, turning the stock market into turmoil and creating a state of uncertainty, which ultimately slowed the Bay Area Listings and sales. Fast forward to March and April, real estate activities and transactions tumbled relative to the same period in 2019. Buyers and sellers alike backed out of more deals, as shown in the MLSListing data from the counties of San Mateo, Santa Clara, Santa Cruz, San Benito, and Monterey. What we do not know right now is the restriction on people who want to move. Of importance to note also is that the number of home sales in escrow that fell through increased by 50 percent from the same time last year. Additionally, sellers
WWW.THEPINMAGAZINE.COM
panicked, and twice as many sellers removed their properties from the market in the past two months compared with 2019. And as expected, the number of home sales fell 9 percent, according to MLS Listing. Despite the invisible killer virus, the shelter-in-place guidelines were loosely enforced, and largely self-regulating were ignored by some agents. Some agents continued to advertised their sales and broker tours until the MLSListings disabled this feature in March. But the pressure is real; most agents want to hit their sales targets, satisfy their clients, and score deals.
Ignorance or Zeal?
A frenzy of buyers, little inventory on the market means that the bidding wars are back. And it is happening everywhere. Real estate agent Vicky Bearman said in “Walnut Creek, Lamorinda, Alamo, Danville, and San Ramon; there’s just not enough inventory for the demand.” “if interest rates stay low and inventory stays low, it will probably be a feeding frenzy again.” Tina Hand, president of the Bay East Association of Realtors, said. With such a situation, you find buyers pushing the realtors to open houses “When it comes down to it, it’s the client’s decision,” he said. “If they have a pressing need, you have to respect that.” Some agents are much more careful, and before the loosening of the shelter-in-place orders, they had to turn down several clients. A decision that some regret because these clients go-ahead to find other agents who are willing to show them the house. So, you
have to wonder, is it determination or just mere ignorance?
“Some agents have been following the rules,” Realtor Alan Wang said. “Some have not.” The California Association of realtors was perhaps one of the very first realtor association group to urge its members to follow and adhere to the local rules; however, most agents remain confused about the direction to take because some parts of the real estate like lenders, escrow agents and some county clerks offices remained open during the shelterin-place while other was closed. To understand more about what’s happening on the Bay Area Housing market, and whether it is safe for you to buy or sell or see an open house, contact one of our VIP Agents in the Bay Area. If you are dying to buy your primary residence today, make sure that you know what is going on in the market right now. Talk to Kenneth Session, a real estate guru with the Session Real Estate today to find out more about the Oakland and Bay Area housing market. Mr. Session is also part of the VIP Agents program powered by The Power Is Now Media. To learn more about the program, and Kenny click here.
Kenneth Session President & CEO Session Real Estate Sources https://www.mercurynews. com/2020/04/06/coronavirusslows-but-doesnt-stop-bay-areareal-estate-agents/ https://www.bdcnetwork.com/ covid-19-and-real-estate-howcoronavirus-impacting-aecindustry
l
69
USE THESE 5 TIPS TO HELP ACE YOUR
RENTAL APPLICATION Don Dunbar
I
n the world of real estate, almost everything is competitive. The rental market is one of the most competitive markets in real estate, and therefore, you need to show that you have all that it takes to make the perfect candidate, you want your application to be approved. I have been a real estate agent for more than ten years, and I have prepared these five tips to help your rental application go through. When it comes to the rental application process, the first and perhaps most crucial step is to decide settling into a new home
Be organized One of the best ways to impress your landlord and to also ensure that the application process goes smoothly is the be as organized as possible. Beforehand, find out the documents that are required to complete your application. For a standard rental application, the main documents that you are required to have will usually include the last two years of your tax returns, a copy of your credit report, proof
72
l
finally. It means you are going for something you want, getting out of your comfort zone, and taking an initiative to change. However, the rental application process is not all that merry, and application rejection can happen. Rental application rejection can happen for several reasons. It could be as a result of your credit history or even lack of references, or perhaps like most of the first-time renters, you lack experience in rental applications. Whatever the reason, consider the following tips before submitting your next apartment application.
of employment, a copy of your bank statement, and a letter from your previous landlord. Nonetheless, these requirements will vary from state to state, and therefore it is essential first to find out all the documents you are required to have. Go above and beyond- it shows you are serious Landlords are comfortable with tenants who will pay them their rent on time and have a reliable source of income; however, not many will give them more than their basic
expectations. You have to be the exception. If a landlord asks you for a one-year lease, go above and beyond, and consider signing for a year and a half even two years. This will show the landlord that you are very serious about the apartment and plan on staying there for a while if they choose you. If you can pay a few months of rent upfront, do that too. Most landlords appreciate when they do not have to worry about collecting rent from their tenants. That, combined
THE POWER IS NOW MAGAZINE | JUNE 2020
required, you may want to think about attaching that letter or a reference to the application as another way to improve your chances of approval. This will give you a good ground and a base of competition from your competitors.
with the promise of staying in their apartment for more than a year, the landlord will be much more inclined to offering you the apartment.
Communication is key
Throughout the rental application process, you should always try to keep the conversation live with your potential landlord. Additionally, you should also keep in touch with your real estate agent. If you need extra time to do something with regards to the application, let them know. Your real estate agent and your landlord will be inclined to give a tenant who is in close communication with them the offer to their apartment.
Be honest in your application
Most people tend to be dishonest in their application, especially when it comes to their history. Telling the truth is a wise decision. For instance, if your credit is in bad shape, or if you left the other apartment in bad terms, come clean and explain the circumstances. There is a good chance that your apartment manager or landlord has seen it all. It won’t do you good to lie. If you are having trouble in your application, it may be best to seek out the counsel of your real estate agent. Therefore, to help streamline the process, always keep your agent in close communication.
Show that you are an agreeable renter
Usually, landlords will want to see from the previous landlord what kind of a renter you are. Did you abide by the pet policies? Were you stubborn? All these questions will be answered in a letter from your former landlord. And while it is not typically
WWW.THEPINMAGAZINE.COM
If you’re looking to buy, sell or rent, talk to Dunbar Real Estate Group. This company based in Oakland and has connections not just in California but across the country. Don will personally prescreen and accompany qualified prospects through your property. In as much as professionalism is essential in real estate when you come to Dunbar Real Estate Group, you not only get a trustworthy realtor but friends too. To learn more about Dunbar Real Estate, go to; https://thepowerisnow. com/vipagentsservices/dondunbar/
Don Dunbar President & CEO Dunbar Real Estate Group Sources https://www.realtor.com/ advice/guide/rentalapplication-tips/ https://www.rentcafe.com/ blog/apartmentliving/tipstricks-renters/know-rentalapplication-process/ https://www.zumper.com/ blog/how-to-ensure-that-alandlord-chooses-you/
l
73
Robert Langston
CONSIDER THESE 4 THINGS BEFORE GETTING AN FHA LOAN
F
inding the right type of loan to finance your homeownership dream can be stressful, especially for firsttime homebuyers. There are many things that you need to be aware of to make it through the buying process and finally becoming a homeowner. One thing you will often cross paths with is the Federal Housing Administration loan.
FHA loans are perhaps one of the most straightforward loans to secure as they have a low-down-payment, which makes it easy for people to access, especially people with a lowdown payment. Apart from a low-down payment, FHA loans have tons of other features for potential homebuyers like being assumable, which means that they can be transferred to another buyer who will take up the loan. However, there are some other things that you have to be aware of when taking an FHA loan. In this article, we are going to dive deeper into some of these things.
MORTGAGE INSURANCE
Did you know that for the life of the loan, you will be subjected to mortgage insurance? When a buyer is not paying a 20% down payment, mortgage insurance will apply. The buyer has to pay monthly mortgage insurance, which is meant to protect lenders in case of default on loan. Mortgage insurance basically is the price that you have to pay for landing a mortgage with lenient qualifications. Not all homes can be bought using FHA loans To get approved for an FHA loan, the house you are considering buying has to pass an inspection conducted by the U.S. Department of Housing and Urban Development. A HUD appraiser will determine the market value of the home and whether the house is safe for you to stay.
WWW.THEPINMAGAZINE.COM
l
75
“Many people don’t know that the guidelines can be pretty strict for an FHA loan,” says Paolo Matita, a former real estate agent who says the inspection was an issue for his FHA loan–holding clients. “The roof, A.C. unit, plumbing, and electrical all need to be fully functional and be able to last for several years if they’re going to pass inspection.” Additionally, if the house will require a few modifications before being sold, they have to be done first, which presents another hurdle for the buyer since they are responsible for the repairs.
IT’S POSSIBLE YOU MIGHT NOT BE ABLE TO USE FHA LOAN FOR RENOVATIONS
will find that there are tons of considerations that have to be made for you to be eligible for an FHA loan, and one of them is the amount of debt that you can carry. As such, it is advisable that you check the current guidelines to make sure that the debt you have is manageable. If you would like to find out more about the FHA loan program, connect today with Robert Langston. One of the VIP agents with the Power Is Now Media representing the beautiful county of Sacramento. To learn more about the program, go to https:// thepowerisnow.com/vipagentsservices/, where you can also find the agent near you.
This is another hurdle for the buyers. With FHA 203(k) loan, you can dedicate up to $35K for home improvement and renovations. The lenders will stipulate the kind of repairs allowable, but the 203(k) loan can be the solution you are looking for. Therefore, before taking out any FHA loan, do your research and find out whether the loan you want will be all-inclusive of your needs.
With a strong desire to help buyers and sellers in all types of situations, Robert E. Langston lends his expertise as a real estate broker in and around the surrounding areas of Fairfield and Sacramento, California. For the best results, you want to work with an agent who understands his market well, and Bobby is your agent. Learn more about Bobby and how he can help you buy your dream home here.
You are still required to have a decent credit People assume that getting an FHA loan is a free pass. However, buyers still need to have a 580-credit score to take advantage of the 3.5% down payment option. The lenders in their part have to stake and will often demand a credit score of 600 or even higher for you to qualify for this loan. In addition, you
Robert Langston
76
l
President & CEO Bobby Real Estate Sources: https://www.realtor.com/advice/finance/fha-loanwhat-i-wish-known/ https://www.fha.com/fha_requirements_checklist
THE POWER IS NOW MAGAZINE | JUNE 2020
SECURED AND UNSECURE
s n a o L
Charles Reynolds
What’s the difference?
W
hen looking to borrow money from a bank or even an individual, you are taking a loan. The lender may allow you to take out that loan with the promise that you
will pay it back, in other circumstances, the lender may ask you to put or attach an asset as the security of the loan. This simple distinction is the main difference between secured and unsecured loans.
WHAT ARE SECURED LOANS
back the repayment terms.
Secured loans or debts are the debts that the borrower has to put up some asset as collateral for the loan. A secured debt instrument simply means that in the event of default, the lender will use the asset to repay the funds it has advanced to you (borrower).
In most cases, the lenders will maintain the equity in the property in question until the mortgage is paid in full. Where the borrower is unable to pay for the loan, the lender seizes the property and sells it to recoup the funds owed.
Some of the most common types of secured loans include but not limited to; mortgage and auto loans, where the items being financed become the collateral for the financing. In the case of a car, if the borrower is unable to pay the loan on time, the lender will eventually repossess the car. If a person takes out a mortgage, the property in question is used to WWW.THEPINMAGAZINE.COM
COUNTERPARTY RISK Counterparty risk is a term that you will find mostly used in association with the secured loans. It basically refers to the risk of default on secured debt to the lender. In a secured loan set up, the counterparty risk tends to be relatively lower as the borrower stands to lose more in the event that he neglects his financial obligations. l
79
The secured loans channel is relatively easy to obtain compared to other types of loans. Since the secured loans carry less risk to the lender, the interest rates are usually lower than those of the unsecured debts.
lender. If you have a poor credit history, or if you are rebuilding your credit, lenders will more likely advise you to go for a secured loan as opposed to an unsecured loan.
Even though the lender might end up taking possession of the property for the defaulted secured loans, it is still possible to end up owing money on the loan if you default. When a lender repossesses the property, they will sell it and use the proceeds of the loan to pay off the balance. If the property doesn’t cover the loan, you will be responsible for paying the difference.
interest rate. This means that secured loans are generally smarter money management vs. unsecured loans. Lastly, secured loans will tend to offer the borrower with higher borrowing limits, which enables the borrower to gain access to more money.
WHAT ARE UNSECURED LOANS
An unsecured loan is not tied to any of your assets. This means that lenders cannot automatically seize your property in case of default as payment for the loan. Personal loans and student loans are some of the common examples of the unsecured loans as they are not tied to any asset that the lender can take if the borrower defaults on a loan payment. For you to get an unsecured loan, you need to have good credit history and a stable income for you to be approved for an unsecured loan. The loan amounts may be smaller since the lender doesn’t have any collateral that they can use to repay the loan amount.
HOW ARE THESE LOANS REPORTED?
You should understand that the lenders do report the payment history of both the secured and unsecured loans to the credit bureaus. Therefore, you should be very careful as late payments and defaults with both the types of loans can be listed on your credit report. With the secured loans, the lenders may use foreclosure to take hold of the asset tied to your loan. This will result in a negative entry being added to your credit report.
SECURED LOANS VS. UNSECURED LOANS
Several factors will determine the type of decision you will make regarding whether to take out a secured loan or unsecured loan. What you will find out is that secured loans are easily accessed as they carry less risk to the 80
l
SECURED LOANS WILL TEND TO HAVE A LOWER
By now, I know you have grasped the meaning of secured and unsecured loans. If you would like help securing any of these loans, get in touch with Charles Reynolds. Charles is an expert in all things real estate. If you are looking to buy or sell, Charles is your guy. He knows first-hand the overwhelming and stress of selling and buying a home. For the past 19 years, he has help clients understand the process of buying and selling a home, also has help clients understand the process of obtaining a mortgage for purchase or refinancing in the areas of Northern California, Solano County, Vacaville, Fairfield, and Vallejo. To learn more about Charles, click here. Charles is also part of the VIP Agents program. This is a program powered and run by the Power Is Now Media. To learn more about the program, click here.
Charles Reynolds Realtor Century 21 M&M
Sources; https://www.consumercredit.com/secured-loanvs-unsecured-loan https://www.investopedia.com/ask/ answers/110614/what-difference-betweensecured-and-unsecured-debts.asp https://www.thebalance.com/how-securedloans-are-different-from-unsecuredloans-960032 THE POWER IS NOW MAGAZINE | JUNE 2020
BAY AREA HOME PRICES JUMPED IN MARCH MOSTLY BEFORE THE LOCKDOWN EMERGENCY
I
n a normal situation, when the demand for a commodity drops, anyone would expect that the prices would drop as well in order to attract potential clients who maybe were scared by the prices earlier. In the Bay Area, that is not the case when it came to home prices. According to the California Association of Realtors. Bay Area home prices increased substantially in March despite a decline in sales as compared to the same time last year. This was happening before the effects of the coronavirus pandemic came knocking on the doors of the US, forcing leading to a lockdown to control the spread of the virus.
Eric Hooks
The housing market changed drastically since Covid-19 was reported in the US forcing businesses to remain temporarily closed and people to stay in their premises. Data from various real estate dealers for the period when coronavirus arrived in the US show a huge decline in pending sales, new listings, new closings, and a significant rise in homes being pulled off the listing. A March report by the Statewide Association showed that towards the onset of the coronavirus pandemic, the Bay Area housing market was going on well in terms of prices. When Covid-19 was first reported in the US, the average cost for an existing single-family home in Bay Area shot up to $1,009,790 in March, which is an 11% increase from February and 7.4% the same period last year. The number of sales that closed in March in the Bay Area also increased by 30.1% from the previous month, but that was a drop by 12.1% compared to the same period last year. Country-wise, house sales dropped in March by 11.5% from the previous month and 6.1% from the same period last year.
l
82
In a news release by the association, Jeanne Radsick, who is the association’s president and a Bakersfield Realtor, explains the sales drop as “only a prelude to what we’ll see in April and May because sales were still modestly strong during the first two weeks of March.” He also states that a 25% decline in pending sales is a suggestion that “the decline could extend beyond the next couple of months.” The Covid-19 pandemic has significantly slowed down sales, but according to Jeff Tucker, an economist at Zillow, buyers and sellers have retreated from the market at an equal rate. Sellers withdrew their homes from the listing while demand and the prices of the homes remained the same. And according to Jeff, “No sign of a slowdown yet.” According to Zillow data, new listings towards the end of March fell by 50% from the same period last year in San Francisco and the East Bay. In the San Jose metro area, new listings decreased by 34% from the same period last year. The declines were some of the worst experienced in the country, Jeff stated. “We entered the crisis with pretty much record low inventory,” Jeff said. In other regions, the story is not much different. In the South Bay region, five counties have recorded a decline in the number of closed sales in March. These counties are San Mateo, Santa Clara, Santa Cruz, Monterey, and San Benito. From March 17 onwards, the numbers have declined to 1, 872 from 2,290 the same time last year in the five counties. New listings also fell from 3768 to 2063 the same time last year. Also, according to MLSListings, this year has seen the number of cancelations or withdrawal from listings increase from 670 in last year to 1140 this year.
measures, there cannot be more than one agent and two buyers in a house at the same time. Also, everyone must have a mask, and the house commonly touched surfaces are disinfected. However, due to the uncertainties surrounding the current situation, both economically and physical wellbeing, many buyers and sellers have halted their plans unless in a case where the need to buy a house is too pressing. If you need to know anything about the home prices and the general housing market in Bay Area, feel free to contact Eric Hooks, our VIP Agent from Bay Area. Being a real estate investigator and realtor for California State, Hooks comes with a lot of experience and knowledge. Before being an investigator and realtor, he served as a Consumer Affairs Representative for California Public Utilities Commission. Eric will be just the realtor you need for any Bay Area housing enquiries. You can reach him at https://thepowerisnow.com/erichooks/. Works cited; https://www.sfchronicle.com/ business/networth/article/Bay-Areahome-prices-jumped-in-Marchmostly-15206485.php. https://www.nationalmortgagenews. com/articles/even-pandemic-cantslow-bay-area-home-prices.
The housing market has changed significantly since Covid-19 was first reported in the US forcing people to remain locked in their homes. The pandemic brought the closure of most businesses, and only the essential businesses are opening doors to offer their services. Fortunately, real estate was categorized under essential services. Despite this categorization, real estate agents are required to adhere to social distancing strictly. The agents are not allowed to hold one-on-one house showing unless the home is vacant or strictly staged in order to follow the public health measures. To adhere to the social distancing
WWW.THEPINMAGAZINE.COM
l
83
THIS VETERAN HAS EXPERIENCED ENOUGH.
HE SHOULDN’T HAVE TO FIGHT HOUSING DISCRIMINATION BECAUSE OF HIS DISABILITY. Sergio lost his leg and his hearing while serving our country overseas. Now back home, he was ready to start a new chapter in his life. But when he found the perfect apartment, the landlord refused to make a reasonable accommodation to allow his service dog in a “no pets” building. Then Sergio learned that the Fair Housing Act protects people with disabilities. He contacted HUD and filed a complaint. Today, Sergio is feeling right at home. If you believe you’ve experienced housing discrimination, please contact
hud.gov/fairhousing 1-800-669-9777 50 YEARS OF OPENING DOORS. A public service message from the U.S. Department of Housing and Urban Development in cooperation with the National Fair Housing Alliance. The federal Fair Housing Act prohibits discrimination because of race, color, religion, national origin, sex, familial status or disability. For more information, visit www.hud.gov/fairhousing.
Virginia housing market
Andre Jackson The impacts of Covid-19 are vast and wide. The pandemic has brought both social, psychological, and economic impacts since it was reported in the US. Economy wise, the pandemic has affected all aspects of the economy. Businesses have temporarily closed while others have laid off their workers to keep the business running. In the housing market, the pandemic has had significant impacts so far, even as experts warn everyone to embrace for tougher times are coming.
I
n Richmond, housing market experts towards the end of April sighted that the Richmond housing market retains its strength, but there are signs that the pandemic is having an impact on home listings. The Central Virginia Regional Multiple Listing Services released a report in mid-April, showing an increase in the number of new listings in the region between February and March. Still, at the same time, there the number of homes taken off the market skyrocketed as the impacts of the pandemic became severe. The months of March, April, and WWW.THEPINMAGAZINE.COM
May record the highest rate of home sales compared to other times of the year. But this year, the story has been different. The social distancing directives and the stay-home campaigns have locked everyone behind their doors, including home buyers and sellers, not only in Virginia but also in most US parts. The housing market in the US began to show signs of a slowdown towards the end of March. According to a March Housing trends report released at the beginning of April by realtor.com, the yearover-year listing inventory had significantly declined this year, and prices decelerated towards
the end of March. In the midst, all this crisis, the housing prices in the Richmond area could never drop. The average prices in the area skyrocketed by 7% to a staggering $270,000 compared to $259,000 in the same period last year. This marks the largest house price increase in the area over the previous two years. Despite the uncertainties surrounding the Covid-19 pandemic, housing agents in Richmond have taken it upon themselves to continue with their usual activities but strictly adhering to the public health directives. According to l
87
Richmond Times-Dispatch, agents in the area are disinfecting the homes before showing to any buyer. Also, they are utilizing the use of virtual house tours to other interested buyers in order to reduce the risk of Covid-19 transmission. Laura Lafayette, the Richmond Association of Realtor’s chief executive officer, commented on this saying, “It’s really important for the overall health of our regional economy that the real estate market continue to work.” The agents were required to follow all the safety guidelines while taking their potential buyer around the house. They are supposed to wear gloves when touching any surfaces around the house. They are also required to sanitize their hands before and entering the house on sale and keep their hands to themselves while inside the house. Lafayette, however, discouraged against holding the public open houses, but they should only continue with the real estate practices. According to a question and answer session on the Virginia Realtors website, the Virginia housing market is not headed for a crash despite the hard economic times. The impacts of the pandemic are dragging the US economy towards recession. Still, experts say that the impact it will have on the housing market will differ from what was witnessed during the Great Depression of 2007. The impacts of the pandemic will be different because of various reasons. First, the mortgage standards currently are stricter than they were during the period of the Great Depression. Back then, mortgage lending was so easier to get, and many people ended up borrowing even without the capacity to payback. Another reason is that, back then, during the Great Depression, Virginia had excess homes for sale after a round of massive new construction of single-family homes. The situation is very different currently as the supply of homes is very limited and regulated. Therefore, there are not too many houses for sale chasing few buyers. According to Virginia Realtors, a price drop across Virginia is likelier as the pandemic 88
l
impacts continue to persist. This will be as a result of many potential buyers adopting the “wait and see” approach while others cancel their home-buying plans due to a disruption in income. However, the real estate agents carry on with their real estate practices; you are advised to employ the safest methods if you want to take a tour of a home. The best way to do this is by asking the agent to guide you through a virtual tour. This is the most recommended method as the country intensifies its war against Covid-19. If you need any further information concerning the housing market in Richmond, you can talk to Bishop Andre Jackson, who is one of our VIP agents in the Richmond area. VIP Agents is a program powered and run by The Power Is Now Media Inc. Bishop Andre is a native resident at Richmond where he has lived for over 21 years and therefore, he understands what is going on in the area better than anyone else. Bishop Andre Jackson is the owner of Jackson Medical Supplies and Equipment, he also owns a record label, Ground Up Record and Production Co. He is also the Vice president of BASA Publishing and The American Clergy Leadership Conference of Northern California and National Co-chair. Bishop Andre holds a master’s degree in Christian Counselling and Theology and a doctorate degree in Christian Education and Theology; both of them from Sacramental Theological Seminary. You can reach out to him with any Richmond housing market questions through https://thepowerisnow.com/andrejackson/.
Works cited https://www.wtvr.com/news/coronavirus/covid19-impacts-richmond-housing-market. https://www.virginiarealtors.org/2020/03/19/faqcovid-19s-impact-on-the-housing-market/. https://www.builderonline.com/money/richmondreal-estate-agents-adapting-to-covid-19_c.
THE POWER IS NOW MAGAZINE | JUNE 2020
EXPERT ADVICE:
SHOULD I BUY A HOME WITH FEARS OF A RECESSION? Joe L. Fisher
T
he flames of the Covid-19 pandemic continue to burn persistently across the whole U.S and the world at large. As the pandemic causes more and more pain to the economy, there are more questions right now than answers. When could the current economic crisis come to an end? Is the current recession headed to a crash, or is it just a slowdown? How hard could the recession hit the housing market? Even as the federal government is laying down plans to reopen the economy, most people, especially home buyers, are finding themselves in a very confusing situation on what decision do they make. The World Health Organization recently declared that Covid-19 is not likely to go away quickly, as we all had anticipated. This announcement by the WHO put homebuyers in a more profound dilemma. Some home buyers have
been caught in between the thoughts of buying a home amidst the current or holding on until the state of normalcy come back. IN FEBRUARY, some economists warned of the likelihood of a recession occurring by next year. On the other hand, some other economists say that we are already in recession since every or at least most of the ma jor economic activities have paused as the number of unemployed people in the U.S continue skyrocketing. Looking back at what happened during the Great Recession between 2007 90
l
and 2009, many people are getting scared of buying a home during such uncertain times. The memories of the Great Recession have never been forgotten. The pain of losing a home or watching your neighbors lose their premises was among the Great Recession’s ma jor characteristics.
policies that made it easier for everyone to qualify for a mortgage. Many people got mortgages, and most of them were not in any position to pay back. Similarly, the coronavirus pandemic is causing a downward trend in interest rates, which is followed by a dramatic increase in demand.
Although the housing market caused the Great Recession, it seems to have almost the same characteristics as what were are experiencing due to coronavirus pandemic. The Great Recession was a result of the housing market
Greg McBride, the chief analyst at Bankrate, commented on the current situation and said, “Despite fear and uncertainty, investors should think to the future, beyond the economic pause and when business and life
THE POWER IS NOW MAGAZINE | JUNE 2020
resumes normalcy. The short-term disruption is unprecedented, but the long-term viability of the economy is not.” A home is more than an investment; it is a place to live. And therefore, with incredibly low mortgage rates, many buyers may find this as the perfect time to get themselves a home. However, it is still challenging for many to buy homes even with the low rates as many are not able to qualify for a mortgage loan due to the uncertain situation on their sources of income. Buying a home during a recession may be the best decision but not for everyone. For those with confidence in their future income flow despite the current economic crisis, such as those dealing in businesses that are still running well amidst this crisis, they can take this period as the perfect opportunity to buy a home with the low mortgage rates. The current trend of the housing market is gradually turning in favor of the buyers’ market as the demand continues dropping, causing a relative drop in prices. Jessica Whiffen, a licensed realtor with Premier Sotheby’s International Realty in Naples, Florida, states that buying a home with fears of a recession could be the best move to get yourself
a great deal, but it also comes with a financial risk which is a limited room for negotiation. “You are not in a traditional negotiating situation, where the buyer is on one side of the table, and the seller is on the other,” Whiffen states. “It is more like a triangle, in which the seller is the middle-man, and doesn’t have much say. You are essentially only negotiating with the bank.” In my opinion, buying a home during a recession depends on the current state of your income generation and how much risk you are willing to take. Just like Greg McBride says, “It takes nerves of steel to sign up for the largest financial commitment you’ve ever had at a time when the economic outlook is bleak, unemployment is rising, and fear and pessimism are rampant.” If your business is still operating and generating income normally during the current economic crisis, or if you are confident about your job security currently, or if you have enough savings and outstanding financial stability to survive you through the current economic tussles, this is the best time to buy your dream house. However, if the current economic decline has struck your business, this is not the perfect time for you to buy a house. For further advice on the housing market in the current situation, you can reach out to Joel L Fisher. Joel is one of our VIP Agents and a real estate industry guru with knowledge of a way around the real estate market especially in Richmond. You can get in touch with Joel at https://thepowerisnow.com/joe-fisher/. Works cited https://www.bankrate.com/mortgages/buying-ahome-before-recession/.
WWW.THEPINMAGAZINE.COM
l
91
WHEN IS THE RIGHT TIME TO BUY AN INVESTMENT PROPERTY? HERE ARE THINGS YOU SHOULD BE LOOKING FOR
Jerel Washington
B
uying an investment property can be an exciting decision to achieve future financial stability wealth generation. This decision also could go horribly wrong if you are not informed. Good returns on your investment are not guaranteed unless you approach it strategically. If you are new in the world of investment properties, you can get easily overwhelmed by the process. To avoid this overwhelming process, there is a lot of things to consider and plan well. Regardless of what you want to invest in, whether it’s a vacation real property, a rental condo in the city, a commercial investment, or any other real estate investment, you need to approach it with a clear mind and good knowhow of making a good purchase. This article features some important guidelines for things you should consider when buying an investment property.
1. LOCATION.
Location is one of the crucial factors that you must consider if you want a good return on your investment. Vacationers will not prefer a flashy vacation home if it is not located in a place frequented by people from all over. Before you buy an investment property, think location first. The right property in the wrong location will not be profitable.
94
l
INVESTMENT PROPERTY DOWN PAYMENT DIFFERENCE
Down payment when buying a standard family home is different from the investment property down payment. Buying a home requires a 1-10% down payment while purchasing an investment property requires a 1520% down payment. Investment properties also do not qualify for mortgage
insurance. When securing finance, investment properties face stricter approval requirements, and that is why they need a substantial down payment. Before you buy an investment property, ensure you have secured financing first and can afford the required down payment.
2. THE 1% RULE
The 1% rule in real estate is the term that investors use
THE POWER IS NOW MAGAZINE | JUNE 2020
to determine whether a specific investment is worth taking. The rule requires that your investment should earn you not less than 1% of the total amount you paid for it. That includes the purchase price and additional expenses, such as repairs and renovations. Take a case where you spend a total of let’s say $250,000 to purchase an investment property and make it ready for use. You should expect to earn at least 1% of $250,000, which is $2500 per month from its operations. If the investment property you are planning to buy doesn’t play at least around the 1% rule, it is not worth taking.
3. VARIABLE AND FIXED EXPENSES
Buying the property is not the end of it all. The property comes with so many other expenses, both fixed and variable. Variable expenses are very challenging to foresee, and that is why you need to have a flexible budget that will accommodate them. The fixed costs, such as property taxes, homeowner insurance property management expenses, among others, need to be included in your yearly or monthly budget. Before you buy an investment property,
analyze all the possible variable expenses, and determine whether the property can cater for them and still maintain profitability.
4. ANALYZE RISKS.
All investments come with varying levels of risks. Before you make a move to buy a property, you must have a knowhow on the risks to prevent frustrations. Some of the risks that come with investment property include; taxes could hike, encountering bad customers, dynamic market forces, and also low rental interest than expected. As much as you should not focus on the risks alone, you should not ignore them. Just make sure you are not too optimistic to see the risks, but instead, you should plan for them.
Having these factors in mind, you are now in a better position to buy an investment property that will be fruitful. Don’t wait any further; the power is now. Works cited https://www.moving.com/tips/6-factors-toconsider-when-buying-an-investment-property/.
www.StopHigherPropertyTaxes.org
Split-Roll Property Tax Measure Hurts Immigrant and Minority Communities
Background: Prop 13 Has Helped All Californians for More Than 40 Years •
For more than 40 years, Prop 13 has provided certainty to homeowners, farmers and businesses that they will be able to afford their property tax bills in the future. Under Prop 13, both residential and business property taxes are calculated based on 1% of their purchase price, and annual increases in property taxes are capped at 2%, which limits increases in property taxes, especially when property values rise quickly.
Split-Roll Property Tax Measure Destroys Prop 13 and Makes Our Economic Crisis Worse •
•
Amid an unprecedented economic crisis, special interests submitted petitions to qualify a measure for the November 2020 statewide ballot that will destroy Prop 13’s property tax protections and will be the largest property tax increase in California history. The measure will raise taxes on commercial and industrial property by requiring reassessment at current market value at least every three years. This type of property tax is known as a “split-roll tax” because it splits the property tax roll, assessing business property differently than residential property. We should reject this measure and maintain Prop 13 protections that have kept property taxes affordable and provided every taxpayer who buys a home or business property with certainty that they can afford their property tax bills in the future. Now is not the time to raise taxes and bring more uncertainty to businesses and all Californians.
Gentrifies Our Longtime Communities •
A split-roll property tax will provide a huge financial incentive for local governments to approve business projects to replace existing housing so they can receive higher property tax revenue. It will also push small minority- and immigrant-owned businesses out of our communities when they can’t afford the higher property taxes. This unintended consequence will intensify the gentrification already occurring in much of the Bay Area and Southern California coastal counties.
Hurts Small Businesses and Consumers •
Most small businesses rent the property on which they operate. The measure’s higher property taxes will mean soaring rents at a time when the federal and state government is trying to provide small businesses with rent relief to keep their doors open. Ultimately, the measure’s tax hike on businesses will get passed on to consumers in the form of increased costs on just about everything people buy and use, including groceries, fuel, utilities, day care and health care.
Hits Minority-, Immigrant- and Female-Owned Businesses the Hardest •
•
•
Small businesses are already struggling. This measure will make it even more difficult for them to reopen their doors or stay in business as a result of this economic crisis. Increasing property taxes on businesses by up to $12.5 billion a year will hurt female- and minority-owned businesses the most and 120,000 jobs will be lost, according to a Berkeley Research Group study. Voters are being asked to consider a measure that will only increase job losses at a time when millions of Californians are applying for unemployment benefits. According to the latest data from the Harvard Business School, about 42% of new companies are founded by immigrants in California and the most recent 2012 Survey of Business Owners by the Census bureau found that 5% of businesses in the state are owned by African Americans. Additionally, the California Latino Economic Institute found that nearly one-quarter of all businesses in California are owned by Latinos, and they are the fastest-growing component of the state’s economy. Most of these businesses start small and stay small, meaning they often rent their property and are subject to higher rents when property taxes increase. In the most recent 2012 Survey of Business Owners by the Census Bureau, 38% of all non-publicly traded businesses were owned by females and another 9% were owned equally by females and males.
Increases the Cost of Living for Everyone and Makes the Homelessness Crisis Even Worse • •
In 2019, US Housing & Urban Development data showed California led the nation with more than one-quarter of the country’s homeless population. California’s cost of living is already among the nation’s highest. We shouldn't do anything to make it even more expensive to live here. The split-roll measure will only increase homelessness and make life more difficult for Californians already living paycheck-to-paycheck.
Homeowners Are Under Attack • If businesses lose their Prop 13 protections, homeowners will be next. Supporters of the measure even admitted
that this initiative was the first step in a plan to end Prop 13, which could mean skyrocketing property tax increases for all California homeowners.
Ad paid for by Californians to Save Prop 13 and Stop Higher Property Taxes, sponsored by California homeowners, taxpayers, and businesses Committee major funding from Western Manufactured Housing Communities Association California Business Roundtable California Taxpayers Association Funding details at www.fppc.ca.gov
s e l e g n Los A
BEST PLACES TO LIVE IN
Briana Frazier
B
eing the second-largest city in the U.S comes with a lot of expectations. You’d expect to find different unique experiences, livelihood, and also impeccable living communities. However, Los Angeles got it all that will satisfy and exceed your expectations. The city boasts of having some of the best neighborhoods and locations to live. Having a population of about 3.8 million residents, L.A is much more than what you hear around and in the news. The modern city features a super-rich culture, sporting activities, entertainment, and recreational facilities. The city also features some of the best neighborhoods you can live in California. This article will feature some of the best places you can line in L.A.
1. WHITTIER
According to Livability.com, Whittier ranks position 82 out of 100 of the best cities to live in the U.S. Jeff Collier, the City Manager commented that “We’re very proud and it’s fantastic for our community to be recognized this way.” Whittier is stationed at a convenient location, which is proximity to big sports teams, colleges, universities, and airports. The city also comprises a very
98
l
family-friendly environment that is rich in urban forestry with plenty of trees and patterns of hills. The city comprises of approximately 85,000 residents with a ma jority being 34 years old and below. According to Livability, the city is most suitable for single individuals (such as students) and families as well.
2. MIRACLE MILE
Located west of downtown L.A, Miracle Mile is part of the Mid-Wilshire community and comprises about 5,500 residents. Miracle Mile is famous for its Museum Row, which is like a collection of museums. The Museum Row features the George C. Page Museum, Los Angeles County Museum of Art, Petersen Automotive Museum, La Brea Tar Pits pavilions, and Craft and Folk Art Museum. The Museum Row comes with a lot of recreational and educational opportunities for visitors. Miracle Mile also is very kid-friendly with paved sidewalks. The neighborhood has a shallow crime rate of 5.5 per 10,000 residents. The neighborhood also has several schools, both private and public. It also features several city parks and a library.
THE POWER IS NOW MAGAZINE | APRIL 2020
3. SHERMAN OAKS
Sherman Oaks is located in the San Fernando Valley neighborhood in L.A. It features a very safe living environment with a very low rate of crime of 8.4 out of 10,000. With a population of about 52,000 residents, Sherman Oaks has a very family-friendly environment with two city parks, a senior center, several public, and private schools. The neighborhood has several shopping centers with a weekly farmers market. The neighborhood also holds an annual Sherman Oaks Street Fair, which you can enjoy with your whole family.
4. TARZANA
With a population of about 35,000 residents, Tarzana is another community-based in the San Fernando Valley neighborhood. Tarzana is named after a famous fictional character created by Edgar Rice Burroughs. The place is also famous for the setting of some Hollywood films such as The Karate Kid, Akeelah, Thirteen, and The Bee, among others.
regions in L.A, but it is definitely worth it.
6. PALMS The palm area of L.A is known for its diverse and affordability residential community that comprises single-family homes, apartments, duplexes, and triplexes. With a population of over 42, 000 residents, the area was once a ma jor agricultural center that turned into a residential community. The cost of living in Palms is relatively low since it is 19% lower than California’s average cost of living. Palms boasts of its safe and secure living neighborhood with a very low crime rate of 2.6 per 10,000. The area also comes with a friendly living environment that features a city park, and various family entertainment activities.
It is true what is said in the streets about Beverly Hills. The place features fabulous glitz, glamour, high-end stores, and is home to several celebrities. The region has one of the most costly zip codes on the west coast only because it is an excellent place to live.
The locations discussed above are just a few of the many awesome neighborhoods in Los Angeles, not in any order. For any professional guidance on the best places, you can settle in Los Angeles and California at large, you can reach out to our VIP Agent, Briana Frazier. Briana is a licensed real estate broker and an active member of National Association of Realtors, California Association of Realtors, Women’s Council of Realtors, Orange County Association of Realtors, and Inland Valley Association of Realtors. Being a member of all these realtor groups, she is for sure your perfect shot for getting the best place to settle in L.A. You can reach her at https://thepowerisnow.com/brianafrazier/.
The region has a population of about 35,000 residents with a very relaxed and friendly neighborhood. With an incredibly low crime rate of about 3.6 per 10,000, Beverly Hills also features top-notch schools and a wealthy population. The cost of living at this place may be incredibly higher than the other
Works Cited https://www.movoto.com/guide/los-angelesca/safest-neighborhoods-in-los-angeles-forfamilies/. https://www.whittierdailynews.com/2013/10/18/ whittier-named-one-of-best-places-to-live-in-us/.
The community comprises of a strong economy with an educated populace and a very minimal crime rate of 6.1 per 10,000. The community has various private and public schools and also is home to the famous Columbia College Hollywood.
5. BEVERLY HILLS
WWW.THEPINMAGAZINE.COM
l
99
THE NATIONAL FAIR HOUSING
MONTH SHOULD BE ABOUT FAIRNESS AND JUSTICE IN HOUSING
HOW TO NEGOTIATE AN OFFER ON A HOME
Jenny Gonzalez
B
uying a house is all about knowing and understanding the art of give and take. In most cases and with the buyers I have worked with over the years, they think that the purchase price is the main negotiating point, and while there is some truth to that, that’s only a minor cog in real estate transactions. Therefore, it is important that you learn what your ma jor negotiation points are, and how you can use them to your advantage. This will undoubtedly give you an advantage of being able to craft up an offer that will work in your favor, and ultimately please the seller. So, what are the areas you should be focusing on?
OFFER PRICE
Well, this is the most obvious factor. In most cases, buyers seem to understand that the listing price of a home is the price that the seller is hoping to make on a sale of a home, and it is often negotiable. But, like in most cases, pricing is where people often lose and deals fall apart. The primary reason for this is that buyers want to score a deal when buying a home. On the other hand, for the seller, the goal is the exact opposite. The seller is hoping for a profit on their home, and possibly, with a larger margin, especially if it was financed and isn’t paid in full. Anything less than their balance means that they’ll be required to pay the difference out of pocket at the time they sell their homes. This means that as a buyer, you’ll have to be flexible. An increase in the sales price can be distributed over the length of the mortgage, which lowers the financial burden at the time of sale. Given this, buyers will have more flexibility on price.
WWW.THEPINMAGAZINE.COM
GET PROOF
Yes, you can submit an offer without the proof that you can afford the home, however, to win the heart of the seller you need to show them that you can afford it. If you are a cash buyer, a statement from your bank or your brokerage that shows the balance equal to or even greater than the offer price should suffice. You can create a separate bank account and transfer the exact amount you want to spend, or equal to the offer. If on the other hand, you want to buy the home using a mortgage, it is advisable to get a preapproval letter that you will submit with your offer. You should note that preapproval is a step above pre-qualification, and these are two different concepts. The preapproval process involves going through with the application process, which includes a credit check and employment, income and asset verifications. Preapproval represents a commitment from the bank to lend to you. Get the preapproval letter with the exact amount of your offer, even if the lender is willing to approve you for more. If you do these things, just wait for the magic to play itself out.
HAVE A CONTINGENCY
It is common that the fewer the contingencies in your offer, the more likely it will be for you to close the deal. Fewer contingencies mean fewer chances of the deal going south. For you to successfully close a deal, each of the outlined contingency must be satisfied in a way that both the parties are comfortable with. If you fail to reach an agreement with the seller, you have l
101
the option to dissolve the contract and walk away, this is a concern for most sellers, and therefore, your willingness to be flexible with your seller’s contingencies will give you more power in the negotiating table.
Remember, as a buyer, the main roles of contingencies is to protect you. For instance, waiving an appraisal contingency simply means that the seller doesn’t have to negotiate the sales price with the buyer if a home is appraised below the offer price. The appraisals are used by the lenders to determine the buyer’s loan amount; this could leave the buyer on the hook for a larger down payment to offset the difference or even force them to break the contract and forfeit their earnest money deposit. Always try to find the middle ground. For example, you may consider shortening the contingency period, rather than waiving the inspection contingency altogether. A decrease in the contingency period means a quicker close of escrow for the seller.
DETERMINE YOUR CLOSING SCHEDULE
This will depend on where you live. In some areas, it is possible to close on a home in as little as 10 to 15 days. It is also possible to write a much longer close to the offer. Typically, the contract period is 30-45 days, but it is also possible to find contracts with 60 days or more to close. The seller wants to close as soon as possible, but it is imperative not to commit to unrealistic short periods. It is common to find lenders advising you to allow a bare minimum of 30 days, but, I’d suggest no more than 45 days. It is also essential to make a consideration of the closing costs. Here, the buyer might request the seller to cover their half-closing costs, or some transfer taxes or fees, by subtracting that costs from the sales prices. Whatever you choose, make sure it is something you are comfortable with. Suppose you want to see some great properties in Corona, be it for residential or commercial purposes, get in touch with one of our VIP agents, Jenny Gonzalez in Corona CA. to learn more about the program, click here. Jenny has been in the real estate business since 1998, climbing the ranks to become one of the most respected, and renown real estate agents in Corona. To learn more about Jenny, click here.
Jenny Gonzalez Realtor Keller Williams Realty
Sources https://www.opendoor.com/w/blog/4considerations-negotiating-house-price https://www.fool.com/millionacres/realestate-market/homebuying/making-offerhome-how-negotiate-your-purchase/ https://www.houselogic.com/buy/how-to-buystep-by-step/how-to-negotiate-an-offer/
102
l
THE POWER IS NOW MAGAZINE | JUNE 2020
Do you know
Peppermint Ridge? We provide a community of loving homes and empowering support services for individuals with intellectual and developmental disabilities.
We
support and encourage our residents to live their
lives and fulfill their dreams by fully embracing their indvidual abilities and interests. With 24-hour specialized care and staffing, we provide comfortable, secure homes and recognize that everyone feels a sense of belonging when they have familiar places in which to spend time with family and friends.
There
is a true sense of family at Peppermint Ridge. Of the 94 adults who
live at The Ridge, 38 have lived here for more than 20 years, with 10 of those calling The Ridge home for 40 years or more. Residents have the opportunity to flex their muscles of independence while developing rich lives of their own away from their loved ones. About 30% of our residents have no family, so other Ridgers and our staff have become their family.
Many
caring companies, organizations and individuals in
the community enjoy getting to know The Ridge by helping on small projects, hosting fundraisers, lending a hand at events, volunteering in our office, and assisting residents in activities such as arts and crafts, pool days, horseback riding, music and piano lessons, and exercise classes.
825 Magnolia Ave • Corona CA 92879 • 951.273.7320 www.PeppermintRidge.org • Tax ID: 95-2409851
Realtor Selling tips
SELLING A HOME SAFELY DURING THE COVID-19 PANDEMIC
Johnnie Morine
D
uring usual times, selling a home was not an easy job. The process could take a 1. Adopt virtual house tours lot of time and energy, therefore, Despite the real estate agents’ allowance draining the seller emotionally. to continue with their operations, they are But now, with the Covid-19 supposed to do so without putting anyone at Pandemic as the new norm, the risk of contracting the virus. The agents should times have changed. The process recognize the power of doing house tours could be easy for some and more virtually. They should consider taking their challenging for others. The home potential clients through the house tours virtually. selling process now requires the Virtual home tours has been there even before, seller to blend in some additional but this is the time it should be utilized the most. safety measures as it is necessary to prevent cut the chain of Covid-19 Michelle Mumoli, the CEO of Mumoli Group, states, transmission. The current Pandemic may have caused the closure of several or most of the businesses, and only the essential services are allowed to continue operating. Fortunately, Homeland Security recently declared real estate as an essential service, although it is not allowed to run as it used to during the good old days. To sell your homes and continue transacting normally, you may need to borrow a few Realtor processes that will ensure your safety and that of your clients. WWW.THEPINMAGAZINE.COM
“Sellers love virtual tours because typically what would be the inconvenience of leaving the residence for 20 to 30 minutes to allow potential buyers access now have the opportunity to allow them access without having to leave.� Mumoli Group is a residential and commercial dealers firm based in Hoboken, NJ. Apart from the agents engaging one on one with the interested client, they can also take eye-catching images and videos of the homes they are selling and post them online. This can be a very significant way of driving traffic and acquiring more home buyers.
l
105
2. Extra precautions for physical home tours.
To ensure everyone’s safety, open house tours with a large group of people are offenses now. On the other hand, buyers want to view homes in person before making their decision. Agents and other sellers on the other side may be worried about the risk of interacting with strangers in their homes. In a case where there has to be a physical house tour, the agents have to be extra cautious on how to go about this. Many agents have introduced a house showing kit that features a sanitizer, booties, and gloves for use during the house tour. Before beginning the showing processes, sellers are advised to disinfect frequently touched surfaces such as doorknobs, closets, cabinets, and switches. The buyers also are encouraged to disinfect themselves before the process begins. To further reduce the frequent touching of these surfaces, the agents are advised to leave doors of closets and other rooms open and ensure the lights are on as well. Once the house showing process is over, it is highly recommended for the seller to disinfect themselves once again to mitigate the risk of having interacted with the buyer.
3. Engage in safe home inspections
In normal circumstances, sellers have to let the inspectors and appraisers brought by buyers to check the homes before the deal is closed. But with the different Covid-19 situation that requires no physical interaction, the home inspections and appraisals should be conducted with no contact. For instance, the HomeMaster, which is a home inspection company in the U.S, is trying its best to reduce any contact. They are asking sellers to remain secluded in a place where they will not come into contact with the inspectors. The buyers are also supposed to be in the appropriate personal protective equipment such as gloves and masks, according to the Centre for Disease Control and Prevention guidelines. If the appraiser allows it, the appraisal
106
l
process can be done without having to go into the house or even virtually.
4. Remote deal closing
The practice of remotely closing home deals has been there in some parts of the country, even before the Pandemic. But currently, the practice is highly recommended for the safety of both the seller and the buyer. A total of 23 states currently have remote notarization policies that allow virtual execution of electronic documents between a notary and a signer. The National Association of Realtors recently reached out to Congress through a letter asking them to expand the policies across the whole of the U.S for the safety and efficiency of the real estate transactions, especially during this Pandemic. The challenge behind remote closing is that some lenders of buyers don’t have the technology the offers a full virtual closing. However, in a case where remote closing is possible, the title company should prepare the required documents and through the physical mail and email or upload them to a portal.
The fight against this virus will require
all of us in order to win. Make it a personal responsibility to observe the safety guidelines to ensure we put to an end the spread of the virus. Stay safe, stay home, and keep washing your hands, and we will be sure to win this war. If you’re a home buyer or a seller have any inquiries on how you can buy or sell your home safely during these difficult times, don’t look no more; our VIP Agent Johnnie Morine is here to help you. Johnnie is the owner of the Morine Group Realtors, which is a prolific real brokerage firm that offers full service brokerage, training, mentoring and coaching services. Johnnie is also a motivational author with S.P.E.C.I.A.L philosophy on sales and marketing. You can get in touch with Johnnie at https://thepowerisnow.com/johnnie-morine/. Works Cited; https://www.realtor.com/advice/sell/is-it-safeto-sell-your-home-during-the-coronaviruspandemic/ THE POWER IS NOW MAGAZINE | JUNE 2020
YOU DESERVE TO LIVE SAFE FROM SEXUAL HARASSMENT.
Sexual harassment by a landlord or anyone related to your housing violates the Fair Housing Act. If you receive unwelcome sexual advances or are threatened with eviction because you refuse to provide sexual favors, you may file a fair housing complaint. To file a complaint, go to
hud.gov/fairhousing or call 1-800-669-9777 If you fear for your safety, call 911.
FAIR HOUSING IS YOUR RIGHT. USE IT. A public service message from the U.S. Department of Housing and Urban Development in cooperation with the National Fair Housing Alliance. The federal Fair Housing Act prohibits discrimination because of race, color, religion, national origin, sex, familial status or disability. For more information, visit www.hud.gov/fairhousing.
MORTGAGE FRAUD HAD DROPPED but its Likely Coronavirus Could Bring a new wave
A
ccording to data released by CoreLogic National Mortgage Application Risk Index, the risk for mortgage fraud application dropped to 8.9% in the 1st quarter of this year from 26.6% in the 1st quarter of 2019. The data further reveals that the 1st quarter of 2020 risk level is parallel to the refinance boom that was witnessed in the 3rd quarter with the same magnitude.
108
l
The mortgage environment is known for its low-interest rates, which led to an overall application increase with refinances accounting for about 59.9% of mortgage transactions during the 1st quarter, something that has never happened for the past 7years. Refinances that are driven by rates feature a lower risk of fraud, therefore, resulting in an improved risk score. A study by CoreLogic has shown that the effects of Covid-19 could bring a new cycle of fraudulent activities that could be based on the behavior of home prices. The effects of the coronavirus have resulted in a massive ripple effect on mortgage lenders. Even before the onset of the Covid-19 pandemic, mortgage lenders were already struggling with their operations due to the low mortgage rates. The low rates increased the number of borrowers and the lenders were handling a storm of borrowers who were seeking to refinance and without forgetting that the lenders we getting distressed from the other existing loans. The lenders were indeed in trouble. To make the matter worse, the federal government, in their course
THE POWER IS NOW MAGAZINE | JUNE 2020
to take action amid the spread of Covid-19, resulted in a significant drop in the rates to almost zero. On the other hand, there was an increasing number of homeowners who wanted to lower their mortgage payments as the economic crisis was getting more severe. In a statement by the principal of mortgage fraud solutions at CoreLogic, Bridget Berg, there is an immediate risk as borrowers are likely to misrepresent their income status in order to qualify for a refinancing. What makes this situation worse is the newly introduced underwriting accommodations, such as flexibility in appraisals that have led to a relaxation in the standards. Individuals are most likely to take advantage of these relaxed standards to overvalue their properties and income as well as assets. Bridget further states that a fall in prices of properties will make it challenging to sell them. Also, a fall in property prices may lead to an upward trending in distressed listing inventory. There will also be massive bailout schemes for builders, an increased number of straw buyers, and massive illegal flipping. As the cycle continues, there will be an increased number of fraudulent loan
WWW.THEPINMAGAZINE.COM
modifications accompanied by short sales with a lot of foreclosure rescue schemes. The crisis could bring liquidity issues to lenders, which could force them to introduce corporate schemes, for example, air loans, warehouse fraud, and misuse of custodial and trust accounts to prevent further losses. In efforts to combat mortgage fraud and mitigate any potential loss, CoreLogic joined hands with Secure Insights in March 2020 and started providing housing agents with the necessary information to avoid getting into wire fraud. The information given to housing agents will enable LoanSafe users to evaluate housing agents before closing to identify potential misappropriations. This will significantly help in preventing the huge losses incurred by lenders from wire fraud.
Works cited https://www.americanbanker.com/news/virusscare-creates-perfect-storm-for-mortgagelenders. https://www.nationalmortgagenews.com/ news/mortgage-fraud-risk-drops-butcoronavirus-could-bring-new-wave.
l
109
A
!
good credit report is a straightforward passage for you to get a good mortgage loan with the best interest rates. A good credit report also gives you very high chances for your loans to get approved. Although you can get a mortgage even when your credit scores are not good, the process can be a lot easier when your credit scores are excellent. Getting your credit scores to attain a good rating may be a challenging task. This article will discuss a few tips that you could use to improve your credit scores before going for that mortgage.
TIPS ON HOW TO IMPROVE YOUR CREDIT SCORE BEFORE YOU BUY A HOUSE 1. LOOK THROUGH YOUR CREDIT REPORTS Before making any move to engage in buying a house process, make sure you go through the three things that the lender is likely to check on. The first is the steadiness of your income as well as your spouse’s; the next one is the amount of down payment that you can afford, and lastly, your credit history. Ensure the three meet the level of the minimum requirements that your lender needs. If all is good, you can proceed with the plan.
2. DISPUTE ANY ERRORS ON YOUR CREDIT REPORT
It is almost normal to find errors in a credit report. The errors could be from a misinterpretation of your credit data or maybe or even errors from typing. Errors in a credit report could affect your credit scores negatively. Ensure you get a copy of your credit records from your bankers and keenly go through them to ensure the information in them is as it should be. In case of any errors, you are supposed to communicate with your bankers for correction.
3. SETTLE ANY ACTIVE DEBTS
Having any outstanding debts whose payment deadline is near or even overdue may put your credit scores at a high risk of dropping. Before you engage with any lender, ensure you pay off those debts to clear your name from the debt books. Clearing any pending debts highly boosts your credit scores.
110
l
THE POWER IS NOW MAGAZINE | JUNE 2020
4. REQUEST FOR AN INCREASE IN YOUR CREDIT LIMIT
After clearing all your pending loan balances, you stand in a perfect position to get your credit limit increased. Getting an increase in credit limit may not make a difference to your debt-to-income ratio, but it will significantly cause decrease in utilization of your credit as your outstanding debt maintains its position leading to an increase in your available credit. In most cases, when you apply for a rise in credit limit after settling all your debts, your request is most likely to be approved instantly. Getting an increase in your credit limit signifies a good gesture about your credit history, and this will instantly increase your credit score.
AVOID ANY NEW LOANS If you are planning to apply for a mortgage, ensure that you keep away from any other debts. Applying for a mortgage when you already have an existing recent loan will lower your chances of getting the mortgage to almost zero. Ensure you keep away from any new loans until you secure a mortgage. To get a better knowhow about improving your credit scores, talk to any of our VIP agents stationed all across the state of California. Use the following link; https://thepowerisnow.com/ vipagentsservices/. In case you want to keep yourself up to date with the current developing stories, visit our blogs page at https://
5. ENSURE A LOW DEBT-TO-INCOME RATIO A high debt-to-income ratio is likely to make your lender doubt your ability to pay off the mortgage. To significantly improve your credit scores, ensure that your debt-toincome ratio is as low as possible; it should be at most 12% of your monthly income. The lower your ratio is, the better your credit score will be, and the higher chances to get a mortgage will be.
WWW.THEPINMAGAZINE.COM
thepowerisnow.com/blog/. Works cited; https://www.thebalance.com/before-you-applyfor-a-mortgage-960362. https://www.huffpost.com/entry/ raise-credit-score-mortgagehouse_l_5d0195c2e4b0304a1209884b. https://www.homelight.com/blog/how-toimprove-credit-to-buy-home/.
l
111
ALL COUNTY DOCUMENT SERVICES OFFERING VIRTUAL PARALEGAL SERVICE Low Cost Quality Legal Assistance Payment Arrangements Available
Corona CA Legal Document Preparation Professional Paralegal Services without the high cost of attorney fees. We offer Virtual Paralegal Services to honor the COVID-19 stay-at-home, so no need to come into the office, we do everything online and utilize the courts efiling system.
• • • • • • •
Living trust Probate Services Family Law Services Divorce Request for Order Marital Settlement Agreements Civil Services
Contact All County Document Services in Corona CA today for a free quote! Licensed, Registered and Bonded Legal Document Assistant No: 271 License No: 659119 Notary Commission #2090397
Legal Assistance You Can Afford! 951-272-5855 951-207-1185 1234 Goldenview Drive Corona, CA 92882
HOW COVID-19
is Exposing Flaws in the U.S. and World Health System
T
he novel coronavirus is fighting so hard to expose the flaws in the health system, not just in America, but all over the world. The fact is, no one, and no country was prepared for a pandemic. Recently, the Group of 20, else known as G-20, said that the pandemic has exposed the “systemic weaknesses” in the global health systems. However, there were no mentions of Washington’s Contentious decisions to halt funding to the WHO.
114
l
Speaking of which, the President announced that his administration would be halting the nation’s funding to the WHO, which is a move that has the potential to exacerbate COVID-19 and cost more lives. Trump said this during a press briefing at the White House, saying that a review is being conducted to assess WHO’s role in addressing the spread of the virus. Back to the main story, there is a growing concern that Americans won’t seek care as the costs involved are high. Even before the crisis hit the United States, the country
was already dealing with another crisis; fewer doctors and fewer hospital beds per capita than most other developed countries. What we see right now is the result of that incompetency where the rollout of the virus testing has been somewhat patchy, reliant on a mix of government and private labs to scale up the capacity to perform the tens of thousands of tests that will be necessary. “Everyone working in this space would agree that no matter how you measure it, the U.S. is far behind on this,” says Jen Kates, director of global health and HIV policy at the Kaiser Family Foundation.
THE POWER IS NOW MAGAZINE | JUNE 2020
NO ROOMS + NO EQUIPMENT = NO MONITORING You won’t know your status until you get checked by the doctor, and this is the disconnect. Americans may avoid medical care even for some severe conditions simply because they cannot afford it. Hospitals will need to be equipped with more equipment, and apart from that, there is a severe deficit for rooms. With no rooms and no sufficient equipment, close patient monitoring and evaluation may be impossible. As of the month of May, the United States was leading both in the number of confirmed cases and death toll. Medical professionals in the country and experts all agree to one thing; the strain on the health care system has severely compromised the ability of the U.S. to fight the virus fully hands-on. They said that the pandemic has revealed that the country needs a shift in the way it views the health care system, as hospitals struggle to treat the surge in patients and lack enough personal protective equipment to keep the workers safe. “We essentially have built a health care system that is perfectly right-sized for the care that was delivered yesterday, with totally just-in-time supply chains because we value efficiency,” said Dr Brendan Carr, chair of emergency medicine for the Mount Sinai Health System in New York. “And what just happened to us is we got caught out on that, and it became very, very clear that we weren’t ready for an unexpected bump in the night.” Experts now urge the industry to heed to the lessons it has learned for the future of medicine. This comes also calling for a change in financial incentives, a more national and global approach to the public WWW.THEPINMAGAZINE.COM
health, creation of an efficient manufacturing and distribution system for critical supplies and a continued increase in the use of telemedicine. Right now, the available ICU spaces in hospitals are not sitting empty. And apart from sheltering coronavirus patients, some non-coronavirus patients need them and will continue to need them through the crisis. The New York governor, Andrew Cuomo has said that nearly 80 percent of the New York City’s ICUs were already filled, even with the COVID-19 outbreak still spreading.
A BROKEN SYSTEM
Let’s agree on one thing, by any of these metrics on pandemic preparedness, America is probably trailing most of the rest of the developed world.
“The U.S. performs worse than average among similarly large and wealthy countries across nearly all measures of preparedness for a pandemic,” Cynthia Cox, director of the Peterson-Kaiser Health System Tracker, told me. “The coronavirus outbreak is already exposing inefficiencies and inequities in our health system, and it is likely to put much more strain on the system in the coming weeks.” The fact is, the country started out small, with slow testing, which is only going to get worse. Testing is a primary step in the fight against this disease. It gets people diagnosed and on appropriate treatment if they do have an infection. Testing also establishes how widespread the virus is and will be. With testing facilities, experts can size up the problem; they know the rate at which the infection is spreading and the rate at which people are being hospitalized or dying, and can be able to follow its movement effectively.
l
115
However, even when testing is being emphasized on a large scale, the country has faltered in rolling out coronavirus tests, putting us far behind other developed countries in tracing management. Take a look at the following;
“The testing failure is putting additional strain on our already challenged health system,” Cox said. “The combination of all of these factors will make the U.S. worse off than similar countries.”
UNIVERSAL HEALTH CARE HAS NO ANSWERS FOR A PANDEMIC AS THIS
People are looking to UHC as if it had the answer to this pandemic. While to some extent, it may help, UHC is not the perfect treatment for emergencies like this. A country like Italy has a UHC system, a federalized national health insurance program very similar to Canada’s, but still, it was unable to contain the virus. “For quite some time in the past, the U.S. politicians had made proposition to make American health care system more like these other nations; either by making carefree or cheap at the point of service, either by having the government cover more of the cost by mandating private insurers cover services related to the outbreak.” – Dylan Scott, Vox.
116
l
THE POWER IS NOW MAGAZINE | JUNE 2020
Its even worse because the country has made primary care a low-margin to negative-margin business for hospitals while other things such as fancy operations and cancer therapy are highmargins. Right now, a change in how the health care businesses are run would likely be determined by either the congressional action or by creating payment incentives for the hospitals.
IT’S NOT THAT WE CANNOT CONTAIN IT, HEALTH CARE COSTS ARE WAY TOO HIGH TO ALLOW CONTAINMENT Right now, about one millionplus case have been reported in America. Moving forward, it is hard to tell whether the country will be able to contain the virus spread. On many measures, the United States’ health care system is worse among the developed nations. A large chunk of the population lacks health insurances, and those who do carry the most medical debt. Fact is, among all the developed countries, Americans often die more from preventable causes, for instance, America is leading in the death toll with about 60K deaths. Among all other problems in this flawed system, the one that stands out is the cost factor. More than any other developed nations, Americans face higher out-ofpocket costs for their medical care than other people. Research shows people will forgo care they need, including for some severe conditions, mainly because of the cost implications. “Patients here are much more likely than those in most other countries to say they had a costrelated barrier to getting medical WWW.THEPINMAGAZINE.COM
care: 33 percent in America vs between 7 percent (Germany) and 22 percent (Switzerland) in other developed economies. Americans are more likely to say they struggled to afford or couldn’t afford medical bills and that their insurance plan had refused to cover some of their medical claims. “- Dylan Scott, Vox. Most Americans will delay care as a result of cost barriers. In fact, in 2019, 33 percent of the Americans said that they put off treatment for medical conditionals because of cost; 25 percent said that they postponed their care for a severe condition. The previous year, a study found that women with breast cancer would delay care simply because of the high deductibles on their insurance plan, even for some basic services. First, the cost factor has an implication in that as the pandemic situation grows, the patient will be more reluctant to visit hospitals. First, they might get wary because they cannot afford the check-up or the testing. Secondly, even if they do get a COVID-19 diagnosis and require hospitalization, they have bills from the hospital that they need to worry about. Sources; https://www.vox.com/policy-andpolitics/2020/3/16/21173766/ coronavirus-covid-19-us-caseshealth-care-system https://www.nbcnews.com/news/ us-news/health-care-experts-saycoronavirus-exposes-ma jor-flawsmedical-system-n1194391 https://www.straitstimes.com/ world/middle-east/covid-19exposes-flaws-in-health-systemssays-g-20 l
117
Celebrating the
BLACK MUSIC MONTH
in Style
The month of June is recognized as the Black Music Month since 1979 when it received a decree of honor by the then-president Jimmy Carter for the very first time in America.
The first celebration for Black Music begins explicitly on June 7. Black music is celebrated for the evident and numerous contributions that African-American musicians made in the US. However, Black Music Month is more than a mere celebration; it is educational, which helps to appreciate the historical events of the African-American cultural contributions in the US. To celebrate the Black Music Month in style, let’s first go back a little bit. Let’s get to know how all these started, where and how it has come this far. Black music refers to a wide range of African-American music from a diverse collection of music genres composed of black Americans. Black music has its origins from the musical environment that rose from the historical events of slavery before the onset of the American civil war. After the civil war came to an end, African-Americans were employed as musicians to play European music events such as military bands, which led to the development of a unique style of music, which was known as ragtime. As time went on, ragtime music steadily evolved into jazz, which is played even in the present day. In the 1940s, black musicians developed some other musical styles related to jazz music, which were known as rhythm and blues. In the 1960s, the black musicians went ahead to produce funk music, which developed into jazz-fusion in the 1970s. In the 1980s, the black artists were still kicking it, and they introduced hip-hop into the world. In late 1980, they introduced the disco-inspired dance style music known as house music. Most of these music genres are still popular in the present day in America and all over the world at large. From the little history, it is only fair to declare that the different forms of music developed by African-Americans are the inspiration behind the development of music in the US and all over the world in this century and in the centuries to come.
118
l
THE POWER IS NOW MAGAZINE | JUNE 2020
Black Music Month did not just turn to be a big deal all by itself. It is also crucial to recognize the able individuals who put their efforts to make it known o the world. Shortly after the Black Music was awarded a period for celebration, a black radio personality, Dyana Williams, together with the iconic duo Kenny Gamble and Leon Huff, launched the Philadelphia soul sound that officially got the Black Music Month the recognition it needed. As we mark the 41st anniversary for Black Music Month, let nothing stop you celebrating it in style. This year may not as good as the previous years’ celebration due to the persisting impacts of the Covid-19 pandemic. But still, there are a couple of ways in which you can celebrate it in style while quarantined at home. Listen to those old jams, watch them on YouTube and other social media platforms and also ensure you subscribe and like their social media pages. To make it even more stylish, you can share the old black music hit songs with your friends and family both virtually and physically. Also, it would be best if you share the history and the development of black music to your siblings and children to keep the spirit of black music alive even to future generations.
Works cited; https://www.essence.com/ entertainment/what-is-blackmusic-month-june/. https://nationaldaycalendar. com/african-american-musicappreciation-month-june/ https://nmaahc.si.edu/blogpost/celebrating-black-musicmonth WWW.THEPINMAGAZINE.COM
l
119
HISTORY OF JUNETEENTH Juneteenth, also referred to as Emancipation Day, or Freedom Day, or the Black 4th of July, or Cel-Liberation Day, among other terms, is the oldest event in America celebrated nationally to commemorate the coming to an end of the slavery period in the US. The day originates back in June 19, 1865, when Major General Gordon Granger led the Union soldiers to Texas. The Major General had gone to announce the end civil war had ended and deliver the message that the slaves be freed.
A
ccording to history, the message of freedom was delivered in Texas two and a half years after Abraham Lincoln, the-then US president, had officially signed an Emancipation Proclamation long ago on January 1, 1863. Slavery had proceeded in Texas for two and a half more years after it had come to an end in other parts of the US. History states that Lincoln’s Emancipation Proclamation implementation delays in Texas were a result of the inadequacy of Union troops in Texas to implement the Executive Order. The Order was eventually fully enforced in Texas following the surrender of the rebellious General Lee in April that year. The US government then sent an 122
l
adequate number of troops to Texas to enforce the orders and overcome the resistance. After freedom was granted to the slaves of Texas, investigations to determine why the state had not honored the Executive Orders for two and a half years took the course. The investigations resulted in the emergence of several different versions that have been passed down to the other generations. One of the versions is the story of the murder of the messenger while he was on the way to Texas to deliver the message that would see the slaves set free. Another version explains that the orders were deliberately upheld by the enslavers so that they could continue using the THE POWER IS NOW MAGAZINE | JUNE 2020
free labor force in their plantations. The other version explains that federal troops delayed the enforcement of the orders for the enslavers to have one last free labor cotton harvesting before going to Texas to implement the Executive Orders. On the other hand, history also explains that the president’s authority over rebellious Texas was questionable. Conditions in Texas during that time were somewhat different from the statutory conditions in other parts of the US.
Well, let’s get back the freedom day. On that day, June 19, 1865, General Granger’s first Order of business was to read out loud the General Order No. 3 to the people of Texas. The Order read, “The people of Texas are informed that in accordance with a Proclamation from the Executive of the United States, all slaves are free. This involves an absolute equality of rights and rights of property between former masters and slaves, and the connection heretofore existing between them becomes that between employer and hired laborer.” The news was received with a pure shock followed by an immediate round of jubilation. The former slaves knew nothing about an employer-employee relationship, and this was a new thing to them. Everyone started to linger around, trying to learn this new relationship. While this was going on, others fled from their former masters even before they negotiated any relationships. This reaction attests to the kind of life they were facing as laborers in the plantations and the new reality of freedom. The thirst to grasp the first sight of freedom since they came to the US compelled many to leave even without having anywhere to go. The North was considered a suitable destination for many to go as it was away from the plantations. On the other hand, the desire to connect with the family members in the neighboring states forced others to move to Louisiana, Arkansas, and Oklahoma. Moving to these new territories and settling as free US citizens brought a different kind of reality to the black people. They had the responsibility to establish a black American status that never existed amongst the WWW.THEPINMAGAZINE.COM
locals, who were once their oppressors. On a recount of the memories the first day they breathed freedom, the black Americans got motivated to face the pressures they encountered trying to settle in their new territories. Since then, the celebration was encrypted “Juneteenth” and has been commemorated down across all the generations. The Juneteenth then was marked as a time for giving reassurance to each other, a time to pray and a get-together for the family members who survived. The day continued to gather more crowds in Texas tens of years later with many descendants of the former slaves undertaking a pilgrimage to Galveston every year, something that takes place up to date. As time passed, the Juneteenth celebrations started adopting a particular kind of tradition. A range of activities was undertaken to mark the celebrations, some of which continue even in today’s Juneteenth celebrations. Barbecuing, baseball, fishing, rodeos, among others, are some of the common activities during Juneteenth since time immemorial. The celebration also features guests who are invited to address education matters as well as matters concerning self-improvement. Elders are also called upon to give a recount on the past events as a way to pass the information down to the current generation. Prayer services also are among the significant events of the celebrations since long ago. Juneteenth celebrations continue to be commemorated even in the US today and have gained more masses than before. The commemorations were faced with a few challenges in the 20th century, such as the assimilation of the black culture due to the American education system, which did not emphasize the events of slavery. However, in the 21st century, the celebrations have gained more and more masses, as many states and cities have resolved to create Juneteenth committees oversee the commemoration of the day. The future of Juneteenth is now as bright as ever.
Work Cited https://www.juneteenth.com/history.htm l
123
Home Ownership By Eric Lawrence Frazier MBA
Home ownership brings stability to individuals and families who have never had a dwelling place that they could call their own. There is something special about owning real estate that is unlike anything else on earth you can own. Real Estate you own is not like cars that decay over time and you have to replace them. Real Estate you own is not like clothes that go out of style and you have to buy new ones. Real Estate you own is not like expensive vacations or experiences that only last a moment in time. Real Estate you own is not like an apartment where the landlord may increase the rent until it’s no longer affordable. Real Estate you own is not like staying at your parents house where you know can’t stay forever. Home ownership is the beginning of wealth that increases over time and becomes your estate & legacy Home ownership is the pride of a mother nurturer and the kitchen her domain Home ownership is the pride of a father provider and protector of his territory and family. Home ownership is the foundation of permanence and the place where life happens, birthdays celebrated, deaths mourned. Home ownership is the place you build memories that can never be taken from you. Memories etched in walls and concrete, experienced in rooms and floors, Memories living in trees and shrubs planted by your hand. Howe ownership is the manifestation of you - your style, your colors, your smell, your stuff, your junk, your memories, your yard and your spaces, your life. It’s the height markers on your first child’s bedroom wall. It’s the hearts drawn in the concrete slabs when you pour your patio floor It’s the birthday parties, and anniversaries in the living room and kitchen. It’s the back yard barbecue with friends, neighbors and family contentions it’s the high school and college graduation, and wedding receptions Its’ the family nights and block parties and the fellowship of family connections Home ownership It’s more than real estate. Land, brick and mortar, wood frame construction and chicken wire. It’s more than money saved, gifts recieved and grants obtained It’s more than the debt you incur to buy it. It’s more than the payments you make to own it. It’s more than the appreciation that comes with keeping it over time. It’s memories, it’s family, and it’s life that can happen in one place Until you say it’s time to move.