DCi
DRY CARGO
international WWW.DRYCARGOMAG.COM
IS S U E NO. 305 S EPTEM B E R 2 0 2 6
FEATURES Feedstuffs & Grains Trades
Bulker Services
Conveying Technologies
Mobile Harbour Equipment
Grain Materials Handling
Enclosed Storage Systems
The world’s leading and only monthly magazine for the dry bulk industry
CONTENTS
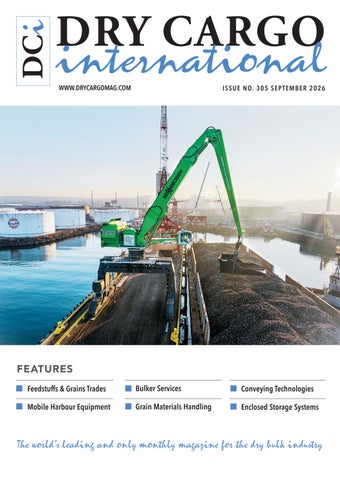
Designed for demanding bulk cargo handling, the electric SENNEBOGEN 895 E at Gateway Terminal in New Haven, Connecticut, offers a 40m reach, sub-one-minute cycle times and low-maintenance operation. Its Green Hybrid energy recovery system reduces energy consumption, while the customized undercarriage ensures efficient handling within the port’s confined working conditions.
DCi
SENNEBOGEN Maschinenfabrik GmbH Hebbelstraße 30 94315 Straubing Germany E: marketing@sennebogen.de W: www.sennebogen.com
jason@dc-int.com
Andrew Hucker-Brown andrew@dc-int.com
EDITORIAL Louise Dodds-Ely
Editor
louise@dc-int.com
Jay Venter
Deputy Editor
editorial@dc-int.com
Samantha Smith
Directories
directories@dc-int.com
Bernice van Wyk
Office Manager
accounts@dc-int.com
SALES Zack Venter sales@dc-int.com
Advertising Sales Manager
CORRESPONDENTS India Europe UK UK UK
Kunal Bose Barry Cross Maria Cappuccio Michael King Richard Scott
ADMINISTRATIVE OFFICE
HEAD OFFICE
Trade Publishing International Ltd does not guarantee the information contained in Dry Cargo International, nor does it accept responsibility for errors or omissions or their consequences. Opinions expressed herein are not necessarily those of Trade Publishing International Ltd
© Trade Publishing Int’l Ltd 2026
featuring... TRADE & COMMODITIES
Growth momentum in dry bulk trade CONFLICTS, ADVERSE WEATHER, HIGH INPUT & VOLATILE ENERGY COSTS IMPACT FEEDSTUFFS OUTLOOK
SHIPPING & TRANSPORT
Electronic evidence is transforming maritime casualty investigations Squeezed out: why dry bulker transits are plummeting at the Panama Canal BEYOND THE FREIGHT RATE: HOW LOADING AND DISCHARGE SHAPE VOYAGE ECONOMICS UPGRADING THE WORKHORSES: PREMIER EQUIPMENT AND TECHNICAL SERVICES FOR DRY BULK SHIPS
PORTS, TERMINALS & LOGISTICS
Another quay at the Port of Gdańsk has a comprehensive upgrade Port of Quequén modernizes dry bulk infrastructure Mechanized shiploading comes to Dhamra Port APSEZ to gain two dry bulk concessions in Paradip Port Asturiana de Fertilizantes battles to stay at Avilés Major new bulk agri-hub at Port of Tilbury opens and welcomes first delivery Declining coal shipments at Duluth-Superior weigh heavily on port tonnage Port of Montreal ships 34-tonne breakbulk cargo to Guyana via CAGEMA Service ArcelorMittal Belgium welcomes the ‘Oceana Frontier’
ENGINEERING & EQUIPMENT
ZEROING IN ON DUST: DUST-SUPPRESSION TECHNOLOGIES COVERING YOUR ASSETS: THE MODERN STANDARD FOR ENCLOSED STORAGE AND HANDLING FEEDING GLOBAL TRADE: OPTIMIZING GRAIN HANDLING OPERATIONS WITH INNOVATIVE EQUIPMENT AGILITY AT SCALE: HOW FLEXIBLE MOBILE SYSTEMS MAXIMIZE EFFICIENCY THE PULSE OF THE PORT: HOW MODERN CONVEYING TECHNOLOGIES KEEP GLOBAL TRADE FLOWING
2 4
13 14 15 18
38 39 39 39 40 40 41 42 43
44 56 66 96 111
DRY CARGO
international
SEPTEMBER 2026
Trade Publishing International Limited Clover House, 24 Drury Road, Colchester, Essex CO2 7UX, UK Tel: +44 (0)1206 562552 Email: info@dc-int.com Website: www.drycargomag.com Twitter: twitter.com/drycargomag ISSN 1466-3643 Insta: www.instagram.com/drycargointernational
SEPTEMBER 2026 issue
www.drycargomag.com
Business Publishing International Corporate Park, 11 Sinembe Crescent La Lucia Ridge, South Africa, 4051 Tel: +27 31 583 4360 Fax: +27 31 566 4502 Email: info@dc-int.com Twitter: twitter.com/drycargomag
WWW.DRYCARGOMAG.COM
DCi
PUBLISHERS Jason Chinnock
DCi 1
BULK CARRIER TRADE & FLEET OUTLOOK
GROWTH MOMENTUM IN DRY BULK TRADE
C
ontinuing signs of support for commodity imports around the world have persisted recently despite some adverse influences restraining cargo volumes. Further growth in global seaborne dry bulk trade during 2026 as a whole and into next year still seems a likely outcome. Global economic growth in the past six months since the Middle East conflict began has proved more resilient than many expectations at the outset. Coupled with other more specific influences, dry bulk trade has benefited. Negative effects on economic activity resulting from the disruption of energy supplies and higher prices for these have been contained, although the impact on individual countries has varied. But prospects for GDP growth remain greatly dependent on geopolitical events.
GRAIN & SOYA
Contrasting with positive influences elsewhere, in several parts of the grain and soya segment potential for a weakening in the 2026/27 year is evident. While soya trade’s upwards trend could continue, imports of wheat and coarse grains into a number of countries could be lower than seen in the previous twelve months, resulting in a reduced overall volume. Forecasts of wheat plus corn and other coarse grains imports published by the US Department of Agriculture last month are shown in table 1, based on a July-June year for wheat and an October–September year for coarse
grains. Following the upturn seen in 2025/26, the year ahead is expected to see reductions in Asia, the Middle East and North Africa. Although European Union imports could rise, global trade in 2026/27 is estimated to decline by 15mt (million tonnes) or 3%, to 453mt.
COAL
Constraints on world energy supplies this year are still providing advantages for coal trade. Among buyers in Asian countries especially, further indications of switching back towards steam coal usage in power stations have been seen. Prospects for major importers China, India, Japan and South Korea are viewed as positive. At the beginning of this year a further annual reduction in China’s seaborne coal imports appeared predictable during 2026, after last year’s large fall. Potential for this outcome has receded. Coal imports into China (including land movements, but mostly seaborne) reportedly totalled 268mt in the first seven months of this year, a rise of 11mt or 4% compared with last year’s same period. Nevertheless, uncertainty about volumes in the remaining months persists.
IRON ORE
Additional iron ore imports into a number of countries seem likely in 2026, resulting in the upwards trend in world seaborne trade continuing. Larger volumes into China, Japan and South Korea among the biggest buyers are foreseeable, while
Europe also may see an upturn. Despite lower steel production, China’s imports have remained buoyant. Crude steel production was 3% lower in the January–July period amid weakness in consumption particularly in the residential property market. Yet iron ore imports in the first seven months rose by 40mt or 6% to reach 737mt. This growth has been explained by high port stocks together with constraints affecting both domestic output of iron ore and usage of scrap in the steel production process.
MINOR BULKS
Seaborne trade in the huge and diversified minor bulks segment is apparently strengthening although variations in performance among individual commodities have been visible. Notably, downwards pressure on fertilizer movements is a contrasting negative influence. But higher volumes of bauxite among other positive commodity changes are expected to provide further support.
BULK CARRIER FLEET
Expansion of the world bulk carrier fleet this year may accelerate as shown in table 2. A growth rate approaching 4% in the twelve months to end-December 2026 mainly reflects estimates of much higher newbuilding deliveries than seen in recent years. Scrapping may remain minimal, offsetting only about a tenth of the new tonnage entering the market.
www.drycargomag.com
TABLE 1: MAJOR GRAIN IMPORTING AREAS (MILLION TONNES) Wheat and coarse grains, crop years ending June (wheat), September (coarse grains) East Asia Southeast Asia European Union Middle East North Africa Sub-Saharan Africa
2021/22 96.5 45.3 26.2 68.5 47.1 30.9
2022/23 89.7 43.2 37.9 64.6 46.0 28.3
source: US Department of Agriculture
*forecast, as at 12 August 2026
2023/24 107.1 52.7 34.3 59.7 53.0 33.3
2024/25* 67.3 51.6 30.9 58.6 54.9 39.0
2025/26* 76.8 59.4 27.1 69.5 63.0 38.2
2026/27* 74.9 58.4 30.9 60.7 55.7 37.6
2025 36.2 5.3 0.2 –0.1 30.6 1,066.3 3.0
2026* 46.0 5.0 0.1 0.0 40.9 1,107.2 3.8
SEPTEMBER 2026
TABLE 2: WORLD BULK CARRIER FLEET (MILLION DEADWEIGHT TONNES)
DCi 2
Newbuilding deliveries Scrapping Losses Other adjustments/conversions Net change in fleet Fleet at end of year % growth from previous year
2021 38.8 5.2 0.1 –0.1 33.4 948.3
2022 32.1 4.3 0.1 0.0 27.7 976.0 2.9
source: Clarksons Research (historical data) & BSA 2026 estimate
2023 35.4 5.4 0.0 –0.1 29.9 1,005.9 3.1
2024 33.8 3.8 0.3 0.1 29.8 1,035.7 3.0
*forecast
by Richard Scott, Bulk Shipping Analysis, Tel: +44 (0)12 7722 5784; Fax: +44 (0)12 7722 5784; e-mail: bulkshipan@aol.com
TRADE & COMMODITIES
Conflicts, adverse weather, high input & volatile energy costs impact feedstuffs outlook in 2026/27
www.drycargomag.com
photo: courtesy of DustCone.
Maria Cappuccio The Middle East conflict is another major shock to a global economy grappling with the lingering effects of recent crises, heightened geopolitical trade tensions and shrinking fiscal space. While a severe global downturn has been avoided, growth
remains subdued and risks substantial. The United Nations (UN) recent assessment of the global economy, forecast growth at 2.6% in 2026 and 2.9% in 2027, less optimistic than at the start of the year. The energy shocks reigniting inflationary
pressures as oil prices soared and remain elevated. In September, the US Federal Reserve raised US interest rates by 0.25%. Conflicts and rising tensions in the Black Sea and Middle East led to a significant uptick for international prices of wheat,
SEPTEMBER 2026
GLOBAL FEEDSTUFFS — PRODUCTION, USE, FEED & STOCKS 2026/27 (MT)
DCi 4
Wheat Coarse grains Total grains Oilseeds
Prod 25/26 844 1,629 2,473 701
Prod 26/27 822 1,588 2,410 723
Use 25/26 824 1,621 2,445 *591
Use 26/27 827 1,615 2,442 *611
Feed 25/26 168 993 1,161 **397
Feed 26/27 165 995 1,160 **403
Trade 25/26 226 259 485 217
Trade 26/27 213 255 468 221
Source: IGC/USDA-Prod major feedstuffs-mainly harvested Jul-Dec/Local Marketing years; *Oilseed crush; **Oil meals feed use-excludes fishmeal
Stocks 25/26 281 332 613 146
Stocks 26/27 276 305 581 146
Experienced ons Agri Inspectio Argentina • Brazil • Parag Paraguay guay • Uruguay
Your glo obal network of ins spection and d analytical l i l services i 21 Sefton Business Park, Aintree, Kingdom Liverpool, Merseyside L30 1RD United K T: +44 (0) 151 525 1488 E: glenn.forbes@alexstewartagriculture.ccom
www.alexstewartagriculture e.com
TRADE & COMMODITIES
corn and soybeans in September. While the rally in prices provides opportunities for farmers to lock in positive margins, those gains are tempered by higher production costs including those for fertilizer and energy. Global harvests for wheat and coarse grains are forecast at 2.41bn/t in 2026/27 reflecting a fall in wheat and sharp fall in coarse grains due to drought and dry weather in parts of the US, EU, Canada, Australia and in other countries. Global oilseed output provisionally seen rising to 723mt (million tonnes) supported by strong demand for biofuels and animal feed.
DROUGHT, WEAK MARGINS REDUCE WHEAT OUTPUT IN 2026/27 Global wheat production is estimated at 822mt. Wheat crops increased in Ukraine 26mt, China 141mt and India 121mt, while weak crop margins and less favourable weather conditions, curbed plantings and yield prospects in key exporting countries. US wheat crop 41mt — lower acreage and persistent droughts across central southern areas, Texas, Oklahoma, western Great Plains, reduced output. US agricultural area continues a long-term shift towards corn, soybean production. Major drought conditions have further limited production prospects with yield reductions and area abandonment, particularly impacting Hard Red Winter wheat. In Canada heat stress, harvest delays, saw wheat output fall to 36mt. Low moisture levels and drought cut winter wheat in the EU134mt and Russia 88mt. In the southern hemisphere, both Argentina 21.5mt and Australia 31mt forecast smaller wheat harvests.
CORN DEMAND TO OUTPACE SUPPLY www.drycargomag.com
DRAWING DOWN COARSE GRAIN STOCKS
Global coarse grain output lower at 1.58bn/t in 2026/27. The 41mt fall in output is due to smaller corn outturns especially in the US 401mt and the EU 50.6mt. With the focus shifting to the growing crops in the southern hemisphere. Current forecasts indicate corn demand will outpace supply in 2026/27, drawing-down global corn stocks.
SOYA , SUNFLOWERSEED, RAPESEED
SEPTEMBER 2026
UNDERPIN RECORD OILSEED OUTPUT 723MT IN 2026/27
DCi 6
For global oilseeds the planted area to rebound due to more favourable margins, relative to competing crops, with production potentially rising to 723mt, a new record. Large soybean crops are anticipated in the US, Brazil and Argentina, together with greater outturn of
GLOBAL WHEAT PRODUCTION 2022/23–2026/27 (MT)
EU UK Other Europe CIS Baltic’s N & C America S America N East Asia Far East Asia Africa Oceanic Total
2022/23 134 17 4 145 83 27 36 276 27 41 790
2023/24 135 14 5 141 86 28 45 285 26 26 791
2024/25 121 11 4 139 92 31 45 295 26 35 799
2025/26 145 14 5 148 96 40 37 296 27 36 844
2026/27 134 12 5 145 80 31 50 301 33 31 822
Source: IGC/USDA-wheat-mainly harvested Jul-Dec/Local Marketing years
GLOBAL WHEAT SUPPLY & DEMAND 2022/23–2026/27 (MT)
Production Consumption Trade Stocks of which China World Key exporters *
2022/23 790 791 218 274 139 135 65
2023/24 791 796 224 270 134 136 64
2024/25 799 808 205 260 128 132 58
2025/26 844 824 226 280 122 158 73
2026/27 822 827 213 276 120 156 63
Sources: IGC, USDA-Production-mainly harvested Jul-Dec/Local marketing years *Argentina, Australia, Canada, US, EU, Kazakhstan, Russia, Ukraine
sunflowerseed in Russia, Ukraine together with large rapeseed crops in the EU and Canada.
EL NIÑO EVENT IN 2026/27 The World Meteorologist Organization (WMO) issued a warning about the prospect of El Niño, forecast to intensify into a very strong event by the end of the year, with cascading impacts on economies and societies. The WMO underlined, when El Niño peaks late in 2026, much of the Southern Hemisphere, southern Africa, South America and Australia will move into their hottest season in the first months of 2027.
SMALLER HARVESTS FOR ARGENTINA , AUSTRALIA IN 2026/27 Buenos Aires Grain Exchange (BAGE) forecast the Argentine crop at 23.4mt (USDA 21.5mt) below last year’s exceptional crop rising global wheat prices, may support some late plantings. Lower planted area in Australia 11.1m/ha in 2026/27 — dry conditions prevail in key areas-fertilizer use depends on cost/availability. Current estimates peg the Australian crop c.31mt, below last year’s crop.
WHEAT FOR FEED USE LOWER AT 165MT Global wheat use is forecast to rise to a
record 827mt in 2026/27. Food/seed/ industry increasing to over 6mt to 657mt with feed use lower at 165mt supported by demand from the intensive animal feed and livestock sectors in China and the Philippines. With total use exceeding production, points to a drawdown in wheat stocks, with tight stocks among key exporters.
STRIKES ON BLACK SEA PORTS HANDICAP EXPORTS
Strikes on Black Sea ports disrupted normal shipping channels. Ukraine’s wheat exports 12.5mt, hampered by Russia’s attacks on the Port of Odessa a key channel for Ukraine’s exports, that remains closed. Russia’s wheat exports 43mt, constrained by damage to its ports, which led to logistic bottlenecks. Without exports, Russian grain accumulated and pressured the domestic market prices, while paradoxically supporting higher international prices. In Sept ‘26, Russian wheat was offered at c.$210mt FOB, however the discount, was more than offset, by additional risks/costs involved in getting the cargoes to buyers.
GLOBAL WHEAT TRADE LOWER AT 213MT Lower global wheat trade due to favourable growing conditions in Morocco and Tunisia and shifts towards self-sufficiency targets
BUILT TO KEEP DRIED DISTILLERY GRAINS MOVING YOUR PARTNER IN PERFORMANCE WWW.E-CRANE.COM
Built for High-Volume Midstream Transfer. E-Crane brings exceptional stability and high-volume performance to demanding midstream transfer operations.&%$#"! &$"& &$ ! " & & ! &#" # & # # & "& $ & & " & $ " & ! $ & & " &! & ! " & ! & " & $#! & # &!$& && "! &! " & & $ # &$ & # & ! & ! "& For Cooper Consolidated, E-Crane developed specially designed 45 m³ grabs to maximize material moved with every cycle& " & # $ !& ! $" & &! $# #! & $ " & ! &! & " & $ # & # &$ ! $"& " & " & " &! & ! & & & & & " " &! $# $#!&! & $ " & " & & # !& & & # !$ & $ #! $"& $ " " & ! ! & ! & " & && " &!$& & # & $& $ " & !& # & $ # ! !
FIND OUT WHAT E-CRANE CAN DO FOR YOUR BUSINESS
TRADE & COMMODITIES
in Algeria. Major wheat importers include Indonesia 12.5mt Egypt 12mt Algeria 8.3mt, Brazil 7.5mt, Philippines 7.1mt Bangladesh 7mt, EU 6.5mt.
BUYERS SWITCH TO ACCESSIBLE WHEAT SUPPLIES
Major exporters quotes rose sharply in Sept ‘26 as Russian quotes fell, due to difficulties shipping via Black Sea ports, that remain closed. In September, buyers switched to wheat exports more accessible to the market. SovEcon estimated Russia’s shipments at 1.8mt versus 4.6mt last year.
GLOBAL WHEAT STOCKS FALL TO 276MT IN 2026/27 Global wheat stocks total 276mt (World 156mt China 120mt) with key exporters wheat stocks, lower by 10mt to c.63mt in 2026/27
GLOBAL PRICES REMAIN FIRM
GLOBAL COARSE GRAIN SUPPLY AND DEMAND 2022/23-2026/27 (MT)
Production Consumption Trade Stocks of which China: Key exporters*
2022/23 1,458 1,463 221 336 207 74
2023/24 1,508 1,499 242 345 213 88
2024/25 1,517 1,538 232 324 193 75
2025/26 1,629 1,621 263 333 178 90
2026/27 1,588 1,615 254 305 166 89
Source: IGC/USDA * US, Argentina, Brazil, Russia, Ukraine, EU, Australia, Canada
GLOBAL CORN SUPPLY & DEMAND 2022/23–2026/27 (MT)
Production Consumption Trade Stocks of which China: Key exporters*
2022/23 1,166 1,175 181 304 206 48
2023/24 1,232 1,222 197 314 211 54
2024/25 1,235 1,253 191 296 192 52
2025/26 1,331 1,325 211 301 177 68
2026/27 1,291 1,320 211 272 165 64
Source: IGC/USDA * Argentina, Brazil, Ukraine, US
In export markets Argentine Grade 2 Up River $252/t FOB [free on board] (18/09/26), EU France Grade 1 (Rouen) $283/t FOB (18/09/26). US SRW $299/t FOB (18/09/26). US HRW $345/t FOB (18/09/26). Nearby premiums remain firm — as importers fill gaps left by halted Black Sea logistics. Algeria’s latest tender 600,000mt c.$320/t CIF (cost, insurance, freight) (18/09/26). Argentina’s winter wheat harvest wraps up in the October to December period and later in the south. New crop supplies are expected to soften FOB values — Argentine CIF landed price for 11.5% milling wheat maintains a competitive edge over other origins on trade to Southeast Asia.
SEPTEMBER 2026
www.drycargomag.com
COARSE GRAINS OUTPUT LOWER IN 2026/27
DCi 8
Following a record outturn last year, coarse grain output is forecast to fall to 1.59bn/t in the current season-the decline in output is largely driven by lower corn production. Despite large crops in China 316mt, Ukraine 39mt and Canada 31mt. Global coarse grains are forecast below last year’s record crop. In the US, higher input costs for corn, saw acres switch to soybeans, this led to a drop in corn output from last year’s record crop to 413mt. In the EU widespread drought seriously affected and reduced output to 131mt.
SMALL INCREASE FOR FEED USE IN 2026/27 Global demand for coarse grains indicates a small increase in feed use to 995mt and fall in food/industry use to 620mt.
COARSE GRAINS STOCKS FALL TO 305MT IN 2026/27 Global corn and sorghum stocks lower, small increase for barley. (World 139mt China 166mt).
LARGE GLOBAL CORN CROP ANTICIPATED IN 2026/27 Despite weather and other challenges global corn output is forecast at 1.29bn/t, boosted by a huge US crop c.401mt, EU 50mt, Ukraine 25mt, and record crop in China 307mt. Provisional estimates for the southern hemisphere crops in Brazil 139mt and Argentina 55mt.
SOUTH AMERICAN CORN PLANTINGS IN 2026/27 Weather is the major focus in Brazil and Argentina this season, with the prospect of an unusual El Niño weather pattern developing later this year and its potential impact on South American corn crops —provisional forecast for Argentina c.64mt, Brazil c.147mt in 2026/27.
US DIESEL PRICES FORECAST TO RISE US Energy Dept, raised its forecast for US diesel prices next year due to the Middle East conflict as tight global supplies keep
domestic inventories unusually low. Higher fuel costs affect truck, rail, barge and ocean freight markets, creating uncertainties, and are not reflected in routine forecasts.
HIGHER DOMESTIC CROPS PRESSURE TRADE IN 2026/27 Coarse grain exports are forecast 5mt lower at 254mt. Exports are partially counterbalanced by higher domestic output in several countries in Sub-Saharan Africa. EU imports rising to 24mt due to unfavourable weather, with imports to Mexico 28mt, China 25mt Egypt 13mt,
CORN ACREAGE RISES IN ARGENTINA AND BRAZIL Argentina sowings began in early September with corn gaining acreage in some central regions due to better profit margins. Northern areas have seen the spread of corn leafhopper pest, causing some acreage to pivot from corn towards soya-which is immune to the pest. The Rosario Grain Exchange raised its corn forecast to 67.5-70.5mt for 2026/27 (USDA 55mt).
Brakkes, Couplings and Components info@sibre.de | www.ssibre.de SIBRE Siegerland Bremsen GmbH | Auuf der Stücke 1 - 5 | 35708 Haiger - (Germaany)
TRADE & COMMODITIES
Vietnam16mt and to some other countries.
TRADE & COMMODITIES
BRAZIL’S CORN PLANTINGS 23.7M/HA IN 2026/27 The planting of Brazil’s first corn crop has begun according to Conab. Sowing remains concentrated in southern Brazil, with Rio Grande do Sul leading field operations. Total corn plantings are projected to rise on 23.7m/ha in 2026/27, production 148mt (USDA 139mt). Brazil’s farmers remain concerned about high fertilizer costs and potential impact from El Niño on the Safrinha crop.
MINIMAL RISE IN FEED, FOOD/INDUSTRY USE LOWER IN 2026/27
Tight global corn stocks in 2026/27 are set
2024/25 687 428 569 376 111 213 144 74
2025/26 701 429 592 397 115 217 146 74
2026/27 723 442 611 409 120 221 146 74
Source: USDA/*Meals cons/trade-excl. fishmeal **Argentina, Brazil
With a rise in the harvested area, barley production is forecast at 161mt in 2026/27. Increased output in Canada 10mt and Australia17.1mt, Ukraine 6.6mt, Turkey 8.8mt, and in other countries offset lower output in other countries. Feed use is higher at 110mt, food/industry 48mt. Greater uptake of barley seen in Australia, Russia, Morocco, Syria, Turkey, and in other countries. Global feed barley FOB export prices are currently trading in a competitive range of $210-$235mt. Regional availability from Australia and Canada cap upside price potential set against localized feed deficits in some areas in Europe.
KEY EXPORTERS CORN STOCKS FALL TO 64MT
www.drycargomag.com
2023/24 658 396 543 361 103 205 136 66
US YELLOW CORN (3YC) GULF FOB $251.28
Corn trade at 211mt is expected to be unchanged from the previous year. Corn export prices — Brazil (Santos/Paranaguá) $237mt, US 2YC FOB Nola PNW $260mt (18 Sept ’26).
SEPTEMBER 2026
2022/23 637 378 524 350 95 202 123 64
to fall by 29mt to 272mt (world 107mt, China 165mt).
CORN TRADE AND STOCKS
10
Production of which (soybeans) Crush Consumption meals* Trade meals* Trade seeds Stocks of which (soybeans) key exporters**
Global corn consumption is forecast lower at 1.320bn/t. A minimal increase is expected in global feed use (827mt) with food/industry use lower at (493mt).
With the US harvest season under way, farmers are seeing higher commodity prices. However, those gains are countered by record-high diesel prices, which in the US hit a retail average of $6.52/gallon. US corn Futures are likely to fall in late September as the market positions itself ahead of President Donald Trump’s meeting with China’s President Xi Jinping. US farmers hopeful, the meeting will unlock China’s market for US grains.
DCi
WORLD — MAJOR OILSEED SUPPLY & DEMAND 2022/23–2026/27 (MT)
RISING BARLEY OUTPUT 161MT IN 2026/27
BARLEY EXPORTS LOWER AT 31.8MT Severe rain and heat in key areas in China’s corn belt forced a heavier reliance on alternative feed grain imports to support livestock operations in 2026/27. USDA anticipates China’s barley import demand
at 13mt in 2026/27. Australia has the dual advantage of proximity and freight. Barley imports into other areas include, Saudi Arabia 4.7mt, Iran 2.5mt, Japan 1.1mt and Brazil 0.9mt. Argentine feed barley (Up River) fob $235/t (15 Sept ‘26); France (Rouen) fob $230mt (15 Sept ‘26 ).
SORGHUM OUTPUT FALLS TO 61MT IN 2026/27 Most of the downturn reflects a sharp fall in the US 7.2mt — tight crop margins will curb sowings, Brazil 6.5mt partially offset by increased output in Nigeria 7mt and India 4.7mt.
EMBRAPA PREDICTS RISING SORGHUM OUTPUT IN BRAZIL China imports of 6.3mt for the feed industry-pig/poultry and for baijiu (a national spirit beverage). In November ‘25, Beijing authorized ten Brazilian facilities concentrated in Mato Grosso, Minas Gerais, Rondônia and Bahia to export sorghum to China. Embrapa predicts Brazil’s sorghum production will double to 15mt over the next decade, utilizing fields that previously sat fallow between summer
Grain handling operations (photo: RIKON).
Rugged Energy & Data Transmission Systems Motor Driven Reels • Monospiral and Level-Wind configurations • Rugged and dependable magnetic coupler for dusty environments
Cable Festoon • Corrosion-resistant, long-life rollers; precision sealed bearings • Systems customized for the application • Preassembled option, for easy installation
Conductix-Wampfler has one critical mission: To keep your bulk material handling operations running 24 / 7 / 365. You need proven, worryfree energy solutions - and Conductix-Wampfler has them. Our systems provide reliable electric power and water to stacker/reclaimers, barge and ship loaders/unloaders, bulk conveyors, tripper systems, and gantry cranes. Conductix-Wampfler systems are rugged, low maintenance, and timetested in tough, dusty environments. All products are backed by the largest sales and service network worldwide! www.conductix.com
Slip Rings • Allow infinite rotation • Combined power, control and media (water, air, oil, vacuum, other) • Available with ATEX and SIL 3 certification
TRADE & COMMODITIES
soybean cycles. In the US, sorghum is used for feed/ethanol use. Global sorghum exports are 8.2mt. Major exporters include the US 4mt, Argentina 1.5mt and Australia 2mt. Sorghum values, like other coarse grains have increased — Texas Gulf FOB $266.42 (15 Sept ‘26).
photo: VIGAN
GLOBAL MEAT OUTPUT RISES TO 391MT IN 2026 Global meat production growth is expected to moderate in 2026. The conflict in the Near East raised energy, fertilizer and other input costs, including feed, that weigh on producers’ margins, though a resolution of the conflict, may gradually ease these pressures. Poultry meat (160.3mt) rising on strong global demand and affordability. Pig meat (129.5mt) is set to rise modestly supported by firm demand and productivity improvements — offset by sow herd contraction in China. Persistent disease adds uncertainty — African Swine Fever (ASF) poses ongoing production risks, while foot-and-mouth (FMD) diseaseserotype SAT1, is spreading beyond Africa with outbreaks in Europe, Asia, and threatens pig, cattle, and small ruminant sectors. Beef meat production (76.9mt) is anticipated to decline — ongoing herd rebuilding in major producing countries is constraining cattle supplies, limiting slaughter availability. Similarly, Sheep meat production (18.3mt), due to a sharp contraction in Australia-flock rebuilding curtails slaughter rates.
year, creates further uncertainty this season.
RECORD CRUSH FOR FOOD, FEED AND FUEL Oilseed crushings seen rising to 611mt in 2026/27, with production of oilmeals for animal feed 409mt, vegetable oils 245mt — increases noted for rapeseed, sunflowerseed and soybeans. Canada’s oilseed processing capacity is rapidly expanding, driven by rising global demand for oilmeals for livestock feed and vegetable oil, for renewable biofuels.
MID-EAST CONFLICT PROMPTS BIOFUELS
SEPTEMBER 2026
www.drycargomag.com
RECORD 723MT GLOBAL OILSEED CROP IN PROSPECT 2026/27
DCi 12
Global oilseed output, is driven by soybeans 442mt, rapeseed 100mt, sunflowerseed 63mt with smaller crops for peanuts 51mt, cottonseed 39mt, palm kernel 21mt and copra 6mt.
RECORD SOYBEAN CROP 442MT IN 2026/27 Brazil’s soybean planted area increased to 49.2m/ha with crop output forecast at 183mt (CONAB) 186mt (USDA); Argentina 50mt, Paraguay 11mt. The increase for Brazil crop, to support a rise in exports and increased use. Paraná, Mato Grosso and São Paulo began the 2026/27 soybean season, planting progress remains limited. Weather concerns in Mato Grosso and Paraná continue to be monitored for risks to crop development. For Brazil’s farmers, more expensive crop inputs (fertilizers), high borrowing costs, rising domestic demand, together with weather warnings for an unusual El Niño later in the
EXPANSION
Given the uncertainty surrounding the conflict, as input costs rise across the agricultural complex, prompts further expansion/development of alternative biofuels. Rising global biofuel mandates are expected to drive demand for soybeans and rapeseed, supporting prices.
($735m) in the development of a lowcarbon fuels industry, was welcomed by farm groups, who hope it will boost demand for biofuel feedstocks like canola, sugarcane, sorghum and tallow.
CHINA TURNS TO ARGENTINA FOR SOY SUPPLIES
Driven by strong domestic demand to feed their large livestock, aquaculture industries, as well as for use in their food industry, China locked-in soybean supply before the year-end with South American supplies. Brazil had difficulty expanding exports in the fourth-quarter due to robust crushing to meet domestic demand — Argentina stepped-in with soybean sales to China, that have accelerated during the last quarter of 2026.
OILSEEDS STOCKS UNCHANGED AT 146MT With greater output and increased use, oilseed stocks remain c.146mt in 2026/27.
EPA TO INCREASE RENEWABLE VOLUME OBLIGATIONS (RVO’S)
ROBUST DEMAND UNDERPINS SOYBEAN
The US Environmental Protection Agency’s (EPA) proposed Renewable Volume Obligations (RVO), is expected to support US prices in 2026 and 2027. The multi-year rise to 25.82bn (2026) and 25.98bn ( 2027) guarantees a reliable, growing market for US farmers. Soybean oil, corn-based ethanol and alternative cover crops camelina (False Flax) and carinata (Ethiopian kale) likely to see sustained demand to meet the billiongallon mandates. In September, the Australian government said it would invest A$1.1Bn
The broader oilseed market experiencing high volatility, riding on a strong rally that recently pushed up prices month-onmonth. With the US soybean harvest beginning, global futures indicate an upward trajectory in 2027. USDA recently revised its season-average price to $12/bu due to aggressive international buying. Brazilian export prices command a premium over Argentine origin, supported by tight spot availability and strong demand. Brazil (Paranaguá) FOB is $540mt Argentina (Rosario) FOB $369mt, US DCi (Gulf) FOB $530mt (16 Sept ‘26).
PRICES
N
gathering for prosecution, the P&I perspective, average adjustment and evidence in the Admiralty and Commercial Court. It also examines the opportunities and risks associated with artificial intelligence. The publication stresses the need for material generated or supported by AI to be verified rather than accepted without professional scrutiny. A further theme is the role of just culture in casualty investigation. The guidance argues that effective learning depends on maritime professionals being able to provide safety-related information openly and fairly, while recognizing systemic factors as well as individual actions.
The foreword is written by Marius Schønberg MSc, Vice President, Head of Loss Prevention at Gard AS. He emphasizes that effective evidence collection has value beyond establishing liability, helping the industry identify technical, operational and human causes and use those lessons to reduce future risk. Guidelines for Collecting Maritime Evidence, Volume 2 – Second edition is an essential companion to Volume 1 and is intended for seafarers, Masters and senior officers, shore-based ship managers, insurers, average adjusters and legal professionals. The publication will be available in paperback and ebook formats.
SHIPPING & TRANSPORT
ew edition of Guidelines for Collecting Maritime Evidence Volume 2 addresses electronic records, AI, digital reconstruction and the changing responsibilities of maritime professionals. The Nautical Institute is highlighting the growing importance of electronic evidence following maritime accidents and incidents as modern ships generate more data and complex records of their operation. The forthcoming second edition of Guidelines for Collecting Maritime Evidence, Volume 2 examines how evidence from onboard systems should be identified, recovered and preserved, and how it can be used to understand the circumstances surrounding a maritime casualty. Originally published in 2019, the updated edition reflects the rapid development of onboard technology and the changing duties, responsibilities and risks faced by Masters, officers, crew and ship managers when an incident occurs. The increasing availability of digital information provides investigators with opportunities that would have been unavailable to previous generations, but it also creates new challenges. Simon Daniels PhD AFNI, Technical Editor of Guidelines for Collecting Maritime Evidence, Volume 2, said: “Ships now produce an extraordinary amount of digital information, but having more data available does not automatically mean that the circumstances of an incident will be easier to understand. “The quality of an investigation still depends on knowing where relevant evidence may be found, acting quickly enough to preserve it and understanding the limitations of the systems that produced it. “For Masters and officers, this is increasingly important professional knowledge. The records created by modern shipboard technology can play a significant role in reconstructing an incident and understanding the decisions that were taken.” The second edition brings together expertise from across the maritime, technical, insurance and legal communities. Subjects include electronic evidence recovery, evidence following fires and machinery failures, cargo deterioration, digital tools and ethics, visual reconstruction and analysis, evidence
NEWS
Electronic evidence is transforming maritime casualty investigations, says The Nautical Institute
DSM Shipbrokers Floating bulk handling cranes
STS loading coal, bauxite, ore ? Call us for bulk handling floating cranes on the 2nd hand market or new built floating lemniscate cranes, built for proven long lifecycle and 24/7/365 operations !
DSM Shipbrokers Specialised brokers on the 2nd hand market for bulkers, barges & floating cranes
Netherlands www.shiptrade.nl tel +31-646-222111