FLOOD INSURANCE
Rising Risks, New Solutions and Expanding Opportunities
Key Takeaways
Flooding is the most common and costly natural disaster in the United States, with an estimated 83% of flood losses
uninsured.
Recurring NFIP disruptions create operational challenges and reinforce the need to evaluate private Flood Insurance alternatives.
Private market capacity across Primary and Excess Flood Insurance has expanded, offering higher limits and greater structural flexibility.
Parametric Flood solutions provide liquidity tied to measurable flood events, addressing economic impacts that traditional policies may not fully capture.
Portfolio-level review and data-driven analytics are becoming essential tools in long-term Flood Insurance planning.
Burns & Wilcox and Floodbase have partnered to launch an exclusive Parametric Flood solution designed to complement Primary and Excess Flood Insurance by addressing exposures such as business interruption, loss of access, and claims timing through rapid, trigger-based payouts.
Introduction
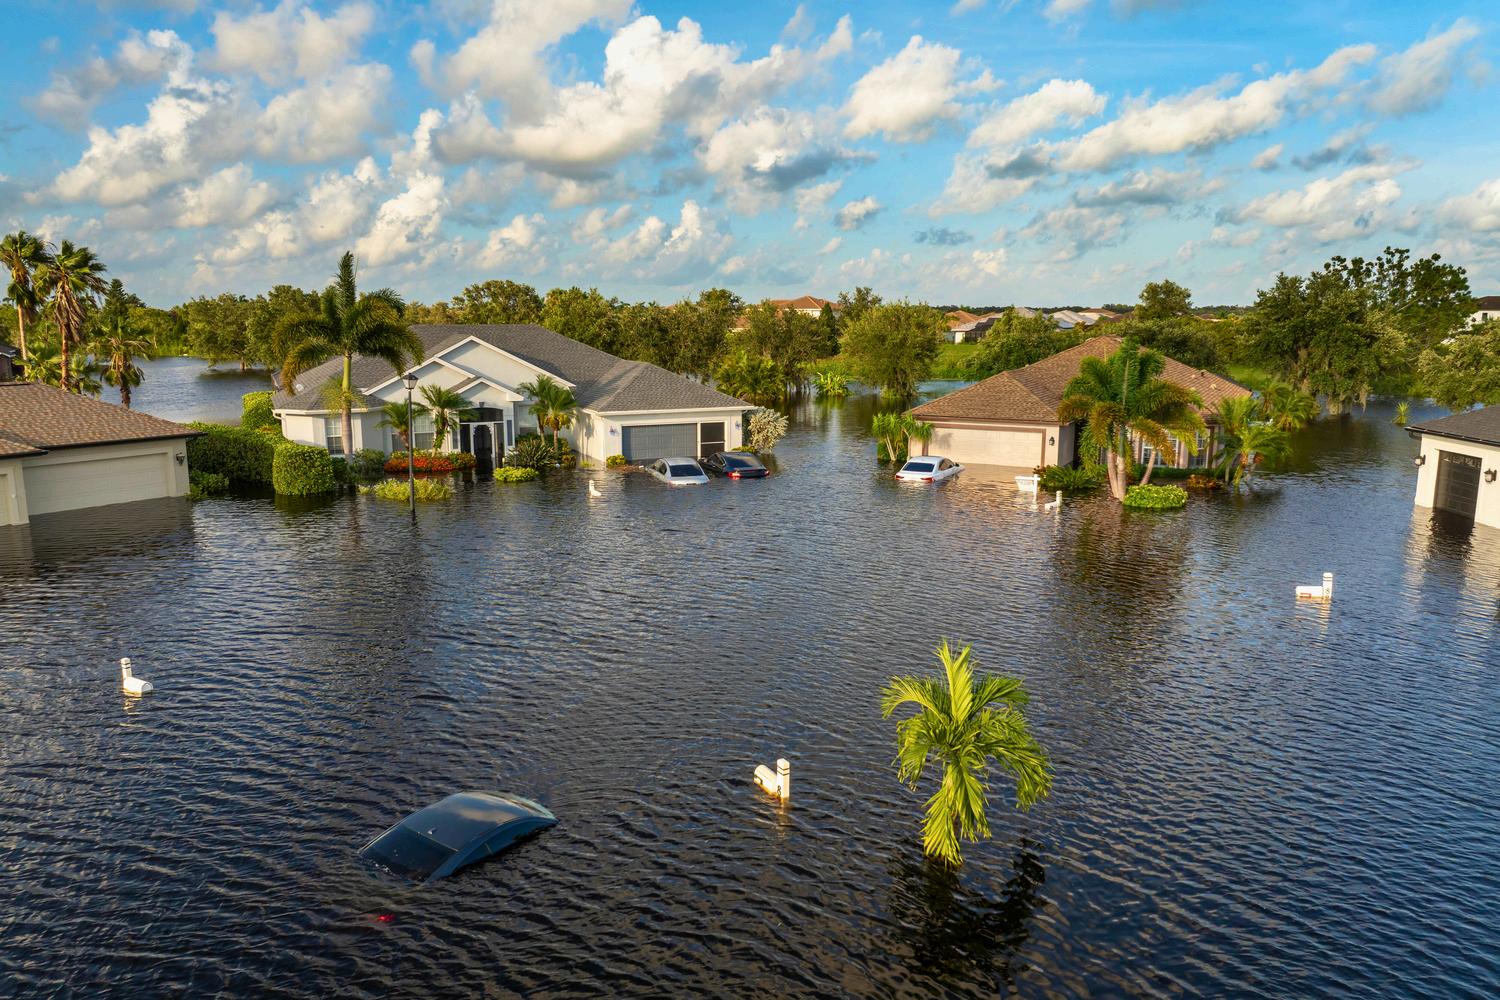
Flood events remain the most common and costly natural disaster in the United States, affecting residential and commercial properties well beyond designated flood zones. As loss frequency and severity increase, the need for comprehensive Flood Insurance solutions has become more urgent.
Despite this exposure, an estimated 83% of flood-related losses remain uninsured, underscoring the scale of the protection gap.
At the same time, recurring disruptions to the National Flood Insurance Program (NFIP) have created uncertainty for brokers, agents, and property owners, reinforcing the importance of private market alternatives. As capacity expands across Primary, Excess, and Parametric Flood Insurance, brokers and agents have greater flexibility to address evolving flood exposures and close coverage gaps.
Navigating NFIP Disruptions
Interruptions to the NFIP can create immediate operational challenges. When lapses occur, new policies cannot be issued, renewals may be delayed, and real estate transactions can stall. This disruption often occurs at critical moments in the insurance placement process.
Even outside of lapse periods, the NFIP operates within defined structural limits. Coverage caps, limited flexibility, and constraints around certain exposures may not align with the needs of higher-value residential properties, complex commercial risks, or multi-location portfolios.
These realities highlight the importance of understanding alternative Flood Insurance options. Rather than relying exclusively on a single government program, brokers and agents are increasingly evaluating where private Flood Insurance may offer broader and more comprehensive protection.
Private Market Expansion
Private Flood Insurance capacity has expanded significantly in recent years, supported by improved catastrophe modeling, refined underwriting discipline, and increased participation within the Excess & Surplus (E&S) market. What was once viewed as a limited alternative to the NFIP has become a more established segment of the flood marketplace.
Primary Flood Insurance solutions now offer higher limits and greater flexibility than traditional federal options. Excess Flood Insurance has also become more accessible, allowing layered programs for higher-value residential properties, commercial risks, and multi-location portfolios.
Portfolio Strategy
As placement options expand, portfolio-level strategy is becoming more central to Flood Insurance planning. Rather than evaluating risks individually, brokers and agents are increasingly reviewing entire books of flood business to identify opportunities for consolidation, excess layering, or private market placement.
Data-driven modeling and multi-property analytics allow for evaluation of exposure concentration, limit adequacy, and overall program structure. This broader view can improve efficiency and placement outcomes, particularly for high-value residential properties, commercial schedules, and multi-location risks.
Expanded capacity combined with portfolio-level analytics is broadening the range of available solutions—especially for risks that exceed NFIP limits or require more customized structures.
Parametric Flood Solutions
NEW EXCLUSIVE SOLUTION AVAILABLE
Burns & Wilcox recently introduced an exclusive Parametric Flood solution in partnership with Atain Insurance Companies, an “A” rated carrier, and Floodbase, the leading AI-powered flood monitoring platform. The program incorporates consistent data from public and commercial satellites, IoT and stream gauges, meteorological information, on-theground sensors, and other verified sources to establish objective, clientspecific parametric triggers.
It is designed to address wider-area economic risk and exposures such as:
Non-damage business interruption
Loss of access
High deductibles
Policy exclusions and limitations
Claims timing
As part of this program, Floodbase provides near-real-time monitoring to determine when flood events occur. Parametric Flood coverage is triggered when a predefined, locationspecific flood parameter is met within a selected geographic boundary, based on verified data inputs such as satellite-observed water inundation or ground-level IoT sensor readings.
New Exclusive Solutio
Once the selected threshold is reached, payment is validated through Floodbase event data and delivered without a traditional adjustment process. Because payouts are tied to measurable event conditions rather than physical damage assessments, funds are typically issued more quickly and may be used at the policyholder’s discretion.
The solution is designed for non-Tier 1 areas and can be applied across a broad range of risks, including:
Scheduled commercial property
Cannabis
Transportation
Municipalities
Golf courses
Amusement parks
Restaurant chains
Retail stores
Hospitals
Real estate portfolios
Other wide-area or multilocation exposures
Formore information regarding the Floodbase Parametric solution, please contact theBurns & Wilcox Flood Practice Group at flood@burns-wilcox.com
Tips for Brokers Agents
As flood risk and placement options expand, a proactive approach can help brokers and agents manage disruption and identify opportunities.
#1 Review NFIP portfolios proactively.
Identify accounts that may be affected by program disruptions or constrained by NFIP coverage limits.
#2 Reassess limits and structure.
Evaluate whether Primary and Excess Flood Insurance placements align with current property values and exposure profiles.
#4 Consider Parametric Flood solutions.
For multi-location risks or properties with operational dependencies, Parametric Flood coverage can complement traditional placements by providing liquidity tied to measurable flood events.
#3 Address economic loss exposure.
Determine where business interruption, loss of access, or wide-area impacts may require solutions beyond traditional Flood Insurance.
#5 Use portfolio-level analytics.
Leverage data-driven modeling to assess exposure concentration and identify consolidation or layering opportunities across books of business.
Flood risk continues to challenge property owners and the brokers and agents who serve them. NFIP disruptions, evolving exposure profiles, and expanding economic losses are reshaping how Flood Insurance is structured.
As Primary, Excess, and Parametric Flood Insurance capacity expands within the E&S market, brokers and agents have greater flexibility to respond with tailored solutions—creating expanded opportunities to close coverage gaps and strengthen overall flood programs.
Contributors
Bill Gatewood
Executive Vice President
Personal Insurance
Burns & Wilcox
Detroit/Farmington Hills, MI
Brad Turner
Click here for contact details > Vice President
National Product Manager, Flood
Burns & Wilcox
Morehead City, NC
Click here for contact details >
Jacob Martin
Jacob Martin
Director, Flood
Burns & Wilcox
Charlotte, NC
Click here for contact details >
Bessie Schwarz
Special Guest Co-Founder and CEO Floodbase
This commentary is intended to provide a general overview of the issues contained herein and is not intended, nor should it be construed, to provide legal or regulatory advice or guidance. If you have questions or issues of a specific nature, you should consult with your own risk, legal, and compliance teams.