MARKET 2025: A RECORD-BREAKING YEAR AND STEADY GROWTH
The year 2025 was arguably a record-breaking one for the Cypriot residential real estate market. According to data from the Department of Lands and Surveys, 14,717 residential property transactions were registered between January and December 2025.
The total volume of sales of all types of real estate (including new buildings, resale, commercial, and land plots) reached 37,418 purchase and sale agreements, which is 7% higher than in 2024. This figure was the highest in the last decade.
Quarterly Dynamics Within the Year
Throughout 2025, market activity was unevenly distributed. The first quarter (January–March) brought 3,035 transactions, the second quarter (April–June) 3,604, and the third quarter (July–September) 3,620. The highest volume was achieved in the fourth quarter (October–December) with 4,458 transactions. Traditionally, December is the month of greatest activity: an analysis of monthly coefficients shows that December accounts for 27% more transactions than the monthly average for the year. It is worth noting that this figure is likely to be adjusted slightly in subsequent reports. This adjustment is more related to the specifics of transaction registration in Cyprus (such as the practice of deferring signings to the year-end or technical lags in the system) than to a dramatic, last-minute surge in buyer activity. Nevertheless, the underlying trend of a strong fourth quarter remains indisputable.
Regions: Growth Leaders and Volumes
Based on the full-year results of 2025 compared to 2024, Larnaca and Nicosia showed the fastest growth. Limassol remains the country's largest market, but growth of the number of sales here has practically stalled (+1%), indicating saturation following the previous boom.
In the fourth quarter of 2025, the absolute leaders in the number
of transactions were Pafos and Larnaca, followed by Limassol. The total value of property sold in the fourth quarter reached €1.27 billion, the highest quarterly figure of the year.
New Developments Dominate
The share of primary housing remains high. In 2025, new developments accounted for 9,651 transactions – 66% of the total. The resale market accounted for 5,066 transactions. Regional differences are significant: in Limassol, new builds make up 74% of the market, in Larnaca 69%, while in Pafos and Famagusta their share is lower, at around 54%.
The Mid- and High-range Segments* – The Main Driver
The mid- and high-range price segments (houses priced from €500,000, apartments from €200,000) continue to grow steadily. In 2025, 5,597 transactions were concluded in these segments, representing 38% of the total market volume. Apartments in these segments were sold almost seven times more frequently than houses: 4,884 transactions compared to 713.
The annual dynamics (2025 vs 2024) in these segments were +38% for houses and +14% for apartments.
The distribution of transactions in the mid- and high-range segments is as follows:
• Limassol is the absolute leader in the share of transactions in the mid- and high-range segments (69% of all city transactions), with 94% of these being apartments.
• Pafos – 37% of transactions (houses priced from €500,000, apartments from €200,000), with houses and apartments represented almost equally (403 and 848 transactions respectively).
• Larnaca and Nicosia – around a quarter of transactions in the midand high-range segments, with a clear predominance of apartments.
• Famagusta – 18% of transactions, predominantly apartments.
Price Dynamics: Moderate Growth and Correction
Median prices for the full year 2025 (Q4 2024 – Q4 2025) showed moderate growth: +4% for houses and +1% for apartments compared to 2024. The median price is the price of the "middle property." If you line up all the sold properties in a row from the cheapest to the most expensive, the median price will be exactly in the middle: half of the properties are sold for less than this price, and half for more. Unlike the
*Mid- and high-range residential segments - apartments priced from €200,000 and houses from €500.000
ABOUT INSIGHTS:
Transaction data are provided by Cyprus’ Department of Lands and Surveys, which records all transfers of ownership and registered contracts of sale (including property description, purchase price, date, etc). The data is processed in order to classify each transaction (as some properties are under construction, their description is not exact, or they form part of bigger projects) and are categorised by property type.
The analysis covers the entire area controlled by the Republic of Cyprus, excludes properties sold at auction (foreclosure), and references property values based on the amount declared by the purchaser at the time of the transaction (which excludes any VAT, transfer fees, or other duties levied).
average price, which can be heavily influenced by a few very expensive transactions, the median shows the real "center of the market" and more accurately reflects what a typical property actually costs.
Main Conclusion
The Cypriot residential real estate market is entering a more mature phase of development. With an overall annual growth rate (all transactions in Cyprus) of 7% referring to the total sales volume of all real estate types in Cyprus (including new builds, resale properties, commercial assets, and land plots) and moderate price increases, the key driver remains the premium segment, where buyer activity is growing at an accelerated pace. Regional differentiation is increasing, and buyers are becoming more demanding regarding quality and location. The high level of activity in the second half of 2025, reinforced by the traditional December peak, creates a solid foundation for sustainable development in 2026.
Thank you for your trust and interest in our analysis of the Republic of Cyprus residential real estate market.
Stay connected,
Anastasia Yianni
Chief Executive Officer
Cyprus Sotheby’s International Realty
5 Bedroom Villa
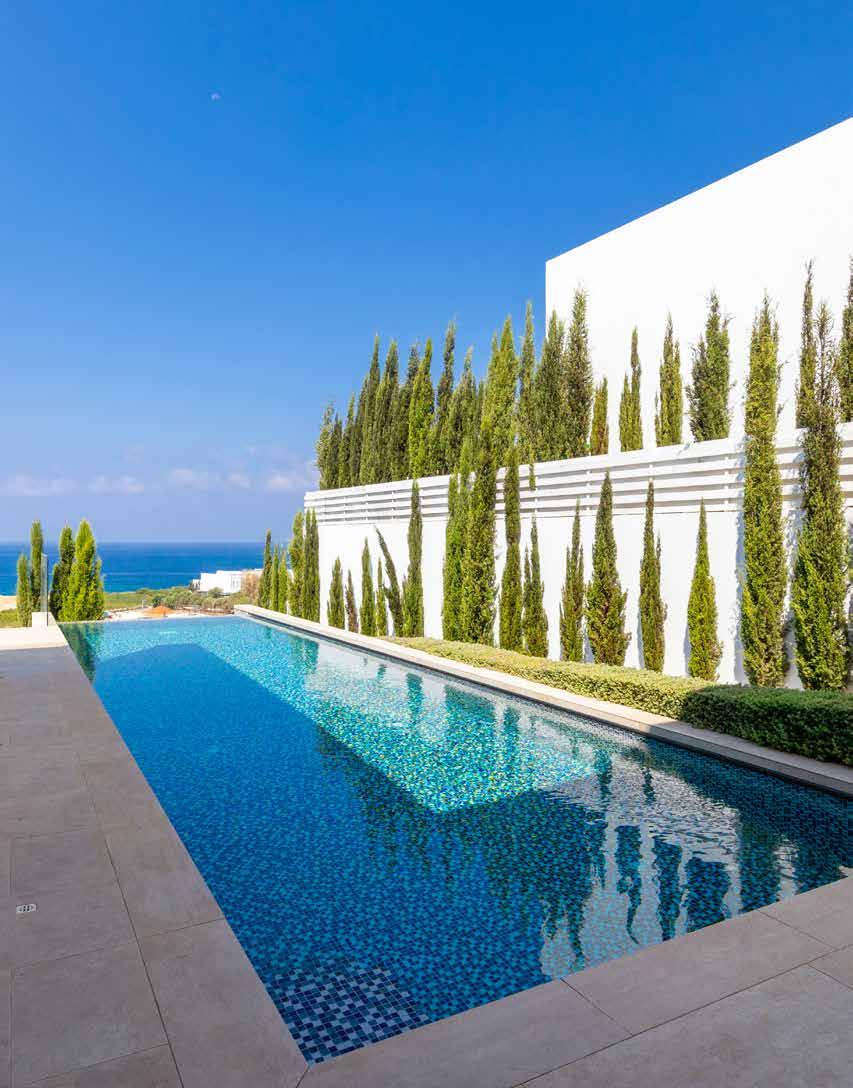
Three minutes on foot to the beach and one of Cyprus's top five-star resorts. The best part: your own five-bedroom villa (private pool, 830 m² plot, sunset views) plus full access to everything the resort offers. Restaurants, spa, gym, even babysitters or a private chef if you need them. Two bedrooms on the ground floor, three upstairs. 280 m², floor-to-ceiling windows, underfloor heating. Resort amenities, your own space.
Pegeia, Pafos
ID: p31800
MARKET INSIGHTS Q4 2025
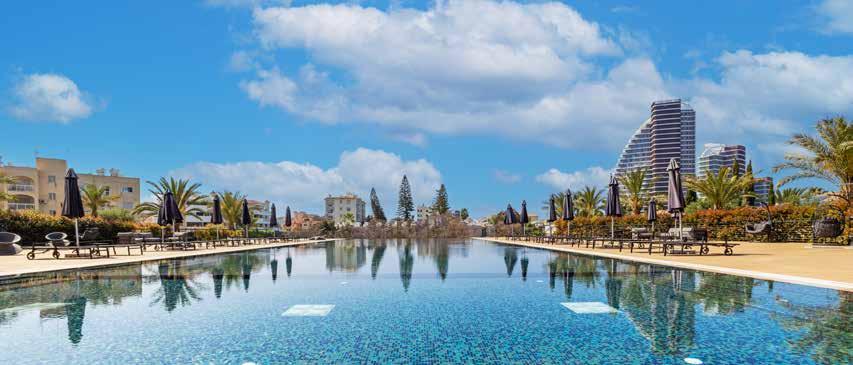
CYPRUS RESIDENTIAL REAL ESTATE MARKET: TRANSITION TOWARD STABILITY AND STRUCTURAL MATURITY
The Cypriot residential real estate market entered 2025 in a phase of structural transition, characterised by a recovery in transaction activity alongside increasingly stable pricing dynamics. Following a temporary slowdown in the final quarter of 2024, transaction volumes rebounded strongly in Q4 2025, producing elevated year-on-year growth rates in both the house and apartment segments. These increases reflect renewed market momentum, while also highlighting the cyclical nature of demand across the year.
When viewed across the full annual period, however, the market demonstrates a more measured and sustainable trajectory. Transaction volumes expanded at a moderate pace, while price movements remained largely stable. This indicates that the market is shifting away from the rapid and uneven growth patterns seen in previous years and entering a more balanced phase driven by end-user demand and long-term residential positioning.
The high and mid-range segment continues to define market structure, accounting for a substantial share of transaction value and activity across key regions. Limassol remains the island’s primary premium residential hub, supported by its international buyer base and established infrastructure. At the same time, Pafos has strengthened its position significantly, particularly in the villa segment, reflecting evolving buyer preferences and increased confidence in the region’s long-term residential potential.
Other regions demonstrate steady and consistent development. Larnaca continues to gain importance as infrastructure investment and urban regeneration enhance its residential appeal. Nicosia remains a stable and predominantly domestic market, while Famagusta continues to represent a smaller but active segment with selective demand.
Median price movements across Cyprus remained broadly controlled, with modest adjustments
reflecting improved supply balance and increased competition. These conditions signal a transition toward a more mature market environment, where pricing is increasingly aligned with underlying fundamentals rather than short-term demand fluctuations.
It is also important to recognise that certain residential transactions, particularly involving newly developed villas without separate title deeds at the time of transfer, may not be fully captured in conventional residential transaction datasets. As a result, activity in the villa segment may be structurally higher than reflected in headline statistics.
This report provides a comprehensive analysis of residential real estate performance across Cyprus, examining transaction volumes, pricing trends, and regional dynamics across Limassol, Pafos, Larnaca, Nicosia, and Famagusta. The findings highlight a market that is becoming more stable, more competitive, and increasingly driven by long-term residential and lifestyle demand.
RESIDENTIAL PROPERTY SALES DISTRIBUTION PER REGION IN Q4 2025
VOLUME OF MID- AND HIGH-RANGE HOUSES & APARTMENTS
Akoursos, Pafos
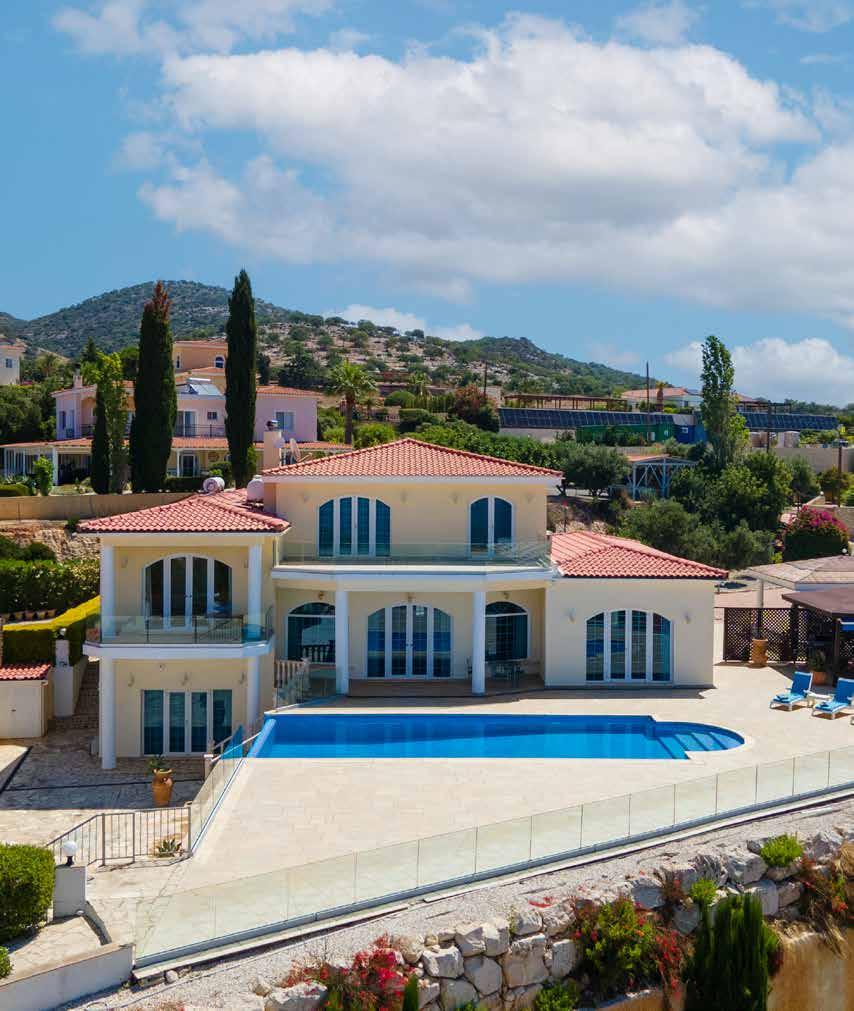
6 Bedroom Villa
ID: p74900
A 545 m² villa with 6 bedrooms on a 3,650 m² hillside plot near Coral Bay, offering panoramic sea views. The layout is designed for both grand entertaining and everyday family life.
The entrance opens to a formal dining area overlooking the pool and coastline. The kitchen and family room connect to the outdoor terrace through wide patio doors — ideal for sunset dinners. Upstairs, two ensuite bedrooms open to private terraces. A separate wing houses the master suite with a private office, lounge, walkin wardrobes, and ensuite bathroom.
On the lower level: two guest bedrooms, a shared bathroom, and a separate maid's room. Outside — shaded barbecue area, mature gardens, and a detached guest house with its own possibilities.
Fully equipped for year-round comfort and privacy.
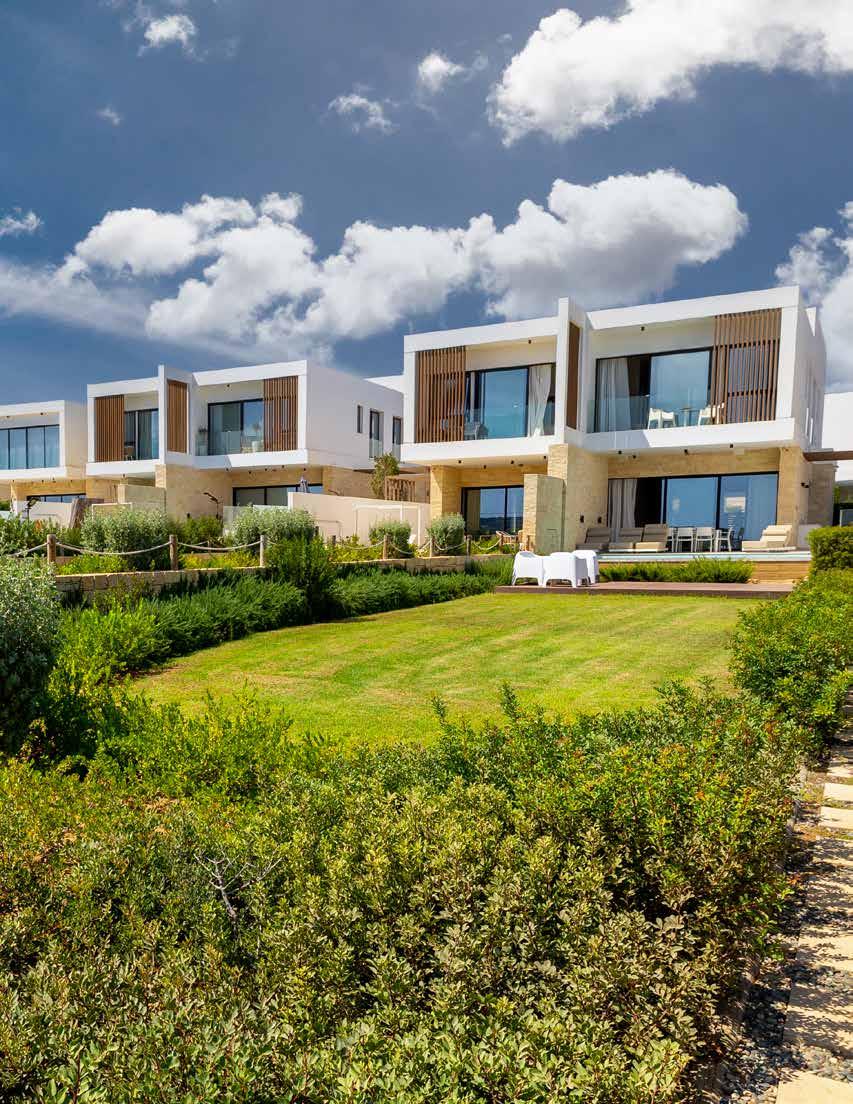
5 Bedroom Beachfront Villa
f12300
A 437 m² villa with 5 bedrooms on a 703 m² plot, set within a gated community on the seafront in Cavo Greco National Park. Direct views of the Mediterranean and walking distance to Konnos Beach with its golden sand.
The ground floor offers a kitchen, dining room, living area, and a furnished terrace with panoramic sea views. Upstairs, four bedrooms each have their own bathroom. The basement level includes a fifth bedroom, an additional bathroom, a kitchen, a lounge area, and a sauna.
The gated community features electronic entry and underground parking, keeping the villas car free and quiet. Residents have access to the Clubhouse with a lobby, spa and fitness center, restaurant, and bar.
A private pool, a garden, and seafront living in complete privacy.
Protaras, Famagusta
ID:
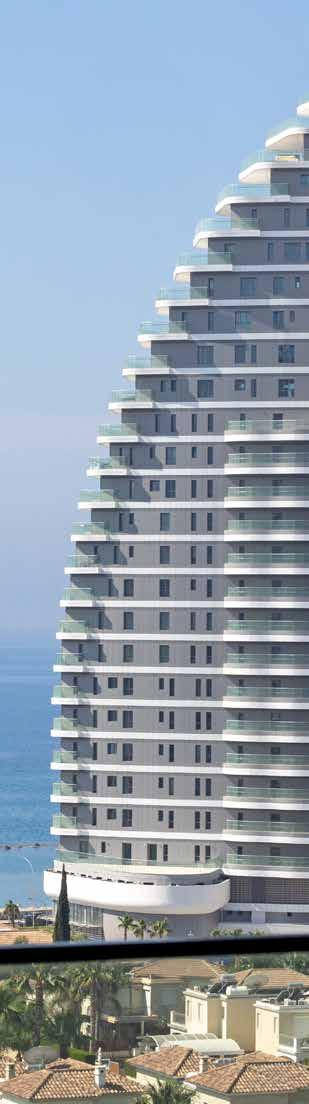
LIMASSOL
Cyprus’s leading premium real estate market
Limassol is Cyprus’s premier real estate hub
A cosmopolitan business city where sustained demand for mid- and high-end properties continues to shape a mature, premium-driven market.
Limassol remains the most dynamic and mature property market in Cyprus, especially in the high and mid-range segment. In Q4 2025, the city recorded 1,008 residential transactions, with an exceptional 71% (686 properties) in this category, confirming its position as the island’s main hub for premium real estate.
Demand was particularly strong for apartments, with 640 transactions, accounting for 45% of all such sales across Cyprus. Houses also showed solid activity, with 46 sales, representing 20% of the national total.
Since Q1 2024, the total residential transaction value reached €3.1 billion, with €2.6 billion (85%) coming from the high and mid-range segment — the highest concentration among all cities.
Median prices stood at €815,000 for houses and €315,000 for apartments. Compared to Q4 2024, prices declined by 22% for houses and 4% for apartments, reflecting market adjustment following previous strong growth.
VOLUME AND MEDIAN PRICES OF MID- AND
HOUSES AND APARTMENTS
Volume of > € 200k Apartments
TRANSACTIONS’ PRICE DISTRIBUTION
PAFOS
A lifestyle-driven market with strong demand for houses
Pafos emerges as Cyprus’s new lifestyle hotspot
With strong demand for premium villas and scenic living, the region is rapidly evolving into a key destination for highend buyers.
Pafos continues to attract buyers seeking lifestyle-oriented properties, particularly houses. In Q4 2025, the city recorded 1,126 residential transactions, with 40% (445 properties) in the high and mid-range segment.
House demand was especially strong, with 136 sales in this category — representing 58% of Cyprus’s total. Apartment sales reached 309 units, accounting for 22% nationally.
Since early 2024, residential sales value reached €2 billion, with €1.1 billion (58%) attributed to high and mid-range properties.
Median prices remained stable at €715,000 for houses and €305,000 for apartments, showing resilience and consistent demand.
AND MEDIAN PRICES OF MID- AND HIGH-RANGE HOUSES AND APARTMENTS
Transaction Volume of > € 200k Apartments
Transaction Volume of > € 500k Houses
Median Prices of > € 200k Apartments
Median Prices of > € 500k Houses
TRANSACTIONS’ PRICE DISTRIBUTION
NICOSIA
A stable, locally driven capital market
Nicosia — the capital city with stable demand driven by international companies, embassies, and government institutions.
As the administrative and business capital of Cyprus, Nicosia offers a stable and consistent residential market. In Q4 2025, the city recorded 930 residential transactions, with 21% (195 properties) in the high and mid-range segment.
Apartments accounted for most activity, with 821 sales, while houses represented a smaller share.
Since early 2024, residential sales value reached €1.1 billion, with €446 million (40%) coming from high and mid-range properties.
Median prices reached €797,000 for houses and €249,000 for apartments. House prices increased significantly year-on-year, while apartment prices showed steady growth.
KEY INDICATORS
PRICES
TRANSACTIONS’ PRICE DISTRIBUTION
LARNACA
A fast-growing market driven by apartment demand
Larnaca — a dynamic coastal city with growing residential demand driven by its strategic location and expanding infrastructure.
Larnaca is emerging as one of Cyprus’s fastestgrowing property markets, supported by infrastructure development and strong apartment demand. In Q4 2025, the city recorded 1,116 residential transactions, with 24% (272 properties) in the high and mid-range segment.
Apartments dominated this category, with 252 sales, representing 18% of Cyprus’s apartment market. Houses accounted for 20 transactions.
Since Q1 2024, total residential sales value reached €1.3 billion, of which €523 million (41%) came from high and mid-range properties.
Median prices reached €715,000 for houses and €248,000 for apartments, with moderate annual price growth.
VOLUME AND MEDIAN PRICES
TRANSACTIONS’ PRICE DISTRIBUTION
FAMAGUSTA
A smaller but evolving coastal market
Famagusta — a niche coastal market focused on high-end leisure properties.
Famagusta remains a smaller but gradually developing property market, particularly in the high and mid-range segment. In Q4 2025, the city recorded 278 residential transactions, with 17% (46 properties) in this category.
Apartment sales totaled 29 units, while houses accounted for 17 transactions.
Since Q1 2024, total residential transaction value reached €441 million, with €60 million (13%) attributed to high and mid-range properties.
Median prices stood at €585,000 for houses and €258,000 for apartments. While house prices declined, apartment prices showed notable annual growth.
INDICATORS
PRICES
TRANSACTIONS’ PRICE DISTRIBUTION
Vasileos Konstantinou 1, office 302, 8020
Beon. Apostolou Pavlou Ave 10, 8046
Olympic Residence A15 353, 28th October, 3107
Unit 3, Giannou Kranidioti 2, 6045
© 2025 Cyprus Sotheby’s International Realty. All rights reserved. Cyprus Sotheby’s International Realty® and the Sotheby’s International Realty Logo are service marks licensed to Sotheby’s International Realty Affiliates LLC and used with permission. ONE Sotheby’s International Realty fully supports the principles of the Fair Housing Act and the Equal Opportunity Act. Each franchise is independently owned and operated. Any services or products provided by independently owned and operated franchisees are not provided by, affiliated with or related to Sotheby’s International Realty Affiliates LLC nor any of its affiliated companies. The information contained herein is deemed accurate but not guaranteed.
Data provided by the Cyprus Department of Lands and Surveys. All data analysis, processing, and insights have been prepared exclusively by Cyprus Sotheby’s International Realty. Cyprus Sotheby’s International Realty makes no representations or warranties regarding the content of this report and disclaims all such representations and warranties, including but not limited to those related to condition, quality, accuracy, suitability, fitness for purpose, or completeness. This report should not be considered financial advice, and you acknowledge that its content is not intended for that purpose.
Cyprus Sotheby’s International Realty, its directors, employees, or other representatives shall not be held liable for any damages arising from or in connection with the use of this report. This is a comprehensive limitation of liability that applies to all types of damages, including (without limitation) compensatory, direct, indirect, or consequential damages, loss of data, income or profit, loss of or damage to property, and third-party claims. All material in this report is provided for general informational purposes only and does not consider the specific circumstances of any individual or entity. Nothing in this report constitutes professional and/or financial advice, nor does it offer a comprehensive or complete statement of the matters discussed or the laws applicable thereto. The information may be inaccurate or outdated due to changes in applicable laws and regulations. No action should be taken or omitted to be taken based solely on this report.