GROWTH CONTINUES
The first quarter of 2026 confirmed what I have been observing for several years now: the Cypriot market is changing not just in size, but in its very nature - 4,308 transactions and €1.26 billion. These are impressive numbers, but something else matters more. The market is no longer growing due to hype, but rather due to depth. Before moving to conclusions, one important caveat: a significant portion of transactions comprises Contracts of Sale — an instrument that reflects not only live demand for new builds, but also the accumulated volume of properties without a formal title deed. This is a structural feature of the Cypriot market, and without understanding it, any forecast for 2026 would be premature.
Among the clear trends: Pafos is no longer a secondary market. Limassol continues to lead, but the gap between the two cities in terms of the number of transactions has narrowed to 55. Just a few years ago, this would have sounded impossible. The total transaction turnover in Pafos in the first quarter of 2026 has doubled compared to the same period in 2025. The city is no longer just a resort story, today it is a fully-fledged market for living and investment, backed by sustained international demand.
Limassol has entered a mature phase. It still leads in terms of capital value, and this trend will continue thanks to unique high-end projects, stable corporate demand, and a structural shift towards luxury apartments. But the era when a property here would sell at any price simply because of its location is now behind us. Buyers have become more rational. This is a healthy normalisation.
In Larnaca and Nicosia, we are seeing a steady structural shift. Geopolitics and affordable entry price points have done their job. I see this not as a temporary spike, but as a redistribution of demand that will continue.
The interesting trend in Cyprus's residential property market is that demand is gradually shifting from apartments to houses. The 2026 buyer is increasingly choosing a comfortable lifestyle. This changes
both the logic of property selection and the way value is assessed.
Cyprus today is several different markets on a single island. That is precisely what makes it more resilient and, frankly, more interesting to work in.
Stay in touch,
Anastasia Yianni Chief Executive Officer
Cyprus Sotheby’s International Realty
*Mid- and high-range residential segments - apartments priced from €200,000 and houses from €500.000
ABOUT INSIGHTS:
Transaction data are provided by Cyprus’ Department of Lands and Surveys, which records all transfers of ownership and registered contracts of sale (including property description, purchase price, date, etc). The data is processed in order to classify each transaction (as some properties are under construction, their description is not exact, or they form part of bigger projects) and are categorised by property type.
The analysis covers the entire area controlled by the Republic of Cyprus, excludes properties sold at auction (foreclosure), and references property values based on the amount declared by the purchaser at the time of the transaction (which excludes any VAT, transfer fees, or other duties levied).
CYPRUS PROPERTY MARKET: Q1 2026 RESULTS
The first quarter of 2026 confirmed: the Cyprus property market continues to grow, but the structure of demand is changing noticeably. Buyers are increasingly choosing property for living, not just for investment, and the market leaders are gradually shifting.
OVERALL MARKET PICTURE
In Q1 2026, Cyprus recorded:
• 4,308 residential property transactions
• Total market volume: €1.26 billion.
Compared to Q1 2025:
• Growth in number of transactions: +43%
• Growth in market volume: +52%.
Analysts note that the quarterly statistics partially include transactions agreed upon as early as late 2025. Therefore, current figures reflect the market's direction rather than the final annual result.
Additionally, the influence of Contract of Sale (CoS) transactions is strengthening:
• 3,096 CoS transactions
• 1,212 transactions with Title Deed
• CoS share reached 72% of the market.
This confirms the growing role of new builds, assignments, and properties without a formal title deed.
KEY TRENDS OF Q1 2026
Pafos becomes a new growth hub
The main trend of early 2026 is the confident rise in interest in Pafos.
In Q1 2026, the city recorded:
• 1,077 transactions
• Sales volume: €401 million
Pafos has nearly caught up with Limassol in terms of the number of transactions. The house segment is growing particularly actively:
• Median price for houses in the mid-to-high price segment* reached €850,000
• Apartments in this segment: approximately €300,000
The market is increasingly oriented toward buyers considering Cyprus for permanent residence.
Limassol transitions to a mature market phase
Limassol retains its leadership in capital volume in Q1 2026:
• €442 million in the first quarter of 2026. However, the market is becoming more balanced:
• Prices are stabilising
• Buyers have become significantly more selective
• Demand is shifting from hype toward quality projects.
Median prices:
• Apartments: €270,000
• Houses: €390,000.
In the mid-to-high price segment*:
• Apartments: €305,000
• Houses: €770,000.
Larnaca and Nicosia strengthen their positions
Larnaca and Nicosia continue to establish themselves as the most affordable markets on the island.
In the first quarter of 2026:
• Larnaca: 995 transactions worth €187 million
• Nicosia: 877 transactions worth €174 million.
Median apartment prices in Q1 2026:
• Larnaca: €160,000
• Nicosia: €155,000.
Housing affordability and growing demand for relocation are making these regions increasingly attractive for permanent residence.
Demand shifts toward houses:
One of the most notable trends is the growing interest in houses and villas.
Across the Republic of Cyprus in Q1 2026:
• 989 house transactions
• Year-on-year growth: +63%
For comparison:
• Apartment segment growth: +38%
Most active demand for houses:
• Pafos: 446 house transactions
• Limassol: 193 transactions
Main drivers:
• Spread of remote work
• Growing demand for lifestyle property
• Shift from an investment model toward living on the island
The Cyprus property market continues to grow, but without signs of overheating.
RESIDENTIAL PROPERTY SALES DISTRIBUTION PER REGION IN Q1 2026
Q1 2026
Famagusta
Limassol
Pafos
Larnaca
Nicosia
Famagusta

LIMASSOL
Cyprus’s leading premium real estate market
Limassol is Cyprus’s premier real estate hub
A cosmopolitan business city where sustained demand for mid- and high-end properties continues to shape a mature, premium-driven market.
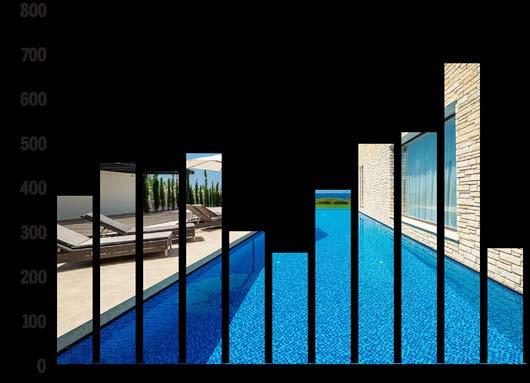
In Q1 2026, Limassol recorded 1,132 residential transactions across all market segments.
Within our defined high- and mid-range segment, 793 properties were transacted in the city during the quarter.
Limassol led Cyprus in high- and mid-range demand:
• 726 apartments, accounting for 47% of the total for Cyprus
• 67 houses, accounting for 26% of the total for Cyprus.
Since Q1 2025, the total transaction value reached €2 billion, of which 86% (€1.7 billion) of high- and mid-range segment.
In Q1 2026, the median transaction price for high- and midrange properties in Limassol stood at €770,000 for houses and €305,000 for apartments. Compared to Q1 2025, median prices increased by 1% for houses but decreased by 3% for apartments.
Price stabilisation in the house segment and a slight softening in apartment values reflect a more selective buyer profile and a healthy market normalisation.
KEY INDICATORS
Q1 2025 vs . Q1 2026
VOLUME AND MEDIAN PRICES
OF MID- AND
HOUSES
AND
APARTMENTS
Volume of > € 200k Apartments
Volume of > € 500k Houses
Prices of > € 200k Apartments
of > € 500k Houses
TRANSACTIONS’ PRICE DISTRIBUTION
/ 2016-2025
OF
/ Q1 2026
PAFOS
A lifestyle-driven market with strong demand for houses
Pafos emerges as Cyprus’s new lifestyle hotspot
With strong demand for premium villas and scenic living, the region is rapidly evolving into a key destination for highend buyers.
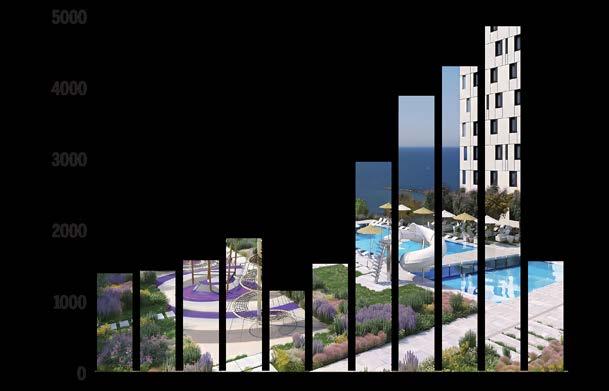
In Q1 2026, Pafos recorded 1,077 residential transactions across all market segments.
Within our defined high- and mid-range segment, 476 (44%) properties were transacted in the city during the quarter.
High- and mid-range houses were in particularly high demand in Pafos:
• 154 house transactions, accounting for 59% of the total for Cyprus
• 322 apartment transactions, accounting for 21% of the total for Cyprus.
Since Q1 2025, the total transaction value of residential properties reached €1.4 billion, of which 65% (€0.9 billion) was in the high- and mid-range segment.
In Q1 2026, the median transaction price for high- and mid-range properties in Pafos stood at €850,000 for houses and €300,000 for apartments. Compared to Q1 2025, median prices increased by 28% for houses but decreased by 10% for apartments.
The sharp rise in house prices coupled with softening apartment values highlights a strong shift in buyer preference toward lifestyle properties for permanent residence, rather than compact investment units.
KEY INDICATORS
Q1 2025 vs . Q1 2026
Transaction Volume of > € 200k Apartments
VOLUME AND MEDIAN PRICES
Transaction Volume of > €
Median Prices of > € 200k Apartments
Median Prices of > € 500k Houses
TRANSACTIONS’ PRICE DISTRIBUTION
NICOSIA
A stable, locally driven capital market
Nicosia — the capital city with stable demand driven by international companies, embassies, and government institutions.
In Q1 2026, Nicosia recorded 877 residential transactions across all market segments.
Within our defined high- and mid-range segment, 214 properties were transacted in the city during the quarter.
High- and mid-range properties in Nicosia during the past quarter included:
• 201 apartments, accounting for 13% of the total for Cyprus
• 13 houses
Since Q1 2025, the total transaction value reached €745 million, of which 40% (€296 million) of high- and mid-range segment . In Q1 2026, the median transaction price for high- and midrange properties in Nicosia stood at €650,000 for houses and €255,000 for apartments. Compared to Q1 2025, median prices for apartments decreased by 10%. House price dynamics yearon-year were not specified in the source.
Interest in houses and lifestyle properties continues to hold steady.
KEY INDICATORS
Q1 2025 vs . Q1 2026
TRANSACTIONS’ PRICE DISTRIBUTION
LARNACA
A fast-growing market driven by apartment demand
Larnaca — a dynamic coastal city with growing residential demand driven by its strategic location and expanding infrastructure.
In Q1 2026, Larnaca recorded 995 residential transactions across all market segments.
Within our defined high- and mid-range segment, 268 properties were transacted in the city during the quarter.
High- and mid-range properties in Larnaca during the past quarter included:
• 256 apartments, accounting for 17% of the total for Cyprus
• 12 houses, accounting for 5% of the total for Cyprus
Since Q1 2025, the total transaction value reached €863 million, of which 43% (€374 million) of high- and mid-range segment.
In Q1 2026, the median transaction price for high- and midrange properties in Larnaca stood at €647,000 for houses and €245,000 for apartments. Compared to Q1 2025, median prices increased by 8% for houses and by 4% for apartments.
Modest but steady price growth in both segments reflects Larnaca's strengthening position as an accessible yet appreciating market, increasingly attractive for permanent residence and relocation.
KEY INDICATORS
Q1 2025 vs . Q1 2026
TRANSACTIONS’ PRICE DISTRIBUTION
FAMAGUSTA
A smaller but evolving coastal market
Famagusta — a niche coastal market focused on high-end leisure properties.
In Q1 2026, Famagusta recorded 227 residential transactions across all market segments.
Within our defined high- and mid-range segment, 50 properties were transacted in the city during the quarter.
Within this segment:
• 37 apartment sales, accounting for 2% of all apartment transactions in Cyprus
• 13 house sales, accounting for 5% of all house transactions in Cyprus
The relatively low share indicates that the high- and mid-range segment remains modest in the overall market of Famagusta. Since Q1 2025, the total transaction value reached €275 million, of which 43% (€118 million) of high- and mid-range segment.
In Q1 2026, the median transaction price for high- and midrange properties in Famagusta stood at €600,000 for houses and €275,000 for apartments. Compared to Q1 2025, median prices decreased by 7% for houses but increased by 19% for apartments.
The divergence in price trends — falling house prices alongside sharply rising apartment values — suggests a niche, opportunity-driven market rather than a broad-based trend.
KEY INDICATORS
Q1 2025 vs . Q1 2026
TRANSACTIONS’ PRICE DISTRIBUTION
Vasileos Konstantinou 1, office 302, 8020
Beon. Apostolou Pavlou Ave 10, 8046
Olympic Residence A15 353, 28th October, 3107
Unit 3, Giannou Kranidioti 2, 6045
© 2026 Cyprus Sotheby’s International Realty. All rights reserved. Cyprus Sotheby’s International Realty® and the Sotheby’s International Realty Logo are service marks licensed to Sotheby’s International Realty Affiliates LLC and used with permission. ONE Sotheby’s International Realty fully supports the principles of the Fair Housing Act and the Equal Opportunity Act. Each franchise is independently owned and operated. Any services or products provided by independently owned and operated franchisees are not provided by, affiliated with or related to Sotheby’s International Realty Affiliates LLC nor any of its affiliated companies. The information contained herein is deemed accurate but not guaranteed.
Data provided by the Cyprus Department of Lands and Surveys. All data analysis, processing, and insights have been prepared exclusively by Cyprus Sotheby’s International Realty. Cyprus Sotheby’s International Realty makes no representations or warranties regarding the content of this report and disclaims all such representations and warranties, including but not limited to those related to condition, quality, accuracy, suitability, fitness for purpose, or completeness. This report should not be considered financial advice, and you acknowledge that its content is not intended for that purpose.
Cyprus Sotheby’s International Realty, its directors, employees, or other representatives shall not be held liable for any damages arising from or in connection with the use of this report. This is a comprehensive limitation of liability that applies to all types of damages, including (without limitation) compensatory, direct, indirect, or consequential damages, loss of data, income or profit, loss of or damage to property, and third-party claims. All material in this report is provided for general informational purposes only and does not consider the specific circumstances of any individual or entity. Nothing in this report constitutes professional and/or financial advice, nor does it offer a comprehensive or complete statement of the matters discussed or the laws applicable thereto. The information may be inaccurate or outdated due to changes in applicable laws and regulations. No action should be taken or omitted to be taken based solely on this report.