Finance
w
62 The power of the broker 82 Bring your child to work ... forever? 92 Unpacking the return-to-office blues MAY 3, 2022
POWER 50 ISSUE
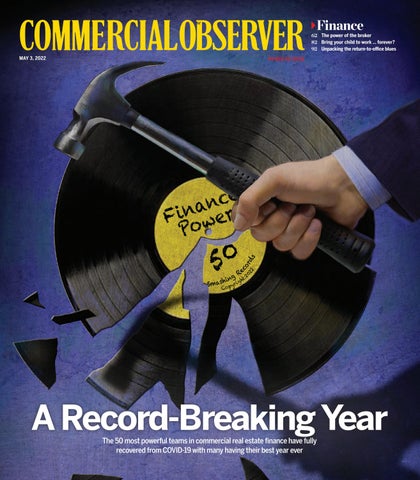
A Record-Breaking Year The 50 most powerful teams in commercial real estate finance have fully recovered from COVID-19 with many having their best year ever
TABLE OF CONTENTS
1 Whitehall Street, 7th Floor New York, NY 10004 | 212.755.2400
Max Gross Editor-in-Chief
Cathy Cunningham Deputy Editor, Finance
Tom Acitelli Deputy Editor, News
Greg Cornfield, Chava Gourarie Associate Editors
Rebecca Baird-Remba, Andrew Coen, Emily Fu, Mark Hallum, Celia Young Staff Writers
74
Josh Rozbruch
Web Editor
Social Media Editor
Robyn Reiss Executive Director
SALES Brigitte Baron Partnerships Director
Natalie Reichel Senior Account Manager
82 FEATURES
4 NEWS BRIEFS
Nicholas Rizzi
Amy Cogan Sales Executive
Child’s Play
Sophia Homa
Can Eric Adams transform offices into day care centers?
Senior Client Success Manager
Ryan Leigh, Gabriela McNichol Client Success Managers
The Sit-Down
82
Danielle Lesser.
Retail Forum Wrap Our annual ranking of the most powerful brokers and lenders in the field of commercial real estate
2022
The Year of the Record If you didn’t have a record year, said one honoree, you’re in the wrong business.
A Match Made in Heaven How the Greystone/Cushman & Wakefield deal came together.
That’s Life! Why insurance lending was so critical in 2021 / 2022.
All Hail the Power Broker! The movers and shakers who made this a record year.
What we learned at CO’s online gathering of retailers and real estate people.
MARKETING & EVENTS Ashley Roseman Senior Events Manager
Emily Benner Event Coordinators
Return to Office Blues
DESIGN, PHOTO & PRODUCTION
It’s the lower-level workers being required to come in ... and they’re not happy about it.
Jeffrey Cuyubamba Art Director
84
Columns Robert Knakal and Dan Gorczycki
Josh Haas Vice President, Product
Charles Taffet Senior Prouduct Manager
ENDNOTES
Jordan Lovinger Email & Newsletter Product Manager
98 The Plan
Ramon Encarnacion IT Manager
A Learning Experience Finance got schooled in 2020. But those lessons are proving helpful now.
OBSERVER MEDIA
Debt Deals of the Week
Joseph Meyer
ChartFinance
Michael Rose
Takeaway
Chairman Chief Executive Officer TOP TO BOTTOM: BRITT SPENCER/FOR COMMERCIAL OBSERVER, DAVE WHIPPLE/FOR COMMERCIAL OBSERVER, STEPHANIE PRICE/FOR COMMERCIAL OBSERVER COVER ILLUSTRATION: DOMENIC FINELLE/FOR COMMERCIAL OBSERVER
2
| MAY 3, 2022 | COMMERCIAL OBSERVER
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
CONGRATULATIONS TO OUR MERIDIAN COLLEAGUES AND THIS YEAR’S POWER 50 Since 1991, Meridian has been committed to providing best-in-class guidance and outcomes for our clients, while working hand-in-hand with the lending community to develop innovative products and solutions to lead the market forward. Thank you to our esteemed clients and lending partners whose continued trust and confidence allowed Meridian to close more than $55 billion in financing nationally in 2021.
220421 Meridian Capital, Power 50, CO 2022-02.indd 1
4/25/22 4:28 PM
BRIEFS
LEV RADIN/PACIFIC PRESS/LIGHTROCKET VIA GETTY IMAGES
News APPLE PAY
Adams’ $100B Budget Aims at Housing, Safety and Transit New York Mayor Eric Adams announced a hulking $99.7 billion executive budget on April 26 that aims to make the city a more secure place for business, improve transportation and invest $22 billion in housing over the next 10 years. Adams’ first budget proposal slightly edges out Mayor Bill de Blasio’s record $98.6 billion executive budget passed during his last term, and Adams revised his own preliminary budget by adding $2 billion that will — as the mayor put it — prioritize public safety and cleanliness. “We must restore the major drivers of our city’s economy, including the central business districts that have been critical engines of success for centuries,” Adams said. “We’re making big investments in the cleanliness and safety of our streets and supporting our businesses in Midtown and Lower Manhattan.” Celebrating his first 100 days in office, Adams told audience members at Kings Theatre in Flatbush, Brooklyn, that his budget
includes $256 million for public safety programs, including homeless outreach, while another $118 million would be allocated for street and park cleaning. The budget also calls for $171 million previously announced to create 1,400 new Safe Haven beds for homeless New Yorkers. Of the $22 billion to be invested in housing, Adams’ budget includes an additional $5 billion that will be split between the Department of Housing Preservation and Development and the New York City Housing Authority’s Permanent Affordability Commitment Together program — which makes nonNYCHA apartments permanently affordable and grants tenancy rights similar to those in public housing — and unit repairs at Gowanus Houses and Wyckoff Gardens. “This is the biggest housing investment in generations, and it would impact many generations to come,” Adams said. “This money will help make critical repairs in NYCHA, subsidize those who need help staying in their
SALES PITCH: Mayor Adams’ proposed budget must win City Council support to be enacted. existing homes to build more deep, affordable housing for the entire city.” Adams added that his office will release a “detailed blueprint for housing and homelessness based on the input of our city’s top experts” soon to “take this dream of equality and turn it into reality that is getting stuff done on a historical level.” Adams’ fiscal year 2023 budget must be approved by the New York City Council before it is enacted July 1. If the budget is approved, $904 million over the next five years will be committed to enhancing street safety with nearly $580 million in capital funding. Adams announced earlier in April that the street safety improvements would go toward revamping 1,000 intersections while his administration works to convince Albany legislators to allow New York City to set speed limits and control automated traffic enforcement.
In an earlier release, his administration said it will work to protect cyclists, speed up buses and reclaim public space for pedestrians as opposed to cars. It’s likely that considerable investments will be made toward bike lanes, bus lanes and open streets as previously laid out in the New York City Department of Transportation’s NYC Streets Plan. But perhaps the most central message in Adams’ address was that his administration intends to restore order to a city with “far too much violence.” Adams underscored the issue by pointing to fatal shootings in the city, including several cop shootings that resulted in the deaths of two officers. Adams also committed an additional $55 million to the Behavioral Health Emergency Assistance Response Division, which sends emergency medical technicians and mental health professionals with police officers who respond to 911 calls. —Mark Hallum
New York Mayor Eric Adams tapped former Goldman Sachs global head of sustainability, Margaret Anadu, as chair of the board of the New York City Economic Development Corporation (EDC). She started April 27. In her new role, Anadu will steer the agency’s 27-member board in spurring economic development across the EDC’s 66 million square feet of property. “With her investing expertise and her deep commitment to underserved communities, Anadu is the right person to ensure the city’s economic development work is building a more prosperous, more equitable and more inclusive city,” Adams said in a statement. “Bringing back our city’s economy is an urgent priority for this administration, but we must think bigger and
4
| MAY 3, 2022 | COMMERCIAL OBSERVER
do better than trying to bring back a prepandemic city.” The ex-Goldman employee’s appointment follows that of Andrew Kimball as president and CEO of the EDC in February. Adams chose Kimball after news broke that Adams’ first choice, New York Building Congress President and CEO Carlo Scissura allegedly lobbied city officials without registering as a lobbyist. Anadu has served on Adams’ transition team as one of the five leaders of the Economic and Workforce Development Committee, and will take over as chair of the board from restaurateur Danny Meyer. “Mayor Adams has a fearless vision to ensure the city’s economic recovery not only rapidly accelerates but also reaches and uplifts all New Yorkers, and I have directly
ANDREW TOTH/FILMMAGIC
Margaret Anadu New Chair of New York EDC Board of Directors
IN IT: Anadu took the chair last month. witnessed EDC’s central role in driving that inclusive growth,” Anadu said in a statement. “I am energized by the opportunity to volunteer my time and effort to build a stronger, more equitable and more resilient future for this great city that we all love.” A 17-year veteran of Goldman, Anadu was
BECOME A COMMERCIAL OBSERVER MEMBER
the youngest Black female partner in the bank’s history and helped create a $1 billion lending platform there for small businesses and communities during the early months of the pandemic in 2020. Rumors of her departure from Goldman began circulating in February, and Anadu’s name was even floated as a potential pick for Joe Biden’s administration after the 2020 presidential election, Bloomberg reported. Anadu has served on the boards of the public policy think tank Center for an Urban Future, the San Francisco-based Low Income Investment Fund, New York Public Radio, Planned Parenthood Federation of America and the Africa Center museum. Goldman did not respond to a request for comment. —Celia Young
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
Certainty of Execution Expertise Refined Over Decades
New York
Los Angeles
San Francisco
Miami Metro
Dallas
©2022 ACORE Capital. Registered trade/service marks are the property of ACORE Capital. All rights reserved.
BRIEFS
CLASSEN/ULLSTEIN BILD VIA GETTY IMAGES
Fitch to Score Buildings on Climate Change Vulnerability
THAT’S RATE: Fitch is gauging climate change in a new way.
Fitch Ratings will publish climate vulnerability scores for each corporate sector beginning in June, in an effort to lay the groundwork for individual company ratings in the future, the company announced ESG last week. The move comes ahead of expected federal disclosure rules for companies regarding their exposure to the effects of climate change. Fitch began publishing climate vulnerability scores for the most exposed sectors in 2021, including the gas, oil, utilities and chemicals sectors. Last month, Fitch added a transportation report, and will follow with additional categories this month and in June, including the building and lodging sectors. “Each sector report contextualizes that sector’s exposure to climate-transition risks, and identifies specific policy, technological or market factors that inform the scoring to 2050,” the company wrote in a statement. “The framework also lays the groundwork for Fitch to provide scores at an entity level.” The move comes as the finance and corporate sectors are beginning to incorporate climate risks more aggressively. In March, the U.S. Securities and Exchange Commission (SEC) proposed climate disclosure rules that will require all public companies to disclose their financial and operational climate exposure, as well as greenhouse gas emissions. (The proposed rule is currently receiving
public comment and is expected to be finalized later this year, with compliance expected by 2024 at the earliest.) While investors in the commercial and financial sectors have been increasingly focused on environmental, social and governance (ESG), none of those factors focus on climate vulnerability specifically. Standard & Poor’s Global, for example, already has an ESG scoring model, but even the environmental section focuses more on what the company is doing regarding sustainability than on its exposure to climate change. Fitch’s ratings take into consideration that there likely will be a rapid transition away from fossil fuels between 2025 and 2050, and accounts for what that means for different sectors at various points along that timeline. “The updated scenario predicts a more forceful regulatory response to climate change across eight policy areas from 2025 to 2050,” Fitch wrote. The Fitch scores lay the groundwork for a more standardized measurement going forward. That’s one of the key benefits of the proposed SEC rules, said Jason Narod, a vice president at GridPoint, which provides energy efficiency solutions for landlords. “There are a lot of companies already doing what the SEC is mandating. I just think everyone’s calculating things their own way,” he said. “Once it’s standardized, you’re able to benchmark and compare.” —Chava Gourarie
Aby Rosen’s RFR Holdings is expanding its Biscayne Boulevard portfolio. The New York City-based firm bought a 17-story hotel along one of Miami’s busiest roads for $25.8 million, property records show. Originally built in the 1920s, Yve Hotel Miami is one of the oldest standing hotels in Miami, although it is not landmarked and its facade has been redone. The 241room property at 146 Biscayne Boulevard sits next door to 100 Biscayne, a 30-story office building that RFR bought for $81 million last year. The seller, Host Hotels & Resorts, paid $57.5 million for the 129,574-square-foot hotel in 2015, marking a nearly $32 million loss, per records. The reason for the apparent discount is unclear. A representative for the firm did not respond to a request for comment. The Maryland-based company bought the hotel from private equity giant Carlyle Group and InSite Group, which had rebranded the establishment following extensive renovations. The hotel may once again undergo a makeover. RFR, led by Rosen and Michael
6
| MAY 3, 2022 | COMMERCIAL OBSERVER
properties. To finance the purchase of the hotel, MSD
Partners provided RFR with $39.7 million, adding to a previous loan of $67 million that MSD had provided for 100 Biscayne in January. The note was then split into two and backed by the two properties. Newmark’s Dustin Stolly and Jordan Roeschlaub arranged the debt. Rosen is one of the most prominent New York City players. He owns the Seagram Building and Chrysler Building, iconic skyscrapers in Midtown, and owned the now-shuttered Gramercy Park Hotel, once a hotspot among celebrities. He’s also notorious for his controversial moves and comments. After he acquired the Seagram Building in 2014, he took down Pablo Picasso’s “Le Tricorne,” a 20-by-22-foot tapestry that had hung in the tower for more than five decades. During the first COVID-19 wave in the spring of 2020, Rosen caught fire for posting pictures on Instagram of his multimillion-dollar mansion and peaceful life in the Hamptons, as millions of people lost their jobs and struggled to make ends meet. —Julia Echikson
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
INN MIAMI: Aby Rosen, right, is famous for repositioning office and hospitality properties. Fuchs, is known for renovating and repositioning historic or architecturally significant
FROM LEFT: ROBERTO MACHADO NOA/LIGHTROCKET VIA GETTY IMAGES, CHANCE YEH/WIREIMAGE
Aby Rosen’s RFR Holdings Buys Yve Hotel Miami at a Discount
Atlanta • Austin • Boston • Charlotte • Chicago • Greenwich • London • Los Angeles • Manhattan Beach • Miami • New York • San Francisco • Washington, DC
LE ADER SHIP Thank you to Max, Cathy and the dedicated team at Commercial Observer and congratulations to our Power 50 friends, partners and Starwood employees on this accomplishment. We are delighted to share this prestigious honor with you once again.
BRIDGE LENDING | FLOATING RATE
CONDUIT LENDING | FIXED RATE
Dennis Schuh
Adam Behlman
Chief Originations Officer 203.485.5108 dschuh@starwood.com starwoodpropertytrust.com
President 305.695.5080 abehlman@starwood.com starwoodmortgagecapital.com
BRIEFS
As a growing number of office users adopt hybrid work models, office investment sales and rental rates nationwide both dropped in the first three months of the year compared with the same period in 2021. U.S. office sales hit $18.9 billion in the first quarter, with the national average price at $280 per square foot, according to a recent report by Commercial Edge, citing Yardi Matrix data. Last year, there was about $22 billion in investment sales in the same period. More than $7.5 billion of this year’s total came in six leading markets, each of which logged more than $1 billion in sales so far this year: Seattle, Dallas, New Jersey, Houston, the San Francisco Bay Area and Manhattan. Manhattan was far and away the most expensive city for office investment sales, averaging $921 per square foot in the first quarter. Los Angeles was just shy of $1 billion in office sales, totaling $998 million in the first three months of the year. The entertainment industry continues to spur investments in a city where office-using employment is lagging, according to Commercial Edge. The city’s top deal year to date was the $93 million sale of the Netflix-occupied office in Hollywood. National office listing rates averaged $38.65 per square foot per year in March. That’s down 2.6 percent compared to last year. On the positive side, Miami and Charlotte, N.C., registered some of the highest gains over the past year, with rates rising 12.2 percent and 10.7 percent, respectively. On the other hand, San Francisco’s $63.04 listing rate was the second-highest nationwide, but also marked a 9.5 percent drop year
DONALD MIRALLE/GETTY IMAGES FOR ROCK’N’ROLL MARATHON
Investment Sales, Rents Drop in Office Markets Nationwide
UP AND AWAY: Seattle was one of the markets that saw at least $1 billion in office investment sales in the first quarter of 2022. over year. Manhattan’s $74.20 rate was 13.5 percent lower than a year ago. The national office vacancy rate hovered at 15.9 percent across the largest 50 U.S. markets, which was an increase of 30 basis points compared with the same period last year. Vacancies in San Francisco grew from a pre-pandemic 7.3 percent to 17.3 percent in March 2022. Boston’s 10.5 percent, Portland, Ore.’s 12.3 percent and Miami’s 12.8 percent vacancy rates were the tightest of the top 50 cities. The shift to remote and hybrid work also led to a smaller pipeline of new supply last year. In 2019, crews started building 86.4 million square feet of new office space. That
figure dropped to 58.4 million in 2020, and inched up to 63.1 million in 2021. Everything is getting bigger in Texas too. In 2021, Austin and Dallas led the country in new office starts, combining for 9.8 million square feet under construction. Austin accounted for 10 million square feet of office space under construction this year, representing 11.5 percent of its existing stock, while planned projects totaled 25.3 percent of the city’s current stock — the highest share among top markets in the nation. Of all the projects under construction across the country, 93 percent will be at least Class A space. If this trend continues, many
owners of Class B and C buildings may feel the squeeze and look for conversion opportunities, according to Commercial Edge. “We expect that those exploring conversions will be looking at life sciences, multifamily and, to a lesser extent, industrial,” the report reads. Markets with a heavy concentration of jobs in the life sciences also saw new development break ground throughout the pandemic. Besides Austin and Dallas, four of the remaining seven top markets for construction starts in 2021 were all life sciences hubs, including San Francisco and the Bay Area, Boston and Raleigh-Durham, N.C. —Greg Cornfield
ED JONES/AFP VIA GETTY IMAGES
Contech Firm Slate Technologies Buys Splash Modular
SLATE OF AFFAIRS: The deal furthers Slate’s digitized construction services.
8
| MAY 3, 2022 | COMMERCIAL OBSERVER
Construction software company Slate Technologies announced last week that it has acquired Splash Modular, an artificial intelligence (AI) and machine-learning firm active in the design manufacPROPTECH turing and assembly (DFMA) market. Splash will operate as part of Slate, according to the acquiring firm. Neither company disclosed the financial terms of the acquisition. In acquiring Charlotte, N.C.-based Splash Modular, Slate Technologies adds another form of industrialized construction (IC) to its platform of services in the increasingly digitized contech sector, said Joel Hutchines, former CEO of Splash and now vice president and head of IC for Slate. Founded in 2019, Splash uses its AI and machine-learning design process to improve the productivity of construction professionals by enabling better, earlier decision-making to help them manage construction site initiatives,
according to the company. Its software connects design teams in the construction process with the manufacturing, assembly and supply chain stakeholders, helping general contractors identify, integrate and manage IC. “The idea with Splash was we actually marketed prefabricated bathroom parts,” Hutchines said. “Rather than being a manufacturer, we licensed the assembly to somebody else. The reason we did that was so that we could showcase how we could productize a design process. So what we did was we codified the design [and] automated the entire process. Then we licensed the assembly to somebody else. “The whole approach there was to show that we could actually streamline the process, making the projects far more efficient and less costly. The next step for us was to create a marketplace full of components. As we were getting ready to do that and starting to work with clients, we were acquired. So we never really created the marketplace.” —Philip Russo
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
R E A L E S TAT E
SENIOR MORTGAGES | MEZZANINE FINANCING CONSTRUCTION & BRIDGE FINANCING
INDUSTRIAL
LIFE SCIENCE
LIFE SCIENCE
$ 200 M
$ 136 M
$ 118 M
HOSPITALITY
MULTIFAMILY
SELF-STORAGE
$ 109 M
$ 104 M
$ 27 M
Various U.S. Markets 3-Year Floating Rate Construction Whole Loan
Chicago, IL
Boston, MA
6-Year Floating Rate Bridge Whole Loan
Miami, FL
San Carlos, CA
5-Year Floating Rate Construction Whole Loan
Various U.S. Markets
5-Year Floating Rate
15-Year Fixed Rate
Bridge Whole Loan
Senior Mortgage Loan
INDUSTRIAL
MULTIFAMILY
MULTIFAMILY
$ 18 M
$ 55 M
$ 39 M
Bridge Whole Loan
Senior Mortgage Loan
5-Year Floating Rate Bridge Whole Loan
Phoenix, AZ
5-Year Fixed Rate Senior Mortgage Loan
New York, NY
5-Year Floating Rate
Denver, CO
15-Year Fixed Rate
STUDENT HOUSING
GROCERY-ANCHORED RETAIL
MULTIFAMILY
$ 93 M
$ 25 M
$ 83 M
Construction Whole Loan
Senior Mortgage Loan
Bridge Mortgage Loan
Gainesville, FL
5-Year Floating Rate
Sparta, NJ
15-Year Fixed Rate
Nashville, TN
5-Year Floating Rate
BRIEFS
COURTESY OF CBRE
JPMorgan Chase to Open First Permanent Office in Fort Lauderdale
BANK ON IT: JPMorgan plans to host 40 workers at The Main Las Olas.
JPMorgan Chase signed a 15,054-squarefoot lease at The Main Las Olas office tower in Downtown Fort Lauderdale, landlords Shorenstein and Stiles Corporation announced last week. The bank is now temporarily stationed inside a Regus location less than a mile away at the Las Olas Square complex, which Stephen Ross’ Related Companies and CP Group bought for $145 million earlier this year. JPMorgan Chase plans to relocate to The Main Las Olas next year, Simon Levine, managing director and head of the Southeast region for JPMorgan’s private bank, told Insider. The bank aims to grow the office to 40 employees by 2025, up from just 15 now. The firm already has offices in Palm Beach, an island town that at least 33 billionaires call home, and in Brickell, Miami’s financial district. (JPMorgan, too, is the largest private occupier of office space in its homebase of Manhattan.) Over the past two years, financial firms have largely neglected Fort Lauderdale. They’ve instead opted to open offices in West Palm Beach, thanks
to its proximity to Palm Beach, and in Miami, which boasts an emerging tech scene. JPMorgan is bucking the trend and wants to tap into Fort Lauderdale’s high net worth population, which grew during the pandemic as Northerners relocated down south. “Proximity does matter,” Levine said. The Main Las Olas is located at 201 East Las Olas Boulevard, adjacent to Southeast Third Avenue. The 25-story property, completed last year, offers 387,402 square feet of office space and is now 93 percent leased, according to its owners. Other tenants include industrial powerhouse Prologis, which occupies just under 5,000 square feet, and Synovus Bank, which took 22,226 square feet. Asking rates for the remaining vacant offices range between $48 and $50 a foot triple net. A representative for the landlord declined to divulge the length of JPMorgan’s lease. Danet Linares of Blanca Commercial Real Estate represented Shorenstein and Stiles Corporation. CBRE’s Zach Wendelin and Chase Deuschle, who represented the tenant, did not respond to a request for comment. —J.E.
The New York City Council on April 28 gave the thumbs up to two residential buildings in Prospect Heights, Brooklyn, that were nearly shot down by the newly elected local council member. EMP Capital’s development at 1034-1042 Atlantic Avenue and Y&T Development’s project at 870-888 Atlantic Avenue would bring a combined 438 apartments to the neighborhood and were approved after the developers listened to Councilmember Crystal Hudson on increasing their affordable housing component. Under the revised plans, each developer committed to reserving 35 percent of each building’s floor area for families making between $38,000 and $57,000, 10 percent more affordable housing than is required under the city’s mandatory inclusionary housing law. The measure allowing the developments to move forward passed the City Council by a vote of 49 in favor, one opposed, and one abstention, according to Hudson’s office. The approval process for these two projects started before Hudson took office in January. Upon being sworn in, Hudson made moves to halt the development unless EMP Capital and Y&T Development agreed to another deal. As the City Council almost always votes in deference to the local council member on matters of land use, Hudson issued an open letter to the City Planning Commission stating that she would vote against the plan unless the developers went back to the drawing board on their proposals.
10
| MAY 3, 2022 | COMMERCIAL OBSERVER
= EMIL COHEN/NYC COUNCIL MEDIA UNIT
NY City Council Approves Two Brooklyn Projects After New Deal
ALL POLITICS IS LOCAL: The two developments fell within the Brooklyn district of City Councilmember Crystal Hudson. The last time the City Council did not vote in line with the local representative was in late 2021 when the New York Blood Center’s new 310 East 67th Street location passed despite opposition from then-Councilmember Ben
Kallos, who was term-limited with just weeks left in office. As April 28’s meeting came to a close, Hudson said she had managed to negotiate for a total of 150 additional units of affordable
housing across both projects. Plans call for 228 units at 870-888 Atlantic Avenue and 210 apartments at 1034-1042 Atlantic Avenue. The developers did not respond to requests for comment. —M.H.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
Dynamic Thinking, Innovative Approach Newmark congratulates Jordan Roeschlaub and Dustin Stolly on being selected to the Commercial Observer’s 2022 Power 50 list of the “Most Powerful Figures in Commercial Real Estate Finance.”
J O R DA N R O E S C H L AU B
D U S T I N S TO L LY
Vice Chairman and Co-Head, Debt and Structured Finance
Vice Chairman and Co-Head, Debt and Structured Finance
We appreciate your invaluable contributions to Newmark’s Debt, Equity & Structured Finance practice, and for being leading members of our Capital Markets platform. Congratulations to all of the honorees.
nmrk.com
New York: 125 Park Avenue, New York, NY 10017 | t 212-372-2000
LEASES
Lease Deals of the Week Wellington Management 71,000 New Private investment firm Wellington Management is opening its first New York office in a new boutique office building in Greenwich Village, continuing a trend of finance and tech firms looking for space outside of Midtown. The firm, which has $1 trillion in assets under management, leased 71,000 square feet at Columbia Property Trust’s 799 Broadway, according to Bloomberg. Wellington will anchor the building with 250 employees who have been working remotely or commuting to the firm’s Boston headquarters. Two other tenants have already inked office deals at 799 Broadway, which was developed last year with an eye toward pandemic concerns such as ventilation and outdoor space. Online mortgage lender Newrez took 25,000 square feet in the building, followed by Bain Capital Ventures with 8,756 square feet. Asking rents in the building are $175 per square foot, a source with knowledge of the deal said. JLL’s Mitchell Konsker, Benjamin Bass and Sam Seiler represented the landlord. Steven Rotter and Randy Abend, also of JLL, brokered the deal for Wellington. A JLL spokesperson didn’t respond to a request for comment on the deal.—Rebecca Baird-Remba
12
Restaurant Depot 64,065 New
A large Restaurant Depot store is coming to the western shore of Staten Island. The wholesale food supplier leased 64,065 square feet at 17451801 South Avenue, an open-air shopping center in an industrial area near the Arthur Kill waterfront, a representative for owner A&H Acquisitions confirmed. Asking rent for the space was $25 a square foot, according to TradedNY, which first posted about the lease. Alex Adjmi’s A&H handled the transaction internally. Metropolitan Skyline’s Allie Beyda represented the tenant. Both sides declined to comment. Other tenants in the Travis shopping center include Dollar Tree, the New York State Department of Motor Vehicles, Planet Fitness, Burlington Coat Factory and Chuck E. Cheese. The 681,000-square-foot shopping center is on South Avenue between Meredith Avenue and the West Shore Expressway, and is largely surrounded by industrial businesses, including Big Apple Ready Mix, the Metropolitan Transportation Authority’s Meredith Bus Depot, Richmond Recycling and City Asphalt. Also nearby is Amazon’s JFK8 distribution center. Restaurant Depot — also known as Jetro — has locations in several other parts of the city, including Gowanus and Canarsie in Brooklyn, College Point and Maspeth in Queens, and Oak Point in the Bronx.—R.B.R.
| MAY 3, 2022 | COMMERCIAL OBSERVER
Verition Fund Management
Brennan Center for Justice
38,000 Relocation
25,476 Expansion
Greenwich, Conn.-based hedge fund Verition Fund Management has relocated its New York City office and more than quadrupled its footprint in one fell swoop. The firm took 38,000 square feet on the 35th floor of HNA Group’s 245 Park Avenue, a sizable increase from the 8,500 square feet it leased nearby at 230 Park Avenue, Bloomberg reported. With the new office up and running as of April 25, the hedge fund, co-founded by Nick Maounis and Josh Goldstein, is offering its workers a full kitchen, a lunchroom, ample work areas and high ceilings with the new location, according to Bloomberg. Verition did not respond to a request for comment, and it is unclear who brokered the deal. The company has greatly expanded its workforce since the pandemic began, bringing on an additional 100 people organization-wide and its total headcount to 275, Bloomberg reported. Verition joins private equity firm Midocean Partners, the U.S. headquarters of French bank Societe Generale and alternative asset manager Ares Capital in the 1.7 million-square-foot 245 Park. —Mark Hallum
Nonpartisan law and policy institute the Brennan Center for Justice upped its presence at Silverstein Properties’ 120 Broadway by 25,476 square feet, the landlord announced. Brennan Center currently has 24,409 square feet in the property, known as the Equitable Building, and the deal brings its presence to 49,885 square feet, Silverstein said. It’s unclear when the nonprofit first moved into 120 Broadway. A spokesperson for Silverstein declined to provide the length of the lease but said the asking rent was in the mid-$60s per square foot. The Brennan Center’s expansion is one of eight deals recently signed at the property, including The Original BARK Company taking 52,000 square feet and lobbying firm Kasirer signing on for 11,035 square feet. “Each of these companies chose 120 Broadway as their home for different reasons,” Harlan Strader, vice president of leasing at Silverstein Properties, said in a statement. “The one thing they all have in common is access to an amenity program unlike anything else in the city.” Silverstein handled the deal in-house via Strader and Joseph Artusa, while the Brennan Center was represented by CBRE’s Stephen Eynon. A spokesperson for CBRE declined to comment.—M.H.
BECOME A COMMERCIAL OBSERVER MEMBER
Felicity House 24,375 Relocation
Nonprofit Felicity House will move its offices to a recently converted parking garage at 23 West 20th Street, Commercial Observer has learned. The organization — which runs a free community space for women with autism — signed a 15-year deal for 24,375 square feet on the fifth through seventh floors of the Flatiron District property between Avenue of the Americas and Fifth Avenue, according to landlord brokers Newmark. A spokesperson for Newmark declined to provide the asking rent. Felicity House is currently located at a nearby townhouse at 25 East 22nd Street and plans to move to its new digs in the first quarter of 2023, Newmark said. The group was founded in 2015 by Audrey Cappell and is one of three nonprofits tied to Cappell’s family organization, the Simons Foundation, to ink deals at 23 West 20th and take over the property’s entire office space, Newmark said. Eric Cagner, David Falk, Alex Leopold and Jordyn Comras of Newmark represented the landlords, Skyway Development Group and The Kash Group. Cushman & Wakefield’s Carri Lyon and Mark Mandell handled the deal for Felicity House. A C&W spokesperson declined to comment. “It was great to work through the nuances of three independent leases simultaneously and come away with new spaces for these meaningful and important foundations to call home,” Cagner said in a statement.—Nicholas Rizzi
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
LEASES
Lease Deals of the Week Foundation for a Just Society
Michelman & Robinson
Mount Sinai Health System
21,517 Relocation
19,871 Relocation
17,464 New
Foundation for a Just Society, a nonprofit that advocates for the rights of women and LGBTQ+ people, inked a deal for 21,517 square feet at a parking garage converted to offices at 23 West 20th Street, Commercial Observer has learned. The organization signed a 15-year lease for part of the second floor and the entire third and fourth floors of the Flatiron District property, according to Newmark, which brokered the deal for landlords Skyway Development Group and The Kash Group. A Newmark spokesperson declined to provide the asking rent. The Foundation for a Just Society is tied to the Simons Foundation and will share the second floor with the AC & JC Foundation, the private philanthropic group of Simons Foundation Founder James Simons’ daughter, Audrey Cappell, and her husband, Jacob Cappell. Three nonprofits related to the Simons Foundation took over the entire office space at 23 West 20th, leaving just the property’s 5,322-square-foot retail space available to rent. Newmark’s Eric Cagner, David Falk, Alex Leopold and Jordyn Comras brokered the deal for the landlords. Carri Lyon and Mark Mandell of Cushman & Wakefield represented the Foundation for a Just Society. A spokesperson for C&W declined to comment.—N.R.
Regulatory and transactional law firm Michelman & Robinson snagged 19,871 square feet at Fisher Brothers’ 605 Third Avenue, according to the landlord. The company took the entire 30th floor of the 44-story tower between East 39th and East 40th streets for 10 years, according to a representative for the landlord. Asking rent was between $70 and $80 per square foot. “As a firm, we’re absolutely committed to our presence and continued growth in New York City — a commitment that’s reflected in our decision to lock into a lease for the 30th floor of this extraordinary building,” Jeep Jensen, COO at Michelman & Robinson, said in a statement. The California-based law firm will relocate from its 11,300-squarefoot offices at 800 Third Avenue in October, a representative from the landlord said. It will join investment manager Global X Fund, media company Univision and engineering business Aecom at the 1.1 million-square-foot 605 Third. Fisher Brothers’ Marc Packman, Charles Laginestra, Clark Briffel and Josh Fisher handled the deal for the landlord in-house, with Cushman & Wakefield’s Bruce Mosler, Lou D’Avanzo, Andrew Ross, Michael Baraldi and Maria Travlos. Newmark’s Scott Brown represented the tenant. C&W did not respond to a request for comment, and Brown declined to comment. —Celia Young
Mount Sinai Health System’s plans for a new cardiology office in NoMad are anything but halfhearted. The hospital network will open a 17,464-square-foot medical center at 373 Park Avenue South in early fall, Commercial Observer has learned. Mount Sinai’s 10-year deal puts the new outpost on the top two floors of the 12-story building between East 26th and East 27th streets, according to a representative for the landlord, ATCO Properties & Management. Asking rent was $59 per square foot. “We’re thrilled to be able to accommodate Mount Sinai’s needs for its new cardiology center and provide the neighborhood with another important health and wellness amenity,” ATCO’s Kate Goodman, who represented the landlord in-house, said in a statement. The medical system — which operates eight hospitals in New York City — closed on the deal in April, according to a representative from ATCO. It will sit above sports betting software developer Simplebet, which snagged the entire ninth floor of the 110,000-square-foot building last July. Hemsley Spear’s Leonard Zimmerman represented Mount Sinai. Zimmerman and Mount Sinai did not respond to requests for comment.—C.Y.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
City Winery
National Alliance on Mental Illness of NYC
15,888 New
14,000 Relocation
City Winery is set to become the Metropolitan Transportation Authority’s newest tenant at Grand Central Terminal. The company signed a threeyear, $4.5 million licensing agreement with the MTA for a 15,888-square-foot section of the Vanderbilt Hall West section of the train station, according to documents from the agency’s finance committee. Formerly home to the Great Northern Food Hall, the deal is the result of a September 2020 request for proposals seeking a vendor for the space. But the RFP was terminated in November 2020 due to a lack of interest, and CBRE began helping the MTA find shortterm tenants, according to the documents. City Winery submitted a letter of intent in August 2021 and was chosen because of its existing customer base in locations such as Pier 57, Rockefeller Center and Greenwich Village. It plans to operate this location as a gastropub with a farm-totable menu and a grab-and-go retail operation, according to the MTA. City Winery and the MTA did not respond to requests for comment. Michael Dorf, CEO of City Winery, told Gothamist he was not at liberty to speak about the transaction until the lease is finalized. City Winery will pay the MTA $500,000 for the first year along with 8 percent of gross sales, similar to the deal with Cipriani for its restaurant in Grand Central.—M.H.
The New York City branch of the National Alliance on Mental Illness (NAMI) inked a deal to nearly triple its footprint when it relocates to 307 West 38th Street in the Garment District. The nonprofit signed an 18-year sublease with the HIV/AIDs nonprofit Gay Men’s Health Crisis (GMHC) for 14,000 square feet across part of the eighth floor of the 21-story George Comfort & Sons building, according to Colliers’ David Kaplansky, who represented the tenant in the transaction. Asking rent was $35 per square foot. “Everyone deserves help, and everyone can get help,” Kaplansky said. “It’s a great feeling to be able to provide a transaction that allows these guys to do [this work].” NAMI currently leases 4,800 square feet at 505 Eighth Avenue, but Kaplansky said the alliance needed more room because of growing demand for its programs. The nonprofit offers classes, support groups and other resources to 30,000 people affected by a mental illness each year, and the larger space will let the organization resume in-person programming when it moves in the summer, according to Matt Kudish, NAMI’s executive director for its NYC branch. GMHC shr unk its 110,000-square-foot headquarters at the building to let NAMI take part of the eighth floor, Kaplansky said. Noah & Co.’s Benjamin Blumenthal represented the sublandlord in the deal. Blumenthal declined to comment.—C.Y.
COMMERCIALOBSERVER.COM
| MAY 3, 2022 | 13
Realize Anything
From I.D. scanners to DOAS systems to self-adjusting solar panels—tomorrow’s spaces need to keep up. We’ll help you integrate all the small parts into one intelligent system—making buildings interconnected and more efficient. Connect all the dots, so you can realize anything.
cbre.com
2022 This past year was one for the books ... By Cathy Cunningham with Andrew Coen, Emily Fu, Larry Getlen, Sara Pepitone and Patrick Sisson.
choppy waters, but — after the past two years — our honorees have got this. They each continue to demonstrate exactly why they’re among the most powerful individuals in commercial real estate finance. As with last year’s list, we didn’t solely focus on the numbers in the ranking. Instead, we took a more holistic view. Sure, this is a finance list and numbers are important, but we also looked at where and how our honorees added value to the market. We believe diverse teams and companies are the strongest ones, so we asked each firm to clearly outline its diversity, equity and inclusion initiatives, and how they’re facilitating long-overdue change in our industry. Within the originations data, we considered: Who expanded product offerings? Who demonstrated a forward-looking approach while uncertainty prevailed? Who showed flexibility and creativity? Who kept the financing ecosystem thriving and played integral roles in their clients’ success? Every single honoree on this list did, and we tip our hat to you all.
COMMERCIALOBSERVER.COM
| MAY 3, 2022 | 15
ILLUSTRATION BY JALACARA
I
t was a record year,” was undoubtedly the catchphrase of this year’s Power Finance list — and our honorees never worked harder to make it so. Their tireless perseverance and commitment to their clients, and the market, was clear in the pages of Commercial Observer throughout the past 12 months, and in our interviews for this list. It was a year of change, a year of recovery and a year of action. And those on this list were the vital engines behind some of commercial real estate’s most high-profile and important financings, helping borrowers execute their business plans, expand into new sectors, seize opportunity when it arose and traverse market volatility. After a rocky 2020, lenders stepped up their game to compete — big time — pivoting and adapting where needed to meet market conditions in addition to borrowers’ needs. Advisory firms worked their socks off securing both debt and equity for transactions across asset types — finding capital providers for even the hairiest of deals, as well as the most coveted ones. The start of 2022 brought plenty of
Ed Adler.
Kara McShane.
Head of Commercial Real Estate at Wells Fargo Last year’s rank: 7
It was a record year for the majority of Commercial Observer’s Power Finance honorees, and Wells Fargo was certainly no exception, closing a whopping $84.8 billion in transactions. “I think of 2021 as a complete contrast to 2020,” Kara McShane said. “I got into the seat as head of commercial real estate in February of ‘20, a month before the pandemic. So, that year was a complete baptism by fire, whereas 2021 was a completely different year. It gave me the opportunity to fully focus on our strengths and capabilities.” Unlike many of its competitors, Wells Fargo’s various offerings are consolidated under one powerful leader in McShane, allowing the firm to pivot between balance sheet and capital markets executions as needed. Wells Fargo reinforced its commitment to
16
the capital markets with gusto — to say the least — originating its highest commercial mortgage-backed securities (CMBS) volume to date and leading some of the most buzzedabout single-asset single-borrower (SASB) executions of the year, including the behemoth One Vanderbilt transaction. The $3 billion, fixed-rate SASB CMBS deal on the iconic office tower was the largest single-property CMBS financing ever and the largest green bond offering done in the U.S. so far. The deal held personal significance for McShane, who also led the building’s construction loan in 2016. The refi closed at a time when “New York City office” was the equivalent of a swear word, but “to me, it was a testament to the fact that when you build first-rate buildings, and when you’re paying attention to what your
| MAY 3, 2022 | COMMERCIAL OBSERVER
tenants want in terms of best-in-class properties and ESG, there’s really good demand for that product,” McShane said. The bank also dug further into COVID19-resistant asset types — such as industrial, multifamily, life sciences, data centers and cold storage — and upped its focus on ESG-oriented financings as well as diverse segments. Other transactions included a $1 billion revolving credit facility for Brookfield Property REIT associated with a strategic recapitalization; a $750 million term-loan facility for Hackman Capital and Square Mile’s acquisition of Culver Studios in Los Angeles — fully leased to Amazon; and the $426.7 million portion of a $1 billion whole loan, 10-year, fixed-rate single-asset CMBS transaction for the refinance of 601 Lexington Avenue, a 1.7
BECOME A COMMERCIAL OBSERVER MEMBER
million-square-foot, Class A office tower in Midtown known as Citigroup Center. Wells Fargo also financed over $8 billion of affordable housing via debt and equity. Its community lending and investment group had a banner year, with $5.7 billion in originations — up 27 percent from 2020 — delivering and preserving 18,785 affordable housing units. Its 2021 ESG production efforts included $1.22 billion of green lending activity. Under McShane’s leadership, too, Wells Fargo’s commercial real estate operating committee has grown to 52 percent gender and racially diverse, and McShane’s direct leadership team is now 27 percent gender and racially diverse. “That was very intentional,” she said. “But, I targeted the best talent, and those were the results. So, I’m very pleased with that.” —C.C.
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
YVONNE ALBINOWSKI/FOR COMMERCIAL OBSERVER
1
Kara McShane
BANK OF CHINA U.S.A. Enables our valued clients with bespoke financing solutions
NEW
YORK
CITY
|
CHICAGO
|
LOS
ANGELES
We Congratulate Our Power 50 Finance Commercial Real Estate Team
BUILDING TRUST AND RELATIONSHIPS | Across the continental United States FINANCING SKYLINES | One loan at a time W W W. B O C U S A .C O M
2
Brian Baker, Al Brooks and Michelle Herrick Global Head of Commercial Mortgages at JPMorgan Securities; Managing Director and Head of JPMorgan Chase Commercial Real Estate; Head of Real Estate Banking at JPMorgan Chase
Origination records were shattered across this list, and JPMorgan Chase came to play. In 2021 alone, the firm’s commercial mortgage originations totaled $54.6 billion, 67 percent higher than its 2020 firmwide originations of $33 billion. The majority of those loans were for multifamily, with $4.5 billion of $26 billion in total multifamily originations going to properties with restricted rents. The firm credits its fortress balance sheet as its competitive advantage, enabling it to support clients with acquisitions of sizable portfolios and involved in other large-scale transactions. Then, of course, there are its people. “I was super proud of how focused the team was, whether it was in Community Development Banking, Real Estate Banking headed up by Michelle Herrick, or our Commercial Term Lending business under Ed Ely’s leadership — all three had a fantastic year,” Al Brooks said. “That success has carried right into this next year. The first quarter was the best we’ve had in the history of the business. We spend a lot of time selecting who
3
Al Brooks.
Brian Baker.
Last year’s rank: 3
we believe are the best clients in the industry, and they’re performing beautifully through market challenges. If you look back, besides the pandemic — which was more of a massive natural disaster than a true economic recession — we’ve had the Russia-Ukraine war and runaway inflation. Through all that our customers just keep performing. So, I tip my hat to how well they run their businesses. The fundamental thing I think they do extremely well is they treat their tenants right.” JPMorgan also worked to support clients developing new supply in some markets where populations had shifted, Herrick said: “We also stayed busy on larger stabilized portfolio transactions, given our execution capabilities to move quickly on complex transactions.” The firm closed two financings for New York City Housing Authority (NYCHA) Brooklyn projects. For NYCHA’s Williamsburg Houses, it provided $223 million in construction lending for the rehabilitation of 1,630 units in 21 buildings, and a $141 million direct equity investment in both New York state and
Michelle Herrick.
federal historic tax credits (HTCs). For NYCHA’s Boulevard Houses, it provided $268 million in construction lending and $9 million in predevelopment lending for the rehabilitation of 1,673 units in 29 buildings, as well as $142 million in direct equity investment in state and federal HTCs. The firm also rolled out its affordable housing preservation program, preserving more than 35,000 units, and surpassed its $2.5 billion goal for last year in August. Brian Baker’s corporate and investment banking group racked up $21.5 billion in originations, up from $17 billion the previous year, and ranked No. 1 in terms of agency commercial mortgage-backed securities (CMBS) book runners in 2021. Newsworthy deals included $600 million of financing to A&E Real Estate for 53 rent-regulated residential buildings in New York City; the $4.65 billion CMBS financing for Extended Stay America, of which JPMorgan took the lion’s share with $2.33 billion; and a $1.4 billion construction loan for Witkoff’s
mixed-use development at 76 11th Avenue in West Chelsea. “We did a CMBS financing on a portfolio of affordable housing — which is a topic of big focus these days — and we’re very proud of that transaction,” Baker said of the A&E deal. “There were several complexities, but we wanted to do an ESG-focused, affordable, impactful transaction. And we were very successful there.” As 2022 progresses, Baker is keeping an eye on the CRE collateralized loan obligation (CLO) market, in which his team plays an integral role as a financing bank for smaller lenders. “As a result of the recent market volatility, there’s definitely been a pause, and spreads are significantly wider,” he said. “But, we have six deals that are coming in the next month, and we think those deals will unpause things.” Regarding diversity, equity and inclusion, JPMorgan’s CRE leaders won several industry awards highlighting progress in that area in 2021. —C.C.
Michael Eglit, Tim Johnson, Katie Keenan and Jonathan Pollack Head of U.S. Originations for Blackstone Real Estate Debt Strategies; Global Head of Blackstone Real Estate Debt Strategies; CEO of Blackstone Mortgage Trust and a Senior Managing Director in Blackstone Real Estate Debt Strategies; Global Head of Blackstone’s Structured Finance Group Last year’s rank: 4
18
in Brooklyn. While the firm had plenty of competition for deals, “we were able to do a ton of business with folks that had put their trust in us prior to 2021, and were happy to win that trust again in 2021,” Johnson said. Blackstone continued to add to its originations team as it tackled this increased volume. It also further built out its capital markets and asset management teams, which Johnson described as “a huge value-add to our business.” “Economics matter, but the experience matters as well,” Johnson said. “How we treated our borrowers during COVID really helped us in our 2021 originations.” Newsworthy deals were plentiful, including Blackstone Mortgage Trust’s (BXMT) $491 million loan for the acquisition and conversion of Charles Park One
| MAY 3, 2022 | COMMERCIAL OBSERVER
Michael Eglit.
Tim Johnson.
& Two in Cambridge, Mass., into a life sciences campus, and the $500 million construction loan for Brookfield’s Eagle + West (formerly Greenpoint Landing) multifamily project in Brooklyn. “We had an instinct that New York City multifamily was going to recover well, but to be able to have the data to back up that instinct and look at our own portfolio — both on the equity and the debt side— to access real-time information was key,” Johnson said of the Eagle + West deal. And, who can forget the Blackstone Real Estate Debt Strategies-led $584 million mortgage and senior mezzanine debt package for L&L Holding Company and Tokyu Land Corporation’s 425 Park Avenue?
BECOME A COMMERCIAL OBSERVER MEMBER
Katie Keenan.
Jonathan Pollack.
Johnson said it was “a really good example of exactly how we’re looking at office — both in New York City and in other markets. We look for markets that are dynamic in terms of tenant demand, and newly built or renovated assets that are more in demand by tenants than they ever have been.” Then, as if that wasn’t enough, the firm launched its new Structured Finance Group last November, which is headed by Pollack. The Blackstone team has also recommitted this past year to increasing diversity, equity and inclusion within its ranks. One-third of its leadership team is diverse today; Katie Keenan was appointed CEO of BXMT in June 2o21, overseeing its most active year yet. —C.C.
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: COURTESY OF JPMORGAN CHASE, COURTESY OF BLACKSTONE
Blackstone Real Estate Debt Strategies closed $22.7 billion in transactions this past year — compared with $10 billion the year before — in the platform’s most active loan originations year yet. “The momentum that we’ve built in our business over the past decade-plus, has really continued to grow,” Tim Johnson said. “Across our platform to date, we’ve made over $100 billion of loans, and we’ve got close to 500 underlying borrowers. That’s a great starting point when you come into any year.” Success begets success, and Blackstone continued its modus operandi of lending on high-quality assets with dynamic sources of demand, such as highly coveted multifamily assets, modern and well-amenitized office projects, and irreplaceable real estate such as Industry City
$114 OVER
BILLION GLOBAL DEBT TRANSACTIONS CLOSED SINCE JANUARY 2021 Eastdil Secured congratulates Grant Frankel, Rob Turner, Ken Ziebelman, and all honorees in the 2022 Power 50.
New York • Los Angeles • London • San Francisco • Atlanta • Boston • Charlotte • Chicago • Dallas • Dubai • Dublin Frankfurt • Hong Kong • Miami • Milan • Orange County • Paris • Seattle • Silicon Valley • Tokyo • Washington, DC
www.eastdilsecured.com
ANDY ROBERTS/GETTY IMAGES
A Record Year Market conditions made CRE lending a fruitful business in 2021, and our firms were ready to compete By Cathy Cunningham | Illustration by Britt Spencer “It’s the eye of the tiger, it’s the thrill of the fight. Rising up to the challenge of our rival.” — Survivor
O
nce our Power Finance honorees absorbed the brutal one-two punch that COVID-19 delivered in 2020, they were ready to get back into the ring in true Rocky Balboa style. And with market conditions firmly on their side, everyone on this list came out fighting, racking up some record-smashing origination activity across the board — despite heavyweight competitors vying for the championship belt. “It was a record year for most people,” Starwood Property Trust’s Jeff DiModica said. “And, if it wasn’t a record year for you, you should probably reconsider what you’re doing for a living, because the amount of
20
transactions was off the charts.” Damn, DiModica. (But also … where’s the lie?) Indeed, in 2021 lending conditions were sent from the heavens above, facilitating origination numbers worthy of Guinness World Records: Real estate continued its reign as a safe haven asset class for investors looking to deploy pent-up capital, interest rates remained fairly low, and the world returned to some vague sense of normalcy in 2021— with the exception of omicron stepping in as the Grinch who stole Christmas, just as everyone was ready to raise an eggnog to the festive season. As part of their record years, several firms further expanded their product offerings, meeting their borrowers’ needs while also boosting revenue streams. “For us, things continued to build
| MAY 3, 2022 | COMMERCIAL OBSERVER
throughout the year, and we had record deployment across property types and borrowers,” Apollo’s Scott Weiner said. “There was also a shift to bigger first mortgages, whereas I would say historically mezzanine financing has always been part of our DNA.” Others further established their national — even international — footprints, following clients wherever they needed financing. “It really was a record year for us,” Cushman & Wakefield’s Rob Rubano said. “I feel really good about how we’re positioned nationally, with the biggest borrowers and top institutional clients.” Others utilized all of their capabilities to duck the market’s jab, cross and hooks, and serve their clients. Case in point: When the bond market got choppy at the end of the year, some lenders who’d enjoyed a peak performance BECOME A COMMERCIAL OBSERVER MEMBER
single-asset, single-borrower CMBS market earlier in 2021 flipped executions to the balance sheet side of their business to make sure deals closed without delay. “There aren’t a lot of groups who could step up last December for a $740 million balance sheet loan,” Barclay’s Larry Kravetz said, adding: “We execute when we say we’re going to,” he added. Damn straight, Kravetz. Throughout this past year, our Power Finance honorees proved their might in the market, and broke records despite all the punches thrown at them, including 2022’s extreme market volatility. As Rocky Balboa said: “It ain’t how hard you hit. It’s about how hard you can get hit, and keep moving forward. How much you can take, and keep moving forward. That’s how winning is done.”
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
Driving innovation. Delivering solutions. NewPoint is creating new opportunities in real estate finance by innovating processes, structures and solutions. We’ve brought together the most experienced professionals in the industry to deliver the best financing execution and servicing for our clients.
Reimagining real estate finance. NEWPOINT.COM Equal Housing Lender Any loans or terms referenced herein are subject to receipt of a complete application, credit approval, and other conditions. This is not a commitment to lend. To view NewPoint’s complete licensing information please visit newpoint.com/licensing-disclosures. ©2022 NewPoint Real Estate Capital LLC All rights reserved.
4
Steven Caldwell.
Francis Gilhool.
Kristin Khanna.
Larry Kravetz, Steven Caldwell, Francis Gilhool and Kristin Khanna Managing Director and Head of CMBS Finance; Managing Director and Head of Originations; Managing Director and Head of CRE Warehouse Lending; Managing Director, Head of Balance Sheet Loan Syndications and Head of Acquisition Facility Lending at Barclays Capital Last year’s rank: 12
“Fluent in Finance” was Barclays’ slogan almost 20 years ago, and it’s safe to say that aptitude hasn’t changed. The bank executed record activity in all areas of its business this past year, providing $22.6 billion of financing and tripling its $7.7 billion in closings the previous year. Blimey! Barclays brought multiple capabilities to bear, closing $9.1 billion in conduit and single-asset, single-borrower (SASB) commercial mortgage-backed securities (CMBS) transactions, $3.4 billion in syndicated balance sheet loans, $1.5 billion in acquisition facilities and $8.6 billion in warehouse financing facilities. It was also a lead bank in some of the most noteworthy mergers and acquisitions (M&A) transactions, and a pioneer in leading the first data center M&A transaction in the commercial real estate space — Blackstone’s $9.68 billion take-private of QTS — as well as the second take-private transaction, KKR and GIP’s $14 billion acquisition of CyrusOne. As for other notable deals? Where to start. There was the $1.1 billion refinancing of a portfolio of five Class A office properties and three studio facilities in Hollywood, Calif., for Blackstone Property Partners and Hudson Pacific Properties; the $380 million STWD 2021-LIH CMBS deal, which was the first 100 percent low-income housing tax credit (LIHTC) for affordable housing SASB with 100 percent environmental, social and governance bond designations; and the $740 million financing for Blackstone Real Estate Income Trust’s acquisition of a portfolio of 13 Class A multifamily properties across seven states, to name a few. “There aren’t a lot of groups who could step up last December for a $740 million balance sheet loan,” Larry Kravetz said of the latter deal, which closed in only three weeks. “We execute when we say we’re going to.”
22
“What we were seeing in the second half of 2021, as far as balance sheet lending opportunities went, tended to be construction or transitional multifamily opportunities,” Kristin Khanna said. “This was one of the first opportunities we saw to lend at scale on a stabilized multifamily pool.” Multifamily comprises the bulk of Barclays’ lending book (46 percent), followed by office (22 percent) and industrial (17 percent). The firm doesn’t shy away from retail, however, providing its clients in the space with some much-needed liquidity. Case in point, the $600 million refinancing of The Florida Mall in Orlando, Fla., for Simon Property Group and Nuveen Real Estate — the largest mall SASB transaction post-COVID-19. “There’s significant relative value in the way mall deals are executing compared to multifamily and industrial, which are priced much tighter,” Steven Caldwell said. “There’s certainly a ‘have and have-nots’ discussion in terms of credit profiles, but we felt like this asset was going to have strong investor demand, and that certainly was the case.” Barclays has been busy building out its secondary trading and CMBS financing business, and it’s all part of a master plan. “What we’re trying to do, successfully, is to have every aspect of our franchise drive the origination business in order to meet our clients’ financing needs as they continue to expand their platforms,” Kravetz said. As such, “we’re in the process of a decent amount of lead left transactions,” Francis Gilhool said. “That really is the last piece of the puzzle that’s proving out the strength of our business and its sustainability.” Today, the Barclays team is approximately 30 percent minority and female. The team has a number of female leaders in the group, including Khanna. —C.C.
| MAY 3, 2022 | COMMERCIAL OBSERVER
Last year’s rank: 5
Citigroup was the lead bookrunner and loan contributor in the U.S. commercial mortgage-backed securities (CMBS) market in 2021, its third consecutive year at the top of Commercial Observer’s leaderboard. It amassed $21.9 billion in loan contributions across single-asset, single-borrower, or SASB, ($16 billion); conduit CMBS ($5 billion); and subordinate debt ($942 million). The bank was also lead book runner on $49.7 billion of product and arranged $20.7 billion of syndicated mortgage debt, for a total of $70.4 billion in U.S. activities. In a year where the Citi team earned top honors, one could say the firm showed broad proficiency. But in a classic overachiever move, Citi found newer and bigger types of deals to close in 2021, showing a relentless drive to diversify and evolve. “You can make a living redoing what you’ve done before,” said David Bouton. “But we like to find new opportunities and asset classes. When the markets are challenging, we like to be able to define opportunities within that.” In one year alone, the firm led the committed financing for StorageMart’s acquisition of Manhattan Mini Storage, a $2.08 billion deal covering 18 assets,
David Bouton.
BECOME A COMMERCIAL OBSERVER MEMBER
the largest CMBS self-storage financing ever executed. It acted as book runner and co-lender with JPMorgan Chase for the $4.65 billion take-private financing of Extended Stay America for Blackstone and Starwood, a portfolio of 567 assets that was the largest CMBS transaction nationwide since the pandemic began. And, it led the first-ever CMBS single-asset, single-borrower (SASB) collateralized by data center assets with Blackstone’s $10 billion acquisition of QTS Realty Trust. “We probably had over 100 one-onones with all the investors to educate them, so when we did go to market, they understood the industry drivers,” Bouton said. “Something as simple as going from square footage to megawatts, that was a big deal.” Starting the year with a heavy deal pipeline, Citi is poised for additional investment through 2022, including the investment it makes in diversity and equity behind its own doors. In addition to numerous industry awards for promoting a diverse and inclusive workspace, the firm has donated roughly $1 billion to efforts to close the racial wealth gap. Despite the uncertainty shaping the market, it’s certain there are opportunities for creative problem solvers. —P.S.
Joseph Dyckman.
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: CHRIS SORENSON./FOR COMMERCIAL OBSERVER, COURTESY OF WELLS FARGO
Larry Kravetz.
Co-Heads of U.S. CMBS at Citigroup
TOP TO BOTTOM: COURTESY OF BARCLAYS, COURTESY OF CITIGROUP
5
David Bouton and Joseph Dyckman
one team JLL congratulates the entire NYC debt team for their part in our recognition among the Power 50
Scott Aiese Kellogg Gaines Michael Gigliotti Geoffrey Goldstein Max Herzog Marko Kazanjian Steve Klein
Jillian Mariutti Aaron Niedermayer Evan Pariser Christopher Peck Brett Rosenberg Peter Rotchford Michael Shmuely
David Sitt Alex Staikos Mike Tepedino Robert Tonnessen Stephen Van Leer Michael Zaremski Eliott Zeitoune
#1 Debt Originations us.jll.com/capitalmarkets
© 2022 Jones Lang LaSalle IP, Inc. All rights reserved
Source: 2021 MBA rankings
6
James Flaum and Kwasi Benneh Global Head of Real Estate Lending; Head of Large Loan Origination and Syndication at Morgan Stanley Last year’s rank: 11
Morgan Stanley executed $21 billion of balance sheet and commercial mortgage-backed securities (CMBS) originations in the U.S. over the past year and helped deploy capital to borrowers in the sectors hardest hit by the COVID-19 pandemic. The investment banking giant’s impressive lending activity included $4.2 billion in office, $2 billion in retail and $1.1 billion of mall financings. It also ranked second in U.S. conduit securitizations last year. “2021 was a textbook year for lending, as well as investing,” James Flaum said. “Our origination numbers were very robust and it was a tighter market so there were good conditions to execute in.” Morgan Stanley’s loan portfolio as of March 9 consisted of 60 percent office, 12 percent industrial, 11 percent hospitality, 9 percent multifamily and 8 percent retail. It provided borrowers with a variety of debt strategies to navigate market conditions, including bridge lending, revolving credit facilities and peer-to-peer
Kwasi Benneh.
Jeffrey DiModica and Dennis Schuh President and Managing Director; Chief Originations Officer at Starwood Property Trust Last year’s rank: 8
Starwood Property Trust closed $15.9 billion in transactions this past year, a significant bump from its $4 billion the previous trip around the sun. “It was a record year for most people,” Jeffrey DiModica said. “And, if it wasn’t a record year for you, you should probably reconsider what you’re doing for a living, because the amount of transactions was off the charts.” The fourth quarter was especially stellar for Starwood, with roughly 40 percent of its originations being executed in those 90 days alone. “We still had plenty of liquidity and capital, and we were able to take advantage of opportunities in the market,” DiModica said. Pivoting when those opportunities beckon is par for the course for this duo, and, in the fourth quarter, the pair directed their attention to multifamily loans. “For the first time, we in real estate all agreed on one thing: Multifamily rents are going to be higher in 2022 than they were in 2021,” DiModica said. “It’s the only thing we’ve ever all agreed on.” With that in mind, the team found an advantage utilizing a forward-looking approach to underwriting deals, while some competitors relied on in-place income and last year’s cash flows. “If you bought a $100 million building in the fourth quarter, you might only have gotten $65 million from the agencies or the CMBS market, or $75 million-plus from someone like us who’s going to say, ‘Hey, we know rents are 20 percent higher, and you’ll roll them
24
James Flaum.
to market.’ It created a massive opportunity for us as nonbank lenders to really lean into multifamily.” Seventy-five percent of the $4.4 billion in loans written in fourth-quarter 2021 were multifamily or industrial — a record for the firm. Its funded multifamily loan book is up 138 percent versus a year ago, and is on pace to become Starwood’s largest property type, with an additional $1 billion of unfunded multifamily commitments presently in the works. Closed multifamily deals include a $295 million refinance for Onni Group’s Hope + Flower in L.A. and a $253 million loan for 54 Madison’s Life Time Coral Gables project in South Florida. Office still comprises 29 percent of the firm’s loan portfolio but “we’re being very selective,” Dennis Schuh said. “There’s a flight to quality in the market, and we’re following the jobs. If there’s an interesting office building like the one [DiModica’s] sitting in right now [Starwood’s new Miami office], we’d be very interested in that, but if it’s a Midwestern office building in an area with declining population and no rent growth, or a tenant market in terms of lots of concessions, we’re not interested.” Tishman Speyer’s The Wheeler, a creative office property in Downtown Brooklyn, was one opportunity that caught the team’s attention. “It’s a beautiful redevelopment above the old Macy’s,” Schuh said. “It’s being built by a best-in-class sponsor and half of the 600,000 square feet was already pre-leased.” —C.C.
| MAY 3, 2022 | COMMERCIAL OBSERVER
TOP TO BOTTOM: COURTESY OF MORGAN STANLEY, COURTESY OF STARWOOD
7
acquisition financing. Notable deals during the past 12 months included a $1.4 billion CMBS debt package for Oxford Properties to purchase a $2.2 billion industrial portfolio of 149 properties across seven states from KKR. The five-year floating-rate loan will be securitized in a single-asset, single-borrower transaction. On the balance sheet side, Morgan Stanley led an $860 million refinance in August for Paramount Group’s 1301 Avenue of the Americas, a 45-story Midtown Manhattan office tower. The deal marked one of the largest office refinances to close post-COVID-19 in New York City. Kwasi Benneh said the versatility to execute large balance sheet deals when the CMBS market cooled in the second half of the year proved instrumental to Morgan Stanley’s success. “There weren’t a lot of large shops that could execute large balance sheet deals,” Benneh said. “The demand was there and we really stepped up for our clients.” —A.C.
Jeff DiModica and Dennis Schuh.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
REAL ESTATE CREDIT
Relationship Focused Lending Expansive suite of lending solutions with flexibility across term, coupon type & size
> Fixed and Floating Rate > Loan sizes from $50mm to $1bn > Senior Secured to Mezzanine and Preferred
Multiple solutions. One provider.
Congratulations to Matt Salem, Patrick Mattson, Rene Theriault, and Joel Traut for their recognition amongst the top players of commercial real estate finance. To our clients, your trust and relationships are our most valued assets. We remain committed to being your partner and to delivering exceptional outcomes as your needs evolve.
REAL ESTATE FINANCE TRUST
@KKR_Co
/showcase/kkr-real-estate-finance-trust/
www.kkrreit.com
|
NYSE: KREF
Scott Weiner, Jason Ourman, Sang Yu and Aaron Welsh Partner and Global Head of CRE Debt; U.S. Partner; U.S. Partner; U.S. Partner at Apollo Last year’s rank: 15
Apollo’s lending platform continued to go from strength to strength last year, with the firm racking up $14.1 billion in originations. “For us, things continued to build throughout the year and we had record deployment across property types and borrowers,” Scott Weiner said. “There was also a shift to bigger first mortgages, whereas I would say historically [mezzanine financing] has always been part of our DNA.” Notable deals included a $565 million, five-year first mortgage to refinance a portfolio of 26 parking facilities on behalf of borrower Interpark Holdings, and a $212 million fixed-rate financing for Brookfield Real Estate Income Trust’s Dreamworks Animation Studios campus in Glendale, Calif. Apollo lent on “a little bit of everything, including office,” Weiner said. “We underwrite every deal, so it wasn’t like we crossed anything off and said, ‘We can’t do that because of COVID — or other reasons.’” And it showed. Apollo lends on behalf of its insurance company platform’s balance sheet, as well as its public mortgage real estate investment trust, providing financing across the capital stack, from long-term, fixed-rate deals to higher-yielding, floating-rate mezzanine loans.
26
Last year’s rank: 10
“We don’t think there’s anyone quite like us in the ecosystem,” Dustin Stolly said. “We’re sort of a hybrid, or an octopus, in terms of our varied debt and equity expertise, and we’re extremely proud of the volume and breadth of transaction activity that we’ve executed.” We don’t get many marine mollusk comparisons on the Power Finance list, but as far as tentacles that reach far and deep into the varied corners of the commercial real estate financing ocean go, Newmark has definitely got ‘em. The Newmark team negotiated 194 deals (or one every 1.8 days) in the 12-month period ending March 31, comprising $29.6 billion in debt, $3.02 billion in equity and $1.7 billion in loan sales, with an average transaction size of $197.7 million. The two started their business financing or raising capital around single assets, and they’ve evolved to a far more institutional realm. In addition to their core debt and equity practice, today they’re busy raising money around portfolios, platforms and companies. “It just keeps spiraling and progressing, like a snowball,” Jordan Roeschlaub said. “We’re reinventing the game, and I’ve never been more pumped in my life.” Highlights from the past year include the $2 billion recapitalization of the Graduate Hotel platform; a $525 million refinance of a 50-asset, 100 percent net-leased portfolio; the $258 million development loan for Related’s Truffles Tribeca — one of the first construction loans of consequence post-COVID-19; a plethora of New York City office deals, including a $178 million loan for 25 Kent Avenue and a $238 million refi for RFR Holding’s 980
Dustin Stolly and Jordan Roeschlaub.
9
Vice Chairmen and Co-Heads of Debt and Structured Finance at Newmark
Scott Weiner.
Jason Ourman.
Sang Yu.
Aaron Welsh.
Roughly $8 billion of Apollo’s volume was executed via its insurance company platform. “We did close to $3 billion of fixed-rate lending across
| MAY 3, 2022 | COMMERCIAL OBSERVER
Madison; a variety of hotel deals, including a $195 million refinance for GFI’s Beekman Hotel and a $230 million refinance of Witkoff’s West Hollywood EDITION; and portfolio financings for megaclients such as Blackstone, KKR, Starwood Capital and Angelo Gordon. Delving into alternative asset classes, the Newmark team also led the recapitalization of Port 32 — a leading owner, operator, developer and acquirer of Class A coastal marinas — enabling the company to accelerate its growth plans and also expand into new markets. While the market has experienced some choppy waters thus far in 2022, Newmark has embraced the opportunity to add value, acting as a “lightning rod for information” for clients, and finding a home for eager capital, Stolly said. He added, “We expanded our business to include platform capitalizations on asset classes that capital wants to be in, including industrial outdoor storage [IOS], life sciences and cold storage.” Case in point, in the IOS space alone, the team capitalized five platforms this past year. Carving out those additional niches to add to their portfolio is just one of the team’s skills. “I think we’re pretty good at seeing where there’s a crease in the marketplace, or an opportunity set for capital to find an entry point, and we run with it,” Roeschlaub said. “We’re never going to be complacent. We’re always looking ahead to get in front of what’s happening in the market.” Five of Stolly and Roeschlaub’s 14-person team are women today, and their two-year analyst program includes minorities every year.—C.C.
multifamily, self- storage and other property types; then we also did a lot of floating-rate debt,” Weiner said. Its differentiated balance sheet capital allowed it to offer clients a holistic solution for larger loans as well as provide certainty of execution and flexibility and creativity in structure. In many instances, Apollo provided large loans for both properties and portfolios, enabling it to offer borrowers a single source of capital. Further, the firm’s average loan size increased to upward of $200 million last year. When it comes to asset classes, “we very much like multifamily,” Weiner said, and although Apollo hasn’t shied away from office deals, or New York office, for that matter, Weiner described the firm as being “cautious” on the sector: “We have a large office exposure but we certainly prefer, and see more value in, newer office or recently renovated office — in terms of what tenants want.” The recent market volatility hasn’t been a terrible thing for the firm, either. “We’ve continued to close deals, and have picked up a bunch of transactions where the borrower got retraded by a different lender, or they’re coming to us and saying, ‘I don’t really trust that [commercial mortgage-backed securities] is going to be there,’” Weiner said. Weiner credits his entire team with Apollo’s success, including Catherine Chen and Ben Gray, U.S. managing directors, and also said that diversity, equity and inclusion is “critical” to the Apollo platform. “It makes us better,” he said. “Finance and private equity can always do better, but different perspectives and approaches to the business are key.” —C.C.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: SASHA MASLOV/FOR COMMERCIAL OBSERVER, COURTESY OF APOLLO
8
Dustin Stolly and Jordan Roeschlaub
Invesco Real Estate Credit Solutions
Built from global strength and local knowledge
Our relationship-driven credit solutions have generated over $14.6 billion of loans globally for our clients.
Invesco Real Estate congratulates
Charlie Rose, Yorick Starr, and Teresa Zien
on making Commercial Observer’s 2022 Power 50 Finance List.
For more information, please contact: iredebt@invesco.com invesco.com This is not an offer or a recommendation. $14.6 billion includes all loans closed by December 31, 2021. Invesco Advisers, Inc. 2162352 - 04/2022
When Greystone Met Cushman ‘Magnetic attraction’ between lender and broker leads to power partnership By Andrew Coen | Illustration by Britt Spencer
I
n early 2021, when Cushman & Wakefield decided it wanted to add a debt platform to complement its longstanding brokerage business, the choice quickly became clear. C&W hired a consultant to gauge the market for firms that would provide it direct agency lending capabilities. C&W quickly homed in on Greystone, an established multifamily lender, which in turn saw its own benefits to creating an alliance. A deal ultimately came together in less than six months, culminating in C&W and Greystone forming a strategic joint venture last October that set up both firms for commercial real estate growth. “We definitely recognized the importance of an alignment with an investment sales firm,” said Stephen Rosenberg, founder and CEO of Greystone. “As soon as it happened it just made so much sense, but to give credit where it’s due, the spark came from Cushman reaching out to us.” The transaction, which closed in the fourth quarter, involved C&W making a $500 million investment to acquire a 40 percent stake in Greystone’s agency lending and servicing business. Greystone is using that capital for new product offerings that can position it for future expansion.
28
Greystone has long been one of the most active multifamily bridge loan providers and originators of Fannie Mae Delegated Underwriting and Servicing (DUS), Freddie Mac Optigo and U.S. Department of Housing and Urban Development debt products. Rosenberg said the joint venture gives the lender new access to thousands of C&W brokers who are constantly in touch with real estate owners that may be seeking new debt solutions. “It was almost like a magnetic attraction,” Rosenberg said. “Cushman was probably the largest real estate service provider that didn’t have a debt platform, and we were probably the largest private lender that didn’t have an investment sales platform.” Prior to the deal, Rosenberg said there were around 100 brokers in 26 offices through the company’s Greystone Capital Advisors brokerage platform. Now, with the C&W partnership, Greystone’s sales advisory reach is in excess of 1,000 professionals. John O’Neill, president of C&W’s U.S. Multifamily Capital Markets, said Greystone was a cultural fit in addition to making business sense. He stressed that Rosenberg’s steady leadership at Greystone for the past 34 years since founding the
| MAY 3, 2022 | COMMERCIAL OBSERVER
firm in 1988 played an instrumental role in C&W deciding to team up. “We have a desire to be the No. 1 multifamily business in the United States as does [Rosenberg], and we needed that debt capability to help us achieve that plan,” O’Neill said. “We got that, plus we got a great partner in the process.” C&W’s Greystone partnership came nearly two years after its acquisition of Pinnacle Property Management Services, the nation’s third-largest multifamily property management firm with 175,000 units under its oversight. O’Neill said C&W will target multifamily deals on a national level with a particular focus on growth markets such as Denver and Texas. While the partnership’s initial focus is targeting the multifamily market, Rosenberg stressed that it could expand into other commercial real estate sectors. “I see our relationship with Cushman as across asset classes being the debt platform for the entire company,” Rosenberg said. “If we do this right, my sense is that every investment sales broker at any company should want to be at Cushman because we can provide tools to them that others don’t.”
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
The global leader in complex commercial real estate credit management and advisory services
33
66
$645B
YEARS IN BUSINESS
COUNTRIES WHERE WE’VE MANAGED CREDIT
ASSET VALUES MANAGED SINCE INCEPTION
FOCUSED exclusively on complex commercial real estate LEADING servicing technologies and security protocols, including Trimont’s global data and analytics tool, Triview NON-CONFLICTED approach to exclusively servicing our clients and their priorities
Trusted partners the world over.
trimontrea.com
10
Matt Salem, Patrick Mattson, Joel Traut and Rene Theriault Partner and Head of Real Estate Credit; Managing Director and Chief Operating Officer of Real Estate Credit; Partner and Head of Originations; Managing Director and Head of Securities Investing for Real Estate Credit at KKR Last year’s rank: 30
Matt Salem.
Patrick Mattson.
Joel Traut.
Rene Theriault.
Miriam Wheeler, Sherry Wang and Daniel Alger Head of the Americas Real Estate Financing Group; Co-Heads of Urban Investment Group at Goldman Sachs Last year’s rank: 6
Goldman Sachs’ proactive actions during the height of the pandemic paid dividends when it came to its 2021 lending volume. The Wall Street giant achieved $15 billion of originations last year compared with $12.5 billion for 2020 and just over $14 billion in 2019. The 2021 figure includes $12.6 billion of single-asset, single-borrower deals and $2.4 billion of conduit transactions. The active year was set in motion in 2020 when Goldman focused heavily on large syndicated balance sheet loans, bridge to securitizations and on-balance sheet CRE collateralized loan obligation products when the commercial mortgage-backed securities (CMBS) market was frozen at the start of the pandemic. The shift positioned it to expand its balance sheet lending. “We have remained incredibly active during COVID,” Miriam Wheeler said. “In addition to our strong CMBS business, we have significantly grown our balance sheet lending and warehouse lending businesses.” Notable 2021 deals included co-leading
30
“We started moving away from just being a transitional lender by adding insurance capital when we acquired Global Atlantic [in February 2021], which is a life and annuity company,” Salem said. “That added a very large capital base for us to write not only floating-rate loans but fixed-rate loans as well, and also focus more on stabilized lending as opposed to just transitional lending.” “Then we also added mezz and preferred equity products, which further introduced us to a new client base,” Salem added. “We have a full suite of loan products that we can offer the market today.” As such, today KKR is lending on everything from core, stabilized properties to value-add opportunities and new construction. “To be able to have that broad array of capital and to build new relationships is great,” Salem said. As if that weren’t enough, the firm also launched KKR Real Estate Select Trust (KREST) in May 2021 — a closed-end fund that thematically invests in high-quality, stabilized, income-oriented commercial real estate equity and debt. The first real estate debt investment via KREST — a $65 million mezz loan for Crescent Heights’ NEMA Chicago luxury residential building — was completed in August 2021. KKR’s team grew to more than 50 investment and asset management professionals last year with 45 percent of new hires being women or historically underrepresented groups (HUGs). This year, 73 percent of the new 11 hires have been women or HUGs. —C.C.
the $3 billion CMBS refinancing for SL Green Realty Corp.’s One Vanderbilt office tower in June. It also organized a $900 million debt package last July along with Bank of Montreal and Deutsche Bank for Stellar Management to refinance its One Soho Square office property. Goldman’s Urban Investment Group (UIG) also stepped up its production in 2021 by committing more than $3.9 billion of capital, up from $1.9 billion in 2020. Sherry Wang and Daniel Alger took over UIG in February 2021 looking to build on the more than 11.2 million square feet of real estate commitments the group made over the last two decades in predominantly minority communities. “At the heart of our approach is identifying opportunities in neighborhoods and assets where other capital providers may perceive risks differently,” Alger said, “and working to drive positive outcomes for the families and businesses in these communities.” UIG deals in 2021 included an $86.1
| MAY 3, 2022 | COMMERCIAL OBSERVER
Miriam Wheeler.
Sherry Wang.
Daniel Alger.
million low-income housing tax credit and brownfield tax credit equity investment to finance the development of Sendero Verde, a 348-unit mixed-income, mixed-use development in Harlem by L+M Development Partners and Jonathan Rose Companies. UIG also provided a $39.1 million equity investment to finance the development of Northeast Heights Phase 1, a 256,800-square-foot office building in the low-income Benning neighborhood of Washington, D.C., within an opportunity zone. The development sponsor is a partnership between Asland Capital, a
Black-led real estate firm; Cedar Realty; and Trammell Crow Company. Twenty-nine percent of UIG’s investment last year was committed to minorityand women-led sponsors on the heels of Goldman announcing its One Million Black Women initiative in March 2021, which pledges more than $10 billion to advance racial equity and economic opportunities. “The Urban Investment Group has committed over $700 million, laying the groundwork to narrow the opportunity gap for more than 50,000 Black women,” Wang said. —A.C.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: COURTESY OF KKR, COURTESY OF GOLDMAN SACHS
11
Quintupling 2019’s lending record this past year? We see you, KKR. “The overall volume of activity on both the loan side and the securities side of our business was quite extraordinary,” Matt Salem said. We don’t disagree. The KKR team originated a whopping $14.5 billion in loans — across 120 deals — and bought more than $4.2 billion of commercial mortgage-backed securities (CMBS) this past year, maintaining its crown as one of the largest investors in the junior tranches of CMBS deals. “My biggest takeaway is I’m just so proud of the team and the effort they put in,” Salem said. “Everyone was focused and driven to accomplish what were very lofty goals in terms of growth.” Among the team’s notable transactions were a $264 million loan for Echelon Seaport, a new, 1.3 million-square-foot luxury mixed-use development in Boston’s Seaport District, and a $300 million whole loan in April 2021 for the acquisition of a Class A, 700,000-square-foot technology campus in Sunnyvale, Calif. KKR expanded its offerings this past year, and significantly broadened its client base in the process, adding 60 institutional borrowers. Roughly half of KKR’s transaction activity last year was dedicated to multifamily deals, with a fair amount of industrial loans also in the mix.
BUILT FOR THE NOW. AND THE NEXT. Thank you to all of our valued clients and partners who have contributed to Berkadia’s success over the past year. As we look to the future, we remain committed to providing actionable, data-based insights and unmatched capital solutions to meet your investment goals. Justin Wheeler, CEO
JUSTIN WHEELER NAMED ONE OF COMMERCIAL OBSERVER’S POWER 50
B E R K A D I A . CO M /CO INVESTMENT SALES
|
M O R TG AG E B A N K I N G
|
S E RV I C I N G
© 2022 Berkadia Proprietary Holding LLC. Berkadia® is a trademark of Berkadia Proprietary Holding LLC. Commercial mortgage loan banking and servicing businesses are conducted exclusively by Berkadia Commercial Mortgage LLC and Berkadia Commercial Mortgage Inc. This advertisement is not intended to solicit commercial mortgage loan brokerage business in Nevada. Investment sales / real estate brokerage business is conducted exclusively by Berkadia Real Estate Advisors LLC and Berkadia Real Estate Advisors Inc. Tax credit syndication business is conducted exclusively by Berkadia Affordable Tax Credit Solutions. In California, Berkadia Commercial Mortgage LLC conducts business under CA Finance Lender & Broker Lic. #988-0701, Berkadia Commercial Mortgage Inc. under CA Real Estate Broker Lic. #01874116, and Berkadia Real Estate Advisors Inc. under CA Real Estate Broker Lic. #01931050. For state licensing details for the above entities, visit www.berkadia.com/legal/licensing.
12
George Gleason, Richard Smith, Brannon Hamblen and Greg Newman Chairman and CEO; Managing Director of Originations; President; Managing Director of Originations at Bank OZK Last year’s rank: 9
George Gleason.
Richard Smith.
Brannon Hamblen.
Greg Newman.
Dino Paparelli Global Head of Commercial Real Estate at Deutsche Bank Last Year’s rank: 17
Deutsche Bank (DB) nearly doubled its U.S. commercial mortgage-backed securities (CMBS) volume last year while also stepping up its lending game on a global level. The bank financed $11.5 billion in the U.S. in 2021, up from $6 billion in 2020, according to data from the Green Street CMBS/loan contributor rankings. It also issued more than $8 billion of banking book loans across a wide range of commercial real estate property sectors globally while expanding its origination business in the European Union. “DB CRE strives to continue to be a market-leading participant in the CMBS primary issuance market here in the U.S. with expansion in our EU business line to meet burgeoning market demand in addition to selective origination in banking book business lines,” Dino Paparelli said. “DB is also a leading player in ESG [environmental, social and governance], financing and green bond issuance.” Among the highlighted CMBS deals Paparelli led in the past year is a $507 million loan for CommonWealth Partners’ acquisition of Hudson Commons, a 26-story LEED-certified Midtown Manhattan office building. It marked
32
high-end Manhattan deals — a $410 million senior construction loan for Rabina’s mixed-use project at 520 Fifth Avenue and a $130 million senior loan to retire debt and recapitalize The Beekman, a Lower Manhattan landmark — the firm also focused on life sciences, with a $246 million construction loan for the Windsor lab project in downtown Boston and a $302 million senior loan to turn a Cambridge, Mass., courthouse into an office-focused, mixed-use development. “In terms of the diversity of our portfolio, I could go on and on and on,” Hamblen said. Coming into the new year, the firm was riding a record-setting fourth quarter, which saw $3 billion in deals. Despite the macroeconomic uncertainties that are adding headwinds to the development business, Hamblen expects a strong deal pipeline to translate into a positive 2022. —P.S.
Deutsche’s first solo ESG deal and the first fixedrate CMBS transaction priced to secured overnight financing rate (SOFR) swaps. “The Hudson Commons acquisition financing, with DB CRE acting as sole lender and bookrunner, highlights our continued commitment to green initiatives and is a great milestone for the CMBS industry,” Paparelli said. “The transaction included not only a best-inclass environmentally efficient property but was also the first successful CMBS pricing over SOFR swaps.” Deutsche also closed a $220 million loan in December 2021 for Lubert-Adler to refinance its roughly 593,000-square-foot office building at 2400 Market Street in Philadelphia that serves as the global headquarters for Aramark. Paparelli served his first full year as Deutsche Bank’s global head of CRE in 2021, after he was first appointed to the role in October 2020 when his predecessor, Matt Bornstein, left to become a partner at Oak Hill Advisors. Paparelli’s previous experience with Deutsche involved 16 years with the firm’s CRE arm, including three years as head of CRE in Europe. —A.C.
| MAY 3, 2022 | COMMERCIAL OBSERVER
TOP TO BOTTOM: COURTESY OF BANK OF OZK, COURTESY OF DEUTSCHE BANK
13
The nation’s preeminent construction lender continued its reign in 2021 to connect with some of the marquee projects set to break ground across the country. In a year highlighted by an $800 million senior construction loan for Gary Barnett’s 50 West 66th Street, an upscale condominium project in New York City, Bank OZK showed it is both well-capitalized and well-positioned for a shifting market, and that its in-house expertise and focus has paid off. “Coming out of COVID and seeing the macro change proves our longstanding belief that building the newest and best product for the market with sponsorship is the best; that thesis proved up in spades,” Brannon Hamblen said. The Little Rock, Ark.-based firm closed $7.94 billion in transactions, maintaining its considerable balance sheet by diversifying across loan size, type and location. In addition to a pair of
Dino Paparelli.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
Blackstone Real Estate congratulates this year’s Power 50.
14
Warren de Haan, Boyd Fellows, Chris Tokarski and Stew Ward Managing Partner and Co-CEO; Managing Partner; Managing Partner and Co-CEO; Managing Partner at ACORE Capital Last year’s rank: 14
ACORE Capital solidified its standing in the past year as one of the nation’s largest and most creative non-bank lenders. The firm originated 89 loans totaling $7.69 billion in the year ending March 31, 2022, including ones in office, industrial/logistics, multifamily, hospitality, self-storage and retail financings. A large chunk of this volume occurred in the fourth quarter, with $2.4 billion closed across 29 deals. ACORE also extended its reach into more nuanced asset classes, including life sciences, data centers, health care and student housing. “The capital at our disposal is much more flexible so that we can do almost anything,” Boyd Fellows said. “When we started this company seven years ago we used to say that our objective was to grow, to be one of the most relevant lenders in the United States. It doesn’t have to mean you’re the biggest, but we want to be having an impact and a very large impact.” ACORE’s versatile deal activity from the past year includes a $290 million loan to a joint venture between NexPoint Advisors and SAFStor to refinance a 29-property self-storage portfolio located across 14 states. It also loaned $140 million to InSite Property Group Holding to develop self-storage properties in the Southwest.
15
In the office sector, ACORE supplied a $139 million loan to Quadrangle Development Corporation to recapitalize National Place, a 440,000-square-foot office building in Washington, D.C. On the multifamily side, it provided a $115 million debt package to TBC Development to develop luxury condominiums at Lake Tahoe Beach Club in Stateline, Nev. In addition to its deal activities, the lender also played an important role in the hotel sector’s ongoing recovery from the pandemic through the $1 billion it raised in 2021 to launch ACORE Hospitality Partners (AHP), an investment strategy backed by institutional investors. AHP acquired structured hotel debt investments, and provided recovery capital for 35 hotel properties as of the end of 2021. ACORE promoted Kyle Jeffers and Tony Fineman to co-heads of origination for the West and East coasts, respectively, in June 2021. It also created a new director of environmental, social and governance, or ESG, role in January, filled by Autumn Gibson. “In addition to the fact that we did $7 billion in originations and broadened everything we do, we also made the company more durable and institutionalized,” Warren de Haan said. —A.C.
Warren de Haan.
Boyd Fellows.
Chris Tokarski.
Stew Ward.
James Millon and Tom Traynor Vice Chairmen in Debt & Structured Finance and Co-Heads of U.S. Large Loans at CBRE Last year’s rank: 19
34
Tom Traynor.
James Millon. lenders. The deal was the recipient of one of REBNY’s ‘Most Ingenious Deal of the Year’ awards. “Terminal Warehouse was big and complicated and closed in a really challenging market, so we had to put a lot of different lenders into it and structure it in a way that fit the capital that was out there at the time,” Traynor said. But, New York City “really needed that deal,” Millon said. Indeed, a mammoth non-recourse construction financing on a 1.2 million-square-foot office with no pre-leasing in place would underscore a commitment to — and belief in — New York City office, and so the Terminal Warehouse
| MAY 3, 2022 | COMMERCIAL OBSERVER
loan became a canary in the coal mine of sorts. The financing closing was the ultimate validation, Millon said, noting, “We were even getting emails from some of our competitors, saying ‘Great job.’” Another pioneering transaction was Medical Properties Trust’s $1.7 billion equity recapitalization and debt financing of a portfolio of eight inpatient general acute care hospitals in Massachusetts. Apollo provided a roughly $920 million loan in the deal, arranged by Millon and Traynor. “We’re blazing a new trail in that field,” Millon said. “It’s not traditionally financed in our market.” —C.C.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: COURTESY OF ACORE CAPITAL, COURTESY OF CBRE
In the deepest depths of the ocean of deals, there are some whales to be found — but only a select few advisory firms can truly decode their songs. CBRE closed $16.1 billion in transactions over the past year, across 44 deals, with an average deal size of a whopping $366 million. The total represents 20 percent of CBRE’s debt and structured finance volume overall in the U.S.— and was achieved by a team of six. At any one point, the team had between $3 billion and $4 billion in the market or at the closing table, across various asset classes, markets and financing executions. Industrial comprised 48 percent of originations — followed by office at 30 percent — but James Millon and Tom Traynor also grew their life sciences activity, and closed their first data center deal. One standout transaction was the $1.25 billion construction loan the team closed in July 2021 on behalf of L&L Holding and Columbia Property Trust for Manhattan’s Terminal Warehouse. It involved not one, but five
CREATIVE AND FLEXIBLE CAPITAL PROVIDERS RELATIONSHIP FOCUSED LOAN SERVICING FOR THE LIFE OF YOUR LOAN www. 3 6 5 0 re it .co m
John O’Neill.
Ken Ziebelman.
Grant Frankel.
Rob Rubano.
Steve Kohn.
Vice Chairman and President of Equity, Debt and Structured Finance; President of U.S. Multifamily Capital Markets; and Executive Managing Director at Cushman & Wakefield Last year’s rank: 18
Cushman & Wakefield’s equity, debt and structured finance team closed $23.5 billion in deals in 2021. It also acquired a 40 percent stake in Greystone’s agency, Federal Housing Administration (FHA) and servicing businesses as the cherry on the cake. First, let’s talk about deals. How about a $950 million refinance for Vornado Realty Trust’s 1290 Avenue of the Americas — also C&W’s headquarters building — or a $905 million refinancing for Stellar Management’s One Soho Square? Dig construction? How about the $700 million development loan for a 1.1 million-square-foot residential and hotel development in Bellevue, Wash. (executed with an offshore lender, no less)? Love logistics? C&W arranged the $235 million permanent financing for a 1.3 millionsquare-foot industrial property in Linden, N.J. “The recovery from the depths of COVID continued very strongly into 2021,” Steven Kohn said. “There was a lot of liquidity, and very competitive pricing from investors and lenders.” Last year was a growth year for sure, with low interest rates and demand far exceeding supply in many markets. While the team was busy negotiating deals across asset classes and property types, the two big winners in 2021 were industrial and multifamily, Kohn said. “The themes today are more of the same,” Kohn said. “Most of the big institutions and a lot of private investors just want as much multifamily and industrial as they can get their hands on.”
36
His team worked hard — and well — under pressure. “We handled double the work with less people,” Kohn said. “I learned how hard people were willing to work to get our transactions over the finish line, and I’m very proud of them.” “It really was a record year for us,” Rob Rubano added. “I feel really good about how we’re positioned nationally, with the biggest borrowers and top institutional clients.” Over the past year, “we’ve done everything from $25 million transitional office deals to $2.4 billion portfolios and everything in between,” Rubano continued. In October, C&W finalized its $500 million investment in Greystone’s agency, FHA and servicing businesses, and John O’Neill was promoted to president of U.S. multifamily capital markets. “This joint venture allows us to offer a robust multifamily debt platform, which is a really critical capability,” O’Neill said. Building out a new partnership during a market that’s all too willing to throw curveballs at every turn is no mean feat. “If you go back to the [global financial crisis of 2007-2009], then the global pandemic, we have all been tested in ways that we never thought we would be tested,” O’Neill said. “All these events create a certain resiliency, and some people tend to retreat, while some advance. The Greystone team, and we at Cushman, pride ourselves on not allowing headwinds to deter you; you just have to find ways to persevere.” —C.C.
| MAY 3, 2022 | COMMERCIAL OBSERVER
Rob Turner.
17
Grant Frankel, Ken Ziebelman and Rob Turner Managing Directors at Eastdil Secured Last year’s rank: 22
“It was a record year for the firm, across both debt and equity,” said Grant Frankel. In 2021, Eastdil Secured originated an average loan size of $237.8 million. “As far as size goes, that’s four times that of our nearest competitor,” noted Robert Turner. The firm overall executed 365 transactions for its global financings and loan sales, for a total of $87 billion, including $18.3 billion generated by the New York team alone. On the debt side of the business, “Eastdil did a tremendous amount of industrial and multifamily deals,” said Frankel, “and we have built out a sizable practice in the studio business.” Indeed, the firm closed 13 studio financings totaling $4.5 billion in gross proceeds across the United States, Canada and the U.K. Eastdil also closed over $6.15 billion of life sciences financings, but who’s counting. Notable transactions included the $600 million in construction financing for Wildflower and Meadow Partners’ Wildflower Studios in Astoria, Queens;
BECOME A COMMERCIAL OBSERVER MEMBER
a $441 million construction financing for DH Property Holdings and Bridge Development’s Sunset Industrial Park in Brooklyn; an $860 million refinancing for Paramount Group’s office building at 1301 Avenue of the Americas; and a $450 million refinancing for Silverstein Properties’ office building at 1177 Avenue of the Americas. Eastdil also double downed on diversity, equity and inclusion (DEI). Eastdil formed a DEI council, which is inclusive of various levels of functions within the organization, and engaged with a number of external DEI partners to develop a pipeline of diverse talent. Looking ahead, “we’re expecting significant volume on the balance sheet side this year. As we’ve seen, the [commercial mortgage-backed securities] markets have gone through some choppy waters over the last few months,” said Ken Ziebelman, adding that he thinks loan sales will continue to be a growing part of the business. “We will continue to be focused on where our clients are [going] from an acquisition perspective.” —E.F.
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
LEFT TO RIGHT: COURTESY OF CUSHMAN & WAKEFIELD, COURTESY OF EASTDIL CAPITAL
16
Steven Kohn, John O’Neill and Rob Rubano
18
Ralph Herzka, Yoni Goodman and David Brickman Chairman and CEO; President; Executive Chairman at Meridian Capital Group Last year’s rank: 21
Maintaining its strong volume during COVID-19, Meridian Capital Group accelerated its momentum during the past year. Meridian closed 4,449 loans companywide totaling $60.5 billion in the 12 months ending March 20, marking a 62.2 percent increase in dollar volume from the prior 12 months. The private brokerage set a new record for itself during calendar year 2021, closing $57.5 billion in financing through 4,250 transactions. Yoni Goodman attributed Meridian’s success over the past 12 months to its longstanding lender relationships that led to closing deals with 300 different institutions. He said achieving growth during Meridian’s 30th anniversary in 2021 underscores its longstanding success as a private brokerage while competing among public firms with far longer histories. “We’re achieving all this success as the only private company left in the big mortgage brokerage sector,” Goodman said. “We are the last person standing of the big brokerages that are achieving real scale that
Ralph Herzka.
David Brickman. our clients almost as their financing arms,” Goodman said. “We estimate that there are hundreds of billions of dollars of loans on the balance sheets of lenders right now that we’ve arranged and we actively manage that on behalf of our clients.” —A.C.
in the multifamily sector . It also brokered $4.9 billion of financing for health care developments via 135 loans. “We have 30 years of deep, loyal client relationships with a huge book of business that we continue to manage on behalf of
Christopher Peck and Michael Gigliotti Senior Managing Directors and Co-Heads of the New York Office at JLL Capital Markets Last year’s rank: 20
“We definitely had a record volume in 2021, JLL globally as a whole, nationally in the U.S. and then in New York,” said Michael Gigliotti. In 2021, JLL originated $17.4 billion in debt, equity and loan sales, with a record $27.3 billion across all capital markets product lines. JLL was ranked first among commercial real estate multifamily finance firms’ annual origination volume, per the Mortgage Bankers Association. JLL executed deals across all property types with a focus on industrial and multifamily. Three of the firm’s top five deals were large New York City office transactions too. Notable transactions in 2021 included a $911 million construction takeout financing for 425 Park Avenue, sponsored by L&L Holding, BentallGreenOak and Tokyu Land; a $587 million debt and equity recapitalization for a Westchester County industrial portfolio; a $425 million construction takeout financing for the JACX in Long Island City, Queens, sponsored by Tishman Speyer; a $393 million construction loan for a life sciences development at 125 West End Avenue
38
Yoni Goodman.
sponsored by Taconic and Nuveen; and a $381 million construction financing for the Bronx Logistics Center, a multistory industrial development in the Bronx sponsored by Turnbridge and Dune. “A big part of our business has become the joint venture equity and structured finance practice,” said Christopher Peck. For example, Fisher Brothers affiliate Lionheart Strategic Management has entered into a loan acquisition agreement with Schroder Investment Management North America to target $250 million in transitional and distressed real estate credit investments. JLL’s Global Capital team advised Lionheart in procuring capital. JLL is also responsible for the $750 million that Fisher Brothers wanted to deploy in the programmatic vehicle, according to Peck. “Fisher Brothers credit us with changing the whole complexion of their credit business when other people couldn’t access capital because they couldn’t get on a plane and meet with anyone,” he noted. “We ran a global roadshow via Zoom.” JLL is also said to be the only real estate
| MAY 3, 2022 | COMMERCIAL OBSERVER
Michael Gigliotti.
Christopher Peck.
intermediary that currently offers a student loan contribution of $5,000 per year to its new hires as part of its need-blind initiative. Nationally, JLL partnered with Project Destined, which has led to significant recent hires. JLL also initiated company-wide unconscious bias training as well as training in how
BECOME A COMMERCIAL OBSERVER MEMBER
to be a better interviewer in order to attract and retain diverse talent. Per Gigliotti: “2021 was a huge year for people realizing that [diversity, equity and inclusion] isn’t something to say that you have someone working on; it’s that every individual has to be a part of it.” —E.F.
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: COURTESY OF MERIDIAN CAPITAL GROUP, COURTESY OF JLL CAPITAL MARKETS
19
aren’t public.” Meridian’s deals on behalf of lenders came in a variety of sectors, including a $955 million refinance of an office property for 601W in Chicago and a $560 million debt package for Prime Storage Group to refinance a 43-asset self-storage portfolio in 15 states. It also arranged a $385 million loan for White Eagle Property Group to refinance an eight-asset multifamily portfolio in the Southeast. Another notable transaction was $367 million of acquisition financing from Square Mile for Atlas Capital Group to purchase a multifamily property at 54 Noll Street and 123 Melrose Street in Brooklyn. At $563 million, it was the largest single-asset multifamily sale in the U.S. since 2018, according to CoStar data. Meridian also arranged a $263 million construction loan for TA Partners’ multifamily project at 18831 Von Karman Avenue and 17422 Derian Avenue in Irvine, Calif. The bulk of Meridian’s deals — 3,115 loans and $39.8 billion of volume — were
Oaktree’s Real Estate Debt Group Named in the Power 50 in Commercial Real Estate by Commercial Observer.
Katy Mao
Managing Director Real Estate Debt
Amy Johannes
Managing Director Real Estate Opportunities
Ainslee Burns
Vice President Real Estate Debt
Oaktree is a leader among global investment managers specializing in alternative investments, with $166 billion in assets under management as of December 31, 2021. Oaktree’s Real Estate Debt strategy, launched in 2010 as an expansion of its Real Estate Opportunities strategy, adheres to Oaktree’s investment philosophy of risk control, consistency and granular credit analysis. As of December 31, 2021, Oaktree’s Real Estate group has $16 billion in assets under management across its opportunistic, debt and income strategies. The team is made up of 54 professionals and the leadership team has an average of 26 years of experience investing in real estate.
$274,000,000 Mezzanine | Mixed-Use Redevelopment | New York
$93,000,000 Mezzanine | Life Science Redevelopment | New York
$98,000,000 Mezzanine | Office Acquisition | New York
Justin Guichard
Co-Portfolio Manager, Real Estate Debt (213) 830-6363 JGuichard@oaktreecapital.com
Warren Min
Katy Mao
Derek Rich
(213) 830-6821 WMin@oaktreecapital.com
(212) 284-1990 KMao@oaktreecapital.com
+44 7900 162513 DRich@oaktreecapital.com
Amy Gall
Kevin Sciarillo
Ainslee Burns
(213) 830-6426 AGall@oaktreecapital.com
(213) 356-3072 KSciarillo@oaktreecapital.com
(212) 284-1981 ABurns@oaktreecapital.com
20
Marcia Diaz, Melissa Farrell and Sara Trybus Managing Director and Head of U.S. Core Debt; Managing Director and Head of U.S. Debt Originations; Managing Director of Global Credit at PGIM Real Estate Last year’s rank: 23
of the Americas and Advance Real Estate, and $101 million in floating-rate bridge financing to Asana Partners for the acquisition and lease-up of a four-property, 168,206-squarefoot retail and office portfolio located in the Fulton Market neighborhood of Chicago. “That one was key for us for multiple reasons,” Farrell said of the Asana deal. “Everyone thinks of us as a core lender, but we definitely have a focus on core-plus, so this fit into our core-plus account. It was mixed-use, with some office and some retail, and it was nice to diversify and find that type of asset. It was a sizable transaction and in a growing market, in terms of this Fulton area in Chicago. So it hit on multiple fronts for us.” Farrell expects similar success for PGIM in 2022. “We were $19.5 billion in 2019 and 2020, so I think we’re going to hopefully be in that same band in 2022,” Farrell said. “I’m expecting a little bit of a shift from floating- to fixedrate, as we’re already starting to see that from our borrowers, requesting it as the Fed is raising interest rates. We’ve definitely seen that shift.”—L.G.
Marcia Diaz.
Sara Trybus.
21
Brad Dubeck.
40
| MAY 3, 2022 | COMMERCIAL OBSERVER
Melissa Farrell.
Brad Dubeck Senior Vice President and New York and New Jersey Market Executive at Bank of America Last year’s rank: 16
Bank of America’s 2021 included the origination of commercial real estate loans totaling approximately $33 billion for its nationwide commercial, corporate and affordable housing clients. Additionally, the bank originated $9.7 billion of commercial real estate loans through its real estate structured finance platform. “In 2021, Bank of America’s commercial real estate-focused teams navigated a challenging environment by remaining focused on our clients and making positive impacts in the communities we serve,” Brad Dubeck said. The company also reported that its community development banking (CDB) business “provided $6.6 billion in loans, tax credit equity investments and other real estate development solutions in 2021, surpassing a record of $5.9 billion in financing in 2020,” according to a company press release.
The company noted that CDB deployed $4.1 billion in debt commitments and $2.5 billion in investments for affordable housing and economic development commitments. “CDB-financed developments produced more than 13,000 housing units, of which 90 percent (more than 11,600) were affordable,” according to B of A. This number included 3,200 units for seniors, 3,400 for veterans in need, and 5,500 certified green units. CDB also provided $1.6 billion to finance 3,300 housing units that include access to health-related services, and more than $368 million to minority- or women-led affordable housing developers, resulting in 1,500 affordable units. The company also says that in April 2021 it became the first bank to launch a fund dedicated to supporting developers of color, contributing a $60 million investment. —L.G.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: COURTESY OF PGIM REAL ESTATE, COURTESY OF BANK OF AMERICA
With $17 billion in debt originated in the U.S. and $22 billion globally, PGIM Real Estate had a very successful 2021, financing $7.4 billion within its portfolio and core business, $2.2 billion within core-plus and high yield, and $7.3 billion of agency debt. “In 2020, we were at about $16.2 billion in the U.S. versus our $17 billion today. So I would say this was a successful year,” Melissa Farrell said. “We also were able to do that in many different capital buckets, [including] high yield, which is becoming more and more of a factor in the marketplace today.” Farrell, a 25-year veteran of PGIM, recently took over the head of originations role from Marcia Diaz, who assumed a role as head of U.S. core debt. In other significant personnel moves, Daniel Kattan joined the company from Canyon Partners as an executive director on PGIM’s debt originations team, and Christy Lockridge was named the firm’s first chief diversity, equity and inclusion officer. PGIM’s notable deals for 2021 included $169 million in fixed-rate financing across three industrial portfolios in Mexico on behalf of its core lending strategy to Corporate Properties
LIFE LESSONS: Life companies had a great year, and held their own among capital sources in a competitive playing field.
Origins of Life More life insurance company dollars are flowing into commercial real estate lending By Andrew Coen | Illustration by Britt Spencer
L
ife insurance companies were alive with commercial real estate lending during the past year and are poised for further growth. Active commercial real estate origination activity was evident at established insurance companies PGIM, MetLife and New York Life while newer players, namely KKR and Apollo, also joined the party with the addition of life company dollars. PGIM upped its U.S. debt origination to $17 billion in 2021 compared to $16.2 billion the previous year. Its dealbook was diverse, comprising $7.4 billion within its portfolio and core business, $2.2 billion within core-plus and high yield along with $7.3 billion of agency debt. One of PGIM’s notable deals involved $101 million floating-rate bridge financing to Asana Partners for the acquisition and lease-up of a four-property, 168,206-square-foot retail and office portfolio in the Fulton Market neighborhood of Chicago. The deal demonstrated PGIM’s versatility to execute a core-plus
42
transaction that aims for larger yields. MetLife Investment Management also had a big 2021 with its commercial mortgage team originating a company-record 235 transactions last year totaling more than $15.3 billion across traditional as well as alternative property types. These included life sciences, self-storage and student housing. MetLife also launched a closed-end hotel debt fund. Overall, MetLife recorded $18.6 billion of new commercial real estate debt and equity transactions and achieved a company high of $109.8 billion in gross commercial real estate assets under management. New York Life Real Estate Investors proved nimble in 2021 with $12.6 billion of transaction volume from core, bridge, construction and mezzanine debt. It exceeded pre-pandemic levels in commercial real estate mortgages with $9.9 billion. Commercial mortgage-backed securities purchases totalled $1.8 billion, and New York Life closed $923 million of equity. Looking to expand from its transitional lending roots, KKR
| MAY 3, 2022 | COMMERCIAL OBSERVER
added insurance capital in February 2021 with the acquisition of life and annuity company Global Atlantic. The move arms KKR with more bandwidth to underwrite longer-term floating-rate and fixed-rate loans in addition to bridge debt. Acquiring Global Atlantic paid early dividends for Manhattan-based KKR with the firm quintupling its previous lending record, set in 2019, with $14.5 billion in loans from 120 deals. The company expanded the scope of its lending with 60 new institutional borrowers. Around half of its transaction activity last year was dedicated to the multifamily sector while also allocating a sizable amount to industrial deals. Commercial real estate lending momentum at the life insurance level was also evident at Apollo. The firm closed $14.1 billion of originations last year with $8 billion of that total deriving from its insurance company platform. As Apollo and KKR further grow their insurance arms in 2022, the insurance company industry presence within commercial real estate lending will only widen.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
Global Reach, Local Expertise
NOW AVA IL A BLE $20,000,000 | Multifamily | Jersey City, NJ Jonathan Zamora
N O W AVAIL A B LE $14,250,000 | Multifamily | Queens, NY Shaun Riney, Joe Koicim, Sean Fopeano, Louis Zarif
CLO SED $10,400,000 | Mixed-Use | Poughkeepsie, NY Joseph French, Kodi Traver, Matthew Gault
C LOS ED $2,800,000 | Mixed-Use | Brooklyn, NY Matt Fotis, Chase Midgley
John Horowitz
Jim McGuckin
First VP/Division Manager jhorowitz@marcusmillichap.com Brooklyn: (718) 475-4300 NY License #: 10311204479
Susan Bands
Regional Manager sbands@marcusmillichap.com Manhattan: (212) 430-5100 NY License #: 10311209023
Regional Manager jmcguckin@marcusmillichap.com New Jersey: (201) 742-6100 NJ License #: 2082114
NJ BOR: Brian Hosey | Lic. # 1434917
Real Estate Investment Sales | Financing | Research | Advisory Services
MarcusMillichap.com
Founder and Corporate CEO of Greystone Last year’s rank: 26
“One thing that has become clear to the world that wasn’t clear 10 years ago, at least to most of the world, is that there’s a very close relationship between selling properties and financing those properties that you’re selling,” said Stephen Rosenberg. Greystone’s total originations in 2021 hit $18.3 billion. One pivotal development for Greystone in 2021 was its strategic joint venture with Cushman & Wakefield. Greystone provided C&W with access to its significant balance sheet, and, in exchange, C&W provided a network of real estate brokers and other services, Rosenberg noted. “We can position Cushman to win a higher percentage of the business that they’re pitching,” he said. With Cushman’s $500 million investment, Greystone is able to continue its expansion, which also includes a joint venture with Monticello Asset Management for bridge lending, a venture with Passco Companies for 1031 exchanges and the launch of a proprietary commercial mortgage-backed securities platform, led by Rich Highfield. Greystone closed a $900 million multifamily collateralized loan obligation (CLO) in August 2021 and a $450 million health care CLO in December. Its
advisory team, Greystone Capital Advisors, arranged a $143 million permanent loan for affiliate entities of RXR to refinance 475 Clermont, a multifamily rental building in Brooklyn. “I would say we’re still catching our breath, but we’re not stopping,” Rosenberg said. Greystone also has a special situations group for clients to get a deal over the finish line when needed. Its Housing Association of Nonprofit Developers (HAND) relationship was key in providing access to capital for developers of color too. Greystone’s people are top of mind for Rosenberg. “It is a core fabric of who we are,” he continued. “Shame on us if we don’t have a diverse employee force. Shame on us if everyone doesn’t have the same opportunity. Shame on us if everyone doesn’t feel at home.” That’s the same ideology backing Greystone’s diversity, equity and inclusion (DEI) efforts. Led by Pranika Uppal Sinha, Greystone is growing a team that is supported by employee-led committees. In 2021, Greystone launched employee resource groups, expanded its targets for college recruitment with historically Black colleges and universities, and developed a relationship with Project Destined, for which Greystone created a custom learning module on debt and lending. Greystone also hosted speakers and trained over 1,200 employees in microaggressions and imposter syndrome, among other topics. The firm is launching a mentor program, too, led by the DEI committee to boost such efforts. —E.F.
23
Michele Evans.
44
| MAY 3, 2022 | COMMERCIAL OBSERVER
Stephen Rosenberg.
Michele Evans Executive Vice President and Head of Multifamily at Fannie Mae Last year’s rank: 2
Nearly two years after assuming the leadership role as Fannie Mae’s head of multifamily business in the summer of 2020, Michele Evans has helped bolster the government-sponsored enterprise’s (GSE) commitment to affordable housing. Fannie Mae closed 2021 with its funding for multifamily affordable housing rising more than 23 percent to the highest level in its 33-year old Delegated Underwriting and Servicing (DUS) program. Multifamily affordable housing volumes totaled $9.6 billion in 2021, up 23.1 percent from 2020. “We are proud of the work we did last year, especially increasing our support of multifamily affordable housing at a time when the need for more affordable housing options became more acute,” Evans said. “We continued to be a steady source of liquidity for multifamily markets amid disruptions to the economy and financial markets related to the pandemic.” The Washington, D.C.-based GSE maximized its lending cap with nearly $70 billion of financings. Last September, Fannie increased its cap for investment in low-income housing tax credit activities to $850 million annually, up from $500 million set in 2017, when the Federal Housing Administration first approved its return to the Low-Income Housing Tax
BECOME A COMMERCIAL OBSERVER MEMBER
Credit market. The institution also introduced a Sponsor Initiated Affordability platform that offers pricing incentives to multifamily borrowers through its network of DUS lenders. The lower borrowing costs are provided to sponsors if they agree to preserve or create a minimum of 20 percent of units per multifamily property as affordable to residents earning less than 80 percent percent of area median income. A busy 2021 for Fannie involved rolling out a new Expanded Housing Choice initiative that provides pricing incentives for Texas and North Carolina multifamily property owners who accept U.S. Department of Housing and Urban Development Housing Choice Vouchers. “This is our latest effort to deliver on our mission and help ensure greater access to sustainable affordable housing,” Evans said. “We are excited about this initiative because we are constantly working to create innovative solutions for promoting sustainable affordable housing, and benefitting renters.” Green finance volume at Fannie last year totaled $13.5 billion, up 3.6 percent from 2020. This helped grow the institution’s multifamily green mortgage-backed securities issuance to more than $100 billion for 2021. —A.C.
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: FRANCESCO SAPIENZA/FOR COMMERCIAL OBSERVER, COURTESY OF FANNIE MAE
22
Stephen Rosenberg
The right partner is the one with real-world solutions. Clients rely on Kramer Levin for creative solutions to complex real estate and land use matters. We have decades of experience representing NYC’s leading developers and institutions, and have advised on many of the city’s signature projects. We understand market terms and conditions and the regulatory environment, and we know how to maximize value while minimizing risk. Let us show you how results-oriented counsel can make your next project a reality. www.kramerlevin.com
Kramer Levin Naftalis & Frankel LLP 1177 Avenue of the Americas, New York, NY 10036 212.715.9100
24
Richard Martinez Senior Vice President of Multifamily Production and Sales at Freddie Mac Last year’s rank: 1
Freddie Mac’s mission shifted in the past year from providing stability to the multifamily market during the height of COVID-19 to focusing on tackling the nation’s affordable housing crisis. “What existed before the pandemic has become more exacerbated post-pandemic, and that is affordability,” Richard Martinez said. “Freddie Mac is now pivoting back to a greater focus on affordability and what can Freddie Mac do to help alleviate the affordability.” The renewed focus came amid a leadership change, too. Debby Jenkins, who had headed Freddie Mac’s multifamily business since 2018, departed the housing finance agency in late 2021 to join Kayne Anderson Real Estate as head of housing. “[Jenkins’] position is a critical position to fill,” Martinez said. “Our president and CEO want to make sure that we have the right individual in that spot to lead us forward in the challenging times we’re facing with respect to affordability.” The government-sponsored enterprise once again maximized its lending
cap, purchasing $70 billion in loans for 2021 while also making $674 million in Low-Income Housing Tax Credit (LIHTC) equity investments. The company financed roughly 650,000 rental units last year, 95 percent of which are affordable. The McLean, Va.-based Freddie Mac securitized a record $80.6 billion through multiple offerings and, in the process, transferred a large majority of expected and stress credit risk to third-party investors. Around 57 percent of Freddie Mac’s volume qualified as mission-driven, which went above and beyond its 50 percent target for the year. In November 2021, the organization launched a new initiative to help renters build credit by encouraging operators of multifamily properties to report on-time rental payments to the three major credit-reporting bureaus. The program, which incentivizes rent reporting via technology created by Esusu Financial, helped establish credit scores for more than 6,000 individuals by the end of 2021. —A.C.
Richard Martinez.
25
Aaron Appel, Keith Kurland, Adam Schwartz and Jonathan Schwartz Chairman and CEO; Senior Managing Directors and Co-Heads of New York Capital Markets at Walker & Dunlop
Aaron Appel.
Keith Kurland.
Adam Schwartz.
Jonathan Schwartz.
46
| MAY 3, 2022 | COMMERCIAL OBSERVER
“Our business has followed much in the way of many of our clients and market trends,” Keith Kurland said. In 2021, Walker & Dunlop’s New York team racked up $7.3 billion in total transactions, as part of the firm’s $48.9 billion in total debt originations. Notable transactions last year included a $1.4 billion construction loan provided by Blackstone for Witkoff and Access Industries’ XI condo project at 76 11th Avenue; a $395 million financing for Blackstone’s acquisition of Project Archer, a multifamily development in Fairfax, Va.; and a $300 million construction financing for Westminster Capital’s age-restricted housing development The Mather Tysons in McLean, Va. With a tremendous amount of liquidity chasing deals, the company was able to leverage its relationships and market fervor into some of the best capital markets executions. W&D’s New York capital markets team executed assignments spread across debt and equity placements, note sales and other advisory work.
Its portfolio has also grown dramatically from a market standpoint throughout COVID-19. “Several years ago, we made it a point to diversify geographically, not just from an asset class perspective,” Kurland said. “That target and thesis have played out well for our business as we have been incredibly active throughout the Sun Belt, South Florida, the Intermountain West and the West Coast.” Almost half of W&D’s business during the past year was from vertical construction or heavy reposition financings, with the remaining being split among acquisitions and refinances. The company also continued its ESG and diversity and inclusion efforts this past year, and currently has five employee resource groups. As for 2022, “We’ve seen sales and gross investment dollars pick up dramatically in New York over the last six to nine months, which has been a very interesting trend,” Kurland said. “As New Yorkers, we’re very happy to see renewed vigor in business, the local economy and markets.” —E.F.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: COURTESY OF FREDDIE MAC, COURTESY OF WALKER DUNLOP
Last year’s rank: 13
Building the future together In today’s environment, deep experience and understanding of the commercial real estate industry is essential in order to develop the right financial solutions to support your real estate needs. At Barclays, our team of leading experts is ready to develop an approach that will help take your business forward. Contact Barclays today: Larry Kravetz MD, Head of U.S. CRE Finance +1 212 526 5838 larry.kravetz@barclays.com Steven Caldwell MD, Head of Originations +1 212 526 6706 steven.caldwell@barclays.com
Francis X. Gilhool MD, Head of U.S. CRE Warehouse +1 212 526 6970 Francis.gilhool@barclays.com Kristin Khanna MD, Head of Loan Syndication and Acquisition Facilities +1 212 526 0870 Kristin.khanna@barclays.com
Barclays offers investment banking products and services to its clients through Barclays Bank PLC. Barclays Bank PLC is authorized in the United Kingdom by the UK Prudential Regulation Authority and regulated by the UK Financial Conduct Authority and the UK Prudential Regulation Authority and is registered in England No. 1026167. Registered Office: 1 Churchill Place, London E14 5HP, United Kingdom. Barclays undertakes its US securities and investment banking business in the name of its wholly-owned subsidiary Barclays Capital Inc., an SIPC and FINRA member. ©2022 Barclays. All rights reserved. Barclays is a registered trademark of Barclays PLC, used under license.
Matthew Masso.
26
Christopher Herron.
Robert Verrone and Christopher Herron Principal Owner; Managing Director at Iron Hound Management Last year’s rank: 27
Retail rescues have been few and far between in recent years, which is why Iron Hound Management’s work to rescue and restructure Hudson’s Bay — an $846 million 34-asset commercial mortgage-backed securities restructuring and single-asset, single-borrower, or SASB, deal that capped an 18-month saga — was so significant. Recognized for its expertise in restructuring and distressed assets, the restructuring, completed in October 2021, showcased the firm doing what it does best. “It was a very large restructuring of retail assets, some of which had lost a tenant completely due to the Lord & Taylor bankruptcy, but it showed a very strong commitment to retail,” said Christopher Herron. “A par restructuring where the retailer invested nearly $100 million isn’t all that common.” Throughout last year, Iron Hound notched $5.8 billion in originations across 48 deals, split evenly between restructuring and debt/ equity placement, including a recapitalization of Brooklyn’s Industry City and a $320
48
million refinancing of 850 Third Avenue for the Chetrit Organization. If 2021 was a transitional year, Iron Hound straddled both sides with its unique business model, fielding numerous restructuring opportunities while riding the upswing via debt/equity placement business and advisory brokerage deals that “don’t have any hair,” Herron said. The two sides of Iron Hound will help keep the firm well-positioned as the country enters a new period of uncertainty as it comes out of the pandemic. “There seemed to be a lender for every deal,” Herron said. “But going into 2022, an increased interest rate environment is something we’ll have to keep our eyes on. Deals are much more expensive than they were eight weeks ago. 2021 was a good year, markets opened up and interest rates remained low, and, for the most part, deals kept their heads above water. If inflation takes over, if growth slows down, there could be some problems, but we’re well-hedged to take advantage of that.” —P.S.
| MAY 3, 2022 | COMMERCIAL OBSERVER
27
Matthew Masso and Stefanos Arethas Head of Commercial Real Estate Finance; Head of Commercial Real Estate Origination at Credit Suisse Last year’s rank: 29
“We’ve done a lot over the past two or three years to target different investor bases and open up different execution channels that we can provide for clients,” Stefanos Arethas said. With total originations of $5.3 billion, Credit Suisse’s loan portfolio in 2021 was a blend of multiple asset classes: retail, hotel, cold storage, office, industrial, health care, senior housing and multifamily. Last year’s notable transactions included a $350 million financing for AECOM Capital and Combined Properties’ Pendry West Hollywood, a condominium development in West Hollywood, Calif.; a $345 million financing for the Four Seasons Hotel at the Surf Club in Surfside, Fla., and the Four Seasons Resort Palm Beach in Palm Beach, Fla.; and a $265 million loan for Brookfield Place in Manhattan’s Battery Park City. Consistent with previous years, Credit Suisse utilized creative distribution strategies. For example, centralizing all CRE mortgage lending under one team
BECOME A COMMERCIAL OBSERVER MEMBER
provides it with a broader market view. The Swiss bank remained committed to conduit and single-asset, single-borrower deals, but also focused on large bridge syndicated loans, non-rated securitizations, aggregation credit lines and warehouse financing. “I think size and speed basically are where we’ve always excelled,” Matthew Masso said. “Because we run lean, we have a team that turns things around quickly for clients that need that and we’re willing to close very large facilities and loans ourselves without putting the syndication risk on our clients.” In recognition of Credit Suisse’s commitment to gender pay equity, the bank was awarded the quality label from the Social Partnership Center for Equal Pay in the Banking Industry and has been certified with the “Fair Pay” label. Credit Suisse remained a top 100 employer in the 2021 U.K. Workers Equality Index ranking, a survey from the Stonewall organization that highlights efforts to promote LGBTQ+ equality in the workplace. —E.F.
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
LEFT TO RIGHT: COURTESY OF IRON HOUND, COURTESY OF CREDIT SUISSE
Robert Verrone.
Stefanos Arethas.
6E32
ABOUT THE AREA
CONTACT
- Citi Bike stations - Nearby parking - Short walk to Madison Square Park, Penn Station and 4, 6, B, D, F, M, N, Q , R, W subway lines
ADAM D. WEISSLEDER Senior VP / Director of Leasing 212.337.7763 aweissleder@merprop.com AMY FABIAN Vice President / Leasing 212.337.7775 afabian@merprop.com MAUREEN PESCATORE Leasing + Marketing Coordinator 212.337.7755 mpescatore@merprop.com
ELEVATE YOUR WORKPLACE. MOVE-IN READY.
6E32
ENTIRE 3RD FLOOR AVAILABLE 16,000 RSF N
Located between 5th and Madison Avenues in Manhattan’s NoMad subdistrict of Midtown South, 6 East 32nd street is located in one of the most desired neighborhoods of Manhattan.
3RD FLOOR FEATURES
3RD FLOOR CONFERENCE ROOM RENDERING
31ST STREET
32ND STREET
Loft-style spaces featuring hardwood floors and abundant natural light have attracted a variety of technology, media and other creative tenants to this 11-story, 173,600-square foot property.
- Open layout - Exposed ceilings - Operable windows
- Tenant controlled A/C - Hardwood floors
6E32
ABOUT THE AREA
CONTACT
- Citi Bike stations - Nearby parking - Short walk to Madison Square Park, Penn Station and 4, 6, B, D, F, M, N, Q , R, W subway lines
ADAM D. WEISSLEDER Senior VP / Director of Leasing 212.337.7763 aweissleder@merprop.com AMY FABIAN Vice President / Leasing 212.337.7775 afabian@merprop.com MAUREEN PESCATORE Leasing + Marketing Coordinator 212.337.7755 mpescatore@merprop.com
ELEVATE YOUR WORKPLACE. MOVE-IN READY.
28
Peter D’Arcy and Matthew Petrula Head of Commercial Real Estate and Senior Executive Vice President; Senior Group Manager of Commercial Real Estate and Executive Vice President at M&T Bank Last year’s rank: 28
M&T Bank’s commercial real estate operation originated $13.3 billion over the past year and is poised for even bigger growth following its merger with People’s United Bank. The Buffalo-based regional bank’s merger with Bridgeport, Conn.-based People’s United took effect in early April 2022, a move that expanded M&T’s footprint into new markets throughout New England. “From a size and scale standpoint it adds another $10 billion to what is already one of the largest real estate portfolios in the country,” Peter D’Arcy said. “It brings more breadth and scale to what was already a sizable platform.” “It will absolutely have tremendous benefits for the real estate group, because both banks are very much invested in real estate and are very relationship-focused real estate banks,” Matthew Petrula added. Some notable deal activity from the past year included an $82 million office building refinance of 50 West 23rd Street on behalf of Two Trees Management. The bank also piloted a $122 million construction loan for PMC Property Group to build out phase 2 of
Matthew Petrula.
Peter D’Arcy.
Sara Queen, Robert Merck, Gary Otten Head of Equity Strategies; Head of Real Estate and Agricultural Finance; Head of Real Estate Debt Strategies at MetLife
Robert Merck.
Last year’s rank: 24
MetLife hit record heights in 2021. The life insurance giant’s commercial mortgage team originated a company record 235 transactions last year totaling more than $15.3 billion across traditional as well as alternative property types including life sciences, self-storage and student housing. It also launched a closed-end hotel debt fund. Overall, MetLife recorded $18.6 billion of new commercial real estate debt and equity transactions and achieved a record $109.8 billion in gross commercial real estate assets under management. “Our real estate platform achieved record investment activity in 2021, creating value for our clients and partners despite continued challenges associated with the pandemic,” said Robert Merck. “This outstanding performance is a testament to the strength of our platform, the experience and agility of our team and our commitment to performance through cycles. We look forward to building on this momentum in 2022 as we continue to seek to deliver
Sara Queen. strong results for our stakeholders.” Notable transactions for MetLife in 2021 included a $184 million first mortgage loan for an EQT Exeter Core industrial portfolio comprising properties around the country. It also executed a $145 million first mortgage deal for joint venture Heitman and Life Storage to acquire a self-storage portfolio. In equity real estate investing, MetLife Investment
Gary Otten. Management (MIM) bought $3.3 billion in properties in 2021, 50 percent over 2020 activity. Notable deals included the $825 million acquisition of One Memorial Drive, a LEEDcertified office property in Cambridge, Mass. MIM was also active around the globe, with $781 million of new equity acquisitions and mortgage originations in Asia, $576 of new mortgage originations in the U.K. and $768 million of the same in Latin America. —L.G. and A.C.
Greg Murphy.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
COMMERCIALOBSERVER.COM
| MAY 3, 2022 | 53
TOP TO BOTTOM: COURTESY OF M&T BANK, COURTESY OF METLIFE
29
its 31-story, 374-unit Riverwalk multifamily project in Philadelphia’s Center City. On the acquisition side, M&T provided a $66 million loan for HUBB NYC Properties to purchase a 169-unit multifamily property at 247 North 7th Street in Williamsburg, Brooklyn. Last year also saw M&T launch new institutional real estate teams in New York and Washington, D.C., in an effort to expand its reach working with real estate investment trusts, private equity firms and debt funds. D’Arcy said the move reflects a formalization of M&T’s recent efforts to conduct business with institutional players and to lay a foundation for more expansion with its off-balance sheet platform. Also, in October 2021, M&T launched a $43 billion community growth initiative to support low- to moderate-income neighborhoods and people of color through loans and investments. The plan includes a further commitment to financing affordable housing, which D’Arcy said will only amplify M&T’s work in an area where it’s already one of the largest forces in the country. —A.C.
Andrea Balkan. Jason Hernandez.
30
Jessica Bailey.
Nailah Flake-Brown.
Alexandra Cooley.
Jason Hernandez, Jessica Bailey, Alexandra Cooley Managing Director and Head of Debt at Nuveen Real Estate; President and CEO of Nuveen Green Capital; CIO and Co-Founder of Nuveen Green Capital Last year’s rank: 31
LEFT TO RIGHT: COURTESY OF NUVEEN, COURTESY OF BROOKFIELD
Amid the myriad market shifts of 2021, Nuveen quietly saw its own longterm transition bear fruit. In 2018, the firm did $50 million in structured finance, which ballooned to $2.7 billion last year. A core part of its record-setting year was $6.5 billion in closed deals as the portfolio shifted to higher risk-adjusted returns and higher-margin credit investments. One highlight, a refinancing of 321 North Clark in Chicago for partners Hines and American Realty Advisors, felt like a smart, strategic play despite the risks associated with office space over the course of the pandemic. Jason Hernandez felt the firm was getting paid an attractive return to take the risk that capital markets would be open for a riverfront trophy asset in a few years. It was a rare foray into office for the firm, because with more action elsewhere, Nuveen can be selective about where it directs its energy. There’s a search for alternatives, one reason why Nuveen added approximately $600 million to its life sciences exposure last year. That mindset also pushed the firm into manufactured housing, with a $260 million deal for two portfolios with Crow Holdings. The sector’s seeing excellent demand amid a lack of supply. “Risk premiums are wider today than they were last year, returns are higher than they were before, and there’s more risk for sure with inflation and proceed levels,” Hernandez said. “You have headwinds for sure. I think it’s an attractive
54
time to go long on real estate credit. We didn’t see any industrial deals last year, and have already closed three this year. The structural volatility in the system makes it really attractive for us, and [2022] will be better than 2021.” Nuveen, which has a diverse debt business leadership comprised of half women and people of color, is also expanding its bridge lending expertise with a new strategy focused on emerging managers of color and women majority-owned funds. Jessica Bailey and Alexandra Cooley founded Greenworks Lending in 2015. Led by several of the C-PACE industry’s policy developers and standard-setters, Greenworks Lending completed the industry’s first rated securitization of CPACE assets in 2017 and went on to complete its second rated securitization in December 2018. Each of these securitizations received the highest possible score (E1) in S&P Green Evaluations. Nuveen acquired Greenworks in April 2021. As the investment manager of TIAA, Nuveen was responsible for $1.2 trillion in assets under management as of Sept. 30, 2021. Greenworks was rebranded as Nuveen Green Capital in 2022. It is now a national leader in sustainable commercial real estate financing solutions. Following its acquisition, Nuveen Green Capital has doubled its origination numbers, expanded into 25 states, and completed the industry’s largest 144A securitization of C-PACE assets. —P.S. and E.F.
| MAY 3, 2022 | COMMERCIAL OBSERVER
John Lee.
31
Andrea Balkan, Nailah Flake-Brown and John Lee Managing Partner of Real Estate; Managing Partner, Head of Debt Originations; Managing Directors of Real Estate at Brookfield Real Estate Finance Last year’s rank: 32
Brookfield stepped up its lending activity this past year with $6.3 billion of volume that was propelled in large part by a rebound in the investment sales market. Acquisition financing accounted for nearly 60 percent of Brookfield’s debt investments across the fund vehicles it manages. Brookfield was well-positioned to capitalize on demand for acquisition loans with the strength of its financing infrastructure. “We can underwrite deals very quickly and we have a very efficient approval process and very good certainty of execution,” Nailah Flake-Brown said, speaking of how Brookfield capitalized on borrower demand for acquisition loans. “It plays to our strengths.” Led by Flake-Brown, Andrea Balkan and John Lee, Brookfield’s platform was active in most of the core real estate sectors in addition to certain alternative asset classes like medical office, self-storage and film studios. Geographically, the team’s lending activity stretched across the U.S. while also growing in the U.K. and Western Europe. The firm’s loan portfolio has evolved from pre-pandemic times, when office lending accounted for around 60 percent of its activities.
BECOME A COMMERCIAL OBSERVER MEMBER
Today industrial and multifamily deals comprise a larger slice of the pie and the office sector now makes up less than 50 percent. Notable deals within the past year include a Brookfield closed-end fund vehicle providing $259 million of mezzanine debt as part of a $1.39 billion bridge financing secured by a multistate portfolio of 109 logistics properties. It also originated a $145 million loan to KSL and East West Partners for the joint venture’s residential condominium development on Kiawah Island in South Carolina. Brookfield has remained proactive in its diversity, equity and inclusion efforts, too, through a number of employee engagement groups, including a Black professionals network, Asian professionals network, women’s network and a Pride network. It also has established an internship program with a focus on attracting diverse candidates. “Brookfield has made a concerted effort to expand our employee engagement groups and to expand our diversity overall,” Flake-Brown said. “We continue to find deliberate ways to focus on getting more diverse candidates, which we are starting to have some success with.” —A.C.
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
Congratulates
Joe Fingerman on being named to the
Commercial Observer Power 50 List
Since joining Signature Bank more than 15 years ago, Joe Fingerman has continually demonstrated his leadership role in the commercial real estate arena. As head of Signature Bank’s Commercial Real Estate Banking Group, over the years he has forged strong client relationships and built a solid reputation industry wide. We deeply appreciate his commitment. All of us at Signature Bank take this distinct opportunity to thank Joe for his significant contributions and invaluable dedication to Signature Bank. We commend him on the prestigious honor of once again being named to Commercial Observer’s Power 50 List. We are proud to call Joe our colleague, and wish him years of continued success.
33
Jeffrey Fastov.
32
Michael Lavipour.
Jeffrey Fastov and Michael Lavipour
Richard Mack, Kevin Cullinan and Priyanka Garg Co-Founder and CEO; Co-Heads of Real Estate Credit Investment Business at Mack Real Estate Credit Strategies Last year’s rank: 34
When the lending market began to show signs of recovery in 2021, Mack Real Estate Credit Strategies (MRECS) was well-positioned to accelerate its loan growth. MRECS originated more than $4.3 billion for the one-year period ending March 15, including $3 billion in the second half of the year, underscoring its increased geographical footprint in a variety of sectors. “We began to have real confidence in the economic recovery, especially in some of the non-coastal, high-growth markets, and that conviction really carried our origination volume,” Kevin Cullinan said. “But we were patient in making sure we were comfortable with where the economy was headed before we really significantly ramped up originations.” Some of MRECS’ notable deals in the past six months include the origination of a $405 million loan in the fourth quarter to refinance The Park, a 249-unit multifamily property in Santa Monica, Calif., owned by Witkoff. Another sizable multifamily deal followed in the first quarter of 2022 with a $170 million loan to refinance X Denver, a new 455-unit property in Denver operated by a joint venture
between The X Company and Raven Capital Management. The lender was also active on the hospitality front in the last year, originating a $225 million whole loan to refinance JW Marriott, a 419-key hotel in Savannah, Ga., purchased by Kessler in 2012. Another big highlight for MRECS in 2021 was the initial public offering of its subsidiary, Claros Mortgage Trust, a real estate investment trust focused primarily on originating senior and subordinate loans for transitional commercial real estate assets. MRECS also in the past year continued its commitment to improve diversity in the CRE industry as a sponsor and active participant in Project Destined. Through the project, the firm will have two or three students interning in the summer and is hopeful this can lead to new hires that create a more diverse workforce. “We believe that a more diverse work environment is going to create value for our business,” Richard Mack said. “The more access we have to bright, young candidates that might end up being the most qualified and the best fit for our business, the better we are.” —A.C.
Senior Managing Director of Credit Strategies; Managing Director of Credit Strategies at Square Mile Capital Last year’s rank: 25
56
Capital Group’s multifamily development located at 123 Melrose Street in Bushwick, Brooklyn; a refinancing to purchase the $187 million HRR bonds on One Vanderbilt in Midtown with a sponsorship group of SL Green Realty Corp., Hines and National Pension Service of Korea; a $142 million construction loan for PMG and Greybrook’s multifamily development in Miami. Square Mile also closed two separate loans for Stream Realty Partners’ 300-acre site in west Houston. To boost diversity at the firm, Square Mile is participating in the Pension Real Estate Foundation’s SEO (Seizing Every Opportunity) program, which trains and places diverse candidates in internships in the real estate industry, by committing to hire and mentor an intern this summer. For the future, the company “will focus on high-quality real estate, probably more so than we have in the past,” Lavipour said. “We will narrow the box in terms of the credit quality of the assets that we’re doing. We’ll also look to expand into different capital flows.” —E.F.
| MAY 3, 2022 | COMMERCIAL OBSERVER
Christopher Richard LaBianca. Mack.
Priyanka Garg.
BECOME A COMMERCIAL OBSERVER MEMBER
Kevin Cullinan.
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: COURTESY OF SQUARE MILE CAPITAL, COURTESY OF MACK REAL ESTATE
The past year was an incredibly active one for Square Mile Capital, according to Michael Lavipour. The firm’s lending arm originated about $6.4 billion, including $3.1 billion of originations in the fourth quarter alone. On the origination side, the company focused on asset classes with proven resilience (Class A multifamily and well-located industrial assets), fast-growing sectors with significantly increased demand (life sciences and data centers), and COVID-19-impacted industries with strong long-term fundamentals (hospitality and residential condominiums). With creative restructurings and modifications on existing loans, Square Mile managed to stay ahead of potential issues in its portfolio. Over 50 percent of its loans were deployed in multifamily nationwide. In addition, the company continued to build its expertise in life sciences, focusing on ground-up construction and office conversion in the primary lab markets. Transactions of note in 2021 included a $368 million bridge loan for Atlas
34
Patrick Hanlon, Jason Krane, Evan Linkner and Russell Schildkraut Principals at Ackman-Ziff Real Estate Group Last year’s rank: 35
The housing market, a maelstrom of rising prices and shrinking availability that’s bedeviled buyers and renters, proved to be one of many bright spots for Ackman-Ziff Real Estate Group last year. Having tallied $5.75 billion in originations in 2021, with more than half exceeding $100 million each, the big deals overwhelmingly tended to involve the red-hot single-family rental (SFR) and buildto-rent markets. “I don’t think we’ve seen an asset class grow as much as this has for us,” Ackman-Ziff President Simon Ziff said. Ackman-Ziff did over $887 million in debt facilities for three large institutional SFR owners with nationwide portfolios, as well as a handful of other select housing deals, including a $120 million multifamily in California, a $101 million equity placement on New York’s Billionaires’ Row and a $132.5 million mixed-use residential refinancing in California. And that’s table setting in many ways for 2022; the firm is looking at
the biggest deal pipeline for the second quarter it has ever had. “It’s not a last year thing,” Ziff said, talking about what made 2021 so lucrative. “We maintain high integrity with our clients and capital sources,” he noted. “It’s a good time for capital advisers when the market is challenging, because you get more business due to the turmoil of the market. While we’re busy, every deal is extremely hard.” In looking back, the firm also sees its probono financing work on behalf of a partnership between the New York Philharmonic and Lincoln Center for the Performing Arts, providing a $175 million non-recourse bridge loan, as a big deal deserving of bragging rights. In addition, the firm’s AZ Educate summer program, which promotes diverse careers in commercial real estate, took on 85 students, many of whom landed internships or fulltime jobs at high-level firms such as Citibank, Amazon, Blackstone, Deutsche Bank and Goldman Sachs. —P.S.
Paul Vanderslice.
Patrick Hanlon.
Jason Krane.
Evan Linkner.
Russell Schildkraut.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
Head of CMBS at BMO Capital Markets Last year’s rank: *New*
Sometimes, a new platform takes a big “Slice” of the pie straight out of the gate. When Paul Vanderslice joined BMO Capital Markets in September 2020, he meant business. The industry veteran left his position as CEO of CCRE to organize the formation of BMO’s new commercial mortgage-backed securities (CMBS) platform, armed with more than three decades of industry experience. A household name in commercial real estate finance circles, Vanderslice previously spent more than 30 years at Citigroup, building out the megabank’s successful CMBS business. BMO Capital Markets, a subsidiary of Bank of Montreal, officially entered the CMBS market in the first quarter of 2021. Since then it has completed 28 CMBS transactions totaling $5.9 billion. Twenty-three of those transactions were single-asset, single-borrower (SASB) deals, and five were conduit deals, including BMO 2022-C1, which priced in February, debuting BMO’s newly formed shelf: BMO Commercial Mortgage Securities.
Not shying away from New York office, which has struggled with vacancy during the pandemic, BMO in March 2021 teamed up with Citigroup and Bank of America Securities as co-lead managers and joint book runners on the $350 million refinance of Vornado Realty Trust’s office tower at 909 Third Avenue. In August, it provided a $215 million, five-year CMBS refinance for ZG Capital Partners’ 1450 Broadway, which had a SASB execution. Since Vanderslice took the reins, the CMBS group has grown to 15 members — with an average of 17 years of industry experience — including Michael Birajiclian, David Schell, Andrew Noonan and Matt Jacobs. Alex Smith-Constantine runs its CMBS syndicate desk And there are no signs of the team’s activity slowing any time soon. Despite plenty of market volatility in the first quarter of 2022, BMO has already executed at least 13 deals totaling $3.2 billion. Any way you Slice it, that’s not too shabby. —C.C.
COMMERCIALOBSERVER.COM
| MAY 3, 2022 | 57
TOP TO BOTTOM: COURTESY OF BMO CAPITAL, COURTESY OF ACKMAN ZIFF
35
Paul Vanderslice
36
Jamie Henderson and Kate Byford Executive Vice President and Head of Commercial Real Estate; Senior Vice President and Head of Agency Finance at Capital One Bank Last year’s rank: 37
Jamie Henderson.
Dan Baker Head of Real Estate Capital at KeyBank Last year’s rank: 38
For the 12 months ending March 31, KeyBank originated $27.4 billion in loan volume across its real estate capital platform, which includes commercial mortgage-backed securities, Fannie Mae, Freddie Mac, Federal Housing Administration (FHA), investor placement and balance sheet. It originated $49.4 billion in loans over those 12 months when factoring in syndications. “Our loan volume was up almost $10 billion over a very volatile market for the last 12 months,” Dan Baker said. The Cleveland-based bank’s notable deals in 2021 included a $354 million Fannie Mae loan to refinance a 17-property student housing portfolio nationwide; a $99 million Fannie Mae loan for Turner Impact Capital’s acquisition of a 1,155unit affordable housing development in Glendale Heights, Ill.; and a $95 million life insurance company loan to refinance Northbridge Partners’ 11-property national industrial portfolio. “Our CMBS business was very busy last year,” Baker said. “We’re putting the money out everywhere, and we’re seeing dramatic growth in our
58
affordable business.” Multifamily represented 64.56 percent of Keybank’s loan portfolio in 2021. Second up was affordable housing at 8.75 percent. KeyBank is a 14-time winner of the Human Rights Campaign Foundation’s Best Places to Work for LGBTQ+ people and a 12-time winner of DiversityInc’s Top 50 Companies for Diversity. KeyBank says that in 2021 it increased the representation of people of color at its senior leadership and executive levels by 16 percent. The bank is committed to increasing representation of people of color in senior leadership and executive roles by 25 percent by 2025 and 50 percent by 2030. Employees at KeyBank are encouraged to get involved with various business impact and networking groups. These groups are designed to support diversity, equity and inclusion, and leverage the knowledge and experience of employees. As for 2022, Baker said, “With regards to inflation and dramatic rent increases, I think we’re going to see a brighter spotlight on the need for affordable housing.” —E.F.
| MAY 3, 2022 | COMMERCIAL OBSERVER
TOP TO BOTTOM: COURTESY OF CAPITAL ONE BANK, COURTESY OF KEYBANK
37
Kate Byford.
Capital One Bank had a record year in 2021, with total originations of $38.8 billion. The McLean, Va.-based bank adapted to the market by rolling out a bridge-to-agency program in 2021. Between March 2021 and March 2022, Capital One completed 27 transactions with 15 different clients through the program, totaling about $1.42 billion. Notable transactions included a $154 million bridge-to-agency loan sponsored by RXR for the acquisition of a 1.1 million-square-foot, full-block development in Brooklyn’s DUMBO neighborhood; and a $34 million bridge-to-agency loan sponsored by Trion Properties to acquire a 197-unit apartment community in Carmichael, Calif. “As we try to diversify geographically, we’re also diversifying by asset classes,” said Jamie Henderson. “We opened offices in San Francisco, Dallas, Atlanta, Denver, Chicago and Boston. We also launched a manufactured housing strategy on our balance sheet, and we have a whole series of specialty types of real estate in our pipeline that we’re trying to launch one per quarter.” Additionally, the bank leaned into data and insights to inform its expansion. Harnessing the data that it controls is a big part of Capital One’s strategy. “We can extract pretty unique insights as compared to peer banks,” Henderson added. As a top-six agency lender, the bank has a $50 billion agency business, which makes Capital One the highest-ranked bank among government-sponsored enterprises. The bank also has a dedicated debt fund strategy that provides leverage to non-bank financial institutions (NBFIs). Also, in 2021, Capital One joined forces with Project Destined to mentor a team in the program’s real estate competition. Project Destined’s mission is to help diverse youth become owners and stakeholders in the communities in which they live, work and play by providing them the opportunity to learn from and engage with developers, operators, agencies, brokers and lenders within commercial real estate. In addition to coaching the team throughout the competition, Capital One also hired two participants at the conclusion of the program. —E.F.
Dan Baker.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
You inspire us to greater heights. KeyBank congratulates our own, Dan Baker, on being recognized by Commercial Observer as a Power 50 Commercial Real Estate Finance Professional. Dan, your contributions to the industry have moved businesses forward and impacted communities at a deeper level. We are proud of you and your accomplishments. As a Top 5 Lender and Top 10 Originator,* Key’s national platform fosters deep relationships with our clients, serving them with innovative ideas and deep expertise. We instinctively know how to collaborate. It’s in our DNA. And we continue to be intentional in protecting our environment and extending our reach for social, economic, and racial equity while we work diligently to place clients where they need to be. Let’s talk.
key.com/rec
*Mx.com, 4/20/21. This is designed to provide general information only and is not comprehensive nor is it legal, accounting, or tax advice. All credit products are subject to collateral and/or credit approval, terms, conditions, availability and subject to change. Key.com is a federally registered service mark of KeyCorp. ©2022 KeyCorp. KeyBank is Member FDIC. 220413-1539868
1539868 KBREC Power 50 ad-P3.indd 1
4/15/22 10:42 AM
38
Last year’s rank: 39
SASHA MASLOV/FOR COMMERCIAL OBSERVER
Scott Waynebern Co-Managing Member at MF1
in Broward County, Fla. Last year’s stellar performance built off 2020, during which MF1 quickly mobilized, lending again within 60 days of the March 2020 lockdowns and seeing its volume jump 80 percent from 2019 to 2020. The team’s combined decades of multifamily experience is augmented with a commitment to diversity and inclusion in the hiring process, bringing a variety of life experiences and perspectives to the group. And 2022 already looks to maintain 2021’s pace, if not exceed it. Pandemic-era housing trends, including the move from higher-cost to lower-cost metros, continues to supercharge the sector. Despite being picky at the beginning of the year, deal volume is running ahead of where it was at the same time last year, Waynebern said, with “the market coming back to us” as inflation and rate fears inject more uncertainty. —P.S.
| MAY 3, 2022 | COMMERCIAL OBSERVER
TOP TO BOTTOM: COURTESY OF NEW YORK LIFE, COURTESY OF MF1
Last year’s rank: New
Within the ups and downs of 2021’s commercial real estate market, MF1, which focuses on bridge loans and multifamily originations, found itself “in the bullseye of the bullseye,” said Scott Waynebern. In a lender’s market, MF1’s originations topped $7.5 billion on 159 loans with a $47 million average loan value — a particularly high figure for a bridge lender, and proof positive of the mass movement to multifamily. “Somehow all roads lead to us and what we were doing last year, and [we] quickly created the No. 1 brand in the market,” Waynebern said. “We tripled our business.” MF1’s activity spanned the nation, including a $338 million refinance of a 421-unit luxury high-rise in Brooklyn; a $737 million loan for Tides Equities to acquire and renovate properties in a trio of Sun Belt cities — Phoenix, Las Vegas and Dallas; a $250 million recapitalization of prewar apartments in Washington, D.C.; and a $281 million loan for two apartment buildings
60
Senior Managing Director at New York Life Real Estate Investors
New York Life Real Estate Investors had an active 2021, lending on core, bridge, construction and mezzanine positions. The company’s transaction volume for 2021 totaled over $12.6 billion, broken down into $9.9 billion of commercial mortgage loans (CMLs), $1.8 billion of commercial mortgage-backed securities purchases and $923 million of equity. “Our CML volumes exceeded pre-pandemic levels, with the vast majority of production occurring during the third and fourth quarters of 2021 and first quarter of 2022,” said a company spokesperson. “New York Life took advantage of evolving capital market dynamics and generated alpha for its clients by providing surety of execution, particularly for year-end 2021 closings, and more recently against a continued backdrop of uncertainty due to inflationary and geopolitical concerns.” Much of the company’s lending activity was concentrated in multifamily and industrial, although tactical investments in office and retail were made “when the risk-value proposition met objectives,” the spokesperson said. There was also lending activity on hotels, medical office buildings and self-storage. Solutions to the pandemic’s sometimes byzantine challenges that New York Life employed included construction loans, bridge financing, mezzanine, and preferred equity positions. Additionally, the firm’s equity program is active in core, value add, new construction and repositioning developments. Notable transactions in 2021 for New York Life included two loans totaling $1.2 billion secured by a diverse portfolio of Class A industrial properties in major U.S. logistics markets, with sponsorship from a private equity investment firm; and a $420 million floating-rate loan secured by a portfolio of grocery-anchored shopping centers throughout the U.S., also with sponsorship from a private equity investment firm. —L.G.
Mark Talgo.
39
Mark Talgo
Scott Waynebern.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
$70 billion in Optigo loan volume $9.6 billion in Targeted Affordable Housing loans $674 million in LIHTC equity Leading the way. That’s our business.
Congratulations on a successful 2021, Rich Martinez and Freddie Mac Multifamily!
POWER HOUR: Our top brokers, including Dustin Stolly, reigned in helping to match borrowers with capital providers in a record year.
Power Sources After a turbulent 2020, top debt and equity brokers returned to the good life with colossal deals in 2021 By Emily Fu Illustration by Britt Spencer
N
ever underestimate the value of a power broker. Teams comprised of these help clients navigate up and down markets, securing financing for even the hairiest of asset classes during a global pandemic. So, after a rough (to say the least) 2020, how was 2021 for debt and equity brokers? They’re not shy in telling you. If you ask Cushman & Wakefield, the team was busy negotiating deals across asset classes and property types, but the two big winners in 2021 were industrial and multifamily. For CBRE, industrial comprised 48 percent of its originations, followed by office at 30 62
percent. The firm also grew its life sciences activity and closed its first data center deal. JLL executed deals across all property types with a focus on industrial and multifamily. “A big part of our business has become the joint-venture equity and structured finance practice,” said Christopher Peck, senior managing director and co-head of the New York office at JLL Capital Markets. Eastdil closed more than $6.15 billion of life sciences financings alone. “We did a tremendous amount of industrial and multifamily deals,” said Grant Frankel, managing director at Eastdil Secured, “and we have built out a sizable practice in the studio business.” Meridian’s 2021 deals were spread out over sectors that included office and selfstorage. The firm also closed what CoStar data indicates was the largest single-asset multifamily sale in the U.S. since 2018: $367 million
| MAY 3, 2022 | COMMERCIAL OBSERVER
of acquisition financing from Square Mile for Atlas Capital Group to purchase a multifamily property in Brooklyn, which sold for $563 million. It also brokered $4.9 billion of financing for health care developments. “Several years ago, we made it a point to diversify geographically, not just from an asset-class perspective,” said Keith Kurland, senior managing director and co-head of New York Capital Markets at Walker & Dunlop. “That target and thesis have played out well for our business as we have been incredibly active throughout the Sun Belt, South Florida, the Intermountain West and the West Coast.” As for Ackman-Ziff, the firm focused on the sizzling single-family rental (SFR) and buildto-rent markets. “I don’t think we’ve seen an asset class grow as much as this has for us,” said Simon Ziff, president of Ackman-Ziff. BECOME A COMMERCIAL OBSERVER MEMBER
Brokers also helped clients deploy capital in a hyper-competitive landscape. As Newmark’s Jordan Roeschlaub said, “I think we’re pretty good at seeing where there’s a crease in the marketplace, or an opportunity set for capital to find an entry point, and we run with it — whether it’s an asset class or a specific strategy.” To summarize brokers’ 2021, Cushman & Wakefield’s John O’Neill perfectly described the market wars brokers have fought, and won: “If you go back to the [global financial crisis of 2007-2009], then the global pandemic, we have all been tested in ways that we never thought we would be tested,” O’Neill said. “All these events create a certain resiliency, and some people tend to retreat, while some advance.” And every single person on our list, regardless of ranking, advanced.
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
Congratulations
Credit Suisse would like to congratulate all honorees on Commercial Observer’s 2022 Power 50 list. credit-suisse.com
© 2022, CREDIT SUISSE AG and/or its affiliates. All rights reserved.
CEO of Berkadia Last year’s rank: 36
If numbers tell a story, Berkadia had a very good 2021: 500 new employees; the continuation of 18 consecutive quarters of growth in servicing; $27 billion in investment sales; $40 billion in mortgage banking; No. 1 in combined Freddie Mac, Fannie Mae and Federal Housing Administration origination volume; and, total yearly production of more than $68 billion. “I felt an immense sense of gratitude when I saw that final number for the first time,” Justin Wheeler, who’s now responsible for a $337 billion servicing portfolio, said. This success didn’t just happen, he added, citing an intentional strategic plan, strong execution and daily hard work from every employee. “Our success simply would not have been possible were it not for the incredible collaboration of teams and individuals across our organization,” Wheeler said. “The pandemic has made it even more evident that people are at the heart of everything we do — and that individual people have individual needs, objectives and challenges.” To keep this heart pumping, and deepen its pursuit of diversity, equity, inclusion and belonging (DEIB), the firm
established a steering committee to oversee DEIB strategy, hired a DEIB consultant and launched resources like digital spaces where employees can connect, and programs like lunch-and-learns aimed at establishing DEIB as a core firm value. “We want DEIB to be a natural part of Berkadia’s culture,” Wheeler said. “The benefits of having a diverse workforce that feels inclusive and with a sense of belonging are well-documented.” Investing profits in people, processes and technology — during the pandemic — clearly paid dividends. Deals for 2021 include acquisition financing, construction, bridge loans and refinancing. A total of $96.5 million for Lincoln Avenue Capital to acquire a 569-unit affordable housing property in Alexandria, Va., and $100.2 million for Reliant Group to acquire a three-property student housing portfolio in Blacksburg, Va., are just two additions to the near doubling of Berkadia’s previous annual total production high ($37 billion in 2019). “We are incredibly proud of the strides made over the past year, and even more excited about where we are headed in 2022 and beyond,” Wheeler said. —S.P.
41
Neha Santiago.
64
Justin Wheeler.
Neha Santiago Head of Real Estate Private Credit at Cerberus Capital Management Last year’s rank: New
Neha Santiago joined Cerberus Capital Management in May 2020 while the world was buckling under the duress of the coronavirus pandemic. After more than a decade at Goldman Sachs, she was then tasked with building Cerberus’ brand-new real estate private credit business from scratch. But, with market disruption comes opportunity, and Santiago and her team quickly got to work. “We were sitting on a significant amount of dry powder while a lot of our competitors were sidelined working out their existing books,” Santiago said. “We were able to see the opportunity set through a clear lens, and take advantage of what was in front of us.” Since then, the platform has racked up $1.5 billion of whole loan originations, including a senior acquisition and redevelopment loan for the conversion of a flex office campus in Washington, D.C., to life sciences use, and a $72.8 million senior construction loan for Related Group’s Wynwood 29 residential and retail development in Miami’s Wynwood neighborhood. Cerberus’ debt platform has gravitated toward sectors that demonstrate resilience amid market volatility. As such, its loan portfolio is heavily (and happily) weighted
| MAY 3, 2022 | COMMERCIAL OBSERVER
to industrial and multifamily today, and it’s recently made strides into life sciences lending. The firm picks its spots carefully, viewing opportunities through a long-term lens with a focus on sustained trends. Leveraging Cerberus’ impressive, broader real estate platform, the debt platform in particular provides value to its borrowers in being flexible and creative in its approach to structuring deals — rather than adopting a one-size-fits-all mindset. “I think competition has always been a pretty constant and consistent characteristic of our industry, but I think our secret sauce — if you will — is definitely the flexibility of our capital,” Santiago said. “There’s a lot we’re able to do, in terms of where we play in the capital stack, and where we think we can generate the best risk-adjusted returns.” Diversity was part of the early DNA for Cerberus’ real estate debt business and has been a top focus for Santiago. Today, one-third of the real estate credit team is women and it’s 35 percent racially diverse. More broadly, Cerberus is dedicated to bridging opportunity gaps for underrepresented groups and fostering an inclusive environment. —C.C.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: COURTESY OF BERKADIA, YVONNE ALBINOWSKI/FOR COMMERCIAL OBSERVER
40
Justin Wheeler
Surround yourself with good people.
At UBS, we have built our business around you, our clients. We know that having the right people in place is fundamental for business success. We want to help you achieve your financial goals and deliver results beyond your expectations. And that means always striving to provide the advice, ideas and excellent execution you need to succeed. So we’re delighted to congratulate our very own David Nass and Christopher LaBianca, as honorees on Commercial Observer’s 2022 Power 50 list of the Most Important People in Commercial Real Estate Finance.
ubs.com/investmentbank
© UBS 2022. All rights reserved.
Managing Director; Senior Director; Managing Director at Invesco Last year’s rank: 45
Like many firms on this list, a true accounting of Invesco’s exceptional 2021 — the firm’s $4.1 billion in originations exceeded the previous record set in 2019 by 33 percent — starts in 2020. Invesco invested in 10 of 12 months that year despite reduced deal volumes, laying the groundwork and ramping up production to enter last year’s rebound; and seized on hot sectors amid a larger expansion of debt funds’ power in the market. Roughly 80 percent of activity was concentrated in residential, life sciences, industrial and self-storage, including a $240 million whole loan to finance the acquisition of a portfolio of five Houston-area apartment complexes by a joint venture between Partners Group and Knightvest Capital. It was a contrarian market for multifamily at the time, Charlie Rose said, but it was a great example of the firm’s flexibility, which allowed it to move quickly and “sprint through” the year.
investors, Rose said. “I’m accustomed to being the only gay person in the room throughout my entire career,” he said. “My team doesn’t think in one way, and, because we’re able to avoid groupthink, that drives better performance for our investors.” Invesco entered 2022 knowing the wind wasn’t at its back in today’s more tactical and volatile environment, with negative leverage on many deals. Nonetheless Rose and his team see an opportunity to expand their business once again, and focus on basics, such as core life sciences hubs with Longfellow, a long-time partner, and aggressively expand their activity in Europe with existing clients. “Being the steady hand in the credit market and there consistently for our clients is the right thing to do for our business, and [will] reap benefits in increased market share over time,” Rose said. —P.S.
“We’re fully embedded in markets around the country, and would typically pursue loans our equity colleagues would own,” he said. “It’s a very bottom-up approach to real estate investing in the credit position in the stack. And it’s truly a relationship approach.” Invesco sees its strategic strengths as both speed and finding a middle ground. As a “property-first” lender that approaches lending as a real estate investor first, Invesco says it aims to offer the flexibility of a responsive, creative non-bank lender, and the tight pricing that institutional investors expect. Diversity also plays a crucial role, with a completely diverse class of managing directors, including Rose, one of the few openly gay portfolio managers in the industry. The firm’s broad diversity commitment includes a targeted mentor program with 45 mentees and a diverse suppliers initiative pilot program. It’s the right thing to do, and also does right by
43 Katy Mao.
Ainslee Burns.
66
Amy Johannes.
Yorick Starr.
Teresa Zien.
43. Katy Mao, Amy Johannes and Ainslee Burns Managing Director in Real Estate Group; Managing Director in Real Estate Group; Vice President in Real Estate Group at Oaktree Capital Last year’s rank: New
Led by an all-female team, Oaktree Capital’s real estate practice played an integral role in organizing mezzanine loans and financing redevelopments for a record number of transactions in the Eastern U.S., according to Katy Mao. Oaktree originated around $1 billion in loans in 2021 alone. The portfolio composition includes office, hospitality, multifamily, for-sale residential, life sciences, retail and industrial. Notable transactions included a $274 million mezzanine loan for the redevelopment of Terminal Warehouse in Manhattan’s West Chelsea; a mezzanine loan in a $500 million acquisition financing for 111 Wall Street, which also included $90 million of C-PACE funding to reduce the building’s carbon footprint and help the owners comply with New York City’s Local Law 97 environmental regulations; and a redevelopment financing of 125 West End Avenue on the Upper West Side from a former ABC studio into a new life sciences and research facility. “The main themes that we are watching closely in real estate include an increased focus on public securities given the current volatility in the market, specifically on single-asset, single-borrower deals, as well as an increased emphasis on [environmental, social and governance], particularly in the areas of energy conservation and tenant wellness,” Amy Johannes said. “In New York, lenders and equity investors are spending an increasing amount of time
| MAY 3, 2022 | COMMERCIAL OBSERVER
Charlie Rose.
understanding the implications of Local Law 97 for sustainable buildings.” Since 2019, Oaktree’s real estate team has been very active in the lending space from both the perspective of private origination as well as commercial mortgage-backed securities/public securities, with a focus on gateway cities and out-of-favor sectors like offices, hotels and condominiums. As of Dec. 31, 2021, Oaktree’s real estate group had $16 billion in assets under management across its opportunistic, debt and income strategies. The team is made up of 54 professionals and the leadership team has an average of 26 years of experience investing in real estate. In terms of diversity, equity and inclusion initiatives, Oaktree stood out with strong female leadership from Mao, Johannes and Ainslee Burns. Mao leads Oaktree’s real estate debt sourcing efforts across the Eastern U.S., while Johannes is a senior member of the firm’s opportunistic team and sits on the credit committee. Burns, who was previously on the opportunistic team, has now transitioned to the debt team to lead the execution of deals. Looking ahead, “We’re also seeing more interesting opportunities in retail properties that have outperformed expectations during the pandemic, as well as more activity in the hospital space for those who take a longer-term view on the ultimate recovery of hotel demand,” Burns said. —E.F.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: COURTESY OF INVESCO, COURTESY OF OAKTREE CAPITAL
42
Charlie Rose, Yorick Starr and Teresa Zien
MF Greenpoint Class A Greenpoint Class A
Sunset Park Conversion Sunset Park to Article 11 Conversion Affordable to Article 11 Affordable
Harlem Workforce Housing Harlem Workforce Housing
Harlem Class A Harlem Class A
Coney Island Class A Coney Island Class A
Jamaica New Construction Jamaica New Construction
Williamsburg Class A Loft Williamsburg Class A Loft
Upper East Side Class A Upper East Side Class A
Murray Hill Class A Murray Hill Class A
44
Christopher LaBianca and David Nass Managing Director and Head of Commercial Mortgage Originations; Managing Director and Head of Real Estate Finance at UBS Last year’s rank: 48
repeat clients sought. “I’d love to say we’ll do every big deal, but that’s not who we are,” Christopher LaBianca said. “Understand what your institution’s mission is, and align your goals with that, and that’s the key to success.” In addition, UBS was the 2021 recipient of the Mortgage Bankers Association’s Commercial/Multifamily Diversity, Equity and Inclusion Leadership Award in recognition of expanded hiring and retention efforts, such as UBS’ diversity recruiting partnership with the nation’s historically Black colleges and universities. “Interesting start to the year,” LaBianca said, with “a lot more activity early on than we had last year, and signs it’ll be difficult given the rate environment. Hopefully we’ll be able to sustain some of that going forward.” —P.S.
Christopher LaBianca.
45
Joseph Fingerman.
68
| MAY 3, 2022 | COMMERCIAL OBSERVER
David Nass.
Joseph Fingerman Senior Vice President of the Commercial Real Estate Lending Group at Signature Bank Last year’s rank: 43
At the start of 2021, many Signature Bank clients were feeling the pandemic’s effects. Residential and commercial tenants struggled to pay rent, making mortgage payments a challenge for borrowers. That’s no surprise to anyone in real estate (or paying attention to the news). Signature was ready and willing. “While many banks did not even answer the phone, our employees stayed in constant contact with borrowers,” said Joseph Fingerman, who has led the bank’s commercial real estate lending group since 2018. While other financiers took a pause through COVID-19, Signature continued to lend. “Today, we are seeing the fruits of our labor,” Fingerman said. “Our borrowers’ buildings are improving with each passing month, and we have seen high client satisfaction levels since we were there when the times were tough.” The “fruits” total 632 loans equaling $4 billion of new transactions. Standout deals included $125 million to Aurora Capital Associates and Edmond Safra to buy a retail condominium at 530 Fifth Avenue in Midtown; $39 million to STRO Companies to refinance a portfolio of eight industrial
BECOME A COMMERCIAL OBSERVER MEMBER
properties in Northern New Jersey; and $127.6 million to the Durst Organization to refinance 10 Halletts Point in Astoria, Queens. Industry-leading turnaround time from term sheet to closing is a source of pride. For the 10 Halletts Point deal, as an example, Fingerman and Aaron Greene, vice president and group director, worked around the clock. Term sheet to commitment/approval time was just under a month, with the deal closing two weeks later. “The team is very practical,” said Fingerman of the ability to efficiently structure transactions that make sense for both borrower and bank. Today, the Signature team is 60 percent women and 40 percent men. Signature always hires the most competent person for the job, said Fingerman, who joined the bank in 2007. “Going back a decade or so, there weren’t many women in the CRE space. Today, I look at our emerging leaders and see women and men both excelling.” He also sees life returning to normal. “Many people bet against New York City during COVID-19,” Fingerman said. “The most exciting part of 2021 was seeing New York City recover and knowing that people want to live, work and play here.” —S.P.
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: COURTESY OF UBS, COURTESY OF SIGNATURE BANK
It’s never simple to devise a winning formula for investment, especially in a tumultuous year. But UBS found that a focus on industrial and multifamily bolstered a banner year that saw $3.6 billion in originations. A series of big deals in these surging pandemic-era sectors — including serving as co-lead for the $2.4 billion ILPT acquisition of 98 industrial assets from Monmouth Real Estate, and $384 million in loan financing for a 12-property, 2,700unit multifamily portfolio — led to strategic success. Half of the firm’s lending focused on the industrial sector. And a more responsive business model ultimately helped service its high net worth client base. By expanding its balance sheet and significantly enhancing it, too, with a bridge loan program that offered short- and long-term options, UBS offered the flexibility its
I N V E ST M E N T T Y P ES » All major property types in growing urban markets
» Shovel-ready ground-up construction
» Flexible and efficient debt structures » Senior loans of $75 million or more
» Inventory loans on completed condominium projects
» Subordinate loans of $50 million or more
» Rescue capital to borrowers
» Heavy value-add repositioning
LOAN SIZE
LOAN TERMS
LOAN TYPE
$ 5 0 M – $ 1 B+
1 -1 0 YEARS
F I X E D / F LO AT I N G
TO LE A R N MO R E , V I S I T WWW. S ILVCAP.CO M Michael May 212.313.4671 mmay@silvprop.com
Marty Burger 212-551-7370 mburger@silvprop.com
Shawn Katz 212.551.7311 skatz@silvprop.com
Tyler Hasemann 212.551.7341 thasemann@silvprop.com
Founder, Chairman and CEO of Arbor Realty Trust Last year’s rank: 44
Ivan Kaufman has been closely involved in all aspects of Arbor Realty Trust’s business since he founded it in 1983. “I am not afraid to get into the details of a deal, and often work directly with our originators and meet with clients to get a deal across the finish line or address issues,” he said. This hands-on approach really paid off last year when business almost exceeded, well, hands. The challenge so many businesses in the U.S. are facing — recruiting and retaining staff — was not an obstacle for Arbor, and it originated $16.1 billion in loans, up 76 percent compared with its record of $9.1 billion in 2020. “Our firm strategy and business model were validated in 2021, as we could accommodate the surge in demand for transitional financing, single-family rental [financing], and continue to be a leader in the securitization market,” Kaufman said. “It was because of our highly experienced and dedicated management team, and our long-tenured employees, that we were able to compensate for staffing challenges, and have such a productive and fruitful year.”
At a granular level, Kaufman said, “Our teams’ processes have become more efficient from screening deals, issuing quotes, underwriting, closing, funding and servicing. We simply would not have been able to have such a big year if we didn’t become more efficient.” Big, as in growing Arbor’s balance sheet book 122 percent in 2021. The largest contributor to that growth was a $166.1 million portfolio loan to AJH Management for acquisition of The Commons at White Marsh, a multifamily property in Maryland. At the firm level, “the rapid growth in our balance-sheet loans has not only contributed to our immediate earnings, but also helped build our future pipeline,” Kaufman said. “Additionally, the return of securitizations, and our position as a leader in [collateralized loan obligation] securitizations, allowed us to generate attractive levered returns on our capital.” To promote diversity and inclusion, Arbor offers internships to college students with diverse backgrounds through Fannie Mae’s Future Housing Leaders program. —S.P.
Ivan Kaufman.
47
John Adams.
70
| MAY 3, 2022 | COMMERCIAL OBSERVER
John Adams Senior Executive Vice President and Chief Lending Officer at New York Community Bank Last year’s rank: 40
John Adams joined New York Community Bank (NYCB) in 2000. Plainly: He manages credit risk, ensuring the bank’s asset quality passes muster. To dress it up a bit: The bank’s multifamily loans rose $2.4 billion (7 percent) and specialty finance loans rose $451 million (15 percent) over the previous year. And asset quality was top-notch with non-performing assets at 7 basis points — of $59.5 billion in total assets. Among other things on the path to loans totaling $45.7 billion for 2021, Adams was responsible for negotiating the terms of NYCB’s biggest deal last year: $163 million for the acquisition of a package of multifamily properties in the Midwest for a long-time client. He says 2021 offered the best kind of challenge: keeping up with the growing needs of the customer base, especially in terms of geographic expansion. How to do it? Be responsive; seize the opportunity; and join them. “As long-term relationships ventured into other markets, we broadened our reach,” Adams said. That meant he got to travel. “I like to kick the tires in different markets,” he said.
BECOME A COMMERCIAL OBSERVER MEMBER
“People can’t help but talk sometimes. They’re honest. Gives you a chance to learn what’s going on in the local market.” The result: expansion of NYCB’s multifamily lending program into the Sun Belt. And expansion to different sectors is in play too. “We’re not a big player in the office market space, but, like everyone, we’ve taken a step back to reevaluate the higher-than-usual, higher-than-industry-norms office vacancies,” Adams said. Don’t misinterpret. This is not an announcement of a strategy shift. NYCB’s focus remains multifamily, the executive said, but the bank can’t help but consider it. NYCB is also considering community impact, recently announcing a five-year commitment to provide $28 billion in loans, investments and other financial support to communities and people of color, low- and moderate-income families and communities, and small businesses. Further, Adams said, without giving anything away, “We look forward to expanding our diversity and inclusion program with upcoming acquisitions.” Stay tuned. —S.P..
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: COURTESY OF ARBOR REALTY TRUST, COURTESY OF NYCB
46
Ivan Kaufman
Trusted partnerships are important. At M&T, we know that growing and maintaining strong relationships with our customers truly matters. Our industry experts work to understand your goals and provide customized solutions to meet each borrower’s unique needs.
Let’s build greatness together. BRIDGE LOANS | CONSTRUCTION LOANS | PERMANENT LOANS | CORPORATE FACILITIES I FANNIE MAE DUS® FREDDIE MAC OPTIGO® | FHA/HUD MULTIFAMILY AND HEALTHCARE I LIFE INSURANCE COMPANY | CONDUIT (CMBS)
350 Park Avenue | New York, NY 212-350-2000
Equal Housing Lender. All loans are subject to receipt of a complete application, credit approval and other conditions. “DUS®” is a registered trademark of Fannie Mae. “OptigoSM” is a registered trademark of Freddie Mac. ©2022 M&T Bank. Member FDIC. NMLS #381076. AMP-2207 220421 mtb.com
Chief Lending Officer; Head of U.S. Commercial Real Estate Lending and Senior Vice President at Bank of China Last year’s rank: 49
Bank of China (BOC) U.S.A. originated a total of $2 billion for the 12 months that ended March 20. “During the pandemic, we continued to execute repeat business with borrowers and other lenders, and we got a lot of word-of-mouth referral business,” said Anthony Wong. In 2021, BOC U.S.A.’s loan portfolio was primarily in urban, infill locations where the bank has branch locations. Specifically, those locations included New York City, Los Angeles and Chicago. According to the team, they only lend to top sponsors in gateway cities where their senior debt stack is moderately levered and well-structured on Class A collateral. “Obviously, we love New York City and have terrific decades-long relationships with the best operators that call the Big Apple home and sponsors located throughout the U.S.,” BOC U.S.A.’s CRE team said in a statement. Notable deals include providing a $1.5 billion construction loan to finance SL Green Realty Corp.’s construction of One Vanderbilt, a Class A, 1.7 million-squarefoot office building adjacent to Grand Central Terminal in 2016. BOC U.S.A., with
the bank group, upsized the construction loan to $1.75 billion in 2018 and contributed to the largest single-asset single-borrower commercial mortgage-backed securities in June 2021. One Vanderbilt became one of the pandemic’s major success stories, with three-figure rents per square foot. The bank refinanced $327 million of a $655 million term loan secured by a 5.7 million-square-foot, mixed-use office building in Brooklyn. BOC U.S.A. also provided a $280 million, solely underwritten term loan to refinance the construction loan of a 76-story, 800-unit luxury multifamily property located on Grant Park in Chicago. “Our greatest asset is our talented CRE team,” Wong said. “What we do is we think as a group, we work as a team, we roll our sleeves up, and we get our mandates close and never quit.” Women hold executive leadership roles throughout all levels of the bank, including in corporate banking, trade finance, retail banking and the technology business. “Throughout the pandemic, we’ve benefited from a 100 percent talent retention rate and there’s no staff turnover,” Wong noted. —E.F.
49 Toby Cobb.
Jonathan Roth.
72
Justin Kennedy.
| MAY 3, 2022 | COMMERCIAL OBSERVER
Anthony Wong.
Raymond Qiao.
Jonathan Roth, Toby Cobb, Justin Kennedy Co-Founders and Managing Partners of 3650 REIT Last year’s rank: New
Zero typically isn’t a figure that makes it onto a financial firm’s annual highlight. But for 3650 REIT, the fact that it saw zero defaults across its portfolio just underscores the high performance and hands-on approach the firm brought to 2021. Nobody else achieved that goal, according to Morgan Stanley’s Originators’ Score Card, with loans in default hitting an industry-wide high of 12 percent. “COVID gave us a chance to test our plumbing,” said Jonathan Roth. “COVID provided that opportunity, and, not at all to make light of the suffering that came during the pandemic, but we were happy to take it.” The nationwide alternative lender and special servicer notched $1.64 billion in originations this past year, and made two preferred equity investments in portfolio transactions worth more than $1.2 billion to launch its preferred equity investment program during 2021. Highlights included playing a key
BECOME A COMMERCIAL OBSERVER MEMBER
role as a sponsor and a retaining sponsor for the monster $1.23 billion loan on the Cambridge Crossing II life sciences complex in Cambridge, Mass., for a partnership of CalSTRS, New York State Teachers’ Retirement System and Divco West, a prominent example of the institutional push in biotech. It also made preferred equity investments in portfolio transactions worth more than $1.2 billion, spanning 33 assets, with an asset class-agnostic approach that was much more open to potential retail and office deals that others avoided, from malls in Reno, Nev., to office towers in Houston. “Everybody else is outsourcing the servicing component,” said Toby Cobb. “We called every borrower in our portfolio and said, ‘don’t default, talk to us.’ So many borrowers wanted to default so they have somebody to talk to; that never happened here. Forty-eight percent of our existing pipeline is repeat borrowers.” —P.S.
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
TOP TO BOTTOM: COURTESY OF BANK OF CHINA, COURTESY OF 3650 REIT
48
Raymond Qiao and Anthony Wong
Mack Real Estate Credit Strategies congratulates all of the industry leaders selected to Commercial Observer’s 2022 “Power 50 List of the Most Important People in Commercial Real Estate Finance”
MACK REAL ESTATE CREDIT STRATEGIES, L.P. 60 Columbus Circle, 20th Floor – New York, NY 10023 212 484-0050 For information about lending programs, please contact: credit@mackregroup.com
Under Pressure COVID in China, war in Ukraine and inflation; 2022 is finding new ways to challenge financiers By Patrick Sisson | Illustration by Britt Spencer
W
hoever said, “may you live in interesting times,” perhaps never had to deal with a capital stack or arrange funding for billion-dollar deals. Just when some of the uncertainty of COVID-19 had begun to fade, the economy was shaken by a ground war in Europe, inflation and rate woes, and a constantly evolving supply chain crisis. It’s no wonder Power 50 winners have found solace, and success, in positive thinking, pushing through the challenges of the pandemic to aggressively seek deals in an active but uncertain time. As Neha Santiago, head of real estate private credit at Cerberus Capital Management, said, even in the fog of conflict and concern, firms need to “see the opportunity set through a clear lens, and take advantage of what was
74
in front of us.” The extreme circumstances, and often record volumes, of 2021 may just have been the boot camp for a more intense ride in 2022. Reactions in response to this tumultuousness have been fierce, with a sharp, V-shaped recovery and significant portfolio shifts toward safer harbors such as warehouses, logistics, manufactured home and life sciences (and now, in many cases, back to retail), as well as a crowded multifamily market. New regulations and environmental laws, like New York City’s Local Law 97, changed some calculations. New circumstances required more deliberate customer management and outreach; or, as JLL’s Christopher Peck put it, “we ran a global roadshow via Zoom.”
| MAY 3, 2022 | COMMERCIAL OBSERVER
And market shifts and new opportunities required that entirely new deal structures and classes be figured out and financed; Citi’s $10 billion single-asset single-buyer deal for the data centers at QTS Realty Trust required new metrics, new understanding and roughly 100 one-on-one meetings. There were also bold plays to buoy signature assets that lost their shine, such as the the $350 million refinance of Vornado Realty Trust’s office tower at 909 Third Avenue, or CBRE’s $1.25 billion construction loan for Manhattan’s Terminal Warehouse, a deal that “New York City really needed,” said CBRE’s James Millon as it was an office redevelopment with no pre-leasing at a time when office was a dirty word. No surprise, then, that the Terminal Warehouse financing deal drew BECOME A COMMERCIAL OBSERVER MEMBER
congrats even from CBRE’s competitors, who understood just how fraught, and frantic, the last year had been. While 2020 may have been a “baptism by fire,” according to Kara McShane, head of commercial real estate at Wells Fargo (and No. 1 on our list), 2021 was a rocketship for many. It could be said that the last few years have been a search for assets and opportunities that offer resilience, but the financing deals behind those assets have required resilient teams willing to constantly reevaluate and reposition themselves in response to an ever-evolving landscape, especially as capital gets more expensive. As Greystone CEO Stephen Rosenberg put it, “I would say we’re still catching our breath, but we’re not stopping.”
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
Chris Niederpruem.
Managing Director and Group Head of Real Estate Finance at CIT Group Last year’s rank: 42
Few need to be told that 2021’s V-shaped pandemic rebound caused volatility in the commercial real estate market, but not everyone knows how to pivot. “We had to remain extra nimble during the dip and rebound, supporting our clients while also figuring out how to work from home,” said Chris Niederpruem. Primarily focused on multifamily and industrial properties, CIT’s ability to be nimble, plus a rebounding financing market, resulted in $1.9 billion of total originations, in addition to record levels of capital raised around commercial real estate strategies in 2021. And the news didn’t stop there. CIT merged with First Citizens Bank at the end of last year (officially closing in January 2022). Niederpruem, who joined CIT in 2011, said it was the most exciting part of last year. “We now find ourselves part of a much larger bank with deeper pockets, a broader range of services, a far larger client base and more expansive physical footprint,” he said. Nationwide even before the merger, a California-based CIT team originated a $41.6 million loan to Tailwind Investment Group and Kairos
BECOME A COMMERCIAL OBSERVER MEMBER
Investment Management Company to acquire and renovate a 276-unit multifamily property in Hemet, Calif. Niederpruem described the transaction as an example of the firm’s relationship strategy and focus on repeat business with experienced, well-capitalized developers. “Those relationships endure in good times and challenging times,” he said, “but are especially important to both sides when markets are volatile and uncertain.” This strategy, he said, accounts for other successes too, like the $35.7 million loan to Quinlan Development Group for the construction of 230 Classon Avenue, a multifamily project in Brooklyn; and $39.6 million in financing for Clarion Partners’ acquisition and development of an industrial facility in Baltimore, Md. Internal relationships are also important. “Leaders across the bank, including those on my team, are committed to advancing the company’s IE and D [inclusion, equity and diversity] efforts by encouraging our associates to participate in IE and D and community development initiatives, as well as share their viewpoints in listening sessions,” Niederpruem said. —S.P.
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
Drew Fung and Thanh Bui.
Honorable Mention Drew Fung and Thanh Bui Head of Debt Investment Group; Managing Director at Clarion Partners Amid market challenges posed by the COVID-19 pandemic, Clarion Partners seized new opportunities within the red-hot industrial sector. The lender originated $570 million in calendar year 2021 with more than 70 percent of its volume concentrated in industrial deals. Clarion, which has always been an active investor in the debt and equity side of industrial properties, capitalized on numerous lending opportunities in the sector, providing subordinate debt at attractive risk-adjusted spreads. “There’s a certainty and a competence that folks have with us because they know that the firm’s pretty familiar with the property type,” Drew Fung said of Clarion’s strong foundation in the industrial sector. “It helps to not be sort of a johnny-come-lately to the sector where you have to kind of learn everything now that it’s popular.” Clarion’s expertise with industrial paid dividends in February 2022 when it supplied a $415 million mezzanine loan as part of a package to refinance a portion of Blackstone’s
Cubic/Colony industrial portfolio comprising 110 properties totaling 15.7 million square feet in 15 markets. The transaction closed in less than three weeks. Fung and Thanh Bui have been business partners since the late 1990s and have overseen Clarion’s debt activity for the last 10 years. The duo specializes in originating and structuring subordinate debt investments for core, value-add and development properties from mezzanine loans, B-notes and preferred equity interests. Clarion was also active with multifamily transactions during the past year, supplying mezzanine capital for ground-up developments in high-growth markets like Memphis; Mesa, Ariz.; and San Bernardino, Calif. The firm has also laid a foundation to target other property sectors with risk-adjusted returns including self-storage, senior housing and single-family rental. Overally, Fung said, “2021 was where we broadened our horizons a bit. You always have to stay fresh and look forward for new ideas.” —A.C.
COMMERCIALOBSERVER.COM
| MAY 3, 2022 | 75
LEFT TO RIGHT: COURTESY OF CIT GROUP, COURTESY OF SASHA MASLOV/FOR COMMERCIAL OBSERVER
50
Chris Niederpruem
FINANCE
Debt Deals of the Week
Wells Fargo Lends $173M on Manhattan Apartment Property Buy Eugene Asset Management landed $172.9 million of acquisition financing for its purchase of an Upper West Side multifamily asset from Related Companies, Commercial Observer has learned. Wells Fargo originated the Fannie Mae-backed loan which carries a seven-year term with five years of interest-only payments to Eugene, a Korean-based asset manager that acquired The Lyric luxury apartment property from Related for $266 million. Cushman & Wakefield’s Gideon Gil and Lauren Kaufman arranged the financing. PincusCo first reported news of the sale, which marked Eugene’s first U.S. purchase. Cushman & Wakefield’s Adam Spies and Doug Harmon arranged the transaction. Located at 255 West 94th Street, The Lyric comprises 285 units within steps of Central Park. The property’s amenities include business center, rooftop sun terrace, children’s playroom and fitness center. Officials for Wells Fargo and C&W did not return requests for comment. Eugene could not be reached for comment.—Andrew Coen
76
345 Park Avenue South. portion of the space as its headquarters today. The investment firm engaged Gensler to lead the property’s redesign and conversion into a vertical life sciences campus, now known as CURE, comprising 11 floors of lab-ready
space. Allowing for either individual or collaborative tenant work, the building includes wet labs, dry labs, workplace zones, rooftop multipurpose space and an educational facility.
Upland restaurant and Bank of America are the building’s retail tenants on the ground floor. CBRE and AIG officials declined to comment. Deerfield didn’t return a request for comment. —Cathy Cunningham
Miami Industrial Park to Double Footprint With $154M Construction Loan Bridge Point Commerce Center, an industrial complex in Miami Gardens, Fla., is expanding. The owner, Bridge Industrial, scored $153.5 million in construction financing from CIBC Bank USA to build the second phase of the development, which will feature two warehouses totaling nearly 1.6 million square feet. The complex is expected to be delivered by the third quarter of 2023, according to the Illinoisbased developer. Steve Roth of CBRE secured the loan. Bridge Industrial three years ago completed the first phase, which is now fully leased. It consists of three warehouses totaling 1.1 million square feet. Last year, Bridge Industrial secured a $117.5 million debt package to refinance the industrial park. Also in 2021, City Furniture
| MAY 3, 2022 | COMMERCIAL OBSERVER
leased 287,000 square feet, which was the year’s second-largest industrial lease in South Florida, according to The Real Deal. The other tenant, HapCor, a grocery distributor to the Caribbean and Latin America, is leasing 114,808 square feet. Located at 4310 NW 215th Street, the 2.6 million-squarefoot development sits on a 186acre site, adjacent to the Ronald Reagan Turnpike and less than four miles from Hard Rock Stadium. Miami Gardens, thanks to its proximity to Miami and Fort Lauderdale, has become a hotbed for industrial development. Earlier last month, private equity giant Blackstone proposed a 2.3 million-square-foot industrial complex that would cost an estimated $700 million. —Julia Echikson
AARONP/BAUER-GRIFFIN/GC IMAGES
PROPERTYSHARK
The Lyric.
Deerfield has refinanced its life sciences innovation campus at 345 Park Avenue South, Commercial Observer has learned. AIG provided the $440 million, 15-year loan in its entirety, sources said, and the deal closed April 22. CBRE’s James Millon, Tom Traynor and P.J. Finley negotiated the debt — the same team that arranged the $540 million Blackstone loan for the property’s acquisition and conversion from office to life sciences use in September 2019. (Finley recently joined North Bridge as a vice president.) The 12-story, 300,000-squarefoot block-front building sits between East 25th and East 26th streets, steps away from Madison Square Park. Deerfield purchased the building from Aby Rosen’s RFR Holding in May 2019 for roughly $525 million, and utilizes a
COURTESY OF CBRE
AIG Refinances Deerfield’s 345 Park Avenue South Innovation Campus With $440M Loan
WELLS, WELLS, WELLS!
Bridge Point Commerce Center.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP Caption caption here.
FINANCE
Redwood Urban has secured $108.4 million in refinancing for nine multifamily properties in Hollywood, Beverly Hills and Long Beach in Los Angeles County. The 400-unit portfolio was refinanced with a Fannie Mae credit facility. Bellwether Enterprise Real Estate Capital (BWE) originated the loan for Redwood and announced the refinancing. REBusiness Online first reported the deal. Redwood did not immediately return requests for comment. Strong investment and increased sales prices persist in Southern California as the average apartment rent rises at more than twice the rate of inflation. For example, Redwood’s refinance follows shortly after MF1 Capital’s $328.8 million acquisition loan for Laguna Point Properties’ big 1,037-unit acquisition downtown. Six properties totaling 267 units in Redwood’s portfolio are adjacent to or within a block and a half of each other near Hollywood’s tourism district just north of Hollywood Boulevard. They are located near the Ovation Hollywood retail center at Hollywood and Highland, and near many other landmarks like the TCL Chinese Theatre and the Capitol Records tower. The portfolio also includes 29 units at 9152 Alden Way in Beverly Hills and at 8600 Burton Way in L.A. near Cedars-Sinai Medical Center. Finally, there are 104 units at 210 Third Avenue and 225 Long Beach Boulevard in Long Beach, which features 15,000 square feet of ground-floor retail space. Jason Krupoff of BWE’s Irvine office originated the loan. —Greg Cornfield
AARONP/BAUER-GRIFFIN/GC IMAGES
Redwood Urban Secures $108M for 400 Units in LA
A view over the Hollywood Hills in L.A.
John Molina’s Pacific6 Enterprises has landed $55 million of financing to implement environmentally friendly upgrades to its planned multifamily property in Southern California, Commercial Observer has learned. X-Caliber Funding, a subsidiary of X-Caliber Capital, and CastleGreen Finance provided the debt package, which includes a $34.4 million short-term first-mortgage loan and $20.6 million in long-term Commercial Property Assessed Clean Energy (C-PACE) financing through the California S t at e w ide C om mu n it ie s Development Authority’s (CSCDA) Open PACE Program. Pacific6 Enterprises will use the funding for a multimillion-dollar renovation and adaptive reuse of its Ocean Center Luxury Apartments project on 110 West Ocean Boulevard in Long Beach, Calif. The deal was led by Chris Callahan, CEO of X-Caliber, and Sal Tarsia, managing partner at CastleGreen Finance. Berkadia’s Matt Raptosh arranged the transaction. Pacific6 Enterprises also received $94 million of financing, including
COURTESY OF PACIFIC 6 ENTERPRISES
X-Caliber, CastleGreen Lend $55M on SoCal Multifamily Development
A view of Long Beach, Calif. a $45.5 million C-PACE loan, from X-Caliber and CastleGreen last September for its Breakers Hotel & Spa property in Long Beach. Molina purchased the Ocean Center Luxury Apartments site in 2018 when it was a vacant office building. The 1920s historic landmark property will house 80 units with amenities that include a terrace, a clubhouse and a fitness center. The $20.6 million C-PACE loan
BECOME A COMMERCIAL OBSERVER MEMBER
will finance energy upgrades aimed at significantly reducing greenhouse gas emissions at the rate of an estimated 189.08 metric tons of carbon dioxide per year. The project, which is slated for completion in early 2023, also includes three restaurants and a retail store. Callahan noted that teaming up with its affiliate company CastleGreen provided an ideal combination for a “one-stop financing”
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
deal that also delivers a positive environmental impact. “C-PACE loans are really designed for this type of project,” Callahan said. “It is a historical property that qualifies under California’s C-PACE program.” CSCDA’s Open PACE Program facilitates financing for property owners seeking infrastructure improvements for energy efficiency, renewable energy and
water conservation. The platform enables borrowers to pay funds back over time through a voluntary tax assessment that provides a longterm, low-cost financing option along with an ability to transfer repayment to the next property owner. “C-PACE is an excellent way for us to demonstrate our commitment to sustainable development,” Molina, founding partner of Pacific6, said in a statement. “We look forward to reopening the historic Ocean Center, bringing the 1920s to the 2020s in grand fashion.” The Ocean Center Luxury Apartments project will save 466,256 kilowatts of electricity a year and reduce water consumption by 4.9 million gallons a year. Savings are estimated at $65,079 in the first year and $1.9 million over 30 years, according to X-Caliber. Callahan foresees continued growth with C-PACE-backed debt deals in California and other areas of the country that are starting to advance the program, including New York City and Chicago. “I really see it growing expeditiously,” Callahan said. “We are just scratching the surface.”—A.C.
COMMERCIALOBSERVER.COM
| MAY 3, 2022 | 77
FINANCE
ChartFinance CMBS Delinquency Rate Improves Slightly “The CRED iQ overall delinquency rate for commercial mortgage-backed securities (CMBS) showed nominal movement during the April 2022 remittance period but still tallied a decline for the 23rd consecutive month,” wrote Marc McDevitt, a senior managing director at CRED iQ. “The delinquency rate, equal to the percentage of all delinquent specially serviced loans and delinquent non-specially serviced loans, for CRED iQ’s sample universe of $500 billion-plus in CMBS conduit and single-asset single-borrower (SASB) loans was 3.83 percent, which compares to the prior month’s rate of 3.84 percent. CRED iQ’s special servicing rate, equal to the percentage of CMBS loans that are with the special servicer (delinquent and non-delinquent), declined month over month to 5.88 percent from 6.09 percent. “The special servicing rate is now approximately 45 percent lower than its pandemic-era peak of 10.79 percent in October 2020. Aggregating the two indicators of distress — delinquency rate and special servicing rate — into an overall distressed rate (delinquencies special servicing) equals 5.97 percent of CMBS loans that are specially serviced, delinquent or a combination of both. “The overall distressed rate declined compared to the prior month rate of 6.19 percent. The overall distressed rates typically track slightly higher than special servicing rates as most delinquent loans are also with the special servicer. The individual delinquency rate for the retail sector spiked higher in April to 7.34 percent, compared to 7.06 percent as of March 2022. “The sharp increase can be attributed partially to a
78
| MAY 3, 2022 | COMMERCIAL OBSERVER
reversion to delinquent payments from the $125 million Westfield Palm Desert loan, which is secured by a regional mall in California. The loan was marked as current in payment during previous months but became 30-days delinquent as of April 2022. “Westfield Palm Desert transferred to special servicing in August 2020 and was delinquent for nearly all of 2021. Notably, the loan sponsor, Unibail-Rodamco-Westfield, was featured in the news in early April 2022 for providing an update on its planned divestiture of U.S.-based regional malls. “The delinquency rate for lodging properties continued to show meaningful and consistent improvement. For a second consecutive month, the outstanding balance of delinquent lodging loans declined by more than $450 million. “The lodging delinquency rate was 7.55 percent in April, which compared to 7.99 percent the month before. One of the largest delinquency cures in April was the $135.1 million Marriott LAX loan, which is secured by a 1,004-room hotel adjacent to the Los Angeles International Airport. The loan was modified in February 2022 and terms of the agreement brought the loan current in payment. The loan transferred to special servicing in December 2020 and had been delinquent in payment until the closing of the modification agreement. “Changes in special servicing rates by individual property type were a mixed bag in April. “The special servicing rate for lodging declined by approximately 15 percent. A large component of the shift was caused by the $982 million loan secured by the
Ashford Hospitality Trust Portfolio. The loan transferred to special servicing in June 2020. The loan returned to the master servicer in April after furniture, fixture and equipment (FF&E) reserves were replenished from being used to pay debt service during a forbearance period. “Special servicing rates for retail (11.21 percent) and office (3.73 percent) both increased compared to the prior month. The increase in the office special servicing rate was anticipated given March’s revelation of Blackstone’s intentions to hand 1740 Broadway back to the lender. “The increase in the special servicing rate for retail was driven by Destiny USA — a 2.1 million-squarefoot regional mall in Syracuse, N.Y., owned by Pyramid Management Group. The distressed shopping center secures a $430 million loan that is securitized in the JPMCC 2014-DSTY CMBS transaction. The loan transferred to special servicing due to imminent default ahead of the loan’s June 2022 maturity date. “The Syracuse mall loan had previously transferred to special servicing in April 2020 and returned to the master servicer in March 2021 after a loan modification. Another one of Pyramid’s properties, Walden Galleria, was a major driver behind increases in retail distress in April. “CRED iQ’s overall CMBS distressed rate by property type accounts for loans that qualify for either delinquent or special servicing subsets. In April, overall distressed rates for retail, office, industrial and self-storage increased while lodging and multifamily exhibited declines in overall distress. Two of the largest loans added to the distressed category, both via transfers to special servicing, were the aforementioned 1740 Source Broadway and Destiny USA.”
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
FINANCE
The Takeaway y Data courtesy of
In March, the number of mortgages filed with the New York City Department of Finance spiked by 46 percent compared to February with 1,191. Deal volume rose considerably in every property sector including industrial (103 percent), hotels (93 percent) and office/lofts (93 percent) and commercial condos (89 percent). Mixed-use and multifamily also showed strength in March with month-over-month increases of 52 percent and 31 percent, respectively.
Refinances vs. Purchases The market for refinances in NYC far oputpaced purchases with debt financing.
895
623
296
Top Lenders JPMorgan Chase maintained its lengthy hold as New York City’s most active lender in March with 147 deals, up 23 percent from February. New York Community Bank and Signature Bank stayed in the second and third place positions, respectively. First Republic Bank jumped to fourth place after not cracking the top 15 in February. Webster Bank moved up to fifth from 10th place. BANK FEB. BANK MAR.
JP Morgan Chase
120
JP Morgan Chase
147
New York Community Bank
45
New York Community Bank
66
Signature Bank
33
Signature Bank
40
Apple Bank
22
First Republic Bank
36
NCB
20
Webster Bank
31
Dime Community Bank
20
Flushing Bank
29
Flushing Savings Bank
19
Cathay Bank
22
Valley National Bank
15
Investors Bank
20
Merchants Bank
14
Ridgewood Savings Bank
19
Webster Bank
14
Amerasia Bank
19
Investors Bank
13
Dime Community Bank
17
First National Bank Of Long Island
13
NCB
16
Connectone Bank
11
Morgan Stanley
16
Cathay Bank
11
Apple Bank
15
TD Bank
11
Most Active ZIP Codes—Financing
192 I
The most active zip codes in March were heavily centered around The Bronx, Manhattan and Brooklyn. FEB.
MAR.
FEB.
REFINANCES
F
MAR.
PURCHASES
Total Sales by Borough Investment sales in the city climbed in every borough. (Staten Island is not tracked).
403
G
442
171 183 126
ZIP CODE
FEB.
ZIP CODE
MAR.
11226
26
A
10029
26
11221
20
B
11229
23
11211
19
C
10011
22
11219
18
D
10467
21
11237
18
E
11219
21
10011
17
F
10457
21
10003
15
G
10033
21
10458
15
H
11211
21
10025
14
I
10458
20
11385
14
J
11226
19
K
11385
19
D
A
C
K H
J
134 E
53 65
80
53 60
FEB. MAR.
FEB. MAR.
FEB. MAR.
FEB. MAR.
FEB. MAR.
ALL
MAN.
BRONX
BROOKLYN
QUEENS
| MAY 3, 2022 | COMMERCIAL OBSERVER
Goose Property Management nabbed an $86.7 million debt package from Scale Lending to build a multifamily development at 575 Grand Street in Williamsburg.
B
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
M U LT I FA M I LY
M U LT I FA M I LY + COMMERCIAL S PA C E
NON-OWNER OCCUPIED COMMERCIAL R E A L E S TAT E
Competitive mortgages. Community expertise. Take advantage of your real estate investment opportunities today. Comprised of experienced lenders with local market knowledge, Flushing Bank’s Real Estate Lending Team offers one-on-one guidance to help you find the most favorable solution to fit your needs. As a leader in NY commercial real estate lending, we provide competitive rates and a streamlined loan process so you can capitalize quickly. Email us at CREcall@FlushingBank.com or call: Scott Barber Al Bozzolo Sean Howland Jeff Levintov
718.512.2783 718.512.2784 516.820.1145 718.593.8069
Tim Lynn Denis Mangan Matt Nugent Ivan Nunez
718.593.8077 718.512.2790 718.512.2868 718.512.2908
John O’Connor 718.512.2826 Denise Ruggiero 516.820.1149 Robert Schepis 718.593.8073
Small enough to know you. Large enough to help you.® 220 RXR Plaza, Uniondale, NY 11556 • FlushingBank.com/lending
Flushing Bank is a registered trademark
FEATURE
Boss Baby
New York real estate is largely silent on Mayor Eric Adams’ plan to turn empty office space into day care — and with good reasons By Celia Young | Illustration by Kevin Whipple ew York Mayor Eric Adams plans to use about $50 million to create a tax abatement and a tax credit program to increase the number of day care centers in the city and make care more affordable — hopefully getting parents back to the office alongside their babies. While Adams expects the abatement and credit to create the thousands of new day care seats by converting office space to day cares and lowering the cost of care to employees, newly constructed child care centers may not arrive for at least a year, given the logistical challenge of converting offices into kidfriendly spaces. And both benefits are likely to run into one major problem: a shortage of child care workers. “From our perspective, incentivizing the creation of new child care facilities and seats is a good thing,” Maya Kurien, the Real Estate Board of New York’s (REBNY) vice president of policy and planning, said. “Financing a center doesn’t mean you’re going to have a child care center tomorrow, because those retrofits are going to take time.” Adams estimated that the employer tax credit could create up to 6,600 new seats for children and that tax abatement– funded renovations could open 11,000 additional seats in New York City. The funding for the two programs comes from tax revenue the city will give up to allow for the benefit, according to the city. At the same time, New York City will expand the availability of child care subsidies to low-income families with $4 billion Albany lawmakers allocated to the city for child care in the latest state budget. New York City, home to an estimated 500,000 children 5 years old or younger, is in desperate need of child care. The impact from a lack of child care has been particularly felt by the city’s mothers, 41 percent of whom are not working compared to 24 percent of the city’s fathers, according to a report from the nonprofit Citizens’ Committee for Children. Statewide, at least 1,500 child care programs closed between April 2020 and June 2021 — most of which were owned by women or minorities as the state delayed distributing federal coronavirus relief funds. Child care deserts — areas without enough day care slots to serve the children living there — are also prevalent in upstate New York. Nationally, providers have struggled to hire child care workers after about 360,000 childcare jobs were eliminated because of initial pandemic-caused shutdowns in 2020. Enter Adams, with a private sector solution: a $25 million property tax abatement program for eligible landlords to build their own day cares. The program is two-tiered, with eligible buildings in child care deserts getting more money than buildings in areas with enough care. But landlords have been quiet on the issue. Thor Equities, Silverstein Properties, Tishman Speyer, RXR and Rudin
82
| MAY 3, 2022 | COMMERCIAL OBSERVER
Management Company declined to comment, and Vornado Realty Trust and Related Companies did not respond to requests for comment on whether the firms would take advantage of the program. A spokesperson for the Durst Organization said the landlord hadn’t looked at the program but supports access to child care generally. The tax abatement program is broken down into two tiers. The state’s Office of Children and Family Services (OCFS) will offer a tax abatement for reasonable construction costs of up to $75 per square foot, or up to $225,000 total, for buildings in child care deserts, and $35 per square foot, or up to $100,000 in total, for other properties, according to the city. The abatement is distributed over the five-year period of the budget, so a landlord with an eligible property in a child care desert could snag $15 per square foot for five years. But those centers could take more than a year to build. First, to gain approval to convert office space to day care space, a landlord would have to check with a variety of city agencies — namely the Department of Buildings (DOB), the New York Fire Department and potentially the Landmarks and Preservation Commission (if the building is landmarked), said Frances Graham, senior managing director of the Northeast and a project manager for Newmark. The DOB can take anywhere from a week to a month to review an application, according to the agency. The DOB would need to approve converting an office to day care space, and issue an ALT-CO permit — a document that lets a landlord renovate a space for a new use, which would also require a new certificate of occupancy. The DOB would then inspect the new facility based on the number of changes a landlord made, according to a spokesperson for the city agency. Next up is the six-month-or-so design and development phase of the project, during which an architecture firm would plan the space’s layout and mechanicals. After that, construction could take nine months to a year to complete, putting the entire timeline at 18 months, plus the city approval process, said Graham. Those construction costs — including building additional exits, bathroom renovations, fire alarm systems and more — would be included in the city benefit, per a city spokesperson. Prior to her work at Newmark, Graham worked on a similar conversion, transforming an office building into an Upper West Side school. The entire construction process took between nine months and a year, and included installing smaller toilets and sinks, replacing interior glass doors with metal locking ones, and installing a double-door entrance system to let school staff securely buzz students in and out of the building. While the process would take more than a year, Graham sees the day care program as potentially very valuable to working parents. “My daughter was in day care from when she was 6 months
old because I had to go back to work, and it was very helpful that there were good day cares around,” Graham said. ”I think it’s a great opportunity for people … so that they feel more comfortable going back to work.” But the lengthy conversion process doesn’t bode well for a speedy return to the office, something Adams has prioritized. Property owners would also have to hire workers to operate a day care center or contract a provider to do so, potentially running into the same problem established child care centers face: a shortage of workers. About 460,000 families across the U.S. lack adequate child care, and the industry as a whole lost about a third of its workforce at the start of the pandemic, according to a Wells Fargo analysis. A lack of child care also may be impacting the so-called “great resignation” — roughly half of workers who quit their jobs last year cited child care issues as a reason why they quit, according to a Pew Research Center survey. “Child care centers have closed across the country, and that has made it hard for people to come back to work in offices,” Kurien of
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
FEATURE
REBNY said. “There are a number of different things that would have to go into actually making these centers possible. But an incentive that helps with the cost of that is a good thing.” With day care positions offering little job stability and a median hourly pay of $12 per hour, employees might not be jumping at the chance to work for less than the minimum wage available at the average Starbucks. “The tax abatement is a great idea [and] the conversion of office space to day care space is great, but we need the caregivers — and they need to be able to make a living being a caregiver,” said Leah Hartman, the department chair for accounting, finance and marketing at the University of New Haven. The United States suffered from a shortage of child care workers before the pandemic, although the lack of staff became particularly pronounced as centers closed, laid off employees or reduced the number of children admitted thanks to pandemic-related social-distancing requirements, Hartman added. Landlords and other businesses could skip the regulatory hoops of the abatement program and go right for the business
BECOME A COMMERCIAL OBSERVER MEMBER
income tax credit Adams is also proposing, although it too could face labor challenges. The tax credit, funded with $25 million in forgone city tax revenue, would give a business money for providing free or subsidized child care to its employees. To qualify for a subsidy, a business must charge employees no more than 40 percent of the market rate for child care, which the OCFS determines. A maximum of 25 children of employees at any business can be counted toward the credit, limiting the program’s impact for large companies. The benefit is calculated based on a child’s age, so that 20 percent of the total annual cost of placing an infant or toddler in a day care can be claimed as a credit against business taxes. Businesses must partner with a permitted child care service provider to be eligible, according to the city. City parents would benefit from more state aid, as the state budget also increases the availability of child care subsidies to families to help ease the burden of care, which can cost anywhere from $10,000 to $20,000 per child each year. The proposed budget would make families with an income of
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
around $83,000 eligible for subsidies, as opposed to the previous $53,000 cap for a family of four — adding an estimated 100,000 eligible children, per the budget. (Notably, children who are undocumented will not be eligible for subsidized care in the budget, leaving out about 5,000 children across the state.) Gov. Kathy Hochul’s budget also includes $343 million in stabilization grants to providers of child care to cover the cost of operating during the pandemic, and the state is expected to change how it calculates reimbursement rates to allow providers to pay their employees more. Paying employees more money, or providing them with other incentives to stay in the child care field, may prove more crucial than the need for day care space, Hartman said. “[It is] fantastic that an employer is going to be able to more cost-effectively offer space, but you still have to have the people to run it — and preferably trained people,” Hartman said. “During COVID-19 we’ve asked a lot of them to put their lives on the line … They were front-line responders and were getting paid $13 an hour.”
COMMERCIALOBSERVER.COM
| MAY 3, 2022 | 83
THE SIT-DOWN
By David M. Levitt | Photographs by Stephanie Price
Veteran litigator Danielle Lesser talks about the unexpected pandemic-era changes in the back and forth between retail tenants and landlords essy, messy, messy. One could argue about this, but it does seem that no other category of commercial real estate is weirder and more haunted at the moment than brick-and-mortar retail. All you have to do is look around and see the abandoned shopping malls, and all the once-envied locations that have been sitting empty for months and months, going on years and years. Stores with doors had their problems even before COVID-19 came along. With the e-commerce revolution, stores had to adjust to the ease with which their customers could order goods on their laptops and smartphones. Many made the adjustment to food and gyms. After all, one can’t exercise or eat a good meal on their phone. Then there was COVID-19, and governors were declaring lockdowns, and tourists were impeded from traveling and shopping. There went that customer base. One of the people who got a guided tour of the wreckage was Danielle Lesser, chair of business litigation at law firm Morrison Cohen, where she’s also a partner. She regularly represents retail tenants in disputes with landlords. It was a dicey situation. Many declared “force majeure” which, translated from legalese, means a force no one could have predicted. After all, who predicted a pandemic? Were it only that easy. Who is the victim here? The retailers who were denied their customers? Or the landlords who were deprived of their rents? Both have to deal with a bank with its hand out. Lesser in late April answered some questions from Commercial Observer and explained what is going on in the grueling world of retail litigation, especially from the tenant perspective. Her remarks have been edited for brevity and clarity. Commercial Observer: What is it that you do and what is your specialization, especially regarding retail? Danielle Lesser: I have been a litigator for about 30 years. And I litigate very frequently in the real estate arena. I specialize in litigating retail leasing issues on behalf of retailers. And very recently, over the course of the last two to three years, I was very heavily involved
84
| MAY 3, 2022 | COMMERCIAL OBSERVER
in litigating a lot of issues on behalf of these very large retailers — nationwide retailers — in their disputes with landlords, which in large measure is a response to the COVID-19 pandemic. So it was not just litigation. It was also negotiation and dispute resolution to resolve issues that those tenants had in the payment of rent. Just about all my questions involve retail. But I also wanted to give you an opportunity to talk about your non-retail expertise. That’s so nice of you. I litigate all manner of real estate-related disputes. I generally stay away from single-family residential. I have represented a lot of national retail tenants, but I also represent a fair number of real estate private equity shops, real estate investors. I have represented developers, generally speaking, in real estate contract issues that have come up. So I have a broad real estate litigation background. Is this a particularly special time in commercial real estate, either because of the pandemic or technology, perhaps? Give me your overview of what has been going on. It’s a very interesting time in real estate. Not specific just to retailers, but I think all parties involved are affected not just by the pandemic, but supply chain issues in very varied and interesting ways. You know, on the one hand in the retail sector you had the parties directly affected by store closures and government regulations. But in other aspects of real estate you see the proliferation of logistics centers and warehouses. You also see a shift in foot traffic. And that, I think, has affected a lot of different aspects of retail leasing. There are certain major corridors, for example, in New York City where people used to pay premium rents because of the foot traffic, and those areas really aren’t experiencing the same foot traffic that they experienced four or five years ago. And today you see a move out to more suburban areas, because of the proliferation of the hybrid work environment and working from home. The consequences of the pandemic are impossible to encapsulate in a two-minute answer, but they are very, very far-reaching and have impacted real estate in a lot of very unique ways. And that has driven litigation in some very
unexpected ways. What ratio are you seeing between retailers trying to break in versus those trying to get out? I would say that, today, for the most part, retailers have really reset their real estate portfolios during the pandemic. And I think, for those retailers who were successful in their negotiations with bigger landlords, they revamped their portfolio, they terminated some leases, extended others in locations that they felt were possibly more lucrative on a long-term basis. You are dealing with retailers who have skinnied down their portfolios, who are now looking to opportunistically take advantage of a much more favorable rental market where landlords are much more flexible than I think they were before the pandemic. So, I think retailers right now are looking for those opportunistic leases in possibly different areas from where they might have looked three or four years ago. It sounds like “flexible” is a euphemism for landlords lowering their rates, so landlords can have occupied space rather than empty storefronts. In a lot of cases, you’re seeing lower base rents with higher percentage rent. You’re seeing changes to the way gross sales are being calculated, so that landlords can benefit from increases in sales that their retail tenants are experiencing. So, yes, I guess they have more skin in the game. I mean, I hate that phrase. But essentially their fortunes are rising and falling with their tenants in order to keep their spaces occupied and to keep foot traffic up. What are the legal ins and outs of the relationship between retail tenants and their landlords these days? And is there enough commonality that they get along, or is it a dispute waiting to happen? During the pandemic, the state of the law was in flux. But now, more than two years later, there are enough decisions out there where the parties really understand the lay of the land. And I think you’re seeing a lot of negotiation, and I think you’re seeing a lot of positive and productive discussions between landlords and tenants. You’re also seeing some changes in provisions like force majeure clauses, which, I like to say, is sort of a new
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
THE SIT-DOWN
Danielle Lesser.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
COMMERCIALOBSERVER.COM
| MAY 3, 2022 | 85
THE SIT-DOWN
‘It all comes down to a complicated mix of paying rent, increasing foot traffic, making sure stores are open ...’
twist on an old clause. Force majeure clauses used to just be boilerplate that nobody ever took a second look at, and they, as you know, rose to prominence during the pandemic. And now those provisions are really getting a very, very careful look, by landlords and tenants, and they are much much more important than they ever were before.
sometimes they’re inserting force majeure clauses to relieve them from the obligation of delivering a premises at a certain time, and they’re unable to complete the tenant improvements because of supply chain issues. So you see the impact of the pandemic seeping into a lot of these standard provisions.
MORE OR LESSER: One of the big questions Danielle Lesser has been dealing with is how force majeure clauses are being written and carried out in a postCOVID-19 world.
It seems these can be seen as existential on both sides. Retailers depend on customers having access to their stores, and landlords depend on their tenants being able to pay rent. What does that look like from your perspective? What it looks like is an allocation of economic risk and issues that people are now far more aware of. It all comes down to a complicated mix of paying rent, increasing foot traffic, making sure stores are open, making sure they can open. And there is a push and pull from a negotiating perspective. What you’re seeing is that some of these less desirable malls are struggling. Having said that, I think you’re also seeing a move from traditional e-commerce brands to using brick and mortar as a tool of marketing. A lot of traditional e-commerce online brands are now opening stores. Maybe not the size of store that you might have seen in the past, but you’re seeing them opening these stores. Whether they walk in, or they just walk by, customers see the brand, and it drives them either into the store, or online to increase sales.
For the people who may not know, explain exactly what force majeure is. A force majeure clause is a clause which frees parties from their obligations under an agreement if certain circumstances take place that are beyond a party’s control. So if there’s an unforeseeable circumstance that interferes with a party’s ability to perform, there’s a force majeure clause to address how the parties are going to deal with the economic consequences of those unforeseen circumstances. So, I would imagine, if you have a hotel, and the governor has just issued a lockdown or some foreign leader has declared there will be no international flights into some city where COVID-19 is happening, the hotel may suffer a sharp and unexpected decline in its clientele, and that might or might not be considered force majeure. Exactly. Force majeure language has been very narrowly interpreted by the court. And it’s also a very, very specific analysis. There are some force majeure clauses, which say an economic impact is not a force majeure event. There are some force majeure clauses that say that, while unforeseen circumstances might interfere with the performance of certain obligations under a contract, it will not be perceived or agreed to interfere with a tenant’s obligation to pay rent. So you might have an unquestionable economic impact as a result of an unforeseen circumstance, but you have to look very closely at the clause to see whether that will excuse your obligation to pay rent. And that’s the very issue that landlords and tenants are focusing on in their negotiation of these clauses. What new clauses are retailers demanding, and how have landlords responded? A lot of them are focused on rent abatement — whether it’s a force majeure clause or a rent abatement clause, or an obligation to stay open. Landlords and tenants have different strategies for addressing those types of provisions. And, obviously, tenants with more bargaining power are successful in achieving more favorable terms. But landlords, for example, are requiring
86
| MAY 3, 2022 | COMMERCIAL OBSERVER
notice that a tenant wants to invoke a force majeure provision or some sort of rent abatement provision. The tenant has to provide notice within 10 days, or some period of time after an unforeseen circumstance arises. And, if the tenant doesn’t do it, then the tenant is foreclosed from saying that a force majeure event, or any other circumstance that would result in a rent abatement, has arisen. Landlords are trying, as I mentioned before, to except the payment of rent from a force majeure or rent abatement clause, and
tenants are obviously pushing back on those sorts of limitations. And tenants are insisting on provisions that talk about government shutdowns, pandemics that may interfere with their conducting their businesses as they normally would, and they’re looking for relief from that. Sometimes what you see in response to that is a limitation on the period of time of the rent abatement; maybe it’s limited only to six months. With the supply chain issues that we’re experiencing today, landlords are having timing issues with tenant improvements. So
It seems we are seeing the recession of the traditional shopping mall model of having a couple of department stores as anchors, and filling in the gaps with smaller stores. Now the mall is built around the food court, or the restaurants on the outparcels, or in some cases, actually in the mall. I agree with you. And I think what you’re seeing generally is a rise in essential services that may not necessarily be essential services — but the provision of food is. And the rise in restaurants at centers, I think, focuses on the center’s recognition that you have to create an experience to drive foot traffic. Right now, you can go online and buy your Lululemon pants without leaving your home; you’re not necessarily going to walk into the store. But if there’s a great restaurant, or if there’s some other attraction at the center that draws you in, you just might walk into that Lululemon store and buy the pants. So you have to convince the consumer to actually have the in-store experience.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
$2,100,000 Yonkers, New York | Multi-Family Building
$4,000,000 Kensington, Brooklyn | Mixed-Use Building
TURNING VISION INTO
OPPORTUNITY
$6,250,000 Crown Heights, Brooklyn | Multi-Family Building
Whether you’re looking to acquire or refinance a multi-family, mixed-use, office or retail property, Ridgewood Savings Bank will provide eligible borrowers up to 75% financing to make your opportunity a reality. Connect with a local real estate pro at ridgewoodbank.com/team.
$7,600,000 Hudson Heights, Manhattan | Multi-Family Building
Credit approval required. © 2022 Ridgewood Savings Bank. All rights reserved.
NYC | BROOKLYN | QUEENS | BRONX | WESTCHESTER | LONG ISLAND
EVENT
That should be behind any successful retail or hospitality strategy coming out of the pandemic, according to experts at a recent Commercial Observer forum By Anna Staropoli he future of New York City’s retail rests on creating an all-encompassing physical experience rather than a mere shopping trip. During Commercial Observer’s annual “Retail & Hospitality Forum: The New & Now Trends Driving the Retail Resurgence” on April 26, industry experts discussed such strategies for sustaining brick-and-mortar retail. One brand spearheading success in this pandemic-hit sphere is Allbirds, a sustainable footwear retailer that recently leased 8,000 square feet at 120 Fifth Avenue. CO’s Max Gross moderated a discussion between Joey Zwillinger, co-CEO of Allbirds, and Nicholas Haines, CEO of Allbirds’ landlord, developer The Bromley Companies. They highlighted the need for retailers like Allbirds to maintain symbiotic relationships with both customers and landlords. “We do really ask something of landlords to commit [to] and share our vision,” said Zwillinger in the forum’s opening fireside chat, entitled, “How One of Today’s Most Innovative Brands Is Driving a Brick-andMortar Expansion.” The Bromley Company and Allbirds have established a shared vision. The landlord experimented with different building objectives, adjusting 120 Fifth Avenue’s efficiency upgrades to meet sustainability standards, Zwillinger said. This tenant-landlord alignment of values has created opportunities beyond shoe sales, as Allbirds ultimately aims to reach not just climate neutrality but also climate positivity. Such a goal requires readjusting all areas of retail — from physical building efficiency, yes, but also to the brand’s manufacturing, production and shipping techniques. As such, retail’s success isn’t necessarily dependent on the product for sale or even the leased space itself. Rather, retail’s output hinges on a brand’s ability to utilize its surroundings to express itself to customers. Allbirds deliberately chose its Flatiron District locale for the environment. The area speaks to the company’s pillars for sustainability and consumer connection. As a bonus, Microsoft also leases space in the building, which Haines anticipates will drive further traffic to Allbirds. Retail’s experiential opportunities cast a positive forecast for shuttered storefronts, especially those seen at malls across the country. In “The Retail Rundown: Luxury, MiddlePricing & Everything in Between,” Michael
88
| MAY 3, 2022 | COMMERCIAL OBSERVER
holistic experience there,” Weitz said. Realistically, customers won’t gravitate to malls for their directory of department stores or singular ticket items. Rather, they’ll visit shopping centers for a day out of the house. If malls can provide experiences that speak beyond apparel — perhaps addressing fitness or wellness offerings instead — malls can reinvent themselves to fulfill market needs. These potential opportunities reject previous predictions for retail, made both before and during the pandemic. Prior to COVID-19, the narrative of the retail apocalypse began to take shape, in which the rise of e-commerce was widely expected to overrule in-person retail altogether. Yet, as Chernofsky noted, what should have been the most significant challenge for brick and mortar — the pandemic — has opened up new avenues for growth. Not only can retail create experiences beyond shopping, but it can also contribute to communities at large. Experts in the next panel — “Refreshing Hospitality & Retail:
Generational Shifts, Location Strategies & an Incoming Urban Boom” — discussed the interplay between hyperlocalization and retail. Soozan Baxter, owner of Soozan Baxter Consulting, moderated the conversation with Jared Epstein, a principal at investment firm Aurora Capital Associates; Dennis Marnick, senior vice president of leasing at global retail developer Unibail-Rodamco-Westfield; Angela Pennyfeather, head of marketing at business improvement district Fifth Avenue Association; and Didier Souillat, CEO of dining experience Time Out Market. The panelists agreed that retail is subjective. It depends on each community and boils down to a simple question: “What does the customer want?” Marnick said. “That’s really what the basis of the story is.” Determining customers’ wants, however, is a delicate act. As communities grow and advance, national chains are more likely to take over neighborhoods, with the potential to change the original character. Epstein used the example of SoHo, an arts district once full of mom-and-pop shops. In recent years, the trendy neighborhood has strayed from its roots, replacing its unexpected and characteristic hidden gems with heavy-hitter retailers. The Meatpacking District is taking careful steps to avoid this same fate and ensure that its character remains intact. Social media has proven a helpful tool for sharing the spirit of the community, Epstein said, noting that Instagram has provided a means to keep in touch with potential visitors and share local stories indicative of the area’s heart. This digital component isn’t enough to sustain the neighborhood, however. Like retail at large, the physical must work in conjunction with online offerings. Simple changes to the streets, such as sprucing up cobblestones or increasing daytime security, can have largescale implications that draw in — and maintain — a satisfied community. Fifth Avenue has taken similar steps to attract visitors to its retail by creating a more desirable external environment. Last spring’s “Fifth Avenue Blooms” saw the installation of 7,000 flowers spread over the avenue. This effort enticed visitors to linger outside, Pennyfeather said, while also capitalizing on what the moment’s retail and its surroundings can create. “We really wanted people to have this journey on Fifth Avenue,” Pennyfeather added. People — potential customers — are at the core of these changes to retail, as well as shifts
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
THE CUSTOMER IS ALWAYS RIGHT: (clockwise from top left) Aurora’s Jared Epstein, Fifth Avenue Association’s Angela Pennyfeather, Sean Bruener of AvantStay and RXR’s Whitney Arcaro. Gerazounis, president and managing principal at engineering firm MG Engineering D.P.C., moderated a discussion with Whitney Arcaro, executive vice president and head of marketing and retail leasing at RXR; Mark D’eon, national vice president of retail leasing at Oxford Properties; Ethan Chernofsky, vice president of marketing at software analytics company Placer.ai; Jake Elghanayan, a principal at developer TF Cornerstone; and David Weitz, a managing partner at private equity and development company Carpe Real Estate Partners. The panelists spoke about the future of malls. While it’s widely acknowledged that the pandemic accelerated the demise of the American shopping mall, the growing desire for shopping experiences has opened the door for malls to make a comeback, albeit repurposed. “It’s really about creating an experience that’s long-lasting and creates a better opportunity for the consumer to really have a whole,
WORKING UNDER YOUR TERMS.
New York City is coming back to work. Whether you are returning to the office full-time or flextime, we have the perfect solution for you.
High-end furnished pre-built suites available for immediate occupancy. Tower suites available ranging from 3,700RSF – 6,475RSF. New safety measures in place based on industry best practices.
100% commission paid on signing.
Barry Zeller
Jonathan Fales
212.841.5913
212.841.5989
Michael Tranfalia 212.841.5981
650Fifth.com
Morgan Feldman 212.589.5144
EVENT
‘What does the customer want? That’s really what the basis of the story is.’ throughout the still-recovering tourism and hospitality industries. Jack Pulvirenti, an audit partner at accounting, tax and consulting firm Berdon, moderated the panel, “Hungry for Hospitality: A Deep Dive Into the Return of Travel & Tourism.” He spoke with Sean Breuner, CEO and founder of hospitality platform AvantStay; Francois-Olivier Luiggi, general manager at The Pierre; and Laura Rapaport, founder and CEO of real estate solutions company North Bridge. Like retail, hospitality has adapted to COVID-induced changes. When the pandemic hit in March 2020, The Pierre closed for six months. Upon reopening, the hotel had to adapt — quickly — and with a focus on domestic travelers looking for more long-term accommodations. The hotel business model evaporated with the pandemic, Luiggi said. Perhaps the most notable change manifested in the duration of customer stays. Rather than book two-night getaways, guests at The Pierre booked an average of seven nights. Such changes presented a unique challenge. Hotel rooms come with a given square footage, consisting of stagnant walls and set amenities: standard furniture, an unchangeable location, an already built layout, etc. Hotels therefore couldn’t change physically and instead had to readjust how they presented themselves to visitors. Short-term rental platforms such as AvantStay were primed for this upheaval. AvantStay accommodates big groups for vacations, offering luxury sites that might otherwise be unaffordable. Rather than pay what might be exorbitant sums per night, groups can instead split the cost among themselves. Widening the opportunity to experience luxury housing has raised the bar for hospitality, allowing groups to come together safely, spatially and seamlessly. “People want to be with people they like,” Luiggi said, noting that guests during the pandemic tended to travel in bubbles. Visitors have opted to stay within their family groups rather than turning to external forms of socialization. Private social clubs have also accounted for these limited social bubbles. In the forum’s closing keynote, Chava Gourarie, associate editor at CO, spoke with Scott Sartiano, founder of Bond Hospitality, about Zero Bond, a members-only club in NoHo. Prior to the pandemic, Sartiano set out to create a space that would literally give its members space; he wanted to offer an environment where people could spread out. “One of the promises I made people was that it would never get overcrowded,” Sartiano said. His promise just so happened to align with consumers’ post-COVID wish lists.
90
| MAY 3, 2022 | COMMERCIAL OBSERVER
RETAIL OF THE TAPE: (clockwise from top left) Nicholas Haines of the Bromley Companies, Jake Elghanayan of TF Cornerstone, Ethan Chernofsky of Placer.ai, Dennis Marnick of Unibail-Rodamco-Westfield, Francois-Oliver Luiggi, the general manager of The Pierre, Joey Zwillinger of Allbirds, Mark D’eon of Oxford Properties and Laura Rappaport, the founder and CEO of North Bridge.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
PARTNER SPONSORED CONTENT Presented by
RETAIL
TWO YEARS LATER
ANALYZING THE LONG-TERM IMPACTS OF COVID ON RETAIL REAL ESTATE
WEDNESDAY MAY 11, 2022
ETHAN CHERNOFSKY
ASHLEY ROBINSON
BRET SWANGO
VP Marketing Placer.ai
Chief Strategic Advisor Seaker Group
VP, Head of Workforce Analytics, Americas Colliers International
REGISTER HERE
FEATURE
A recent survey of workers’ attitudes toward face time and flex offers sobering results for employers and office owners — but what if the labor market shifts? By Rebecca Baird-Remba | Illustration by David Wink here are more white-collar workers back in the office now than at any time since March 2020, and they’re more unhappy than ever. More than a third of workers across multiple countries reported being back in the office five days a week, and they were twice as unhappy as their remotework colleagues, a survey out last week from Future Forum found.
92
| MAY 3, 2022 | COMMERCIAL OBSERVER
Messaging app Slack founded Future Forum, a work culture-focused organization that includes a consortium of furniture company MillerKnoll, nonprofit Management for Tomorrow and Boston Consulting. Future Forum surveys 10,818 knowledge workers each quarter across the U.S., Australia, France, Germany, Japan and the U.K. Employees who are back in the office full time reported higher levels
of anxiety, stress and professional dissatisfaction, with workers who spend five days a week in the office 2.6 times as likely as their colleagues with flexible schedules to look for a new job in the coming year. Full-time office employees also said they were 1.6 times less satisfied at work and had 1.5 times more work-related stress and anxiety than those doing hybrid and remote jobs. And work-life balance scores for
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
WITH GRATITUDE
Thank you to our event speakers and partners for making this informative and interactive event possible. KEYNOTE SPEAKERS
TIM JOHNSON
JONATHAN POLLACK
ELIZABETH DAHILL
MARK EDELSTEIN
Global Head of Blackstone Real Estate Debt Strategies Blackstone
Global Head of Blackstone’s Structured Finance Group Blackstone
Partner Seyfarth Shaw
Partner, Chair Global Real Estate Group Morrison & Foerster LLP
DREW FUNG
JO HASTINGS
Managing Director Clarion Partners
THOMAS LASALVIA Senior Economist Moodys Analytics CRE
ADAM SCHWARTZ
Senior Managing Director & Co-Head, Capital Markets Walker & Dunlop
Presenting Sponsor
MD, Deputy Head, Real Estate Structured Finance Societe Generale
CHRIS NIEDERPRUEM
Group Head, Real Estate Finance CIT
DUSTIN STOLLY
Vice Chairman & Co-Head, Capital Markets Debt & Structured Finance Newmark
Program Sponsors
JESSICA BAILEY
President & CEO Nuveen Green Capital
JEFF ERXLEBEN
President, Debt & Equity Northmarq
MICHELLE HERRICK
Head of Real Estate Banking JPMorgan Chase
CHARLIE ROSE
GERI BORGER URGO
Co-Deputy Editor & Finance Editor Commercial Observer
TONY FINEMAN
NAILAH FLAKE-BROWN
RALPH HERZKA
URI ITKIN
Senior Managing Director Co-Head of Originations ACORE Capital
Chairman & CEO Meridian Capital Group
BRAD ROSS
Managing Director Portfolio Manager Invesco Real Estate
Managing Director & Head of Originations Parkview Financial
JOEL TRAUT
JOSH S. WINEFSKY
Head of Originations KKR Real Estate Credit
CATHY CUNNINGHAM
Head of Production NewPoint Real Estate Captial
Partner Kramer Levin
Managing Director Brookfield Asset Management
Partner Kasowitz Benson Torres LLP
DENNIS SCHUH
Chief Originations Officer Starwood Property Trust
JOSH ZEGEN
Managing Principal, Co-Founder Madison Realty Capital
FEATURE
five-day-a-week office workers in the first quarter declined twice as much as those for people with flexible arrangements. “In the U.S., what we’re seeing is that close to 95 percent of people want flexibility in when they work,” said Sheela Subramanian, a vice president at Slack and co-founder of Future Forum. “They want to be able to not just choose the hours every single day but have flexibility in a framework.” There’s another wrinkle adding to the general angst, per the survey. The C-suite is not spending as much time in the office as the rank and file. Nonexecutive employees are twice as likely to be working from the office full time, and they scored their work-life balance 40 percent lower than their bosses. Thirty-five percent of rank-and-file workers said they were back in the office full time, while only 19 percent of executives were. Regular employees also reported twice as much work-related anxiety and stress as executives. “It’s very much a do-as-I-say-not-as-I-do mentality, where executives are saying that people need to be back in the office but not going back in themselves,” Subramanian said. She noted that execs planning return-towork initiatives should not assume that their employees’ lives resemble their own. After all, how many CEOs and CFOs take public transit or share an open office? “If you’re a leader planning your employees’ return to office based on your own experience, it’s not going to look like yours,” she explained. “The reason for this disconnect is confirmation bias. Two-thirds of leaders are not including their broader organizations as they’re planning what’s next about return to office. Executives have higher flexibility scores, stronger networks and more autonomy.” Subramanian pointed out that employees of color were more likely than their white counterparts to express a preference for flexible and hybrid work. “Overall it enables people to have a higher sense of belonging,” the Slack exec said. “One potential reason is not having to code-switch every day to fit into office norms. Being able to work flexibly allows people to bring more of their whole selves to work, improving relationships with co-workers and managers. You’re able to focus more on the outcomes around work — what are the results that people are driving, rather than does this person play a good round of golf?” In addition, women prefer hybrid work and flexible schedules more than men. Fifty-eight percent of women surveyed wanted a flex arrangement at least three days a week, compared to 48 percent of men. The number of working mothers who said they needed location flexibility also hit an all-time high this quarter, at 82 percent. Across the board, parents want scheduling flexibility and the ability to work remotely three to five days a week — 57 percent of working moms and 48 percent of working dads. Parents are also much more likely than non-parents to worry that remote work is negatively impacting their careers — 46 percent vs. 34 percent — and to report that they have
94
| MAY 3, 2022 | COMMERCIAL OBSERVER
OFFICE SPACE: Workers who are back in the office five days a week report being significantly more dissatisfied and more likely to search for a new job than their remote work colleagues, according to a recent survey by Future Forum. been negatively impacted by bias in the workplace over the past year. For parents, “flexibility in the work hours is as important as flexibility in the location,” said Tim Rowley, COO of digital staffing agency PeopleCaddie. “We recently hired a working mom who left her former employer because she had to be there on-site. She wanted a remote opportunity, and she wanted the flexibility to start work at 6 a.m. and work till 3 in the afternoon and then pick her kids up at daycare. In order to get working moms to rejoin the workforce, they need the flexibility, otherwise they’ll continue to sit on the sidelines.” Some major employers are starting to feel
the pressure. Even JPMorgan Chase, which faced criticism for forcing traders back into the office at the height of the pandemic, is reportedly allowing some employees to work in the office just two days a week. Office owners, meanwhile, are betting employees will have less bargaining power when the job market and the economy weaken. The U.S. unemployment rate remains well under 4 percent, and roughly 1 in 5 adults switched jobs last year, according to a Pew Center analysis. Should that change, attitudes toward the office could become moot. “We have found business leaders all acknowledge that productivity is better with
in-person presence, but the employees have more of the bargaining power with the great resignation,” said Christina Chiu, the chief financial officer at Empire State Realty Trust. “We see in the form of leasing activity and momentum and inquiries that companies are planning ahead of that. That’s accentuated by the current activity we see in the marketplace today. As the market becomes more competitive, there should be a movement back. “It doesn’t mean people are chained to their desks five days a week,” Chiu added. “But if people don’t have a place to go to collaborate, it gets harder to build a relationship among colleagues, and build a book of business.”
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
RETAIL & HOSPITALITY FORUM The New & Now Trends Driving the Retail Resurgence
WITH GRATITUDE
Thank you to our event speakers and partners for making this informative and interactive event possible.
WHITNEY ARCARO
SOOZAN BAXTER Owner Soozan Baxter Consulting
Chief Executive Officer & Founder AvantStay
SEAN BREUNER
ETHAN CHERNOFSKY
JAKE ELGHANAYAN
JARED EPSTEIN
MICHAEL GERAZOUNIS, P.E., LEED AP
MAX GROSS
NICHOLAS HAINES
BRADLEY JONES
EVP, Head of Marketing & Retail Leasing RXR Realty
Principal Aurora Capital Associates
FRANCOIS LUIGGI
General Manager The Pierre, a Taj Hotel, New York
President/Managing Principal MG Engineering D.P.C.
ANGELA PENNYFEATHER Head of Marketing Fifth Avenue Association
DIDIER SOUILLAT
CEO, Time Out Market Time Out Market
SPONSORS
Editor in Chief Commercial Observer
JACK R. PULVIRENTI Audit Partner Berdon LLP
DAVID WEITZ
Managing Partner Carpe Real Estate Partners
VP Marketing Placer.ai
CEO The Bromley Companies
LAURA RAPAPORT Founder + CEO North Bridge
JOEY ZWILLINGER Co-CEO Allbirds, Inc.
Principal TF Cornerstone
Head of Retail Oxford Properties
SCOTT SARTIANO Founder Bond Hospitality
COLUMNS
HOME RUN
Tug of War Within the Housing Market Could Turn Out to Be a Good Thing loans are at their highest in 11 years. While The explosion of single-family housing the march upward to 3 percent Treasuries demand over the last year, particularly in the reversed slightly in late April to fall just short, Southeast, is well documented. But we are at a much of this was likely a flight crossroads. With rising interest rates, from the ailing equities market. will single-family demand persist? With Federal Reserve Chairman One market indicator, the CaseJerome Powell telling Congress that Schiller index, continues to rise. it is time to retire the word “tranHome prices increased 19.8 percent sitory” with respect to inflation, in February year over year with the interest rates are likely to resume largest gains coming in Phoenix, their upward bias into the summer. Tampa and Miami. Housing bears Rising interest rates will have will point out that the recent spike the largest demand effects on in supply will more than meet curDan Gorczycki. lower- and middle-income buyrent demand. However, the populaers. According to bankrate.com, tion growth in certain markets in only 54.2 percent of families earning a typiSoutheast and Sun Belt states has far outpaced cal income could afford to purchase a house the housing supply and is evidenced by conin the fourth quarter of 2021. That number is tinued record housing prices. likely below 50 percent now. As for interest rates, yes, 30-year fixed-rate
Larger rental housing communities and multifamily developments are set to capture this cohort of homebuyers for whom the prospect is no longer affordable. Just last week, TrueRate financed an $87.7 million loan (that amount includes phasing) for a build-for-rent housing complex on a 500-acre parcel 40 miles outside Atlanta. A recent market study on the development proved to the construction lender that pent-up demand is strong enough to absorb any rental increases, since the alternative for prospective renters is increased borrowing costs if they became homeowners instead. Fast forward to May 2022. Are there any new warning signs beyond the statistics? Well, while the Southeast remains heated, other areas such as Peoria, Ill., and Norfolk, Va., have seen recent price declines and
underwater mortgages. With single-family prices declining in some markets and developers rushing to the build-to-rent space, it feels like a real-time adjustment in the single-family housing space is underway. Cap rates usually lag interest rates by roughly six months, so there is certainly at least a mild correction coming that could reach further than a couple of select markets. The housing boom may cool off, but it was overheating. With a viable alternative in buildfor-rent space, this slowdown might turn out to be a welcome respite, and, dare I say, a blessing in disguise for the housing market. Dan Gorczycki is managing director of TrueRate Services, which works to streamline transaction complexity in the commercial real estate capital markets.
CONCRETE THOUGHTS
Investment Sales in New York City Seem Poised for a Big Year After a robust fourth quarter of investment sales in Manhattan last year, we were curious to see what was going to happen in the first quarter of 2022. First-quarter numbers tend to be somewhat muted so a disappointing result in the first quarter this year would not have been surprising. However, the activity that we saw in fourth-quarter 2021 continued in first-quarter 2022 and has us feeling very optimistic about where the market is headed moving forward. In Q1 2022, the dollar volume of investment sales in Manhattan (south of 96th Street on the East Side and south of 110th Street on the West Side), for transactions over $10 million was $8.6 billion. This result was fantastic relative to what we have seen in past first quarters. It also comes on the heels of an $8.56 billion Q4 2021, which saved last year from being horrendous. If we did not have the robust Q4, last year would have finished below the anemic $11.1 billion of sales volume that we had in 2020. The pandemic was a logical excuse for 2020 performance, but to have 2021 produce results below 2020 would have been
a better metric to look at for real market catastrophic. activity versus dollar volume. The $8.6 billion Q1 2022 total, if annualWith regard to the number of properties ized, would lead to about $34.4 billion for the sold, which is always a better indication of year. This pace is 118 percent above the $15.75 market activity than the dollar volume, there billion total in 2021 and 208 percent above were 55 sales closed in Manhattan 2020’s $11.1 billion. The first-quarin Q1 2022. This puts the market ter total of $8.6 billion is the highon pace for 220 for the year which est quarterly total of sales we have would be 15 percent higher than the seen going back to Q4 2019, when 191 sales that occurred last year. The there was $9.5 billion in sales vol220 sales pace is identical to what ume. If this pace can continue, we had in 2019 pre-pandemic. It and the market achieves $34.4 bilwould also be about 55 percent lion for the year, this will be the below the 484 sales that occurred highest yearly total going back to at the peak of the market in 2015. the $39.5 billion we had in 2016. Robert Knakal. Within the outer boroughs, the For reference, the highest annual numbers would also lead to an optitotal we have had was $57.5 billion mistic outlook for 2022. The dollar volume of in 2015. sales was $1.7 billion, putting the market on It should be noted that a major reason pace for $6.8 billion for the year. This pace why the dollar volume was so high was would be 30 percent below the $9.8 billion in because of the pickup in office building sales last year but 31 percent ahead of the $5.2 sales, which accounted for 67 percent of the billion total achieved in 2020. It is important total. The disproportionate impact office to note that in the outer boroughs the analysis sales typically have on dollar volume is of sales over $10 million can greatly skew the why the number of properties sold is often
2022 EVENTS 96
| MAY 3, 2022 | COMMERCIAL OBSERVER
perception of the market as the overwhelming majority of sales in the outer boroughs are below $10 million. In my next column we will look at sales citywide above $500,000 as opposed to above $10 million. It will be interesting to see what conclusions can be drawn from that data versus this approach. Regarding the number of properties sold, there were 54 sales above $10 million in the outer boroughs in Q1 2022. This puts the market on pace for a 216 for the year, which would be 29 percent above the 168 sales that occurred last year. It would also be 38 percent above the 157 sales that occurred in 2020. For perspective, the 216 sales pace would be 44 percent below the cyclical peak in 2015 when 383 properties traded hands in the outer boroughs. All of this activity is just what we needed after the pandemic wreaked havoc on our market. As things return to whatever our new normal will be, it is great to see sales volume picking up. Here’s to a great rest of 2022. Robert Knakal is chairman of New York investment sales at JLL.
VISIT COMMERCIALOBSERVER.COM/EVENTS TO VIEW THE FULL EVENT CALENDAR
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
A MU LT I - C I T Y EVENT
FUTURE FORWARD
WASHINGTON, D.C. T h e R i t z - C a r l to n G e o rg e tow n Tu e s d ay, M ay 1 0
AN INVITATION ONLY FORUM FOR C-SUITE LEADERS IN CRE, PE AND FAMILY OFFICES
DAVID ARENA
KO BARRETT
Head of Global Real Estate, Managing Director JPMorgan Chase & Co.
NOAA Senior Advisor for Climate & Vice-Chair of the IPCC NOAA/IPCC
CRYSTAL BERGEMANN
CEDRIC BOBO
MARK EIN
CEO, Co-Founder Project Destined
Chairman Kastle Systems
ANDREW LOSCHMANN
Senior Advisor for Climate US Department of Housing and Urban Development
JOHN FALCICCHIO
TONY FINEMAN
BRAD GREIWE
ALLISON LLOYDS
Deputy Mayor Office of the Deputy Mayor for Planning and Economic Development
Senior Managing Director, Co-Head of Originations ACORE Capital
Co-Founder and Managing Partner Fifth Wall
Global Head of Investor Relations and Capital Development Willow
RICHARD MACK
BRYAN MCDONNELL
SONU PANDA
DON PEEBLES
CEO, Co-Founder Mack Real Estate Group
Head of U.S. Debt and Chair of Global Debt PGIM Real Estate
CEO Prescriptive Data
Chairman & CEO The Peebles Corporation
Co-Founder and Chief Operating Officer Field Effect
MATTHEW A. PESTRONK President Post Brothers
MICHAEL PHILLIPS
ANDY SHALLAL
JESSE STEIN
SIMON ZIFF
Principal and President Jamestown
Founder and CEO Busboys & Poets
Global Head of Real Estate Airbnb
President Ackman-Ziff
REGISTER NOW
SPONSORS
1212 AVENUE OF THE AMERICAS
The Plan WHO’S WHO FOR 1212 AVENUE OF THE AMERICAS
COURTESY OF CUSHMAN & WAKEFIELD
LANDLORD: STAWSKI PARTNERS ARCHITECTS: LTL ARCHITECTS, SPECTORGROUP MEP ENGINEERS: JB&B
MIDTOWN REDUX: An early 1960s Emery Roth & Sons-designed office building at 1212 Avenue of the Americas is getting a new entrance with a gold marquee and a fresh lobby with bronze accents, stone-fluted walls and matching stone floors and reception desk. A new prebuilt space on the 12th floor will have wooden accent paneling on the ceiling and an open seating area.
By Rebecca Baird-Remba Another day, another 1960s Midtown office tower getting renovated to keep up with its newer contemporaries. This week’s entry is 1212 Avenue of the Americas, a 24-story Emery Roth & Sonsdesigned property from 1963. Landlord Stawski Partners is revamping the first floor, entry and mechanicals of the 270,000-square-foot building between West 47th and West 48th streets, near Rockefeller Center. While the building’s dark glass facade
98
| MAY 3, 2022 | COMMERCIAL OBSERVER
will stay, its drab ground floor is being refreshed. The property is getting a bronze marquee, a new lobby with fluted gray stone walls and matching stone floor, updated elevator cabs and a full-floor prebuilt office suite designed by Spector Group. LTL Architects oversaw the first-floor renovations and the mechanical upgrades. The lobby renovations include a new back wall clad in warm wood, a new gray stone reception desk and thin strips of bronze that run continuously across the ceiling, walls and floor, connected to vertical wooden LED light fixtures. The thin bronze strips also run vertically up the base of the back wall, and there
is a bronze panel on the front of the new check-in desk. “The last time we renovated the lobby was in the 1990s,” said Faith Ryan, CEO of Stawski Partners. “We took the time to update the look and use richer materials than what was there before.” The mechanical systems also got a soupto-nuts upgrade. “The engineers at JB&B wanted to decrease our carbon footprint and increase energy savings, so they demolished the entire HVAC system of the building and replaced it with new boilers and chillers, new cooling towers and a building-management system so
everything runs efficiently,” Ryan explained. Other improvements include touchless restroom access, a new emergency generator, a bike room and three new landscaped terraces for tenants. The new 14,600-square-foot prebuilt on the 12th floor will have wooden accent paneling on the ceiling, blond wood midcentury modern-inspired furniture, and an open seating area with leather couches and armchairs with plants overhead, hanging from a long, horizontal light fixture. Construction began in 2019 but was paused for much of 2020. Work is expected to wrap this summer.
BECOME A COMMERCIAL OBSERVER MEMBER
| JOIN AT COMMERCIALOBSERVER.COM/MEMBERSHIP
FOLLOW US ON
@Commercial Observer
Check out our other social channels
PRODUCED BY COMMERCIAL OBSERVER’S CONTENT STUDIO
AFFORDABLE HOUSING With an already challenging housing market in flux due to skyrocketing housing costs, it’s essential for business and government to work together to create reasonably-priced housing. The Future Of Affordable Housing program will discuss current and future initiatives for setting the nation’s housing situation on the right path.
BROUGHT TO YOU BY
VIEW JPMORGAN CHASE’S FUTURE OF AFFORDABLE HOUSING PROGRAM: