MARKET DATA
OFFICE MARKET SNAPSHOT Q3 2026 Stock
4,503k sqm +1.7% yoy
Avg. Rent
Avg. Vacancy
13.1%
-0.4 pps. yoy
Spec. Vacancy
Completion
16.8%
47,298 sqm
36,000 sqm
-0.1 pps. yoy
YTD: 104,942 sqm
YTD: 78,810 sqm
Prime
New Build
EUR/sqm/mth
EUR/sqm/mth
25.5
Net Take-up
19-23
DISTRIBUTION OF TRANSACTIONS (Q1-Q3 2025, Q1-Q3 2026) 2,8% 13,9%
Q1-Q3 2026 (307,423 sqm)
7,3%
Cat. A
25,0%
7,0%
17.3
EUR/sqm/mth 41,4%
MACRO
Pre-lease New
Q1-Q3 2025 (314,891 sqm) 38,4%
Expansion Renewal
6,4%
Following GDP growth of 1.8% in H1 2026, Hungary’s economy is projected to expand by approximately 1.8–1.9% for the full year. Inflation edged up to 1.6% in September, its highest level since June. The EUR/HUF exchange rate hovered around 363 in mid-October amid international tensions but supported by the relatively high domestic interest rate environment. Meanwhile, the unemployment rate edged up to 4.7% in August 2026, indicating a slight upward trend.
OO
5,8%
51,9% Source: Colliers, BRF
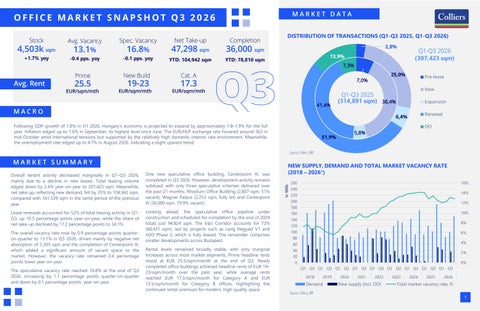
Overall tenant activity decreased marginally in Q1–Q3 2026, mainly due to a decline in new leases. Total leasing volume edged down by 2.4% year-on-year to 307,423 sqm. Meanwhile, net take-up, reflecting new demand, fell by 35% to 104,942 sqm, compared with 161,539 sqm in the same period of the previous year.
One new speculative office building, Centerpoint III, was completed in Q3 2026. However, development activity remains subdued, with only three speculative schemes delivered over the past 21 months: Rhodium Office Building (2,807 sqm, 51% vacant), Wagner Palace (2,253 sqm, fully let) and Centerpoint III (36,000 sqm, 79.9% vacant).
Lease renewals accounted for 52% of total leasing activity in Q1Q3, up 10.5 percentage points year-on-year, while the share of net take-up declined by 17.2 percentage points to 34.1%.
Looking ahead, the speculative office pipeline under construction and scheduled for completion by the end of 2029 totals just 94,824 sqm. The Váci Corridor accounts for 72% (68,431 sqm), led by projects such as Lang Negyed V1 and H2O Phase 2, which is fully leased. The remainder comprises smaller developments across Budapest.
The overall vacancy rate rose by 0.9 percentage points quarteron-quarter to 13.1% in Q3 2026, driven mainly by negative net absorption of 5,303 sqm and the completion of Centerpoint III, which added a significant amount of vacant space to the market. However, the vacancy rate remained 0.4 percentage points lower year-on-year. The speculative vacancy rate reached 16.8% at the end of Q3 2026, increasing by 1.1 percentage points quarter-on-quarter and down by 0.1 percentage points year-on-year.
Rental levels remained broadly stable, with only marginal increases across most market segments. Prime headline rents stood at EUR 25.5/sqm/month at the end of Q3. Newly completed office buildings achieved headline rents of EUR 19– 23/sqm/month over the past year, while average rents reached EUR 17.3/sqm/month for Category A and EUR 13.5/sqm/month for Category B offices, highlighting the continued rental premium for modern, high-quality space.
NEW SUPPLY, DEMAND AND TOTAL MARKET VACANCY RATE (2018 – 2026*) In 1000s
MARKET SUMMARY
260
16%
240
14%
220 200
12%
180
10%
160 140
8%
120 100
6%
80
4%
60 40
2%
20
0
0% Q1 Q3 Q1 Q3 Q1 Q3 Q1 Q3 Q1 Q3 Q1 Q3 Q1 Q3 Q1 Q3 Q1 Q3
2018
2019
Demand Source: Colliers, BRF
2020
2021
2022
New supply (incl. OO)
2023
2024
2025
2026
Total market vacancy rate, % 1
OFFICE MARKET SNAPSHOT Q3 2026
Developers are expected to remain cautious, with new office deliveries largely limited to pre-let or owner-occupied projects. This is likely to constrain new supply and support prime rent of EUR 25.5/sqm/month. Demand will continue to favour modern, energy-efficient and ESGcompliant offices, supported by international market entrants and the BSC sector’s shift towards higher value-added R&D, technology and knowledgeintensive activities.
VÁCI CORRIDOR
NORTH BUDA STOCK (sqm)
342,431
STOCK (sqm)
1,175,874
VACANCY (%)
9.2%
VACANCY (%)
13.3%
NET-TAKE-UP (sqm)
1,290
NET-TAKE-UP (sqm)
19,289
COMPLETION (sqm)
0
COMPLETION (sqm)
36,000
NET-ABSORPTION (sqm)
-1,030
NET-ABSORPTION (sqm)
2,943
AVERAGE RENT (EUR/sqm)
13.2
AVERAGE RENT (EUR/sqm)
15.9
SPECULATIVE PIPELINE (sqm)
68,431
SPECULATIVE PIPELINE (sqm)
OUTLOOK
0
CENTRAL BUDA
CBD
Meanwhile, older buildings increasingly require refurbishment to meet occupier and sustainability requirements, while obsolete assets may be converted to alternative uses. Looking ahead, the office market is expected to remain in an adjustment phase, with the balance between new demand, limited development and the release of existing space shaping performance. The limited development pipeline is reducing the number of options available to large occupiers seeking to relocate to newly built office buildings. Tenants with substantial space requirements are advised to enter the market early and consider preleasing or build-to-suit (BTS) solutions to secure suitable premises.
NON-CENTRAL PEST
STOCK (sqm)
454,837
STOCK (sqm)
346,867
STOCK (sqm)
632,614
VACANCY (%)
7.8%
VACANCY (%)
10.0%
VACANCY (%)
16.8%
NET-TAKE-UP (sqm)
1,486
NET-TAKE-UP (sqm)
4,983
NET-TAKE-UP (sqm)
9,172
COMPLETION (sqm)
0
COMPLETION (sqm)
0
COMPLETION (sqm)
0
NET-ABSORPTION (sqm)
-3,836
NET-ABSORPTION (sqm)
3,825
NET-ABSORPTION (sqm)
-7,335
AVERAGE RENT (EUR/sqm)
16.9
AVERAGE RENT (EUR/sqm)
20.0
AVERAGE RENT (EUR/sqm)
12.2
SPECULATIVE PIPELINE (sqm)
1,300
SPECULATIVE PIPELINE (sqm)
3,000
SPECULATIVE PIPELINE (sqm)
13,020
SOUTH BUDA
CENTRAL PEST
PERIPHERY
STOCK (sqm)
709,376
STOCK (sqm)
729,976
STOCK (sqm)
111,062
VACANCY (%)
10.5%
VACANCY (%)
17.4%
VACANCY (%)
20.4%
NET-TAKE-UP (sqm)
6,690
NET-TAKE-UP (sqm)
4,310
NET-TAKE-UP (sqm)
79
COMPLETION (sqm)
0
COMPLETION (sqm)
0
COMPLETION (sqm)
0
NET-ABSORPTION (sqm)
1,068
NET-ABSORPTION (sqm)
-661
NET-ABSORPTION (sqm)
-276
AVERAGE RENT (EUR/sqm)
14.4
AVERAGE RENT (EUR/sqm)
15.9
AVERAGE RENT (EUR/sqm)
10.3
SPECULATIVE PIPELINE (sqm)
9,073
SPECULATIVE PIPELINE (sqm)
SPECULATIVE PIPELINE (sqm)
0
Contact us Kristóf Tóth Associate Director, Head of Research, Hungary Kristof.Toth@colliers.com
Miklós Ecsődi
Partner, Head of Occupier Services, Hungary Miklos.Ecsodi@colliers.com
Kata Mazsaroff
Managing Partner, Hungary Kata.Mazsaroff@colliers.com This document has been prepared by Colliers for advertising and general information only. Colliers makes no guarantees, representations or warranties of any kind, expressed or implied, regarding the informa- tion including, but not limited to, warranties of content, accuracy and reliability. Any interested party should undertake their own inquiries as to the accuracy of the information. Colliers excludes unequivo- cally all inferred or implied terms, conditions and warranties arising out of this document and excludes all liability for loss and damages arising there from. This publication is the copyrighted property of Colliers and/or its licensor(s). ©2026 All rights reserved. Colliers International Group Inc.
0
2