INVESTMENT MARKET SNAPSHOT Q3 2026
Total Investment Volume-Q1-Q3:
659 mEUR | yoy: -15.2% Office share/ prime yield:
36.1% | yield: 6.5% Industrial share/ prime yield:
14.8% | yield: 6.75% Retail share/ prime yield:
30.5% | yield (SC): 7% Hotel share/ prime yield:
0% | yield: 7%
Supported by a strong pipeline of ongoing negotiations, full-year investment activity could exceed EUR 1.0 billion.
MACRO
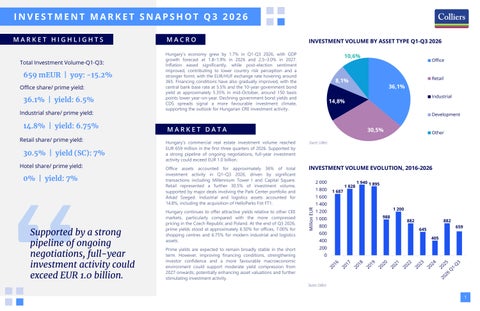
INVESTMENT VOLUME BY ASSET TYPE Q1-Q3 2026
Hungary’s economy grew by 1.7% in Q1-Q3 2026, with GDP growth forecast at 1.8–1.9% in 2026 and 2.5–3.0% in 2027. Inflation eased significantly, while post-election sentiment improved, contributing to lower country risk perception and a stronger forint, with the EUR/HUF exchange rate hovering around 365. Financing conditions have also gradually improved, with the central bank base rate at 5.5% and the 10-year government bond yield at approximately 5.35% in mid-October, around 150 basis points lower year-on-year. Declining government bond yields and CDS spreads signal a more favourable investment climate, supporting the outlook for Hungarian CRE investment activity.
10,6%
Office
Retail
8,1%
36,1% Industrial
14,8%
Development
MARKET DATA
30,5%
Other
Hungary’s commercial real estate investment volume reached EUR 659 million in the first three quarters of 2026. Supported by a strong pipeline of ongoing negotiations, full-year investment activity could exceed EUR 1.0 billion.
Source: Colliers
Office assets accounted for approximately 36% of total investment activity in Q1–Q3 2026, driven by significant transactions including Millennium Tower I and Capital Square. Retail represented a further 30.5% of investment volume, supported by major deals involving the Park Center portfolio and Árkád Szeged. Industrial and logistics assets accounted for 14.8%, including the acquisition of HelloParks Fót FT1.
INVESTMENT VOLUME EVOLUTION, 2016-2026
Hungary continues to offer attractive yields relative to other CEE markets, particularly compared with the more compressed pricing in the Czech Republic and Poland. At the end of Q3 2026, prime yields stood at approximately 6.50% for offices, 7.00% for shopping centres and 6.75% for modern industrial and logistics assets.
Million EUR
MARKET HIGHLIGHTS
Prime yields are expected to remain broadly stable in the short term. However, improving financing conditions, strengthening investor confidence and a more favourable macroeconomic environment could support moderate yield compression from 2027 onwards, potentially enhancing asset valuations and further stimulating investment activity.
2 000 1 800 1 600
1 687
1 828
1 940 1 895
1 400 1 200 1 000 800 600 400
1 200 988
882
882
659
645 405
200 0
Source: Colliers
1
INVESTMENT MARKET SNAPSHOT Q3 2026
OUTLOOK
PRIME GROSS INITIAL YIELDS
Improving market sentiment is expected to encourage domestic investors to return to Hungary after several years of focusing on opportunities abroad. CEE investors, particularly Czech buyers with established local experience, are also likely to remain active, alongside growing interest from the Baltics and the Balkans.
9,5% 8,5% 7%
7,5%
6,75%
6,5%
A more favourable environment should also bring additional assets to market. Many owners postponed disposals over the past two years due to the gap between buyer and seller price expectations. Improving financing conditions and greater pricing certainty could help bridge this gap, supporting higher transaction volumes.
6,50%
5,5% 4,5% 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 Q3 2026 Office
Industrial
Retail (Shopping Center)
From 2027, a broader range of international institutional capital, including German, other Western European and North American investors, could reenter the market as pricing stabilises and investment conditions improve.
Source: Colliers
MAIN TRANSACTIONS Q1-Q3 2026
Renewed inflationary pressures could keep ECB and other major central bank policy rates higher for longer, limiting yield compression and slowing the recovery. In Hungary, however, this should be partly offset by the country's declining risk premium, meaning higher ECB policy rates would not necessarily translate into a comparable rise in euro-denominated financing costs.
Name of property
Asset type
Purchaser
Vendor
Size (sqm/rooms)
Óbuda Gate
Office
Gránit RE Fund
Equilor
13,900
Árkád Szeged
Retail
HOME Ingatlanfejlesztő Alap (BONITAS)
ECE
58,575
Millennium Tower I
Office
Wizz Air
CA IMMO
18,073
Head of Research, Hungary Kristof.Toth@colliers.com
Park Center Portfolio
Retail
Gránit RE Fund
Revetas Capital
46,400
Balázs Zelles-Görgey
Korzó Shopping Center
Retail
TriGranit/DRFG Investment
confidential
18,760
Capital Square
Office
WING
CA IMMO
31,795
HelloParks Fót Ft1
Industrial
Confidential
Futureal/HelloParks
46,000
Herceghalom (former Tesco)
Industrial
Confidential
W. P. Carey
47,000
Corner6 Business Center
Office
Forestay
CBRE IM
6,981
Olympia project
Mixed-use
WING
Atenor
74,000 Source: Colliers
Contact us Kristóf Tóth
Head of Capital Markets, Hungary Balazs.Zellesgorgey@colliers.com
Kata Mazsaroff
Managing Partner, Hungary Kata.Mazsaroff@colliers.com This document has been prepared by Colliers for advertising and general information only. Colliers makes no guarantees, representations or warranties of any kind, expressed or implied, regarding the information including, but not limited to, warranties of content, accuracy and reliability. Any interested party should undertake their own inquiries as to the accuracy of the information. Colliers excludes unequivocally all inferred or implied terms, conditions and warranties arising out of this document and excludes all liability for loss and damages arising there from. This publication is the copyrighted property of Colliers and/or its licensor(s). ©2026 All rights reserved. Colliers International Group Inc.
2