ILEP Symposium Recap: The PSLRA at 30 — Lessons, Impact, and the Road Ahead
This past March, the Institute for Law and Economic Policy, together with the Business Law Journal, hosted its annual symposium.
PAGE 2
Court Allows Investor Fraud Claims Over Trade Desk’s Kokai Platform to Proceed
PAGE 10
Pump-and-Dump Schemes Are on the Rise
PAGE 6
Antitrust Settlement Ends Wage-Fixing Suit That Recovered Nearly $400 Million for Low-Wage Poultry Workers
PAGE 13
Fiduciary Focus: That ‘70s Show
PAGE 16
Team Profile –Cristine Turner
PAGE 20
ILEP Symposium Recap: The
PSLRA at 30
— Lessons, Impact, and the Road Ahead
This past March, the Institute for Law and Economic Policy (ILEP), together with the Business Law Journal, hosted its annual symposium. Marking a significant milestone, this year’s convening focused on The 30th Anniversary of the Private Securities Litigation Reform Act (PSLRA).
Over two days, the Symposium brought together esteemed jurists, academics, practitioners, and former Securities and Exchange Commission officials for wide ranging and thought provoking discussions on investor protection, securities litigation, and the evolving civil justice landscape.
By ensuring that only non frivolous claims survived to discovery, the PSLRA has led to significantly larger recoveries in cases that cleared its high thresholds. According to the Stanford Clearinghouse, nearly $120 billion has been recovered for investors.
Looking back, speakers examined how the PSLRA and caselaw interpreting the statute since have reshaped class certification, Section 11 claims and the traceability of shares, attorneys’ fees, and pleading standards. Looking ahead, discussions turned to forced arbitration, precatory shareholder proposals, and the growing attempt to privatize securities law. The program also featured insights from Northern District of California Federal Judge Jon S. Tigar on class certification, and Delaware Supreme Court Justices Collins J. Seitz, Jr. and Abigail M. LeGrow and Vice Chancellor Paul A. Fioravanti, Jr. on Delaware’s most recent corporate law reforms and landmark cases. The Symposium concluded with two fireside conversations—one with Delaware Supreme Court Chief Justice Seitz, and the other with former SEC Commissioner Caroline A. Crenshaw.
The Private Securities Litigation Reform Act, commonly known as the PSLRA, was enacted in December 1995, over the veto of President Clinton, and represents the most sweeping overhaul of the federal securities laws since the passage of the Securities Act of 1933 and Securities Exchange Act of 1934. At its core, the legislation was premised on the belief that the securities litigation system was broken. Critics argued that non meritorious cases were filed too frequently, that nearly all cases survived early motion practice only to settle without regard to the merits, and that class actions were driven more by lawyers than by investors themselves.
Laura H. Posner Partner
F. Jackson
To address these perceived problems, Congress enacted reforms that were widely viewed at the time as a boon to public companies, their executives, investment banks, and accounting firms. The PSLRA imposed new restrictions and procedural hurdles, including reforms to the selection and compensation of lead plaintiffs; limits on recoverable damages and attorneys’ fees; an automatic stay of discovery while motions to dismiss are pending; a safe harbor for certain forward looking statements; a mandate requiring courts to sanction attorneys who violate Rule 11(b), with penalties potentially reaching 100 percent of defendants’ fees; and, most significantly, heightened pleading requirements for falsity and scienter that exceeded even Rule 9(b) of the Federal Rules of Civil Procedure. Taken together, the PSLRA codified a set of tools designed to delay and defeat securities fraud claims and to discourage plaintiffs’ counsel from filing suit.
There is little dispute that the PSLRA succeeded in achieving at least one of its primary objectives. While the number of securities class actions filed has remained relatively stable since 1995, dismissal rates have dramatically increased.
There is little dispute that the statute succeeded in achieving at least one of its primary objectives. While the number of securities class actions filed has remained relatively stable since 1995, the PSLRA dramatically increased dismissal rates. As Symposium panelist Susan Saltzstein recently observed in her New York Law Journal article, “Reflections on the PSLRA at 30,” heightened pleading standards fundamentally reshaped early motion practice. Data from the Securities Class Action Clearinghouse, operated by Stanford Law School in partnership with Cornerstone Research, confirms this shift: since the PSLRA’s enactment, 3,306 cases have been dismissed and 3,004 have settled—a dismissal rate of 52%.
Dismissal rates have climbed even higher over time, particularly as the Supreme Court has interpreted and strengthened the PSLRA’s requirements in decisions such as Tellabs, Halliburton, Janus, Omnicare, and Slack. NERA’s 2025 year end report found that between 2016 and 2025, motions to dismiss were granted in full in 62% of cases, partially granted in another 21%, and denied entirely in only 17%. As Professor and former SEC Commissioner Joseph Grundfest—himself involved in the PSLRA’s drafting and another one of the Symposium’s speakers—recently remarked, the statute was “a major success” that brought long needed discipline and order to securities litigation.
Importantly, however, the PSLRA did not extinguish private enforcement of the federal securities laws. Instead, by ensuring that only non frivolous claims survived to discovery, the statute contributed to significantly larger recoveries in cases that cleared its thresholds. According to the Stanford Clearinghouse, since 1995, nearly $120 billion has been recovered for investors—an average of $4 billion per year. All 100 of the largest securities class action settlements in history occurred after the PSLRA’s passage, and both average and median settlement amounts have increased substantially.
Private class actions also continue to play a vital role in policing markets and deterring fraud. According to a 2025 ISS report, only 27 of the top 100 securities class action settlements had related SEC enforcement actions. In those cases, private litigation recovered more than $34 billion for investors, compared to just $4.6 billion recovered by the SEC—meaning private actions yielded, on average, more than seven times what SEC-related actions covered. Overall, the top 50 private securities settlements recovered over $58 billion, while the top 50 SEC actions recovered less than $14 billion, much of which was never returned to investors.
Against this backdrop, investors now face a renewed challenge. SEC Chair Paul Atkins has argued that declining numbers of public companies and IPOs are attributable to regulatory burdens and fears of frivolous litigation. Yet empirical research does not support his claim. A recent Journal of Financial Economics study found that regulatory compliance costs explain just 7.3 percent of the decline in IPOs. Instead, the primary drivers are the expanding availability of private capital or M&A activity. Further, if litigation costs were the culprit of the IPO decline, IPO activity should have increased as the PSLRA increased dismissal rates—but data shows precisely the opposite trend.
Despite this evidence, efforts continue to weaken private enforcement through forced arbitration, expanded safe harbors, and pressure on states to adopt investor hostile laws. As the Symposium made clear, 30 years on, the PSLRA’s legacy is complex. But private securities litigation remains indispensable to market integrity and investor protection.
Laura Posner is a partner in the Securities Litigation & Investor Protection practice and president of ILEP. Benjamin Jackson, also a partner in the Securities Litigation & Investor Protection practice, is the secretary of ILEP.
Pump-and-Dump Schemes Are on
the Rise
Financial regulators and market observers are raising the alarm that the stock market has reached what one analyst described as “the apex of the pump-and-dump.” Once viewed as fringe activity confined to penny stocks and retail investors, these schemes are now appearing more frequently on established U.S. exchanges, raising serious concerns about market integrity and investor protection.
Analysts underscore how modern pump-and-dump operations have become more sophisticated, global, and difficult to detect in real time, exacerbated by social media, AI deepfakes, and online chatrooms. The proliferation of cryptocurrency pumpand-dump schemes no doubt helps fan the flame.
According to an FBI report pump-and-dump stock fraud complaints grew by a staggering 300% from 2024 - 2025. Bloomberg recently reported a growing number of questionable market episodes involving small, newly listed companies—often based in Asia—that enter U.S. markets through underwriters specializing in microcap stocks. Since 2023, more than 250 companies have gone public on the Nasdaq Capital Market. Roughly a quarter of those companies were later promoted in WhatsApp group chats and online forums, followed by dramatic price collapses or trading suspensions by the SEC amid concerns of potential manipulation. According to Bloomberg, a similar pattern emerged among several microcap firms that debuted on the New York Stock Exchange’s small-cap platform during the same period.
Kate Fitzgerald Senior Manager Marketing Communications
202.408.4600
kfitzgerald@cohenmilstein.com
Once viewed as fringe activity confined to penny stocks and retail investors, modern pump-anddump schemes now appear more frequently on established U.S. exchanges, raising serious concerns about market integrity and investor protection. Regulators and exchanges are responding with heightened scrutiny.
Old Scam, New Technology
While pump-and-dump schemes are not new, advancements in electronic trading platforms, WhatsApp, Reddit, and the unregulated Wild West of AI are making them faster and easier to pull off—and making grifters bolder. Increasingly, AIgenerated ads and bots are luring investors by impersonating well-known investors.
Pump-and-dump schemes typically exploit stocks with low public floats—meaning relatively few shares are available for public trading—making prices easier to manipulate. In these
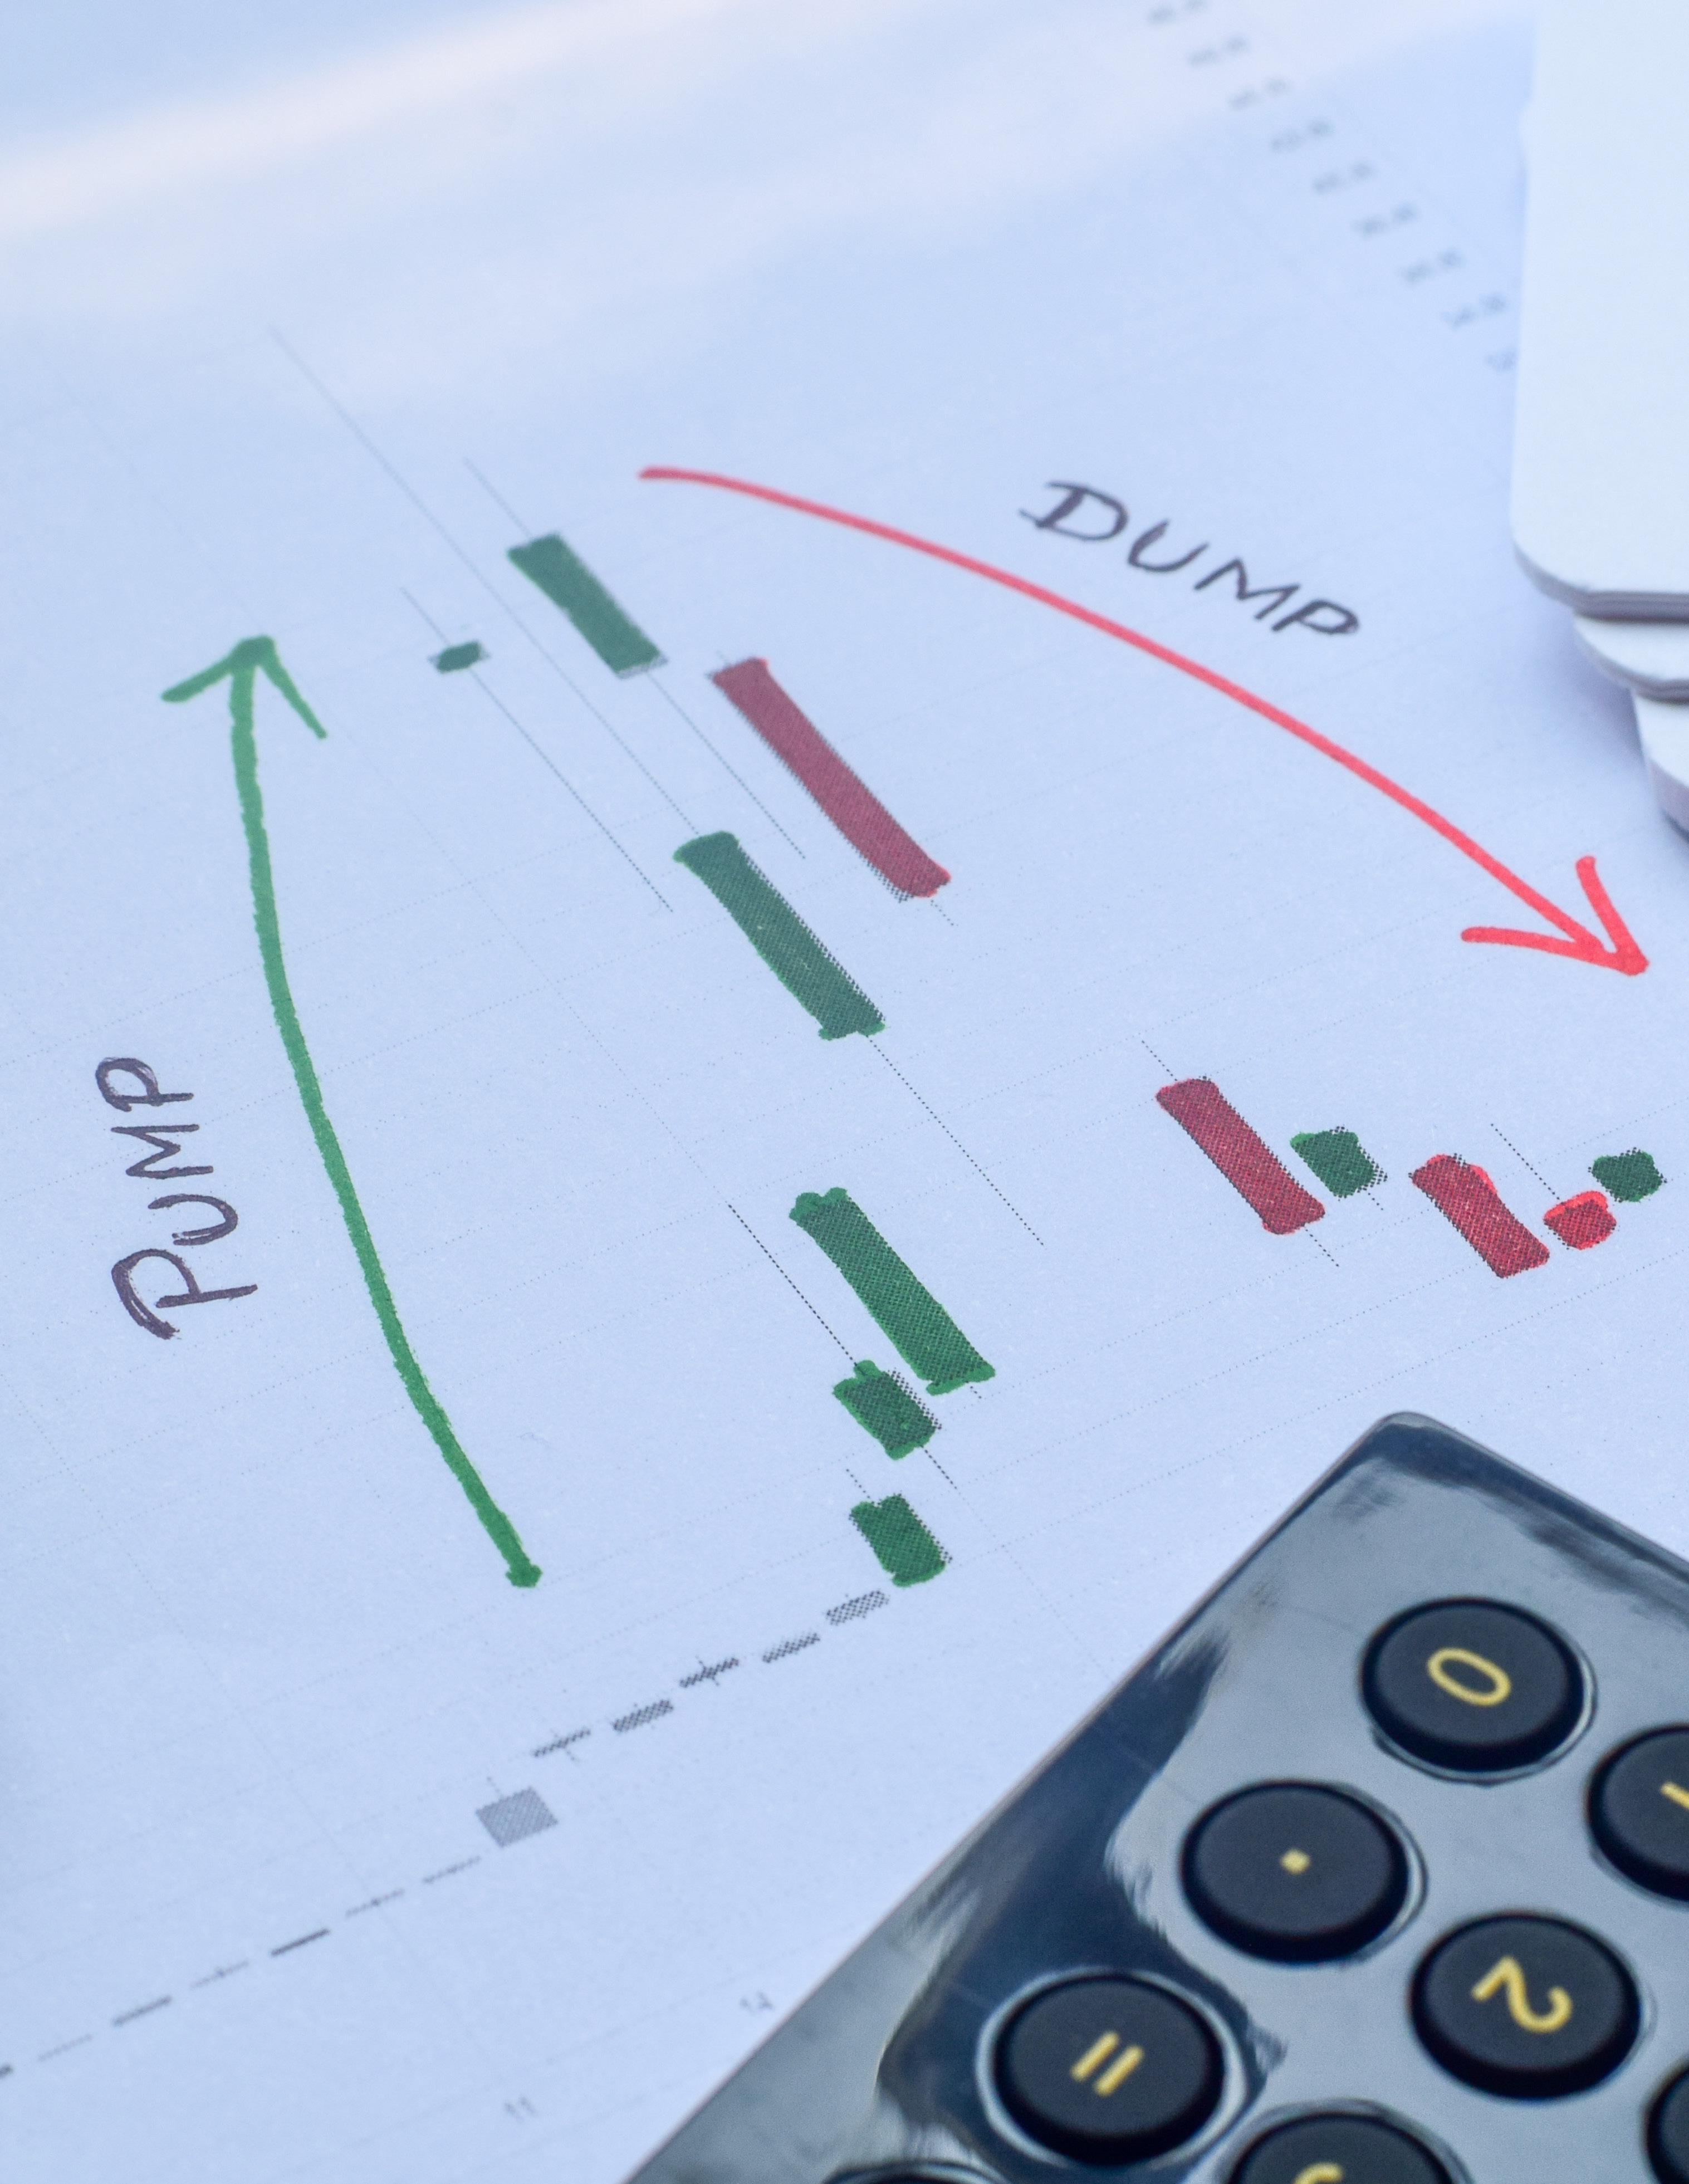
cases, perpetrators accumulate shares at low prices, then aggressively promote the stock through social media, chatrooms, and online forums using exaggerated or misleading claims. As the price rises rapidly, unsuspecting investors are lured in. Once demand peaks, the manipulators sell their holdings en masse, triggering a steep price decline and leaving retail investors with substantial losses.
Stimulated by new frontiers for investing stocks or cryptocurrencies and the fear of missing out, a subset of retail investors is emerging—those who are attracted to pump-and-dump schemes for the sheer thrill of potentially beating the odds. Academics suggest this convergence of new technologies is fueling momentum investing, which can roil markets when driven by fraudulent schemes.
The rise of pump-and-dump activity on major U.S. exchanges is not just a retail investor problem. It can pose material risks for institutional investors whose portfolios depend on market integrity, liquidity, and reliable price discovery.
Why This Matters for Institutional Investors
The rise of pump-and-dump activity on major U.S. exchanges is not just a retail investor problem. It can pose material risks for more conservative institutional investors like public pension and TaftHartley funds whose portfolios depend on market integrity, liquidity, and reliable price discovery. While large asset managers are unlikely to be primary victims of such schemes, the secondary impacts may intersect with institutional investment strategies.
• First, artificially inflated prices that later collapse can distort index composition, particularly in micro-cap, small-cap, and equal-weighted benchmarks. These distortions may trigger forced rebalancing, increase tracking error, and generate unexpected transaction costs for pension funds and other institutions that rely on index-based exposures, ultimately weakening confidence in benchmark integrity itself.
• Second, reputational risks become more acute. Exposure, even inadvertent, to companies later found to be tied to market manipulation can prompt scrutiny from boards, beneficiaries, regulators, legislators, and the press, raising questions about diligence and governance standards. Over time, such scrutiny can undermine public confidence in a fund’s stewardship and intensify political or oversight pressure.
In short, the escalation of pump-and-dump schemes on reputable exchanges challenges the foundational assumption that listed markets offer a baseline level of trust and transparency.
How effectively regulators and exchanges respond will influence not only retail confidence, but also institutional capital allocation decisions across the small-cap and cross-border investment landscape.
What Regulators and Exchanges Are Doing
Regulators and exchanges are responding with heightened scrutiny. Last September, the SEC launched a cross-border task force, highlighting pump-and-dump schemes involving companies from China, Hong Kong, Singapore, and offshore jurisdictions like the Cayman Islands. The agency is also considering new disclosure rules, revisions to the definition of foreign private issuers, and expanded authority for exchanges to deny listings deemed especially susceptible to manipulation.
The SEC has also increased its reliance on suspension powers. In September, the agency imposed 10day trading halts on firms such as QMMM Holdings Ltd. and Smart Digital Group Ltd., citing potential social media-driven manipulation. QMMM’s shares had surged nearly 1,000% in under three weeks following online promotion tied to a vague cryptocurrency strategy. Such suspensions are often followed by longer exchange-imposed trading halts meant to protect investors without fully delisting the stock.
Atkins doubled down on these positions before the U.S. House Financial Services Committee in February, noting the suspension of fourteen Asia-based issuer stocks due to pump-and-dump schemes. “I am working within the securities laws to protect investors from those who seek to use international borders to evade and undermine U.S. investor protections. Markets are global. Investor protection must be as well,” Atkins stated.
Nasdaq has also taken an aggressive stance. Last September, it raised minimum public float requirements and other listing standards for companies with significant ties to China. Then in December, Nasdaq began rejecting listings when it identifies red flags, such as concerns about the integrity of underwriters or auditors.
Similarly, the CFTC, FBI, and IRS are ramping up enforcement to combat a surge in investor scams. In late March, federal grand juries indicted ten executives and employees from four Asia-based cryptocurrency brokers for orchestrating pump-and-dump schemes to artificially inflate trading volume and prices.
Together, these efforts signal a recognition that pump-and-dump schemes are no longer isolated abuses. Instead, they represent a systemic challenge that tests the credibility of U.S. capital markets and investor stamina in an era of globalized finance and digital hype.
Kate Fitzgerald is a Senior Manager Marketing Communications at Cohen Milstein.
Court Allows Investor Fraud Claims Over Trade Desk’s Kokai Platform to Proceed
On March 17, 2026, the Central District of California Court held that Lead Plaintiff, Arkansas Public Employees’ Retirement System and Public Employees’ Retirement System of Mississippi, sufficiently alleged that The Trade Desk Inc. and its top executives knowingly misled shareholders about the performance and adoption rates of its new ad-buying platform, Kokai.
According to the class complaint, the alleged misstatements and omissions by Trade Desk, founder and CEO Jeff Green, former CFO Laura Schenkein, and Chief Strategy Officer and Executive Vice President Samantha Jacobson contributed to billions of dollars in shareholder losses as corrective disclosures revealed the truth. As Co-Lead Counsel, Cohen Milstein represents Lead Plaintiff on behalf of investors who purchased Trade Desk stock between November 15, 2023, and August 8, 2025.
In March, federal court held that the Arkansas Public Employees’ Retirement System and Public Employees’ Retirement System of Mississippi sufficiently alleged that The Trade Desk and its top executives knowingly misled shareholders about the performance and adoption rates of a new ad-buying platform that Defendants touted as “state of the art.”
Trade Desk is a technology company that operates a digital platform enabling advertisers to place ads across digital spaces, including websites, podcasts, and streaming services. In 2023, the company launched an ad-buying platform called Kokai. Trade Desk touted the new platform as state-of-the-art, telling investors that the company would quickly transition clients from its legacy system and that Kokai’s new user interface and AI-powered performance improvements would boost client spending and drive company growth.
Lead Plaintiff alleges that, following Kokai’s launch, Defendants repeatedly made false and misleading statements to investors regarding clients’ adoption of the new platform, reporting adoption rates inconsistent with the company’s internal data, touting manipulated metrics to support these false claims, and concealing a company-wide pressure campaign to force otherwise unwilling clients to adopt the new platform.
Additionally, Lead Plaintiff alleges that Defendants misrepresented Kokai’s performance to investors, even
though the company knew that clients were openly dissatisfied with the platform’s features, accuracy, pace of spending, and user interface.
In her March ruling, Judge Christina A. Snyder held that Lead Plaintiff adequately alleged that Defendants were aware of, but did not disclose, data that contradicted their positive claims regarding Kokai’s adoption rates. The Court also found that Defendants’ unqualified statements touting Kokai’s performance and capabilities were sufficiently pled as misleading given the alleged contrary facts known to Defendants.
The Trade Desk decision reflects a broader trend of heightened scrutiny around the accuracy of companies’ disclosures as they increasingly market new platforms emphasizing automation and AI-driven capabilities.”
The Court further concluded that Lead Plaintiff adequately pled scienter as to the executive defendants. The Court cited allegations that each executive was directly informed of and internally discussed client dissatisfaction with Kokai, and that they collectively sold a staggering $465 million in stock during the class period at artificially inflated prices, with multiple suspiciously timed sales. Notably, Lead Plaintiff alleges that Defendant Jeff Green sold $48 million in stock just one day before a February 2025 earnings call began to reveal Kokai’s slow adoption and a related revenue miss (news which triggered the then-largest stock price drop in the company’s history). The Court found that these allegations, “taken collectively,” supported a strong inference of scienter.
Finally, the Court held that Lead Plaintiff adequately pled loss causation. The class complaint outlined three corrective disclosures that reduced the company’s artificially inflated stock price: revenue target misses due to Kokai’s slow adoption during earnings calls in February and August of 2025; and an exposé published by trade publication AdWeek in March 2025, which further revealed the truth regarding Kokai’s adoption and performance issues. The Court found these connections plausibly tied Defendants’ misstatements to investors’ losses over Defendants’ arguments to the contrary.
This decision reflects a broader trend of heightened scrutiny around the accuracy of companies’ disclosures as they increasingly market new platforms emphasizing automation and AI-driven capabilities, a practice known as “AI washing.” Courts are signaling that when companies choose to tout these new products, they must do so in a way that does not mislead investors into believing a rosier state of affairs than actually exists.
Defendants must now answer the amended complaint and the case moves into discovery, where Lead Plaintiff will pursue evidence that further establishing that Defendants’ public statements about Kokai adoption and capabilities contradicted what was known internally at the time.
Laura Posner is a partner in the Securities Litigation & Investor Protection practice. Kay Jewler is a paralegal in the Securities Litigation & Investor Protection practice.
Antitrust Settlement with Data Vendor Ends WageFixing Suit That Recovered Nearly $400 Million for Low-Wage Poultry Workers
Capping seven years of litigation, a federal judge recently approved an industry-changing injunctive relief settlement against Agri Stats, Inc., a data vendor that allegedly helped poultry manufacturers to unlawfully suppress workers’ pay. The court’s March 10 order followed its approval last June of $398.05 million in class action settlements against 18 of the nation’s leading poultry producers.
Cohen Milstein was co-lead counsel in the case, which resulted in the largest recovery ever in an antitrust class action for low-wage workers in the United States and the second-largest recovery ever in a wage-fixing class action in the United States.
Poultry processing plant workers, whose work includes hanging, slaughtering, and deboning chickens and turkeys, claimed that since 2000, the country’s leading poultry producers conspired to lower corporate labor costs by suppressing their pay and benefits.
Poultry processing plant workers, who hang, slaughter, and debone chickens and turkeys (among other difficult and dangerous jobs), claimed that since 2000, the country’s leading poultry producers conspired to lower corporate labor costs by suppressing their pay and benefits. The poultry producers own and operate over 200 processing plants, hatcheries, and feed mills nationwide. The lawsuit alleged that they carried out this scheme by sharing competitively sensitive compensation data, in part through industry data vendors like Agri Stats.
“We are grateful that we achieved some measure of justice and long overdue financial relief for tens of thousands of hard-working poultry plant workers,” said Antitrust Partner Alison Deich, a member of the Cohen Milstein litigation team. “The settlement with Agri Stats includes significant conduct reforms that will benefit workers across the industry.”
Specifically, as a part of the injunctive relief settlement, Agri Stats agreed to eliminate relevant plantlevel data fields related to labor costs in its broiler chicken reports that it circulates to subscribers.
Filed in 2019, the lawsuit by poultry workers claimed that their employers formed, implemented, monitored, and enforced the conspiracy to suppress compensation in at least three ways:
First, senior executives, including human resources executives and directors of compensation, held recurring “off the books” in-person meetings where worker compensation was discussed and set.
Second, on a highly frequent basis, defendants exchanged detailed, non-public wage and benefits information through surveys.
Third, managers at the poultry processing plants engaged in bilateral and regional exchanges of wage and benefits information, including future plans.
In 2022, the U.S. Department of Justice filed a lawsuit against many of the same poultry producers, alleging a long-running conspiracy to suppress worker pay with the same allegations uncovered by the extensive independent private investigation by co-lead counsel.
“We are grateful that we achieved some measure of justice and long overdue financial relief for tens of thousands of hard-working poultry plant workers,” said Antitrust Partner Alison Deich, a member of Cohen Milstein’s litigation team. “The settlement with Agri Stats includes significant conduct reforms that will benefit workers across the industry.”
Oxfam, a global think tank that fights economic inequality and poverty, has reported that plant workers in the U.S. poultry industry earn wages that put them near or below the poverty line.
The plaintiffs in Jien, et al. v. Perdue Farms, Inc., et al. were represented by co-lead counsel Cohen Milstein Sellers & Toll PLLC, Handley Farah & Anderson PLLC, and Hagens Berman Sobol Shapiro. Berger Montague and Lockridge Grindal Nauen PLLP served as additional counsel.
Fiduciary Focus: That ‘70s Show
For 16 years, the Department of Labor (DOL) under successive administrations grappled over the details of a federal rule expanding who qualifies as a fiduciary when providing private investment advice—and therefore owes clients a higher duty. Last month, the DOL quietly engineered the death of its own rule and restored a five-part test from 1975 as the standard, arguably leaving beneficiaries less protected when making lifechanging financial decisions.
The 10 days that shook the investment world began on March 10, 2026, when the DOL filed a joint motion asking a federal court to formally vacate its so-called Retirement Security Rule. A week later, on March 17, Judge Jeremy D. Kernodle of the U.S. District Court for the Eastern District of Texas approved the motion, formally striking the rule from the books. Three days later, on March 20, DOL published new guidance in the Federal Register making official what the court ordered: the restoration of the 1975 test as the governing standard for determining who qualifies as a fiduciary when providing investment advice under Employee Retirement Income Security Act of 1974 (ERISA).
The death of the rule ended a long and contentious effort by the federal government to replace the 1975 test with a comprehensive rule.
Most proximately, the Trump administration’s actions eliminated the Retirement Security Rule released by the Biden-era DOL in April 2024, which itself was the culmination of more than a decade of stopand-go regulatory work. The rule by the Biden DOL primarily sought to broaden the definition of “investment advice fiduciary” under both ERISA and the Internal Revenue Code, replacing the 1975 test with a standard that the DOL argued better reflected the realities of the modern retirement marketplace.
The death of the Retirement Security Rule ended a long and contentious effort by the federal government to expand the situations in which financial professionals qualified as fiduciaries when providing private investment advice. Fiduciaries owe clients higher duties of obedience, loyalty, and care.
According to the Biden DOL, the five-part test left retirement savers legally unprotected at the exact moments they were most likely to assume advisors had their best interests at heart: when making one-time, irreversible investment decisions. For example, a broker recommending an annuity purchase or an IRA rollover— decisions often involving a worker’s entire retirement savings—owes no fiduciary duty under the five-part test simply because the interaction is a one-time event and therefore exempt under the test.
Jay Chaudhuri Of Counsel
jchaudhuri@cohenmilstein.com
The 2024 rule was not the DOL’s first attempt to close that gap. In 2010, the Obama administration proposed an expansion of the fiduciary standard, only to withdraw it in face of fierce opposition from the financial services industry and members of Congress. The effort resumed in 2015, this time backed by a more rigorous analytical foundation. The White House Council for Economic Advisers released a report titled The Effects of Conflicts Investment Advice on Retirement Savings, which estimated that conflicted investment advice cost retirement savers approximately $17 billion annually in reduced returns, a figure that became the economic cornerstone of every subsequent effort.
In 10 days that shook the investment world, the Department of Labor engineered the death of its own rule, restoring a standard that arguably leaves retirement plan beneficiaries less protected when making life-changing financial decisions.
The Obama administration further argued that the American retirement system had structurally changed since ERISA’s creation in 1974. The decline of the traditional defined benefit plans led to the corresponding rise of defined contribution plans like 401(k) plans. Unlike defined benefit plan participants, defined contribution plan participants bear responsibility for contribution levels, asset allocation, rollover decisions, and withdrawal timings. These complex decisions established conditions where conflicted investment advice could financially hurt retirees, and what President Obama called “backdoor payments and hidden fees” to investor advisors went largely unchecked by the existing regulatory framework.
In April 2016, the Obama administration finalized its fiduciary rule replacing the five-part test with a broader standard that treated most professional retirement recommendations, including one-time rollovers and annuity advice, as fiduciaries subject to the ERISA’s highest duties of loyalty and care. The rule’s most prominent and controversial feature, the Best Interest Contract Exemption, permitted advisers to receive commission-based compensation only if they contractually committed to their clients’ best interests and met strict disclosure requirements.
The financial services and insurance industries challenged the rule almost immediately. In 2018, the U.S. Court of Appeals for the Fifth Circuit vacated the regulations, holding DOL had exceeded its statutory authority under ERISA.
Under the Biden administration, a third, more narrowly drafted version of the fiduciary rule sought to crack down on “junk fees” in retirement investment advice. The 2024 rule tied fiduciary status to the nature of the advice relationship compared to a rule based on the type of transaction. Specifically, the 2024 rule limited fiduciary status in two ways: (1) whether the recommendations were made by individuals who held themselves as trusted investment advisers; and (2) whether such advice focused on retirement accounts such as an IRA rollover account in the context of the trusted advice relationship. But in 2026 the courts vacated the new rule, finding that, despite its narrower scope, it still constituted an overreach of DOL’s statutory authority under ERISA.
With each of the past three fiduciary rules failing over the last 16 years—struck down by courts, abandoned by successive administrations, or both—the original five-part test established in 1975 once again determines who qualifies as a fiduciary under ERISA. Under the restored standard, a financial professional owes a duty to a retirement investor only if the advice: (1) is provided on a regular basis, (2) pertains to a mutual understanding, (3) serves as a primary basis for investment decisions, (4) is individualized to the investor’s specific needs, and (5) is rendered for compensation. Because all five prongs must be met, an investment advisor who makes a one-time rollover recommendation will almost never qualify as a fiduciary under the restored standard.
The change will impact a broad range of plan beneficiaries. Taft-Hartley benefit plans are of course directly subject to ERISA so plan participants must be wary about the standards that apply to financial advisors throughout their investing years. The situation is a bit more complicated for public pension beneficiaries. Police officers, firefighters, teachers, and municipal workers often spend their entire career in a single pension system, generally with limited access to independent financial advice. When they retire and face a decision whether to roll over their investments or purchase annuities, they may be approaching such complex financial decisions for the first and only time. With the death of the 2024 Retirement Security Rule, they will now be less protected. This as waves of baby boomers reach retirement age each year, driving rollovers to historic highs.
Jay Chaudhuri is Of Counsel at Cohen Milstein.
Team Profile
Cristine Turner | Senior Advisor for Investor Relations
561.515.1400 | cturner@cohenmilstein.com
Cristine Turner is a Senior Advisor for Investor Relations in the Securities Litigation & Investor Protection practice. Cristine joined the firm in 2025 and brings more than 30 years of focused experience in the public pension industry. Over the years, she has established and fostered strong, long-term client relationships. Cristine is based in the Palm Beach Garden office. For this issue of the Shareholder Advocate, Cristine spoke with editor Christina Saler.
I grew up in … a small, rural town south of Jacksonville, Florida. My mom moved us from Atlanta to the country because she trained horses and riders as well as judged horse shows. Over the years, I grew to love living in the country, but I always loved riding. My mom taught me to ride English Style. I regularly competed in horse shows grabbing a blue ribbon here and there. Florida is still my home state.
During college … I worked my way through by also working fulltime at Barnett Bank. I started out in the technical support area and then moved to the investment management side. I worked closely with the portfolio managers which led me to take the Series 65 exam to become a licensed Investment Advisor Representative. Barnett Bank was acquired by another bank so the portfolio managers with whom I worked broke off to start their own investment management firm. I made the move with them and am glad I did. It really launched me into the public pension communities of Florida and Georgia.
The public pension community … is close knit. Even though there are always changes in trustee seats and administrative leadership positions, I’m fortunate to say that I have worked with some of the same people for decades. I value those relationships and always look forward to reconnecting at pension conferences. Since joining the firm, I’ve continued to work with pension funds in Florida and Georgia and have also started to focus some of my time in Louisiana.
Making the move to Cohen Milstein … has been an easy transition. Having an investment background has helped me quickly get my arms around securities litigation and the important role that institutional investors play in holding corporations accountable for securities fraud and mismanagement that harms investors. And I’m able to continue to work with my longstanding clients and interact with other members of the pension community but just in a different context.
I recently watched … the series Silo. I’m usually hooked on true crime shows and books so Silo was a departure for me. It’s a drama set in a dystopian future where humans live in an underground silo. It’s grim but interesting.
Recent Highlights
IN THE NEWS
Investors Give Courts Fresh Look in Bid to Hold Auditors Liable
SEC’s Arbitration Shift Still Sparks Fears Over US Stock Valuations
CIO – March 4, 2026
SEC Plans Changes on Audit and Accounting Requirements
Accounting Today – February 20, 2026
Pegasystems Settles Mass. Shareholder Actions for $7M
Law360 – February 11, 2026
2nd Circ. Won’t Kick Luxottica Pension Fight to Arbitration
Law360 – February 5, 2026
Justices Leave in Place 4 Collective
Certification Approaches
Law360 – January 14, 2026
SEC War on ‘Frivolous’ Litigation Upends
Wall Street Cop’s Role
Bloomberg Law – January 8, 2026
AWARDS & ACCOLADES
24 Cohen Milstein Lawyers Named Leading Plaintiff Financial Lawyers
Lawdragon – Recognizing Molly Bowen, S. Douglas Bunch, Suzanne Dugan, Michael Eisenkraft, Carol Gilden, Laura Posner, Julie Reiser, Christina Saler, Daniel Sommers, and Steven Toll – March 27, 2026
Cohen Milstein Earns Fifth ERISA Practice Group of the Year Recognition
Law360 – January 19, 2026
Legal Lions of the Week – Block Inc.
Law360 – January 12, 2026
Eleven Cohen Milstein Lawyers Honored as Leading Plaintiff Consumer Lawyers
Lawdragon – February 13, 2026
Eight at Cohen Milstein Named Among 500 Leading Global Antitrust & Competition Lawyers in 2026
Lawdragon – January 16, 2026
UPCOMING EVENTS
April 26-29 | Texas Association of Public Employee Retirement Systems Annual Conference
Galveston, TX – J.D. Davis and Cristine Turner
May 17-20 | National Conference on Public Employee Retirement Systems Annual Conference & Exhibition
Las Vegas, NV – J.D. Davis, Richard Lorant, Christina Saler, and Cristine Turner
June 10 | Oklahoma State Firefighters Association Annual Convention Golf Tournament
Oklahoma City, OK – Richard Lorant and Cristine Turner
June 28 - July 1 | Florida Public Pension Trustees Association Orlando, FL – Cristine Turner
May 16-19 | Michigan Association of Public Employee Retirement Systems Spring Conference
Bay City, MI – Richard Lorant
May 31 - June 3 | Massachusetts Association of Contributory Retirement Systems Spring Conference Springfield, MA – Richard Lorant
June 16-19 | National Association of Public Pension Attorneys Legal Education Conference
Grand Rapids, MI – Luke Bierman, Suzanne Dugan, Julie Reiser, and Daniel Sommers
BOSTON, MA
CHICAGO, IL
Editor: Christina D. Saler
Editorial Team: Richard E. Lorant and Samuel P. Waite
Please contact us with questions or comments at 202.408.4600.
The materials in this edition of the Shareholder Advocate are for informational purposes only. They are not intended to be, nor should they be taken as, legal advice. The opinions expressed herein reflect those of the respective author.