INTEREST WHO'S GROWS PAYING FORIN ALL BONDS THESE DATA CENTERS? SAILING WITH RITZ CARLTONSANTORINI YACHTS SANS CROWDS PORSCHE'S NEXT ELECTRIC JOURNEY
26
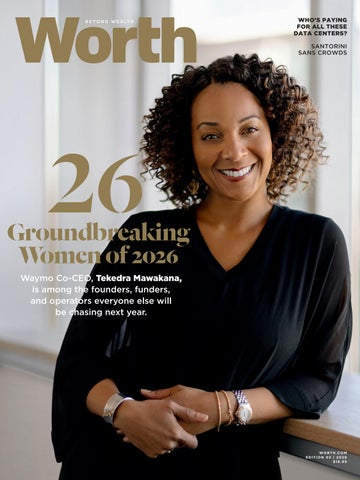
Groundbreaking Women of 2026 Waymo Co-CEO, Tekedra Mawakana, is among the founders, funders, and operators everyone else will be chasing next year.
WORTH.COM EDITION 03 | 2026 $18.95
Your New Basecamp for Adventure is Coming to Crested Butte LIVE SLOPESIDE AND BE AMONG THE FIRST GENERATION OF OWNERS
Crested Butte’s base area is about to see its first major
ski beach. Impeccably designed in an iconic location right at
redevelopment in decades. With an estimated construction
the lift, guests and owners alike will enjoy a first-of-its-kind
completion in late Fall of 2027, Elevation Hotel & Spa will
experience with intentional, quality care and openhearted
transform into The Beckwith — a four-star resort with hotel
service. Beckwith Residences offers one, two, three and
rooms, luxury residences, a private club, and world-class
four-bedroom luxury turn-key residences. These ski-in, ski-
amenities including multiple restaurants, spa, ski valet,
out retreats offer the best of The Beckwith, all designed to
adventure concierge, meeting spaces, hot tub terrace, and
make ownership as effortless as it is enjoyable.
LIMITED TIME, P R E- C O N S T R U C T I O N P R I C I N G
9 70. 5 1 9. 267 7
S TA R T S AT $ 1 . 3 M
This does not constitute an offer to sell nor the solicitation of an offer to purchase made in any jurisdiction nor made to residents of any jurisdiction where registration is required. The Resort is under development and is not yet complete. The depictions and design of the Resort and Residences as shown are based on current development plans. Development plans and all improvements, features, land uses, views, amenities, floor plans, specifications, furnishings, trim, brand names, and other information shown here or in any renderings, illustrations, photos, simulated views, graphic images, maps, or other visual depictions are illustrative only and may be changed without notice. No guarantees are made that the Resort and Residences will be renovated, or if renovated, that the Resort and Residences will be renovated, used, operated, or sold in conformance with this information. All rights reserved.
C ON T E N T S EDITION 03 |
2026
28
Groundbreaking Women 2026
42
Santorini Sans Crowds
50
Buying Time
62
The New Executive Order: Longevity Medicine 42
02
FA L L 2 0 2 6
WORTH.COM
KEEP FLYING WITH THE BEST
Thank you for honoring us as Europe’s Best Airline for the 10th time and awarding us in 8 categories at the Skytrax World Airline Awards.
Best Airline in Europe
Best Airline in Southern Europe
Best Business Class Onboard Catering
Best Business Class in Europe
Best Business Class in Southern Europe
Best Business Class Onboard Catering in Europe
Best Economy Class in Europe
Best Economy Class Onboard Catering in Europe
Living Well 68 The End of the Average Patient
70 Clinically Ignored
72 22
Trends
92
The Cheapest Longevity Drug Is a Mindset 68
16 This Electric SUV is Porsche’s Most Powerful Car Ever
92 Who Is Paying for All These Data Centers?
98 Sleep Past the Tracker
20 All Aboard the Auction Block
Forecast
22
100 Your Brain on Screens
Barcelona by Design
Departments
26
102
Wine Clubs Grows Up
76
Ahead of Her Time
It’s Time for the Fed to Hike Interest Rates
106
78 Don’t Mistake Wealth for Legacy
80 Family Offices: The New Kid on Wall Street 26 04
Techonomy
FA L L 2 0 2 6
WORTH.COM
83 Worth’s Leading Advisors
Times Square: Coolest Hood in NYC?
110 Lambrusco: The Wine Eternally Reinventing Itself
112 Mixed Media
114 The Best New Hotels
LĀNA'I, HI
SENSEI.COM 808-481-5547
Space to breathe, support to grow On the secluded island of Lāna'i, Sensei offers more than a peaceful retreat. Guided by an evidence-led philosophy and personalized one-on-one support, each stay unfolds at your own pace through private wellness sessions, restorative spa treatments, enriching daily experiences, and Sensei by Nobu dining. Thoughtfully curated around your goals, every experience helps cultivate practices for a healthier, more balanced life.
CHAIRMAN
Jim McCann CHIEF EXECUTIVE OFFICER
Josh Kampel PRESIDENT
Paul Stamoulis PUBLISHER
Andy Whitehouse
EDITORIAL E D I TO R I A L D I R E C TO R
Dan Costa
S E N I O R E D I TO R
Eva Crouse
A S S I S TA N T E D I T O R C R E AT I V E D I R E C T O R CO N T R I B U TO R S
Caroline Bienfang Nicole Dudka
Cait Bazemore, Larry Kantor, Bob Diamond, Jonathan Russo, Deborah Grayson, Oliver Rist, Kirsten Cluthe, Tim Stevens, Paul Tumpowsky, Alexis Buncich, Dr. Stephanie McNally, Nora Walsh, Jason Allen Ashlock
PARTNERSHIPS, ADVERTISING & EVENTS D I R E C TO R O F PA R T N E R S H I P S V P, S A L E S & M A R K E T I N G
Matt McCann Kendall Wyckoff
V P O F PA R T N E R S H I P S
Ron Stern
V P O F PA R T N E R S H I P S
Ginger Murphy
B R A N D PA R T N E R S H I P S A S S O C I AT E
Adam Kamphaus
A S S O C I AT E A C C O U N T M A N A G E R
Neil Madlener
D I R E C TO R O F S P E C I A L P R OJ E C T S
Gabrielle Doré
PRODUCT, OPERATIONS & FINANCE DIRECTOR OF HOSPITALITY
Kimberly Anderson-Marichal
Our Mission Is Building Worth Beyond Wealth Worth helps our influential, successful community better invest their time and money. We believe business is a lever for social and economic progress. From practical financial advice to exclusive profiles of industry leaders, Worth inspires our readers to lead more purpose-driven lives. Through our conferences, digital channels, and quarterly print publication, we connect the people and companies that are building the future. We showcase products and services that are indulgent, luxurious, and sustainable.
WORTH HEADQUARTERS 155 EAST 44TH STREET NEW YORK, NY 10017 INFO@WORTH.COM
06
FA L L 2 0 2 6
WORTH.COM
worth.com
CHAIRMAN’S LETTER
Leadership That Lasts How Groundbreaking Women amplify their impact. BY JIM MCCANN
E
very year at Worth Media’s Groundbreaking Women event, I catch myself watching the room before the program starts. Longtime friends hug and catch up while newcomers are introduced across the aisles. You can feel a palpable sense of purpose, an energy that makes this gathering unlike any other. That electricity comes from the participants themselves. The women in the room have built success across every industry, and they amplify it by opening doors. Every conversation feels rooted as much in accomplishments as in whom they can help next. It’s easy to see why the event, with its annual Groundbreaking Women list featured in this month’s issue of Worth magazine, remains our most popular program year after year. Worth exists to build and empower communities, and these women show us what that looks like at its best. This year’s honorees are reshaping industries from AI and finance to sports and media. They’re also opening doors for whoever comes next, from found-
08
FA L L 2 0 2 6
WORTH.COM
ers to the next generation of women in their fields. Take Daniela Amodei, cofounder and president of Anthropic, who prioritizes communication and interpersonal skills alongside technical credentials in hiring, broadening pathways into AI. Or Karen S. Carter, who became the first woman to lead Dow in its 128-year history after a career spent developing talent and mentoring the next generation of leaders. Then there is Maggie Kang, director of K-Pop: Demon Hunters, who actively mentors emerging animators through the BRIC Foundation’s Career Readiness Bootcamps. And Kirsty Coventry, the first woman and first African elected president of the International Olympic Committee, who built a swim academy and youth program in Zimbabwe long before assuming global leadership. What unites these leaders is not just their personal and professional achievements but their commitment to lifting others as they climb. They represent the exact force of character that has
widened possibilities for generations. That’s precisely why I bring my wife, my daughter, and my granddaughters every year: I want them to see firsthand what a room full of driven, supportive women can accomplish. When my sisters were growing up, college was rarely spoken of as an option. Today, my granddaughter is choosing her own path forward without artificial limits, standing on the shoulders of the trail blazers who came before her. That shift is the direct result of decades of women creating opportunities for people they might never meet. On behalf of everyone at Worth: congratulations to this year’s Groundbreaking Women. Thank you for your vision, your generosity, and for showing us that true influence is built through deep relationships.
— Jim McCann C H A I R M A N , WO RT H M E D I A
jim.mccann@worth.com
CEO’S LETTER
The Uneven Pace of Progress BY JOSH KAMPEL
T
here are moments in history when progress unfolds gradually, and there are moments when it accelerates so quickly that the assumptions we have relied upon for decades suddenly need to be reconsidered. I believe we are living through one of those moments. The first half of 2026 has made one thing clear. Artificial intelligence is becoming a foundational capability that is transforming how businesses are built, how decisions are made, and how ideas become reality. Every major technological breakthrough has promised to make us more productive, but AI has the potential to make us more capable. Entrepreneurs can build products without writing code, marketers can create sophisticated campaigns with a fraction of the resources they once required, and creative people who never learned design software can transform concepts into compelling visuals in minutes. We have experienced the transformation firsthand at Worth. Like many organizations, our team has evolved over the past year as colleagues have pursued new opportunities, new talent has joined us, and our workflows have changed. We have embraced AI not as a replacement for people, but as a tool that enables our team to spend less time on repetitive tasks and more time creating meaningful journalism, memorable experiences, and stronger partnerships. That conversation will continue at
10
FA L L 2 0 2 6
WORTH.COM
this year’s Techonomy conference, where leaders from business, technology, government, and academia will examine how artificial intelligence is reshaping our economy and society. These discussions matter because the decisions made today will influence how organizations compete and how people work for decades to come. The pace of progress, however, is not universal. While technology can transform industries almost overnight, expanding opportunity and reshaping institutions often requires years of determined leadership. That contrast is at the heart of this issue. Each year, Worth recognizes extraordinary women whose leadership is changing industries, building remarkable companies, advancing science, strengthening communities, and expanding opportunities for others. Their accomplishments deserve to be celebrated on their own merits, but they also remind us that meaningful progress often requires persistence long after the spotlight has moved on. Gender equality has advanced significantly over the past several decades, yet women remain underrepresented in executive leadership, boardrooms, venture capital, and many of the places where consequential decisions are made. The leaders featured in this issue have not only broken through those barriers, they are helping remove them for the generations that follow. Their stories re-
mind us that lasting progress is built through resilience, determination, and a commitment to creating opportunities for others. The contrast is striking. We can generate software with a simple prompt, create sophisticated images from a sentence, and solve problems that once required teams of specialists. Yet many of the structural challenges that have limited opportunity remain firmly in place. Innovation alone does not guarantee progress. Real progress requires leadership, intentionality, and the courage to challenge the status quo. At Worth, we seek to convene conversations that matter, celebrate leaders who create lasting impact, and help our community navigate an increasingly complex world with confidence, perspective, and purpose. The institutions that endure are not those that resist change, but those that remain clear about who they are while continually evolving how they serve the people who depend on them. Leadership, after all, is not measured by how tightly we hold on to the present. It is measured by whether we leave the people, the organizations, and the ideas we care about stronger, more capable, and better prepared for what comes next. Artificial intelligence is changing what is possible, but it remains our responsibility to decide what is worth building and who benefits from what we build. Technology may be moving at an unprecedented pace, but leadership remains, and always will be, a profoundly human endeavor. The distance between imagination and execution has never been shorter. That makes vision, judgment, and character more important than ever.
— Josh Kampel C E O, WO RT H M E D I A
josh.kampel@worth.com
E DITOR ’ S LE T TE R
Get In the Room!
In today’s algorithm-driven world, getting to the right people is more important than ever. BY DAN COSTA
“F
ace-to-face conversation is the most human—and humanizing—thing we do.” Sherry Turkle, the MIT professor who has spent four decades studying what screens do to us, wrote that in 2015. This was when machines could only interrupt our conversations. Now they can conduct them. Meetings arrive presummarized. Emails are drafted by software and, increasingly, read by software. Which makes the premise of this issue, and of everything Worth is doing this fall, feel more impactful: there is power in being in the room. Not influence, not reach, not engagement. Power. The kind that moves capital, settles arguments, and decides who gets a say. Deals are announced in press releases, but they are made in hallways. Anyone can watch a livestream; what the livestream cannot deliver is the person to your left. Every story in this issue is, one way or another, about a room and who controls it. And the consequences of *not* being in the room.
12
FA L L 2 0 2 6
WORTH.COM
Start with the rooms you will never enter. “Who Pays for Data Centers?” the feature anchoring this issue, examines the buildings at the center of the AI boom: windowless, nearly workerless, and funded in part by you. The independent market monitor for PJM, the grid operator serving 13 states and Washington, D.C., points to data-center demand as a primary reason for $23 billion in customer price increases expected to run through at least 2028. Capacity costs in that market rose $9.3 billion in a single delivery year. Nationally, residential electricity prices have climbed 42% in five years, according to the U.S. Energy Information Administration. The hyperscalers get the compute. Ratepayers and taxpayers get the invoice. Power, in both senses, is concentrating in rooms designed to keep most people out. Then consider the women who got into the room the hard way. The Groundbreaking Women of 2026, this issue’s other centerpiece, profiles leaders remaking business, finance, media, health, and policy. Karen S. Carter took over Dow this summer, the first woman and the first Black woman to lead the company in its 126-year history. Daniela Amodei co-founded Anthropic and pre-
sides over one of the handful of labs deciding what AI becomes. Luana Lopes Lara, a former professional ballerina, built the prediction market Kalshi and became the world’s youngest selfmade woman billionaire. Shirley Chisholm’s famous advice was that if they don’t give you a seat at the table, you bring a folding chair. These are the women who brought the chair, and, in many cases, are now running the table. On September 15 in New York, our Groundbreaking Women summit offers an exclusive opportunity to explore how power is built: access to capital, representation in media, and industry influence. Three weeks later, on October 6, Techonomy 26 in the San Francisco Bay Area offers a chance to ask who really pays for data centers, emphasizing the importance of being in the room where change happens and decisions are made. Some things can only happen in person. You cannot skim a person the way you skim a feed, making in-person meetings essential for meaningful engagement. One piece of good news. Getting into these rooms is a little easier than it was for the women on the Groundbreaking Women list. Both gatherings are invitation-only, but Worth readers, as always, have preferential access—no folding chair required.
— Dan Costa E D I TO R I A L D I R E C TO R
dan.costa@worth.com
J E T C A R D S I C H A R T E R I F R AC T I O N A L & W H O L E OW N E R S H I P
M AG E L L A N J E TS .CO M +1 (877) 550-5387 (JETS)
CONTRIB UTORS
Stephanie McNally MD Stephanie McNally, MD, holds a unique and synergistic role at Northwell Health, the largest non-profit health system in the Northeast United States. She serves as the Medical Director for the Katz Institute for Women’s Health, the System Director for the Center for Menopause and Midlife Health, and Vice President of the OB/GYN Service Line. In this position, she initiates change across multiple disciplines to bring about the best clinical outcomes with the highest quality and innovative programs, including the creation of multi-disciplinary women’s health care centers. As the System Clinical Lead for Northwell’s Center for Menopause and Midlife Health, she is working to create a standard of care in the perimenopause and menopausal space—from treatment to research. Dr. McNally also co-founded and co-directs Northwell Health’s first female physician leadership program. The CALLS (Career Advancement Learning Leadership and Strategy) Program is Northwell’s first two-tiered program for mentors and high-level advocates for female physicians 2-5 years out of training. Dr. McNally has been a featured lecturer within the industry and has been invited to give webinars and grand rounds at regional, national, and international meetings. She is also an Associate Professor Donald and Barbara Zucker School of Medicine at Hofstra/ Northwell.
Nora Walsh Nora Walsh is an award-winning journalist and podcast host specializing in luxury travel, wellness and longevity. She writes for national newspapers and magazines focusing on experiential travel, destination guides, hotels, spas, dining and design. Her work appears in the New York Times, Wall Street Journal, AFAR, Travel + Leisure, Conde Nast Traveler, Robb Report, Forbes, Food & Wine, National Geographic Traveler, Vogue, among others. As a certified yoga instructor and mindfulness meditation teacher trained by Jack Kornfield and Tara Brach and accredited by UC Berkeley’s Greater Good Science Center, Nora offers customized mindfulness courses, workshops and retreats that support well-being.
Tim Stevens Tim Stevens is a freelance automotive and technology journalist with more than 25 years of experience. He is a frequent contributor to major domestic and international online, print, and broadcast news outlets including MotorTrend, TechCrunch, Wired, CBS and the AP, sharing his insights and perspectives on everything from cybersecurity to supercars.
14
FA L L 2 0 2 6
WORTH.COM
AUTO
This Electric SUV Is Porsche’s Most Powerful Car Ever Driving the new, 1,139-horsepower Cayenne Coupe Electric. BY TIM STEVENS
S
port utility vehicles are supposed to be mainstream offerings for mainstream buyers. They’re go-anywhere and do-anything machines that can haul your kids and cargo to all manner of destinations, both epic and mundane, with a good degree of comfort and compliance along the way. Some SUVs lean harder into the sport part of the acronym than others, but Porsche has pushed its latest to the extreme. It’s the new Cayenne Electric, and in Turbo form, it’s the most powerful production Porsche ever. That’s right, all those wild, bewinged widowmakers over the years have less performance than this relatively humblelooking four-door, two-row electric SUV. It is, of course, remarkably quick, and the Cayenne’s new interior is plenty charming as well, but the experience isn’t entirely perfect across the board.
16
FA L L 2 0 2 6
WORTH.COM
TRIMS AND OPTIONS As is typical for all things Porsche these days, you can get yourself a Cayenne in a variety of configurations to suit your needs for power. It starts on the low end with the base Cayenne Electric, which makes 435 horsepower and 615 pound-feet of torque from a pair of electric motors, one at the front and another at the back, to give it all-wheel drive. Step up to the Cayenne S and the power jumps substantially, delivering 657 hp again to all
four wheels. Finally, there’s the maximum-performance, headlinegrabbing Cayenne Turbo, which produces an astonishing 1,139 hp. To deliver that kind of power, the Turbo relies on a rear motor with an advanced design borrowed from motorsport. It has an internally cooled stator, keeping the coilwrapped part that creates the magnetic field from overheating. This configuration was developed for Porsche’s racing efforts in Formula E, making it perhaps the most significant example of
technology developed in that fledgling all-electric series that made it to the road. All Cayenne electrics are powered by the same 113-kilowatt-hour battery pack, situated down in the floor of the SUV, as is de rigueur in modern EVs. Porsche still hasn’t quoted official EPA range estimates for any of these SUVs, but you can expect somewhere between 300 and 350 miles, depending on which configuration you go with.
“All those wild, bewinged widowmakers over the years have less performance than this relatively humble-looking four-door, two-row electric SUV.”
AERO-MINDED DESIGN Beyond the power output and range, you have another big decision to make in pondering a Cayenne Electric: What shape do you want? Porsche will sell you either the typical SUV style with a longer roof and more upright rear end, or what it calls the Cayenne Coupe, which lops a little off the back to give it a sportier look and a slightly more aerodynamic shape. Having driven both, I can tell you there’s nothing between them from an outright feel and performance standpoint. Even the rear headroom in the Coupe is quite acceptable. It’s just a necessary reduction in cargo capacity for the shorter-roofed version: 18.9 cubic feet behind the rear seats in the Coupe, down from 27.6 in the SUV. Still plenty for a weekend getaway with the fam. In either profile, the Cayenne isn’t exactly eye-catching from afar, but it is littered with sharp design elements and details that make it a good-looking SUV up close. All models get a pop-up spoiler or wing at the back that deploys at highway speeds, but only the Turbo gets some additional appendages situated vertically in the rear bumper. These deploy outward and to the rear, subtly lengthening the Cayenne’s aerodynamic profile to reduce drag and, therefore, increase range. I’m inclined to think they’re a better conversation piece than a functional piece of equipment, but they certainly do look cool.
TECH BOOST INSIDE Porsche hasn’t just grafted the new Cayenne Electric with more power than any other machine in its history. It’s also seen a strong infusion of tech throughout, most notably in the new dashboard design, which features a weirdly kinky center touchscreen. That display looks like it was left in the sun a little too long and has slid down the dashboard, but it was a conscious design decision to create a touchable surface that’s both easy to read and easy to tap while driving. You can set your hand on a palm rest just below the display and manage the most frequently used controls on the bottom. Key information like maps or media displays higher up on the display. At first glance, I thought this would be a horrible user experience, as it just looked a little too odd to me. But, after spending a day behind the wheel, I decided I quite liked it. It’s much more ergonomic than your average automotive touchscreen, yet still easy to use, and Porsche’s latest software ensures the interface keeps up with your intents. You can use both Android Auto and Apple CarPlay wirelessly with the Cayenne, and there’s wireless smartphone charging too, but there’s some rather more significant wireless charging happening underneath the car. Buyers can opt for Porsche’s wireless charging pad for their garage, which can juice up the SUV at 11 kW. That’s only about 10% slower than regular, wired athome charging. When equipped, the Cayenne automatically detects when you’re near the pad and displays a sort of targeting reticule on the center display to help you park in the perfect spot. It’s not quite as cool as nailing an ok three wire on a carrier landing as a naval aviator, but I wouldn’t blame you if you fired up the Top Gun soundtrack just the same.
WORTH.COM
FA L L 2 0 2 6
17
AUTO For charging when you’re not at home, the Cayenne features an 800volt architecture capable of charging at 400 kilowatts. That means an 80% charge in just 16 minutes. DRIVE TIME It probably goes without saying that the Cayenne Turbo is quick. Launch the thing from a standstill, and it can get to 60 mph in just 2.4 seconds, which is the kind of performance figure that is more uncomfortable than thrilling. More impressive is that it’ll absolutely leap forward at just about any speed, the kind of urgency that makes even the quickest of cars with internal combustion feel tame by comparison. The lower-spec Cayenne S feels very nearly as quick in everyday driving, and even the base Cayenne Electric has plenty of performance. I was expecting all that. What I wasn’t expecting was how harsh the base car feels compared to the higher trims. While all Cayenne Electric models have adaptive air suspension as standard, only the S and Turbo offer Porsche’s optional Active Ride suspension. This takes adaptive damping to a new level, not only dynamically adjusting the feel of the suspension to suit conditions and drive modes, but also dynamically leaning the car into corners and even raising the nose under braking to give a less disruptive and more stomachfriendly ride to your passengers. Porsche’s Active Ride delivered a wonderfully smooth ride over the worst asphalt imperfections I could find, even though the Turbo I drove was wearing 22-inch wheels and aggressive summer performance tires. That all-round, mega-SUV dominance comes at a cost, of course. The electric Cayenne Turbo I drove cost a whopping $220,330, nearly doubling the base model’s $113,800 entry price. But with its combination of neck-snapping power and roadsmoothing suspension, this might just be the pinnacle of sporty SUVs.
18
FA L L 2 0 2 6
WORTH.COM
Lasting legacies are built with intention
Families with significant wealth often face their most complex decisions together. Those conversations aren’t always easy, but they’re among the most meaningful. At Edward Jones Generations®, we help families navigate them with experience, empathy and a long-term perspective that reflects a shared commitment to a future grounded in what matters most. One of the greatest acts of stewardship is preparing the next generation.
Learn more about Edward Jones Generations at generations.edwardjones.com or speak with a financial advisor about building your family’s legacy together.
GEN-23565-A-E-AD EXP 31 AUG 2027 © 2026 EDWARD D. JONES & CO., L.P. ALL RIGHTS RESERVED. AECSPAD
Edward Jones Generations® is offered through Edward Jones, a dually registered broker-dealer and investment adviser. Clients of the Edward Jones Generations offering may be referred to Edward Jones Trust Company (EJTC) for trust and related services. EJTC is a federally chartered savings association and an affiliate of Edward Jones.
YA C H T S
All Aboard the Auction Block Superyacht sellers have a habit of holding out for the impossible number. This upstart auction house says the smarter move is to just let the market decide. BY JONATHAN RUSSO
T
here’s a house next door that has been for sale for seven years. Every year the Memorial Day issue of the local paper features the house; the price remains the same. The late Milton Friedman, the father of market pricing efficiency, would have been horrified. He believed in pricing to clear the market. If you thought real estate pricing was illogical (Bill Koch’s Aspen house just sold for $33 million—the original listing was $125 million), the pricing of yachts, and especially superyachts (boats over 100 feet), is even more so. The leading superyacht publication, BOAT International, runs a feature in every issue called “Seriously for Sale,” showcasing price drops by motivated sellers—sometimes a $60 million yacht will carry an $8 million reduction. It’s not unusual to see a yacht listed in a September issue of a yachting magazine, and then see that same listing again every month... seemingly forever. Much of the problem is structural. Many superyachts are custom, from the design of the exterior and interior to the naval architecture and the yard where they were built. Luxury goods in general suffer from a lack of comparables, and the resale value of unique or custom products tends to be set by the owner, who usually has an emotional investment in the number. Pricing and sales both suffer for it. The ultra-wealthy, simply put, are rarely under pressure to sell. Into this small and truly intimate world of major yacht sales comes Boathouse Auctions (BHA). Its founder, Jack Mahoney, a yachtsman himself, ardently believes that the auction process—usually associated with the world of art—is a far more efficient way to transact the sale of a yacht.
20
FA L L 2 0 2 6
WORTH.COM
Many of the steps in BHA’s process are identical to the traditional brokerage model. Most interestingly, though, BHA only works with brokers. “The role of the brokerages enhances the return to the seller, and we do not auction yachts without the participation of the listing brokers,” Mahoney told me. Here’s how it works. First, all the relevant stats on the yacht are collected—everything from the original construction drawings to actual engine hours, refit and modification history, and condition. Value surveys are conducted. Extensive photos are taken, with an emphasis on unique exterior and interior features. Video has become almost standard, with elaborate 3-D walk-throughs the most informative of all. Remember, buyers can come from anywhere, and they’re not going to travel halfway around the globe unless they’re convinced this may be the yacht for them. Once all the data is in one place, two things happen simultaneously. The first is an agreement on whether to use a reserve or no-reserve auction approach. The second is completion of the bid package and the setting of an auction date. The original listing broker makes all of this happen, just as they would for any sale. The auction approach is the keystone of the entire process. BHA and the broker—and by extension the yacht owner—must agree that if this
price is met, the boat will be sold. Since the vast majority of boats that come to BHA have already been on the market for an extended period, realistic pricing is the catalyst that triggers an offer. “We refuse quite a few yachts because the seller insists on an unrealistic price,” Mahoney says, “and we just can’t take those to market.” Usually, a yacht captain, buyer’s broker, or charter manager inspects the yacht when a potential bidder is unavailable to do so. Then the complete sales packet is distributed online, and a date is set for the auction. Packets are sent to other brokers, acting as buyer’s brokers, asking them to alert their clients to a potential opportunity to purchase a yacht at a realistic price—or, hopefully, at a significant discount. All the traditional fee splits between brokers are outside BHA’s purview, as brokers receive a fee for their auction services from the buyer. Then, in real time, online, watchable on a cell phone or computer, the auction begins. All bids and
price improvements are transparent, ensuring there isn’t any inside or hidden information. Bidders are preregistered and vetted. Deposits are put in escrow to ensure that a winning bidder fulfills the transaction. The highest accepted bid is final, and closing must happen within 30 days or less. Founded in 2018, BHA’s growth rate is nearly 100% per year. To date, about 80 boats have been auctioned. Mahoney estimates this represents only “1-2% of the $8 billion previously owned superyacht market, so for sure we have lots of room to grow.” Kevin Merrigan, chairman of Northrop & Johnson, a top-tier brokerage, offered his own perspective. Merrigan recently worked with BHA on the sale of Serengeti, a 130’ Westport powerboat. “Auctions are just another arrow in your quiver as a broker,” he says. “Our job is to act in our clients’ best interest, and sometimes an auction is the right way to do it. They tend to expedite a sale.”
“Auctions are just another arrow in your quiver as a broker. Our job is to act in our clients best interest, and sometimes an auction is the right way to do it. They tend to expedite a sale.”
Mahoney sees the primary challenge facing yacht auctions not as the process itself, but as a misunderstanding of the economics behind an accelerated sale. “Too many sellers focus solely on the asking price and overlook the true cost of time,” he says. “When a yacht remains on the market for months or years, the owner’s opportunity cost and substantial carrying costs quickly erode wealth. We help sellers and brokers recognize that a time-certain sale can frequently produce a stronger financial outcome by converting a depreciating asset into liquidity far sooner than a traditional listing.” As in the art world, sometimes there is a bidding war—and when that happens, the sales price can far exceed the agreed-upon reserve. “This happens from time to time,” Mahoney observed, “and the seller really benefits.” As for the opposite scenario, when no bidder meets BHA’s reserve price, “That happens,” he says, “but we operate at about an 80% success rate, which is rather high for an auction house.” WORTH.COM
FA L L 2 0 2 6
21
BARCELONA
Barcelona by Design A century after Gaudí’s death, art remains the clearest way into the city.
B
arcelona has always made its history visible. Every era that ruled the city left something you can still stand in front of—the Romans who laid the first grid, the medieval builders who raised the Gothic Quarter stone by stone, the Modernist architects who turned the turn-of-the-century boom into façades that seem to breathe. No one understood that better than Antoni Gaudí, whose buildings remain the most extreme expression of Barcelona’s belief that art and architecture are how a place declares who it is. This year, that belief is everywhere: 2026 marks the centennial of Gaudí’s death, and the city has spent the year in tribute. It is the perfect time to visit. WHAT TO DO It was the 100th anniversary of Gaudí’s death on June 10, and dedications and celebrations spread across the city. The Tower of Jesus Christ, the basilica’s tallest spire, was structurally completed on February 20, 2026, bringing Sagrada Família to its full height of 172.5 meters and making it the tallest church in the world; Pope Leo XIV led a ceremonial blessing to mark the occasion. But “finished” is relative—interior work on the tower continues through 2027 and 2028, and the Glory Façade, the
22
FA L L 2 0 2 6
WORTH.COM
main entrance, isn’t expected to be complete until 2034 or 2035. The building has been under construction for 144 years and counting, which is either the least or the most Barcelona thing about it, depending on how you look at it. Book an early morning audioguided tour where the detail and level of obsession behind the design reveal themselves up close. To understand not only the architect’s evolution but also that of Barcelona, a walking tour of Gaudí’s lesser-known work provides perspective. Casa Vicens, Gaudí’s first com-
missioned work, was a summer house designed for a wealthy tile and brick merchant. Completed when Gaudí was in his early 30s and already rejecting architectural convention, the house shows him working out his visual language before he fully found it, which makes it a fascinating place to start. From there, tracing his work through the city becomes its own kind of map: Casa Batlló on the Passeig de Gràcia, its facade so encrusted with scales and curves that locals call it the House of Bones; Casa Milà just up the street, all undulating stone and surreal rooftop warriors, was his last secular building. Following Gaudí through the neighborhoods is a way to understand the city’s ambition. In the late 19th and early 20th century, Barcelona was asserting itself culturally, economically, and politically—and Gaudí was the most extreme expression of that energy. The Modernista movement wasn’t just aesthetic; it
I M AG E CO U RT E SY O F T R U
BY KIRSTEN CLUTHE
was Catalan identity making itself visible in stone. The men who commissioned his buildings—Güell, Batlló, Milà—were the industrial bourgeoisie who built modern Barcelona, and their choices tell you exactly who had power and what they wanted to signal with it. WHERE TO EAT AND DRINK Barcelona’s food scene has evolved dramatically in the last two decades. When elBulli, Ferran Adrià’s legendary restaurant up the coast, closed in 2011, the talent dispersed and Barcelona absorbed it. Younger chefs reconnected with Catalan tradition, natural wine bars multiplied, and serious coffee finally arrived. The city that once felt like a backdrop to one chef’s culinary revolution turned out to have plenty of its own. Bar Alegria Gràcia, Gràcia— the sister spot to the popular Bar Alegria, headed by chef and restaurateur Tomás Abellán, serving contemporary tapas and small plates in what was formerly restaurant Can Tosca. The room feels exactly like Barcelona is supposed to feel: neighborhood-y, lively, warm, and buzzy. Reservations are essential.
TRÜ, L’Antiga Esquerra de l’Eixample—a new project from chef Artur Martínez, and a standout. Martínez temporarily closed his Michelin-starred restaurant Aürt to find a better location, and TRÜ is where he and his team are cooking in the meantime. Their modern riffs on traditional Catalan dishes are inventive, gorgeous, and delicious. The kitchen—visible from the dining room—is the epitome of chill focus, and the restaurant carries a cool but approachable vibe. Ask the server for recommendations: our server described the Mediterranean rockfish soup as something his grandmother would have made, though the version on the plate is anything but traditional. The wine list also delivers, with enough variety to match the dishes on the menu. Here, we also asked for a recommendation and were surprised by a light red from Mallorca called Soca-Rel. Martínez, Montjuïc—Martínez is a chic, high-end “chiringuito” (beachstyle shack) overlooking the city, and the views are stunning. Mussels and paella are excellent here, and at 62 euros, the tasting menu with wine is a worthwhile way to go. Before dinner, walk the gardens of the five-star Hotel
Miramar Barcelona, an urban resort tucked into the Montjuïc hillside, where the grounds look out over both the Mediterranean and the city—a good spot to sit above Barcelona and watch the light change over the water before dinner. Lascar 74, Poble Sec—a ceviche and pisco bar located in the lively El Poble-sec neighborhood known for its high-energy, intimate vibe and masterful Latin American-Asian fusion seafood. A neighborhood favorite that is anything but touristy. Bar Pimentel, El Born—chic and vibrant, Bar Pimentel is tucked into the heart of El Born. An elevated homage to traditional Catalan market cuisine, serving up modern dishes like patatas bravas and razor clams to pair with the wine of the day—for us, it was a perfectly chilled Catalan rosado, which truly helped offset the summer heat. La Violeta, Barceloneta—in the Ciutat Vella district, one of the city’s best wine bars: rustic and unpretentious, with a fantastic list and the best gazpacho around (the rest of the food is equally good). Time your visit for ver-
WORTH.COM
FA L L 2 0 2 6
23
BARCELONA
mouth o’clock, typically noon to 2 p.m. Served over ice, usually with a splash of soda and an olive or a slice of orange, the drink comes with something small to eat—anchovies, chips, olives, or a bite of cheese. The point isn’t the drink exactly; it’s the pause. A reminder to stop moving for an hour or two and watch the city go by. DAY TRIP: PENEDÈS WINE COUNTRY A day trip worth adding to any Barcelona itinerary: Penedès wine country, an hour by train from the city. Penedès has a winemaking history that stretches back roughly 2,700 years, to Phoenician traders who first planted vines here—one of the oldest wine cultures in Catalonia, if not quite Spain’s oldest (that distinction belongs to Jerez, settled by the Phoenicians a few centuries earlier). The vineyards here today, however, are considerably younger: phylloxera wiped out most of the region’s plantings in the late 1800s, forcing a near-total replant
24
FA L L 2 0 2 6
WORTH.COM
that also shifted the region from mostly red grapes to the white varieties now used in cava. Familia Torres, founded in Vilafranca del Penedès in 1870 and now run by its Forneration, is one of Spain’s most celebrated producers. For good reason: the estate’s 1970 Mas La Plana Cabernet Sauvignon beat a lineup of Bordeaux first-growths at a blind tasting in Paris in 1979 and put Spanish wine officially on the world map. The vineyard is so expansive it requires a tram to drive visitors around the property, cutting through terraced rows that climb from the coast toward Montserrat’s jagged silhouette on the horizon. The visit ends with a four-glass
“Following Gaudí through the neighborhoods is a way to understand the city’s ambition.”
tasting paired with tapas bites. The tasting draws from vineyards spanning sea level to 700 meters in the Upper Penedès, a range that explains the breadth of what the region produces in a single afternoon’s driving distance. The place is always booked, so make a reservation, and plan to stay for lunch if a table opens up. WHERE TO STAY Hotel Arts Barcelona, a Ritz-Carlton property, occupies a 44-story tower on the seafront at Vila Olímpica, built for the 1992 Games and still one of the few true skyline landmarks the city allows itself. The location trades the Gothic Quarter’s tangle for direct beach access and unbroken sea views. Frank Gehry’s golden fish sculpture, El Peix, sits just outside; all 483 rooms have been fully reimagined in a recent redesign by Meyer Davis, and the two-Michelinstarred Enoteca, chef Paco Pérez’s dining room, anchors the food program.
Time, beautifully spent.
4 0 0 + LU X U RY R E S I D E N C E S & E X P E R I E N C E S . 7 5 + D E ST I N AT I O N S . 1 C LU B. exclusiveresorts.com Information current as of 08.11. 26. Club membership is subject to terms of Club Membership Agreement. Additional terms and conditions apply. E xperience Collection travel and European Villas are of fered by third par ties in collaboration with E xclusive Resor ts related par ties, including FDL Event Management, LLC which is registered as a seller of travel in the States of Florida, Hawaii, and Washington, and provides travel ser vices under Fla. Seller of Travel Reg. No. ST4 4910. Club membership does not provide or constitute any investment, equit y, or ownership interest, or any real proper t y interest. See E xclusiveResor ts.com for more information. E xclusive Resor ts and the E xclusive Resor ts flower logo are registered trademarks of E xclusive Resor ts, LLC. ©2026, E xclusive Resor ts, LLC. All rights reser ved.
WINE CLUBS
Wine Clubs Grow Up As the old shipping-subscription club fades, a sharper, curated version of membership is emerging as one of the wine industry’s clearest paths forward. BY KIRSTEN CLUTHE
T
he other day, I received a text message from an unknown number. The message was from Williams Selyem, a winery that has never used a storefront to sell anything. Their Fall allocation was opening soon, the text said, and prompted me to make sure my details are current, so I don’t miss out. It’s a small thing, a two-line nudge from a number I hadn’t saved. But it’s also an example of how the wine world is shifting: new release announcements are made via direct line to the customer who has become a member by signing up to be “on the list”. Williams Selyem has been operating this way, in one form or another, since 1987—long before “curation” was a word wineries reached for in marketing copy. Understanding why reveals something the rest of the wine industry is only now catching up to. For decades, the wine club worked the same way: sign up in a tasting room, get upsold into quarterly boxes of whatever the winery needed to move, and forget to cancel. Now, that supply is shrinking, and the model built on top of it is going with it. What’s replacing it looks nothing like what came before. THE NEW WINE CLUB The shift is visible in the numbers, but they’re really just confirming what’s already happening on the ground: the club is being rebuilt around access instead of volume. The old version shipped whatever was available and hoped members wouldn’t notice. The new version curates allocations of wine a member cannot buy anywhere else, guided by someone who knows the wine and, increasingly, knows the people behind it. That distinction is the whole story. It’s the difference between a subscription and a relationship, and it’s turning out to be the difference between wineries that are shrinking and wineries that aren’t.
26
FA L L 2 0 2 6
WORTH.COM
Large producers, selling primarily through wholesale distribution, saw direct-to-consumer volume drop 23% last year—a third straight year of underperforming the broader market, according to the 2026 Directto-Consumer Wine Shipping Report from Sovos ShipCompliant and WineBusiness Analytics. The smallest wineries, those producing fewer than 1,000 cases a year, saw volume dip just 5%, while the value of their shipments actually grew 10%, the same report found. Those are the wineries with no distributor to fall back on— almost entirely dependent on direct sales, whether shipped or sold out of the winery itself. Distributors make their margin on volume and velocity, moving cases through a warehouse to hundreds of accounts; a winery producing 800 cases a year simply can’t supply enough inventory to make that math work, no matter how good the wine is. So for the smallest producers, the list wasn’t a growth channel added on top of a wholesale business. It was the business, out of necessity, years before the rest of the industry started paying attention to that
model. What’s new is how many other wineries are being pushed toward the same setup—not by choice, but because the alternative is disappearing. Williams Selyem is one of the clearest examples of what this model looks like once it’s fully built out. Founders Burt Williams and Ed Selyem started the winery in a two-car garage in the 1980s, making wine in repurposed dairy tanks because they couldn’t afford real equipment. They had no tasting room, no storefront, and no outside capital, which meant there wasn’t a way for customers to walk in and purchase their wine. When their Pinot Noirs started drawing serious critical attention in the mid-1980s, demand outran what a few hundred cases a year could satisfy almost immediately. Selling through a distributor would have meant giving up margin they couldn’t spare and still not solving the basic problem: there wasn’t a place for anyone to buy the wine. So in 1987, after their Rochioli Vineyard Pinot Noir won the Sweepstakes Prize at the California State Fair, demand for a wine they were making only a few thousand cases of instantly outran supply. Ed Selyem started a handwritten register of customer names, not as a marketing strategy, but as a way to fairly divide a tiny amount of wine among the people already asking for it, and to lock in sales before the wine was even bottled. The wait to get on the list stretched to two or three years at its peak. By 1998, when the founders sold the winery, production had grown to around 8,000 cases—still nowhere near enough to satisfy demand—and the list wasn’t a supplement to a traditional sales strategy—it was the primary business. Today, the winery reports that roughly 95% of its wine still goes directly to list members. That’s the model in its most mature form: scarcity managed through relationships rather than through retail, built not out of ambition but because there was genuinely no other way to sell the wine. Distributor consolidation has been building for years, but 2025 delivered a
genuinely startling marker: Republic National Distributing Company, long the industry’s second-largest wholesaler, announced it was exiting the California market entirely, according to this year’s BMO Wine Market Report. Nearly a quarter of all wineries surveyed for that report said they’d lost a primary distributor in the past year. The club isn’t just competing with the retail wine shop anymore. For a growing number of producers, it’s replacing the distributor outright. Total U.S. wine spending actually grew 3% in 2025, to more than $115 billion, even as the market logged its second consecutive year of declining volume, per the BMO report. The pressure is sharper still in direct-toconsumer specifically, where volume has now fallen for four straight years, according to the DtC shipping
report—and the decline isn’t people trading up to better bottles. The membership on-ramp cuts both ways. It’s not just teaching new drinkers; it’s exposing longtime ones to producers they’d otherwise never encounter. Meghan Zobeck, who spent seven years negotiating player contracts for the Denver Broncos before leaving football for wine in 2012, worked her way through Screaming Eagle and years as winemaker at Burgess Cellars before Opus One named her its first-ever director of winemaking this year. Her day job is one of the most visible in Napa. Her own label, M. Zobeck Wines, is the opposite: a personal project sold entirely through her own list—I’ve been on it myself, and there’s no retail shelf where you’d stumble onto the wine—in quantities smaller even
than the sub-1,000-case tier discussed above; a single vintage of Gamay Noir came to just 107 cases, and a Cabernet Sauvignon to 42. It’s an extreme version of the same mechanism, but that’s what makes it worth noting: the same allocation model built out of necessity by a garage winemaker in 1987 is now, at its smallest scale, the only way to discover some of the most interesting winemaking happening today, regardless of how long someone’s been drinking or how deep their cellar already runs. Whether that rebuilding scales into something genuinely new is still an open question. A curated, allocation-based membership could become the on-ramp a skeptical, price-conscious younger drinker actually needs. In the current economy, finding a way to build trust in a $60 bottle before being asked to trust an entire cellar makes a lot more sense. Or it could settle into something narrower: a model that rewards people who already have the money and the relationships to get on the list. At the same time, everyone else is left with whatever’s still on a shrinking shelf. Much of the industry frames this as a recovery story. The BMO report found 71% of wineries surveyed expect the broader market to improve within three years. But “recovery” implies a return to something, and it’s not clear that’s what’s actually underway. What the numbers describe looks more like survival: producers figuring out, in real time and without a guarantee it pays off, which parts of the old model are worth keeping and which ones simply aren’t coming back. Membership, done well, is one of the few things so far proving it can hold. The more interesting question isn’t whether wine recovers. It’s whether the version of the industry that makes it through this stretch is one built to bring in the next generation of drinkers—or just built to keep serving the ones who already found the list.
WORTH.COM
FA L L 2 0 2 6
27
20 Groundbreaking Women A trillion-dollar valuation, a century-old math problem, and a billion hours of streaming. This year’s 26 honorees have nothing in common except how they got there. BY EVA CROUSE
T
his year, after coming back to the sport she’d quit, on terms she set herself, Alysa Liu ended a 24-year American drought, winning figure skating’s first individual Olympic gold since 2002. Maggie Kang made the movie she wishes she’d had at 12; it became the most-watched film in Netflix’s history, seen 682 million times, proof that a story built around K-pop and Korean folklore was never the niche bet the industry assumed. Rhiannon Giddens finished an album that refuses to let a hundred years of erased musical history stay erased. If you ask enough accomplished women what advice they’d offer their younger selves, the answer is almost always some version of the same four
28
FA L L 2 0 2 6
WORTH.COM
2 06 words: stay true to yourself. It’s the most common piece of advice there is, and perhaps the least useful—until you actually learn to embody it. The longer you sit with these stories, the clearer the throughline becomes. It may arrive in different clothes, but the pattern is the same—in field after field, year after year. The women finding the most success are finding it through authenticity: embracing joys that were once laughed at, reclaiming time that was once commandeered, and standing by values that were once dismissed. Today, in Worth’s 2026 Groundbreaking Women list, we bring you 26 stories—26 women who have continued the work of your mother and grandmother, carving out space in a culture seemingly determined to undo their progress. That’s what this list is actually for, not just to celebrate what these women accomplished, though they’ve earned every bit of the applause, but to put proof on the record for your daughter. Your granddaughter. You.
WORTH.COM
FA L L 2 0 2 6
29
G ROU N DB RE AKING WOM E N
Lisa Anderson CO-FOUNDER & FORMER PRESIDENT & CEO, PARAGONIX TECHNOLOGIES, INC.
Daniela Amodei
Lisa Anderson was studying type 1 diabetes when she got her first look at how a donor pancreas travels: sealed in sterile bags, dropped into a cooler, and packed in crushed ice. She called the organ procurement agency to ask if they could package it more carefully next time. There was a long pause. “Yeah, we kind of did,” they told her. The method hadn’t changed since organ transplantation began, more than 70 years before. She left her research career at Harvard and the Broad Institute to found Paragonix Technologies in 2010, then spent nearly a year shadowing donor and transplant teams across the U.S. and Europe before asking her engineers to beat a box of ice. Paragonix’s devices now use a passive, phase-change cooling technology that needs no battery or power source, paired with real-time tracking. Nearly half of all donor hearts and a third of all donor lungs in the U.S. now travel in a Paragonix device. In 2025, the company launched KidneyVault, the first portable system built specifically for kidneys. It was acquired by Getinge for $477 million.
Daniela Amodei isn’t an engineer by training. Her degree is in English literature, and she got to UC Santa Cruz on a classical flute scholarship—a very unlikely résumé for someone now running the operational core of a nearly trillion-dollar AI company. By 2020, she was OpenAI’s VP of Safety and Policy, inside the lab that would go on to launch ChatGPT and ignite the generative AI boom. Two years later, she and her brother Dario, then OpenAI’s VP of Research, walked away anyway in late 2020, convinced the safety commitments they’d been hired to build were nothing but rhetoric. Anthropic launched a month later, in January 2021. The division of labor between the Amodei siblings is a classic duo: Dario is the technical visionary; Daniela turns that vision into company that actually runs. Under that structure, Anthropic’s run-rate revenue went from $9 billion to $47 billion in five months. In May 2026, the company closed a $65 billion round at a $965 billion valuation—edging past OpenAI’s own $852 billion mark—and by June had confidentially filed for an IPO. Between them, the company she left and the one she built are worth close to $1.8 trillion: the twin engines of an industry that barely existed when she walked out the door. The industry likes to frame safety and speed as a trade-off. Amodei has spent five years building her counterargument.
30
FA L L 2 0 2 6
WORTH.COM
GETTY
PRESIDENT & CO-FOUNDER, ANTHROPIC
Yasmin Barkett
CO-FOUNDER, READ ON YOUR OWN (ROYO)
Eliza Blank
GETTY
CEO, THE FARMLINK PROJECT The irony of the hunger problem in the U.S. is that we have enough food. What’s missing is the systemic infrastructure to make sure it ends up where it’s needed most. The Farmlink Project is a nonprofit built to fill that gap. It started in 2020, when two college students, sent home during COVID, saw struggling food banks on the news and began cold-calling farmers whose buyers had disappeared, offering to move their surplus produce to the banks. They thought they’d move a million pounds. They hit that number in weeks. After 12 years building The Sill, the houseplant brand she founded at 26, Eliza Blank was named Farmlink’s CEO. Six years after its founding, Farmlink runs on relationships: a network responsive enough to match a rejected truckload of tomatoes with a food bank within 48 hours, before the produce goes bad. What Farmlink supplies is the logistics; it organizes and pays for a nationwide network of contracted drivers, and has a network responsive enough to make matches in a matter of hours. Since 2020, that network has moved more than 500 million pounds of food, and Farmlink raises the money to cover transportation costs the donors and food banks it serves can’t afford themselves.
When Yasmin Barkett moved from teaching kindergarten to second grade, she found that her students’ reading levels, even within the same classroom, ranged from preschool to well above grade level, and she had no way to give each of them the attention they needed. After digging into it, she realized that there was no one-size-fits-all answer. That reading level gap she noticed is a national problem: on the most recent federal reading assessment, only 31% of American fourth graders scored “proficient” in reading, and 40% fell below the basic aptitude benchmark—the worst showing in over two decades. The type of instruction that’s proven to close that gap, like the phonics-heavy small-group model, requires two teachers per classroom and resources most public schools don’t have. So, she built the resource. In 2024, Barkett co-founded ROYO with Lara Pinto Stein: a platform that listens to a child read aloud, catches errors in real time, and serves up books matched to their exact phonics level. It also increases engagement by letting them pick the topic and see themselves as the story’s avatar. In 2026, on $2 million in seed funding, it’s reached 3,000 teachers and roughly 10,000 students nationwide. Barkett is clear that it’s not a replacement for a teacher. It’s the second teacher most classrooms will never be able to afford.
Sarah Haacke Byrd CEO, WOMEN MOVING MILLIONS Before she was moving millions, Sarah Haacke Byrd was trying to get hundreds of thousands of rape kits out of evidence lockers and into labs. As managing director of the Joyful Heart Foundation, which was founded by Mariska Hargitay (featured below), she helped convene survivors, legislators, law enforcement, and funders around a fact most people found hard to believe: A huge share of the kits collected after a sexual assault were never tested. Haacke Byrd’s campaign raised roughly $169 million and helped pass 35 new laws across 26 states. She carried that force into Women Moving Millions, where she became CEO in 2018. The requirement to join is pretty blunt: every member must commit at least $1 million to causes benefiting women and girls. Since its founding in 2007, WMM has moved more than $1 billion. Haacke Byrde’s goal is to move a second billion over the next five years. She’s making good progress, too. In 2025 alone, the network mobilized $220 million, and since she joined as CEO, she’s has directed over $1.5 billion in new funding toward women and girls globally. WORTH.COM
FA L L 2 0 2 6
31
G ROU N DB RE AKING WOM E N
IMMUNOLOGIST At 3 a.m. on October 6, 2025, Mary Brunkow’s phone lit up twice with calls from Sweden. She assumed it was spam and muted it. Minutes later, an Associated Press photographer knocked on her door. She thought it was an elaborate scam until she got the Nobel Committee on the phone herself. The prize recognized work she’d done a quarter-century earlier, at a small biotech company. The immune system’s job is to attack foreign threats—bacteria, viruses, anything it doesn’t recognize. An autoimmune disease is when that system response starts turning on the body’s own healthy cells. Something has to hold the immune system back from making that mistake. Until now, we weren’t sure what that thing was. Brunkow traced it by researching one such autoimmune disorder, a fatal condition in mice, to a single broken gene —the last of twenty tested. That gene called the “peacekeeper.” When that gene is broken, it can cause all sorts of problems, not least of which is IPEX—a severe autoimmune disease in infants. The discovery opened an entire field. More than 200 clinical trials are now testing therapies built on it: boosting these peacekeeper cells to calm autoimmune diseases like rheumatoid arthritis and type 1 diabetes, using them to prevent the body from rejecting a transplanted organ, or, in cancer, disabling them so the immune system can attack tumors it was otherwise holding back from. She says of the discovery. “We knew we were doing something important.” It just took the rest of the world 24 years to agree.
Karen S. Carter
CEO, DOW
Karen Carter joined Dow in 1994 as a sales intern. She was named CEO on July 1, 2026—the first Black woman, and the first woman, to lead the 130-year-old chemical giant. She has spent that last 32 years at the company, climbing through sales, packaging, and manufacturing. She served five years running HR as Dow’s first chief inclusion officer; and command of its $23 billion packaging and specialty plastics division before she made COO. She took the job at a hard moment: Dow posted its worst quarter in years the same month she started, in the middle of a restructuring, layoffs, and plant closures across Europe. “It’s a blessing to be stressed by the thing you prayed for and hoped for,” she said in her first weeks as CEO.
Kirsty Coventry PRESIDENT, INTERNATIONAL OLYMPIC COMMITTEE Kirsty Coventry grew up in Harare, Zimbabwe. She competed at five Olympics between 2000 and 2016, winning seven of her country’s eight Olympic medals in swimming—including back-to-back 200m backstroke gold in 2004 and 2008—before retiring from swimming and turning to sports administration. In June 2025, she took office as the International Olympic Committee’s 10th president: the first woman, first Zimbabwean, and first African to hold the job, and the youngest to hold it in a century. She had served as Zimbabwe’s sports minister from 2018 to 2025. Eight months into the job, she ran her first Games as president. Milano Cortina 2026 opened February 6 and closed February 22, with Coventry noting it a truly successful edition of record global engagement. She’s already looking forward, toward Los Angeles 2028.
32
FA L L 2 0 2 6
WORTH.COM
TO P I M A G E , A N G I L E W I S S T U D I O S G E T T Y / OT H E R S , G E T T Y
Mary Brunkow
Dr. Canan Dagdeviren
GETTY
ASSOCIATE PROFESSOR, MIT MEDIA LAB In 2015, Canan Dagdeviren’s aunt was diagnosed with breast cancer that her regular mammograms had missed. She died at 49, six months after the diagnosis. Before she did, she and Dagdeviren, then a postdoc at MIT, sketched an idea together: a device a woman could wear that would scan for cancer as often as she wanted, not just once a year in a clinic. Cancers that slip through between annual mammograms account for 20% to 30% of all breast cancer cases and tend to be more aggressive than those caught on schedule. Diagnosed early, breast cancer has a survival rate near 100%; diagnosed late, that drops to around 25%. That sketch became the cUSBrPatch, a flexible, honeycombed ultrasound patch that clips onto a bra and images the entire breast in seconds. In April 2025, it flew to space with Amanda Nguyen aboard Blue Origin’s all-female crew—the first since 1963. Dagdeviren now runs the Conformable Decoders lab at MIT Media Lab and leads its Women’s Health program; she was granted tenure this year, effective July 2026.
Rhiannon Giddens MUSICIAN, COMPOSER Rhiannon Giddens has spent her career correcting a persistent myth: the banjo isn’t Appalachian, or a hillbilly instrument. It’s African, developed by the Black musicians who created bluegrass music, before the recording industry segregated American music into marketable categories a century ago. She trained classically at Oberlin, headed for opera. Instead of immediately pursuing a career in opera, she went home to North Carolina and learned to play the banjo under Joe Thompson, one of the last Black string-band fiddlers of his generation. She co-founded the Carolina Chocolate Drops, and has spent two decades proving that American roots music left out the people who built it. That work reached its fullest expression in Omar, the opera she cocomposed about a Senegalese scholar whose Arabic-language autobiography, written while he was enslaved, is one of the few slave narratives in a non-European language, and among the rare firsthand records of an enslaved African Muslim’s inner life. It won the 2023 Pulitzer Prize for Music, plus a MacArthur and multiple Grammys. Her newest album, “Hope Is the Thing With Feathers,” arrives September 18—its title lifted from Emily Dickinson, the poem about the bird that “sings the tune without the words” and never stops. She’s candid about the tension underneath it: the art she wants to make sits inside a business built to sell something else. Her answer has been to hold her line and trust people to respond to conviction, not compromise. She got the MacArthur and the Pulitzer doing exactly that—not despite refusing to bend, but because of it. WORTH.COM
FA L L 2 0 2 6
33
G ROU N DB RE AKING WOM E N
Mariska Hargitay ACTRESS & PHILANTHROPIST Mariska Hargitay has spent 27 seasons playing a “Special Victims Unit detective on Law & Order: SVU.” She didn’t become an activist because of the scripts she read on set. She became one because of the thousands of letters real survivors sent her, disclosing their own assaults after watching her on TV. In 2004, she founded the Joyful Heart Foundation to work on the actual system her character was a part of in the show. Its flagship campaign, End the Backlog, hit a milestone on May 1, 2026: after 16 years of state-by-state organizing, Maine became the last holdout to sign on, bringing all 50 states, Washington, D.C., and Puerto Rico under at least one pillar of rape kit reform. This September, she’ll host the Emmys—the first woman to do the job in 15 years.
Lisa Gelobter Lisa Gelobter is often credited with inventing the GIF. She didn’t—Steve Wilhite’s team at CompuServe built the format in 1987—but the myth persists because what she actually built was foundational: as Macromedia’s director of program management in the ‘90s, she led development of Shockwave, the platform that first brought real animation and motion to the web, laying groundwork for Flash and, eventually, HTML5. She spent the next two decades moving between media and government: helping launch Hulu, running product and technology as BET’s chief digital officer, then joining the Obama administration as the Department of Education’s Chief Digital Service Officer, where her team rebuilt the College Scorecard and helped fix HealthCare.gov’s application process. In 2017, she founded tEQuitable, a platform for reporting workplace bias and harassment, and raised more than $2 million for it—making her one of roughly three dozen Black women ever to clear $1 million in venture funding. In February 2026, Mayor Zohran Mamdani named her New York City’s Chief Technology Officer and Commissioner of its Office of Technology and Innovation.
34
FA L L 2 0 2 6
WORTH.COM
GETTY
CTO, NYC
Maggie Kang
DIRECTOR, WRITER, CREATOR, KPOP DEMON HUNTERS Growing up in Toronto, Maggie Kang hid her K-pop albums from her non-Korean friends because they thought the music was lame. Thirty years later, she created KPop Demon Hunters, which became the mostwatched original film in Netflix’s history—a 52-week, still-unmatched run atop its Global Top 10, with over a billion viewing hours—and has racked up 143 awards against 203 nominations. That’s on top of the Oscar for Best Animated Feature, a sweep of the Annie Awards, and a Grammy for one of the movie’s many now-famous songs, “Golden,” the first K-pop song to ever win one. Kang and producer Michelle Wong became the first female Asian winners in the category’s history. Accepting the Oscar, she told the audience she was sorry it had taken this long for people who looked like her to see themselves in a movie like this—and that the wait was over for whoever came next.
Luana Lopes Lara
MUSICIAN, FOUNDER, SERVICE95 BOOK CLUB
In December 2025, at 29, Luana Lopes Lara became the youngest self-made woman billionaire in the world—the fourth person to hold that title in five years, after Whitney Wolfe Herd (31, Bumble’s 2021 IPO), Taylor Swift (33, the first to earn it from music rather than equity), and Scale AI’s Lucy Guo (30, April 2025). Lopes Lara took it from Guo eight months later. She spent eight years training at a Bolshoi Ballet Academy in Brazil, then danced Swan Lake professionally in Austria, before studying computer science at MIT, where she met Tarek Mansour. In 2018, the two founded Kalshi, an exchange that lets people trade contracts on real-world events: elections, weather, the Fed’s next rate move. The premise was a hard sell until 2024, when Kalshi won federal approval to offer contracts on the U.S. presidential election— the first time in over a century that kind of betting had been legal in America. Its valuation then quintupled in six months, from $2 billion in June 2025 to $11 billion by December, then doubled again to $22 billion by this past May. It’s now seeking $40 billion. Lopes Lara’s 12% stake is what put her on the billionaire list.
Dua Lipa built Service95, her weekly culture newsletter, out of the same book recommendations she’d been sending friends since she was a kid— launched in 2022, well into a career that already included three Grammys and a run of global hits. It grew into a monthly book club that same year, then, in June 2026, into the Manifesto Library, a room of 100 banned and censored books inside Livraria Lello, the Porto bookshop that’s traced its history to 1869 and is regularly ranked among the world’s most beautiful. The collection is organized around four themes—Power, Control, Voice, Memory—and includes books pulled from school and library shelves somewhere in the world for their politics, race, or sexuality: Salman Rushdie’s The Satanic Verses, Margaret Atwood’s The Handmaid’s Tale, George Orwell’s Nineteen Eighty-Four among them. It’s a permanent installation, not a pop-up, housed in a new cultural space at Lello designed by the Pritzker Prizewinning architect Álvaro Siza.
CO-FOUNDER, KALSHI
GETTY
Dua Lipa
WORTH.COM
FA L L 2 0 2 6
35
G ROU N DB RE AKING WOM E N
Alysa Liu OLYMPIC FIGURE SKATER Alysa Liu hurtled into the public eye in February of 2026—on razor-sharp skates. With horizontally striped hair that looks as indifferent to gravity’s natural order as her jumps, Liu’s breathtaking performance, which earned her Olympic gold, is only half the story. For most of her childhood, the ambition wasn’t hers. Her father, Arthur Liu, fled China after organizing protests near Tiananmen Square, arrived in America with nothing, and built a law practice. Then, as a single father of five, all born via surrogate, he spent—by his own estimate—half a million to a million dollars turning his eldest, Alysa, into a champion: hiring and firing coaches, timing her with a radar gun rinkside, even disguising himself once to watch a session he’d been banned from. She became the youngest U.S. women’s champion in history at 13, small enough that she needed a lift to reach the top of the podium. “It was basically his business,” she’s said. “It wasn’t even really mine.” In a move echoing her dad’s rebellious spirit, she impulsively retired at 16 via a single Instagram post, then deleted the app so she wouldn’t see the reaction. She used her newfound freedom to hike to Everest Base Camp, road-trip with friends, and start at UCLA as a psychology major—for two years, she says, she didn’t think about skating at all. When she came back, she came back changed: she called her old coach herself and set her own terms—her music, her choreography, her training load, her diet. And in February 2026, she showed the world that she had enough determination to achieve excellence without anyone else pushing her up that hill—individual Olympic gold, the first American woman to take the title in 24 years, with a score of 226.79.
Lynn Martin Lynn Martin grew up coding on a Commodore 64 in Smithtown, Long Island, before majoring in computer science at Manhattan College and picking up a master’s in statistics from Columbia. She started at IBM’s financial services practice, then moved through a string of exchange and clearing jobs inside Intercontinental Exchange before becoming NYSE Group’s 68th president in January 2022. Four years in, she’s rewired what the 234-yearold exchange actually is. In 2025, she launched NYSE Texas, the first securities exchange to operate in the state; more than 100 companies dual-listed there in under a year. The same year, NYSE led the industry with $61 billion in capital raised in six months. American Banker named her one of finance’s 25 most powerful women in 2024. Now she’s presiding over what she calls a potential “super cycle” for public markets, with Anthropic and OpenAI both preparing IPOs on the heels of SpaceX’s record-setting one. The exchange floor she runs is about to price the AI boom.
36
FA L L 2 0 2 6
WORTH.COM
GETTY
PRESIDENT, NYSE GROUP
Tekedra Mawakana CO-CEO, WAYMO
Bridgit Mendler
GETTY
CEO & CO-FOUNDER, NORTHWOOD SPACE Bridgit Mendler came to fame on the Disney Channel show, “Good Luck Charlie.” She played a teenager who records video diaries for her baby sister to watch once she’s old enough to understand them—a show built entirely around the idea of leaving guidance for someone coming up behind you. While filming for “Good Luck Charlie” and exploring a potential career as a singer-songwriter with singles like “Ready or Not,” Mendler had been quietly taking undergraduate courses on the side. While filming a movie in Massachusetts, she visited MIT on an off day, and ended up talking her way into the Media Lab. She went on to earn her master’s there—followed by a JD from Harvard Law. To fans who’d only ever seen her on a Disney Channel set, it looked less like a career pivot than a complete chataacter rewrite. It wasn’t. The realization brought her to found Northwood Space came in law school, working on a Starlink terminal project for rural Alaska. She read a public comment from a school describing how transformative satellite internet would be for its students. Most people, she’s pointed out, think the future of space is Mars. She’d found something that mattered more: what space could already be doing for people on Earth, right now, if the infrastructure existed to deliver it.
Tekedra Mawakana runs the only self-driving car company whose safety claims can actually be checked. When the Insurance Institute for Highway Safety, an independent nonprofit funded by insurers, tried to calculate real-world crash rates for autonomous vehicles this year, it could only do the math for one company: Waymo, the Alphabet-owned robotaxi service Mawakana has co-run since 2021. Cruise and Zoox, its two closest rivals, had crashes on the books but no public mileage data to measure them against. Waymo’s own driverless miles were public. The result: a 68% lower crash rate than human drivers, with even sharper drops in Phoenix and Los Angeles. That transparency coincides with the incredible scale she has been able to achieve. Waymo logged 15 million autonomous trips in 2025, more than tripling its 2024 total, and was handling more than 400,000 paid rides a week across six U.S. cities by early 2026—itself a tenfold jump from roughly 50,000 weekly rides two years earlier. Mawakana has said the company is targeting 1 million weekly rides by year’s end, alongside its first expansion beyond the U.S.: testing has been underway in Tokyo since 2025, and in London since this spring, with London positioned to be the company’s first international commercial launch. In February 2026, Waymo raised $16 billion at a $126 billion valuation— more than double the $45 billion valuation it held after its previous round 16 months earlier, and the largest funding round any autonomous vehicle company has ever raised. The company Mawakana runs looks nothing like the one she joined. Born in Mississippi in 1971 and raised across Georgia, Texas, and Virginia, she arrived at Waymo in 2017 as vice president of public policy and government affairs, tasked with building a legal case for self-driving cars that, at the time, didn’t really exist as a regulatory category. She’d spent the two decades before that inside the legal and policy departments of AOL, Yahoo, and eBay, after a law degree from Columbia and a political science degree from Trinity Washington University.he became Waymo’s chief operating officer in 2019, then, in April 2021, co-CEO—splitting the job with Dmitri Dolgov, who runs the engineering side while she runs the business, policy, and legal strategy. Her chief rival in the robotaxi business, GM’s Cruise, no longer exists: GM shut it down in December 2024 after burning through more than $10 billion. Tesla’s robotaxi effort remains far smaller in commercial deployment than Waymo’s, even with a vastly larger dataset of supervised-driving miles behind it. For now, at least, the market that once looked crowded has narrowed to whoever can prove, with real numbers, that the thing works.
WORTH.COM
FA L L 2 0 2 6
37
G ROU N DB RE AKING WOM E N
Gwynne Shotwell PRESIDENT & COO, SPACEX
38
FA L L 2 0 2 6
WORTH.COM
Emma Stone ACTOR At the 2026 Oscars, Emma Stone picked up two nominations for Bugonia—Best Actress for playing a pharmaceutical CEO convinced she might actually be an alien, and Best Picture as one of the film’s producers. That pushed her career total to seven nominations, making her, at 37, the youngest woman ever to reach that number—she beat Meryl Streep’s record by a year, and trails only Walt Disney, who got there at 34, among any gender. The double nomination is rare on its own. Only one other person has ever pulled it off: Frances McDormand, nominated for both acting and producing Nomadland in 2021. Stone has now done it twice—for Poor Things in 2024, and again this year for Bugonia— making her the first person to repeat the feat. Bugonia, her fourth collaboration with director Yorgos Lanthimos, is a strange one even by his standards: an adaptation of a 2003 Korean cult film about conspiracy theorists convinced their kidnapping victim is an alien. Stone shaved her head on camera for the part. It got a six-minute standing ovation at Venice.
GETTY
In 2002, Gwynne Shotwell had lunch with a former colleague who had just joined a startup called SpaceX. He gave her a tour of the offices afterward, and she spoke with the company’s founder, Elon Musk, for a few minutes. She wasn’t looking for a job. That afternoon, SpaceX called and asked her to apply anyway. She got the job, ultimately leaving a stable position at Microcosm, a small rocketry firm, where she held a 3% equity stake. She joined as one of the company’s first dozen employees, initially as vice president of business development, at a time when SpaceX had not yet successfully launched a rocket. Shotwell has been SpaceX’s president since December, 2008, overseeing day-to-day operations while Musk sets long-term direction and technical strategy. Under her leadership, the company built the reusable Falcon 9 rocket into the dominant vehicle in global spaceflight: in 2025, SpaceX conducted 165 launches, 51% of all orbital launches worldwide, and carried 83% of the mass sent to orbit—nearly 10 times more than its closest competitor, the Chinese state space program. SpaceX went public on June 12, 2026, under the ticker SPCX, at a valuation of $1.77 trillion, the largest initial public offering in history; shares rose more than 19% on their first trading day, pushing the company’s market value past $2 trillion, roughly three times the size of the entire global space economy. The offering raised about $75 billion, roughly $20 billion of which is earmarked to pay down debt. Shotwell’s own 12.6 million shares were worth more than $2 billion at the IPO price. Shotwell was born in 1963 in Evanston, Illinois, and studied mechanical engineering and applied mathematics at Northwestern University before working at Chrysler, the Aerospace Corporation, and the rocketry firm Microcosm. Looking ahead, Shotwell has pointed to Starship, still in-flight testing at Starbase, as the platform for SpaceX’s next phase: an expanded Starlink network, and orbital data centers to support artificial intelligence computing, which the company’s IPO prospectus targets launching as early as 2028. The rationale, she has said, is physical: solar cells generate roughly six times more power in orbit than on Earth, and radiative cooling in space is free. SpaceX has also disclosed a contract to supply AI compute to Anthropic worth $1.25 billion a month through May 2029.
Dafna Bar-Sagi CSO, NYU LANGONE Dafna Bar-Sagi grew up in Israel and trained as a neurobiologist, at Bar-Ilan University and then at SUNY Stony Brook, before turning to cancer research. Ras—one of the most commonly mutated genes in human cancer—normally acts as a switch; mutated, it sticks in an active state, firing nonstop growth signals. In 1986, at Cold Spring Harbor, she discovered Ras also triggers macropinocytosis, letting cells engulf their surroundings— unseen in mammalian cells before. A 2013 study from her lab found cancer cells hijack that mechanism to scavenge nutrients, swallowing nearby protein for fuel. Her lab now hunts for ways to starve pancreatic tumors of it. She’s spent most of her career at NYU Langone, where she’s now executive vice president, vice dean for science, and chief scientific officer—overseeing the hospital system’s entire research enterprise. She holds six U.S. patents. In December 2025, the National Academy of Inventors named her to its 2025 class of fellows, its highest honor for academic inventors.
Nabila Said
EDITOR, PLAYWRIGHT, ARTIST Nabilah Said started as a journalist, not a playwright. She worked as an arts correspondent and theatre critic for The Straits Times before turning her attention to writing for the stage—work that, in Singapore, meant writing in two languages at once. Malay is one of Singapore’s four official languages, but its theatre scene is a fraction the size of the English-language mainstream. Said writes in both, and much of her career has been about building the infrastructure that Malay-language playwriting in Singapore didn’t otherwise have. Her 2019 play Angkat, about a mother and her adopted daughter set against Singapore’s shifting national landscape, won Best Original Script at the Life Theatre Awards in 2020. Another 2019 play, Inside Voices, follows three Malay-Muslim women abruptly transported into a room together, working through folklore figures like the pontianak, a vampiric spirit traditionally used as a cautionary tale about women who defy patriarchal norms. Said has described the play as an act of reclamation, giving her characters “a sense of power that they may not otherwise have as women”—and said she built it around three women rather than one deliberately: “One woman on her own might feel really lonely... but having three together, I feel like they really embolden each other.” Inside Voices took the Outstanding New Work prize at London’s VAULT Festival and was published by Nick Hern Books. She earned an M.A. in Writing for Performance from Goldsmiths, University of London, on a Tan Ean Kiam scholarship, and her writing since has circled a consistent set of questions: gender, race, and religion; minority communities; the dislocations that come from moving between geographies and generations. In 2016, she founded Main Tulis Group, Singapore’s only collective of playwrights writing in Malay and English—the name is a pun on “playwright”: “main” means play, “tulis” means write. The group runs Nusantara Open Circle, a development program for new scripts from Indonesia, Malaysia, and Singapore, treating Malaylanguage playwriting as a regional practice rather than a national afterthought. She also co-founded the theatre collective Rupa co.lab, and edits ArtsEquator, a Southeast Asian arts-criticism platform. She’s presented work with some of Singapore’s most established companies— Teater Ekamatra, The Necessary Stage, T:>Works—as well as with independent artists outside them. Her current research project looks at the Malay community on Christmas Island, the Australian territory in the Indian Ocean, and the layered identities—Malay, Asian, Australian—its residents hold at once, alongside the island’s own tangled political and ecological history. Her most recent play, Conjuring a Square, toured five cities across four countries in 2025—Kathmandu and Itahari in Nepal, Singapore, Taipei, and Busan. She is currently the writer-in-residence at Centre 42, a Singapore theatre archive and development space, and in 2026 was named the Patricia Kailis International Writing Fellow, an Australian fellowship that brings international writers to Perth for a residency. WORTH.COM
FA L L 2 0 2 6
39
G ROU N DB RE AKING WOM E N
CHAIR & CEO, AMD Lisa Su was born in Tainan, Taiwan, in 1969 and immigrated to Queens, New York, with her family at age three. She earned three degrees in electrical engineering from MIT, including a PhD in 1994, then spent nearly two decades in semiconductors at Texas Instruments, IBM, and Freescale before joining AMD in 2012. She became CEO in October 2014, when AMD’s stock traded near $3 and the company’s market value had fallen to roughly $3 billion, with some analysts predicting bankruptcy. Su bet the company’s survival on a from-scratch redesign of its processor architecture, Zen, launched in 2017—a turnaround that has since made AMD Nvidia’s most credible rival in AI chips. That bet has kept paying off. In 2025 and 2026, AMD signed deals with OpenAI and Meta to supply a combined 12 gigawatts of AI chips, including its new MI450 series, and its stock hit a record high above $575 in July 2026. AMD’s market value has climbed past $700 billion—more than 200 times what it was worth the day she took over.
40
FA L L 2 0 2 6
WORTH.COM
Hong Wang
MATHEMATICIAN, NYU COURANT INSTITUTE / IHES Point a needle in every possible direction in three-dimensional space while sweeping through as little volume as possible: that’s the entire problem. First posed in 1917, it took more than 100 years to solve—until Hong Wang and collaborator Joshua Zahl posted a 127-page proof in February 2025. Nets Katz, a mathematician at Rice University, said: “This thing doesn’t need hyping up. It’s a once-in-a-century kind of result.” Wang’s own explanation was plainer: “I just wanted to understand why it’s hard.” In July 2026, Wang won the Fields Medal, math’s highest honor, awarded once every four years: the third woman to receive it since 1936, and the first Chinese woman ever. She’s already working on what comes next: a harder, related conjecture that her Kakeya proof has helped bring within reach. She splits her time between NYU’s Courant Institute and the Institut des Hautes Études Scientifiques outside Paris.
L E F T, G E T T Y / R I G H T, I M A G E B Y D AV I D S O N G / N Y U
Lisa Su
SANTORINI
42
FA L L 2 0 2 6
WORTH.COM
Santorini Sans Crowds Beyond the cruise ships and social media hotspots, the island rewards travelers willing to slow down. BY CAROLINE BIENFANG
P
erched on the upper terrace of Ammoudi Fish Tavern in Oia, somewhere between my last bite of octopus and my first taste of loukoumades, I watched the dimly lit waters of the Ammoudi Bay settle into evening. Catamarans slipped into their berths for the night while skippers disappeared ashore. The wind softened the conversations around us, lending an unexpected intimacy to the meal. Then a cruise ship emerged. Stretching more than 1,000 feet long, the vessel looked less like a ship and more like a floating city. I watched as rows of illuminated cabins, pools scattered across multiple decks, and neon lights glowing high above the water rolled by. As it pushed through the channel, the bay transformed. The calm water was suddenly littered with white caps. Restaurant staff hurried to move tables away from the patio’s edge as waves rolled over the dock below. Somewhere aboard were thousands of tourists preparing for their next port of call.
WORTH.COM
FA L L 2 0 2 6
43
SANTORINI For a moment, Santorini’s reputation sailed directly in front of me. Then it passed. Santorini welcomes roughly 3.4 million visitors each year, despite having only about 15,500 year-round residents. On some summer days, cruise arrivals alone have reached well into five figures, prompting the island to cap daily cruise visitors at 8,000 and introduce a peak-season disembarkation tax, according to a 2024 report from CNN. Still, during my four days on the outskirts of Oia, I experienced a rare sense of calm, as the crowds felt distant and unobtrusive. The ship continued into the darkness, carrying the crowds with it. The bay grew quiet again. It wouldn’t be the last time Santorini’s reputation failed to match my experience. Set within the cliffs above Ammoudi Bay, Santo Mine occupies the site of a former stone mine on the outskirts of Oia. Built within the hillside, the all-suite property is connected to the rest of the Santo Collection by a tunnel carved through the rock. Integrated into the landscape, the property feels less like a resort than a hideout— which, on an island this crowded, is the whole point. Maybe it’s the Manhattan conditioning, but the serenity and quiet of the spot almost made me uncomfortable. The property was at 70% capacity according to the staff. Yet, I could have sworn we were the only group there. Weaving through a shadowed tunnel, our bags chattering on the tail hitch behind our golf cart. The tunnel connects both of the Santo Collection’s main residences. Our Santo Mine suites were carefully concealed on a perch overlooking the water. Between the glass doors and the Caldera sat a narrow infinity pool that appeared to spill directly into the Aegean below. Before our cart driver had finished placing
44
FA L L 2 0 2 6
WORTH.COM
my bags in the room, I had already submerged my swollen airplane feet. Our driver laughed and asked, “First time to Greece?” to which I replied, beaming, “First time to Santorini!” That night, I made my way down the winding stone path following signs for Rhoē Wine Bar. I was thankful for my overpacking of at least three pairs of slip-on sandals, as Oia, or all of Greece for that matter, surely wasn’t built for a heel. I gathered my hair into a clip in preparation for the wind, and just as I shuffled my bag, shawl, and phone between my hands, I peeked around the corner of the towering white stone. I was greeted by a sunset that looked like a magazine clipping decoupage right over the shoreline. I opted for the signature ‘Secret Garden’: tequila, red cabbage, raspberry, topped off with grapefruit soda, which I returned to at each cocktail hour that followed. I sat quietly as evening catamarans slipped in and out of the port, setting off for their nightly sunset cruises. Overjoyed by the idyllic painting stretched across the horizon, I was unfazed by the occasional gust that accompanies their windy season. Shortly after I took my last sip, our cart arrived once again to take us across the property to one of Santo Pure’s restaurants, Alios Ilios. The restaurant got its name from the Greek translation, “the sun that rises and falls in the sea”. Overlooking the Aegean waters, the sunset tucked itself in for the night and welcomed the chill of the evening to take its place. Alios Ilios is known for its quintessential rendition of traditional Greek comfort food. Beef carpaccio to start, accompanied by panseared tuna “tigania” that melted on the tongue. Grouper “spetsiota” took center stage, adding warmth to the meal, while blankets from the staff did the rest of the heavy lifting.
WORTH.COM
FA L L 2 0 2 6
45
SANTORINI
Santo Collection’s Marketing Communications supervisor, Nikos Fournaris, joined us for our meal at Alios Ilios. Fournaris shared the history of the Santo Collection and the mission behind sustainability, tying each fact back to the land, the people, and the culture. Fournaris spoke about the sustainability initiatives, including its LEED certification and “Stay With Purpose,” earned by Santo Mine’s intentional placement of suites occupying the site of a former stone quarry. At the same time, rooftop gardens are planted with native island flora. Maybe it was the ‘family style’ eating of Greek culture, or Fournaris’s genuine curiosity, that shifted
46
FA L L 2 0 2 6
WORTH.COM
conversations from drawn-out introductions and work talk to family morals, cultural differences, and passions outside of work. By the second night, passing plates and stealing bites off one another’s forks had become the ritual—the kind of meal that felt less like a work dinner and more like a family dining room table. OIA BY BOAT If you tell anyone you’re traveling to Greece, they’ll first gush about its beauty, then offer a warning. The roads are busy. The resorts are packed. The lookout points are shoulder-to-shoulder with tourists chasing the same sunset.
The closest I came to experiencing that version of Santorini was from a distance. Our catamaran slipped in and out of coves as we lay stretched out, sipping local wine, with a taste of home from The Doobie Brothers. Our Michelin-caliber steward was roasting fresh veggies on an open grill just off the stern, while Fira’s port nestled itself into the distance. There is no question that sightseeing by catamaran was the right choice for getting the best views while avoiding crowds. Rising from the center of Santorini’s caldera, between Fira’s port and the Karavolades Stairs, is a jagged island forged by volcanic fire. The
caldera itself was formed by one of history’s largest volcanic eruptions around 1600 BC, an explosion so immense it reshaped the island and helped inspire legends of Atlantis. The mineral-rich waters that surround it are so warm and inhospitable that even fish avoid lingering there—Palea Kameni’s only ever official population: zero. However, that population was once off by just one. The island’s only-ever resident is a man named Sostis. For Sostis, an urban legend and lovesick hermit, zero may be the perfect symbol for the essence of true love. With an official population of zero, Sostis isn’t even counted. The tale of Sostis
was shared by our chief steward while peering over the rails of our catamaran just off the shore of Oia, Greece. The modern folklore was shared shortly after being warned of what felt like the side effects and possible outcomes from a drug commercial, if we swam in the water surrounding Palea Kameni, due to its high levels of sulfur, iron and magnesium. The volcanic island within the Santorini caldera is named after the Greek translation meaning “old burnt island”. Sostis, a former tour boat operator around Santorini, found his ‘Juliette,’ an Italian tour guide he met when visiting Italy. After being met with the devasta-
tion of an unmatched love, he chose complete solitude, claiming never to love again. This heartache led him to find sanctuary in the loneliest place, the island of Palea Kameni. For 40 years, he lived among a small menagerie of chickens and goats, finding peace in his quaint garden home to one olive tree, a couple of lime trees, and a prickly pear cactus. Sostis passed away this year from heart disease, refusing treatments as he wanted to pass in complete tranquility. A man who gave his entire life to a place, and the island doesn’t officially acknowledge he was ever there. But maybe that’s the way Greece prefers it. WORTH.COM
FA L L 2 0 2 6
47
SANTORINI
48
FA L L 2 0 2 6
WORTH.COM
FINDING STILLNESS My recommendation for a relaxing spa day is without a doubt an experience at Santo Pure’s Anassa Spa. After a thorough conversation with the staff, they tailored a full-body massage to my needs exactly—just the right amount of pressure, never rushed. Every movement felt intentional, with extra attention to my shoulders and neck, after evidence from a career in editing has shown it never goes easy on the posture. The staff made me feel as though I could—and should— lounge by the indoor pool, sipping antioxidant tea for as long as possible. After the sun got the best of my German roots the following morning, I returned to Anassa again for one of their facial treatments. I opted for a combination of their signature eye recovery, a triple action against tired eyes, with lifting and lightening properties. They recommended adding the AHA and double peel glow treatment, and to my surprise, my sun-scorched face was immediately cooled, hydrated, and soothed. GASTRONOMY It would be an injustice not to mention the breakfast at Santo Mine. It quickly became a topic of conversation among our group— and a recurring feature in my family group chat. Each morning, tables overflowed with freshly baked breads, local cheeses, cured meats, seasonal fruits, and traditional Greek specialties. My plate was never modest. I’d pile it high, convinced I couldn’t possibly fit another bite, only to find myself returning for one more pastry or a second helping of yogurt with local honey. With panoramic views stretching across the Aegean and nowhere else to be, breakfast felt less like a meal and more like an invitation to slow down and savor the morning.
As we neared the end of our stay, we commemorated the experience with a wine tasting at Santo Collection’s wine cellar. We indulged in five of the resort’s most promising grape varieties, paired with artisanal cheese. For someone who only recently was able to distinguish a Noir from a Cabernet, the experience was more than just reconciling the components of a red; it was a way for us to connect with the heritage of Santorini. The island’s volcanic soil protected many of its vines from phylloxera, leaving centuries-old ungrafted Assyrtiko vines that are still cultivated today. Many are trained into low basket-shaped “kouloura” coils to shield the grapes from Santorini’s relentless wind. On our final night, as I took my last sip of Assyrtiko, I found myself thinking of Sostis. More than his solitude, I envied the stillness he had found. In a destination increasingly defined by overtourism headlines, relentless Instagram carousels, and weary tales of crowds, the moments worth writing home about were the quiet ones: Ammoudi Bay after the cruise ship disappeared into the darkness. The silence of my private pool overlooking the caldera. Dinners that felt more like family gatherings than work obligations. Waitstaff, chefs, and sommeliers eager to share stories of the island they call home. For all the attention Santorini receives, Santo Collection seems designed to offer guests the chance to step away from it. Not from the island itself, but from the noise surrounding it. Built into the landscape rather than imposed upon it, the resort creates space to experience Santorini as more than a checklist of landmarks and sunsets, leaving room for something increasingly difficult to find there: presence.
WORTH.COM
FA L L 2 0 2 6
49
PLANES
Buying Time Ownership, fractional shares, jet cards, subscriptions, on-demand charter. What each really buys you, what each really costs, and how to build the right mix. BY DAN COSTA
B
efore Greg Raiff built Elevate Aviation Group, he was an 18-year-old trying to get 472 students to the Bahamas on a chartered plane. The job was purely transactional: point A to point B, lowest possible price. What he remembers nearly four decades later is how fast the whole thing could fall apart when something went wrong, and how little anyone cared about the price at that moment. “In aviation people are not really buying the flight itself,” Raiff says. “They are buying certainty. They are buying time, predictability, and the removal of stress.” That is the product every private aviation company is selling in 2026, and there have never been more ways to buy it. A whole airplane. A fractional share. A jet card. A subscription. A charter booked from an app. The distance between the right answer and the wrong one now runs well into six figures, and your job is to know which of those, or which combination, your flying actually calls for.
50
FA L L 2 0 2 6
WORTH.COM
WORTH.COM
FA L L 2 0 2 6
51
PLANES
THE STATE OF THE MARKET By almost any measure, 2026 has been a turbulent year. War in Europe, war in the Middle East, climbing inflation, global tariffs, even an AI bubble. Somehow, the markets have held strong. So has private aviation. Business-jet activity through June ran about 4% ahead of last year, per WingX, with North America closer to 5%—modest-sounding growth stacked on top of what was already the busiest year in the industry’s history. For two decades, private flying tracked the portfolio. Equities up, flight hours up. Despite all the noise and uncertainty, the pattern is the same today. Doug Gollan, who runs Private Jet Card Comparisons, the independent buyer’s guide, has watched this market longer than almost anyone, and
52
FA L L 2 0 2 6
WORTH.COM
his answer fits in a sentence: “Flying privately, you are buying time.” He counts the drivers: a high-net-worth population that keeps growing the pool, the door-to-door savings of flying nonstop from small fields, “over 5,000 versus less than 500 served by airlines in the U.S.,” and an airline system so full that a cancellation “can often mean a day or more until they can rebook you.” The supply side is betting this is permanent. Honeywell’s annual outlook projects 8,500 new business-jet deliveries worth $283 billion over the next decade, the largest forecast in the report’s 34-year history; one in five operators worldwide has at least one aircraft on firm order, and fractional fleets have grown more than 65% since 2019. Manufacturers are betting on more flights.
SHIFTING DEMOGRAPHICS The buyer is also getting younger. “New Flexjet Owners are on average 10 years younger than they were in 2019,” says Michael Silvestro, Flexjet’s CEO and the longest-tenured chief executive in fractional aviation. “This younger cohort deploys their capital differently. Time, convenience and the ability to experience more seem to matter more than other things.” His second driver is blunt: “Every time there is ‘friction’ in the commercial airline sector, the addressable market for private aviation services expands.” And the money is getting more mobile. Leona Qi, president of Vista U.S., watches a single fleet fly every continent, which gives her a live feed of where wealth is moving. The U.S. is still the biggest market, but in 2025 VistaJet’s traffic between Africa and Asia rose 42%,
with the Middle East–North America and South America–Europe corridors each up 28%. “Our Members are not thinking about travel within one region,” Qi says. “They are moving between several, often in one itinerary.” “Studies have suggested that the vast majority of people who can afford to fly private have never flown private,” says George Mattson, who runs Wheels Up under Delta’s control. The boom pulled in occasional flyers, but the ones who only go up a few times a year are the first to reconsider when the math tightens. A correction, if it comes, starts at the margins. The core has never been more committed. The most notable news is that fliers have never had more options. All come with pros and cons, andfew customers will be fully satisfied by a single option— except perhaps the most price-oblivious shopper.
“This younger cohort deploys their capital differently. Time, convenience, and the ability to experience more seems to matter more than other things.”
1. Whole Ownership This simplest and most misunderstood option is to buy a plane. You get total control: your crew, your schedule, your interior, your tail number. You also get the annual carry. On a large-cabin jet, fixed costs alone— crew, hangar, insurance, training— can top $2 million a year before you’ve bought a gallon of fuel, and fuel runs $3,000-plus an hour at 2026 prices. Industry break-even analyses put the crossover where ownership beats the alternatives above roughly 200 to 250 flying hours a year. Below that, you’re paying for an idle asset and bragging rights. Even at volume, ownership rarely travels alone, because one airplane can only be in one place. Among whole-aircraft owners in Gollan’s subscriber base, 55% also hold jet cards,
WORTH.COM
FA L L 2 0 2 6
53
PLANES 47% book ad hoc charter, and 31% hold fractional shares on top of the plane in the hangar. Sometimes the aircraft is down for maintenance. Sometimes it’s the wrong size for the mission. Sometimes it’s parked on the wrong continent. Leona Qi, president of Vista U.S., sees the same thing from the other side of the desk. Owners hand VistaJet their aircraft to manage, then buy a membership anyway, “because ownership alone doesn’t always provide the flexibility or global coverage they need.” The question she hears from clients now cuts at the asset itself: “Why own a depreciating asset when you can subscribe to guaranteed access on a global fleet?” 2026 has presented a fresh reason to own, despite the limitations: the return of 100% bonus depreciation makes the purchase far more attractive on paper. The IRS noticed. In early 2024, its Large Business and International division launched a compliance campaign aimed squarely at business-aircraft write-offs, opening dozens of audits of corporate and high-income owners over how flight hours are split between business and personal use, and the effort has only widened since. Although it is fair to say the IRS’s priorities have shifted under the current administration, this could be a concern if those priorities change in the future. 2. Fractional Shares The fractional share is the industry’s flagship product: you buy a slice of an aircraft, typically a sixteenth to a half, commit to a multi-year contract, and get guaranteed access with as little as a day’s notice. It is the strongest form of guaranteed lift short of ownership, and in 2026 it’s where the growth is; fractional flying rose more than 10% last year. The math deserves a hard look. A 16th share buys roughly 50 hours a year, and entry runs from about $700,000 for a piece of a light or midsize jet to $2.5 million and up for large-cabin, before monthly management fees and an occupied-
54
FA L L 2 0 2 6
WORTH.COM
hourly rate that together can add well into six figures annually. You’re paying for the guarantee twice, once in capital and once in fees, which is exactly what a buyer of certainty does. Just do it knowingly. “If you’re serious about making private jet travel a consistent part of your life, want guaranteed access to an aircraft, and expect unwavering service consistency, fractional ownership is the most effective way to achieve it,” Silvestro says. The year we’re living through does his selling for him. “When the world feels less certain, certainty of experience becomes more valuable, and that’s exactly what fractional ownership provides.” “Nearly 85% of the aircraft we are adding to our fleet this year are midsize aircraft and larger,” he adds. “Some call it cabin creep; we refer to it as younger, larger and further.” New owners start bigger and step up to Gulfstream G650S and G700S faster than they used to. NetJets, the market’s center of gravity, did not respond to Worth’s interview requests. Still, the public record speaks: the Berkshire Hathaway subsidiary flies roughly 850 aircraft, more than three times Flexjet’s fleet, is adding about 80 jets this year, and had pre-sold well over half of its 2026 deliveries before the year began. When the two biggest fractional players are expanding that fast, the guarantee is the product they’re betting on. The fine print to respect: most fractional programs guarantee only one aircraft per day, and swapping cabin sizes comes with restrictions and fees. The share is an anchor. That’s precisely why 40% of Gollan’s fractional-shareholders also carry a jet card and 32% layer on charter. Mattson, whose Wheels Up sells flexibility against the model, calls fractional “in effect a timeshare of an airplane,” a high-fixed-cost structure that can’t be optimized on a trip-by-trip basis. He’s talking his book, but the critique is worth hearing before you sign a five-year commitment.
WORTH.COM
FA L L 2 0 2 6
55
PLANES 3. Jet Cards The jet card is the industry’s middle product: buy a block of hours, usually 25 or 50, at a locked or capped hourly rate, with guaranteed availability inside a defined service area: no asset, no multi-year commitment, a known number against which to plan the year. That number, in 2026: the average North American card runs a little over $11,300 an hour—about $8,500 on a light jet, $15,200 on a large cabin—and a 25-hour light-jet card typically costs $150,000 to $225,000. Rates actually dipped about 1% in the second quarter, which sounds like good news until you see where the margin went: peak days, the calendar dates when guarantees loosen, and surcharges kick in, keep multiplying. The sticker held. The asterisks grew. Also check whether the quote includes the 7.5% federal excise tax; that one line item moves the effective rate by hundreds of dollars an hour. Beyond the rate, the structures differ. Programs price three ways: fixed hourly, capped hourly, or dynamic pricing that floats with the market. In a high-fuel year, those are very different products. Fixed rates are insurance; in a calm market you overpay a little, in a spiky one they’re the cheapest seat in the room. Dynamic looks great until it isn’t. And the contracts have been drifting in the provider’s favor. Gollan notes programs have quietly added fuel surcharges and “escape hatches” allowing changes they deem commercially necessary, citing wars, tariffs, supply chains. His dry addendum: “By the same token, you don’t want your provider to go out of business.” The trap that actually empties accounts is duller than pricing. “Not understanding cancellation terms is a huge mistake,” Gollan says. On some cards and charters, once you book, there is no refund and no credit. “We’ve seen people lose well over $150,000 on a transatlantic charter booking.”
56
FA L L 2 0 2 6
WORTH.COM
The card’s best role in 2026 is glue: the flexible layer over a share, the backup for an owned aircraft, or the whole solution for someone flying 25 to 50 predictable hours. Quite a few of Gollan’s subscribers hold multiple cards, one tuned for short hops, another for long-haul. 4. The Subscription VistaJet sells none of the above: no share, no block hours you own, but a membership contract guaranteeing access to a fleet the company owns outright, anywhere in the world. It’s the asset-heavy bet that the future flyer wants consistency without a balance sheet entry. Wealth is transferring to younger hands, and Qi sees in that cohort “a growing preference for access and efficiency over the responsibilities that come with ownership.” Her client wants one partner and one standard on every continent, and the expectations have escalated to match the price. “They expect the same aircraft quality, the same level of service, and local expertise wherever they are,” she says. The cabin itself is no longer where the argument gets won: reliable Wi-Fi, “onboard dining that meets the standards of their personal chef or nutritionist,” a seat that works like the office and sleeps like home.
“Not understanding cancellation terms is a huge mistake. We have seen people lose well over $150,000 on a transatlantic charter booking.”
The catch is that global coverage is priced like global coverage. Published program rates start around $11,000 an hour on a supermidsize Challenger 350 and reach roughly $19,500 on a Global 7500, against a multi-year commitment that typically starts at 50 hours a year—call it $1.5 million or more annually on the big cabins, all-in, before you board. The subscription wins for the flyer who genuinely crosses three regions in one itinerary. The flyer whose year is mostly Teterboro to Palm Beach is paying for continents she’ll never use. 5. Charter, Brokers, and the App At the bottom of the commitment ladder sits on-demand charter: no contract, no deposit, pay by the trip. Rates in 2026 run roughly $2,500 to $5,500 an hour for a light jet, $4,000 to $8,000 for midsize, and $8,000 to $14,500 and beyond for heavy and ultra-long-range metal—with the caveat that headline rates routinely understate the all-in cost once fuel surcharges and airport fees land. It’s also where the technology is moving fastest. The broker case is about whose side of the table your advisor sits on. “Operators with fleets or jet card programs are inherently incentivized to sell their own lift,” says Joel Thomas, who built the first charter-brokerage franchise at Stratos Jets. Owning no aircraft, he argues, removes the bias: “We’re not selling lift. We’re managing risk, aligning fully with the client’s mission.” Wheels Up sits deliberately between the camps. Mattson’s company sells membership on its own Phenom and Challenger fleet, runs one of the world’s largest charter brokerages in Air Partner, and plugs into Delta, so a member can book the jet out and fly premium commercial home under one relationship. He argues that the industry’s products, not its customers, are the problem: flyers should “seamlessly move between private
and commercial aviation,” trip by trip. He is, in effect, selling the blend itself—which happens to be where this story is headed. Raiff, the teenager from the Bahamas charter, built Elevate around the lesson that flight taught him: the work has to happen before the customer ever feels friction. His app, with an AI travel agent named Ruby handling requests, is the scale play, but he is precise about where the machine stops. Private jet bookings are highstakes and unforgiving, “which means you cannot fully automate decision-making,” he says. Every account holder still gets a human advisor. “We are not in the business of connecting clients to an operator and stepping away.” Charter is the right whole answer below about 25 hours a year, and the right partial answer at almost every
level above it: the international oneoff, the last-minute save. Just read the cancellation terms. STOP PICKING A LANE The old question was a fork: charter, card, share, or own. You picked a lane and stayed in it. That logic is dead, and treating it as live is the most common way flyers overpay. “Once you get over 25 hours, many flyers have more than one solution,” Gollan says. His analogy is the one to remember: “It’s like cars in a driveway. You may have an SUV for the lake house, a sports car to go to the club, and a convertible for the beach.” The breakpoints: under 25 hours, stay liquid in charter or a card. Between 25 and 100, build a portfolio, anchoring predictable flying with a share or card and layering charter over the rest. Past 100, question
whether any program still fits. Gollan recently ran the numbers for a subscriber flying 150 hours a year and delivered a diagnosis instead of a product: fractional and jet cards, the industry’s two bestmarketed offerings, simply weren’t built for his pattern. The real options were the two extremes, whole ownership or booking one flight at a time. “There is no single answer,” Gollan says. Which lands back where Raiff started. The 472 students on that Bahamas charter cared about exactly one thing: whether the flight worked when it mattered, and no price was low enough when it didn’t. Decades later, the buyer has changed completely, and the purchase hasn’t changed at all. The jet was never the luxury. The time was. Buy accordingly.
YOUR MOST TRUSTED TRAVEL PARTNER FITS IN YOUR WALLET. Insurance gets you to the "nearest adequate" facility. A Medjet Membership gets you to a hospital AT HOME.
al)Medjef l!l �l!l AIR MEDICAL TRANSPORT �: .1.: & SECURITY RESPONSE l!l, •• MEMBERSHIPS
Women’s Health Takes Center Stage The Milken Institute’s Women’s Health Network, chaired by Dr. Jill Biden, brings the oft-neglected area into focus as a global priority.
I
t was Women’s Health Week USA in May and Dr. Jenica Patterson, Senior Director of the Women’s Health Network at the Milken Institute, was on a panel in a room of the industry’s innovators when she said it: roughly half of all venture capital currently goes to AI, while only 2% goes to healthcare for the gender that represents 51% of the population. It’s a statistic that encapsulates one aspect of the challenging arena of women’s healthcare. Funding has not only been lacking but so has awareness of that fact. Other issues run similarly deep. It wasn’t until 1993 that the National Institutes of Health (NIH) required women and minorities to be included in clinical research. And it took twenty-plus more years—until 2016—for the agency to require “sex as a biological variable” to be considered in its research and grant-designing policy. Still today, less than 10% of NIH funding goes to women-focused research despite the gender being affected disproportionately, differently, or uniquely—as in the cases of maternal health or menopause—by conditions. And yet: There are signs of a golden moment in women’s health emerging. What some say started this period was 2023’s establishment of the White House Initiative on Women’s Health Research by then-First Lady Jill Biden. A first-of-its-kind program, it directed $1B of government research funding towards women’s health, including more than $100 million to the ARPAH’s Sprint for Women’s Health, which focused on catalyzing innovation and accelerating commercialization of early-stage technologies, as well as $500 million for female service members’ healthcare via the Department of Defense and more. It also sparked a cultural conversation—which in turn furthered financial and medical progress beyond government walls. Last year the nonprofit Wellcome Leap and Melinda Gates’ Pivotal, a group of organizations dedicated to women’s social progress, announced a $100 million partnership focused on research. They’re far from alone. The women’s health market is also rapidly expanding. It’s projected to reach $66 billion by 2033. Among the brightest lights when it comes to the current wave of actors is the Milken Institute’s new global Women’s Health Network. Created last year by the nonpartisan nonprofit think tank, it’s focused on solving systemic issues and reducing the siloing of information that can blunt the impact of even the best ideas. It’s also being chaired by Dr. Biden herself, who sees it as a way to continue the work she spearheaded in Washington, but take it worldwide.
Composed of more than 170 member organizations spanning academia to finance, technology to pharma—and including Merck, Microsoft, and the American Heart Association—the Network started off by identifying the field’s top 10 biggest challenges. In addition to severe underfunding, these include gaps in data and clinical research, continued underrepresentation of women in leadership, and cultural stigma surrounding women’s health conditions. To address them, the Network took a multi-pronged approach focused on: funding initiatives, working groups that home in on the biggest issues, and the establishment of a digital platform where members can share expertise. Here, we take a closer look at each: • Funding. The Network’s two main financial initiatives are its Catalytic Philanthropic Fund and its Elevate Investment Initiative. The former will be a $50 million Evergreen Fund—the first fund to be run by the Milken Institute itself—that will provide flexible, lower-cost capital and enable innovators to develop their ideas more boldly and quickly. It will also increase their ability to scale market access. Says Caitlin MacLean, Managing Director of Catalytic Capital at the Milken Institute, “We aren’t expecting a 10x return. We want recipients to use the funds to go into new counties, serve different populations at an affordable price point, and navigate complex regulatory systems” with more ease. Elevate will offer emerging fund managers the opportunity to participate in Milken Institute conferences and events across the globe, and provide increased access to capital via its network of institutional investors, family offices and asset managers. • Working groups. After uncovering the top challenges facing the field, the Network created a series of groups to approach the problems via five areas: funding, regulatory issues, insurance coverage and reimbursement, health access and education, and employer engagement. These groups are focused on both deep research and quick-tomarket deliverables. So far—among the white papers, reports, events and panels that have resulted—are this Spring’s “Employers Investing in Women: Advancing Business, Employees and Communities” brief, created in conjunction with the Milken Institute’s Employer Action
PA R T N E R C O N T E N T
58
FA L L 2 0 2 6
WORTH.COM
Exchange. A “Coverage and Reimbursement Roadmap for Women’s Health Innovation” is being released this month. Up next will be a comprehensive guide to how healthcare systems can better meet the needs of women throughout their cancer journey, created in conjunction with the American Cancer Society and publishing later this Fall. More is to come.
This is only the beginning. Catalytic Philanthropic Fund investments are set to begin in early 2027 (although donors interested in becoming anchor givers are welcomed this year). Elevate’s requestfor-application process opened in May. And Biden and Network leadership are slated to continue their meetings with entrepreneurs, researchers, and other healthcare leaders nationwide and globally this Fall.
• Digital platform. The Milken Institute may be best known for its events that help leaders in business, health, and more cross-pollinate ideas and create solutions. When it comes to the Women’s Health Network, the aim is the same—but in addition to annual member meetings, the Network has launched a digital platform which allows for members to access data, resource sharing, and virtual discussion. Patterson describes it as “the connective tissue or the API layer of the Network. It’s really an opportunity for members to exchange knowledge—of all types—further.”
Patterson hopes that the Network can simply—yet meaningfully—help normalize women’s care as part of health in general. “It’s a great moment, but I think it needs to change into an everyday discussion,” she says. “Women’s health is health, and it relates to better health for everybody.” MacLean adds that the area’s momentum partly derives from health issues being so personal—and women sharing about them in increasing numbers. “Never underestimate the ability for our individual experiences to galvanize action,” she says. “We see that each time we recount getting pregnant through IVF, facing cancer, struggling with endometriosis...The more we open up, the more we break down barriers.”
PA R T N E R C O N T E N T WORTH.COM
FA L L 2 0 2 6
59
What the Wealthiest Travelers Are Really Buying Melissa Xides spent years mastering the art of knowing exactly what her Bergdorf Goodman clients wanted before they asked. Now, as President of Exclusive Resorts, she’s using that instinct to help families spend the one luxury they can never buy more of—time. BY EVA SHAE CROUSE
M
elissa Xides spent three decades in luxury retail, most notably as Chief Retail Officer at Bergdorf Goodman, before joining Exclusive Resorts as President. Her career has been built on a simple belief: once you reach a certain level of luxury, relationships matter more than products. That belief found a natural home at Exclusive Resorts, the private club with a billion-dollar portfolio of residences, dedicated Ambassadors, and decades-long Member relationships. We sat down with Xides to discuss what she’s brought from Bergdorf, what she’s learning from hospitality, and why the future of luxury belongs to brands that know their customers well enough to help them spend their time, not just their money. The planning and logistics structure behind a trip is usually invisible to a member, which I guess is the point. How much of the value of membership lives in that hidden layer? The logistics aren’t the value. Their absence is. Anyone can help you book a trip. Much harder to find is someone who knows your family well enough that you don’t have to explain yourselves every time you travel. That’s what our Ambassadors
do. They stay with Members for years, often decades, learning the rhythms of a family—the traditions worth repeating, and the moments that call for something new. Eventually, travel stops feeling like something you organize and starts feeling like part of the life you’re already living. In luxury—whether goods or travel—you’re not selling a necessity. So, what are you actually selling? I think luxury has become overly focused on access. Access isn’t difficult anymore. The internet has made almost anything bookable. Judgment is what’s valuable. Our Members aren’t joining because they need another vacation. They’re joining because they want someone they trust to help them spend their lives intentionally. That’s a very different business. Our sales process often lasts well over a year because we’re not simply selling a membership— we’re beginning a relationship. You’ve touched on something interesting: the tension between going somewhere new every time versus the comfort of returning to the same place. How do you think about those two different modes of travel? I think about it all the time because I don’t believe you have to choose. One of my first visits as President was to Real del Mar. Our concierge, Mario, greeted a returning family with a framed photograph from their visit a decade earlier. They walked into what felt like their second home and saw a younger version of themselves on the wall. At the same time, I love discovering somewhere completely new. The richest life isn’t built entirely on novelty or entirely on tradition. It’s a balance of both. Trust is clearly central to this business. Where do you think trust is most commonly lost? Usually in communication—or more often, the lack of it. People can forgive almost anything if they feel informed, heard, and respected. They lose trust when they don’t. Worth’s motto is “Worth Beyond Wealth.” How do you measure impact over revenue? Wealth gives people choices. What they’re ultimately searching for is meaning. Did we help a family spend more meaningful time together? Did we create traditions they’ll return to for years? Did we introduce them to a place or culture, or even another Member that changed the way they see the world? Twenty years from now, I want them to remember that this was where their children learned to ski, where three generations celebrated an anniversary, or where lifelong friendships began. Visit us at: exclusiveresorts.com
PA R T N E R C O N T E N T
60
FA L L 2 0 2 6
WORTH.COM
GETTY
LIVING WELL
Grind culture has a rival: executives trading all-nighters for biomarkers and longevity memberships (62). Medicine was built on population averages. AI is dismantling that, one protein signature at a time (68). Three decades after Congress mandated women’s inclusion in clinical trials, medicine still treats them as an afterthought, a $1 trillion blind spot (70). And the highest-yield longevity drug isn’t a supplement: a Yale study says believing you’ll age well buys more years than any diet or device (72). WORTH.COM
FA L L 2 0 2 6
61
H E A LT H
62
FA L L 2 0 2 6
WORTH.COM
The New Executive Order: Longevity Medicine As burnout becomes an occupational hazard, a new class of executives is trading grind culture for genomics, biomarkers, and data—not chasing longer careers, but longer and healthier lives. BY NORA WALSH
F
or decades, the American office has been defined by a relentless, grind-it-out culture. In this world, ambition is a performance: staying up the latest, sleeping the least, and being the first to reply to an email at 3:00 a.m. These have been the hallmarks of success. The results of this pace are well-documented. According to Gallup’s 2026 State of the Global Workplace report, half of U.S. workers and 40% of employees worldwide report feeling significant daily stress—the highest levels on record. The terminal point of this trajectory is almost always burnout. And these are the stats for the workforce overall—the average worker. CEOs and executives typically drive themselves even harder. And the effects are often addressed only after a catastrophic health event. Chronic stress does more than just ruin your mood; it wrecks your body. A 2024 meta-analysis in Frontiers in Psychiatry found that elevated cortisol and suppressed immune function can raise the risk of heart disease by 27%. The damage even reaches down to the cellular level. One study revealed that chronically stressed caregivers aged the equivalent of a decade more than their peers living lower-stress lives.
WORTH.COM
FA L L 2 0 2 6
63
H E A LT H “Longevity medicine has exploded,” says Dr. Frank Lipman, the functional medicine pioneer and founder of Eleven Eleven Wellness. “I’ve been doing this for 40 years, and I’ve never seen an interest level like what we’ve seen in the last few years.” Today, 57% of consumers say prioritizing “aging well” is more important than it was five years ago, per NielsenIQ. This shift is visible on the wrists of executives everywhere. Wearables like Oura and Whoop now dictate “readiness scores,” using heart rate variability and recovery data to tell users if they are actually primed for the day’s work. It is a massive business; the global wearable market has topped $84 billion and is expected to double by 2030. Bolstered by breakthroughs in AI, biotechnology, and genomics, this new field allows leaders to proactively manage their health with precision, fostering a sense of control and confidence.
64
FA L L 2 0 2 6
WORTH.COM
It is a move away from the reactive nature of traditional medicine toward a data-heavy approach focused on extending “healthspan”—the years we spend in good health—by fixing problems before they become diseases. THE BIOMARKER BOOM The standard annual physical is outdated. Today’s high-resolution diagnostics reveal early signs of health issues before symptoms appear. Among the options now available are: l Prenuvo is a radiation-free whole-body MRI that detects early signs of cancer and other abnormalities. l Neko uses sensors and imaging to map skin health, cardiovascular risk, and other key biomarkers. l DEXA scans measure bone density and osteoporosis risk.
l Genetic and epigenetic testing reveals biological age and predispositions to inflammation, poor detoxification, or neurodegenerative disease. l Continuous glucose monitors (CGMs) offer real-time insight into metabolic health. l Neuro-mapping technologies are making cognitive health quantifiable for the first time. l Body composition analysis calculates muscle mass and visceral fat—both key predictors of longevity.
“There are so many biomarkers we can check now that traditional doctors aren’t even looking at,” Dr. Lipman says. “Then you have the therapies— peptides, hormones, hyperbaric oxygen, stem cells. It’s a whole new world.” Anna Bjurstam has spent three decades in the wellness industry. She co-founded Raison d’Etre and later shaped the global strategy for Six
Senses. She has seen the trend move from simple relaxation to a complex convergence of traditional medicine and nervous system regulation. Many top-tier hospital programs at places like Princeton and Johns Hopkins provide life-saving data, though their high price tags and exclusivity mean they remain out of reach for most. But even for those who can afford them, data isn’t always a cure. “For many hospital programs, you go in, you get tested, you get a report, and then you’re essentially on your own,” Bjurstam noted. “The behavior change piece is often missing.” THE IMMERSION OPTION That gap has given rise to a second category: immersive, hospitality-driven medical wellness clinics and retreats. These models combine clinical insight with long-term lifestyle intervention. Experts emphasize that for longevity medicine to be effective, diet, exercise, sleep, and stress management must be prioritized. No peptide or IV drip can compensate for poor sleep or chronic stress, making these the foundation of any successful longevity plan. For executives who need a kickstart, medical wellness retreats like SHA, Clinique La Prairie, and Lanserhof offer complete immersion in a healthy, habit-forming environment. “They’re not spa holidays,” Bjurstam explained. “They combine diagnostics, protocols, science, and therapeutic programming at a very high level.” When SHA opened in Alicante, Spain, in 2008, it was operating ahead of the curve. Wellness, at the time, was still largely seen as indulging oneself at the spa for relaxation or temporary escape. “Our conviction was clear,” says Alfredo Bataller, CEO of SHA and AB Living Group. “Health should not be understood only as the absence of disease, but as a result of how we live, how we eat, how we manage stress, how we recover, and how meaningful our relationships are. What has evolved is the depth of the science available to support our vision.”
International Health Tourism Sometimes, you need to step out of the office to truly turn the tide on your health. These multi-day retreats are designed for full immersion, providing the space and time necessary to transition from raw data into hard-wired daily habits. Lanserhof – Longevity Programs Locations: Lans, Austria; Sylt, Germany Program Cost: The Four-Day Longevity Check starts at ~$3,350 (excluding accommodation) Since 1984, Lanserhof has been a European gold standard for integrative wellness. They don’t just run diagnostics; they blend clinical rigor with naturopathic therapies in settings designed for deep restoration. Whether you are there for the four-day check or a longer stay, the focus is on a medically grounded, total-system reset that covers everything from your gut health to your biological age. SHA Wellness Clinic – Sleep and Gut Health Program Locations: Alicante, Spain; Costa Mujeres, Mexico Program Cost: Starting at ~$4,200 With over two decades of experience, SHA has mastered the art of the immersive medical retreat. Their four- to 10-day programs go deep into biomarker analysis, cognitive testing, and oxidative stress to build a hyperpersonalized roadmap for your health. What’s impressive is the follow-up: you leave with a Whoop wearable and a plan that integrates clinical insights directly into your daily life. Tulah Clinical Wellness – Executive Recharge Location: Kerala, India Program Cost: Starting at $9,800 Tulah is a next-generation entrant that proves clinical-grade diagnostics can exist in a retreat setting. Their Executive Recharge is a minimum seven-night commitment that brings together MRI, genomics, epigenetics, and microbiome analysis to identify exactly which systems are aging the fastest. They prioritize targeted, intelligent interventions over generic advice, bolstered by a 10-month follow-up program delivered via their app. Clinique La Prairie – Longevity Programs Location: Montreux, Switzerland Program Cost: $15,000 – $50,000 Nearly a century of clinical history informs the work at Clinique La Prairie. Their “Five-Step Longevity Method” is a highly structured, multidisciplinary process that utilizes over 300 biomarkers to map your health. A team of 65 physicians and 25 specialists works to ensure that by the time you leave, you have a precise, actionable roadmap for your nutrition, movement, and recovery that is designed for the long haul.
WORTH.COM
FA L L 2 0 2 6
65
H E A LT H THE MEMBERSHIP MODEL For executives looking to begin their longevity journey closer to home, clinics like Next Health, Fountain Health, and the Comite Center for Precision Medicine & Healthy Longevity offer ongoing, personalized care. For many, the entry point is modest—a consult with a nutritionist, a first real look at gut health, or a cortisol panel that finally puts chronic stress into hard numbers. But if you are ready to scale, the longevity is there to scale with you. Dr. Darshan Shah, a surgeon who turned to functional and longevity medicine after his own autoimmune health crisis, founded NextHealth, an integrated membership model combining lifestyle medicine, functional medicine, hyper-preventive diagnostics, and longevity therapies—From custom IVs and plasma exchange to more experimental treatments like EBOO (extracorporeal blood oxygenation and ozonation), all under one roof. “The biggest problem with healthcare is that everything is so disjointed,” Dr. Shah said. “You don’t have enough time in the day to piece it all together.” NextHealth was designed to simplify that process by giving patients a single destination to manage their health proactively. “We address the root cause of chronic disease, including gut issues, inflammation and metabolic dysfunction, and then layer in advanced therapies when appropriate.” Patients undergo quarterly testing across roughly 500 biomarkers spanning metabolic health, hormones, cardiovascular risk, and organ function, alongside body composition analysis and strength testing. “We designed a beautiful center where patients can receive these treatments as part of their membership, creating a more proactive, collaborative approach to their health,” he said. Bi-coastal executive Sam Bakhshandehpour, President of Merchants at Bilt, is a longtime
66
FA L L 2 0 2 6
WORTH.COM
NextHealth client and early adopter of longevity medicine. He pairs treatments across providers, using NextHealth and Restore Hyper Wellness for red light therapy, cryotherapy, and NAD IV drips, while relying on Function Health, a preventive health platform, for advanced blood testing. He also undergoes regular Prenuvo and DEXA scans to track body composition and bone density. The results, he noted, have been substantial. “Morning clarity has been off the charts. I don’t need an alarm to wake up. I feel more regulated, and my decision-making is a lot clearer and calmer. At 50, I honestly feel better than I did at 30.” Armed with data from wearables like Oura Ring and Whoop, he began to recognize patterns in his own physiology that now influence how he manages his workday. “If my readiness score is low, I know that’s not the day to make big decisions,” he said. “If I’m well rested, I push harder, physically and mentally.” And he’s not alone. Roughly a quarter of the global population now tracks metrics like heart rate variability, sleep, and recovery, turning abstract fatigue into measurable data. For executives looking to assess their health, strengthen the fundamentals, or optimize their healthspan through longevity therapies, a growing number of programs now offer a more comprehensive path forward. We identified 10 of the most compelling executive health programs globally, evaluating clinical depth, physician leadership, breadth of diagnostics, integration of longevity science, efficiency, level of personalization, and overall track record. We asked each program for its costs, but those numbers are hard to apply. Flat fees often come with surcharges depending on the amount of testing and treatment you need. And of course, these costs are not always covered by insurance.
The A-List The 10 programs below range from single-day executive physicals to multi-year membership models— chosen not for price, but for clinical rigor. NEXTHEALTH – APEX PROGRAM Locations: Los Angeles, CA; New York, NY; Miami, FL; Chicago, IL; Nashville, TN; Scottsdale, AZ; Sacramento, CA; Montecito, CA; Seattle, WA; Vancouver, BC Program Cost: Available upon request
NextHealth treats longevity not as a static, annual audit, but as an ongoing, managed project. By merging advanced diagnostics— including full-body MRI and coronary imaging—with continuous, physician-led care, the Apex Program moves well beyond the traditional physical to address the root causes of chronic illness. It’s a data-heavy, quarterbacked approach that keeps you in the loop long after you leave the clinic, which is precisely why founder Dr. Darshan Shah was recognized as the 2025 Longevity Doctor of the Year.
FOUNTAIN LIFE – APEX ADVANCED PRECISION EXAM Locations: Houston, TX; Dallas, TX; Naples, FL; Orlando, FL; Westchester, NY Program Cost: $11,500 – $23,500
If you want to know what’s coming before it arrives, Fountain Life is the answer. Their APEX exam is a deep dive into your biological future, leveraging whole-genome sequencing, full-body MRIs, and coronary scans to map your health against the recognized hallmarks of aging. What sets them apart is Zori, their proprietary platform, which takes an avalanche of data and boils it down to actionable, rootcause insights. It is a sophisticated, precision-first approach backed by founders Bill Kapp, Peter Diamandis, Tony Robbins, and Robert Hariri.
MAYO CLINIC – EXECUTIVE HEALTH PROGRAM Locations: Rochester, MN; Jacksonville, FL; Scottsdale, AZ; London, UK Program Cost: Starting at $4,900
The gold standard of executive medicine, Mayo Clinic doesn’t need to chase trends; they set them. With a footprint that spans the globe, their executive program is a highly coordinated, one- to three-day deep dive that plugs you directly into the world’s most integrated healthcare network. It’s the choice for the executive who values the stability of a historic institution but demands the precision of modern predictive genomics and multicancer screening.
PRINCETON LONGEVITY CENTER – THE PLC COMPREHENSIVE PREVENTIVE MEDICINE EXAM Locations: Princeton, NJ; New York, NY; Shelton, CT; Fairfax, VA Program Cost: Starting at $5,000
For the executive who operates on a tight schedule, Princeton Longevity Center offers a masterclass in clinical efficiency. In just six to seven hours, you receive a rigorous workup that includes everything from cardiovascular testing and full-body CT imaging to DEXA scans and glucose monitoring. Led by physicians with top-tier academic affiliations, the program pairs these extensive diagnostics with detailed, actionable reporting that tracks your health trends for up to two years post-exam.
COMITE CENTER FOR PRECISION MEDICINE & HEALTHY LONGEVITY – NOF1 PRECISION HEALTH ANALYSIS Locations: New York, NY; Miami, FL; Palo Alto, CA Program Cost: $100,000 – $200,000 annually
The Comite Center is for the executive who wants a bespoke solution. Founded by Yale-trained endocrinologist Dr. Florence Comite, the Nof1 program treats your health as a single-subject clinical study.
This isn’t a one-and-done exam; it is a multi-year engagement involving continuous monitoring of your metabolic, hormonal, and genetic data. The goal isn’t just maintenance—it’s predictive analytics meant to reverse agerelated disorders like heart disease, diabetes, and cognitive decline.
CENEGENICS – OPTIMIZE PROGRAM Locations: Beverly Hills, CA; Miami, FL; New York, NY; San Francisco, CA; Las Vegas, NV; Denver, CO; Park City, UT; Tulsa, OK; Houston, TX; Dallas, TX; Chicago, IL; Cleveland, OH; Philadelphia, PA; North Carolina, NC; Atlanta, GA; Washington, DC; Jacksonville, FL; Alaska, AK Program Cost: Starting at $3,499
With nearly three decades in the field, Cenegenics is a pillar of performance-focused medicine. Their Optimize Program marries deep-dive diagnostics—including whole-body MRI, VO₂ max, and epigenetic analysis—with a practical, coach-led model. The differentiator here is the network of 35+ board-certified physicians and health coaches who ensure that the data doesn’t just sit in a file. Actually, it influences your daily nutrition, exercise, and therapeutic protocols.
JOHNS HOPKINS – EXECUTIVE & PREVENTIVE HEALTH PROGRAM Location: Baltimore, MD Program Cost: $2,700 – $3,200
Rooted in one of the world’s most respected medical institutions, Johns Hopkins delivers a highly efficient, hospital-based model. You’ll get a comprehensive diagnostic suite—cardiovascular, metabolic, neurocognitive, and beyond—wrapped into a four- to six-hour visit. Because you are within the Johns Hopkins system, the transition from discovery to specialist referral is seamless. It is a benchmark for traditional, academically grounded executive care.
BIOGRAPH EXECUTIVE PHYSICAL Locations: New York, NY; San Mateo, CA Program Cost: Starting at $7,500
Biograph focuses on the “Big Five” drivers of chronic disease: cancer, cardiovascular issues, metabolic dysfunction, neurodegeneration, and physical resilience. This is a concierge-led day that prioritizes continuous intervention over reactive medicine. It’s clearly resonating with the tech-forward C-suite—companies like OpenAI, Twitch, and Zipline have turned to Biograph to help their teams quantify and improve their long-term health performance.
DIFFERENT HEALTH – EXECUTIVE HEALTH MEMBERSHIPS Locations: New York, NY; San Francisco, CA; On-site options available Program Cost: Starting at $2,500
Different Health breaks the mold by bringing the clinic to you. A favorite among Fortune 100 teams, their pop-up diagnostic labs turn workplaces into human performance centers. Beyond the initial testing, members get a dedicated physician, personal trainer, and a digital dashboard to track progress. If you need a partner to build lasting habits around sleep, nutrition, and recovery without disrupting your work week, this is a highly practical entry point.
EXTENSION HEALTH – LONGEVITY MEMBERSHIP PROGRAM Location: New York, NY Program Cost: $50,000 – $250,000 annually
Led by Dr. Jonathan Kuo, Extension Health is at the forefront of the regenerative movement. This isn’t just about diagnostics; it’s about intervention. The program leverages cutting-edge therapies—including stem cell and exosome treatments, peptides, ozone therapy, and hyperbaric oxygen—to optimize recovery and slow the clock. It is a white-glove, high-touch membership for executives who want to invest aggressively in their healthspan through advanced, interventional medicine. WORTH.COM
FA L L 2 0 2 6
67
H E A LT H
The End of the Average Patient Medicine was built on population averages. AI is dismantling that, one protein signature at a time. The question nobody on stage could fully answer is whether knowing more about your body actually makes you healthier. BY DAN COSTA
D
r. Jay Luthar described the flaw in modern medicine in a single sentence, and once you hear it, you can’t unhear it. “The traditional medical model to this point has used population studies to find what the average person responds to and then fits an individual to an average,” he said. “Whereas we know that every individual is not an average, but very individual.” Tell me if this sounds familiar. Your doctor treats you with drugs validated on a population you don’t belong to. (Basically, every woman in the U.S., see page 70) The trial reported an average response. You are not the average. Nobody is. Some patients in that trial got better, some got nothing, a few got worse, and the number that reached your chart was the mean of all three. The research bears this out uncomfortably well. Randomized trials are designed and powered to estimate average treatment effects, not what will happen to you specifically. For most treatments, only a small share of patients responds the way the “average” patient did. Clinicians have been guessing from that average for a century and calling it ‘evidence-based’. Luthar, who is on faculty at Harvard Medical School and founded Lutanen Health, wants to invert it. Look at the patient in front of you “almost like an n-of-1 research study.” That phrase isn’t a metaphor he made up. N-of-1 trials are a real design, and the Evidence-Based Medicine Working Group of the AMA has held that they sit at the top of the evidence hierarchy for decisions about an individual patient. The catch, which is real, is that the statistical methods for aggregating them aren’t standardized, and they carry almost no weight in guidelines or regulatory decisions.
68
FA L L 2 0 2 6
WORTH.COM
Dr. Julie Chen, chief medical officer at Radence and formerly CMO at Human Longevity, reframes the same shift as a question. Traditional medicine asks, in her words, “are you sick yet.” Radence asks whether you are “changing in a not-so-great direction.” If the answer is yes, you’re still inside the window where prevention means something. The machinery underneath that question got real in the last two years. Luthar is most excited about proteomics, and the numbers explain why. We carry tens of thousands of protein signatures. Researchers at Stanford measured more than 7,000 plasma proteins across 60,542 people and built models estimating the biological age of over 40 cell types. Roughly 20% to 25% of people showed accelerated aging in a single cell type. The associations are not subtle: accelerated organ aging carried 20% to 50% higher mortality risk, accelerated heart aging came
with a 250% higher heart failure risk, and people with extremely aged skeletal myocytes had a 12.7-fold higher risk of developing ALS. Two patients can look identical on paper, Luthar said, same age, same gender, same diagnosis, and have “totally different underlying physiology, totally different reason for even having the same disease.” The proteome sees the difference. The intake form never will. Chen’s version runs through imaging and time. Not a single snapshot but a trend line: organ volumetrics, brain atrophy, liver iron, visceral fat, muscle composition, tracked against your own baseline rather than a reference range built from strangers. “Clinicians are as good as the data that we get,” she said, “so it’s not about getting massive amounts of data but getting the right data.” She also flagged the part that should interest anyone writing checks in this category. Interventions can now be audited per person. A treatment “supposed to help them” can be checked against whether it actually is, in that specific body, compared to cohorts that resemble them instead of a general population “where there could be people that have nothing, no characteristics like you.” So that’s the promise, and the market seems to think it is real. The precision medicine market ran between $110 billion and $119 billion in 2025 depending on whose model you trust, with forecasts in the $400 billion range within a decade. Multiomics is the small, fast piece: about $3.1 billion in 2025, projected past $12 billion by 2035. Measuring more of a healthy person is not the same as helping them, and medicine has learned this the hard way. Whole-body MRI screening for asymptomatic people confirms cancer in roughly 1.1% to 1.5% of scans while turning up a much larger pile of incidental findings. The American College of Radiology doesn’t recommend it for people without symptoms, risk fac-
GETTY
tors, or relevant family history, and JAMA has published against elective whole-body scans on overdiagnosis grounds. Patients get follow-up tests. Some get surgery for things that would never have hurt them. All of them get to carry the knowledge that something is in there. The genomics layer has its own asterisk. Luthar cited the MGH/MIT polygenic risk score for cardiovascular stratification, and polygenic scores do work as risk enhancers. They also inherit a structural bias: because most genome-wide association studies were run on people of European ancestry, the
scores predict less well for everyone else. In one Broad Institute validation cohort, there weren’t enough cardiovascular events among non-European ancestry groups to produce stable estimates. A tool that personalizes better for some patients than others is not a small footnote in a story about ending the average patient. To their credit, neither doctor oversold it. Chen was blunt that AI is “not at a point where clinical decisionmaking or judgment can be the end-all, be-all yet,” and that “humility in medicine” is part of the job. Her own operation runs a team of MD-
PhDs whose function is reading the thousands of studies published daily to sort what is evidence-based from what is merely interesting. That team exists because the field generates more claims than it does proof. Luthar’s framing of the near term is the honest one. Focus on early detection and lifestyle, and “help people live healthily up until some of these more revolutionary treatments can come down the pipeline.” Translation: the personalization is real, the therapeutics are not there yet, and the job right now is staying alive and in good repair long enough to use them.
WORTH.COM
FA L L 2 0 2 6
69
Clinically Ignored Three decades after women were mandated into clinical trials, medicine still doesn’t fully understand their biology, instead treating women as just smaller men—and it’s a $1 trillion blind spot. BY STEPHANIE MCNALLY, MD
T
he year is 1993, a time many remember for blockbuster movies like “Jurassic Park” and Whitney Houston’s hit, “I Will Always Love You.” I remember this year for an entirely different reason: it marked a pivotal legislative change—the passage of the National Institutes of Health (NIH) Revitalization Act. This landmark legislation mandated the inclusion of women and minorities in clinical research, a crucial step forward from an era in which white men were considered the physiological default in studies, assuming their biology accurately represented the entire population. Women were frequently prescribed medications and treatment regimens that had not been adequately tested or validated for their biology—the byproduct of a research culture that viewed female hormonal fluctuations not as a subject worth exploring, but as an obstacle to manage or avoid. That left significant knowledge gaps regarding drug efficacy, side effects, and disease progression in women and diverse populations.
70
FA L L 2 0 2 6
WORTH.COM
UNGRANTED Only an average of 10.5% of NIH research grants were allocated to women’s health from 2013 to 2021, even as the agency’s total budget grew significantly. The disparity holds even within well-studied diseases: women face a 50% higher mortality rate in the year following a heart attack, yet only 4.5% of the NIH’s coronary artery disease budget funds womenfocused research. Closing the global women’s health research gap could add an astonishing $1 trillion to the global GDP annually by 2040, according to the McKinsey Health Institute—proof that this is as much an economic opportunity as a clinical necessity. That figure is driven largely by women experiencing fewer health conditions—avoiding a combined 24 million years of life lost to disability, while adding up to $400 billion in productivity—along with expanded workforce partici-
GETTY
WOM E N
pation equivalent to 137 million women gaining full-time employment by 2040. The return on that investment is substantial: closing the gap is projected to generate roughly $3 in economic growth for every $1 spent, per the same McKinsey Health Institute analysis. That could help offset delayed diagnoses, ineffective treatments, and reduced quality of life for millions—factors I see daily in my practice, and ones that ripple into workforce participation, family well-being, and overall societal health. WRITTEN OUT OF THE DATA Conditions disproportionately affecting women remain profoundly underfunded relative to the burden they cause, a landmark 2024 report from the National Academies of Sciences, Engineering, and Medicine found—identifying a continued gap between disease burden and research investment. Endometriosis is a stark example: women often endure diagnostic delays of up to a decade, enduring prolonged suffering and confusing, suboptimal care—a direct result of systemic underfunding and the historic exclusion of women from clinical trials, which left critical gaps in our understanding of women’s physiology and disease progression. A misread study is still shaping how we treat menopause today. The Women’s Health Initiative (WHI) trial—halted prematurely in 2002 after early results showed higher rates of heart disease, stroke, and breast cancer among women on combined hormone therapy—triggered widespread alarm and a steep, lasting decline in hormone therapy prescriptions. But the study didn’t adequately differentiate outcomes by the timing of a woman’s menopausal transition,
a flaw that stalled research and education on perimenopause and menopause for years. I hear the fallout in my own conversations with patients almost daily. We cannot deny that biology matters. The SRY gene, for instance, plays a fundamental role in embryological development, signaling the creation of distinct male or female biological differences. These differences manifest in hormonal profiles, anatomy, and metabolism, profoundly influencing drug pharmacology and effectiveness.
“Women face a 50% higher mortality rate in the year following a heart attack, yet only 4.5% of the NIH’s coronary artery disease budget funds women-focused research.”
Women are disadvantaged— through lower efficacy, less access, or both—in 64% of medical interventions with sexdisaggregated data, compared to just 10% for men, according to a 2024 analysis of 183 widely used interventions. Baby aspirin is a familiar case: prescribed to reduce heart attack risk in men, it showed no similar benefit for women, though it did lower their stroke risk. Digoxin, used for heart failure, caused higher complications and toxic levels in women given the standard male dose. Researchers saw the same pattern with zolpidem until the FDA halved the recommended dose for women in 2013. Momentum is building. Melinda Gates’s Pivotal Ventures has directed significant donations toward women’s health research and education; the White House Initiative on Women’s Health Research and the NIH’s “Sex as a Biological Variable” policy—both launched in 2023–2024—now require researchers to account for sex in study design and analysis. But legislative recognition is outpacing the sustained, consistent government funding needed to back it up. To make this happen, the policy changes that began in 1993 need a cultural shift in how we approach medical research and healthcare delivery. Yes, that includes sustained, equitable funding for women’s health research. It also means embedding these priorities into medical school and residency education to inform and inspire the next generation of clinical experts. Ultimately, that’s one of our most fundamental tools in achieving genuine health equity and undoing the long-held, mistaken notion that women are simply tiny men. WORTH.COM
FA L L 2 0 2 6
71
LONG E VIT Y
The Cheapest Longevity Drug Is a Mindset
The optimizing class is spending billions to buy a few more years. Modern Elder Academy Founder Chip Conley says the highest-yield intervention costs nothing—and the wellness industry can’t bottle it. BY DAN COSTA
T
he longevity business has a pricing problem, and it isn’t the one you think. Walk the floor of any executive wellness conference, and you can watch capital move in real time. Continuous glucose monitors on people who don’t have diabetes. Full-body MRIs marketed as annual maintenance. Cold plunges, redlight beds, NAD drips, whole-genome sequencing, $40,000 diagnostic memberships that promise to catch the tumor before it announces itself. The global biohacking market ran somewhere between $38 billion and $45 billion in 2025, and the forecasters have it clearing $200 billion within a decade. The broader wellness economy is a $5.4 trillion machine. Every dollar of it is a bet that you can buy yourself more time. I spent a recent day hosting a longevity conference where that bet was the ambient religion. Then I sat down on stage with Chip Conley, beamed in to a full room, and he made the case to all of us that we were optimizing the wrong variable. Conley is not a wellness skeptic—he runs a school built on the science of living longer. But when I asked him, in front of that audience, what actually moves the needle, he didn’t reach for a supplement stack. He reached for Becca Levy’s work, a Yale epidemiologist who has worked extensively in the longevity space. “When you shift your mindset on aging from a negative to a positive,” he told me, “you gain seven and a half years of additional life.” Then the kicker, delivered without a setup: a pro-aging perspective “can actually extend your life more than any ice bath can.” In 2002, Levy, an epidemiologist at the Yale School of Public Health, published a study in the Journal of Personality and Social Psychology tracking 660 people over the age of 50. Those who held positive beliefs about their own aging lived, on average, 7.5
72
FA L L 2 0 2 6
WORTH.COM
years longer than those who didn’t. The effect held after controlling for age, gender, income, loneliness, and baseline health. And the attitudes had been recorded up to 23 years before the outcomes—so this wasn’t healthy people feeling cheerful. It was a mindset, measured decades earlier, predicting who was still alive. For scale: 7.5 years is a larger longevity gain than the ones associated with lower blood pressure, lower cholesterol, healthy weight, not smoking, or regular exercise. Levy’s mechanism is partly physiological—chronic stress from a grim self-narrative wears on the body—and partly behavioral: someone who believes later life is worth showing up for keeps moving, keeps eating well, keeps making the appointment. Economists have spent two decades mapping what David Blanchflower calls the U-curve of happiness: across 145 countries, life satisfaction sags through adulthood and bottoms out around age 47, then climbs again. The midlife trough is real, it’s global, and it lands squarely on the demo-
graphic with the disposable income to do something about it. Conley knows the curve intimately. His own late 40s were, by his account, a wreck—five friends lost to suicide between the ages of 42 and 52, a near-death experience from an allergic reaction, and no roadmap. “I didn’t really feel like I had much in the way of resources,” he said. The absence became the business plan. That business is the Modern Elder Academy, which Conley bills as the world’s first “midlife wisdom school.” The name comes from his second act: at 52, after selling his boutique hotel company at the bottom of the Great Recession, he was recruited by Airbnb’s twentysomething founders as their “modern elder”—someone, as they defined it, “as curious as they are wise.” He turned the idea into a campus. Then two. MEA now runs roughly 120 public workshops and 40 private retreats a year across a beachfront site in Baja and a 2,600-acre regenerative horse ranch outside Santa Fe. It has put close to 9,000 graduates through its doors, average age 54-55— right at the floor of the curve. The curriculum rests on four pillars: reframing aging, shifting from a fixed to a growth mindset, navigating transitions, and what MEA calls regeneration. Tuition for a weeklong workshop runs $4,000 to $5,500. For the money, you get surf lessons, beachside meditation, farmto-table dinners, and, by the accounts of alums, something less expected. One graduate, a facilitator herself, described a library curated not by subject but by provocative question, and rituals engineered to mark midlife the way weddings and graduations mark everything else—”rites of passage I didn’t know I needed.” Conley’s teaching leans hard on that rewiring, and it’s bracingly unsentimental. “Ten years from now, what will you regret if you don’t learn it or do it now?” At 20, he points out, you have no anticipated regret—the runway is endless. At 55, you do. “Anticipated regret,” he said, “is a form of wisdom.”
Stop Optimizing. Start Redesigning. Sensei’s Sarah Matyko on why healthspan isn’t a supplement or a hack—it’s the architecture of your daily life. BY WORTH STAFF
A
n industry-wide fixation on longevity has quietly crowded out a more important question: What good is more time if you spend it with poor quality of life? Longevity asks how long we can live. Healthspan asks how well. The signals that predict healthspan show up in mundane places: how well you slept, how clearly you’re thinking at 3 p.m., how quickly you recover from a hard week, whether you have the energy for the people and work that matter most. They don’t read as end-of-life concerns—but they’re the conditions that eventually shape them. That’s where Sarah Matyko, PhD, VP of Preventive Medicine and Scientific Affairs at Sensei, focuses her work. Sensei is a science-led wellness retreat with two U.S. campuses: Sensei Lāna‘i, A Four Seasons Resort, on Hawai‘i’s most secluded island, and Sensei Porcupine Creek in California’s Coachella Valley. THE SINGLE-FIX TRAP When people decide to get serious about their health, they usually look for one solution: a diet, a supplement, a workout protocol someone credible has sworn by. The appeal is understandable, but the body doesn’t work in single variables. “A supplement cannot carry chronic sleep debt,” Matyko says. “A diet cannot overcome a schedule that makes nourishment an afterthought.” The more useful question isn’t what to add—it’s what your environment is already deciding for you. Consistency is less a personality trait than an outcome of structure. “Most people think they need more discipline,” Matyko says. “Often, they need less friction.” Is movement built into the day’s rhythm, or does fitting it in require heroics? Is sleep protected, or negotiated away each night? That reframe sits at the center of Sensei’s approach. Rather than prescribing a rigid protocol, on-site specialists in movement, nutrition, mindset, and behavior change map the architecture of a guest’s life across three interconnected paths—Move, Nourish, Rest—treated as one system: how you move shapes how you recover, and how you rest shapes how you function. It’s also why more data isn’t the answer. Today’s high performer already tracks sleep scores, glucose, HRV, steps—dashboards that multiply at the cost of clarity. What’s missing is trusted interpretation: someone who sees the full picture and
knows what deserves attention first. That’s the Guide relationship at both campuses—not advice at scale, but personalized discernment. Sensei’s collections sharpen that further: Metabolic Health uses continuous glucose monitoring to show how nutrition, movement, sleep, and stress shape energy regulation; Cognitive Fitness examines how lifestyle shapes mental clarity and resilience. Guests at Sensei are typically excellent at producing results but rarely apply the same rigor to recovery, treating rest as a reward instead of the infrastructure that makes the next hard week sustainable. READING THE PATTERN Guests usually arrive convinced they have a discipline problem, but the assessment often reveals something else: that afternoon crash is more likely a sleep problem than a caffeine issue; that end-of-week depletion may be evidence the system isn’t designed to restore. “There is a palpable relief,” Matyko says, “when a high performer stops blaming themselves and starts seeing the pattern. The body was not failing them. It was responding honestly.” That shift—from “what’s wrong with me?” to “what is my body showing me?”—is where real change begins, creating agency without shame. For anyone just starting, Matyko’s advice is grounded: begin with the behaviors your body lives inside every day—sleep, movement, nourishment, recovery, connection. The most powerful healthspan work looks unremarkable: no dramatic reset, no single intervention, just ordinary patterns repeated until the better choice feels less like effort and more like who you are.
PA R T N E R C O N T E N T WORTH.COM
FA L L 2 0 2 6
73
GETTY
FORECAST
AI spending is propping up an economy that inflation says shouldn’t be this hot. Is the the Fed is behind the curve? (76). Robert Balentine walked away from a public company at the bottom of a crisis to rebuild his wealth management firm from scratch—40 years and $9 billion later, he’s teaching his own daughter the same lesson (78). Family offices now control more capital than the entire venture capital industry, and Wall Street is finally building infrastructure just to keep them as clients (80). Plus, Worth’s Leading Advisors of 2026 (83). WORTH.COM
FA L L 2 0 2 6
75
AT L A S R E P O R T
It’s Time for the Fed to Hike Interest Rates AI spending continues to support the economy, inflation remains well above the Fed’s target, and signs of a bubble in financial markets are emerging. BY LARRY KANTOR AND BOB DIAMOND
T
he policies of the current Administration have received a lot of attention, and that’s no surprise considering how much they’ve differed from historic norms. We’ve experienced:
• The biggest increase in tariffs in our lifetimes • A sharp drop in immigration and a surge in deportations • A war with Iran that has caused energy prices to soar These are all what economists call negative supply shocks, which raise prices and reduce output. Despite them, the U.S. economy and financial markets have performed remarkably well. That’s because we are in the midst of an historic technological spending boom. Global spending on data centers alone– heavily concentrated in the U.S. - is expected to amount to as much as $7 trillion (more than 20% of U.S. GDP) over the next few years. The net effect of all these influences has been solid economic growth, higher inflation, strong growth in corporate profits, a robust stock market and higher bond yields. This suggests that the current stance of monetary policy is stimulative at a time when inflation has been consistently above the Fed’s 2% target. New Fed Chair Kevin Warsh has been clear about his commitment to that inflation target, but the Federal Open Market Committee nevertheless decided to maintain its policy rate at its late July meeting. The financial market reaction reflected the need for higher rates by bidding up bond yields to their highest levels since 2007.
76
FA L L 2 0 2 6
WORTH.COM
The near-term outlook for the economy is bright because the burst of spending on AI shows no sign of slowing down. Both the users and producers of AI as well as their suppliers believe that it is critical to their future success and are competing for supremacy. Investors don’t want to be left behind either, so they continue to bid up stock prices. Higher energy prices usually bring demand destruction, but the income created by massive spending on AI is boosting overall demand. While second-quarter GDP growth slowed to 1.5% (from 2.1% in Q1), domestic demand (equal to consumer plus business spending) accelerated to 3.9%, up from 1.7% in Q1. Retail sales, car sales and travel are all strong, despite much higher prices for gasoline, electricity and airfares. Strong demand usually means a healthy labor market, and clear signs of improvement have appeared there as well (despite the weaker-than-expected jobs report for July). Job growth averaged 75,000 per month in the first half of this year compared with an average decline of 8,000 in the second half of last year. The unemployment rate has dropped from a peak of 4.5% in November to
4.1% in July. Jobless claims for unemployment insurance have moved down, consistent with a declining unemployment rate. The notion that AI will reduce overall employment is misguided. Hiring for some entry-level positions has slowed, but that is being more than offset by new jobs generated by the huge AI infrastructure buildout. Over time, new business lines will develop that were not available before the widespread adoption of AI. Recall that during the dotcom boom, online shopping was expected to kill retail stores, and it has displaced a significant number of jobs at many outlets. But that loss of employment has been more than offset by staffing at warehouses and an explosion in the delivery business. The Fed’s preferred inflation measure–the core PCE index–rose by 3.4% in the second quarter, down from 4.4% in Q1 but still well above its 2% target. Inflation is likely to remain elevated even as oil prices come back down. The pass-through from higher energy prices to related items takes several quarters to play out, and the costs of production inputs, transportation, and travel are all still rising. AI is presumed to be deflationary because it will automate work and increase productivity, and that will probably be the case eventually. But the building of AI is inflationary because it increases overall demand before the productivity gains fully materialize. Memory chip prices have surged after falling for most of their history, while the building of AI data centers is putting upward pressure on electricity prices. The implications for Fed policy are clear: It needs to begin raising rates now if it wants to lower inflation back to its 2% target. The Fed reduced short-term interest rates from well over 5% in August 2024 to just over 3.5% at the end of last year, where they are now. The driving force was a significant drop in job growth, from over 200,000 per month to modest net job losses. The labor market is now improving while the war with
Four Week Average of Unemployment Claims 4-week Moving Average of Initial Claims 240,000
230,000
220,000
210,000
200,000
190,000
Sept. 2025
Oct.
Nov.
Dec.
Jan. 2026
Feb.
March
April
May
June
July
Aug.
Source: FRED
Iran kicked off a significant rise in inflation. Even before that, inflation has been above the Fed’s 2% target for five years. The unemployment rate has moved down and nominal GDP growth has accelerated. Financial conditions remain significantly supportive: stock and bond issuance has surged, credit spreads are tight and the stock market is up solidly this year after a nearly 80% rise in the previous three years. While the outlook for both the economy and financial markets is positive for this year, there are signs of a bubble emerging. Technology revolutions that transform the economy have a long history of attracting more investment than near-term returns justify. The internet turned out to be the gamechanger everyone thought it would be, but that didn’t prevent stock prices from falling some 50% and dotcom stocks by even more. The AI buildout is by far the largest capital spending surge in U.S. history, swamping what was spent during the internet boom: U.S. investment dur-
ing the dot com boom doubled over 5 years; AI spending has skyrocketed by a factor of 4.5 in under 3 years. Investors have bid up the valuations of companies expected to dominate, lenders have funded an unprecedented infrastructure buildout, and suppliers have expanded to meet the demand. The economy has become reliant on AI investment at a time when near-term profit gains from AI are relatively small because it is not yet ready for full-scale deployment. Signs of excess in financial markets have already emerged. Private credit funds–which exploded after the financial crisis as regulations discouraged banks from making high interest loans– are now a $3 trillion industry, attracting both institutional and retail investors. They perform banking functions by taking in investor money and lending to companies that tend to have a high risk profile but are much less regulated. Banks have made an estimated $1.4 trillion in loans to private credit firms, which are now facing heavy withdrawal
demands. Meanwhile, margin debt has soared to record highs, implying considerable leverage in the stock market. Brokerages are tightening margin requirements, heightening vulnerability to a market correction. While we seem to be in a period of excess that will end badly at some point, it is very difficult to predict when bubbles burst, and they usually last longer than most expect. Former Fed Chair Alan Greenspan coined the term “irrational exuberance” during a sharp rise in the stock market in late 1996, and the internet bubble didn’t burst until March 2000. There were also signs of a bubble before the global financial crisis emerged: House prices in the U.S. peaked in early 2006, the Bear Stearns credit funds failed in June 2007 and the stock market didn’t crash until September 2008. The bottom line is that AI will probably deliver the super-charged productivity boost that markets expect, but getting there may involve an historic investment cycle, financial vulnerabilities and even a recession. WORTH.COM
FA L L 2 0 2 6
77
BALENTINE
Don’t Mistake Wealth for Legacy Robert Balentine left Wall Street in 1987, built a wealth management firm from scratch, sold it at the top of the market, then walked away from the company that bought it to start over. BY DAN COSTA
I
n September 2008, Robert Balentine was fly fishing in northern Mongolia when Lehman Brothers collapsed. He had already built one wealth management firm from nothing—founded with his father in 1987, grown to $4 billion in assets, sold to Wilmington Trust in 2002—and now the crisis was tearing through the institution that had bought it. A year later, he resigned as CEO of that publicly traded business, at the bottom of the worst market in a generation, to start over as an independent firm with no name recognition and no safety net. That decision is the spine of everything Balentine has built since. Today his Atlanta-based firm advises roughly 300 families on more than $9 billion in assets, and it remains employee-owned in an industry consolidating into private equity roll-ups. Balentine argues the misalignment is structural: an owner working toward an exit makes different decisions than one building something meant to outlast them—the same distinction at the center of First Generation Wealth, the 2021 book he co-wrote with CEO Adrian Cronje. He’s now making that case inside his own family. His daughter, Emily, made partner this year—the firm’s third generation. We talked about wealth, power, and the conversations his clients are most afraid to start.
LEGACY & FOUNDING VISION You left Wall Street in 1987 to start Balentine with your father. What convinced you there had to be a better way? My father and I had come to believe early on that the traditional, commission-based model created an inherent conflict—one that didn’t align with how we would want to be advised if we were the client. What compelled me to leave was a conviction around the fiduciary standard and an independent, open-architecture approach that put clients unequivocally first, which was far from the norm in 1987, and the opportunity to partner with my father. We were ahead of our time, but it was the right call that brought me to where I am today. You’re “second generation” in your own firm. What did you learn from your father that shaped how you rebuilt the business in 2009? Technically, I’m “second generation,” but my father and I started the firm together as 50/50 partners—so what I inherited from him wasn’t a business, it was a way of being. He was diagnosed with cancer just months after we launched, and in that short time, what stayed with me wasn’t strategy or structure, but his example of integrity, humility, and how you treat people when it matters most. He was my father, my best friend, and my partner—and when we rebuilt in 2009 without him, those values became the foundation for everything we set out to do. THE THREE PRINCIPLES Your first principle is “Don’t mistake wealth for legacy.” What’s that conversation like with a self-made entrepreneur who’s built a fortune? It’s often a reframing conversation, because many entrepreneurs are used to measuring success in very clear, quantitative terms—and that works in business. Still, it breaks down when you start talking about legacy. I’ll tell
78
FA L L 2 0 2 6
WORTH.COM
them that money may be how you keep score in the marketplace, but it’s not how your life will ultimately be measured—there are plenty of people with great wealth and little legacy, and others with modest means who leave an extraordinary imprint. The real work is helping them separate those two ideas and think more intentionally about what they want to be remembered for, beyond the balance sheet. How do you help a 70-year-old founder understand a 25-year-old heir who may not want to preserve the family business at all? This refers to our third principle, “See the world through the next generation’s eyes.” It starts with empathy—helping founders recognize that seeing the world through the next generation’s eyes is a discipline, not a given, and it requires setting aside their own assumptions about what success should look like. I encourage them to focus on passing down values and judgment, not just assets or a business, because legacy endures far better when it’s chosen rather than imposed. The wisest leaders I’ve seen are willing to let go—even when it’s difficult—because they understand that forcing either aptitude or desire rarely leads to a successful outcome. CRISIS & RESILIENCE You were fly fishing in Mongolia when Lehman collapsed. A year later, you walked away from a public company to rebuild Balentine. Why was that your best decision? During the financial crisis, we had the opportunity to leave a large institution and build the kind of firm we would trust with our own capital—because managing generational wealth requires a very different mindset than managing to quarterly earnings or a five-to-seven-year exit. There’s an inherent misalignment in those models, whether it’s public markets or private equity, that
makes it difficult to prioritize longterm stewardship, culture, and client trust. What we believed then—and still believe—is that wealth management is most credible in an independent, employee-owned firm, where a team of principled individuals is aligned around building something meant to endure. Balentine remains employeeowned in an era of private equity roll-ups. Why didn’t you sell, and what would outside capital destroy? We’ve been very intentional about staying employee-owned because the time horizon matters. Private equity, by design, is working toward an exit, while we’re building a firm meant to endure across generations. That misalignment shows up quickly in culture and decision-making; when you layer in rapid acquisitions or leverage, you inevitably start optimizing for short-term outcomes rather than long-term stewardship. Our goal is to preserve a model where ownership transitions to the next generation of advisors, so the people serving clients are the same ones thinking and acting like owners with real skin in the game. You’ve chaired major Atlanta institutions—the Symphony and the Woodruff Arts Center. What responsibility do people of significant wealth have beyond writing checks? I’ve come to believe that wealth carries a responsibility that goes well beyond writing checks—it’s about investing your time, your abilities, and your voice in the communities that made your success possible. In many cases, the institutions we value most are sustained largely by private leadership and engagement, not just public funding, which means they depend on people who are willing to show up and take ownership. There’s a moral dimension to that—being present, being engaged, and helping steward something that will endure beyond you.
You advise 300 families managing over $9 billion. What misconceptions do outsiders have about how the truly wealthy think about power? One of the biggest misconceptions is that wealth equates to excess or entitlement, when in my experience, particularly with first-generation wealth, it’s far more often accompanied by discipline, humility, and a deep sense of responsibility. Many of the wealthiest people I know live well below their means; they’re focused on building, preserving, and stewarding capital over time, not displaying it, which aligns more closely with what The Millionaire Next Door described decades ago. That said, the growing wealth gap is real and worth paying attention to— because over time, disparities in who participates in asset growth versus wage growth can create broader societal and economic tensions that none of us can afford to ignore. FUTURE & SUCCESSION Your daughter Emily just made Partner—third generation. What are you doing differently in succession than your father did with you? With Emily, the firm has been very intentional about letting her earn her election to partner—perhaps to a fault. We were so focused on avoiding any perception of favoritism that she was likely held back longer than her talent warranted. Over 16 years, she’s built a deep foundation across nearly every part of the firm. Now we’re seeing that compound quickly—what I’ve described to her as “black bamboo,” where the real growth happens after years of unseen work, just as the black bamboo grows its roots deeply before it flourishes above ground. What I’m most focused on now is encouraging her to trust her judgment and use her voice, because her emotional intelligence and instincts are among the strongest I’ve seen.
WORTH.COM
FA L L 2 0 2 6
79
Family Offices: The New Kid on Wall Street Family offices now control more capital than the entire global venture capital industry and are closing in on private equity. BY WORTH STAFF
H
illspire, Eric Schmidt’s family office, made 15 investments in 2025, most of them in artificial intelligence. They include a Paris-based AI voice startup, an open-source LLM, and a software platform for luxury travel and experiences. For the former Google CEO, his family office investments reflect his own career and expertise. That’s not an institution allocating capital on behalf of a diversified client base. It’s a family’s team, deploying their capital on their own timeline. And Hillspire is far from alone: family offices now control more capital than the entire global venture capital industry and are closing in on private equity.
80
FA L L 2 0 2 6
WORTH.COM
THE SCALE OF IT Every sufficiently large pool of capital eventually faces the same question as any growing company: is it cheaper to keep paying an outside vendor, or to build the capability in-house? For most of private wealth’s history, the math favored paying an outside vendor. Setting up an equivalent operation wasn’t worth the fixed cost. However, above a certain amount of capital, the math flips. Single-family offices alone oversee around $5.5 trillion in assets globally—Citi Wealth’s broader estimate puts the figure at $5.9 to $6.9 trillion. By various estimates, the global venture capital industry’s assets under management (AUM) run $1 trillion to $1.5 trillion; private equity’s is closer to $7 trillion to $10 trillion. And that $5.5 trillion figure reflects? That’s just single-family offices—if multiplefamily offices were included, family office prowess would be even more significant.
GETTY
FA M I LY O F F I C E
Back in 2019, the total estimated wealth for family offices was $3.3 trillion—meaning it has roughly doubled in six years. Deloitte expects it to reach $9.5 trillion by 2030, with the number of family offices worldwide growing more than 75% since 2020, to over 10,700. David Teten, Partner at Orange Collective and Founder of Investors for a Better America, compared the rise to the growth of hedge funds in the past 40 years. He told Worth, “Hedge funds are many hundreds of billions, they’re a whole category, and there’s a whole ecosystem of service providers around them. That’s what’s happening in family offices. They’re recruiting firms, tech providers, and so on. [Family offices are] institutionalizing; they’re competing with traditional financial players for talent, and they’re paying market rates. And there’s a whole ecosystem serving their needs.” The top family offices alongside Hillspire in 2025, like Jeff Bezos’ Bezos Expeditions, Peter Thiel’s Thiel Capital, and Barry Sternlicht’s Jaws Estates Capital, each manage at least $1 billion. And each employs investment professionals who source deals, run diligence, and shape day-to-day strategy. Wall Street has noticed. Goldman Sachs Private Wealth Management launched an Alternative Investment Platform for Wealth in July 2026, giving family offices and wealthy clients direct co-investment access to preIPO companies like SpaceX, Stripe, and Canva. A bank, built on controlling access to private deals, building infrastructure just to keep family offices as clients is itself a concession of how much leverage this money now has. The generational wealth transfer now underway has been forecast to be the largest in American history: Cerulli Associates projects $124 trillion will pass from Baby Boomers and older generations to heirs and charities by 2048, with high-net-worth and ultra-high-net-worth households alone accounting for $62 trillion of
that—half the total, despite representing a tiny fraction of U.S. households. According to Bank of America Private Bank’s 2026 Study of Wealthy Americans, how wealthy Americans acquire their businesses has essentially reversed since 2022: the share who inherited a business jumped from 5% to a projected 23%, while the share who bought one outright fell from 28% to 11%. The shift from acquisition to inheritance is already reshaping how families structure their capital: rather than defaulting into institutional funds built for someone else, they’re building family offices designed around their unique goals, timeline, and next generation. WHERE FAMILY OFFICES WIN Seventy percent of family offices surveyed by Citi said that they were making direct investments, allowing them to compete directly with PE and VC. First, family offices sit outside a regulatory framework almost no one else in the industry escapes entirely. Registered investment advisers must file a public Form ADV disclosing their assets, fees, and disciplinary history. Even venture funds that skip full registration still file as Exempt Reporting Advisers, putting basic figures in the SEC’s public database. A 2011 rule, mandated by Dodd-Frank, excludes family offices from that framework altogether—no filing of any kind—as long as they invest solely on behalf of one family.
“Offices sit outside a regulatory framework almost no one else in the industry escapes entirely.”
Family offices can also offer flexibility. They are often looking to make decisions more quickly than PE/VC, making them enticing to founders, who might also want a speedy turnaround. Unlike VC and PE funds, which typically operate on 7-10-year fund cycles with fundraising and exit pressure built in, family offices deploy permanent or multi-generational capital with no limited partner (LP) redemption clock. This lets them hold through downturns, back longer-duration bets, and negotiate more flexible deal terms. Unlike institutions, they can engage in early risk-taking, distressed or illiquid opportunities, and blended structures, such as structures that are partially philanthropic and partially commercial. THE LIMITS, AND THE LESSONS Despite family offices’ ability to curate personal relationships, it’s difficult to quickly mirror the institutionalized, tried-and-true methods of PE/VC. Ethan Werner, Principal at Bluelake.vc, emphasized that the strategic insight venture capitalists have simply can’t be matched by a single-family office. “To a founder that already has enough capital available to him, he’s looking for strategic value, or a value add. [A family office] can’t really provide that value as we can with bringing new business, or helping them fundraise, or all these other things. And so, aside from finding the opportunities in the first place, we go to conferences, we have friends emailing us deals, and aside from that, it’s actually providing enough of a value to deserve and earn a spot on the cap table,” he told Worth. Scale gets a family office into the room. It doesn’t buy the sourcing networks, the diligence teams, or the founder relationships that institutional firms have spent decades building.
WORTH.COM
FA L L 2 0 2 6
81
FA M I LY O F F I C E That capability gap has a flip side, though: family offices don’t need to build what they can rent. A growing ecosystem of outsourced CIOs, specialized recruiters, and deal-access platforms exists specifically to sell single-family offices the diligence teams, sourcing pipelines, and specialized expertise that would otherwise take a PE or VC firm years to build in-house. Deal flow runs on a similar logic. PE and VC firms often source deals through an established brand in a given sector—founders and other investors bring them opportunities because everyone already knows what the firm invests in and how it operates. A family office can’t build that same brand-based pull without becoming genuinely large, or without a principal famous enough to substitute for one; Thiel Capital and Bezos Expeditions get deal flow because of who’s attached to them, not because of a decades-old sourcing reputation VCs work to build. For a family office that’s neither huge nor helmed by a household name, that’s a real limit—and not one patient capital or a lighter compliance load does anything to fix. Where family offices do have an edge over PE and VC is in what they’re structurally not exposed to: the fee-and-fundraising pressure that a fixed-life fund puts on its own managers to deploy committed capital and stay competitive on hot deals. A family office isn’t exposed to that particular pressure, because there’s no outside LP base asking when the money comes back. That’s not the same as being immune to risk more broadly. Permanent capital removes the specific pressure behind PE and VC’s mostdocumented mistakes. It doesn’t remove risk itself. FAMILY, NOT FIRM Family offices spend more time than PE or VC on one thing in particular: supporting the family’s own operating business and preparing the next generation to take
82
FA L L 2 0 2 6
WORTH.COM
over. Since the office manages its own money rather than someone else’s, it’s natural for its bets to track the family’s own interests— which can mean investing in the very businesses its leaders know best, just like Hillspire. That personal-ties advantage extends to how family offices develop their own people, including preparing the next generation, or Next Gen, to eventually take over. Monish Verma, Founding Partner and CEO at Vardhan Wealth, an RIA that specializes in providing family office services to UHNW families, emphasized to Worth the importance of passing on not only wealth, but values, to those in the family. “[UHNWIs] want [the Next Gen] to be out there helping. They want them to have some flexibility in their work schedule so they can do that. And then, you know, educating them why it’s so important to give back.” Verma also emphasized that many of the families his office works with are the very first generation of wealth, making the aspects of giving back and true understanding of the family’s journey even more important.
“Where family offices do have an advantage over PE and VC in what they’re structuraturally not exposed to: the fee-and-fundraising pressure that a fixed-life fund puts on its own managers to deploy committed capital and stay competitive on hot deals.”
For single-family offices, professionals often enter after years of working with the family in different capacities, like a former business partner or trusted advisor. That’s part of why family offices end up as something closer to a jack-of-alltrades practice than a pure investment shop—expected to carry deep expertise in alternative investments and portfolio construction alongside tax preparation, trust and estate work, and legal demands. Verma mentioned that he’s had clients ask for his advice on everything from private security to which car color to choose. The same white-glove approach extends to those the families are making deals with, as well. Personal relationships build clever agreements and deep networks. Conversations are not only being held “behind closed doors,” but in rooms that the rest of the private markets aren’t even aware exist. LOOKING FORWARD As the family office industry matures, prime talent will not only be attracted to the traditional routes of private equity or venture capital, but also to family offices. Growth and standardization are giving family offices access to the same tools PE and VC have always had. What they’re not inheriting along with those tools is the incentive structure that produced some of those industries’ costliest mistakes—the fund clock that forces bad-timed exits, the fee model that rewards extraction over stewardship, the pressure to chase whatever deal everyone else is chasing. Wealthy families didn’t set out to build a rival to Wall Street. They set out to keep control of money that, for a growing share of them, was inherited— and once there was enough of it, to stop paying someone else’s fee for infrastructure they could build themselves. As $124 trillion changes hands over the next two decades and family offices keep absorbing capital that used to flow through funds, the story worth watching is whether an industry built to answer to one family can keep learning from institutions’ mistakes as fast as it’s starting to replace them.
LE A D I N G A DVI SO R S
2026
Worth’s Leading Advisors of 2026
GETTY
In an era of dynamic shifts in financial landscapes and the increasing intricacy of personal wealth management, Worth magazine understands the necessity for guidance that anticipates the needs of the affluent. The Leading Advisors program, which has been recognizing top-tier wealth management firms since its establishment in 2002, relaunched in 2024 with a fresh, data-driven focus. This reinvigoration is more than just a renewal of commitment; it’s a direct response to the evolving demands of our readers searching for reliable and insightful financial stewardship. The genesis of the Leading Advisor program was to spotlight the prowess and integrity of independent Registered Investment Advisor (RIA) firms that stand out in a crowded marketplace. However, as the financial world has grown in complexity, so too have the concerns of our readers. High-net-worth individuals face various challenges, from navigating volatile markets to planning for intergenerational wealth transfer, requiring sophisticated and personalized advice. The program aims to address today’s turbulent financial environment by providing a curated list of advisors who are leaders in their field and pioneers in adapting to market changes and the evolving needs of affluent clients. Working with our partners at ISS Market Intelligence, Worth’s editorial staff evaluated more than 41,000 RIAs and financial advisors in the United States and identified the top 428 firms.
Leading Advisor Criteria The core value of the Leading Advisor program lies in its rigorous selection process and the credibility it bestows upon listed advisors. Each firm featured has successfully cleared stringent benchmarks: Assets Under Management (AUM) of Over $500 Million: Demonstrates substantial experience and trust in handling significant wealth.
n
Predominantly High-Net-Worth Clients: Shows specialized expertise in managing the complex financial situations typical of wealthier clients.
n
Substantial Planning Clientele: Indicates a focus on comprehensive financial planning rather than simple asset management.
n
Independence from Broker-Dealers: Ensures advice is unbiased and purely client-centric.
n
WORTH.COM
FA L L 2 0 2 6
83
LE A D I N G A DVI SO R S These criteria spotlight firms that manage wealth and craft tailored strategies considering the broader financial picture. Thus, they enhance our readers’ ability to make informed choices about who manages their wealth. Editorial Integrity and Independence At Worth, our commitment extends far beyond the mere presentation of data. The Leading Advisor program is constructed on a bedrock of editorial integrity and independence, devoid of any influence from the firms we evaluate. This independence is pivotal in upholding our readers’ trust and ensures that our listings genuinely reflect merit and excellence in wealth management. Our methodology is transparent and comprehensive, ensuring that the advisors we feature are among the industry’s best. We believe in the importance of not just growth but growth by design. This means that our featured firms are
A Renewed Commitment to Excellence The of the Leading Advisor program affirms Worth’s dedication to excellence in financial journalism and our commitment to serving as a vital resource for the high-net-worth community. Worth is more than a magazine; it’s a platform where the best in the business converge to discuss, innovate, and shape the future of wealth management. We will update The Leading Advisor list annually as new company data is released. To learn more about the list or license the Leading Advisor logo email Matt.McCann@Worth.com.
Anderson Growth Partners LLC Birmingham, AL 205-909-0950
Blume Capital Management Inc. Berkeley, CA 510-549-3534
Financial Alternatives Inc. La Jolla, CA 858-459-8289
Sivia Capital Partners LLC Mill Valley, CA 415-231-7490
Sand Hill Global Advisors LLC Palo Alto, CA 650-854-9150
BMSS Wesson Wealth Solutions Birmingham, AL 205-982-5555
Intelligence Driven Advisers LLC Carlsbad, CA 888-401-2083
Halbert Hargrove Long Beach, CA 562-435-5657
Integris Wealth Management LLC Monterey, CA 831-333-1717
RPG Investment Advisory LLC Pleasanton, CA 925-384-0071
The Arkansas Financial Group Inc. Little Rock, AR 501-376-9051
Gould Asset Management LLC Claremont, CA 909-445-1291
Wealth Architects LLC Mountain View, CA 650-325-9044
Avalon Capital Management Redwood City, CA 650-306-1500
Versant Capital Management Inc. Phoenix, AZ 602-635-3760
Pacific Capital Corona, CA 844-777-8777
ARQ Wealth Advisors LLC Scottsdale, AZ 480-214-9572 Ironwood Investment Counsel LLC Scottsdale, AZ 480-609-4700
84
actively enhancing their capabilities and offerings to serve their clients better, not merely growing their assets under management by riding market trends.
Check Capital Management Inc. Costa Mesa, CA 714-641-3579 Weatherly Asset Management Del Mar, CA 858-259-4507
Sensible Money LLC Scottsdale, AZ 480-719-7290
Running Point Capital Advisors LLC El Segundo, CA 424-502-3501
Cambridge Financial Group LLC Tucson, AZ 520-531-0550
Morling Financial Advisors LLC Fremont, CA 844-667-5464
Morton Wealth Agoura Hills, CA 818-222-4727
Slow Capital Inc. Greenbrae, CA 415-727-7569
Lodestar Private Asset Management LLC Alamo, CA 925-838-1234
AlphaCore Capital LLC La Jolla, CA 858-875-4100
FA L L 2 0 2 6
WORTH.COM
Evoke Advisors Los Angeles, CA 424-372-1776 Oakmont Corporation Los Angeles, CA 213-891-6300 SEIA Los Angeles, CA 310-712-2323 Signature Estate & Investment Advisors Los Angeles, CA 310-712-2323
Beacon Pointe Advisors LLC Newport Beach, CA 949-718-1600 Knightsbridge Wealth Management Newport Beach, CA 949-644-4444
Creative Capital Management Investments LLC San Diego, CA 619-298-3993 Atlas Capital Advisors Inc. San Francisco, CA 415-354-2400
Tarbox Family Office Inc. Newport Beach, CA Baker Street Westmount Partners LLC 949-721-2330 Advisors LLC Los Angeles, CA San Francisco, CA 310-556-2502 415-344-6180 Liberty Wealth Management LLC Legacy Capital Group Oakland, CA BakerAvenue 510-903-5489 San Francisco, CA California Inc. 415-986-1110 Los Gatos, CA 408-399-6330 Veris Wealth Partners Chequers Financial LLC Monograph Wealth Oakland, CA Management LLC 415-814-0580 San Francisco, CA Advisors LLC 415-964-5001 Manhattan Beach, CA 310-496-7377 Bell Investment Advisors Fort Point Capital Inc. Lyell Wealth Orinda, CA Partners LLC 510-433-1066 San Francisco, CA Management LP 415-449-0570 Menlo Park, CA 650-353-3692 Frank, Rimerman Mission Creek Capital Advisors LLC Palo Alto, CA Partners Inc. 650-845-8100 San Francisco, CA 415-363-0400
One Wealth Advisors LLC San Francisco, CA 415-729-1770
Angeles Wealth Management LLC Santa Monica, CA 310-393-6300
Bourgeon Capital Management LLC Darien, CT 203-280-1170
Osborne Partners San Francisco, CA 415-362-5637
Willow Creek Wealth Management Inc. Sebastopol, CA 707-829-1146
Connecticut Wealth Management LLC Farmington, CT 860-470-0290
Blankinship & Foster LLC Solana Beach, CA 858-755-5166
AdviceOne Advisory Services LLC Glastonbury, CT 860-659-4900
Burton Enright Welch Walnut Creek, CA 925-932-8010
Rossmore Private Capital LLC Glastonbury, CT 860-200-6079
Seven Post Investment Office LP San Francisco, CA 415-341-9300 WP Advisors LLC San Francisco, CA 415-777-2900 BetterWealth LLC San Jose, CA 408-659-2390 Clarity Wealth Advisors San Jose, CA 408-560-3220 Silicon Valley Capital Partners LP San Jose, CA 408-236-7300 Cardiff Park Advisors San Marcos, CA 760-635-7526 Bailard Inc. San Mateo, CA 650-571-5800 IEQ Capital LLC San Mateo, CA 650-581-9807 Neumann Capital Management San Mateo, CA 650-548-9200 Summitry LLC San Mateo, CA 650-212-2240 Team Hewins LLC San Mateo, CA 650-620-3040 Fiduciary Financial Group LLC San Rafael, CA 415-352-1100 Mission Wealth Management LP Santa Barbara, CA 805-882-2360
Capital Advantage Inc. Walnut Creek, CA 925-299-1500 Destination Wealth Management Walnut Creek, CA 925-935-2900 BSW Wealth Partners Boulder, CO 303-444-9696 Colorado Capital Management Boulder, CO 303-444-9300 Align Impact LLC Denver, CO 805-243-8055 Bason Asset Management Denver, CO 720-446-8555 IWP Wealth Management LLC Denver, CO 720-328-9700 JFG Family Office Denver, CO 720-475-1195 Schaefer Financial Management Inc. Englewood, CO 303-770-6700 Matson Financial Advisors Inc. Danbury, CT 203-743-0131
Greenwich Wealth Management LLC Greenwich, CT 203-618-0100
RZH Advisors LLC Stamford, CT 203-355-0880 Fierston Financial Group Inc. West Hartford, CT 860-521-2100
Evensky & Katz/Foldes Wealth Management Miami, FL 305-448-8882 GenTrust Miami, FL 305-677-6688
Coastal Bridge Advisors Westport, CT 203-683-1530
Sanctuary Advisors LLC Miami, FL 317-975-7729
Geometric Wealth Advisors LLC Washington, DC 973-525-4901
Aviance Capital Partners LLC Naples, FL 239-598-4747
Clariti Wealth Advisors Wilmington, DE 302-994-4444
American Financial Advisors Inc. Winter Park, FL 407-207-9006
Palisades Hudson Asset Management LP Fort Lauderdale, FL Bradley Foster & Sargent 954-524-5552 Inc. Hartford, CT Tobias Financial 860-527-8050 Advisors Fort Lauderdale, FL Main Street Research LLC 954-424-1660 Lakeville, CT 860-435-2350 Koss-Olinger Consulting LLC Principle Wealth Gainesville, FL 352-373-3337 Madison, CT 203-318-8892 Intrepid Capital Gilman Hill Asset Management Inc. Jacksonville Beach, FL Management LLC 904-246-3433 New Canaan, CT 203-571-0225 SlateStone Wealth LLC HTG Investment Advisors Jupiter, FL 561-244-2504 Inc. New Canaan, CT 203-972-8262 Rainey & Randall Wealth Advisors, Inc. Kissimmee, FL Kreitler Financial LLC 727-344-7711 New Haven, CT 203-867-4396 Core Wealth Advisors Clear Harbor Asset Inc. Lakeland, FL Management LLC 863-904-4745 Stamford, CT 212-867-7310 Wealth Care LLC Granite Group Advisors Merritt Island, FL 321-543-1099 LLC Stamford, CT 203-210-7814 Element Pointe Family Office Jackson, Grant Miami, FL Investment Advisers Inc. 786-655-9790 Stamford, CT 203-322-1198
Balentine Atlanta, GA 404-537-4800 Regent Peak Wealth Advisors LLC Atlanta, GA 470-867-3550 Sage Mountain Advisors LLC Atlanta, GA 404-795-8361 SignatureFD LLC Atlanta, GA 404-253-7600 Waypoint Wealth Counsel LLC Atlanta, GA 404-955-7481 ZWJ Investment Counsel Inc. Atlanta, GA 404-873-2211 Chatham Capital Group Inc. Savannah, GA 912-691-2320 Southeast Asset Advisors, LLC Thomasville, GA 229-226-8839 West Financial Advisors LLC Des Moines, IA 515-284-1011
WORTH.COM
FA L L 2 0 2 6
85
LE A D I N G A DVI SO R S Syverson Strege West Des Moines, IA 515-225-6000 Aspen Capital Management LLC Boise, ID 208-345-0174 Perspective Wealth Partners LLC Boise, ID 208-429-0960 The Caprock Group LLC Boise, ID 208-368-9600 Summit Wealth and Retirement Partners Eagle, ID 925-927-1900 Onyx Financial Advisors LLC Idaho Falls, ID 208-522-6400 Chesley, Taft & Associates LLC Chicago, IL 312-873-1260 Chicago Partners Investment Group LLC Chicago, IL 312-284-6363 Cresset Asset Management LLC Chicago, IL 312-429-2400 Factor Wealth Management Chicago, IL 312-644-5040 Financial Solutions Advisory Group Chicago, IL 773-714-1540 Fountainhead Financial LLC Chicago, IL 312-222-9840 Gresham Partners LLC Chicago, IL 312-960-0200 HighTower Advisors LLC Chicago, IL 312-962-3800
86
FA L L 2 0 2 6
WORTH.COM
Oak Family Advisors LLC Resource Financial Chicago, IL Group Ltd. 312-373-7221 Wilmette, IL 847-256-7495 Studio Investment Goelzer Investment Management Chicago, IL Management 312-399-0828 Carmel, IN 317-264-2600 The Mather Group LLC Chicago, IL Halter Ferguson 888-537-1080 Financial Inc. Carmel, IN Urban Financial Advisory 317-875-0202 Corporation Chicago, IL Oxford Financial 312-379-0150 Group Ltd. Carmel, IN 317-843-5678 Vivaldi Capital Management LP Chicago, IL Valeo Financial 312-248-8300 Advisors LLC Carmel, IN 317-218-6000 Zuckerman Investment Group Chicago, IL Galecki Financial 312-948-8000 Management Inc. Fort Wayne, IN JMG Financial Group Ltd. 260-436-8525 Downers Grove, IL 630-571-5252 Vestia Personal Wealth Advisors Coyle Fort Wayne, IN 877-669-1126 Glenview, IL 847-441-5644 Bedel Financial Aberdeen Wealth Consulting Inc. Indianapolis, IN Management LLC 317-843-1358 Lake Bluff, IL 312-456-3315 Elser Financial Crescent Grove Planning Inc. Indianapolis, IN Advisors 317-731-5615 Lake Forest, IL 847-752-0292 Fi3 Financial Mowery & Schoenfeld Advisors LLC Wealth Management LLC Indianapolis, IN 317-426-8800 Lincolnshire, IL 847-247-8959 Northwest David Vaughan Financial Services Investments LLC Inc. Peoria, IL Indianapolis, IN 309-685-0033 317-844-0448 Choreo LLC Rockford, IL 888-312-2467 ShankerValleau Wealth Advisors Inc. Skokie, IL 847-475-2900
Quantum Financial Services Inc. Indianapolis, IN 317-845-1786 Wallington Asset Management Indianapolis, IN 317-575-8670
Creative Planning Leawood, KS 866-909-5148 Stepp & Rothwell Inc. Overland Park, KS 913-345-4800 Saling Wealth Advisors Louisville, KY 502-805-3000 FPL Capital Management LLC Metairie, LA 504-828-1969 Waters, Parkerson & Co. LLC New Orleans, LA 504-581-2022 Cabot Wealth Management Beverly, MA 978-745-9233 Aureus Asset Management LLC Boston, MA 617-728-8900 Birch Hill Investment Advisors LLC Boston, MA 617-502-8300 Choate Investment Advisors Boston, MA 617-973-4900 Crestwood Advisors Boston, MA 617-523-8880 Great Point Wealth Advisors LLC Boston, MA 617-585-0050 Loring, Wolcott & Coolidge Fiduciary Advisors LLP Boston, MA 617-523-6531 Moody, Lynn, Lieberson & Walker LLC Boston, MA 617-973-0590 O’Rourke & Company, Incorporated Boston, MA 617-482-4200
Reynders, McVeigh Capital Management LLC Boston, MA 617-226-9999 Riverview Capital Advisers LLC Boston, MA 617-423-0080 RWA Wealth Partners Boston, MA 857-255-2100 SCS Capital Management LLC Boston, MA 617-204-6400 Single Point Partners Boston, MA 617-600-0510 TFC Financial Management Inc. Boston, MA 617-210-6700 Twin Focus Capital Partners LLC Boston, MA 617-720-4500 Welch & Forbes LLC Boston, MA 617-523-1635 Zevin Asset Management LLC Boston, MA 617-742-6666 Pinney & Scofield Inc. Cambridge, MA 617-492-6223 Gray Private Wealth LLC Canton, MA 781-232-2020 Monument Group Wealth Advisors LLC Concord, MA 978-369-7705 Florek Financial LLC Duxbury, MA 781-934-9400 One Charles Private Wealth Hingham, MA 617-337-4208 Sandy Cove Advisors LLC Hingham, MA 617-622-1500
Wingate Wealth Advisors Inc. Lexington, MA 781-862-7100
Heritage Investors Management Corp. Bethesda, MD 301-951-0440
Lifecycle Financial Planners Bloomfield Hills, MI 248-737-7090
JVL Wealth Strategies Wyoming, MI 616-261-2800
Focus Partners Wealth LLC Saint Louis, MO 314-725-0455
Arjuna Capital LLC Manchester, MA 978-704-0112
LGG Financial Bethesda, MD 301-312-6660
Boston Research and Management Inc. Manchester, MA 978-526-9700
Pennington Partners & Co. LLC Bethesda, MD 202-370-6435
Northern Financial Advisors Inc. Bloomfield Hills, MI 248-985-1632
The Advocate Group LLC Hopkins, MN 952-693-2630
Foundation Wealth Management LLC Saint Louis, MO 314-726-6789
Blue Chip Partners LLC Farmington, MI 248-848-1111
IFG Advisors LLC Saint Louis, MO 314-569-0500
Mayport Wealth Management Newton, MA 617-545-5700
Trumbower Financial Advisors LLC Bethesda, MD 301-215-8340
Accredited Investors Wealth Management Minneapolis, MN 952-841-2222
Fiduciary Wealth Partners LLC Newton Lower Falls, MA 617-602-1900
Warner Financial Inc. Bethesda, MD 301-961-9505
Ballentine Partners Waltham, MA 781-314-1300
Cornerstone Advisory Cockeysville, MD 410-468-1693
Montis Financial LLC Waltham, MA 781-541-5057
Marathon Capital Management Cockeysville, MD 410-329-1522
L2 Asset Management LLC Wayland, MA 508-350-7150 New England Private Wealth Advisors LLC Wellesley Hills, MA 781-416-1700 Stage Harbor Financial Westwood, MA 781-934-3130 Carl P. Sherr & Co. LLC Worcester, MA 508-791-7126 Lafayette Investments Inc. Ashton, MD 301-570-2959 &Wealth Partners Baltimore, MD 410-844-3300 Brown Advisory Baltimore, MD 410-537-5400 Aegis Wealth Bethesda, MD 301-664-2313
Black Diamond Financial LLC Lutherville Timonium, MD 443-841-7772 WBH Advisory Inc. Pikesville, MD 410-653-7979 Kendall Capital Management Rockville, MD 301-838-9110 MaineGreat Diamond Partners LLC Portland, ME 207-274-2500 HeadInvest Portland, ME 207-773-5333 Portland Global Advisors LLC Portland, ME 207-773-2773 R M Davis Inc. Portland, ME 207-774-0022
Grand Wealth Management LLC Grand Rapids, MI 616-451-4228 LaFleur & Godfrey Private Wealth Management Grand Rapids, MI 616-942-1580 NPF Investment Advisors Grand Rapids, MI 616-459-3421 Sigma Investment Counselors Northville, MI 248-223-0122
Palisade Asset Management LLC Minneapolis, MN 612-455-2900 Punch & Associates Investment Management Inc. Minneapolis, MN 952-224-4350 SilverOak Wealth Management LLC Minneapolis, MN 952-896-5700 NavPoint Financial Inc. Prior Lake, MN 952-746-1115
Provident Investment Management Inc. Novi, MI 248-380-1700
Dougherty Wealth Advisers LLC Wayzata, MN 612-376-4040
LVM Capital Management Ltd. Portage, MI 269-321-8120
High Note Wealth LLC Wayzata, MN 952-224-7970
Zhang Financial Portage, MI 269-385-5888 Arbor Wealth Advisors LLC Troy, MI 855-927-2679 Baron Wealth Management LLC Troy, MI 248-251-0161 ISTO Advisors LLC Troy, MI 248-458-1100 MKD Wealth Troy, MI 248-418-5100
Acropolis Investment Management Chesterfield, MO 888-882-0072 Atwood & Palmer Inc. Kansas City, MO 816-931-2266 Argos Capital Partners LLC Saint Louis, MO 314-898-9893 Clayton Financial Group LLC Saint Louis, MO 314-446-3250
Moneta Group Investment Advisors LLC Saint Louis, MO 314-726-2300 Plancorp LLC Saint Louis, MO 636-532-7824 Precision Wealth Strategies LLC Saint Louis, MO 314-994-6460 Sunpointe Investments Saint Louis, MO 314-880-0821 Hardy Reed LLC Tupelo, MS 662-823-4722 Stack Financial Management Inc. Whitefish, MT 406-862-8000 Veratis Advisors Inc. Cary, NC 919-460-8875 Delegate Advisors LLC Chapel Hill, NC 919-932-8400 Hamilton Point Investment Advisors LLC Chapel Hill, NC 919-636-3765 Old Peak Finance Chapel Hill, NC 919-459-8181 Woodward Financial Advisors Inc. Chapel Hill, NC 919-929-2495
WORTH.COM
FA L L 2 0 2 6
87
LE A D I N G A DVI SO R S Alpha Financial Advisors, LLC Charlotte, NC 704-716-1100
CMH Wealth Management LLC Portsmouth, NH 603-379-8161
Biltmore Family Office LLC Charlotte, NC 704-248-5230
Black Coral Financial Advisors LLC Budd Lake, NJ 973-352-8600
Colony Family Offices LLC Charlotte, NC 704-285-7300
Chatham Wealth Management Chatham, NJ 973-635-4275
Defender Capital Charlotte, NC 704-373-1716
Covenant Asset Management LLC Chester, NJ 908-879-4090
MBL Advisors Charlotte, NC 704-333-8461
Personal CFO Solutions LLC Chester, NJ 908-955-7055
Novare Capital Management Charlotte, NC 704-334-3698 Verum Partners LLC Charlotte, NC 980-771-3999 Smith Salley Wealth Management Greensboro, NC 336-379-7556
Pathstone Englewood, NJ 201-944-7284 Oliver Luxxe Assets LLC Gladstone, NJ 908-741-4884 The Genwealth Group Inc. Maplewood, NJ 973-761-0400
BlueSky Wealth Advisors Parisi Gray Wealth Legacy LLC New Bern, NC Management LLC 252-633-0107 Mendham, NJ 973-358-4921 Financial Symmetry Inc. Raleigh, NC McRae Capital 919-851-8200 Management Inc. Morristown, NJ 973-387-1080 Live Oak Private Wealth LLC Wilmington, NC Private Advisor 844-469-5679 Group LLC Morristown, NJ 973-538-7010 Milestone Financial Planning LLC Bedford, NH Simon Quick 603-589-8010 Advisors LLC Morristown, NJ 973-525-1000 The Harbor Group Inc. Bedford, NH 603-668-0634 GSG Advisors LLC Mount Laurel, NJ Clark Asset Management 856-234-9595 LLC Portsmouth, NH Accretive Wealth 603-237-1341 Partners LLC Parsippany, NJ 973-970-2627
88
FA L L 2 0 2 6
WORTH.COM
Roundview Capital LLC Princeton, NJ 609-688-9500
Wealthspire Advisors Melville, NY 631-227-3900
NCM Capital Management LLC Ramsey, NJ 201-529-1429
BBR Partners LLC New York, NY 212-313-9870
Regency Wealth Management Ramsey, NJ 201-447-5850 Circle Wealth Management LLC Summit, NJ 908-206-1306 Modera Wealth Management LLC Westwood, NJ 201-768-4600 The Investment Counsel Company Las Vegas, NV 702-871-8510 Independent Family Office LLC Albany, NY 518-452-8050 Ogorek Wealth Management LLC Buffalo, NY 716-626-5000 Sanderson Wealth Management LLC Buffalo, NY 716-566-2420 Hollow Brook Wealth Management LLC Katonah, NY 212-364-1848 Frisch Financial Group Inc. Melville, NY 516-694-7900 Heller Wealth Management Melville, NY 631-248-3600 Wealthspire Advisors Melville, NY 631-227-3900
Bridgewater Advisors Inc. New York, NY 212-221-5300 Capital Counsel LLC New York, NY 212-350-9333 Cerity Partners LLC New York, NY 212-850-4260 Circle Advisers Inc. New York, NY 212-885-4200 Douglas C. Lane & Associates New York, NY 212-262-7670 Ehrenkranz Partners L.P. New York, NY 212-891-8600 Ellevest New York, NY 844-355-7100 Joel Isaacson & Co. LLC New York, NY 212-302-6300
Silvercrest Asset Management Group LLC New York, NY 212-649-0600 Tiedemann Advisors LLC New York, NY 212-396-5900 Williams Jones Wealth Management LLC New York, NY 212-935-8750 Howe and Rusling Inc. Rochester, NY 585-325-4140 Shade Tree Advisors LLC Saratoga Springs, NY 518-290-9460 Tortoise Investment Management LLC West Harrison, NY 914-686-0024 Matrix Asset Advisors Inc. White Plains, NY 212-486-2004 The Portfolio Strategy Group LLC White Plains, NY 914-288-4900 Capital Advisors Ltd. LLC Beachwood, OH 216-295-7900
Bahl & Gaynor Inc. Klingman and Associates Cincinnati, OH 513-287-6100 LLC New York, NY 212-867-7647 Bartlett & Co. Wealth Management LLC MIO Partners Inc. Cincinnati, OH 513-621-4612 New York, NY 212-203-4000 Constellation Wealth Patton Wealth Advisors Cincinnati, OH Advisors 513-871-5500 New York, NY 214-234-9900 Foster & Motley Inc. Perennial Cincinnati, OH 513-561-6640 New York, NY 212-652-3900 Johnson Investment Satovsky Asset Counsel Inc. Cincinnati, OH Management LLC 513-661-3100 New York, NY 212-584-1900
Opus Capital Management Cincinnati, OH 513-621-6787
Vista Capital Partners Inc. Portland, OR 503-772-9500
RTD Financial Advisors Inc. Philadelphia, PA 215-557-3800
Capital Wealth Management LLC West Warwick, RI 401-885-1060
Meridian Wealth Advisors LLC Austin, TX 512-717-5580
Truepoint Inc. Cincinnati, OH 513-792-6648
Sterling Investment Advisors Ltd. Berwyn, PA 610-560-0400
Wescott Financial Advisory Group LLC Philadelphia, PA 215-979-1619
Verity Investment Partners Beaufort, SC 843-379-6661
Root Financial Partners Austin, TX 760-452-0720
Tiller Private Wealth Inc. Bethlehem, PA 610-954-9940
Guyasuta Investment Advisors Inc. Pittsburgh, PA 412-447-4560
Abacus Planning Group Inc. Columbia, SC 803-933-0054
Henry H. Armstrong Associates Inc. Pittsburgh, PA 412-471-1551
BNA Wealth Rock Hill, SC 803-324-7100
St. Clair Advisors LLC Cleveland, OH 440-925-5670 Wellspring Financial Advisors LLC Cleveland, OH 216-367-0680
Waldron Private Wealth Bridgeville, PA 412-221-1005
G2 Capital Management LLC Columbus, OH 614-484-1400
Baldwin Investment Management LLC Conshohocken, PA 610-260-1555
Gerber LLC Columbus, OH 614-431-4343
Mill Creek Capital Advisors LLC Conshohocken, PA 610-941-7700
Summit Financial Strategies Inc. Columbus, OH 614-885-1115 Trinity Financial Advisors LLC Columbus, OH 614-848-7667
Miller Investment Management LP Conshohocken, PA 610-834-9820
Trebuchet Consulting LLC Pittsburgh, PA 412-388-0715
Elgethun Capital Management Sioux Falls, SD 605-367-3336
Venturi Private Wealth Austin, TX 512-220-2035 Warwick Partners Bryan, TX 979-260-9777 Briaud Financial Advisors College Station, TX 979-260-9771 Paragon Financial Advisors College Station, TX 979-693-3907
Legacy Advisors LLC Plymouth Meeting, PA 610-943-3000
Abound Wealth Management LLC Franklin, TN 615-226-3667
Lountzis Asset Management LLC Reading, PA 610-375-2585
Leading Edge Financial Planning LLC Knoxville, TN 865-240-2292
Cypress Point Wealth Management LLC Dallas, TX 214-736-8887
Proffitt & Goodson Inc. Knoxville, TN 865-584-1850
Strata Wealth Advisors LLC Dallas, TX 214-420-7020
Sage Financial Group Inc. Conshohocken, PA Roble, Belko and 484-342-4400 Company Inc. Sewickley, PA Windsor Advisory Group Brandywine Oak Private 724-935-4990 LLC Wealth LLC Columbus, OH Kennett Square, PA The Fairman Group LLC 614-545-0300 484-785-0050 Wayne, PA 610-889-7300 PDS Planning Inc. Atwater Malick Dublin, OH Lancaster, PA Gibson Capital LLC 614-481-8449 717-400-1505 Wexford, PA 724-934-3200 Castlepoint Wealth Cordatus Wealth Conservest Capital Advisors Management LLC Oklahoma City, OK Morrisville, PA Advisors Inc. 405-705-2906 215-579-5981 Wynnewood, PA 610-642-9588 Jackson Hole Capital FFT Wealth Management Philadelphia, PA Young Richard C Partners LLC 610-545-6100 Tulsa, OK & Co Ltd. 918-879-4698 Newport, RI 401-849-2137 myCIO Wealth Partners Allium Financial Advisors LLC Philadelphia, PA Parsons Capital LLC 267-295-2280 Lake Oswego, OR Management Inc. 877-487-6860 Providence, RI 401-521-2440 Roffman Miller Ferguson Wellman Associates Inc. SK Wealth Capital Management Inc. Philadelphia, PA 215-981-1030 Portland, OR Management LLC 503-226-1444 Providence, RI 401-331-1575
Kelman Lazarov Inc. Memphis, TN 901-685-8284 Steel Grove Capital Advisors LLC Memphis, TN 901-498-6300 Fielder Capital Group LLC Nashville, TN 212-918-4860 Woodmont Investment Counsel LLC Nashville, TN 615-297-6144
Beaird Harris Dallas, TX 972-503-1040
Three Bell Capital LLC Dallas, TX 650-843-9836 Tolleson Private Wealth Management Dallas, TX 214-252-3250 True North Advisors LLC Dallas, TX 214-360-7300 Optas LLC Dripping Springs, TX 888-284-7139
Austin Asset Austin, TX 512-453-6622
Autumn Lane Advisors LLC Houston, TX 713-636-2075
Maslow Wealth Advisors Austin, TX 512-610-6930
Avidian Wealth Solutions Houston, TX 281-822-8800
WORTH.COM
FA L L 2 0 2 6
89
LE A D I N G A DVI SO R S Financial Synergies Houston, TX 713-623-6600 Franklin, Parlapiano, Turner & Welch LLC Houston, TX 281-599-3129 Goodman Financial Corporation Houston, TX 713-599-1777 Mosaic Advisors Houston, TX 713-980-4100 New Capital Management LP Houston, TX 713-874-1444 Pin Oak Investment Advisors Inc. Houston, TX 713-871-8300 Sequent Asset Management LLC Houston, TX 713-467-0008 Tanglewood Legacy Advisors LLC Houston, TX 713-599-4999 Tanglewood Total Wealth Management Inc. Houston, TX 713-840-8880 Corus Family Wealth Advisors Inc. McKinney, TX 972-422-1010 SFMG Wealth Advisors Plano, TX 972-960-6460 The Watchman Group Inc. Plano, TX 469-241-0122 WealthStar Advisors LLC Plano, TX 972-372-2935
Stansberry Asset Management LLC Roanoke, TX 646-854-4370
Hopwood Financial Services Inc. Reston, VA 703-787-0008
Pathway Financial Advisors LLC South Burlington, VT 802-660-7086
Avion Wealth Spring, TX 281-528-1200
Mason Investment Advisory Services Inc. Reston, VA 703-716-6000
Capital Planning LLC Bellevue, WA 425-643-1800
Enrich Financial Partners LLC Madison, WI 608-275-3442
Emerald Advisors LLC Bellevue, WA 425-458-3853
Isthmus Partners LLC Madison, WI 608-729-0949
Evergreen Capital Management LLC Bellevue, WA 425-467-4600
Resonant Capital Advisors LLC Madison, WI 608-733-6220
MarsJewett Financial Group Bellevue, WA 425-289-5000
Broadview Financial Management LLC Menomonee Falls, WI 414-390-1492
Parcion Private Wealth LLC Bellevue, WA 425-278-9555
Richardson Capital Management LLC Menomonee Falls, WI 262-255-4100
Tolsma Investments LLC Bellevue, WA 425-458-3999
Milestone Investment Advisors LLC Middleton, WI 608-826-5730
Brighton Jones LLC Seattle, WA 206-258-5000
Diversified Management Inc. Milwaukee, WI 414-292-1900
The Sum Spring, TX 281-940-4859 WJ Interests LLC Sugar Land, TX 281-634-9400 Sather Financial Group Inc. Victoria, TX 361-570-1800 Soltis Investment Advisors LLC Saint George, UT 435-674-1600 Cynosure Group LLC Salt Lake City, UT 801-521-3100 A. N. Culbertson & Company Inc. Charlottesville, VA 434-972-7766 Graves Light Lenhart Harrisonburg, VA 540-433-3076 Covenant Wealth Advisors Henrico, VA 804-729-5265 Steigerwald, Gordon & Koch Wealth Advisors Leesburg, VA 703-777-8826 Andersen McLean, VA 571-382-0020 West Financial Services Inc. McLean, VA 703-847-2500
The Burney Company Reston, VA 866-928-7639 Canal Capital Management LLC Richmond, VA 804-325-1450 Godsey & Gibb Wealth Management Richmond, VA 804-285-7333 Heartwood Wealth Advisors LLC Richmond, VA 804-269-8711 Heritage Wealth Advisors Richmond, VA 804-643-4080 Seneca House Advisors Richmond, VA 804-332-6574 WealthCrossing Richmond, VA 804-237-1700 WealthCrest Financial Services LLC Springfield, VA 703-372-1717 Glassman Wealth Services, LLC Vienna, VA 703-534-4444 Meridian Financial Partners LLC Warrenton, VA 540-878-5416 Rock Point Advisors LLC Burlington, VT 802-864-2266
Empirical Wealth Management Seattle, WA 206-923-3474
Wise Planning Inc. Seattle, WA 847-834-9473
Oarsman Capital Inc. Milwaukee, WI 414-221-0081
Fulcrum Capital LLC Seattle, WA 206-223-9790
Operose Advisors LLC Milwaukee, WI 414-209-3280
Garde Capital Inc. Seattle, WA 206-552-7900
Schaper Benz & Wise Investment Counsel Inc. Neenah, WI 920-727-1137
Kutscher Benner Barsness & Stevens Inc. Seattle, WA 206-462-6100 LNW Seattle, WA 206-464-5100
Shakespeare Wealth Management LLC Pewaukee, WI 262-814-1600 McKinley Carter Wealth Services Inc. Wheeling, WV 304-230-2400
Disclaimer Worth magazine is a publisher and does not recommend or endorse investment, legal, insurance, or tax advisors. The listing of any firm in the 2025 Worth Leading Advisors Program is conducted by our editorial team (at times in partnership with certain research organizations) and does not constitute a recommendation or endorsement by Worth magazine of any such firm and is not based upon Worth magazine’s experience with, or prior dealings with, any advisor. The information presented for each firm and/or advisor, including but not limited to any related profile, statistical data, presentation, report, commentary, recommendation, or strategy, has been provided by such advisor and/or third party data sources without independent verification by Worth magazine. Any such information is the sole responsibility of the advisor and/or third party data sources. Worth magazine makes no representation or warranty as to the accuracy or completeness of such information, assumes no liability for any inaccuracies or omissions therein, and disclaims responsibility for the suitability of any particular investment recommendation or strategy for any person. Nothing contained in Worth magazine constitutes or should be construed as any form of investment, legal, insurance, or tax advice or as a recommendation to buy, sell, hold, or trade any securities, financial instruments, or assets. Readers are advised to consult their legal, financial, insurance, and tax advisors prior to making any investment or pursuing any investment strategy. Past, model, or hypothetical performance is not indicative of future results.
90
FA L L 2 0 2 6
WORTH.COM
GETTY
TECHONOMY
Big Tech will spend nearly $700 billion on data centers this year, and 2026 is the year the bill for power, water, and tax breaks came back to developers (92). Sleep trackers taught us to measure our nights; now, an entire industry has grown around helping us improve them (98). And one clinician now argues screen addiction is worse than heroin (100). WORTH.COM
FA L L 2 0 2 6
91
D ATA C E N T E R S
Who’s Paying for All These Data Centers? BY OLIVER RIST
The AI buildout ran on other people’s electricity rates, water tables, and tax bases. This year, county by county and statehouse by statehouse, the invoice is being returned to sender.
F
ive companies—Microsoft, Alphabet, Amazon, Meta and Oracle—will spend between $660 billion and $690 billion in capital expenditure this year, almost all of it on data centers built to train and serve artificial intelligence. Amazon’s share is roughly $200 billion. Alphabet’s is $175 billion to $185 billion. Meta’s is $115 billion to $135 billion. The numbers keep climbing, and the markets financing them have barely started pricing the risk and costs that comes with them.
92
FA L L 2 0 2 6
WORTH.COM
Stargate, the OpenAI-led joint venture announced in January 2025, said last September it had reached nearly seven gigawatts of planned capacity across Texas, New Mexico and Ohio. It has since blown past nine gigawatts and picked up Wisconsin and Michigan along the way. Set that against any private infrastructure program in American history—the transcontinental railroads, the fiber buildout of the late 1990s—and this one is bigger, faster and far more concentrated. “Compared to more traditional load growth,” Federal Energy Regulatory Commission member David Rosner told the commission at its June open meeting, “the large loads seeking to connect to the grid today are larger, sometimes by orders of magnitude, and more concentrated.” Federal regulators do not reach for “orders of magnitude” casually.
The pro formas circulating through investment committees right now look like beautiful plans. Land, shells, chips, cooling systems, power purchase agreements, depreciation schedules, offtake risk; all modeled, all sourced, all footnoted. What they rarely model is the part of the bill that never touches the developer’s balance sheet. These include transmission upgrades spread across people who have never bought a GPU, water pulled from basins that were already having a rough decade, thirty years of municipal tax revenue waved cheerfully goodbye, and a political backlash that has spent 2026 rewriting the rules on projects that are already pouring concrete. Those costs are real, and 2026 is the year they started coming home for big tech. Large-load tariffs, repealed
tax abatements, groundwater permits and federal interconnection reform are all doing the same thing: moving the bill off the public ledger and onto the projects themselves. The timing is unkind. This repricing arrives as hyperscaler debt has tripled as a share of capital spending and the industry’s own accountants are arguing about how fast a GPU dies. The rest of this story is that bill, item by item. POWER IMBALANCES Start with the capacity price, because it is the one number nobody can spin. PJM Interconnection, the grid operator for more than 67 million people across 13 states and the District of Columbia, pays generators to promise they’ll show up when demand peaks. In the 2024/25 delivery year
that price was $28.92 per megawatt-day. For 2026/27 it is $329.17—an increase of more than 1,000%, essentially all of it in a single auction. Monitoring Analytics, PJM’s independent market monitor, attributed 63% of the jump in the 2025/26 auction to data centers—roughly $9.3 billion recovered from customers in higher rates. A broader estimate, using a different measure over a longer period, puts data center demand behind some $23 billion in customer price increases and expects the pressure to persist until at least the end of 2028. The utilities aren’t pretending otherwise. “Residential supply costs in the Mid-Atlantic have increased by up to 80% or more over the past five years,” Exelon chief executive Calvin Butler told analysts in May. “Without addressing supply constraints, affordability
WORTH.COM
FA L L 2 0 2 6
93
D ATA C E N T E R S challenges will persist.” Translated: your bill went up, it will keep going up, and the utilities would like the record to show it wasn’t their idea. The politics arrived on schedule. Speaking at PJM’s own annual meeting that same month, Maryland Governor Wes Moore told the room that “the single largest driver of capacity price increases is strain on the system from large loads and data centers,” and that “data centers must pay their own way.” This can be harder that it looks. Developers shop the same project to several utilities at once, and grid operators can’t easily tell a financed campus from an optimistic spreadsheet. Brian Fitzsimons, whose firm GridUnity sells software into this market, says one of the largest U.S. utilities watched nearly 30% of its 2024 applications evaporate. Utilities plan, procure and build against those forecasts anyway. If the load never turns up, the transmission is still there, still expensive, and somebody still amortizes it. Historically that somebody has been the ratepayer. “Ohio households should not be asked to subsidize speculative infrastructure investments for extraordinary private load growth,” Maureen Willis, director of the Office of the Ohio Consumers’ Counsel, told a state legislative committee in May. The rules are being rewritten to stop precisely that. In June the Federal Energy Regulatory Commission sent “show cause” orders to the six regional grid operators, opening what Rosner called “a dialogue.” The intent, in his words, is that “if new infrastructure is built to accommodate a data center, and that data center doesn’t show up, residential customers are not left on the hook to pay the costs.” Nothing is in force yet, and the industry will fight it, because of what the fix actually does: it moves the stranded-asset risk onto the data center developer, and onto whoever financed the developer.
94
FA L L 2 0 2 6
WORTH.COM
WATER HOARDING Water is where both sides of this argument are least informed. The current crop of U.S. data centers directly consumed about 17.4 billion gallons in 2023. Lawrence Berkeley National Laboratory puts the water consumed upstream—generating the electricity they drew—at another 211 billion gallons, twelve times as much. That figure includes evaporation off hydropower reservoirs as well as thermal plant cooling, and the Information Technology and Innovation Foundation, the industry-friendly think tank that most recently compiled it, believes the number is probably too high. The direction survives the quibbling: most of a data center’s water footprint sits in the power plants behind it rather than in its cooling towers. But the smaller number is the one that lands in somebody’s actual aquifer. Roughly two-thirds of data centers fully built or under development since 2022 sit in water-stressed areas. That is the entire problem in one sentence: a facility drawing a million gallons a day is a rounding error nationally and a crisis locally. Easier siting options exist, but developers keep targeting places where water is already at a premium— Virginia, Ohio, and further inland, Kansas and Iowa. Virginia did the arithmetic. A state environmental study released in July concluded that “under current conditions, it appears unlikely that a data center with evaporative cooling technology (or any comparable water user) would find a reliable, sufficient groundwater supply anywhere” in the eastern coastal plain. Virginia currently hosts 371 operating data centers, with another 438 planned, including one just announced in Fairfax. You can read those two sentences in either order. Neither improves the other. The deeper problem is that nobody knows what’s actually being used, in part because so few will say. Of the 341 facilities the Texas Water Development Board surveyed for its 2025 water use report, 17% replied. The board’s water supply planning director, Temple McKinnon, described reconstructing the
rest as “forensic accounting.” Asked at a June hearing what governs a data center pumping groundwater in a county with no conservation district, she didn’t hedge: “There would be no entity in place to regulate that use.” Representative Brad Buckley summed it up: “We don’t have the fundamental data we need to make decisions moving forward, nor does the Texas Water Development Board, nor does ERCOT, nor does PUC.” Texas is planning its water future on an a industry where 83% of the participants operate in the dark. TAX BREAK AND BUILD When it comes to tax subsidies, Texas keeps better receipts. And they are shocking. When the legislature created its data center sales tax exemption in 2013, the state figured it would cost about $14.6 million across the 2014–15 budget cycle. The comptroller’s 2025 forecast put it at $3.2 billion over the following two years—a number the comptroller’s office conceded was almost certainly an underestimate, given how many new facilities were lining up. The Senate Finance Committee now projects $3.3 billion for 2028–29. The statute was written for server farms. AI campuses are orders of magnitude larger, measured against thresholds that never moved. A facility above 100,000 square feet must create 20 permanent jobs paying 120% of the area’s median salary and invest $200 million over five years. Twenty jobs. Of 138 certified recipients, 20 have been audited; six were found in breach, at least four of them for failing the jobs requirement. Asked at a Senate Finance Committee hearing in July how many jobs a data center creates, the comptroller’s chief revenue estimator, Brad Reynolds, replied: “That, I don’t know. I just know that clearly some of them have difficulty achieving the 20.” “No tax exemption should operate on autopilot,” committee chair Senator Joan Huffman told the room. Autopilot would be an improvement. Autopilot implies somebody once set a course.
The national pattern is consistent. By Good Jobs First’s count, 16 of 36 state data center subsidy programs require no job creation whatsoever, and the three states that measured their returns are losing between 52 and 91 cents on the dollar. The industry’s figures tell a different story. A PwC study commissioned by the Data Center Coalition credits data centers with $65.8 billion in Texas GDP in 2024 and more than 103,000 direct jobs—428,000 once indirect and induced employment is counted. Both things can be true at once: the economic activity is real, the permanent on-site employment is thin, and the reporting was structured to reflect neither. What changed in 2026 is that legislatures started reading their own statutes. Massachusetts halted its incentive in June, Arizona enacted a three-year pause, Illinois and Ohio suspended theirs, and Governor Greg Abbott—who spent a decade recruiting these projects—has said that if reelected he’ll work to repeal the Texas exemption in 2027. Capital committed against a twenty-year abatement is being repriced in year four. THE LAND, THE NOISE, THE NDAS The local objections stopped being local some time ago. Data Center Watch—a research project of 10a Labs, a consultancy that works for AI companies, which is worth knowing before you weigh its numbers—counted 75 projects blocked or delayed in the first quarter of 2026, disrupting some $130 billion in project value. That is roughly five-sixths of the $152 billion it logged across all of 2025, in a single quarter. It puts active opposition groups in 49 states, up from 42 at the end of last year. More than 300 data center bills were filed in state legislatures in the first six weeks of the year, and of 63 local moratorium actions introduced, considered or adopted, 54 have passed. Some of the grievance is siting. Virginia’s legislative auditors found that a third of the state’s data centers sit near residential areas; in Fairfax
WORTH.COM
FA L L 2 0 2 6
95
D ATA C E N T E R S
County, 55% are within 200 feet of somebody’s house. Prince William County residents have complained of noise routinely topping 60 decibels. When the county tightened its industrial limits in 2,025 it landed on 73 decibels by day—above the 67 its own consultants recommended. More of it is process. Roughly 80% of Virginia localities hosting data centers have signed non-disclosure agreements with developers, and one agreement in Bessemer, Alabama required city officials to destroy records. Communities are routinely learning how large a project is only after the land is optioned and the incentives are signe. That sequencing is converting a zoning question into a political one. “This is Appalachia. We have a very long memory here,” Rachel Wilson told a town hall in Boyd County, Kentucky, in June. “Most of that memory is boom and then bust, so you want us to get excited about a
96
FA L L 2 0 2 6
WORTH.COM
boom. We’re all concerned about how much that boom is going to cost us, and when is it going to bust, and who’s going to pay for that bust.” One popular objection, though, doesn’t hold up. There is no good statistical evidence that proximity to a data center depresses home values—and neither of the two existing studies settles much. A George Mason University analysis of Northern Virginia sales found no effect, though its author notes an average result is compatible with individual homes getting clobbered; an Indiana study showing near-facility homes appreciating was commissioned by a developer with a live application pending, and three
“Daily water usage over the course of an entire year is roughly equivalent to what a single resturant would use.”
of its four counties underperformed. The costs here—noise, sightlines, traffic, and above all trust—are real. On the evidence, they aren’t equity. And the campuses now proposed are far larger than anything either study measured. THE DATA CENTER DEFENSE Of course, the datacenter industry has its own data to cite. Start with rates, where causation is most acrimoniously contested. Analysts at E3 examined PJM’s 2025/26 capacity auction. They attributed roughly half the price increase to load growth of every kind, the remainder to changes in market parameters, supply constraints and the assumed cost of new generation. That is a materially smaller share than the market monitor’s 63%, and it is the more carefully constructed piece of work. It is also, as the report itself discloses, a whitepaper funded by the Data Center Coalition and reviewed by the coalition before publication.
Virginia’s legislative auditors likewise found no evidence that data centers had historically shifted costs onto residential customers—while projecting that a typical Dominion residential customer could pay $14 to $37 more per month in real terms by 2040, and warning of cost shifts “that may be inequitable” without rate reform. E3 was the contractor on that analysis too. The structural response has moved faster than the argument about it. At least 38 large-load tariffs, which oblige data centers to cover the cost of serving them, were established between 2018 and 2026, 30 of them in the last two years. Two Southern Company utilities have agreed to rate freeze the utility industry credits partly to data center growth. “In Southern Company territory, this growth is helping us freeze rates in many jurisdictions for the next few years,” said Chris Womack, Southern’s chairman and chief executive, at an Edison Electric Institute event in April. The freezes cover base rates only; fuel and storm recovery come through the door as usual. On water, the argument is that everybody has the scale wrong. Microsoft has designed a data center that eliminates evaporative cooling and says the design will avoid more than 125 million liters per facility each year. The first two such sites, in Phoenix and Mount Pleasant, Wisconsin, don’t come online until late 2027; until then, every existing Microsoft data center keeps evaporating as usual. Satya Nadella told attendees at Microsoft’s Build conference in June that in those closed-loop designs a facility’s “daily water usage over the course of an entire year is roughly equivalent to what a single restaurant would use.” That is true of on-site cooling—and it quietly excludes the water embedded in the electricity those campuses will draw. The efficiency argument is the weakest of the lot. Between 2010 and 2018, data center electricity consumption rose 6% while computing output rose 550%, a statistic the Data Center
Coalition still keeps in circulation. The trend has since broken: Berkeley Lab finds consumption more than doubled between 2017 and 2023 on the back of AI servers, reaching 4.4% of U.S. electricity and headed for 6.7% to 12% by 2028. Citing 2018 efficiency figures in defense of a 2026 AI buildout is an exercise in nostalgia. What survives all of it is the concession, and it is a real one. “Especially when tech companies are so profitable,” Microsoft vice chair and president Brad Smith wrote in January, “we believe that it’s both unfair and politically unrealistic for our industry to ask the public to shoulder added electricity costs for AI.” Microsoft’s commitment, in his words: “We’ll pay our way to ensure our datacenters don’t increase your electricity prices.” That is the most creditable thing anyone in this industry has said. It also concedes, in the politest available language, that until recently they weren’t paying. THE RECKONING None of this will stop the buildout, and nobody building it thinks otherwise. “There’s just nowhere near enough compute for all the demand,” Mark Zuckerberg told analysts in July. Alphabet’s Sundar Pichai, a week earlier: “We continue to be supply constrained.” Whatever else is wrong here, nobody is short of customers. They are short on showing revenue. What’s contested is how much of the announced pipeline is real. Sightline Climate, tracking 190 gigawatts across 777 projects, found that of the 16 gigawatts slated for delivery in 202, 6 only about five were physically under construction, and judged 30% to 50% of the pipeline unlikely to come online this year. SemiAnalysis called Sightline’s denominator “hugely flawed, off by multiples,” noting that its own North American hyperscaler forecast had shifted by roughly 1% over six months. Both firms sell forecasts for a living. Nobody knows which announcements are projects and which are press releases with a site plan attached.
So what’s changing is who absorbs the costs. Large-load tariffs, repealed abatements, groundwater permitting, local moratoriums, FERC’s proposed interconnection reform. Every mechanism now in motion is doing the same thing, moving costs off the public ledger and onto the project’s. In the main, that is the right outcome. It is also a repricing, and it arrives just as the projects are becoming harder to finance. And it won’t stop at the developer’s books: costs that land on the project get passed to the customers buying the compute. The vendor side already shows the strain. Debt has gone from 9% of hyperscaler capital spending in FY2024 to 32% by midyear. Alphabet raised $84.75 billion in equity in June. Oracle closed its financial year with negative free cash flow of $23.7 billion and was downgraded in July to one notch above junk, on concentration risk from a single customer. Memory prices roughly doubled in the first quarter. And the accounting points in two directions at once: Microsoft extended the assumed life of its data center shells from 15 to 25 years in the same quarter its chief financial officer noted that roughly two-thirds of capital expenditure went to shortlived chips. “Accounting statements may reflect orderly depreciation,” Goldman Sachs analysts wrote in May, “but operational obsolescence can impose a very different economic reality.” A typical campus underwritten in 2024 assumed cheap interconnection, a twenty-year exemption and untested water consumption—and assumed all three would hold. None of them will. The hidden costs of the data center boom were never really hidden. They were assigned to people who were not in the room, and who have now, county by county and statehouse by statehouse, let themselves in. The question is not whether the buildout continues. It is what these things are worth once the bill finally lands.
WORTH.COM
FA L L 2 0 2 6
97
S L E E P TR AC K I N G
Sleep Past the Tracker
A decade of rings and wristbands taught us to measure our sleep, but changing it might be more important. BY DAN COSTA
I
t takes nerve to program a sleep panel right after lunch, which is exactly what I did at Living Well 2026. I said so from the stage, and the room laughed because half of them were fighting fatigue. There was coffee in the hallway. We survived. Then I did what everyone in that room does every morning. I checked my Oura ring. It had flagged my sleep midpoint the night before. Not the hours. The hours were fine. The midpoint had drifted off my baseline, and the ring wanted me to know. “That alone can be destabilizing,” I told the panel. Dr. David Benavides, a sleep physician at Harvard Medical School and Mass General Brigham, answered in one word: “Massively.” We built devices that measure sleep with real precision. The measurement became a new thing to lose sleep over. The interesting question now isn’t better data. It’s whether a machine can do something with the data besides tell you last night went badly. RAND puts the cost of insufficient sleep to the U.S. economy at up to $411 billion a year, 2.28% of GDP, plus a 13% bump in mortality risk and 1.2 million lost working days. The CDC counts 30.5% of American adults sleeping less than seven hours, and the shortfall peaks between 50 and 64. The long-term bill is worse. In Whitehall II, the British civil-servant cohort followed for decades, people sleeping six hours or less in their 50s and 60s carried roughly a 30% higher dementia risk years later. Oura raised more than $900 million last October at a valuation near $11 billion, the largest round in sleep-tech history. Whoop shipped two new bands in the spring. Wearable sleep trackers cleared $16 billion in 2025. All of it
98
FA L L 2 0 2 6
WORTH.COM
rests on one premise: see your sleep, and you’ll fix it. Benavides gives the wearables their due. “Thanks to wearable companies, patients and consumers are starting to notice that sleep is actually really important,” he said. He sees the awareness surfacing in cardiology, neurology, and endocrinology. But he also watches the data turn on its owner: “I’m already worried about my sleep. Now I’m looking at my data. Now I’m getting more stressed about my sleep because I saw I slept badly last night. Now I am more stressed about getting good sleep tonight.” There’s a clinical name for that spiral: orthosomnia. Kelly Baron and colleagues at Rush coined it in a 2017 Journal of Clinical Sleep Medicine paper about patients so fixated on perfect sleep scores that the fixation wrecked their sleep. A 2024 meta-analysis found consumer wrist devices still don’t match clinical polysom-
nography, with some overestimating sleep by nearly half an hour and misreading REM. This raises questions about the reliability of sleep data from wearables, which is important for readers to understand when interpreting their sleep scores. Benavides’s prescription is to demote the number. A tracker is a baseline instrument, not a report card. “Where sleep trackers can be useful is not the night-to-night data,” he said, “but understanding what your baseline is, so that when you see a deviation from that norm, you can interrogate what was going on.” Build years of data. Watch the trend. Stop grading the night. That’s a sensible answer to an inadequately designed product. Caitlin Shure is building a better one. Shure runs product and content at NextSense, a spinout of Alphabet’s X moonshot lab that raised a $16 million Series A in November, with backers including the neuroscientist David Eagleman and Esther Dyson. The product is a pair of earbuds with six clinical-grade EEG sensors, three per ear. EEG is a hundredyear-old technology that normally lives in a sleep clinic and requires a headful of wires. NextSense put it in something you’d wear on the subway. She’s precise about what the sensors deliver. “We’re not reading your mind,” she said. “It’s more like a brain rhythm.” Because the signal comes from your head instead of your wrist, the data beats anything a ring can produce. But data isn’t the pitch. “Our big thesis is to go beyond tracking, and not simply say, hey, your sleep was bad.” She played the customer’s reply for the room: “Yeah, that’s why I bought a product. I thought you were going to make my sleep better.”
“People sleeping six hours or less in their 50s and 60s carried roughly a 30% higher dementia risk years later.”
Benavides, for the record, still steers most patients to the cheapest tool in the drawer: same bedtime, same wake time, seven or eight hours, every night, over everything else. Old-fashioned, he admits. It also works. The earbuds beaming pink noise into your skull at 3 a.m. are betting they can beat that advice, or at least earn a spot beside it. The scoreboard that matters isn’t on your ring in the morning. It’s whether, a year from now, any of this has put you to sleep.
GETTY
So, the earbuds try to make it better. During deep sleep, they play frequencies timed to boost slow waves, the brain activity that drives physical restoration and, in some studies, next-day cognition. The starting material was already in our ears. The most popular sleep sounds on the platform are rain, campfire, and waves. Shure’s theory: those are the acoustic environments our brains spent a few hundred thousand years falling asleep in.
WORTH.COM
FA L L 2 0 2 6
99
SCREEN ADDICTION
Your Brain on Screens From neck pain to a higher risk of dementia, stroke, and Parkinson’s, the evidence for treating screen addiction as a medical condition has been mounting for years. Dr. Nicholas Kardaras, author of Glow Kids, and Dr. Dale Atkins, who prescribes ‘green time’ explain. BY CAROLINE BIENFANG
A
simple Google search about screen addiction will take you down a rabbit hole of finger-pointing at whichever generation is leading the charge that week. Gen Z is often the pin cushion of these debates, with the occasional eye roll reserved for boomers. But the best research comes from standing on a crowded subway car as it screeches into a station. You’re hot, you overslept, you’re late for work, and the cluster of commuters standing between you, the door, and the two minutes you need to catch your transfer are unmoved by the train’s chime. Glance at their hands. I’ll put my money on a small, glowing rectangle being the culprit. That was a common theme at a session during Worth’s Living Well summit, where Dr. Nicholas Kardaras, the clinician and author who coined the term “Digital Heroin,” told a story that stuck with me and with the audience. After he published “Glow Kids” in 2016, he began receiving thousands of emails from parents asking for help, including one from a mother
100
FA L L 2 0 2 6
WORTH.COM
THE IPHONE IS THE NEW CIGARETTE The real cost isn’t just our attention spans or work-life balance. According to a 2023 report from the Journal of Education and Health Promotion, titled “The Hazards of Excessive Screen Time: Impacts on Physical Health, Mental Health, and Overall Well-Being,” excessive screen time has been linked to physical complaints like neck, shoulder, and back soreness, along with mental health effects including depression and anxiety. A 2024 article from Stanford Lifestyle Medicine, “What Excessive Screen Time Does to the Adult Brain,” cited research finding that increased screen use among adults, particularly ages 18-25, can cause the cerebral cortex, the part of the brain that processes memory and handles higher-order thinking like weighing decisions and solving problems, to thin. Adults who watch five-plus hours of TV daily face an elevated risk of stroke, dementia, and Parkinson’s disease. Screens don’t wait for us to grow up before they sink their teeth in. If phone use has crept into every corner of adult life, the meetings, the subway platforms, the bedside table, it’s because we built the habit first, and our kids are inheriting it younger than we ever did. “The phone has become the new smoking. It’s the new whenever there’s any time or pause, you reach for the phone. There’s an anxiety reducer,” said Dr. Nicholas Kardaras.
GETTY
whose 9-year-old son, a gamer, had become violent enough that she’d hospitalized him twice trying to separate him from his games. When she finally found a therapist willing to see him, she was told, ‘This is just gaming. It’s not a big deal.’ She knew better. She just didn’t have the language for it yet, because in 2016, almost no one did. Hers wasn’t an isolated case. It was one of thousands of emails Kardaras received, evidence of a problem too big for any single family to solve alone, and a preview of the research he’d build his career on.
The numbers make the timeline uncomfortably clear. According to a 2025 survey from The Common Sense Census: “Media Use by Kids Zero to Eight,” children ages 2-4 average two hours and eight minutes of media use a day, before most of them can tie their shoes. By ages 5-8, that number climbs to three hours and 38 minutes. It keeps climbing from there: a 2021 Common Sense Media report found kids ages 8-12 average about five and a half hours of screen use daily, and by the time they’re teenagers, the Common Sense Census: “Media Use by Tweens and Teens,” puts that figure at eight hours and 39 minutes a day for ages 13-18, nearly a full workday before they’ve even started one. Dr. Nicholas Kardaras has spent his career watching that trajectory up close. As founder, CEO, and chief clinical officer of Omega Recovery LLC, he was one of the first clinicians to name what he was seeing in his own patients as more than just heavy use. “This new way of living was affecting our lives, and it was not just a social lubricant, and it was not just a fun way to find information, it was profoundly impacting the way we are as a species, the way we interact, the way we think, the way we process information,” said Kardaras. Kardaras first put a name to it in a 2016 New York Post piece called “Digital Heroin,” which drew 6 million views. He analogized screen addiction to having the same diagnostic features as heroin addiction. Nearly a decade later, he believes it’s actually worse. “I’ve come to believe that it’s actually quite a bit worse than heroin addiction... fentanyl doesn’t have predatory, predictive algorithms that target psychologically vulnerable people and then can drive them to do things like commit suicide... And heroin isn’t in our pockets. Well, it might be in your pockets right now,” said Kardaras. It’s a diagnosis, not just a complaint, and it raises the obvious next question: if the habit starts this early and climbs this steadily, what determines whether a family gets swallowed by it, or learns to live alongside it?
WHAT RESILIENT FAMILIES DO DIFFERENTLY As is the case for all forms of addiction, treatment looks different depending on the needs of the patient. Worth sat down with Dr. Dale Atkins, licensed psychologist, author, and relationship expert, to discuss combatting screen time with green time. Dr. Atkins advocates for rewriting the script we pass to our children about the relationships we have with our own screens. “If we’re afraid of it, and if we are driven by fear, then we’re probably going to be that way with our children... we get punitive right off the bat because we’re really working out of fear and we don’t know what we should do,” said Dr. Atkins. That fear tends to build a household defined by rules rather than curiosity, one where kids feel monitored rather than understood. It’s also not limited to how parents police their children’s screens. It’s just as much about what parents model with a phone in their own hand. A 2024 study in Frontiers in Child and Adolescent Psychiatry on parental phone use around children found a negative correlation between the amount of time parents spend on their screens and how much they interact with their kids. Children of parents who were frequently distracted by screens were more likely to act out, growing more prone to frustration and emotional outbursts. The study also found that when parents are absorbed in a screen and cut back on talking and gesturing to their kids, it can measurably slow language development over time. Children imitate the behaviors we model, whether we mean them to or not, the same current running under Atkins’s next point: “What we have are relationships with our devices rather than relationships with each other,” she said. It’s not just about kids and their relationships with screens. It’s about what we model. For Atkins, the fix isn’t more restriction. It’s more attention. “If we are concerned about time management
but not attention management, how do we really address what it means to be attentive?” she asked. Her answer is simple: put the devices down before bed and use that reclaimed time for actual conversation. “The main point is that in my view, you don’t want to lose your kid. You don’t want to have a relationship where you’re constantly on them to say ‘get off this device,’” she said. Presence isn’t something you schedule around your screens. It’s something you actively choose over them, again and again, at the dinner table, before bed, or riding in the car. “When you have a child whose device is constantly telling them and curating whatever they’re looking at that it’s about them and their needs, this is not the real world,” said Dr. Atkins. GREEN TIME AS THE ANTIDOTE The best way to ‘break up’ with the toxic relationship we have with our screens is more accessible than almost any therapeutic remedy. Those eight-plus hours a day spent scrolling social media, answering emails that could wait until nine, and watching just one more episode are often the only things standing between us and the outdoors. More time on screens means less time outdoors, regulating our bodies the way they were built to. The Children & Nature Network’s research digest reviewed 186 studies and found a clear pattern: kids who spent more time on screens showed higher rates of depression, anxiety, and difficulty regulating their emotions. Kids who spent more time in nature trended the opposite direction, showing stronger mental health and sharper cognitive function. Dr. Atkins has watched this digital transition compound across decades of clinical work, and the toll has stayed with her. “I have never been more worried, never in my entire professional life. I’m 78 years old. I have never been more worried about the next generation than I am now,” said Dr. Atkins.
WORTH.COM
FA L L 2 0 2 6
101
WAT C H E S
Ahead of Her Time
She inherited a watch company in freefall and ran it alone through a world war. Betty Fiechter then built two of watchmaking’s most iconic collections. BY CAIT BAZEMORE
T
he watch industry has long been, and continues to be, a man’s world. In 2024, the non-profit organization Watch Femme co-authored a landmark report with Deloitte, which found that while 43% of the Swiss watchmaking workforce is made up of women, the majority remain at the bench level, not the boardroom. In the history of modern watchmaking spanning over a century, only 10 women have held the title of CEO. The first Swiss woman to do so was Betty Fiechter, who became the CEO and co-owner of Blancpain in 1933.
102
FA L L 2 0 2 6
WORTH.COM
In her three decades at the helm of Blancpain, Fiechter created an enduring legacy that forged a path for other women to carve out their place in the male-dominated watchmaking industry and left a lasting impact on both the evolution of women’s watches and the mastery of miniaturization in mechanical movements. Today, Blancpain perpetuates this legacy on the monumental 70th anniversary of one of Fiechter’s most memorable and enduring designs: the Ladybird. At its debut in 1956, the Ladybird introduced the world’s smallest round mechanical movement to be manufactured in serial production in what would become Blancpain’s signature ladies’ line. Now, its story continues with a new chapter, the contemporary evolution of Fiechter’s original vision. Fiechter’s origin story is a familiar one for many men who have risen in the ranks of the watchmaking industry. She came from a horological background, with her father owning a watch movement company. Following in his footsteps, she entered an apprenticeship in 1912 when she was just 16 years old with a brand called Blancpain, whose workshop was situated in her hometown of Villeret in the Swiss Jura mountains, the heart of watchmaking. Blancpain is a brand of significant stature in the span of horological history, standing as the oldest watch brand in the world, founded in 1735. When Fiechter first entered the company, it was in its seventh generation of family leadership, and she soon began to work closely with Frederic-Emile Blancpain, who had the massive undertaking of carrying on his family’s legacy at the time. He saw something special in Fiechter and took her under his wing as his protégé. The two developed a distinct rapport, with Blancpain ultimately trusting Fiechter enough to oversee the brand’s manufacturing operations while he was at his home in Lausanne, about 60 miles away from the Maison’s headquarters. Two decades later, Blancpain passed away, and when his only remaining heir, his daughter, did not
want to carry on the family business, the fate of the company became uncertain for the first time in its monumental 200-year history. With no family successor willing to take over the business, Fiechter and the brand’s commercial director Andre Leal decided to take a bold gamble. They secured loans from several lenders and acquired the Manufacture in 1933. Then, Fiechter officially became co-owner and CEO of Blancpain. Aside from the internal shifts the brand was facing with changes in ownership and leadership, this was an incredibly challenging period between the Great Depression and the onset of the Second World War. Then, in 1939, Fiechter’s partner Leal died suddenly, and she found herself alone at the helm of the company of more than 200 employees. Fiechter’s first act as the first female CEO of a Swiss watch brand was to usher the company through wartime. She did so with fortitude and grace, setting her sights on strengthening Blancpain’s international presence, particularly in the American market. Soon, she realized this initial goal, and the Maison became a leading supplier of movements to major American horological houses like Gruen, Lucien Piccard, Elgin, and Hamilton. Another area where Fiechter demonstrated particular insight was in developing watches for women. Well ahead of her time, she understood that ladies’ timepieces merited the same ingenuity and mechanical integrity as any other watch—a belief that many watchmakers have still yet to adopt today, many decades later. She set out to make women’s offerings yet another one of Blancpain’s defining strengths, but as she was getting older, she could not do it alone. In 1950, her nephew Jean-Jacques Fiechter joined her, and over the next two decades, the pair would shape the trajectory of the brand. Together, they gave rise to two collections that continue to define Blancpain today: the Fifty Fathoms, first introduced in 1953, and, of course, the Ladybird, first introduced in 1956.
WORTH.COM
FA L L 2 0 2 6
103
WAT C H E S
Thanks to its rugged masculinity, the Fifty Fathoms has gone on to solidify its place in horological history for Blancpain and the industry as a whole. The collection introduced one of the world’s first professional dive watches and has gone on to serve as the blueprint for the modern dive watch with details like a rotating bezel, double O-ring crown for water resistance, and high-contrast details for legibility. However, Blancpain’s Ladybird collection has also set the standard for both design and technical excellence in women’s watches. Fiechter’s ambition behind the Ladybird was bold—for the design, she wanted to create the world’s smallest round mechanical movement, and she wanted it to be able to be manufactured in a serial production. The result was a feat of industrialization and mechanical miniaturization measuring just 11.85mm thanks to two key innovations. The first was the addition of a fifth wheel to the gear train. A conventional mechanical movement has four, from the barrel to the seconds wheel. Fiechter’s
104
FA L L 2 0 2 6
WORTH.COM
solution was to add an additional one, controlling the force reaching the escapement and reducing the caliber’s overall dimensions. The second was the inclusion of shock protection for the balance wheel—an element that most very small movements omitted, to their detriment in durability. Blancpain found a way to adapt these protections to the micro-dimensions of the Ladybird caliber, producing a movement that was both remarkably small (barely the size of a fingertip) and genuinely robust, unlike other small calibers of the time. With the Ladybird caliber as a strong foundation, Blancpain was able to take full creative license with the design of the Ladybird models. Over the years, the line has spanned a vast range from straightforward, everyday designs on a simple leather strap to more elaborate high-jewelry versions set with gemstones and diamonds. One of the most famous collectors to adorn the Ladybird was the legendary Marilyn Monroe, who unsurprisingly opted for one of the more opulent diamond-set versions of the design.
Today, we continue to see the versatility and endless possibilities of the Ladybird thanks to the timelessness of Fiechter’s original design language and the ingenuity of the movement that powers it. Blancpain brings the Ladybird into the modern era with subtle updates that allow the collection to be just as relevant to the next generation of collectors while maintaining the integrity of the original. Some watches commemorate history, and others continue it. The new evolution of the Ladybird is fresh and effortless yet still timeless in a way that perpetuates Fiechter’s vision from 70 years ago. This is not a reissue. It is the contemporary reinterpretation of a simple and radical idea born in 1956: to fit fine mechanical watchmaking into an object the size of a jewel. This vision guided the entire development of the watch. Its architecture was built around Blancpain’s automatic caliber 615, whose technical specifications were embraced from the very beginning of the project. This manufacture movement is made up of 180 components and yet measures just 15.70mm in diameter and 3.90mm in thickness. Although the caliber 615 remains be-
hind a closed caseback, it is not just a functional component powering the watch. It has received the same meticulous attention to detail and upholds watchmaking traditions with finishings like plates decorated with Cotes de Geneve. Built from the inside out, form follows function with the new collection. The case, sapphire crystal, polished rehaut, integrated pass-through strap, and water resistance were all developed in parallel to accommodate the movement within an unprecedented spherical configuration that took over thirty technical drawings to bring to life. The unique result is not quite a traditional round watch nor a shaped watch, and its distinctive qualities extend from the case to the bracelet loop, which is integrated and passes directly through the case, with no lugs or visible attachment. Conceived in volume rather than surface, the design is a mechanical bubble. While watches are traditionally defined by their diameter, this model is defined by its volume: 2.90 cubic centimeters. This three-dimen-
sional measurement is highly unusual in watchmaking. While it presented new challenges from construction to decoration, it still maintains a high level of handfinishing with a combination of perfectly continuous polishing, satin-finishing, and micro-blasting across the small spherical surface. Altogether, these are defining features that set this model apart as more than just a watch. It’s a design object, a jewel, a sculptural piece of art for the wrist, and still, at its core, a timepiece. Yet, the Ladybird and its new, contemporary counterpoint alongside the iconic Fifty Fathoms are not the only elements Betty Fiechter leaves in her legacy. In the decades following the initial debut of these core collections in the 1950s, she continued to lead Blancpain in ways that would propel the brand forward for years to come. Under her direction, the Maison joined a group called the Société Suisse pour l’Industrie Horlogère that helped continue Blancpain’s work as a producer of movements for other members of the alliance, like Omega and Tissot. The relationships forged here have ultimately landed these brands under the Swatch Group umbrella, with Tissot being acquired in 1983,
followed by Omega in 1985 and later Blancpain in 1992 as one of the luxury group’s small subset of prestige brands. Most importantly, Fiechter left her mark on the watch industry for other women, paving the way for them to follow in her footsteps as leaders in the field. It was not until 2008—75 years after Fiechter stepped into her role as CEO—that another woman would claim the title when Christine Hutter became CEO of the German watchmaker Moritz Grossmann. Today, Hutter is among a small handful of just eight women to hold the position of CEO in the watch industry, including Christelle Rosnoblet of Speake Marin, Nayla Hayek of Harry Winston, Chabi Nouri of Piaget, Catherine Renier of Jaeger-LeCoultre and later Van Cleef & Arpels, Ilaria Resta of Audemars Piguet, Laura Burdese of Bulgari, and Beatrice Goasglas of TAG Heuer. However, this fight for equality all began with one woman who was far ahead of her time, Betty Fiechter, and her legacy continues to live on in each of these women and in collections like Blancpain’s new interpretation of the Ladybird. WORTH.COM
FA L L 2 0 2 6
105
T R AV E L C A P S U L E
Times Square may be the quintessential tourist trap, but real New Yorkers know these five littleknown spots are worth fighting the crowds. BY KIRSTEN CLUTHE
T
imes Square is the neighborhood every New Yorker tries to avoid. Inevitably, we all end up there for one reason or another, whether it’s for meetings or business travel. For many people who have never been to New York City before, it’s usually the first place they encounter, thanks to the sheer concentration of hotels in the neighborhood. I’ve overheard more than a few conversations—on a plane, on the subway—about how to survive a few days in Times Square as a visitor, and have held back the urge to tell them to skip it altogether. Yet, it’s also one of the few neighborhoods in Manhattan where a five-block radius can hold a dive bar older than the current line-up on Broadway, a basement jazz club with the best musicians in town, and a speakeasy where Broadway talent unwinds after the curtain falls. You just have to be willing to push past the M&M’s store to find it all.
106
FA L L 2 0 2 6
WORTH.COM
St Kilda Coffee, 328 West 44th St. Opens 7 a.m. Can you get good coffee in Times Square? Yes, and it’s not in your hotel. Halfway down the block on West 44th Street is St. Kilda, founded by former Yahoo employee Artie Rangini after a backpacking trip to Australia. He positioned the shop on the edge of the theater district to provide a caffeine sanctuary for actors, stagehands, and musicians rushing between rehearsals and show days— and thankfully serves anyone else scrambling to find a decent cup of coffee in the neighborhood as well. Here, you’ll find a Flat White, the definitive Australian classic, along with other espresso, specialty roasts, and flash-brewed single-origin coffee served cold to beat the heat. St Kilda has a cool, surfer-punk vibe that feels very downtown—a world away from the sterile coffee chains a block away. Find the original, intimate subterranean shop at 328 West 44th Street, and its sister cafe on 374 West 46th Street.
L I Z Z S PA N O
Times Square: Coolest Hood in NYC?
MORNING:
running on the classic physical cabinet layout (CDs have replaced the original 45s), loaded strictly with soul, jazz, blues, and classic R&B. There’s even a Spotify playlist. Many celebs have spent time in the establishment over the last few decades, and more recently, prominent New York politicians, state lawmakers, and civic leaders who are trying to save it from an eviction battle. Jimmy’s is a beer-and-a-shot joint, though I decided to order a martini the last time I was there boldly and was kindly schooled by the bartender. “Here, a cocktail is whatever spirit you want, and that’s it. A martini is a gin served in a cold martini glass with ice.” Against the 95-degree day outside, it was quite perfect. EVENING ENTERTAINMENT:
AFTERNOON: Jimmy’s Corner, 140 W 44th St cash preferred, open late Stay with me here. To get a seat at this iconic establishment, it’s best to arrive between 1-4 p.m. If a midafternoon drink isn’t in your plans, you can do what I did and wait outside until someone leaves, then quickly dash in and grab a stool at the bar or a table in the back. This works especially well if you time it when theater-goers vacate right before curtain, which temporarily frees up space before the late-night crowd arrives. Jimmy’s is named for founder Jimmy Glenn, a successful amateur boxer who opened the bar as a haven in 1971 Times Square—a neighborhood that was, at the time, undeniably gritty and dangerous. A narrow room lined wall-towall with vintage fight posters, historic clippings, and personal photographs, Jimmy’s is a living museum of boxing history. The jukebox is widely regarded as one of the best-curated in the city, still
The Pocket, 130 W 46th St. at The Muse hotel While the streets in Times Square fill with people rushing between dinner, shows, and catching an Uber all at the same time, you can escape into the serene cool that belongs to The Pocket, a newly minted jazz club tucked inside The Muse hotel. This is the kind of stop that makes whatever kind of day you’ve had worthwhile: worldclass live music in a space that channels the golden age of jazz. Designed by a team of Michelinstarred hospitality veterans and legacy jazz players, The Pocket prioritizes acoustics and sightlines, creating an up-close listening experience no matter where you’re sitting. VIP tables are only a few feet from the performers—I was seated so close to the stage for the Mingus Big Band performance that I could have handed the baritone sax player a cocktail. Rail seating is a less expensive ticket option, and while the view can be semi-obstructed, the sound carries so well you won’t miss a note. A matte black ceiling makes the room disappear when
the lights go down, crimson and burgundy curtains pad the walls for a glamorous speakeasy feel, and tables are lit with soft amber brass fixtures that don’t compete with what’s happening onstage. The cocktail program is mid-century-inspired—classic drinks alongside inventive ones like a Cold Brew Martini and a French Martini with framboise and pineapple. The food leans brasserie comfort: at my table, a Muffuletta salad big enough to share, perfectly cooked onion rings, and a classic Negroni were on order. Grant Gardner, who is the owner and operator of The Pocket, told us that they wanted to “create a menu that doesn’t exist at other clubs around town: oysters, deviled eggs, prime rib, and pie.” He also says that Times Square is having a moment. “There are so many legendary places in the area if you know where to look Jimmy’s Corner, Joe Allen, Aldo Sohm/Le Bernardin, Becco…or new spots like Bar Rocco, Nothing Really Matters, Din Tai Fung. The culture of congestion here means you really have to sift through the madness, but there are true gems, and we’re happy to be part of that.” The Pocket calendar features weekly residencies, like Mingus Mondays with the Mingus Big Band, who celebrate the complex, high-energy compositions of Charles Mingus, and Afro Latin Jazz Tuesdays, bringing explosive brass and Afro-Cuban rhythms to the room. Upcoming performances include Donny McCaslin, an acclaimed, boundary-pushing saxophonist known for his heavy fusion work and leading David Bowie’s final band, and Donald Harrison, an NEA Jazz Master and New Orleans saxophone legend. Showtimes are generally 7 and 9 p.m., but check the calendar for updates. There’s a two-menu-item minimum per person, per show.
WORTH.COM
FA L L 2 0 2 6
107
T R AV E L C A P S U L E
POST-CURTAIN: Bar Centrale, 324 W 46th St. Here’s the thing about Broadway: the curtain call isn’t really the end of the show—not for the people who were in it. The audience empties onto the street within twenty minutes, most of them with no idea where the cast goes next. The answer, for a meaningful number of shows within walking distance, is Bar Centrale. Hidden on the parlor level of a townhouse next to Joe Allen, who opened it as a quieter counterpoint to his own bustling tavern next door, this spot earns its IYKYK reputation—no sign on the street and a reservation system that requires you to call one week in advance to get a table. On any given night, you’re in the company of the people who actually work on Broadway—it could be Harry Connick Jr., or a director, a writer, a stagehand. For years, the bar refused to print an official cocktail list; the regulars knew what they liked, and the bartenders simply accommodated them. There’s a menu now, but the vibe holds: cocktails come with a side carafe on ice, no standing at the bar,
108
FA L L 2 0 2 6
WORTH.COM
and no party larger than six. And if you spot someone famous, don’t make it a thing. To get a reservation, call ahead to secure a table (the reservation line doesn’t open until5 pmm). You may have noticed a pattern in the listings so far. The trick to finding the right high-quality/ low-tourist combination is peeking behind the proverbial curtain. In other words, the best places are often up the escalator, down the stairs, or hidden behind a brightly lit neon sign that you would be inclined to walk right past. DINING: The View, 1535 Broadway When I tell people to go to The View, a Danny Meyer joint on the 47-48th floors of the Marriott Marquis hotel, I always add a caveat: it’s dead center in Times Square and sits at the top of one of the busiest hotels in the neighborhood - and yes, it’s a revolving restaurant. But that’s what makes it cool. Before Meyer took it over, it was a high-volume buffet-style restaurant, and the only feature was the fact that it offered 360-degree views.
Meyer has transformed it into a sophisticated supper club where you can enjoy classic American food done expertly—Prime Rib au jus with horseradish cream, butter-poached halibut with mint pea puree, and of course, a perfectly done—nay, elevated—burger. The wine list spans the globe, and the cocktail program plays on New York nostalgia: drinks as a liquid tour of the city. The New Amsterdam Sour, a nod to New York City’s original 17th-century colonial name; the Marquee Old Fashioned, a tribute to the Broadway theaters below; and so on. You can also order a drink from the lounge on the floor below. I asked our server for the Katz’s Deli Martini, designed to mimic the flavors of eating a classic Pastrami sandwich on rye - Bombay Sapphire Gin that has been fatwashed with dry-aged beef/brisket tallow, splashed with Brennivín Aquavit for the caraway and dill flavors, in a glass rimmed with Katz’s pastrami spice blend. Is there anything more New York cool than sipping a classic cocktail whilst revolving around the top of Manhattan and listening to a live piano player in the evening? I don’t think so.
THE ETHICAL CELLAR
The Great Lambrusco Comeback From Etruscan tables in 700 BC to a 1980s American sugar rush to today’s quality revival, the world’s oldest sparkling wine keeps reinventing itself. BY DEBORAH GRAYSON AND JONATHAN RUSSO
I
magine a table set in central Italy in 700BC. Dinner, served by the Etruscans who predated the Romans, featured a diverse array of vegetables, legumes and wild game such as boar, venison and fowl. They also ate fruits and nuts. Meals extended for hours and were central to their enjoyment of life. Their wine was an ancient strain of the Lambrusco grape family—the grape that thousands of years later became Italy’s number one wine export in the 1970s and 80s. Uncomplicated and fizzy, the red wine is slightly sweet and was often served as an aperitif. The Lambrusco vines’ cultivation has never ceased, and the grape has evolved significantly. However, most American wine drinkers and serious cognoscenti haven’t kept up with this progression. Unlike “newer” grapes such as cabernet sauvignon—itself a single, genetically distinct variety dating back a mere 400 years—Lambrusco is an umbrella term for an entire family of some 60 distinct grape varieties. Grown in Emilia-Romagna, the region is famous for its food. The majority of Lambrusco production occurs in the Po River Valley, which is considered the epicenter for Lambrusco viniculture. BOTTLING THE BUBBLES Lambrusco’s fizz is older than any single vintner’s ledger. As far back as 1597, the physician Andrea Bacci described the region’s wines as sparkling; by 1814, Count Vincenzo Dandolo had already published instructions for bottling sparkling wine in Modena. What Cleto Chiarli did in 1860 wasn’t invent the bubbles—it was protect them. His introduction of the mushroom cork kept the wine’s natural carbonation from escaping the bottle. Chiarli closed his trattoria to found what’s credited as Emilia-Romagna’s first wine-producing company, which still carries his name today. The real engine behind Lambrusco’s mass-market future arrived nearly a century later, when producers—the Chiarli family among them—adopted the Charmat, or tank, method, industrializing the fermentation process enough to fuel the wine’s explosive rise as Italy’s top U.S. export in the 1970s and 80s.
110
FA L L 2 0 2 6
WORTH.COM
Over time, the fermenting process that produces Lambrusco’s carbonation changed, and most producers embraced the newer, easier Charmat method. Charmat allows for greater quality control and a more homogeneous taste over the vintages. Today, over 90% of Lambruscos are made via the Charmat method. Lambrusco has three classifications: Secco (very dry), Amabile (dry to sweet), and Dolce (very sweet). The first is a wine to drink with meals, the second serves as an aperitif, and the last is a dessert wine. Like a half-drunk bottle of fizzy wine left out overnight, the Lambrusco craze went flat in the 1990s. Its highwater mark was 1985 when 13 million cases were imported into the USA. Producers, rushing to cash in on the trend, often compromised quality by adding sugar. The result was wine too sweet to pair with food. Lambrusco almost disappeared from American restaurant lists and wine stores. Enter American Armon Moore, whose newly introduced Saint Enzo Lambrusco sold out its modest first release in 2025. He confirmed the above when he told Worth, “The frustrations have been mostly about education. Lambrusco is one of the oldest sparkling wines in the world and, in America, it has spent four decades as a bit of a punchline. The stuff that arrived
here in the 70’s and 80’s was sweetened, mass-produced, and sold in volume. The category never really recovered.” He continued, “I can recall one sommelier telling me before tasting, ‘I honestly can’t remember the last Lambrusco that wasn’t sweet.’ After the first sip, he paused and shook my hand before saying, ‘I need to rethink everything I thought I knew about this category.’ That’s when I realized I wasn’t fighting the quality of the wine. I was fighting decades of perception.” Moore, along with his business partner and wife Myisha spent their careers crafting consumer messages for giants in the technology, fashion and sports worlds. He has deep roots in luxury marketing including a stint as Creative Director and Product Design Leader for Sarment, a Bulgari family company. Utilizing this aptitude for product design and message, Moore found a local Lambrusco vintner whose organic growing standards and non-intervention in the cellar techniques aligned with his vision for a hyper-quality re-introduction of this sparkling wine. He said, “I searched Northern Italy and specifically Emilia Romagna for years looking for the right vineyard to fulfill my ambition. I studied the area’s geography, grapes and winemaking traditions until I finally found what I was looking for it in the hills of Castelvetro di Modena.” His efforts have been rewarded. Winning a double gold, 98 points, at the San Francisco Wine Competition and Wine of the Year at the International Wine and Spirits Competition confirmed that he’d gotten the most important part right: the wine. Saint Enzo is grown in one of the six Lambrusco DOCs (Denominazione di Origine Controllata) which means every aspect must adhere to strict guidelines in order to bear the DOC label.
GETTY
Saint Enzo’s DOC is Lambrusco Grasparossa di Castelvetro. This area’s vines produce riper, lusher fruits that translate into a deeper red, richer, more aromatic Lambrusco. The DOC demands that 85% of the grapes are Grasparossa. Importantly, Saint Enzo uses 100% Grasparossa. Authentic Italian restaurateurs who knew that quality Lambrusco existed have kept it on their wine lists over the years. According to Gabriel Berlendis, General Manager of New York City’s fine dining Il Gattopardo and more casual Mozzarella & Vino, told Worth, “In both of our locations we promote Lambrusco as an aperitif wine, as an ingredient in mixed drinks, but especially as a good pairing with certain dishes. “At Il Gattopardo, we serve a high-end, truly exceptional product, Lambrusco “Phermento” produced by Medici Ermete. Alessandro is the current winemaker running this fifth-generation winery, and he deserves credit for his focus on a modern approach that includes organic conversion and the natural sparkling method.” He continued, “At Mozzarella & Vino, instead, we serve Lambrusco di Sorbara “La Svolta” made by Cantina della Volta and produced by Christian Bellei, a fourth-generation oenologist. Christian is widely known for making world-class wines, such as this Lambrusco produced with the classic (Champenoise) method and natural fermentation.” While Gabriel acknowledges that some of the producers may be disappointed to learn their fine quality wines are being turned into a component of a cocktail, he says the result is worth the risk of their disappointment. Gabriel ended by telling us, “Lambrusco is a product with an incredible potential and it’s our job as ambassadors to share it and tell the story behind the bottle. It is not just an aperitif as the majority of customers think, it is a product with an enormous versatility and complexity, a product that expresses the results
of hard work and ancient grape’s potential.”Ermete. Alessandro is the current winemaker running this fifthgeneration winery, and he deserves credit for his focus on a modern approach that includes organic conversion and the natural sparkling method.” He continued, “At Mozzarella & Vino, instead, we serve Lambrusco di Sorbara “La Svolta” made by Cantina della Volta and produced by Christian Bellei, a fourth-generation oenologist. Christian is widely known for making world-class wines, such as this Lambrusco produced with the classic (Champenoise) method and natural fermentation. It is an awesome wine, a little fruity, and pairs well with arancini, frittura di mare, and pasta dishes.”
Also, at both restaurants, quality Lambruscos are used for original mixed drinks and spritzes. While Gabriel acknowledges that some of the producers may be disappointed to learn their fine quality wines are being turned into a component of a cocktail, he says the result is worth the risk of their disappointment. Gabriel ended by telling us, “Lambrusco is a product and it’s our job as ambassadors to share it and tell the story behind the bottle. It is not just an aperitif as the majority of customers think, it is a product with an enormous versatility and complexity, a product that expresses the results of hard work and ancient grape’s potential.” WORTH.COM
FA L L 2 0 2 6
111
MIXED MEDIA
In her sequel to Finding the Mother Tree, Suzanne Simard turns from communication to inheritance, and finds an answer to grief in the forest’s architecture of dying and renewal. BY JASON ALLEN ASHLOCK BOOK
When the Forest Breathes: Renewal and Resilience in the Natural World BY SUZANNE SIMARD
Among the Secwépemc, whose territory covers the Interior British Columbia valleys where Suzanne Simard grew up, mourning has a shape. For a year, the bereaved withdraw from public gathering and public speech. Rather than perform their grief for the community, they simply step outside its ordinary business. When the year has closed, they return. Such an architecture of grief built on a cycle of seasons opens the space required for the trauma of loss to become neither an event to endure nor a permanent condition to manage. Simard did not invent this practice, but her new book When the Forest Breathes is organized on exactly this logic: grief handled well requires a cycling through seasons. Simard learned to see a forest this way from the Splatsin people who share her home valley, and from a grandfather who took only what the family needed and left, in his words, a forest still standing behind him. It is a smaller claim than “Indigenous wisdom will save the planet,” the kind of bannerheadline Simard’s publicity has occasionally reached for. It is also a truer one. Specific knowledge, developed over specific centuries, by people whose relationship to that land predates every timber company’s stump count. Decades ago, when Simard began telling new stories of old trees, it was not the timber companies she was up against. In 1997, she published a paper in Nature demonstrating that Douglas fir and paper birch trade carbon back and forth through shared fungal threads, a finding the journal’s editors nicknamed the “wood-wide web” and the forestry establishment labeled a heresy. She was told, by more than one colleague, to find other work. Her international bestselling
112
FA L L 2 0 2 6
WORTH.COM
book Finding the Mother Tree turned that vindication into one of the rare forest-science books to sell in the millions. When the Forest Breathes is a difficult sequel. Where Finding the Mother Tree had a plot – young scientist takes on a skeptical establishment, a shape as old as fiction – When the Forest Breathes has a cycle, and cycles resist narrative momentum What do you do with an argument once you’ve won it… but the clearcutting continues anyway? Simard’s answer runs on two parallel registers. In one, she and her team at the Mother Tree Project spend years testing what happens when logged sites retain some fraction of their old overstory instead of being flattened by clearcut reflex. It’s large, muddy, collaborative science, testing what the retained elders do for carbon storage, biodiversity, and a forest’s odds in a hotter, drier future. In the other, she is watching her own daughters become adults, watching her mother die, and in a most devastating thread, mourning Amanda Asay, her graduate student, killed in an avalanche mid-fieldwork. A dying elder tree, in Simard’s telling, does not simply vanish from the forest’s accounting. It opens a gap in the canopy that feeds the seedlings that have been waiting in its shade for exactly this light, for years, sometimes decades. The tree’s death might be seen as an interruption of the forest’s story. To Simard, it is the mechanism of its unfurling. You want to criticize this. You want to say this is sentiment dressed as science. But somehow Simard altogether avoids such a trap. She is so delicate with these two registers, so frugal, keeping them in relation rather than in metaphor. The Secwépemc bounded-mourning year and the fungal carbon transfer are two independently earned observations that happen to, when set beside each other, rhyme. The industrial forestry model she’s spent a career opposing has no year of silence built into it, no gap left open for what comes next. It offers only the immediate, total harvest, followed by a replant schedule designed to erase the idea that anything was lost at all.
But so very much was. The contemporary case for the book, though Simard never states it so baldly, is that we have lost the capacity for bounded endings across every register she writes in. We grieve on a bereavement-leave schedule and are expected to have “moved on” by the time the out-of-office expires. We extract from a landscape until a spreadsheet says the yield has dropped, then walk away from what’s left, calling the walking-away efficiency rather than abandonment. We have grown so estranged from the mechanisms of a living system that we require someone like Simard to stand at the tree line and translate it back to us, an ecologist as tour guide to a country we used to live in. We are a civilization that has forgotten how to let something end well, whether that something is a life, a stand of old growth, or an extractive arrangement with the planet that has clearly finished paying out. Without a space for grief—nay, without a shape—we make things much more dangerous for a person, and for a hillside. The Secwépemc do not grieve forever but for a year. Silent for seasons, then reaching for speech again. The forest does not mourn its mother tree forever, either. It feeds on her for exactly as long as it takes to grow past needing her. Both traditions, in their different registers, are making the same argument Simard has spent thirty years trying to get her own field to hear: an ending handled with enough attention is the essential precondition for new growth. How does a forest survive its oldest tree falling? One can imagine the Secwépemc asking. By having already grown what comes next in her shade.
Twenty years after desktop publishing handed everyone a podium, the leadership genre has produced an ocean of confidence and a puddle of evidence. Caroline Webb’s new book is a bet that the tide can still turn. BY JASON ALLEN ASHLOCK BOOK
Leadership Intelligence: Science-Backed Strategies for Mastering 21 Everyday Management Challenges BY CAROLINE WEBB
In 1997, a management consultant named Tom Peters published an essay called “The Brand Called You,” arguing that every professional ought to think of themselves as a marketable identity, complete with a value proposition and a distribution strategy. At the time it read like a provocation. It reads now like a prophecy. LinkedIn in 2003, blogging platforms by middecade, Kindle Direct Publishing by 2007, a TED stage in any city with a dimly lit auditorium and an aspiration toward virality. Once the cost of publishing a leadership philosophy dropped to zero, everyone who had ever managed a team, survived a layoff, or read half of Sun Tzu had one. Two decades on, we are drowning in frameworks and no wiser for it. Jeffrey Pfeffer, the Stanford organizational behavior scholar, made the case bluntly a decade into this onslaught: the leadership development industry had grown into a many-billion-dollar business built largely on feel-good bromides that no one could show actually worked. That was 2015. Since, the industry has professionalized further. And only gotten worse. The Harvard Business Review case study became its own genre of soft fiction with a replicable template: a firm, a challenge, a consultant, a triumphant chart. The implicit pitch was never subtle: hire the person who wrote this, and the
story could be yours too. Gartner supplied the scaffolding for the rest of it, a quadrant or a maturity model or a set of pillars for every occasion, never entirely falsifiable. A pillar is, of course, not a hypothesis. This is productized expertise, the framework as merchandise. It has made an entire class of managers fluent in the language of transformation and no better at the conversations that transformation requires.
Caroline Webb’s Leadership Intelligence seems to have been built by someone allergic to, well, all of that. Odd, given she came to her platform in the midst of the industry’s insidious formation. Webb spent the 1990s as an economist at the Bank of England before joining McKinsey, where she became a partner and helped build the firm’s leadership practice over twelve years, and she has spent the years since running her own coaching practice. Her first book, on the science of a good working day, was itself an attempt to replace vibes with mechanism. This one is more ambitious and more disciplined at once: twenty-one chapters, each opening not with an overplayed parable but with a plainly stated challenge. Like: How to disagree well, how to hand someone a layoff notice with something resembling dignity, how to keep a team’s nerve in a crisis. And each closing with a named, repeatable technique built from a specific body of cited research, footnoted at the back for anyone who wants to check her homework. If folks still do that. Webb organizes the whole system around three “double unlocks” tied to how the brain processes information, reward, and threat. When each is applied to the concrete challenges of realworld leadership, what you get is an elegant kind of curation: she chooses problems that are common but felt as unique to the humans suffering through them, and then, from a vast amount of atomized research, she plucks the most essential findings to create better conditions for action. Somehow, all of that coheres. One can almost forgive her for seeking a blurb from Daniel Pink. For those unfortunate business travelers and desperate managers who have consumed too many drab business books, Webb’s tone will be appreciated almost as much as her advice. She’s simply too busy being useful to bother with posturing. Her bet, it seems, is that honest usefulness shall triumph, and that the manager who admits she doesn’t yet have the answer, but has a reliable method for finding it, will triumph too. Twenty years in, that shouldn’t feel radical. It does.
WORTH.COM
FA L L 2 0 2 6
113
HOTE L S
The Best New Hotels The hotels expanding the map of modern luxury. BY PAUL TUMPOWSKY
L
uxury hospitality has never been more geographically ambitious. This season’s most compelling openings aren’t simply arriving in established capitals or familiar resort enclaves—they’re introducing new reasons to travel altogether. Aman debuts in Mexico, Capella enters Taiwan, Four Seasons takes to the Mediterranean by yacht, while intimate properties in Rwanda, Rote Island (Indonesia), and Ireland invite travelers to look beyond the obvious. Whether perched above Lake Wakatipu, tucked into Rome’s historic center, or overlooking an empty stretch of Baja coastline, each property reflects the growing, industrywide shift toward experiences defined by authenticity and intimacy.
NIHI Rote, Indonesia Rote Island, Indonesia
Indonesia’s southernmost island has long been known to surfers for its uncrowded breaks and untouched coastline. Now it has another reason to command attention. NIHI Rote is a new sister property of the quietly celebrated NIHI Sumba, bringing its signature blend of barefoot luxury and purpose-driven travel to the remote island of Rote. Villas draw inspiration from traditional Rotenese architecture, pairing hand-carved timber, thatched roofs, private pools, and open-air living with views across Bo’a Beach and one of Indonesia’s most celebrated surf breaks. Dining centers on fresh, locally sourced seafood, while days unfold between guided island adventures, diving, yoga, and boat excursions through crystalline waters. At its heart sits the NIHI Hospitality Academy, where local students train alongside international guests in a living classroom dedicated to hospitality, language, and cultural exchange. Developed with educator Michael Schwab and in partnership with Nobel Peace Prize laureate José Ramos-Horta, the academy’s goal is to transform every stay into something more enduring than a holiday. Here, luxury is measured not only by privacy and place, but by the opportunity to leave both guests and community changed.
114
FA L L 2 0 2 6
WORTH.COM
Fouquet’s Mykonos Mykonos, Greece Parisian glamour has found a new address on the shores of Mykonos. Perched between Paraga and Paradise Beach, Fouquet’s Mykonos brings the Barrière Collection’s signature blend of understated elegance and social energy to one of the island’s most coveted stretches of coastline. Designed as a collection of 60 suites and three expansive villas, the property favors natural stone, warm earth tones, and sculptural architecture that dissolves into the surrounding landscape. Nearly every accommodation opens toward the Aegean, with private pools, jacuzzis, or terraces that frame uninterrupted sea views. Dining is anchored by the first Greek outpost of ROKA, where robatayaki and Japanese flavors transition seamlessly from long lunches to lively evenings, while EOLE celebrates Mediterranean cuisine above the water’s edge. A rock-carved spa featuring Dr. Barbara Sturm treatments offers a quieter counterpoint to Mykonos’ famously spirited beach clubs. The result is a resort that embraces the island’s enduring dual personality: equal parts serene retreat and cosmopolitan playground.
Capella Taipei Taipei, Taiwan Capella has arrived in Taipei’s tree-lined Songshan district, extending its quietly confident approach to luxury hospitality. Designed by André Fu as a “modern mansion,” the hotel echoes the city’s rhythm, refined and contemporary yet rooted in Taiwanese heritage. Dining spans five venues including an omakase counter, refined Cantonese restaurant Rong Ju, and Ember 28, where dry-aged meats and seafood cook over an open flame. The spa, inspired by Taiwan’s mountainous landscapes with sculptural, organic forms that encourage a slower pace. Capella Curates offers guests access to the destination through experiences like tea harvesting in Pinglin and guided walks through historic Dadaocheng. In a city full of standout hotels, Capella offers something rarer: a luxury address rooted in Taipei, not just placed within it.
White Elephant Aspen Aspen, Colorado Nantucket’s White Elephant is heading West, trading sea spray for snow flurries with the opening of White Elephant Aspen. This “island in the sky” leans into mountain contemporary with a knowing wink: Roman clay–washed walls, patinated brass, leather details, and a palette that suggests both après-ski chic and very expensive outerwear. It’s boutique in scale and positioned squarely in the heart of Aspen’s skiing-shopping-dining-industrial complex. Guests will find ski lockers, a private shuttle to the slopes, outdoor hot tubs, a pool, and a courtesy car—because walking in Aspen is optional. Lola 41°, beloved by White Elephant loyalists in Nantucket and Palm Beach, arrives with its globally influenced seafood menu, joined by a hidden speakeasy for evenings that extend well past the last run. It’s familiar and refined—just with more layers and better boots. WORTH.COM
FA L L 2 0 2 6
115
HOTE L S
ROKI Collection Queenstown Queenstown, New Zealand Queenstown and the surrounding area have long excelled at adrenaline, but its luxury hotel scene leans toward secluded lodges situated beyond the town. ROKI Collection Queenstown offers a different proposition, bringing an intimate, designforward retreat directly to the shores of Lake Wakatipu. With just 15 expansive suites, the property pairs views of The Remarkables with interiors by New Zealand designer Virginia Fisher that favor understated elegance over excess. Dining is a major draw, marking the first opportunity for guests outside a remote lodge setting to experience celebrated chef Paul Froggatt’s cuisine. His three distinct venues range from refined European-inspired tasting menus at Essence to relaxed seafood at The Terrace and cocktails in The Library Bar. Wellness is equally considered, with ROKI Pure offering thermal experiences, tailored spa rituals, and a dedicated Sleep Concierge after days spent hiking, skiing, or exploring nearby vineyards. Just a short, three minute walk from Queenstown’s lively center, ROKI succeeds in bringing sophisticated urban luxury to New Zealand’s adventure capital without sacrificing the sense of place that makes the destination so compelling.
Four Seasons I Mediterranean Ports
For more than six decades, Four Seasons has perfected luxury hospitality on land. Now it is turning its attention to the sea. Four Seasons I marks the brand’s first purpose-built yacht, offering an experience that feels closer to a private floating estate than a traditional cruise. Measuring 207 meters and carrying just 95 residential-style suites, every accommodation features generous indoor-outdoor living, while many include expansive terraces and private plunge pools. Design by Tillberg Design of Sweden and Martin Brudnizki favors understated glamour, allowing the Mediterranean to remain the main attraction, along with a cleverly translucent TV screen that will never obstruct your view of the horizon. Culinary ambitions are equally elevated, with 11 restaurants and lounges highlighted by a rotating Chef-inResidence program featuring Michelin-starred talent from regional Four Seasons properties around the world. Wellness extends beyond the spa through thermal circuits, sunrise yoga, cryotherapy, and personalized fitness programming, while the vessel’s innovative transverse marina opens directly onto the sea for swimming and watersports. Because of the smaller size, sailing itineraries that combine iconic ports with lesser-known harbors reinforce the property’s greatest luxury: the freedom to experience the Mediterranean from an entirely new perspective.
116
FA L L 2 0 2 6
WORTH.COM
The Pinnacle Kigali Kigali, Rwanda Rwanda has earned global recognition for its mountain lodges, yet its capital has often been treated as a stopover rather than a destination with an incredibly rich history and art scene in its own right. This is a mistake that the Pinnacle Kigali aims to change. Perched above the city’s rolling hills in the leafy Rebero district, this nine-suite retreat brings an unusually intimate vision of urban luxury to East Africa while becoming Rwanda’s first member of Small Luxury Hotels of the World. Originally conceived as a private residence, the property retains a distinctly homey atmosphere, with bespoke furnishings, curated pan-African art, and sweeping views of the skyline throughout. Despite its modest scale, the amenities are remarkably ambitious, ranging from a saltwater infinity pool and full-service spa to a private cinema, four-lane bowling alley, and rooftop restaurant serving Afro-Asian cuisine alongside panoramic city vistas. Thoughtfully curated experiences introduce guests to Kigali’s museums, creative districts, and thriving culinary scene, encouraging travelers to linger before or after gorilla trekking. The result is a compelling new reason to spend time discovering one of Africa’s most dynamic and underrated capitals.
Amanvari, Los Cabos East Cape, Mexico On Baja’s East Cape, far beyond the churn of Cabo’s hotel corridor, Amanvari Los Cabos marks Aman’s first foray into Mexico and, characteristically, does so with restraint. Set within the 1,500-acre Costa Palmas development, the property benefits from infrastructure, a marina, and a swimmable stretch of Sea of Cortez, while maintaining the sense of remove the brand successfully trades on. The architecture follows Aman’s familiar discipline. Eighteen freestanding casitas are positioned to frame sea, desert, and mountain views, with clean-lined concrete, natural stone, and locally crafted details allowing the landscape to lead. The scale is deliberately minimal, more private compound than resort. Dining spans Italian, Japanese, and Bajadriven menus, while the Aman Spa introduces a contemporary temazcal alongside open-air yoga and treatment pavilions. Residences extend the offering for longer stays, with full integration into the broader Costa Palmas ecosystem. What makes Amanvari notable is timing. As Los Cabos continues to expand, this is one of the few openings moving in the opposite direction, toward quiet. WORTH.COM
FA L L 2 0 2 6
117
HOTE L S
The Grace, Westport Estate Westport, County Mayo, Ireland One of Ireland’s most anticipated hotel openings has arrived: The Grace is a 129-room retreat anchoring the ambitious transformation of the 430-acre Westport Estate along the Wild Atlantic Way. Set just steps from the 300-year-old Westport House, the hotel takes its name from two remarkable women with ties to Mayo: the formidable pirate queen Grace O’Malley and the effortlessly elegant Grace Kelly. The result is a property that favors understated luxury over spectacle, with interiors reflecting the region’s landscapes and heritage. Dining celebrates the West of Ireland through seasonal ingredients sourced from local producers, while the spa offers restorative treatments inspired by the surrounding countryside. Beyond the estate, County Mayo is celebrated for its dramatic Atlantic coastline, mountain landscapes, and charming villages, with visitors drawn to hiking Croagh Patrick, exploring Clew Bay’s hundreds of islands, and driving the spectacular Wild Atlantic Way. Guests can also explore the reimagined estate’s restored gardens and immersive cultural experiences. At a moment when travelers increasingly seek destinations with genuine roots, The Grace offers a thoughtful gateway to Ireland’s storied West.
Casa J.K. Place, Roma Rome, Italy The latest addition to the J.K. Collection offers something increasingly rare in Rome: the privacy of a grand residence paired with the service of one of Italy’s most admired luxury hotel brands. Hidden on the quietly elegant Via dei Prefetti, just moments from Piazza di Monte Citorio, Casa J.K. Place Roma comprises 15 impeccably designed apartments ranging from one to three bedrooms, each conceived by longtime J.K. architect Michele Bönan. Interiors favor timeless craftsmanship over spectacle, layering marble baths, bespoke furnishings, curated art, and generous living spaces that feel more like an impeccably appointed Roman home than a hotel suite. Guests enjoy the full benefits of a luxury hotel, including dedicated concierge service, an all-day restaurant, a spacious fitness center, and access to Drink Kong, one of the world’s most celebrated cocktail bars. As luxury travelers increasingly seek longer, more residential stays without sacrificing personalized service, Casa J.K. Place Roma feels like a natural evolution of the boutique hotel, offering a sophisticated address for experiencing the Eternal City at an unhurried pace.
118
FA L L 2 0 2 6
WORTH.COM
EVENTS COURT SIDE, TRACK SIDE, BOARDROOM AND BOW— WORTH’S NEXT QUARTER IS STACKED WITH THE MOMENTS THAT MATTER.
SEPTEMBER
US Open (Tennis)
Italian Grand Prix
AUGUST 23-SEPTEMBER 13 USTA BILLIE JEAN KING NATIONAL TENNIS CENTER, QUEENS, NEW YORK
The world’s top tennis players return to Flushing Meadows for the final grand slam of the season, delivering two weeks of championship competition and New York’s signature late-summer energy.
SEPTEMBER 4-6 MONZA, ITALY TRACK: AUTODROMO NAZIONALE MONZA
One of Formula 1’s most iconic races, the Italian Grand Prix combines blistering speed, rich motorsport history and the unmatched atmosphere of Monza’s legendary circuit.
OCTOBER
Techonomy 26 OCTOBER 6 SAN FRANCISCO, CA
Worth’s flagship technology conference brings together leaders across business, government and innovation to examine how emerging technologies are reshaping industries and society.
120
FA L L 2 0 2 6
WORTH.COM
Worth’s Groundbreaking Women Summit
NYC Climate Week
SEPTEMBER 15TH, NEW YORK CITY
Global leaders, policymakers, investors and innovators gather across New York for a week of discussions and initiatives focused on advancing climate solutions and sustainable growth.
Worth convenes influential executives, founders and investors for a day of conversations exploring leadership, innovation and the women shaping the future of business.
SEPTEMBER 20-27 NEW YORK CITY
NOVEMBER
DECEMBER
Fort Lauderdale Boat Show
Worth’s Leading Advisors Summit
Art Basel Miami Beach
OCTOBER 28-NOVEMBER 1 BAHIA MAR YACHTING CENTER, FORT LAUDERDALE, FL
NOVEMBER 4 NEW YORK CITY
DECEMBER 4-6 MIAMI BEACH CONVENTION CENTER, MIAMI BEACH, FLORIDA
The world’s largest in-water boat show showcases the latest yachts, marine technology and luxury lifestyle experiences across multiple waterfront venues.
Worth’s newest flagship gathering convenes the CEOs of the nation’s top RIA firms for a day of candid conversation on growth, M&A and the business that lives beyond the portfolio.
North America’s premier contemporary art fair returns for its 23rd year, drawing top galleries, collectors and a citywide slate of satellite fairs and parties that make Miami the center of the art world for one December week.
GETTY
AUGUST
Custom, not customized.
Truly custom travel. Designed entirely around you.
PRIVATE CUSTOM TRAVEL BY TCS
Crafted by the most awarded private jet expedition company.
1.888.232.9587 TCSWORLDTRAVEL.COM/PCT
A Ladybird is for eternity. the history of feminine watches. It embodies extraordinary. our passion for the extrao
NEW YORK · 40 EAST 57TH STREET · 212 396 1735