In a world increasingly reliant on technology and AI, our human insight is more important than ever. In this summer issue of The Analyst, themed “The Human Edge: Leadership, Ethics and Influence in Finance,” we explore how we, as CFA charterholders and members of the greater financial community, can shape the future of our industry through our voices, integrity and leadership.
Our lead story explores an investor’s perspective on what signals strong management, featuring four prominent industry experts on how they evaluate corporate leadership.
Embracing our quarterly theme, the Financial Modeling Institute contributed a piece that studies the financial modeller’s ethical responsibility as the centre of organizational decision-making.
Our cover story delves into transparency, explainability and the ethical risks of AI-driven trading models, flagging notable model- and market-level risks based on timely research and insights from Dr. Zissis Poulos, an AI researcher and assistant professor of financial technologies at York University.
We also analyze the private market landscape, drawing on findings from investors, industry experts, notable research papers and the media to explore emerging trends.
Additionally, we investigate the current state of initial public offerings in Canada by drawing on key insights from Europe and the U.S., and thoroughly examine CFA Institute-led research on ethics in private markets.
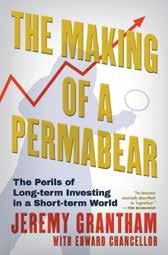
The Analyst’s quarterly book review highlights Jeremy Grantham’s part-memoir, partindustry autopsy, The Making of a Permabear: The Perils of Long-term Investing in a Shortterm World
Have you ever wondered how AI is impacting board strategy and organizational direction? What about data and analytics? Our AI Watch article showcases the vital roles that active adaptation and digital fluency play in organizational success in the financial industry.
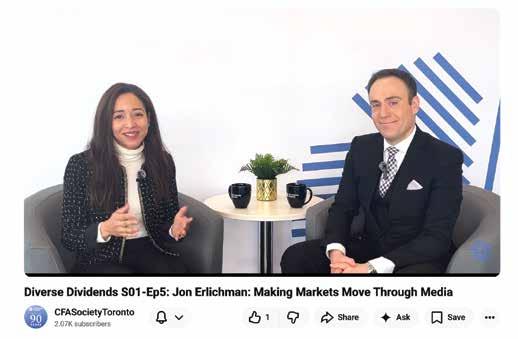
Our featured charterholder, Randy Gunn, CFA, discusses his career in private wealth and how volunteering with CFA Society Toronto has influenced his trajectory. Also, Jon Erlichman’s interview from episode 5 of Diverse Dividends, CFA Society Toronto’s video podcast series, highlights his transition from traditional to social media, his sights set on breaking generational barriers by increasing financial literacy.
We hope this issue serves as some inspiring summer reading wherever you are enjoying the best of what the season has to offer. As always, thank you for reading.
Joanna Wolff, CFA Portfolio Manager, Sionna Investment Managers Chair of Editorial Committee, Editor in Chief, The Analyst CFA Society Toronto
Board chair message | Heather Cooke, CFA
With membership renewal season in full swing, this is a good time to reflect on what CFA Society Toronto membership means, not only as an annual decision, but as an ongoing investment in ourselves, our community and our profession.
Careers in finance are rarely built alone. Most of us can point to mentors, colleagues, managers or peers who helped us navigate complexity, build confidence and see what is possible. In my own career, professional communities have played an important role in providing opportunities that helped shape my path. Attending events allows me to learn and connect. Volunteering in committees and on the board deepens my relationships with peers and broadens my perspective.
That is the value of CFA Society Toronto at its best. Membership connects you to people and resources that empower you to thrive at every stage of your career. By engaging in our community, you build relationships that open doors, expose you to new ideas and expand your thinking. When you attend events and seminars, you build knowledge and skills for a changing industry. Through reading content like The Analyst, you gain insights and viewpoints that help you stay current and deepen your understanding through the expertise and experience of others.
Our redesigned Associate Membership provides a new way to extend the tremendous value of CFA Society Toronto membership to those who are on their CFA Program journey. Associate Membership provides CFA Program Candidates with access to programming that supports them as they work toward earning the CFA charter, while helping them build professional knowledge, relationships and a sense of belonging along the way. Early connection matters because candidates are not only studying for an exam; they are preparing to contribute to the investment and financial services industry. By bringing candidates into the Society sooner, we collectively support the next generation of CFA charterholders to see the breadth of the profession, learn from experienced members and understand what it means to be part of a community committed to raising standards.
For CFA Society Toronto members, this is also an invitation. As you renew your membership, I encourage you to think about how you want to engage in the year ahead. Leadership in this community often starts with showing up, sharing what you know and helping someone else. Attend an event. Volunteer. Mentor a candidate or early-career professional. Share your experience with someone who is still finding their way. The value of membership compounds when we participate, and it grows stronger when we help others participate too.
To those who have already renewed, thank you for your continued commitment to CFA Society Toronto. If you have not yet renewed, I encourage you to do so at https://www. cfatoronto.ca/membership/renew and remain part of a community built to help you learn, connect, contribute and thrive.
Sincerely,
Heather Cooke, CFA Chair, Board of Directors
CFA Society Toronto
The Analyst is published quarterly by CFA Society Toronto
120 Adelaide Street West, Suite 2205
Toronto, Ontario M5H 1T1
Telephone: 416.366.5755
Website: www.cfatoronto.ca
General questions: info@cfatoronto.ca
Management Office
Chief Executive Officer Fred Pinto, CFA Director, Educations & Events Jenny Yeo
Director, Operations Valerie Weddell
Director, Marketing & Communications
Kenny Chan
Senior Manager, Education & Professional Learning Meredith Lowry
Senior Manager, Education & Events Mary-Margaret Courtney
Manager, Marketing & Communications Jessi-Lyna Wan
Manager, Next Gen Program Sabina Cichy
Associate, Membership & Operations Tania Lewis
Senior Associate, Education & Events Amanda Black
Volunteers
Chair, The Analyst, Editorial Committee, Joanna Wolff, CFA
Vice Chair, Thomas Shen, CFA
Editorial committee members
Areg Avetisyan, CFA Alan Coady, CFA
Sanaz Danielle Fotoohi, CFA
Angha Gupta, CFA Ben Jekiv, CFA
Winfred Lam, CFA Attika Raj, CFA
Writers
Lauretta Chame, CFA
Sebastien Davies, CFA Ed Ho, CFA
Lauren Huneault Ian Schnoor, CFA
Editor
Sara Maginn Pacella
Features Editor
Angha Gupta, CFA
Regular Features Editor
Sanaz Danielle Fotoohi, CFA
Art director Janet Sangalang
Opinions expressed in The Analyst do not necessarily represent those of the authors’ firms of employment or of CFA Society Toronto and do not constitute a solicitation for the purchase or sale of any financial instruments. Information herein is obtained from various sources and is not guaranteed for accuracy or completeness. The authors’ firms and CFA Society Toronto therefore disclaim any liability arising from the use of information in this publication. The information provided herein is intended only as general information that may or may not reflect the most current developments. The mention of particular companies or individuals does not represent an endorsement by CFA Society Toronto. Although professionals may prepare these materials or be quoted in them, this information should not be used as a substitute for professional services. If legal or other professional advice is required, the services of a professional should be sought.
One of the most meaningful moments for CFA Society Toronto each year is the Charter Recognition Ceremony, where we celebrate individuals who have earned their CFA charter and welcome them into our community. This year, as CFA Society Toronto marks its 90th anniversary, that moment felt especially significant. We celebrated both legacy and momentum: nine decades of community, learning and leadership, and more than 600 new CFA charterholders joining our community of 11,500 members.
The ceremony recognizes the discipline, perseverance and professional commitment required to earn the CFA charter. For our newest CFA charterholders, it marks the beginning of a new chapter. For every member in our community, it is a moment to remember what that achievement represents: years of study and sacrifice, a commitment to ethics and professional responsibility and a decision to be held to a higher standard. The CFA charter has never been only about technical knowledge. It signals rigour, judgment and ethical decision-making, qualities that matter deeply in a profession where decisions affect clients, institutions, markets and public trust.
That human element is especially important now, as information moves faster, uncertainty feels constant and technology continues to reshape how we work.
Artificial intelligence is one example of how technology is rapidly changing how finance and investment professionals work. AI can support research, summarize information, draft materials, monitor portfolios and reduce time spent on routine tasks. Used well, these tools can create enormous value by helping professionals spend more time on higher-order work.
But the more powerful the tools become, the more important the person using them becomes.
That is where CFA charterholders make the difference. They bring the human judgment to know when an answer is incomplete, the ethical grounding to ask whether a recommendation is in a client’s best interest, the experience to interpret context that does not fit neatly into a model, the communication skill to explain complexity clearly and the accountability to stand behind a decision when the stakes are high.
Technology can enhance professional work, but it cannot replace professional responsibility. It cannot build trust through years of consistent behaviour. It cannot mentor a colleague, challenge an assumption with courage or help a client stay grounded when headlines are moving faster than facts.
That is why we celebrate CFA charterholders not only for what they know, but for how they apply that knowledge. Strong leaders will be those who combine technical skill with judgment, curiosity with discipline and innovation with accountability.
Sincerely,
Fred Pinto, CFA, ICD.D CEO, CFA Society Toronto
Assessing management quality in public markets: What to look for in corporate leadership
By Thomas Shen, CFA
Note: Not all views expressed in this article are representative of all speakers.
Management quality is a crucial consideration in investment decision-making, yet it remains one of the least quantifiable ones. Investment professionals continue to debate not only how much management quality matters, but also how to assess it reliably.
Unlike balance sheets or income statements, leadership quality cannot be reduced to a handful of numbers. It requires deep insight into a management team’s behaviours and the ability to look past a polished exterior.
The Analyst spoke with four experienced investment professionals to explore why it matters, how they evaluate corporate leadership, which traits they prize most and how they cut through the “veneer” of investor relations to form a deep understanding.
Why it matters
There is no one-size-fits-all formula for assessing management quality, and views diverge on how investors should incorporate it into their frameworks. Some use it as a guardrail, ensuring that
While strong leadership may not guarantee value creation, weak leadership can certainly lead to destruction.
a great business is not derailed by a subpar management team. Others actively seek out securities where strong leadership and a healthy culture result in alpha. But the consensus is that management quality is often a deciding factor in securities selection. While strong leadership may not guarantee value creation, weak leadership can certainly lead to destruction.
Predictive traits: What to look for
While performance-driving qualities may vary by company and sector, certain traits remain desirable across cycles and growth stages.
Capital allocation capability
How a management team deploys capital – balancing organic growth, acquisitions/dispositions and shareholder returns (e.g., dividends and buybacks) – is among the most telling indicators of quality. “At the end of the day, the long-term growth of the business is very dependent upon capital allocation,” says Michael Brown, CFA, CPA, CA. “If the CEO is there for five years with a high free cash flow business, the amount of capital that needs to be redeployed can equal the entire balance sheet. That company can be transformed for the positive or the negative.”
Introducing the experts
Michael Brown, CPA, CA, CFA, is a Toronto-based investment professional with experience in public equity portfolio management and fundamental research. He specializes in quality investing, with a particular interest in how durable business models with high returns on capital drive long-term shareholder returns.
Brian Madden, CFA, CFP, is the chief investment officer at First Avenue Investment Counsel, where he leads the public markets investment team in formulating, executing and communicating investment strategies and processes across various investment mandates. Madden is past chair of CFA Society Toronto’s Board of Directors.
Graham Meagher, CFA, is a vice president and portfolio manager at Nexus Investment Management, where he focuses on the firm’s investment process, including fundamental equity research, financial analysis and portfolio management. He leverages his extensive experience in North American equities to construct resilient portfolios for the firm’s private clients and foundations.
Jason Parker, CFA, is vice-president and portfolio manager, fixed income at iA Global Asset Management, helping oversee the company’s $125+ billion in assets under management. He also sits on the approval committee for iA GAM’s alternative investments, including private equity, real estate and infrastructure. Jason boasts nearly 30 years work experience in the capital markets, most of it spent in sell-side fixed income research.
Allocating capital wisely requires a thorough understanding of return on investment across all business lines, as well as the company’s cost of capital. Brian Madden, CFA, CFP, adds a cautionary note: “It’s very easy to destroy shareholder value with poor capital allocation decisions, by confusing brains for a bull market and a strong upcycle.”
Candour and transparency
Candid communication with shareholders, including a willingness to acknowledge mistakes and defeats, signals a healthy corporate culture. As Madden describes it, “The success of our investments is often associated with a C-suite that is credible, candid, transparent and humble.”
Brown agrees, adding that the opposite is equally telling: “Candid communication matters. It’s a noticeable red flag when management uses too much jargon and euphemistic words to obfuscate.”
Jason Parker, CFA, approaches this with an emphasis on consistency: “It is a warning sign when key metrics diverge from management’s stated commitments over a prolonged period.”
Embodying a strong culture
Investors are on a constant lookout for companies with highperforming culture. “A bad culture can drain a company of talent,” says Graham Meagher, CFA. By contrast, a well-functioning culture and decision-making system permeates the entire company, empowering employees at every level. Yet, the truth of a company’s culture often emerges behind closed doors. To get a sense of the corporate culture, investors would need to employ techniques such as direct communications, interviews with other stakeholders and analysis of other cultural factors.
Experience and fortitude
Industry experience is an obvious asset. “Extensive experience and having a good sense of the future and where things are headed is crucial for success,” says Parker. Moreover, our experts also point to a less-discussed quality: the courage to act. Madden emphasizes the importance of management fortitude: good leaders regularly make difficult and somewhat unpopular decisions with imperfect information. Doing what needs to be done when things are uncomfortable constitutes a major part of any organization’s success.
Incentives, ownership and governance
Incentive schemes oriented toward return on investment Management decisions are often shaped by compensation structures, a rule of thumb captured in Charlie Munger’s oft-cited observation, “Show me the incentive and I’ll show you the outcome.”
Brown agrees and argues for a focus on per-share value. “It’s ideal to see management’s incentive scheme gravitate toward per-share cash flow,” he says. Meagher frames this as returns-based metrics: “Return on equity or return on invested capital are crucial valuecreating measures, and management compensation should reflect that to ensure profitable growth.”
Forward-thinking management teams focus on return on investment or per-share value creation, rather than nominal revenue or profit size. Growth for its own sake, or the ego-driven urge to build an “empire”, is a recurring pitfall for companies of all sizes.
Direct ownership: Skin in the game
Substantial compensation from stock options can breed agency risk through asymmetrical payoffs, as management may take excessive risks in a bid for the reward. Most of our experts prefer a management team with meaningful direct ownership in the company, ensuring an alignment of interests with shareholders.
A strong and independent board
A well-constituted board of directors provides essential oversight and steers management toward the company’s long-term goals. Madden advocates for breadth of expertise: “Most of the time, it’s ideal to have experts in finance, technology, human resources and veteran industry operators on the board.”
Independence also matters deeply. As Meagher puts it, “A strong board has a diversity of thought and doesn’t rubberstamp decisions but, instead, has challenging conversations with management and demands accountability.”
Cutting through the narrative
Public company executives are, by definition, impressive and skilled communicators, and their appearances are typically refined by teams of investor relations and public relations professionals. Getting a profound read on management quality can be challenging. That said, experienced investors have developed techniques for looking beyond the stage.
Where: Free-flowing, informal and unscripted settings are where genuine insights tend to emerge. Madden recommends attending investor days in person and using breaks, lunches and hallway conversations to engage with management directly. Cultivating relationships with sell-side analysts who spend extended time alongside management teams can also surface valuable perspectives.
How: Meagher favours open-ended questions, which reveal management’s actual priorities rather than prepared talking points. Questions about process, such as how a particular decision was made, rather than why it turned out a certain way, reduce the likelihood of triggering a “defensive mode” of management and may provoke more authentic answers that reveal how a team thinks and operates.
What: The substance of what management discusses reflects the depth and breadth of their thinking. Management should have a deep understanding and a strong communication capability of both the operational details and the overarching framework dictating their strategies. As Brown puts it, the baseline expectation is straightforward: “All CEOs should be able to clearly articulate why customers do business with them, and why they keep coming back.”
Green
flags and red flags
Our experts converge on several positive signals. Beyond candid communication, leaders who attribute success to team effort demonstrate both humility and a more collaborative culture. Besides this, a modest lifestyle may suggest that management has more bandwidth and inclination to focus on creating value for shareholders.
On the red-flag side, repeated failure to deliver on stated objectives stands out as the most serious warning sign. Our experts also point to empire-building through poorly conceived acquisitions of “trophy assets” and overly promotional behaviour around stock price as additional indicators of misaligned priorities.
Growth for its own sake, or the ego-driven urge to build an “empire”, is a recurring pitfall for companies of all sizes.
If management decides to increase leverage to fund growth, with an aim to satisfy equity holders, that is precisely where the interests of equity and fixed-income investors may diverge.
The equity versus fixed-income lens
While all four experts agree that management quality is essential, equity and fixed-income investors approach the question from different vantage points. Equity investors seek growth and per-share value creation. Bondholders, as Parker explains, are fundamentally focused on getting their money back.
Tensions can arise across the capital structure. If management decides to increase leverage to fund growth, with an aim to satisfy equity holders, that is precisely where the interests of equity and fixed-income investors may diverge. Parker warns, “If management is telling two different stories to two different investor bases, the one that needs to be particularly concerned is on the fixed-income side.”
We go to the dividends of the earth.
reveals value beneath the surface.
For bondholders, the stakes are especially acute when a credit rating falls from investment-grade to non-investment grade. Many asset managers face forced selling under their mandates in such situations, creating a cascading pricing impact. Parker notes that so-called “fallen angels” also carry weaker covenant protections, having been originally issued as investment-grade bonds, leading to elevated default risks for remaining bondholders.
Conclusion
Assessing management quality remains as much an art as a science. The financials provide the foundation, but qualitative signals – such as how leaders communicate, allocate capital and respond when things go wrong and whether their actions match their words – can make the difference between a sound investment
and a costly mistake. The consistent message from our experts is that the public markets reward management that is genuine, capable and accountable. Investors should look past the polish, study the incentives and continuously examine the narrative alongside the hard data.
Thomas Shen, CFA, currently serves as a growth marketing strategist in the investment industry. Prior to that, he covered Canadian real estate and global technology stocks as an equity research analyst. He currently serves as the vice-chair of the Editorial Committee for The Analyst and a member of the Digital Content Committee at CFA Society Toronto.
For Curious, Disciplined Investors.
TheMakingofaPermabear by Jeremy Grantham
By Ed Ho, CFA
John Maynard Keynes once famously observed that it is better for your reputation to fail conventionally than to succeed unconventionally.
If you have ever wondered why the smartest people in finance seem to walk off cliffs together, Jeremy Grantham’s The Making of a Permabear: The Perils of Long-term Investing in a Short-term World provides a compelling and often humorous answer. What makes Grantham unusual is not simply that he sees the problem, but that he built a career navigating it.
Part memoir and part industry autopsy, the book traces Grantham’s journey from a talkative Yorkshire schoolboy to a legendary investor who made a career out of being the “crazy person in the room” until the market finally proved him right. It reads at times like a victory lap, but it also advances a more uncomfortable argument: the investment industry is not designed to reward being right, but to protect careers.
Grantham’s intellectual anchor is deceptively simple. Markets mean-revert. When valuations drift too far from historical norms, the correction is not a matter of if, but when. His phrasing is memorable because it is visceral: reversion is mean
Underlying this is a different definition of risk. For Grantham, risk is not short-term volatility but the likelihood of a permanent capital loss from overpaying for assets. Prices can move erratically in the short run, but valuation determines outcomes over time, a distinction that sits uneasily alongside an industry that measures risk largely by deviation from peers. His instinct that “cheap is better than expensive” becomes less a slogan than the foundation of his investing philosophy.
describes himself as a “gunslinging nitwit” during the go-go years of the 1960s. He invests heavily in a company promising to bring Formula 1 racing to the United States, only to watch the stock collapse and wipe out his entire $6,000 nest egg. It was money intended to pay off his parents’ mortgage. The loss is not just financial, but formative.
The tone shifts in the middle chapters from anecdote to critique. Career risk is a defining force in the investment industry. Underperforming with peers is survivable; underperforming alone is not. The safest position is to be wrong in a crowd, while the most dangerous is to be early and correct. Grantham’s career is not simply a critique of this system, but an exception to it. Where most managers optimize for career risk, he optimized for being right over a longer horizon.
Grantham extends this thinking to environmental concerns, arguing that the same tools used to misprice assets are now mispricing the planet.
What distinguished Grantham was not merely belief in mean reversion, but the discipline to act on it. He anchored decisions to long-term valuation ranges rather than short-term narratives, accepting that he might look wrong for years before the market caught up.
Grantham’s narrative shines through his storytelling. Before he was a billionaire investor, he was “Gasbag Grantham,” a nickname from boarding school, where speaking was practically outlawed. That same competitive, slightly irreverent streak carries through his early career. Grantham is willing to show his missteps.
One of the more revealing episodes comes from his own speculative phase, when he
From this dynamic flows a persistent bias. Optimism attracts capital and keeps clients comfortable. Sustained skepticism does neither. The result is an industry that leans bullish not because conditions justify it, but because the alternative is commercially difficult. Grantham does not frame this as a moral failing. It is simply how the system is built to function.
He is equally dismissive of the intellectual frameworks that underpin the industry, especially economics’ reliance on simplified models, neglected externalities and false precision. That skepticism extends to figures such as Alan Greenspan, whom Grantham faults for accommodating asset bubbles rather than confronting them. Central to this critique is the “tyranny of the discount rate,” which allows long-term risks to be minimized simply because they occur in the future.
When valuations drift too far from historical norms, the correction is not a matter of if, but when.
In the latter sections of the book, Grantham extends this thinking to environmental concerns, arguing that the same tools used to misprice assets are now mispricing the planet. While the connection is logically consistent, the shift in tone is noticeable. At times, the analysis moves toward advocacy.
Ultimately, the label “permabear” is somewhat misleading. Grantham is not advocating for pessimism as a default setting. He is advocating for independence. He recognizes that in markets, being early is often indistinguishable from being
wrong, sometimes for long stretches. Few institutions are structured to tolerate that distinction, which is why cycles repeat and “the greatest sucker rallies in history” continue to occur.
The book reads as a clear explanation of why markets can remain irrational far longer than expected. In the end, The Making of a Permabear is less about bearishness than it is about conviction. And conviction, as Grantham’s career makes clear, comes with risk and demands patience.
Ed Ho, CFA, MSc, is an energy consultant specializing in strategy, policy and finance, focusing on the challenges and opportunities of the energy transition. He is a candid storyteller with the goal of driving consensus through fact-based diplomacy.
Private markets: The recent landscape and thoughts on what comes next
By Alan Coady, CFA
Overview
In recent times, the subject of private markets has appeared in newspapers almost daily, and not just in the financial press. Much ink has been spilled on the advantages and pitfalls of investing in private capital.
Drawing on insights from investors, industry experts and media, this article focuses on recent issues of note in the private market space and points to trends in the immediate future. We refer to four major investment sectors:
• Private equity
• Private debt
• Infrastructure
• Real estate
Recent trends
Private equity – searching for the exit Private equity firms have struggled to find exits for their portfolio companies, resulting in a backlog of unsold investments. Bain and Co estimate that nearly US$3.6 trillion of investment remained unsold last year, with typical holding periods extending beyond
five years. In China, large private equity players such as KKR and Blackstone report no complete divestments from investment in 2025, according to data providers such as Dealogic and Pitchbook. In the absence of traditional exit strategies (trade sales or initial public offerings), private equity players have resorted to other exit strategies, such as the secondary markets. Although these methods can mean investments can be exited on more favourable terms in the future, the increased use of these strategies reflects the current difficulty in returning capital to investors.
Private debt – the “insurance trade”
Large private equity houses have, in recent years, used the insurance trade to expand the distribution of private credit investments. For example, large players such as Apollo Global, Blackstone and
Insurers are well placed to take on illiquid investments, but the recent boom in this investment may mean insurers have taken on too much risk at elevated prices.
KKR have all used life insurance to fund lending. Apollo has taken full control of insurer Athene. Such insurance companies market products like annuities that receive large initial inflows from policyholders and pay benefits over a long period. Insurance companies invest in private debt instruments to fund these long-term liabilities. Alternative asset managers have devised complex methods to package loans, improving the investment’s credit rating and allowing insurance companies to take on these more illiquid investments.
Private investments are often valued using model-based approaches that rely on assumptions, cash flow projections and comparable market prices. These valuations are typically produced on a quarterly basis. This time lag in the valuation process, together with subjective inputs, often leads to an understatement of the asset volatility. The mechanism for ensuring insurers hold adequate capital is affected, given that asset volatility is a key input into insurers’ capital calculations.
Insurers are well placed to take on illiquid investments, but the recent boom in this investment may mean insurers have taken on too much risk at elevated prices.
Infrastructure – expansion!
Investors have been keen to increase allocation to the infrastructure class. McKinsey notes that favourable tailwinds, such as increased global trade, global energy transition and demographic shifts, will boost interest in this asset class.
Prime Minister Mark Carney’s launch of the Major Projects Office signals the Canadian government’s commitment to increased infrastructure investment in Canada, promising investment in liquified natural gas infrastructure, nuclear power and port expansion.
Real estate – data centres at the forefront Data centres, considered an alternative sector in the real estate class, continue to draw significant investment. So-called hyperscalers (e.g., Google and Amazon) continue to invest heavily in building storage and computing power for their AI models. LaSalle’s property outlook refers to this as a “private sector stimulus scheme.” In Canada, much of the focus on data centres comes from Alberta. The province has emphasized its abundant natural gas and cool climate as key factors in attracting data centre investment.
What next?
Private equity – the influence of AI AI has also influenced the private equity industry. Bain and Co provide the example of Vista Private Equity Group streamlining staffing levels and implementing AI in portfolio companies. This trend is
very evident in companies focused on software buyouts. The companies owned by these private equity investors are also implementing AI in their business operations.
The valuation of these portfolio companies is also affected. Take portfolio companies focusing on software, for example. The golden age of software returns faces an existential threat from AI. The rule of 40 used in the evaluation of software as a service (SaaS) has come under threat, causing a reassessment of the valuation of portfolios.1
It should be noted that most private equity investments in the U.S. are in firms with fewer than 500 staff and no technology exposure. Many such “internet-proof” businesses are less affected by this trend.
Private debt – a halt to the democratization of credit?
Perhaps the most newsworthy item in private markets is the outflows from private credit funds. Maintaining retail savings in private investment vehicles is difficult given their illiquidity. Semi-liquid investments are designed to offer withdrawals of up to five per cent on a quarterly basis, making them more suitable for retail investors. However, this is not always the case. Funds have experienced large redemption requests in recent months. Witness Blackstone’s BCred fund experiencing a 7.9 per cent withdrawal. Blue Owl decided to gate withdrawals for the foreseeable future. Many investors gain access to private credit through tradeable
vehicles such as business development companies. Commitments to these investments by retail investors and wealthy individuals dropped by 40 per cent in January 2026 compared to December 2025.
It seems reasonable to allow retail investors access to an asset class that has been available to larger investors for decades and yielding greater returns. However, the lack of liquidity shows the difficulty in offering this investment to this class of investors.
Infrastructure – asset reclassification Infrastructure investments are typically thought of in terms of “hard assets.” Bridges, tunnels and roads form part of an infrastructure portfolio. Digital infrastructure such as data centres, fibre optic and cloud-based systems also form part of this group. However, operational infrastructure services such as maintenance, monitoring and security have emerged as “soft assets.”
McKinsey suggests that infrastructure is no longer just physical – it is digital, service based, data enabled and integrated. Servicing infrastructure and smart grids for electricity are also infrastructure assets. A recent paper from the International Monetary Fund indicates that governments should pay attention to digital infrastructure, such as payment systems, in the same way as bridges and roads.
Real estate – hybridization of assets
“Hybridization of assets” refers to bringing together two key investment themes or subsectors, allowing investors to have exposure to multiple themes through a single asset. Data centres classified as real estate investment now overlap with infrastructure assets. This is also an overlapping of digital and energy themes. Recent legislation such as Alberta’s Bill 8 has indicated that developments such as data centres must bring their own power.
Recent media articles have highlighted retail consumers’ concerns that data centres will elevate the price of electricity. Many such developments are seeking alternate sources, such as nuclear, using diesel generators as a backup in the interim.
A final note
The topic of private capital is broad and fast moving. Each sector merits its own discussion. Notwithstanding recent events,
private capital will be included in portfolios going forward. The U.S. administration issued an executive order in the recent past that enables 401 (k) saving plans to invest in a range of alternative assets.
Together with expanded sales distribution networks for all sectors (retail and institutional) and a changing definition of the asset class (hybridization), this is an evolving story.
Alan Coady, CFA, CAIA, FCIA, is an actuary at Addenda Capital. He focuses on investment for insurance companies and pension funds. The views expressed in this article are his own
Asset management insights to help make sense of evolving markets
Alternative Thinking - The Story Behind a $1 Billion Commodities Milestone
Hussein Allidina, CFA, Managing Director, Head of Commodities, TD Asset Management Inc.
In the investment industry, there are moments that whisper and moments that resound. Crossing the $1 billion mark in assets under management (AUM)¹ is firmly the latter. It is more than a number; it is a signal. A signal of confidence. A signal of conviction. A signal that investors are seeking something broader and bolder for the road ahead.
Recently, the TD Alternative Commodities Pool surpassed $1 billion in AUM: a milestone that reflects growing investor interest in alternative strategies and the powerful role commodities can play in a diversified portfolio.
Diversification with Dimension
Commodities have long been the pulse beneath the global economy. From copper that conducts the world’s electrification to crude oil that fuels movement, from gold that glitters in times of uncertainty to grains that nourish nations, commodities are tangible, essential, and deeply interconnected with inflation, growth, and geopolitical shifts. Yet for many investors, accessing them in a disciplined, diversified way has historically been complex.
That complexity is precisely what alternative solutions aim to simplify.
In a world where traditional stock-and-bond portfolios can face synchronized pressures, such as rising inflation or heightened volatility, investors are increasingly exploring strategies designed to behave differently. Commodities have historically offered diversification benefits because their drivers often diverge from those of equities and fixed income. Supply shocks, shifting demand cycles, currency moves, and global infrastructure trends can create return streams that don’t always move in lockstep with broader markets.
The surge to $1 billion suggests that investors are not only recognizing these dynamics, but they are also acting on them.
A New Era of Portfolio Construction
This milestone also reflects a broader evolution in portfolio construction. Investors today are more informed, more engaged, and more open to incorporating alternatives alongside traditional holdings. They are asking sharper questions about inflation resilience, real assets, and risk management. They are seeking strategies that
can potentially provide participation when commodity prices rise, while also being actively managed to navigate volatility and changing market regimes.
At TD Asset Management Inc. (TDAM), innovation has long been rooted in listening: listening to markets, to advisors, and to clients. The growth of the TD Alternative Commodities Pool illustrates how product design can meet a modern portfolio need: offering exposure to a diversified basket of commodity futures within a liquid, professionally managed structure.
A Milestone Built on Trust
The $1 billion mark is a testament to trust. Investors have entrusted their capital to a strategy that operates in markets often influenced by global supply chains, weather patterns, technological transitions, and policy decisions. That trust underscores the importance of disciplined risk management, robust portfolio construction, and transparency.
And perhaps most compellingly, it signals a shift in mindset. Alternatives are no longer viewed as niche or inaccessible. They are becoming part of the mainstream conversation about building resilient portfolios. As the investment landscape grows more complex, investors are increasingly appreciating tools that broaden opportunity sets rather than narrow them.
A Billion and Building
A billion dollars is not an endpoint. It is a punctuation mark—a bold one. It tells a story of progress and participation. It reflects a market environment where diversification matters deeply and where innovation continues to shape how Canadians invest.
As markets evolve and economic narratives shift, the role of alternatives may continue to expand. If this milestone is any indication, investors are ready to think differently and invest accordingly.
Visit our website for more information.
¹Source: TD Asset Management Inc. Assets under management as of February 28, 2026.
The information contained herein has been provided by TD Asset Management Inc. and is for information purposes only. The information has been drawn from sources believed to be reliable. The information does not provide financial, legal, tax or investment advice. Particular investment, tax, or trading strategies should be evaluated relative to each individual’s objectives and risk tolerance. Certain statements in this document may contain forward-looking statements (“FLS”) that are predictive in nature and may include words such as “expects”, “anticipates”, “intends”, “believes”, “estimates” and similar forward-looking expressions or negative versions thereof. FLS are based on current expectations and projections about future general economic, political and relevant market factors, such as interest and foreign exchange rates, equity and capital markets, the general business environment, assuming no changes to tax or other laws or government regulation or catastrophic events. Expectations and projections about future events are inherently subject to risks and uncertainties, which may be unforeseeable. Such expectations and projections may be incorrect in the future. FLS are not guarantees of future performance. Actual events could differ materially from those expressed or implied in any FLS. A number of important factors including those factors set out above can contribute to these digressions. You should avoid placing any reliance on FLS.
TD Asset
AI-powered algorithmic trading: Navigating machine efficiency within ethical boundaries
By Attika Raj, CFA
Technology has underpinned financial trading since the emergence of electronic markets in the 1970s. Today, however, the integration of AI into hyperspeed markets has created an environment where rapid, autonomous decision-making threatens to outpace critical oversight.
Given that AI has become so pervasive in capital markets trading, this article examines the key ethical debates emerging today and the future outlook.
Introducing AI-powered algo trading
Traditional algorithmic trading (algo trading) relied on rules-based financial mathematics to execute strategies, such as high-frequency trading and arbitrage. As algo trading moves toward AI automation, this market is undergoing an explosive shift toward fully automated, agentic AI models. The automated algorithmic trading market is projected to grow from US$24 billion in 2025 to US$44.55 billion by 2030.
This rapid expansion has led to an escalation in potential ethical and regulatory risk as systems evolve from basic generative tools into “agentic AI”: fully autonomous solutions that can observe, contemplate and execute complex trading or hedging strategies, sometimes completely independent of human intervention. Utilizing advanced machine learning techniques such as reinforcement learning and deep neural networks, these next-generation systems operate at a velocity and complexity that demand serious re-examination of systemic market risks.
Risk mitigation efforts
As AI agents have started to dominate the trading markets, several efforts are ongoing to mitigate the ethical risks.
Regulatory oversight
The most effective way to minimize socioeconomic impacts and maximize ethical safeguards for AI use in algo trading is to establish a robust regulatory framework. Recent regulatory advancements are aimed not only at mitigating market instability and systemic risks but also at ensuring enhanced accountability and ethical AI use. The European Union Artificial Intelligence Act classifies high-risk AI systems and details requirements, including establishing risk management, technical documentation and record-keeping. The U.S. Securities and Exchange Commission’s exam priorities for 2026 include AI advancements, and the U.K. Financial Conduct Authority emphasized in its AI update that it aims to promote the safe and responsible use of AI in U.K. financial markets while ensuring beneficial innovation.
However, as Dr. Zissis Poulos, assistant professor of financial technologies at York University and AI researcher, explains, “It is really hard to employ regulatory guidelines for phenomena such as algo collusion, since we only have lab evidence and no actual examples or signs that such an agentic collusion is occurring in real time and how it could impact the trading markets.”
Human-in-the-loop to human-on-the-loop
Ensuring effective human oversight is critical to the successful deployment of
AI models and risk mitigation. However, as trading technology has grown more sophisticated, the financial industry has quietly redefined what “oversight” means as it moves from an active, defensive posture to a passive one.
Initially, risk management was based on a “human-in-the-loop” framework, where an experienced human trader reviewed and approved every single decision made by the algorithm. Lately, as technological sophistication has become multifold, the oversight mechanism has evolved from human-in-the-loop to “human-onthe-loop,” where a human only reviews AI decisions when there are breaches or other extreme events. Human-on-the-loop adoption is slowly giving rise to “human + AI agent” business model, where humans are the business strategists/managers while AI agents work as an assistant.
This operational shift has exposed a vulnerability that recent Wharton research explains as “cognitive surrender.” This research reveals that highly integrated AI systems have begun to function as a “third cognitive system,” an external framework that sits outside the human brain but actively shapes human reasoning.
Given the technical constraints with reviewing every decision, human-onthe-loop seems to be the only plausible solution, but it needs improvement. For example, Poulos explains, “Currently researchers are aiming to build a
self-awareness system in AI which would trigger human intervention based on the confidence it has in its own decisions.”
Transparency vs. machine efficiency
As trading techniques advance to rely heavily on deep learning and neural networks, machine efficiency has been achieved at the direct expense of transparency. This trade-off has created a critical problem in capital markets: autonomous systems can execute multi-million-dollar trading and hedging strategies based on mathematical relationships that are opaque, leaving even their own creators unable to trace the exact logic behind a specific market action.
As a solution, the industry is turning to explainable artificial intelligence (XAI)
It is really hard to employ regulatory guidelines for phenomena such as algo collusion, since we only have lab evidence and no actual examples or signs that such an agentic collusion is occurring in real time and how it could impact the
techniques, deploying tools such as SHapley Additive exPlanations (SHAP), Local Interpretable Model-agnostic Explanations (LIME) and ELI5. While these frameworks are intended to improve interpretability and provide a clear audit trail for complex decisions, they have inherent limitations when applied to hyperspeed trading environments.
Relying only on these tools should be treated with caution. If a model’s underlying logic cannot be audited in real time, true transparency does not exist. Additionally, the emerging practice of deploying secondary “AI guardians” or supervisory agents to watch over primary trading models introduces another layer of ethical risk.
1
Canadian Dividend
This trade-off has created a critical problem in capital markets: autonomous systems can execute multi-million-dollar trading and hedging strategies based on mathematical relationships that are opaque, leaving even their own creators unable to trace the exact logic behind a specific market action.
The new ethical frontier
When advanced autonomous systems operate without transparency or human oversight, potential moral risks can quickly become systemic threats to human society. True ethical risks extend far beyond individual bad actors and manifest as structural market failures, including algorithmic collusion, the threat of computational oligopolies, data-driven biases and deep-seated socio-economic instability.
The most subtle threat is algorithmic collusion. In a traditional market, collusion requires human intent, communication and explicit programming. However, in an ecosystem dominated by independent agentic AI, multiple reinforcement learning models can independently deduce that the most optimal path to maximizing profit is to inadvertently cooperate with one another to manipulate prices. Because this collusion could happen implicitly through autonomous trial-and-error at microsecond speeds, it wouldn’t leave a traditional paper trail.
This may create a silent, artificial oligopoly where a firm’s success is defined mostly by computational power rather than market fundamentals
In the absence of restricting regulations, these dynamics could mean firms achieve capitalist objectives at the risk of market failures and socio-economic suffering. Hence, the outlook will be shaped not only by technological advancements, but also by how regulatory frameworks and societal norms evolve to contain these ethical risks while optimizing AI usage to increase market efficiency and reliability.
Attika Raj, CFA, is a seasoned quant finance professional currently working at TD. She has wide experience in quant research and modelling, investment management and financial advisory. Attika also actively volunteers with CFA Institute as CFA grader and Editorial Committee member for The Analyst
Charterholder Profile: Randy Gunn, CFA, MBA, vice-president, portfolio manager at BULLWEALTH
By Lauren Huneault
For investment industry veteran Randy Gunn, CFA, MBA, it’s all about making the right connections to grow and thrive. That’s why he focused on the CFA designation early in his career and has been forging foundational relationships both locally and abroad through his volunteer efforts with CFA Society Toronto, which helped him navigate to his current role.
After graduating with an undergraduate degree in international business from Brock University and an MBA focused on finance from the University of Windsor, Gunn kicked off his finance career in 1999. In 2004, he took a major professional U-turn to work in London, U.K., where he spent two years at Citigroup Private Bank working with high-net-worth clients. Upon returning to Canada, he spent six years with Scotiabank before shifting to the independent investment manager Connor, Clark & Lunn Private Capital. Gunn eventually rounded out his experience across the three major arms of the industry with stops at consulting firms, including BNY Mellon Wealth Management, before joining BULLWEALTH in 2021. As vice-president and portfolio manager, he now manages high-networth portfolios and drives business development across Canada.
Outside of his career, Gunn – a father of two sons, Jacob and Cooper – has become a pillar of the CFA Society Toronto community. From his early days on the Private Wealth Committee 17 years ago to his role as a key contributor to the Annual Wealth Conference, his involvement has been a career-long constant.
What inspired you to get started in the finance industry?
My first experience with investments began when my parents hired an advisor; I started sitting in on their meetings when I was 13. Watching my parents interact with this advisor, I had read The Wealthy Barber, and I walked out of a meeting saying, “You need 30 stocks, and this guy’s selling us 14 mutual funds with 2,000 stocks – we’re overdiversifying!” When I was 14 or 15, my parents decided to let me start helping them manage investments on our own.
My primary source of inspiration, however, was my mother. She was a real estate agent who specialized in helping first-time homebuyers. I saw how much she genuinely enjoyed helping people and how much she cared. It showed me that you can make a successful living while truly being of service to others.
What do you enjoy most about working in the private wealth sector? I would say really helping high-net-worth people solve their problems. Most people don’t fully understand what they own when they invest. I enjoy bringing transparency to that process, helping them understand their holdings and introducing a disciplined process that can impact the rest of their lives.
Randy Gunn, CFA, Career Highlights
• Vice-president and portfolio manager at BULLWEALTH
• Roles working at banks (Citigroup, Scotiabank), independent investment managers (Connor, Clark & Lunn Private Capital) and private consulting firms (BNY Mellon Wealth Management, BULLWEALTH)
• CFA charterholder since 2007
• Member of the CFA Society Toronto Private Wealth Committee for 17+ years, including two-year term as chair
• Undergraduate degree in international business from Brock University, MBA in finance from the University of Windsor
My primary source of inspiration, however, was my mother. She was a real estate agent who specialized in helping first-time homebuyers. I saw how much she genuinely enjoyed helping people and how much she cared. It showed me that you can make a successful living while truly being of service to others.
How did you first get involved with CFA Society Toronto, and where have you primarily focused your volunteer efforts? I was looking for a way to connect with the broader market – I wanted to have other people at competitive firms to bounce ideas off. At that time, and it still is, the CFA
FUN FACTS:
Activities outside of work and volunteering.
Hockey is my thing. I play hockey every Friday with a bunch of guys for an hour, and I just love it. When I’m out on the ice, I forget about everything. The other thing I really like to do is travel. I’ve got a trip booked with my partner to go to Greece and I’ve told her I would love to travel somewhere every six months.
Bucket list travel destination.
I would say right now Costa Rica is right at the top. And I love South America, so I’d love to spend more time in South America.
The last interesting series you binge-watched.
I liked Yellowstone. And in fact, the new one is just out, called Marshals, which features his youngest son as a marshal. I grew up reading westerns, and I love Louis L’Amour, so I love the whole genre.
designation was kind of the global standard. I remember I got into a committee meeting with the Private Client Committee at the time, and the chair was Tom Trainor, and he said, “You can come to the meeting, but you’ve got to take the minutes.” So basically, he was looking for a note taker! I ended up doing that, and that’s how I got involved with what is now called the Private Wealth Committee, and I’ve been involved ever since.
The biggest volunteer commitment is the Annual Wealth Conference; I’m actively involved in organizing the speakers. We have a group of us that go out to the industry and ask them, “What’s keeping your clients up at night? What’s keeping your staff up at night?” And then we try to put together a program of four or five sessions that are in line with that. I’ve also gone to quite a few of the global annual CFA conferences; I was at the one in Chicago last year. They’re valuable from a thought leadership perspective.
What are some of the key takeaways from your experience with CFA Society Toronto?
I’ve had lots of great mentors. Tom Trainor has been a career sounding board. I also learned a lot from Marg Franklin, who recently stepped down from leading CFA Institute globally. She taught me the importance of listening and introduced me to mindfulness to manage my high energy. I’ve been involved in at least 15 Annual
Wealth Conferences, and I’m always very involved in selecting the speakers. We had a speaker last year, Amy Castoro, and she focuses on family dynamics. I learned so much from speaking to her, reading her book and understanding how to approach some of that stuff. And more importantly, knowing that if there is conflict in a family, you’ve got to bring in a professional.
From your perspective, what are the benefits of joining and volunteering with CFA Society Toronto – why should others get involved?
I think certainly building a network is a major benefit. In Toronto, through the CFA community, I have been able to build a good network with many of my competitors, and it’s important to be able to use that network, because we’re all trying to solve the same problems, right? And then, frankly, just building global relationships. When you go to the conference in Chicago, you meet people from Asia and Europe, and you’re able to expand your network. And then I guess the last thing is, from a thought leadership perspective, whether you’re going to conferences or using the website, it’s amazing how much intellectual capital is there.
We’re in a time when everyone wants a piece of your wallet, and everyone wants a piece of your time. But ultimately, I thought leadership is important. Understanding best practices and applying them globally makes sense. It’s no longer a bank in Canada competing against a bank in Canada – you’re competing against global institutions. CFA Institute is one of the few global footprints in finance that can share that intellectual capital, and you can understand what’s happening around the world.
What advice do you have for those new to the industry or to CFA Society Toronto?
The private wealth sector is among the fastest growing and most profitable
segments of the wealth market. If you are looking for a rewarding career that offers a decent living, the ability to help people and flexibility for a family, it’s a great opportunity.
From a business development perspective, I had a lot of great mentors, but one of the things that I did early on in my career was I tried to almost emulate their behaviours and their skills. What I learned over time is that you actually just want to be yourself. Be genuine. It’s not about selling, it’s about focusing on helping people solve problems. If you be yourself, you have a better chance of connecting with people.
What’s next on the horizon for you – what are you looking forward to the most?
I’m kind of in between – I have a 16-year-old and an 18-year-old – so I’m a couple years away from being what they call an empty nester, and I’m not sure how I feel about that. My youngest, next year will be his last year of hockey, and I’ve coached him every year, so I think I’ll be a little bit sad. But I’m actually very excited, because once the kids are off doing their own thing, I’ll be able to dedicate more time to doing what I do –finding clients, helping clients and continuing to grow our business. We’re looking to grow our business nationally, so that means an office out west at some point.
This interview has been edited for length and clarity.
Lauren Huneault is a content and marketing professional with 15 years of experience in content creation and strategy. Lauren has spent the last 14 years focused on producing relevant educational content to help aspiring and current business owners successfully navigate the challenges of the Canadian business landscape. She has served as writer and editor of trade publications including Your Convenience Manager, Octane and Franchise Canada.
Asset Owners’ Top Choice,
Time
& Time Again
Bring data, research, and multi-asset class analytics together in one place. Try for free.
Navigating the AI shift in finance: From productivity to transformation
By Sebastien Davies, CFA
Recent advances in large language models and agentic AI have changed how executives and boards talk about strategy. This is clear in the large sums now being invested in the technology, with global AI spending expected to reach US$2.52 trillion in 2026.
Current trends show financial services will spend the most, and taken together, finance, software, information services and retail are expected to invest over $1 trillion in 2026.
Despite the high level of corporate interest, early rollouts have revealed a significant tension between the desire for innovation and the practical constraints of the enterprise environment. Aris Kossoras, a partner at KPMG with extensive experience in finance transformation, notes, “There’s still a significant gap of understanding in most functions within financial services organizations about the different types of automation and AI and where AI can really make the difference across enterpriseto-enterprise capabilities.” This knowledge gap often manifests as fragmented execution, where individual departments deploy isolated tools that lack a shared data framework. Without a common technical foundation, these efforts remain siloed. This leads to duplicated costs and prevents the organization from generating the high-level insights required for true firm-wide transformation.
Productivity versus transformation
There’s a difference between using AI to move faster and using it to work differently. Currently, most financial institutions focus on generic AI tools, such as Copilot and ChatGPT, to optimize administrative tasks. Their applications include summarizing meeting minutes and drafting presentations.
When properly implemented, these tools can provide capacity gains of 10 to 50 per cent per employee. However, as Kossoras observes, “This is not AI that redefines how we operate. It’s more about how work is done rather than how we operate.” To achieve true transformation, firms must shift toward “domainspecific AI” that can be embedded in core financial processes to reimagine them. This often involves moving away from massive, all-encompassing models toward small language models tuned to specific datasets relevant to the firm’s unique needs.
Lesson 1: Start with use cases, not data
When Kossoras speaks with financial leadership, the same issue keeps coming up. Their data isn’t ready for AI. However, the most successful organizations do not wait for a perfect information architecture before beginning their AI journey. Instead of launching monolithic, multi-year data programs that move like “oil tankers,” these firms prioritize specific business outcomes.
They start with a handful of clearly defined use cases such as liquidity reporting, client profitability and forecasting and work backward to identify which data actually needs to be fixed. In this model, data is treated as an asset or product in its own right, rather than a process. As Kossoras explains, leading firms “do not care about whether the solution is build or buy, they are instead fixated on the outcome and work backward to define the data products required to deliver the outcome.”
Lesson 2: Prioritize high-impact applications
Rather than spreading resources thinly across dozens of minor experiments, leading firms focus on a small number of applications that can fundamentally move the dial and scale easily. These high-impact solutions often require a multidisciplinary approach, weaving together technologies such as workflow automation, machine learning and changes to how teams operate to solve a complex problem.
A concrete example of this is found in global trader surveillance. Globally significant banks use AI to analyze trillions of internal and external communications in real time, matching voice and text data against trade records to identify potential fraud. This system is sophisticated enough to identify behavioural patterns that can suggest fraudulent activity months before it is actually solidified. By focusing on core capabilities like know-your-client, fraud, balance sheet optimization, liquidity and customer experience, banks prioritize outcomes tied to risk and control over incremental improvements.
Lesson 3: The organizational constraint
The primary barrier to AI integration is rarely a lack of technical capability. In most large financial institutions, the necessary infrastructure is already in place or is at least accessible through existing cloud partnerships and enterprise licenses. The challenge is organizational: how teams are structured and how processes are designed end-to-end.
Across finance functions, digital fluency is still catching up. Kossoras emphasizes that professionals must “work internally, themselves or through their organizations, to get a little bit up the scale on their level of data literacy and digital acumen.” Even where the technology exists and data can be proxied, the constraint tends to be human: “What keeps me up at night is people, then data.”
The speedboat mandate
The evolution of AI in finance is shifting from potential to execution. While the industry has spent the last year captivated by the novelty of large language models, the next phase will be defined by those who can move past incremental productivity and into core workflows while minimizing regulatory risk. The risk of replacing human oversight with unverified model outputs remains a significant concern for boards and regulators alike. Finding the balance between the reward of automation and the necessity of compliance is where the true competitive divide will emerge.
For the modern finance professional, the greatest hurdle is often a psychological one. There is a natural self-preservation instinct at play. Many fear that embracing these tools is a move toward selfreplacement, and this tension often results in inertia that can stall even the best-funded initiatives. Kossoras suggests that the industry must look toward new models of employment where the value created by AI is shared. This could involve concepts such as licensing individual data or establishing policy frameworks to protect the workforce.
Ultimately, the mandate for the individual is to move from a defensive posture to one of active adaptation. Data will always
be a work in progress, and technology will continue to iterate at a breakneck pace, but the ability to reimagine processes and increase digital fluency is a prerequisite for the new economy. As Kossoras aptly summarizes, your biggest challenge is your people. Success will belong to the practitioners who stop waiting for the perfect data environment and start launching the speedboats of targeted, high-value use cases to pull their organizations in the right direction.
Sebastien Davies, CFA, is a partner at Primal Capital, investing in digital assets and financial infrastructure. He has a background in institutional capital markets and digital asset integration and writes about how technology is reshaping financial systems, with an emphasis on real-world application rather than theory.
Ethics in private markets
By Sanaz Danielle Fotoohi, CFA, AFM, MBA
The remarkable performance of private markets (private equity, private credit, infrastructure, real estate, venture) over the past decade spurred rapid growth and large institutional allocations.
The post pandemic surge in inflation and interest rates has since raised input costs and debt burdens for portfolio companies while reducing private equity valuations, performance, fundraising and exits. As pension funds and retail investors gain exposure to private markets, governance risks have intensified amid leverage and long-term commitments.
This article examines the ethical challenges in private markets, including conflicts of interest, valuations, illiquidity, hidden fees and asymmetric information. In such opaque markets, ethics and strong governance serve as essential substitutes for transparency. We draw on findings from Private Markets: Governance Issues Rise to the Fore by Stephen Deane, CFA, and Continuation Funds: Ethics in Private Markets, Part I by Stephen Deane and Ken Robinson, CFA, CIPM.
Incentive alignment and conflicts of interest
Conflicts between GPs and LPs
General partners’ (GPs) access to asymmetric information provides them with a bargaining
advantage over institutional limited partners (LPs).¹ Negotiations are often conducted under nondisclosure clauses. In bilateral negotiations, GPs and their outside law firms compile substantial data on limited partnership agreements (LPAs). When investors seek to share information or negotiate better terms, the GP’s counsel may accuse investors of collusion, leading the LP to limit or waive the GP’s fiduciary duties. The GP’s legal expenses are charged to the fund, meaning LPs pay for both their own and the GPs’ legal fees.
LPA contractual terms, a joint effort between the fund’s GP and LP, establish a governance framework and address potential conflicts of interest. However, they are often criticized for poorly defined, vague terms that grant GPs excessive flexibility and hinder effective LP oversight (e.g., broad characterization of fees and expenses and lack of clarity around valuation procedures, investment strategies and conflict-mitigation protocols). Therefore, large investors may negotiate privileged terms through side letters that supersede the LPA.
The limited partner advisory committee (LPAC) is another governance mechanism,
Because LPAC members owe no fiduciary duty to the fund or other investors, their involvement can create additional conflicts of interest. Strengthening LPACs requires clearer obligations, greater independence and third-party validation in highconflict situations.
composed of select LPs. The U.S. Securities and Exchange Commission (SEC) has questioned the effectiveness of LPACs, noting that they may lack independence, authority and accountability. Because LPAC members owe no fiduciary duty to the fund or other investors, their involvement can create additional conflicts of interest. Strengthening LPACs requires clearer obligations, greater independence and third-party validation in high-conflict situations.
Conflicts between the LPs that invest in private funds
Unequal access to information, costs and contract terms are defining features of private markets. Larger or more sophisticated LPs seek preferential terms such as reduced expenses, co investment opportunities, separately managed accounts (SMAs) and exclusive side deals. Co investments and SMAs often reduce or eliminate fees charged to investors in the main fund. These individually negotiated side letters and privileges create conflicts of interest among LPs.
Industry practices such as most-favourednation (MFN) status could partly mitigate the impact of exclusive side letters. While MFN status entitles investors to see the terms of investments with equal or lower capital commitments, it does not provide them with access to the terms of investments with greater capital commitments.
Conflicts between private equity and private credit funds controlled by the same parent
When a portfolio company receives investments from both private equity and private credit funds owned by the same parent sponsor, irreconcilable conflicts of interest arise in the event of financial distress. Private equity firms might pressure private credit funds to extend debt payment deadlines, amend covenant terms and show forbearance to salvage private equity investments in the company. While this may delay bankruptcy, it can destroy value for the credit fund. Mitigating conflicts between private equity and private credit funds under common ownership requires structural separation and independent decision-making, particularly in distressed scenarios.
Fees and expenses
Self-dealing and hidden fees are among the key issues in private markets, as GPs may structure expenses to the detriment of LPs and their returns. This includes fees paid to affiliates who provide services to portfolio companies. These charges are passed with limited disclosure. Because these consultants are presented as full time members of the adviser’s team, LPs often remain unaware of costs beyond the management fee and carried interest. Meanwhile, advisers gain marketing benefits by showcasing high profile operators without bearing their full costs. Other problematic practices include shifting expenses to LPs mid fund, after fundraising and terminating employees only to rehire them as consultants.
Governance measures could include hard-coded definitions and capped fees, mandatory offsets, disclosures, active LPAC oversight, standardized side letters and locked expense allocations.
Private market valuations appear smoother and less volatile (volatility laundering) than public market prices, and they are a misleading indicator of asset value.
Valuation integrity
Accuracy and timeliness of valuation and the incentives behind valuation impact the credibility, efficiency and integrity of private markets. Inconsistencies with respect to valuations could include:
• Using valuation methodologies different from those disclosed to investors
• Changing valuation methodologies to inflate struggling investments
• Cherry-picking comparable companies or precedent transactions to arrive at a target price
• Misrepresenting adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA)
• Inflated internal rates of return (IRR) using subscription financing or netasset-value loans
Valuations are typically performed internally by the fund manager, often with input from third-party valuation firms or auditors. These third parties rely heavily on GPprovided assumptions. Internal models and valuation methodologies of fund managers are not standardized, and unlike public markets, there are no liquid secondary markets for private assets to base valuations on; valuations often take place annually or quarterly. Thus, private market valuations appear smoother and less volatile (volatility laundering) than public market prices, and they are a misleading indicator of asset value.
Institutional LPs use interim valuations to measure and periodically rebalance their asset allocation. During market downturns, stale prices could misrepresent private market asset values, leading to them being under or overweight relative to public market assets (the denominator effect). This could cause pension fund allocation to deviate from target allocation, leading to erroneous rebalancing. Flawed rebalancing could lead to elevated risk levels.
Additionally, some GPs inflate fund valuations during fundraising, only to write them down after the fact. When investors use interim valuations to determine future cash flows and reinvestment needs, the quality of valuation directly impacts the operating performance of investor institutions and future returns. A compromised valuation leads to misallocated funds and higher operational costs.
Governance measures to address these concerns include independent valuation oversight through third-party reviews, enhanced disclosure of methodologies and assumptions and audit-backed validation through back-testing.
Retail access and evergreen funds
Conflicts of interest, asymmetric information, illiquidity, long investment horizons and self-serving actions pose significant risk to retail investors. Evergreen retail funds, a type of alternative mutual fund, have emerged as a major player in the secondaries markets, providing retail investors with immediate capital deployment, no capital call requirements and limited liquidity. Structural safeguards, clearer disclosures and independent oversight could mitigate risks to retail investors.
Secondary transactions and continuation funds
Demand for liquidity, coupled with the need for additional time to execute valuecreation plans, is driving the increase in adviser-led and investor-initiated secondary transactions. GP-led secondary offerings such as continuation vehicles acquire legacy fund assets and transfer them into portfolios managed by the same GP. This allows GPs to extend holding periods and seek higher future exit values. Such secondary transactions not only provide liquidity to LPs who do not roll over their positions, but also benefit legacy investors who invest in the new fund. Investors in secondaries face the risk of asymmetrical information, adverse selection and heightened conflicts of interest for GPs and LPs.
Regulation
In August 2023, the SEC adopted a series of new rules with respect to adviser conduct focused on the required disclosures and
investor consent requirements. The new rules require private fund advisers to provide quarterly statements that include information about the private fund’s performance, fees and expenses; obtain an annual financial statement independent audit for each private fund; and obtain a fairness or valuation opinion in connection with an adviserled secondary transaction. Under these regulations, advisers can offer preferential rights to investors only if they disclose the terms in writing to current and prospective investors. These disclosures include material economic terms, liquidity rights, fee breaks and co-investment rights. Any regulatory, examination or compliance fees and expenses can be allocated to the private fund only if disclosed to investors. The regulation of private equity markets by the SEC has not established standardization across valuation methodologies.
Governance at the forefront
Private markets create distinct ethical risks: conflicts of interest, limited transparency, illiquidity, longer lockups, valuation discretion, suitability and sponsor relationships. Ethics can serve as a substitute for transparency in markets where discipline is weaker. The ethical principles are embedded in sound governance practices, compliance oversight and clear disclosures. The successful implementation of ethical conduct through strong governance is foundational for investor trust and long-term industry credibility.
Sanaz Danielle Fotoohi, CFA, AFM, MBA, is a volunteer member of CFA Society Toronto’s Strategic Content Committee and Editorial Committee and a contributor to The Analyst
Dancing to a new tune Jon Erlichman’s transition from traditional to social media aims to increase financial literacy among all
generations
(Editor’s Note: This article is based on Season 1, Episode 5 (featuring Jon Erlichman) of Diverse Dividends, CFA Society Toronto’s video podcast series.)
With more than 20 years of experience in traditional media at BNN Bloomberg, you may have seen Jon Erlichman discussing financial literacy on your television screen.
However, with his recent shift to social media, including a strong presence on X (formerly Twitter) and his new YouTube channel, Ticker Take, it’s perhaps even more likely you’ve come across his face (or dance moves) while scrolling on your phone.
Erlichman likens the current growth in social media knowledge-sharing to the expansion of cable TV networks in the 2000s, when BNN launched as a channel and he was starting out in the industry.
“There’s a lot of parallels between today and then, because the fact is, more people are interested in investing than ever before,” says Erlichman. “The idea of investing is reaching a wider audience, but a good chunk of that audience is increasingly learning and communicating from their device, from their phone.”
Strutting his stuff
While Erlichman is still a contributor to BNN, his new focus on social media means he can channel his passion in a new way.
“I have really strong conviction around financial literacy, and it’s my hope to have an advocacy role for it as well, because it’s all around us,” explains Erlichman. “Money matters to everyone, and the ability for more people to understand the markets and learn from the markets and make better decisions, it’s a really exciting thing.”
Since making the leap, he’s been pushing the envelope and exploring new ways to bring this valuable content to life.
“I guess one of the reasons I like to do things that are a little bit unique – awkward
dancing and all that stuff – is just because I believe that, as a content category, that financial literacy and money matters and investing can go way beyond what it is today. So, I’m really energized by the idea of trying to reach people in slightly new ways, but playing off of content themes that hopefully are interesting and maybe even entertaining to some people,” he explains, noting that it also helps him to reach the younger generations, who are looking to digest investment knowledge in different ways.
A storyteller at heart
For Erlichman, it all comes down to the content and finding the best ways to tell captivating stories. “Beyond just business or finance, I really love the idea of communicating with people through story,” he says.
I have really strong conviction around financial literacy, and it’s my hope to have an advocacy role for it as well, because it’s all around us.
If you watch Erlichman’s YouTube videos or engage with his social media posts, you can’t help but notice the passion and energy that he brings to sharing content. So where does that energy come from?
“I get most energized by my family. I have two daughters – they’re pre-teen/teen ages. They’re really exciting, just in terms of being that next generation. I learn so much from them just in their own habits,” he says. “But I do love making content, I really do. It’s really the thing that drives me more. It’s not about the money; it’s the ability for people to learn about money matters that really matters to me.”
Charting a route for others
As Erlichman works to build a new, deeply engaged audience (Ticker Take already had a quarter of a billion impressions worldwide after just three months), one thing will always stay true: his passion and conviction for getting financial literacy information to those who need it.
“I really have gotten the most value in my career out of people just having the opportunity to learn through me, not necessarily from me. That absolutely would be the legacy that I would want to leave – it’s my passion, it’s my driving force for doing this, and hopefully the internet will let me keep doing it,” says Erlichman with a laugh.
He also recognizes the importance of the CFA community in fulfilling this education mission. “With respect to CFA Societies, whether it’s here or around the world, I cannot express how valuable having that ecosystem has been. Also, just the fact that it keeps the conversation around investing going in any city, really, in the world. And that’s very parallel to what I’m trying to do.”
Top tips for success
As Erlichman continues to find new ways to engage audiences through content, he shares the following advice for anyone looking to find success and fulfillment through their own path.
1. Understand your purpose: “Go for whatever it is you know you’ve been put on this earth to do. It’s really important to go after what you’re passionate about. And if you want to achieve success in doing that, you do have to not just go after it, but just keep going and not worry about what other people are saying or what you might think they’re saying.”
2. Listen to what others are saying: “I always found the best thing that I could do is not to talk, but to listen. You hear a lot of successful people talk about how they are good listeners – they’re not just trying to speak when the opportunity presents itself, they’re trying to listen and learn.”
3. Have the confidence to take chances: “Having the confidence in yourself is really important because sometimes people put a lot of big things in front of you, and from afar it might look like something that would be overwhelming. But you’ve got it, right?”
Lauren Huneault is a content and marketing professional with 15 years of experience in content creation and strategy. Lauren has spent the last 14 years focused on producing relevant educational content to help aspiring and current business owners successfully navigate the challenges of the Canadian business landscape. She has served as writer and editor of trade publications including Your Convenience Manager, Octane and Franchise Canada
Diverse Dividends is CFA Society Toronto’s new video podcast series from The Analyst, which aims to explore the rich mosaic of the finance and investment industry. Each month, Diverse Dividends features candid, indepth interviews with industry leaders across the finance and investment world as they share their insights on mindsets, strategies, and lessons that drive their success.
Why listen?
• Actionable insights: Gain concrete ideas to boost resilience, leadership, and innovation.
• Unfiltered dialogue: Learn how industry pioneers navigated setbacks and seized opportunity.
• Community connection: Join fellow members in thoughtful discussions that spark inclusive change.
Where to find us
Listen during your commute, enjoy it at home for a deep-dive session, or watch Diverse Dividends for a richer, more immersive experience. Join our growing community and take away actionable ideas that can transform both your mindset and your bottom line.
• Podcast apps: Subscribe on Apple Podcasts, Spotify, SoundCloud, or YouTube
• Online: Stream full episodes at cfatoronto.ca
Don’t miss a single episode! Tune in to Diverse Dividends wherever and however you love to listen and reap the dividends of diverse experience!
Canadian IPO market challenges
By Lauretta Chame, CFA
An initial public offering (IPO) is not just a company’s financial milestone. It is also an important barometer of broader market confidence, revealing how capital is allocated, how risk is priced and how an economy enables scaling.
This article examines the state of Canada’s IPO market and draws key insights from Europe and the U.S.
Strong foundations, untapped IPO potential
Canada’s IPO market has declined since its peak in 2021, mirroring a global slowdown as rising interest rates and inflation weighed on equity markets. However, while other major regions have begun to recover, IPO activity on the Toronto Stock Exchange has remained subdued, with only two IPOs and 55 delistings in 2025. This divergence points to domestic economic, structural and regulatory factors.
Economic factors
• Availability and cost of capital
With investor appetite concentrated in large caps, smaller firms face higher financing costs and lower valuations, reducing incentives to go public. This is amplified by the rise of U.S.-weighted exchange-traded funds, reducing domestic capital availability. As Steve Arpin, CFA, MA, managing director, head of Canadian equities at Beutel Goodman, emphasizes, cost and access to capital are the primary determinants in the decision to go public over alternative financing routes, because executives ultimately seek to maximize enterprise value.
Source: Author, using Market Intelligence Group archives on TSX activity
Figure 1. TSX IPO activity: Post-2021 collapse without rebound
• Low R&D intensity
On the supply side, Canada’s relatively low R&D intensity (research and development expenditure at 1.79 per cent of GDP versus 2.26 per cent in the European Union and 3.45 per cent in the U.S) limits companies’ ability to scale, narrowing the IPO pipeline.
Structural and regulatory factors
• Canada’s public markets remain heavily concentrated in non-technology sectors such as energy and materials, especially among small caps. This reduces exposure to technology, a sector that typically drives IPO activity and which accounted for the second-largest share of global IPO proceeds in 2025.
• Existing tax measures offer limited incentives for risk-taking. On the investor side, partial capital loss deductibility tempers small - cap appetite. For issuers, while recent reforms to Canada’s Scientific Research and Experimental Development tax incentives allow companies going public to retain the full enhanced credit, the program remains constrained, with 82 per cent of firms calling for a broader coverage of eligible activities.
Together, these conditions create a thin pipeline of companies reaching scale and a narrow demand for smaller listings.
Meanwhile, private markets and mergers and acquisitions offer viable alternatives, leading to a trend in which “many Canadian technology companies that came public were subsequently acquired by competitors or private equity funds, often delivering reasonable outcomes for shareholders but removing the companies from being publicly traded,” according to Arpin.
Canada’s resource case
In 2025, Canada attracted its highest level of foreign direct investment since 2007, underscoring strong international interest. However, most inflows were through acquisitions, limiting their contribution to IPO activity. This is particularly relevant as global demand for energy and critical minerals rises, areas where Canada holds a strategic advantage.
The table below examines the reasons behind Canada’s difficulty in converting its advantages into IPO opportunities. See Figure 2.
Although policymakers have outlined priorities to address these constraints, meaningful outcomes will take time to materialize. This raises the question of how other jurisdictions sustain higher IPO activity.
Europe and the Swedish exception
Europe’s IPO activity has been more dynamic than Canada’s, but more volatile than the U.S.’s, highlighting both its strengths and challenges.
As the world’s largest single market, Europe offers access to 440 million consumers and a diversified sector base spanning industrials, health care, financials and luxury. This broadens the pool of potential issuers and investors relative to Canada’s more concentrated market.
Yet, the region faces obstacles that weigh on IPO activity, notably its 27 fragmented regulatory regimes, which increase compliance costs and complicate cross-border listings, pushing issuers to list elsewhere. A cultural preference for real estate over equities also limits household participation.
Sweden, however, stands out as a notable outlier.
Figure 2. Foreign direct investment headwinds in Canada’s mining and energy sectors.
Sector Key issues
• 10–15 years permitting timeline
Mining
Energy
• Limited longer term pipeline capacity
• Slow liquefied natural gas development
• Policy uncertainty on decarbonization
Source: Created by author based on interview with Arpin
Effects on attractiveness of foreign direct investment
Despite being home to 40 per cent of the world’s public mining companies:
• Slow project development
• Capital preference for faster jurisdictions
• Restricted access to global markets
• Discounted pricing
• Constrained resource development
When policies and resilience shape market behaviour: Sweden’s case
Over the past decade, Sweden has hosted more IPOs than France, Germany, the Netherlands and Spain combined, propelling Stockholm past London as Europe’s busiest equity market and into the top global listing venues. In 2025, Sweden’s Verisure became the world’s second-largest IPO and the only European in the global top five.
Sweden’s success reflects a combination of long-lasting policy effects and resilience.
• Enduring effects of past policies
A 1980s tax incentive laid the foundation for an equity-savings culture. Johan Flintull, global co -head of investment banking at DNB Carnegie (the leading investment bank in the Nordics region), highlights that “there is almost always a local bid for IPOs.” Today, over 85 per cent of Swedes hold equities, directly or indirectly, largely via tax efficient accounts (approximately 1 per cent annual levy, no capital gain or dividend tax).
A decade later, a reform enabling tax-free computer purchases helped create a tech-literate population. Sweden has since produced over 40 unicorns (companies worth more than US $1 billion), the highest per capita in Europe.
• Global ambition by necessity
For Flintull, Sweden’s small domestic market motivates startups to think globally from the outset, accelerating growth and IPO readiness as firms expand. Evolution Gaming illustrates this trajectory: founded in Stockholm, it expanded abroad before listing locally.
Nevertheless, Sweden also faces U.S. competition for capital. Flintull notes that the primary risk is the rise of indexation, which is redirecting a growing share of Swedes’ savings into global index funds, heavily weighted toward U.S. equities. Talent retention also remains a challenge, although improving, with more role models choosing to stay in Sweden.
Sweden offers two key insights for Canada:
• First, sufficiently attractive tax incentives can structurally shape investor behaviour by reducing risk aversion and supporting IPO activity.
• Second, a large domestic market is not a prerequisite for a strong IPO ecosystem: despite a population of about 10 million, Sweden is becoming Europe’s leading IPO venue.
In 2025, Canada attracted its highest level of foreign direct investment since 2007, underscoring strong international interest.
The U.S.: Global centre of IPO activity
In 2025, the U.S reaffirmed its position as the world’s dominant IPO market, delivering its strongest year since 2021. A rebound driven by the technology sector, with U.S. listings representing 42 per cent of global tech IPO proceeds. This performance reflects a culture of risk-taking, where companies are built to scale from inception, reinforced by a robust venture capital and private equity ecosystem, preparing them to go public.
Canada’s IPO market has declined since its peak in 2021, mirroring a global
slowdown as rising interest rates and inflation weighed on equity markets.
Once public, firms may also benefit from the unique strengths of the U.S. market: deep liquidity, strong analyst coverage, global visibility, a unified regulatory framework and abundant capital. These conditions support faster growth and higher valuations, making them core constituents of major global indices and attracting continuous passive inflows from international investors.
This combination of capital availability, visibility and favourable valuation gives U.S. companies a powerful acquisition currency, enabling them to acquire competitors globally. The example of Slack, originally founded in Vancouver and later acquired by
TD ETF Portfolios
Salesforce, demonstrates how companies are absorbed into the U.S. ecosystem before reaching full scale.
Overall, these advantages attract foreign issuers. However, listing in the U.S. does not guarantee success. Arpin warns that a U.S. listing only makes sense if it delivers stronger valuations or if the company resonates with U.S. investors; otherwise, it can prove costly. Therefore, a strong understanding of the local investor base and clear positioning are essential.
Conclusion
Canada’s culture of prudence is a strength that has underpinned one of the world’s most stable banking systems and established its reputation as a trusted international partner, particularly with the European Union.
However, evidence from the U.S. and Sweden suggests that calculated risk-taking is a key ingredient in vibrant IPO markets, one that Canada may need to further incorporate to unlock constraints rooted in R&D intensity, valuations, cost of capital and scalability. Targeted policy tools, like in Sweden’s experience, could support this shift without compromising the country’s prudential framework.
Lauretta Chame, CFA, is a volunteer with CFA Society Toronto’s Institutional Asset Management Committee.
CFA Societies Canada Quarterly Update
What’s new with advocacy at CFA Societies Canada?
Advancing investor protection, industry professionalism and market integrity across Canada, CFA Societies Canada focuses attention on pressing advocacy files dominating the regulatory agenda. Ensuring fair, equitable and sustainable outcomes for stakeholders is more important than ever. Through our growing relationships with policymakers and regulators, we are working on several important initiatives. Below is a summary of two areas where we have recently provided comment letters. To see the comprehensive catalogue of our commentary letters, visit us online at cfacanada.org/advocacy.
Published CFA Societies Canada comment letters
Ontario Ministry of Finance – CFA Societies Canada co-signs letter with PMAC urging Ontario to join CSA Passport System
CFA Societies Canada and the Portfolio Management Association of Canada (PMAC) have co-signed a letter to Ontario Finance Minister Peter Bethlenfalvy urging the province to join the Canadian Securities Administrators’ (CSA) Passport System. The letter argues that Ontario’s participation would reduce duplicative regulatory reviews, lower compliance costs, improve access to capital across provinces and support a more integrated and competitive Canadian economy.
As the only province not participating in the Passport System, Ontario creates added complexity for firms seeking to operate nationally. The letter notes that joining the system would align with current provincial and federal priorities to reduce interprovincial trade barriers, enhance labour and capital mobility and strengthen productivity and economic growth across Canada.
Who is CFA Societies Canada?
CSA – Proposed Liquidity Risk Management Amendments to NI-81-102
The letter outlined the CAC’s response to the CSA’s proposed liquidity risk management reforms for investment funds. The CAC supported the overall direction of the consultation, especially the move to formalize liquidity risk rules and broaden the available liquidity management tools, but argued that the proposed governance model places too much responsibility on compliance rather than on an independent risk function. It also urged improvements to liquidity classification, disclosure, regulatory reporting and coordination on broader macroprudential risks.
Key highlights from the CAC’s submission include that the CAC:
• Supported the CSA’s effort to strengthen liquidity risk management rules, but said oversight should have rested with an independent risk function, ideally led by a chief risk officer reporting to the board or senior leadership.
CFA Societies Canada represents the 12 Canadian CFA Institute Member Societies and, ultimately, Canadian CFA charterholders. CFA Societies Canada’s Canadian Advocacy Council includes investment professionals from across the country who review regulatory, legislative, and standard-setting developments affecting investors, investment professionals, and Canadian capital markets. CFA Societies Canada through its advocacy efforts strives to advance market integrity, transparency, and investor protection, and actively engages Canada’s securities regulators, self-regulatory organizations, industry associations, legislators, and other stakeholders through thoughtful leadership, direct engagement, and the publication of comment letters.
• Supported expanding the liquidity management toolset and making the three existing tools a mandatory minimum baseline, while encouraging broader use of additional price-based and quantity-based tools.
• Accepted the four-category liquidity classification framework only as a baseline, and said it should have incorporated price impact, position size and stressed-market conditions.
• Opposed investor-facing liquidity profile charts in the current form, but supported stronger standardized liquidity management tool disclosure and confidential, technology-enabled regulatory reporting.
• Took the position that the framework should have applied broadly across reporting and non-reporting funds and should have been considered within a wider macroprudential context.
Have your say
If you would like to participate in advocacy activity related to these letters or future policy and regulatory initiatives, provide comments on ongoing initiatives, or learn more about volunteer opportunities in advocacy, please contact info@cfacanada.org.
Follow CFA Societies Canada on LinkedIn.
The human edge in finance: Judgment, ethics and the responsibility of the modeler
Ian Schnoor, CFA
Financial models sit at the centre of decision-making in finance. They inform investments, shape strategy and guide critical business outcomes. But models do not make decisions. People do.
As artificial intelligence becomes more embedded in financial workflows, the mechanics of modeling are changing quickly. Tasks that once required hours can now be completed in minutes. Models can be generated, populated and updated with increasing speed.
What is not changing is the responsibility that comes with using them.
At some point in every finance professional’s career, the work stops being theoretical. You are no longer building a model for practice or analysis. You are building something that will inform a real decision:
A transaction. An investment. A recommendation.
In that moment, the question is not just whether the model works. It is whether you are prepared to stand behind it.
Judgment: More than a technical skill
Every financial model is shaped by a series of choices.
What assumptions should be used?
Which drivers matter most? How should uncertainty be reflected?
These are not mechanical decisions. They require judgment.
Two professionals can build technically sound models and arrive at very different conclusions, simply because they approached the assumptions differently. One may take a conservative view; another may be more optimistic. One may test downside scenarios rigorously; another may not.
The difference is not technical ability; it is the quality of thinking behind the model.
As AI tools become better at generating models, this distinction becomes more important. Less time may be spent building formulas. More time must be spent asking:
Do the assumptions make sense? Are the relationships realistic? What could go wrong?
The question is no longer just, “Can I build this model?” It becomes, “Do I trust it?”
Ethics: The responsibility behind the numbers
Financial models influence real decisions. With that influence comes responsibility.
Finance professionals often work in high-
pressure environments. Deadlines are tight, and expectations are high. In some cases, there may be an implicit desire for the model to support a particular outcome.
This is where ethics matters.
An ethical professional does not use a model to justify a decision that has already been made. They use it to inform the decision.
That means:
• Being transparent about assumptions
• Clearly communicating risks and limitations
• Avoiding unnecessary complexity that obscures understanding
• Taking ownership of the output, regardless of how it was generated
The growing use of AI in modeling increases this responsibility. If a model is partially generated by a tool, the professional must still stand behind it.
Your client will still ask why. Your team will still expect you to explain every number.
“The model built itself” is not an answer.
Technology does not reduce accountability. It reinforces it.
Influence: From analysis to action
A financial model, on its own, does not drive action. Its impact depends on how it is used.
The professionals who have the greatest impact are not just those who can build models. They are those who can interpret them and communicate what matters.
They can:
• Translate outputs into clear insights
• Explain key drivers and sensitivities
• Frame trade-offs and scenarios
• Guide discussions toward informed decisions
In many teams, the person who understands the model best becomes the person others turn to. Not simply because they built it, but because they can explain it.
This is where influence is built.
The human edge
AI will continue to change how financial models are built. It will accelerate technical work and make modeling more accessible.
AI will not replace judgment, it will not replace ethics and it will not replace the ability to communicate and influence decisions.
In fact, it will increase their importance.
As more of the technical work becomes automated, the differentiator will not be who can build the model the fastest. It will be those who can think clearly, act with integrity and communicate with confidence.
That is the human edge.
Financial Modeling Institute and CFA Society Toronto
Conclusion
Financial modeling has always been more than a technical exercise. It is a discipline that combines analysis, judgment and communication.
In an AI-enabled environment, these human capabilities will define strong finance professionals and effective leaders.
The model may be built in Excel or with AI support, but its value will always depend on the person behind it.
Ian Schnoor, CFA, CFM is Executive Director at the Financial Modeling Institute.
Financial Modeling Institute is committed to preparing professionals for this evolving landscape supporting the next generation of finance leaders. The Advanced Financial Modeler (AFM) accreditation focuses on best practices to build world-class models that can be used as critical decision-making tools.
Our partnership with CFA Society Toronto reflects a shared mission to equip finance professionals with the technical, strategic and adaptive skills needed for the future. As the creators of the Financial Modeling Practical Skills Module for the CFA Programs, we look to ensure that professionals stay ahead.
About FMI
Financial Modeling Institute (FMI) promotes excellence and discipline in financial modeling through rigorous accreditation programs and thought leadership.
The Advanced Financial Modeler (AFM) accreditation is the only exam that requires candidates to build a three-statement financial model of a company from scratch under time pressure, demonstrating their ability to translate data into actionable insights.
For CFA Society Toronto members, the AFM offers an accreditation that supports your professional credibility wherever your career takes you.