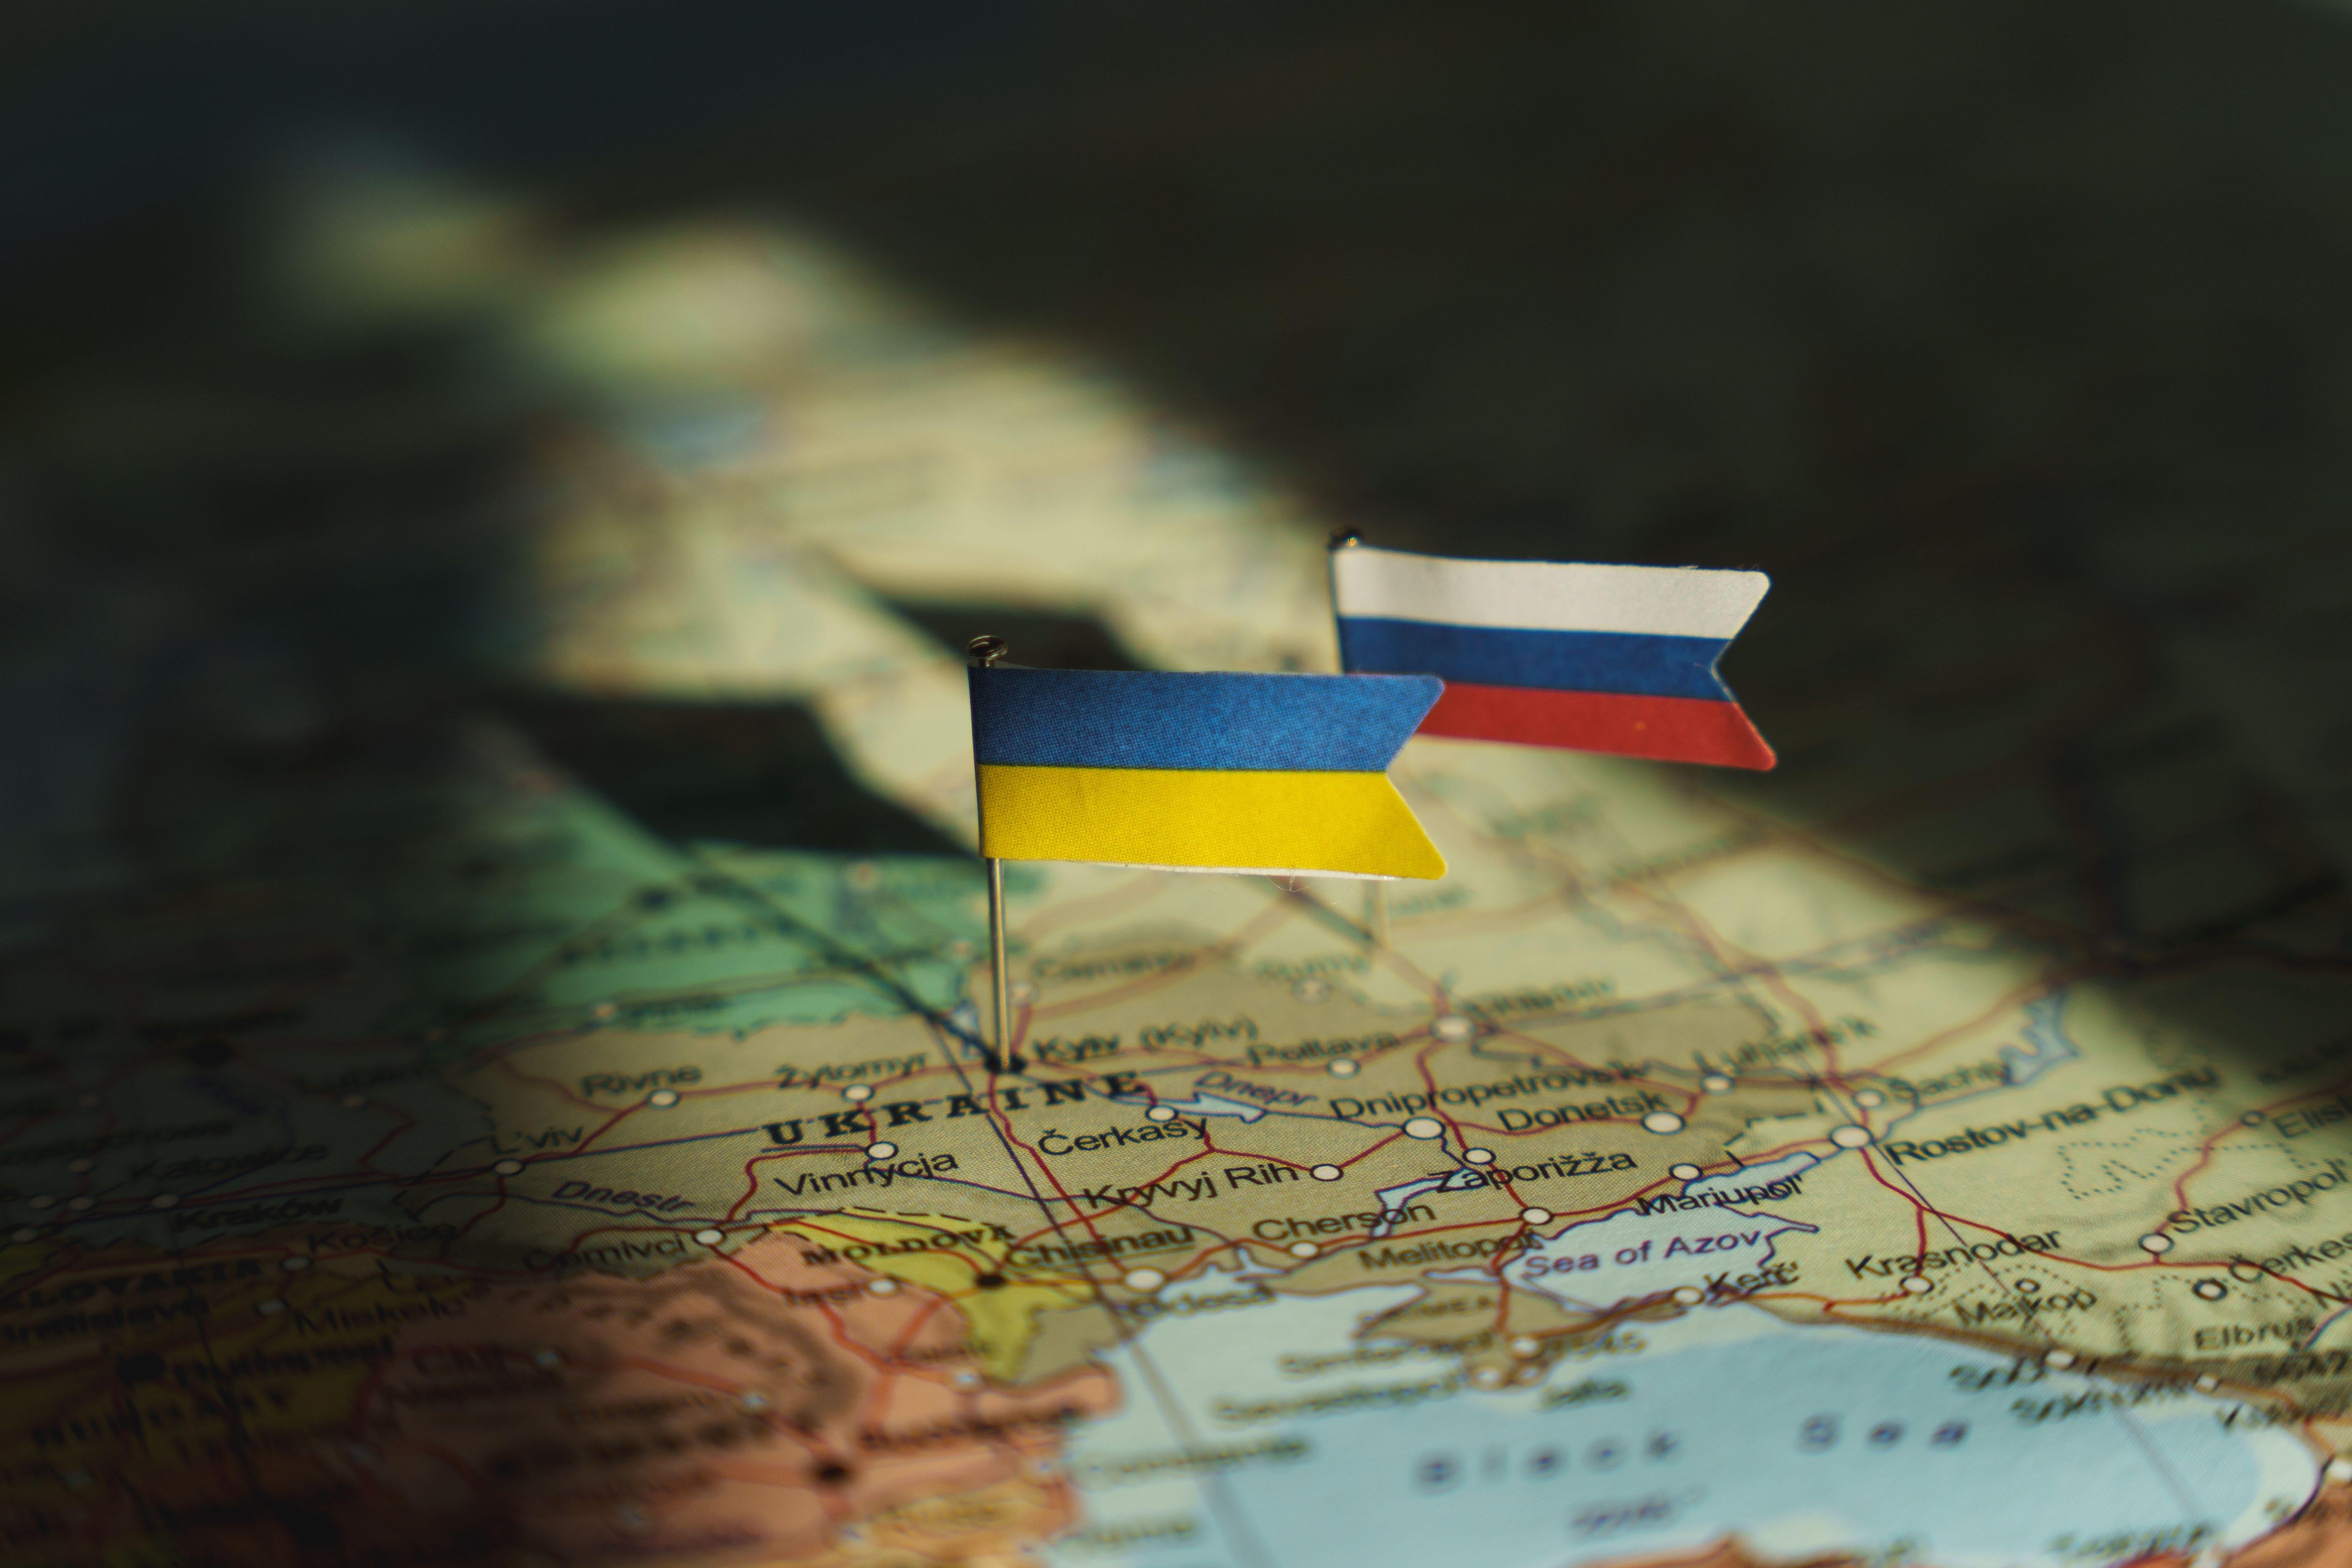
Russia’s full-scale invasion of Ukraine began on 24 February 2022 and has now continued for more than four years, involving missile strikes, drone attacks, occupation, counter-offensives, and large-scale civilian displacement. Whilst Russia’s original objective of seizing the country as a whole proved completely unrealistic, the majority of the Donbas region remains under Russian control, while fighting remains intense along the eastern and southern fronts, with periodic strikes across the country.1 By comparison, the Gulf states became involved in the 2026 Gulf conflict when Iranian forces and proxies escalated attacks across the region, including missile and drone strikes on UAE territory and continued disruptions in the Strait of Hormuz. The UAE responded through coordinated defence measures with allies, maintaining internal stability while operating under heightened regional military tension.2
What have been the effects of both conflicts on the countries’ respective housing markets? And since the war in Ukraine has continued for several years, are there lessons to learn about how short and long-term effects compare?
In the first months after Russia’s full scale invasion in February 2022, Ukraine’s housing market split into very different regional markets. Combat zones in the north, east and south-east saw immediate collapse: millions fled these regions, and vast numbers of buildings were damaged or destroyed as fighting intensified. Estimates for 2022 suggest up to 800,000 residential buildings were damaged or destroyed in that year alone, with cities such as Severodonetsk and Bakhmut left with virtually no intact structures.3 But although residential transactions across the country fell from approximately 320,000 in 2021 to around 100,700 in 2022 – a decline of nearly 70%,4 Kyiv experienced a temporary exodus during the assault on the capital, followed by a rapid return once Russian forces were forced to withdraw from the north. This produced a rebound in residential real estate demand and pressure on remaining undamaged stock. Further west, especially in Lviv and surrounding regions, internal migration drove a surge in demand. Hundreds of thousands of displaced people sought temporary accommodation, pushing up rents and increasing interest in secondary market purchases.5 Early estimates suggested that even by March 2022, western cities were already seeing rising demand and modest price increases for smaller units. The result was a housing market split between devastation in the east, disruption and recovery in Kyiv, and unexpected buoyancy in the west. As the war moved beyond its initial shock phase, Ukraine’s housing market defied expectations that it would collapse; instead, alongside the country as a whole, it reorganised itself geographically, responding to shifting front lines, internal migration, and the uneven distribution of destruction. The early pattern of devastated East, disrupted Centre, and buoyant West persisted, but the dynamics within each region evolved subsequently in distinct ways.
By late 2022, the east had settled into a difficult balance. Cities such as Sloviansk and Kramatorsk, repeatedly targeted and within artillery range, saw sale prices fall to negligible levels. Nominal
housing price growth slowed to just 1.8% in 2022, while real growth adjusted for inflation fell to –19.6%.6 Yet rents in certain areas moved in the opposite direction. Limited supply, high military wages, and the constant rotation of troops created a market where landlords could charge very high rents for even basic accommodation. Kyiv, by contrast, experienced a pattern of disruption followed by rapid recovery. After the failed Russian assault on the capital, residents, institutions, and foreign missions returned, creating renewed pressure on the rental market. Despite the disruption, relatively safer central regions showed early signs of stabilisation, supported by returning residents and continued institutional activity, so even by 2023, demand for secure, well-located units surged. Properties with bomb shelters, reinforced basements, or underground parking became premium assets and often sold very quickly, sometimes even within hours. Kyiv’s market became defined not by flight but by selective resilience: people returned, but with new preferences shaped by missile strikes and blackouts.7 Meanwhile, the west continued to absorb internal migration. Lviv, in particular, became the country’s most expensive major market. Western cities such as Lviv and Ivano Frankivsk experienced relatively stable demand, driven largely by internally displaced persons seeking housing, such that by 2023, average prices had already risen to $1,720 per square metre, 64% higher than at the start of the war and even exceeding Kyiv’s levels, driven not only by displaced households but also by businesses relocating from the east, NGOs establishing regional bases, and returning expatriates seeking perceived safety. Western cities became the main safe-haven markets, with strong demand for smaller, ready-to-occupy units and a near-total shift away from off-plan purchases.8
By 2023–2024, a new trend emerged: eastward return migration. As front lines stabilised and Ukrainian counter-offensives regained territory, many who had fled west began returning to their home cities. This produced unexpected hotspots. Kharkiv, only 30km from the front line and heavily damaged, became an attractive investment location. One-bedroom flats that had once cost five times the average annual wage now cost three and a half, drawing buyers willing to bet on long-term recovery and future compensation schemes. Nationally, by 2023, residential transactions had recovered to approximately 172,600, rising further to 178,500 in 2024. Construction costs remained 10–30% above pre-war levels, shifting demand toward end users rather than speculative investors.9 This increase did not, however, prevent a remarkable increase in residential construction: 79,200 units were completed between January to September 2024, up almost a quarter from the previous year. Nationally, Ukraine was now building housing at a far faster rate than it was losing it, although construction was predictably increasingly focused in the West.10
Across 2024 and 2025, the market’s segmentation deepened. The east remained a zone of depressed sale prices but high, volatile rents. The centre, especially Kyiv and Dnipro, stabilised around a new security-driven logic: lower floors, reinforced structures, distance from military targets, and access to shelters became key determinants of value. The west remained structurally tight, with elevated rents and prices supported by persistent internal migration and business relocation. By 2026, Ukraine’s housing market had unmistakably evolved into a three-tier system that had taken on the appearance at least of permanence: Three trends are evident.
First, the obvious geography of risk: proximity to the front line remains the single strongest predictor of price declines or stability.
Second, internal migration. Movements westward in 2022 and partial returns eastward from 2023 onward reshaped demand.
Thirdly, security-driven preferences: across the country, buyers and renters now prioritise safety features over aesthetics or speculative potential.
The conflict in the Gulf this year placed the UAE under its most serious regional security pressure in decades. Although the country was never threatened with invasion, it has faced a series of missile and drone threats within a wider confrontation involving Iran and its regional proxies. The immediate effect was a brief expatriate outflow, mainly among risk-averse households and internationally mobile professionals. This mirrored earlier episodes of regional tension: those with the least attachment to the UAE were the first to leave. However, the outflow stabilised quickly. The UAE’s air-defence systems exceeded expectations, attempted strikes were intercepted, and government and private sector operations continued without interruption.11 Within weeks, the UAE had won a new reputation, for operational continuity under pressure. Housing markets that withstand such trials have traditionally performed well when the pressure relents, as Kyiv demonstrates.
The UAE housing market has so far responded through internal reallocation rather than external inflows. The vast majority of residents remained; demand concentrated in central Dubai and Abu Dhabi, while older stock and peripheral emirates have seen what may well prove only temporary softening. Corporate tenants, rather than relocating to the UAE, focused on continuity planning and short-term lease flexibility. The UAE’s experience therefore diverges sharply from Ukraine’s: no widespread destruction, no internal displacement, no migration surge – but a temporary expatriate contraction followed by rapid stabilisation and a shift in preferences within the existing population.
In housing market terms, the UAE in 2026 most closely resembles Kyiv in 2022–23: a national centre under threat, experiencing disruption but not displacement, and stabilising rapidly once the immediate danger passed. The comparison is especially acute given that both cities were approaching the peak of a conventional housing cycle.12 13If Kyiv’s experience thereafter is a guide to the future, the UAE’s housing market in 2026 is likely to follow the pattern of a national centre under threat: a short period of disruption, a temporary outward movement among the most mobile residents, and then rapid stabilisation as confidence returns. Kyiv did not collapse under missile fire; it reorganised. Demand shifted inward, not outward. Secure, central, well-built stock became the focus of the market, while the city’s role as the country’s administrative and economic core ensured a swift return of population and
activity once the immediate danger passed. The UAE’s position in the Gulf system is structurally similar: a political and economic centre that absorbs shocks, rather than dispersing them, and whose housing market responds through reallocation within the system, not flight from it. Unlike Ukraine, where government-backed mortgage programmes such as ‘eOselya’ supported displaced households,14 the UAE’s response was market-driven, almost entirely by existing residents moving home within the jurisdiction.
There are obvious differences. Ukraine is a sovereign state fighting a desperate and prolonged land war; the UAE is a wealthy, globally connected hub facing regional missile and drone threats. Kyiv’s stabilisation was supported by internal migration from the east; the UAE has no equivalent inflow. Ukraine’s economy does not depend on foreign direct investment; by comparison the UAE as a whole is now one of the world’s top destinations for foreign direct investment, although FDI dependence in the UAE is highly uneven: Dubai is structurally the most FDI-driven emirate, attracting the overwhelming majority of new projects and capital inflows, while Abu Dhabi relies far more on state-owned and sovereign-wealth investment and the northern Emirates a only marginal share.15 Kyiv’s recovery was driven by returning citizens; the UAE’s population is overwhelmingly expatriate and therefore more mobile, more reversible, and in some cases more sensitive to perceived risk. All of this is true. But none of it breaks the underlying parallel, because the right comparison is not between the conflicts themselves – it is about the behaviour of central cities under threat. In both cases, within the city itself price levels have been maintained; all that has been observable have been trends towards more secure buildings that can absorb shocks. And in the case of Kyiv, the centre’s political and economic gravity ensured that once the immediate danger passes, activity returned quickly and decisively. The parallel holds because the mechanism is the same, even if the circumstances differ. Kyiv shows how a central city behaves when threatened by an enemy that quickly proved unable to achieve its original objectives, yet retained the capacity to inflict serious damage on civilian infrastructure. The UAE has now confronted a similar dynamic, albeit on a very different scale.
There is one other parallel that is undoubtedly worth drawing, and that is to the pandemic, which also curtailed UAE residential property demand. The UAE’s residential market recovered from Covid much faster than expected, with Dubai leading the rebound. Even by early 2021, residential transactions volumes and prices were already increasing.16 As movement restrictions eased, capital values began rising again, the recovery accelerating into 2022: Property Monitor reported that Dubai ended the year with 11% annual price growth, the second highest sales volume on record, with prices rapidly returning to pre-pandemic levels.17 Demand shifted decisively toward ready units and villas, supported by the UAE’s rapid vaccination rollout, business friendly reforms, and long-term residency initiatives, all of which helped restore confidence and attract both end users and global investors. This trajectory does not prove that the end of the conflict will see a similar recovery in UAE residential markets, especially as they were at the peak of a conventional real estate cycle immediately before the conflict escalated – but it does clearly demonstrate the inherent capacity of the market to rebound after even as serious and prolonged a crisis as the pandemic.
The war in Ukraine and the current Gulf conflict are no doubt several orders of magnitude different in terms of their impact on the respective countries. Ukraine is engaged in a prolonged, existential struggle for survival against a longstanding adversary. The war has seen extensive destruction of housing and infrastructure, and reshaped internal migration, rents, prices, and investment behaviour. Yet by 2026, it is evident that Ukraine’s housing market is not merely surviving; it is adapting, often in counter-intuitive ways. It remains fragmented, mobile, and deeply shaped by the geography of war – a market functioning under extraordinary pressure, yet one still functioning effectively in most parts of the country.
By contrast, the UAE has been drawn into a conflict not directly of its own making but where its geopolitical interest in peace, economic development and freedom of commercial shipping has required it to take a principled stand. Yet because the Ukraine war has divided the country into three very different housing markets, it is possible to identify within Ukraine the Kyiv market as the closest parallel to the UAE. Its resilience has now been demonstrated over almost half a decade. Given its own proven resilience, the UAE housing market is likely to follow suit in any prolonged conflict.
Disclaimer:
644 5089