H1 2026

H1 2026
Dubai’s office market recorded approximately 2,600 sales transactions during H1 2026, up 38.2% year-on-year, with total sales value reaching AED 15.8 billion, representing a 199.3% increase compared with H1 2025. The increase in transaction value was primarily driven by a higher number of high-value office transactions, with more than 220 office sales above AED 20 million recorded during the period.
The market composition continued to shift towards the off-plan segment, which accounted for 64.8% of total office sales during H1 2026. This shift was supported by newly launched commercial developments, which supported transaction volumes during the period. However, market momentum moderated during Q2 2026, with transaction activity slowing, particularly within the ready segment, as regional geopolitical uncertainty contributed to a more cautious buyer environment.
Office sales prices reached AED 2,012 per sq. ft. in H1 2026, while average rental rates reached AED 189 per sq. ft. per annum, recording year-on-year growth of 15.1% and 14.1%, respectively. However, both measures recorded slight quarterly moderation in Q2 2026, reflecting softer market conditions and a more measured approach from buyers and occupiers.
Approximately 92,300 sq. m. of new office space was delivered during H1 2026, bringing total office stock to approximately 9.46 million sq. m. While future supply is expected to increase from 2027 onwards, near-term availability of high-quality ready office space remains relatively limited.
Dubai’s office market enters the second half of 2026 with strong underlying fundamentals but a more measured near-term outlook. Continued business formation, DIFC expansion and government support measures provide a supportive backdrop, although future market performance will depend on the recovery in buyer and occupier confidence, broader regional developments and the pace of new supply delivery.
Sales Transactions
Value H1 2026
Dubai’s economic environment remained broadly stable during H1 2026, supported by the emirate’s diversified economic base despite heightened regional geopolitical uncertainty. While economic momentum moderated during the period, Dubai’s economy continued to expand, with GDP reaching AED 232 billion in Q1 2026, representing 2.4% year-on-year growth. The broader UAE economy is forecast to grow by 1.7% in 2026, reflecting a temporary moderation following the strong growth recorded in 2025. Nevertheless, the UAE’s strong fiscal position, continued investment activity and targeted policy measures, including the CBUAE Financial Resilience Package and Dubai’s AED 2.5 billion business support package, have helped cushion external pressures and support economic activity.
Dubai’s position as an international business hub continued to strengthen, supported by growth in key sectors such as financial services, technology and professional services. DIFC attracted 2,318 new active registered companies during H1 2026, representing a 30% year-on-year increase and bringing the total number of active firms to 10,018. Financial services companies increased to 1,134, while AI and FinTech firms reached 1,933, supporting continued demand for modern office space. DIFC’s improvement to seventh place in the Global Financial Centres Index further reinforced Dubai’s growing role as a regional and international financial centre. Business retention also remained positive, with Dubai Chamber of Commerce recording a record 30,697 membership renewals in April 2026.
Despite these structural strengths, business momentum moderated during Q2 2026 as regional uncertainty weighed on sentiment. The S&P Global Dubai Purchasing Managers’ Index declined to 50.7 in June 2026 from 52.0 in May, marking the weakest reading since early 2021, although it remained above the neutral 50.0 threshold and indicated continued expansion in the non-oil private sector. The moderation in business activity reflects a more cautious private-sector environment, however, Dubai’s diversified economy, strong investment fundamentals and supportive business landscape are expected to provide resilience against external pressures.
Dubai continues to solidify its position as a global business hub with record new company registrations in key financial sectors. While heightened regional uncertainty has introduced a more cautious buyer environment recently, the sustained demand for premium commercial space reinforces the enduring appeal of the emirate for international investors.
Vidhi Shah Director, Head of Commercial Valuation
higher proportion of high-value office transactions completed during H1 2026.
While overall activity during H1 2026 remained well above the level recorded a year earlier, market momentum softened during Q2 2026. Transaction volumes totalled approximately 1,000, down 35.8% compared with Q1 2026 but 4.4% higher than the same period last year. The slowdown was primarily concentrated in the ready office segment, reflecting seasonal factors alongside heightened regional geopolitical uncertainty, which contributed to more cautious buyer sentiment
The composition of Dubai's office sales market continued to shift towards the off-plan segment during H1 2026. Off-plan transactions totalled approximately 1,700, accounting for 64.8% of total office sales, while the ready segment recorded around 900 transactions, representing the remaining 35.2%. The off-plan share has increased significantly in recent years, rising from just 2.6% in H1 2023, highlighting a structural shift in buyer preference towards newly launched commercial developments.
On a quarterly basis, both market segments recorded lower transaction volumes in Q2 2026, with the off-plan segment recording approximately 700 transactions and the ready segment around 300 transactions, representing quarter-on-quarter declines of 53% and 24.7%, respectively. While both segments recorded lower activity compared to Q1 2026, off-plan transactions remained above Q2 2025 levels, whereas the ready segment recorded a softer performance. As transaction registration lags continue to unwind, Q2 2026 provides an early indication of underlying market activity, with Q3 2026 expected to offer greater clarity on broader market conditions.
Sales Transactions - By Volume
Despite transaction volumes increasing by 38.2% year-on-year, total office sales values rose significantly, reaching AED 15.8 billion during H1 2026, representing a 199.3% year-on-year increase. The sharp increase in transaction values was largely driven by a shift towards higher-value transactions. H1 2026 recorded more than 220 office transactions above AED 20 million, the highest level on record and a significant increase from the 20 transactions recorded in both H1 2025 and H2 2025. Of these, 210 were off-plan sales, concentrated within a limited number of newly launched projects, with Lumena (84 transactions) and Lumena Alta (62) accounting for around two-thirds of all transactions above AED 20 million, followed by AHS Tower (40).
This shift towards higher-value transactions was particularly evident in the off-plan segment, where the average ticket price increased from AED 3.5 million in H1 2025 to AED 8.3 million in H1 2026 (+133.1% year-on-year). In comparison, the ready segment recorded a more modest increase, with the average transaction value rising from AED 2.6 million to AED 3.0 million (+13.8% year-on-year).
Within the off-plan segment, units below 1,000 sq. ft. accounted for over half of all transactions (50.6%), indicating continued demand for smaller office units. However, H1 2026 also recorded an increase in transactions for units above 2,000 sq. ft., as several high-value transac tions during the period were for larger office spaces. In contrast, the ready market was dominated by offices between 1,000 and 2,000 sq. ft. (52.9%), reflecting stronger demand for mid-sized office units.
Off-Plan Sales Transactions by Unit Size (%)
Ready Sales Transactions by Unit Size (%)
Source: Cavendish Maxwell, Property Monitor
Combined Ready and Off-Plan Transactions
Office sales activity remained concentrated across a limited number of key commercial locations during H1 2026, with the top five areas accounting for approximately 70.6% of total transactions. Business Bay recorded the highest transaction volumes, supported by activity across both the ready and off-plan segments, while Al Sufouh 1 ranked second, driven primarily by off-plan transactions. Jumeirah Lakes Towers continued to record steady sales activity, highlighting its position as an established commercial hub, with Dubai Maritime City and Barsha Heights completing the top five locations.
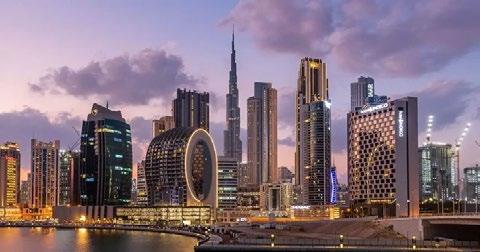
Business Bay 814 Transactions
Al Sufouh 1 498 Transactions
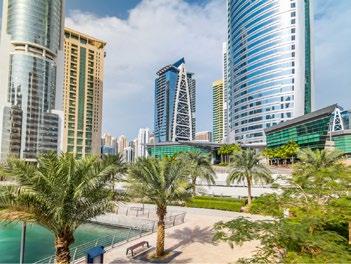
Jumeirah Lakes Towers 333 Transactions
Dubai Maritime City 88 Transactions
Barsha Heights 82 Transactions
Source:
Approximately 92,300 sq. m. of new office space was delivered during H1 2026, bringing Dubai's total office stock to approximately 9.46 million sq. m. A further 150,000 sq. m. is scheduled for completion by year-end, increasing total stock to approximately 9.61 million sq. m., with an additional 379,000 sq. m. projected for delivery in 2027 and 718,000 sq. m. in 2028.
Despite the sizeable medium-term pipeline, office supply is expected to remain relatively constrained over the remainder of 2026. As with previous years, construction delays are likely to continue affecting delivery schedules, resulting in a portion of the planned supply being deferred rather than cancelled. While regional geopolitical uncertainty could contribute to further delays, particularly for projects in the earlier stages of development, the majority of near-term completions comprise projects that are already well advanced in construction. Consequently, delays are expected to redistribute supply across future periods rather than materially reduce the overall pipeline.
Source: Cavendish Maxwell, MEED Projects
*The projected supply is based on the information available at the time of preparing the report and may differ from other projections. It is subject to revision as additional details about these projects become available in the future.
Dubai office sales prices reached AED 2,012 per sq. ft. in H1 2026, up 15.1% year-on-year. However, the pace of growth moderated slightly on a quarterly basis, driven by softer conditions in the ready office market. Heightened regional geopolitical uncertainty contributed to a more measured buyer environment, resulting in slower transaction activity and longer deal completion timelines. In response, some sellers adjusted pricing expectations to facilitate transactions, contributing to the modest moderation in quarterly price growth.
Average office rental rates in Dubai reached AED 189 per sq. ft. per annum in H1 2026, up 14.1% year-on-year. While annual rental growth remained positive, momentum eased during Q2 2026, with average rates declining slightly on a quarterly basis following the strong growth recorded over previous periods. The softer quarterly performance was partly influenced by regional geopolitical uncertainty, which weighed on occupier decision-making, with some businesses adopting a more measured approach toward expansion and relocation.
Rental growth remained broad-based across Dubai's office submarkets during H1 2026, with most locations recording positive year-on-year increases. On a quarterly basis, however, rental growth moderated across several submarkets, reflecting a more measured pace of occupier activity as regional geopolitical uncertainty continued to weig
Downtown Dubai recorded the strongest annual rental growth at 17.5%, followed by Barsha Heights (17.2%), DIFC (17.1%), Business Bay (16.0%) and Jumeirah Lakes Towers (15.1%). In contrast, older and more peripheral office stock recorded weaker rental performance, with average rental rates declining by 2.1% in Deira, while Bur Dubai remain
Dubai’s office market enters the second half of 2026 navigating a more uncertain operating environment. While year-on-year indicators remained positive during H1 2026, quarterly trends point towards a moderation in market momentum, with transaction volumes, sales prices and rental rates recording slight quarter-on-quarter declines in Q2 2026. The softening was most evident in the ready segment, where regional geopolitical uncertainty contributed to a more cautious buyer and occupier environment, resulting in slower deal activity, longer decision timelines and some adjustment in seller expectations.
Near-term transaction activity is expected to remain closely linked to business confidence, developer activity and broader market conditions. Higher off-plan activity during H1 2026 was supported by newly launched projects, and sustaining similar levels of activity will depend on continued developer confidence and the availability of attractive new opportunities. Should uncertainty persist, both launch activity and buyer decision-making could remain more measured.
On the supply side, the limited availability of high-quality ready office space continues to support market conditions across established business districts. However, this constraint is expected to gradually ease as additional stock enters the market from 2027 onwards, with approximately 379,000 sq. m. scheduled for delivery in 2027 and 718,000 sq. m. in 2028. While this future supply will improve market availability, delivery timelines remain subject to construction progress and market conditions.
The near-term trajectory for sales prices and rental rates will largely depend on the recovery in buyer and occupier confidence following the softer market conditions recorded in Q2 2026. While the limited availability of quality office stock is expected to provide some support, continued regional uncertainty could result in a more measured pace of growth compared with previous periods.
The structural foundations of Dubai’s office market, including its diversified economy, strategic location and pro-business regulatory environment, remain intact. However, performance in the coming periods will increasingly depend on the interaction between geopolitical developments, the pace of future supply delivery and the depth of occupier demand. Q3 2026 will provide a clearer indication of whether the Q2 moderation was a temporary response to external factors or the start of a broader adjustment in market activity.
