THE ASIA ISSUE
Issue 4 2026
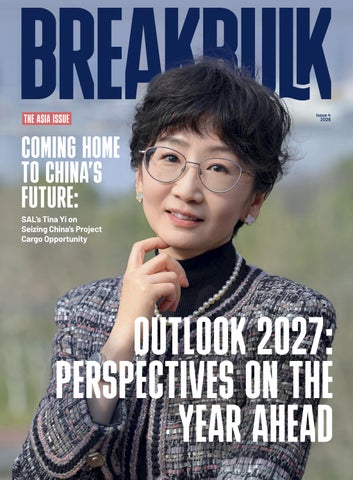
COMING HOME TO CHINA’S FUTURE:
SAL’s Tina Yi on Seizing China’s Project Cargo Opportunity
OUTLOOK 2027: PERSPECTIVES ON THE YEAR AHEAD
APAC’S ENERGY POLICY DILEMMA Ben Carrozzi examines the high-stakes choices facing the region’s governments
THE PERFECT FIT Our 32,000 dwt Super B-Class vessels are already breaking cargo intake records - handling the size and scope of project components previously impossible. They embody AAL's award-winning commitment to being the world's most trusted project heavy lift carrier. With ongoing fleet, service and sustainability investment, we aim to be the perfect fit for our customer demands.
Inside This Issue
35 Global Outlook 2027 Perspectives on the Year Ahead
78
Cover Story
Coming Home to China’s Future: SAL’s Tina Yi on Seizing China’s Project Cargo Opportunity
12 UpFront: Movers and Shakers
25 UpFront: Thought Leader
52 Global Navigating a Brave New World
Highlighting recent industry hires, promotions and departures
AI starts with people
14 UpFront: Waves of Cargo
Two teams, one global operation
Why project cargo is taking the West Coast route
16 UpFront: News Bites
28 UpFront: Future Thinkers Poll
Breakbulk Asia Keynote Mehmet Öğütçü on why a disrupted globe demands bolder business leaders
26 UpFront: Thought Leader
A roundup of Breakbulk shippers and exhibitors in the news
Beyond the lowest bid? Not so fast
18 UpFront: The Logistics Lens by Hatch
Building the next generation of maritime logistics professionals
The chokepoint era: Why logistics is the project now
20 UpFront: Breakbulk Asia
Meet the Asia founders advisory board
22 UpFront: Breakbulk Asia
200+ Exhibitors, 38 countries
24 UpFront: Exhibitor Spotlight
57 Asia APAC’s Energy Policy Dilemma
30 UpFront: BBAM Education Day
The Asia-Pacific region is at an energy crossroads
32 UpFront: Waves of Cargo
64 Asia After 900 APMT Moves, This Crew Won’t Go Back to Diesel
Five RTGs, two quay cranes, one project
35 Global Outlook 2027 Perspectives on the Year Ahead Industry comment from around the world
Meet some of the companies showcasing their expertise at Breakbulk Asia
4 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Field testing of mixed formations lets fleet owners reduce costs without scrapping diesel units
69 Asia Three Straits, One Global Risk
Why breakbulk can’t ignore a disruption in Malacca, Singapore or Taiwan
Port Houston City Docks
Delivering what your customers need. Whether it’s steel coil, grain, lumber, or oversized heavy-lift cargo for the energy and industrial sectors, you can count on Port Houston to deliver what you need at our multi-purpose facilities. Flexibility and connectivity set us apart, and a skilled and dedicated labor force gives you reliability. Get your cargo to your customers faster by choosing Port Houston.
www.porthouston.com
Inside This Issue
88
Baltic Breakout
Be a part of Breakbulk
74
AAL Rides Australia’s Battery Boom
Breakbulk Asia November 18-19 Sands Expo and Convention Centre, Singapore
MIDDLE EAST FEBRUARY 2-3 2027
Breakbulk Middle East February 2-3 Dubai World Trade Centre Dubai, UAE
EUROPE MAY 11-13 2027
Breakbulk Europe May 11-13 Rotterdam Ahoy Rotterdam, Netherlands
AMERICAS OCTOBER 19-20 2027
Breakbulk Americas October 19-20 George R. Brown Convention Center Houston, USA
88 Europe Baltic Breakout
74 Asia AAL Rides Australia’s Battery Boom
Rising demand for grid-scale energy storage is opening a new breakbulk market
78 Asia Coming Home to China’s Future: SAL’s Tina Yi on seizing China’s project cargo opportunity
83 Middle East Projects Driving the Middle East Forward
6 Issue 4 2026
93 Breakbulk Americas Update Where Innovation Meets Industry
Opsima takes top honors at Breakbulk Americas 2026 Innovation Pitch
94 Americas North American Project Cargo in 2030:
Evans Transportation’s view of the next industrial logistics cycle
We examine the region’s continued appeal to international investors and spotlight some of the latest developments
Breakbulk Magazine
Offshore wind pipeline shifts focus from ambition to execution
breakbulk.com
98 Back Page The Last Look
Great photo, innovative project
Foreword
PRACTICE MAKES PERFECT We’re in Singapore for the launch of Breakbulk Asia, our first new event in a decade. Asia is a region of opportunity that connects the world, Leslie Meredith and we’ve made this issue your resource on its most important issues and trends. It’s also our annual outlook, so we’ll take you into 2027 across all four regions. Whether you’re here in Singapore with us or somewhere else in the world, we’ve got you covered. If you want to know where the capital is headed, start with “APAC’s Energy Policy Dilemma.” Ben Carrozzi of Norton Rose Fulbright argues that bankability, not ambition alone, will decide which of the region’s energy projects get built. If you’re in Singapore, his colleague Aditya Rebbapragada puts that idea to the test at the Project Finance Forum. Mehmet Öğütçü, a former Turkish diplomat who was posted to Beijing in 1989, sees opportunity in a disrupted world. His advice for Asia: diversify around China, not away from it, and follow the electricity. Data centers and new factories across the region need generation, transformers and transmission, and that means project cargo. Read his profile alongside “Three Straits, One Global Risk,” on the region’s shipping chokepoints. Öğütçü will also give Thursday’s keynote. When it came to the cover, I knew right away it had to be Tina Yi. I met her years ago in Shanghai, where her silver butterfly shoes belied the experienced seafarer within. She was one of the few female executives in maritime, and she exuded authority
Editorial Director
Leslie Meredith Leslie.Meredith@breakbulk.com
and leadership. I later learned she credits China’s one-child policy for her outlook: she was treated the same as any boy her age. Tina was one of the original Women in Breakbulk Europe members and will deliver this year’s keynote at the women’s breakfast in Singapore. In Outlook 2027, you’ll hear from commentators around the world, from “cautiously optimistic” in Asia to “absolutely bullish” in the Americas. They agree that next year’s challenge is execution, not demand. The energy transition used to dominate the conversation. Now it’s about power, whatever the source, and getting the equipment there on time. In the Middle East, project awards have kept coming despite the conflict. As Mohammad Jaber of Combi Lift Projects puts it, “Whoever books capacity early wins the year.” Breakbulk Middle East in Dubai is where it starts. Planning for disruption is what drives Future Thinkers, our newest community, and the group keeps growing as many call this an environment of permanent uncertainty. Join us. We’ll keep working through scenarios together and building a community of strategists ready for whatever comes next. Unsurprisingly, disruption came up across the board in our stories in this issue. So did “stronger,” “opportunities,” “expansion,” “growth,” “resilient” and “accelerating,” again and again. Is our industry ready for the challenges ahead? A resounding yes! In 2026, we knew we had to be resilient. In 2027, we’ll put it into practice.
7 Issue 4 2026
Simon West simon.west@breakbulk.com
Designer Mark Clubb
Reporters
Luke King, Liesl Krog, Amy McLellan, Malcolm Ramsay
Contributing Editors Jonathan Cournoyer Hatch Tyler Sullivan ICAT
Breakbulk Magazine Editorial Board
John Amos Amos Logistics Tina Benjamin-Lea On assignment at Lilly Faycal Boumerkoufa National Air Cargo Jonathan Cournoyer Hatch Elisabeth Cosmatos Cosmatos Group of Companies/The Heavy Lift Group Dennis Devlin HLI Rail & Rigging, LLC Payne Fischer GEODIS Dharmendra Gangrade Larsen & Toubro John Hark Bertling North America /Texas A&M University Itoro Ibanga Air Liquide Margaret Kidd San Jacinto College Gautham Krishnan Fluor John Pittalis AAL Shipping Tyler Sullivan ICAT Jake Swanson DHL Global Forwarding Edward Talbot Trans Global Projects Grant Wattman Jade Management Group, Inc. Andrew Young Bechtel Corporation
Portfolio Director
Jessica Dawnay Jessica.Dawnay@breakbulk.com To advertise in Breakbulk Media products, visit: http://breakbulk.com/page/advertise Subscriptions To subscribe, go to https://breakbulk.com/page/ breakbulk-magazine A publication of Hyve Group plc. The Studios, 2 Kingdom Street Paddington, London W2 6JG, UK
Best, Leslie Meredith Product and Editorial Director
Breakbulk Magazine
Senior Reporter
breakbulk.com
Inside This Issue
Exhibitors and Breakbulk Global Shippers: Movers and Shakers (p. 12) Air Charter Service, Blue Water Shipping, Buchanan Hauling & Rigging, DENZAI, DHL Global Forwarding, Faymonville, Gulftainer, Hapag-Lloyd, Jacksonville Port Authority, J M Baxi, Pacific International Lines, PD Ports, Trans Global Projects
Global Outlook 2027 (p. 35) Al Faris, AAL Shipping, BBC Chartering, Chinaland Shipping, Combi Lift Projects, deugro, Fracht Group, JGC Corporation, Mitsubishi Power, Project Logistics Engineering Solutions, Rhenus Project Logistics, Trans Global Projects, UTC Overseas
Two Teams, One Global Operation (p. 14) Rhenus Project Logistics Global
Three Straits, One Global Risk (p. 69) Maersk Project Logistics, Gulftainer
News Bites (p. 16) AD Ports, ArcelorMittal, Bechtel, Fluor, GEODIS, Halliburton, JGC Corporation
AAL Rides Australia’s Battery Boom (p. 74) AAL Shipping Coming Home to China’s Future (p. 78) JSI Alliance, SAL
Logistics Lens The Chokepoint Era: Why Logistics Is the Project Now (p. 18) Hatch
Projects Driving the Middle East Forward (p. 83) Aramco, L&T, Mitsubishi Heavy Industries, Saipem, Samsung E&A
Why Project Cargo Is Taking the West Coast Route (p. 26) PCC Logistics
Baltic Breakout (p. 88) GE Vernova, JSI Alliance, Ørsted, Port of Gdańsk, UTC Overseas, Van Oord, Vestas
Beyond the Lowest Bid? Not So Fast (p. 28) Andritz Hydro, Siemens Energy Five RTGs, Two Quay Cranes, One Project (p. 32) Shanghai Hamel Supply Chain Technology
Destination 2030: Breakbulk Americas Scenario Contest (p. 94) Evans Transportation
Key: Breakbulk exhibitor Breakbulk Global Shipper Program participant
A special thank you to our advertisers:
Credit: UTC Overseas
AAL Shipping, CMA CGM, Dahlia Technologies, DHL Industrial Projects, DP World, Drewry, GPLN, Move It, MSC, Plant & Equipment, Port Houston, RHB, Sealand Project Line, Swire Shipping
8 Breakbulk Magazine
Issue 4 2026
breakbulk.com
d
ou Pr lia ra st
Au n ri be 21 em 20 M N ce PL Sin G Visit us at
Breakbulk Asia Singapore
Nov 18-19, 2026 GPLN Booth No: F02
Es t. 04
20
Membership Available in Selective Markets! Application: info@gpln.net / www.gpln.net
INSIDE Movers & Shakers Waves of Cargo (I): Rhenus Project Logistics News Bites Ayman Elbanan: The Chokepoint Era Meet the Asia Advisory Board Breakbulk Asia: Discover who’s coming to Singapore Adnan Rajput: AI Starts With People Leo Lopez: Project Cargo and the West Coast Route Future Thinkers update Future of Management poll results Breakbulk Americas Education Day Waves of Cargo (II): Shanghai Hamel Supply Chain Technology
An offshore wind tower segment on a Vastwin APMT. Credit: Vastwin
MOVERS AND SHAKERS
Buchanan Hauling & Rigging
Rafael de los Santos Diaz has joined the heavy haul team at Buchanan Hauling & Rigging, based in Fort Wayne, Indiana. De los Santos has previously served as managing director at logistics recruitment firm Pino Alto, business development Rafael de los Santos manager at Mammoet in Mexico, Diaz and before that, more than 15 years at the family-owned heavy transport company Tradelossa, including seven years as CEO.
Highlighting Recent Industry Hires, Promotions and Departures
DENZAI
Pacific International Lines
Wan Chee Foong has been appointed deputy CEO of Pacific International Lines (PIL), effective Oct. 5, 2026, and will succeed Lars Kastrup as CEO in April 2027. Foong brings nearly three decades of leadership experience across transportation, ports and logistics, including senior roles at PSA Wan Chee Foong International, PSA BDP and Temasek. Kastrup will remain CEO through the handover period, thereafter serving as adviser to the board.
Dinah Teo has been appointed a director of DENZAI International Holdings. The executive joined DENZAI in 2020 following the acquisition of her former company, Huationg. She has since played a “central role” in DENZAI’s Singaporean and international operations, contributing to the group’s Dinah Teo corporate planning and finance, business expansion, investment evaluation and governance of global group companies.
SF Supply Chain
Gulftainer
Simon Farhat
Gulftainer has appointed Simon Farhat as chief operating officer of ports and terminals. Farhat, who will be based in the UAE, brings more than two decades of experience in ports, terminals and logistics. Prior to his new role, he served as CEO at Vietnam’s Gemalink container terminal, a joint venture between CMA CGM and Vietnamese group Gemadept.
Marcus Ng
PD Ports
Blue Water Shipping
Anna Ude
Anna Ude has joined Blue Water Shipping as VP, Projects Europe, where she will lead the company’s project activities across the region. Based in Hamburg, Ude brings more than two decades of experience in project logistics, sales and business development. She has held leadership roles at deugro, DB Schenker and Hansa Meyer Global.
Paul Foreman
12 Breakbulk Magazine
China-headquartered logistics service provider SF Holding has tapped Marcus Ng to lead SF Supply Chain and International’s global airfreight forwarding operations. Ng joins the company from Maersk, where he served as head of airfreight for AsiaPacific. The executive has also held various managerial roles with DHL Global Forwarding, based in Singapore.
Issue 4 2026
breakbulk.com
Paul Foreman has begun his new role of CEO of PD Ports, taking over from Frans Calje, who is stepping down after almost 10 years at the helm. Foreman joined the UK-based ports operator in late-2020, first as chief technology officer then chief operating officer. Prior to that he served almost 20 years at surfacing solutions provider Formica Group Europe.
J M Baxi
Hapag-Lloyd
Captain Alpesh Abhaay Sharma has been promoted to regional president for strategic business development, IMEA region, at J M Baxi Ports and Logistics. Sharma, who joined the company in mid-2024, had been serving as chief commercial officer. He has now been charged Captain Alpesh with driving strategic business Abhaay Sharma development and policy advocacy across the Group’s container and core businesses.
Anders Boenaes has become the new chief operating officer at Hapag-Lloyd. Boenaes joined the ocean carrier six years ago as senior managing director and member of the executive committee. Prior to that, he spent 27 years at Maersk in a series of managerial and Anders Boenaes executive roles across Europe, Africa and Asia. He has spent two years as board member at Höegh Autoliners.
Air Charter Service
Timo Kaden
Fujian Highton Development
Air Charter Service has brought in Timo Kaden as cargo business development director for ACS Germany. Kaden, who will be based in Frankfurt, boasts more than 30 years of experience in logistics, with 19 of those working for KN Airlift, the specialized airfreight forwarding subsidiary and facility of Kuehne+Nagel.
Lee Qingyi has joined China-based multipurpose vessel operator Fujian Highton Development as director of projects and MPP. He brings more than 10 years of experience in the shipping sector, having held various managerial roles at Chipolbrok before joining Lee Qingyi Singapore-headquartered carrier and vessel operator Centurion MPP, where he most recently served as senior chartering manager.
Faymonville
Faymonville has launched a new entity in the U.S. and has selected Matthew Schattgen to lead the setup. Based in Little Rock, Arkansas, Faymonville Group North America gives its customers direct access to the manufacturer’s portfolio of MAX Trailer, Faymonville, Matthew Schattgen Morello and Cometto products. Schattgen was recruited from U.S. trailer dealer Hale. He has also held roles at Barnhart Crane & Rigging and XL Specialized Trailers.
Trans Global Projects
Sergio Rivas
Jacksonville Port Authority
DHL Global Forwarding
Maja Šmidt is taking on a new position as chief information officer for the Middle East and Africa at DHL Global Forwarding. Šmidt, who has also joined the regional management board, has held several leadership roles across DHL Global Forwarding since joining the company more Maja Šmidt than 15 years ago, most recently serving as head of IT and business process optimization in the Gulf.
Bobby Wein
13 Breakbulk Magazine
Trans Global Projects has launched an office in the northern Spanish city of Bilbao, with Sergio Rivas heading up the new entity as TGP’s managing director, Spain. Rivas, who will oversee a seven-strong project team in Bilbao, brings more than three decades of experience in logistics. Prior to TGP, he spent nearly 16 years at GEODIS.
Issue 4 2026
breakbulk.com
Jacksonville Port Authority (JAXPORT) has recruited Bobby Wein as incoming chief commercial officer, part of the Florida port’s long-term succession plan. The executive will work alongside current CCO Robert Peek until his planned retirement in October 2027. Prior to JAXPORT, Wein served as vice president for commercial at SSA Marine’s Conventional Division.
Waves of Cargo
TWO TEAMS, ONE GLOBAL OPERATION
In the first Waves of Cargo project in this issue, we catch up with Colin D’Abreo, VP Director of Rhenus Project Logistics, to hear how project teams in Canada and China worked side-by-side to transport over 400 metric tons of transformer equipment — including two, 80-ton transformers — in support of a major Canadian industrial project. The operation involved a series of complex multimodal shipments from China to Canada, demonstrating Rhenus’ expertise in moving oversized and heavy-lift cargo. Q: Can you describe the route, from the transformers leaving the factory in China, across the ocean into Canada, and finally to the installation site?
carriers, rail providers, and local transportation partners to ensure the equipment moved safely and according to schedule.
Colin D’Abreo: Our project logistics teams in Canada and China worked closely to transport these units through a multimodal journey combining ocean, rail and road transport, along with specialized methods, Colin D’Abreo, Rhenus Project to safely deliver and position Logistics them for installation. All starting from the manufacturing site in China, the transformers were lifted out from the factory and safely prepared and loaded onto a vessel to be transported via ocean from the Port of Shanghai across to the Port of Tacoma. Following customs clearance and cargo handling operations, the transformers were transferred to rail for the majority of their inland journey to Ontario, Canada.
CD: Heavy-lift equipment was used to safely lift out the transformers from the manufacturing site to the Port of Shanghai where our projects logistics team in China arranged the preparation and loaded the units onto the RoRo vessel. Upon arrival in North America, specialized handling equipment was used to facilitate the transfer of the cargo to rail transportation for its inland journey. For the final delivery in Ontario, our team in Canada transferred the units from rail onto an SPMT for transport to the project site. Once onsite, jackand-slide and turntable rigging systems were used to precisely maneuver and position the units onto their concrete foundation pads for installation.
The final leg of the journey was completed via specialized road transport to the project site, where the units were prepared for installation. Rhenus Project Logistics coordinated with its local teams in China and Canada, as well as port operators, ocean
Q: What specialized heavy-haul and lifting equipment was required for each stage of the journey?
Q: What were the biggest challenges you identified at the beginning of the project? Were there any unexpected challenges during execution? CD: As with many oversized cargo projects, the biggest challenge at the beginning of the project was determining the safest and most efficient transportation route, given
14 Breakbulk Magazine
Issue 4 2026
breakbulk.com
The transformers are transferred onto an SPMT for final mile delivery.
the complexities based on Canada’s terrain and climatic conditions. This required careful planning, from factory lift-out, customized lashing and securing, and specialized port loading to ocean voyage planning. To address these challenges, the teams in China and Canada worked closely together from early planning stages, combining heavy-lift expertise with local knowledge to validate route surveying solutions and mitigate potential risks.
Credit: Rhenus Project Logistics
During execution, maintaining alignment between the transformer’s production schedule and the transportation timeline required ongoing coordination. Rhenus Project Logistics worked proactively with the manufacturer and adjusted shipping schedules as needed to keep the project on track. This close collaboration has allowed the team to deliver the transformers safely and on time to the port of Tacoma in just 17 days. Q: How important was having Rhenus teams in both China and Canada to the success of the operation? How did the two teams work together? CD: Our greatest strength and success at Rhenus is our global team. We have developed a team of experts around the world with the knowledge and experience to move and execute complex and oversized cargo, which is critical to the success of this project. Our teams in Canada and China worked closely together from the early planning phases of the project, maintaining constant communication and sharing their expertise to address challenges and identify the most effective solutions. From the beginning, the teams in China and Canada collaborated on route surveying, operational planning and the execution strategy for transporting the transformer from the manufacturing facility in China to its final installation site in Canada. By combining local expertise and maintaining close coordination throughout every stage of the project, the teams successfully found solutions on how to navigate through Canada’s complex terrain and climatic conditions while ensuring the safe and efficient delivery of the transformers.
Each 80-metric-ton transformer required coordinated transfers between ocean vessels, rail networks and specialized heavy-haul road transport before final installation at the site. Credit: Rhenus Project Logistics
While this project is still ongoing, it is a testament to the strength of Rhenus’ global project logistics network and demonstrates how expertise developed across different geographies can be leveraged to support complex international projects, delivering greater reliability and value throughout the supply chain.
CD: Like every project we complete, it is rewarding to see months of planning, coordination and execution come together successfully. What made this project meaningful was the close collaboration between our teams in China and Canada. Both teams combined their local expertise and worked through each phase and step of this specific project together, taking each challenge and advising one another solutions. Their teamwork, commitment and problem-solving capabilities highlight the strength of Rhenus global network and the value of collaboration, making this all worthwhile and successful.
Q: What was the most rewarding aspect of the project for you and your team?
15 Breakbulk Magazine
Issue 4 2026
breakbulk.com
NEWS BITES FROM AROUND THE WORLD: QUICK HITS, BIG IMPACT! A roundup of Breakbulk shippers and exhibitors in the news
Credit: Petros
PETROS, HÖEGH EVI TO DEVELOP LANDMARK LNG TERMINAL IN MALAYSIA
Malaysian state energy firm Petroleum Sarawak Berhad (Petros) and Norway’s Höegh Evi have agreed to jointly develop the Kuching LNG terminal in the Malaysian state of Sarawak. The terminal, the first to be built in Sarawak, will comprise a floating storage and regasification unit (FSRU), mooring infrastructure, pipelines and onshore receiving facilities, and will be jointly developed, owned and operated
by the two companies, with first gas targeted for the end of 2029. The terminal will supply gas to Sarawak, Malaysia’s largest state geographically, while also supporting small-scale LNG distribution, truck loading, bunkering, storage and reloading. According to Reuters, Malaysia is the world’s fifth-largest LNG exporter, shipping more than 28 million tons in 2025, mainly to China, Japan and South Korea.
HALLIBURTON STRIKES VENEZUELA DEVELOPMENT DEALS Halliburton has signed memorandums of understanding with Brazilian energy company Eneva and WESCA to support energy development opportunities in Venezuela’s oil and gas sector. The agreements build on Halliburton’s nearly 90-year presence in the country, supported by local bases, operational capabilities and expertise. Under the agreements, Halliburton and Eneva will identify and pursue development opportunities, while its partnership with WESCA will focus on field evaluation and development planning. Halliburton is one of several oilfield services firms that have announced plans to boost their presence in Venezuela, following the removal of Nicolás Maduro from power in January and the easing of U.S. sanctions.
Credit: GEODIS
ETIHAD RAIL, AD PORTS LAUNCH FUJAIRAH-ABU DHABI RAIL NETWORK
GEODIS LAUNCHES NEW FORWARDING OFFICE IN THE PHILIPPINES GEODIS has strengthened its footprint in Asia following the launch of a new freight forwarding office in the Philippines. Located in Manila, the new base will provide a range of services including air and ocean freight, project logistics and supply chain optimization. According to GEODIS, the launch comes amid increased investment
in the Philippines, particularly in the country’s manufacturing, technology and other high-value industries. The Philippine Economic Zone Authority (PEZA) approved PHP151.9 billion (US$2.43 billion) in new and expansion projects in the first seven months of 2026, up 67% year over year, the forwarder said.
16 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Etihad Rail and AD Ports Group have launched a direct rail service connecting Fujairah Terminals with the Industrial City of Abu Dhabi (ICAD), creating an integrated inland logistics gateway. The service will transport cargo about 200 kilometers by rail from Fujairah to ICAD, where customers can access customs clearance, inspection and cargo release services. Operating three times a week, the service is designed to simplify customs procedures, reduce cargo handling and road congestion, and bring goods closer to warehouses and industrial facilities. The designation of ICAD with its own United Nations Location Code — AECAD — also allows cargo to be booked directly to the inland gateway.
BECHTEL-WESTINGHOUSE AND PEJ AGREE TO TERMS FOR POLAND’S FIRST NPP Poland’s first nuclear power plant (NPP) has taken a major leap forward after the Bechtel-Westinghouse consortium and Polskie Elektrownie Jądrowe (PEJ) agreed to the main commercial terms of the project’s EPC contract. Detailed negotiations are continuing, Bechtel said, with the parties targeting completion of the remaining contract terms by the end of this year.
The Bechtel-Westinghouse consortium is responsible for the construction of the NPP, with first electricity to the Polish grid from the plant expected to flow in 2036. The facility will use Westinghouse AP1000 reactor technology, with a combined installed capacity of about 3.75 gigawatts. The site is at Lubiatowo-Kopalino in Credit: Bechtel Pomerania, close to the Baltic Sea.
NEW EU STEEL CHIEF TARGETS GROWTH AND EXPORTS
Credit: SSAB
European steel association Eurofer’s new president Geert Van Poelvoorde is pushing for stronger regional steel markets, secure export access and a more resilient industrial base as global trade fragments, and the sector faces declining production. EU steel exports to third countries fell 20% in the first half of 2026, while steel production in 2025 reached historic lows. Van Poelvoorde, chairman of
ArcelorMittal Europe, welcomed the EU’s new steel trade measure aimed at protecting European steelmakers from the effects of global steel overcapacity and trade diversion, but called for further action. He urged competitive energy costs, stronger demand for European-made products and adjustments to the EU Emissions Trading System to support investment, low-carbon steelmaking and international competitiveness.
FLUOR, JGC JOINT VENTURE SELECTED FOR LNG CANADA PHASE 2 EXPANSION
Credit: Fluor
A joint venture between Fluor and JGC Corporation has won a multi-billiondollar contract to deliver engineering, procurement, fabrication, construction and commissioning for Phase 2 of LNG Canada’s liquefied natural gas (LNG) export facility at Kitimat, British Columbia. Phase 2, which will be built adjacent to the existing Phase 1 facility, will include the construction and commissioning of an additional LNG storage tank and two new liquefaction units, or trains, doubling the facility’s production capacity to some 28 million tonnes per year. LNG Canada is a JV comprised of Shell (40%), PETRONAS (25%), PetroChina (15%), Mitsubishi Corporation (15%) and Korea Gas (KOGAS) (5%).
17 Breakbulk Magazine
Issue 4 2026
breakbulk.com
THOUGHT LEADER – The Logistics Lens Through a strategic practitioner’s lens, Hatch Logistics’ global experts explore the forces shaping project and breakbulk logistics: from risk and execution to geopolitics, sustainability and decision-making in complex cargo environments.
THE CHOKEPOINT ERA: WHY LOGISTICS IS THE PROJECT NOW
By Ayman Elbanan
When Plan B Is Not Good Enough
In project logistics, we used to preplan our routes a few months in advance. Today, we can find ourselves reevaluating them weekly. Working as one of the project delivery teams at Hatch gives us a front-row view of this change. We move heavylift modules, oversized equipment and critical long-lead items. These are not shipments that Ayman Elbanan, Hatch can simply be rerouted overnight or replaced on short notice. And when a major shipping corridor becomes unavailable, it is no longer just a logistics problem. It becomes an engineering, procurement, construction and schedule problem.
The response to disruption was simple for decades. If one corridor was choked, we used another. The logic only works if the alternative is still trusted. Today, projects are increasingly faced with the need to address disruption in multiple corridors simultaneously. A contingency route may in turn depend on another exposed port, strait or overland corridor. A Plan B that depends on another vulnerable corridor is not really a Plan B.
The Real Cost Is Uncertainty
Freight rates and insurance premiums attract attention as both are visible. But in project logistics, the bigger impact can be elsewhere. Change the port of discharge and you may need new route surveys, permits, customs arrangements, heavy-haul engineering, bridge assessments, civil works and construction-interface planning. In one of our shipments, the proposed port of discharge was changed three times in approximately six weeks, with each change triggering another cycle of assessments and coordination. The lesson was simple: Route uncertainty becomes project uncertainty.
Alternative Routes Must Be Engineered
We are increasingly evaluating alternative gateways and overland corridors to maintain optionality when traditional routes become constrained. On a map, an alternative corridor can look straightforward. Moving heavy and oversized cargo through it may require cross-border customs coordination, road surveys, bridge assessments, civil modifications, permits, specialized transport equipment and continuous engagement with authorities. The alternative route cannot simply sit in a contingency plan. It must be engineered. Ideally, before we need it. Project logistics operations supporting the safe movement of oversized and critical cargo for complex project delivery. Credit: Hatch
18 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Heavy-lift and project cargo activities, where route planning, engineering and execution come together. Credit: Hatch
Logistics Moves Upstream
About the Author
Ayman Elbanan is the regional logistics manager, Middle East & Africa, for Hatch. He has almost 20 years of experience at DSV, CMA CGM, CEVA and Agility, having led multi-country teams and delivered complex heavy-lift projects for major energy, industrial and EPC customers across the region.
This is where I believe engineering, procurement and construction management (EPCM) projects should go. Logistics should not start after engineering and procurement decisions have already been made. A package’s size determines whether it can be transported. Routing is affected by supplier locations. Port capabilities drive modularization. Road constraints affect engineering. Delivery sequencing affects construction. So, logistics must have an impact on these decisions much earlier. The question is no longer just: “What is the most efficient route?” It becomes increasingly: “What combination of routes makes this project doable when things change?” This means designing two or even more corridors, not one preferred route. It means bringing logistics decisions into engineering and procurement at an earlier stage. And that means testing logistics strategies throughout the lifecycle of the project, instead of treating contingency planning as a one-off activity.
The Bottom Line
The chokepoint era does not end with the opening of one shipping lane. For projects, it ends when we stop treating resilience as an aspiration and start treating it as an engineering requirement. Logistics is more than simply moving cargo in the best possible way. It’s about making sure the project is executable when the best way is no longer there.
Logistics in action, coordinating specialized transport and project interfaces to keep critical cargo moving. Credit: Hatch
19 Breakbulk Magazine
Issue 4 2026
breakbulk.com
MEET THE ASIA FOUNDERS ADVISORY BOARD BREAKBULK ASIA 2026
THE ASIAN PROJECT MARKET IN THREE WORDS
UNTAPPED. UNSTOPPABLE. UNPRECEDENTED. MURRAY COOPER, PRIME TRADE MANAGEMENT SERVICES
SINGAPORE
UAE
SINGAPORE
Kumaresh Bala
Farid Belbouab
Murray Cooper
Senior Trade Manager, Asia Project Cargo
CEO
CEO
Gulftainer
Prime Trade Management Services
CMA CGM
PORTS & TERMINALS
MARITIME TRANSPORT
CZECHIA
CONSULTING / FORMER EPC
JAPAN
SINGAPORE
Miroslav Jakab
Koichi Kaizu
Namir Khanbabi
Fluor Fellow, Logistics
Subject Matter Expert, Logistics & Module
General Manager
Fluor SHIPPER · EPC
JGC Corporation
MARITIME TRANSPORT
SHIPPER · EPC
20 Breakbulk Magazine
Issue 4 2026
Swire Projects
breakbulk.com
““
SINGAPORE
UK
CL
EBreakbulk vents like this Asia creates a single room where project owners, forwarders, accelerate trust, and carriers and financiers canChung align on theLaw challenges ahead. The fact that Ming Mehmet Öğütçü in project logistics, shippers from companies like GE Vernova, Siemens Energy, Fluor and L&T CEO Chairman trust is what moves are already registered tellsSingapore you theLogistics demand for this conversation is real. Association Global Resources Partners cargo. ADNAN R A JPUT, LOGICSOLS ADNAN RAJPUT, LOGICSOLS
SINGAP ORE CYPRUS
ChungPittalis Ming Law John
CEO Head of Marketing & Singapore Logistics Association Communications AAL Shipping F R E IG H T F O RWA R D I N G MARITIME TRANSPORT
FREIGHT FORWARDING
SHIPPER · ENERGY
““
“
UK
BBreakbulk reakbulkAsia Asiacan can help helpaccelerate accelerategrowth growth by bringing by bringing together together entire the entirethe project project ecosystem. ecosystem.
Mehmet member,Öğütçü about 15
KKUMARESH U MARE SH BALA, BA L A , CMA C M ACGM C GM
AWAITING S H IP P E R ·RESPONSE E N E R GY
CYPUAE RU S
UA E INDONESIA
[Pull quote from a FAB
Chairman words] Global Resources Partners
“
I N D ON ES I A
John Pittalis Adnan Rajput
Adnan Schoenert Rajput Daniel
Head of Marketing & CEO Communications Logicsols AAL Shipping
CEO Managing Director Logicsols thyssenkrupp Uhde Indonesia
Asia is the core driver of project Daniel Schoenert development for the Managing Director next decade. thyssenkrupp Uhde Indonesia
TECHNOLOGY M A R IT IM E T R A N SP O R T
T E C HN OLOGY SHIPPER · EPC
KOICHI S H IP P EKAIZU, R · E P CJGC CORPORATION
“
SINGAP ORE JAPAN
[Pull quote from a FAB
Kohki Uemura member, about 15 CEO words] DENZAI
AWAITING HE AV Y L IFRESPONSE T ENGINEERING
SINGAPORE JAPAN
“
“
[Pull quote from a FAB Kohki about 15 AsiaUemura is [the] core drivermember, for the project CEO words]
development in the next decade.
DENZAI KOICH I K A I ZU, JGC C O R P O R AT I O N HEAVY LIFT ENGINEERING
21 Breakbulk Magazine
Issue 4 2026
breakbulk.com
AWAITING RESPONSE
Where to meet your next business prospect In the exhibitor stands! Free-to-attend conference sessions at Breakbulk Live and Voices stages
200+ exhibitors. 38 countries. Two days in Singapore.
Women in Breakbulk Lounge Singapore country pavilion Wednesday's networking party at The Lantern Rooftop Bar (reservation required) NextWave 30 networking party BUSINESSrun Women in Breakbulk Power Breakfast (ticket required) Breakbulk on the Rise Download the o cial Breakbulk app for details.
22 Breakbulk Magazine
Issue 4 2026
breakbulk.com
BY R E G I O N
BY C O U N T R Y
Six regions on the floor
Top 5 exhibitor countries
62.2%
Asia
62.2%
Europe
15.7%
Middle East
9.3%
Americas
6.4%
Africa
4.1%
Oceania
2.3%
#1
Singapore
28.5%
#2
China
16.9%
#3
UAE
5.8%
#4
India
#5
Germany and United States (3.5% each)
4.7% 3.5%
Together these countries make up 62.8% of exhibitors
BY S E C T O R
Top sectors, all exhibitors 35.5%
30.2% 13.4%
Maritime Transport
8.7%
Freight Equipment Ports & Forwarder Supplier Terminals
4.7%
43%
Industry Related Services
Also exhibiting: Technology (3.5%), Road Transport (2.9%), Air Transport (1.2%)
SPOTLIGHT
37.5% Doha Jeddah
Middle East exhibitors are ports and terminals Sharjah Dubai Abu Dhabi
Singapore
23 Breakbulk Magazine
Issue 4 2026
breakbulk.com
of Asian exhibitors are in maritime transport
EXHIBITOR SPOTLIGHT
Meet some of the companies showcasing their expertise at Breakbulk Asia DCS DAH Star Logistics manufacturing, energy transition and infrastructure investment,
Alex Xu General Manager – South China Shenzhen, Guangdong Province Freight Forwarder Stand: E32
which makes it a key driver of project cargo demand. Renewables, LNG, mining and urban infrastructure all drive heavy-lift and multipurpose cargo to and from the region. We see the strongest growth in energy transition projects and intraAsia trade. In both, better data on vessel availability and market conditions help companies plan with more confidence.
What makes Asia such an important region for project logistics today, and where do you see the greatest opportunities for growth? Asia stands as the global heart of project logistics. China is the world’s largest manufacturing base not only for traditional heavy industrial equipment, but also for products including new energy vehicles, battery energy storage systems and internet data center (IDC) modules. Asia’s extensive port network, especially China’s major coastal hubs, handles breakbulk, heavy-lift and over-dimensional cargo. The region sits on key trade routes linking Europe, the Middle East, Africa and Latin America. Moving forward, the strongest growth opportunities align closely with China’s export priorities. What made you decide to exhibit at Breakbulk Asia, and what are you hoping to achieve or take away from the event? We chose to exhibit at Breakbulk Asia as it is Asia’s flagship breakbulk and project cargo event. It serves as an ideal platform connecting Chinese project logistics providers with global partners, carriers and customers. We showcase our expertise in large industrial projects, vessel chartering, port operations, road transport and digital cargo visibility. We also aim to gather market insights and explore cooperation to support exports of China’s new quality productive forces products.
Alphaliner by Signal Ocean
Stephen Fletcher CCO Athens, Greece Technology Stand: E41
What makes Asia such an important region for project logistics today, and where do you see the greatest opportunities for growth? Asia is at the center of global
What made you decide to exhibit at Breakbulk Asia, and what are you hoping to achieve or take away from the event? Breakbulk Asia brings together the shippers, carriers, forwarders and project owners who shape the region’s project logistics market. Alphaliner by Signal Ocean and our investment Nextvoyage have many customers operating in breakbulk and container shipping. We’re here to meet them, understand their challenges and show how our management tools, data and analytics support better commercial decisions, from vessel tracking and fixtures to liner and multipurpose market intelligence. We hope to leave with new relationships, feedback and a clearer view of where the market is heading.
Karl Gross Group
Martin Kollmann Managing Director Bremen, Germany Freight Forwarder Stand: G43
What makes Asia such an important region for project logistics today, and where do you see the greatest opportunities for growth? Asia is very diverse in regard to technology and manufacturing companies. There is a manufacturing sector contracting overseas projects, while other companies act as suppliers for projects contracted by non-Asian manufacturers. What made you decide to exhibit at Breakbulk Asia, and what are you hoping to achieve or take away from the event? We have been active and present in Asia for more than two decades, namely in China since 2000 and Vietnam since 2006. Project logistics has been playing an important role at our locations all the while. With the launch of Breakbulk Asia, it was a logical consequence for us to attend, fly our “project logistics flag” and connect with customers, partners and suppliers from the region.
24 Breakbulk Magazine
Issue 4 2026
breakbulk.com
THOUGHT LEADER
AI STARTS WITH PEOPLE
The Hard Part of Artificial Intelligence in Logistics Isn’t the Technology By Adnan Rajput
Adnan Rajput, Logicsols
The logistics industry knows AI Lead with outcomes, not AI is coming. The question is no Externally, it is tempting to lead with the technology itself. longer whether to adopt it, but Clients care about outcomes. “We identified where you overpaid how to bring people along. on freight last quarter” starts a conversation. “Our platform uses advanced AI algorithms” does not. After 25 years moving freight across multiple verticals, and Talk about faster RFQs, fewer documentation errors, better cost now working on AI for logistics, visibility and catching problems before they become expensive. I have seen both worlds up close. The technology is Build trust with evidence advancing fast. The way we At a recent Future Thinkers* session in Rotterdam, AI readiness manage its adoption is not. across the project cargo industry was scored between 1 and 2.5 out of 10. The barriers raised were scattered data, disconnected systems and a lack of trust in digital tools.
Start with the people doing the work
In organizations I have worked for, the most common mistake I saw leaders make was introducing a new system without involving the people who would use it.
For one oil and gas client, checking every freight invoice against the quoted rate identified more than US$258,000 in billing variances. Running every shipment through competitive quotes reduced freight costs by 13.2%, or US$1.58 million. Neither was visible while information sat in emails and spreadsheets.
Leadership selects the system, designs the workflows, and only then brings the team into the conversation. That is usually where the conflict starts.
Bringing the data and workflows together surfaced them, and the numbers built trust.
The people managing shipments every day know where the real problems are. They know where information gets lost, which spreadsheets exist because the current system does not work, and which exceptions never appear on a process map. Leadership still needs to lead. But asking your team to make the decision is very different from asking them to help define the problem. The same applies to AI. If the first message employees hear is automation, efficiency and cost reduction, they will naturally wonder what it means for their jobs. Show them instead what AI takes off their plate: chasing emails, reconciling invoices, checking documents manually and rebuilding spreadsheets.
Getting AI right means involving your people and proving the value. But that also depends on what sits underneath: reliable data, clear ownership and knowing how the technology should respond when the real world does not follow the plan. That is what I will be exploring at Breakbulk Asia on Nov. 18. Until then, ask your team which spreadsheet they would delete first. Adnan Rajput is a global supply chain and logistics executive with more than 25 years of experience across multiple verticals and modes of transportation. Following senior leadership roles at GE and Bechtel, Rajput transitioned from logistics executive to technology entrepreneur as CEO of Logicsols.
Rajput will be speaking on the Breakbulk Asia “AI-Ready Supply That work consumes time that experienced professionals could Chains: Data Maturity, Cybersecurity and Scenario Planning spend managing relationships, resolving exceptions, negotiating in Project Logistics” panel on the Breakbulk Live Stage on and making judgment calls. AI will change logistics roles, but the Wednesday, Nov. 18 from 3:00pm-3:50pm. shift is from processing information to acting on it. *Learn more about Breakbulk’s Future Thinkers and how you can get involved at breakbulk.com/page/future-thinkers 25 Breakbulk Magazine
Issue 4 2026
breakbulk.com
THOUGHT LEADER
WHY PROJECT CARGO IS TAKING THE WEST COAST ROUTE Ocean diversions and tight project deadlines are pushing more project cargo into West Coast ports. PCC Logistics’ Leo Lopez explains why speed is beating the all-water route and where the cargo is headed next By Leo Lopez PCC Logistics has seen a significant increase in project cargo requests coming into the West Coast. The reasons will be familiar to anyone in this industry. The Red Sea situation, low water levels in the Panama Canal and the war in the Middle East have forced cargo to divert. For many of our customers, the answer has been to land cargo on the West Coast and move it inland from there.
move it across the country. Some of it goes by rail, but most of the project cargo we handle moves over the road. Money-wise, the all-water route can be more economical in the long run. But when a product is due and a project is on a deadline, you have to speed up the timeline. That cargo was shipped for a reason, and the project can’t move forward without it. As project schedules become increasingly aggressive, developers need logistics providers that can coordinate transportation, warehousing, staging, inventory management and site delivery with precision.
What We’re Moving
Much of this cargo starts in Asia, as China, South Korea, Vietnam, India, Indonesia, Malaysia and Singapore continue to serve as manufacturing and export hubs for large-scale infrastructure, energy and industrial projects.
The cargo mix shows where investment in the U.S. is going. We are handling inverters, transformers and battery energy storage systems (BESS) for mining projects and data centers. A lot of infrastructure is coming back to the United States, and that is making the country stronger.
Time Beats the All-Water Route
For data centers, that includes large power transformers, backup generators, switchgear, cooling infrastructure and modular data center components. Many of these assets are manufactured in Asia and exported through major gateways
Our customers want faster transit. When a project is waiting on equipment, they can’t wait another 15 or 20 days for it to reach the East Coast by water. So we pick it up at the port and
26 Breakbulk Magazine
Issue 4 2026
breakbulk.com
“I SEE PROJECT CARGO GROWING MORE AND MORE EVERY YEAR.” before arriving at project sites throughout the United States. Mining projects located in Nevada, Arizona, Utah, Idaho, Alaska and California need oversized processing equipment, crushers, conveyors, transformers and substations. Many of these components originate from Asian manufacturers. AI is adding to that demand. As the technology develops, I expect to see more data centers and more infrastructure built across the country. I see project cargo growing every year.
The Grid Is Next The modernization of North America’s electrical grid remains one of the largest drivers of project cargo demand. Utilities and energy developers continue investing in high-voltage transformers, substation equipment, battery energy storage and transmission upgrades. These projects regularly involve oversized and high-value cargo that requires transportation planning, route surveys and permitting. The result is a sustained pipeline of project cargo opportunities extending well beyond the traditional energy sector.
in the cost of moving cargo over the road, and there is a lot of discussion across the country about what can be done. Our focus is on keeping cargo moving for our customers and their projects.
Close to the Port PCC is a family-owned company and has been in business since 1988. Under the leadership of Mike McDonnell, Brandon McDonnell and me, we support supply chain requirements across government, infrastructure, technology, mining and industrial sectors. We grew into new commodities as carriers and forwarders brought us opportunities, and we have handled breakbulk and project cargo for the past 15 years. We are asset-based and keep our own assets in-house, offering port drayage, transload, warehousing and staging, inventory management and final mile. Our facilities sit close to the ports in Los Angeles and Long Beach along the Alameda Corridor, in Oakland and in Seattle and Tacoma. Being near the port lets us dray cargo in and out quickly and keep turnaround times short when a project is waiting.
Looking to Asia Our growth isn’t limited to the U.S. We are building our presence in Asian and European markets, which is why I attend Breakbulk events outside the country. I want PCC to be there for the projects coming into and going out of the U.S.
Moving utility transformers, BESS, generators, mining machinery and oversized modules demands extensive coordination between manufacturers, ports, carriers, terminal operators and final-mile transportation providers. As governments and private investors continue to support critical mineral development, project logistics providers will play an increasingly important role in making sure these facilities are built safely and on schedule.
Singapore is becoming a big transshipment hub, and I see more cargo coming from Asian countries. The Port of Singapore links Asian manufacturers with infrastructure, mining, energy and data center projects throughout North America. That’s why I’m looking forward to being in Singapore for Breakbulk Asia.
Rising Costs on the Road The past two or three months have brought new pressure from fuel charges. Many companies are seeing a big increase
Leo Lopez is Vice President of Project Cargo & Operations at PCC Logistics.
27 Breakbulk Magazine
Issue 4 2026
breakbulk.com
FUTURE THINKERS POLL
AI is set to transform tendering in breakbulk and project logistics. But a new poll suggests the industry is less ready to move beyond price than it might like to think. The findings will be debated at Breakbulk Asia in Singapore.
Beyond the Lowest Bid? Not So Fast
Join the Future Thinkers Community Group breakbulk.com/page-en/future-thinkers-sign-up
By Dr. Sven Hermann Managing Director and Professor for Logistics & Supply Chain Management ProLog Innovation GmbH and Northern Business School QUESTION 1
T
he promise is compelling: AIsupported data and analysis could finally allow shippers to evaluate bids on quality, reliability, risk and sustainability rather than price alone. Whether the industry will seize that opportunity is the question at the heart of the Future Thinkers spotlight “The future of tender management: Beyond the lowest bid” on Nov. 19 on the Breakbulk Live Stage. Ahead of the session, 35 professionals took part in a poll on AI and tendering by 2030. Nearly half (17) work in supply chain and logistics, 13 represent project owners, EPC contractors and manufacturers, and five come from maritime and ports.
Machines Will Do the Legwork
Who took part?
Respondents agree that automation is coming, though not on its scale. Twelve expect 25% to 50% of the tendering process to be automated by 2030; another 12 put the figure at 50% to 75%. Three foresee more than 75%, while eight expect less than a quarter. On decision-making, the verdict is clear. Three-quarters (26) expect AI to pre-screen bids while humans make the call. Eight believe AI will decide and humans merely confirm. Nobody expects AI to decide end-toend, and only one respondent thinks procurement will stay as it is today.
17 13 5
Supply chain and logistics Project owners, EPCs and manufacturers Maritime and ports
QUESTION 2
QUESTION 3
How automated will tendering be by 2030?
Who decides: human or machine? HUMAN
12
8 0%
12
25%
50%
26
1
3 75%
M AC H I N E
Procurement teams, AI pre-screens, humans decide as today
8
AI decides, humans AI decides only confirm end-to-end
100%
Three-quarters keep a human in the decision seat
24 of 35 expect between 25% and 75% of tendering to be automated
28 Breakbulk Magazine
Issue 4 2026
breakbulk.com
0
Q U E S T I O N 4 · T H E M O S T S T R I K I N G R E S U LT
Is price still king?
15
of 35 say no factor will outweigh price by 2030
None: price stays king
15
Reliability and track record
Risk profile and resilience
14
6
Sustainability and emissions data
0
Not a single vote
Price Keeps Its Crown, for Now The most striking result concerns the session’s own premise. Asked which factor could outweigh price, 15 respondents answered: none, price stays king. Fourteen named reliability and track record, six risk profile and resilience. Sustainability and emissions data received not a single vote. For a sector serving the energy transition, that is a sobering signal: if environmental performance is to count in tenders, it will need to become measurable and comparable first, which is precisely where AI could help.
Aware, but Not Acting The industry’s self-assessment is equally candid. Not one respondent considers logistics service providers well prepared. A full 80% (28) describe them as “aware, but not acting,” six as barely aware, one as completely unprepared. Views on the future of the shipperprovider relationship are divided. Twelve fear tendering will become more transactional with less trust. Nine expect fewer but deeper partnerships, nine see no real change, and just five believe AI will make tendering fairer and more transparent.
From Both Sides of the Table These tensions will be explored by a panel that brings together cargo owners and technology: André Starke, Director Project Logistics Global at Andritz Hydro; François Méroc, Senior Manager Global Project Logistics at Siemens Energy; and Marcello Curto, Founder and Managing Director of Cat & Mouse Software. The session is moderated by Dr. Sven Hermann, Managing Director of ProLog Innovation, Professor for Logistics & Supply Chain Management at Northern Business School and Future Thinkers Academic Chair for Middle East and Europe. The key questions: Can AI make quality and reliability as easy to compare as price? Who remains accountable when algorithms shortlist? And what must providers do now to turn awareness into action before the next tender lands?
QUESTION 5
How ready are logistics service providers?
80%
“Aware, but not acting”
28 Aware, but not acting 6 Barely aware 1 Completely unprepared 0 Well prepared QUESTION 6
What happens to the shipperprovider relationship? WO R S E
At Breakbulk Asia: Future Thinkers Spotlight: The Future of Tender Management
SAME
12
9
12 More transactional, less trust
Thursday, Nov. 19 Breakbulk Live Stage 12:15pm - 1:00pm
9 No real change 9 Fewer, deeper partnerships 5 Fairer and more transparent
Only 5 see AI making tendering fairer
29 Breakbulk Magazine
Issue 4 2026
breakbulk.com
BETTER
9
5
Breakbulk Americas Education Day
BUILDING THE NEXT GENERATION OF MARITIME LOGISTICS PROFESSIONALS
By Cassia B. Galvao and Margaret A. Kidd
Breakbulk Americas Education Day continues to strengthen its role as a bridge between industry and education, bringing together students, educators and maritime logistics professionals to develop the next generation of talent. In 2026, the program reached new milestones, not only in participation, but also in the breadth of students involved and the opportunities created for direct engagement with industry. The interest in Education Day reached a new record, with 588 student and educator registrations in 2026, up from 513 in 2025, a 14.6% increase. Education Day itself welcomed 305 students and educators compared with 288 the previous year, while total student and educator attendance at Breakbulk Americas increased from 368 to 443, a remarkable 20.3% increase. Behind these numbers is an important story: Students are increasingly recognizing the value of engaging with industry before graduation, while maritime and logistics organizations are demonstrating their commitment to helping prepare the workforce they will need in the years ahead. This year also marked an important expansion in the reach of the program. For the first time, high school students
Speed mentoring was introduced for the first time at Breakbulk Americas. Credit: Marco Wang Photography
L-R: Cassia Galvao (co-chair of Education Day), Rubie Drake (Hyve), Ivy Jenkins (co-chair from 2027), Margaret A. Kidd (co-chair). Credit: Marco Wang Photography
participated in the Education Day poster competition, introducing younger students to maritime logistics, project cargo and the broader supply chain ecosystem. Their participation represents an important step toward building awareness of maritime careers earlier in the educational pipeline. The poster competition also expanded opportunities at the other end of the academic spectrum. Cash prizes were extended to graduate students, recognizing the increasingly sophisticated research and ideas being brought to Breakbulk Americas by students at different stages of their education. Together, the participation of high school, undergraduate and graduate students demonstrates the potential for Education Day to connect multiple stages of the maritime talent pipeline. Another major addition in 2026 was the introduction of speed mentoring, designed to move industry engagement beyond traditional presentations and create opportunities for genuine conversation. More than 30 working professionals in leading positions across maritime logistics organizations volunteered their time to participate. Students met with professionals in small groups, allowing them to ask questions, hear candid perspectives on career development and learn directly from people working across the industry.
30 Breakbulk Magazine
Issue 4 2026
breakbulk.com
The winners of the Education Day poster competition gather on stage at Breakbulk Americas. Credit: Marco Wang Photography
The initiative complemented the new session, “Being Industry-Ready: The Unspoken Rules for Professional Success,” which focused on an important dimension of workforce preparation: the professional skills and knowledge that are not always found in textbooks. Communication, relationship building, workplace expectations, professional credibility and career decision-making are learned in large part through interaction with experienced professionals. These conversations reflect one of the central purposes of Education Day. Universities provide students with knowledge, analytical capabilities and technical foundations. Industry provides another essential dimension: exposure to the realities of professional practice. Bringing the two together helps students connect what they learn in the classroom with the careers, challenges and opportunities they will encounter after graduation.
Students listen to a presentation during Education Day. Credit: Marco Wang Photography
The success of 2026 is already providing momentum for the next chapter. Planning for Education Day 2027 is underway, with two important new additions to the leadership team. San Jacinto College and the Port of Houston Partnership for Maritime Education (PHPME) will participate directly in the planning process, with Jacqueline Young and Ivy Jenkins joining the Education Day team as co-chairs. This collaboration will further strengthen connections among educators, students and Houston’s maritime community. The continued growth of Education Day demonstrates something fundamental about workforce development: preparing the next generation is a shared responsibility.
Students speak to project professionals on the show floor in Houston. Credit: Marco Wang Photography
Maritime logistics is ultimately an industry of people. Creating opportunities for students to meet those people, learn from their experiences, share their own ideas and begin seeing themselves as members of the professional community is what makes Education Day more than an event; it makes it an investment in the future of the industry!
About the Authors
Cassia Bomer Galvao is associate professor, Department of Maritime Studies Texas A&M University at Galveston. Margaret A. Kidd is department chair, Business, Logistics and Supply Chain Management at San Jacinto College.
31 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Waves of Cargo
FIVE RTGS, TWO QUAY CRANES, ONE PROJECT
In the second Waves of Cargo project in this edition, John He, general manager at Shanghai Hamel Supply Chain Technology, takes us behind the scenes of an operation to transport a shipment of heavy cranes from China to Indonesia. He explains the vessel selection, loading methodology and challenges the team overcame to deliver the cargo safely and on schedule.
Q: Can you give an overview of Q: Why was the company’s self-owned decker Yong Ao the project and its objectives? Guo Ji selected for this project? What characteristics of the vessel made it suitable for transporting this John He: The purpose of particular combination of RTGs and port cranes? the project was to ship five rubber-tired gantry cranes JH: Yong Ao Guo Ji is our self-owned decker for (RTGs) and two quay cranes international shipping projects. The vessel is suitable for from the southern Chinese city a wide range of oversized and heavy-lift cargoes and can of Zhuhai to the Indonesian meet the loading requirements for large port machinery capital, Jakarta, to ease and equipment. pressure on the Port of Jakarta and strengthen its loading Q: What special lifting equipment, spreaders, lifting capacity. beams or other project-specific gear did the cargo John He require during loading? Q: Why was the Zhuhai–Jakarta route selected for this shipment? JH: We employed a specific loading methodology: The RTGs drove onto the vessel under their own power. The JH: The manufacturer is located in Zhuhai and has its own bulk components of the quay cranes were loaded using pier for loading and unloading, making our own decker the the SPMT (self-propelled modular transporter) sidebest choice due to its sufficient flexibility. rolling method. Other smaller and looser parts were lifted onboard by cranes. Given the overall height of the cargo, Q: What were the dimensions and weights of the five RTGs we deployed supports, chocks, steel wire ropes and other and two port cranes? fittings for lashing and securing during operations to ensure stability. JH: Each RTG measured 26.6 x 12.2 x 29.2 meters and weighed 166 tons, while the bulk components of the port cranes measure 27.0 x 1.84 x 6.39 meters and weighed 105 tons.
32 Breakbulk Magazine
Issue 4 2026
breakbulk.com
A tug guides the Yong Ao Guo Ji at Zhuhai before its onward journey to Jakarta. Credit: Shanghai Hamel
Q: What were the biggest challenges encountered during the planning or execution of the project?
The RTGs await loading at a laydown zone in Zhuhai. Credit: Shanghai Hamel
JH: The project was originally scheduled to ship just the five RTGs. Accessories for the quay cranes were added later on an ad-hoc basis. Our team immediately coordinated with the factory to adjust the loading and stowage plan, making every effort to keep the vessel’s departure on schedule while ensuring safe operations. Q: Looking back at the project, what are you most proud of? JH: Despite the challenge of additional over-dimensional cargo being added at short notice, the project team completed the loading operations safely and efficiently, ensuring that the customer’s demanding delivery timeline was met. Shanghai Hamel Supply Chain Technology is an exhibitor at Breakbulk Europe.
33 Breakbulk Magazine
Issue 4 2026
breakbulk.com
MOVING COMPLEX CARGO. CONNECTING GLOBAL SUPPLY CHAINS. From port operations and maritime services to integrated logistics, DP World brings together the expertise and global network to move complex project cargo safely, efficiently and reliably.
VISIT US AT STAND L10
OUTLOOK 2027:
ASIA · MIDDLE EAST · EUROPE · AMERICAS By Simon West
PERSPECTIVES ON THE YEAR AHEAD Featuring commentary from: Al Faris, AAL Shipping, BBC Chartering, Chinaland Shipping, Combi Lift Projects, deugro, Fracht Group, JGC Corporation, Mitsubishi Power, Project Logistics Engineering Solutions, Rhenus Project Logistics, Trans Global Projects, UTC Overseas
BBC Houston passes through St. Lambert Lock, Canada, with a full shipload of wind turbine blades. Credit: BBC Chartering
35 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Outlook Asia
ASIA’S PROJECT PIPELINE HOLDS STRONG
We begin our global outlook in Asia, where industry executives assess opportunities, challenges, shifting trade routes and emerging disruptions
Looking ahead to 2027, how would you describe the business outlook for Asia’s breakbulk and project cargo sector? Ling Ling Lim, managing director, Trans Global Projects Malaysia: The outlook remains positive, although growth will vary considerably between markets and sectors. Energy, infrastructure and industrial investment continue to create opportunities for project cargo across Asia. Southeast Asia in particular is expected to maintain solid economic growth in 2027. At the same time, geopolitical tensions, energy costs and trade uncertainty mean that project decisions and schedules may remain less predictable. For logistics providers, this creates a market with good underlying demand, but one that requires flexibility and strong local knowledge.
Ling Ling Lim, Trans Global Projects
Koichi Kaizu, JGC
Bobby Zhu, Chinaland Shipping
Koichi Kaizu, logistics subject matter expert for module transportation, JGC: Demand is expected to remain strong, driven by liquefied natural gas (LNG), energy transition and industrial projects requiring large-scale module transportation across Asia.
expect an uneven market, with stronger opportunities for carriers that can match suitable tonnage with customers’ delivery requirements.
Bobby Zhu, managing director, Chinaland Shipping: I am cautiously optimistic about Asia’s breakbulk and project cargo outlook for next year. Asia combines a substantial industrial investment pipeline with the manufacturing capacity to supply projects worldwide. From a Chinese shipowner and operator’s perspective, opportunities will come from both equipment exports and growing demand within Asia. However, project announcements will not all translate into shipments on schedule. Financing, approvals and execution will determine actual volumes. We
36 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Dharmendra Gangrade, a thought leader on global shipping and logistics: My view for 2027 is cautiously optimistic. I expect Asia, with India and the Middle East playing increasingly important roles, to remain one of the strongest markets for breakbulk and project logistics. Investments in energy, infrastructure, manufacturing and the energy transition should sustain cargo volumes. However, I believe the real issue will be predictability rather than demand. Geopolitical developments, specialized vessel availability and infrastructure constraints will keep challenging schedules and costs. For cargo owners, resilience and execution certainty will matter as much as freight competitiveness.
Outlook Asia
Dharmendra Gangrade
Which sectors or specific projects do you expect to be the biggest drivers of the region’s breakbulk and project cargo volumes in 2027? LL: Power and energy should remain among the main sources of project cargo demand. Across Southeast Asia, investment in power generation, grids, renewable energy and battery energy storage systems (BESS) is creating opportunities, alongside gas and LNG infrastructure. Malaysia is also seeing strong data center development, bringing further demand for power infrastructure and associated equipment. Industrial development, infrastructure and steelrelated cargo should provide additional opportunities. Together, these sectors should support a diverse project cargo market across the region in 2027. KK: LNG, petrochemicals, renewable energy and mining projects will have steady demand. In addition, data center projects will generate significant project cargo volumes on top of those conventional projects.
“EARLY INTEGRATION OF ENGINEERING, SOURCING, LOGISTICS, PORTS AND CARRIERS WILL INCREASINGLY DETERMINE BOTH PROJECT COST AND SCHEDULE RELIABILITY.” DHARMENDRA GANGRADE Chinese equipment suppliers will remain important to projects across Asia and beyond. Data centers could also generate demand through their power and cooling infrastructure. For 2027 planning, I would focus on projects with committed funding and clear equipment delivery schedules. DG: I see energy, infrastructure and industrial investment as the major demand engines. India’s investments in renewables, power transmission, hydrocarbons, heavy manufacturing and infrastructure will generate sizeable project movements. I also expect increasing movement of equipment between Indian manufacturing clusters and Middle Eastern projects, particularly heavy engineering, power, process-industry and fabricated equipment, strengthening the IndiaGulf project logistics ecosystem. What do you see as the biggest challenges facing the sector in Asia over the coming year?
LL: Uncertainty remains the biggest challenge. Geopolitical tensions can quickly affect shipping routes, fuel costs and supply chains, while extreme BZ: I would put power and grid weather and trade-policy changes investment high on the list, alongside add further pressure. Southeast Asia’s wind energy, industrial plant construction dependence on imported energy and and mineral processing. For breakbulk concentrated supply routes also leaves carriers, the cargo opportunities include the region exposed to disruption. For transformers, wind turbine components, project logistics, where cargo often heavy machinery and prefabricated requires specialist equipment and modules. Southeast Asia’s manufacturing careful planning, changes can have expansion and India’s infrastructure significant operational consequences. investment deserve attention, while Maintaining alternative routing options
37 Breakbulk Magazine
Issue 4 2026
breakbulk.com
and involving logistics teams early in project planning will therefore become increasingly important. KK: Limited heavy-lift assets and geopolitical uncertainty remain key challenges. We are also concerned about the continuous port congestion in all major ports in Asia, which presents us with further uncertainty for scheduling or resourcing vessels. BZ: It’s maintaining delivery certainty when project schedules, trade rules and voyage costs can all change. For carriers, a delayed cargo can disrupt several subsequent commitments, particularly when specialized tonnage has been positioned in advance. Larger components also put pressure on port handling, inland transport and engineering capabilities. Meanwhile, cargo growth does not automatically mean stronger earnings: vessel supply and competition still matter. We need to price operational risk properly and understand the readiness of the entire transport chain before committing capacity. DG: For me, the biggest challenge is managing uncertainty without compromising project commitments. Geopolitical disruption can change routing, vessel availability, insurance exposure, transit time and freight economics very quickly. At the same time, project cargo is becoming larger and more complex, while port and hinterland capabilities do not always develop at the same pace. My experience is that logistics can no longer be
does not always offer easy alternatives once a movement has started, so detailed preparation and the ability to adjust plans before problems become critical are increasingly important.
Trans Global Projects (TGP) managed the handling and loading of 12 evaporators and condensers in Malaysia as part of an international project cargo movement to Australia. Credit: TGP
treated as an activity that starts after procurement. Early integration of engineering, sourcing, logistics, ports and carriers will increasingly determine both project cost and schedule reliability. How are changing trade routes, sourcing strategies and supplychain relationships affecting project cargo flows in and out of the region? Are you seeing new trade corridors or emerging markets that could become more important in 2027? LL: We are seeing supply chains become more diversified rather than simply shifting from one location to another. China remains highly important, while Southeast Asia is developing further as both a manufacturing base and a destination for investment. Growing intra-Asian trade and closer links with markets including India, Australia and the Middle East are also creating a broader network of project cargo flows. For logistics providers, this means being able to connect multiple origins, destinations and transport modes rather than relying on established corridors alone. KK: Growing local content requirements are influencing sourcing strategies. In some countries, expectations exceed local industrial and logistics capabilities, creating major challenges for efficient project execution and cargo movements. BZ: Supply-chain diversification is creating additional cargo movements within Asia. New factories in Southeast Asia still need imported production equipment, often from China, while regional fabrication adds new origins for project shipments. We expect ChinaSoutheast Asia links to deepen, with
KK: Disruption is forcing EPC contractors such as JGC to prioritize India also becoming more important as supply chain resilience over pure both a destination and a manufacturing cost optimization. Thus, diversified base. Beyond Asia, routes serving Middle sourcing, earlier logistics integration Eastern and African projects warrant and greater execution flexibility will attention, subject to security and become key competitive advantages financing conditions. For carriers, more for us — this would be my message dispersed sourcing increases the value of to the breakbulk industry. flexible port coverage and coordination across multiple loading points. BZ: We need to build contingency planning into the original transport DG: I see a clear move from cost-led solution. That means assessing sourcing toward resilience-led sourcing. alternative ports and routes, allowing Companies are looking more closely realistic schedule buffers, and at total landed cost, geopolitical agreeing how additional costs will be exposure, lead-time certainty and handled before disruption occurs. alternative supply bases. India is Ship operators, forwarders and cargo becoming increasingly relevant as both owners should engage earlier, while a manufacturing and project-export equipment dimensions and delivery hub, while Saudi Arabia, the UAE and sequences can still be adjusted. Oman are building deeper local industrial Better shipment visibility helps, ecosystems. In my view, India-Gulf but experienced operations teams corridors, India-Africa via Middle and reliable local partners remain Eastern hubs, intra-GCC movements essential. Commercially, customers and stronger Southeast Asia-Indiaand carriers need arrangements Middle East linkages deserve particular that support reliable service through attention in 2027. These changes changing conditions. Flexibility has a will progressively reshape traditional cost, which should be recognized. Asia-centric project cargo flows. DG: From a cargo-owner perspective, With disruption becoming an resilience must now be engineered increasingly persistent feature of global into the project, not added when trade, how does the breakbulk and disruption occurs. For complex project cargo sector need to adapt? breakbulk and project cargo, the ability to switch routes, gateways or LL: The industry needs to treat transport solutions cannot be created disruption as part of project planning overnight. It requires early logistics rather than as an exception. That means involvement, optionality in supplyassessing alternative routes, ports and chain design and deeper strategic transport options early, monitoring relationships with carriers, ports and developments closely and maintaining logistics partners. Digital visibility strong local relationships across the is important, but visibility without supply chain. Communication is equally response capability has limited value. important: clients need to understand In an increasingly volatile environment, quickly how changes may affect execution certainty will become a schedules and costs. Project cargo competitive advantage in its own right.
38 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Outlook Middle East
KEEPING GULF PROJECTS MOVING AMID DISRUPTION
In the Middle East, industry executives assess a strong project pipeline, rising demand for heavy-lift services and the challenges of navigating ongoing disruption Steffen Behrens, deugro
Mohammad Jaber, Combi Lift Projects
Kieve Pinto, Al Faris
Looking ahead to 2027, how would you describe the business outlook for the Middle East’s breakbulk and project cargo sector?
Mohammad Jaber, CEO, Combi Lift Projects MEA: Cautiously bullish, from where we sit as the ones actually moving the cargo. The project pipeline financed over the last few years is now hitting the execution phase, which means more RFQs for engineered transport, not fewer. What’s changed is what clients expect from a logistics partner: route surveys and contingency plans up front, not a quote and a hope. 2027 rewards carriers who can flex when a berth slot or a road permit falls through.
commitment to energy, infrastructure and industrial development remains, and the project pipeline across the GCC is still very substantial. I expect 2027 to be shaped by two forces: the restart of projects that were paused or slowed, and the repair and reinstatement of existing energy and industrial infrastructure. Both will demand heavier, more complex lifts on tighter schedules. The companies that succeed will be those with the engineering depth, equipment and people to execute reliably when conditions are anything but predictable.
Credit: Al Faris
Steffen Behrens, CCO, deugro: The outlook remains overall very positive, but to some degree we also need to be patient. While geopolitical tensions and supply chain disruptions have added complexity, the Middle East continues to offer one of the strongest project pipelines globally. We are now seeing major investments and especially final investment decisions (FIDs) in oil and gas, LNG and petrochemicals. There will certainly be lots of demand for repair jobs and therefore creating sustained demand for heavy-lift and project logistics services. We expect the UAE and Saudi Arabia to remain the primary growth engines, supported by increasing activity in Oman and Qatar as governments continue to invest in energy security and industrial diversification.
Kieve Pinto, CEO, Al Faris: I am optimistic about 2027, but it is a measured optimism, and anyone working in this region has to be honest about the year we have just come through. The conflict and the disruption to shipping through the Strait of Hormuz have delayed project timelines, damaged critical energy assets and made investors more cautious. Yet the fundamentals have not changed. The region’s
39 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Which sectors or specific projects do you expect to be the biggest drivers of breakbulk and project cargo volumes in the Middle East in 2027? SB: Energy will remain the dominant driver. In Saudi Arabia, projects linked to Aramco’s gas expansion strategy, including Jafurah and associated processing facilities, will generate
Outlook Middle East
“WHAT’S CHANGED IS WHAT CLIENTS EXPECT FROM A LOGISTICS PARTNER: ROUTE SURVEYS AND CONTINGENCY PLANS UP FRONT, NOT A QUOTE AND A HOPE.” MOHAMMAD JABER significant cargo volumes. In the UAE, ADNOC’s ongoing investments in gas, LNG, carbon capture and offshore developments will continue to create demand for complex logistics solutions. We also see growing momentum in power transmission, grid expansion, battery storage and certain green hydrogen developments, particularly in Saudi Arabia and Oman, where large-scale industrial projects are moving from planning to FID. MJ: We’re quoting more moves tied to power generation and grid infrastructure, such as transformers, turbines and battery enclosures, rather than traditional oil and gas modules these days. Petrochemical plant expansions and downstream units are still steady work, and Red Sea and Gulf coastal construction keeps adding civil and marine cargo to our books. From a transport-planning point of view, the shift is toward heavier, more awkward single-lift pieces than we were handling five years ago. KP: Energy will remain the biggest driver, but with a different emphasis than a year ago. Alongside new oil and gas, petrochemical and LNG capacity, including major expansions such as Qatar’s North Field program, I expect a significant volume of work in rehabilitating and reinstating damaged facilities. That often means replacing heavy, long-lead components such as transformers, compressors, reactors and columns under urgent timelines. Power generation and transmission will be a close second, as utilities strengthen grid resilience and continue adding renewable capacity. Saudi Arabia, given the scale of its pipeline, will remain the largest market, while the UAE, Oman and Qatar will each contribute significant activity.
I would also highlight infrastructure that improves supply-chain resilience, such as ports, rail and logistics links that offer alternative routes into the region. Across all of these, modular construction will keep pushing component sizes and weights upward, increasing demand for self-propelled modular transporters (SPMTs), high-capacity cranes and engineered lifting solutions. What do you see as the biggest challenges facing the sector in the Middle East over the coming year? SB: The biggest challenge is no longer just securing projects but executing them efficiently in an increasingly constrained and difficult environment. We are facing vessel availability issues, skilled labor shortages, pressure on transport infrastructure, rising compliance requirements and continued schedule acceleration by project owners. At the same time, geopolitical developments have increased uncertainty around routing, transit times and project planning. The companies that will succeed are those able to combine in-house engineering expertise, local execution capability and contingency planning rather than relying solely on available transportation capacity. MJ: Equipment and crew availability, plainly. Heavy-lift vessels, SPMTs, cranes and the rigging teams who know how to use them haven’t grown at the same rate as project awards, so lead times on booking specialized transport are stretching. Add port congestion at key hubs and slower permitting for oversized road convoys, and there’s very little margin left for the kind of quick turnaround clients used to take for granted. Whoever books capacity early wins the year.
40 Breakbulk Magazine
Issue 4 2026
breakbulk.com
KP: The most immediate challenge is operating in an environment where the security and shipping picture can change from week to week. Restricted access through the Strait of Hormuz and pressure on Red Sea routes affect not only when cargo arrives, but where it arrives, and that has knock-on effects for inland transport, permits and site schedules. Insurance, freight and material costs have also risen, putting pressure on project budgets at exactly the moment clients need to move faster. Beyond geopolitics, the structural challenge remains execution capability. Heavy cargo movements depend on route surveys, ground conditions, engineering approvals and coordination between many stakeholders, and none of these can be rushed. Skilled people are another constraint, as experienced engineers, riggers and operators are in short supply across the region. My concern is that urgency must not outpace planning. Early engineering involvement and realistic schedules will matter more than ever. How is your company responding to the continued uncertainty around the Strait of Hormuz and wider regional shipping and geopolitical risks? SB: Over the past year, resilience has become a core element of project logistics planning. We have expanded our contingency planning, assessed alternative corridors through Oman, Saudi Arabia and the UAE east coast, increased our focus on multimodal solutions and strengthened cooperation with clients during the front-end engineering design (FEED) stages of projects. The key lesson from recent disruptions is that logistics must be integrated into project planning much earlier.
Outlook Middle East
By combining transport engineering, route studies, marine solutions and alternative routing strategies, we help clients maintain project continuity even under challenging conditions. MJ: We stopped treating the strait as a given a while back. Every routing plan we put together now includes a prequalified alternative through Fujairah, Duqm or Jeddah, and we’re holding more buffer in our schedules for clients’ time-critical components. We’ve also started building delay and diversion clauses into our contracts up front rather than negotiating them mid-crisis. Clients increasingly expect their logistics partner to have already gamed this out, not to be scrambling when it happens.
alternative route surveys, permit preparation and close communication with clients and authorities, so that if one option closes, another is already engineered. Above all, the safety of our people is non-negotiable. When circumstances change quickly, the ability to adapt the execution plan without compromising safety or reliability is what our customers value most. What is one development or trend in the Middle East project cargo market that you expect to have a much bigger impact in 2027 than the industry is currently anticipating?
SB: I believe the accelerated development of logistics infrastructure designed to bypass traditional maritime KP: Our approach has been to stay chokepoints will have a bigger impact focused on what we can control. In than many currently expect. Investments practical terms, that means working with in Fujairah, GCC rail connectivity, customers much earlier to assess routing Oman logistics corridors and eastoptions, including cargo discharged coast energy export infrastructure are at ports outside the Gulf and moved being driven not only by growth but overland. This places heavier demands increasingly by resilience and therefore on road transport, route engineering long-term reliability considerations. and cross-border coordination, and These developments will gradually it is exactly where a land-side heavy reshape cargo flows, project execution transport and lifting specialist adds strategies and industrial investment value. Our operations across the GCC decisions across the region. For help us here, because we can assess project logistics providers, this could conditions on the ground in several be as transformative as any individual markets and position equipment and energy megaproject, but we need to be teams where they are needed. We have mindful that there is space for private also strengthened our contingency companies like ourselves who invest in planning: equipment readiness, the individual countries and regions.
MJ: In-country localization rules. Governments are pushing harder for fabrication and assembly to happen onshore instead of shipping in finished units. For us that doesn’t mean less cargo; it means a different cargo mix: more inbound components and raw materials, less outbound finished equipment. Carriers still planning their 2027 fleet and route capacity around the old cargo profile are going to find themselves poorly positioned. KP: I believe the shift toward modularization will have a far bigger impact than many expect, and recent events will accelerate it. When supply routes are uncertain and site labor is under pressure, there is a strong case for doing more fabrication in controlled yards and delivering larger, more complete modules to site. That reduces on-site risk, but it moves complexity into transport and installation. Modules are getting larger and heavier, and the methodology for moving and setting them now has to shape project design from the earliest stages rather than be solved at the end. This will drive demand for SPMTs, hydraulic trailers, gantry systems and integrated lifting solutions, and for the engineers who can plan them. I expect 2027 to reward companies that combine engineering expertise with the equipment capacity to deliver, and that are brought into projects at the concept stage, not just the execution stage.
Al Faris Group recently added 100 new conventional hydraulic trailer axle lines, taking its fleet beyond 350 axle lines. Credit: Al Faris
41 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Outlook Europe
A TWO-SPEED MARKET TAKES SHAPE
In Europe, executives explore the opportunities created by the region’s energy transition and infrastructure investment alongside ongoing challenges in traditional export markets Felix Schoeller, AAL Shipping
Ruedi Reisdorf, Fracht Group
Ulrich Ulrichs, BBC Chartering
Looking ahead to 2027, how would you describe the business outlook for Europe’s breakbulk and project cargo sector?
positive. Demand is being supported by substantial investments in energy infrastructure, grid expansion, industrial modernization and strategic supply-chain resilience. While freight markets may remain cyclical, the underlying project pipeline is strong. The defining trend for 2027 is that project logistics is no longer just about moving cargo. It is about managing risk, securing critical supply chains and enabling Europe’s energy and industrial transformation.
Which sectors or specific projects do you expect to be the biggest drivers of breakbulk and project cargo volumes in 2027?
Felix Schoeller, chief commercial officer, AAL Shipping: Europe’s project cargo market is entering 2027 on a two-speed footing. Import demand remains the bright spot, driven by renewable energy investment and broader energy security priorities, which continue to support steady volumes into our Super B-Class fleet. Export remains more challenging, however, as the Persian Gulf, a key traditional market for European EPCs, machinery and steel makers, stays largely inaccessible, leaving Europe’s export project cargo outlook considerably more subdued. Ruedi Reisdorf, owner, Fracht Group: The outlook for Europe remains
Ulrich Ulrichs, CEO, BBC Chartering: I would describe the overall situation as stable and generally satisfactory, but not exceptionally positive. We continue to see renewable energy cargoes moving inbound and outbound, alongside outbound industrial goods including cables, transformers and engines.
42 Breakbulk Magazine
Issue 4 2026
breakbulk.com
FS: Renewable energy, especially offshore wind, remains Europe’s single biggest volume driver, alongside conventional power generation and data-center builds. We also expect defense-related infrastructure upgrades (ports, rail and dual-use corridors being reinforced for military mobility) to generate meaningful project cargo, as networks built to lighter commercial standards are brought up to heavier load capacity. Nuclear new-build and life-extension projects across the UK, France and Eastern Europe should add further momentum. RR: We expect power transmission and grid infrastructure to be among the
Outlook Europe
AAL Shipping’s Super B-Class AAL Newcastle. Credit: AAL Shipping
strongest volume drivers, alongside renewable energy, conventional power generation, battery storage and large industrial investment programs. Data centers are emerging as a major indirect driver, creating significant demand for transformers, substations and energy infrastructure. We also see continued activity in mining, metals, chemicals and selected oil and gas projects where energy security remains a strategic priority. UU: Renewable energy projects will clearly be the main driver of cargo volumes in 2027. We expect demand to remain strong worldwide, also in Europe. In terms of trade flows, we currently anticipate import cargoes to outweigh exports.
“RENEWABLE ENERGY, ESPECIALLY OFFSHORE WIND, REMAINS EUROPE’S SINGLE BIGGEST VOLUME DRIVER, ALONGSIDE CONVENTIONAL POWER GENERATION AND DATA-CENTER BUILDS.” FELIX SCHOELLER
Europe is investing heavily in energy security, infrastructure and domestic industrial capacity. What impact do you expect these priorities to have on breakbulk demand in 2027?
is accelerating offshore wind, LNG and grid-scale battery storage projects, while renewed industrial and defense investment is upgrading ports, bridges and rail links to handle heavier, oversized loads. This dual-use infrastructure is being built closer to project cargo specifications than ordinary freight standards, which should mean better accessibility and sustained demand for specialist heavy-lift tonnage like our 800-tonnecapable Super B-Class vessels.
the breakbulk and project logistics sector. New power plants, transmission networks, transformer programs, manufacturing facilities and energytransition projects require oversized and heavy-lift equipment. Beyond increasing cargo volumes, they also drive demand for engineering, route studies and specialized transport solutions. We expect energy-security and reindustrialization initiatives to remain among the sector’s most important growth drivers in 2027.
FS: These priorities are a clear positive for breakbulk. Energy security
RR: These investments create exactly the type of cargo that moves through
UU: While Europe’s focus on energy security, infrastructure and industrial
43 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Outlook Europe
resilience should, in theory, support breakbulk demand, we currently see only a limited impact from these investments. Renewable energy projects we indeed see a lot, but other goods suffer from “green deal” commitments of the EU and its member states. The European industry is facing increasing challenges from high energy costs and regulatory requirements such as EU Emissions Trading System (ETS) and FuelEU Maritime, which add costs and administrative complexity. As a result, some production is shifting within Europe or relocating outside the EU altogether. In addition, strong investment activity in markets such as the U.S. and China, particularly in data centers and AI-related infrastructure, appears to be attracting a larger share of industrial cargo demand than Europe at present. What do you see as the biggest challenges facing the sector over the coming year? FS: Tightening environmental regulation, including FuelEU Maritime and the EU ETS, is raising operating costs just as port and inland bottlenecks add delay to project execution. Geopolitical instability around the Middle East and Baltic corridors continues to disrupt routing. For AAL, the defining challenge is balancing decarbonization investment — we’ve cut fleet Energy Efficiency Operational Indicator (EEOI) by nearly 20% since 2023 — with the heavy-lift flexibility our customers depend on.
RR: The main challenges are uncertainty and complexity rather than a lack of demand. Geopolitical tensions, sanctions, trade restrictions and changing regulations continue to reshape supply chains. At the same time, skilled labor shortages, infrastructure constraints, permitting requirements and increasing sustainability obligations add pressure. Successful project logistics providers will be those that manage risk proactively, maintain operational flexibility and remain close to customers throughout the project lifecycle. UU: The biggest challenges are likely to come from geopolitical and regulatory developments. Ongoing conflicts in the Persian Gulf region and Eastern Europe, as well as the continued security situation in the Red Sea, have the potential to disrupt trade flows and increase transportation costs. In addition, tariffs, potential U.S. regulatory measures affecting shipping, Office of the U.S. Trade Representative (USTR), and a growing number of trade and transit restrictions worldwide, including constraints at the Panama Canal, continue to create uncertainty for global supply chains. In such an environment, maintaining flexibility and reliability will remain essential for all market participants. With global trade routes and supply chains being reshaped by geopolitical tensions, tariffs and sanctions, how is the European breakbulk and project cargo sector adapting?
“WE EXPECT ENERGY-SECURITY AND REINDUSTRIALIZATION INITIATIVES TO REMAIN AMONG THE SECTOR’S MOST IMPORTANT GROWTH DRIVERS IN 2027.” RUEDI REISDORF 44 Breakbulk Magazine
Issue 4 2026
breakbulk.com
FS: Flexibility and compliance have become essential. With safe export to the Persian Gulf and Black Sea no longer possible, and the U.S. market increasingly difficult to sell into, European shippers are actively seeking new markets. AAL is responding with early communication and planning alongside our regulators and customers, and the operational flexibility of our global fleet and office network to redirect cargo quickly as trading patterns shift. RR: The industry is adapting by placing greater emphasis on resilience, flexibility and contingency planning. Alternative routings, diversified sourcing strategies and earlier logistics involvement have become standard practice on many major projects. Customers increasingly recognize that the lowest transportation cost is not always the lowest total project cost. As a result, project logistics providers are evolving into strategic risk-management partners, helping customers navigate uncertainty while maintaining reliable project execution. UU: The European breakbulk and project cargo sector has become accustomed to managing crises and adapting quickly to changing market conditions. This has already been visible in recent years, when it comes to geopolitical disruptions, supply chain challenges or regulatory changes. However, several industries in Europe are coming under increasing pressure from higher energy costs, limited access to certain raw materials and the growing cost burden associated with environmental regulations. These factors are already affecting industrial competitiveness and investment decisions, and their impact is likely to be felt across the wider breakbulk and project cargo sector in the years ahead.
Outlook Americas
KEEPING PACE WITH SURGING DEMAND
In the Americas, project professionals see rising demand driven by energy, infrastructure and industrial investments alongside growing pressure on logistics capacity and looming bottlenecks in Panama
Looking ahead to 2027, how would you describe the business outlook for the breakbulk and project cargo sector in the Americas? Agustin Harriague, VP, Logistics and Supply Chain Operational Excellence, Mitsubishi Power: I remain very optimistic about the outlook for 2027. We are seeing sustained investment across power generation, transmission, industrial manufacturing, LNG, mining and digital infrastructure. Demand for reliable energy continues to accelerate, fueled by electrification, AI, data centers and industrial growth. The opportunity is significant, but it will also bring greater complexity. In project logistics, certainty is becoming just as valuable as capacity. Success will increasingly depend on early planning, integrated supply chains and reliable execution.
Agustin Harriague, Mitsubishi Power
“PANAMA IS CARRYING A ROUTING BURDEN IT WAS NEVER DESIGNED TO ABSORB ALONE. WITH HORMUZ EFFECTIVELY CLOSED SINCE THE WAR BEGAN AND THE RED SEA STILL IMPAIRED, PANAMA IS THE LAST MAJOR SHORTCUT WORKING.” MARCO POISLER Kevin Kwateng, heavy-lift and transport consultant, Project Logistics Engineering Solutions (PLES): Absolutely bullish. AI is pushing power demand faster than the grid can keep up, and the entire energy chain is being rebuilt at the same time. That is not a one-year spike; it is a cycle that will run for years. Demand for heavy transport is rising across every
mode, road, rail and barge. For the first time in a long time, the limit on our industry isn’t the amount of work available. It’s the capacity to deliver it.
Kevin Kwateng, Project Logistics Engineering Solutions (PLES)
Marco Poisler, UTC Overseas
45 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Marco Poisler, COO, Global Energy and Capital Projects, UTC Overseas: It’s complicated, with real upside sitting behind a logistics constraint. The Americas’ energy buildout of
Outlook Americas
Luis Rodriguez, Rhenus Project Logistics
terminals, grid infrastructure and data centers keeps generating heavy project cargo. Panama is carrying a routing burden it was never designed to absorb alone. With Hormuz effectively closed since the war began and the Red Sea still impaired, Panama is the last major shortcut working. The National Oceanic and Atmospheric Administration (NOAA) now gives near-certain odds of a very strong El Niño by year-end. Luis Rodriguez, director of project logistics, LATAM, Rhenus Project Logistics: We see a positive outlook for the breakbulk and project cargo sector across Latin America, driven by continued investment in energy transition, mining, infrastructure and industrial expansion projects throughout the region. These largescale developments are becoming increasingly complex, creating greater demand for integrated logistics solutions that can coordinate multimodal transportation, specialized equipment and end-toend project execution. We expect particularly strong opportunities in markets investing heavily in renewable energy, infrastructure modernization, mining, oil and gas, and technology-driven developments such as data centers and supporting power infrastructure. These sectors will continue to generate significant demand for project cargo expertise and tailored logistics solutions.
Which sectors or specific projects do you expect to be the biggest drivers of cargo volumes in 2027? AH: Power generation and grid infrastructure will remain among the strongest drivers of project cargo demand. Utilities continue investing in new generation assets while expanding and modernizing transmission networks to improve reliability. Beyond energy, I expect continued growth from LNG, mining, advanced manufacturing and large industrial developments. Data centers may not generate all the project cargo themselves, but they are accelerating investment across the entire energy value chain by driving unprecedented demand for reliable electricity. KK: Data centers are the engine, and everything that powers them follows. That has created entirely new markets, led by battery energy storage systems (BESS), along with small modular reactors and a renewed push in nuclear, plus the transformers and transmission upgrades needed to connect it all to the grid. Wind and hydro remain strong, and aerospace and satellites are a growing source of oversized cargo. Each of these sectors feeds into or depends on the grid, and each one relies on heavy components that don’t fit on a standard truck. MP: U.S. data center and power generation lead, with grid-scale batteries and transformers close behind. The Gulf crisis has pulled Asian energy buying toward the U.S. Gulf, and through Panama. In August, SK Gas paid a record US$5.3 million at auction so its liquefied petroleum gas (LPG) carrier could skip a queue of up to 11 days. That demand squeezes capacity for breakbulk and multipurpose (MPP) cargo. Rebuilding energy infrastructure, now estimated by Rystad Energy at up to US$58 billion, will add major volume once routing stabilizes.
46 Breakbulk Magazine
Issue 4 2026
breakbulk.com
LR: We expect several sectors to be key drivers of project cargo volumes across Latin America in 2027. The energy sector will remain one of the most significant contributors, particularly through renewable energy projects such as solar, wind and battery energy storage systems as countries continue to invest in energy transition and grid reliability. Infrastructure will also be a major source of demand, with ongoing investments in rail and road development, port expansions and urban transportation projects aimed at supporting economic growth and improving regional connectivity. At the same time, the rapid expansion of the digital economy is driving substantial investment in data centers, telecommunications networks and the power infrastructure required to support them. What do you see as the biggest challenges facing the sector over the coming year? AH: The biggest challenge is not demand. It is execution. The industry is managing growing project volumes while navigating constraints across transportation capacity, specialized equipment, permitting, terminal infrastructure and skilled labor. At the same time, equipment continues to become larger and heavier, adding complexity throughout the logistics chain. Companies that invest in planning, engineering, digital visibility and strong partnerships will be better positioned to deliver execution certainty in an increasingly constrained environment. KK: Everything is being stretched to the maximum. Experienced people are retiring faster than new people can be properly trained, and the work is happening now. Equipment is scarce, especially in rail. Many companies are solving both problems through mergers, acquisitions and joint ventures, buying access to trained teams and fleets rather than building them. On top of that, permitting is
Outlook Americas
Project Logistics Engineering Solutions manages the transport of a heavy transformer in the U.S. Credit: PLES
getting harder as infrastructure ages. There simply aren’t enough companies, people or equipment for the volume of work coming. MP: Panama. The Panama Canal Authority cut daily transits to 34 on Sept. 3 and 32 on Sept. 15, the deepest cuts since the 2023-24 drought. Rain has since allowed a partial easing to 33 from today, but the canal says the water deficit persists. The real test is the 2027 dry season, January to May. Cargo fixed today for that window moves under contracts never stress-tested with all three shortcuts impaired at once. Who absorbs the queue, the auction premium and the Cape detour will be settled by the charter party wording. LR: One of the biggest challenges we are facing is that regulatory and customs requirements continue to
evolve across several Latin American markets, creating additional compliance obligations and potential delays if not managed proactively. At the same time, ocean freight markets remain volatile, influenced by geopolitical developments, weather-related disruptions and carrier network adjustments. This can impact both costs and schedule reliability for large-scale projects. We are also seeing constraints in some markets related to the availability of specialized equipment and heavyhaul transportation capacity, which can become critical for oversized or time-sensitive cargo movements. Infrastructure remains another challenge. While investment is increasing, port congestion and inland transportation bottlenecks can still affect project execution timelines and create additional complexity for moving project cargo. Finally,
47 Breakbulk Magazine
Issue 4 2026
breakbulk.com
customers continue to face pressure to control costs while maintaining the highest standards for safety, compliance and operational excellence. With tariffs and trade policy reshaping sourcing and investment decisions, what impact are you seeing on project cargo and industrial projects across the Americas? AH: Trade policy continues to influence sourcing strategies, procurement decisions and project schedules. While companies adapt to evolving regulations, the underlying demand for energy and industrial infrastructure remains strong. We are seeing organizations place greater emphasis on supply chain resilience through supplier diversification, regional manufacturing where practical and earlier procurement decisions. Flexibility,
Outlook Americas
“DATA CENTERS MAY NOT GENERATE ALL THE PROJECT CARGO THEMSELVES, BUT THEY ARE ACCELERATING INVESTMENT ACROSS THE ENTIRE ENERGY VALUE CHAIN.” AGUSTIN HARRIAGUE visibility and proactive planning have become essential capabilities for managing an increasingly dynamic global trade environment. KK: Honestly, I am not seeing a major effect overall. Some projects have taken a hit and a few no longer make financial sense under the new tariffs, so there are slowdowns in places. But there is so much work and so much potential across the Americas that, in the grand scheme of things, it doesn’t change the outlook. It’s business as usual, and business as usual right now means more than enough work to go around for everybody. MP: Tariffs are reshaping where capital projects source equipment, and that matters for routing. More Western Hemisphere manufacturing cuts some long-haul exposure but loads U.S. Gulf ports and the canal from the south. Equipment sourced from Asia to replace Middle Eastern supply transits Panama just as transit capacity is under pressure. Trade policy is driving sourcing shifts while El Niño restricts the canal, so the projects most affected by tariff-driven reshoring are also the most exposed to the canal constraint heading into 2027. LR: We are seeing customers diversify their supplier base and manufacturing locations to reduce risk and improve resilience, which is creating new trade lanes into the region as more equipment is sourced from alternative manufacturing hubs. At the same
time, longer procurement cycles and increased regulatory complexity mean that logistics planning needs to start much earlier, with greater visibility across the entire supply chain. We are also seeing trade policy shifts drive new industrial investments and nearshoring opportunities in selected markets, particularly where companies are looking to strengthen regional supply chains and serve key end markets more efficiently. For example, we have been seeing the growing participation of Chinese investors, EPC contractors and equipment manufacturers in large-scale infrastructure, energy, mining and industrial projects across Latin America, which is influencing sourcing strategies and project execution models.
KK: AI and technology. Modern problems deserve modern solutions. With people and equipment stretched this thin, the real question for 2027 is efficiency: how can the same team and the same fleet do more? Tools that automate surveys, engineering and planning will let companies take on more work without compromising safety, at least until the next wave of new people and new equipment catches up with demand. MP: The Panama Canal slot auction. Average Panamax premiums ran roughly 16 times year-ago levels in August, and the Neopanamax locks drew up to 15 bidders for a single slot. When transit is scarce, the canal allocates by price, and it now gives LNG and LPG carriers first call on canceled slots. Project cargo rarely wins that contest. The result for breakbulk is not a slower transit but no booked transit at all. The most important action before year-end is reviewing the canal-risk wording in every active and pending fixture while it can still change.
LR: We expect to see continued growth in renewable and energy transition projects across Latin America, alongside an expansion of mining activities driven by global demand for critical minerals. Significant What developments do you expect investments in rail, road, port and to have the biggest impact on the urban transportation infrastructure will project cargo market in 2027? continue to support growth across the region, while the rapid growth of data AH: The continued growth in electricity centers will drive additional investment demand will likely be the defining in power and supporting infrastructure. factor for our industry. AI, data centers, At the same time, digitalization is electrification and industrial expansion becoming increasingly important, are driving unprecedented investment with greater adoption of tools that across the energy value chain. At the provide end-to-end project visibility, same time, digital technologies are cargo tracking and risk management improving visibility and planning, while capabilities. We also anticipate sustainability and resilience continue continued development of strategic to influence how projects are executed. infrastructure and port capacity The companies that will lead in 2027 to support large-scale industrial will be those that combine operational projects and evolving trade patterns. excellence with long-term planning, collaboration, and the ability to adapt * Breakbulk Exhibitor quickly to changing market conditions. *Breakbulk Global Shipper Program participant
48 Breakbulk Magazine
Issue 4 2026
breakbulk.com
INDUSTRIALPROJECTS
WE SEE THE
BIGGER PICTURE DHL GLOBAL FORWARDING INDUSTRIAL PROJECTS
THE BIGGER PICTURE
FIG 01 ⮞
Our dedicated experts understand every detail of your project logistics needs - planning, coordinating and delivering the bigger picture for your peace of mind. Whether it’s an ad-hoc shipment or a full end-to-end industrial project, we deliver the highest levels of compliance, safety and expertise from early stages through to the final delivery.
DHL Global Forwarding – Excellence. Simply delivered.
Find out more
CARGO DIVERSITY, SHIPPING FLEXIBILITY.
atlanticparcels@swirebulk.com
pacificparcels@swirebulk.com
DIVERSE CAPABILITIES, INTEGRATED SOLUTIONS.
chartering@swireshipping.com
Global
By Luke King
NAVIGATING A BRAVE NEW WORLD
Breakbulk Asia Keynote Mehmet Öğütçü on Why a Disrupted Globe Demands Bolder Business Leaders
52 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Global
M
ehmet Öğütçü is quite literally a man in motion. Chatting over several weeks, I catch him preparing to address government and business leaders in India one day, traveling between homes in London, Türkiye and southern France another. From the outset, his appeal as an international speaker is apparent. A former Turkish diplomat turned energy executive and strategic adviser, Öğütçü moves easily between the worlds of geopolitics and business, which are themselves becoming hard to separate. He has spent decades negotiating their meeting point, and believes their increasingly turbulent interaction offers opportunity for those willing to seize it. “Very often, good business might come from conflict regions,” he says. “The margins might increase incredibly.” It is a provocative message for an industry contending with disrupted shipping routes, expensive insurance and uncertain investment decisions. But the keynote speaker at Breakbulk Asia argues that difficult conditions reward those with the knowledge, relationships and, most importantly, the leadership to navigate them.
assignment became a longer stay when he decided to pursue a master’s degree at the London School of Economics. Work with NATO followed before he returned to Türkiye and joined the diplomatic service. Assigned to the NATO department during the Cold War, he was on what he describes as a fast track. His next move, however, was one of his own choice: Beijing. “Many people saw China as a poor country,” he recalls, but reading its history had given him a different perspective. The curious young diplomat wanted to understand its people, learn Mandarin and see its reforms firsthand. “I knew that learning more about China, its language and its people would serve me well in the long term,” Öğütçü says. His posting from 1989 to 1992 placed him in China during an extraordinary period. He recalls being in Tiananmen Square on his bicycle as events unfolded, and meeting Chinese leaders through his diplomatic work. He has recently completed a book of personal recollections, “There Is No Escaping China.” Spells in Brussels and Paris followed. At the Organization for Economic Cooperation and Development, he established its Diplomacy Meets Business China program and worked across the Raised in Ankara in a family he Asia-Pacific region. The experience describes as “below middle class,” sharpened his negotiating skills: Öğütçü worked hard to reach Mülkiye, different governments brought Ankara University’s prestigious different priorities, expectations Faculty of Political Sciences, long and egos to the table. associated with the training of BG Group subsequently diplomats and senior public officials. recruited him to London. After six His first job was as a bank or seven years, he decided to build inspector. The pay was better than something of his own, establishing diplomacy offered, but a life immersed the London Energy Club, a closedin figures held little charm. Instead, door discussion forum operating he moved to the prime minister’s under Chatham House Rule, and a office, becoming an adviser and commercial advisory business. speechwriter to Turgut Özal. Diplomacy taught him relationship After two years, Özal sent him to management, while business provided London for training at the Central a sharper test. As chairman of the Office of Information, where he studied London Energy Club and Global public information techniques and Resources Partners, a strategic dealing with the press. A six-month advisory and investment firm,
53 Breakbulk Magazine
Issue 4 2026
breakbulk.com
he draws on both, but has little patience for cordial exchanges that produce no tangible result. “Niceties do not generate business,” Öğütçü says. The ability to negotiate and compromise remains useful, but must ultimately help a company identify an opportunity and create value. “You have to focus on creating value, creating business and profit for your company. Otherwise, you are useless.” That commercial discipline does not mean rushing to close a deal, however. Öğütçü believes pressure to deliver results can often lead executives to neglect the groundwork that yields success. “People often rush to do deals because they are pushed by their boards. They have to show results in the next quarter.” His diplomatic experience taught him to respect competing interests; business taught him to turn that understanding into commercial success. Both require attention to how decisions are made and what matters to the people making them. “You have to appreciate the business culture, the personal behavior of the people you are dealing with,” he says. “Do a little bit of research first and understand the country’s traditions and how they do business.”
Asia’s Economic Gravity
That experience informs his view of Asia, where he cautions against assuming that a familiar commercial approach will work everywhere. It also underpins his conviction that China’s influence will endure despite the pressures surrounding it.
At Breakbulk Asia: Mehmet Öğütçü: Winning the Next Twenty Years Thursday, Nov. 19 Breakbulk Live Stage 10:40am - 11:10am
Global
depend on energy moving through those routes. Öğütçü cites the exchange as evidence that common commercial needs can complicate apparently straightforward geopolitical alignments. He argues that India’s manufacturing ambitions need to translate into execution, and he identifies land acquisition, regulatory consistency, infrastructure reliability and financing as issues investors must examine. Southeast Asia, meanwhile, is developing a more distributed manufacturing network, with Indonesia, Vietnam, Malaysia and Thailand consolidating their positions and Singapore providing financial and maritime coordination. In terms of project cargo, he sees electricity infrastructure as an increasingly important source of demand. “Follow the capital,” he says. “And increasingly, follow the electricity.” Data centers require generation, transformers, substations, transmission and storage, he points out, while industrial development necessitates supporting infrastructure well beyond the factory gate. His argument is that logistics companies should appreciate the wider investment landscape, rather than pursue shipments in isolation.
Öğütçü and former UK Prime Minister Boris Johnson. Credit: Mehmet Öğütçü
Courage and Connection
He sees its development as a reemergence rooted in a much longer history, believing that its advantage lies in the concentration of suppliers, engineers, factories, infrastructure and finance supporting industrial production. “You cannot recreate that ecosystem overnight in another country. The intelligent approach is to diversify around China, not pretend that China no longer matters.”
For Öğütçü, identifying opportunity is only the beginning and acting on it requires bold leaders who are unafraid to make decisions when circumstances change. “You might have the greatest ideas, a wonderful India offers substantial team and the strategy,” he says. opportunities, but he doubts that it “But if you don’t have a crazy and will simply serve as a counterweight smart leader, nothing happens.” to China. Its leaders will pursue Indian Smaller energy businesses have interests, including cooperation long operated in countries where where those interests overlap. security concerns deter larger At a recent Goa conference, an competitors. He believes adaptable Indian general told Öğütçü that companies can find profitable niches India and China should cooperate in such markets, provided they to protect the Strait of Hormuz understand the exposure and have and Bab el-Mandeb, since both safeguards in place. The principle
54 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Global
extends to project logistics, where difficult delivery conditions increase the value of capable operators. With higher shipping and insurance costs, risks to vessels and terminals, and less predictable delivery times, comes opportunity, suggests Öğütçü. Success hinges on a company’s ability to manage those conditions. “But you have to be agile. You have to move very quickly,” he says. “Don’t do too much planning.” Direct engagement is a key feature of his playbook. Executives should travel to the markets where they want to work, meet prospective partners and assess conditions themselves. Calculations and artificial intelligence can never replace the human connection. “Take the trouble and go to India, go to the Gulf, go to Saudi Arabia, wherever you want to do business, and talk directly,” he says. “Eye to eye, face to face.” Creativity matters in financing, too. Where a customer has resources but little available cash, he suggests flexibility: infrastructure can be delivered in exchange for commodities, with a trader helping to turn those commodities into payment. Difficult financing conditions demand persistence and novel ways of structuring business. Away from negotiations, he applies his energy to more tangible pursuits. In Türkiye, he restores old Greek houses with a stonemason from Mardin, preserving buildings he regards as part of the country’s legacy. He describes the work as a “responsibility” rather than a commercial venture. Öğütçü and wife Aynur Tattersall also maintain an olive grove of about 1,000 trees. She is a “connoisseur,” and much of their production goes to friends. “It’s a passion, actually, and I spend more than I earn. My wife loves it more than I do, therefore I naturally have to be of the same opinion,” he jokes.
Mehmet Öğütçü and wife Aynur Tattersall maintain an olive grove. Credit: Mehmet Öğütçü
The olive grove offers a balance to a career spent pursuing opportunities across borders. In Singapore, he will bring that experience to his Breakbulk Asia keynote, “Winning the Next Twenty Years by Rethinking Energy, Infrastructure and Supply Chains,” on Nov. 19. His message for a project logistics sector facing uncertainty retains
55 Breakbulk Magazine
Issue 4 2026
breakbulk.com
the practical optimism of someone who has repeatedly changed course himself: “Where there is business, there is always a way.” Involved in the project logistics industry since 2007, Luke King is a regular contributor to Breakbulk Magazine and host of the Project Cargo Professionals podcast.
COMPLEX CARGO. SMARTER LOGISTICS.
Engineered to move. Equipped to deliver. From heavy-lift cargo and plant relocation to multimodal transportation and global shipping, Sealand combines decades of project logistics experience with engineering-led planning and intelligent digital solutions.
20+
Years of Experience
1 MILLION+ FRT Handled Globally
OUR DIGITAL ADVANTAGE FLAGSHIP
• GPS Route Mapping • Offline Data Capture • Digital Survey Reports
Your Digital Logistics Command Centre One intelligent platform bringing shipment visibility, rate intelligence, cargo planning, and logistics management together. Centralised Logistics Workspace
Vessel & Route Intelligence
Multimodal Shipment Tracking
Freight Rate Intelligence
Smart Cargo & Load Planning
VISIT US AT BOOTH
• Lead & Sales Management • Shipment Operations • Billing & Invoicing
· Integrated with LogiDashboard
· Also available as standalone solutions
Complex Cargo? Let's Move it. From ship chartering and project cargo to breakbulk, bulk shipping, multimodal transport and plant relocation.
info@spl-asia.com
spl-asia.com
Asia
APAC’S ENERGY POLICY DILEMMA
The Asia-Pacific region is at an energy crossroads. Demand is surging, energy security is back at the top of the agenda and the race to decarbonize is colliding with the realities of cost, infrastructure and geopolitics. In this three-part feature, Ben Carrozzi, partner at Norton Rose Fulbright, examines the choices confronting governments across the region.
By Ben Carrozzi
At Breakbulk Asia: Project Finance Forum: Bankability, risk and capital for Asia’s major projects
A Mammoet Giant JV lifts a 563-ton wind turbine jacket for an offshore project in Taiwan. Credit: Mammoet
Wednesday, Nov. 18 Breakbulk Live Stage 4:00pm - 4:50pm
57 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Asia
COAL, GAS AND THE GRAVITATIONAL
PULL OF THE STATUS QUO Asia-Pacific’s energy policy dilemma: from pain to opportunity or retreat?
U
ntil recently, some 20% of global liquefied natural gas (LNG) and a quarter of seaborne oil transited the Strait of Hormuz. Qatar alone has typically supplied about a fifth of global LNG, meaning any sustained disruption translates directly into higher power generation costs across Asia-Pacific, a region where gas-fired power generation underpins electricity systems from Singapore to South Korea. While the immediate impacts of the Middle East disruption are now well documented, the more consequential question is whether this is a temporary shock or the beginning of a more unstable, “higher-for-longer” global energy environment. The answer will depend on whether governments treat this disruption as a genuine inflection point for energy policy across APAC, or whether it will ultimately be absorbed as another shock leaving the region’s structural energy dependencies intact. Bound up in this question is a harder one: what does a pragmatic approach toward decarbonization actually look like in a region where net-zero commitments, economic development, energy access and security can sometimes pull in competing directions? The policy responses that emerge will need to strike a delicate balance and, in some
Ben Carrozzi, Norton Rose Fulbright
green electrons are inherently more secure than imported molecules. The third and most difficult is to make the more expensive, longterm decarbonization bets — green molecules, carbon capture and storage (CCS) and nuclear — in the interests of lasting energy security. Whether current events shift the equilibrium meaningfully toward longer-term investments remains an open question.
Doubling down: coal, gas and the gravitational pull of the status quo
The risk of reversion is most acute in countries that are resource-rich and structurally tied to legacy thermal power generating fleets. Over the course of the crisis, we have seen Indonesia reduce coal exports in order to protect its domestic power prices. Similarly, Pakistan increased coal dispatch in response to LNG supply curtailments. Of particular interest is whether this constitutes a rational, time-limited fallback or whether it entrenches coal dependence for a further generation. And, indeed, whether the binary framing of this policy choice is itself unhelpful.
Coal and clean coal technologies cases, may diverge from prevailing assumptions about what counts as an acceptable pathway toward a cleaner and more secure energy future.
Three competing strategic responses
In seeking to chart a path beyond the current crisis, governments in the region face three broad, yet interrelated, strategic policy options. The first is to double down on traditional fuel dependencies — coal in resource-rich nations, expanded LNG infrastructure elsewhere. The second is to accelerate investment in conventional renewables — solar, wind and battery storage — on the basis that domestically generated
58 Breakbulk Magazine
Issue 4 2026
breakbulk.com
In Indonesia, supercritical and ultrasupercritical plants, coal gasification technologies that produce syngasderived products (including hydrogen, ammonia, methanol, dimethyl ether (DME) and other synthetic fuels that can be decarbonized by pairing them with CCS) and coal-to-liquid (CTL) processes are all under active consideration. Indonesia’s sovereign wealth fund Danantara continues to back the revival of the country’s coalto-DME program as part of the government’s broader downstream energy strategy. A groundbreaking ceremony initially planned for February 2026 was postponed pending further assessment of technology selection and commercial viability. In July, Danantara entered into a memorandum
Asia
of understanding with Latitude Energy Holdings to explore a large-scale coalgasification platform. The program remains strategically attractive as a means of reducing Indonesia’s heavy dependence on imported liquefied petroleum gas (LPG), although its economics, emissions profile and financing prospects remain uncertain. CTL technologies hold a broader attraction for Indonesia, which has a significant number of constructed but not-grid-connected coal-fired power plants; however, the economics and emissions profile continue to raise significant concerns. These concerns are further compounded by an increasingly restrictive investment and financing landscape, undermining this pathway’s long-term viability and access to capital. Multilateral and development finance institutions have adopted entrenched positions against any coal-related financing, and commercial banks have followed suit under similar ESG commitments. This position appears unlikely to change in the near term despite the apparent merits and emerging energy transition narrative surrounding some of these technologies.
Gas and LNG: the bridge that keeps extending Gas nevertheless remains difficult to displace from the regional energy mix. As electricity demand grows and variable renewable capacity expands, dispatchable generation will continue to play an important role in maintaining system reliability. The policy question is therefore not simply whether Asia-Pacific should use more or less gas, but whether its gas strategy is sufficiently diversified, flexible and resilient to withstand a structurally more volatile market. Paradoxically, current events have also accelerated LNG infrastructure development in the region — albeit with a sharpened focus on supply diversification. Critically, recent disruptions have also refocused attention on Australian LNG, which
deugro transports a massive 800-metric-ton C3 tower column over a 6-kilometer route from Gebeng in Malaysia to Kuantan Port. Credit: deugro
despite its higher cost base, offers shorter and more predictable shipping routes to South and Southeast Asia. Yet Australia’s capacity to serve as a regional supply buffer is constrained. LNG exports account for approximately 83% of Australia’s gas production, leaving domestic consumers exposed to tight supply and elevated prices. The Australian government has responded by conducting quarterly domestic-supply assessments under the Australian Domestic Gas Security Mechanism, which permits LNG export controls where a shortfall is forecast. Production from existing projects is already mostly contracted, and new projects face high costs and stringent emissions obligations under the Safeguard Mechanism. The net effect is that Australia’s role as an LNG supplier to Asia is becoming as much a domestic political question as a commercial one. Supply resilience is not solely a question of replacing one source of LNG with another. It also depends on portfolio diversification, contractual flexibility, access to shipping and regasification capacity, and an appropriate balance between long-term contracted supply and spot-market exposure. Vietnam presents a nuanced example of the inherent tension between energy security ambitions and the need for regulatory reform. Its National Power Development Plan targets 22.4 gigawatts (GW) of LNG power by 2030, but S&P Global expects only 6 to 7 GW to materialize. The obstacle is bankability.
59 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Vietnam’s Decree 56 (March 2025) sets a minimum contracted electricity output of 65% for LNG-to-power projects, capped at 10 years — well short of the 15- to 20-year guarantees foreign developers and lenders require. A draft amendment proposed in January 2026 seeks to raise the offtake guarantee to 75% and extend the tenor to 15 years; however, uncertainty persists regarding payment security, dispatch, curtailment and LNG fuel-alignment risks.
Geothermal: the domestic baseload alternative
Indonesia has one of the world’s largest geothermal resources, with estimated potential exceeding 23 GW, and the world’s second-largest installed capacity at about 2.7 GW. The government has set a target of over 7 GW of geothermal power capacity in its updated 20252034 roadmap, and the sovereign wealth fund Danantara has allocated US$120 million for 19 geothermal projects. The Asian Development Bank signed a US$92.6 million financing agreement in January 2025 to develop geothermal resources in West Sumatra. Yet projects remain affected by delays, high exploration risk and community opposition. Singapore is also exploring geothermal as part of its diversification strategy, though its geological characteristics are less favorable. The energy security case is compelling — domestic, baseloadcapable, weather-independent — but unlocking it at scale demands sustained regulatory reform.
Asia
RENEWABLES AND GREEN MOLECULES: THE HARDER, LONGER BET Asian countries weigh the benefits of investing in clean technology
T
he disruption to Middle East supply routes has forced Asia-Pacific governments to confront a familiar question with new urgency: Does energy security mean falling back on the fuels the region already knows, or does it mean accelerating investment in the cleaner technologies it has long found difficult to scale? For resource-poor, importdependent markets in particular, the crisis has sharpened the appeal of the second path, even where the economics remain unproven and the timelines uncomfortably long. Two categories of technology sit at the center of this harder bet: conventional renewables, which are commercially mature but constrained by intermittency and grid readiness; and green molecules (hydrogen, ammonia, biofuels — including sustainable aviation fuel — and carbon capture), which promise deeper decarbonization but have struggled to definitively clear the bankability threshold.
Conventional renewables: emboldened or exposed?
The Philippines has taken a distinctively greener approach, doubling down on its bold ambition of a renewables-led clean energy future. Its Green Energy Auction Program (GEAP) targets at least 25 GW of new renewable capacity by 2035, with the sixth to ninth rounds targeting over 3,200 megawatts (MW) of solar and 5,565 MW from other technologies. GEA-5, the country’s first dedicated offshore-wind auction, targets 3,300 MW of fixed-bottom capacity. However, the auction was suspended in July 2026 while the government recalibrates its
guaranteed round-theclock power at tariffs that are competitive and declining. In September Credit: Jumbo Offshore 2025, India signed its first “load-following” renewable power purchase agreement (PPA), requiring 80% fulfillment of hourly demand profiles using hybrid technology, a landmark for a market that only a few years ago treated renewables as inherently intermittent. If recent developments sharpen the imperative for energy-intensive industries and data center operators to secure firm, clean power, India’s emerging contracting architecture may provide a useful approach to port and grid readiness, template for other APAC markets. permitting, environmental requirements In Northeast Asia, the picture and implementation risk. An indicative is more complex. Throughout this auction date of Dec. 1, 2026, has been period of elevated geopolitical risk, announced, subject to completion of the South Korea, Japan and Taiwan have recalibration process and revised auction been acutely exposed to elevated gas documentation. The episode illustrates prices. South Korea’s President Lee both the strength of the energy-security Jae-myung has called the situation an case for indigenous renewables and “opportunity to swiftly and extensively the challenges of translating ambitious transition to renewable energy.” targets into financeable projects. Japan, by contrast, appears to India is demonstrating how to address be pursuing a different policy mix: this challenge directly. Its renewables restricting mega-solar projects and program has introduced demand-driven accelerating nuclear restarts, while Firm and Dispatchable Renewable expanding its role as an LNG trader. Energy (FDRE) tenders, combining solar, Japanese electricity futures have spiked wind and battery storage to deliver since the onset of the conflict, and Jumbo Offshore transports transition pieces for Taiwan’s Yunlin offshore wind farm.
60 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Asia
the country’s excess LNG contracts, while providing short-term insulation, risk locking in long-term fossil fuel dependence. Taiwan fell materially short of its previous target for renewables to supply 20% of electricity by 2025, while its wind and solar program continues to face cost and delivery challenges. The energy security rationale for offshore wind has never been stronger, particularly for countries such as South Korea, Japan and Taiwan that lack meaningful domestic hydrocarbon reserves but have extensive coastlines. Yet the complexity of development, enduring supply chain constraints and escalating development and finance costs are complicating the picture.
Green molecules, green fuels and CCS: can current events unlock what markets have not?
Green hydrogen, green ammonia and CCS have occupied an awkward space in APAC energy policy for the better part of a decade: universally acknowledged as essential for deep decarbonization, yet persistently unable to clear the commercialization hurdles that would make them bankable and deliverable at scale. BloombergNEF projects the levelized cost of green hydrogen to fall by 85% globally by 2050, but achieving those reductions depends on electrolyzer deployment and infrastructure buildout at a significantly higher pace than has so far materialized. Sustainable aviation fuel (SAF) represents another frontier for green molecules across the region, although policy support remains a patchwork of mandates, targets, levies and voluntary arrangements. Singapore has established an initial 1% SAF target supported by a passenger-levy model, while Japan is pursuing a 10% SAF share by 2030. South Korea and Indonesia are moving toward initial requirements from 2027, while Thailand has introduced a voluntary 2026 pathway, and Malaysia is developing a
The 70-MW Capa Wind project in Ilocos Norte, Philippines. Credit: ACEN
longer-term roadmap. Neste’s expanded Singapore refinery is producing SAF at commercial scale, while Australia has announced an A$1.1 billion Cleaner Fuels Program to support domestic low-carbon liquid-fuel production. Biofuels are also assuming a broader energy-security role beyond aviation. Indonesia launched its B50 program in July 2026, increasing the mandatory palm-based biodiesel blend from 40% to 50% in an effort to reduce imported diesel consumption and strengthen domestic demand for palm oil. The program is expected to require approximately 16.7 to 18 billion liters of fatty acid methyl ester, although its durability will depend on feedstock availability, the cost differential between palm oil and petroleum diesel, and the fiscal sustainability of the subsidy mechanism. Marine biofuels present a related regional opportunity. Singapore, the world’s largest bunkering hub, permits blends up to B100 subject to applicable fuel-quality and sustainability standards, while recent transactions involving B25, B30, B100 and co-processed marine fuels point to an emerging Malaysia-Singapore value chain linking regional feedstock, storage, blending and bunkering infrastructure. Unlike aviation, however, shipping does not yet have a single global blending mandate, so demand remains driven by a combination of commercial commitments, regional regulation and anticipated international measures. CCS faces comparable commercialization challenges, but an
61 Breakbulk Magazine
Issue 4 2026
breakbulk.com
APAC-wide value chain is beginning to emerge. Critically, this is not a singlecountry proposition: the emerging model involves carbon capture at industrial facilities in emissionsintensive jurisdictions — think Vietnam, South Korea, Japan, Singapore — with compressed CO2 shipped for permanent sequestration in geological storage hubs in depleted reservoirs offshore Malaysia, Australia, Thailand or Indonesia. This cross-border architecture requires harmonized regulatory frameworks, bilateral agreements on liability and long-term stewardship, and shared transport infrastructure. The current geopolitical environment could change the calculus in two ways. First, by making the energy security argument for domestically produced fuels and feedstocks more compelling to policymakers than abstract decarbonization commitments that alone have failed to catalyze meaningful investment to date. Second, by driving a reassessment of whether continued dependence on LNG — even at contracted prices — represents an acceptable long-term risk. The disruption strengthens the strategic case for green molecules and CCS, but it has not removed the need for bankable long-term offtake, infrastructure coordination and public policy support. Whether that translates into bankable projects, however, depends on whether governments can match their stated targets with the fiscal and regulatory frameworks needed to derisk private investment.
Asia
AI, NUCLEAR AND THE CASE FOR REGIONAL COLLABORATION
Governments in the region contend with an explosive growth in power consumption
B
eneath the immediate scramble to secure fuel and firm up supply chains, a demand-side force barely on the radar five years ago is reshaping the calculus for every government in the region: the explosive growth of power consumption from data centers and AI. This is adding urgency to a nuclear conversation that would have seemed implausible in Asia-Pacific up until very recently, and it is exposing just how far individual countries’ energy systems remain from the resilience that current events demand. That exposure is, in turn, sharpening the case for a more collaborative regional approach. No single Asia-Pacific market, however well-resourced, can fully insulate itself from supply shocks acting alone. What follows examines how the nuclear conversation is evolving, and why crossborder power grids and green molecule supply chains may prove just as decisive to the region’s energy security as any single country’s domestic policy choices.
Chain reaction: how AI and data could drive a nuclear policy boom
In Southeast Asia alone, power demand from data centers is set to quadruple from 2.6 GW to 10.7 GW between 2025 and 2035, accounting for 3% to 4% of peak demand by 2035. Data centers may become a force for accelerating the energy transition. Their operators have the capital, the long-term contracting appetite, and — in the case of global hyperscalers — the corporate sustainability mandates to anchor new renewable and nuclear capacity. They also risk overwhelming grids that are
already under strain, and their growth adds urgency to the need for baseload zero-carbon technologies that can complement intermittent renewables. Australia is considering a more interventionist response: Proposals released in August 2026 would require new data centers to support additional renewable generation, demonstrate sufficient contracted firming capacity and, potentially, register as large loads in the National Electricity Market. Related reforms seek to ensure that data centers bear the network-augmentation costs they cause or accelerate. Emerging corporate procurement frameworks may offer part of the solution. Vietnam significantly expanded its Direct Power Purchase Agreement (DPPA) regime in June 2026, allowing qualifying consumers, including data centers, to procure renewable electricity through privategrid arrangements or national-grid structures involving financial settlement. Malaysia’s Corporate Renewable Energy Supply Scheme (CRESS) permits bilateral physical renewable-energy contracts through regulated open access. Thailand is moving in the same direction, but its DPPA framework remains under development, with key commercial matters such as wheeling charges, balancing and grid access still to be finalized. In the near to medium term, however, this same demand growth may reinforce the role of gas. Data centers require firm, highly reliable power on development timelines that can be considerably shorter than those for nuclear deployment, major
62 Breakbulk Magazine
Issue 4 2026
breakbulk.com
transmission expansion or emerging long-duration storage technologies. Unless clean firm capacity develops more rapidly, part of the immediate response may therefore be additional gas-fired generation, even as operators contract for renewable electricity. In a twist that was virtually unimaginable a few years ago, regional attitudes toward nuclear energy are shifting markedly, with nuclear increasingly being considered as a potential source of firm, low-carbon power. Singapore has moved beyond purely conceptual consideration of nuclear energy and is now building the institutional capability needed to make an informed decision. In May 2026, it announced that the International Atomic Energy Agency would conduct a Phase 1 Integrated Nuclear Infrastructure Review in 2027. That process is not a commitment to deploy nuclear power or small modular reactors (SMRs), but it marks a material step in Singapore’s nuclear-readiness program. Similarly, Malaysia launched a fresh nuclear feasibility study in 2025 under its 13th Malaysia Plan. Meanwhile, India’s Nuclear Energy Mission targets 100 GW by 2047, while the SHANTI Act has opened a pathway for greater private-sector participation. Draft implementing rules released in August 2026 address operator liability, insurance and financial-security requirements, illustrating that the policy ambition is now moving into the more difficult phase of regulatory implementation. In the U.S., hyperscalers are already co-locating with or restarting existing
Asia
nuclear plants and signing PPAs with SMR developers. In fact, the scale of power demand from data centers challenges the very viability of SMRs — typically only 50 to 300 MW — as a solution for next-generation hyperscale campuses whose power requirements are being measured in gigawatts. The current geopolitical environment strengthens the energy security case for low-carbon baseload power that is less directly exposed to internationally traded fossilfuel disruption, but the barriers remain formidable: advanced SMR designs are largely still under development, lead times are measured in decades, and capital requirements are immense.
chains — hydrogen, ammonia, methanol and their derivatives — will inevitably transcend national borders. India’s National Green Hydrogen Mission targets 5 million tonnes of annual production by 2030, with significant export-oriented ammonia capacity planned at coastal sites including Kandla, Paradip and Tuticorin — designed to serve demand centers in Japan, South Korea, Singapore and Europe. CCS value chains, as discussed above, require cross-border coordination at every level. The realization of these decarbonization initiatives will require significant coordination at a policy, regulatory and infrastructure level.
Beyond borders: the case for greater regional collaboration
Lasting shift or temporary response?
The current geopolitical environment has underscored a fundamental truth about energy security in a region as geographically dispersed and economically diverse as Asia-Pacific: no country can solve this alone. The ASEAN Power Grid — a long-discussed initiative to connect the electricity systems of the 11 ASEAN member states — could receive a significant policy boost from current events. The rationale is simple: a country experiencing gas supply disruption could draw on surplus hydropower from Laos or Cambodia, or geothermal or renewable baseload from Indonesia or the Philippines, if interconnected transmission infrastructure existed. Laos already exports significant volumes of hydropower to Thailand and Vietnam, and Cambodia’s Mekong basin resources represent further untapped cross-border supply potential. Scaling these bilateral arrangements into a genuinely multilateral grid — one capable of balancing intermittent renewables across time zones and weather systems — would materially strengthen the region’s collective energy resilience. But the case for regional collaboration extends well beyond interconnected power grids. Green molecule supply
Developments during 2026 have reinforced the need for Asia-Pacific governments to pursue energy security, affordability and decarbonization together; however, they have not yet produced a uniform regional policy reset. Instead, countries are pursuing different combinations of domestic renewables and storage, diversified gas supply, nuclear readiness, regional interconnection and, in resourcerich markets, continued reliance on indigenous fossil fuels to weather the effects of the shocks experienced by global energy markets. History counsels against assuming that the present momentum will endure.
The energy shock following Russia’s invasion of Ukraine generated similar urgency, only for parts of the policy response to weaken as markets adjusted. Many of the impediments to structural change remain: fiscal constraints, regulatory inertia, underdeveloped grids and ports, uncertain offtake structures, fragmented regional markets, and the difficulty of mobilizing long-term capital for complex infrastructure. The emerging dividing line is therefore not simply between conventional and clean energy. It is between short-term measures that manage the immediate shock and durable frameworks capable of delivering investable projects and securing a sustainable, long-term energy future. Across LNG-to-power, offshore wind, hydrogen, biofuels, CCS and nuclear, ambition alone is insufficient. Bankable offtake, credible risk allocation, coordinated infrastructure, workable permitting and appropriate public support will determine which policies translate into operating assets. If governments can address the underlying vulnerabilities, the crisis may yet herald the dawn of a more resilient, affordable and progressively lower-carbon regional energy system. Ben Carrozzi is a partner at Norton Rose Fulbright and an energy and infrastructure specialist, advising clients on project development, debt and equity transactions for energy transition and lowcarbon infrastructure projects worldwide.
SAL’s MV Regine carries project cargo in Singapore. Credit: SAL
63 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Asia
AFTER 900 APMT MOVES, Field testing of mixed formations, combining all-electric with diesel-hydraulic units, lets fleet owners reduce cost and maintenance without scrapping diesel units
64 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Asia
THIS CREW WON’T GO BACK TO DIESEL By Leslie Meredith
A
t the Yangjiang offshore wind equipment base in Guangdong, China, a fleet of all-electric Advanced Power Modular Transporters (APMTs) spent 11 months working alongside diesel-hydraulic selfpropelled modular transporters (SPMTs). Between October 2025 and September 2026, the electric fleet completed some 900 production moves of nacelles, tower sections, hubs and jacket structures for Hydropower Fourth Bureau (Yangjiang) Marine Equipment’s fabrication program. Loads ran from 80 to 560 tonnes, over distances of 0.2 to 7 kilometers. In the largest formation, 20 electric axle lines and 20 conventional hydraulic axle lines carried a wind turbine and jacket in a single formation. A meter from the electric drive units, the sound level was 65 decibels, about the level of normal conversation. The diesel units in the same formation measured 100 decibels at the same distance. On a yard where riggers walk beside the load for every meter of every move, that 35-decibel gap changes how a crew gives instructions and how safely it works.
At Breakbulk Asia: Megaproject Asia: Delivering the next phase of industrial growth Wednesday, Nov. 18 Breakbulk Live Stage 2:05pm - 2:50pm Building foundations at Yangjiang yard. Credit: Vastwin
65 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Asia
Running Alongside Diesel
Credit: Vastwin
LOOKING AHEAD TO AUTONOMOUS HEAVY HAUL Following the successful job site deployment of the allelectric APMT in Yangjiang, Super Transport Robot (STR) is advancing toward the next frontier of heavy logistics: autonomous, AI-driven heavy transport. Field testing is underway on selfdriving APMT models equipped with multisensor fusion that combines LiDAR, high-precision GNSS positioning and millimeter-wave radar. The platform integrates proprietary AI algorithms for real-time dynamic
route planning, obstacle detection and automated multiunit synchronization. Designed to eliminate human operational errors in high-risk project environments, the autonomous APMT enables centimeter-accurate positioning during heavy module transfers in shipyards, automated container terminals and fabrication yards. As field trials progress, the company aims to deliver fully automated, zeroemission heavy-haul solutions to global fleet operators in the near future.
The transport contractor’s crews tracked energy use, synchronization and maintenance across both fleets. Their results show fleet owners what APMTs cost to run and how they work with existing diesel SPMTs.
repetitive, machines return to the same base every night and crews on foot handle precision cargo for entire shifts. At Yangjiang, peak construction season adds heat, high humidity and salt-laden coastal air. In that setting, zero exhaust at breathing height and a fixed overnight charging point become operational advantages.
Built Electric From the Start
Most electric SPMT operations to date have used conventional hydraulic platforms with an electric power pack in place of the diesel engine. The APMT from Super Transport Robot (STR) was designed as an all-electric transporter from the ground up. Its published specification (Breakbulk Magazine, Issue 2, 2026) runs to a six-axle-line platform with a 255ton payload, a 400.61 kWh CATL lithium iron phosphate (LFP) battery at 700 volts, dual-port fast charging to 80% in about two hours, permanent-magnet synchronous motors with independent electric drive and CE certification. A fabrication and marshaling yard is close to the ideal duty cycle for that design. Moves are short and
Cost per Move, Side by Side On a documented 6-kilometer move of a 310-ton load, the electric formation used 140.8 kWh. The transport team puts diesel consumption for the same move at 70 to 80 liters. At local energy prices, the electricity cost roughly a quarter of the diesel bill. The carbon numbers point the same way. Seventy-five liters of diesel emits roughly 200 kilograms of carbon dioxide; the same move’s electricity, at Chinese grid factors, carries roughly 75 to 80 kilograms, a reduction of around 60%. STR quotes around 118 tonnes of CO2 saved per APMT per year at 1,500 operating hours.
66 Breakbulk Magazine
Issue 4 2026
breakbulk.com
For fleet owners, the buying question is whether going electric strands the diesel assets already on the books or upgrades them formation by formation. The crews found that the most sensitive case was the opposite of what most people expect: light loads under 100 tons spread across many electronically synchronized axle lines, where they are hardest to keep in step. The electric motors’ instant torque means the APMTs naturally want to pull away faster than the diesel units when starting, so the team taught them to follow. A multimotor synchronization control senses the diesel units’ start acceleration and matches it. With that tuning in place, speed, steering and lift in combined formation ran smoothly, the crew reported. The same instant torque gave fine low-speed control when positioning jackets onto barge decks or alignment pins. “The most convincing part of the Yangjiang test was that we didn’t have to change our standard operating procedures,” Dafang Hui, the chief field engineer for Zhong Lian Hai Guang Ying Project Logistics Co., Ltd. (Vastwin), the project’s transport team, said. “The APMT moved in perfect tandem with our conventional diesel fleet. It gave us the extra payload capacity and zeroemission benefits without requiring us to scrap our existing equipment. That ‘plug-and-play’ compatibility is what makes electrification scalable for fleet owners.”
Maintenance Without Downtime
Ask the transport team what separated the two fleets day to day and the answer is maintenance. The APMT’s routine checks of fault codes across the battery, motor and control systems, coolant and oil levels, and a motor cooling filter are mostly software and inspection work, done in the gaps between moves. For the diesel units, maintenance means stopping the
Asia
machine and stripping components. With less hydraulic pipework on the APMTs, technicians also reported zero hydraulic leaks from the electric units. For 11 months the routine never changed: work the day, charge once, work the next. Battery management became second nature to the crews the way fuel management used to be, except the charging point now sets the timetable.
diesel units burn,” Mr. Zang, site project manager for the project owner Hydropower Fourth Bureau (Yangjiang) Marine Equipment Co., Ltd., said. “Over some 900 moves they worked inside our existing hydraulic fleet and got on with the program. “What we would ask for next is simple: a bigger battery, more intelligence on board and obstacle avoidance above all.” The owner’s requests for more The Verdict From the Yard battery capacity and obstacle Crews unanimously supported the avoidance point to what STR is testing integration of electric units. “Once next, Zinguang Jin, spokesperson you’ve driven the electric ones, you for Vastwin and STR, said. don’t want the diesel back. It costs less Electric heavy transport reached to run, it’s quiet enough to talk normally European ports this year too. In August, beside the load, and new hands pick it Osprey, operator of the U.K.’s largest up fast,” Zhongyang Zhao, crew leader SPMT fleet, ran the country’s first for the project’s transport team, said. electric SPMT operation in a port. “Our electric lines run in the same In September, Mammoet moved a formation as the diesels, and the whole 1,700-ton monopile at Denmark’s Port train steers and lifts as one machine. of Rønne on electric SPMTs, avoiding “And this is no pilot. The units are out an estimated 25,000 to 30,000 liters working every day. Anyone who wants of diesel on a single move. Both were to see what they can do is welcome single moves under close watch. to come to the site and watch.” Roughly 900 production moves The project owner’s side across 11 months of daily duty is an reached the same conclusion. intensity and a duration no electric “We judge transport equipment heavy-transport program outside China by what a move costs us, and on has yet matched in published service. that measure the electric units have The APMT proved itself inside a working proved themselves: the energy cost fabrication program, under challenging per move is a fraction of what the conditions and a tight schedule.
That record arrives as Singapore, South Korea, Japan and Vietnam tighten carbon and port noise rules, pushing EPCs and transport contractors to cut emissions without giving up lifting capacity. Fleet owners, EPCs and project teams who want to see electric heavy transport under full load are welcome on site, Jin said. STR, for its part, is ready to take the APMT from this yard to projects worldwide. Leslie Meredith is the product and editorial director for Breakbulk Events & Media. *Breakbulk Exhibitor
TEST SITE AND TEAM Where: Located in the Port Industrial Park of Yangjiang High‑tech Zone, Guangdong Province, the Yangjiang offshore wind fabrication complex is a key manufacturing hub for large‑scale offshore wind components in South China operated by China. Project Owner and Yard Operator: A subsidiary of state-owned PowerChina, Hydropower Fourth Bureau (Yangjiang) Marine Equipment Co., Ltd., manufactures heavy‑duty offshore wind hardware including jackets, tower sections, nacelles and turbine hubs, with direct access to Yangjiang Port for cargo shipment to offshore windfarm sites across the Asia‑Pacific region. Transport Execution Partner: Zhong Lian Hai Guang Ying Project Logistics Co., Ltd. (Vastwin) Electric SPMT Equipment Supplier: Anhui Super Transport Robot Co., Ltd. (STR), founded in 2024 in Xuancheng, Anhui, China, builds the APMT (Advanced Power Modular Transporter), co-developed with Vastwin.
67 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Breakbulk Asia 2026 . Booth B30
COMPLEXITY IS INEVITABLE. INEFFICIENCY ISN'T. Built for Industrial Excellence.
From dismantling and asset management to
procurement, vendor coordination, and financial control,
Engineered for Smarter Outcomes.
Dahlia Technologies transforms complex industrial
processes into connected, intelligent digital workflows.
DISMANTLING MANAGEMENT SYSTEM 3D Digital Twin
Expense Log
From First Inspection to Final Handover.
Digitising complex dismantling operations with greater control, transparency, and traceability. Intelligent P&ID Mapping
Asset Management Tracker
QR Asset Traceability
FEATURED
Master Inventory Control
ProcureEase
CostRanker
Vendor Management System
• OCR Scanning
• QR Asset Tracking
• Post-PO Tracking
• Vendor Comparison
• Manage POs & Requests
• Spend Analytics
• Asset Verification
• Dispatch Approvals
• Approval Workflows
• Access Ledger & TDS
• Travel Bookings
• Lifecycle Management
• Quality Inspections
• Savings Tracking
Your Next Digital Breakthrough Starts Here. Let's explore smarter solutions for your operations.
• Track Payment Status
Asia
THREE STRAITS, ONE GLOBAL RISK Why Breakbulk Can’t Ignore a Disruption in Malacca, Singapore or Taiwan By Amy McLellan
Aerial view of ships anchored in the Singapore Strait. Credit: Saksham Vikram
T
he global shipping system is increasingly vulnerable to disruption. From drought-induced restrictions in the Panama Canal to conflict in the Middle East, recent years have shown how quickly the closure or disruption of a strategic maritime chokepoint can ripple through tightly interconnected supply chains. While the Middle East often dominates contingency planning, Asia is home to several waterways whose disruption could have equally far-reaching consequences. Three stand out in particular: the Strait of Malacca, the Singapore Strait and the Taiwan Strait. A prolonged closure or serious blockage of any of these routes would pose a major challenge for global trade and give executives in the breakbulk and project cargo sectors plenty to worry about. “The world would quickly discover that Malacca, Singapore and Taiwan are not three separate waterways,” says Mehmet Öğütçü, chairman
of Global Resources Partners and the London Energy Club, and a former diplomat and International Energy Agency (IEA) executive. “Together they form the circulatory system of the Asian economy.” Disruption here could take many forms: a collision blocking part of the channel, a cyberattack disabling port and navigation systems, or a regional military confrontation prompting insurers to withdraw cover. “For me, the question isn’t ‘What event could close a strait?’ but ‘What could make using a strait sufficiently difficult or risky that normal shipping patterns start changing?’” says Rafael Vicens, head of Maersk Project Logistics IMEA. Risks could range from geopolitics, particularly around Taiwan, to navigation constraints, a quarantine or more traditional maritime risks such as collision and grounding, as well as cyber and technology-related threats. According to Vicens, a strait doesn’t have to be physically closed to
69 Breakbulk Magazine
Issue 4 2026
breakbulk.com
cause significant disruption. “As we are seeing on the Bab el-Mandeb and Hormuz, if the security risk becomes too high, vessels may already start avoiding an area, insurance conditions can change and established shipping patterns can quickly be affected.”
Risks Laid Bare
The Malacca and Singapore straits connect the Indian Ocean with the South China Sea and the wider Asian manufacturing ecosystem. In the first half of 2025, an average of 23.2 million barrels of oil and petroleum
At Breakbulk Asia: Fragmentation, Flows and the Future of Trade: Navigating Asia’s New Trade Map Wednesday, Nov. 18 Breakbulk Live Stage Noon - 12:50pm
Asia
The installation vessel Green Jade carries out work at the Hai Long offshore wind project inside the Taiwan Strait. Credit: Hai Long Offshore Wind
Rafael Vicens, Maersk Project Logistics
Mehmet Öğütçü, Global Resources Partners
products passed through the Strait of Malacca each day, alongside large volumes of LNG, coal, iron ore, food, chemicals and manufactured goods. “More than 102,500 ships transited the Malacca Strait in 2025, which gives an indication of the scale involved,” says Vicens. “Alternative routes exist, particularly through the Indonesian archipelago, but rerouting means additional distance, time and cost, while potentially transferring congestion to other waterways.” Singapore, as a global center for refining, bunkering, container transshipment, commodity trading,
marine insurance and shipping finance, magnifies the importance of the route. A disruption here would affect not only where ships could sail, but also the availability and cost of bunkering, port services, logistics and other critical elements of the maritime ecosystem. Meanwhile, an estimated US$2.5 trillion worth of goods — more than one-fifth of global maritime trade by value — passed through the Taiwan Strait in 2025, with the island hosting some of the world’s most important semiconductor, electronics, automotive and advanced-manufacturing clusters.
70 Breakbulk Magazine
Issue 4 2026
breakbulk.com
“The immediate crisis would be psychological as much as physical,” says Öğütçü. “Markets would not know whether the disruption would last three days, three weeks or three months and that uncertainty would produce panic buying, hoarding and speculative price movements.” Tankers would likely slow, container vessels would anchor outside ports and LNG carriers would change direction. Freight rates would jump, and oil and gas prices would surge. Longer diversions would increase fuel, freight and insurance costs and reduce vessel availability while alternative ports could quickly become congested.
Regional Impact
China would suffer on both the import side, particularly for energy and other strategic commodities, and on the export side, as manufacturers depend on maritime routes to reach overseas markets. Beijing has built pipelines, railways, ports, strategic storage facilities and Belt and Road corridors partly to reduce its dependence on vulnerable sea routes. But the China-Myanmar oil pipeline, which
Asia
bypasses Malacca, carries only a small fraction of China’s crude-import needs. Railways, meanwhile, cannot match the volumes moved by sea. Taiwan depends on the sea for almost all its imported energy. Chip plants require uninterrupted electricity, ultrapure water, chemicals, industrial gases and spare parts. Finished chips can be flown out, but the thousands of materials needed to make them cannot all be airlifted in. Japan and South Korea both maintain substantial strategic petroleum reserves, giving them some buffer against an energy shock. They could also seek alternative supplies and routes across the Pacific. Their factories, however, rely on production networks spread across China, Taiwan, Korea and Southeast Asia, leaving them vulnerable to shortages. A prolonged interruption to Taiwanese and South Korean semiconductor production could
therefore have consequences far beyond Asia, disrupting automobile production, telecommunications equipment, data center construction and other technology-intensive industries worldwide.
the global fleet. To avoid the Taiwan Strait, vessels could pass through the Luzon and Bashi channels and along Taiwan’s eastern coast, though a military conflict in the area could see insurers exclude the entire region. Overland alternatives would become more important. China would maximize oil and gas imports through Russia, Kazakhstan, Central Asia and Myanmar, although some of those regions face their own conflict-related disruptions. Eurasian railways would carry more machinery, electronics and high-value goods. But maritime trade operates on a scale that land transport cannot match. Pipelines carry only specific commodities and cannot suddenly be expanded. Railways face different gauges, capacity constraints and political risks. New projects such as the Kra Canal or the proposed Thai land bridge would take many years to fill the gap.
Alternative Routes?
The world would not be completely trapped. The Sunda Strait, between Sumatra and Java, provides the nearest substitute for Malacca, but it is narrower, shallower and unsuitable for some fully loaded tankers. It could absorb additional traffic, but not the full volume normally passing through Malacca. The deeper Lombok Strait would be the main alternative for large tankers and bulk carriers. Ships could sail north through the Makassar Strait and continue into the western Pacific. The route is viable but longer, meaning more fuel, higher costs and less effective capacity in
An AAL vessel carrying wind towers, granite and bulk from China transits the Singapore Strait. Credit: AAL Shipping
71 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Asia
Farid Belbouab, Gulftainer
According to Öğütçü, the shock “could be larger than the combined effects of the Suez blockage, the Red Sea attacks, the Ukraine war and the pandemic-era semiconductor shortage because it would strike energy, manufacturing, shipping and technology at the same time.” The lesson is that redundancy planning should be in place now. Governments around the world must treat maritime resilience as part of national security rather than transport policy. Whether it’s diversified energy stocks, east-facing ports, protected undersea cables or coordinated plans for keeping essential shipping lanes open, resilience requires multiple layers of protection and redundancy.
Impact on Project Cargo
For large and heavy cargo such as turbines, transformers, generators and industrial equipment, the concern is that they cannot easily be moved by other means or through alternative routes. For major construction, energy and industrial projects, the bigger problem is that one overdue piece of equipment can delay an entire project. When it comes to disruption impacting Taiwan, for example, it is interruption to manufacturing and exporting the smallest components — semiconductor chips — that could then negatively impact some of the biggest items: wind turbines, generators and processing equipment.
One critical component arriving late can matter more than hundreds of components arriving on time. “Project cargo behaves differently from standard containerized cargo,” says Vicens. “Moving a heavy transformer, pressure vessel, turbine component or oversized module requires engineering around the vessel, ports, lifting arrangements, draft restrictions, inland infrastructure and ultimately the construction schedule. If the maritime route changes, you potentially have to reconsider several pieces of that puzzle.” Unlike oil, which can be rerouted even if that route takes longer, project cargo needs an alternative route that also works with the vessel, ports, infrastructure and project schedule. “That’s what makes major chokepoint disruption particularly relevant for project logistics,” says Vicens.
Understand the Priorities
The immediate priorities are straightforward, he says: protect people, understand the risks and then protect continuity of the cargo flow. The industry should look at alternative maritime routings, different gateways, vessel deployment and, where appropriate, combinations of ocean, road, rail or air. “For major projects, critical cargo should be identified early, routing constraints understood, and realistic alternatives considered before they’re needed,” says Vicens. Communication matters too. “Customers don’t just need to know where their cargo is. They need to understand what disruption means for their project,” he says, noting that a seven-day transportation delay does not automatically equal a seven-day project delay. “The real question is whether the delayed cargo sits on the project’s critical path.”
Lessons From Hormuz
In 2026, Hormuz showed that a waterway doesn’t need to be closed;
72 Breakbulk Magazine
Issue 4 2026
breakbulk.com
the threat alone can affect vessel movements, shipping patterns, insurance and freight costs. Still, there are differences: Hormuz is an access point into and out of the Arabian Gulf, but Malacca and Singapore connect two major maritime regions. Taiwan, meanwhile, sits alongside one of the world’s most important technology ecosystems. “We shouldn’t assume that the routes that worked yesterday will always be available tomorrow,” says Vicens. Resilience, he adds, does not mean expensive backup plans for every shipment. “It means understanding where you are exposed, which cargo is genuinely critical and what realistic alternatives are available.” The industry has proven its capacity to adapt and find solutions to unexpected problems, whether that is drought in the Panama Canal or COVID-19 restrictions. “As we have seen this year with the ongoing disruption in the Strait of Hormuz, this is an industry that is flexible and experienced at solving problems on behalf of its clients,” says Farid Belbouab, Group CEO of Gulftainer, which recently expanded into Southeast Asia with a strategic investment in the Suksawat Terminal, just south of Bangkok. “In the UAE, we have pivoted our operations, quickly establishing new inland logistics corridors in order to keep trade moving through the region, with the number of containers we’re handling at Khor Fakkan jumping from 2,000 a week to 75,000 a week. Further expansion is planned. As proven in recent years, from COVID to recent conflicts, this is an industry that is resourceful and resilient, and customers can trust us to keep trade moving.” Award-winning freelance journalist Amy McLellan has been reporting on the highs and lows of the upstream oil and gas and maritime industries for over 20 years.
*Breakbulk exhibitor
Asia
AAL RIDES AUSTRALIA’S
BATTERY BOOM Rising Demand for Grid-Scale Energy Storage Is Opening a New Breakbulk Market By Malcolm Ramsay
The AAL Antwerp loaded with BESS units arrives in Newcastle, Australia. Credit: AAL Shipping
74 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Asia
A
ustralia’s renewable energy transition is driving a surge in battery storage projects, creating a new source of breakbulk demand and transforming how cargo is handled, transported and moved through the supply chain. At the crest of this wave, heavylift project carrier AAL Shipping has steadily built up a dedicated battery energy storage system (BESS) offering over the last few years, launching one of the first regular BESS sailings from Taicang, China, to Australia to meet the growing demand on this route. “The turning point came in late 2023, when the IMO reclassified BESS units as Class 9 dangerous goods,” said Jack Zhou, AAL’s general manager and chief representative for China. “That single regulatory shift told us there would be real demand for a carrier with the specialist safety systems and operational expertise to move this cargo compliantly, so we moved quickly to test whether AAL could meet that bar. We started with a single trial voyage to prove our operational and safety readiness under the new requirements. And it was a success.” With one of the best solar irradiation profiles in the world, Australia is a natural choice for solar power generation, but its grid has struggled to keep up with load balancing as more power has come online. The country now has over 4.4 million solar installations, with a combined capacity of more than 45 gigawatts (GW). The grid must relay this power across vast distances while balancing peak daytime production and meeting nighttime demand. Battery storage has emerged in recent years as the leading solution to solve this problem, with 3.6 gigawatthours (GWh) already installed, and a further 4.2 GWh of large-scale battery capacity at or near final investment decision. However, unlike home battery solutions, the majority of industrial BESS products are heavy, large-scale units, often weighing
more than 10 tons apiece, measuring several meters in length, and requiring careful transportation due to their composition and inherent safety risks.
Building From Scratch
The scale of modern BESS installations is evident in AAL’s current project, transporting multiple UN3480 lithium-ion battery units for a 720-unit installation set to become one of Australia’s largest grid-connected battery projects. Located on the site of a former power station, this system not only marks a major step forward in developing clean-energy facilities but also minimizes the need for new land development. In a first phase, this giant grid battery will provide enough storage to supply almost 800,000 homes with electricity, and future phases are set to boost capacity by a further 50%. “BESS are fundamental to the next phase of the global energy transition, and AAL is proud to support this landmark project,” Zhou said, adding that the process to get to this latest project from an initial trial shipment had been complex. “The hardest part wasn’t the trial itself; it was what came after: building the supporting infrastructure essentially from scratch. There were no established handling procedures or precedents for moving BESS as part cargo on multipurpose vessels, so we worked closely with the Maritime Safety Administration, port authorities and terminal stakeholders to create them. “The Taicang International Container Terminal (TICT, in Jiangsu Province, China) was central to that effort. We helped it develop formal handling procedures, upgrade its cargo-handling capabilities and roll out specialist training and storage protocols, turning it into one of the region’s first dedicated breakbulk gateways for BESS.” This process has continued,
75 Breakbulk Magazine
Issue 4 2026
breakbulk.com
with AAL and TICT now conducting quarterly operation summary review meetings to continuously strengthen safety measures for both the terminal and vessels. As part of this process, AAL has also begun equipping vessels on BESS routes with enhanced fire protection and flammable gas detection systems, continuous temperature and humidity monitoring, portable thermal imaging cameras and high-capacity submersible pumps. Following several smaller shipments, AAL began the project in 2025, with the first 192 BESS units delivered via its established Asia-Australia East Coast (AUEC) liner service. Each unit measured 3.1 meters long, 2.66 meters high and 2.06 meters wide, and weighed 14 tonnes, bringing the total cargo weight to more than 2,600 tonnes.
Selecting the Right Vessel
Preparations for the project began months before the first unit was loaded, as AAL put together its technical requirements and assessed the most effective way to deliver the valuable cargo. “Selecting the right vessel for BESS cargo comes down to three things: deck strength, crane capacity and crew technical expertise,” Zhou said. “As containerized transport options for these heavy, sensitive units are increasingly phased out of the market, specialist multipurpose tonnage has become essential. Our Super B-Class vessels, with their 700–800 tonne lifting capacity, give us the flexibility to keep pace as BESS units continue to grow in both size and weight.
At Breakbulk Asia: Megaproject Asia: Delivering the next phase of industrial growth Wednesday, Nov. 18 Breakbulk Live Stage 2:05pm - 2:50pm
Asia
Jack Zhou, AAL Shipping
Frank Mueller, AAL Shipping
“As BESS weights increasingly exceed the capacity of terminal lifting gear, AAL has also had to design and produce a dedicated lifting spreader beam to ensure safe, more productive lifting operations. Ahead of every shipment, a critical preparatory step is the completion of all required “hot work,” including welding the D-rings used for lashing, carried out strictly under permit and inspection before any cargo operation commences.” As well as these physical changes to the vessel, AAL also ensured that all
crew members underwent mandatory drills ahead of every sailing, supported by dedicated contingency planning for fire, spillage and other BESSspecific emergency scenarios. With all these checks complete, the units were then loaded on the 3,000-square-meter deck of the A-Class vessel AAL Brisbane, with cargo stored across the hatch covers. With the vessels prepared and at dock, loadout was conducted at Taicang in just days, and the cargo was ready to begin its more-than-5,000-mile journey
AAL’s Super B-Class vessels offer the flexibility to keep pace as BESS units continue to grow in both size and weight. Credit: AAL Shipping
76 Breakbulk Magazine
Issue 4 2026
breakbulk.com
to Eastern Australia. While much work had been put into developing TICT as a BESS breakbulk hub, the sector in the Australian city of Newcastle in New South Wales state has seen less development, leaving AAL to rely on its expertise to ensure the safe loading and onward transport of the units. “Receiving the BESS units ashore was not without problems, as a lot of local legislation and approvals and stevedoring licenses did not cater for the sheer volume of IMDG Class 9 cargo being discharged in one sailing,” said Frank Mueller, general manager for AAL Australia and Oceania. “Special arrangements had to be made to discharge the BESS units directly to truck for transport to an off-site storage facility able to accommodate these volumes of dangerous goods.” Alongside this, AAL had to ensure that berthing and operational restrictions were adhered to and the company worked closely with the terminals, stevedores and receivers to keep additional costs at a minimum.
Asia
Deck space is maximized on the AAL Brisbane to transport BESS equipment. Credit: AAL Shipping
A Burgeoning Market
Since this first shipment of 192 units was successfully delivered at the end of last year, the outlook for breakbulk demand related to BESS projects in Australia has gone from strength to strength. “Looking ahead, the BESS market’s next growth wave is increasingly being shaped by data centers,” Zhou said, noting that “global demand for AI and data infrastructure is accelerating,” with the need for grid-connected energy storage and third-generation BESS units forecast to reach some 57 tonnes per unit from 2027 as a result. “This will reinforce the critical role of specialist heavy-lift operators with vessels capable of handling this larger, heavier cargo,” he added. AAL is working to meet this demand as it predicts that Australia’s data center sector “is entering a
period of extraordinary growth,” with Australian Energy Market Operator (AEMO) predicting demand from data centers will rise sharply over the next decade as AI and hyperscale cloud infrastructure expand. Given the steady base load power requirement of this infrastructure, battery storage is increasingly seen as the tool that helps unlock grid connections for these facilities rather than simply backing them up. From a breakbulk perspective, the future remains complex as the specifications, size and handling of these units all rapidly evolve. Economies of scale suggest that batteries may grow even larger, and with that come further fire and safety risks. Regulatory changes likewise make forecasting vessel capacity complex for breakbulk operators as these units must transit different legislative regimes.
77 Breakbulk Magazine
Issue 4 2026
breakbulk.com
“New International Maritime Dangerous Goods (IMDG) requirements that came into force in January 2026 have mandated on-deck stowage for UN3536 BESS cargo,” Zhou noted. “While that will reduce the volume we can carry per voyage, we expect it to be offset by stronger freight yields.” Despite these challenges, AAL expects early, proactive collaboration with regulators and infrastructure partners to deliver a genuine competitive edge. Breakbulk operators that invest in the required infrastructure, it says, can expect revenue per voyage to increase as the market develops. Based in the UK, Malcolm Ramsay has a background in business analysis and technology writing, with an emphasis on transportation and ports. *Breakbulk exhibitor
Asia
COMING HOME TO CHINA’S FUTURE SAL’s Tina Yi on Seizing China’s Project Cargo Opportunity
T
ina Yi never thought a moment at an airport would change the course of her life. In 2006, she arrived home from the UK for a visit and found her parents waiting for her. She was working for a British-based forwarder at the time, but seeing them made her reconsider where she wanted to build her life. “I remember looking at them and thinking they were growing older, and I was not there to help. I made the decision to move back home right then and there,” she said. As an only child, Yi wanted to be closer to her parents. She settled in Shanghai, where China’s industrial expansion was creating opportunities in shipping. Power plants, steel mills and petrochemical projects were getting built, driving demand for increasingly large and complex cargo movements.
At Breakbulk Asia: Women in Breakbulk Asia Power Breakfast Tuesday, Nov. 17 from 9:00am - 11:00am Keynote speaker: Tina Yi Add ticket to registration
Today, as managing director of SAL and JSI Alliance in China, she regards that decision as one of her most important choices. Her reason for coming home was personal, but the timing would prove important professionally. Her path into shipping, however, began far away from China. After a first degree in marketing and economics at home, she wanted to study abroad, completing a postgraduate degree at the University of Surrey before choosing a master’s in international logistics at the University of Plymouth. China had recently joined the World Trade Organization and Yi recognized the potential for shipping and logistics to grow alongside its economy. While she had no immediate plans to return home, she saw shipping as an early indicator of changes in the global economy, where her initial interest lay. Studying the industry, however, quickly revealed how well it suited her personality. “I found that shipping was a perfect match for me. It requires knowledge of the global economy, patient analysis and hands-on work. Its complexity was also very much part of the attraction,” she said.
78 Breakbulk Magazine
Issue 4 2026
breakbulk.com
By Liesl Krog
After her master’s, she faced a choice between continuing toward a PhD or putting her knowledge into practice. A job offer from Eagle Freight in the UK gave her the opportunity to do the latter. Working first with containers and then some breakbulk cargo, she began learning how the trade she had studied operated on the ground. When she returned to China, Shanghai’s ports and international connections made it a natural place to seek work. She moved into broking breakbulk cargo and handysize tonnage as China’s industrial projects generated more work and increasingly complex shipments. “In the UK my work was mostly around importing containers from China, but now I found myself on both sides, and there were some massive projects taking place in China at the time,” she said.
Asia
“IT DOES NOT MATTER HOW EXPERIENCED A LEADER BECOMES; THERE IS ALWAYS MORE TO LEARN ABOUT THE MARKET.” The Curiosity Factor
Among the companies she approached for freight rates was SAL. Its quotations puzzled her. “I kept thinking how they have such small vessels, much smaller than the handysize, so why the rate?” When a chartering position became available, she applied. Asked at the interview why she wanted to join, she candidly explained that she wanted to understand why SAL’s rates were so high. She laughs as she recalls her answer, but her frankness proved no obstacle. SAL offered her the job. She joined in 2007 and soon found the explanation. SAL’s vessels were specialized for heavy cargo and project shipments. Once she understood what they could do, the rates she had questioned made sense. “Ultimately, I chose SAL and they chose me,” she said. Looking back, she believes she made the right choice at the right time. Nearly 20 years later, she leads SAL’s business in China. “Heavy-lift shipping requires knowledge that takes years to acquire, and I have chosen to build mine within a company whose fleet and services have continued to expand. Each project is different and each has its own way to deliver,” she said. “I like the challenges and complexities. I found a space that I have been able to thrive in.”
Asia
Yi has been an active member of Women in Breakbulk and will deliver the keynote at this year’s breakfast. Credit: Hyve
The work continues to hold her interest, requiring her to keep learning as projects, equipment and customer requirements change. Through the infrastructure and industrial projects she has worked on, she has also witnessed China’s economic expansion firsthand.
Reading the Market
For Yi, understanding China’s project cargo market starts with the policies directing its development. “China is a policy-driven market. No market moves faster. One policy shift can create a whole new industry within a year.”
Yi is no stranger to China’s ports as she understands the value of hands-on experience. Credit: SAL
80 Breakbulk Magazine
Issue 4 2026
breakbulk.com
The country’s five-year plans provide signals about where investment and demand are likely to emerge. Studying them helps companies identify opportunities and prepare their capabilities before projects reach the shipping stage. By the time a policy produces visible demand, she believes, the bestprepared companies will already have done their groundwork. Preparation also requires regional knowledge. China’s scale does not make it a single, uniform market. The Yangtze Delta, northern China and the south have different industries, project requirements and business cultures, all of which influence how companies operate. “You have to be able to bridge those differences. Having in-depth local knowledge is critical for success, including understanding local policies and business culture.” Competition, she said, has intensified as Chinese capabilities have grown and customers have become more sophisticated. Yi’s task includes helping the head office in Germany understand these developments, identifying local opportunities and expanding SAL’s business in the region. Geopolitical uncertainty has
Asia
Yi has traveled aboard SAL vessels, along with their cargoes. Credit: SAL
further complicated the market. “Supply chains are more complex, with more stakeholders than ever before. Ultimately, decisions are harder and more important than ever.” Yi remains cautiously optimistic about demand, particularly across energy and industrial projects. Offshore wind operations and maintenance, floating wind farms, green methanol and ammonia projects offer opportunities, while renewable energy development also requires investment in grid and power infrastructure. “The challenge is not whether the projects exist; it is how we deliver them faster, cleaner and in a way that works for clients, governments and communities,” she said. “That takes more than machinery. It takes trust, clarity and shared understanding.” Exports of high-end Chinese equipment are another source of demand. Chinese engineering,
procurement and construction contractors are undertaking overseas projects through what she describes as a greener, more selective “Belt and Road 2.0.” Data centers and semiconductor plants are also emerging as project cargo markets. These developments have changed China’s place in the industry. Once a major importer of equipment, it has become an important source of equipment, expertise and shipping capabilities. “Perhaps China missed the great maritime age of the last century. Twenty-five years ago, China was mainly a cargo market. After twenty-five years of fast growth, it is no longer just a cargo market. It has become a resource market too,” she said. “In its own way, China is opening its own great maritime era, and we are lucky to be right here, in the middle of it.” For SAL, responding means
81 Breakbulk Magazine
Issue 4 2026
breakbulk.com
understanding where its services are needed and maintaining relationships with customers whose requirements continue to evolve. Heavy-lift capacity is limited, and customers value the certainty of securing it. They have their own shorthand for this. “Our clients often refer to SAL as ‘Space Always Limited,’ or some say, ‘Service Always Luxury,’” she said. That kind of reputation depends on relationships, and building them requires an understanding of how business is conducted locally. Yi compares mature Western markets to chess, with established rules and contracts. “China is a developing market that has grown remarkably fast. Here the players have less accumulated experience to draw on and business is more like go — the board is open. Positions are still evolving, and it can take a little longer to build mutual trust at the initial stage,” she said.
Asia
“Neither is better or worse, simply different games. In China, trustbuilding is not a formality. It is the foundation, and once established, partnerships tend to be very durable.”
Yi’s own route into leadership began on the operational side. She worked as senior chartering and project manager, handling large, complex projects for SAL’s heavy-lift fleet, before becoming Growing Together managing director of SAL China Her colleagues at SAL have been in 2020 and JSI China in 2021. equally important to Yi’s career. Within her team, she describes She credits the company’s inclusive herself as a safety net. Colleagues culture with giving her room to have room to work out their develop her own approach in a own solutions, knowing she predominantly male industry. “They is available to help. She also allowed me to be myself and to play considers humility important. to my strengths rather than ask “It does not matter how me to fit a template,” she said. experienced a leader becomes; there She hopes others will follow. “I is always more to learn about the would like to use my experience to market. It keeps changing, bringing encourage more women in shipping. new challenges and new solutions. This industry is entering its most I have been with SAL for almost 20 fascinating decade. The energy years and staying has never meant transition is the biggest project cargo standing still,” she said. “I have story of our generation and it needs grown with every new chapter.” new minds, especially female minds.” Away from work, she enjoys
BID SMART. BUY RIGHT.
82 Breakbulk Magazine
Issue 4 2026
breakbulk.com
reading, going to the gym and traveling with her family. She is involved with her daughter’s school, sometimes giving lectures to parents and students about teenage issues. Family life includes her husband, their 15-year-old daughter, her parents and the family dog. The support of her parents has given a different meaning to the decision she made at the airport. “I thought I was coming back to take care of them, but actually they are the ones taking care of me and supporting me behind the scenes, especially with how busy shipping can be,” she said. Nearly 20 years on, she has no doubts about the choice. “I feel that I made the best decision ever to come back to China,” she said. Liesl Krog is a transportation journalist based in South Africa.
Middle East By Simon West
PROJECTS DRIVING THE MIDDLE EAST FORWARD In the second in our series on Middle East projects, we examine the region’s continued appeal to international investors and spotlight some of the latest developments driving opportunities for breakbulk and project cargo. Opening the section, MEED’s Colin Foreman assesses the GCC’s resilient market while highlighting the growing challenges of project delivery.
Petrofac clean fuels project, Kuwait. Credit:Petrofac
83 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Middle East
GULF PROJECTS KEEP MOVING AMID REGIONAL CONFLICT By Colin Foreman
Al Faris handles a massive stripper vessel at an industrial project in the UAE.
T
he GCC construction market has proved more resilient in 2026 than many expected. When hostilities broke out on Feb. 28, there were fears that projects would stall. Instead, almost all projects have continued as planned, and clients have kept awarding contracts. The UAE awarded US$85.9 billion of contracts in the first nine months of the year, ahead of its pace in 2025, according to regional projects tracker MEED Projects. Saudi Arabia awarded US$68.8 billion. That is 13% lower than in the same period last year, although the kingdom’s monthly awards have exceeded 2025 levels in all but two months since the conflict began. Delivering those projects has been harder. The effective closure of the Strait of Hormuz severely disrupted supply chains into the Gulf, and contractors responded by bringing materials in through ports outside the strait. In the UAE, cargo has been landed at Fujairah and Khor Fakkan on the east coast, and at Omani ports including Colin Foreman, MEED
Credit: Al Faris
Sohar and Duqm on the Arabian Sea. Saudi Arabia has used its Red Sea coastline, importing through Jeddah and the Port of Neom in the northwest of the kingdom. Security risks around the Bab el-Mandeb strait have since added a further complication, although projects are so far progressing as planned. The outlook for 2027 is mixed. Private developers have delayed real estate launches and are likely to remain cautious. Governments have responded by accelerating infrastructure spending. Abu Dhabi is committing to rail projects, Dubai is pressing ahead with Al-Maktoum International Airport (see opposite page) and its Gold Line and
84 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Airport Express metro schemes, and Saudi Arabia is advancing King Salman International Airport and new railways. That pipeline will be supplemented by investment to strengthen the region’s logistics networks and reduce its reliance on Hormuz. MEED estimates that new rail, water and port connectivity alone could require US$30 billion to US$50 billion, alongside spending on roads and oil and gas export pipelines. Colin Foreman is editor and a construction specialist at the Middle East Economic Digest (MEED), a business intelligence service providing companies with the latest news, data and analysis from across the Middle East and Africa.
Project: Al Maktoum International Airport Expansion Location: Dubai, UAE Developer/Implementing authority: Dubai Aviation City Corporation / Dubai Aviation Engineering Projects (DAEP) Total investment: AED128 billion (about US$34.9 billion) for the new passenger terminal and associated development program. Recent awards: More than US$3.5 billion of contracts are currently under execution. Recent awards include the Phase 1 automated people mover (APM) system to a consortium of Larsen & Toubro (L&T) and Mitsubishi Heavy Industries. A roughly US$272 million contract for construction of the airport’s second runway was previously awarded to Binladin Contracting Group, while enabling works were awarded to Tristar E&C. Latest news: Construction of the first phase of the Al Maktoum International Airport expansion is progressing and is on course to begin operations in 2032. Work underway includes enabling
Project: Uthmaniyah Gas Compression Plant Location: Uthmaniyah, Eastern Province, Saudi Arabia Client/Owner: Saudi Aramco Total investment: Undisclosed Awards: Main EPC package awarded to SNSH, a 50:50 JV between Saipem and Nasser Saeed Al-Hajri Contracting
A mock-up of the new Al Maktoum International Airport. Credit: Mitsubishi Heavy Industries Credit: deugro
works, runway infrastructure, more than 17,000 concrete piles, excavation of more than 45 million cubic meters and the initial structural foundations for passenger terminals and aircraft gates. In August 2026, L&T and Mitsubishi Heavy Industries confirmed the award of a design-and-build contract for the Phase 1 APM system. The turnkey scope covers the APM system and associated infrastructure, including guideways, traction power, signaling and telecommunications, platform screen doors and depot equipment. The system will connect the airport’s terminals and concourses. The overall airport plan provides for 14 APM stations. “With challenging execution milestones, advanced technologies and multiple system interfaces including guideway, power supply, state-of-theart telecom, platform screen doors
and depot equipment, this project exemplifies the scale and complexity of integrated APM rail systems that L&T is uniquely positioned to deliver,” said Ramkumar S, EVP and head of transportation infrastructure at L&T. DAEP is preparing further major packages for award by the end of 2026, with a combined value exceeding US$15 billion. These include substructure works for the Western Passenger Terminal, the fourth aircraft concourse, baggage-handling systems, superstructure works for the Western Passenger Terminal and the first three aircraft concourses, long-span structural frameworks, southern airfield infrastructure, power generation and district cooling plants. Facade and roofing packages are also planned for award during 2026.
Company. Saipem’s share of the contract is about US$1 billion; MEED has reported the overall SNSH award at an estimated US$1.24 billion.
field in eastern Saudi Arabia. SNSH formally began EPC work at the site in August 2026, following the award in June. The contract is scheduled to run for about 42 months. The facility will serve the Uthmaniyah non-associated gas field, extending its productive life and supporting Saudi Arabia’s growing energy requirements. It is designed to handle 882 million standard cubic feet of gas per day. The plant forms part of a wider Saudi Aramco program to increase gas compression and processing capacity in the kingdom’s Eastern Province. Aramco has also awarded the program’s early site-preparation package to Al-Shalawi International Company Trading and Contracting, MEED said. As of the latest reporting available, the separate Uthmaniyah gas pipeline package had not yet been awarded.
Latest news: The Uthmaniyah Gas Compression Plant is a major natural gas infrastructure project located at the Uthmaniyah non-associated gas
The Wasit natural gas processing plant in Al-Jubail. Credit: Saudi Aramco
85 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Middle East
Project: Round-the-Clock (RTC) Renewable Energy Project Location: Abu Dhabi, UAE Developers: Masdar, Emirates Water and Electricity Company (EWEC) Total investment: US$6.1 billion (US$1 billion Masdar equity and US$5.1 billion financing). EPC awards: Larsen & Toubro and PowerChina
Masdar is involved in the development of the Mohammed bin Rashid Al Maktoum Solar Park in Dubai. Credit: Masdar
Latest news: The RTC Renewable Energy Project is billed as the world’s first giga-scale 24/7 clean energy facility, combining a 5.2-gigawatt (GW) solar photovoltaic (PV) plant with a 19-gigawatt-hour (GWh) battery energy storage system to deliver a continuous 1.0 GW of baseload power. Operations at the landmark facility are slated to begin in 2027. According to Mohamed Al Muharrami, associate director of project delivery at Masdar, the US$5.1 billion financing package is
technologically advanced system of its kind in the world,” he said. “Financial close demonstrates that large-scale renewable energy projects capable of delivering round-the-clock power have evolved from technical ambition to commercially bankable infrastructure.” The project, which broke ground in October 2025, will integrate utility-scale solar generation with battery storage capable of shifting and supplying electricity when solar power is unavailable. This configuration is intended to support rising electricity demand from data centers, AI, advanced manufacturing and wider economic growth.
EPC award: Contract awarded to a consortium comprising Egypt’s Petrojet and Jordanian contractor Ahmad Yousef Al-Tarawneh and Partners.
Yousef Al-Tarawneh and Partners. The project covers the design, procurement, construction and installation of a 22-kilometer natural gas pipeline linking Al-Muwaqqar to the Arab Gas Pipeline. The scope also includes gas pressure reduction and metering stations, and sending and receiving facilities for pipeline inspection equipment. Construction is scheduled to be completed within 18 months. The Al-Muwaqqar project forms part of a wider US$70 million program, supported and financed by the ADFD, to supply natural gas to two Jordanian industrial cities. The second project will supply AlRawdah in the Ma’an Development Zone and has been awarded separately to TAQA Arabia Group. Jordan’s energy ministry said the two projects are aimed at providing industrial users with an alternative energy source, reducing energy costs and strengthening the competitiveness of the country’s industrial sector.
Latest news: Petrojet has signed a US$22.7 million contract to connect Jordan’s Al-Muwaqqar Industrial City, south of Amman, to the country’s natural gas network. The contract was signed in August 2026. Petrojet will execute the work in a consortium with Jordan’s Ahmad Credit: Aleksandarlittlewolf Magnific
Project: Al-Muwaqqar Industrial City Natural Gas Supply Project Location: Al-Muwaqqar, south of Amman, Jordan Client: Jordan Ministry of Energy and Mineral Resources Financing: Abu Dhabi Fund for Development (ADFD), as part of a US$70 million program supporting natural gas supply projects for the Al-Muwaqqar and Al-Rawdah industrial cities. The US$70 million applies to the two projects combined, not solely to Al-Muwaqqar.
backed by 13 leading international and local banks, demonstrating the strong confidence in the project’s commercial fundamentals and Masdar’s execution capabilities. Financial close was achieved in July 2026. Masdar announced in January 2025 that Larsen & Toubro (L&T) and PowerChina were preferred EPC contractors, with letters of award signed for both. Earlier this year, PowerChina disclosed a US$1.9 billion EPC contract for its portion of the project; the value of L&T’s contract has not been disclosed. “Integrating a 5.2-GW solar PV plant with a 19-GWh battery energy storage system, RTC is the largest and most
86 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Middle East Project: Misfah CCGT Power Plant Location: Misfah, Muscat Governorate, Oman Owners/Developers: Consortium formed by Nebras Power (Qatar), Emirates Utilities Development Company (UAE) and Bahwan Infrastructure Services (Oman) Total investment: The Misfah project forms part of a joint investment program for the Misfah and Duqm CCGT plants with a combined estimated investment of about US$2.6 billion. The investment figure for Misfah alone has not been disclosed. EPC award: JV between China’s SEPCOIII and South Korea’s Doosan Enerbility. Siemens Energy is supplying the gas turbines and long-term services. Latest news: SEPCOIII and Doosan announced the signing of the turnkey EPC contract for the 1.7-GW Misfah combined-cycle gas turbine (CCGT) power generation plant in Oman in August 2026. The total
A mock-up of the Misfah CCGT project in Oman. Credit: SEPCOIII
contract amount is roughly US$693 million, according to Doosan. The plant will be located some 20 kilometers west of Oman’s capital city Muscat, with operations scheduled to begin in April 2029. Once completed, the project will provide 1.7 GW of new gas-fired generation capacity to support electricity demand and strengthen the security and reliability of Oman’s power supply.
SABIC awarded the EPC contract in September to Samsung E&A. Credit: SABIC
Project: SAN-7 Fertilizer Project Location: Jubail Industrial City, eastern Saudi Arabia Client/Developer: SABIC Agri-Nutrients EPC award: Samsung E&A Total investment: Approximately US$3.5 billion EPC contract
Latest news: Samsung E&A signed the EPC contract for the SAN-7 project in September 2026, with completion scheduled for 2030. The facility will produce 3,500 metric tons of ammonia and 7,700 metric tons of urea per day, with all urea production destined for
87 Breakbulk Magazine
Issue 4 2026
breakbulk.com
“Our successful project execution and differentiated strategy in neighboring Middle Eastern countries such as Saudi Arabia and Qatar have led to this contract award,” said Hyeonho Lee, CEO of Doosan Enerbility’s Plant EPC Business Group. “We will work with our partners to build a world-class power plant and contribute to stabilizing electricity supply in Oman.”
export. The project will incorporate a post-combustion carbon-capture system to use CO2 generated during ammonia production in the urea synthesis process. The SAN-7 project will significantly expand SABIC Agri-Nutrients’ fertilizer production capacity in Jubail and is expected to strengthen Saudi Arabia’s position in the global agriculturalnutrients export market. The project represents a major expansion of conventional ammonia and urea production, while incorporating carbon-capture technology to reduce emissions intensity. “Through this expansion project, we aim to secure reliable and sustainable supplies for our customers, maximize value for our shareholders, contribute to realizing the goals of Saudi Vision 2030, and support global food security,” said Fahad Al-Battar, CEO of SABIC AN. *Breakbulk Global Shipper Program participant
Europe
BALTIC BREAKOUT
Offshore Wind Pipeline Shifts Focus From Ambition to Execution By Luke King
The MV Lone supports the installation of a transition piece for the Baltic Power offshore wind farm in Poland. Credit: SAL
88 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Europe
O
ffshore wind has endured a difficult few years in Europe. Rising costs, supply chain pressures and problems with auction models have delayed projects and, in some markets, caused developers to reconsider investments. In the Baltic Sea, however, the direction of travel looks rather different, with Poland in particular moving from years of planning into construction and execution. The region has an estimated offshore wind technical potential of more than 90 gigawatts (GW), with Poland emerging as the largest nearterm market. After years in which much of that potential existed largely on paper, turbines are now turning, specialist port infrastructure is nearing completion and increasingly complex project cargo is actually moving through the supply chain. Baltic Power, the 1.14-GW project being developed by ORLEN and Northland Power off Poland’s northern coast, began generating its first electricity this summer. The project comprises 76 Vestas V236 15.0-megawatt (MW) turbines and is one of the first commercial deployments of the manufacturer’s latest offshore platform. Behind it comes a growing pipeline, led by the 1.5-GW Baltica 2 project being developed by PGE and Ørsted, while Baltica 3, BC-Wind and further developments could extend construction activity well into the next decade. “The feeling of ‘I will believe it only after I see it with my own eyes’ is now gone,” Jakub Walasek, director Poland at UTC Overseas, told Breakbulk. Walasek has good reason to say so. UTC was involved in logistics for Baltic Power, transporting four 345-ton transformers and four 135-ton shunt reactors to a greenfield site in an area whose infrastructure was never designed with cargo of that scale in mind.
89 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Europe
A rendering of the completed T5 Offshore Wind Terminal, designed to support Baltica 2. Credit: Istrana
Jakub Walasek, UTC Overseas
Lech Paszkowski, Istrana
“What was most significant was that the delivery location is a greenfield in a rural, tourist area and local roads were not prepared for that,” he said. “We needed to start from scratch and find the right solution.”
from the main port, Gdańsk or Gdynia, but still the bridges are class B or C.” The answer increasingly involves multimodal logistics, with ocean shipping, barging and heavy road transport combined according to the limitations of individual sites. Bigger Cargo, “The more demanding the final Bigger Challenges destination, the more multimodal That experience illustrates one the transport is,” Walasek said. of the challenges facing Baltic “We are in a race where engineers offshore wind. Baltic Power’s are preparing the best solution for a onshore substation is located at problem with certain rules, trying to Osieki Lęborskie, close to Poland’s find a suitable solution for the least Baltic coast, meaning UTC had to amount of money. Someone wins, and find a route for the transformers then the rules change because there and reactors through an area where is another project with different rules. infrastructure was never designed It’s like motorsport, that is basically for cargo of that scale. Walasek a description of our business.” sees road access as potentially the Recent work on Baltica 2 provides biggest logistics challenge as more another example. COLI Group projects move into construction. completed a six-month campaign for “This part of northern Poland was GE Vernova involving 14 large power primarily a tourist area, and all the transformers moved from Türkiye infrastructure was developed for that to Poland across three chartered purpose,” he said. “There are fishing voyages. Ten units weighing between ports nearby to skip the road transport 110 and 170 tons were discharged in
90 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Gdynia for onward road transport, while four 361-ton transformers followed a different route, moving by barge to Władysławowo before a complex RoRo operation. The land transport required temporary flyover structures to be installed over existing bridges that could not support the cargo, while movements were coordinated with local authorities and continued through temperatures as low as minus 15C. “Moving 14 large and heavy units to the same site in three months in challenging conditions is not something any freight forwarder does every day,” Felix Peinemann, managing director of COLI Group, said. Offshore execution is becoming equally specialized. JSI member SAL’s vessel MV Lone carried out the installation of all 76 transition pieces for Baltic Power, working with Van Oord and the wider project team. SAL’s scope went beyond transport and lifting, including the design and fabrication of dedicated installation and lifting tools and a custom sea-fastening grillage. The campaign was MV Lone’s first transition piece installation project.
Port Readiness
Major investment is also taking place ashore, including at the Port of Gdańsk, where a new installation terminal is being developed specifically for offshore wind. The structure behind the project involves several entities. The Port
Europe
Navigator Transport delivers a large electrical transformer for the Baltica 2 wind farm. Credit: UTC Overseas
of Gdańsk Authority manages the wider port, while Baltic Hub Container Terminal operates the neighboring deepwater container terminal. Baltic Hub, together with the Polish Development Fund’s PFR FIZAN investment fund, is a shareholder in Istrana, the special-purpose company responsible for developing the new T5 Offshore Wind Terminal. The 21-hectare heavy-duty facility is being constructed on reclaimed land alongside Baltic Hub and will initially support the construction of Baltica 2, giving the project a purpose-built base for the storage, pre-assembly and loading of offshore wind components. Lech Paszkowski, CEO of Istrana, said the development demonstrates how far the market has moved. “For many years, offshore wind in the Baltic Sea was discussed primarily in terms of potential. Today, we are seeing tangible assets
being built, investments being committed and infrastructure being delivered,” he told Breakbulk. “Two years ago, the T5 project existed largely on paper. Today, the terminal is substantially completed, all key administrative decisions and permits have been secured, including the final occupancy permit, and we are in the final phase of finishing surface and infrastructure works ahead of handover to our first sub-lessee later this year.” T5 has been designed specifically around the dimensions and weights of modern offshore wind equipment. Three dedicated quays will support different cargo flows, including an outbound quay capable of accommodating two jack-up installation vessels simultaneously, as well as separate facilities for LoLo and RoRo imports. Paszkowski said the terminal will be able to handle next-
91 Breakbulk Magazine
Issue 4 2026
breakbulk.com
generation blades, towers and nacelles and, in the future, large monopiles. But building enough port infrastructure is only part of the equation. Offshore wind manufacturers are confronting similar challenges as they increase production of ever-larger equipment, providing an indication of what can happen when a new supply chain is asked to scale rapidly. Vestas began producing its V23615.0 MW nacelles at Szczecin, Poland, in 2025. Baltic Power is among the first commercial projects using the turbine, which has 115.5-meter blades and a rotor diameter of 236 meters. In its 2025 annual report, Vestas was candid about the challenges of industrializing the platform, saying the learning curve across its factories had been “steeper than planned,” resulting in bottlenecks and delays despite mitigation efforts across its value chain.
Europe
UTC handles equipment in Poland for the Baltic offshore wind farm. Credit: UTC Overseas
The manufacturer said it had subsequently reduced production times significantly, but described the journey toward serial production and installation at Baltic Power and Germany’s He Dreiht project as “long and challenging.” The experience points to a wider issue for the Baltic: a large project pipeline promises work for manufacturers, ports, vessel operators and project forwarders, but delivering too much capacity simultaneously risks overwhelming the very supply chain being created to serve it.
Managing the Build-Out
Paszkowski said Poland currently has only two locations with dedicated installation terminal capabilities for large offshore wind campaigns, Gdańsk and Świnoujście. Even large terminals cannot efficiently accommodate an unlimited number of projects simultaneously, given that offshore wind campaigns require extensive areas for storage, preassembly and vessel operations. “If too many projects are scheduled within the same timeframe, capacity constraints can emerge, leading to higher logistics and installation costs and potentially forcing some activities to be relocated outside Poland or delayed,” he said. “Port infrastructure cannot simply be expanded overnight, so project schedules need to be
aligned with the capacity that will realistically be available in the market.” The objective, Paszkowski added, should be a stable and predictable pipeline, allowing ports, contractors, vessel operators and other supply chain companies to plan investments around a phased rollout rather than a sudden concentration of projects. Investment in supporting infrastructure is also extending beyond Poland. In July, WIND Group signed a long-term agreement with Smålandshamnar to establish a dedicated cable storage and offshore service hub at the Port of Oskarshamn in Sweden. The facility will provide cable transportation and storage, carousel rental, marshaling, equipment supply, maintenance and vessel mobilization services. The port offers a 435-meter quay and minimum water depth of 10.3 meters, allowing ship-to-ship cable transfers and access for vessels serving projects across the Baltic. Similar investment will be needed as offshore wind development expands around the region. Lithuania has about 1.4 GW of capacity envisaged across two projects, while further developments are planned in the German Baltic. For Poland, meanwhile, the logistics sector is already treating offshore wind less as a future opportunity and more as an established market.
92 Breakbulk Magazine
Issue 4 2026
breakbulk.com
UTC has participated in further tenders since its Baltic Power work and is expanding its engineering capabilities in anticipation of more complex assignments, according to Walasek. The change in attitude among local ports and other stakeholders has been equally significant. What was regarded with skepticism only two years ago, he said, is increasingly seen as “business as usual.” For Paszkowski, the bigger challenge now is ensuring that the projects themselves keep pace with the infrastructure being built to serve them. “Ultimately, the biggest remaining bottleneck is not the availability of port infrastructure itself, but ensuring that the development of offshore wind projects, supply chain capacity and logistics assets progresses in a coordinated manner.” For the Baltic offshore wind industry, that may be the clearest indication of how far the market has come. The debate is no longer about how many gigawatts could eventually be installed. Increasingly, the challenge is how to manufacture, move, marshal and install the equipment required to turn that potential into operating wind farms. Involved in the project logistics industry since 2007, Luke King is a regular contributor to Breakbulk Magazine and host of the Project Cargo Professionals podcast. *Breakbulk exhibitor *Breakbulk Global Shipper Program participant
Breakbulk Americas Update
WHERE INNOVATION MEETS INDUSTRY Opsima Takes Top Honors at Breakbulk Americas 2026 Innovation Pitch
C
ongratulations to Opsima, winner of the Breakbulk Americas 2026 Innovation Pitch. The live startup competition brought five companies head-to-head on the Breakbulk Voices Stage, pitching market-ready solutions to an expert judging panel and an audience of attendees at Breakbulk Americas in Houston. Opsima impressed the judges with its “software factory,” which turns customers’ workflows into production-ready software. The company focuses on processes that standard business systems often struggle to handle, helping operators replace manual tasks such as packing list data entry and equipment tracking. Its pitch also showcased work with Port Newark Container Terminal (PNCT), where Opsima reports a 5% increase in fleet availability and 15% fewer breakdowns. The competition is designed to give companies a platform to test their ideas, gain industry feedback
Alon Gozlan, co-founder and chief business officer at Opsima, pitches to judges and attendees at Breakbulk Americas in Houston. Credit: Marco Wang
and raise their profile, while giving the breakbulk and project cargo industry a glimpse of what’s next. Our congratulations again to Opsima, and thanks to fellow finalists Freight Canvas, Project Logistics Engineering Solutions, CargoEZ and Emerger for sharing their ideas. And a special thank you to judges Shazia Panjwani, AI product manager at UTC Overseas, and Matthew Costello, co-founder and CEO of Voyager Portal, for their time and expertise. The Breakbulk Asia 2026 Innovation Pitch will be held on the Breakbulk Voices Stage on Wednesday, Nov. 18 from 1:50pm - 3:00pm. Surya Dhamija, co-founder of CargoEZ, outlines his company’s innovation at the Breakbulk Voices Stage. Credit: Marco Wang
93 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Americas
NORTH AMERICAN PROJECT CARGO IN 2030: EVANS TRANSPORTATION’S VIEW OF THE NEXT INDUSTRIAL LOGISTICS CYCLE
Presenting the winner of Breakbulk’s first scenario-writing contest, where future-thinking contestants answered the question: How will the U.S. domestic manufacturing boom reshape the project cargo supply chain by 2030? By Brock Simon
B
y 2030, the reshoring and expansion of U.S. manufacturing have fundamentally changed the project cargo and breakbulk landscape across North America. What began in the middle of the decade as a series of major investments in semiconductors, batteries, energy infrastructure, data centers, advanced manufacturing and industrial facilities evolved into a broader reconfiguration of how large-scale freight moves across the continent. From Evans Transportation’s perspective, the most important change has not simply been an increase in freight volume. It has been an increase in complexity. The project cargo market of 2030 requires deeper planning, stronger carrier relationships, better technology, greater visibility and logistics partners capable of managing the entire operating environment surrounding a shipment. Evans’ current strategy already points in that direction. Our focus is on relationship-driven partnerships, technology-enabled transportation management, specialized expertise,
structures and other oversized components moving from multiple suppliers to tightly controlled job sites. Evans was already managing this type of complexity in 2025, executing more than 20,000 data center-related shipments, including hundreds of generator enclosures and high-voltage transformers. By 2030, similar logistics models have become common across other industrial sectors. Brock Simon, Large manufacturing facilities, Evans Transportation energy projects, battery plants, semiconductor facilities and carrier diversification and advanced industrial sites repeatable operating processes increasingly depend on synchronized that allow us to support increasingly deliveries from multiple origins. complex supply chains. The result has been a shift away from thinking about project cargo as A Different Mix a collection of individual heavy-haul of Projects and Cargo shipments. Instead, major projects Looking back from 2030, one of are managed as integrated supply the defining characteristics of chains involving truckload, heavy the industrial expansion has been haul, rail, port activity, temporary the diversity of the projects. storage, staging, transloading, The data center sector became one rigging and final-mile delivery. of the clearest examples. Individual That shift has created a campuses required generators, much greater need for logistics high-voltage transformers, cooling providers that can coordinate equipment, electrical gear, fabricated these pieces under one plan.
94 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Americas
Credit: Evans Transportation
New Freight Corridors and More Multimodal Thinking
North American project cargo flows have also become less predictable and more distributed. By 2030, the traditional port-toproject model still plays an important role, but a larger share of project freight originates within North America. Domestic manufacturing has created new flows between equipment manufacturers, fabrication facilities, assembly plants, rail terminals, inland storage locations and construction sites. Cross-border movements between the United States and Mexico have also become increasingly important. Evans’ experience supporting generator deliveries into the Mexico City region demonstrated the value of established cross-border infrastructure, carrier relationships and coordination through locations
such as Laredo. By 2030, corridors connecting Mexican manufacturing centers with U.S. industrial projects have become a larger part of the project logistics network. No single transportation mode has been able to handle that growth alone. Ports continue to serve as critical gateways for transformers, industrial modules, machinery and imported equipment. Railroads have become more important for long-distance movement of heavy components where highway weight and infrastructure limitations create challenges. Specialized trucking remains essential for final delivery and time-sensitive movements. Heavy-lift and specialized carriers provide the equipment and technical expertise required to move increasingly large cargo safely. The strongest solutions increasingly combine those modes instead of treating them independently.
95 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Logistics Partnerships Have Become More Integrated
Perhaps the largest structural change by 2030 is the role of the logistics provider itself. Customers no longer want to manage dozens of independent providers and resolve problems shipment by shipment. They increasingly expect a lead logistics partner to coordinate carriers, permitting, routing, storage, site access, technology, reporting and exception management. Evans has been building toward this control-tower model. Our specialized project teams bring together project managers, account management, operations, billing, leadership and subject-matter experts to create centralized oversight. That model has expanded across the industry.
Americas
Ports, railroads, trucking companies, heavy-haul carriers, EPCs, crane and rigging firms, storage providers and technology companies are still independent organizations, but the most successful project environments operate as collaborative networks. EPCs and manufacturers increasingly involve transportation providers earlier in project planning. Ports and railroads provide input on capacity and infrastructure limitations before equipment is produced. Specialized carriers help determine the most practical trailer configuration and route. Technology providers connect shipment data, location information and project milestones. The companies that collaborate early tend to avoid the most expensive surprises later.
Customer Expectations Have Changed
By 2030, simply delivering freight safely and on time is no longer enough to differentiate a project logistics provider. Those expectations remain fundamental, but customers increasingly expect logistics partners to provide visibility, risk identification, cost control, planning support and measurable operational improvement. Evans has already seen this evolution. Customers value KPI monitoring, pre-project site visits, on-site coordination, specialized capacity, storage solutions, purchase-order cost control and technology integration. Technology has played an important role, but not necessarily in the way many expected. Real-time tracking, automated alerts, digital documentation, integrated TMS platforms and dynamic reporting have dramatically improved visibility. Evans has already used real-time technology to identify permitted-route deviations and intervene before an incident occurred.
But technology has not replaced experienced project managers. Instead, the most effective model has become technology identifying the issue and experienced people determining the response. The repetitive work has increasingly been automated, while experienced logistics professionals spend more time on planning, customer communication, carrier management, risk mitigation and exception handling. That aligns directly with Evans’ broader technology strategy of using automation to support people rather than replace the relationshipdriven nature of logistics.
The Biggest Constraints Were Not Always Where Expected
Looking back from 2030, the greatest constraints were not simply transportation capacity. Labor remained important, especially experienced drivers, project managers, equipment operators, rigging professionals and permitting specialists. Specialized trailer availability also became difficult during peak project cycles. But some of the most significant obstacles appeared outside the traditional freight market. Permitting complexity remained a major issue because oversized and overweight transportation still depends on state, local and sometimes municipal requirements. Evans’ experience has long shown that permit lead times, escort requirements, routing restrictions, seasonal frost laws, bridge limitations and superload approvals can materially affect both cost and schedule. Infrastructure also became a larger constraint. Bridges, road geometry, overhead clearance, turning radius and site access were not designed around every new industrial project. In many cases, the question was not whether a trailer existed that could carry the cargo; it was whether
96 Breakbulk Magazine
Issue 4 2026
breakbulk.com
the surrounding infrastructure could accommodate the move. Grid capacity emerged as another major factor. Projects could have land, financing, construction plans and transportation strategies in place but still face delays because power generation and transmission infrastructure could not keep pace with demand. Trade policy and geopolitics added another layer of uncertainty. Changing sourcing strategies forced project teams to maintain greater flexibility in origins, ports, suppliers and transportation corridors.
Regional Winners and Challenged Markets
The regions that benefited most were generally those able to combine industrial investment with transportation infrastructure, labor availability, land, energy capacity and access to multiple freight modes. Markets with strong highway networks, inland logistics infrastructure, rail connectivity, nearby manufacturing and access to major ports were better positioned to handle project growth. At the same time, some of the fastest-growing areas experienced the greatest pressure. A region could attract billions of dollars in development and still struggle with narrow road networks, limited staging space, insufficient specialized carrier capacity, permitting delays or overloaded local infrastructure. This created an important lesson: Attracting the project was only the first step. The surrounding logistics ecosystem had to scale with it.
The Assumption That Proved Wrong
Perhaps the biggest surprise between 2026 and 2030 was the belief that technology and additional freight capacity would make project logistics substantially easier. They did not.
Americas
Technology made information faster. New capacity increased options. Automation reduced repetitive work. But the projects themselves became more complicated even faster. More suppliers, tighter schedules, larger components, constrained job sites, cross-border sourcing, changing regulations and increasing customer expectations meant that visibility alone did not solve the problem. The industry learned that information is not the same as execution. Knowing where a 150,000-pound piece of equipment is located does not determine whether the next bridge can support it. A digital platform does not replace a route survey. An automated rate does not determine whether a trailer can make the final turn into a job site. Tracking technology does not eliminate the need for a project manager to respond when a
permitted-route deviation occurs. That realization reinforced something Evans has believed for years: Logistics remains a people-driven business.
What the Industry Looks Like in 2030
By 2030, the most successful project cargo organizations are not necessarily the companies with the most trucks, the largest technology platform or the most locations. They are the companies capable of bringing people, technology, specialized capacity and partnerships together around a disciplined operating process. Evans’ vision for that environment is straightforward. Project logistics must become fast, clean and predictable even when the projects themselves are anything but simple. That requires earlier
involvement, better planning, trusted carrier relationships, multimodal thinking, strong compliance, real-time visibility and people who understand how to solve problems before those problems affect the project. The industrial transformation of North America has created tremendous opportunity for the breakbulk and project cargo industry. It has also raised the standard for everyone involved. By 2030, moving the freight is only one part of the job. The real value lies in managing the complexity around it. Brock Simon is VP Strategy & Ops - SSD at Evans Transportation.
The world’s leading magazine for heavy lifting and transport equipment M A G A Z I N E
©
M A G A Z I N E
©
THE WORLD'S LEADING MAGAZINE FOR HEAVY LIFTINGTHE & TRANSPORT EQUIPMENT WORLD'S LEADIN G MAGAZ September 2026 INE FOR HEAVY LIFTING & TRANSPORT EQUIPM ENT
April -May 2026
FlexMAX ahead of
a 140 kms
journey
IDEA Logistics: More Than a Move
MOVE IT MAGAZINE
newsletter now :
Jaso Cranes Conquer Chile’s Chacao Canal
combinations
What’s Moving in France?
Register to
TexasRT Factory TEREX The New Giants and Current Trends Infrastructure the TTC 70 Launch of Nuclear in Construction Surge Construction Technology
HidDen cost of incidents
SUBSCRIBE AND FOLLOW US ! Autonomous Logistics and Port Operations
moveitmagazine.com
97 Breakbulk Magazine
Issue 4 2026
breakbulk.com
THE LAST LOOK
Port of Pascagoula and its partners at Signet Maritime transport an offshore rig to its final voyage after occupying the port’s West Harbor for nearly a decade. More than the end of an era, its removal clears valuable waterfront space for future development, new opportunities and continued growth, showing the power of partnership to make way for what comes next. Port of Pascagoula entered this photo in Breakbulk Americas’ “Houston, We Have Power” photo contest. Credit: Joseph Powell
98 Breakbulk Magazine
Issue 4 2026
breakbulk.com
Lifting your cargoes faster
stevedoring & warehousing rotterdam PROJECT CARGO & HEAVY LIFTS UP TO 2200 TONS 2 X 208 TON CAP. SHORECRANES OPTIMIZED TRUCK EXIT FOR WINDMILL BLADES & TOWERS HEAVY LIFT STORAGE AREA MOBILISATION/DEMOBILISATION OFFSHORE PROJECTS ISPS CERTIFIED AEO-F CERTIFIED
Waalhaven n.z. 4 3087 BL Rotterdam P.O. Box 55092 3008 EB Rotterdam Portnumber 2157 TELEPHONE
+31 (0)10 429 94 33 FA X
+31 (0)10 429 02 61 E-MAIL
office@rhb.nl WEB
www.rhb.nl
shorecranes up to 312 tons (combined)