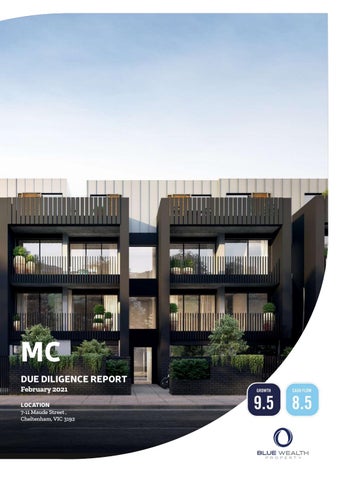
MC DUE DILIGENCE REPORT February 2021 LOCATION 7-11 Maude Street , Cheltenham, VIC 3192
Disclaimer The information in this document is not investment advice. The information in this document has been published as an information service. The information contains general information and does not take into account any investor’s particular circumstances and needs. Each investor should consider whether the information is appropriate for his or her particular needs, financial situation and investment objectives. While the information provided by Blue Wealth Property is believed to be accurate, Blue Wealth Property does not accept responsibility for any inaccuracy or any actions taken upon reliance of the information in this report. No returns or performance is guaranteed. Any forecasts are dependent on the current market conditions and knowledge available at the time of producing this document. Important Notices This information is subject to change without notice. Updated information can be obtained by contacting Blue Wealth Property on (02) 9743 0077 or their authorised Business Partners.
CONTENTS
CONTENTS Cheltenham
01
1.0 MC
10
3.0 Cheltenham
10
3.1 Population & Demographics
03
2.0 Melbourne
11
3.2 Economics & Employment
04
2.1 Population & Demographics
12
3.3 Infrastructure Spending
05
2.2 Economics & Employment
13
3.4 Supply & Demand
07
2.3 Infrastructure Spending
08
2.4 Supply & Demand
14
4.0 Floorplate
15
5.0 Renders
19
6.0 Pitard Group
1.0 MC
1.0 MC Project Details • Located 18 kilometres south-east of Melbourne • Bound by Black Rock, Sandringham and Hampton, some of Melbourne’s most sought-after suburbs • Home to several of Melbourne’s most prestigious golf clubs and the Southland Westfield, Cheltenham offers a desirable lifestyle • Based on population forecasts, the City of Kingston’s population is set to increase by 1,400 residents per from from now until 2036 • Median weekly household incomes in Cheltenham are only $200 below Hawthorn where the median house
34 apartments
below balanced levels and
Price ranges
indicating a severe undersupply • Indigo is located less than 500
1 bedroom, 1 bathroom, 1 car space: from $535,000
metres from the local train station,
2 bedroom, 2 bathroom, 1 car space: from $665,000
Westfield and local shopping
Size ranges
strip, a well-connected location enhances the resale and rental demand • The well-designed floor plans combined with high quality and amenities exposes a strong value proposition • A boutique project of only 34 generous apartments • Combined developer/builder means outstanding quality and
Cheltenham’s. This represents
attention to detail
the opportunity for future growth
Number of dwellings
by a vacancy rate of 0.8%, well
price is $1 million higher than strong relative affordability and
1
• Strong rental market characterised
1 bedroom, 1 bathroom, 1 car space: 59 - 67sqm 2 bedroom, 2 bathroom, 1 car space: 76 – 97sqm
Estimated completion Completed
Estimated outgoings Council & Water Rates: $2000 p.a approx Indicative Strata Levies: $1,600 - $2,800 p.a approx
Conditions of purchase Holding Deposit: $1,000 Deposit on Exchange: 10% on exchange of contracts Deposit Type: Cash and Bank Guarantee (balance on completion)
1.0 MC
MC Cheltenham, Victoria
2
2.0 MELBOURNE
2.0 MELBOURNE Victoria
‘Melbourne was voted the world's most liveable city for seven years running' Melbourne is Australia’s second largest city and voted the world’s most liveable city for seven consecutive years by the Economist Intelligence Unit. This comes down to a unique combination of diverse demographics, strong sports, entertainment and café culture and well-planned transport systems and infrastructure. The Melbourne property market has a rare structure, with varying growth rates on product type (houses and apartments) and location making it difficult to place the city on the property clock. Broadly speaking, Melbourne’s housing market performed strongly between 2012 and 2017 – with only Sydney recording a higher growth rate. The markets segmented nature means each region must be assessed on its individual merit. The division in the market exposes opportunities and the sub-markets best representing growth potential.
3
2.0 MELBOURNE
‘By 2031 Melbourne is
2.1
projected to overtake Sydney as Australia’s most populous city’
Population & Demographics As of August 2018, ABS reported
is based on the evolution of a
that the population of Greater
population’s age structure, gender
Melbourne reached 5 million
or living arrangements. The way we
residents. Melbourne has added
live provides policy makers with the
over 120,000 new residents each
information they need to plan for
year for the past three years – the
future demands for housing, land and
highest of any Australian city.
infrastructure.
With population growth like this, Melbourne needs to add 45,000 new dwellings per year, or nearly 1,000 per week. A record 18,000 Australians migrated to Victoria in 2017, largely because of housing affordability and job creation. Melbourne has been growing faster than Sydney over the past decade, according to the Australian Bureau of Statistics (ABS), and is set to become Australia’s most populous city by 2031. To accommodate for this growth, the city will require an additional 1.6 million dwellings.
The current household size of 2.7 people and the growing proportion of lone person households suggest that the dwellings required could be provided through apartment development. As at June 30th 2018, the lone person household and coupled families without children make up 49% of Greater Melbourne’s population. This means that half of Greater Melbourne’s households are well suited to apartment living. The number of lone person households is projected to grow 59% by 2031, the fastest of the varying household
Assessing the population structure
types. Strong house price growth in
and how this may change in the
Melbourne’s metropolitan areas is
future is critical to understanding
likely to strain affordability and result
where the demand for property
in an increase in demand for more
will come from. Government policy
affordable apartment dwellings.
4
2.0 MELBOURNE
2.2
Economics & Employment
Victoria
Gross state product
Percentage of Australian gross domestic product
$385.9 billion
23.6%
Melbourne has solidified its position
The Melbourne economy is
Over the last 5 years, Victoria has
as Australia’s strongest economic
continually shifting away from the
added more jobs than any other state.
performer, now boasting the
manufacturing based industries into
According to data from the federal
country’s highest contribution to
the less volatile professional services.
government, Victoria’s employment
the GDP. According to Commsec’s
This has been the most significant
base increased by 100,200 jobs in
quarter 4, 2018 State of States
change to Melbourne's economy.
the 12 months to 2018. This job
report it also recorded 3.3% annual
The evolution has allowed for a more
creation was dominated by full
GSP growth making it the nation’s
diversified base of employment-
time employment signifying the
top performer. A solid indicator
generating industries, which has
strength of the diversified economy.
for the strength of state economy
strengthened the resilience of the
In the five years between 2017 to
is the acceleration in retail trade.
city’s labour market to external
2022, federal statistics forecast
Over the past 12 months, retail
shocks and structural adjustment
Victorian employment to increase
trade has grown by almost 5%, in
pressures.
8.8% - outpacing that of the national
a performance outpacing all other states.
5
average.
2.0 MELBOURNE
Victoria’s gross state product grew by 3.3% over 2018, making it the country's top perfromer
6
2.0 MELBOURNE
2.3
Infrastructure Spending Melbourne has been nominated as the world’s most liveable city seven out of the last eight years. The Victorian Government maintains that the key to upholding this status rests upon infrastructural investment as a driver. To proactively plan for future needs, while implementing innovative visions the ‘Plan Melbourne’ vison was conceived. The plan that extends its vision through to 2050, is structured to design Melbourne’s housing, commercial and industrial development for future levels of need.
Sky Rail Project This multi billion project is aimed at easing traffic congestion throughout the whole of Greater Melbourne. 75 differing level train crossings are being removed and lifted over a 5 year construction timeframe.
The plan integrates over 112 future action plans to accommodate for future
Completion is expected to be finished
population, housing and employment needs. Major growth corridors in the
by 2022.
Southwest (Wyndham-Geelong), North (Hume) and Southeast (Dandenong) will ultimately be connected as a planned economic triangle. Major investments
Fishermans Bend Urban Renewal
include:
The largest urban renewal project in Australia, the precinct is located
West Gate Tunnel Project Construction on the project begins in 2018 and completion is anticipated for 2022. It involves widening the West Gate Tunnel enhancing connectivity from the south west of Melbourne into the CBD. The project is expected to create 6,000 jobs. Metro Tunnel Rail Link The $10 billion project consists of two 9 kilometre train tunnels, including five underground stations from South Kensington to South Yarra. The construction will result in the employment of 3,500 people. Construction will began in 2018 and is forecast to be completed by 2020. On completion the project will service an extra 35,000 commuters during peak hour.
7
1 kilometre south west of the CBD. Over 250 hectares has been rezoned for residential, commercial and retail spaces in an attempt to expand the capital city zone. The area has potential to accommodate 40,000 jobs and 80,000 residents.
2.0 MELBOURNE
2.4
Supply & Demand The Melbourne property market
high-density dwellings tenanted
can be best described as segmented,
and occupied quickly. Melbourne
with discontinuity on a suburb by
had a vacancy rate of 2.9% as of
suburb basis. The result is, significant
August 2019, with 3% indicating a
variation in property market gauges
balanced market, as a result Greater
(supply, vacancy rates, time on
Melbourne is heavily undersupplied.
market, yields and the like) when a
With projected population increases
granular (suburb by suburb) approach
exceeding those of other capital
of analysis is taken.
cities, Melbourne is challenged
The strong performance in Melbourne’s housing market and strain on affordability is driving demand for townhomes and apartments. This coupled with strong population growth in Metro
with the task of ensuring long term strategies are applied that will allow supply to match demand sustainably. Projections suggest that 1.6 million dwellings are required to keep up with population forecasts to 2031.
Melbourne has seen medium and
8
3.0 CHELTENHAM
Cheltenham, Victoria
9
3.0 CHELTENHAM
3.0 CHELTENHAM 3.1 Population & Demographics Population growth
Median age
Average household size
1,400 new residents by 2036
40
2.5
City of Kingston LGA is forecast to
resident is 40 years old an employed
There is a strong presence of couples
experience population growth of
in white collar occupation. Around
without children (making up over
18.6% per cent to 198,340 by 2041,
30% of the local workforce are
34.6% of local families) indicating the
equating to approximately 1,500
employed in either a professional,
specific need for apartment supply,
new residents per year. The LGA
or managerial role - indicating the
particularly in an area where median
development guidelines restrict the
strength of the local tenant pool.
house prices have performance
density of future development. This
The average household size of 2.5
strongly over the last 5-year period.
will ensure demand is high for the
indicates that both one and two
The significant disparity between
existing homes and new dwellings
bedrooms are suited to the market
house and apartment prices will be
which offer an affordable option for a
demographic.
a major driver for apartment demand.
down sizers demographic.
According to ABS data, over 24.9%
According to the Australian Bureau
of dwellings within Cheltenham
of Statistics census data, Cheltenham
are rented (a statistic higher than
has a population of 22,291 living in
the Australian and Victorian state
9,649 dwellings with an average
average) highlighting the suitability
household size of 2.5. The average
of rental tenure within the suburb.
10
3.0 CHELTENHAM
‘Median household incomes in Blackburn are 26.7% higher than the Victorian state average’
3.2
Economics & Employment Gross Regional Product
Industry Profile
Income Growth
$11.37 billion
White Collar
5%
Melbourne boasts Australia’s fastest
The hospital industry employs
The employment profile of
growing economy, in the 12 months
the largest portion of residents
Cheltenham residents is white
to May 2017, Victoria recorded the
(3.9%), many of which are likely
collar. The average weekly household
highest rate of job creation in the
to be employed at the Moorabbin
income is $1,502, 5% higher than the
country. It added over 115,000 new
Hospital. Some of the other key local
Victorian median household income.
jobs whilst the nation’s net job
employment nodes are:
Median house prices in Cheltenham
creation was 95,000.
Monash University, Caulfield
The City of Kingston has a Gross
Campus: This is the second
Regional Product of $10.94 billion
largest Monash University
representing 2.7% of the state’s
campus. The campus educates
Gross State Product (GSP). The City
over 1,050 students and employs
of Kingston provides 91,988 local
over 1,900 staff
jobs with the largest industry being manufacturing. In Cheltenham, the industries of employment are quite diverse, no industry makes up more than 5% of the total employment. The diversity of employment makes the suburb less susceptible to risk of widespread unemployment.
11
•
•
are 14 times the median annual household income, as opposed to the Victorian suburb of Hawthorn where median house prices are 24 times the median household income. This illustrates relative affordability, highlighting the opportunity and
Morabbin Business and
potential for future growth in
Industrial Park
Cheltenham.
The Melbourne CBD is also very accessible from Cheltenham. The suburb offers a direct train line into Melbourne which only takes 35 minutes.
3.0 CHELTENHAM
3.3
Infrastructure Spending The Victorian Government continue
There has also been a focus on
Westfield Southland has now
to invest in the state infrastructure.
transport and road infrastructure
established its own train station,
Understanding the extent of
throughout Victoria. The removal
which is Melbourne’s newest station
the population growth they are
of level crossings has been a focus
and only 500 metres from Indigo.
experiencing, it is critical that
throughout the south-east. This
The $21 million project increases the
sufficient infrastructure is in place to
eases transport within the suburb,
capacity of the current train line.
cope with future growth.
removing traffic congestion while
The Monash Freeway Upgrade is
also increasing the capacity of the
worth over $400 million, widening
train line. The removal of level
the M1 free way to improve roads and
crossings as part of the Sky Rail
reduce travel time into the city.
The Victorian Budget for 2018/19 has highlighted education as a major focus for Melbourne’s inner south east. Over $800 million will be dedicated to building new and upgrading existing schools in the south east. Schools such as the below are being upgraded: •
Bentleigh West Primary
•
East Bentleigh Primary
•
Ormond Primary
•
Sandringham East Primary
•
McKinnon Secondary College
Project has already occurred in suburbs like Carnegie, McKinnon, Bentleigh and is scheduled to occur in late 2018 at the Cheltenham Train Station. The Sky Rail Project ($1.6 billion) involves the upgrade of train stations between Caulfield and Dandenong increasing accessibility from the south-east into the city.
12
3.0 CHELTENHAM
3.4
Supply & Demand
Vacancy Rate
Dwellings Required
Estimated time on market
1.9%
15,000 by 2036
57 days
The best measure of supply and
Height restrictions and floor to space
In the past five years, Cheltenham’s
demand is a vacancy rate. A
ratio regulations have meant that
median house price increased by 80%.
balanced market is likely to present
most of development within the
As of December 2019, the vacancy
a vacancy rate of 3% this allows for
inner parts of a suburb are low rise
rate in Cheltenham is 1.9% indicating
the natural vacation and uptake of
and boutique. Apartment projects
a heavily undersupplied market.
rental properties. Markets with a
of 30 – 50 apartments have become
vacancy rate below 3% suggests they
very acceptable and are attracting
are undersupplied. Generally, the
high demand from the downsizer.
south-eastern region of Melbourne
The lack of affordable accommodation
has maintained low vacancy rates,
has been reflected in the growth in
particularly the City of Bayside and
median house prices, many suburbs
the City of Kingston. The LGA’s have
experiencing increases in excess of
maintained higher levels of control
60%.
around future development.
13
Constrained supply and rising demand is likely drive an uplift in apartment prices. The significant disparity between house and apartment prices of 70% will result in a considerable demand shift away from homes toward apartments.
4.0 FLOORPLATE
4.0 FLOORPLATE
Private Open Space: 12m2
AC
AC
Private Open Space: 12m2
AC
AC 1.01 Area: 80m
1.09 Area: 76m2
Private Open Space: 11m2
Private Open Space: 14m2
N
1.02 Area: 77m
2
2
Private Open Space: 11m2
1.10 Area: 82m2 AC
1.08 Area: 59m2
1.03 Area: 59m2 Private Open Space: 10m2 AC 1.06 Area: 67m2
1.04 Area: 84m2
AC
AC
Private Open Space: 12m2
Private Open Space: 13m2
AC AC
Private Open Space: 16m2
Private Open Space: 18m2
1.07 Area: 82m2
1.05 Area: 68m2
M A U D E S T RE E T EFFECTIVE FLOOR PLANS, WITH AN EFFICIENT USE OF ALL FLOOR SPACE
REV DOCUMENT / DRAWING IS PROTECTED BY FEDERAL A GHT LAW COPYING IN ANY SHAPE OR FORM, IN WHOLE OR IN ITHOUT THE WRITTEN AUTHORISATION OF EWERT LEAF Pty. TRICTLY PROHIBITED.
O NOT SCALE, USE FIGURED DIMENSIONS ONLY. ALL MENSIONS ARE TO BE CONFIRMED ON SITE PRIOR TO OMMENCEMENT OR FABRICATION OF ANY WORK. NY DIMENSIONAL DISCREPANCY TO BE BROUGHT TO THE TENTION OF EWERT LEAF IN WRITING. L WORK IS TO BE CARRIED OUT IN ACCORDANCE WITH THE RRENT BUILDING CODE OF AUSTRALIA AND ANY RELEVANT USTRALIAN STANDARD, AND ALSO ANY LOCAL AUTHORITY -LAW'S.
LARGE EXTERNAL AREAS, APPEALING TO THE OWNER OCCUPIER DEMOGRAPHIC
FLOOR TO CEILING GLASS WINDOWS, ALLOWS MAXIMUM NATURAL LIGHT THROUGHOUT ALL APARTMENTS
LANDSCAPED FEATURES THROUGHOUT BALUSTRADES – SHOWING HIGH QUALITY TOUCHES IN PROJECT
M C C H E LT E N H A M . C
This floorplan is for marketin The information contained in produced in good faith with been measured in accordanc of Australia method of meas
FIRST FLOOR DATE 10.09.18
DESCRIPTION
CHECKED
REV
DATE
DESCRIPTION
CHECKED
PROJE
ISSUE FOR INFORMATION
7-1 14
7 C V
5.0 RENDERS
5.0 RENDERS Pace Of Blackburn
Building Exterior MC, Cheltenham
15
5.0 RENDERS
Living Area MC, Cheltenham
Kitchen MC, Cheltenham
16
5.0 RENDERS
Bedroom MC, Cheltenham
17
5.0 RENDERS
Bathroom MC, Cheltenham
18
6.0 PITARD GROUP
6.0 PITARD GROUP Pitard Group has been built on our commitment to quality and innovation, and our team brings unmatched skill, vision and dedication to everything we do. By collaborating as one unit, we seek to create unique places that foster a greater sense of health and wellbeing for those who inhabit them. Our expertise extends to all areas of acquisition, feasibility, design and development, construction, sales and property management. We specialise in all facets of development, from land acquisition to construction, sales and property management. With a history spanning more than two decades, we have garnered a trusted reputation for our fastidious attention to detail, exceptional quality of products and deep community focus.
19
6.0 PITARD GROUP
Matilda on Maude Pitard Group
20
Level 2, 8 Australia Avenue, Sydney Olympic Park, NSW 2127 P: +61 (0)2 9743 0077 | E: enquiries@bluewealth.com.au | W: www.bluewealth.com.au