AI boom lifts whilemining competing for power
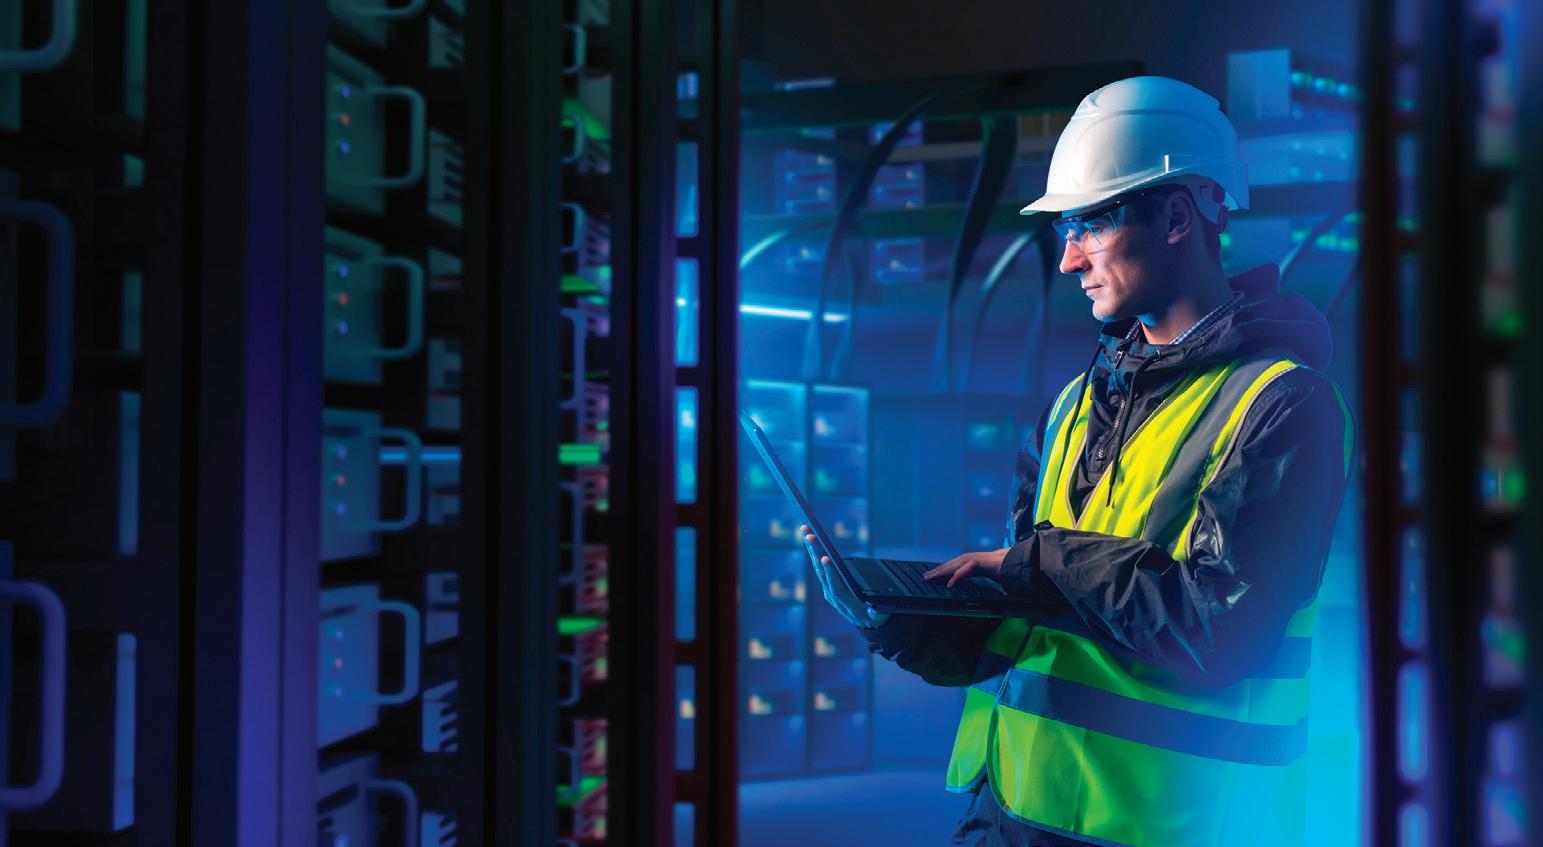
Data centres challenge mines beyond metal demand
BY HENRY LAZENBY
Alberta’s data-centre rush is spilling onto mine development, with E3 Lithium (TSXV: ETL; US-OTC: EEMMF) saying opposition to nearby proposals is tarnishing the goodwill it built for its Clearwater lithium project.
Facebook owner Meta Platforms (Nasdaq: META) broke ground in July on a 1-gigawatt AI centre worth more than $13 billion (US$9.5 billion) in Sturgeon County, about 35 km northeast of Edmonton. Roughly 200 km south, E3 is advancing one of Canada’s largest battery metal projects, Clearwater near Olds, where separate data-centre plans have stirred concerns over noise, water and industrial growth.
“We have a very strong reputation that’s being tarnished a little bit by the data centres who have come in and not done that proper engagement,” E3 CEO Chris Doornbos told The Northern Miner. “They have just come in and stated what they’re going to do without really listening.”
Artificial intelligence is becoming both customer and rival for
mining. Data centres lift demand for copper, lithium, aluminium, uranium and rare earths, but they also draw on the same electricity, workers, equipment and public support for large projects that miners need to supply those materials. Alberta and British Columbia are already changing power rules before fast-moving, hyper-scaling technology companies crowd slower mine projects out of scarce infrastructure.
Metals Pull
AI’s demand prize for mining is substantial. With the International Energy Agency expecting global data-centre electricity use to roughly double to about 950 terawatt-hours by 2030, or close to 3% of world demand, that buildout requires oodles of copper and aluminium.
Data halls, substations, generating plants and transmission lines all need the metals. Backup systems add battery metals, while chips depend on silicon, gallium and other specialty materials.
S&P Global (NYSE: SPGI) forecasts copper demand will rise by half to 42 million tonnes in 2040 from 28 million tonnes in 2025.
“Electricity has become a strategic resource, just like the critical minerals we mine.”
CHRIS MCCLEAVE, VALE BASE METALS CHIEF TECHNICAL OFFICER
Without large investments in mines, processing and recycling, supply could fall 10 million tonnes short, the research firm told The Northern Miner by email.
Vale Base Metals, the copper and nickel arm of Brazil-based Vale (NYSE: VALE), likewise sees AI as a driver for copper demand and nickel to a lesser extent mainly through batteries that provide backup power.
“The rapid growth of AI, cloud computing and hyperscale data centres has added a new structural source of copper demand on top of electrification, renewable energy, grid expansion, defence, robotics and electric vehicles,” Vale Base
Metals Chief Technical Officer
Chris McCleave said in a response to emailed questions.
Doornbos said some data-centre developers are considering extending battery backup from four hours to eight, which would double the battery capacity needed at those sites. Western battery plants built for stronger electric-vehicle forecasts are already pursuing stationary-storage customers, he said.
Power queue
The Alberta Electric System Operator imposed an interim 1,200-megawatt (MW) limit on large new connections through 2028. The grid operator is now drafting longer-term rules for data centres and other big users, including a system that would favour projects paired with new power generation.
Generation presents the largest bottleneck to serving data centres and traditional industries at the same time, the operator told The Northern Miner by email. It assesses all large users by the power requested and whether the grid can serve them reliably, though it recognizes data centres carry a differ-
Artificial intelligence is improving operations, driving demand for metals and increasing pressure on electricity grids.
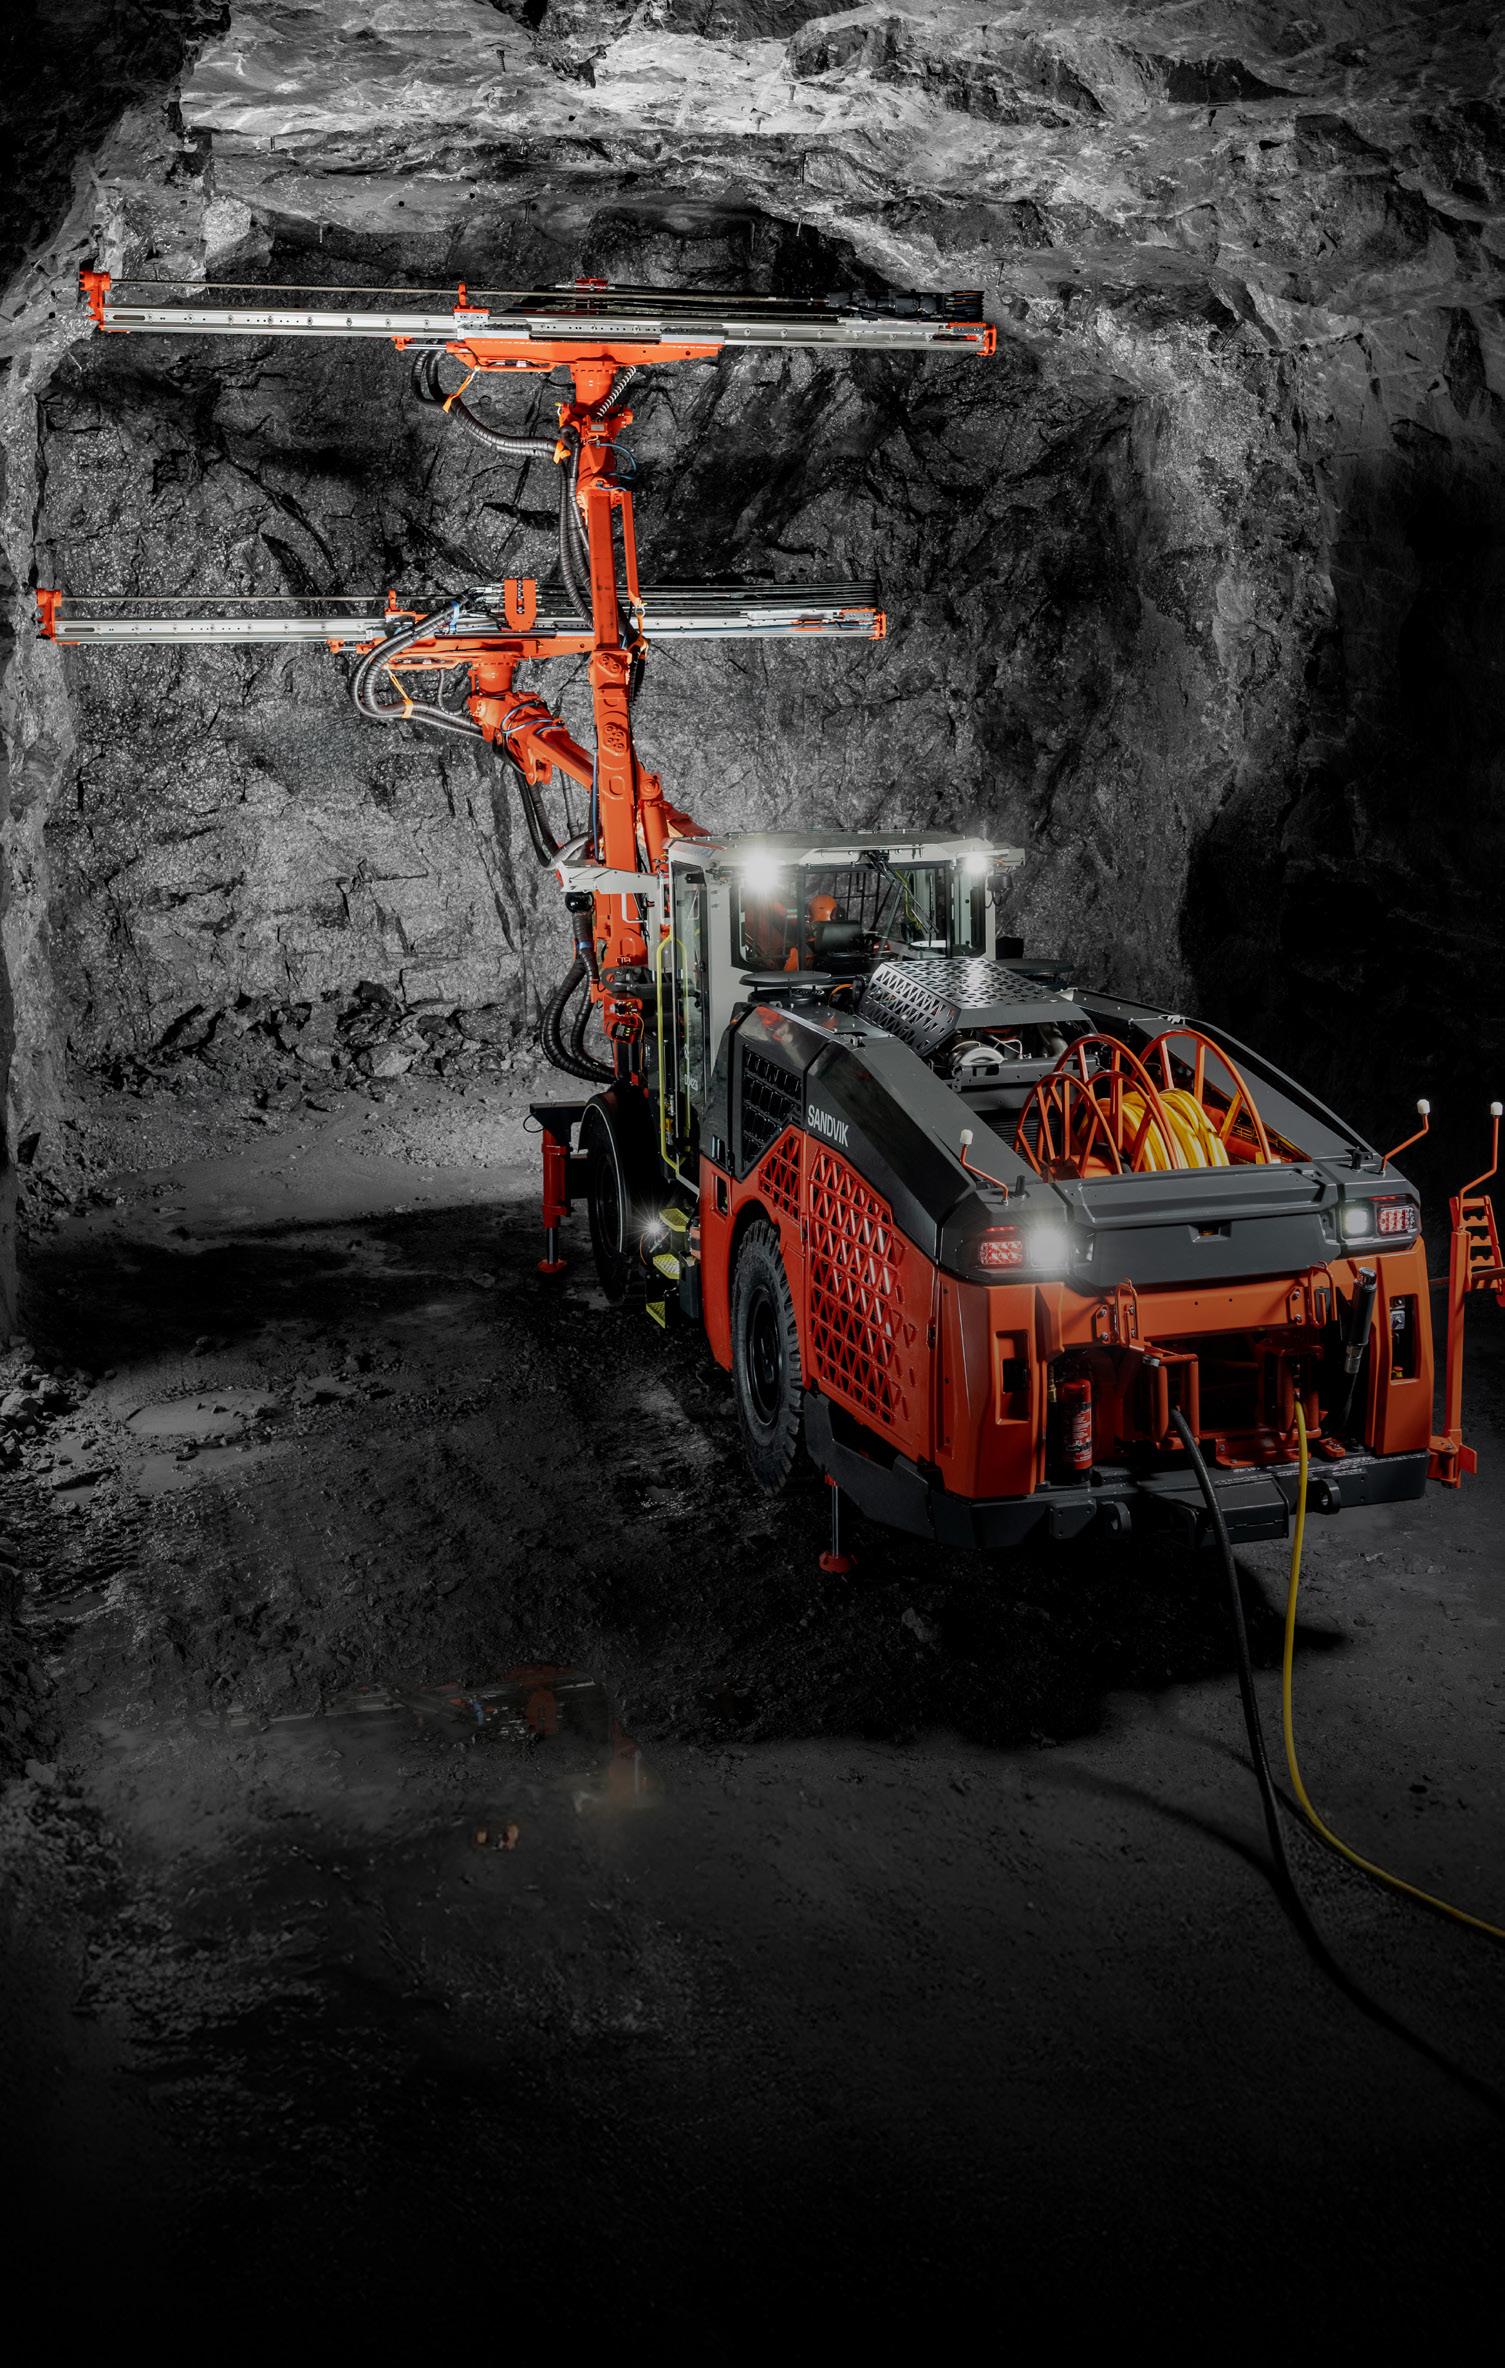
This highly intelligent drill offers more versatility thanks to its new boom design increasing both the face coverage and crosscut drilling. It can drill face sizes from 4 to 7.8 meters.
inbrief
n Digital push
Canada has launched a digital permitting initiative aimed at accelerating approvals for major resource projects by improving coordination among federal departments and reducing regulatory delays.
The platform found at https://osdp-psdo.canada.ca/dp/en brings together geospatial science, environmental monitoring, mapping tools and regulatory records from federal, provincial and territorial governments into a single online portal.
It’s intended to give regulators, companies, Indigenous communities and the public access to the same authoritative science and regulatory information. It will support Ottawa’s broader push to speed development of critical minerals and other strategic resource projects.
n Cadillac bet
Agnico Eagle is investing another $60 million (US$42.6 million) in Cadillac Mines, raising its stake as the junior advances a large land package in Quebec’s Abitibi greenstone belt.
The investment, announced in late July as Cadillac was preparing a $385-million initial public offering, strengthens Agnico’s exposure to gold projects surrounding its existing mines while supporting the junior developer’s exploration plans.
Backed by mining entrepreneur Pierre Lassonde, Cadillac is consolidating historic gold camps and advancing nearby targets. The deal reflects Agnico’s strategy of securing future exploration opportunities close to its assets.
n Goodbye Ekati
Canada’s first diamond mine is due to shut in mid-August following years of declining output.
Ekati in the Northwest Territories was placed into receivership last month by a Supreme Court of British Columbia ruling after no buyer could be found. It had been producing diamonds since 1988.
Low diamond prices, U.S. tariffs, growing competition from synthetic stones and inflationary pressures all played a part in Ekati’s demise.
Attention will now shift to reclamation and environmental protection. Anglo American’s Gahcho Kué is Canada’s last major diamond mine.
n Hollywood hire
British Columbia-based junior Novared Mining named U.S. film producer Lee Caplin to its board in a bid to tap his political and business connections.
The appointment expands NovaRed’s push beyond mineral exploration as it seeks to commercialize MetalCore AI, a platform that uses artificial intelligence, machine learning, computer vision and predictive analytics to analyze geological data and identify exploration targets while advancing the Wilmac copper-gold project and Lamont Ridge property in B.C.
NovaRed made headlines in June by appointing former U.S. Secretary for Homeland Security Kristi Noem as an advisor.
BY NORTHERN MINER STAFF
n Gold-free gold
A proposed U.S. gold dollar coin promoted by President Donald Trump would contain no gold despite its name.
The commemorative coin will carry a gold-coloured finish but will be struck from base metals and enter production in Philadelphia ahead of a planned release this fall, according to a U.S. Mint spokesperson cited by The Wall Street Journal
The proposal has generated criticism because it depicts a sitting president. It also highlights the distinction between circulating coinage and bullion products.
n De Beers bid
Former De Beers CEO Gareth Penny is leading an investor group seeking to acquire the diamond business that Anglo American has put up for sale.
The bid comes as Anglo restructures following investor pressure to sell assets.
Any transaction would rank among the mining sector’s largest deals this year and could reshape the global diamond industry as it grapples with weak demand and competition from lab-grown stones.
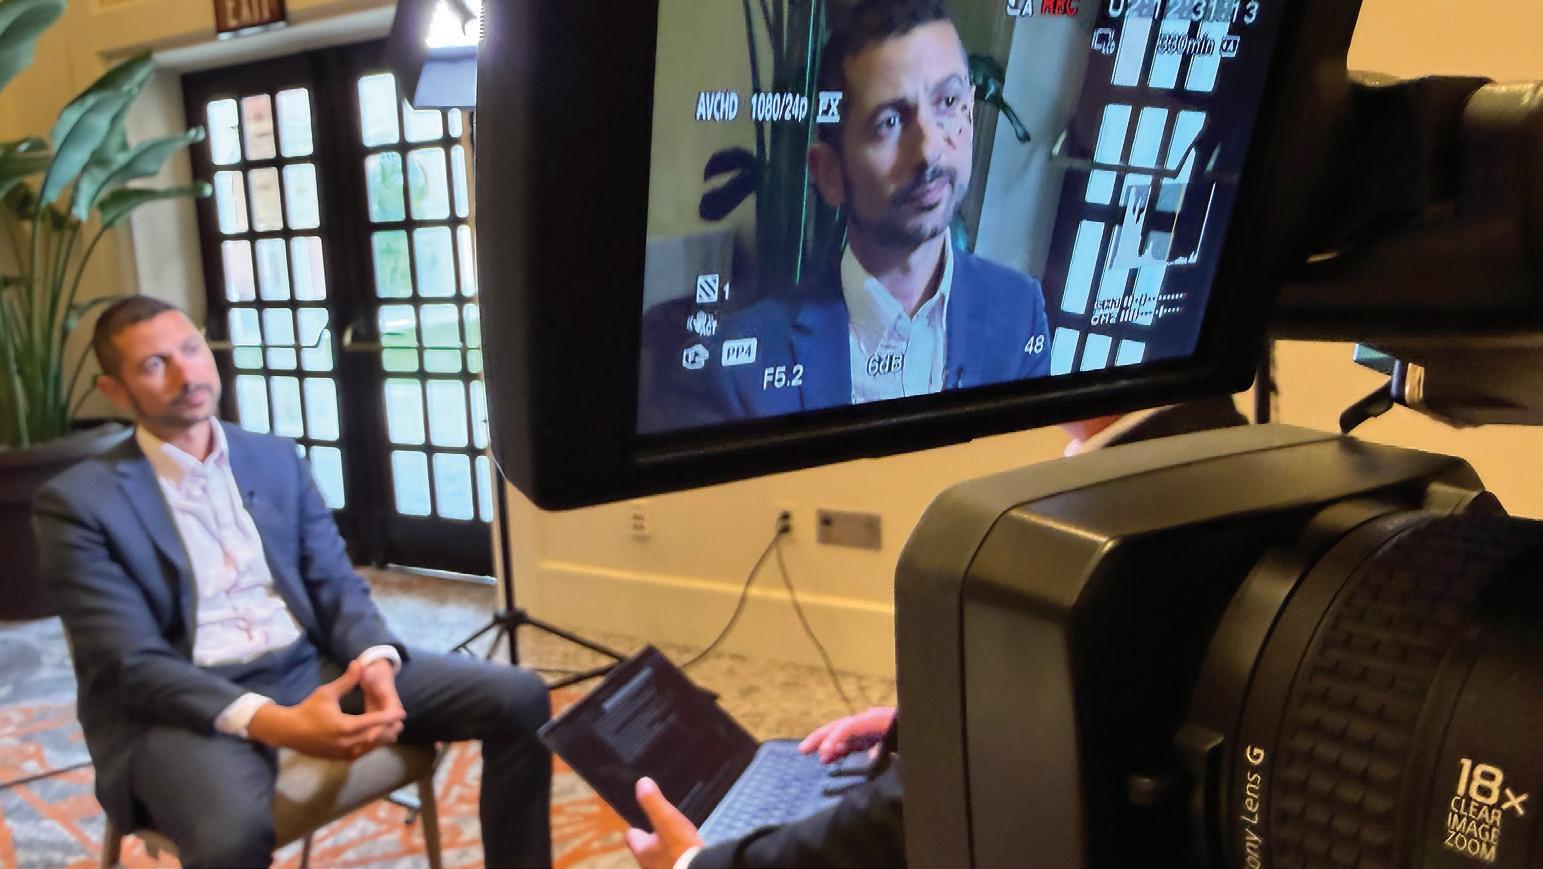
First Majestic Silver President and Chief Corporate Development Officer Mani Alkhafaji speaks with The Northern Miner’s Henry Lazenby at the Rule Symposium in Boca Raton, Fla. The miner raised its silver production outlook as stronger prices
cash flow
funded expansion across its Mexican operations.
CREDIT: HENRY LAZENBY
GLOBAL MINING NEWS • SINCE 1915 www.northernminer.com
PRESIDENT THE NORTHERN MINER GROUP: Anthony Vaccaro, CFA, MBA avaccaro@northernminer.com
EDITOR-IN-CHIEF: Colin McClelland cmcclelland@northernminer.com
COPY EDITOR AND PRODUCTION EDITOR: Blair McBride bmcbride@northernminer.com
SENIOR STAFF WRITER: Frédéric Tomesco ftomesco@northernminer.com
WESTERN EDITOR: Henry Lazenby hlazenby@northernminer.com
PODCAST HOST: Adrian Pocobelli apocobelli@northernminer.com
ADVERTISING: Robert Hertzman (416) 898-6654 rhertzman@northernminer.com
Kathleen Plamondon (514) 917-5284 kplamondon@northernminer.com
Michael Winter (416) 510-6772 mwinter@northernminer.com
SUBSCRIPTION SALES/ APPOINTMENT NOTICES/ CAREER ADS
George Agelopoulos (416) 510-5104 (Toll free) 1-888-502-3456, ext. 43702 gagelopoulos@northernminer.com
PRODUCTION MANAGER: Jessica Jubb (416) 510-5213 jjubb@northernminer.com
CIRCULATION/CUSTOMER SERVICE: (416) 510-6789 | 1-888-502-3456 northernminer2@northernminer.com
REPUBLISHING: (416) 510-6768 jmonteiro@northernminergroup.com
ADDRESS: Toronto Head Office
69 Yonge St, Toronto, ON M5E 1K3 (416) 510-6789 tnm@northernminer.com
SUBSCRIPTION RATES: Canada:
C$130.00 one year; 5% G.S.T. to CDN orders.
7% P.S.T. to BC orders
13% H.S.T.
809744071RT001
EDITORIAL
opinion
Industrial power returns
BY COLIN Mc
For much of the past three decades, mining executives struggled to convince governments that minerals were strategic assets. They no longer have to make that case because the world has made it for them.
Russia’s invasion of Ukraine exposed the importance of industrial capacity in sustaining modern warfare. China’s willingness to use export controls on critical minerals demonstrated that processing can be as powerful as production. Artificial intelligence is driving unprecedented demand for electricity, copper and the infrastructure needed to connect them. (See our page one story.)
These drivers are often treated as separate stories, but they aren’t. Together, they mark a profound shift in how governments think about mining. It is no longer viewed simply as a cyclical industry that produces commodities. It is increasingly seen as a foundation of economic resilience and national security. The evidence stretches far beyond mining circles.
In May, the Washington-based Center for Strategic and International Studies (CSIS) defined economic warfare as “the use of financial, industrial, trade, and regulatory tools to shape how states convert resources into military power.”
Industrial power has always underpinned military success, from Britain’s Industrial Revolution to the United States out-producing Germany and Japan during World War 2. Today, however, it is measured as much by critical minerals, refining, semiconductors, electricity and AI as by factories and shipyards.
In June, G7 leaders agreed to establish a critical minerals alliance aimed at reducing dependence on any single supplier like China, coordinating stockpiles and expanding the International Energy Agency’s role in monitoring markets and issuing early warnings.
The initiative is about more than trade since it reflects a recognition that secure mineral supply chains are now considered part of national preparedness.
These aren’t isolated policy announcements because they reflect a broader realization that resilience in supply chains is becoming as important as the efficiency that drove them for decades.
Ukraine has reinforced that lesson. The war has become one of industrial endurance as much as battlefield tactics, with the ability to produce shells, drones and missiles proving as important as military strategy. Manufacturing capacity is once again viewed as a defence capability.
As Gracelin Baskaran and Meredith Schwartz of CSIS observed in their April report on China’s rare earth export restrictions, “True resilience will be measured not by policy announcements or deployed capital, but by sustained output, diversified supply, and the ability to attract private investment.”
The challenge is that industrial capacity takes years to permit, finance and build. Despite billions of dollars in federal support and almost 150 critical minerals projects, the U.S. still can’t produce enough rare earths, tungsten, tantalum and magnets to meet defence demand on its own, Reuters reported in late July. A Jan. 1 deadline for self-sufficiency is out of reach.
Of course there are lots of challenges. In Alberta, proposed AI data centres are competing with industrial projects for electricity and grid connections. Across North America, utilities are warning that transmission capacity, not generation, is becoming the bottleneck.
Governments are simultaneously scrambling to secure supplies of copper, rare earths, graphite, tungsten and other materials needed not only for batteries and power grids, but also for missiles, aircraft, radar systems and communications equipment. Increasingly, the same metals serve both civilian and military purposes.
NATO members are rebuilding munitions stockpiles and strengthening domestic industrial capacity after decades of outsourcing and just-intime supply chains. The objective is not simply to field better weapons, but to ensure they can continue producing them during a prolonged conflict.
This convergence is changing mining’s place in the economy as the industry no longer simply supplies manufacturers. It’s supporting the infrastructure on which digital economies, energy systems and national defence all depend.
Researchers at the Washington-based Resources for the Future reach a similar conclusion from a different direction. In a report from May, the group argues rebuilding domestic mineral supply chains requires far more than geology. Workforce shortages, processing capacity, infrastructure, permitting, community support and long-term policy certainty all determine whether new supply can actually be developed.
In other words, critical minerals policy is becoming industrial policy. Success, however, will depend less on discovering the next orebody than on building the infrastructure, processing capacity and social licence needed to bring those resources to market.
For years, the industry argued that it deserved a place at the centre of economic policy. Governments often viewed that as special pleading from another cyclical sector.
Now, they see mines producing copper, nickel, rare earths and uranium as the first link in supply chains that underpin AI, the energy transition and national defence. That changes the conversation, even if it doesn’t guarantee higher prices or easier permitting.
Mining has become more important, not because the industry is waving flags, but because governments, military planners and technology companies have all reached the same conclusion. Industrial strength begins with secure supplies of minerals.
And that means the path to economic and military power increasingly begins where mining has always begun: in the ground. TNM
COMMENTARY
Seeing the district for the deposit
BY JAMES COOPER
Amineral
ore body usually sits by itself in a remote, rarely visited location. An anomaly in an otherwise barren expanse of nothing.
But sometimes they form clusers or groups of deposits. It’s these types of places where the geology is so fertile that one discovery is not the end of the story but the beginning of several new ones.
Chile’s Atacama Desert is a good example. A single porphyry copper system, cracked open by explorers last century, went on to spawn the Escondida, Chuquicamata and Collahuasi mines. These mines have contributed a major share of global copper output for well over 100 years, and they’re still operating today.
Zambia’s Copperbelt tells a similar story. Early 20th century discoveries gave rise to mines that have now operated for generations, underpinning an entire national economy along the way. So, what did they have in common?
These regions didn’t come to fame from a single discovery. They gave birth to multiple major discoveries over several years, fuelling the national income of their host countries.
Those are two examples of what giant mineral frontiers can look like: a handful of early discoveries prove up a large, mineralized belt, and from there, decades of follow-on mines emerge.
And if you thought the days of discovering regions like this were over, you’d be wrong.
High Andes frontier
Sitting high up in the Andes of Argentina is an area vastly underexplored compared with the heavily trodden ground across the border in Chile. It’s a region called the Vicuña District, and it bears striking parallels to the historic copper provinces of the past.
To date, the district hosts only one moderate-sized mine: Caserones. So, it’s not there yet; the region is still in its infancy.
But nearby, Filo del Sol and Josemaría, two advanced copper-gold-silver projects, are being carried toward development by a joint venture between major players Lundin Mining and BHP. These miners bought out the original discoverer, Filo Mining.
In February, Lundin Mining released a technical study describing a project capable of ranking among the top five copper, gold
and silver mining complexes on the planet, with an initial mine life stretching beyond 70 years. But that’s unlikely to be the last we hear of the Vicuña.
Discovery pattern
One sign of a giant mineral frontier is repetition: new discoveries keep turning up along the same trend. Vicuña has already delivered that pattern.
Explorer NGEx Minerals, working a target called Lunahuasi just a few kilometres from Filo del Sol, has returned some of the highest-grade copper-gold-silver intercepts seen anywhere in the world, including a high-grade core running above 30% copper-equivalent.
Then came a discovery hole that intersected more than 1,600 continuous metres of copper-gold mineralization, opening up a new porphyry target beneath the highgrade veins already being drilled. And with that, a swarm of smaller explorers moved in.
Several companies have since staked claims along the same structural corridor, within a few kilometres of Filo del Sol and Lunahuasi. Chasing the same geological trend that’s rapidly building this district into a major new copper district.
That’s how Chile’s Atacama and Zambia’s world-famous Copperbelt unfolded: a major discovery, followed by a wave of explorers proving that the fertility extends beyond the original find.
Why frontiers matter
Individual mines get depleted. Mineral frontiers don’t, at least not on any timeframe that matters to an investor. As one deposit moves toward development, exploration continues along the rest of the trend, and new discoveries keep the region relevant for decades. When companies of the size of BHP and Lundin Mining commit capital to a district this early, it’s usually because they see the same pattern we’ve described here. None of this means every company in the district will succeed. Exploration is exploration, and plenty of ground here remains untested.
But the ingredients that turned the Atacama and the Copperbelt into mining provinces that lasted a century are visible in Vicuña today: a major early discovery, repeat success along the same trend, and majors willing to commit for the long haul. TNM
James Cooper is a geologist based in Australia who runs the commodities investment service Diggers and Drillers. You can also follow him on X @JCooperGeo.
CLELLAND
Can better chemistry solve mining’s processing problem? Inside Dundee
BY DEVAN MURUGAN, THETFORD MINES, QUE.
Mining has always been about overcoming obstacles.
For much of the industry’s history, the challenge was finding deposits. Today, many producers face a different problem: extracting metals economically from increasingly complex ore bodies while satisfying stricter environmental and social expectations.
With miners tapping into lowergrade and more complicated resources, processing has become a major challenge. The real question now is not just if the metal is there, but if it can be recovered in a way that makes sense for business and the environment.
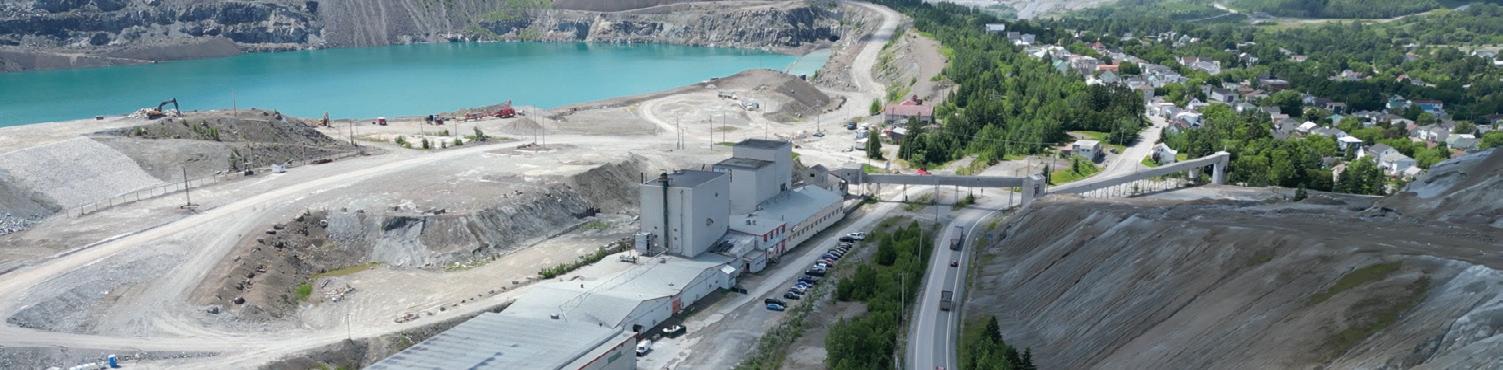
That challenge is evident at Dundee Sustainable Technologies’ facility in Thetford Mines, Que., where the company has spent more than a decade developing and demonstrating alternative metallurgical processes aimed at improving metal recovery while addressing some of mining’s most persistent environmental concerns.
“We’ve been here for over a decade,” president and CEO Jean-Philippe Mai said during a recent tour of the company’s operation. “We’ve built everything from laboratory facilities to pilot-scale operations and industrial demonstration plants.”
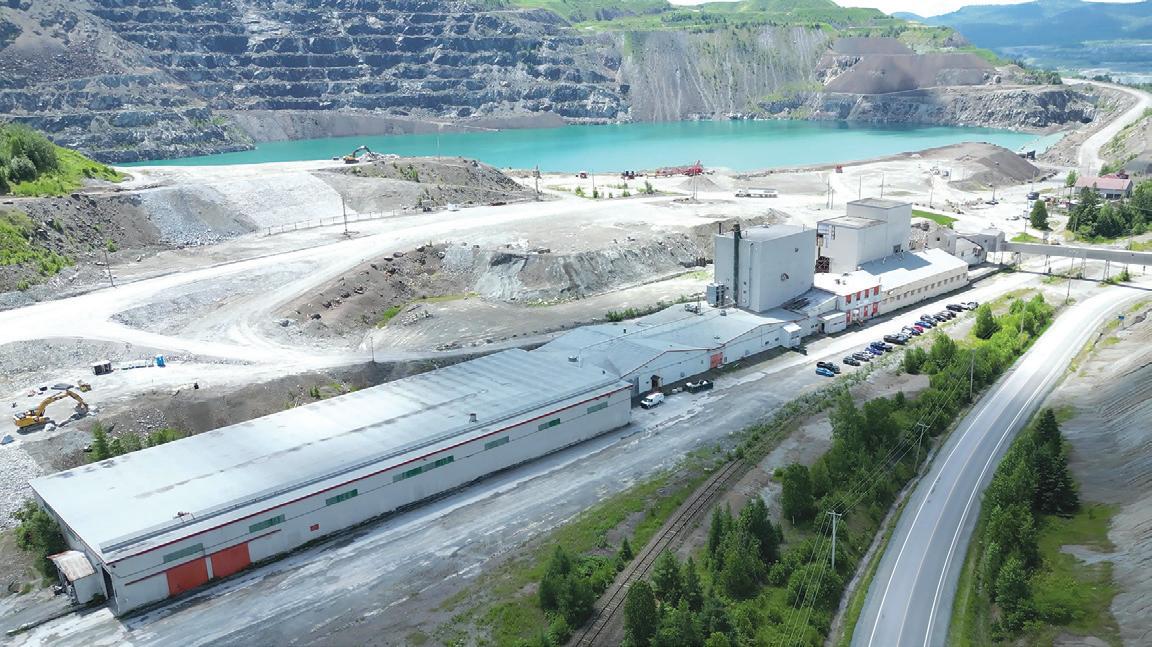
The 80,000-sq.-ft. (7,400-sq.-metre) site serves as both a testing centre and a demonstration facility where mining companies can evaluate how their materials respond to DST’s technologies before making investment decisions.
For an industry often criticized for being slow to adopt new technologies, that distinction is important.
Bridging the gap
Mining is full of new ideas. Every year, companies roll out fresh ways to recover metals or tackle environmental issues. But a lot of these technologies never make it past the lab.
The challenge lies in proving that a process can work reliably at a larger scale.
DST’s answer has been to create a facility capable of moving projects from laboratory testing to pilot campaigns and, eventually, to industrial-scale demonstration. The company receives ore and concentrate samples from clients and processes them through increasingly larger systems to generate operational data.
“When you’re developing new metallurgical processes for the industry, it’s very important to build and demonstrate at scale,” Mai said. “You need to provide data and allow people to make informed decisions.”
The approach reflects a reality familiar to mining executives. Before committing hundreds of millions of dollars to a project, companies need confidence that a proposed flowsheet will work under realworld operating conditions.
That need has become even more important as deposits grow more complex.
Many of the industry’s easiest-toprocess ore bodies have already been developed. New projects increasingly contain impurities, refractory mineralization or other characteristics that complicate metal recovery. In many cases, environmental considerations add another layer of complexity.
That’s why the right processing technology can make or break a project today.
Gold extraction
One of DST’s best-known technologies is CLEVR, a hydrometallurgical process designed to recover gold without cyanide. For more than a century, cyanide has been the dominant reagent used in gold
Sustainable Technologies’ Quebec facility
“The novelty isn’t the equipment. It’s really the chemical approach.”
CEO
JEAN-PHILIPPE MAI, DUNDEE SUSTAINABLE TECHNOLOGIES
extraction. It remains highly effective and is widely used across the industry.
However, it continues to attract scrutiny from communities, regulators and environmental groups.
Alternative approaches have therefore attracted growing interest, particularly where companies seek to reduce environmental risk or improve project acceptance.
At DST’s demonstration plant, CLEVR uses sodium hypochlorite and a catalytic amount of sodium hypobromide to dissolve ore for its gold.
According to Mai, the process can achieve rapid leaching times, often placing gold into solution within one to two hours.
The company has also designed the process as a closed-loop system.
“We have no liquid effluent exiting the circuit,” Mai said.
Electrolysis cells regenerate the reagents used within the process, allowing them to be recycled rather than discharged.
The broader significance may extend beyond the chemistry itself.
What stands out during a tour of the facility is that much of the equipment appears familiar to anyone who has visited a conventional processing plant. Tanks, pumps, piping and control systems resemble technologies already used throughout the industry.
“The novelty isn’t the equipment,” Mai said. “It’s really the chemical approach.”
That observation may prove important for adoption.
Mining companies are often reluctant to
embrace technologies that require entirely new operating philosophies or unfamiliar equipment. DST has instead attempted to build its processes around equipment already proven at an industrial scale.
The company says CLEVR also operates at ambient temperature and pressure, allowing for simpler construction materials and potentially lower capital costs.
In a sector where economics frequently determine whether innovation succeeds or fails, that may be as important as any environmental benefit.
Arsenic challenge
If CLEVR addresses one of gold mining’s most visible processing issues, GlassLock targets a challenge that many industry insiders consider even more significant.
Arsenic remains a major issue for mining companies around the world.
The element is commonly associated with precious-metal deposits and can create substantial environmental and operational challenges. Arsenic-bearing concentrates often require special handling, can affect marketability and may complicate permitting efforts.
For some projects, arsenic management becomes one of the defining factors influencing development decisions.
DST’s GlassLock process is designed to permanently stabilize arsenic by incorporating it into a vitrified glass product.
At the Thetford Mines facility, arseniccontaining materials are first processed through a fluidized bed reactor. The captured arsenic is then treated through vitrification, producing a stable glass matrix intended to immobilize the contaminant.
“This is really one of the biggest value propositions Dundee Sustainable Technologies is providing,” Mai said.
The issue is particularly relevant as miners increasingly pursue more complex deposits.
Many high-grade discoveries still contain challenging mineralogy. As companies search for new sources of gold, copper and critical minerals, the industry is often forced to confront materials that previous generations of miners may have ignored.
Managing those materials safely and economically has become a competitive advantage.
In that sense, technologies like GlassLock are not simply environmental tools. They may also expand the range of deposits that can be considered viable for development.
Familiar systems
One of the more striking aspects of DST’s operation is the effort to replicate conditions found at commercial mines.
The facility’s industrial demonstration plant is managed through a centralized digital control room similar to those used in larger mines. Operators can monitor material handling, pretreatment, leaching and process performance from a single location.
The objective, according to Mai, is to demonstrate not only that the chemistry works, but that the process can function within an operating environment familiar to mining companies.
“When clients come here, they can see that the process is mature and can operate in scenarios that are very similar to what is already being used in the mining industry,” he said.
Years of operating campaigns have also generated a growing database of performance information that can be incorporated into engineering studies and project evaluations.
For mining companies assessing new technologies, that operational track record can be just as valuable as laboratory results.
Changing industry
Whether technologies such as CLEVR and GlassLock ultimately achieve widespread adoption remains to be seen.
Mining is an inherently conservative industry, and for good reason. Processing failures can have enormous financial consequences. Yet the pressures facing producers continue to evolve.
Ore bodies are becoming more difficult. Environmental expectations continue to rise. Investors, communities and regulators increasingly expect companies to demonstrate both operational efficiency and environmental responsibility.
Against that backdrop, the next wave of mining innovation may not come solely from larger trucks, automation systems or artificial intelligence. It may also come from chemistry and research.
“We bring comfort to the industry and provide the data for enlightened decision making,” Mai said. “People can move forward through our processes.” TNM
—The preceding sponsored article is PROMOTED CONTENT paid for by Dundee Sustainable Technologies and produced in co-operation with The Northern Miner. Visit: https://www. dundeetechnologies.com for more information.
An over overhead view of Dundee’s site in Thetford Mines, Que. DUNDEE SUSTAINABLE TECHNOLOGIES
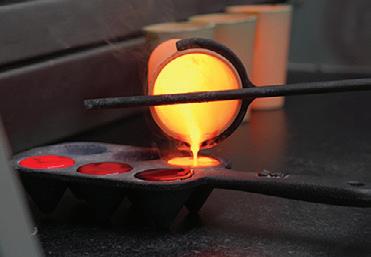
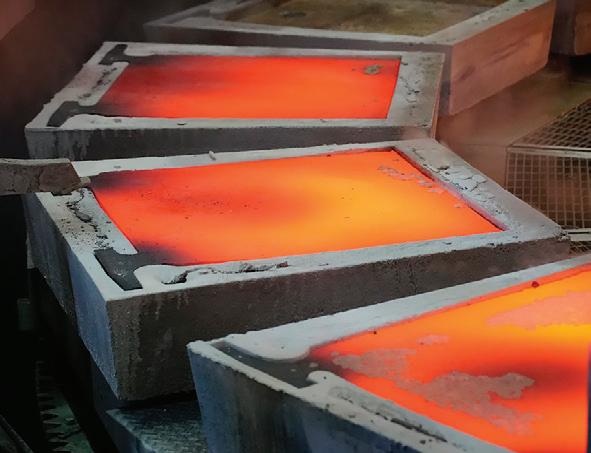
A gold pour. DUNDEE SUSTAINABLE TECHNOLOGIES
THE WAGE MINE
By Northern Miner Staff
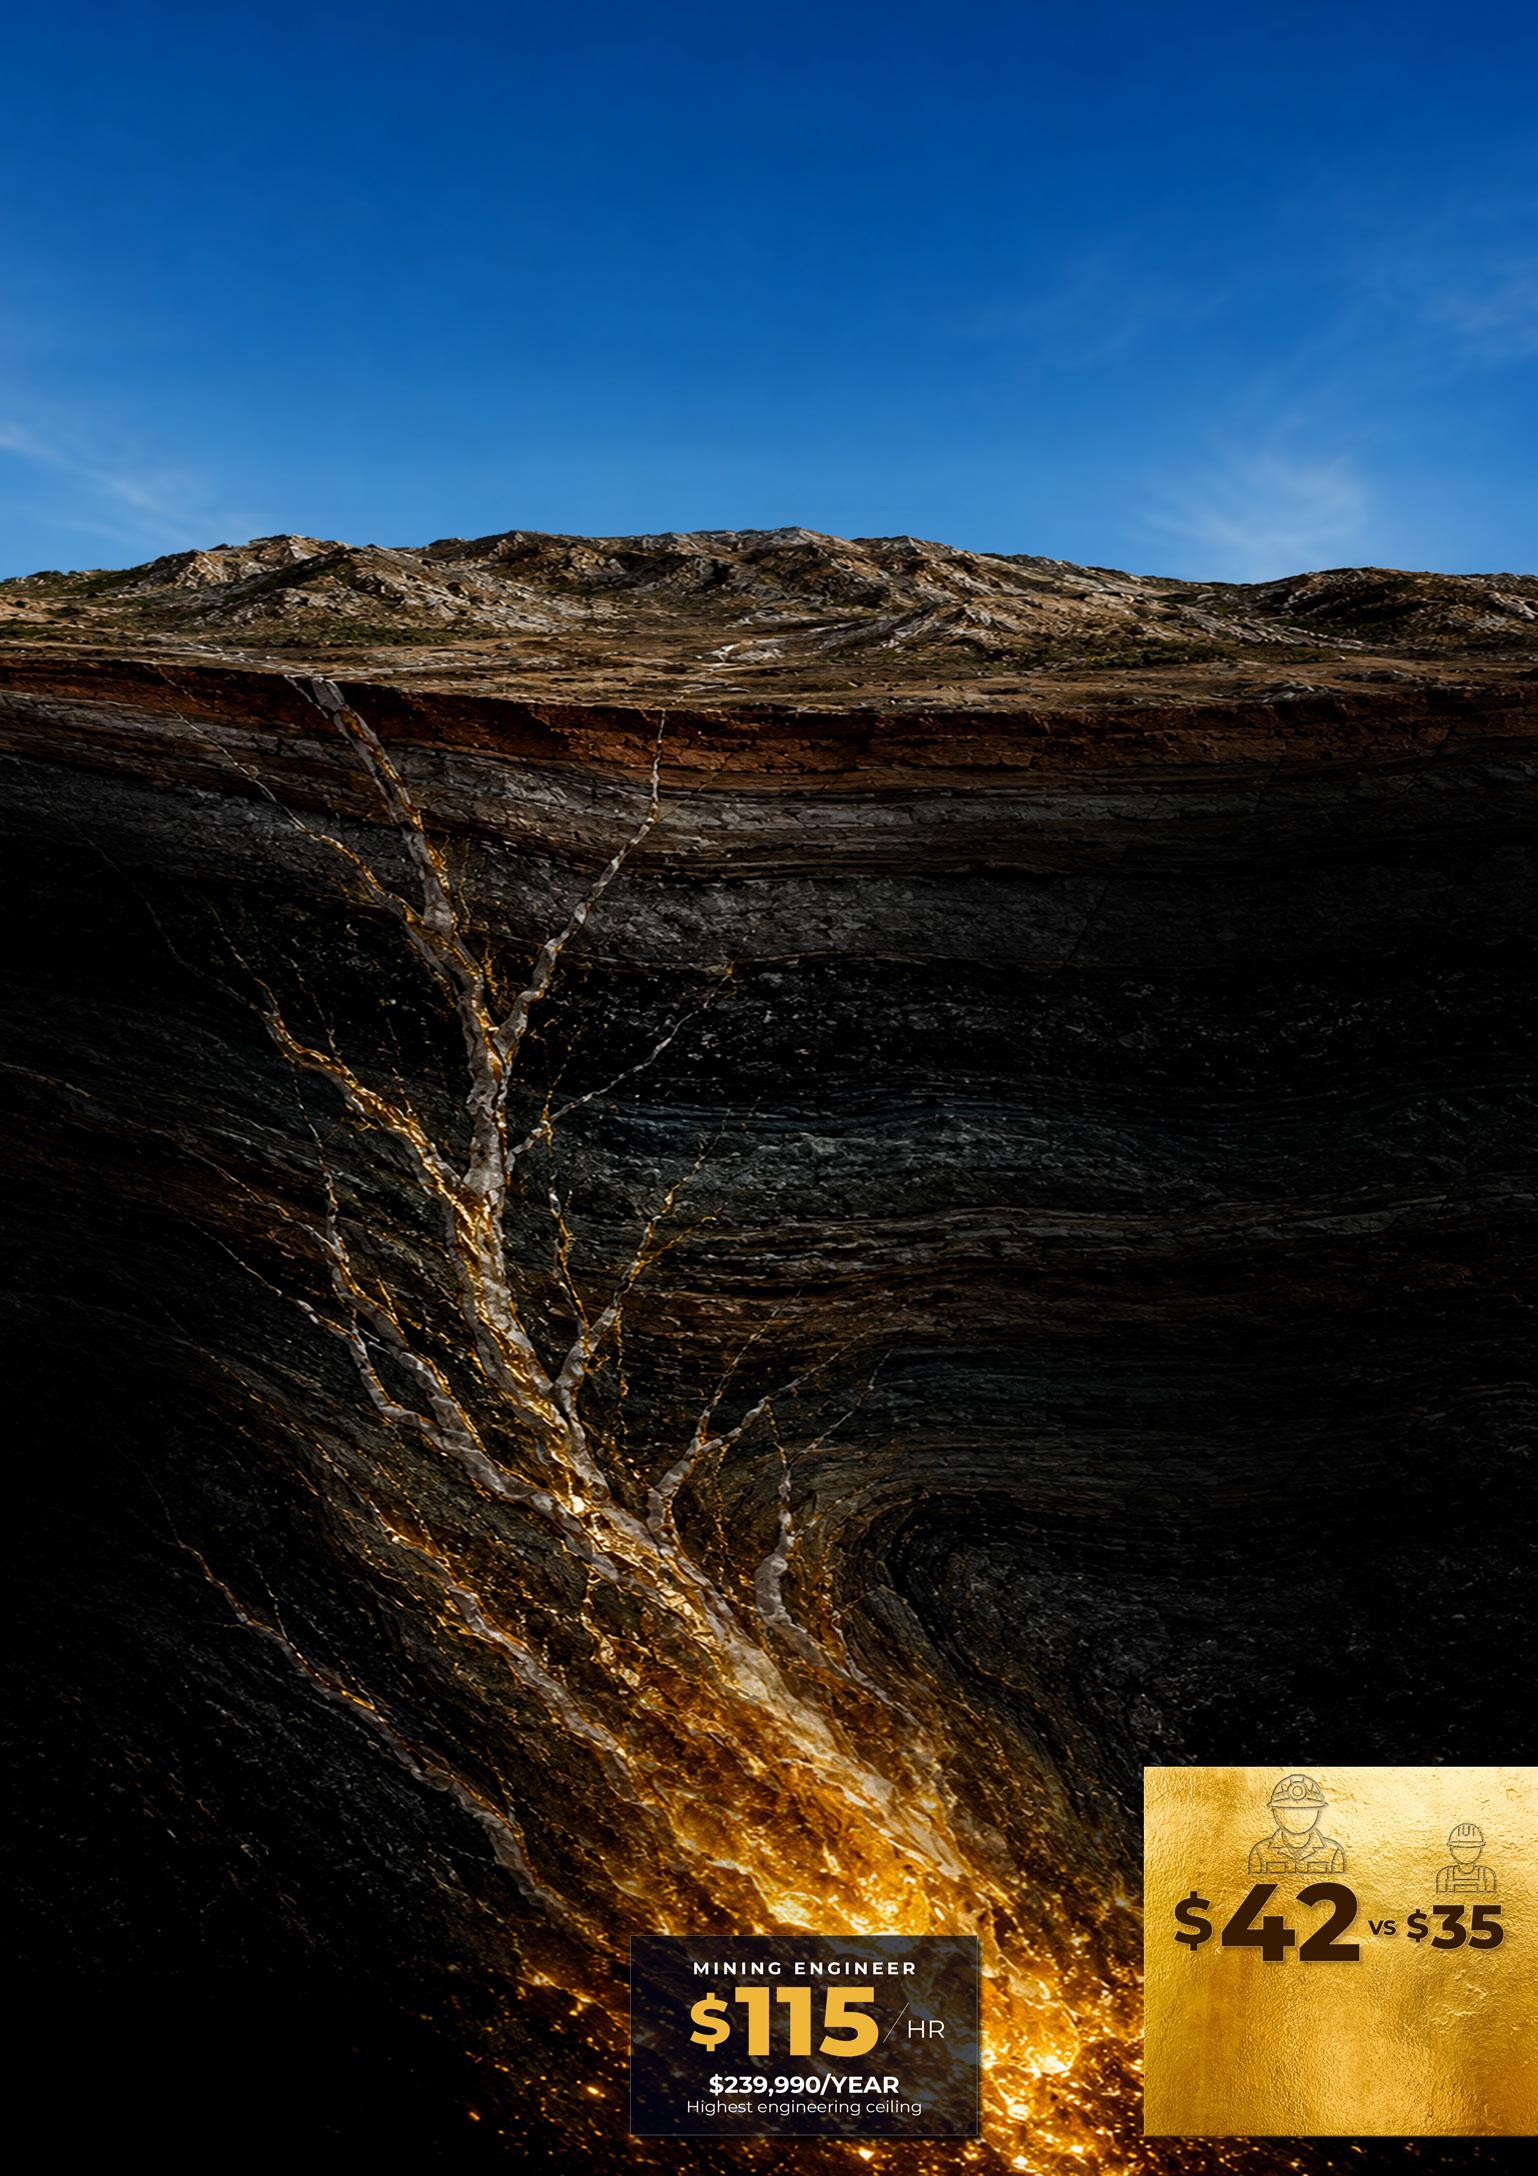
Mining is not just about breaking rock. Across exploration, development, operations, and reclamation, the sector relies on drivers, drillers, mechanics, electricians, pipefitters, equipment operators, and other skilled trades. Working in mining can push these occupations toward the upper end of their wage range, where remote premiums, fly-in fly-out allowances, union agreements, long shifts, and site premiums can turn the ceiling into the floor.
Below is a vertical view of the trades, jobs, and engineering disciplines that power mining, plotted by upper-end hourly wage inside a geological gold-deposit cross-section. Read from the surface down: the deeper the seam, the richer the pay.

MEGA-MINERS
Agnico,
Barrick
top the list of miners
CANADA | Role of critical metals grows
BY BLAIR MCBRIDE
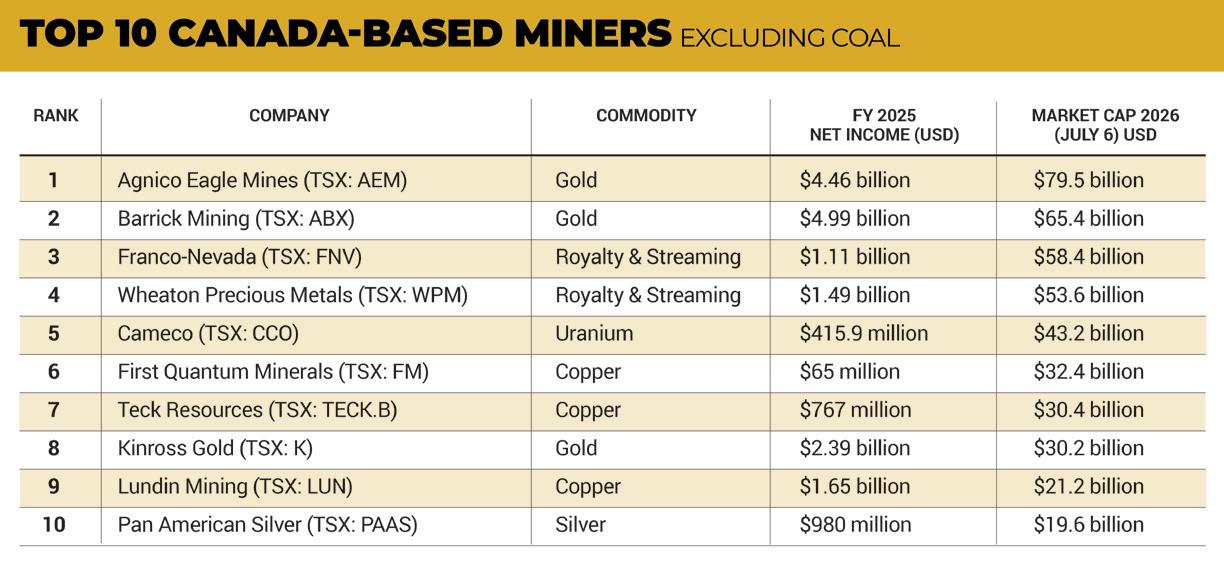
Agnico Eagle Mines (TSX, NYSE: NEM) leads the list of Canadian miners by market value at $79.5 billion (C$112.8 billion). Agnico runs the country’s largest mines by output: Canadian Malartic and Detour Lake.
The miner attributed this year’s first quarter net income of $1.69 billion—more than double last year’s first quarter earnings—to record operating margins due to higher realized gold prices, which reached an all-time high of $5,589.38 per oz. on Jan. 28.
“We delivered a solid start to 2026, achieving record operating margins while production and costs tracked well to plan,” Agnico’s President and CEO Ammar Al-Joundi said in a release. “With gold production expected to be weighted to a stronger second half of the year, we are managing cost volatility through disciplined execution and asset optimization, supported by our regional operating model.”
The major approved construction in May for the $2.4-billion Hope Bay underground mine in western Nunavut, with production expected to start in as little as four years. The mine could produce 400,000 to 435,000 oz. gold annually over an initial 11-year life.
Expansion
Also in May, Agnico earmarked $10.2 billion for expansions, project development and exploration in Ontario. About $1.4 billion is to support the Detour Lake underground project and the Upper Beaver gold-copper project.
In Finland, Agnico is working to consolidate a district-scale gold camp in the Central Lapland Greenstone Belt, secured by the $2.1-billion acquisition of Rupert Resources, which closed in June.
Barrick Mining (TSX: ABX; NYSE: B) is in second spot by market cap at $65.4 billion and first in 2025 net income at $4.99 billion.
The miner, which continues its move towards copper-gold and away from a pure gold profile, produced 719,000 oz. gold and 49,000 oz. copper in the first quarter. That represents a 4% rise in gold output and an 11% gain in copper compared to the same period last year.
Former CEO Mark Bristow abruptly resigned last September after leading the company for almost seven years.
Mali
Barrick’s bitter row with Mali over its Loulo-Gounkoto mine was mostly resolved last November when the company reportedly paid $430 million to settle a tax dispute. Barrick withdrew its arbitration case at the World Bank and the government returned operational control of the mine to the company.
Its Reko Diq copper-gold project in Pakistan experienced setbacks due to security concerns in the restive Balochistan province as well as wider insecurity with the war in Iran. Barrick extended a review
income was boosted by higher uranium prices and sales volumes.
Cameco reaffirmed 2026 guidance of 19.5 to 21.5 million lb. uranium oxide but then in July it temporarily halted operations at its
period for the project by one year until next July. The $9-billion capex Reko Diq ranks among the world’s largest undeveloped copper and gold resources.
Barrick also announced plans to spin out its Nevada Gold Mines joint venture with Newmont (TSX: NGT; NYSE: NEM) and the Pueblo Viejo mine in the Dominican Republic into a new listed company by the end of 2026. The move is part of a strategic pivot away from
“risky” jurisdictions.
Cameco (TSX: CCO; NYSE: CCJ) is fifth on our list by market capitalization at $43.2 billion and ninth by 2025 net income at $415.9 million.
The world’s second-largest uranium producer, behind Kazatomprom (LSE: KAP), booked first quarter net earnings this year of $92.4 million, 87% higher than in the same period last year. Increased
McClean Lake mill in Saskatchewan, operated by France’s Orano. That mill processes ore from Cameco’s Cigar Lake mine.
India
In March, the Saskatoon, Sask.headquartered company signed a deal worth about $1.9 billion to supply almost 22 million lb. of uranium over nine years to India for use in the country’s nuclear reac-
tors. Deliveries are expected to start in 2027 and run through 2035.
McClean Lake is one of the world’s largest uranium processing plants, with an annual production capacity of 24 million pounds. Cigar Lake, situated 70 km southwest of the mill, is the world’s highest-grade uranium mine.
Teck Resources (TSX: TECK.A, TECK.B; NYSE: TECK) takes seventh spot, with a market cap of $30.4 billion and $767 million in 2025 net income.
As the miner expands its portfolio towards producing more critical metals, the Canadian government gave it a boost in July with a potential C$400-million investment for its Trail, B.C. smelter. The backing is to help Teck raise its capacity for producing germanium and antimony, and add the capability to produce gallium.
The major made history in December after shareholders and Ottawa approved its $53-billion mega-merger with Anglo American (LSE: AAL). It’s one of the largest deals in the mining sector’s history. The merger is expected to close by the end of this year or in early 2027. TNM
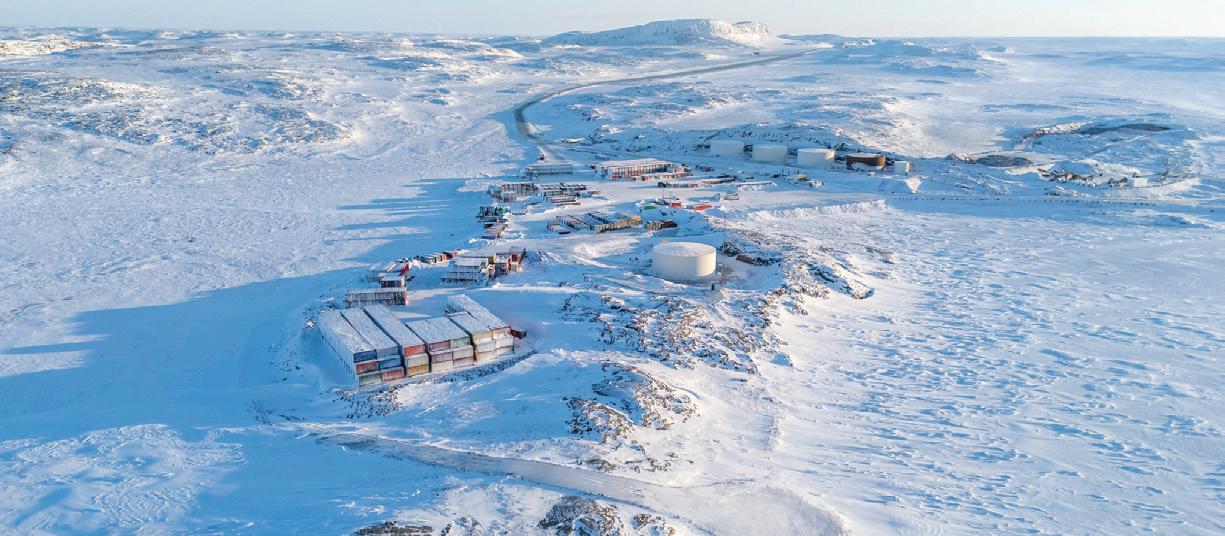
Agnico’s Hope Bay project in the Kitikmeot region of Nunavut. AGNICO EAGLE MINES
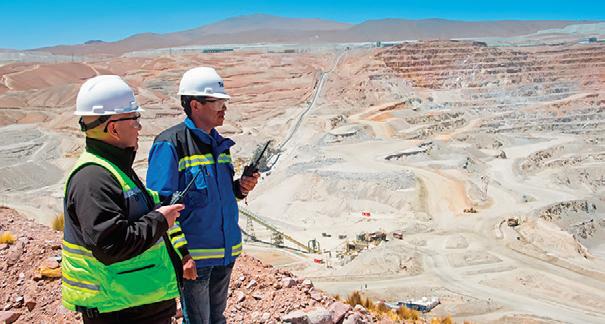
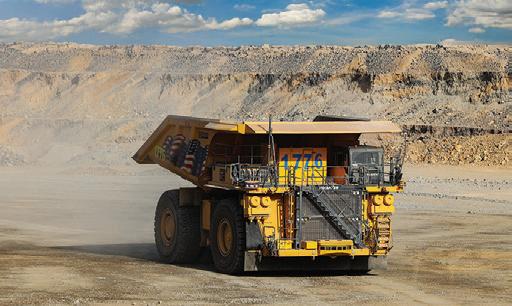
Above: At Teck’s QB copper site in northern Chile. TECK RESOURCES Right: A haul truck at Barrick and Newmont’s Nevada Gold Mines joint venture project. BARRICK MINING
Southern Copper, Newmont lead pack
UNITED STATES | Expansion, asset sales highlight year
BY FRÉDÉRIC TOMESCO
Rising metals prices helped global miners Southern Copper (NYSE: SCCO), Newmont (NYSE: NEM) and Freeport-McMoRan (NYSE: FCX) extend their dominance of U.S. peers in terms of both market capitalization and earnings.
Southern Copper delivered record financial results while continuing to advance long-term copper growth projects in Peru and Mexico. Net income rose 28% to $4.33 billion (C$6.07 billion) on the back of stronger copper, silver, molybdenum and zinc prices and higher by-product production, while sales climbed 17% to $13.4 billion.
The Grupo Mexico unit is to invest about $20.5 billion over the next decade as part of a plan to lift annual copper production to 1.6 million tonnes by 2033. A key component of that expansion will be the $1.8-billion Tía María copper project in Peru, which is a decade-long in the making and has been beset by controversy. Peru reauthorized the project’s mining permit this year after authorities had earlier forced a fresh review.
By the end of April, Southern Copper said Tía María was about one-third complete, with first production targeted for the second half of 2027. The mine will be capable of producing 120,000 tonnes of copper annually from 2028.
Newcrest takeover
Newmont’s recent story has been one of portfolio optimization following the 2023 purchase of Newcrest. The world’s largest gold miner recently completed a sweeping divestiture program, raising about $4.3 billion in gross proceeds through the sale of non-core operations such as the Musselwhite, Éléonore and Porcupine mines in Canada. In September, the company also sold its stake in Orla Mining to raise capital for core operations.
Denver-based Newmont reported record financial performance in 2025, producing 5.89 million attributable gold oz. while benefiting from higher gold prices that helped net income more than double to $7.1 billion.
Newmont generated $7.3 billion in free cash flow, cut debt by $3.4 billion, returned $3.4 billion to shareholders through dividends and share repurchases, and finished the year in a net cash position.
Last year was one of significant leadership and organizational changes as long-time CEO Tom Palmer retired at the end of December to make way for former chief operating officer Natascha Viljoen. Newmont also completed a broad restructuring tied to the Newcrest integration, reducing its workforce by about 16% as part of its Project Catalyst initiative to streamline operations and improve productivity.
Grasberg suspension
Operational issues dogged Freeport-McMoRan’s year. A catastrophic mud flow at the company’s Grasberg mine in Indonesia in September 2025, which killed seven workers, forced mining to be suspended in parts of the operation.
Attributable net income rose 17% to $2.2 billion, supported by strong copper fundamentals and continued
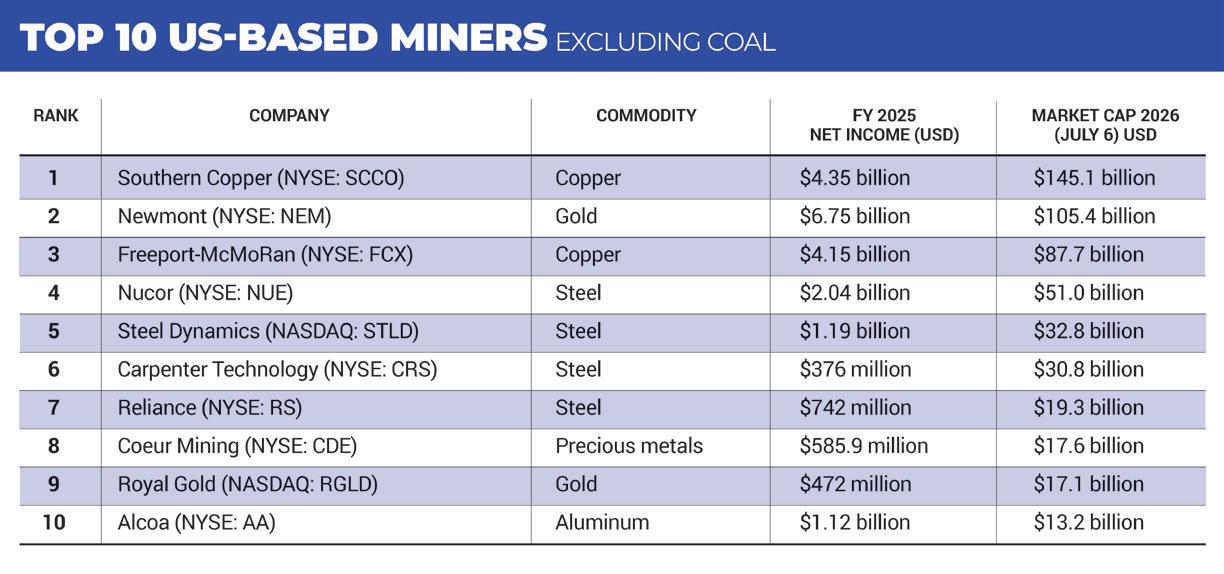
investment in growth projects, while revenue advance 1.8% to $25.9 billion. Capital expenditures remained elevated as Freeport advanced underground mining, leaching initiatives in the United States and downstream processing facilities in Indonesia.
Throughout 2026, Freeport has focused on safely restarting production at Grasberg. A slower-than-expected recovery prompted the company in April to lower its 2026 copper and gold sales guidance. Even so, Freeport’s management reiterated its positive long-term outlook, citing growing copper demand from electrification, power infrastructure and artificial intelligence-related data centres.
steel market led Nucor (NYSE: NUE) to report a 14% drop in annual profit. Net income dropped to $1.7 billion amid margin compression at the company’s sheet steel mills and scheduled outages in the raw materials business. Sales nevertheless rose 6% to $32.5 billion as new mills and downstream facilities buoyed production.
Royal Gold (Nasdaq: STLD) completed its acquisition of Sandstorm Gold and Horizon Copper last year, adding new streams and royalties and increasing its exposure to a broader base of producing and development-stage assets.
Attributable net income rose to a record $466.3 million while revenue jumped 44% to $1.03 billion. Royal Gold also raised its annual dividend for the 25th consecutive year.
Several assets in Royal Gold’s
portfolio advanced. Centerra Gold’s (TSX: CG; NYSE: CGAU) Mount Milligan operation in British Columbia benefited from an updated mine plan extending its life to 2045, while assets such as Barrick Mining’s (TSX: ABX; NYSE: B) Pueblo Viejo and Newmont’s Peñasquito fueled growth in attributable metal sales.
Aluminum
Alcoa (NYSE: AA) reported a significant turnaround in 2025, with revenue increasing 8% to $12.8 billion and net income soaring to $1.2 billion—from $60 million in 2024 —amid higher aluminum prices, stronger operating performance and improved production at several facilities.
Several strategic transactions marked the past year. Alcoa sold
its interest in the Ma’aden joint venture in Saudi Arabia, formed a new partnership with IGNIS Energy Holdings to support the San Ciprián aluminum complex in Spain, and permanently closed the Kwinana alumina refinery in Australia after determining the facility was no longer economically viable.
The dealmaking has extended into 2026. In late June, Alcoa announced plans to acquire bauxite, alumina and aluminum assets from Australia’s South32 (ASX, LSE: S32) in a transaction valued at about $4.7 billion, including debt—a move aimed at expanding the upstream resource base and increasing alumina and aluminum capacity. It’s also explored opportunities to repurpose inactive industrial sites, including potential sales to data centre operators. TNM
Above: Newmont’s Ahafo mill in Ghana. NEWMONT
Far Left: Bauxite excavation at Alcoa’s Huntly mine in Western Australia. ALCOA Left: Drilling at Freeport’s Sierrita project in Arizona. FREEPORT-MCMORAN
BHP leads heavyweights Down Under
AUSTRALIA | Copper and gold gain weight
BY HENRY LAZENBY
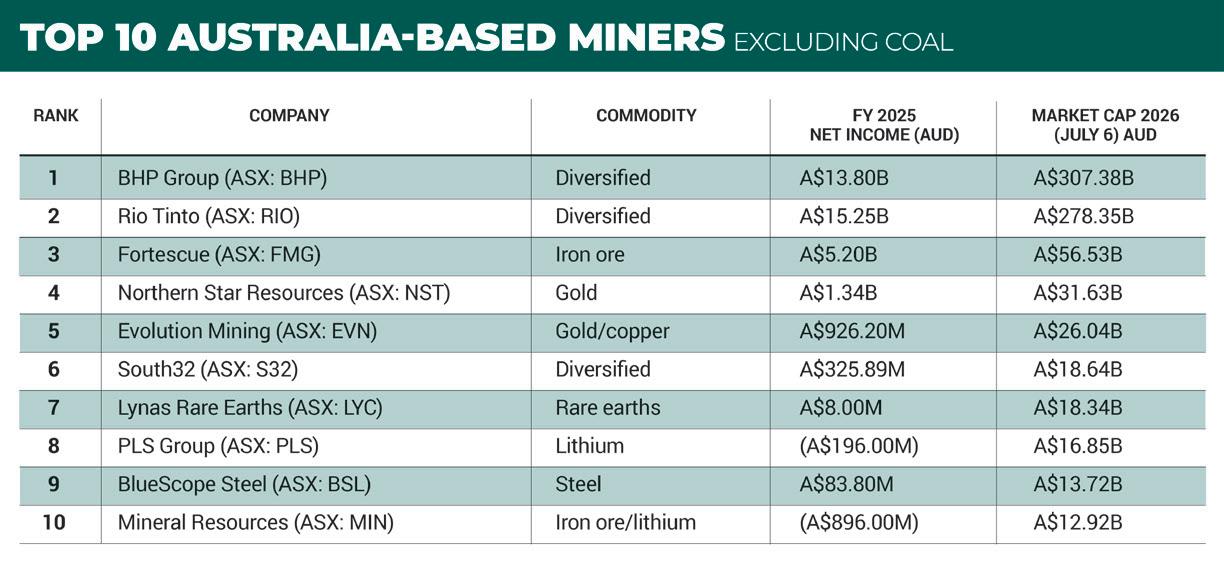
BHP Group (ASX, LSE, NYSE: BHP) leads Australia’s biggest listed mining and metals companies by market value, while Rio Tinto (ASX, LSE, NYSE: RIO) posted the strongest fiscal 2025 profit.
BHP was worth A$307.4 billion (US$213 billion) on July 3, ahead of Rio at A$278.4 billion. It earned A$13.8 billion in fiscal 2025. Its cornerstone Olympic Dam copper, gold and uranium complex lies about 560 km north of Adelaide, South Australia’s capital.
“We think that gives us a unique set of advantages to be very successful in the market, but copper clearly is a focus,” BHP CEO Brandon Craig said at a mining conference in May.
Diversified miners and iron ore producers still control most of the value and profit, but gold, copper and rare earths companies have climbed as investors seek metals tied to electrification, defence and constrained supply. Lithium producers remain highly valued despite losses, showing how far expectations have moved ahead of current earnings.,
Diversified giants
Rio Tinto earned A$15.3 billion in fiscal 2025. Its iron ore business still funds expansion into copper and lithium through assets such as Oyu Tolgoi in Mongolia and the Arcadium Lithium portfolio.
That broader mix gives Rio more paths to growth as mature Pilbara iron ore mines face higher costs and declining grades. The company has paired its Australian iron ore base with copper, aluminium and lithium operations across the Americas, Africa and Asia.
Fortescue (ASX: FMG) placed third at a market capitalization of A$56.5 billion and earned A$5.2 billion. It remains far more exposed to iron ore than BHP or Rio, tying its cash flow closely to Chinese steel demand and benchmark prices.
The Perth-based miner has pushed into renewable power, green hydrogen and copper, but Pilbara iron ore shipments still drive its earnings. That concentration helped Fortescue generate strong cash flow during high-price cycles, while leaving it more vulnerable when Chinese demand weakens.
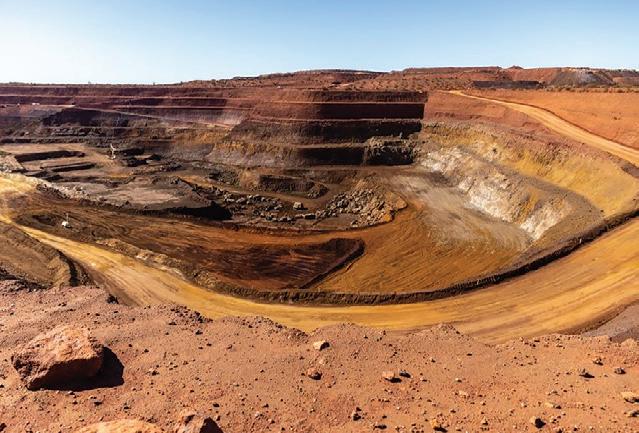
Gold, copper and rare earths companies have climbed as investors seek metals tied to electrification, defence and constrained supply.
Gold strength
Northern Star Resources (ASX: NST) took fourth place with a market capitalization A$31.6 billion after earning A$1.34 billion last year. Its takeover of De Grey Mining added the Hemi project in Western Australia and strengthened its position among the world’s largest listed gold producers.
Hemi gives Northern Star another large growth project beyond its Kalgoorlie and Yandal operations. The deal expanded its resource base but added development risk and capital demands as the company works to lift output from its existing mines.
Evolution Mining (ASX: EVN) ranked fifth at a market cap of A$26 billion and posted A$926 million in net income. Its gold mines and Ernest Henry copper operation give it more exposure to copper than
most Australian gold producers. Northern Star and Evolution have benefited from record gold prices, but their valuations reflect different growth paths. Northern Star has pursued scale through acquisitions, while Evolution has relied more heavily on mine expansion and the cash flow from Ernest Henry. South32 (ASX, LSE: S32) ranked sixth at A$18.6 billion, with fiscal 2025 profit of A$326 million. Its spread of aluminium, copper, zinc, silver and manganese assets lowers dependence on any single metal, though weaker prices and operating setbacks have weighed on returns.
Critical minerals
Lynas Rare Earths (ASX: LYC; US-OTC: LYSCF) placed seventh at A$18.3 billion despite earning
only A$8 million. The gap between its profit and valuation reflects its strategic role as one of the few suppliers globally of separated rare earths outside China.
Lynas mines ore at Mt Weld in Western Australia and processes material in Australia and Malaysia. Its supply chain has gained relevance as Western governments seek alternatives to China for metals used in permanent magnets, electric vehicles, wind turbines and defence systems.
PLS Group (ASX: PLS), formerly Pilbara Minerals, ranked eighth at a market cap of A$16.9 billion after posting a A$196-million loss. Its Pilgangoora lithium operation, about 1,200 km north of Perth, remains one of the world’s largest hard-rock lithium mines.
The company’s valuation rests
less on current earnings than on the scale of Pilgangoora and expectations for a lithium market recovery. That leaves its shares highly exposed to spodumene prices after a supply surge pushed the sector from boom to retrenchment.
BlueScope Steel (ASX: BSL; US-OTC: BLSFY) took ninth place at A$13.7 billion, with net income of A$84 million.
Mineral Resources (ASX: MIN) rounded out the list at A$12.9 billion after losing A$896 million. Its portfolio combines iron ore, lithium and mining services, but heavy spending and weak lithium prices have strained its balance sheet. Its place in the ranking, alongside PLS and Lynas, shows investors still assign high value to scarce mineral exposure even when nearterm profits lag.
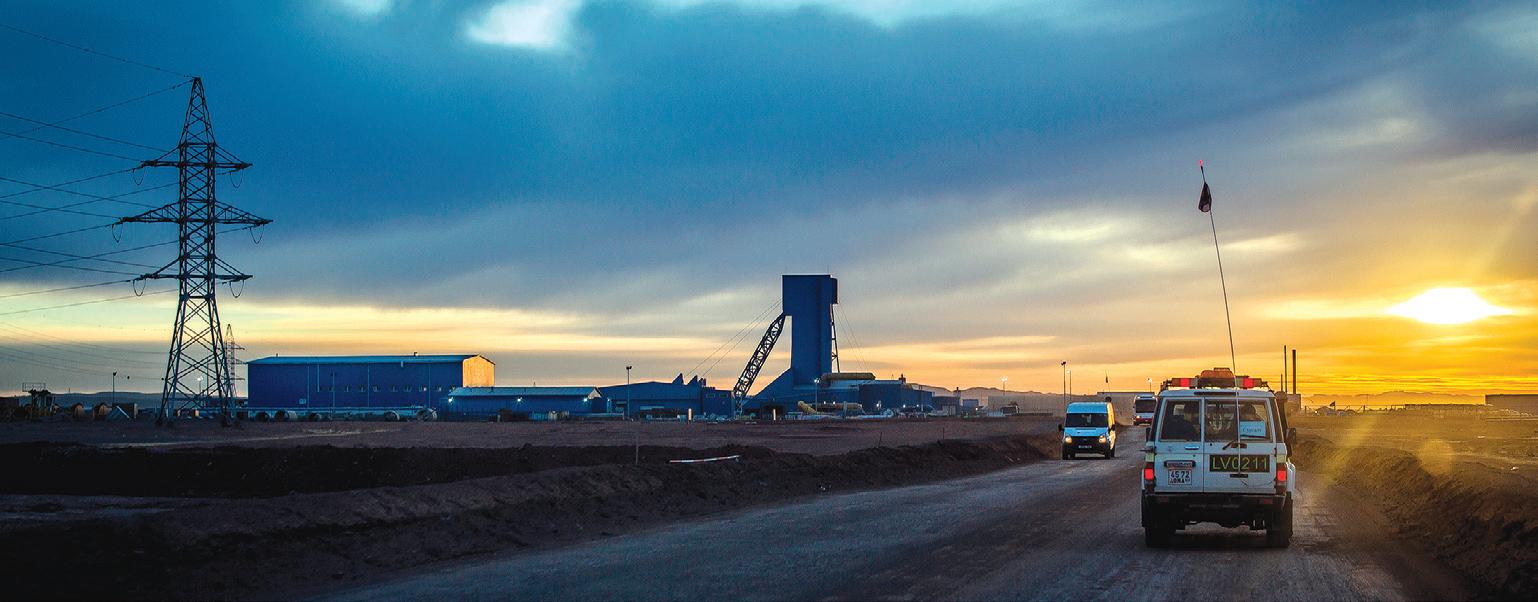
Above: Rio Tinto’s Oyu Tolgoi copper mine in southern Mongolia. RIO TINTO
Left: Lynas’ Mt Weld mine in Western Australia. LYNAS RARE EARTHS
Zijin’s global expansion pays off
REST OF WORLD | Several miners eye copper growth
BY FRÉDÉRIC TOMESCO
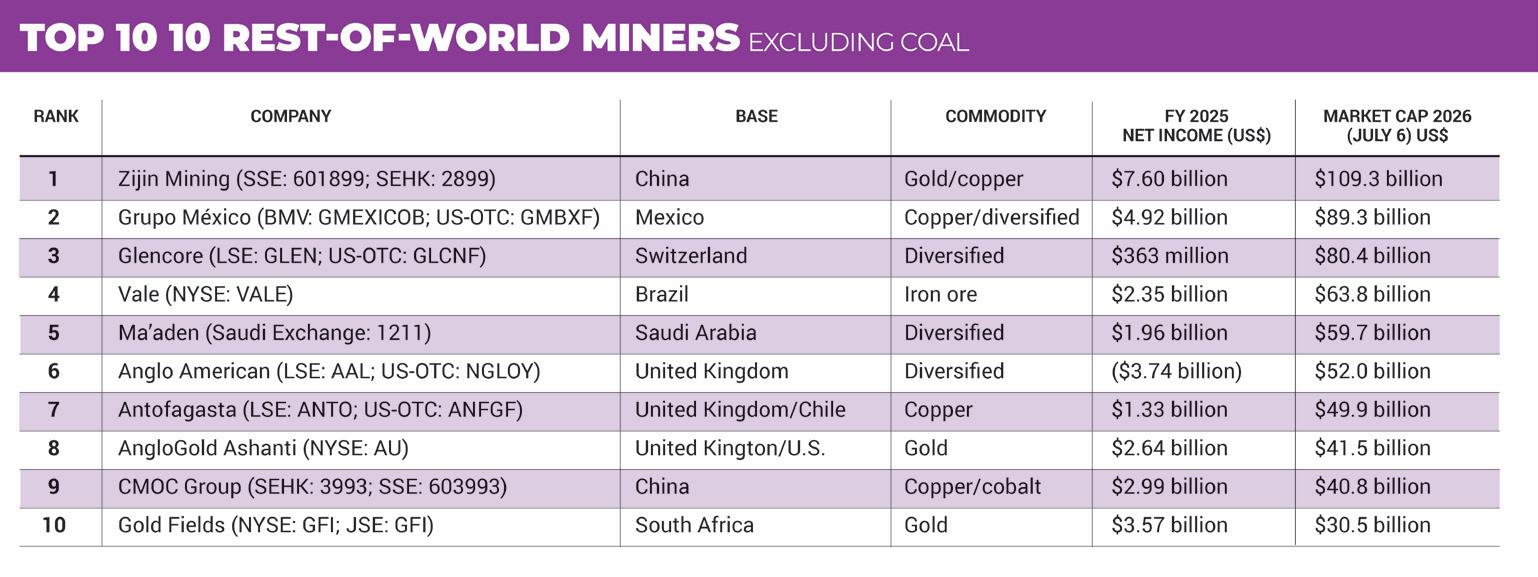
Zijin Mining’s (SSE: 601899; SEHK: 2899) expansion strategy paid dividends as the Chinese miner topped global peers located outside North America and Australia for market capitalization.
Attributable net income jumped 62% to a record $7.4 billion (C$10.4 billion), supported by higher copper and gold prices as well as increased output. Revenue rose 15% to $49.7 billion.
Acquisitions drove a 23% surge in 2025 output as Zijin churned out 90 tonnes of mined gold. Two key assets fuelled the increase: Ghana’s Akyem gold mine, which Zijin bought from Newmont in April for $1 billion, and Kazakhstan’s Raygorodok operation, acquired in October.
Zijin continued investing in its copper business. It advanced plans for a $1.5-billion expansion at Peru’s La Arena copper-gold operation that aims to extend mine life and boost copper production. Zijin bought La Arena from Pan American Silver (TSX, Nasdaq: PAAS) in 2024.
M&A remains a major focus. In January, Zijin unveiled a friendly C$5.5-billion deal to acquire Canadian producer Allied Gold (TSX, NYSE: AAUC). The transaction would add Mali’s Sadiola mine, the Bonikro and Agbaou operations in Côte d’Ivoire, and the Kurmuk project in Ethiopia. It was scheduled to close by the end of July.
Peso winner Grupo México (BMV: GMEXICOB; US-OTC: GMBXF) rode strong copper prices, disciplined cost management and continued investment across its mining, transportation and infrastructure businesses to become the country’s most valuable company by market value. Its stock rose 72% in peso terms.
Sales rose 12% to a record $18.2 billion while net profit climbed 18% to $4.6 billion.
Improved operational performance across its mining businesses helped Glencore (LSE: GLEN; US-OTC: GLCNF) swing to a profit of $363 million in 2025 from a year-earlier loss of $1.6 billion.
Discussions with Rio Tinto (NYSE, LSE, ASX: RIO) over a combination valued at roughly $260 billion ended in February
Anglo American’s signature move was the signing in September of a proposed $53-billion merger with Canada’s Teck Resources to create a major global copper producer.
after the companies failed to agree on valuation and leadership terms.
Operationally, Glencore achieved production guidance for key commodities for the second straight year. Copper output dropped 11% in 2025 to 851,600 tonnes because of lower grades and recoveries, but second-half production rebounded sharply as performance improved at several mines.
2035 goal
Copper has become the centrepiece of Glencore’s strategy amid rising demand from electrification and energy infrastructure. In December, executives outlined a pathway to become one of the world’s largest producers of the red metal, targeting annual production of about 1.6 million tonnes by 2035.
Brazil’s Vale (NYSE: VALE) is another miner focused on growing
its copper footprint. It advanced studies and investments at its copper assets last year, including operations in Brazil and Canada, while maintaining efforts to improve performance at its nickel business amid challenging market conditions.
Its base metals unit agreed in December with Glencore to assess a brownfield copper development in the Sudbury Basin.
Attributable net income dropped 62% last year to $2.4 billion as Vale booked a $3.5-billion impairment charge on its Canadian nickel assets due to a downward revision in long-term price assumptions.
Ma’aden, as Saudi Arabian Mining is known, reported record results on the back of rising phosphate and aluminum output. Net attributable profit more than doubled to about $2 billion while revenue rose 19% to $10.3 billion.
Critical minerals
Key to Ma’aden’s strategy is a continued expansion beyond the company’s traditional phosphate and aluminum businesses. The company is now looking to increase gold output, develop copper and explore opportunities in rare earth elements and critical minerals.
Ma’aden also advanced exploration partnerships. In December, it formed a joint venture with Midana Exploration, a company backed by Australian mining entrepreneur
Gina Rinehart, to explore large areas of the Arabian Shield for gold.
Anglo American’s (LSE: AAL; US-OTC: NGLOY) signature move was the signing in September of a proposed $53-billion merger with Canada’s Teck Resources (TSX: TECK.A, TECK.B; NYSE: TECK) to create a major global copper producer. Shareholders of both companies have since approved the combination, and Anglo American has been working on securing regulatory approvals.
London-based Anglo also continued divesting non-core assets under a 2024 strategy working on the separation of its De Beers subsidiary and the sale of steelmaking coal and nickel operations.
Higher gold prices, cost control and asset sales helped AngloGold Ashanti (NYSE: AU) strengthen its financial position. Attributable income more than doubled to $2.6 billion while free cash flow tripled to a record $2.9 billion as gold production rose about 16% year-overyear to more than 3 million ounces.
Brazil sale AngloGold continued reshaping its asset portfolio by completing the sale of its Serra Grande mine in Brazil while advancing a pipeline of organic growth projects in Nevada, Ghana, Tanzania and Egypt. Capital spending remained focused on extending mine lives and developing higher-return projects intended to support long-term production.
Chile’s Antofagasta (LSE: ANTO; US-OTC: ANFGF) is another miner looking to expand copper output. Group capital spending jumped more than 50% to $3.7 billion in 2025, reflecting peak investment activity at major projects.
At Los Pelambres, one of the world’s biggest copper mines, investments include an expanded desalination plant and a new concentrate pipeline.
At the Centinela open-pit mine, construction of a second concentrator is expected in 2027 to support Antofagasta’s medium-term goal of lifting production by 30%. TNM
Left: A Glencore employee performs a slag tap at the Sudbury smelter. GLENCORE
BELOW: Anglo American’s Los Bronces copper mine in Chile. ANGLO AMERICAN
projectupdates
ETM battles Greenland over ‘expropriation’
RARE EARTHS | Refusal to renew licence sparks dispute
BY STAFF WRITER
Energy Transition Minerals
(ASX: ETM) says Greenland has effectively seized one of the world’s largest rare earth deposits outside China by blocking development of the Kvanefjeld project and refusing to renew the exploration licence underpinning it.
The Australian-listed company says it has invested about $150 million in Kvanefjeld through subsidiary Greenland Minerals since 2013, advancing the project through resource definition, environmental studies and public consultation before applying for a mining licence in late 2020.
Months later, Greenland’s new coalition government passed Act 20, banning projects with uranium concentrations above 100 parts per million (0.01%), halting Kvanefjeld’s application.
Managing director Daniel Mamadou argues the legislation was designed specifically to stop the project after the government campaigned on opposing its further development.
“We’ve got a Greenlandic government that states that it is open for business and that it wants to do more mining projects,” Mamadou said last month on The Northern
Miner Podcast. “And yet we have what is the most advanced shovel-ready project in Greenland in rare earth, in critical minerals, that is essentially stopped.”
Greenland government officials hadn’t responded to e-mailed requests for comment from The Northern Miner as of press time.
‘Pack up and go’ Energy Transition Metals were
trading at A5¢ apiece in Sydney as press time neared, valuing the company at A$99.6 million (C$98.6 million). That’s unchanged from June 26, when Greenland rejected a licence-renewal request.
The dispute has since widened beyond the mining application. Mamadou said Greenland had routinely renewed the company’s exploration licence every three years, including once after Act 20
became law, when officials maintained that the legislation applied only to mining activities, not exploration.
The current government has since reversed that position, refusing to renew the permit on the grounds that the project can never comply with the uranium threshold. ETM argues the decision ignores exploration results from 2025 identifying rare earth miner-
alization with uranium levels well below the legal limit across largely unexplored parts of the licence area. It also says the government rejected its proposal to separate uranium from the rare earth concentrate and permanently return it underground.
At the centre of the legal battle is whether Act 20 applies retroactively to the Kvanefjeld project and, if so, whether doing so amounts to expropriation.
Mamadou said the legislation’s explanatory notes allow the government to waive the law where applying it would constitute expropriation, yet Greenland has avoided answering that question despite more than three years of arbitration and court proceedings. ETM says its objective is not financial compensation but rather the reinstatement of its mining licence application.
Strategic stakes
Kvanefjeld hosts neodymium, praseodymium, dysprosium and terbium, rare earth elements essential for permanent magnets used in electric vehicles, wind turbines and defence technologies. ETM has previously estimated the project
https://dundeetechnologies.com/home | info@dundeetechnologies.com
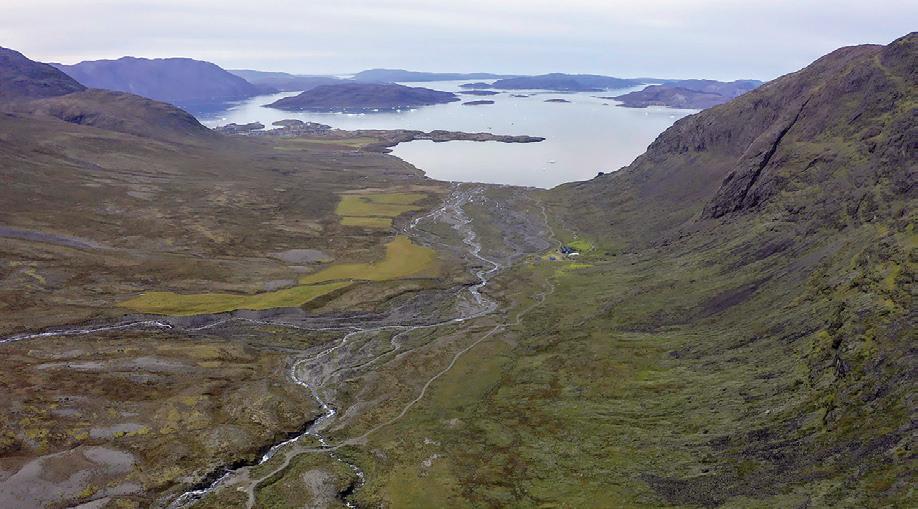
ETM’s Kvanefjeld rare earths project in southern Greenland. ENERGY TRANSITION MINERALS
projectupdates
Getchell sees $905M Fondaway value
GOLD | Study builds on resource
BY FRÉDÉRIC TOMESCO
Getchell Gold (CSE: GTCH; US-OTC: GGLDF) says a revised preliminary economic assessment (PEA) for its proposed Fondaway Canyon open-pit gold mine in Nevada has boosted the project’s value by 67% thanks to increased resources and output.
Using an 8% discount rate and a $3,200-per-oz. average gold price, Fondaway Canyon now has an after-tax net present value (NPV) of $905 million (C$1.3 billion), an internal rate of return (IRR) of 53% and a payback period of two years, Getchell said July 21. Initial capital is estimated at about $265 million, while life-of-mine cash flow is pegged at $1.59 billion.
Fondaway Canyon holds 22.1 million indicated tonnes grading 1.4 grams gold per tonne for 999,000 contained oz. gold and 45.6 million inferred tonnes grading 1.24 grams gold for 1.81 million contained ounces.
The company envisions a conventional open-pit mining operation feeding an 8,000-tonne-perday mill over 10.1 years.
“Today’s release marks a material upgrade to the size, scale, and economics of the Fondaway project, all achieved in just over one year and only drilling 10 holes in that period,” Ben Pirie, a mining analyst at Atrium Research, said Tuesday in a note.
“Not only does it generate a robust NPV, but with an initial capex of just $265 million, the project should be straightforward to finance, substantially mitigating development risk,” he added. Fondaway Canyon “now ranks among the higher-quality gold development assets in the region.”
Shares of Getchell surged 20% to 20¢ apiece in Toronto on the day of the announcement before rising to 30¢ near press time for a market capitalization of C$59.8 mil-
lion ($42.4 million). The stock has traded between 21¢ and 47¢ in the past year.
Higher prices
Getchell’s initial PEA, released in February 2025, outlined an aftertax NPV of $543 million at an average gold price of $2,250 per ounce. Higher gold prices and an enlarged resource base account for the subsequent increase in project value.
Fondaway Canyon would produce about 150,000 oz. gold annually over the mine’s life, according to the new study. Life-of-mine operating costs are projected at $1,373 per oz., while cash costs are estimated at $1,740 per oz. of produced gold.
Annual output of 150,000 oz. “would likely place Fondaway Canyon in the top 10 mining operations in Nevada,” Getchell President Mike Sieb said in the statement.
Expansion potential
Estimates used in the PEA are limited to the open-pit resource in the
project’s central area, Getchell says. Underground resources below the main pit aren’t included in the calculations, nor are the open-pit resources outside the central area.
Gold mineralization remains open along strike and at depth with significant potential for expansion, according to the company.
Located about 170 km east of Reno, Fondaway Canyon is a past-producing gold property with exploration dating back to the 1970s. Getchell acquired the project in 2020 and has since completed multiple drill campaigns that substantially expanded mineralization and identified new zones.
The updated PEA comes about three months after Getchell filed a counter-claim in response to a third party staking on 120 of its 261 claims, including ground covering the conceptual pit area. Getchell has said its claims remain valid and in good standing. The new PEA didn’t mention the alleged illegal staking. TNM
Thunder preps Tower Mountain growth
ONTARIO | Resource update due this year
BY FRÉDÉRIC TOMESCO
New drilling by Thunder Gold (TSXV: TGOL; US-OTC: TGOLF) at its Tower Mountain project in Ontario has confirmed the deposit’s main trend continues at depth and remains open for further expansion.
Standout hole TM26-204 at the UV target cut 45 metres of 1.79 grams gold per tonne from 277 metres depth within a broader interval of 142 metres averaging 0.67 gram gold from 190 metres downhole, Thunder Gold said last month. Hole TM26-203, meanwhile, cut 14 metres averaging 0.61 gram gold from 3 metres depth in previously un-estimated rock.
“Ultimately, Thunder Gold now has a stronger understanding of the UV target,” Atrium Research mining analyst Riley Venton said in a note. “Step-out holes have confirmed continuity of the lowgrade core at depth, which remains open, while shallow drilling identified additional near-surface mineralization within the pit.”
Thunder Gold is planning to drill about 15,000 metres at Tower Mountain this year ahead of a resource update in the fourth quarter. The site is about 40 km west of Thunder Bay.
The company is targeting an expanded resource of as many as 5 million oz. gold, which would include 1.5 million indicated oz. and 3.5 million inferred ounces. This would position Thunder Gold to deliver a preliminary economic assessment, Venton said.
January resource
Tower Mountain holds 34.5 million indicated tonnes grading 0.46 gram gold for contained metal of 514,000 oz. gold, according to a January resource. It also has 211.1 million inferred tonnes at 0.45
assays point to bigger lode
BY BLAIR MCBRIDE
New assay results from Awalé Resources’ (TSXV: ARIC) Newmont(TSX: NGT; NYSE: NEM) backed gold-copper Odienné project in Côte d’Ivoire show the high-grade core of the BBM target extends under the open-pit resource, suggesting it hosts an underground portion.
Highlight hole BBDD-31 returned 7 metres grading 7.04 grams gold per tonne, 0.16% copper, 0.88 gram silver and 94 parts per million (ppm) molybdenum from 385 metres depth, Awalé reported July 20. That included 36 metres at 1.51 grams gold, 0.47% copper, 2.14 grams silver and 391 ppm molybdenum. Odienné is about 600 km northwest of the country’s financial capital Abidjan.
Calling the results “positive,” SCP Resource Finance analyst Justin Chan said he models a 10.5-year open pit mine at BBM producing grades of 1.1 grams gold and 0.3% copper, as well as 10.5 years at 200,000 tonnes annually at 5 grams gold at the Charger deposit.
“An [underground mine] at BBM would extend mine life,” he said. “Today’s drilling highlights that there are still meaningful
value levers to add to net asset value, including adding ounces on Awale’s ground, plus defining Charger 2 and BBM underground, to extend mine life beyond 10 years and potentially lifting production [higher than] 150,000 oz. per year.”
Investment tailwind
The results from Awalé, which is fresh off of a $14.2-million (US$10.1-million) investment last month from mid-tier West African producer Predictive Discovery (ASX, TSX: PDI), could help significantly expand the target and raise Odienné’s resource towards the size of its larger peers in Côte d’Ivoire.
“The presence of Fortuna and Predictive on the register shows that producers see the ‘will be a mine’ potential at Odienné that we see and are willing to see out Newmont’s presence in the JV and Awale’s register,” Chan said.
Awalé shares gained 8% to 80¢ apiece in Toronto on the day of the announcement before rising to 87¢ near press time for a market capitalization approaching $103 million. The stock has traded in a 12-month range of 48¢ to $1.18
Highest grades
The first holes below the open pit hit as expected and returned the highest gold grade drilled at the deposit to date, Awalé CEO Andrew Chubb said in a release.
“This tells us the high-grade core contin-
Thunder Gold is planning to drill about 15,000 metres at Tower Mountain this year.
gram gold for about 3.1 million oz. gold.
Other new drill results include hole TM26-200, which cut about 239 metres averaging 0.26 gram gold from about 362 metres depth. Hole TM26-198, meanwhile, intersected 39 metres of 0.32 gram gold within 100 metres of surface in a new mineralized zone immediately adjacent to the current optimized pit limit.
The new results improve “the overall economics of a potential open-pit operation,” CEO Wes Hanson said in the statement. “The step-out holes confirm that the low-grade core at UV continues at depth and remains open, while the shallow holes have identified new zones of near-surface mineralization in areas previously modelled as waste.”
Drill program
Resource definition drilling, which will aim to convert inferred resources to indicated, should begin Aug. 1 and run through Sept. 30, Hanson also said. Results are anticipated by mid-October in advance of an updated resource, subject to any delays related to extreme forest fire conditions in northwestern Ontario.
Tower Mountain is located along the Trans-Canada Highway within 3 km of rail and hydro power lines.
Shares in Thunder Gold have declined to 11¢ apiece near press time from a high of 17¢ on June 3. The company has a market capitalization of $30.8 million. TNM
ues at depth and reinforces our belief that the system has more to give.”
Another highlight hole at BBM, BBDD-30, cut 46 metres at 1.93 grams gold, 0.39% copper, 1.78 grams silver and 444 ppm molybdenum from 364 metres depth, including 17 metres grading 2.93 grams gold, 0.45% copper, 2.01 grams silver and 791 ppm molybdenum.
That hole also returned 38 metres at 2.24 grams gold, 0.46% copper, 2.09 grams silver and 529 ppm molybdenum, Awalé said.
Seven rigs
The two holes are the first of 12 in a program targeting areas under BBM’s core, which extends down 600 metres. Seven rigs are currently drilling at the project.
Odienné hosts 32.4 million inferred tonnes grading 1.33 grams gold and 0.33% copper holding 1.4 million oz. contained gold and 93,000 tonnes copper across the BBM, Charger and Empire deposits. BBM comprises most of the resource.
Awalé manages exploration activities across the area of its joint venture with Newmont, while the major provides funding. TNM
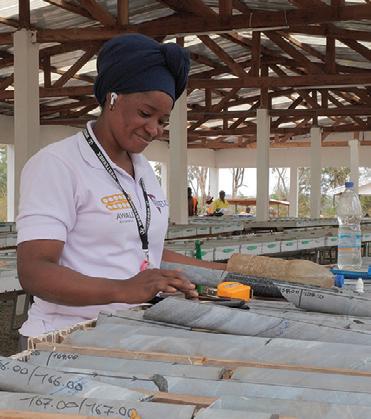
Examining cores at Awalé’s main Odienne project in Côte d’Ivoire AWALE RESOURCES
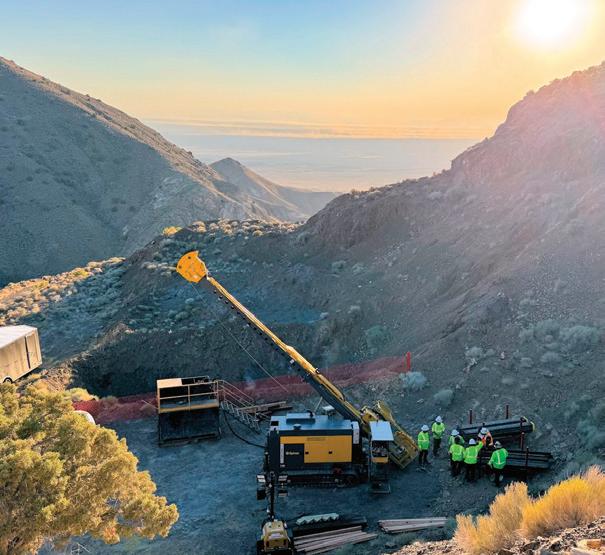
Drilling in the Colorado pit at the Fondaway project. GETCHELL GOLD
donedeals
Seabridge lands $100M loan
GOLD | Money to help advance KSM project
BY COLIN MCCLELLAND
Seabridge Gold (TSX: SEA; NYSE: SA) has secured a $100-million (C$137-million) credit line from an unnamed investor to advance its KSM project in British Columbia despite mounting legal uncertainty surrounding one of the world’s largest undeveloped gold-copper projects more than a decade after government approvals.
The unsecured financing carries a 7% interest rate compounded monthly and matures Dec. 31. Seabridge can draw the funds in minimum $10-million tranches to support work at KSM, the company said last month. It’s an $8.8-billion development about 270 km northwest of Terrace and 950 km northwest of Vancouver in the Golden Triangle region.
The deal comes as the project faces two separate legal hurdles: a B.C. Supreme Court ruling requiring renewed Indigenous consultation over KSM’s “substantially started” status and an ongoing dispute with Tudor Gold (TSXV: TUD) over permits for the Mitchell Treaty Tunnels, a 12.5-km section that crosses Tudor’s Treaty Creek property.
“We are pleased to secure financing to support the significant investments we are making in our summer season work programs,” chair and CEO Rudi Fronk said in a release. “Our 2026 work programs at KSM include building of roads to provide improved access to future infrastructure areas and the collection of geotechnical, metallurgical and environmental data… required to support KSM’s feasibility level design and engineering activities.”
The deal comes as the project faces two separate legal hurdles.
Court issues
In June, the B.C. Supreme Court ordered the Environmental Assessment Office to reconsider whether KSM had been substantially started after finding the province failed to adequately consult the Tsetsaut Skii km Lax Ha Nation before making its 2024 determination. Separately, B.C. has withheld amendments to permits for the Mitchell Treaty Tunnels until Seabridge and Tudor resolve their dispute over the route.
KSM hosts proven and probable reserves of 2.29 billion tonnes grading 0.64 gram gold per tonne, 0.14% copper, 2.2 grams silver and 76 parts per million molybdenum for 47.3 million oz. gold, 7.3 billion lb. copper, 160 million oz. silver and 385 million lb. molybdenum, according to a 2022 prefeasibility study.
The financing gives Seabridge the flexibility to continue advancing KSM while it seeks a development partner for the project. If the loan remains outstanding at maturity, the company may repay it in cash or, subject to Toronto Stock Exchange approval, with common shares.
Since acquiring KSM from Placer Dome in 2001, Seabridge has invested about $1.2 billion in the project and says it has completed more than $200 million in additional permanent works since applying for substantial-start status in January 2024. TNM
Forrest’s $133M bet lifts EQR
TUNGSTEN | Top Western producer
BY STAFF WRITER
Mining billionaire Andrew Forrest agreed to buy a 17% stake in EQ Resources (ASX: EQR) from Oaktree Capital Management, sending the Australian tungsten producer’s shares to their biggest gain in nearly 18 months.
EQ Resources shares surged 34% on July 20 to 30¢, up from their previous close of 22¢, marking their strongest one-day gain since February 2025. That boosted the tungsten producer’s market capitalization to A$1.52 billion (US$1.06 billion).
Forrest’s private investment vehicle, Wonongarra, will acquire Oaktree’s entire holding of about 862.1 million shares and 35.6 million options, EQ Resources said last month. The transaction values the stake at A$190 million based on the July 17 closing price and makes Forrest the company’s largest shareholder.
Oaktree became a cornerstone investor in 2023, backing EQ through a period of weak tungsten prices and helping finance its acquisition of the Barruecopardo mine in Spain and expansion of the Mt Carbine project in Queensland.
“Oaktree backed our vision at a pivotal time, and their partnership has been instrumental in establishing EQR as the leading Western tungsten producer,” managing director Craig Bradshaw said. He described Forrest’s investment as “a strong endorsement for EQ Resources.”
The deal underscores growing investor interest in Western sources of tungsten as governments and manufacturers seek alter-
natives to China, which produces about 80% of the world’s supply.
Prices have surged since Beijing imposed export controls on the metal, while rising defence demand and a U.S. ban taking effect on Jan. 1, 2027, on defence contractors using tungsten sourced from China, Russia, Iran or North Korea are expected to tighten global markets further.
“The world has woken up to how fragile critical mineral supply chains have become,” Forrest said. “Tungsten is essential to the machines that build our homes, hospitals, cities and modern-day energy systems, as well as the semiconductors in every phone and computer. Yet global supply is remarkably concentrated.”
Australia holds the world’s second-largest tungsten reserves after China, according to the Department of Industry, Science and Resources.
EQ Resources says it is the largest Western tungsten producer, and the company said Forrest’s investment will not affect its strategy, management team, day-to-day operations or employees. TNM
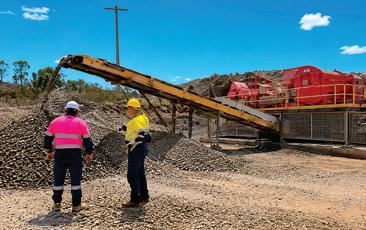
The Mt Carbine processing plant. EQ RESOURCES
eye on australia
Genesis boss hails Vault merger as perfect pairing
GOLD | Deal to generate $1.4B in savings
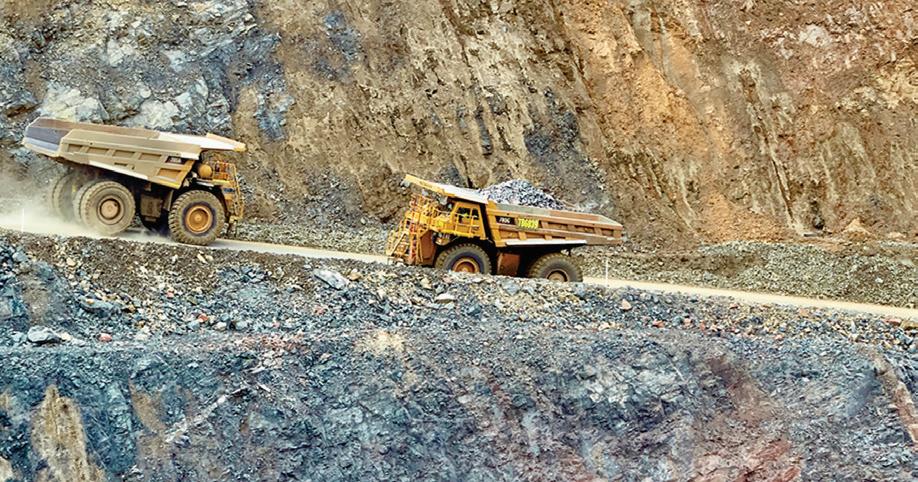
BY KRISTIE BATTEN
Genesis Minerals (ASX: GMD) says its proposed merger with Vault Minerals (ASX: VAU) is the “perfect pairing” to create Australia’s third largest locally listed gold producer with A$2 billion (US$1.4 billion) in projected synergies.
The all-share and cash transaction values Vault at about A$5.6 billion. It will create a Western Australian-focused producer with a pro-forma market capitalization of almost $9 billion (A$12.6 billion).
Rival suitor Regis Resources (ASX: RRL) last month abandoned its pursuit of Vault, clearing the way for the deal with Genesis to proceed. Regis said July 13 it wouldn’t exercise its right to match or improve Genesis’ superior proposal under an existing agreement with Vault. It will receive a break fee of about A$50.7 million when the agreement is terminated.
Vault shareholders will receive 0.7629 of a new Genesis share plus A47.5¢ in cash for each Vault share, leaving them with about 40% of the combined company. The merged group is expected to produce 600,000-700,000 oz. of gold annually, hold 33.6 million oz. in resources and 9.4 million oz. in reserves, ranking behind only Northern Star Resources (ASX: NST) and Evolution Mining (ASX: EVN) among ASX-listed gold producers.
“This will be a globally relevant scale of liquidity sought by global
“We have a lot of upfront cost-saving synergies that will come through immediately to make us more robust in a declining gold price environment.”
RALEIGH FINLAYSON, CHAIR, GENESIS MINERA
investors, including potential index inclusions and upweighting,” Executive Chairman Raleigh Finlayson said on a mid-July conference call. “But to be clear, this is an outcome or reward for shareholders—not a reason for the deal.”
Asset proximity
The merger brings together neighbouring operations in Western Australia’s Leonora-Laverton district, where the companies’ flagship assets sit just 35 km apart. Genesis estimates the combination will generate A$1.5 billion over a decade in synergies tied directly to the proximity of the assets.
Ore from Genesis’ Tower Hill project will be processed through Vault’s King of the Hills mill, eliminating the need to build a new processing plant and expand the Laverton mill, saving an estimated A$715 million in growth capital.
Genesis expects the combined company to hold A$611 million in pro-forma net cash and A$1.4 billion in liquidity, supported by underlying quarterly cash flow exceeding A$200 million across both businesses.
Finlayson said the merger builds on Genesis’ recent A$669-million
acquisition of Magnetic Resources and its 2.2-million-oz Lady Julie gold deposit, while leaving room for additional operational improvements.
“We have a lot of upfront cost-saving synergies that will come through immediately to make us more robust in a declining gold price environment, but also, we have the second largest resource position in Australia which gives us upside as far as organic growth opportunities in the portfolio,” he said.
Not a ‘fix-it’ job
Genesis expects the transaction, unanimously recommended by the Vault board, to close in November. Finlayson will lead the integration and a strategic review of the combined asset portfolio, with an updated corporate plan due in the first half of 2027.
He declined to say whether smaller assets such as the Deflector mine in Western Australia or the Sugar Zone project in Canada would remain core to the business.
“To be clear, this merger is not a fix-it job,” Finlayson said. “All mines across both portfolios are running well.”
BHP strike rattles supply
IRON ORE | First walkout since 2000
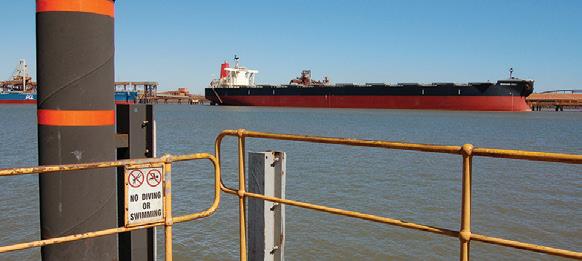
BY STAFF WRITER
Workers at BHP’s (LSE, NYSE, ASX: BHP) Port Hedland operations in Western Australia launched the first strike at the company’s Pilbara iron ore hub in decades after last-ditch negotiations failed.
About 200 operators and maintenance workers represented by the Combined BHP Ports Unions walked off the job for an eighthour stoppage on July 16. A fivehour bargaining session, facilitated by Australia’s Fair Work Commission, failed to produce a breakthrough. Further talks were scheduled as The Northern Miner went to press.
“We have tabled a draft agreement which includes a 16% pay increase over four years for the majority of employees, improved allowances and simplified pay structures,” BHP said in a statement. “We will hold further discussions with unions.”
The dispute has become one of the largest union campaigns at BHP’s iron ore operations in years and could draw close attention from commodity markets if it escalates into prolonged disruptions at the world’s largest bulk-export terminal. Iron ore futures in Singapore climbed as high as $102 a tonne on the day the walkout occurred, their highest level since July 2.
Six-month talks
The unions say they have spent more than six months trying to negotiate a collective agreement, arguing BHP’s reliance on individual employment contracts leaves workers on inconsistent terms and conditions.
“For eight months this company has stonewalled and gaslit the people whose labour generated $15 billion in profits last year,” Adam Woodage, Western Australia secretary of the Electri-
Malaysia probes Lynas’ Pentagon deal
Malaysia is scrutinizing Lynas Rare Earths’ (ASX: LYC)
$96-million supply agreement with the U.S. Department of Defense after a parliamentary committee reviewed whether the deal could affect the country’s support for the Palestinian cause and future rare earths policy.
The parliamentary special select committee on international rela-
tions and international trade, chaired by MP Wong Chen, met on July 16 to examine the Australian company’s role in the U.S. defence supply chain, according to a statement.
The committee heard from government officials, non-governmental organizations and Lynas executives. It recommended the government develop a clearer foreign investment policy to protect Malaysia’s national interests and
sovereignty and issue an official position on the matter within two weeks.
“The committee convened this proceeding to examine and assess the impact of the supply agreement, which is viewed as potentially affecting Malaysia’s reputation as a steadfast supporter of Palestine,” the committee said.
Domestic pressure
The review follows growing do-
mestic pressure over Lynas’ fouryear Pentagon agreement. More than 20 Malaysian civil society organizations, including Greenpeace Malaysia, urged greater oversight of the country’s rare earths supply chain, arguing the agreement supports the U.S. military, which backs Israel in its war against Hamas in Gaza.
Muslim-majority Malaysia has long supported the Palestinian cause and has not established dip-
cal Trades Union, said in a statement. “Today we are sending a message that Australian workers will not be worn down.”
About 575 million tonnes of iron ore moved through Port Hedland last year, although the port is also used by other mining companies unaffected by Thursday’s strike. BHP said it has contingency plans to ensure operations continue safely during the industrial action.
Investment plans
BHP’s iron ore production fell 3% year over year in the quarter to June 30, although full-year output remained broadly unchanged despite the weaker finish to the fiscal year, the company reported in mid-July.
“BHP’s fiscal fourth-quarter operational update was a touch better than expected, including iron ore of 68.1 million tonnes and copper of 492,000 tonnes, although the company reported a stronger than expected finish in both met and thermal coal (+9/17%),” BMO Capital Markets mining analyst Alexander Pearce said in a note.
“Positively, fiscal 2026 costs in copper are expected to be at the bottom end of prior guidance,” Pearce said. “Looking ahead, maiden fiscal 2027 production guidance is as expected, which includes broadly flat year on year iron ore, but about a 12% year on year decline in copper.”
Separately, BHP said it had approved a $900-million investment in the Ministers North project, a high-grade Brockman iron ore deposit southeast of Yandi in Western Australia’s Pilbara region.
The development will add 20 million tonnes of annual production capacity once fully ramped up, supporting BHP’s medium-term production target of 305 million tonnes a year. First ore is expected in fiscal 2029. TNM
lomatic ties with Israel.
The committee said its findings will help shape Malaysia’s rare earths policy as the country seeks investment to expand its domestic industry.
Lynas, the world’s largest rare earths producer outside China, operates the world’s biggest rare earths processing facilities in Malaysia. It didn’t respond to requests for comment by press time. TNM
Haul trucks at Genesis’ Jupiter gold mine in Western Australia. GENESIS MINERALS
Port Hedland, Western Australia. BAHNFREND/WIKIMEDIA COMMONS
Treasurehunt
Canada’s first mining frontier
COIN SEARCH | Mineral rushes precede Klondike
BY NORTHERN MINER STAFF
Long before prospectors flooded the Klondike in search of gold, long before Sudbury became synonymous with nickel and long before Saskatchewan uncovered its vast potash deposits, Nova Scotia was already mining.
In many ways, it was Canada’s original mining frontier. Its treasures were not hidden in remote mountains or northern wilderness. They lay along windswept coastlines, beneath fishing villages and under the crashing waves of the Atlantic Ocean. Coal, gold, iron, gypsum, salt and copper helped build Nova Scotia, powered Canada’s industrial growth and transformed quiet settlements into bustling company towns.
The province’s mining story is unlike any other in Canada. It is a tale of remarkable discoveries, engineering triumphs, colourful characters and generations of miners who helped shape a young nation. It is also a story marked by hardship and hard-won lessons that would ultimately help make Canada one of the world’s most respected min ing jurisdictions.
Nova Scotia’s gold mining predates the rest of the country’s marquee min ing stories. Its first rush started in 1861 at Mooseland, more than 30 years before the Klondike, and it saw three distinct boom periods through 1942.
Nation-building coal
The first Europeans to notice Nova Scotia’s mineral wealth were astonished by how easy it was to find.
In 1672, French explorer Nicolas Denys reported seeing coal seams exposed along the shores of Cape Breton. In some places, black coal literally pro truded from sea cliffs. By the early 1700s, French soldiers at Louisbourg were mining coal near present-day Port Morien, creating what many historians consider some of the earliest commercial mines in Canadian history.
metres beneath the Atlantic Ocean, where miners laboured with thousands of tonnes of seawater hanging above them.
Coal from Nova Scotia powered locomotives, fuelled steel mills and supplied both world wars. For generations, it helped drive Canada’s industrial development.
Hard lessons underground
Every treasure comes with a price.
Nova Scotia miners endured some of the toughest working conditions in Canadian history. Cave-ins, explosions and flooding were constant dangers.
No place symbolized this reality more than Springhill, where a series of disasters culminated in the famous Springhill Bump of 1958. The rescue effort captured international attention and remains one of the defining moments in Canadian mining history.
Gold processing in the 19th- and early-20th-centuries left arsenic- and mercury-laden tailings scattered near old mine sites. They are a defining feature of mining legacy conversations
Coal quickly became Nova Scotia’s first great treasure.
As Britain industrialized, demand for fuel soared. The vast coalfields of Cape Breton, Pictou County, Springhill and Joggins became strategic assets of the British Empire.
One unlikely pioneer was Reverend James McGregor, a Presbyterian minister credited with identifying important coal deposits near Pictou in 1798. By the 1820s, British investors were pouring money into Nova Scotia’s mines. The General Mining Association introduced steam engines and modern mining methods, while the famous Samson locomotive became the first locomotive in Canada to run on iron rails.
Nova Scotia was no longer simply a fishing colony. It was becoming an industrial powerhouse.
King coal
For much of the 19th and early 20th centuries, coal was the backbone of Nova Scotia’s economy.
The mines of Cape Breton fuelled factories, railways, steamships and homes across eastern North America. Entire communities grew around collieries whose names became famous across Canada: Glace Bay, New Waterford, Sydney Mines, Springhill and Stellarton.
At its peak, Cape Breton’s coal industry ranked among the largest energy enterprises on the continent. Some underground workings stretched kilo-
Cape Breton were already extracting the red metal from the hills overlooking Sydney Harbour.
Iron mines at Londonderry supplied one of Canada’s earliest steel industries, while gypsum, salt and barite operations contributed to an extraordinarily diverse mining economy.
For a province of modest size, Nova Scotia produced a remarkable range of mineral wealth.
Treasure beneath the waves By the late 20th century, coal production declined, steel mills struggled and environmental challenges such as the Sydney Tar Ponds left lasting impressions on public opinion.
Yet the geology never disappeared.
Today, Nova Scotia remains richly endowed with gold, copper, critical minerals and industrial resources. In 2025, the province rescinded the 44-year ban on uranium exploration. The government has created what it calls “faster, smarter permitting” to chop permit timelines in half. And it’s targeting a grid transformation of reaching 80% clean power generation by 2030.
Companies are probing dormant
“Nova Scotia’s gold mining predates the rest of the country’s marquee mining stories. Its first rush started in 1861, more than 30 years before the Klondike.”
fracking moratorium for years, both grounded in public health and environmental opposition going back to a 1981 uranium moratorium. That’s a stricter stance than provinces like Saskatchewan, which has been a major uranium producer for decades.
The coalfields also became battlegrounds for workers’ rights. Labour leader J.B. McLachlan emerged as the voice of Cape Breton miners during bitter struggles for safer workplaces and fair wages.
Those conflicts left deep scars, but they also helped drive improvements in mine safety, labour standards and worker protections. Many of the practices that Canadians take for granted today were forged through experiences like those in Nova Scotia’s coalfields.
The province helped teach Canada how to mine better.
Gold, copper
Coal may have dominated Nova Scotia’s economy, but it was far from the province’s only treasure.
The Mooseland discoveries in 1860 spawned camps at Waverley, Sherbrooke, Tangier and dozens of other locations. The province became one of Canada’s leading gold producers for decades.
Nova Scotia was also home to some of Canada’s earliest metallic mining ventures. At Coxheath near Sydney, copper mining began in the late 1700s and is often regarded as one of the first significant metal mining operations in the country. Long before copper became essential for electric vehicles and power grids, miners in
Industry remembers Chester Millar
OBITUARY | Engineer advanced explorers to producers
BY BLAIR MCBRIDE
CHESTER MILLAR, a Canadian Mining Hall of Fame (CMHF) entrepreneur and pioneer of the heap leach recovery method, passed away on June 23. He was 98. Millar, leader of several companies, co-founded Alamos Gold and guided its acquisition of the Mulatos gold project in Mexico. He also headed the discovery of the Afton copper-gold deposit in Kamloops, B.C. He started Afton Mines which was acquired by Teck Resources in 1981.
People over numbers
Inducted into the Hall of Fame in 2008, his acceptance speech showed that mining meant a lot more to him than just balance sheets or the next discovery.
“Mining companies are in danger of leaving a bad impression, by going down to these places and very quickly building mines and leaving them with nothing,” he said. “We should not let the stock exchange tell us guys how to run a mine.”
Under Millar and Alamos Gold CEO John McCluskey’s leadership, the pair purchased the Mulatos mine in Mexico in 2003 when Millar was in his mid-70s, McCluskey told The Northern Miner in an email.
Mulatos success
While they had started Alamos almost a decade earlier, low prices put the company in a tough spot and they limited the overhead to survive.
gold mines to take advantage of record prices. And explorers are searching for the materials needed to support electrification, renewable energy and modern infrastructure, such as lithium, rare earths, tin and antimony.
They are building on the province’s mining legacy, which is more than a story of what was taken from the ground. It is a story of innovation, resilience and learning.
Nova Scotia gave Canada some of its first coal mines, first industrial railways, earliest metal mines and most important mining communities. Its miners helped power a nation, while their experiences helped shape the safety standards, labour protections and environmental expectations that define modern Canadian mining.
Walk along a Cape Breton shoreline at sunset and you might still spot a seam of coal peeking from the cliffs. It is a small reminder of a remarkable truth. Long before Canada became a mining nation, Nova Scotia was already digging up its future. TNM
This campaign is proudly presented with the support of industry sponsors including Agnico Eagle Mines, Sprott Money, EarthLabs, Iamgold, Kinross Gold, The World Gold Council, Alamos Gold, Ernst & Young, MINING.COM, CEO.CA and The Canadian Mining Journal.
For more information, including full contest rules, FAQs and updates, visit treasure.northernminer.com. Follow @northernminer (X/FB/YouTube) | @thenorthernminer (IG) | @mining (X) | @miningdotcom (IG/FB/YouTube) | @ceodotca (X/IG/FB/TikTok) | @ceocafilm (YouTube) for ongoing clues and community updates.
“Chester deserves a lot of credit for helping us acquire the mine,” McCluskey said. “Over the next couple of years the project was permitted, financed and built. It has gone on to mine over 4 million oz.of gold, generate over $1 billion in profit for Alamos shareholders and has paid over $300 million in taxes to the government of Mexico.
“It is one of the most profitable mines ever developed by a junior mining company.”
In his roles as chairman of Glamis Gold and Eldorado Gold in the 1980s and 1990s, Millar helped advance them from juniors to gold producers.
In addition to his CMHF accolade, in 1989 Millar was awarded the B.C. and Yukon Chamber of Mines’ Edgar A. Scholz Medal for his outstanding contributions to mine development.
Heap leach pioneer
In the 1970s, Millar was focusing on heap-leach gold mining, where a chemical solution dissolves gold from low-grade crushed ore. After he discovered a large, lowgrade gold property in 1975 near Glamis, Calif., about 360 km southeast of Los Angeles, he started the first heap leaching operation in the state.
He was made co-owner of that mine and he then acquired a gold site that became the Picacho mine under Glamis Gold. His heap leach expertise was applied again to mines elsewhere in the U.S., Latin America and New Zealand.
Millar is survived by his daughter Susan, his daughterin-law Allison Clokie, his grandchildren Taylor, Kerry, and Charlotte (Ben); and his great-grandchildren, James and Emma.
Millar was born in Powell River, B.C. and raised in North Vancouver. He graduated from the University of British Columbia with a degree in mining engineering. Early in his career in the 1960s, he worked for coal and iron companies before pursuing the drilling and blasting business.
Speaking at Millar’s CMHF induction ceremony in 2008, McCluskey recalled a discussion with him from years before about the potential profitability of a mine in Honduras.
“I’m here for other reasons,” Millar said in McCluskey’s account of the exchange. “That mine employs 500 people. Think of all the families that have a decent standard of living because of those jobs. There’s a lot more dignity in holding a job than getting a handout.”
Alamos CEO John McCluskey, left, and Millar at the Picacho site in California in 1984. ALAMOS GOLD
NOVA SCOTIA
Why miners are rethinking tailings
BY NORTHERN MINER STAFF
Tailings management is becoming a larger part of the mining industry’s planning process as companies seek to reduce water use, extend the lives of existing storage facilities and lower longterm environmental liabilities.
At the same time, advances in dewatering technology and mineral processing are prompting operators to look at tailings not only as a waste stream, but also as a potential source of additional metal recovery.
Those trends are encouraging miners to consider alternatives to conventional slurry storage, particularly as permitting new tailings facilities becomes more difficult and projects face growing pressure to improve water stewardship and reduce risk.
TODD WISDOM, PRINCIPAL CONSULTANT IN NON-CONVENTIONAL TAILINGS AT SRK CONSULTING
The Northern Miner’s video host Devan Murugan spoke with Todd Wisdom, a principal consultant in non-conventional tailings at SRK Consulting, about how changing approaches to tailings management could affect mine economics, permitting, water management and the recovery of valuable metals from both active and historical tailings.
The Northern Miner: What are nonconventional tailings, and why are miners paying more attention to them?
Todd Wisdom: Conventional tailings management has changed little over the past century. A mine pumps leftover slurry from its processing plant to a tailings storage facility, then tries to recover some water for reuse.
That slurry typically contains particles measuring 100 to 200 microns and about 30% solids. Non-conventional tailings is a category that covers approaches departing from that model, mainly by removing more water before the material reaches the storage facility.
A thickener can raise the slurry to about 50% solids. Further dewatering can produce a paste, while filters can remove most of the water and sharply change how the material is stored.
Other methods mix tailings with waste rock in one facility. Coarse-particle flotation can produce tailings suitable for mine-site construction instead of treating the material solely as waste.
TNM: Why should mine operators treat tailings as a water management issue?
TW: Water drives tailings facility stability, environmental compliance and closure liability. Removing it can cut costs and reduce long-term risk.
Water also links the entire mining system. Operators may dewater the mine and use that water in the processing plant. They add water to help recover minerals, then pay to remove it before sending the tailings to storage. They later recover part of that water and pump it back to the plant.
The more efficiently a mine manages that cycle, the more it can lower costs and improve profitability.
TNM: How can dewatering help extend an operating mine’s life?
TW: This is one of the most practical reasons to consider non-conventional tailings.
An operating mine may discover more resources and convert them into reserves, extending its expected life. Building and permitting a new tailings facility can be
“Greater water recovery also cuts the amount of fresh water a mine needs. That matters in dry regions. It offers just as much value in wetter parts of Canada.”
— TODD WISDOM PRINCIPAL CONSULTANT IN NON-CONVENTIONAL TAILINGS AT SRK CONSULTING
costly, while approval timelines are often uncertain.
Removing more water allows a mine to place denser tailings within its existing footprint. Operators can build higher and more compactly, adding storage capacity and potentially extending mine life by several years.
Canadian mines have already used this approach successfully.
It does not have to be an all-or-nothing decision. A mine can divert part of its tailings stream, test a different method and gain incremental value while learning how the new system performs.
TNM: Can a different tailings strategy make permitting easier?
TW: It can help. Removing some or all of the water can reduce the size of the dams needed to retain slurry. Those dams rank among the largest risks and liabilities regulators examine when reviewing a mine proposal.
Smaller dams and less stored water can reduce risk and may shorten permitting timelines.
Greater water recovery also cuts the amount of fresh water a mine needs. That matters in dry regions, but it can offer just as much value in wetter parts of Canada. Mines in water-rich areas often discharge excess water into the
environment. The less water they bring into the operation, the less they must treat before discharge. Greater tailings dewatering can therefore benefit mines in both wet and water-scarce regions.
TNM: How much value could remain in old tailings?
TW: As a rough estimate, modern mines may leave behind 10% to 15% of the original value of the metals they sought to recover. For tailings produced a century ago, the figure could reach 20% to 30%. Better equipment, reagents and process controls can recover part of that lost value. Critical minerals could add another source of revenue. Many older mines were not looking for these materials when they designed their processing plants. Recovering both the original target metals and previously overlooked critical minerals could change the business case for old tailings.
TNM: Must operators excavate an old tailings facility to recover those metals?
TW: Not always. Re-mining an old facility can prove difficult. Operators may not know how minerals are distributed through the deposit, and building a reliable block model can be challenging.
An operating mine has another option. It can reprocess tailings as they flow from the plant to the storage facility.
A mine could add equipment to recover critical minerals or other metals that its main process leaves behind. Interest in that approach is growing because it can capture value before the material enters permanent storage.
TNM: How will tailings management change over the next five to 10 years?
TW: Mining, processing and tailings teams often work in separate groups with limited crossover. Yet every decision made at the mine or plant affects the tailings facility. The way a company mines its ore, including the amount of clay it handles, affects metal recovery, water use, tailings behaviour and long-term liability. Bringing those teams together earlier can unlock substantial value.
Future mines will focus more closely on reducing both waste rock and tailings. Ore sorting can reject barren rock before milling, and mines can mix some of that material with tailings. Pre-concentration can reduce grinding needs, while coarseparticle flotation can produce material that is easier to drain and handle.
Operators may also separate their tailings streams instead of treating everything the same way. Coarse material could form stronger outer zones in a storage facility. Finer material that is harder to drain or more likely to generate acid could remain in the interior, where operators could manage it under a water cover.
The industry can improve tailings safety, water recovery and metal production, but only if companies design the mine, plant and storage facility as one system rather than three separate silos. TNM
—The preceding sponsored article is PROMOTED CONTENT paid for by SRK and produced in co-operation with The Northern Miner. Visit: https://www.srk.com/en/ for more information.
Above: Dry stack hydro sluicing at a site in Africa. SRK CONSULTING
Left: A tailings reprocessing unit. SRK CONSULTING
metals & markets
18 Market News contents
19 Capital Raisings
20 Drill Results
21 Warrants + Shorts
22 Rare Earths
23 NVIDIA
*Data may not be comprehensive and is provided on a best-efforts basis as of press time. Investors are responsible for their own due diligence.
24 Market Data + Mining events
Delivering fit-for-purpose solutions across the entire project life cycle
Delivering fit-for-purpose solutions across the entire project life cycle
Delivering fit-for-purpose solutions across the entire project life cycle
Delivering fit-for-purpose solutions across the entire project life cycle
Our fit-for-purpose solutions encompass the skills of qualified geologists, geostaticians, analytical chemists, mineralogists, metallurgists, process engineers and mining engineers and inspectors brought together to provide accurate and timely mineral and process evaluation services across the entire project life cycle.
Our fit-for-purpose solutions encompass the skills of qualified geologists, geostaticians, analytical chemists, mineralogists, metallurgists, process engineers and mining engineers and inspectors brought together to provide accurate and timely mineral and process evaluation services across the entire project life cycle.
Our fit-for-purpose solutions encompass the skills of qualified geologists, geostaticians, analytical chemists, mineralogists, metallurgists, process engineers and mining engineers and inspectors brought together to provide accurate and timely mineral and process evaluation services across the entire project life cycle.
Our fit-for-purpose solutions encompass the skills of qualified geologists, geostaticians, analytical chemists, mineralogists, metallurgists, process engineers and mining engineers and inspectors brought together to provide accurate and timely mineral and process evaluation services across the entire project life cycle.
WWW.SGS.COM/NATURALRESOURCES NAM.NATURALRESOURCES@SGS.COM
WWW.SGS.COM/NATURALRESOURCES NAM.NATURALRESOURCES@SGS.COM
WWW.SGS.COM/NATURALRESOURCES NAM.NATURALRESOURCES@SGS.COM
WWW.SGS.COM/NATURALRESOURCES NAM.NATURALRESOURCES@SGS.COM
Week of July 13-17, 2026
Middle East conflict hits stocks
Gold drop weighs on miners
By Frédéric Tomesco
North American equity markets declined as renewed geopolitical tensions in the Middle East and a selloff in semiconductor and artificial intelligence-related stocks hit investor sentiment.
The Dow Jones Industrial Average declined 490.59 points, or 0.9%, to 52,146.42, the S&P 500 lost 117.70 points, or 1.6%, to 7,475.69, and the Nasdaq Composite fell 761.36 points, or 2.9%, to close at 25,520.24.
In Canada, the S&P/TSX Composite Index slipped 0.1% to 35,263.85, while the S&P/TSX Venture Composite Index fell 51.09 points, or 5.64%, to close at 854.89 amid weakness in junior mining and technology shares.
The S&P/TSX Global Mining Index fell 52.62 points, or 0.8%, to 6,892.82, the S&P/ TSX Global Gold Index dropped 32.55 points, or 4.4%, to 704.87, and the spot gold price declined $91.50 (C$128.85), or 2.2%, to $4,012.70 per ounce.
The S&P/TSX Global Base Metals Index fell 20.40 points, or 6.2%, to close at 310.09, while COMEX copper futures for July delivery lost 1.35¢ cents, or 0.22%, to $6.22 per pound.
Among NYSE-listed stocks, gold producers Newmont and Kinross Gold were among the week’s biggest losers as inflation worries tied to the escalating Middle East conflict depressed the price of the yellow metal. Kinross fell 6.5% to $22.57 while Newmont declined 5.9% to $89.70.
Lucara Diamond rose 6.3% to 17¢ in S&P/TSX trading after the company announced the recovery of an exceptional 1,305.4 carat diamond from its Karowe mine in Botswana.
On the S&P/TSX Venture Exchange, Sandfire Resources America soared 68% after the junior explorer said its Black Butte copper project in Montana added reserves over a previous study from 2025.
2
drillresults
TNM DRILL DOWN: TOP ASSAYS OF THE MONTH
Our TNM Drill Down features the top 10 gold, copper and silver assays of the past month. Drill holes are ranked by grade x width.
June 17, 2026 to July 15, 2026
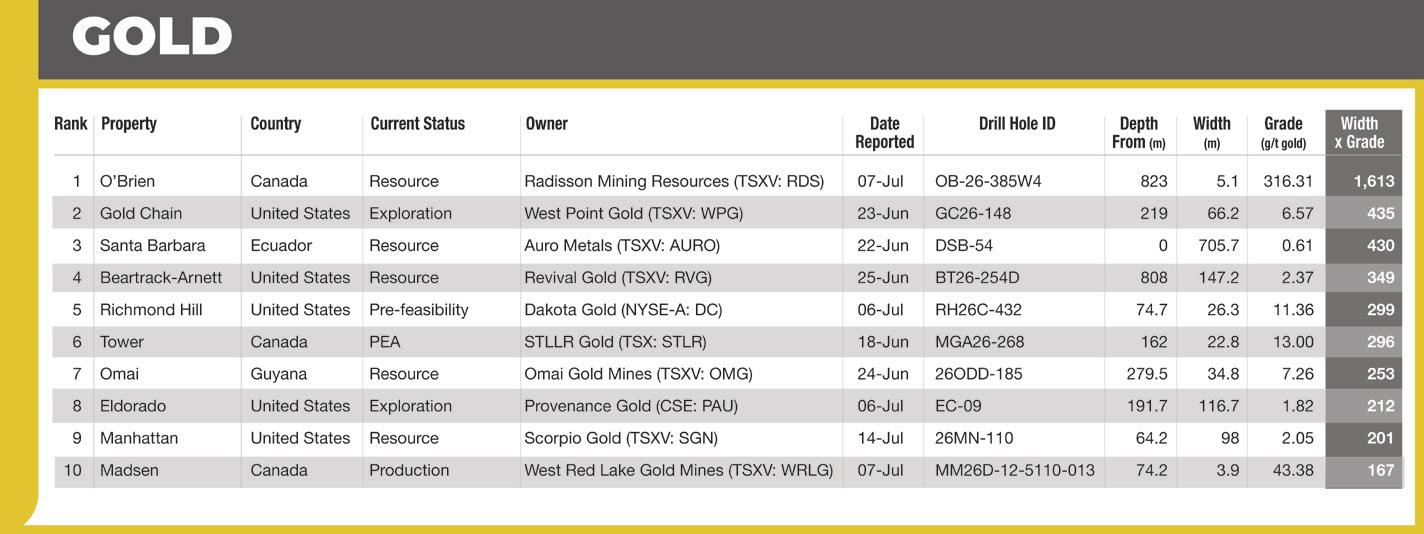
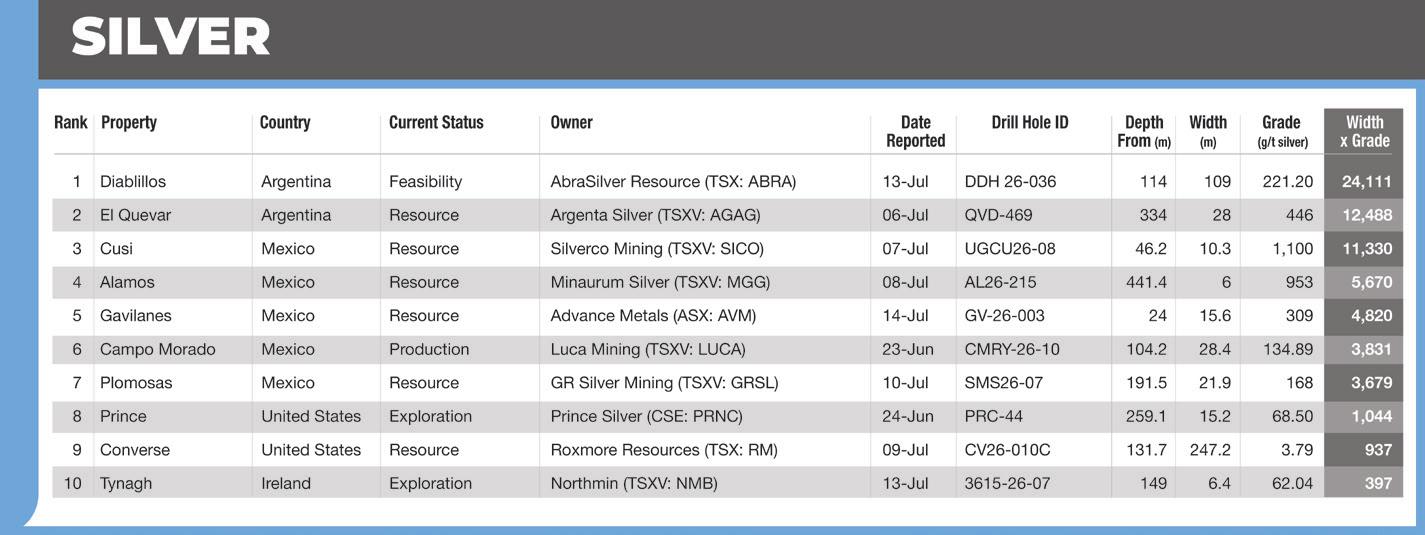
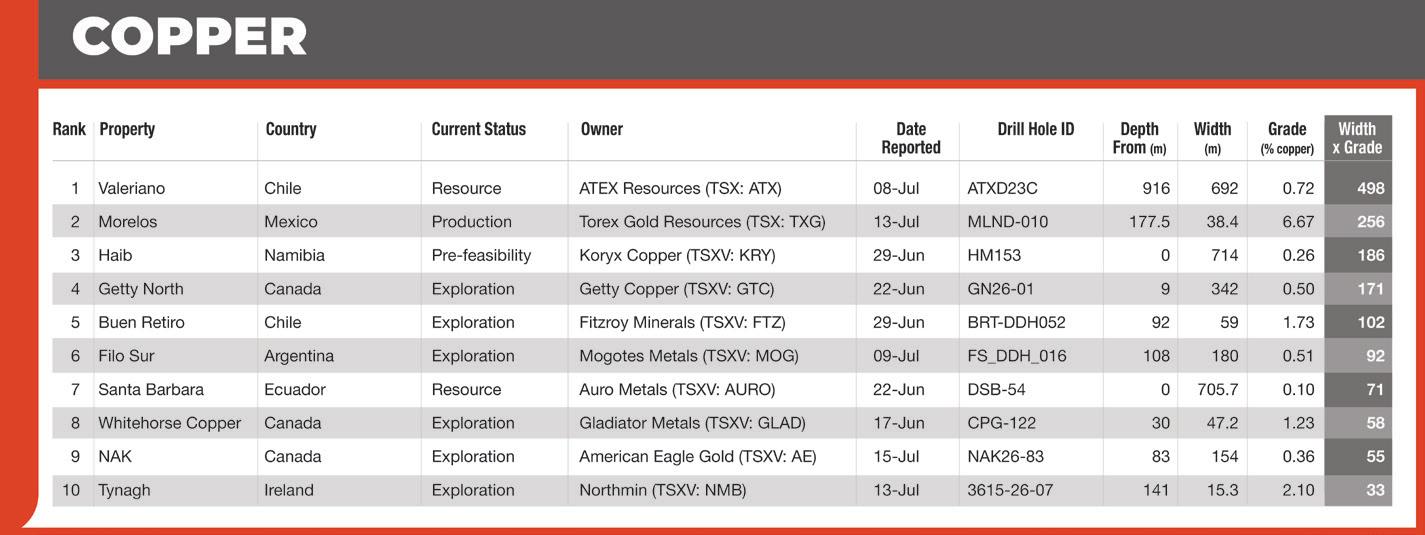
warrants&shorts
TSX WARRANTS
Talisker Resources Ltd. SK.WT One Warrant to purchase one common 5-05-2028 share of the Issuer at $0.75 until expiry
Name Symbol Subsciption Terms Expiry Date
Aurania Resources Ltd. ARU.WT.B One warrant to purchase one common 10-21-2026 share at $2.20 per share.
Tuktu Resources Ltd. TUK.WT One warrant to purchase one common 11-23-2026 share at 13¢ per share.
Freeman Gold Corp FMAN.WT.U One warrant to purchase one common 11-29-2026 share at US65¢ per share.
Palisades Goldcorp Ltd. PALI.WT One warrant to purchase 0.060538 12-06-2026 common share at 50¢ per share.
Mogotes Metals Inc. MOG.WT One warrant to purchase one common 01-31-2027 share at 30¢ per share.
Osisko Development ODV.WT.A One warrant to purchase one common 03-02-2027 Corp. share at $14.75 per share.
Integra Resources Corp. ITR.WT One warrant to purchase one common 03-13-2027 share at $1.20 per share.
Elevation Gold Mining ELVT.WT.A One warrant to purchase one common 03-24-2027 Corp. share at 70¢ per share.
Anfield Energy Inc. AEC.WT One warrant to purchase one common 05-12-2027 share at 18¢ per share.
Osisko Development ODV.WT.U One warrant to purchase one common 05-27-2027 Corp. share at US$10.70 per share.
Sun Summit Minerals SMN.WT One warrant to purchase one common 05-30-2027 Corp. share at 11¢ per share.
Graphite One Inc. GPH.WT One warrant to purchase one common 08-22-2027 share at $1.10 per share.
GoGold Resources Inc. GGD.WT One Warrant to purchase one common 11-27-2028 share of the Issuer at $3.50 until expiry
TSX SHORT POSITIONS
Short positions outstanding as of July 15, 2026 (with changes from June 30, 2026)
Largest short positions Company Ticker Short position Change
Denison Mines Corp. DML 39832673 543777
B2Gold Corp. BTO 29643900 1187720
Discovery Mining Ltd. DSV 29366624 1490596
i-80 Gold Corp. IAU 28725861 -493922
Ivanhoe Mines Ltd. IVN 23212508 553604
Osisko Metals Inc. OM 18588778 -4052039
Barrick Mining Cor. ABX 16814522 3267
Equinox Gold Corp. EQX 13462594 -483652 Global Atomic Corp. GLO 12679403 -114596
NexGen Energy Ltd. NXE 12663970 127135
Lithium Americas Corp. LAC 11751437 536859
Capstone Copper Corp. CS 11704654 -1501419 First Mining Gold Corp. FF 11481002 673426 Vizsla Silver Corp. VZLA 11315759 -32108 Ur-Energy Inc. URE 13348278 203725
Largest increase in short position Hudbay Minerals Inc. HBM 9735805 4571260 Discovery Mining Ltd. DSV 29366624 1490596 Champion Iron Ltd. CIA 3849217 1259601 OR Royalties Inc. OR 2454631 1211460
B2Gold Corp. BTO 29643900 1187720
Largest decrease in short
West
Mines Ltd. share at 90¢ per share.
10-24-2027
i-80 Gold Corp. IAU.WT One warrant to purchase one common 11-14-2027 share at 55¢ per share.
Nexmetals Mining Corp. NEXM.WT One warrant to purchase one common 11-17-2027 share at $8.00 per share.
Lion One Metals Ltd. LIO.WT.A One warrant to purchase one common 02-14-2028 share at 41¢ per share.
West Red Lake Gold WRLG.WT.C One warrant to purchase one common 02-25-2028
Mines Ltd. share at 90¢ per share.
Silver Mountain AGMR.WT.B One warrant to purchase one common 04-24-2028 Resources Inc. share at 13.5¢ per share.
Bear Creek Mining Corp. BCM.WT One warrant to purchase one common 10-05-2028 share at 42¢ per share.
E3 Lithium Ltd. ETL.WT One warrant to purchase one common 10-14-2028 share at $1.50 per share.
Oroco Resource Corp. OCO.WT One warrant to purchase one common 01-15-2029 share at 53¢ per share.
West Red Lake Gold WRLG.WT.A One warrant to purchase one common 03-19-2029 Mines Ltd. share at 95¢ per share.
Osisko Development ODV.WT.V One warrant to purchase one common 10-01-2029 Corp. share at US$3.00 per share.
Cat Strategic Metals CAT.WT One warrant to purchase one common 11-21-2030 share at 5¢ per share.
Short positions outstanding as of July 15, 2026 (with changes from June 30, 2026)
Largest short positions
Company Ticker Short position Change West Red Lake Gold WRLG 18460389 723866 1911 Gold Corp.
54723
-559763
16, 2026
CRITICAL METALS TRENDS
By Blair McBride
Lithium carbonate prices hit a high in late May as disruptions to spodumene concentrate supply, tighter availability of lithium salts and downstream restocking underpinned the market, S&P Global Market Intelligence analyst Pranay Shukla said in an early July note. Prices declined through June and expectations of increased supply and ample inventories in early July limited a brief rebound despite resilient electric-vehicle and energy-storage demand, according to S&P Global Commodity Insights analysts Lucy Tang and Litian Wang.
Western Benchmark cobalt prices rose early in the year before remaining broadly stable through mid-July. The shutdown of Canada’s largest cobalt refinery in June after U.S. sanctions disrupted Cuban feedstock highlights the vulnerability of Western cobalt supply chains. Despite efforts to build refining capacity, the West remains dependent on a small number of politically risky sources of cobalt feedstock, particularly the Democratic Republic of Congo which introduced export quotas last year and plans to revise its mining code. China dominates cobalt refining.
After surging above $101 per lb. in January, uranium spot prices consolidated in the mid-$80s during the second quarter. “This is a healthy consolidation phase,” Global X research analyst Brooke Thackray said in an article published by Investing News Network in late June. Strengthening utility contracting and long-term supply-demand fundamentals remain supportive of uranium prices, while production disruptions at mines in Kazakhstan and northern Saskatchewan will be “positive” for uranium prices, Thackray said.
By Frik Els
In the middle of July last year, Nvidia became the first company to touch $4 trillion, and the
numbers against the combined worth of the world’s 50 most valuable mining companies. The
the Top 50. But with mainstream investors not valuing the production of copper the same way as the
hallucinations about the production of copper, here’s a sobering thought: What Nvidia shed between mid-May – a peak of $5.5 trillion – and early July represented nearly five BHPs, and BHP has never been worth more. That was about the value of the whole Top 50 for most of this decade. As press time neared, Nvidia's market cap sat at $5 trillion.
Aluminum: $1.45/lb.
Cobalt: $25.53/lb.
Gold: $4,134.55/oz.
$5,700
Coal: Central Appalachia, 12,500 Btu, 1.2 S02-R,W: $82/t
Copper: $6.44/lb.
Coal: Powder River Basin, 8,800 Btu, 0.8 S02-R, W: $14.65/t
Copper: CME Group Futures Sept. 2026: $6.49/lb.
Lead: $0.8614/lb. Lithium carbonate: $21,109.95/t Nickel: $7.70/lb.
Rhodium: $8,200/oz.
Tin: $24.44/lb.
miningevents
n August
August 11
Critical Minerals and Energy Transition Australia Conference and Exhibition — Sydney
VENUE: Hilton Sydney
MORE INFORMATION: australiaenergytransition.com
Ruthenium: $1,675/oz.
Uranium (U 3O 8): $85.70/lb.
August 17-20
The 65th Annual Conference of Metallurgy and Materials — Calgary, Alta.
VENUE: Calgary TELUS Convention Centre
MORE INFORMATION: com.metsoc.org
August 25-26
African Critical Minerals Summit 2026 — Johannesburg VENUE: Indaba Hotel
MORE INFORMATION: acmsummit.com
Silver: $59.651/oz.
Zinc: $1.63/lb.
n September
September 2-3
Digitalization & AI in Mining — Toronto
VENUE: The Westin Toronto Airport
MORE INFORMATION: mininginnovationnetwork. swoogo.com/dmna26
September 9-10
Central Canada Resource Expo — Thunder Bay, Ont.
VENUE: Superior Inn Hotel and Conference Centre
MORE INFORMATION: virtex.cencanexpo.ca
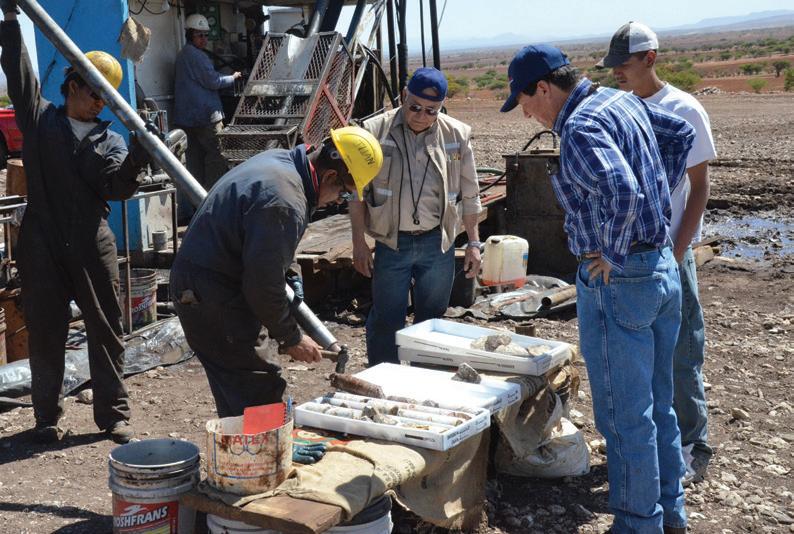
Southern Silver Exploration Corp. is an exploration and development company whose focus is on developing the 100% owned Cerro Las Minitas silverlead-zinc project located Durango, Mexico, in the heart of Mexico’s Faja de Plata. We have assembled a team of highly experienced technical, operational and transactional professionals to support our exploration and current development efforts in de-risking and advancing the Cerro Las Minitas project into a premier, high-grade, silver-lead-zinc mine.
rulesymposium
Weak hands risk missing resource gains: Rule
METALS | Summer dip seen after longer bull market
BY HENRY LAZENBY BOCA RATON, FLA.
Metals and mining stocks could be headed for a summer pullback that might test investors before a longer resource bull market rewards those who buy quality assets, Rick Rule told his investment conference.
The resource financier said investors who can weather shortterm declines in quality junior miners are likely to be rewarded over time as years of underinvestment tighten resource supply.
“We have probably a multi-year, perhaps decade-long bull market in both precious metals and natural resources,” Rule told retail investors, hundreds of whom were attending the symposium for the first time.
“That being said, I expect the next two or three months to be soft.”
Junior mining investors now face the hardest part of a bull market: holding quality names through falling share prices even as the long-term supply picture improves for resource companies.
Market test Rule’s gold case starts with debt. He put U.S. public debt near $40 trillion (C$56.7 trillion) and said the total burden rises to about $60 trillion once future obligations such as Medicare, Medicaid, military pensions and government pen-
sions are included. He argued that the growing debt burden weakens confidence in paper assets and strengthens gold’s role as a store of purchasing power.
“Gold does not need panic to work,” he argued. “It needs investors to question whether cash, bonds and other paper claims will hold value over time.”
That same logic applies to industrial materials, he said. More people want more things, while miners and energy companies have spent too little on new supply for years.
“Short of a global synchronized depression, we’re going to have to ration raw materials by price,” Rule said.
That does not mean prices rise in a straight line. Rule warned investors who chase momentum that prices could be shaken out by a soft market through the summer. That kind of break often creates the best entry point.
“When things go on sale, the shoppers often leave the store,” according to Rule. “I love periods like that.”
Takeover wave
The veteran investor says mergers and takeovers could shape the next two or three years in mining as large producers seek growth they failed to build through exploration.
The biggest miners have stronger balance sheets, deeper trading
and index support. Smaller producers, developers and explorers often hold deposits that could extend mine lives, fill mills or cut costs if folded into existing operations.
“We’ve been underinvested in exploration now for 13 years,” he said.
The gap leaves major producers short of new projects just as shareholders press them to return cash. Rule said that tension makes acquisitions the faster path to growth, especially where a junior’s asset sits
“Gold doesn’t need panic. It needs investors to question paper money.”
same mistakes: too many stocks, too little study, weak patience and a mismatch between a long-term thesis and short-term trading.
“Many investors say they own juniors for a five-year outcome, but can’t hold a stock over a long weekend,” he said. “The sector rewards the opposite habit.”
A key test of his own holdings showed the average 10-bagger took more than five years and forced investors through a 50% shareprice drop along the way.
“Speculation is like a rodeo,” Rule said. “You kind of hang on to the bull.”
Investors who want sector exposure without that amount of work can invest in the delta (pure exposure to the sector’s price movements without taking on individual company risk) by owning royalty companies, streamers or top producers, Rule explained.
near an existing mine, mill or processing plant.
He urged investors to look for companies a buyer would want for hard business reasons. The best targets, he said, improve mine plans, add feed or lower unit costs for a stronger operator.
Investor work
Rule saved his sharpest warning for resource speculators. He said he has reviewed almost 100,000 portfolios over 35 years and keeps seeing the
Lara drills Planalto in Brazil
COPPER | Developer targets 560,000-tonne output
Those who want the upside in developers and explorers must do the work daily—read regulatory filings, study resource reports, call management and build their own view of value.
For Rule, the coming pullback is not a reason to leave the sector. It’s the next exam.
“Money is made mostly on the delta between price and value,” he said. “If you don’t take time to understand value, the price information is of no use.” TNM
BY HENRY LAZENBY
BOCA RATON, FLA.
Lara Exploration (TSXV: LRA; US-OTC: LRAXF) has seven rigs turning at its Planalto copper-gold project in northern Brazil, a 14,000-metre program aimed at expanding resources and improving the economics of a proposed mine.
Planalto could produce 560,000 tonnes copper and 111,000 oz. gold over an 18-year life, according to a November preliminary economic assessment (PEA). The study gives Planalto a post-tax net present value of $378 million (C$537 million) based on initial capital costs of $546 million and a 3.5-year payback. Located in Para state, Planalto is about 1,900 km north of Rio de Janeiro.
“Simple projects move faster. Simple projects get built because they’re not complicated,” CEO Simon Ingram told investors during a lunch presentation at the Rule Symposium. “This project has the opportunity to be built and I think it has even more value because of that.”
Major copper producers need new projects as older operations decline, but developers increasingly have to prove they can deliver stronger economics before attracting a buyer. Lara’s current drill campaign is testing whether higher-grade material and resource upgrades can improve an already
sizable project enough to make Planalto a more attractive acquisition target.
Lara’s Toronto-listed shares have doubled over the past 12 months, trading at C$4.02 as press time neared. That values the company at about C$241 million ($170 million).
Resource work
Planalto holds 47.7 million indicated tonnes grading 0.53% copper and 0.06 gram gold per tonne for 253,000 tonnes copper and 92,000 oz. gold. Inferred resources add 154 million tonnes at 0.36% copper and 0.04 gram gold for 549,000 tonnes copper and 224,000 oz. gold.
Lara’s current drill program aims to move more material in the planned pit into the measured and indicated categories. The company
is also testing a higher-grade core at Cupuzeiro and targets along the Silica Cap trend, where Ingram says higher-grade feed could improve early cash flow.
Lara has said it sees strong chalcopyrite mineralization in new drill core, but the assays feeding into the next resource update must show whether the higher-grade zones are broad and continuous enough to change the mine plan.
Carajás edge
Planalto lies in one of Brazil’s main mining districts, about 30 km from the mining town of Canaã dos Carajás and 45 km from Parauapebas, a regional mining centre. Vale (NYSE: VALE) runs the Sossego copper mine about 32 km away and owns the Cristalino
deposit about 10 km from Lara’s ground. BHP (NYSE, LSE, ASX: BHP) previously owned the Pedra Branca and Antas North copper assets nearby before selling them to privately held conglomerate CoreX Holding.
Existing infrastructure is central to Lara’s development proposal. The PA-160 state highway and high-tension power lines run within 4 km of the proposed mine site. The land is private farmland, not rainforest, and the surrounding towns already supply miners, mechanics, contractors and other workers to Vale, BHP and other operators.
Planalto is to produce about 120,000 tonnes of clean chalcopyrite concentrate a year grading 28% copper. Lara says the concentrate carries no arsenic, an advantage in a district where some copper deposits contain impurities that can draw smelter penalties.
Buyer question
Atalaya Mining Copper (LSE: ATYM) invested in Lara in April when it bought 4.5 million shares for $13.5 million. The Spanish copper producer runs the Riotinto complex in southwest Spain, an open-pit operation with a 15-million-tonne-a-year plant and a grade profile close enough to Planalto to make its investment appear more than a passive bet.
Lara does not present itself as the likely builder. Its manage-
ment team made its name through Reservoir Minerals, which discovered the Čukaru Peki copper-gold deposit in Serbia with FreeportMcMoRan (NYSE: FCX), then sold the company to Nevsun Resources for $512 million in 2016. China’s Zijin Mining Group later bought Nevsun and put Čukaru Peki into production.
Early stage
Lara must complete higher-level engineering, convert resources, file environmental applications and secure licences before any builder can make a construction decision.
Ingram expects permitting to set the pace. It is gathering wet- and dry-season baseline data, including studies on water, wildlife, dust, noise and local health conditions, before filing an environmental impact study. Pará’s state-level process gives Lara a clear path, helped by recent mine approvals in the district, Ingram said.
The next test is whether Lara can close the gap between Planalto’s study value and its own market value without losing the leverage that makes the story compelling, Ingram said. The drill core, permit filing and Atalaya’s next move will show if Planalto becomes a mine a buyer can price, or another junior copper study waiting for capital.
“If you drill, it’s a truth machine,” Ingram said. “You find out what’s really there.” TNM
Channel sampling in volcanic saprolite exposed in the roadbed on the Silica Cap copper trend at Planalto. PLANALTO MINERAÇÃO
Rick Rule speaks at the 2026 Rule Symposium on Natural Resource Investing in Boca Raton, Fla. HENRY LAZENBY
rulesymposium
Gold, critical minerals gain trust
METALS | Investors seek assets governments can’t print
BY HENRY LAZENBY
BOCA RATON, FLA.
Gold is returning as the “apex predator” of a debt-heavy financial system, while critical minerals are becoming the ground governments fight over, investors heard last month at the Rule Symposium.
Central banks around the world have been buying a total of more than 1,000 tonnes annually since 2022, only declining to 863 tonnes last year. Investors have been shifting away from U.S. dollar-denominated assets since the millennium, now at 57% from 70%. All while the West has prioritized critical minerals as never before to erode Chinese dominance.
Grant Williams, author of the Things That Make You Go Hmmm… newsletter, told a conference session that gold is operating like the re-introduction of grey wolves in Yellowstone National Park, echoing a talk he first gave in 2018. Wolves did more than cut deer numbers, he said. They changed how the herd moved, letting trees, birds, beavers and riverbanks recover.
“Every financial ecosystem needs its own apex predator, something that keeps the entire system below it honest and functioning properly,” Williams said. “Gold tells you what your currency is worth, not the other way around.”
Paper check
The analogy casts the resource rally as a fight over discipline and control, not just price. Williams framed gold as the force returning to check paper money. Fellow panelist Nomi Prins, a former Wall Street banker who founded Prinsights Global, showed how countries are now fighting over the habitat around real assets such as mines, processing plants, stockpiles, export rules and trade routes.
Miles Franklin founder and CEO Andy Schectman said China’s gold buying, gold repatriation from Western vaults such as futures exchange COMEX and the growth of alternative payment systems outside the dollar are signs of strain in the paper-based metals trade centred on London and New York.
“This is the market plumbing moving from a Western-based paper settlement system to a non-
Western-based, ‘give me the damn metal now’ system,” Schectman said.
The speakers’ shared argument boils down to this: companies with scarce deposits in trusted jurisdictions stand to gain as investors seek assets governments cannot print and rivals can’t easily block.
After the U.S. cut the dollar’s last formal link to the metal in 1971, governments and central banks leaned harder on debt, lower interest rates and market rescues whenever stress spread, Williams said.
Gold’s appeal, in his telling, comes from what it does not need.
It has no CEO, debt load, power bill, credit risk or business plan. It carries no promise from a borrower and relies little on government.
“It does not require the faith or goodwill of others,” Williams said. “It does not require me to trust anyone at all, except that you must hold it in a very safe place.”
Reserve stress
Central bank buying gives the wolf narrative its market reality. By the end of last year, gold had overtaken U.S. Treasuries as the largest official reserve asset, at 27% of global reserves versus 22% for Treasuries, according to the European Central Bank. The move mainly reflected the jump in bullion prices rather than a rush of new buying.
Williams said Russia’s invasion of Ukraine and the freezing of Russian reserves accelerated the shift. The move showed reserve managers that assets held abroad could become political hostages.
He did not argue governments must choose a new gold standard because they want one. He argued markets can push old anchors back into use when debt, inflation and broken trust narrow policy choices.
“There comes a time when choices get made for you,” Williams said.
Supply habitat
Prins carried the same trust argument from money into mined supply. Commodities have entered a “lockout” stage, she said. Countries no longer fight only over commodity price. They fight over the choke points that turn ore into usable metal: processing, refining, shipping, stockpiles and end users.
“The volume of trade in the paper
Royalty juniors seek higher value
STREAMS | But can face lumpy returns
BY HENRY LAZENBY BOCA RATON, FLA.
Smaller royalty companies say stronger metals prices and growing demand for mine financing are creating opportunities to narrow the valuation gap with their larger peers.
London-based Ecora Royalties (LSE, TSX: ECOR; US-OTC: ECRAF) doubled its first-quarter portfolio contribution to $12.3 million (C$17.5 million), led by base metals, while Empress Royalty (TSXV: EMPR; US-OTC: EMPYF) more than tripled first-quarter revenue to $9.1 million as stronger production and higher metal prices boosted returns.
Executives from both companies made the case for the royalty model at the Rule Symposium in June.
“We don’t own mines, we don’t hire trucks,” Empress CEO Alexandra Woodyer Sherron told investors. “We don’t deal with labour, unit costs or fuel costs. We provide capital, so our operating partners build the mine. If production grows for them, if the mine expands, additional resources are discovered, we participate in that upside without having to spend any additional capital.”
Smaller royalty companies could benefit as miners seek alternative sources for funding expansions, restarts and new projects while investors remain wary of cost overruns. Royalty and streaming firms offer a middle path: they fund mine owners in return for a slice of revenue or discounted metal, giving shareholders leverage to commodity prices and mine growth without direct exposure to operating costs or risk.
“Every financial ecosystem needs its own apex predator.”
GRANT WILLIAMS THINGS THAT MAKE YOU GO HMMM…
markets way outpaces the volume of the ability of physical supply to be extracted, produced, moved, used at their end sites,” Prins said.
Silver shows the split, she said. Trading in the largest silver exchange-traded fund can represent tens of millions of ounces a day, while yearly mine supply sits near 820 million oz. and the market has spent years in deficit.
Copper held up better during recent volatility, she said, because utilities contract supply far ahead and paper trading plays a smaller role than in precious metals.
China has already shown how that leverage works in copper, Prins said. It doesn’t control copper the way it controls rare earths markets, but it can and recently did restrict sulphuric acid, a key chemical used to leach copper ore. That kind of choke point can raise processing costs and push governments or buyers to stockpile metal elsewhere before supply tightens.
Critical fight
Rare earths show what the habitat fight looks like when one country controls the best ground.
China dominates rare earth separation, processing and magnet manufacturing, leaving the U.S. and its allies exposed in defence, electronics, power and vehicle supply chains. That grip has pushed Washington from grants and studies toward direct market support.
The U.S. Department of Defense last year agreed to invest $400 million (C$568 million) in MP Materials (NYSE: MP), operator of the Mountain Pass rare earth mine in California, as part of a wider push to build a domestic magnet supply chain. The deal made the Pentagon MP’s largest shareholder.
Then in June, China added MP Materials and USA Rare Earth (Nasdaq: USAR) to an export control list. For Prins, the move showed how minerals can become pressure points without a shot fired. TNM
The catch is that royalty holders depend on operators they don’t control.
Market gap
Ecora is working to leave coal behind. Kestrel, the Australian steelmaking coal royalty that once drove the business, is winding down as the mine plan shifts to ground where Ecora doesn’t earn royalties. Growth now rests on copper and other critical minerals, with Ecora aiming to be coalfree after 2030.
That shift started to show in the first quarter. Base metals contribution rose 152% to $8.3 million even though some of Vale’s (NYSE: VALE) Voisey’s Bay cobalt shipments slipped into the second quarter. Ecora says base metals made up half of portfolio contribution last year and could reach about 85% by 2030.
The company’s question is whether investors will pay for future copper growth before the cash arrives. Ecora says its attributable copper exposure could rise from less than 5 million lb. a year to almost 20 million lb. over the next decade as several development-stage royalties move toward production.
“We don’t own mines, we don’t hire trucks. We don’t deal with labour, unit costs or fuel costs. We provide capital, so our operating partners build the mine. If production grows for them, if the mine expands, we participate in that upside without having to spend any additional capital.”
ALEXANDRA WOODYER SHERRON, EMPRESS ROYALTY, CEO
Precious bet
Empress offers the simpler precious metals version of the trade. It owns four producing royalties and streams tied to gold and silver mines in Mexico, Peru, South Africa and Mozambique.
The Vancouver-based company expects revenue to climb to about $30 million this year from $17 million last year and says it has sufficient liquidity to pursue additional royalty acquisitions.
The Tahuehueto mine in Mexico carries the most weight. Empress put $5 million into the silver stream while Luca Mining (TSXV: LUCA; US-OTC: LUCMF) completed construction and says it has received $22 million to date from the investment since commercial production began last year.
That concentration cuts both ways, since a small royalty company can move quickly when one or two mines perform, but misses and delays also show up quickly. Empress’s first-quarter revenue from Golconda Gold’s (TSXV: GG; US-OTC: GGGOF) Galaxy mine included a 200-oz. catch-up delivery from a prior-year shortfall, a reminder that royalty revenue can be lumpy even when metal prices help.
Risk-reward model
Royalty companies don’t run mine plans, budgets, labour, permits, shipping or exploration. They often rely on public disclosure and operator forecasts for the assets that pay them.
Ecora felt that in the first quarter when shipping timelines pushed some Voisey’s Bay cobalt into the second quarter and Kestrel produced no royalty revenue because mining fell on land outside Ecora’s private royalty area. Neither setback reflected on Ecora’s own operations, but both affected its results.
Yet royalty companies can give investors exposure to mine growth without diesel bills, wage pressure or sustaining capital. They can also help executives fight dilution by giving miners capital without issuing shares or taking on more debt. TNM
A grey wolf moves through snow in Yellowstone National Park. U.S. NATIONAL PARK SERVICE/JIM PEACO
SPOTLIGHT: Around the world
BY NORTHERN MINER STAFF
Junior exploration companies across the globe stand or fall on drill programs that could turn them into bigger stories. Here are eight juniors with company-making discovery potential in proven mineral districts.
n Abitibi Metals
Abitibi Metals (CSE: AMQ; US-OTC: AMQFF) is advancing its B26 polymetallic project in northwestern Quebec, which it fully secured in June under an agreement to acquire the remaining 20% from SOQUEM, a mineral exploration company and subsidiary of Investissement Quebec.
SOQUEM will retain a 1% net smelter return (NSR) royalty. In addition, Abitibi Metals will have the right of first refusal on the agency’s Wagosic and Carheil projects, which are located within or close to B26.
The project is about 620 km north of Montreal and just 7 km southeast of the past-producing Selbaie mine.
Abitibi is fully funded for a 40,000-metre drill program this year at B26. The deposit remains open laterally and at depth and in May the junior returned one of its strongest intercepts yet. Hole 127425-378W1 cut 46.7 metres grading 1.33% copper, 0.13 gram gold per tonne and 3.39 grams silver from 946 metres depth, including 14 metres at 3.63% copper, 0.37 gram gold and 7.67 grams silver. The intercept sits within the main B26 horizon.
Another hole, 1274-25-378, returned 46.9 metres grading 0.43% copper, 0.1 gram gold and 1.69 grams silver from 877.35 metres, including 8.3 metres at 1.62% copper, 0.23 gram gold and 3.39 grams silver.
An updated resource in February outlined 12.96 million indicated tonnes grading 1.19% copper, 1.16% zinc, 0.44 gram gold and 30.8 grams silver, for 340 million lb. of contained copper, 332 million lb. zinc, 184,000 oz. gold and 12.8 million oz. silver.
Inferred resources total 12.34 million tonnes at 1.6% copper, 0.16% zinc, 0.68 gram gold and 8.14 grams silver, for 435 million lb. of contained copper, 43 million lb. zinc, 268,000 oz. gold and 3.2 million oz. silver.
Abitibi Metals has a market cap of about $153 million (US$108 million).
n Brunswick Exploration
Brunswick Exploration (TSXV: BRW) is focused on lithium exploration in Quebec’s Eeyou IstcheeJames Bay region and kicked off a 4,000-metre drill program at its main Mirage project in July. Mirage, about 40 km south of the Trans-Taiga Highway, is one of the largest undeveloped hard-rock lithium projects in the Americas.
The project hosts an inferred
resource of 52.2 million tonnes grading 1.08% lithium oxide (Li20) and 131 parts per million tantalum oxide (Ta205) for 585,000 tonnes of Li20, according to an initial resource released in January. More than 70% of the resource is contained within five dykes found above a vertical depth of 150 metres from surface, all of which remain open in all directions.
The company discovered highgrade spodumene pegmatite dykes outcropping on the property in 2023 and has delineated nine main dykes so far. The spodumene-bearing boulder train at Mirage measures about 6.5 km in length and 1.4 km in width.
Summer drilling at Mirage will initially target the MR-1 and MR-4 dykes. The MR-1 dyke remains open in all directions and previous highlight results include 25.8 metres grading 2.57% Li20 in hole MR-23-02.
Highlights from earlier drill programs include 93.45 metres grading 1.55% Li20 in drillhole MR-24-62; 69.3 metres at 1.64% Li20 in drillhole MR-24-61; and 28.3 metres of 1.17% Li20 in MR-24-50. All the intercepts are from the MR-6 dyke and started from surface.
The company has focused its drilling within Mirage’s conceptual pit shell, leaving areas outside the resource untested, including an outcropping spodumene pegmatite 3.5 km to the northeast.
Brunswick also plans to drill about 2,000 metres at its Anatacau Main project, about 22 km east of Rio Tinto’s (LSE, NYSE, ASX: RIO) Galaxy project.
Highlights from previous drilling include 90.5 metres grading 1.31% Li20 from 202 metres depth in drill hole AN-26-07 and 120.7 metres grading 1.31% Li20 from 30 metres in AN-25-05.
In April the company completed its option agreement for the Anatacau Main and nearby Anatacau West projects. It now owns a 90% stake in both. The remaining 10% free-carried interest is held by Electric Elements Mining, a company controlled by Osisko Develop-
ment (NYSE: ODV, TSXV: ODV), with Agnico Eagle Mines (TSX, NYSE: AEM) holding a stake.
In Greenland, Brunswick is exploring its early-stage Nuuk lithium project, about 90 km northeast of the namesake capital. Helicopter-supported prospecting and mapping started in July.
Brunswick Exploration has a market cap of about $44 million.
n Carnaby Resources Carnaby Resources (ASXL: CNB) is focused on its Greater Duchess copper-gold project in the Australian state of Queensland, about 1,500 km northwest of Brisbane.
The 1,946-sq.-km project contains six deposits including Mount Hope, Nil Desperandum, Lady Fanny and Trekelano, as well as copper-rich iron oxide copper gold targets over a 100-km corridor.
A prefeasibility study (PFS) completed in March envisioned mining six open pits over the first six years and transitioning to underground mining at the Mount Hope Central and Nil Desperandum deposits in year three for another nine years. Over a 12-year-mine life Greater Duchess would churn out 147,000 tonnes of copper and 70,000 oz. gold.
The study outlined a post-tax net present value (at a 7% discount rate) of A$322 million (C$316.5 million) and an after-tax internal rate of return (IRR) of 281%. Pre-production capital costs of A$11 million could be repaid in 13 months.
Greater Duchess contains 17 million indicated tonnes grading 1.5% copper and 0.3 gram gold for 550 million lb. of contained copper and 145,700 oz. gold. Inferred resources add 12.2 million tonnes grading 1.1% copper and 0.2 gram gold for 288 million lb. copper and 84,500 oz. gold.
All the deposits remain open at depth. The Greater Duchess project also hosts the historic Duchess mine, which produced about 205,000 tonnes grading 12.5% copper between 1900 and 1940.
The company launched a 3,000metre reverse circulation drill pro-
gram in April targeting priority targets at Trekelano, where recent results from Trek 2 include 18 metres grading 4% copper and 1.1 grams gold from 115 metres in hole TW-12.
The company has a toll milling and offtake agreement with Glencore International (LSE: GLEN) for all of the project’s fresh sulphide ore and concentrate.
Carnaby Resources has a market cap of about A$153 million.
n Dakota Gold
Dakota Gold (NYSE-A: DC) plans to complete a PFS before the end of the year on its Richmond Hill gold project, about 320 km west of South Dakota’s capital, Pierre.
The project hosts a large oxide gold system amenable to conventional open-pit mining and heap leach processing and is part of a 180-sq.-km land package controlled by the company near the historic Homestake mine. (Homestake pro-
Building the Next Gold Mine in the Homestake District, South Dakota
ADVANCING STUDIES
Pre-Feasibility Study (Q4 2026) and Feasibility Study (H1 2027)
TARGETING PRODUCTION IN 2029
STRONG CASH BALANCE
$107 Million (as at March 31, 2026)
Medallion’s Harbour View open pit at the Ravensthorpe project in Western Australia. MEDALLION METALS
Snapshot
duced about 40 million oz. gold over more than 145 years.)
According to an S-K 2300 Initial Assessment report last year, Richmond Hill is one of the largest development stage oxide gold resources in the United States. The report gave the project an after-tax net present value (NPV) of $1.6 billion (C$2.4 billion) and an aftertax IRR of 55% at initial costs of $384 million, based on a gold price assumption of $2,350 per ounce.
Richmond Hill could produce 2.6 million oz. over a potential mine life of 28 years. Those estimates are based on 244.7 million measured and indicated tonnes grading 0.46 gram gold and 4.83 grams silver for 3.6 million oz. of contained gold and 38 million oz. silver, according to an initial resource from February 2025. Dakota is targeting production in 2029.
Drilling has recently identified additional pockets of higher-grade mineralization within the mine’s planned open-pit development area. In July the company reported that expansion hole RH26C-432 cut 26 metres grading 11.36 grams gold and 14.92 grams silver from about 75 metres depth. Hole RH26C-437 returned 38 metres of 2.89 grams gold and 8.18 grams silver from about 145 metres downhole.
Other highlights include hole RH26C-452, which returned 16 metres of 1.63 grams gold and 12.03 grams silver from 79 metres depth. The drill program, which finished in July, comprised 17,273 metres across 112 holes.
Data from more than 350 holes completed this year and last will be incorporated into the upcoming PFS.
Dakota Gold has a market cap of about $604 million.
n Emerita Resources
Emerita Resources (TSXV: EMO; US-OTC: EMOTF) expects to complete a prefeasibility study on its flagship Iberian Belt West project in southern Spain in the third quarter of the year.
The IBW project, which consists of three polymetallic deposits— Infanta, El Cura and Romanera— lies in the prolific Iberian Pyrite Belt, a historic mining district known for its volcanogenic massive sulphide deposits. The cornerstone asset lies in the western part of the belt, adjacent to the border with Portugal, about 435 km southwest of Madrid and 50 km from the port of Huelva.
IBW hosts 18.9 million indicated tonnes grading 2.8% zinc, 1.42% lead, 0.5% copper, 1.28 grams gold and 66 grams silver for 547,000 tonnes of contained zinc, 269,000 tonnes lead, 94,000 tonnes of copper, 783,000 oz. gold and 40.2 million oz. silver, according to this year’s update.
Inferred resources total 6.8 million tonnes at 3.25% zinc, 1.5% lead, 0.73% copper, 0.77 gram gold and 56.3 grams silver for 221,000 tonnes zinc, 102,000 tonnes lead, 49,000 tonnes copper, 168,000 oz. gold and 12.3 million oz. silver.
Emerita’s Spain portfolio includes the Aznalcollar project, a past-producing open pit mine that it is seeking to redevelop following a long-running legal dispute over ownership, and the Nuevo Tintillo project. Both assets are about 40 km north of Seville.
In May, Denarius Metals (CBOE: DMET; US-OTC: DNRSF) abandoned efforts to acquire Emerita after the junior refused to hold talks
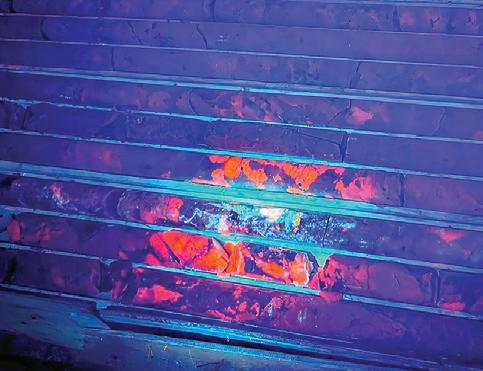
over the proposed all-share deal. Denarius holds the Aguablanca, Lomera and Toral assets near the IBW project as well as producing assets in Colombia and had argued a combination would have been a good strategic fit.
Emerita Resources has a market cap of $90.5 million.
n Headwater Gold Headwater Gold (CSE: HWG; US-OTC: HWAUF) is exploring for gold in the western U.S. and has
six projects in Nevada and Idaho partnered with gold majors Newmont (TSX: NGT; NYSE, ASX: NEM), OceanaGold (TSX, NYSE: OGC) and Centerra Gold (TSX: CG; NYSE: CGAU).
The company’s main asset is
Spring Peak, a high-grade epithermal gold discovery in western Nevada’s Walker Lane trend, about 275 km southeast of Reno.
Newmont is funding exploration as part of an earn-in agreement signed in August 2022. Newmont can acquire up to 75% of the project by spending $55 million in exploration and completing a PFS. It owns 51% and has elected to continue to earn into the project.
The property sits next to Hecla Mining’s (NYSE: HL) past-producing Aurora mine, where existing infrastructure includes a 600ton (544-tonne)-per-day mill, several production water wells and high-voltage three-phase power.
Last October, Headwater’s exploration permit on Spring Peak was selected as part of the FAST41 program, a U.S. federal initiative designed to streamline approvals for vital infrastructure related to mining projects.
Highlight drill results from the Disco zone at Silver Peak include 34.72 metres grading 2.73 grams gold starting from 256 metres, including 2.01 metres of 10.43 grams gold and 2.38 metres of 15.92 grams in drillhole SP22-13. Newmont is also earning up to 75% of Headwater’s Lodestar project, about 10 km north of Spring Peak.
In northern Nevada, Headwa-
> Snapshot from P27
Dakota Gold’s Richmond Hill project in the western portion of South Dakota. DAKOTA GOLD
A rock outcrop with spodumene pegmatites in Quebec’s Eeyou Istchee region. BRUNSWICK EXPLORATION
Lithium-containing cores under ultraviolet light at Brunswick’s Mirage project in Quebec. BRUNSWICK EXPLORATION
The Bullabulling gold project in Western Australia. MINERALS260
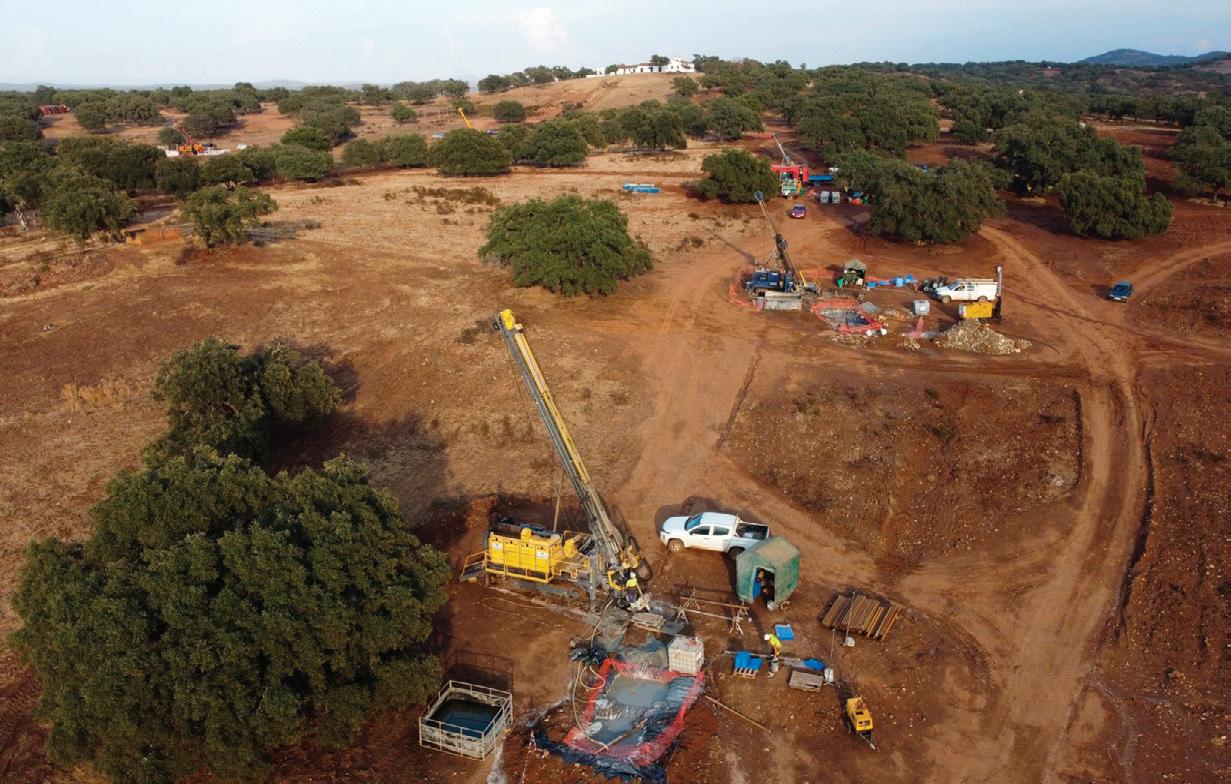
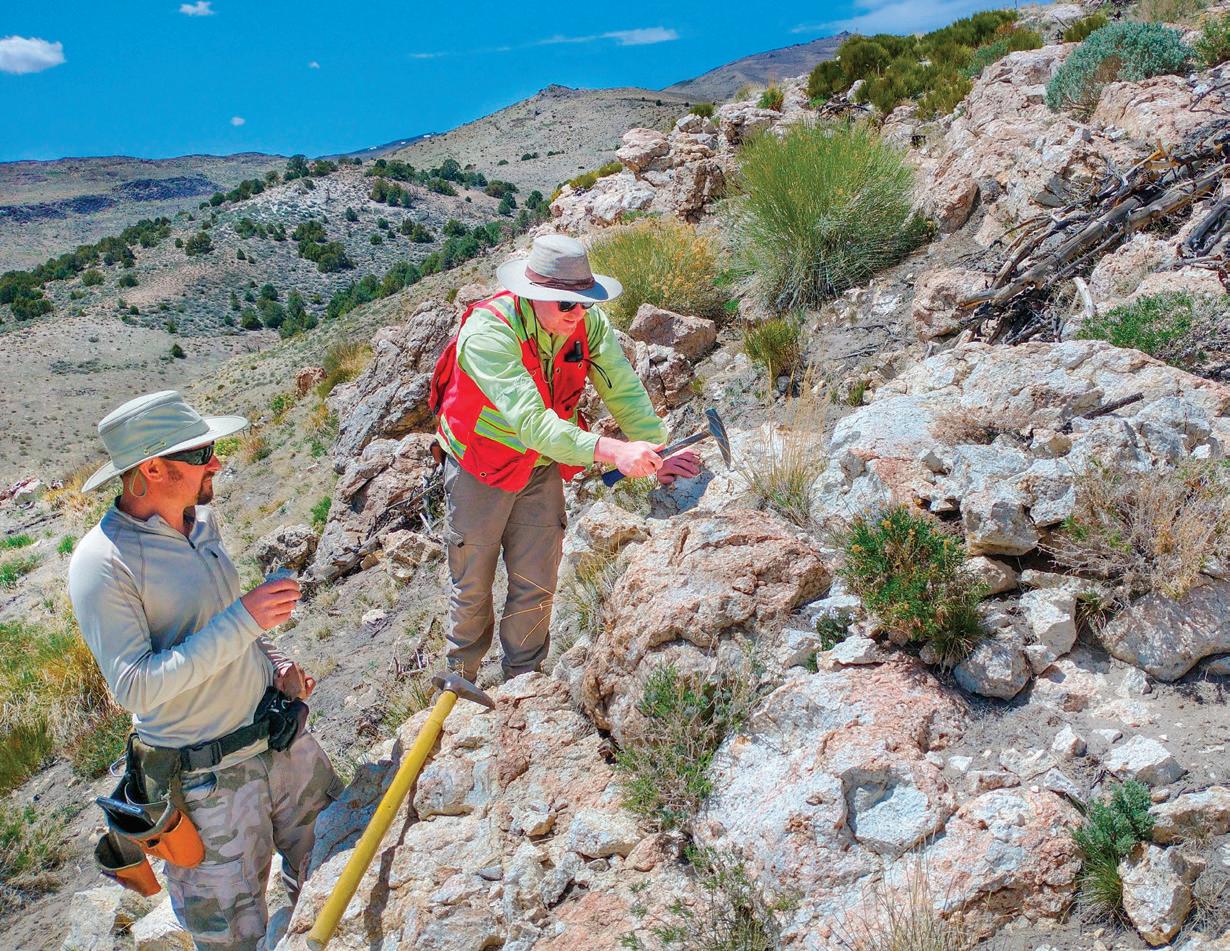
ter has earn-in agreements with OceanaGold at its TJ, Jake Creek and Hot Creek projects. The TJ project is less than 10 km east of Nevada Gold Mines’ Turquoise Ridge complex, a joint-venture between Barrick Mining (TSX: ABX; NYSE: B) and Newmont.
Jake Creek lies 65 km northwest of Winnemucca and Hot Creek sits about 17 km northwest of First Majestic Silver’s (TSX, NYSE: AG) Jerrit Canyon mine.
In April, Headwater reported the highest gold grades yet at TJ. Drillhole TJ25-01 cut 19 metres grading 0.48 gram gold starting from 112 metres downhole, and TJ2504 returned 10 metres of 0.93 gram gold from 141 metres.
In western Idaho, Centerra is earning 70% in Headwater’s Crane Creek project, where historic intercepts include 62.5 metres grading 1.21 grams gold. The project is about 90 km northwest of the capital of Boise.
Newmont acquired a 7.1% equity stake in Headwater in August 2022 and Centerra a 9.9% stake in September 2024.
Headwater Gold has a market cap of about $38 million.
n Medallion Metals
Medallion Metals (ASX: MM8) plans to start underground development work in August at its Ravensthorpe copper-gold project in Western Australia, about 550 km
southeast of Perth.
A feasibility study in December envisioned the underground site producing a total of 374,000 oz. gold and 15,000 tonnes copper over an initial life of 5.7 years generating post-tax cashflow of A$624 million.
Ravensthorpe’s after-tax NPV (at an 8% discount rate) was pegged at A$443 million, with an IRR of 87%, based on a gold price of A$5,200 ($3,380) per ounce. Pre-production capital of A$138 million could be repaid in one year. Processing will take place at its Forrestania operations, about 160 km south of Ravensthorpe. Medallion completed the acquisition of Forrestania from IGO (ASX: IGO) in March. The property includes
RC26KP1263.
The drilling is also probing potential extensions to a new lode discovered last year within the footwall of the primary Gem lode, which sits outside the current resource. DD24KP1232 returned 7.7 metres grading 5.9 grams gold, 3.4% copper and 22.2 grams silver from 350.5 metres downhole, including 3.7 metres of 11.3 grams gold, 4.8% copper and 33.3 grams silver.
The project hosts 3.15 million indicated tonnes grading 4.8 grams gold and 0.7% copper for 23,000 tonnes contained copper and 490,000 oz. gold. Inferred resources add 2.56 million tonnes grading 4.3. grams gold and 0.5% copper for 13,000 tonnes copper and 360,000 oz. gold.
At its Forrestania gold project, Medallion is validating historical drill results from the Lounge Lizard deposit. Significant intersections beneath the old pit and surrounding areas include 11 metres grading 6.94 grams gold from 50 metres and 9 metres of 8.69 grams gold from 67 metres.
Medallion Metals has a market cap of about A$351 million.
n Minerals 260
Minerals 260 (ASX: MI6) is advancing its Bullabulling project in Western Australia, one of the country’s largest undeveloped gold projects not owned by an existing producer.
The project, which Minerals 260 acquired in April 2025, contains five gold deposits on a 1,160-sq.-km land package in the heart of the Eastern Goldfields, about 65 km southwest of Kalgoorlie.
The company is targeting first production in late 2028 and early construction activities are already underway.
A PFS released in July envisioned an open-pit mine producing 150,000 oz. gold per year over 19 years at an all-in sustaining cost of A$2,500 per oz. generating A$330 million in average annual free cash flow at a base case gold price of $3,800 per ounce.
The study forecast an after-tax NPV (at a 5% discount rate) of A$2.3 billion, an IRR of 43% and a two-year payback of pre-production capital of A$115 million.
The PFS was based on probable reserves of 90 million tonnes grading 0.86 gram gold for 2.5 million contained oz. of gold.
The operation would start with a 5-million-tonne per year conventional carbon in leach (CIL) plant, but could be expanded later to 7.5 million tonnes per year.
the Cosmic Bay concentrator and related infrastructure as well as the historic Teddy Bear and Lounge Lizard gold deposits.
Medallion has all primary environmental approvals in place to advance final development planning and a $50-million funding and offtake agreement with Trafigura for Ravensthorpe’s copper concentrate and gold doré.
Significant drill results from an 18,000-metre infill and extension drill program launched in January include 13.5 metres grading 3.3 grams gold and 5.1% copper from 380 metres downhole in drillhole DD26KP1243 and 12 metres of 9.9 grams gold, 1.8% copper and 10.3 grams silver from 58 metres in
Minerals 260 recently updated the resource estimate based on about 78,000 metres of drilling since acquisition, growing the resource from 2.3 million oz. gold to 6.2 million oz. gold. The resource estimate will support an updated ore reserve that is to be completed in conjunction with the definitive feasibility study.
Currently, Bullabulling contains 140 million indicated tonnes grading 0.98 gram gold for 4.4 million contained oz. gold and another 51 million inferred tonnes averaging 1 gram gold for 1.7 million ounces.
Recent drill results include 20 metres grading 3.4 grams gold from 93 metres in drillhole BBRC0668 at the Phoenix deposit; 15 metres of 2.3 grams gold from 204 metres in BBRC0700 in the Bachus deposit; and 18 metres of 2.9 grams gold from 332 metres in the Dicksons deposit.
Minerals 260 has a market cap of about A$1.7 billion. TNM
Drill rigs at Emerita’s Iberian Belt West polymetallic project in southern Spain. EMERITA RESOURCES
Headwater’s main Spring Peak epithermal gold project in western Nevada. HEADWATER GOLD
>
ent risk than established industrial loads.
“Any significant increase in firm load requests, AI or otherwise, impacts the availability of firm power for future requests until new supply is added to the system,” the operator said.
B.C. has made the trade-off explicit. AI and data-centre proposals must compete for as much as 400 MW over two years, while mining, forestry, manufacturing and liquefied natural gas projects remain outside the cap.
BC Hydro judges technology projects by their economic, community, First Nations and environmental benefits, the price users are willing to pay for power and their ability to cut demand when the grid is tight. The utility told The Miner the system is meant to protect capacity for mines and other established industries. It knows of no mining project delayed by a data-centre application.
Tech giant Meta has assembled dedicated and grid-linked supply for its Alberta project. Capital Power (TSX: CPX) agreed to provide 250 MW for more than 10 years starting in the second half of 2028. Pembina Pipeline (TSX: PPL; NYSE: PBA) and Kineticor are building a 932-MW gas plant dedicated to data-centre customers, reducing the project’s call on the public grid.
Clearwater shows the importance of power even when a data centre has not displaced a mine project. Electric pumps would drive E3’s planned operation and electricity would account for about a third of operating costs, Doornbos said.
E3 completed its power engineering early in anticipation of equipment and connection work taking between three to five years. Suppliers now indicate the company could secure what it needs within a couple of years. Power remains an execution risk, but Doornbos said data-centre growth has not yet
materially constrained the project.
The developer is expanding its demonstration plant and completing a feasibility study with as much as $36.5 million in federal support. It aims to have Clearwater ready for construction by mid-next year.
Competing projects
Rivalry for the same resources is to intensify as more industries switch to electricity, Vale’s McCleave said.
“As the electrification trend accelerates, the level of competition is increasing. This could spur higher costs, slow production and delay projects,” McCleave said. “Electricity has become a strategic resource, just like the critical minerals we mine.”
The conflict may strike metal processing before many mines. U.S. aluminium smelters already struggle with high power costs, while large data-centre operators can pay substantially more for firm supply, S&P Global said.
High electricity costs helped drive the decline of U.S. smelting from the 1980s and attempts
to rebuild the sector may falter if data centres keep bidding up power, S&P said. Higher grid rates could also weaken mine economics, while competition for electricians, engineers and other skilled workers could raise construction and maintenance costs.
Social credit
Around E3’s Clearwater, community support has become the more immediate conflict. Doornbos said some data-centre proponents entered the Olds area without first listening to residents or adapting their plans. He declined to name them.
E3 spent about a year and a half meeting landowners, community groups and local governments before filing permit applications. That work may not shield it when residents view data centres, mines and other large projects as one wave of industrial development.
“Anytime somebody does something like this, it paints a bad brush over all developments,” Doornbos said. “People look at industry and
could supply as much as 15% of global rare earth production, potentially providing Europe with a significant non-Chinese source of critical minerals as Western governments seek to diversify supply chains.
Greenland’s government has consistently maintained the project lacks community support. Foreign Minister Múte Egede has said residents do not want the mine near Narsaq, reflecting longstanding concerns about uranium and environmental impacts.
But Mamadou disputes that characterization, pointing to support from some local labour leaders and opposition politicians while acknowledging that the company lost ground in its public engagement during the COVID-19 pandemic as criticism of the project intensified.
While the Greenland dispute continues through the courts, ETM has broadened its strategy by acquiring the Penouta brownfield project in Spain, which it aims to restart as Europe’s only producing tantalum mine. The company has also assembled an advisory board including former foreign ministers from Denmark and Australia as it continues pursuing Kvanefjeld, which Mamadou still views as ETM’s defining asset.
“Our case comes down to one simple question,” Mamadou said. “Are you expropriating us? Yes or no?” TNM
don’t necessarily tell the difference between you or somebody else.”
Build bubble
Data centres can bring a rush of construction work but employ relatively few people once operating, Kaiser Research Online founder John Kaiser said in an interview. Noise, power demand, water fears and concern over AI-driven job losses can harden local opposition.
“There is a growing anxiety, which is easy to translate into opposition to a local data centre being built,” Kaiser said. “Once these things are built, they also run on minimal human workers.”
Kaiser warned cheaper opensource models may leave some costly data centres as “white elephants.”
At least 20 U.S. data-centre projects worth US$42 billion and requiring 3.5 gigawatts were cancelled in the first quarter after local pushback, The Economist reported in June. The disputes centred on power, transmission lines, noise, water and the limited number of lasting jobs.
Respectful
The conflict will not reach every mining district. Data centres tend to cluster near cities, power lines and gas pipelines, while many explorers work in remote mountain and desert regions, Kaiser said. Slow permits and shortages of rigs, crews and equipment remain more immediate threats for many juniors.
Alberta may have enough gas, land and engineering skill to host both industries. Whether it can add power and preserve public trust fast enough will decide whether AI helps build the mines it needs or makes them harder to develop.
“We all have to approach stakeholder engagement respectfully,” Doornbos said. “If somebody doesn’t, it impacts everybody.” TNM
—With files by Colin McClelland.
The Origins of Agnico Eagle Mines
As The Northern Miner focuses this month on Top 10 mining companies, we trace the history of what is now Canada’s foremost miner by market capitalization: Agnico Eagle Mines.
In the 1950s, a handful of companies were mining cobalt and trying to squeeze out what remained of the silver deposits in Cobalt, Ont., decades after its 460-million-oz. silver rush had ended. In January 1953, five struggling companies joined to form Cobalt Consolidated Mining.
The Northern Miner reported that the company had produced 117,661 oz. silver and 7,774 lb. cobalt in August of 1957. While a respectable haul, it perhaps wasn’t enough for long-term success in the Cobalt camp.
That same year, the company reorganized itself to try and draw more financing. It was renamed Agnico Mines, representing the abbreviated chemical symbols for silver (Ag), nickel, (Ni), and cobalt (Co).
A turning point came in 1963 when Paul Penna became company president. He steered Agnico in a more growth-oriented direction, leading it through its Cobalt Lake reclamation work in the mid 1960s, recovering silver from tailings worth millions of dollars in today’s money.
That showed its ability to generate cash and set the stage for its June 1972 merger with Eagle Gold Mines, giving the company the Joutel site in Quebec and marking its entry into gold.
In February 1986, Agnico Eagle gained a 30% interest in the Dumagami property in Quebec, which became its premier LaRonde mine that has produced more than 8 million oz. of gold.
In December 1993, Agnico’s acquisition of Goldex and its namesake deposit in Val-d’Or was a major step in its development as a gold producer. Goldex went into production in 2008, and still produces today as the Goldex complex.