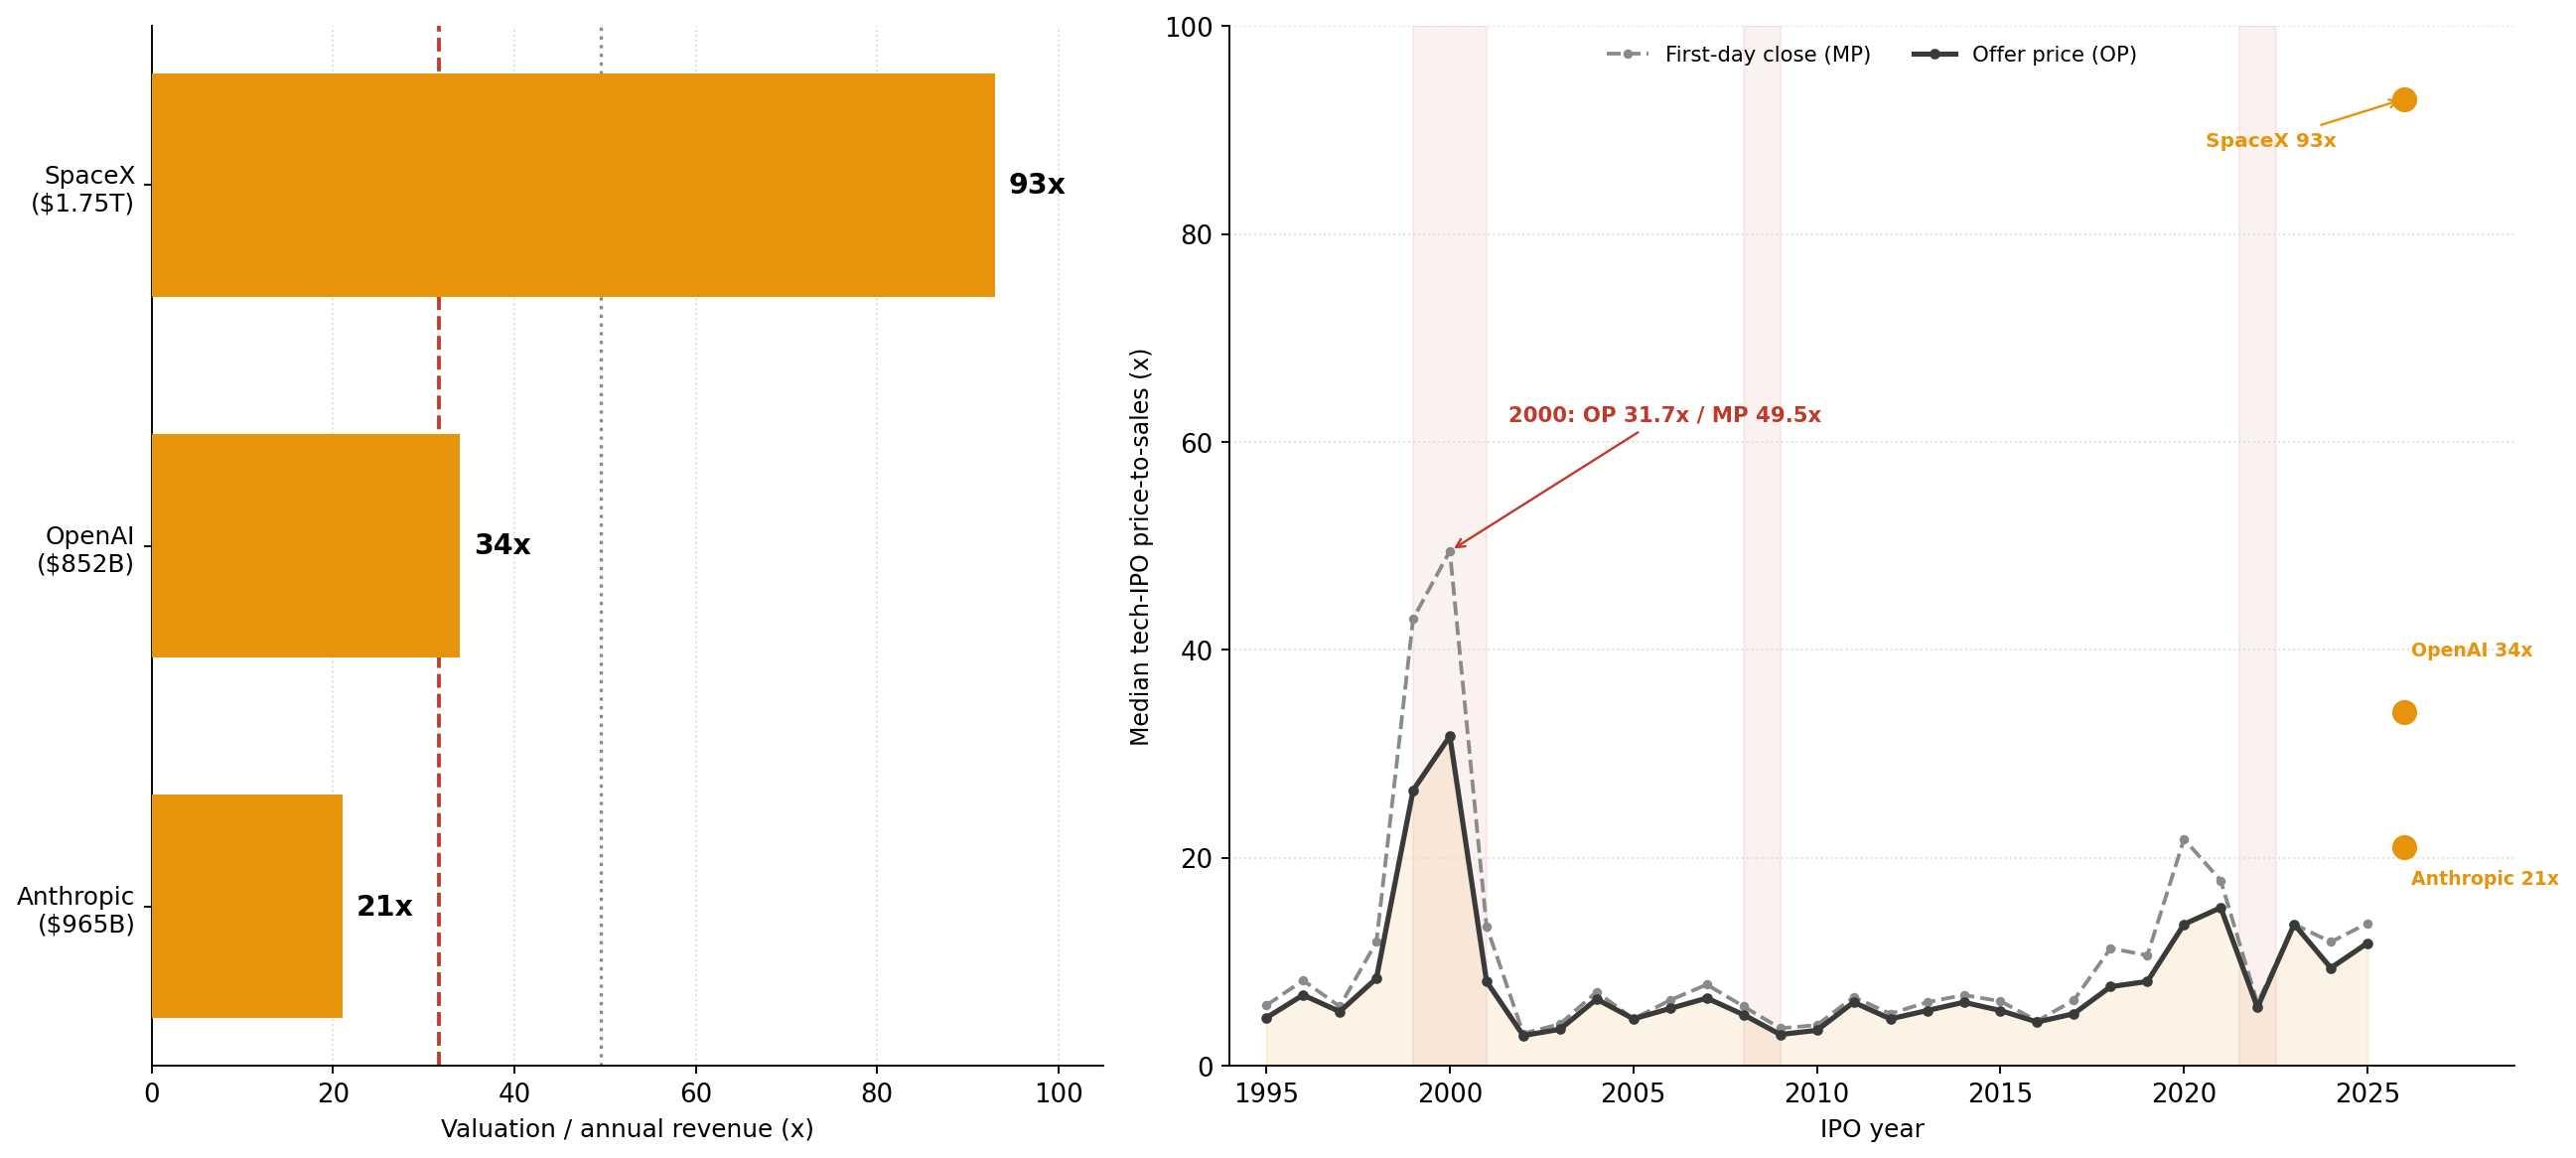
Главными направлениями стали Южная Корея, Тайвань и Япония — рынки, где спрос на ИИ
уже подтверждается ростом заказов, загрузкой
мощностей и прибылью компаний.
Локомотивом стала Южная Корея: на фоне
дефицита памяти операционная прибыль
Samsung и SK Hynix кратно выросла год к году, а их рыночная капитализация превысила
отметку в триллион долларов.
модели, данные и будущую
монетизацию: американская корзина
полупроводников торгуется в районе 35-40x
прогнозной прибыли, а отдельные ИИ-
платформы — кратно дороже. В Азии рынок
покупает более материальную часть цикла —
производство чипов, память, оборудование, тестирование, передовую упаковку и
инфраструктуру центров обработки данных.
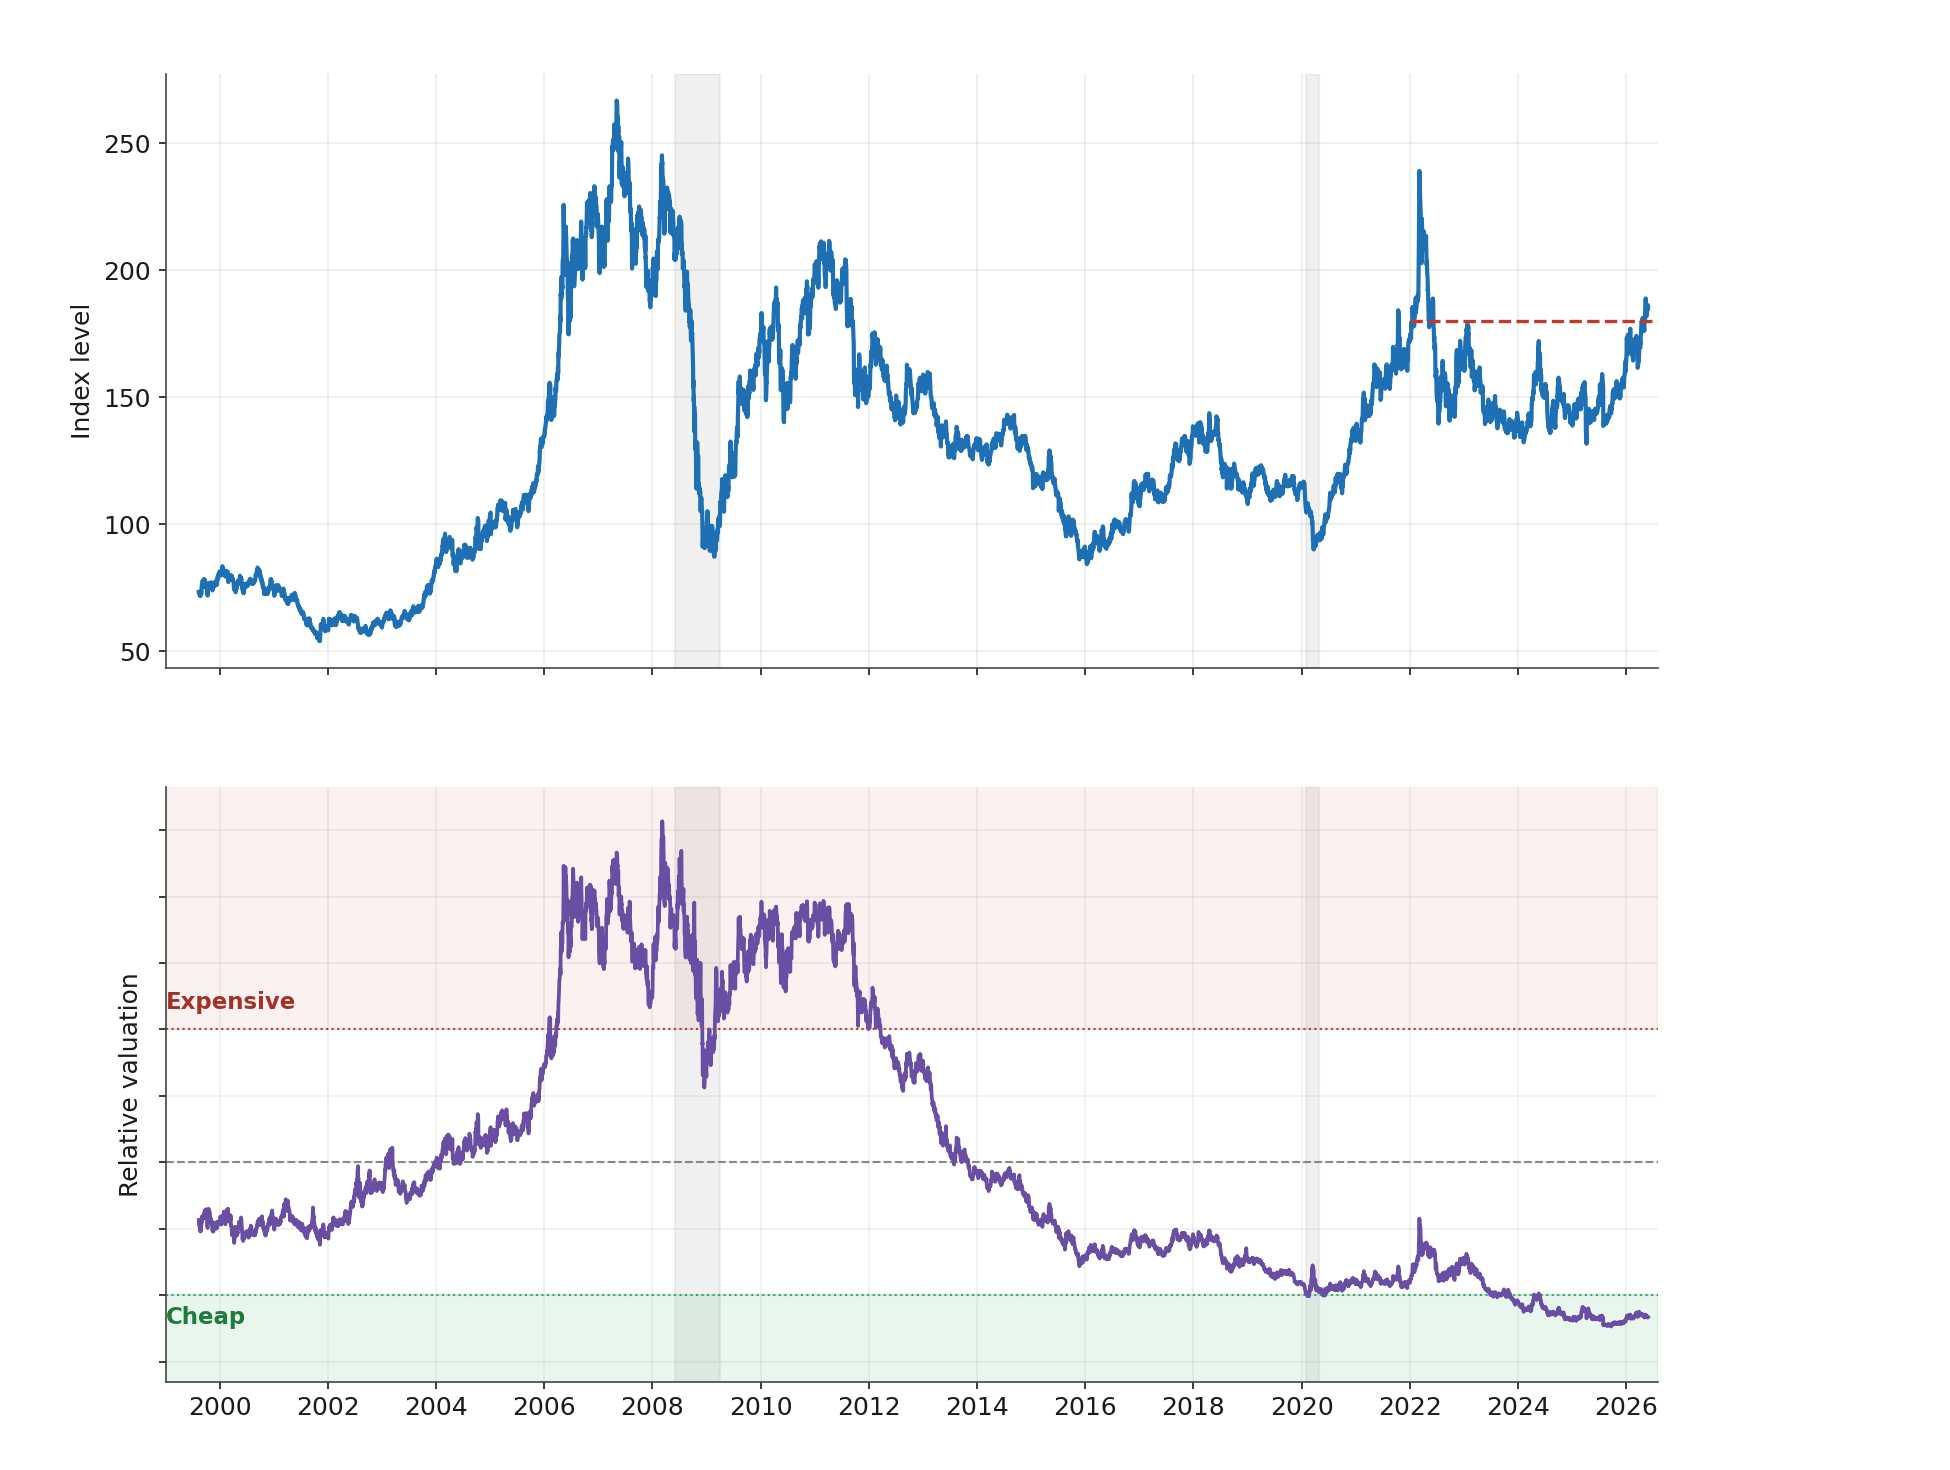
Особенно дёшево стоит память: прогнозный
P/E Samsung и SK Hynix опустился до
однозначных значений — порядка 7–9x, поскольку прибыль растёт быстрее, чем котировки.
Развивающиеся рынки (EEM US Equity, iShares MSCI Emerging Markets ETF)
полупроводниковый сектор занимает около 16,2% индекса.
Развивающиеся
Source:
Экономика
Реальные располагаемые доходы в апреле
упали на 0.5% м/м (1.1% г/г). Норма
сбережений опустилась до 2.6% — минимума с
июня 2022 года, против 5.8% год назад.
Потребление всё больше поддерживается не
ростом реальных доходов, а сокращением
сбережений.
Слабость потребительской базы частично
компенсируется инвестициями в AI. В Q1 2026
бизнес-инвестиции впервые в истории
обогнали потребление по вкладу в рост ВВП.
По оценкам, AI-капекс (дата-центры, чипы, ПО)
обеспечил около половины — а по более
широким расчётам до трёх четвертей —
квартального роста экономики; без него рост
был бы близок к нулю. Капекс вне AI — нежилое строительство, обрабатывающая
промышленность — при этом стагнирует.
Индекс расходов на личное потребление PCE — ключевой инфляционный индикатор ФРС
апреле ускорился до
Source:
Source: Bloomberg, Astero Falcon analytics.
Макрофон в мае стал менее благоприятным
для акций, но не остановил рост индексов.
Ралли S&P 500 стало самым узким за 35 лет. За
месяц S&P 500 вырос на 5,2%, тогда как
равновзвешенный индекс — лишь на +2,6%. На
уровне индекса майский прирост поддержали
прежде всего тяжеловесы из Великолепной 7.
Но внутри Mag 7 динамика оставалась
неоднородной – лидерами стали Apple (+15,0%)
и Tesla (+14,2%), а чистые ИИ-имена Microsoft, Nvidia, Amazon и Alphabet показали более
скромную динамику.
Настоящими фаворитами внутри технологического сектора стали более
прикладные бенефициары инфраструктурного ИИ цикла. Dell, Super Micro, Datadog и AMD
получили поддержку благодаря улучшению
прогнозов и спросу на серверы, вычислительные мощности, оборудование и
инфраструктуру центров обработки
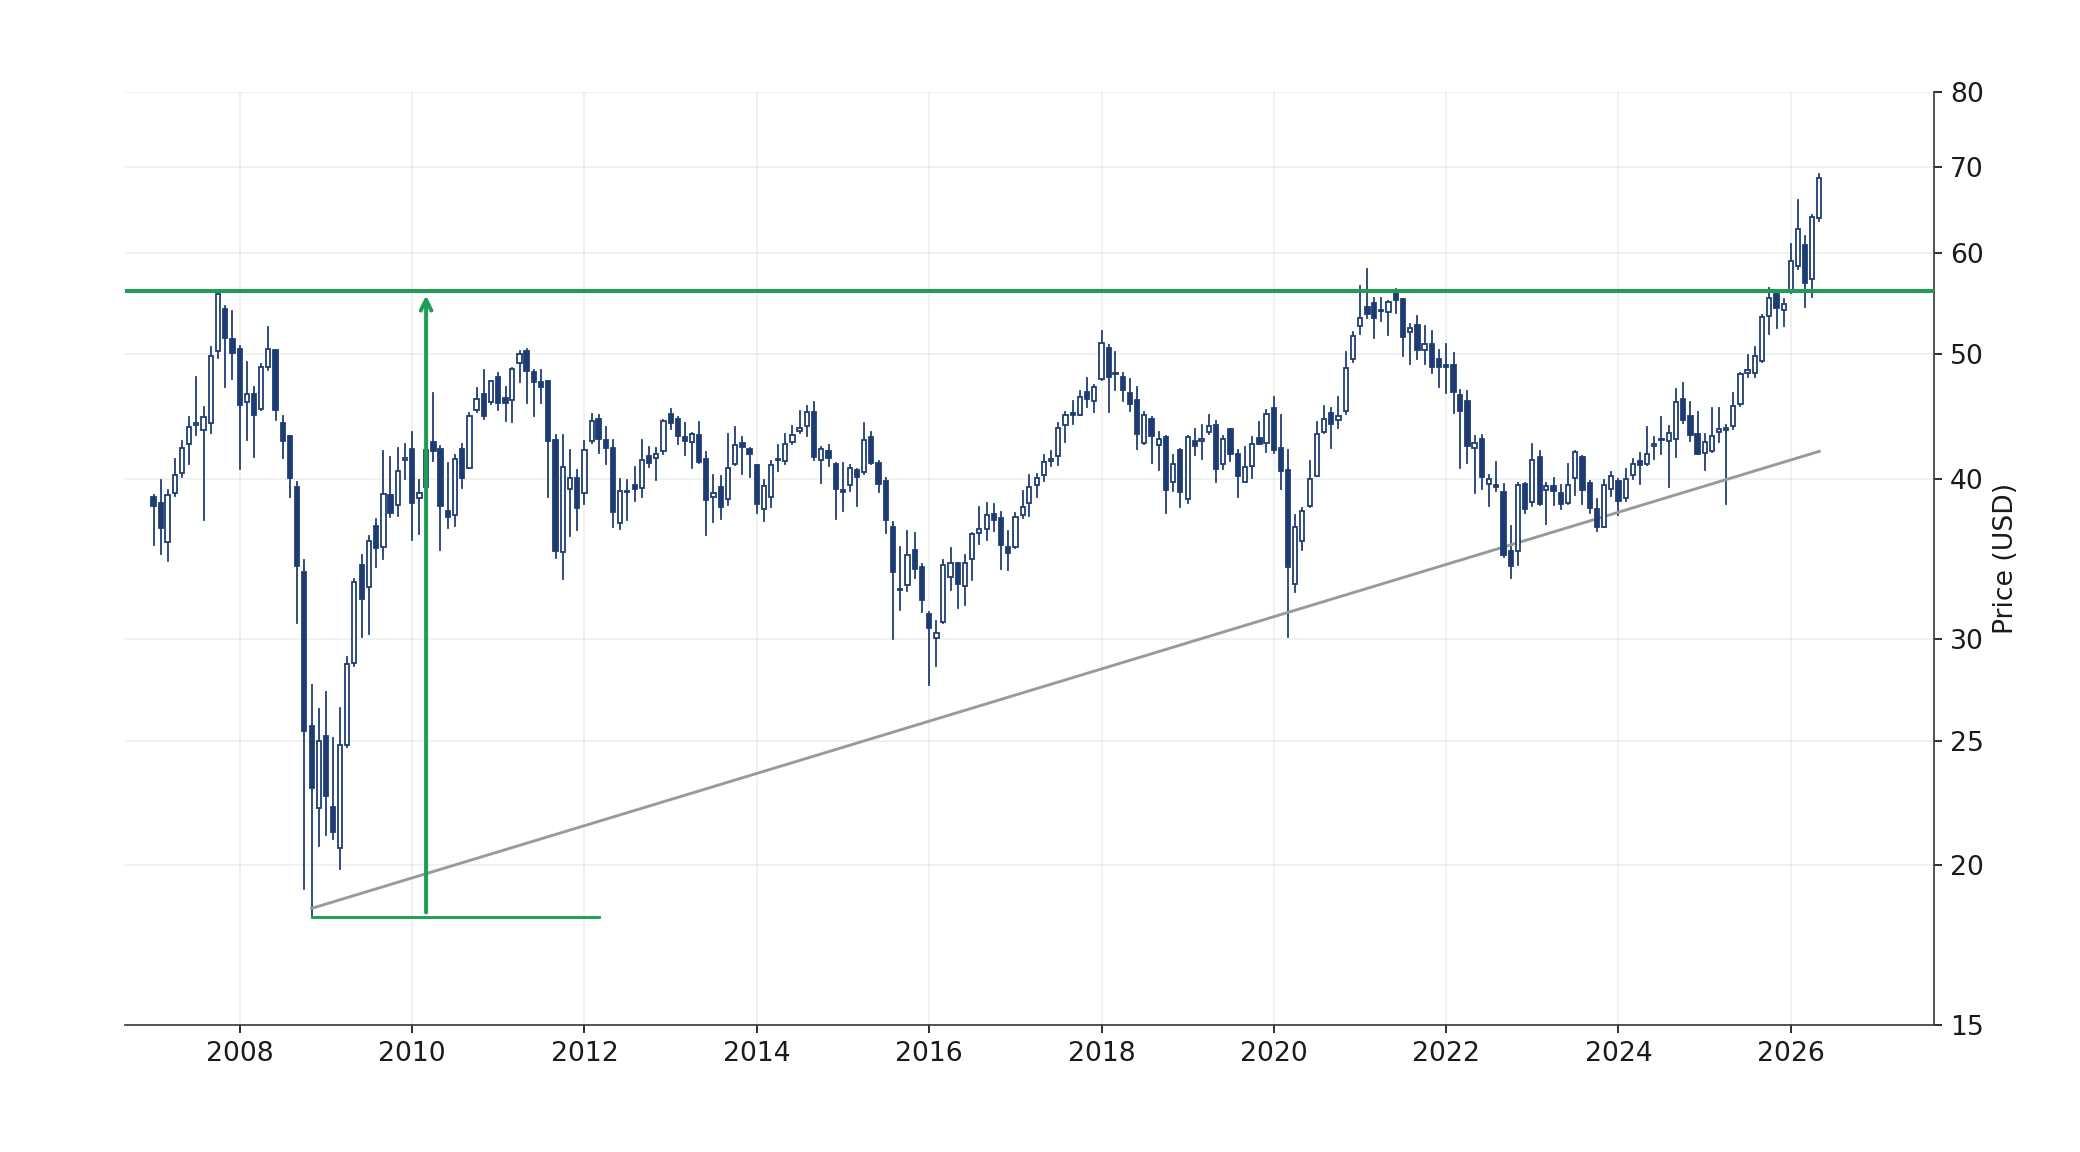
Micron вырос на 88% за месяц и превысил $1 трлн капитализации, еще до публикации
отчетности. Рынок стал воспринимать
полупроводниковый сегмент, а как
критический элемент масштабирования
высокой, что даже сильная отчётность
импульсом и видимым ростом
прибыли.
Рынок входит в июнь после сильной отчётности, но без большого запаса на ошибку. При 97% отчитавшихся компаний 85% эмитентов S&P 500
квартал выросла на 28,6% г/г.
Форвардный P/E снизился с 22,5x до 20,9x —
жёстче, а рынок ставок
начал закладывать около 12 б.п. повышения к
декабрю против нуля месяцем ранее. Пока
прибыль пересматривается вверх, акции
выдерживают более жёсткие ожидания по ставкам; если этот импульс ослабнет, под
давлением могут оказаться дорогие компании роста.
Оценки software уже
и возобновить
нисходящий тренд, который формируется с
начала 2025 года.
Дополнительным сезонным фактором остаётся
летний период, который традиционно менее
благоприятен для доллара из-за снижения
волатильности. В то же время падение доллара
может быть ограничено: продолжающиеся
притоки в американские акции поддерживают спрос на долларовую ликвидность
Source:
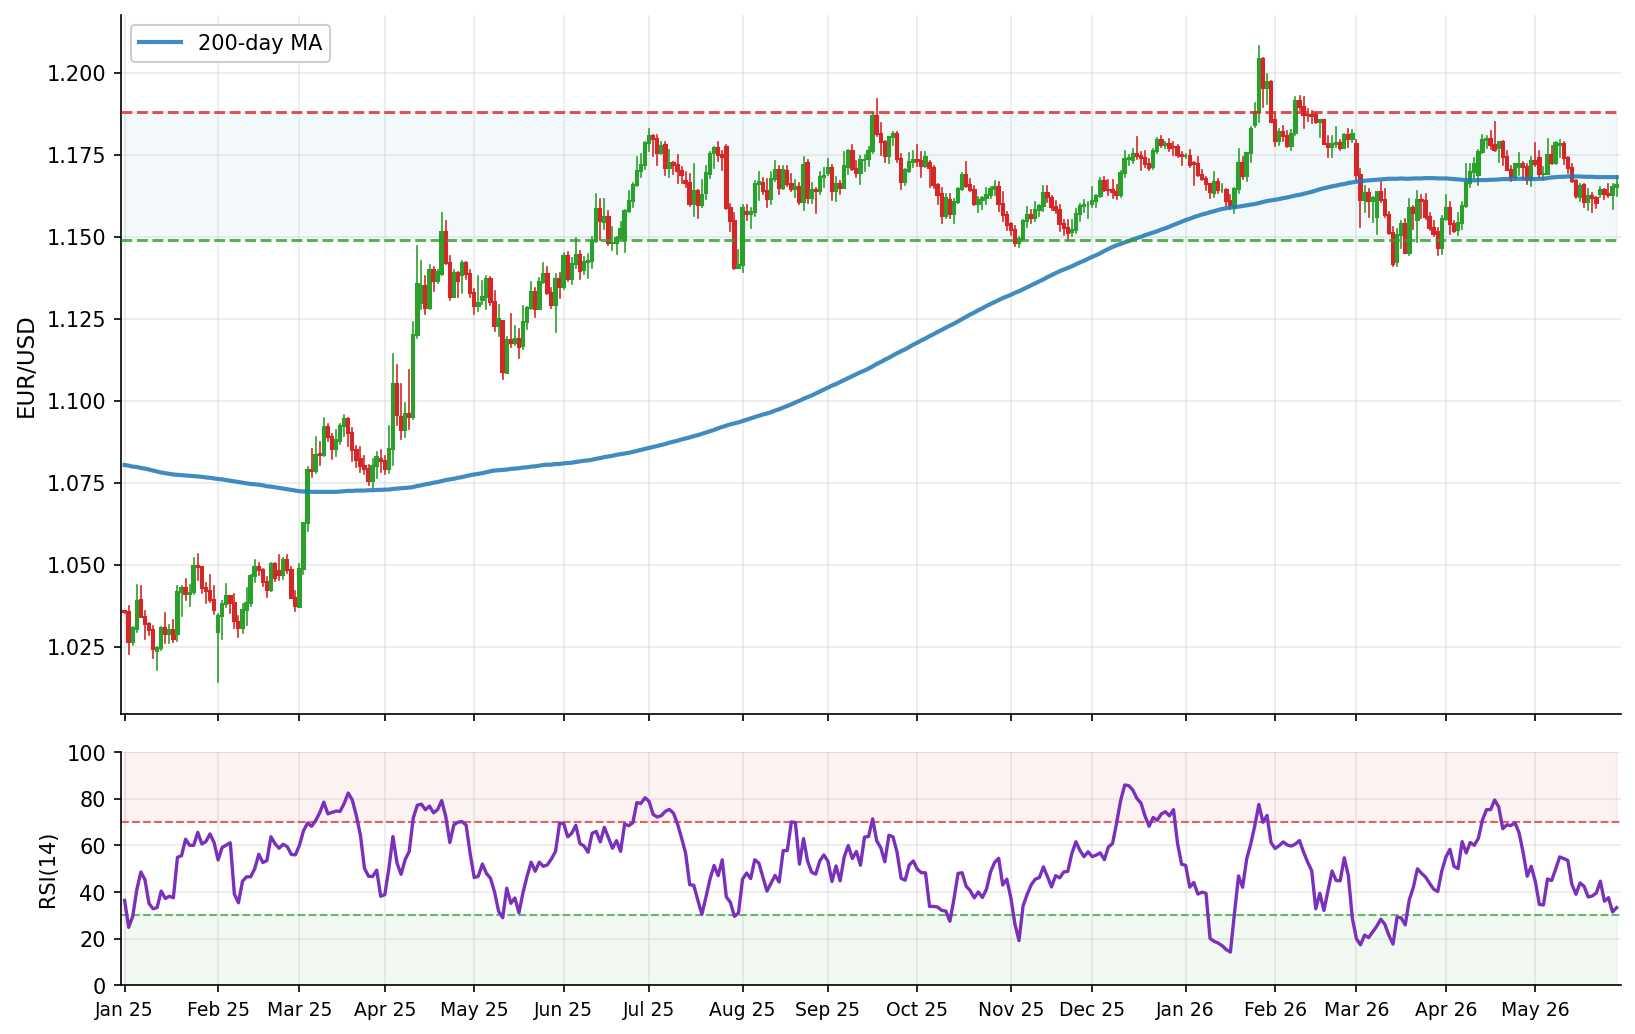
Euro (EUR/USD)
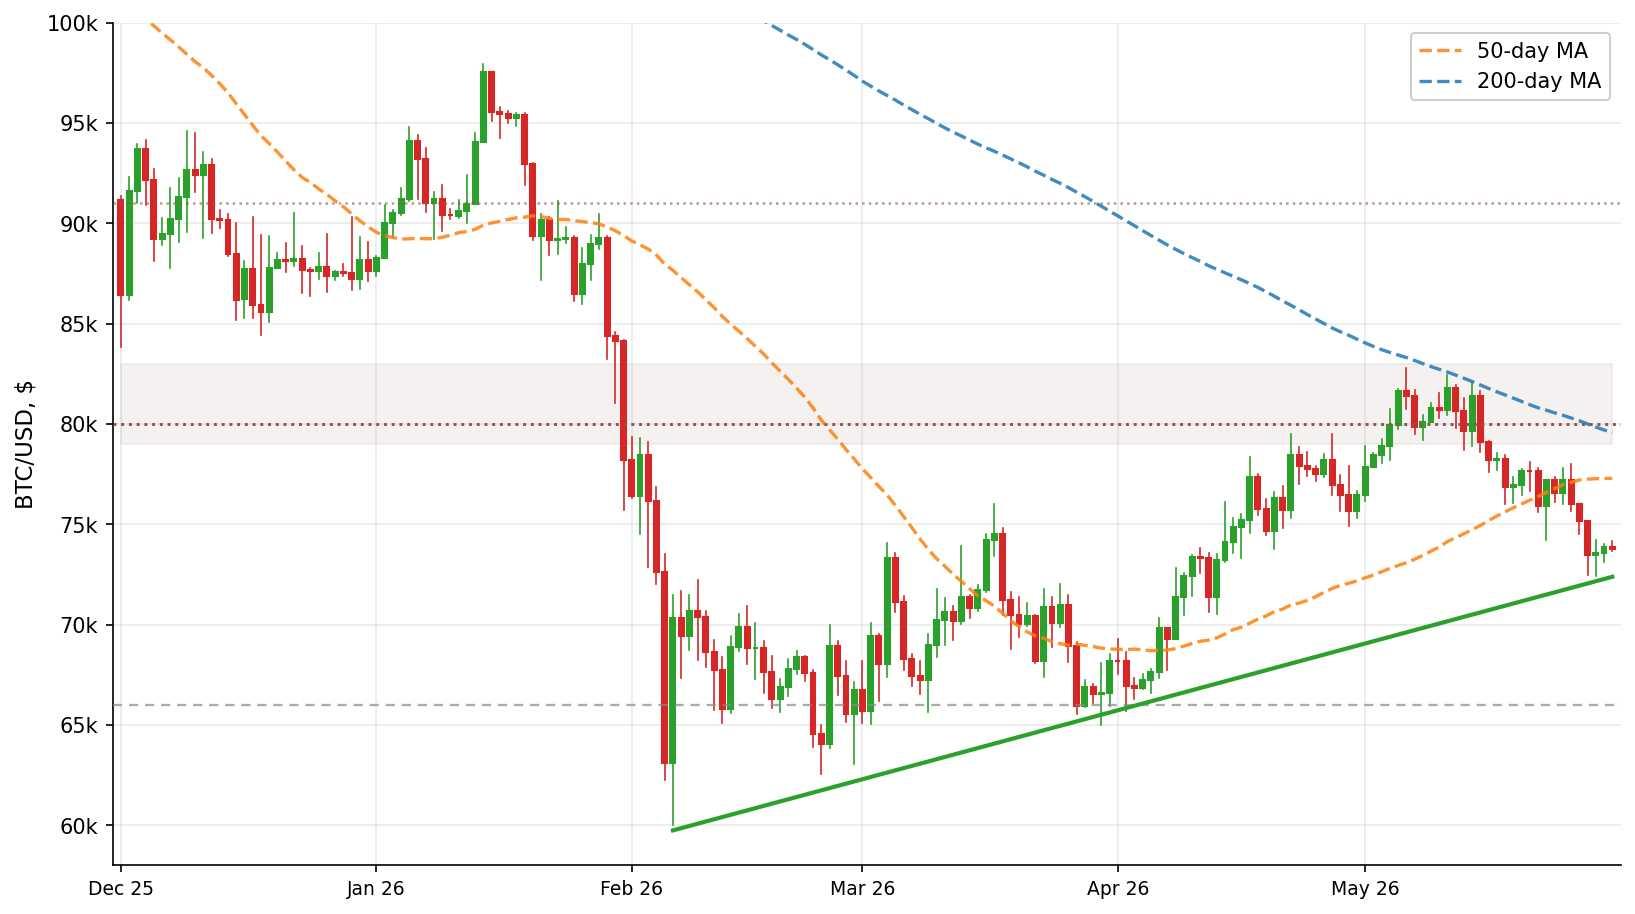
Bitcoin (BTC/USD)
Source: Bloomberg, Astero Falcon analytics.
Техническая
средних; зона $4 600 стала ближайшим
сопротивлением. Ключевая поддержка
проходит около $4 400, в районе 200-дневной
средней. Пока золото ниже сопротивления, движение выглядит скорее как консолидация
после сильного ралли, а не как новый импульс
вверх.
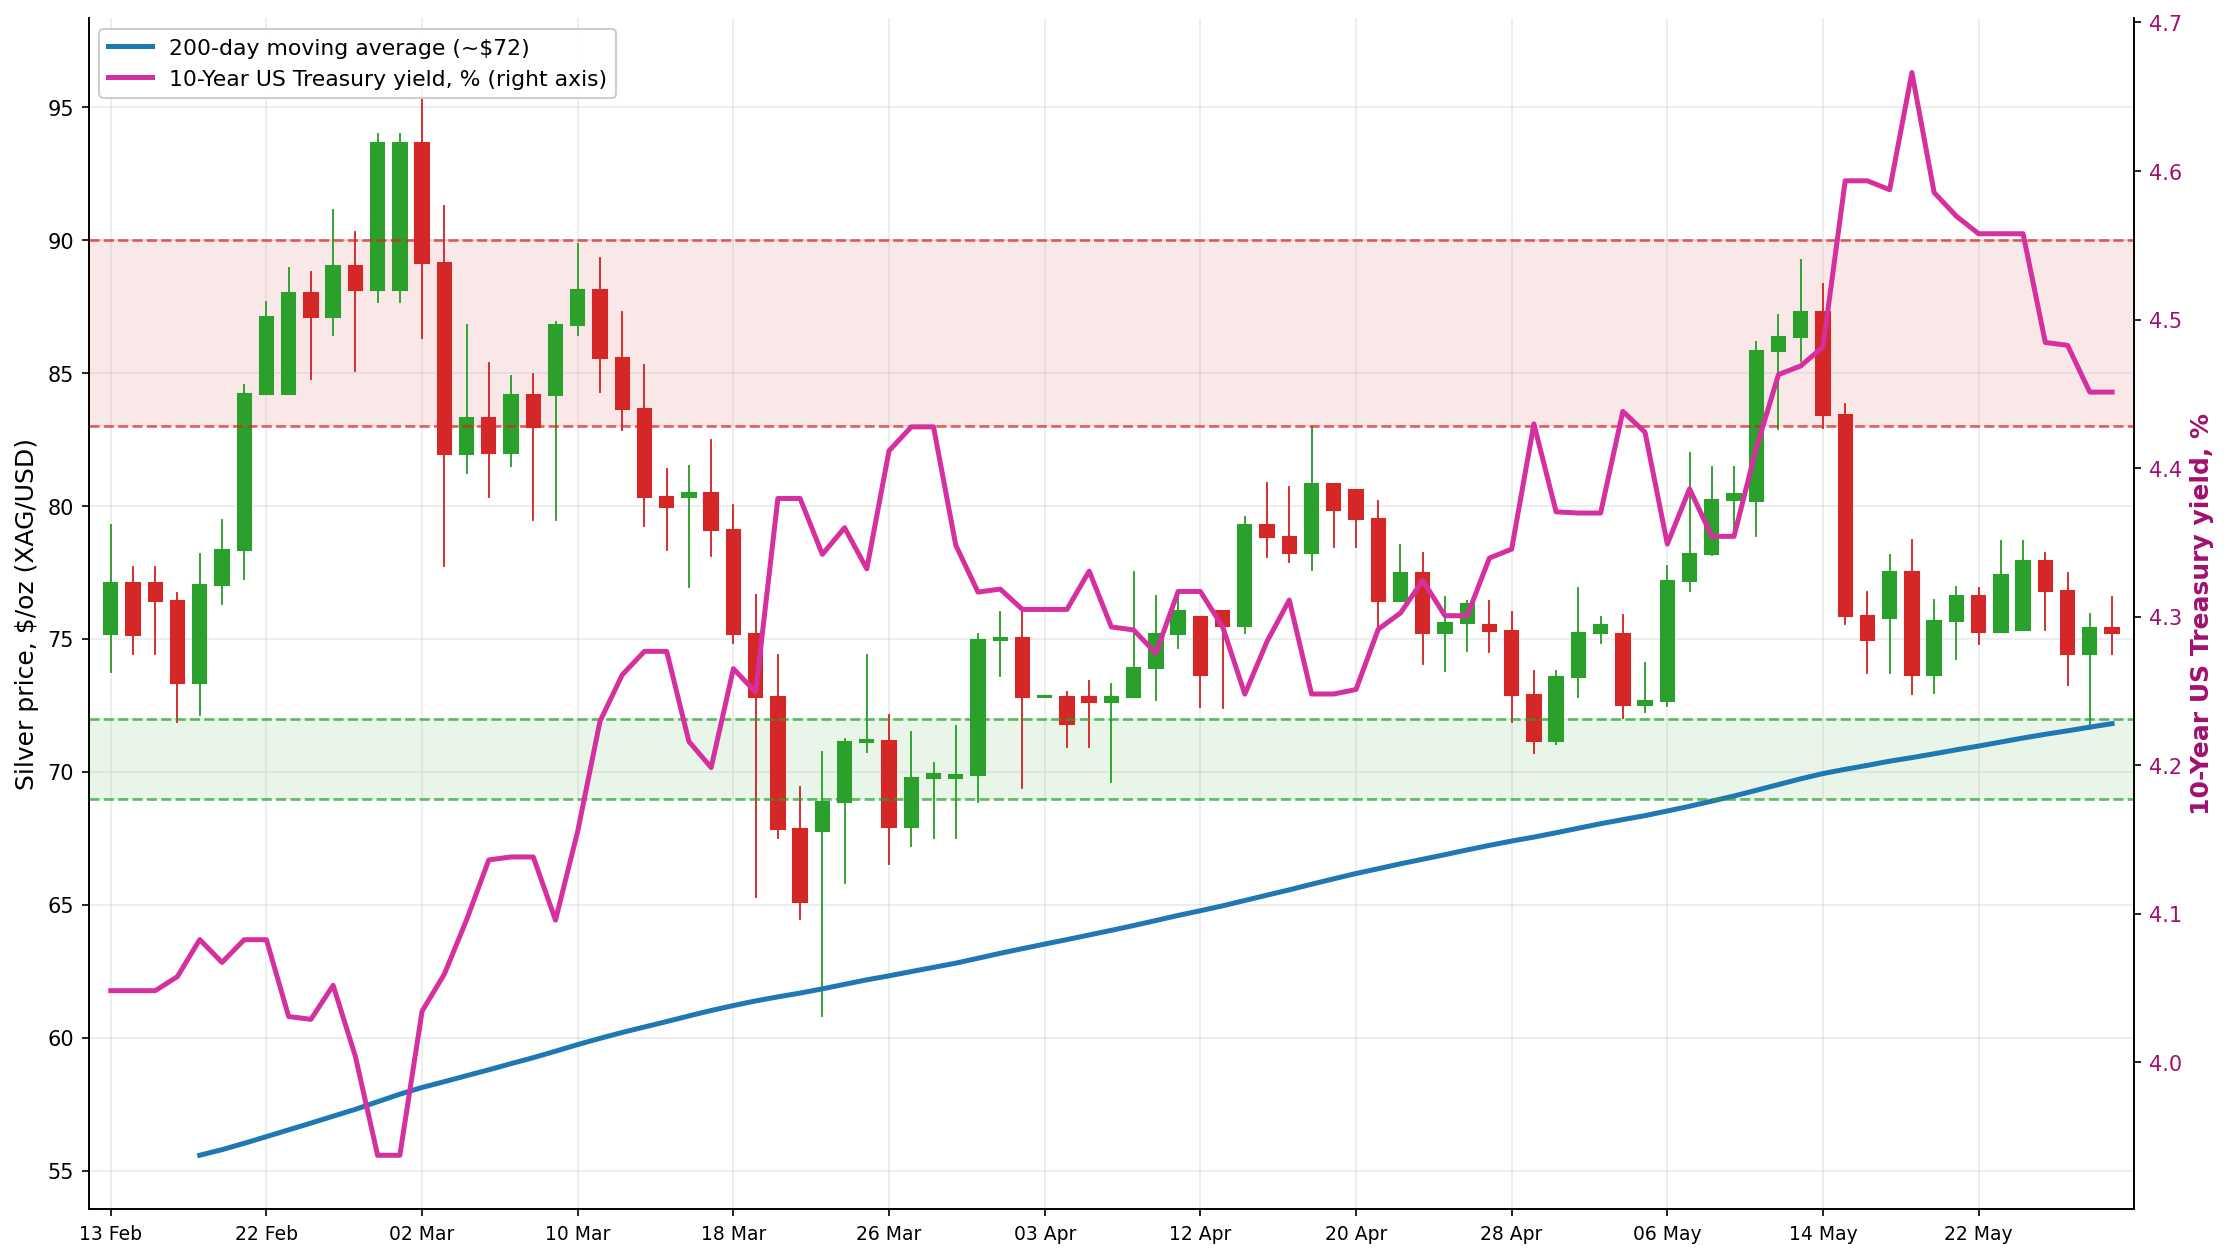
В первой половине месяца серебро выглядело устойчивее золота за счёт промышленной
Source: Bloomberg, Astero Falcon analytics.
Source:
Главная история начала года получила
продолжение: капитал в частных рынках всё
сильнее концентрируется вокруг ИИ-
инфраструктуры — энергетики, центров
обработки данных и вычислительных
мощностей.
Покупатели осторожнее подходят к срокам и
оценкам сделок: геополитическая
неопределённость, напряжение на рынке
частного кредита и волатильность публичных
оценок осложняют закрытие сделок.
Регионально восстановление также остаётся
неравномерным: рост активности наблюдался
в основном в Северной Америке, тогда как в
остальных регионах рынок продолжил ослабевать.
Выходы
инвесторам, удлиняет сроки удержания портфельных компаний
Source: Bloomberg, Astero Falcon
розничные платформы на базе бессрочных фондов. Именно
традиционный институциональный закрытый фандрайзинг остаётся более слабым.
Семейные офисы пока действуют осторожно, но
Source: Bloomberg, Astero Falcon analytics.
Облигации
Swiss Bond Index (SBI) AAA-BBB
Bloomberg Barclays Euro Aggregate Corporate TR
Bloomberg Barclays Pan-European High Yield TR
Bloomberg Barclays US Corporate High Yield TR
Bloomberg Barclays Sterling Corporate TR
Bloomberg Barclays China Aggregate TR
Bloomberg Barclays Asia USD High Yield TR
Bloomberg Barclays Global High Yield TR
JPM EMBI Global Total Return Index
Bloomberg Barclays Global-Aggregate TR
Акции
NASDAQ 100 Stock Index
S&P 500 INDEX
Dow Jones Industrial Average
MSCI World Index
MSCI Europe Index
MSCI Emerging Markets Index
SPI
SMIM
DAX
FTSE 100 Index
Hang Seng Index
Shanghai Shenzhen CSI 300 Inde
Nikkei 225
Сырьевые рынки
Gold
Silver
Copper
WTI
BRENT
Bloomberg Commodity Index
Валюты
EURCHF
CHFUSD
CHFGBP
EURUSD
EURGBP
GBPUSD
Source: Bloomberg, Astero Falcon analytics.
Май 2026
-0,03%
1,06%
0,93%
0,34%
2,04%
0,00%
0,00%
0,70%
0,82%
0,34%
Май 2026 10,49%
5,15%
2,78%
4,37%
2,56%
9,49%
3,27%
2,15%
3,34%
0,29%
-2,30%
0,00%
0,00%
Май 2026
-1,68%
2,10%
7,81%
-16,86%
-20,08%
-3,84%
Май 2026 0,66%
-0,05%
-1,13%
-0,61%
-0,47%
-1,09%
2026 -0,04%
0,88%
1,32%
0,50%
0,24%
1,81%
2,94%
1,94%
2,19%
0,50%
2026 20,13%
10,73%
6,18%
9,80%
5,71%
24,76%
5,15%
1,70%
2,51%
4,81%
-1,75%
5,66%
31,76%
2026 5,11%
5,07%
12,44%
52,14%
49,75%
23,17%
2026 2,23%
-1,47%
-1,61%
-0,74%
0,60%
-0,14%
Disclaimer 12
This document has been prepared and issued by Astero Falcon (DIFC) Limited ("Astero Falcon"), a company incorporated in the Dubai International Financial Centre ("DIFC") and authorised and regulated by the Dubai Financial Services Authority ("DFSA") under Firm Reference Number F010362.
PROFESSIONAL CLIENT RESTRICTION
This document constitutes a Financial Promotion for the purposes of the DFSA Rulebook and is directed exclusively at Professional Clients and Market Counterparties as defined under the DFSA Conduct of Business ("COB") Module.
This document is not intended for Retail Clients and must not be distributed to, relied upon by, or acted upon by any Retail Client or any person who does not meet the applicable DFSA client classification criteria.
INFORMATION PURPOSES ONLY
The information contained in this document is provided solely for informational, discussion, educational and general market commentary purposes and does not constitute:
• investment advice;
• investment research;
• a recommendation or personal recommendation;
• portfolio management advice;
• legal, tax, accounting or regulatory advice;
• an offer or solicitation to buy, sell, subscribe for or dispose of any investment or financial instrument;
• an arrangement in relation to investments; or
• any other regulated financial service under the DFSA Rulebook.
This material has not been prepared in accordance with the legal or regulatory requirements designed to promote the independence of investment research and should not be construed as "Investment Research" under the DFSA Conduct of Business Module.
MARKET COMMENTARY AND FORWARD-LOOKING STATEMENTS
The views, opinions, estimates, forecasts, projections, targets, expectations and forward-looking statements expressed herein reflect the judgment of Astero Falcon as at the date of publication only and are subject to change without notice.
Such statements involve known and unknown risks, uncertainties, assumptions and other factors that may cause actual results, market developments or investment outcomes to differ materially from those expressed or implied. No representation, warranty or assurance is given that any forecast, projection, target, estimate or expected outcome will be achieved.
No representation is made that any investment strategy, market view, forecast, projection, market theme, asset class, sector outlook or investment opportunity referred to in this document will be successful or achieve any particular outcome.
References to specific asset classes, sectors, markets, securities, digital assets, industries, investment themes or market opportunities are provided solely for illustrative and informational purposes and should not be interpreted as investment recommendations.
References to specific securities, issuers, sectors, asset classes, digital assets, markets, investment themes, strategies or investment opportunities do not constitute a recommendation, endorsement, solicitation or advice to invest, divest, acquire, dispose of or maintain exposure to any particular investment, asset class, market or strategy.
INVESTMENT RISKS
Any references to market performance, historical data, economic indicators, market trends or investment themes are provided for illustrative purposes only.
Past performance is not a reliable indicator of future performance.
The value of investments may rise or fall, and investors may not recover the full amount originally invested. Investments may be illiquid, volatile, leveraged or subject to substantial fluctuations in value.
Investments and financial markets involve risks including, but not limited to:
• market risk;
• liquidity risk;
• credit risk;
• counterparty risk;
• interest rate risk;
• currency and foreign exchange risk;
• valuation risk;
• concentration risk;
• operational risk;
• technology and cyber-security risk;
• geopolitical risk;
• regulatory and legal risk; and
• risk of partial or total loss of capital.
Disclaimer 13
DIGITAL ASSETS AND VIRTUAL ASSETS RISK WARNING
Any references to cryptocurrencies, digital assets, virtual assets, crypto-assets, crypto tokens, blockchain technology or related products are provided solely as part of general market commentary and for informational purposes only.
References to digital assets, cryptocurrencies, virtual assets or related technologies are included solely as part of general market commentary and should not be interpreted as a recommendation to acquire, dispose of, maintain exposure to or otherwise transact in such assets.
Such assets may not be regulated by the DFSA unless specifically classified under the applicable DFSA regulatory framework.
Digital assets are highly speculative and may experience extreme price volatility. Investors may lose all or a substantial portion of their investment. Digital assets may not be suitable for all investors and may be exposed to significant risks including:
• extreme market volatility;
• reduced liquidity;
• technology failures;
• cyber-security incidents;
• operational failures;
• market abuse;
• valuation uncertainty;
• custody risks;
• fraud risks;
• regulatory changes; and
• complete loss of invested capital.
NO RELIANCE
This document has been prepared without taking into account the specific investment objectives, financial situation, risk tolerance, tax status or particular needs of any recipient.
Recipients should conduct their own independent assessment and obtain independent legal, tax, accounting, regulatory and financial advice before making any investment or financial decision.
No reliance should be placed on the contents of this document as the sole basis for any investment decision.
PORTFOLIO ALLOCATION AND SUITABILITY
Any references to portfolio diversification, strategic asset allocation, investment positioning or market opportunities are provided solely as part of general market commentary and do not take into account the investment objectives, financial circumstances, tax status, risk tolerance or particular needs of any recipient.
Such references should not be interpreted as a recommendation that any investment, asset class, investment strategy or portfolio allocation is suitable for any specific investor.
SOURCES AND DATA
Information contained herein has been obtained from sources believed to be reliable, including Bloomberg, third-party market data providers and Astero Falcon analysis.
However, Astero Falcon does not represent or warrant, expressly or impliedly, the accuracy, completeness, reliability, timeliness or suitability of such information and accepts no liability whatsoever for any loss arising directly or indirectly from reliance upon this document or its contents.
REGULATORY AND ONBOARDING REQUIREMENTS
Any potential engagement, onboarding or provision of financial services by Astero Falcon remains subject to:
• applicable DFSA laws, rules and regulations;
• internal approval processes;
• client classification requirements;
• suitability and appropriateness assessments where applicable;
• Know Your Customer ("KYC") requirements;
• Anti-Money Laundering ("AML"), Counter-Terrorist Financing ("CTF") and sanctions screening requirements;
• tax and regulatory assessments where applicable; and
• execution of definitive legal documentation.
CONFIDENTIALITY AND DISTRIBUTION
This document is confidential and proprietary to Astero Falcon.
It may not be copied, reproduced, distributed, transmitted, disclosed, published or circulated, in whole or in part, without the prior written consent of Astero Falcon.
Distribution of this document may be restricted by law or regulation in certain jurisdictions. Recipients are responsible for ensuring compliance with all applicable local laws and regulations.
© 2026 Astero Falcon (DIFC) Limited. All rights reserved.
Astero Falcon (DIFC) Limited
Office 33, Level 7, Gate Village 10
Dubai International Financial Centre
Dubai, United Arab Emirates
Email: info@asterofalcon.com
Website: www.asterofalcon.com
Chief Investment Officer: Elena Nefedova